Auto insurance costs can vary dramatically—sometimes by hundreds of dollars annually—yet most drivers never compare quotes systematically. Behind these price swings lie complex algorithms weighing personal risk, regional exposure, and coverage choices. Understanding how insurers calculate premiums isn’t just about finding the cheapest rate; it’s about aligning protection with budget while avoiding hidden pitfalls. From credit scores to urban accident trends, every factor plays a role, and small adjustments—like bundling policies or opting for telematics—can unlock unexpected savings. This guide breaks down the science of pricing, equips you with comparison tools, and reveals strategies to cut costs without sacrificing security.
The core of auto insurance price comparison lies in transparency. Insurers use data—your driving record, vehicle type, even your ZIP code—to predict risk, but consumers often overlook how these inputs interact. For example, a single speeding ticket can raise premiums by 20% in some states, while a rural resident might pay half as much as an urban driver for identical coverage. Meanwhile, discounts for low mileage or safety features remain underutilized, leaving money on the table. By mastering the comparison process—from manual quote analysis to leveraging AI tools—drivers can navigate a system designed to maximize profits while securing fair, tailored policies.
Auto Insurance Price Comparison Overview and Core Mechanisms
Auto insurance price comparison is the systematic evaluation of quotes from multiple insurers to identify the most cost-effective and suitable coverage options for drivers. Its relevance lies in empowering consumers to make informed decisions, balancing affordability with adequate protection against financial risks. Without comparison, drivers may overpay for policies or underinsure due to lack of awareness about available discounts, coverage tiers, or regional pricing variations.
The process leverages transparency in the insurance market, where premiums are not standardized and vary significantly based on provider policies, underwriting criteria, and regional factors. Historical data shows that drivers who compare quotes save an average of 15–30% on annual premiums, while also gaining access to tailored coverage that aligns with their risk profiles. This practice is particularly critical for high-risk drivers, such as young adults or those with prior claims, who face steeper premiums and benefit most from identifying niche insurers or specialized programs.
---
Core Factors Influencing Auto Insurance Pricing
Auto insurance premiums are determined by a combination of actuarial risk assessments and provider-specific policies. The primary factors include:
Risk = (Probability of Claim × Average Claim Cost) × Provider Overhead + State Regulations
Driver Demographics
Age, gender, and marital status directly impact perceived risk. Younger drivers (under 25) and single males typically face higher premiums due to statistical correlations with higher accident rates. Conversely, married drivers often qualify for discounts, as insurers associate lower risk with stable lifestyles.
Location and Regional Data
Urban areas with high traffic density, theft rates, or adverse weather conditions (e.g., hail-prone regions) result in elevated premiums. Zip code-level data is used to adjust rates, with some states mandating minimum coverage levels that artificially inflate costs in high-risk zones.
Vehicle Characteristics
Make, model, year, and safety features determine repair costs and theft vulnerability. Luxury or sports cars incur higher premiums due to expensive parts, while vehicles with advanced safety tech (e.g., automatic braking) may qualify for discounts. Vehicle age also plays a role: older cars with higher mileage or depreciated value may have lower collision coverage costs.
Driving History and Claims Record
Traffic violations (e.g., DUIs, speeding tickets) and prior claims increase premiums for 3–5 years. A single at-fault accident can raise rates by 40–60%, while a clean record may unlock discounts. Insurers also consider credit scores in some states, as studies link financial responsibility to lower risk-taking behavior behind the wheel.
Coverage Limits and Policy Type
Minimum state-required liability coverage is cheaper than comprehensive or collision plans. Higher deductibles reduce premiums but increase out-of-pocket expenses during claims. Additional endorsements (e.g., roadside assistance, rental reimbursement) further modify costs.
Understanding these factors enables consumers to proactively mitigate costs—such as bundling policies, enrolling in defensive driving courses, or selecting a safer vehicle—before comparing quotes.
---
Primary Goals of Auto Insurance Price Comparison
The comparison process serves three interconnected objectives: financial optimization, risk management, and coverage alignment. Each goal addresses distinct consumer needs but collectively ensures a balanced insurance strategy.
Cost Savings Through Competitive Quotes
Insurers employ diverse underwriting models, leading to price disparities for identical coverage. For example, a driver in a high-theft city might find a 20% premium difference between a provider that heavily penalizes location and one that offers regional discounts. Aggregator tools compile these variations, allowing users to identify outliers or negotiate better rates with existing insurers by leveraging competing offers.
Coverage Optimization for Risk Exposure
Standard policies may not address unique risks, such as classic car owners requiring agreed-value coverage or rideshare drivers needing commercial endorsements. Comparison tools highlight gaps in standard plans and suggest add-ons (e.g., uninsured motorist protection) based on local accident statistics or vehicle use patterns.
Risk Assessment and Long-Term Planning
Beyond immediate savings, comparisons reveal how lifestyle changes (e.g., relocating, adding a teen driver) will impact premiums. Tools can simulate scenarios—such as switching from a traditional policy to usage-based insurance—to project annual cost fluctuations. This foresight helps consumers align insurance strategies with life events, such as retiring from a high-mileage job or purchasing a second vehicle.
---
How Price Comparison Tools Function: Data Inputs and Algorithms
Price comparison tools operate as intermediaries between consumers and insurers, standardizing the quoting process while preserving provider autonomy. Their functionality relies on structured data inputs and proprietary algorithms that balance speed with accuracy.
Data Collection and Standardization
Users input core details through forms or connected accounts (e.g., bank portals, DMV records). Required fields include:
Driver information (age, license status, prior violations).
Discount eligibility (e.g., military service, employer partnerships).
Tools normalize this data to mitigate discrepancies—for example, converting partial ZIP codes to full addresses or cross-referencing VINs with safety ratings databases.
Algorithm-Driven Quote Generation
Behind the scenes, algorithms perform three key functions:
Risk Profiling
Machine learning models analyze input data against historical claims databases to assign a risk score. For instance, a 22-year-old male driving a 2020 Mustang in Miami may receive a higher score than a 45-year-old female driving a 2018 Honda Accord in Des Moines, triggering different underwriting tiers.
Provider Matching
The tool filters insurers based on compatibility with the user’s risk profile. High-risk drivers may only see quotes from specialty insurers, while low-risk users access mainstream providers. Some tools prioritize insurers with strong financial ratings (e.g., AM Best A++).
Dynamic Pricing Adjustments
Real-time factors—such as current fuel prices (affecting accident rates) or local weather alerts (influencing claim frequency)—are incorporated to refine quotes. Usage-based insurers may also pull telematics data (e.g., hard braking frequency) to adjust premiums post-quote.
Output and Actionable Insights
Results are presented in ranked order, often with visual aids like:
Side-by-side tables comparing premiums, deductibles, and coverage limits.
Bar graphs illustrating savings potential vs. baseline rates.
Alerts for missed discounts (e.g., multi-policy bundles, paperless billing).
Advanced tools integrate with policy management systems, allowing users to bind coverage directly or schedule callbacks with agents for complex cases.
---
Comparative Analysis of Auto Insurance Pricing Models
Insurers employ distinct pricing models to align premiums with driver behavior and risk. Below is a structured comparison of three prevalent approaches, highlighting their mechanisms, suitability, and trade-offs.
Pricing Model
Description
Pros
Cons
Best For
Traditional (Actuarial)
Premiums are fixed based on broad demographic and vehicle data (e.g., age, location, credit score). No real-time monitoring of driving behavior.
Predictable monthly costs; no surprises from usage fluctuations.
Wider availability from insurers without telematics infrastructure.
Simpler for drivers who prefer set-and-forget policies.
Overcharges safe drivers and undercharges high-risk drivers.
No incentives to improve driving habits.
Less competitive in states with strict rate regulations.
Premiums are calculated based on actual miles driven, using an installed odometer or smartphone app. Base rate covers minimum coverage, with additional fees per mile.
Significant savings for low-mileage drivers (e.g., 50% reduction for <5,000 miles/year).
Encourages fuel-efficient driving and reduced wear-and-tear.
Transparent pricing aligned with real usage.
Requires compatible vehicles (e.g., OBD-II ports) or mobile apps.
Potential for higher costs during high-mileage periods (e.g., road trips).
Limited provider options; primarily offered by niche insurers.
Premiums are dynamically adjusted based on real-time driving behavior, monitored via telematics devices or apps. Factors include speed, braking, phone use, and time of day.
Rewards safe driving with discounts (e.g., 10–30% savings for low-risk behavior).
Personalized feedback
Auto Insurance Price Comparison Template in Word, Google Docs - Download Templat
Top 5 Most Impactful Factors in Auto Insurance Premium Determination
Auto insurance premiums are calculated using a complex algorithm that balances risk assessment with actuarial data. The five most significant factors—ranked by their influence—directly correlate with claim likelihood, severity, and insurer profitability. These variables are weighted differently across providers but universally shape underwriting decisions.
Insurers prioritize factors based on statistical predictability and cost impact. While some states regulate certain variables (e.g., credit scores), the core principles remain consistent: driver behavior, vehicle characteristics, location, coverage limits, and claims history dominate premium calculations. Below is a ranked breakdown of their significance, supported by industry trends and regulatory frameworks.
---
Driving Record and Claims History
A driver’s history of accidents, traffic violations, or prior claims is the single most influential factor in premium determination. Insurers classify drivers into risk tiers using loss ratios—the ratio of claims paid to premiums collected. For example:
At-fault accidents: A single at-fault collision can increase premiums by 30–50% for three to five years, depending on severity.
Moving violations: Speeding tickets or DUIs may raise rates by 20–40% annually, with DUI convictions often triggering high-risk classifications.
No-claim discounts: Drivers with five or more years without claims may qualify for discounts up to 30%.
Actuarial Formula: Premium Adjustment = Base Rate × (1 + [Violation Severity Weight × Years on Record] + [Claim Frequency Multiplier]).
Insurers also analyze pattern recognition—frequent minor claims may indicate higher risk than a single major incident. States like California and New York enforce accident forgiveness programs, capping rate increases for first-time offenders, but most markets retain historical data for underwriting.
---
Vehicle Make, Model, and Year
The type of vehicle drives both repair costs and theft risk, directly impacting premiums. Insurers categorize vehicles using:
Collision repair costs: Luxury or high-performance cars (e.g., Porsche, BMW) incur 40–60% higher repair expenses than economy models (e.g., Honda Civic, Toyota Corolla).
Theft rates: Vehicles like the Honda Accord (2016–2018) and Ford F-Series appear frequently in theft statistics, increasing comprehensive coverage costs.
Safety ratings: Models with top IIHS or NHTSA safety scores (e.g., Subaru Outback, Volvo XC60) may qualify for 10–25% discounts on liability coverage.
Depreciation Impact: A 2020 model may cost 20–30% less to insure for collision than a 2018 model of the same make, due to lower replacement value and advanced safety tech.
Regional theft hotspots (e.g., California for luxury cars, Texas for trucks) further adjust rates. Insurers also factor in parts availability—older European cars with discontinued parts may face higher premiums due to inflated repair costs.
---
Location and Urban vs. Rural Risk Profiles
Geographic data, including zip code, crime rates, and road conditions, accounts for 15–25% of premium variation. Urban areas exhibit higher accident frequencies but lower theft risks in some cases, while rural regions may have fewer accidents but higher liability claim costs due to longer emergency response times.
Key metrics by region:
Accident frequency: Urban drivers file ~30% more claims annually than rural drivers, with Los Angeles and Miami ranking highest for collision claims.
Claim severity: Rural areas often see higher average claim payouts (e.g., $8,000+ for property damage in farm-heavy states like Iowa vs. $5,000 in suburban areas).
Theft vulnerability: New York City leads in vehicle theft claims, while Oklahoma and Kansas report lower theft rates but higher vandalism-related losses.
Regional Premium Example:
New York (Urban): $2,500/year (high collision/low theft).
North Dakota (Rural): $1,200/year (low collision/high liability).
Insurers also adjust for weather risks—states like Florida (hurricane damage) or Montana (winter road hazards) may inflate comprehensive/collision rates by 10–20%.
---
Coverage Limits and Deductibles
The type and extent of coverage selected directly correlates with premium costs. Insurers categorize policies into tiers based on:
Liability limits: Minimum state requirements (e.g., 25/50/25) cost 30–50% less than full coverage (e.g., 100/300/100).
Deductible levels: Opting for a $1,000 deductible reduces collision/comprehensive premiums by 15–25% compared to a $500 deductible.
Additional coverages: Uninsured motorist protection or roadside assistance can add 5–15% to premiums.
Cost-Benefit Tradeoff:
Higher deductibles lower premiums but increase out-of-pocket expenses. For example, a driver paying $1,200/year with a $500 deductible may drop to $900/year with a $1,500 deductible—a 25% savings—but risks higher payments per claim.
State-mandated minimums vary widely:
Florida: $10,000 property damage liability.
Massachusetts: $20,000 bodily injury per person.
Virginia: $25,000 bodily injury per accident.
---
Credit-Based Insurance Scores
Credit scores are a controversial but widely used factor in 39 U.S. states, where insurers correlate financial responsibility with claim likelihood. A FICO Auto Insurance Score (300–900 scale) can adjust premiums by up to 50% between the lowest and highest tiers.
Regional and Legal Variations:
States allowing credit use: Alabama, Arizona, California (phasing out), Colorado (restricted), etc.
States prohibiting credit use: California (2021 ban), Hawaii, Massachusetts, Michigan.
Score impact:
Excellent (750+): 10–20% lower premiums.
Fair (600–650): 30–50% higher premiums.
Poor (<580): May trigger high-risk classifications, requiring SR-22 filings.
Credit Score vs. Premium Example:
A driver in Texas with a 780 score may pay $1,500/year, while a driver with a 620 score could face $2,200/year—a $700 annual difference for the same coverage.
Critics argue credit scores reflect socioeconomic status rather than driving risk, but insurers defend the practice as a proxy for long-term financial stability and claim payment reliability.
---
Step-by-Step Process for Manually Comparing Auto Insurance Quotes and Required Documentation
Obtaining accurate and competitive auto insurance quotes requires a systematic approach to ensure all relevant factors are considered. Manual comparison allows for deeper scrutiny of terms, exclusions, and fine print that automated tools may overlook. Below is a structured process to gather and evaluate quotes, along with the essential documentation insurers will request.
Preparation of Required Documentation
Before requesting quotes, gather the following documents to streamline the process and ensure consistency across insurers. Incomplete or inconsistent information may lead to inaccurate quotes or delays in approval.
Driver Information
Full legal names, dates of birth, and driver’s license numbers for all household members listed on the policy.
Driving history, including traffic violations, accidents, or claims filed in the past three to five years.
Credit score or credit history (some insurers use this to determine risk and premiums).
Vehicle Details
Vehicle Identification Number (VIN) for each car to be insured.
Year, make, model, and trim level of the vehicle.
Purchase date, current mileage, and whether the vehicle is financed or leased.
Modifications or aftermarket additions (e.g., upgraded stereo, performance parts) that may affect coverage.
Preferred deductible amounts for collision and comprehensive coverage (e.g., $500, $1,000).
Additional endorsements or riders (e.g., roadside assistance, rental reimbursement, gap insurance).
Usage and Location Information
Primary and secondary driving locations (e.g., urban, suburban, rural).
Annual mileage estimates and typical routes (e.g., commuting, long-distance travel).
Parking details (e.g., garage, driveway, street parking).
Whether the vehicle is used for business or rideshare purposes (e.g., Uber, Lyft).
Policy Exclusions and Special Circumstances
Any known exclusions (e.g., racing, off-road use, modified engines).
Existing policies or coverage gaps (e.g., switching from another insurer, adding a new driver).
Discounts or affiliations (e.g., employer discounts, alumni associations, bundling with home insurance).
Selecting Insurers for Comparison
Focus on a mix of national insurers, regional providers, and specialty insurers to ensure a broad range of options. Prioritize companies with strong financial ratings (e.g., AM Best A++ or A.M. Best A) and positive customer service reviews. Common categories include:
Major national insurers (e.g., State Farm, Allstate, Progressive, Geico).
Regional or local insurers (e.g., USAA for military members, Farm Bureau for rural areas).
Specialty insurers (e.g., those catering to high-risk drivers, classic cars, or luxury vehicles).
Direct writers (insurers selling policies exclusively online or via call centers).
Requesting Quotes
Contact insurers through their official websites, call centers, or licensed agents to obtain quotes. Use the same coverage details and driver information for each request to maintain consistency. Document the date and method of each quote request for follow-up purposes.
Online Quote Tools
Enter details directly on the insurer’s website or through a third-party aggregator (ensure data privacy and security).
Save quotes as PDFs or screenshots for record-keeping.
Phone or Agent Consultations
Speak with a licensed agent to clarify coverage nuances or ask about discounts not available online.
Request a written summary of the quote, including all fees and exclusions.
Avoiding Quote Shopping Penalties
Some insurers may adjust rates if multiple quotes are obtained within a short period. Space requests over a few weeks if possible.
Use incognito or private browsing modes to prevent cookies from affecting quote accuracy.
Evaluating and Organizing Quotes
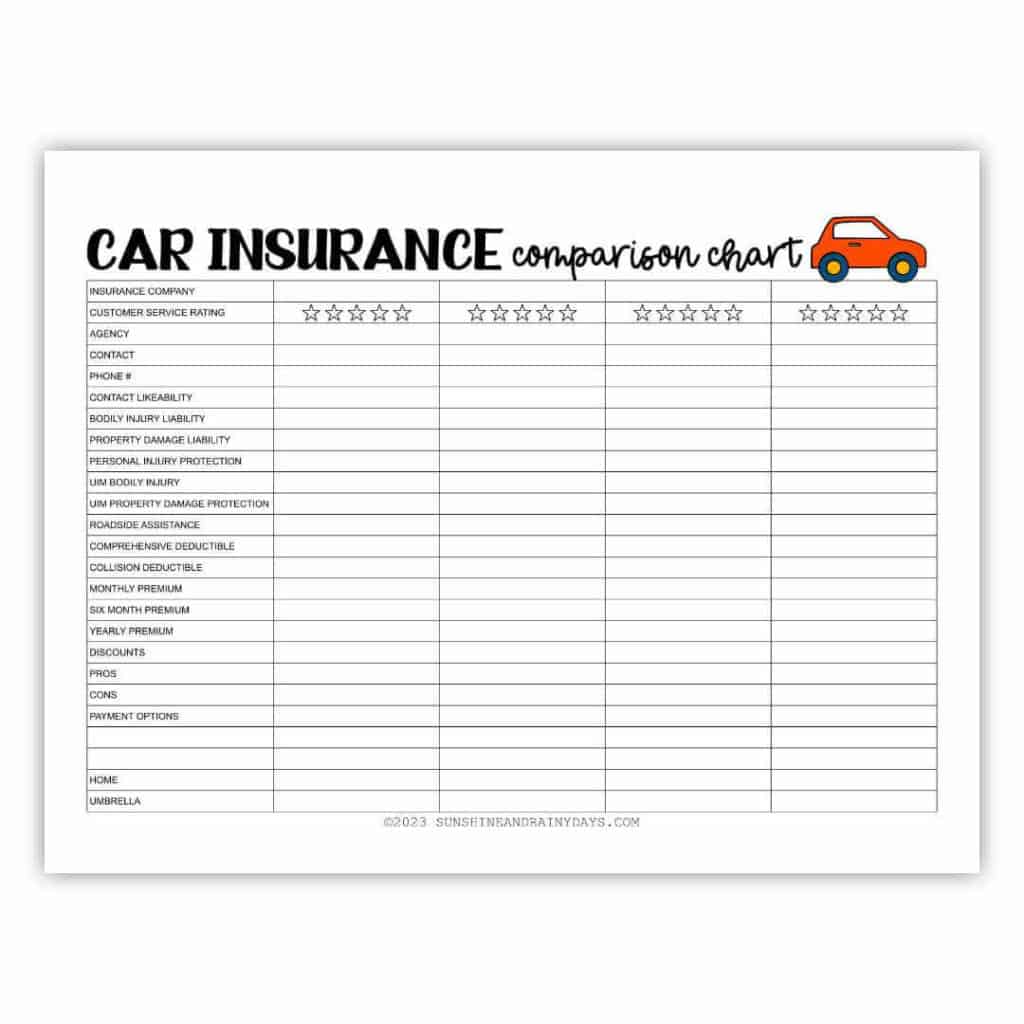
Use a standardized template (provided below) to compare quotes side by-side. Focus on the following criteria to identify the best value:
Premium costs (monthly, semi-annual, or annual).
Coverage limits and deductibles for each policy type.
Exclusions, limitations, or sub-limits (e.g., glass coverage, personal injury protection).
Discounts applied and their eligibility requirements.
Customer service ratings and claims satisfaction scores.
Financial strength ratings and complaint records (e.g., from the National Association of Insurance Commissioners).
Follow-Up and Verification
After compiling quotes, verify critical details with each insurer to resolve ambiguities. Key actions include:
Confirm that all discounts are applicable and will be applied at policy issuance.
Clarify any exclusions or conditions that may void coverage in specific scenarios.
Ask about additional fees (e.g., administrative charges, late payment penalties).
Request a binding quote or commitment letter if negotiating terms.
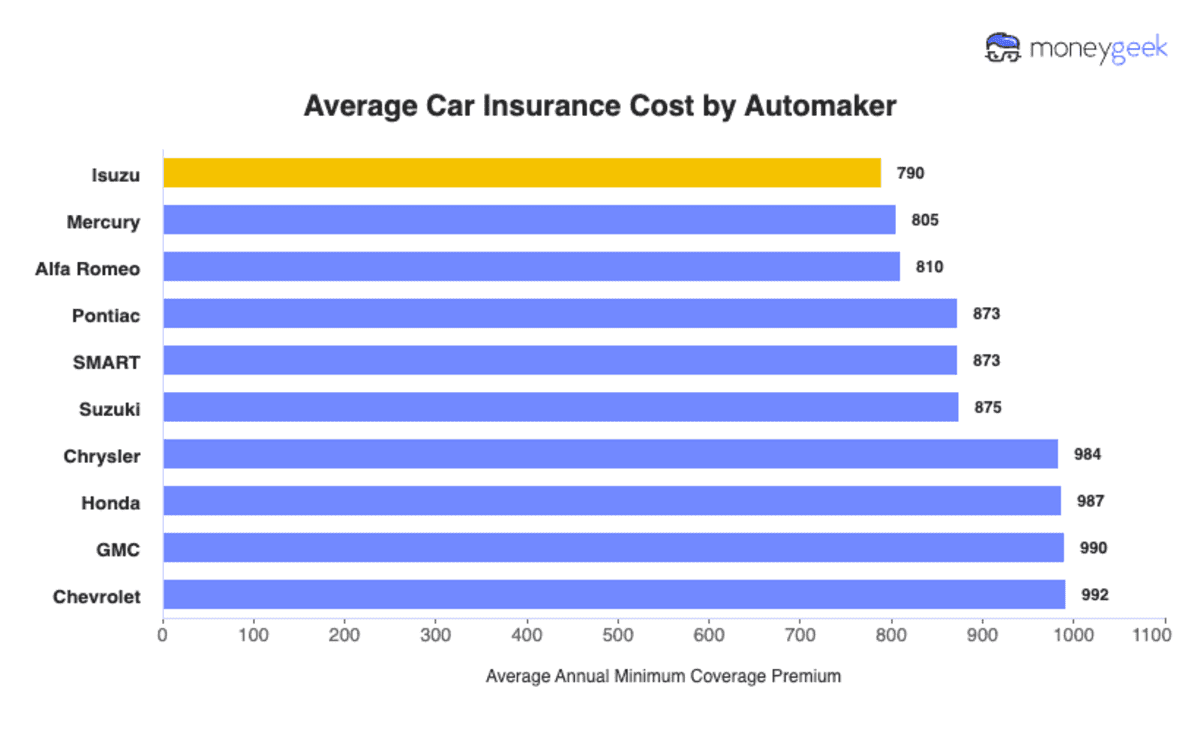
Insurance Rates by Car Model (2026 Estimates)
Standard Auto Insurance Coverage Types and Their Cost Implications
Auto insurance policies typically bundle multiple coverage types to protect drivers from financial losses resulting from accidents, theft, or other incidents. Each coverage type serves a distinct purpose and contributes differently to premium costs. Understanding these components helps policyholders balance protection with affordability. Below is a detailed breakdown of standard coverages, their definitions, cost drivers, and typical price ranges relative to policy limits and deductibles.
Liability Coverage
Liability coverage is legally required in most states and pays for damages and injuries caused to others in an at-fault accident. It does not cover the policyholder’s own vehicle or medical expenses. Costs vary significantly based on state minimums, coverage limits, and personal risk factors.
Standard Liability Limits (per state):
Bodily Injury Liability (BI): Covers medical expenses for injured parties (e.g., $25,000 per person, $50,000 per accident).
Minimum liability policies (e.g., 25/50/10) typically cost $300–$800 annually for average drivers, depending on location. States with high accident rates (e.g., Florida, California) may see premiums exceed $1,500 due to higher claims frequency.
Increasing limits (e.g., 100/300/100) adds $200–$600/year but provides significantly higher asset protection in lawsuits.
Key Factors Affecting Cost:
State minimum requirements (e.g., New Hampshire has no mandatory liability insurance, while New Jersey requires $15,000 BI/$30,000 PD minimum).
Driving history (e.g., at-fault accidents or DUIs can increase liability costs by 50–150%).
Vehicle type (e.g., luxury cars may face higher PD liability claims due to repair costs).
Collision Coverage
Collision coverage pays for damage to the policyholder’s vehicle resulting from a collision with another object (e.g., another car, guardrail, or tree). It is optional but often required if financing a vehicle. Deductibles range from $250–$2,000, with higher deductibles lowering premiums.
Cost Implications:
Average annual cost: $300–$1,200, depending on vehicle age, repair costs, and deductible.
Newer or high-value vehicles (e.g., Tesla Model 3, Ford F-150) may cost $1,500+/year due to expensive repair parts.
Older vehicles (e.g., 10+ years old) may not justify collision coverage if the vehicle’s value is less than the premium.
Cost-Saving Strategies:
Choosing a higher deductible (e.g., $1,000 vs. $500) can reduce premiums by 20–40%.
Monitoring depreciation: Dropping collision when the vehicle’s market value falls below 10% of premium costs (e.g., a $5,000 car with $500/year collision coverage).
Discounts for anti-theft devices or safe driving programs (e.g., Progressive’s Snapshot).
Comprehensive Coverage
Comprehensive coverage protects against non-collision incidents, including theft, vandalism, fire, hail, or falling objects (e.g., tree branches). Like collision, it is optional but often bundled with loans. Deductibles typically mirror collision policies.
Cost Implications:
Average annual cost: $150–$800, with higher costs for theft-prone areas (e.g., urban centers like Los Angeles or Chicago) or luxury vehicles.
Theft risk varies by vehicle model: A Honda Civic may cost $200/year, while a BMW X5 (targeted by thieves) can exceed $1,000/year.
Natural disaster-prone regions (e.g., Florida for hurricanes, Texas for hail) see 30–50% higher comprehensive premiums.
Regional Variations:
High-Risk Areas: Florida drivers pay $1,200–$2,500/year for comprehensive due to hurricane/hail claims. Texas follows with $900–$1,800 for hailstorms.
Low-Risk Areas: Rural states like Maine or Vermont average $150–$400/year with lower theft/vandalism rates.
Uninsured/Underinsured Motorist Coverage
This coverage protects the policyholder if the at-fault driver lacks sufficient insurance. It covers medical expenses, lost wages, and vehicle repairs. State laws vary widely on requirements and limits.
Cost Implications:
Average annual cost: $50–$300, depending on state mandates and coverage limits.
States with high uninsured driver rates (e.g., 25%+ in Mississippi, Michigan) may see premiums exceed $400/year.
Stacking vs. Non-Stacking: Policies in some states (e.g., New York) allow stacking limits across multiple vehicles, increasing costs by $100–$300.
State Requirements:
Mandatory States: New Hampshire, Virginia, North Dakota (but may require proof of financial responsibility).
Optional States: Texas, California (but highly recommended due to high uninsured driver rates).
High-Limit Add-Ons: Increasing UM/UIM limits from $25,000 BI/$50,000 to $100,000/$300,000 adds $100–$250/year.
Medical Payments (MedPay) and Personal Injury Protection (PIP)
MedPay covers medical expenses for the policyholder and passengers, regardless of fault. PIP extends coverage to lost wages and rehabilitation costs, mandated in no-fault states (e.g., New York, Florida, Michigan).
Cost Implications:
MedPay: $50–$200/year for $1,000–$10,000 in coverage.
PIP: $200–$600/year in no-fault states, with higher limits (e.g., $100,000) adding $300–$800/year.
State-Specific Costs: Michigan’s PIP can cost $1,500+/year due to high medical inflation and unlimited lifetime benefits.
Key Differences:
MedPay: Covers only medical bills; optional in most states.
PIP: Covers medical, lost wages, and funeral costs; mandatory in no-fault states.
Deductibles: PIP often has $0 deductibles but may include $200–$500/year for higher limits.
Cost Comparison: Full Coverage vs. Minimum Liability Policies
Full coverage typically includes liability, collision, and comprehensive, while minimum liability policies cover only state-required limits. The disparity in costs reflects the trade-off between protection and affordability.
Coverage Type
Minimum Liability (State Required)
Full Coverage (Liability + Collision + Comprehensive)
No Liability Insurance States: New Hampshire (proof of financial responsibility required).
High Minimum Limits: New Jersey ($15,000 BI/$30,000 PD), Alaska ($50,000 BI/$100,000 PD).
Full Tort vs. Limited Tort States: Florida (no-fault, PIP required), Pennsylvania (limited tort restricts lawsuits).
Case Study: Identical Vehicles Insured Under Different Coverage Tiers
Scenario: Two 2022 Toyota Camry LE vehicles (same model, same driver profile, same location: Dallas, Texas) are insured under different coverage tiers.
Coverage Tier
Annual Premium
Deductibles
Out-of-Pocket Risk (Worst-Case Scenario)
Total Cost of Ownership (5-Year Estimate)
Minimum Liability (25/50/10)
$
Average Auto Insurance Costs by U.S. State and Key Influencing Factors
Auto insurance costs vary significantly across states due to differences in traffic density, state regulations, weather risks, and economic factors. The average annual premium in the U.S. ranges from under $800 in low-cost states to over $2,500 in high-cost regions. Florida, Michigan, and California consistently rank as outliers, driven by unique regulatory environments, litigation risks, and high repair costs. Below is a breakdown of state-specific trends and the underlying causes.
---
State-Specific Cost Variations and Their Primary Drivers
The following table highlights average annual auto insurance premiums by state (2023 data) and the key factors contributing to price disparities. States are categorized into quartiles for clarity.
State
Avg. Annual Premium
Primary Drivers of Cost
Michigan
$2,712
No-fault insurance system with mandatory personal injury protection (PIP), increasing administrative costs.
High frequency of fraudulent claims and litigation.
Strict liability laws requiring insurers to cover third-party damages regardless of fault.
Florida
$2,481
High population density and hurricane risks leading to frequent claims.
No-fault insurance system with limited bodily injury liability, encouraging lawsuits.
High repair costs due to older vehicles and lack of standardized parts pricing.
California
$1,708
High vehicle repair costs due to labor-intensive labor markets and specialized parts (e.g., luxury cars).
Urban congestion and high theft rates in cities like Los Angeles.
Regulatory caps on premium increases, forcing insurers to limit availability.
Ohio
$1,125
Competitive market with multiple insurers offering discounts.
Moderate traffic density and lower litigation rates.
North Dakota
$783
Low population density and minimal traffic congestion.
Fewer weather-related risks (e.g., no hurricanes, limited hailstorms).
State-mandated minimum coverage is among the lowest in the nation.
---
Impact of State Regulations on Insurance Pricing
State laws directly influence auto insurance costs by dictating coverage requirements, claim processes, and insurer behaviors. The following regulations have the most significant impact:
"State insurance laws create either a competitive marketplace or a monopolistic environment where consumers have little choice. No-fault states, for example, shift litigation costs to insurers, inflating premiums, while tort states allow for more direct compensation but may lead to higher legal expenses."
— National Association of Insurance Commissioners (NAIC) Report, 2022
No-Fault Laws: States like Florida, Michigan, and New York require insurers to cover medical expenses and lost wages regardless of fault, increasing administrative overhead. This often leads to higher premiums due to inflated claim costs.
Minimum Coverage Requirements: States with low minimum liability limits (e.g., Mississippi: 25/50/25) may see lower base premiums but expose drivers to higher out-of-pocket risks. Conversely, states like New Hampshire (no minimum requirements) allow insurers to set higher base rates.
Assignment of Benefits (AOB) Laws: Florida’s permissive AOB laws enable claimants to transfer insurance benefits to third parties (e.g., repair shops), leading to widespread fraud and premium spikes.
Insurer Market Share Caps: States like California restrict insurer market dominance, preventing price collusion but sometimes leading to reduced competition and higher rates when insurers exit the market.
Uninsured/Underinsured Motorist (UM/UIM) Coverage Mandates: States requiring UM/UIM coverage (e.g., Vermont) see higher premiums due to added protection costs, while optional states (e.g., Texas) may offer lower rates but higher risk exposure.
---
Urban vs. Suburban vs. Rural Pricing Within a Single State: Texas Example
Texas demonstrates stark pricing disparities based on location due to its diverse geography, traffic patterns, and crime rates. Below is a comparison of average annual premiums across three regions:
Region
Avg. Annual Premium
Key Factors Influencing Cost
Houston (Urban)
$1,850
High traffic congestion increasing accident risk.
Elevated theft and vandalism rates in certain neighborhoods.
Higher repair costs due to labor market demand.
Austin (Suburban)
$1,450
Moderate traffic but lower congestion than Houston.
Growing population leading to increased claim frequency.
Low population density reducing accident likelihood.
Limited repair shop availability may lower repair costs.
Lower crime rates and minimal traffic-related risks.
The urban-suburban-rural divide in Texas reflects broader national trends: urban areas pay 50–100% more than rural counterparts due to exposure risks, while suburban zones act as a midpoint influenced by infrastructure development.
---
States with the Most Competitive Auto Insurance Markets for Price Comparison Savings
Competitive markets—defined by low concentration among insurers, high price transparency, and consumer-friendly regulations—offer the greatest potential for savings through comparison shopping. The following states stand out for their favorable environments:
Market Characteristics: These states typically feature:
High insurer market share diversity (no single insurer controls >30%).
Up to 30% savings by switching insurers (high competition).
North Carolina
$1,025
State Farm (18%)
Geico (16%)
Allstate (14%)
Up to 25% savings with multi-policy discounts.
Virginia
$950
State Farm (19%)
Progressive (13%)
Farmers (11%)
Up to 20% savings via usage-based programs.
Iowa
$850
Farmers (22%)
State Farm (18%)
Allstate (15%)
Up to 28% savings due to low insurer concentration.
South Dakota
$790
State Farm (25%)
Farmers (15%)
Allstate (12%)
Up to 35% savings in rural areas.
---
Comprehensive List of Common Auto Insurance Discounts Categorized by Eligibility
Auto insurance discounts reduce premiums by rewarding policyholders for specific behaviors, affiliations, or vehicle features. These discounts vary by insurer but typically fall into broad categories based on eligibility criteria. Understanding these categories helps drivers identify applicable discounts and strategically apply them to lower costs. Below is a structured breakdown of the most common discounts, organized by eligibility type.
Insurers often combine multiple discounts, but eligibility and stacking rules differ. Some discounts may conflict (e.g., a safe driver discount might exclude high-risk drivers), while others require proof of qualification. Always verify with the provider to ensure discounts are applied correctly.
---
Discounts Based on Policy Bundling
Bundling discounts apply when combining multiple insurance policies (e.g., auto with home, renters, or life insurance) with the same provider. This reduces administrative costs for insurers and incentivizes customer loyalty.
Multi-Policy Discount:
Savings of 10%–25% for bundling auto with homeowners, renters, or umbrella insurance. Some insurers offer tiered discounts (e.g., 15% for two policies, 25% for three).
Example: A driver with auto and home insurance through the same company may save $300–$600 annually on auto premiums alone.
New Policy Discount:
First-time customers bundling multiple policies may receive a one-time discount (5%–10%) for the first policy year.
Loyalty Discount:
Long-term customers (5+ years) who bundle policies may qualify for additional loyalty-based savings (5%–10%) beyond standard bundling discounts.
---
Discounts for Safe Driving and Low Risk
Insurers reward drivers with clean records, defensive driving habits, or low accident frequencies. These discounts often require proof, such as a driving record or completion of a certified course.
Accident-Free Discount:
Drivers with no at-fault accidents in the past 3–5 years may receive a 5%–20% discount. Some insurers extend this to 3–5 years of claim-free history.
Note: At-fault accidents may void the discount for 3–6 years, depending on the insurer.
Safe Driver Discount:
Policyholders with a clean driving record (no moving violations in 3–5 years) qualify for discounts ranging from 5% to 30%. Severity of violations (e.g., speeding vs. DUI) affects eligibility.
Defensive Driving Course Discount:
Completing an approved defensive driving or driver safety course (e.g., through local departments of motor vehicles) can yield 5%–15% off premiums. Some states mandate these courses for high-risk drivers.
Example: Courses like the National Safety Council’s Defensive Driving Course are widely accepted.
Low Mileage Discount:
Drivers who log fewer than 7,500–10,000 miles annually may qualify for discounts of 5%–15%. Usage-based programs (e.g., telematics) often verify mileage.
Anti-Theft Device Discount:
Vehicles equipped with approved anti-theft systems (e.g., GPS tracking, immobilizers) receive 5%–20% off. Common systems include LoJack or OnStar.
---
Discounts for Vehicle Features and Usage
Discounts in this category depend on the car’s make, model, safety features, or usage patterns. Newer or well-equipped vehicles often qualify for higher savings.
Safety Feature Discount:
Cars with advanced safety tech (e.g., automatic braking, lane-keep assist, airbag systems) may earn 5%–25% off. Examples include vehicles with IIHS Top Safety Pick ratings.
Anti-Lock Brakes (ABS) Discount:
Vehicles with ABS systems qualify for 5%–10% off. This discount is common for older models where ABS was a luxury feature.
Hybrid/Electric Vehicle Discount:
Eco-friendly vehicles (e.g., Toyota Prius, Tesla Model 3) may receive 5%–15% off due to lower accident rates and reduced environmental impact.
Some insurers offer additional discounts for plug-in hybrids or vehicles with high MPG ratings.
Pay-As-You-Drive (PAYD) Discount:
Usage-based programs (e.g., Progressive’s Snapshot) track driving habits and offer discounts to low-mileage or safe drivers (10%–30%).
Good Student Discount:
Full-time students with a GPA of 3.0 or higher (or equivalent honors) may qualify for 10%–25% off. Some insurers extend this to part-time students or those in vocational programs.
---
Discounts for Professional and Affiliation-Based Eligibility
Certain professions, affiliations, or lifestyles qualify for niche discounts. These often require proof of membership, employment, or specific lifestyle choices.
Military and Veterans Discount:
Active-duty military, veterans, and their families may receive 5%–15% off. Some insurers partner with organizations like USAA (exclusive to military) or offer discounts through Veterans Affairs programs.
Good Student Discount:
Full-time students with a GPA of 3.0 or higher (or equivalent honors) may qualify for 10%–25% off. Some insurers extend this to part-time students or those in vocational programs.
Affinity Group Discounts:
Members of specific organizations (e.g., alumni associations, credit unions, or professional groups) may receive 5%–10% off. Examples include discounts for AAA members or employees of partner companies.
Senior Discount:
Drivers aged 55+ may qualify for discounts through retirement communities or senior-specific programs (e.g., AARP partnerships). Some insurers offer discounts for mature drivers with low claim histories.
Homeowner Discount:
Policyholders who own (rather than rent) their home may receive 5%–10% off auto insurance. This reflects lower risk profiles among homeowners.
---
Niche and Regional Discounts
Some discounts are tied to specific regions, occupations, or unique circumstances. These are less common but can yield significant savings for eligible drivers.
Low Risk Occupation Discount:
Professions deemed low-risk (e.g., teachers, nurses, engineers) may qualify for 5%–10% off. Insurers justify this based on lower accident rates among certain careers.
College Student Away-at-School Discount:
Students attending college more than 100 miles from home may receive 10%–20% off if the car is stored during the school year. Some insurers require proof of enrollment and reduced usage.
Paperless Discount:
Opting for electronic statements or policy documents may save 5%–10%. This discount incentivizes digital adoption.
Early Shopper Discount:
Purchasing or renewing a policy early (e.g., 30–60 days before expiration) can yield 5%–10% off. This reduces administrative costs for insurers.
State-Specific Discounts:
Some states offer unique discounts, such as:
California: Discounts for drivers with California Low Cost Auto Insurance Program (CLCA) eligibility.
Florida: Discounts for drivers with Florida Resident Discount or participation in the Florida Auto Insurance Affordability Program.
New York: Discounts for drivers with New York’s No-Fault Insurance Discount for low claim frequencies.
Telematics and Usage-Based Insurance (UBI) Programs in Auto Insurance Pricing
Traditional auto insurance pricing relies on broad demographic factors such as age, location, driving history, and vehicle type. However, telematics and usage-based insurance (UBI) programs introduce a shift toward real-time behavioral data to personalize premiums. These programs collect granular driving metrics, enabling insurers to reward safer behaviors and penalize risky ones, fundamentally altering how risk is assessed and priced.
Telematics-based pricing replaces static risk assumptions with dynamic, driver-specific data, creating a more equitable and responsive insurance model.
Data Collection Methods in Telematics
Telematics systems employ a combination of embedded devices (OBD-II ports, smartphones, or dedicated dashboards) and telecommunications networks to gather driving behavior data. Key metrics include:
Speed and Acceleration: Hard braking, rapid acceleration, and excessive speed are flagged as high-risk behaviors. For example, a driver consistently exceeding speed limits by 10 mph may face higher premiums, while smooth acceleration patterns could qualify for discounts.
Distance Traveled: Pay-per-mile programs (e.g., for low-mileage drivers) reduce premiums for those who drive infrequently, such as retirees or remote workers. Data is collected via GPS or odometer readings, with some insurers capping mileage at 15,000–20,000 miles annually for discounted rates.
Time of Day and Route: Nighttime driving or frequent trips on high-risk routes (e.g., urban areas with heavy traffic or poor road conditions) trigger higher risk scores. Some insurers offer discounts for avoiding peak commute hours or using designated safe routes.
Phone and Distraction Detection: Usage-based programs monitor phone usage while driving, with hands-free calls often permitted but texting or browsing triggering penalties. Bluetooth connectivity logs can distinguish between safe and unsafe device interactions.
Vehicle Health and Maintenance: Telematics can track engine diagnostics, tire pressure, and maintenance alerts. Insurers may offer incentives for regular servicing, as neglected vehicle upkeep correlates with higher claim frequencies.
Impact on Traditional Pricing Models
The integration of telematics disrupts traditional pricing by introducing three key changes:
Shift from Group to Individual Risk Assessment: Instead of grouping drivers by broad categories (e.g., "all 25-year-olds in City X"), insurers evaluate each policyholder’s unique driving patterns. A 25-year-old with a clean telematics record may pay less than a 50-year-old with erratic braking habits.
Dynamic Premium Adjustments: Some UBI programs allow premiums to fluctuate based on monthly or quarterly driving behavior. For instance, a driver who improves their speeding habits over three months may see their premium decrease retroactively.
Increased Transparency and Incentives: Drivers receive real-time feedback via mobile apps, showing how their behaviors affect their risk score. This gamification encourages safer habits, reducing overall claim costs for insurers while lowering premiums for compliant drivers.
Privacy and Ethical Considerations
While telematics enhance accuracy, they raise concerns about data privacy and consent. Regulatory frameworks, such as the California Consumer Privacy Act (CCPA) and GDPR in the EU, require insurers to:
Disclose data collection methods upfront and obtain explicit consent.
Allow policyholders to opt out of telematics programs without penalty.
Anonymize or aggregate data to prevent misuse or discrimination (e.g., denying coverage based on non-driving factors like location demographics).
Insurers mitigate risks by:
Using on-device processing to minimize data transmission.
Offering data-sharing controls, such as pausing tracking during specific hours.
Providing clear explanations of how data influences pricing.
Top 5 Mistakes Consumers Make When Comparing Auto Insurance Prices
Many consumers approach auto insurance comparisons with good intentions but often overlook critical details that lead to financial pitfalls or inadequate protection. These errors range from incomplete applications to dismissing policy exclusions, which can result in unexpected costs or denied claims. Understanding these common mistakes helps consumers make informed decisions, ensuring they secure the best coverage at a fair price without hidden drawbacks.
"An incomplete application or overlooked exclusions can void coverage when it matters most."
Incomplete or Inaccurate Applications
Submitting incomplete or inaccurate information on an auto insurance application can lead to policy rejection or inflated premiums. Consumers frequently omit details such as:
Driving history discrepancies (e.g., unpaid tickets or accidents not disclosed).
A policy may appear affordable until a claim is denied due to an unnoticed exclusion.
Focusing Solely on Monthly Premiums
Low monthly premiums are attractive, but they often come with trade-offs such as:
High deductibles (e.g., $1,000 vs. $500), increasing out-of-pocket costs.
Limited coverage (e.g., state-minimum liability instead of full coverage).
Short-term discounts (e.g., first-year incentives that disappear upon renewal).
Consumers should evaluate the total cost of ownership, including deductibles, claim reimbursement limits, and long-term savings potential.
Assuming All Insurers Use the Same Rating Factors
Insurance companies weight risk factors differently, leading to variations in pricing for the same driver. Key discrepancies include:
Credit score impact (some states ban this, while others use it heavily).
Usage-based pricing (telematics programs may lower premiums for safe drivers).
Loyalty discounts (long-term customers often receive better rates).
Comparing quotes without understanding these nuances can result in overpaying or underinsuring.
Neglecting to Review the Full Policy Before Purchase
Some consumers sign up for a policy based on a quote alone, only to discover unfavorable terms later. Critical elements to review include:
Claim filing procedures (e.g., mandatory police reports for accidents).
Sublimation clauses (allowing the insurer to take over a claim from another policy).
Assignment of benefits (restrictions on who can file a claim).
A rushed decision may lead to surprises during a claim, such as delayed payouts or denied coverage.
Case Study: A Driver’s 30% Savings After Switching Insurers
A 32-year-old professional with a clean driving record and moderate annual mileage faced rising premiums from their long-time insurer. By systematically comparing quotes, adjusting coverage limits, and negotiating with multiple providers, they reduced their annual premium by 30% without compromising protection. This case demonstrates how proactive comparison and strategic adjustments can yield significant savings while maintaining adequate coverage.
Driver Profile and Initial Conditions
The driver, Alex Carter, had the following baseline details:
Age: 32, male
Driving Record: No at-fault accidents or violations in the past 5 years
Annual Mileage: 12,000 miles (primarily commuting and occasional road trips)
Vehicle: 2018 Honda Civic (primary driver, valued at $18,000)
Current Insurer: State Farm (premium: $1,250/year)
Credit Score: 740 (considered "good" by most insurers)
Residence: Suburban area in Texas with moderate crime rates
Coverage Changes and Negotiation Tactics
Alex’s strategy involved three key phases: comparison, optimization, and negotiation. Each step required research and direct engagement with insurers.
Key Insight: Insurers often adjust rates based on perceived risk, bundling options, and regional pricing models. A driver’s willingness to compare multiple quotes—especially from non-traditional providers—can unlock discounts not offered by legacy insurers.
Phase 1: Price Comparison Across Providers
Used online tools (e.g., independent comparison platforms) to generate quotes from 15 insurers, including major brands and regional specialists.
Identified three competitive quotes below $900/year, with one from GEICO at $850/year and another from Progressive at $890/year.
Noted that State Farm’s premium had increased by 12% over the past 2 years despite no changes in driving behavior.
Phase 2: Coverage Optimization
Increased the collision deductible from $500 to $1,000, reducing the GEICO quote by $70/year.
Dropped uninsured motorist coverage (a state-optional coverage) after verifying Texas’ minimum liability limits were sufficient for their risk profile.
Bundled homeowners insurance with GEICO (saving an additional $120/year) by switching their existing policy.
Phase 3: Direct Negotiation
Called GEICO’s customer service to inquire about loyalty discounts, receiving a one-time 5% reduction for switching from State Farm.
Mentioned a competing quote from Progressive, prompting GEICO to match it with an additional $50/year discount.
Requested a final review, highlighting Alex’s clean record and low mileage, which led to a $30/year reduction for "safe driver" incentives.
Final Outcome and Lessons Learned
After switching to GEICO with adjusted coverage, Alex’s annual premium dropped from $1,250 to $820, a 34.4% savings. The breakdown of savings was as follows:
Source of Savings
Amount Saved (Yearly)
Lower base rate from GEICO
$380
Increased collision deductible
$70
Dropped uninsured motorist coverage
$40
Bundling discount
$120
Loyalty and competitive discounts
$80
Critical Takeaway: Drivers should:
Compare quotes annually, as insurers frequently adjust rates.
Negotiate directly with agents, referencing competing offers.
Adjust deductibles and optional coverages based on personal risk tolerance.
Bundle policies to maximize discounts without sacrificing essential protections.
Legal Rights of Consumers in Auto Insurance Price Comparison and Data Privacy Protections
Consumers comparing auto insurance prices are protected under a framework of federal and state laws designed to ensure fairness, transparency, and privacy. These rights govern how insurers collect, use, and disclose personal data while requiring clear communication of policy terms. Violations may result in penalties, regulatory action, or legal recourse for affected individuals.
Federal laws such as the Gramm-Leach-Bliley Act (GLBA) and the California Consumer Privacy Act (CCPA) establish baseline protections for personal information collected during insurance comparisons. State-specific regulations, such as the New York Insurance Law or Texas Insurance Code, further refine these rights, often imposing stricter requirements on insurers regarding data handling and pricing transparency.
Federal and State Privacy Laws Governing Auto Insurance Data
Federal laws create a foundational layer of consumer protections, while state laws often supplement or expand these safeguards to address local concerns.
"Consumers have the right to know what data insurers collect, how it is used, and who it is shared with during the comparison process. Transparency in pricing algorithms and underwriting criteria is essential to prevent discriminatory or predatory practices."
Gramm-Leach-Bliley Act (GLBA):
Requires financial institutions (including insurers) to disclose their information-sharing practices and provide consumers with opt-out rights for non-affiliated third-party disclosures. Insurers must maintain reasonable security measures to protect nonpublic personal information (NPI) collected during quotes.
Fair Credit Reporting Act (FCRA):
Regulates how insurers use credit-based insurance scores (CIS) when determining premiums. Consumers can dispute inaccuracies in their credit reports, which may indirectly affect insurance pricing. Insurers must provide clear notice if credit history influences underwriting decisions.
Health Insurance Portability and Accountability Act (HIPAA) (Limited Relevance):
While primarily health-focused, HIPAA’s privacy rules may apply if insurers handle medical data (e.g., for high-risk drivers). Consumers can request restrictions on how such data is used.
State-Specific Data Privacy and Insurance Transparency Laws
Many states have enacted laws to enhance consumer protections beyond federal standards, particularly in data privacy and pricing transparency. These laws often mandate additional disclosures, limit discriminatory practices, and impose penalties for non-compliance.
California:
The California Insurance Code § 790.14 prohibits insurers from using certain personal characteristics (e.g., gender, marital status) to discriminate in pricing unless justified by actuarial data. The CCPA grants consumers the right to access, delete, or opt out of the sale of their personal data, including during insurance comparisons.
New York:
The New York Insurance Law § 2324 requires insurers to provide clear explanations of how premiums are calculated and prohibits unfair discrimination based on protected classes. The New York State Department of Financial Services (NYDFS) enforces strict cybersecurity regulations (23 NYCRR Part 500) for insurers handling consumer data.
Texas:
The Texas Insurance Code § 501.153 mandates that insurers disclose all factors used in rate calculations, including credit history if applied. Consumers can request a free copy of their insurance score and challenge inaccuracies.
Massachusetts:
The Massachusetts Fair Premium Act bans the use of credit scores in personal auto insurance pricing, ensuring that premiums are based solely on driving record and other non-discriminatory factors.
Hawaii:
The Hawaii Insurance Code § 431:10A-138 prohibits insurers from using gender as a rating factor for personal auto insurance, aligning with broader anti-discrimination principles.
Consumer Rights During the Insurance Comparison Process
Consumers engaging in price comparisons have specific rights to ensure fair treatment and access to accurate information. These rights include the ability to challenge pricing decisions, request explanations for quotes, and report violations.
Right to Fair Underwriting:
Insurers must provide a declaration page or policy summary outlining all coverage terms, exclusions, and premium breakdowns. Consumers can request clarifications on how factors (e.g., driving history, vehicle type) affect pricing.
Right to Access Personal Data:
Under laws like the CCPA or Virginia Consumer Data Protection Act (VCDPA), consumers can request a copy of all personal data collected during comparisons, including:
Driving records obtained from state DMVs.
Credit reports or scores used for pricing.
Any third-party data (e.g., telematics, location history).
Right to Dispute Inaccuracies:
If an insurer uses outdated or incorrect data (e.g., a past traffic violation no longer on record), consumers can dispute the information. Insurers must investigate and correct errors within a specified timeframe (typically 30–45 days).
Right to Opt Out of Data Sharing:
Consumers can prohibit insurers from sharing personal data with non-affiliated third parties (e.g., marketing firms) under GLBA or state laws like California’s Opt-Out Provisions.
Right to File Complaints:
Violations of insurance laws can be reported to:
State insurance departments (e.g., California Department of Insurance, Texas Department of Insurance).
Federal agencies like the Consumer Financial Protection Bureau (CFPB) for credit-related disputes.
Regional Better Business Bureau (BBB) or National Association of Insurance Commissioners (NAIC) for mediation.
Penalties for Insurers Violating Consumer Rights
Non-compliance with privacy laws or unfair pricing practices can result in financial penalties, regulatory sanctions, or legal action. State insurance departments and federal agencies actively monitor for violations.
Violation Type
Potential Penalties
Enforcing Authority
Unfair Discrimination in Pricing
Fines up to $10,000 per violation (varies by state); mandatory rate adjustments; license suspension.
State Insurance Commissioner
Failure to Disclose Policy Terms
Civil penalties of $1,000–$5,000 per violation; mandatory corrective disclosures.
State Insurance Department
Data Breach or Privacy Violations
Fines up to $750 per affected consumer (CCPA); regulatory orders to implement security measures.
State Attorney General / CFPB
Misrepresentation in Quotes
Restitution to consumers; revocation of insurance licenses; criminal charges in cases of fraud.
State Insurance Commissioner / District Attorney
Emerging Technologies and Their Impact on Auto Insurance Pricing Models Over the Next Decade
Emerging technologies such as autonomous vehicles, electric vehicles (EVs), and advanced telematics are poised to fundamentally alter how auto insurance pricing models are structured. These innovations introduce new variables—such as vehicle safety ratings, energy source risks, and real-time driver behavior—that insurers will integrate into risk assessment frameworks. The shift toward data-driven underwriting and predictive analytics will accelerate, potentially reducing premiums for low-risk technologies while increasing costs for high-risk applications. However, the transition will not be uniform; regional adoption rates, regulatory hurdles, and consumer acceptance will dictate the pace of change.
The evolution of insurance pricing will depend on three key technological trends: autonomous driving systems, electric vehicle infrastructure, and connected car ecosystems. Each of these will interact with traditional underwriting factors (e.g., driver history, location) to create hybrid pricing models. Insurers may adopt tiered pricing based on vehicle autonomy levels, battery degradation risks, or cybersecurity vulnerabilities in connected systems. Below, the expected impacts of these technologies are analyzed in detail.
---
Autonomous Vehicles and the Decline of Driver-Related Risk
Autonomous vehicles (AVs) are projected to reduce accident rates by up to 90% within the next decade, primarily by eliminating human error—currently responsible for 94% of crashes. This shift will force insurers to transition from driver-centric pricing to vehicle-centric models, where premiums are determined by:
Software update cycles (frequent patches may lower risk over time).
Geofencing and urban vs. highway usage (higher autonomy in controlled environments).
Insurance premiums for fully autonomous vehicles could drop by 30–50% compared to traditional cars, but liability questions—such as who is at fault in a mixed-traffic accident—will complicate pricing structures.
Key Challenges:
Liability ambiguity: Insurers may face lawsuits if AVs cause harm due to software flaws, leading to higher reserves for legal exposure.
Cybersecurity risks: Hacking or ransomware attacks on AV systems could introduce new coverage categories (e.g., "digital theft" or "remote tampering").
Gradual adoption: Early adopters of AVs may pay higher premiums due to limited historical data, while mass-market adoption (expected post-2030) will stabilize pricing.
---
Electric Vehicles and New Risk Profiles
The rise of electric vehicles (EVs) introduces distinct risk factors that traditional insurers are only beginning to address. Unlike internal combustion engine (ICE) vehicles, EVs present:
Lower mechanical failure rates (fewer moving parts) but higher battery-related risks (fire hazards, degradation over time).
Regional energy grid dependencies (e.g., areas with unreliable power may see higher claims for battery damage during charging).
A 2023 study by the National Fire Protection Association found that EV fires are 20% more likely to cause property damage than ICE vehicle fires, though they occur less frequently.
Pricing Adjustments Expected:
Battery warranty coverage: Insurers may partner with manufacturers to offer deductible waivers for battery replacements under warranty.
Charging location risk: Premiums could vary based on whether a vehicle is charged at home (lower risk) or at public stations (higher risk of theft/damage).
Resale value depreciation: EVs may depreciate faster due to battery degradation, leading insurers to adjust actual cash value (ACV) payouts more frequently.
---
Connected Cars and Dynamic Pricing Models
The proliferation of telematics and IoT-enabled vehicles allows insurers to shift from static pricing to real-time, usage-based models. Key developments include:
Pay-as-you-drive (PAYD) and pay-how-you-drive (PHYD): Premiums fluctuate based on mileage, speed, braking patterns, and even road conditions (e.g., higher rates in flood zones).
Predictive maintenance alerts: Insurers may offer discounts for vehicles with real-time diagnostics that prevent accidents (e.g., tire pressure monitoring, collision avoidance system alerts).
Insurtech partnerships: Companies like Oracle or IBM are developing AI-driven platforms that analyze traffic patterns, weather, and driver biometrics to adjust rates dynamically.
Dynamic pricing could reduce overall premiums by 15–25% for safe drivers but may increase costs for high-risk behaviors (e.g., late-night driving in urban areas).
Implementation Barriers:
Consumer privacy concerns: 53% of drivers surveyed in 2023 expressed discomfort with always-on telematics tracking, potentially limiting adoption.
Data standardization: Insurers rely on proprietary telematics data from automakers (e.g., Tesla, GM), creating fragmentation in pricing algorithms.
Regulatory scrutiny: Some states (e.g., California) are exploring caps on dynamic pricing surcharges to prevent exploitation of low-income drivers.
---
Hybrid Pricing Models: Traditional vs. Future Approaches
The transition to technology-driven pricing will result in a coexistence of traditional and futuristic models for the next 5–10 years. Below is a comparative table outlining their expected adoption rates and key differences:
Federal AI oversight, GDPR-like data privacy laws, cybersecurity audits
50% traditional, 50% emerging regulations
Consumer Transparency
Limited access to underwriting data
Real-time dashboards showing risk factors and savings opportunities
70% opaque, 30% transparent
Note: Adoption rates assume moderate regulatory support and 50% consumer acceptance of tracking-based models. Slower adoption is expected in regions with strict privacy laws (e.g., EU, parts of Asia).
---
Sequential Guide for Comparing and Finalizing Auto Insurance Policies
Auto insurance comparison requires a structured approach to ensure accuracy, cost-effectiveness, and compliance with coverage needs. This guide outlines a step-by-step process, from gathering personal data to finalizing a policy, while integrating tools for documentation, evaluation, and decision-making.
The process involves five key phases: preparation, research, comparison, evaluation, and finalization. Each phase builds on the previous one, ensuring no critical detail is overlooked. Below is a detailed breakdown of each step, including templates, scripts, and analytical tools to streamline the workflow.
---
Phase 1: Gathering Personal and Vehicle Data
Accurate data forms the foundation of insurance quotes. Incomplete or incorrect information can lead to mispricing, coverage gaps, or policy denials. Collect the following details systematically to avoid errors:
Driver Information:
Full legal name, date of birth, and driver’s license number.
Driving history, including traffic violations, accidents, and claims filed in the past 3–5 years.
Credit score (if applicable in your state; some insurers use it for risk assessment).
Annual mileage and primary use of the vehicle (commute, pleasure, business).
Vehicle Details:
Make, model, year, and VIN (Vehicle Identification Number).
Purchase date and whether the vehicle is financed or owned outright.
Current safety features (e.g., anti-lock brakes, airbags, backup cameras, telematics).
Primary use (e.g., daily driver, occasional use, rideshare if applicable).
Household and Location Data:
Primary residence address (zip code impacts premiums due to theft/accident rates).
Garaging location (if different from residence).
Number of licensed drivers in the household and their ages.
Security measures at home (e.g., gated community, alarm system).
Tip: Use your vehicle’s registration or title document as a reference for the VIN and purchase details. For driving history, request a Motor Vehicle Report (MVR) from your state’s DMV or a third-party provider like LexisNexis.
---
Phase 2: Researching Insurers and Coverage Options
Not all insurers offer the same coverage types, discounts, or pricing structures. Research should focus on identifying providers that match your needs while ensuring financial stability and customer service quality.
Identify Potential Insurers:
National insurers (e.g., State Farm, Progressive, Allstate) often provide broad coverage options.
Regional or local insurers may offer competitive rates for specific areas or driver profiles.
Specialty insurers (e.g., for high-risk drivers, classic cars, or rideshare services).
Consideration: Check insurer ratings from sources like J.D. Power or the National Association of Insurance Commissioners (NAIC) for claims satisfaction and financial strength.
Understand Coverage Types:
Liability: Mandatory in most states; covers bodily injury and property damage to others.
Collision: Pays for damage to your vehicle from accidents.
Medical Payments (MedPay) or Personal Injury Protection (PIP): Covers medical expenses for you and passengers.
Uninsured/Underinsured Motorist (UM/UIM): Protects you if the at-fault driver lacks sufficient coverage.
Gaps Coverage: For financed vehicles, ensures payouts exceed loan balances.
Determine Coverage Limits:
State minimum limits (e.g., 25/50/25 in many states: $25K per person/$50K per accident for bodily injury, $25K for property damage).
Recommended limits (e.g., 100/300/100 or higher for assets protection).
Deductible amounts ($500, $1,000, or higher; higher deductibles lower premiums but increase out-of-pocket costs).
---
Phase 3: Requesting and Documenting Quotes
Obtaining quotes requires clear communication with insurers. Use the template below to standardize the process and ensure comparability. The template includes fields for tracking insurer responses, follow-ups, and key details.
Insurer Name
Quote Date
Premium (Annual)
Coverage Details
Deductibles
Discounts Applied
Out-of-Pocket Max
Customer Service Rating
Follow-Up Action
Notes
$
Liability: X/X/X
Collision: Yes/No
Comprehensive: Yes/No
UM/UIM: Yes/No
Collision: $
Comprehensive: $
Multi-policy: Yes/No
Safe Driver: Yes/No
Low Mileage: Yes/No
Telematics: Yes/No
$
/5 (J.D. Power)
Call/Email/Review
Template Notes:
Use the "Notes" column to record insurer responses to questions (e.g., "Does this quote include a rideshare discount?").
For discounts, specify the type and savings amount (e.g., "Safe Driver: -$150").
Track follow-up actions to ensure no quote is overlooked.
---
Script for Reaching Out to Insurers
Clarifications may be needed to compare quotes accurately. Below are sample scripts for emails and calls, focusing on key details that affect pricing.
Email Template:
    Subject: Request for Clarification on Auto Insurance Quote #XXXX

    Dear [Insurer Representative],

    Thank you for providing the quote for [Policyholder Name] on [Quote Date]. To ensure an accurate comparison with other providers, could you please clarify the following:

    1. Are the premiums quoted based on a [6-month/annual] payment plan?
    2. What specific discounts are applied, and are they guaranteed for the policy term?
    3. Does the quote include any fees (e.g., administrative, state taxes) not listed separately?
    4. What is the process for filing a claim, and are there any exclusions not mentioned in the quote?
    5. Are there any penalties for early cancellation or non-renewal?

    Additionally, I’d like to confirm the coverage limits for:
Collision and Comprehensive deductibles: [$XXX/$XXX]
Please provide this information by [Deadline Date] to assist in my decision-making process. Thank you for your assistance.
Best regards,
[Your Full Name]
[Your Contact Information]
Phone Call Script:
    "Hello, I’m calling regarding the auto insurance quote provided to [Policyholder Name] on [Quote Date]. I have a few questions to ensure I understand the coverage and pricing fully:

    1. Can you confirm the annual premium is [XXX] before taxes and fees?
    2. Which discounts are included in this quote, and are they renewable annually?
    3. What is the claims process like, and how quickly can I expect a resolution for a collision claim?
    4. Are there any restrictions on usage (e.g., rideshare, commercial use) that would void the policy?
    5. If I bundle this with my home insurance, what additional savings would I receive?

    I’d also like to verify the deductibles for collision and comprehensive—are they both set at [$XXX]?"
---
Phase 4: Evaluating the Total Cost of Ownership
Premiums represent only a portion of the financial impact of an auto insurance policy. Hidden costs, such as deductibles, out-of-pocket maximums, and claim reimbursement delays, can significantly affect affordability. Use the following checklist to assess the true cost:
Premium Structure:
Annual vs. monthly payments (some insurers charge fees for monthly plans).
Payment plan penalties (e.g., late fees, interest on installments).
Out-of-Pocket Expenses:
Deductible amounts for collision and comprehensive claims.
Out-of-pocket maximum (if applicable, the most you’ll pay per claim or year).
Co-pays for towing, rental cars,
Creating Visual Comparisons of Auto Insurance Premiums by State Using Bar Charts
Auto insurance premiums vary significantly across states due to differences in traffic laws, population density, accident rates, and regulatory environments. A bar chart effectively communicates these variations, allowing consumers and analysts to quickly identify states with the highest or lowest average costs. Tools like Excel, Google Sheets, and open-source software provide intuitive ways to generate such visualizations with minimal technical expertise.
The process involves collecting state-specific premium data, organizing it in a structured format, and applying chart customization techniques to ensure clarity and readability. Below are the steps to create a bar chart in Excel or Google Sheets, including data preparation, formatting, and design best practices.
Data Collection and Preparation
To create an accurate bar chart, reliable data on average auto insurance premiums by state is required. Sources may include industry reports, government databases, or insurer filings. Ensure the dataset includes:
State names: List all 50 states and the District of Columbia for comprehensive coverage.
Average annual premiums: Use the most recent data available, typically from the past 1–2 years. Example values (hypothetical for illustration):
Data source attribution: Note the origin of the data (e.g., "NAIC 2023 Auto Insurance Report") to maintain transparency.
Organizing Data in Excel or Google Sheets
Structured data simplifies chart creation. Use two columns:
Column A: State Names: Alphabetical or regional grouping (e.g., Northeast, Midwest) for logical sorting.
Column B: Average Premiums: Numerical values corresponding to each state.
Example table structure:
State
Average Annual Premium ($)
Alabama
950
California
1200
Florida
1800
Michigan
1900
Creating the Bar Chart in Excel
Excel’s built-in chart tools automate the visualization process. Follow these steps:
Select the data range (including headers).
Go to the Insert tab and choose Bar Chart > Clustered Bar or Stacked Bar (clustered is preferred for direct comparisons).
Customize the chart:
Add Chart Title: "Average Annual Auto Insurance Premiums by State (2023)."
Label the X-axis as "State" and the Y-axis as "Premium ($)."
Adjust axis scaling to start at 0 to avoid misleading visuals (e.g., truncating values).
Use data labels to display exact premium values above each bar.
Apply a color scheme that ensures accessibility (e.g., avoid red-green contrasts for colorblind users).
Sort states by premium (ascending or descending) for clearer trends. Use the Sort & Filter tool in Excel.
Export the chart as an image (PNG or SVG) for reports or presentations.
Creating the Bar Chart in Google Sheets
Google Sheets follows a similar workflow but with slight interface differences:
Highlight the data range.
Click Insert > Chart. Google Sheets will auto-generate a bar chart.
Customize via the Customize tab:
Edit the Chart Title and axis labels.
Enable Data Labels under Series.
Adjust Colors in the Customize > Background section.
Use the Sort Rows option to reorder states by premium.
Download the chart as a high-resolution image via File > Download > PNG.
Design Best Practices for Bar Charts
A well-designed bar chart enhances readability and impact. Apply these principles:
Consistency in scaling: Ensure all bars represent the same range (e.g., $0 to $2,500) to avoid distorting comparisons.
Minimalist color use: Limit colors to 3–5 shades to prevent visual clutter. Use a palette tool like Adobe Color or Google’s Material Design palette.
Annotations for outliers: Highlight states with premiums significantly above or below the national average (e.g., Michigan’s no-fault system drives up costs).
Legend placement: Position the legend outside the chart area if space is limited, or use labels directly on bars.
Responsive sizing: Test the chart at different resolutions (e.g., 800x600px) to ensure bars remain legible.
Steps to File a Complaint with a State Insurance Department for Inaccurate Price Comparisons
When an insurer provides misleading or inaccurate auto insurance price comparisons, consumers may experience financial losses or misguided purchasing decisions. State insurance departments oversee insurer compliance with regulations, ensuring transparency in pricing and advertising. Filing a complaint involves clear documentation, adherence to deadlines, and structured communication to maximize the likelihood of resolution.
The process begins with gathering evidence of the discrepancy, followed by submission to the state insurance regulator. Each state maintains its own complaint procedures, but most require written documentation, proof of the error, and a timeline of events. Below are the structured steps to follow, along with key considerations for each phase.
Gathering Evidence of the Inaccurate Comparison
Before filing a complaint, consumers must compile proof that the insurer’s price comparison was incorrect. This evidence serves as the foundation for the complaint and strengthens its validity. Inaccuracies may include:
Mismatched coverage details between the advertised price and the final policy terms.
Incorrect application of discounts (e.g., bundling, safe driver, or loyalty discounts).
Discrepancies in deductible amounts or premiums after policy issuance.
Misrepresentation of competitor prices or policy features.
Changes in pricing after the initial quote was provided.
Documentation should include:
Email or digital correspondence with the insurer containing the original quote.
Policy documents or confirmation letters outlining the final terms.
Screen captures of online price comparison tools or advertisements.
Written records of phone conversations (e.g., call summaries, timestamps).
Any internal notes or follow-up communications referencing the error.
Consumers should also note the exact nature of the inaccuracy, such as whether the premium was understated, coverage was misrepresented, or discounts were improperly applied. This specificity aids regulators in assessing the complaint’s validity.
Identifying the Correct State Insurance Department
Complaints must be filed with the insurance regulator of the state where the policy was purchased or where the insurer operates. Each state has its own department, often referred to as the "Department of Insurance" or "Office of the Insurance Commissioner." For example:
California: California Department of Insurance (CDI)
Texas: Texas Department of Insurance (TDI)
New York: New York State Department of Financial Services (DFS)
Florida: Florida Office of Insurance Regulation (OIR)
Illinois: Illinois Department of Insurance
Consumers can locate their state’s insurance department by searching "[State Name] insurance department complaint filing" or visiting the National Association of Insurance Commissioners (NAIC) website for a directory of state contacts. The NAIC also provides templates and guidance on the complaint process.
Submitting the Complaint
Most state insurance departments accept complaints via:
Online complaint forms (preferred for speed and tracking).
Mail or fax (with a signed, dated letter and supporting documents).
In-person submission (less common, but some departments offer this option).
When submitting, include:
A clear, concise description of the issue, including dates, names of representatives, and policy numbers.
Copies of all relevant documents (originals may be requested later).
Contact information for follow-up communication.
A request for acknowledgment of receipt (some departments provide a reference number).
Deadlines vary by state but typically range from 30 to 90 days from the date of the error’s discovery. Some states require complaints to be filed within one year of the incident. Consumers should check their state’s specific timeline to avoid delays.
Follow-Up and Resolution Process
After submission, the state insurance department will:
Assign a case number and notify the consumer of the next steps.
Contact the insurer for an official response or investigation.
Request additional documentation if needed.
Mediate between the consumer and insurer to resolve the dispute.
The timeline for resolution varies but often takes 30 to 120 days, depending on the complexity of the case. If the complaint is upheld, the insurer may be required to:
Adjust the policy to reflect accurate pricing.
Refund overcharges or underpayments.
Issue a corrected quote or rebate for misrepresented discounts.
Implement corrective actions to prevent future inaccuracies.
Consumers should monitor their email or mail for updates and respond promptly to any requests for information.
Escalation Options if the Complaint is Denied or Ignored
If the state insurance department fails to resolve the issue within the expected timeline or denies the complaint without justification, consumers have additional avenues for recourse:
Appeal to a Higher Authority: Some states allow appeals to the state’s insurance commissioner or a consumer affairs division.
File with the NAIC: The NAIC’s Consumer Information Source can assist in escalating unresolved complaints to the insurer’s home state regulator.
Small Claims Court: For financial disputes under a certain threshold (typically $5,000–$15,000, depending on the state), consumers may sue the insurer for damages.
Better Business Bureau (BBB): While the BBB does not resolve insurance disputes, it can mediate complaints and provide public pressure on the insurer.
Legal Action: Consulting an attorney specializing in insurance law may be necessary for complex or high-stakes cases.
Consumers should document all interactions and deadlines to strengthen their position in escalation efforts.
Key Considerations for a Successful Complaint
To maximize the chances of a favorable outcome, consumers should:
Act promptly—delays may weaken the complaint’s validity.
Be specific about the error and its financial impact.
Provide complete documentation without omissions.
Follow up professionally if no response is received within the expected timeframe.
Consider seeking assistance from consumer advocacy groups if the case is complex.
State insurance departments prioritize complaints that demonstrate clear violations of pricing transparency laws, such as those outlined in the Unfair Claims Settlement Practices Act or state-specific insurance codes. Consumers who present well-documented cases are more likely to achieve resolution.
Navigating auto insurance price comparisons isn’t just a one-time task; it’s an ongoing process that adapts to life changes—new cars, moves, or even credit score improvements. The key takeaway is that the "best" policy depends on your unique risk profile, not just the lowest sticker price. Armed with the right tools—comparison tables, discount stacking, and regional cost data—you can challenge the status quo and demand fairer rates. Whether you’re a first-time buyer or a seasoned driver, the power to save lies in asking the right questions, spotting hidden fees, and leveraging technology to your advantage. The future of auto insurance pricing is shifting toward dynamic, personalized models, but today’s consumers still hold the upper hand when they compare wisely.
Car Insurance Price Comparison in Word, Google Docs - Download Template.net
Frequently Asked Questions
Why do auto insurance prices vary so much between providers?
Auto insurance prices vary due to factors like company underwriting, risk assessment models, customer data, and regional claim frequencies. Some insurers offer better rates for specific demographics or vehicle types, while others prioritize customer service or claim handling speed. Competition and market demand also influence pricing differences.
How can I find the cheapest auto insurance without sacrificing coverage?
Use price comparison tools, request quotes from multiple insurers, and evaluate coverage limits and deductibles. Focus on providers with strong financial ratings and customer reviews. Avoid dropping comprehensive or collision coverage if your vehicle’s value justifies it, as this may leave you underinsured in an accident.
What discounts can lower my auto insurance premium every year?
Common discounts include safe driver, multi-policy (bundling home/auto), good student, low mileage, and anti-theft device discounts. Insurers may also offer loyalty, paperless billing, or usage-based (telematics) discounts. Always ask insurers about available promotions and eligibility criteria to maximize savings.
Does my ZIP code affect how much I pay for car insurance?
Yes, ZIP codes influence premiums due to regional crime rates, traffic density, weather risks, and local claim statistics. Urban areas often have higher rates because of increased accident and theft risks, while rural areas may offer lower prices. Even within the same city, neighborhoods with higher accident rates can lead to higher costs.
Can switching insurers mid-policy save me money next renewal?
Switching insurers mid-policy isn’t common, but shopping around before renewal can yield savings. Some insurers raise rates at renewal, while others may offer loyalty discounts. Compare quotes 60-90 days before your policy expires to secure better rates without gaps in coverage.
What’s the best way to compare auto insurance quotes accurately?
Ensure all quotes use identical coverage limits, deductibles, and optional features. Provide consistent driver and vehicle details across providers. Use independent comparison tools for unbiased results, but verify final terms directly with insurers. Avoid focusing solely on price—consider customer service, financial stability, and claim satisfaction.