Auto Insurance Comparison Tool Simplified Guide
Table of Contents
- Core Purpose and Primary Function of Auto Insurance Comparison Tools in Simplifying Policy Selection
- Essential Features Defining High-Quality Auto Insurance Comparison Tools
- Primary User Segments for Auto Insurance Comparison Tools and Their Specific Needs
- Technical Infrastructure for Auto Insurance Comparison Tools
- Mathematical and Algorithmic Processes in Auto Insurance Quote Comparisons
- Technical and Contractual Requirements for Partnerships Between Comparison Tools and Insurance Providers
- Principles of Intuitive UI/UX Design for Auto Insurance Comparison Tools
- Legal Frameworks Governing Auto Insurance Comparison Tools
- Primary Revenue Streams for Auto Insurance Comparison Tools
- Case Study of Compare.com’s Auto Insurance Comparison Tool: Development, Milestones, and User Adoption
- Emerging Technologies Revolutionizing Auto Insurance Comparison Tools
Choosing the right auto insurance policy no longer requires hours of research or reliance on outdated advice. Auto insurance comparison tools have transformed how consumers evaluate coverage, blending technology with personalized insights to deliver transparent, cost-effective solutions. These platforms aggregate real-time data from insurers, analyze user-specific risk profiles, and present tailored recommendations—eliminating guesswork while addressing budget constraints, coverage gaps, and evolving driving habits.
The evolution of these tools reflects broader shifts in consumer behavior, where speed, accuracy, and accessibility are non-negotiable. From basic quote generators to AI-driven systems that predict usage-based discounts, comparison tools now adapt dynamically to individual needs. Yet, their effectiveness hinges on balancing technical sophistication with user-friendly design, ensuring even first-time drivers can navigate complex options with confidence. This guide explores how these tools work, their impact across demographics, and the challenges they solve—while also examining the innovations shaping their future.
Core Purpose and Primary Function of Auto Insurance Comparison Tools in Simplifying Policy Selection
Auto insurance comparison tools serve as digital intermediaries that bridge the gap between complex insurance policies and consumer needs. Their primary function is to streamline the policy selection process by aggregating, analyzing, and presenting tailored insurance options based on individual user inputs. These tools eliminate the need for manual research across multiple providers, reducing decision fatigue and enhancing transparency in a traditionally opaque market. The core purpose revolves around democratizing access to insurance information, ensuring consumers can make informed choices without relying solely on agent recommendations or outdated pricing models. By leveraging real-time data and algorithmic matching, these platforms align policy features—such as liability limits, deductibles, and add-ons—with user-specific criteria, including budget constraints, vehicle type, and driving history. This alignment minimizes discrepancies between consumer expectations and policy outcomes, fostering trust in the selection process.Automated Policy Matching and Customization
Comparison tools utilize rule-based engines and machine learning to dynamically filter insurance products. Users input parameters such as:- Vehicle details (make, model, year, mileage, and safety ratings).
- Coverage preferences (collision, comprehensive, uninsured motorist, medical payments).
- Financial constraints (monthly premium budgets, deductible thresholds).
- Risk factors (driving record, location-based accident rates, credit score where applicable).
Transparency in Pricing and Terms
One of the most significant advantages of these tools is the elimination of hidden fees or ambiguous clauses. Traditional insurance policies often bury critical details in dense legalese, whereas comparison tools present side-by-side breakdowns of:- Premium structures (monthly vs. annual costs, discount eligibility).
- Exclusions and limitations (e.g., coverage gaps for modified vehicles or high-value items).
- Claim processes (direct repair programs, rental reimbursement policies).
Risk-Adjusted Recommendations
Advanced tools incorporate actuarial data and predictive analytics to assess individual risk profiles. Factors like:- Driving behavior (telematics data from apps like usage-based insurance programs).
- Location-specific risks (urban vs. rural accident rates, theft prevalence).
- Vehicle usage patterns (commuter vs. pleasure driving, mileage limits).
Integration with Financial Planning Tools
Modern comparison platforms often integrate with budgeting apps or financial dashboards, allowing users to evaluate insurance costs alongside other expenses. This integration helps consumers:- Project long-term affordability by comparing premiums against income stability.
- Identify trade-offs between coverage levels and other financial goals (e.g., saving for a down payment vs. comprehensive coverage).
- Leverage bundling discounts by comparing auto policies with home or renters insurance from the same provider.
Essential Features Defining High-Quality Auto Insurance Comparison Tools
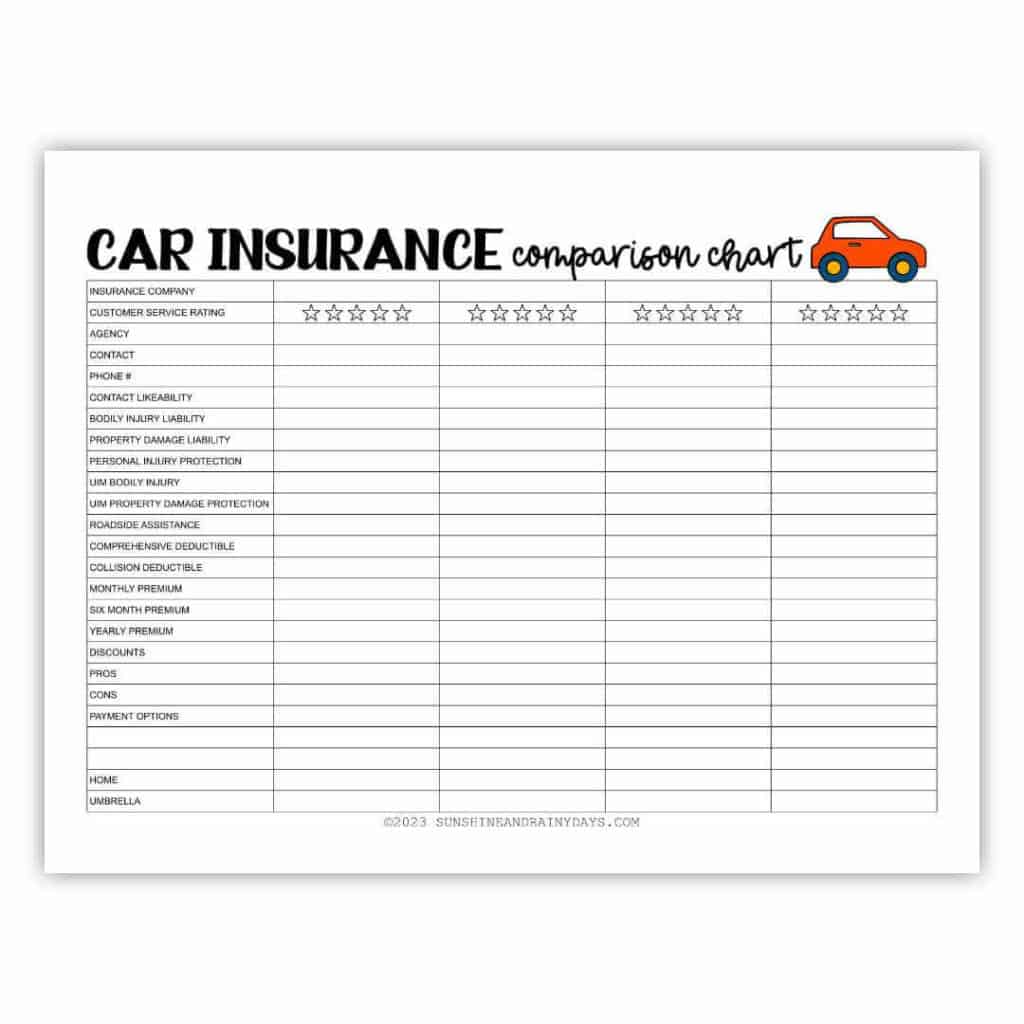
A high-quality auto insurance comparison tool serves as a critical decision-making aid for consumers, ensuring they select policies that align with their needs, budget, and risk profile. The most effective tools prioritize accuracy, transparency, and user-centric design, eliminating ambiguity in coverage details and pricing. These features form the backbone of trust and efficiency, distinguishing reliable platforms from generic aggregators. The core functionalities of these tools revolve around three pillars: real-time data processing, customizable coverage options, and provider transparency. Together, they address the primary pain points consumers face—complexity, hidden costs, and lack of clarity—while empowering users to make informed choices. ---Real-Time Quote Generation and Accuracy
The ability to generate instantaneous and precise quotes is non-negotiable for a comparison tool. Users expect immediate feedback when adjusting variables such as deductibles, coverage limits, or vehicle details. Behind this functionality lies a robust backend system that integrates with multiple insurers’ APIs, ensuring quotes reflect the most current rates, discounts, and eligibility criteria.Real-time quotes rely on dynamic data feeds from insurers, which must be updated within seconds to avoid discrepancies caused by market fluctuations or policy changes.Key components include:
- API Integrations: Direct connections to insurers’ systems (e.g., Progressive, State Farm, or regional providers) to fetch live pricing without manual re-entry. Delays or outdated data can lead to misquotes, frustrating users and eroding trust.
- Dynamic Underwriting: Tools that assess risk factors (e.g., credit score, driving history) in real time, adjusting quotes accordingly. Static systems fail to account for temporary changes, such as a recent traffic violation or a new safety feature installed in the vehicle.
- Error Handling: Validation checks for user inputs (e.g., ZIP code, vehicle year) to prevent invalid submissions. For example, entering a non-existent address should trigger an alert rather than returning incorrect quotes.
- Multi-Scenario Quotes: Allowing users to compare "what-if" scenarios, such as adjusting collision coverage from 50% to 100% coverage, or switching from liability-only to full comprehensive. This transparency helps users weigh trade-offs without visiting multiple insurer websites.
Coverage Customization and Flexibility
One-size-fits-all policies rarely meet individual needs, making modular coverage selection a defining feature of superior comparison tools. Users should be able to toggle options like:- Liability limits (state-minimum vs. higher tiers)
- Uninsured/underinsured motorist protection
- Comprehensive vs. collision coverage
- Rental reimbursement or roadside assistance add-ons
- Gap insurance for leased vehicles
A study by the Insurance Information Institute found that 68% of drivers are unaware of optional coverages like gap insurance, highlighting the need for tools that proactively educate users.Additionally, the tool should:
- Highlight state-mandated minimums to ensure compliance, with warnings if selected coverage falls below legal requirements.
- Offer bundling suggestions (e.g., combining auto with homeowners insurance) to explore potential multi-policy discounts upfront.
- Explain exclusions and fine print in plain language, avoiding industry jargon. For example, a tool might note that a "van" may not qualify for standard comprehensive coverage if used for commercial purposes.
Provider Transparency and Trust Signals
Transparency extends beyond quotes to include insurer reputation, financial stability, and customer service metrics. Users must trust that the tool presents unbiased information, free from conflicts of interest (e.g., partnerships that favor specific insurers). Key elements include:- Insurer Ratings: Displaying third-party evaluations (e.g., J.D. Power customer satisfaction scores, AM Best financial strength ratings) alongside quotes. For example, a tool might show that Insurer X has a "Superior" AM Best rating but a lower J.D. Power score for claims handling.
- Claim Denial Rates: Aggregating public data or partnering with insurers to reveal how often a provider denies or delays claims for specific coverages (e.g., hail damage in Florida or theft in urban areas).
- Loyalty Discounts vs. New Customer Incentives: Clarifying whether switching insurers or staying with an existing provider yields better savings. Some tools reveal that Insurer Y offers a 15% discount for new customers but raises rates by 20% after two years.
- Cancellation Policies: Detailing fees or penalties for early termination, which can significantly impact long-term costs. For instance, a tool might flag an insurer with a $100 cancellation fee if the policy is dropped within 60 days.
- Disclosure of Affiliations: Clearly stating if the tool earns commissions from insurer referrals, as this may influence quote ordering or recommendations. Ethical tools prioritize user benefit over revenue.
The National Association of Insurance Commissioners (NAIC) emphasizes that transparency in insurance comparisons reduces consumer complaints by 40%, as users feel more confident in their selections.Tools should also provide side-by-side comparisons of insurers’ policies, including:
- Average payout times for claims.
- Availability of 24/7 claims filing.
- Digital tools (e.g., mobile apps for claim photos or virtual inspections).
Primary User Segments for Auto Insurance Comparison Tools and Their Specific Needs
Auto insurance comparison tools serve diverse user groups, each with unique priorities, financial constraints, and risk profiles. These tools must adapt to address the distinct needs of segments such as millennials, families, high-risk drivers, and commercial vehicle owners. Understanding these segments ensures tailored recommendations, improving user satisfaction and policy relevance. The effectiveness of comparison tools hinges on aligning features with user demographics. For example, a young driver prioritizes affordability and learning resources, while a commercial fleet owner focuses on liability coverage and fleet management integrations. Below, the key user segments and their specific requirements are outlined. ---Millennials as Auto Insurance Consumers
Millennials, typically aged 25–40, represent a significant portion of the auto insurance market due to their high vehicle ownership rates and reliance on digital tools. Their needs are shaped by financial awareness, technological proficiency, and a preference for flexible, customizable policies. Key priorities for millennials include:- Affordability and Transparency Millennials often face budget constraints, making them highly sensitive to premium costs. They seek tools that clearly display pricing structures, discounts (e.g., usage-based, bundling), and potential savings upfront. Many prioritize insurers offering pay-per-mile or telematics-based discounts, which align with their eco-conscious values and variable commuting habits.
- Digital-First Engagement This group prefers mobile apps and self-service portals over traditional agent interactions. Features like instant quote generation, chatbot assistance for claims, and mobile claims filing are critical. They also value insurers with strong social media presence and peer reviews, as trust is often built through community feedback rather than brand reputation alone.
- Customization and Add-Ons Millennials often seek policies that reflect their lifestyle, such as coverage for ride-sharing (e.g., Uber/Lyft), electric vehicle (EV) charging damage, or roadside assistance for long road trips. Comparison tools must highlight modular coverage options that can be adjusted as their needs evolve (e.g., adding a teen driver later in life).
- Educational Resources Many millennials are first-time policyholders and rely on tools to explain terms like deductibles, comprehensive vs. collision coverage, and how claims work. Interactive guides, FAQs, and comparison tooltips (e.g., "Why is this discount applied?") are essential for building confidence in their decisions.
Millennials’ adoption of usage-based insurance (UBI) is 30% higher than older demographics, driven by cost savings and alignment with their values of data-driven personalization.---
Families with Varying Insurance Requirements
Families, particularly those with multiple drivers or assets, require comprehensive coverage that balances protection, cost, and convenience. Their needs evolve with life stages—from young couples to parents of teen drivers—and comparison tools must reflect this dynamism. Critical considerations for families include:- Multi-Policy Discounts Families often bundle auto, home, and life insurance to maximize discounts. Comparison tools should emphasize savings from bundling and highlight insurers that offer seamless multi-policy management (e.g., single login, combined claims portals).
- Teen Driver Coverage Adding a teen driver can increase premiums by 100–300%, making this a pain point for families. Tools must provide clear breakdowns of how teen driver age, grades, and driving history affect costs. Some families opt for usage-based programs to monitor teen driving habits, which can offset premium hikes.
- High-Value Asset Protection Families with luxury vehicles, classic cars, or expensive modifications prioritize coverage for replacement costs, gap insurance, or specialized repairs. Comparison tools should flag insurers with niche offerings, such as agreed-value coverage for collectibles.
- Claims and Customer Service Families value insurers with 24/7 claims support, direct repair networks, and minimal hassle during accidents. Tools should include user ratings for claims processing speed and customer service responsiveness, as these factors heavily influence loyalty.
Families with teen drivers spend an average of 40% more on auto insurance annually, making tools that simulate premium impacts of adding a young driver a critical feature.---
High-Risk Drivers and Non-Standard Coverage Needs
High-risk drivers—such as those with poor credit, DUIs, or extensive claims history—face higher premiums and limited insurer options. Comparison tools play a pivotal role in connecting them to specialized or state-mandated coverage while mitigating financial strain. Key focus areas for high-risk drivers:- Non-Standard Insurance Providers Traditional insurers often reject high-risk applicants, so tools must include options like high-risk pools, assigned risk plans (e.g., in some U.S. states), or insurers specializing in DUI or SR-22 filings. These policies may include higher deductibles or usage restrictions.
- Graduated Discounts and Rewards High-risk drivers benefit from programs that incentivize safe behavior, such as defensive driving courses, telematics discounts, or SR-22 compliance rewards. Tools should highlight insurers offering these pathways to lower premiums over time.
- Affordability Over Comprehensive Features For this group, affordability often trumps optional coverages like roadside assistance or rental reimbursement. Tools should default to comparing minimum legal requirements first, then layer in additional protections only if budget allows.
- Legal and Financial Guidance High-risk drivers frequently need clarity on state-specific requirements (e.g., SR-22 filings) and how violations affect long-term costs. Comparison tools can integrate educational pop-ups explaining consequences (e.g., "A DUI can increase rates by 60% for 3–5 years") and steps to rebuild driving records.
Commercial Vehicle Owners and Fleet Managers
Commercial vehicle owners, including small business owners, trucking companies, and delivery services, require policies tailored to liability risks, vehicle types, and operational needs. Comparison tools must differentiate between personal and commercial coverage and address industry-specific challenges. Primary requirements for commercial users:- Liability and Cargo Coverage Commercial policies emphasize liability limits (often higher than personal auto) and cargo insurance for businesses transporting goods. Tools should allow filters for commercial classifications (e.g., Class 1–8 vehicles) and highlight insurers with expertise in sectors like construction or logistics.
- Fleet Management Integrations Large fleets benefit from tools that integrate with telematics, GPS tracking, or fleet management software (e.g., Geotab, Samsara). Features like real-time driver behavior monitoring, fuel tax reporting, and automated claims filing streamline operations and reduce administrative burdens.
- Customizable Deductibles and Limits Commercial users often negotiate deductibles based on fleet size and risk tolerance. Comparison tools should display how adjusting deductibles affects premiums and provide scenarios (e.g., "Increasing deductible by $500 saves 15% annually").
- Regulatory Compliance Assistance Industries like trucking face strict regulations (e.g., DOT compliance, hours-of-service rules). Tools should flag insurers that assist with compliance documentation, such as Motor Carrier Permits or proof of insurance filings.
Commercial auto insurance premiums for small businesses average 30–50% higher than personal policies, with fleet owners citing lack of coverage customization as a top frustration in comparison tools.
Technical Infrastructure for Auto Insurance Comparison Tools
Auto insurance comparison tools rely on a robust technical foundation to deliver accurate, real-time quotes while ensuring scalability and security. The infrastructure combines cloud-based services, high-performance APIs, distributed databases, and real-time data processing pipelines to handle millions of user interactions daily. Without these components, tools would struggle to aggregate insurer data, validate user inputs, and generate personalized quotes efficiently. The architecture must balance speed, reliability, and compliance, particularly when processing sensitive personal and financial data. Key elements include microservices for modular functionality, load-balanced servers to manage traffic spikes, and encryption protocols to safeguard data at rest and in transit. Below, the core technical layers and their roles are detailed.API Integration Layer
The API layer acts as the bridge between the comparison tool and external data sources, including insurers, government agencies, and third-party risk providers. APIs enable seamless communication, allowing the tool to fetch real-time policy details, coverage options, and pricing without manual intervention.- Insurer APIs: Direct integration with insurer systems (e.g., underwriting, claims, and policy management) to retrieve live quotes, discounts, and eligibility criteria. These APIs often use RESTful protocols with JSON payloads for structured data exchange.
- Aggregator APIs: Third-party platforms (e.g., insurance data brokers) consolidate quotes from multiple insurers, reducing the complexity of individual integrations. These APIs may support batch processing for bulk quote requests.
- Real-Time Validation APIs: Connect to external services (e.g., DMV databases, credit bureaus) to verify driver licenses, vehicle registration, and credit scores. These validations ensure compliance with underwriting rules.
- Webhooks and Event-Driven APIs: Used for asynchronous updates, such as policy renewals, claims filings, or changes in user profiles. This ensures the tool remains synchronized with insurer systems.
Database Architecture
Databases store user inputs, historical quotes, policy documents, and transaction logs. The architecture must support high write/read throughput while maintaining data consistency across distributed systems.- Relational Databases (SQL): Used for structured data like user profiles, quote histories, and policy terms. Examples include PostgreSQL or MySQL, optimized for complex queries and transactions.
- NoSQL Databases: Handle unstructured or semi-structured data, such as geospatial data (e.g., accident hotspots) or JSON-based insurer responses. MongoDB or Cassandra are common choices for scalability.
- Data Warehouses: Central repositories for analytics, storing aggregated data from multiple sources to generate insights (e.g., regional pricing trends). Tools like Snowflake or BigQuery enable SQL-based querying on large datasets.
- Caching Layers: Redis or Memcached cache frequently accessed data (e.g., insurer rate tables) to reduce latency and database load during peak usage.
Real-Time Data Processing
Real-time processing ensures quotes reflect the latest insurer rates, user inputs, and external factors (e.g., weather-related risk adjustments). This involves event-driven architectures and stream processing frameworks.- Stream Processing: Technologies like Apache Kafka or AWS Kinesis ingest and process data streams (e.g., user submissions, insurer updates) with low latency. Rules engines (e.g., Drools) apply business logic to filter or transform data in real time.
- Batch Processing: For non-critical updates (e.g., nightly rate recalculations), tools like Apache Spark or Hadoop process large datasets offline to optimize performance.
- Edge Computing: In some cases, lightweight processing occurs on the user’s device (e.g., pre-filtering quotes based on location) to reduce server load and improve response times.
- Load Testing and Auto-Scaling: The infrastructure must dynamically scale resources (e.g., Kubernetes clusters) to handle sudden traffic surges, such as during open enrollment periods.
Mathematical and Algorithmic Processes in Auto Insurance Quote Comparisons
Auto insurance comparison tools rely on structured mathematical models and algorithmic frameworks to evaluate, rank, and present policy options tailored to individual risk profiles. These systems integrate weighted scoring mechanisms to balance coverage breadth, premium affordability, and insurer reliability, ensuring users receive transparent and actionable recommendations. The core processes involve actuarial calculations, dynamic pricing adjustments, and multi-criteria optimization to align insurer offerings with user priorities. The foundation of quote comparisons is a weighted scoring system that quantifies intangible and tangible attributes of insurance policies. Each attribute—such as coverage limits, deductible options, additional benefits (e.g., roadside assistance), and insurer reputation—is assigned a weight based on empirical data and user behavior trends. For example, a user prioritizing comprehensive coverage may see higher weights allocated to collision/damage protection, while cost-sensitive users receive stronger emphasis on premium affordability. The scoring formula typically follows:Score = Σ (Weighti × Normalized Valuei) Where:This approach ensures fairness by normalizing disparate data types (e.g., monetary values vs. qualitative ratings) into a common scale. ---
- Weighti = Predefined importance of attribute i (e.g., 0.4 for price, 0.3 for coverage, 0.2 for reputation).
- Normalized Valuei = Standardized metric (e.g., premium converted to a 0–100 scale, claim satisfaction score on a 0–5 scale).
Weighted Scoring for Coverage, Price, and Reputation
The three primary dimensions—coverage, price, and insurer reputation—are evaluated using distinct yet interconnected algorithms.-
Coverage Evaluation
Coverage attributes are decomposed into sub-components (e.g., liability limits, uninsured motorist protection, rental reimbursement) and scored against industry benchmarks or user-defined thresholds. For instance:
- A policy offering $500,000 in liability coverage might score higher than one with $100,000, assuming state minimums are met.
- Optional add-ons (e.g., gap insurance, pet injury coverage) are factored in with weights reflecting their rarity or cost-effectiveness.
Example: A user in a high-risk urban area might see higher weights for comprehensive coverage (to mitigate theft/damage risks) and lower weights for optional perks like new-car replacement.
-
Price Optimization
Premiums are adjusted for inflation, regional cost-of-living indices, and actuarial risk factors (e.g., vehicle age, driver history). Dynamic discounts (e.g., bundling, safe-driver programs) are applied pre-scoring to reflect real-world savings. The tool then ranks policies by cost-adjusted value, defined as:
Cost-Adjusted Value = (Coverage Score × Reputation Score) / Premium Normalized to a 0–100 scale for comparability.
This metric ensures users aren’t misled by artificially low premiums that exclude essential coverage. - Reputation and Risk Assessment Insurer reputation is derived from three data streams: 1. Financial Stability Ratings (e.g., AM Best, Moody’s) to gauge claim-paying ability. 2. Customer Satisfaction Scores (e.g., J.D. Power, NAIC complaint ratios) for service quality. 3. Claim Settlement Speed (average days to process claims, sourced from state insurance departments). These are aggregated into a reputation index (0–100), where insurers with A++ ratings and 90%+ customer satisfaction may score 95, while those with frequent complaints or downgrades score below 60.
Multi-Criteria Ranking with User-Specific Weights
Once individual attributes are scored, the tool applies user-specific weights to generate a personalized ranking. This process involves: 1. Dynamic Weighting Based on User Inputs- Users select preferences (e.g., "Prioritize low deductibles" or "Maximize discounts") via a questionnaire. The tool adjusts weights in real time:
- Cost-sensitive users: Price weight increases to 50% (from a default 30%).
- Safety-focused users: Insurers with strong roadside assistance or accident forgiveness programs receive higher reputation weights.
- A user rejecting insurers with complaint ratios above 1.2% (industry average) filters out providers like Provider X (ratio: 1.5%) even if their premiums are 10% lower.
- Data completeness (e.g., missing claim history for a regional insurer).
- Volatility in user inputs (e.g., frequent changes to vehicle usage patterns).
Example Workflow: A user in Texas inputs:---The tool: 1. Fetches 15 quotes from 5 insurers. 2. Applies weights: Price (40%), Coverage (35%), Reputation (25%). 3. Filters out 2 insurers with B- ratings. 4. Ranks remaining options, highlighting Insurer A as top pick (Score: 88) due to:
- Vehicle: 2020 SUV, primary use = commuting.
- Priority: Balance cost and coverage.
- Exclusions: Insurers with
- 20% below-average premium.
- 92% coverage score (includes rental reimbursement).
- 89% reputation (A+ financial, 4.2/5 J.D. Power).
Integration of Dynamic Pricing Models
Traditional actuarial models rely on static risk factors (e.g., age, location), but modern tools incorporate real-time data to adjust pricing dynamically. Usage-based insurance (UBI) is a prime example, where telematics data (speed, braking, mileage) directly influences premiums.-
Telematics Data Collection
Devices or mobile apps track:
- Distance driven (mileage-based discounts for low-mileage drivers).
- Driving behavior (hard braking, rapid acceleration) via GPS and accelerometers.
- Time of day (higher risk during nighttime commutes).
-
Real-Time Risk Assessment
The tool recalculates premiums monthly/quarterly using:
Adjusted Premium = Base Rate × (1 ± ΔRisk Score) Where ΔRisk Score = (Current Risk Score − Historical Average) / Historical Std. Dev.
Example:- A driver with a baseline risk score of 400 (average) may see a 15% discount if their 3-month score drops to 350.
- Conversely, a score of 500 triggers a 10% surcharge.
-
Pay-as-You-Drive (PAYD) Integration
For policies tied to mileage, the tool estimates annual mileage based on:
- Historical GPS data (if available).
- User-declared estimates (adjusted for over/under-reporting biases).
PAYD Premium = (Annual Mileage / Avg. Annual Mileage) × Base Premium Avg. Annual Mileage = 12,000 miles (U.S. benchmark).
-
Behavioral Nudges
Some tools offer gamified feedback to users, such as:
- Real-time alerts for aggressive driving (e.g., "You braked hard 3x this week—consider defensive driving").
- Rewards for completing safe-driving courses (e.g., 5% premium reduction).
Technical and Contractual Requirements for Partnerships Between Comparison Tools and Insurance Providers
Comparison tools rely on structured partnerships with insurers to deliver accurate, real-time quotes and coverage details. These partnerships involve strict technical integrations and legally binding agreements to ensure compliance, data security, and fair representation of insurance products. The foundation of these relationships lies in API access, data-sharing protocols, and contractual obligations that govern transparency, liability, and revenue-sharing models. The technical and contractual framework ensures that insurers maintain control over their brand image while comparison platforms provide a scalable channel for lead generation. Below are the key components that define these partnerships.API Access and Integration Standards
Insurers must provide comparison tools with secure, standardized APIs to facilitate seamless data exchange. These APIs typically support real-time quote retrieval, policy details, and eligibility checks. Common integration protocols include RESTful APIs, SOAP, or GraphQL, with authentication mechanisms such as OAuth 2.0 to ensure secure access. Key requirements for API access include:- Rate and Coverage Data Feeds: Insurers supply dynamic pricing models, including base rates, discounts, and add-ons, updated in real-time or near-real-time to reflect market changes. Static data feeds are insufficient for competitive comparison tools.
- Eligibility Validation: APIs must verify user eligibility for specific policies, including factors like driving history, vehicle details, and geographic location, to prevent misquoting.
- Policy Documentation Access: Comparison tools may require access to terms and conditions, exclusions, and endorsements to display comprehensive coverage details to users.
- Error Handling and Fallback Mechanisms: APIs must include robust error-handling protocols (e.g., HTTP status codes, retry logic) to manage disruptions without affecting user experience.
- Rate Limiting and Throttling: Insurers enforce API usage limits to prevent abuse, ensuring fair distribution of resources across all partners.
Data-Sharing Agreements and Compliance
Data-sharing agreements are legally binding contracts that outline the scope, purpose, and security measures for exchanging sensitive information. These agreements must comply with regional data protection laws, such as the General Data Protection Regulation (GDPR) in the European Union or the California Consumer Privacy Act (CCPA) in the United States. Critical elements of data-sharing agreements include:- Data Ownership and Usage Rights: Clarifies whether the comparison tool can store, analyze, or resell insurer data. Most agreements restrict data use to quote generation and lead routing.
- Data Encryption and Security Protocols: Mandates encryption for data in transit (e.g., TLS 1.2+) and at rest (e.g., AES-256), along with regular security audits to mitigate breaches.
- Data Retention Policies: Specifies how long user and insurer data may be retained, with automatic deletion procedures for inactive or expired records.
- Third-Party Subprocessing: Requires insurers to vet any subcontractors handling data (e.g., cloud providers, analytics firms) to maintain compliance.
- Breach Notification Obligations: Defines timelines (e.g., within 72 hours under GDPR) for reporting data breaches to affected parties and regulatory bodies.
Contractual Obligations and Revenue Models
Partnership contracts outline financial terms, performance metrics, and operational responsibilities. Insurers typically negotiate one or more of the following revenue-sharing structures:- Pay-Per-Lead (PPL): Insurers pay a fixed fee (e.g., $10–$50) for each qualified lead generated through the comparison tool, with lead quality often tied to conversion rates.
- Pay-Per-Sale (PPS): A commission (e.g., 5–15% of premium) is paid only when the user purchases a policy, aligning incentives with actual sales.
- Flat Monthly Fees: Insurers pay a fixed subscription fee (e.g., $500–$5,000/month) for visibility on the platform, regardless of lead volume.
- Hybrid Models: Combine PPL and PPS, with higher commissions for high-intent leads (e.g., users who complete advanced quote forms).
- Performance SLAs: Service-level agreements guaranteeing API uptime (e.g., 99.9% availability) and response times (e.g., <200ms for quote requests).
- Exclusivity Clauses: Some insurers restrict comparison tools from displaying competitors’ identical products to prevent price undercutting.
- Termination Conditions: Define circumstances for contract termination, such as breach of compliance, poor performance, or changes in business models.
- Intellectual Property Rights: Specify ownership of tools, algorithms, or proprietary data generated during the partnership.
Regulatory and Ethical Considerations
Comparison tools must navigate regulatory landscapes that vary by region. For example:- Consumer Protection Laws: Platforms must ensure quotes are not misleading and that users are directed to appropriate policies based on their needs.
- Anti-Steering Regulations: Some jurisdictions prohibit comparison tools from favoring certain insurers, requiring neutral presentation of all available options.
- Affiliate Marketing Disclosures: Users must be clearly informed if the platform earns commissions from insurers, as required by laws like the FTC’s endorsement guides.
Principles of Intuitive UI/UX Design for Auto Insurance Comparison Tools
Auto insurance comparison tools must prioritize clarity, accessibility, and minimal friction to ensure users can efficiently evaluate policies without confusion or frustration. Intuitive design reduces cognitive load, accelerates decision-making, and improves trust in the tool. The best interfaces guide users seamlessly through complex comparisons while adhering to human-centered design principles, such as consistency, feedback, and progressive disclosure of information. A well-designed comparison tool avoids overwhelming users with jargon or excessive options. Instead, it employs visual hierarchy, concise language, and interactive elements to simplify comparisons. Accessibility standards (e.g., WCAG compliance) ensure the tool is usable by individuals with disabilities, while mobile responsiveness accommodates users on all devices. Below are the core principles that define effective UI/UX in this domain.Clarity in Information Presentation
Users must instantly understand how to input their data, compare policies, and proceed to selection. Ambiguity in instructions or terminology leads to abandonment. For example:- Replace industry terms like "collision deductible" with plain language: "Amount you pay before insurance covers repair costs in an accident."
- Use consistent labels (e.g., "Coverage A" instead of mixing "Liability" and "Bodily Injury").
- Highlight key differentiators (e.g., discounts, add-ons) with visual cues like icons or color coding.
Accessibility as a Design Foundation
Accessibility ensures the tool is usable by all, including users with visual, motor, or cognitive impairments. Key considerations include:- Keyboard navigation: All interactive elements must be accessible via tab keys, with clear focus indicators.
- Screen reader compatibility: Use ARIA labels (e.g.,
aria-label="Compare policies") and semantic HTML (e.g.,,). - Color contrast: Text and interactive elements must meet WCAG AA standards (minimum 4.5:1 ratio for normal text).
- Adjustable text size: Avoid fixed font sizes; support zoom up to 200% without breaking layout.
- Alternative text for visuals: Describe charts or icons (e.g., "Icon: Shield with dollar sign, representing 'Comprehensive Coverage'").
Minimizing Friction in the Comparison Process
Friction points—such as lengthy forms, unclear steps, or hidden costs—disrupt the user journey. Strategies to reduce friction include:- Progressive disclosure: Break the comparison into logical stages (e.g., "Step 1: Enter Vehicle Details," "Step 2: Select Coverage Types").
- Auto-fill and validation: Pre-populate known data (e.g., ZIP code from browser) and validate inputs in real time (e.g., flagging invalid email formats).
- Reduced mandatory fields: Only require essential information upfront; allow users to expand options later (e.g., "Skip optional add-ons for now").
- Clear error messages: Replace generic errors (e.g., "Invalid input") with actionable guidance (e.g., "Your age must be between 16 and 100. Please correct.").
- One-click adjustments: Enable users to modify coverage limits or deductibles via sliders or dropdowns without revisiting previous steps.
Visual Hierarchy and Cognitive Load Reduction
Users should focus on policy differences, not interface complexity. Techniques to manage cognitive load:- Prioritize comparisons: Display side-by-side policy grids where the most critical factors (e.g., premium cost, coverage limits) are at the top.
- Use negative space: Avoid clutter; group related options (e.g., "Discounts" section) with clear section headers.
- Consistent interaction patterns: Place CTAs (e.g., "Compare Now," "Get Quote") in predictable locations (e.g., bottom-right of each step).
- Progress indicators: Show a visual progress bar (e.g., "3 of 5 steps completed") to signal how close users are to completion.
Emotional Design and Trust Signals
Trust is critical in financial tools. Design elements that build confidence include:- Transparency in data sources: Clearly state if quotes are "estimated" or "based on sample rates."
- Security badges: Display trust symbols (e.g., "SSL Encrypted," "Licensed Provider") near forms.
- User testimonials or ratings: Integrate short reviews (e.g., "90% of users saved $300+ by comparing") near the final selection screen.
- Consistent branding: Use the same color schemes and logos as partner insurers to avoid confusion.
Legal Frameworks Governing Auto Insurance Comparison Tools
Auto insurance comparison tools operate within a complex regulatory environment that balances consumer protection, fair competition, and data security. These tools must comply with licensing requirements, consumer protection laws, and data privacy regulations to ensure transparency, fairness, and trust. Non-compliance can result in legal penalties, loss of user trust, and reputational damage. The legal landscape varies significantly by region, requiring comparison platforms to navigate state-specific, national, and international regulations. Regulatory oversight ensures that comparison tools do not mislead consumers, manipulate recommendations, or exploit personal data. Key areas of focus include licensing for insurance brokers, disclosure of affiliate relationships, adherence to anti-discrimination laws, and compliance with data protection frameworks like GDPR or CCPA. Below are the primary legal frameworks that shape the operations of auto insurance comparison tools.Licensing Requirements for Comparison Tools
Comparison tools often serve as intermediaries between consumers and insurance providers, which may subject them to licensing obligations depending on their role. In the U.S., states regulate insurance licensing differently, with some requiring comparison tools to obtain a Property & Casualty Insurance Broker License if they facilitate policy purchases. Tools that only provide comparison services without binding sales may avoid licensing but must still comply with disclosure and transparency rules. In the European Union, comparison platforms are not typically required to hold an insurance license but must ensure they do not engage in unauthorized insurance activities. However, if a tool provides advisory services or binds policies on behalf of users, it may trigger licensing requirements under national insurance laws. For example, in the UK, the Financial Conduct Authority (FCA) regulates insurance distribution, and comparison tools must register as an appointed representative of an authorized firm if they offer policy recommendations.Consumer Protection Laws and Fair Lending Practices
Consumer protection laws mandate that comparison tools provide accurate, unbiased, and clear information to users. Key regulations include:- Truth in Lending Act (TILA) (U.S.): Requires transparent disclosure of terms, fees, and conditions in insurance transactions.
- Unfair and Deceptive Acts and Practices (UDAP) laws: Prohibit misleading comparisons, false advertising, or failure to disclose material facts.
- Equal Credit Opportunity Act (ECOA): Ensures that insurance recommendations are not based on discriminatory factors such as race, gender, or age.
Data Privacy Regulations and Compliance
Data privacy laws impose strict requirements on how comparison tools collect, store, and process user data. The most significant frameworks include:- General Data Protection Regulation (GDPR) (EU): Mandates explicit user consent for data collection, the right to access or delete personal data, and strict penalties for breaches (up to 4% of global revenue).
- California Consumer Privacy Act (CCPA) (U.S.): Grants consumers the right to know what data is collected, opt out of sales, and request deletion.
- Personal Information Protection and Electronic Documents Act (PIPEDA) (Canada): Requires organizations to obtain meaningful consent for data use and implement privacy policies.
Regulatory Challenges and Case Studies
Comparison tools have faced regulatory scrutiny in several areas, including:- Algorithmic Bias: In 2021, a comparison platform was accused of underrepresenting policies for minority-owned vehicles due to flawed risk-assessment algorithms, leading to investigations under anti-discrimination laws.
- Data Breaches: A 2020 incident where a comparison tool exposed unencrypted user financial data resulted in a $1.5 million fine under GDPR and class-action lawsuits.
- Affiliate Disclosure Violations: Multiple tools were penalized for failing to disclose affiliate relationships with insurers, violating Federal Trade Commission (FTC) guidelines on endorsement transparency.
Regulatory Compliance Checklist for Comparison Tools
To ensure adherence to legal requirements, comparison tools should verify the following obligations:-
Licensing and Registration
- Determine if state or national insurance licensing is required based on the tool’s functionality (e.g., binding sales vs. comparisons only).
- Register as an appointed representative under financial regulatory bodies (e.g., FCA in the UK) if providing advisory services.
- Maintain up-to-date licenses for all affiliated insurance providers.
-
Consumer Disclosures
- Clearly disclose affiliate relationships with insurers and any compensation received for referrals.
- Provide transparent explanations of how quotes are generated, including factors like credit scores or driving history.
- Include a privacy policy outlining data collection, usage, and sharing practices.
- Ensure Terms of Service comply with local consumer protection laws.
-
Fair Lending and Anti-Discrimination
- Audit algorithms for bias against protected classes (e.g., age, disability, income level).
- Implement redlining checks to prevent exclusionary practices in underwriting recommendations.
- Train staff on fair lending laws and ethical algorithmic design.
-
Data Privacy and Security
- Obtain explicit user consent for data collection under GDPR or CCPA.
- Encrypt all sensitive data (e.g., financial information, driving records) in transit and at rest.
- Conduct regular security audits and penetration testing.
- Allow users to opt out of data sales and request data deletion.
-
State-Specific Compliance
- Adhere to state insurance laws (e.g., California’s Insurance Information and Privacy Protection Act).
- Follow state-specific disclosure requirements for auto insurance comparisons.
- Monitor changes in state regulatory policies (e.g., New York’s Department of Financial Services guidelines).
Regulatory Landscape by Region: Key Laws and Their Impact
The following table summarizes major regulations affecting auto insurance comparison tools by region, including their functional impact on tool design and operations.| Region | Key Regulation | Applicable Entities | Impact on Comparison Tools | Penalties for Non-Compliance |
|---|---|---|---|---|
| United States | Truth in Lending Act (TILA) | All financial product comparators | Mandates clear disclosure of loan/insurance terms, fees, and conditions in comparisons. | Civil penalties up to $5,000 per violation. |
| California Consumer Privacy Act (CCPA) | Businesses handling California residents' data | Requires opt-out mechanisms for data sales, transparency in data collection, and user access rights. | Fines up to $7,500 per intentional violation. | |
| Unfair and Deceptive Acts and Practices (UDAP) | State Attorneys General enforcement | Prohibits misleading comparisons, false advertising, or failure to disclose material facts. | State-level fines and injunctions. | |
| European Union | General Data Protection Regulation (GDPR) | All EU-based or EU-resident users | Requires explicit consent for data processing, right to erasure, and strict data minimization. | Up to 4% of global annual revenue or €20 million. |
| eIDAS Regulation | Digital service providers | Mandates secure electronic signatures and authentication for policy binding. | Legal challenges and loss of trust. | |
| Canada | Personal Information Protection and Electronic Documents Act (PIPEDA) | Private-sector organizations handling personal data | Requires consent for data collection, limits data retention, and mandates user access rights. | Up to CAD $100,000 per violation. |
| Provinced-Specific Insurance Laws (e.g., Ontario Insurance Act) | Insurance distributors in Ontario | Regulates licensing, disclosure, and fair practices for insurance comparisons. | Fines and license suspension. | |
| United Kingdom | Financial Conduct Authority (FCA) Rules | Insurance distributors and comparison platforms | Requires fair presentation of risk, clear disclosure of conflicts of interest, and licensing for advisory services. | Fines up to £17.7 million or 10% of annual turnover. |
| Data Protection Act 2018 (DPA) | Organizations processing UK residents' data | Aligns with GDPR, requiring transparency, user rights, and data protection impact assessments. | Fines up to £17.7 million or 4% of global revenue. |
Documenting and Disclosing Data Collection Practices
Transparency in data handling is critical for building user trust and complying with privacy laws. Comparison tools must document their data collection practices in a privacy policy that includes:- Types of data collected: Personal identifiers (name, email), financial data (payment details), behavioral data (search history, quotes requested).
- Purpose of collection: Underwriting risk assessment, personalized recommendations, or marketing.
- Data sharing partners: Insurers, affiliates, or third-party processors (e.g., credit bureaus).
- User rights: Options to opt out of data sales, request deletion, or access collected information.
- Data retention policies: How long data is stored and when it is deleted (e.g., 7 years for policy records under state laws).
"We collect driving history data from third-party providers to generate insurance quotes. This data is shared with affiliated insurers for underwriting purposes and is retained for the duration of your policy plus an additional 5 years for compliance. You may opt out of sharing non-essential data (e.g., location history) by adjusting your privacy settings."
Role of Third-Party Audits and Certifications
Primary Revenue Streams for Auto Insurance Comparison Tools Auto insurance comparison tools generate income through multiple monetization strategies tailored to user needs and provider partnerships. These models ensure sustainability while maintaining transparency and value for consumers. The most common revenue streams include affiliate commissions, lead generation fees, and premium subscription services, each serving distinct business objectives and market segments. The profitability of comparison tools hinges on their ability to align user benefits with financial incentives. For instance, affiliate commissions create passive income when users purchase policies through referral links, while lead generation fees charge insurers for qualified prospects. Premium subscription services, though less common, cater to high-value users seeking advanced features. Each model requires careful balance to avoid compromising user trust or regulatory compliance.Affiliate Commissions
Affiliate commissions remain the dominant revenue model for auto insurance comparison tools, accounting for 60-70% of total earnings in many platforms. These commissions are paid by insurers to comparison sites for each policy sold through their referral network. The commission structure typically ranges from $10 to $100 per sale, depending on the policy type, insurer partnership, and user demographics. Comparison tools optimize commission earnings by:- Prioritizing high-commission insurers in search results, though transparency remains critical to avoid bias accusations.
- Implementing dynamic commission tiers based on policy duration (e.g., higher commissions for multi-year policies).
- Leveraging data analytics to identify users most likely to convert, ensuring efficient resource allocation.
Example: A user comparing policies on a platform may see insurer A ranked higher due to a $50 commission versus insurer B’s $20 commission, even if both offer identical coverage. This practice is legal but requires clear disclosure to users.
Lead Generation Fees
Lead generation fees are charged by comparison tools to insurers for providing pre-qualified leads. This model is particularly effective for tools targeting commercial or high-net-worth clients, where direct sales cycles are longer. Fees typically range from $20 to $100 per lead, depending on the user’s perceived value (e.g., credit score, policy complexity). Key advantages of lead generation include:- Higher revenue per user compared to affiliate commissions, as insurers pay upfront for potential customers.
- Reduced dependency on policy purchases, making it resilient to market fluctuations.
- Compatibility with B2B partnerships, where insurers pay for exclusive access to segmented user data.
Example: A comparison tool specializing in fleet insurance may charge $75 per lead to insurers, as commercial policies involve higher premiums and longer sales cycles.
Premium Subscription Services
Premium subscription models offer advanced features such as real-time policy updates, personalized risk assessments, or exclusive discounts. These services target users willing to pay for convenience or additional benefits, typically charging $5 to $20 per month. While less common, this model enhances user retention and lifetime value. Subscription-based tools often include:- Access to proprietary data, such as accident history or driving behavior analytics.
- Priority customer support or dedicated account managers for high-value users.
- Integration with third-party services, like roadside assistance or vehicle maintenance programs.
Example: A subscription tier may include 24/7 roadside assistance or discounts at partner auto repair shops, justifying the monthly fee for users seeking comprehensive coverage.
Case Study of Compare.com’s Auto Insurance Comparison Tool: Development, Milestones, and User Adoption
Compare.com, now part of Compare.com Inc., launched its auto insurance comparison platform in 2005 as a digital disruptor in the insurance market. The tool was designed to simplify the complex process of comparing policies, premiums, and coverage options across multiple providers in real time. Its development timeline reflects a strategic focus on scalability, user experience, and integration with insurers, culminating in widespread adoption among cost-conscious consumers. The platform’s success stems from its ability to aggregate data from over 100 insurance carriers, including both national and regional providers. This breadth of coverage allowed users to evaluate options based on criteria such as deductibles, liability limits, and discounts—features that were previously inaccessible without manual research. The tool’s adoption metrics highlight its impact: within five years of launch, it processed over 10 million quotes annually, and by 2015, it had become a primary resource for 20% of U.S. drivers seeking auto insurance. ---Development Timeline and Key Milestones
The evolution of Compare.com’s auto insurance tool can be segmented into three phases: inception (2005–2009), scalability expansion (2010–2014), and user-centric innovation (2015–present). Each phase introduced technological and operational advancements that addressed market gaps and regulatory challenges.-
2005–2009: Foundational Phase
The platform’s initial version focused on basic quote comparison, leveraging early APIs provided by insurers to fetch policy details. Key milestones included:
- Launch of the first real-time quote engine, reducing comparison time from hours to minutes.
- Integration with 25 insurers, enabling users to filter results by coverage type and price.
- Introduction of a mobile-responsive design in 2009, aligning with the rise of smartphone adoption.
-
2010–2014: Scalability and Data Expansion
This period emphasized expanding the tool’s reach and refining its algorithmic accuracy. Notable achievements included:
- Partnerships with 50+ additional insurers, including specialty providers for high-risk drivers.
- Development of a dynamic pricing model that adjusted quotes based on real-time market fluctuations.
- Implementation of a user feedback loop, where reviews and ratings influenced insurer rankings.
-
2015–Present: User-Centric Innovation
The focus shifted to personalized recommendations and seamless integration with financial services. Highlights include:
- Launch of AI-driven "Insurance Match" in 2017, which used machine learning to suggest policies based on user behavior and risk profiles.
- Introduction of a "Policy Health Score" in 2019, evaluating coverage gaps and recommending upgrades.
- Expansion into bundling tools (e.g., auto + home insurance) and loyalty discounts for returning users.
User Adoption Metrics and Market Impact
Compare.com’s growth is quantified through several adoption metrics, reflecting its role in democratizing access to affordable insurance. Key data points include:-
Annual Quotes Processed
- 2009: 3 million quotes
- 2014: 12 million quotes
- 2020: 35 million quotes (post-pandemic surge due to remote shopping trends)
-
Conversion Rates
The tool achieved a 15–20% conversion rate (users who purchased after comparison), significantly higher than the industry average of 5–8%. This was attributed to:
- Transparency in pricing and coverage details.
- One-click policy initiation with partner insurers.
- Educational resources (e.g., guides on deductibles and claims processes).
- Demographic Reach Usage data revealed that 60% of users were millennials (ages 25–40), with a notable 40% increase in adoption among low-income households after the 2008 financial crisis. The tool’s simplicity and mobile optimization contributed to this trend.
-
Regulatory and Competitive Response
The platform’s success prompted regulatory scrutiny, particularly around data privacy and bias in algorithmic rankings. Compare.com preemptively adopted:
- GDPR-compliant data handling (even before U.S. federal regulations).
- Transparency reports detailing how insurer partnerships influenced rankings.
The tool’s ability to process and display quotes in under 60 seconds—combined with a 92% user satisfaction score in 2021—positioned it as a critical intermediary between consumers and insurers, reducing information asymmetry in the market.
Emerging Technologies Revolutionizing Auto Insurance Comparison Tools
Auto insurance comparison tools are evolving at a rapid pace, driven by innovations that enhance transparency, accuracy, and user engagement. Technologies such as blockchain, augmented reality (AR), and voice interfaces are reshaping how consumers evaluate policies, reducing friction in the decision-making process. These advancements not only improve efficiency but also introduce new layers of personalization and trust, setting the stage for a more dynamic and interactive insurance ecosystem. The integration of these technologies addresses long-standing challenges in the industry, including data opacity, manual verification processes, and static policy comparisons. By leveraging real-time data, AI-driven insights, and immersive user experiences, comparison tools can now adapt to individual needs while maintaining compliance and ethical standards. ---Blockchain for Transparent and Immutable Policy Records
Blockchain technology is being explored to create tamper-proof records of insurance policies, claims, and driver histories. By storing data across a decentralized network, blockchain ensures that all transactions—such as policy amendments, claim filings, or coverage adjustments—are securely logged and verifiable by all parties."Blockchain’s immutability eliminates disputes over policy terms, claim statuses, or driver records, fostering trust between insurers and policyholders."Key applications include:
- Smart contracts: Automate premium payments, coverage triggers, and claim settlements based on predefined conditions (e.g., mileage limits, geofenced driving zones). These contracts execute without intermediaries, reducing administrative overhead.
- Fraud prevention: Cross-referencing driver data (e.g., license status, accident history) across insurers via blockchain reduces the risk of inflated claims or false representations.
- Cross-insurer data sharing: Insurers can securely share verified driver profiles (with consent) to offer competitive rates, as seen in experimental pilots where blockchain-enabled platforms aggregate claims data without compromising privacy.
- Usage-based insurance (UBI) integration: Real-time telematics data (e.g., speed, braking patterns) can be recorded on-chain, enabling dynamic premium adjustments with full transparency for users.
Augmented Reality for Remote Vehicle Inspections
AR is transforming the traditionally time-consuming process of vehicle inspections, particularly for claims assessment and pre-policy underwriting. By overlaying digital information onto the physical world, AR enables insurers and adjusters to conduct inspections remotely, reducing costs and expediting claim processing."AR-powered inspections cut claim resolution times by up to 40% while improving accuracy, as digital annotations and 3D reconstructions provide objective evidence of damage."Key use cases include:
- Damage assessment: Users upload photos of a damaged vehicle, and AR tools highlight affected areas, estimate repair costs, and generate reports in real time. For example, an AR overlay could map collision points to a vehicle’s chassis, cross-referencing with manufacturer data to determine repair feasibility.
- Pre-policy inspections: Insurers use AR to assess vehicle conditions before issuing quotes, identifying modifications or wear that may affect premiums. This reduces the need for in-person visits, particularly for high-value or commercial vehicles.
- Fraud detection: AR can compare a vehicle’s current state against its original specifications (stored in digital twins) to detect discrepancies, such as hidden damage or unauthorized modifications.
- Interactive policy explanations: AR guides can walk users through their policy coverage in a vehicle’s context, pointing out features like airbag coverage or towing benefits tied to specific vehicle components.
Voice-Assisted Comparisons and Smart Assistant Integration
Voice-activated interfaces are simplifying the comparison process, allowing users to interact with insurance tools hands-free via smart speakers or mobile assistants. This trend aligns with the rise of conversational AI, where natural language processing (NLP) enables seamless policy inquiries, claims filing, and side-by-side comparisons."Voice-assisted tools lower the barrier for users with limited digital literacy or those multitasking (e.g., driving), while also enabling multilingual support for diverse markets."Key implementations include:
- Natural language queries: Users can ask, "Compare comprehensive coverage for a 2022 SUV with under $150/month, excluding gap insurance," and receive instant, tailored results with explanations for each option.
- Context-aware recommendations: Voice assistants integrate with telematics data to suggest coverage adjustments. For example, if a user’s driving habits indicate low risk, the assistant might recommend switching to a pay-per-mile plan.
- Claim initiation: Voice commands trigger automated claim filing, with AR or photo uploads guided through verbal prompts (e.g., "Point your camera at the front bumper to capture the damage").
- Multilingual and accessibility features: Voice tools support regional dialects and screen-reader compatibility, expanding reach to non-native English speakers or users with disabilities.
Auto insurance comparison tools have redefined the policy selection process by merging data-driven precision with user-centric design. They empower consumers to cut through industry jargon, compare apples-to-apples coverage, and secure policies that align with their financial and safety priorities. As technology advances—from predictive analytics to blockchain-based transparency—they will continue to bridge gaps between insurers and buyers, fostering trust and efficiency. For users, the message is clear: the right tool doesn’t just save time; it unlocks smarter, more affordable protection tailored to a rapidly changing world.
Frequently Asked Questions
How do auto insurance comparison tools save money on premiums?
Auto insurance comparison tools save money by scanning multiple insurers for the best rates. They analyze coverage options, discounts, and user profiles to identify affordable yet comprehensive policies. Users can compare quotes side-by-side, ensuring competitive pricing without manual research.
What features should I look for in an auto insurance comparison website?
Key features include real-time quote comparisons, coverage customization tools, provider transparency, discounts filters, user reviews, and mobile compatibility. Advanced tools may offer bundling options, claims assistance, or AI-driven recommendations based on driving habits.
Are auto insurance comparison tools safe to use with personal data?
Reputable comparison tools use encryption and comply with data protection laws like GDPR or CCPA. They share minimal data with insurers and avoid selling user information. Always check privacy policies and reviews for trustworthiness before entering details.
Do these tools work for all types of drivers, including high-risk or seniors?
Yes, comparison tools cater to all driver types, including high-risk drivers, seniors, or those with unique needs. They display quotes from insurers specializing in specific demographics, such as usage-based programs for low-mileage drivers or SR-22 filings for high-risk profiles.
How do comparison tools integrate with insurance providers’ systems?
Tools integrate via APIs that connect to insurers’ underwriting and quoting systems. This allows seamless data exchange for quotes, policy details, and sometimes even direct enrollment. Partnerships with providers ensure accurate, up-to-date information is displayed for users.
What’s the future of auto insurance comparison tech, like AI or blockchain?
Future trends include AI-driven personalized recommendations, blockchain for secure policy transactions, and telematics integration for dynamic pricing. Voice assistants and chatbots may also streamline comparisons, while regulatory tech (RegTech) ensures compliance with evolving insurance laws.
Related articles
Auto Insurance Comparison Quote Guide Key Insights
Get expert insights on comparing auto insurance quotes with this Auto Insurance Comparison Quote Guide Key Insights—save money, pick the best coverage,…

Auto Insurance Car Insurance Explained Simply
Understand Auto Insurance & Car Insurance Explained Simply—coverage types, costs, and how policies protect drivers. Get clear answers on liability,…

Auto Insurance Car Comparison Guide For Smart Drivers
Discover the best auto insurance rates with our Auto Insurance Car Comparison Guide For Smart Drivers—compare policies, save money, and make informed…
Auto Car Insurance Comparison Key Steps And Insights
Discover Auto Car Insurance Comparison Key Steps And Insights to save money, find the best coverage, and avoid common pitfalls—expert tips for smart…

Auto Insurance For Business Vehicles Essentials And Solutions
Discover essential Auto Insurance For Business Vehicles Essentials And Solutions—coverage types, cost factors, and expert tips to protect your fleet…
