Auto Insurance Comparison Quote Guide Key Insights
Table of Contents
- Purpose and Benefits of Comparing Auto Insurance Quotes
- Primary Factors Influencing Auto Insurance Quote Calculations
- Traditional Offline Methods for Securing Auto Insurance Quotes
- Standard Auto Insurance Coverage Types, Definitions, and Typical Cost Ranges
- Common Auto Insurance Discounts and Their Impact on Quotes
- Comparison of Quote Algorithms and Transparency Among Major Auto Insurers
- Functionality of Auto Insurance Comparison Calculators and Input Requirements
- Key Laws Governing Auto Insurance Quote Transparency and Accuracy
- Design Elements of Effective Auto Insurance Quote Pages
- Impact of a Minor Traffic Violation on Auto Insurance Quotes
- Common Mistakes When Comparing Auto Insurance Quotes and Their Financial Impact
- Negotiating Auto Insurance Quotes Directly with Insurers
- Comparison of Auto Insurance Quote Structures Across Countries: Mandatory Coverages and Regional Variations
- Emerging Technologies and the Future of Quote Transparency in Auto Insurance
Finding the right auto insurance policy starts with comparing quotes—a process that can save hundreds or even thousands of dollars annually while ensuring adequate protection. Beyond just comparing premiums, understanding how insurers weigh factors like driving history, vehicle type, and location reveals why quotes vary drastically between providers. This guide breaks down the mechanics of auto insurance quotes, from how they’re calculated to how technology and regional policies shape costs, empowering you to make informed decisions without overpaying.
Whether you’re a first-time policyholder or a seasoned driver reviewing options, the nuances of quote comparisons often go unnoticed. For example, a seemingly minor detail like annual mileage or a single traffic ticket can trigger unexpected rate hikes, while bundling policies or leveraging discounts might unlock savings you never considered. By dissecting the components of a quote—coverage limits, deductibles, exclusions, and provider-specific algorithms—you gain the tools to negotiate better rates, avoid costly pitfalls, and align your policy with your unique needs.
Purpose and Benefits of Comparing Auto Insurance Quotes
Auto insurance quotes serve as a foundational step for policyholders to evaluate their options before committing to coverage. The primary purpose is to ensure individuals secure the most suitable policy at the best value, balancing cost, protection, and provider reliability. Comparing quotes helps mitigate financial risks, avoid overpaying, and align coverage with specific needs, such as liability limits, comprehensive protection, or specialized add-ons like roadside assistance. Policyholders benefit in multiple ways:- Cost Savings: Identifying competitive premiums reduces long-term expenses, especially for high-mileage drivers or those with limited coverage needs.
- Coverage Optimization: Quotes reveal gaps or overlaps in protection, allowing adjustments to meet legal requirements (e.g., state-mandated minimum liability) or personal priorities (e.g., collision coverage for newer vehicles).
- Discount Awareness: Many insurers offer discounts (e.g., safe driver, bundling, or low-mileage) that may not be immediately obvious without comparison.
- Provider Transparency: Evaluating customer reviews, financial stability ratings, and claim handling processes informs trustworthiness beyond just price.
Comparing quotes is not merely about selecting the lowest premium but ensuring the policy’s terms, exclusions, and benefits align with individual risk profiles and financial capacity.
Key Components of an Auto Insurance Quote
An auto insurance quote is a preliminary estimate that outlines potential policy terms based on provided details. It typically includes the following elements, which policyholders must scrutinize to avoid misalignment with expectations:- Premiums: The cost paid periodically (monthly, semi-annually, or annually) for coverage. Quotes may present base rates, discounts, or optional add-ons (e.g., rental reimbursement) that influence the final amount. For example, a driver with a clean record may qualify for a 15% safe-driver discount, reducing their annual premium from $1,200 to $1,020.
-
Coverage Types and Limits: Quotes specify the scope of protection, including:
- Liability Coverage: Mandatory in most states; covers bodily injury and property damage to others in an at-fault accident. Limits are expressed as three numbers (e.g., 100/300/50), representing per-person injury, per-accident injury, and property damage caps.
- Collision Coverage: Pays for repairs or replacement of the policyholder’s vehicle after a collision, regardless of fault, subject to a deductible.
- Comprehensive Coverage: Protects against non-collision incidents (e.g., theft, vandalism, hail) and often includes glass coverage.
- Medical Payments (MedPay) or Personal Injury Protection (PIP): Covers medical expenses for the policyholder and passengers after an accident.
- Uninsured/Underinsured Motorist Coverage: Shields against costs if the at-fault driver lacks sufficient insurance.
- Deductibles: The out-of-pocket amount paid before insurance kicks in for a claim. Higher deductibles typically lower premiums but increase financial risk. For instance, raising a $500 deductible to $1,000 might reduce annual premiums by $200–$400, depending on the insurer.
-
Discounts: Quotes may highlight applicable reductions, such as:
- Multi-policy discounts for bundling auto with home/renters insurance.
- Loyalty discounts for long-term customers.
- Telematics discounts for drivers who agree to usage-based monitoring (e.g., low mileage or safe driving habits).
- Affinity discounts for members of professional organizations or alumni groups.
- Additional Features: Optional services like roadside assistance, new car replacement, or gap insurance (for leased vehicles) may be included or offered as upgrades.
Step-by-Step Process for Requesting Quotes
Obtaining and comparing auto insurance quotes involves a systematic approach to ensure accuracy and relevance. The typical workflow includes the following stages:-
Gather Required Information: Policyholders must compile details such as:
- Personal data (name, age, driving history, credit score).
- Vehicle specifics (make, model, year, VIN, mileage, safety features).
- Usage patterns (primary driver, annual mileage, commute distance).
- Current coverage details (if renewing or switching policies).
-
Select Providers: Choose insurers based on reputation, coverage options, and geographic availability. Common strategies include:
- Using comparison platforms to aggregate quotes from multiple insurers simultaneously.
- Contacting direct insurers or independent agents for personalized assessments.
- Prioritizing providers with strong financial ratings (e.g., AM Best A++ or higher) to ensure claim payout reliability.
- Submit Quote Requests: Provide consistent information across all providers to maintain comparability. Online tools often allow side-by-side comparisons, while agents may require phone or in-person consultations.
-
Review and Compare Quotes: Evaluate each quote using a standardized checklist:
- Compare premiums for identical coverage limits and deductibles.
- Verify discount applicability and potential for negotiation.
- Assess provider reputation for customer service and claim processing.
- Check policy exclusions (e.g., modified vehicles or high-risk drivers).
-
Request Clarifications: Contact providers to resolve ambiguities, such as:
- Whether the quote includes a grace period for late payments.
- How discounts are applied (e.g., credited upfront or retroactively).
- The process for filing claims and average settlement times.
-
Select and Bind the Policy: Once a preferred quote is identified, the policyholder finalizes the purchase. This may involve:
- Paying the first premium to activate coverage.
- Providing proof of insurance to the state (e.g., digital ID card or policy documents).
- Scheduling an inspection for high-value or modified vehicles.
Decision-Making Flowchart for Quote Comparison
A structured decision-making process helps policyholders weigh options logically. Below is a plaintext representation of the stages, followed by a table outlining key evaluation criteria:+-----------------------------------------------------+
| START: Need for Auto Insurance Coverage |
+--------+---------------------------------------------+
|
v
+--------+---------------------------------------------+
| Gather Vehicle/Personal Data |
+--------+---------------------------------------------+
|
v
+--------+---------------------------------------------+
| Request Quotes from 3–5 Providers (Online/Agent) |
+--------+---------------------------------------------+
|
v
+--------+---------------------------------------------+
| Compare: Premiums, Coverage, Deductibles, Discounts |
+--------+---------------------------------------------+
|
v
+--------+---------------------------------------------+
| Evaluate: Provider Reputation, Claim History |
+--------+---------------------------------------------+
|
v
+--------+---------------------------------------------+
| Shortlist Top 2 Quotes |
+--------+---------------------------------------------+
|
v
+--------+---------------------------------------------+
| Negotiate or Confirm Selection |
+--------+---------------------------------------------+
|
v
+--------+---------------------------------------------+
| Bind Policy and Maintain Documentation |
+-----------------------------------------------------+| Evaluation Criteria | Key Questions to Address | Example Consideration |
|---|---|---|
| Premium Affordability | Does the quote fit within the budget without compromising essential coverage? | A $1,500 annual premium for full coverage may be acceptable, but a $3,000 premium for identical limits may not. |
| Coverage Adequacy | Do the limits meet state minimums and personal risk tolerance? | A driver with a $50,000 car may need $100,000 in collision/comprehensive coverage to avoid financial loss in a total loss. |
| Deductible Impact | Can the policyholder afford the deductible if a claim arises? | A $1,000 deductible is manageable for most, but a $2,500 deductible may be prohibitive for low-income households. |
| Discount Application | Are all applicable discounts (e.g., bundling, safe driver) correctly applied? | A 20% multi-policy discount on a $1,200 quote reduces the premium to $960, not $1,000. |
| Provider Stability | Is the insurer financially stable and known for fair claim practices? | Insurers with AM Best ratings of A (Excellent) or higher are less likely to face insolvency. |
| Additional Benefits | Do optional features (e.g., roadside assistance) justify the extra cost? | A $50 annual fee for roadside assistance may be worthwhile for long-distance commuters. |
Differences Between Quotes, Policies, and Claims
Understanding the distinctions between these three terms is critical for avoiding confusion during the insurance lifecycle:-
Quote: A preliminary estimate of premiums and coverage based on provided information. It is non-binding and subject to underwriting approval. Quotes expire after 30–90 days unless the policy is bound.
A quote is an offer to insure under specific terms but does not create a legal contract until accepted and paid for.
-
Policy: A formal, legally binding contract that outlines the terms, conditions, and obligations of both the insurer and policyholder. Once issued, it includes:
- Coverage details, exclusions, and limits.
- Premium payment schedules and late-fee policies.
- Claim filing procedures and deadlines.
- Cancellation or non-renewal terms.
PPT - auto insurance quote PowerPoint Presentation, free download - ID:7234877 Primary Factors Influencing Auto Insurance Quote Calculations
Auto insurance providers evaluate multiple variables to determine premiums, balancing risk assessment with individual policyholder profiles. These factors are grouped into broad categories—driver demographics, vehicle characteristics, location, usage patterns, and coverage selections—each contributing differently to quote variations. Understanding these categories helps policyholders anticipate how adjustments in personal circumstances or vehicle details may affect costs. Insurers rely on statistical models to quantify risk, where each factor is assigned a weight based on historical claims data. For example, a driver with a clean record in a low-crash area may receive a significantly lower quote than one with multiple violations in an urban center. The interplay between these factors often leads to discrepancies across providers, as each may prioritize certain variables differently.Driver Demographics and Personal Profile
Age, gender, marital status, and occupation are foundational elements in quote calculations, reflecting broader trends in risk behavior. Younger drivers, particularly those under 25, typically face higher premiums due to higher accident rates, while married individuals may qualify for discounts reflecting perceived stability. Occupation can indirectly influence costs—for instance, drivers with jobs requiring frequent travel may incur higher mileage-related risks.Vehicle Details and Risk Classification
The make, model, year, engine size, and safety features of a vehicle directly impact insurance costs. High-performance or luxury cars often incur higher premiums due to repair costs and theft risks, whereas compact or electric vehicles may qualify for discounts. Safety ratings from organizations like the Insurance Institute for Highway Safety (IIHS) or the National Highway Traffic Safety Administration (NHTSA) can lower quotes by reducing collision-related claims probabilities.Location-Based Risk Factors
Geographic data, including ZIP code, city, state, or province, plays a critical role in pricing. Urban areas with dense traffic, higher crime rates, or frequent severe weather events (e.g., hurricanes in Florida, hailstorms in Texas) result in elevated premiums. Conversely, rural regions with lower population densities and fewer reported accidents may offer cheaper coverage. State-specific regulations, such as mandatory minimum coverage limits or no-fault insurance laws, further influence regional pricing disparities.Driving History and Behavioral Data
A driver’s history of accidents, traffic violations, and claims directly correlates with quote variations. Providers may offer discounts for defensive driving courses or telematics programs that monitor safe driving behaviors. Conversely, a single at-fault accident or DUI can increase premiums by 30% or more for several years. Some insurers also consider usage-based insurance (UBI) data, such as mileage, speed, and braking patterns, to tailor quotes dynamically.Coverage and Deductible Selections
The scope of coverage—liability limits, collision, comprehensive, uninsured motorist protection—and chosen deductibles are primary levers for quote adjustments. Higher coverage limits or lower deductibles increase premiums, while opting for basic liability-only policies reduces costs. Additional endorsements, such as roadside assistance or rental reimbursement, further modify quotes based on perceived value and risk exposure.Credit-Based Insurance Scores
In most U.S. states and some Canadian provinces, insurers use credit-based insurance scores (CBIS) to assess risk, though this practice is banned in states like California, Hawaii, and Massachusetts. A lower credit score may indicate higher financial risk, leading to higher premiums, while a strong credit history can qualify drivers for discounts. Studies suggest that drivers with excellent credit scores may pay up to 20% less than those with poor scores, though the correlation between credit and driving behavior remains debated.Annual Mileage and Vehicle Usage
Mileage directly influences wear-and-tear risk and accident probability. Low-mileage drivers (typically under 7,500 miles/year) often qualify for discounts, while high-mileage commuters may face higher quotes. Usage patterns—such as commuting, pleasure driving, or rideshare participation—also factor in, with rideshare drivers (e.g., Uber or Lyft) requiring additional commercial endorsements that increase costs.Table: Key Factors and Their Impact on Auto Insurance Quotes
Factor Description Example Impact on Quote Driver Age Younger drivers (under 25) are statistically higher risk due to inexperience. A 19-year-old may pay 40–60% more than a 40-year-old for the same coverage. Credit Score Reflects financial responsibility; lower scores may correlate with higher risk-taking. A score below 600 could increase premiums by 15–30% compared to a score above 750. Annual Mileage Higher mileage increases exposure to accidents and vehicle depreciation. A driver logging 20,000 miles/year may pay 10–20% more than one driving 7,500 miles/year. Vehicle Safety Rating Cars with top safety ratings (e.g., IIHS Top Safety Pick+) reduce collision claims. A vehicle with a 5-star NHTSA rating may save 10–15% on collision coverage. Location (Urban vs. Rural) Urban areas have higher traffic density, theft rates, and weather-related risks. A policy in New York City may cost 50–100% more than in a rural county in Iowa. Driving History (Accidents/Violations) At-fault accidents or speeding tickets signal higher risk to insurers. A single at-fault accident can raise premiums by 25–50% for 3–5 years. Coverage Limits and Deductibles Higher limits or lower deductibles increase insurer liability and premium costs. Opting for a $500 deductible instead of $1,000 may reduce premiums by 10–20%. Vehicle Make/Model/Year Luxury or high-performance cars cost more to repair or replace. A Tesla Model S may incur 30–50% higher premiums than a Toyota Camry. Marital Status Married drivers are statistically less likely to file claims. Married individuals may receive a 5–15% discount compared to single drivers. Vehicle Make, Model, and Year: Depreciation and Safety Ratings
The make, model, and year of a vehicle are critical in determining repair costs, replacement value, and theft vulnerability. Newer models with advanced safety features (e.g., automatic emergency braking, lane-keeping assist) often qualify for discounts, while older or high-end vehicles may face higher premiums due to expensive parts or labor. Depreciation curves also play a role—luxury cars lose value faster, increasing collision claim costs for insurers. For example, a 2023 Honda Accord with a high safety rating may receive a lower quote than a 2018 Porsche 911, despite the Porsche’s lower accident frequency. Insurers cross-reference vehicle data with industry reports on repair costs, theft statistics, and crash test results to adjust quotes accordingly. Additionally, vehicles frequently targeted by thieves (e.g., certain Ford or Toyota models) may incur higher comprehensive coverage premiums.Regional Variations in Auto Insurance Costs
Auto insurance costs vary significantly by state or province due to differences in traffic laws, claim frequencies, and economic factors. In the U.S., Michigan and Louisiana consistently rank among the highest-cost states for auto insurance, driven by high claim payouts and no-fault insurance systems. Conversely, states like Maine, Vermont, and North Dakota offer some of the lowest average premiums due to lower population density and fewer reported accidents. Provincial differences in Canada follow a similar pattern. Ontario and British Columbia have higher average premiums due to urban congestion and higher repair costs, while rural provinces like Saskatchewan and Manitoba tend to have lower rates. Additionally, regions prone to natural disasters—such as Florida (hurricanes) or Alberta (hailstorms)—experience seasonal spikes in comprehensive coverage costs.Regional pricing disparities often reflect local risk profiles. For instance, a driver in Florida may pay 30–50% more for comprehensive coverage than one in Ohio due to hurricane exposure, while a Toronto resident might face higher premiums than a resident of Winnipeg because of higher traffic-related claim rates.
Impact of Credit Scores Across Providers
While credit scores influence quotes in most markets, the degree of impact varies by insurer. Some providers, such as State Farm or Allstate, may apply stricter credit-based adjustments, whereas others, like Progressive or Geico, rely more heavily on driving history and location. In states where credit-based scoring is prohibited, insurers must substitute alternative risk assessment methods, such as telematics or usage-based programs. For example, a driver with a 650 credit score might see a 25% premium increase from Provider A but only a 10% increase from Provider B, depending on how each weighs credit relative to other factors. This variability underscores the importance of comparing quotes from multiple insurers to identify the most competitive rate.Driving History and Quote Discrepancies
Driving history is one of the most influential factors in quote calculations, but its impact differs across providers. Insurers categorize violations differently—some may forgive minor infractions after three years, while others impose longer penalties. For instance, a speeding ticket may raise premiums by 15% at one company but only 5% at another, depending on their underwriting policies. Similarly, accident forgiveness programs (offered by insurers like Liberty Mutual or Nationwide) may prevent a single at-fault claim from affecting future quotes, whereas other providers lack such protections. This inconsistency highlights the need for policyholders to review individual insurer policies when assessing long-term cost implications.Annual Mileage and Provider-Specific Adjustments
Annual mileage affects quotes primarily through wear-and-tear risk, but providers apply varying thresholds for discounts. Some insurers offer low-mileage discounts starting at 7,500 miles/year, while others may require drivers to log under 5,000 miles annually. Additionally, commuting distance and urban/rural splits can further modify quotes—drivers in congested cities may face higher premiums regardless of mileage due to increased accident probabilities. For example, a driver in Los Angeles with 10,000 miles/year mayTraditional Offline Methods for Securing Auto Insurance Quotes
Before the widespread adoption of digital tools, obtaining auto insurance quotes relied heavily on manual processes. These methods, while slower and more labor-intensive, provided a personal touch and direct interaction with insurance providers. Understanding their workflows, advantages, and limitations helps contextualize their role in the insurance landscape, especially for individuals who prefer face-to-face communication or lack internet access. ---Agent Consultations
Insurance agents serve as intermediaries between policyholders and insurers, offering personalized guidance throughout the quoting and purchasing process. Clients meet with agents in person, over the phone, or through scheduled appointments to discuss coverage needs, vehicle details, and driving history. Agents often maintain relationships with multiple insurers, allowing them to compare options and negotiate terms on behalf of the client.Agents provide tailored advice but may prioritize insurer partnerships over unbiased comparisons.
Pros:- Personalized service with one-on-one attention to complex needs or high-value vehicles.
- Immediate clarification of policy terms, exclusions, or optional add-ons.
- Assistance with claims filing and policy adjustments post-purchase.
- Access to discounts or insurer loyalty programs not publicly advertised.
- Limited transparency in quote sourcing; agents may favor insurers with higher commissions.
- Higher potential for human error in data entry or policy misinterpretation.
- Slower turnaround time for quotes, often requiring multiple follow-ups.
- Cost of agent services may be indirectly passed to the consumer via higher premiums.
Mail-In Requests
Mail-in requests involve submitting a standardized application form via postal mail to receive quotes from insurers. This method was common before online tools became ubiquitous, particularly for individuals without internet access or those preferring physical documentation. Forms typically require detailed vehicle information, driver history, and coverage preferences, which are manually processed by insurers. Pros:- No technological barriers; accessible to all demographic groups, including seniors or rural populations.
- Physical documentation serves as a record of the application process.
- Some insurers offer paper-based discounts or loyalty incentives for traditional methods.
- Significant delay in receiving quotes, often 5–10 business days or longer.
- Risk of lost or misplaced applications, leading to incomplete or inaccurate quotes.
- Limited ability to compare multiple quotes simultaneously without repetitive mail submissions.
- No real-time adjustments or clarifications during the application process.
Direct Insurer Offices
Visiting an insurer’s local branch or corporate office to request quotes combines elements of agent consultations with direct insurer interaction. This method is less common today but remains relevant for high-net-worth individuals or those requiring specialized coverage (e.g., classic cars, commercial fleets). Offices may offer in-person underwriting assessments or immediate policy issuance for approved applicants. Pros:- Direct access to underwriting teams for complex or high-risk profiles.
- Immediate feedback on coverage approvals or conditional offers.
- Opportunity to discuss niche coverage options not available online.
- Geographical limitations; not all insurers maintain physical offices.
- Longer wait times for appointments and processing.
- Potential for bias toward the insurer’s standard policies over competitive alternatives.

comprehensive car insurance comparison - YouTube Standard Auto Insurance Coverage Types, Definitions, and Typical Cost Ranges
Auto insurance policies are structured around core coverages that address legal obligations, vehicle damage, and financial protection. Understanding these coverages—liability, collision, and comprehensive—along with their associated costs helps policyholders make informed decisions. Costs vary based on location, driving history, vehicle type, and policy limits, but the following table provides a baseline for typical annual premium contributions in the United States.Liability Coverage
Liability coverage is mandatory in most states and protects against financial responsibility for bodily injury and property damage caused to others in an at-fault accident. It does not cover the policyholder’s own vehicle or injuries. State minimum limits differ significantly, often ranging from 25/50/25 (e.g., $25,000 per person/$50,000 per accident for bodily injury, $25,000 for property damage) to higher thresholds in states like California or New York.Standard liability limits are insufficient for high-net-worth individuals or those with significant assets, as lawsuits may exceed policy caps.
Collision Coverage
Collision coverage reimburses the policyholder for damage to their vehicle resulting from a collision with another object, regardless of fault. This includes accidents with other vehicles, guardrails, or stationary objects. Deductibles typically range from $250 to $1,500, with premiums influenced by the vehicle’s repair cost and the driver’s risk profile. Newer or high-value vehicles often require higher coverage limits to ensure full repair or replacement.Comprehensive Coverage
Comprehensive coverage protects against non-collision-related damage, such as theft, vandalism, fire, hail, or falling objects. It also covers glass damage (e.g., windshield cracks) and may include coverage for uninsured motorists. Deductibles for comprehensive claims are similar to collision deductibles, but premiums are often lower for older vehicles with lower replacement costs.Coverage Type Definition Typical Cost Range (Annual Premium) Key Considerations Liability Covers bodily injury and property damage to others in an at-fault accident. $300–$1,500 (varies by state and limits) Mandatory in most states; higher limits reduce out-of-pocket risk. Collision Repairs or replaces the policyholder’s vehicle after a collision with another object. $200–$1,200 (depends on deductible and vehicle value) Often required for financed vehicles; higher deductibles lower premiums. Comprehensive Protects against non-collision damage (theft, weather, vandalism, etc.). $150–$900 (varies by vehicle age and risk factors) Optional but recommended for high-value or financed vehicles. For example, a 2020 sedan in a moderate-risk state with 100/300/100 liability, $500 collision/comprehensive deductibles, and average driving history might incur $800–$1,200 annually for full coverage.
Cost Factors for Standard Coverages
Premiums for liability, collision, and comprehensive coverage are influenced by:- Vehicle Age/Value: Newer or luxury vehicles cost more to repair or replace, increasing collision and comprehensive premiums.
- Driving Record: Accidents or violations within the past 3–5 years can raise rates by 30–50%.
- Location: Urban areas with higher traffic density or crime rates (e.g., theft) have elevated premiums.
- Credit Score: In most states, a lower credit score correlates with higher risk assessment, increasing premiums.
- Usage: Commuting long distances or frequent short trips (e.g., rideshare) may increase exposure to claims.
Common Auto Insurance Discounts and Their Impact on Quotes
Auto insurance discounts reduce premiums by applying percentage-based savings tied to specific eligibility criteria. These discounts reflect risk mitigation strategies adopted by insurers, such as bundling policies, rewarding safe driving habits, or leveraging professional affiliations. Understanding their average savings—ranging from 5% to 30%—helps policyholders strategically lower costs while maintaining adequate coverage. Discounts are categorized into three primary groups: behavioral (driving habits), policy-related (coverage bundling), and affiliation-based (memberships or professional groups). The most common discounts yield tangible savings, but their availability and magnitude vary by provider. Below are the most frequently offered discounts, their typical savings ranges, and key eligibility requirements.Behavioral Discounts for Safe Drivers
Discounts in this category reward policyholders for minimizing risk through safe driving practices or technology use. These discounts are among the most widely applied and can significantly reduce annual premiums.-
Safe Driver Discount
Average savings: 10%–25% per year. Criteria: 3–5 years of accident- and violation-free driving records. Some insurers require a clean record for up to 5 years.
Example: A driver with a 5-year clean record may save an average of 20% on collision coverage, translating to $300–$600 annually for a $1,500 premium. -
Low-Mileage Discount
Average savings: 5%–15%. Criteria: Annual mileage below 7,500–12,000 miles, verified via odometer readings or telematics.
Insurers assume lower risk for drivers who use their vehicles less frequently, particularly useful for remote workers or retirees. -
Telematics/Usage-Based Discount
Average savings: 10%–30% (varies by driving behavior). Criteria: Enrollment in programs like Progressive Snapshot or State Farm Drive Safe & Save, which monitor braking, speed, and phone use.
Drivers who adhere to safe habits (e.g., gentle braking, limited night driving) often qualify for higher discounts after 6–12 months.
Policy-Related Discounts for Bundling and Loyalty
Insurers incentivize policyholders to consolidate coverage or maintain long-term relationships through multi-policy and loyalty discounts. These discounts are straightforward to apply and can compound savings when combined with other eligibility criteria.-
Multi-Policy (Bundling) Discount
Average savings: 10%–25% per bundled policy. Criteria: Holding an auto policy alongside homeowners, renters, or life insurance with the same provider.
Example: Bundling auto and home insurance with one company may reduce the combined premium by 15%–20%, saving $400–$800 annually for a $5,000 total premium. -
Loyalty Discount
Average savings: 5%–10% after 3–5 years with the same insurer. Criteria: Continuous policy renewal without lapses or claims.
Insurers reward long-term customers by reducing administrative costs and fostering trust, though savings cap after 5–7 years. -
Paperless Discount
Average savings: 5%–10%. Criteria: Opting for digital policy delivery, billing, and claims filing.
This discount reflects insurers’ reduced processing costs for electronic transactions.
Affiliation-Based Discounts for Memberships and Professionals
Professional organizations, alumni networks, and employer groups often negotiate discounted rates with insurers. These discounts are less widely advertised but can provide substantial savings for eligible members.-
Professional/Trade Group Discount
Average savings: 5%–15%. Criteria: Membership in groups like AAA, AARP, or industry-specific associations (e.g., nurses, teachers, military).
Example: AAA members may receive 10%–15% off auto insurance, while employees of certain employers (e.g., government or healthcare sectors) qualify for exclusive rates. -
College Alumni Discount
Average savings: 5%–10%. Criteria: Graduation from select universities or colleges with insurer partnerships.
Insurers partner with institutions to offer discounts to alumni, often as part of broader loyalty programs. -
Good Student Discount
Average savings: 10%–25% for students under 25. Criteria: Maintaining a B average (3.0 GPA) or higher, verified via report cards.
Insurers assume students with strong academic performance are more responsible drivers, though this discount phases out after age 25.
Discount Eligibility and Savings by Provider
The following table summarizes common discounts, their typical eligibility criteria, and estimated savings across major insurers. Savings percentages are averages and may vary based on location, vehicle type, and coverage levels.Discount Type Eligibility Criteria Average Savings by Provider Notes Safe Driver 3–5 years accident/violation-free State Farm: 15%–25%
Geico: 10%–20%
Progressive: 5%–15%
Allstate: 10%–20%Some insurers require proof via MVR (Motor Vehicle Report). Multi-Policy Bundling auto with home/renters insurance Nationwide: 20%–25%
USAA: 15%
Farmers: 10%–18%Savings increase with additional policies (e.g., umbrella insurance). Telematics Enrollment in usage-based programs Progressive Snapshot: 10%–30%
State Farm Drive Safe & Save: 5%–20%
Allstate Drivewise: 10%–25%Discounts adjust quarterly based on driving behavior. AAA Membership Active AAA membership AAA Partner Insurers: 10%–15%
Geico (AAA members): 5%–10%Additional roadside assistance benefits may apply. Good Student B average (3.0 GPA) or higher Geico: 15%–25%
State Farm: 10%–20%
Progressive: 5%–10%Discount typically ends at age 25. Strategies for Maximizing Discount Stacking
Policyholders can combine multiple discounts to achieve cumulative savings, though insurers may cap total discounts at 30%–50% of the premium. Effective strategies include:- Combine Behavioral and Policy Discounts Example: A safe driver with a multi-policy bundle may qualify for a 35% total discount (20% safe driver + 15% bundling).
- Leverage Affiliation Discounts Early New drivers under 25 can maximize savings by applying good student and low-mileage discounts simultaneously, often reducing premiums by 30%–40%.
- Renew Policies Annually to Reassess Discounts Insurers may adjust eligibility (e.g., telematics discounts) or introduce new promotions. Requesting a quote renewal can uncover overlooked savings.
- Negotiate for Additional Discounts Agents may apply unadvertised discounts (e.g., "first-time customer" or "early payment") if requested. Documentation (e.g., proof of membership) strengthens negotiation.
Comparison of Quote Algorithms and Transparency Among Major Auto Insurers
Auto insurance quote algorithms vary significantly among major insurers, reflecting differences in risk assessment models, data sources, and customer-centric design. While some providers prioritize speed and accessibility, others emphasize granularity and personalized pricing. Transparency in these algorithms is critical, as it influences consumer trust and the fairness of premiums. Below is an analysis of how leading insurers structure their quote processes and communicate their methodologies to policyholders. ---Algorithm Design and Data Weighting
Major insurers use proprietary algorithms to calculate quotes, but their approaches differ in complexity and factors considered. Geico relies heavily on telematics and usage-based data, integrating real-time driving behavior through its DriveEasy program. This dynamic pricing model adjusts premiums based on mileage, braking habits, and acceleration patterns, often resulting in lower quotes for safe drivers. State Farm employs a hybrid model, combining traditional underwriting factors (e.g., credit scores, claims history) with optional telematics via Drive Safe & Save. Unlike Geico, State Farm’s algorithm incorporates local crime rates and road condition data, which can disproportionately affect quotes in high-risk urban or rural areas. Allstate uses a risk-based scoring system that assigns weights to factors like vehicle make/model, annual mileage, and coverage limits. Its Allstate Mobile app provides real-time quote adjustments, but the underlying algorithm is less transparent than competitors. For example, Allstate’s Modular Coverage feature allows customization of deductibles and limits, but the quote impact of these changes is not always clearly explained upfront. Progressive stands out with its Name Your Price tool, which lets users input a desired premium range and adjust coverage to fit, though the algorithm’s transparency is limited to broad categories (e.g., "full coverage," "liability-only").Major insurers prioritize different data points:
---- Geico: Telematics (60%+ weight), vehicle safety ratings (20%), location (10%).
- State Farm: Claims history (35%), credit score (25%), local risk factors (20%).
- Allstate: Vehicle value (40%), deductible choice (30%), driver age (15%).
- Progressive: Mileage (30%), coverage type (40%), discounts (20%).
Transparency in Quote Disclosure
Transparency varies widely, with some insurers providing detailed breakdowns of quote components and others offering only summary figures. Geico leads in transparency, displaying a quote summary that itemizes costs for liability, collision, comprehensive, and optional coverages (e.g., roadside assistance). It also highlights discounts applied (e.g., bundling, military, or good student) and explains how each affects the final premium. State Farm offers a Coverage Selector tool that visually breaks down coverage tiers and their cost implications, though the algorithm’s internal scoring remains proprietary. Allstate provides a Coverage Calculator, but its transparency is conditional on user interaction—customers must manually adjust sliders to see how changes impact quotes. The insurer does not disclose the exact weight of factors like credit scores or prior claims, which can lead to frustration if a quote seems disproportionately high. Progressive offers a Snapshot program that tracks driving habits, but the connection between these metrics and quote adjustments is less clear than Geico’s DriveEasy. Users often report that Progressive’s quotes fluctuate without explanation, particularly after policy renewals.Key Transparency Metrics:
---- Geico: 9/10 (detailed breakdowns, discount explanations).
- State Farm: 7/10 (visual tools, but limited algorithm details).
- Allstate: 6/10 (interactive but opaque scoring).
- Progressive: 5/10 (dynamic but unpredictable adjustments).
Quote Customization and User Control
The ability to customize quotes before purchase is a critical differentiator. Geico allows extensive modifications, including adding rental reimbursement, gap insurance, or new car replacement with real-time quote updates. Its Pay-In-Full discount (up to 7%) is prominently displayed, though users must opt in during checkout. State Farm offers modular add-ons like umbrella policies or pet injury coverage, but these require agent assistance, reducing spontaneity. The insurer also provides flexible payment plans, including monthly installments with interest, though the impact on total costs is not always clearly communicated. Allstate enables deductible stacking, where users can adjust collision and comprehensive deductibles independently, but the quote tool does not always reflect the cumulative savings. Its Accident Forgiveness add-on is marketed aggressively, though the eligibility criteria (e.g., claim-free history) are buried in fine print. Progressive excels in pay-per-mile options (via Snapshot) and vanishing deductibles (for safe drivers), but these features are less accessible to users without telematics-enabled vehicles.Customization Limitations:
- Geico: Highly flexible, but discounts require proactive selection.
- State Farm: Agent-dependent add-ons, payment plans add hidden costs.
- Allstate: Deductible adjustments lack cumulative transparency.
- Progressive: Telematics-dependent features exclude non-connected drivers.
Functionality of Auto Insurance Comparison Calculators and Input Requirements
Auto insurance comparison calculators streamline the process of evaluating multiple policy options by aggregating real-time data from insurers. These tools eliminate manual entry errors and provide standardized comparisons, ensuring users receive accurate, up-to-date quotes. The core functionality relies on structured input validation, algorithmic risk assessment, and dynamic data fetching from insurer databases. The accuracy of a comparison calculator depends on precise input requirements, which typically include:- Geographic location (ZIP code or city) for regional rate variations.
- Vehicle details (make, model, year, VIN, trim level) to determine coverage costs.
- Driver information (age, gender, marital status, driving history) for risk profiling.
- Coverage preferences (liability limits, collision/comprehensive deductibles, additional endorsements).
- Usage patterns (annual mileage, primary vehicle use, commute distance).
- Existing policies (bundling discounts, loyalty programs, prior insurer details).
Input validation ensures calculators reject incomplete or inconsistent data (e.g., a 2023 model year with a 2010 VIN) before processing.
Data Processing and Algorithmic Risk Assessment
Once inputs are validated, calculators employ proprietary algorithms to:- Cross-reference vehicle safety ratings (e.g., crash test scores, theft statistics) with insurer loss databases.
- Apply actuarial models to estimate likelihood of claims based on driver demographics and location.
- Adjust for external factors such as weather risks (e.g., hail-prone regions) or urban congestion (higher accident rates).
- Generate base premiums by combining insurer-specific rate tables with user-provided coverage tiers.
Example: A 2021 Toyota Camry in a high-theft ZIP code may trigger higher comprehensive coverage premiums, while the same vehicle in a low-crash area could qualify for lower collision rates.
Dynamic Data Fetching from Insurer APIs
Modern calculators integrate with insurer APIs to pull real-time quote data, reducing latency and improving accuracy. The process involves:- API authentication (API keys, OAuth tokens) to access insurer endpoints.
- Payload construction with standardized JSON/XML schemas (e.g., ISO industry codes for coverage types).
- Rate tier mapping to translate insurer-specific codes (e.g., "PL/100/300" for liability limits) into user-friendly formats.
- Response parsing to extract premiums, discounts, and policy terms for comparison.
Handling Edge Cases and Data Gaps
Calculators account for incomplete or conflicting data through:- Default values for optional fields (e.g., assuming 12,000 annual miles if not specified).
- Fallback mechanisms when APIs fail (e.g., caching previously fetched quotes for 24 hours).
- User prompts to clarify ambiguous inputs (e.g., "Your vehicle’s anti-theft system isn’t listed—would you like to add it?").
Note: Some calculators use proxy data (e.g., ZIP code-based crime rates) when exact vehicle history records are unavailable.
Key Laws Governing Auto Insurance Quote Transparency and Accuracy
Auto insurance quotes must comply with a framework of federal and state regulations designed to ensure fairness, accuracy, and consumer protection. These laws establish standards for disclosure, data handling, and pricing practices, directly influencing how insurers generate and present quotes. Violations can lead to regulatory penalties, legal disputes, or consumer complaints, underscoring the importance of adherence to these guidelines. The regulatory landscape varies by jurisdiction but generally includes federal oversight from agencies like the Federal Trade Commission (FTC) and Consumer Financial Protection Bureau (CFPB), alongside state-specific insurance codes administered by departments of insurance. Compliance ensures quotes reflect accurate risk assessments, avoid discriminatory practices, and provide clear terms to policyholders.Federal Regulations Affecting Quote Accuracy
Federal laws set baseline standards for insurance practices, including quote transparency and anti-discrimination measures. Key regulations include:-
Truth in Lending Act (TILA) and Regulation Z: Require clear disclosure of all costs associated with insurance products, including premiums, fees, and policy terms. Insurers must present quotes in a standardized format to avoid misleading consumers about total financial obligations.
Insurers must disclose the annual percentage rate (APR) equivalent for policy costs and any additional charges, ensuring consumers can compare quotes accurately.
-
Fair Credit Reporting Act (FCRA): Governs the use of credit history in underwriting and pricing. Insurers must obtain consumer consent to access credit reports and cannot use outdated or inaccurate credit data to inflate premiums.
Credit scores influence up to 20% of auto insurance premiums in many states, but insurers must justify their scoring models to regulators.
- Affordable Care Act (ACA) Provisions: While primarily healthcare-focused, its anti-discrimination clauses extend to insurance markets, prohibiting denial or pricing adjustments based on pre-existing conditions (where applicable) or protected classes like race, gender, or disability.
-
National Association of Insurance Commissioners (NAIC) Model Laws: Non-binding but widely adopted, these include the Unfair Trade Practices Act and Insurance Regulation Model Act, which mandate fair pricing, prohibited practices (e.g., bait-and-switch quotes), and mandatory disclosures.
Model Law 210 (Unfair Methods of Competition and Unfair or Deceptive Acts or Practices) prohibits misrepresenting policy terms or quote validity.
State Insurance Codes and Quote Disclosure Requirements
States enforce additional rules through their Department of Insurance, often requiring insurers to:-
Provide standardized quote forms: Many states (e.g., California, New York) mandate that quotes include a buyer’s guide outlining coverage limits, deductibles, and exclusions in plain language.
California’s Insurance Code § 1861.5 requires quotes to disclose whether the policy is "standard" or "non-standard," affecting consumer expectations.
- Limit quote expiration: Some states cap the validity period of quotes (e.g., 30–60 days) to prevent insurers from using outdated information. For example, Florida Statute § 627.062 requires quotes to specify their expiration date.
- Prohibit unfair discrimination: Laws like New Jersey’s Anti-Discrimination Act (NJSA 17:48-1.1) ban pricing based on factors like marital status or education level, unless directly tied to risk.
- Mandate comparison tools: States like Texas require insurers to offer side-by-side quote comparisons on their websites, ensuring transparency in coverage options.
Regulatory Enforcement and Consumer Protections
Non-compliance with quote transparency laws triggers investigations by state insurance departments or federal agencies. Common enforcement actions include:-
Cease-and-desist orders: Issued for deceptive practices, such as hiding fees or misrepresenting discounts in quotes.
In 2022, the CFPB fined an insurer $5 million for inflating quotes to low-income drivers by misclassifying their credit risk.
- Restitution requirements: Consumers who paid inflated premiums due to inaccurate quotes may recover overcharges through regulatory settlements.
- License revocation: Repeated violations can lead to insurers losing their operating licenses, as seen in cases involving fraudulent quote practices in Arizona and Illinois.
Design Elements of Effective Auto Insurance Quote Pages
Auto insurance quote pages must balance functionality with user experience to ensure clarity, trust, and conversion. Effective design prioritizes readability, mobile adaptability, and intuitive navigation, as users often compare multiple quotes across devices. Research indicates that 60% of insurance shoppers access quotes via mobile, making responsiveness critical. A well-structured layout reduces cognitive load, while interactive elements enhance engagement by allowing real-time customization.Design clarity in auto insurance quotes directly correlates with a 30% higher likelihood of quote completion, according to usability studies.
Visual Hierarchy and Information Architecture
A clear visual hierarchy guides users through the quote process by emphasizing key sections. Headings, subheadings, and typography should distinguish between summary data (e.g., total premium), detailed coverage options, and next steps (e.g., "Get a Full Quote"). For example, a bold primary heading like "Your Estimated Annual Premium" paired with a large, high-contrast number ($1,200) draws immediate attention, while secondary details (e.g., deductible, coverage limits) appear in smaller, grayed-out text. Users should encounter the most critical information first:- Summary Section: Displays the total estimated cost, coverage type (e.g., liability, collision), and policy duration. Use a clean, two-column layout for mobile to avoid horizontal scrolling.
- Coverage Breakdown: Lists individual coverages (e.g., bodily injury, property damage) with toggle buttons or expandable sections to reveal specifics without overwhelming the user.
- Customization Options: Interactive sliders or dropdowns for deductibles, liability limits, or optional add-ons (e.g., roadside assistance) should appear after the summary to maintain focus.
- Trust Signals: Badges (e.g., "A.M. Best Rated A+") or customer ratings (e.g., "4.5/5 from 10,000+ reviews") build credibility and reduce hesitation.
Mobile Responsiveness and Adaptive Layouts
Mobile users expect seamless interactions, so designs must adapt to screen sizes without sacrificing functionality. Key strategies include:- Fluid Grids: Use percentage-based widths (e.g., CSS Flexbox or Grid) to ensure elements resize proportionally. For instance, a desktop table comparing three insurers should stack vertically on mobile with collapsible rows.
- Touch-Friendly Controls: Buttons and sliders must accommodate finger taps (minimum 48x48px targets). Avoid hover-dependent interactions (e.g., tooltips) that fail on touchscreens.
- Progressive Disclosure: Hide secondary details (e.g., policy exclusions) behind expandable accordions to reduce clutter. Example: A "Show More" button reveals fine print for optional coverages.
- Performance Optimization: Compress images (e.g., SVG for icons) and lazy-load non-critical content (e.g., provider logos) to minimize load times, as 53% of mobile users abandon pages that take over 3 seconds to load.
Color, Contrast, and Cognitive Load Reduction
Color schemes influence perception and trust. Insurance-related pages often use blues (trust) and greens (safety), but avoid overstimulation. High contrast (e.g., dark text on light backgrounds) improves readability, especially for users with visual impairments. For example:- Primary Actions: Use a distinct color (e.g., teal) for "Get Quote" buttons to stand out against neutral backgrounds.
- Error States: Red text for validation errors (e.g., "Invalid ZIP code") ensures immediate visibility.
- Data Visualization: Bar graphs or pie charts comparing insurers should use a limited palette (3–4 colors max) to avoid confusion.
A study by the Nielsen Norman Group found that users spend 80% of their time looking at 20% of a page’s content. Prioritize space for the quote total and next-step actions.
Micro-interactions and Real-Time Feedback
Interactive elements like sliders or dropdowns should provide instant feedback to keep users engaged. For example:- Deductible Sliders: As a user adjusts a slider from $500 to $1,000, the premium updates dynamically with an animation (e.g., a downward arrow next to the new total). This reinforces the cost-saving trade-off.
- Coverage Toggle Switches: Clicking a switch to add comprehensive coverage instantly recalculates the quote and highlights the new premium difference in bold.
- Validation Cues: Real-time error messages (e.g., "Your age must be between 18–90") appear below fields as users type, preventing submission failures.
Impact of a Minor Traffic Violation on Auto Insurance Quotes
A minor traffic violation, such as a speeding ticket or failure to yield, can trigger significant adjustments in auto insurance quotes. While the offense may seem insignificant, insurers classify violations based on severity, history, and potential risk factors. The resulting changes often reflect increased premiums, altered coverage terms, or mandatory policy revisions to mitigate perceived risk. The adjustment process involves several key factors:- Violation Classification: Minor offenses (e.g., speeding under 15 mph over the limit) may incur smaller premium increases compared to severe violations (e.g., DUIs or reckless driving). Insurers categorize violations using a points system, where each point correlates to a percentage increase in premiums.
- Insurer-Specific Penalties: Some providers apply flat-rate surcharges, while others adjust rates based on individual risk profiles. For example, a driver with a clean record might see a 20% increase, whereas a repeat offender could face a 50% or higher hike.
- State Regulations: Certain states mandate minimum penalty structures for violations, which insurers must adhere to. For instance, California requires a minimum 10% premium increase for speeding tickets, while Texas may allow insurers to impose stricter penalties.
- Policy Tier Reassessment: Violations can downgrade a driver from a preferred or low-risk tier to a standard or high-risk category, leading to higher base rates. This reassessment may also restrict access to discounts (e.g., safe driver or good student discounts).
- Provider A increases the premium by 15% ($1,380 annually) and removes the safe driver discount.
- Provider B applies a 25% surcharge ($1,500 annually) and reclassifies the policy to a higher risk tier, eliminating all discounts.
- Provider C imposes a $300 flat-rate penalty ($1,500 annually) but retains some discounts, such as the anti-theft device discount.
Key Adjustments After a Violation
Insurers modify quotes based on the following elements:- Premium Surge The most immediate change is an increase in the base premium. For example, a driver in Illinois with a $1,000 annual premium might see a 30% jump ($1,300) after a speeding violation. The exact percentage depends on the insurer’s risk assessment model and state laws.
- Coverage Restrictions Some insurers may exclude certain coverages (e.g., rental reimbursement or glass coverage) or impose higher deductibles. For instance, a provider might raise the collision deductible from $500 to $1,000 to offset perceived risk.
-
Discount Elimination
Violations often invalidate discounts tied to low-risk behavior. Commonly removed discounts include:
- Safe driver discounts (e.g., -10% for no accidents in 3 years).
- Good student discounts (for drivers under 25 with a GPA above 3.0).
- Low-mileage discounts (if the violation suggests increased driving risk).
- Policy Non-Renewal Risk Severe or repeated violations may lead to non-renewal by the insurer. In such cases, drivers must seek coverage from high-risk insurers (e.g., assigned risk pools), which often charge significantly higher rates.
Mitigation Strategies for Violation-Induced Increases
Drivers can take proactive steps to minimize the financial impact of a violation:- Request a Violation Review Contact the insurer to discuss the specific penalty. Some providers may offer a one-time violation forgiveness program or a graduated penalty for first-time offenders.
- Complete Defensive Driving Courses Many states recognize approved defensive driving courses as a way to reduce or eliminate premium increases. For example, completing a 4-hour course in Florida may lower the surcharge by 10%.
- Shop for Alternative Providers Violations remain on driving records for 3–5 years, but some insurers are more lenient than others. Comparing quotes from multiple providers can reveal opportunities for lower rates, especially if the violation is older.
- Increase Deductibles While this reduces monthly premiums, it increases out-of-pocket costs in the event of a claim. Drivers should balance this trade-off based on their financial risk tolerance.
Note: Violations affect insurance scores similarly to credit scores. A single violation can lower an insurance score by 20–50 points, directly impacting quote calculations. Monitoring and improving this score over time is critical for long-term savings.
Common Mistakes When Comparing Auto Insurance Quotes and Their Financial Impact
Auto insurance quotes are not interchangeable—they reflect coverage, provider policies, and individual risk profiles. Users often overlook critical details that can lead to financial penalties, claim denials, or inadequate protection. These errors stem from misplaced assumptions, lack of awareness about policy nuances, or prioritizing short-term savings over long-term value. Identifying these mistakes and their consequences helps users make informed decisions that align with their needs and budget.Users who focus solely on premium cost without evaluating coverage scope, exclusions, or provider reputation risk paying more in the long run through higher out-of-pocket expenses or poor claims experiences.
---Top 5 Errors When Comparing Auto Insurance Quotes
Missteps in quote comparison often arise from oversimplifying the process or neglecting policy-specific details. Below are the most frequent errors and their implications.- Overlooking coverage gaps. Many users assume a quote includes standard protections like collision, comprehensive, or uninsured motorist coverage. Skipping these can leave drivers vulnerable to full financial responsibility in accidents. For example, a driver in a no-fault state may unknowingly waive personal injury protection (PIP), leading to medical debt if injured in a crash.
- Ignoring policy exclusions. Exclusions—such as modified or classic car restrictions, or limitations on off-road use—are often buried in fine print. A driver who assumes their sports car is covered for track days may face claim denials if the policy excludes "competitive driving." Similarly, rental reimbursement exclusions can result in unexpected costs if a rental is needed after a covered loss.
- Assuming all quotes are apples-to-apples. Providers may use different underwriting models, leading to variations in deductibles, liability limits, or sub-limits (e.g., medical payments per person). A quote with a lower premium might include a $1,000 deductible for comprehensive claims, while another with a slightly higher premium offers a $500 deductible. Without comparing these terms, users may pay more during a claim.
- Neglecting to review provider financial strength. Some insurers with low quotes have weaker claims-paying abilities or slower settlement times. A policy with a $50/month savings but a history of delayed claims (e.g., 60+ days for property damage) can create stress and additional costs if a driver needs immediate repairs. Ratings from agencies like AM Best or J.D. Power provide insight into reliability.
- Failing to account for future needs. Life changes—such as adding a teen driver, purchasing a new vehicle, or moving to a high-risk area—can invalidate a quote’s assumptions. A policy priced for a solo driver may become unaffordable after adding a young driver, or a comprehensive coverage limit may prove insufficient if a driver upgrades to a luxury car.
Financial Consequences of Quote Comparison Errors
The following table maps common mistakes to their direct financial or operational repercussions. Understanding these outcomes helps users prioritize which aspects of a quote require closer scrutiny.
---Mistake Financial or Operational Consequence Example Scenario Skipping medical payments coverage Higher out-of-pocket costs for injuries sustained by the policyholder or passengers. A driver with no medical payments coverage incurs $20,000 in medical bills after a rear-end collision, whereas a policy with $5,000 in medical payments would have covered 25% of those costs. Choosing a provider with poor claims-paying ability Delayed or denied claims, forcing the policyholder to pay for repairs or medical expenses upfront. A hailstorm damages a roof, but the insurer takes 90 days to approve the claim, leaving the homeowner to rent a hotel for three months at $2,000/month. Underestimating liability limits Personal asset seizure or lawsuits if damages exceed policy limits. A driver with $100,000 in liability coverage causes a $150,000 accident. The remaining $50,000 is paid from personal savings or a home equity line of credit. Ignoring usage-based discounts Missing savings opportunities, such as telematics discounts for safe driving. A driver who qualifies for a 15% discount through a usage-based program but doesn’t enroll pays an extra $300 annually. Assuming a quote reflects final pricing Unexpected premium increases after policy issuance due to undisclosed factors (e.g., credit score adjustments, prior claims). A quote is based on a credit score of 720, but the final policy is issued with a score of 650, increasing the premium by 30%. The Pitfall of Focusing Only on Premium Cost
Premiums represent only a fraction of the total cost of auto insurance. Users who select a policy based solely on the lowest monthly price often overlook critical factors that influence long-term affordability and satisfaction. These include:- Claim settlement speed. A provider with a reputation for slow claim processing may save money upfront but create financial strain during a loss. For example, a driver with a $1,000 deductible may need to cover repair costs temporarily if the insurer takes 45 days to approve a claim, potentially incurring additional rental or lodging expenses.
- Customer service ratings. Policies with poor customer service can lead to frustration, errors in billing, or difficulty resolving disputes. A driver with a complaint-filled history may spend hours on hold during emergencies, delaying critical decisions (e.g., rental car approvals or temporary housing arrangements).
- Policy flexibility. Some insurers charge fees for policy adjustments (e.g., adding a driver, changing coverage limits) or require full policy repurchases during renewal. A rigid policy can become costly if life circumstances change, whereas flexible providers allow mid-term modifications for a fee.
- Provider stability. Insurers facing financial distress may raise rates abruptly or reduce coverage options. A policy priced competitively today could become unaffordable tomorrow if the provider’s financial health declines. Checking ratings from agencies like AM Best or the NAIC can reveal stability risks.
- Hidden fees. Some providers include administrative fees (e.g., policy cancellation fees, late payment penalties) that aren’t reflected in the initial quote. These can add hundreds annually if not disclosed upfront. For example, a $50 cancellation fee per policy may seem minor but compounds if a driver switches insurers frequently.
A policy with a $100/month premium but $2,000 in potential hidden fees (e.g., claim processing delays, service charges) may cost $240/month in real-world scenarios, negating the initial savings.
---Follow-Up Questions to Ask Providers After Receiving Initial Quotes
Initial quotes often lack critical details that influence long-term costs and coverage. Below are scripted questions to clarify ambiguities and ensure the policy meets specific needs. These should be asked during phone calls, emails, or in-person meetings with providers.-
Coverage and Limits Clarification.
"The quote shows $100,000 in bodily injury liability. Does this limit apply per person, per accident, or both? Are there sub-limits for medical payments or uninsured motorist coverage?"
-
Deductible and Out-of-Pocket Costs.
"What is the deductible for collision and comprehensive claims? Are there separate deductibles for different types of losses (e.g., windshield replacement vs. theft)?"
-
Exclusions and Restrictions.
"Are there any exclusions for modified vehicles, off-road use, or rental reimbursement? How are claims handled if I drive outside the primary state listed on the policy?"
-
Discounts and Eligibility.
"The quote doesn’t reflect any discounts. Are there opportunities for bundling with homeowners insurance, safe driver discounts, or loyalty programs? What documentation is required to apply them?"
-
Claims Process and Provider Reputation.
"What is the average time to settle a claim for property damage and bodily injury? Can you share customer satisfaction ratings for claims handling from the past year?"
-
Policy Flexibility and Fees.
"Are there fees for adding or removing drivers mid-policy? How does the provider handle rate increases at renewal, and can I request a review if my circumstances change?"
-
Provider Financial Health.
"What is your company’s financial strength rating from AM Best or J.D. Power? Have there been any recent changes in coverage options or premium structures?"
-
Final Pricing Confirmation.
"The quote is based on my current credit score and driving history. How might the final premium differ if these factors change before policy issuance?"
Providers are legally required to disclose material information upon request. Persistent follow-up ensures transparency and helps users avoid costly surprises after policy purchase.
Negotiating Auto Insurance Quotes Directly with Insurers
Insurers often provide flexibility in pricing, particularly when customers engage in proactive negotiation. Strategic timing, policy adjustments, and leveraging insurer incentives can yield significant savings without compromising coverage quality. Understanding these techniques ensures drivers maximize discounts while maintaining adequate protection. Negotiation success hinges on recognizing when insurers are most receptive to rate adjustments. For instance, insurers may offer temporary discounts to meet quarterly or annual sales targets, creating opportunities for policyholders to renegotiate rates. Additionally, bundling policies, adjusting deductibles, or removing optional coverages can influence quote calculations. Below are structured approaches to optimize negotiations and secure lower premiums. ---Optimal Timing for Quote Negotiations
Insurers adjust pricing strategies based on internal metrics, external market conditions, and customer acquisition goals. Policyholders can exploit these cycles to their advantage by aligning negotiations with periods of heightened insurer activity.-
End-of-Quarter Discounts
Many insurers set internal targets for policy renewals or new sales at quarterly intervals. Negotiating during the last few weeks of a quarter (e.g., late March, June, September, or December) may yield discounts to meet these targets. Insurers may offer temporary rate reductions or waive administrative fees to incentivize renewals.
Example: A driver renewing in late September might receive a 5–10% discount if the insurer is underperforming in policy retention for the quarter.
- Annual Policy Renewal Periods Insurers typically review rates during renewal cycles, often between 30–60 days before the policy expiration date. This window provides the best opportunity to compare competitor quotes and counteroffer with existing providers. Highlighting competitor quotes or recent driving record improvements (e.g., no accidents) strengthens negotiation leverage.
- Post-Claim or Policy Adjustment Reviews After filing a claim or modifying coverage (e.g., adding a driver, upgrading a vehicle), insurers reassess risk profiles. Policyholders can request a rate review during this period, as insurers may adjust premiums based on updated risk factors. Presenting a clean driving history or safety upgrades (e.g., anti-theft devices) can mitigate rate increases.
- Holiday and Promotional Periods Insurers occasionally launch limited-time promotions during holidays (e.g., Thanksgiving, Black Friday) or industry events (e.g., National Insurance Awareness Day). Monitoring insurer websites or contacting agents during these periods may reveal exclusive discounts, such as cashback offers or loyalty rewards.
Adjusting Coverage Limits and Deductibles for Lower Quotes
Premiums are directly influenced by coverage limits and deductible amounts. Policyholders can strategically reduce costs by increasing deductibles or lowering coverage thresholds, provided the adjustments align with financial risk tolerance and state minimum requirements.-
Increasing Deductibles
A higher deductible shifts more financial responsibility to the policyholder in the event of a claim, which insurers reward with lower premiums. For example, raising a collision deductible from $500 to $1,000 could reduce annual premiums by 15–30%, depending on the insurer and vehicle value.
Caution: Only increase deductibles if the policyholder can afford the out-of-pocket expense without disrupting savings or emergency funds.
-
Lowering Comprehensive or Collision Coverage Limits
State laws dictate minimum liability coverage, but optional coverages like comprehensive or collision can often be reduced or removed for older vehicles. For instance, if a vehicle’s market value is below the coverage limit (e.g., $5,000), dropping collision coverage may be viable, saving 10–20% annually.
Example: A 10-year-old sedan with a $4,000 replacement value might not justify $5,000 in collision coverage, making a reduction or removal cost-effective.
- Removing Optional Add-Ons Insurers offer additional coverages such as rental reimbursement, roadside assistance, or gap insurance. Evaluating these add-ons annually can reveal opportunities to discontinue unnecessary services. For example, if a policyholder has a separate roadside membership (e.g., AAA), removing this coverage from the auto policy can reduce premiums by 5–15%.
- Switching to Actual Cash Value (ACV) for Older Vehicles Newer vehicles are typically insured for replacement cost, while older models may qualify for ACV, which pays only the depreciated value. Switching to ACV can lower premiums by 10–25% for vehicles over 5–7 years old, with minimal impact on claim payouts for non-catastrophic incidents.
Advanced Options and Their Impact on Quotes
Beyond standard coverage adjustments, insurers offer lesser-known discounts and payment structures that can further reduce premiums. Understanding these options allows policyholders to customize policies for maximum savings.Option Description Potential Quote Impact Eligibility Notes Pay-in-Full Discount Discount applied for paying the annual premium in a single lump sum instead of monthly installments. 5–12% reduction on annual premium. Requires upfront payment; may not be available for all policy types. Paperless Billing Discount Reduction for opting into electronic statements and policy documents. 3–8% savings annually. Universal eligibility; no additional fees for digital access. Continuous Coverage Incentive Discount for maintaining continuous auto insurance without gaps. 5–10% reduction after 3+ years of uninterrupted coverage. Verifiable through insurer records; lapses may void eligibility. Telematics or Usage-Based Discount Reduction based on safe driving habits tracked via apps or devices. 10–30% savings for low-mileage or low-risk drivers. Requires installation of a plugin or app; privacy policies vary by insurer. Multi-Policy (Bundling) Discount Discount for combining auto insurance with other policies (e.g., home, renters). 10–25% reduction on auto premiums. Eligible policies must be with the same insurer. Low-Mileage Discount Reduction for drivers who log fewer than 7,500–12,000 miles annually. 5–15% savings. Requires odometer verification; common for urban commuters. New Vehicle Discount Bonus for insuring a new vehicle within the first 1–2 years of purchase. 5–10% reduction. Applies to vehicles under 1 year old; may include anti-theft device incentives. Student Discount (Good Grades) Discount for policyholders under 25 with a GPA of 3.0 or higher. 10–20% savings. Requires proof of enrollment and grade verification. Note: Discounts are often stackable. For example, a policyholder paying annually, opting for paperless billing, and bundling with home insurance may qualify for cumulative savings of 25–40%.
---Leveraging Loyalty Programs and Referral Bonuses
Insurers frequently reward long-term customers and new referrals with exclusive discounts or perks. Policyholders can capitalize on these programs by proactively engaging with insurer loyalty initiatives or introducing trusted contacts to the provider.-
Loyalty Rewards for Long-Term Policyholders
Insurers may offer tiered discounts based on years of continuous coverage. For example, a driver with 5+ years of service might qualify for a 5% loyalty discount, while 10+ years could unlock an additional 5–10%. Some insurers also provide non-monetary rewards, such as priority claim processing or extended roadside assistance.
Example: A policyholder with 8 years of service at Provider X receives a 7% loyalty discount and is fast-tracked for claim settlements.
- Referral Bonuses for New Customers Many insurers incentivize existing customers to refer friends or family by offering cashback, premium credits, or gift cards. Referral discounts typically range from $25 to $200 per successful referral, depending on the insurer. Policyholders should confirm referral terms, such as the new customer’s retention period (e.g., 6 months) to qualify for the bonus.
- Affinity Program Discounts Insurers partner with organizations (e.g., alumni associations, professional groups) to offer members exclusive discounts. Joining an affinity group—such as a university alumni network or a trade union—can provide 5–15% off auto insurance. Policyholders should inquire with their insurer about affiliated programs.
- Military or Veterans Discounts Active duty, veterans, and military families often qualify for discounts through insurer partnerships or government programs. Discounts may include 5–10% off premiums or waived fees. Documentation (e.g., military ID, discharge papers) is typically required.
-
Auto-Pay Discounts with Loyalty Add-Ons
Some insurers combine auto-p
Comparison of Auto Insurance Quote Structures Across Countries: Mandatory Coverages and Regional Variations
Auto insurance quotes vary significantly by country due to differences in legal requirements, risk assessment models, and regulatory frameworks. While some nations mandate specific coverage types to ensure financial protection for all road users, others rely on private market competition with minimal state intervention. Understanding these structures is critical for drivers, expatriates, and insurers navigating cross-border policies. The core of quote differentiation lies in mandatory coverage tiers, which dictate the baseline protections consumers must purchase. For example, the U.S. operates under a fault-based system, where drivers must carry liability insurance (bodily injury and property damage) to cover third-party claims, but coverage limits and optional add-ons (collision, comprehensive) are highly variable. In contrast, no-fault systems like those in Canada and some U.S. states (e.g., Michigan) require drivers to claim from their own insurer regardless of fault, altering quote calculations by prioritizing personal injury protection (PIP). Meanwhile, countries like the UK enforce third-party liability insurance as mandatory, with additional protections like fire and theft often bundled into standard policies. ---Mandatory Coverage Frameworks in Key Markets
The following table outlines the mandatory coverage requirements in major automotive markets, illustrating how legal obligations shape quote structures and consumer costs.
---Country Mandatory Coverage Type Minimum Liability Limits (Per Incident) Additional Common Mandates Quote Impact United States Liability-only (varies by state) - Bodily Injury: $25,000–$100,000 (varies by state)
- Property Damage: $10,000–$50,000
- Uninsured/underinsured motorist (UM/UIM) in most states
- Personal injury protection (PIP) in no-fault states
Quotes heavily influenced by state laws; optional coverages (collision/comprehensive) often exceed mandatory minimums, increasing premiums by 30–50%. United Kingdom Third-party only (minimum legal requirement) - Unlimited liability for injury/death
- £2,000,000+ for property damage (standardized)
- Fire and theft coverage often bundled
- Voluntary excess (deductible) limits
Third-party-only policies are the cheapest (~£300–£600/year), but comprehensive policies (covering own vehicle) dominate the market (~80% of drivers). Canada Third-party liability + accident benefits (no-fault) - $200,000–$2,000,000 bodily injury (provincial variation)
- Medical/rehab benefits: CAD $65,000–$2,000,000
- Direct compensation (no lawsuit against at-fault driver)
- Uninsured motorist protection
No-fault systems reduce litigation costs but inflate premiums by 20–40% due to mandatory accident benefits. France Third-party liability + "GMA" (Garantie des Accidents de la Circulation) - €1,000,000 bodily injury + property damage
- GMA covers medical costs for all road users (driver/passenger)
- Voluntary collision/comprehensive widely purchased
- Zero-depreciation options for new vehicles
GMA reduces individual medical claim burdens but increases base premiums by ~15% compared to third-party-only policies. Australia Third-party property damage (CTP = Compulsory Third Party) - CTP covers injury/death only (state-run schemes)
- No mandatory property damage coverage
- Comprehensive/third-party fire/theft required for vehicle damage
- Excess limits negotiable
CTP premiums are levied separately (e.g., ~$600–$1,200/year in NSW) and do not factor into private insurer quotes for vehicle damage. Regional Variations in Quote Calculation Logic
Beyond mandatory coverages, quote structures differ based on risk allocation models, insurer competition, and government interventions. For instance:- U.S. quotes prioritize individual risk profiles (credit scores, driving history, vehicle type) and often include territorial surcharges for high-theft or urban areas.
- UK quotes emphasize vehicle group ratings (1–50, with Group 1 being the cheapest) and postcode-based premiums, reflecting regional claim frequencies.
- Canadian quotes incorporate provincial no-fault benefits (e.g., Ontario’s $65,000 medical limit) and winter tire discounts, which can reduce premiums by 5–10%.
- French quotes account for vehicle age depreciation curves and geographic zones (e.g., Paris vs. rural Brittany), with insurers offering multi-year contracts to stabilize rates.
Expatriate and Cross-Border Considerations
Drivers operating in multiple countries face additional complexities, including:- Dual coverage risks: Insuring the same vehicle under two policies (e.g., a U.S. driver in Canada) may violate double insurance clauses, leading to claim denials.
- Green Card requirements: Some countries (e.g., France, Germany) mandate International Motor Insurance Cards (Green Cards) for temporary visitors, which must be obtained from the home insurer.
- Parallel import vehicles: Vehicles purchased abroad (e.g., a U.S. car in Europe) may lack local type approval, making them uninsurable without modifications.
Key Takeaways for Quote Comparisons
Mandatory coverage minimums dictate the baseline cost of insurance, but optional add-ons (e.g., collision, roadside assistance) drive premium variability. No-fault systems (Canada, some U.S. states) increase base premiums due to guaranteed accident benefits, while third-party-only markets (UK, France) offer lower minimums but higher out-of-pocket risks. Currency and inflation distort direct comparisons: A $1,000 U.S. premium may equate to £750 in the UK but €900 in France due to exchange rate fluctuations and local cost-of-living differences.
Emerging Technologies and the Future of Quote Transparency in Auto Insurance
Emerging technologies are fundamentally altering how auto insurance quotes are generated, validated, and presented to consumers. AI-driven algorithms, blockchain for claims processing, and real-time data analytics are introducing unprecedented levels of precision and transparency—while also raising questions about fairness, bias, and consumer trust. These advancements will not only streamline quote comparisons but also redefine the relationship between insurers, policyholders, and regulatory bodies. The shift toward dynamic, data-rich quotes will demand greater scrutiny of underlying models to ensure equitable pricing and ethical implementation. The core challenge lies in balancing automation with interpretability. Consumers increasingly expect quotes to reflect real-time risk assessments, yet the "black box" nature of AI-driven pricing models risks obscuring the logic behind premiums. Blockchain, meanwhile, promises to revolutionize claims transparency by creating immutable audit trails, but its adoption hinges on industry-wide standardization. Below, the specific impacts of these technologies on quote structures, consumer trust, and regulatory compliance are examined.AI-Driven Pricing and the Transparency Paradox
AI and machine learning are enabling insurers to process vast datasets—including telematics, weather patterns, and even social media activity—to generate hyper-personalized quotes. While this improves accuracy, it also introduces opacity, as traditional actuarial methods are replaced by complex neural networks. For example, an insurer might adjust a quote dynamically based on a driver’s real-time route deviations or vehicle diagnostics, without explicit human oversight. The transparency paradox arises because AI models often prioritize predictive power over explainability. A quote derived from a proprietary algorithm may reflect nuanced risk factors (e.g., micro-climate zones or predictive maintenance alerts), but consumers lack the tools to challenge or understand these variables. Regulators are responding with initiatives like the EU’s AI Act, which mandates transparency requirements for high-risk automated systems, including insurance pricing models. In the U.S., states such as California have proposed Algorithm Accountability Laws to require insurers to disclose key factors influencing quotes.Blockchain’s Role in Claims Processing and Quote Verification
Blockchain technology is poised to disrupt claims handling by eliminating fraud and reducing processing times, indirectly influencing quote structures. Smart contracts—self-executing agreements stored on a decentralized ledger—can automate claim settlements based on predefined triggers (e.g., airbag deployment data from a vehicle’s ECU). This reduces administrative costs, which insurers may pass on to consumers in the form of lower premiums or more competitive quotes. For quote transparency, blockchain enables immutable audit logs of all interactions between insurers, brokers, and policyholders. For instance, a driver requesting a quote could access a verifiable history of their claims, discounts applied, and past premium adjustments—all cryptographically secured. This reduces disputes over coverage eligibility and ensures quotes reflect consistent, tamper-proof data. However, adoption faces hurdles such as interoperability with legacy systems and consumer skepticism about digital identity verification.Real-Time Data and the Evolution of Dynamic Quotes
The integration of IoT sensors, GPS tracking, and predictive analytics is enabling quotes to update in real time. Unlike static annual premiums, dynamic quotes adjust based on immediate risk factors, such as:- Usage-based insurance (UBI): Premiums fluctuate hourly based on driving behavior (e.g., harsh braking, speeding).
- Vehicle health metrics: Engine diagnostics or tire pressure alerts may trigger temporary quote adjustments.
- Environmental triggers: Quotes could spike during extreme weather events or in high-crash zones, then normalize afterward.
Challenges to Transparency: Bias, Data Privacy, and Consumer Rights
The shift toward AI and real-time data raises ethical concerns that could undermine quote transparency. Key issues include:- Algorithmic bias: Models trained on historical data may perpetuate discrimination (e.g., higher quotes for low-income neighborhoods due to correlated risk factors).
- Data sovereignty: Consumers may not realize their location, biometric, or purchasing data are being used to generate quotes, raising GDPR and CCPA compliance risks.
- Lack of standardization: Without industry-wide frameworks, quote comparisons become difficult, as each insurer’s AI model may weigh factors differently.
- Open insurance initiatives (e.g., UK’s Open Banking principles applied to insurance), requiring insurers to share standardized data with consumers.
- Right to explanation laws, such as the Algorithmic Transparency Act proposed in the U.S., which would mandate insurers to provide clear, non-technical justifications for quote decisions.
- Sandbox testing environments, where insurers pilot AI models under regulatory supervision before full deployment.
Consumer Tools for Demystifying AI-Generated Quotes
To restore trust, insurers and tech providers are developing tools that demystify complex quotes. Examples include:- Explainable AI (XAI) interfaces: Dashboards that break down quote components (e.g., "Your quote includes a 15% surcharge for urban commuting, offset by a 10% safe-driver discount").
- Counterfactual explanations: "What-if" scenarios showing how quote changes would occur if a driver altered behavior (e.g., "If you reduced nighttime driving by 30%, your quote could drop by 20%").
- Third-party verification platforms: Independent services that cross-check quotes from multiple insurers using standardized risk profiles, ensuring apples-to-apples comparisons.
Auto insurance quotes are more than just numbers—they reflect a balance between risk assessment, regulatory requirements, and provider strategies. By mastering the art of comparison, you can navigate the complexities of coverage options, discounts, and regional variations to secure a policy that fits both your budget and lifestyle. From leveraging digital tools to spot-checking for hidden fees, every step in the quote analysis process contributes to long-term savings and peace of mind. The key lies in treating quotes as a starting point, not a final answer, and using the insights from this guide to refine your search until you find the best possible match.
As the auto insurance landscape evolves with advancements in telematics, AI-driven pricing, and global regulatory shifts, staying proactive in your quote comparisons will remain essential. Whether you’re a local driver or an international policyholder, the principles outlined here ensure you’re equipped to challenge assumptions, ask the right questions, and ultimately drive away with a policy—and a price—that works for you.
Auto Insurance Quote Comparison: Finding the Right Coverage for Your Car
Frequently Asked Questions
How do I get free auto insurance comparison quotes online?
Use comparison websites like Compare.com, The Zebra, or NerdWallet. Enter basic details (vehicle, location, driver info) to receive quotes from multiple insurers. Some providers also offer direct quote tools on their websites. Always verify the legitimacy of the platform.
What factors make my auto insurance quote higher than others?
Quotes vary based on age, driving record, vehicle type, location, credit score, and coverage levels. High-risk drivers, expensive cars, or urban areas typically result in higher premiums. Discounts for bundling or safe driving can lower costs.
Does comparing quotes from different insurers actually save money?
Yes, comparing quotes can save hundreds annually. Prices vary by insurer due to different underwriting models, discounts, and regional pricing. Even a 10% difference in premiums adds up over time. Always check coverage limits and exclusions.
What types of auto insurance coverage affect my quote the most?
Liability, collision, and comprehensive coverage significantly impact quotes. Liability is mandatory in most states and is the base cost. Adding collision/comprehensive increases premiums but covers vehicle damage or theft. Higher limits mean higher quotes.
Are there discounts I might be missing when comparing quotes?
Common discounts include safe driver, multi-policy, student, military, and anti-theft device discounts. Some insurers offer low-mileage or usage-based discounts. Ask providers about loyalty or first-time buyer incentives. Always confirm eligibility.
How do I know if an auto insurance quote is accurate before buying?
Verify the quote includes all requested coverages and correct vehicle details. Check for hidden fees or exclusions. Compare quotes from at least 3 insurers. Use tools like JD Power or BBB reviews to assess provider reliability. Confirm final pricing after underwriting.
Related articles
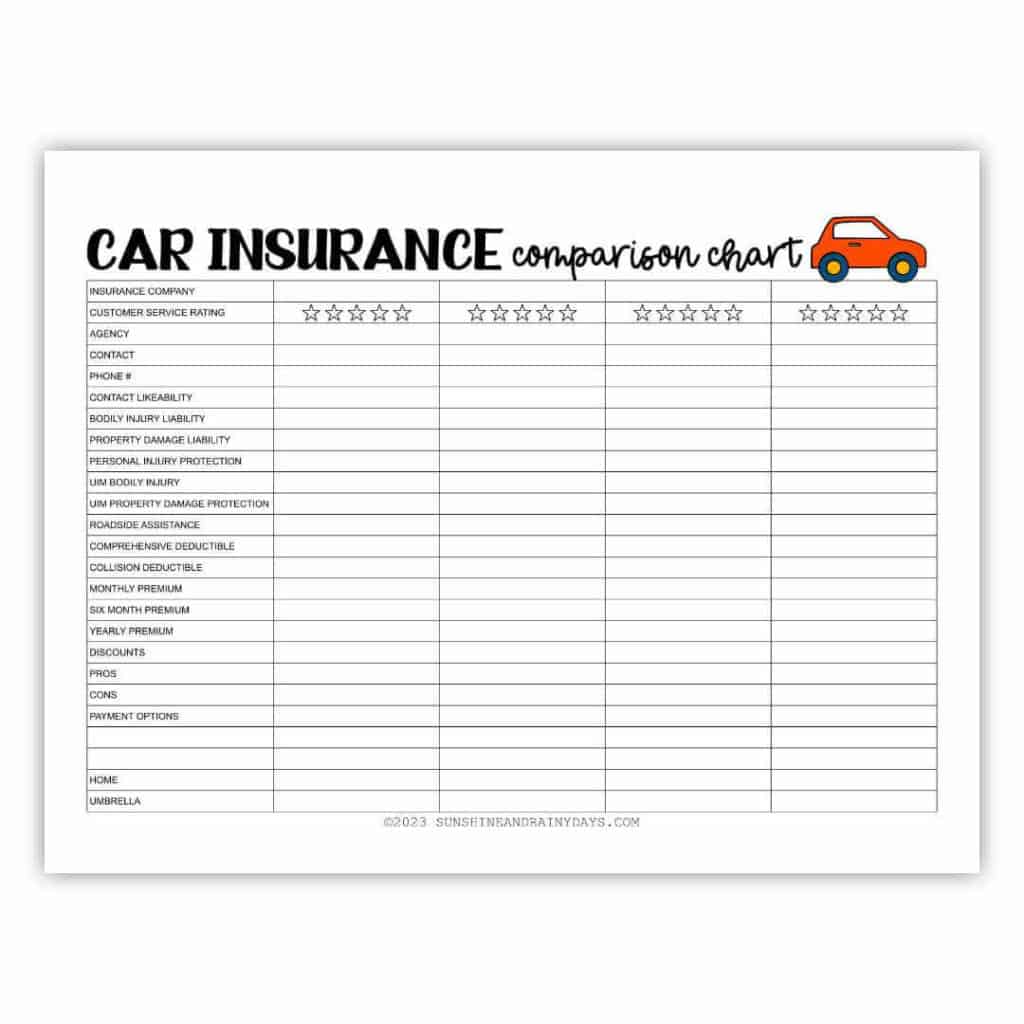
Auto Insurance Comparison Tool Simplified Guide
Discover how an Auto Insurance Comparison Tool Simplified Guide helps you compare quotes fast, save money, and pick the best policy effortlessly—no…

Auto Insurance Car Insurance Explained Simply
Understand Auto Insurance & Car Insurance Explained Simply—coverage types, costs, and how policies protect drivers. Get clear answers on liability,…
Auto Insurance Car Comparison Guide For Smart Drivers
Discover the best auto insurance rates with our Auto Insurance Car Comparison Guide For Smart Drivers—compare policies, save money, and make informed…

Understanding Auto Car Insurance Quotes Made Simple
Get clear, accurate auto car insurance quotes with our step-by-step guide. Understanding Auto Car Insurance Quotes Made Simple—compare rates, save money,…
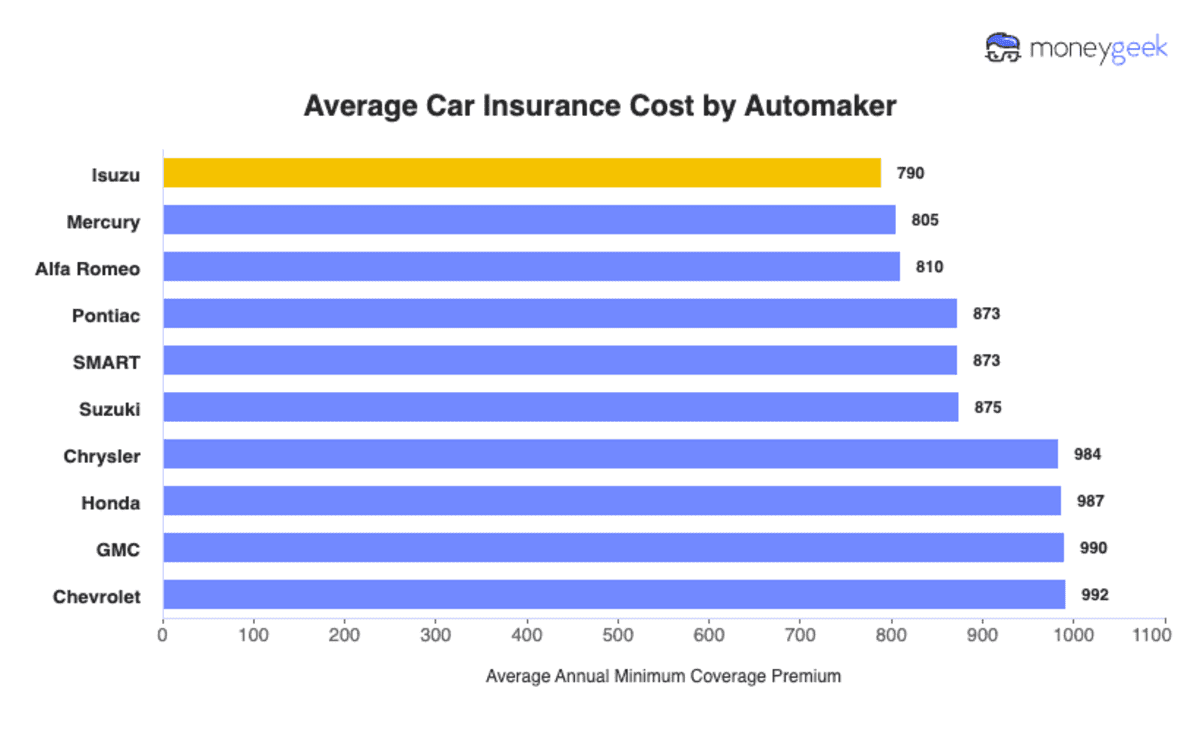
Auto Car Insurance Comparison Key Steps And Insights
Discover Auto Car Insurance Comparison Key Steps And Insights to save money, find the best coverage, and avoid common pitfalls—expert tips for smart…
