Auto Car Insurance Comparison Key Steps And Insights
Table of Contents
- The Core Purpose of Comparing Auto Insurance Policies
- Five Critical Elements to Evaluate in an Auto Insurance Policy
- Categorization of Auto Insurance Providers
- Popular Online Tools and Apps for Auto Insurance Comparisons
- State Laws and Their Impact on Auto Insurance Requirements and Costs
- Components That Contribute to Auto Insurance Premiums
- Steps in Filing an Auto Insurance Claim
- Use of Actuarial Data to Predict Future Premium Changes
- Niche Auto Insurance Coverage Types and Specialized Policies
- Common Pitfalls in Auto Insurance Policy Comparison
- Legal Requirements for Auto Insurance in a General Context
- Emerging Technologies and Their Transformative Impact on Auto Insurance Comparisons
- 7-Step Process for Comparing Auto Insurance Policies Effectively
- Real-World Savings Through Auto Insurance Provider Switching
- Visual Simplification of Auto Insurance Policy Comparisons Through Infographics
- Key Differences Between U.S. and European Auto Insurance Markets
- Barriers Preventing Effective Auto Insurance Policy Comparisons for Vulnerable Groups
- Comparing Auto Insurance Policies for Luxury Cars vs. Economy Models
Auto insurance is one of the most critical yet complex financial decisions drivers face, yet most policyholders settle for the first quote they receive without exploring alternatives. A thorough auto car insurance comparison isn’t just about finding the cheapest premium—it’s about aligning coverage with real-world risks, financial constraints, and long-term needs. From deciphering deductible trade-offs to navigating state-specific mandates, the process demands a structured approach to avoid costly oversights. This guide breaks down the essential elements of comparison, from traditional broker negotiations to AI-driven digital tools, ensuring you make an informed choice that balances protection and affordability.
At its core, comparing auto insurance policies involves evaluating not just price but also the fine print—what’s covered, what’s excluded, and how claims are handled when accidents occur. Factors like driving history, vehicle type, and even local weather patterns can shift premiums dramatically, yet many drivers overlook these variables until it’s too late. Whether you’re a first-time buyer, a seasoned policyholder, or someone transitioning to an electric vehicle, understanding the nuances of comparison can save thousands over a policy’s lifetime. This exploration covers every stage, from identifying hidden discounts to leveraging technology for smarter decisions, ensuring no stone is left unturned in your search for optimal coverage.
The Core Purpose of Comparing Auto Insurance Policies
Auto insurance is not a one-size-fits-all product. Each policy varies in coverage, cost, and terms, making it essential for drivers to assess their options carefully. The primary purpose of comparing auto insurance policies is to ensure that individuals select a plan that aligns with their financial needs, driving habits, and legal requirements while maximizing value for money. Without comparison, consumers risk overpaying, underinsuring, or missing critical protections that could save them thousands in the event of an accident or claim. A well-informed comparison process reduces uncertainty and empowers buyers to make decisions based on transparency, rather than assumptions or default choices. It also helps identify hidden fees, exclusions, or limitations that may not be immediately apparent in standard policy descriptions. For example, a policy with a low monthly premium might include high deductibles or limited coverage for specific scenarios (e.g., uninsured motorist protection), which could prove costly in the long run. ---Definition of Policy Comparison in Auto Insurance
A **comparison of auto insurance policies** involves systematically evaluating multiple insurance plans from different providers to determine which offers the best balance of coverage, cost, and customer service. This process goes beyond surface-level price checks to include an analysis of: - **Coverage limits and types** (liability, collision, comprehensive, medical payments, etc.). - **Deductible amounts** and how they impact out-of-pocket expenses. - **Additional benefits** (roadside assistance, rental car coverage, accident forgiveness). - **Provider reputation** (customer reviews, claim settlement ratios, financial stability). - **Discounts and incentives** (safe driver discounts, bundling with home insurance, loyalty programs). The goal is to create a side-by-side evaluation that highlights trade-offs, such as a policy with slightly higher premiums but broader coverage or a provider with faster claim processing times. For instance, comparing a state-mandated minimum coverage policy (e.g., $25,000 bodily injury per person) against a full-coverage plan ($100,000+ per person) reveals how much additional protection is feasible within a given budget. ---Key Benefits of Conducting a Thorough Comparison
A structured comparison process yields tangible advantages for policyholders, extending beyond immediate cost savings. Below are the primary benefits, categorized by their impact on financial security, legal compliance, and peace of mind.*"The average driver who compares three or more quotes saves 15–30% on annual premiums, while also identifying coverage gaps that could expose them to legal or financial risks."* — *Insurance Information Institute (III), 2023***Financial Savings and Value Optimization** Comparing policies exposes discrepancies in pricing that providers often do not disclose upfront. For example: - A driver in Texas might find premiums ranging from **$1,200 to $2,500 annually** for identical coverage tiers due to regional underwriting differences. - Discounts (e.g., **telematics-based safe driving programs**) can reduce premiums by **5–15%** without compromising coverage. - Bundling auto with home/renters insurance may yield **10–20% savings** on both policies. **Coverage Alignment with Personal Risks** Not all drivers face the same risks. A comparison helps tailor coverage to individual needs, such as: - **High-value vehicles**: Comprehensive coverage with **agreed-value settlements** (instead of actual cash value) to avoid depreciation penalties. - **Urban vs. rural drivers**: Policies in cities like Los Angeles may include **higher theft/comprehensive limits** due to higher risk of vandalism or accidents. - **Commuters with long drives**: Additional **umbrella liability** (e.g., $1M+) to protect against lawsuits from multi-vehicle collisions. **Avoiding Penalties and Legal Exposures** Many states enforce **minimum liability coverage requirements** (e.g., 25/50/25 in most states), but failing to meet these can result in: - **License suspension** or fines (e.g., California penalties up to **$5,000** for uninsured driving). - **Financial liability** for damages exceeding policy limits (e.g., a $200,000 medical bill if liability coverage is only $50,000). - **Higher premiums** if gaps in coverage are discovered during a claim. **Access to Better Customer Service and Claims Handling** Insurance providers vary significantly in claim processing efficiency and customer satisfaction. Key metrics to compare include: - **Average claim settlement time**: Top-rated insurers (e.g., **State Farm, Geico**) resolve bodily injury claims in **20–30 days**, while others may take **60+ days**. - **Customer complaint ratios**: The **National Association of Insurance Commissioners (NAIC)** tracks complaints per policy; providers with ratios **above 1.0** may indicate poor service. - **24/7 support availability**: Some insurers offer **AI chatbots or live agents** for claims, while others rely on call centers with long wait times. **Flexibility for Future Needs** Life changes—such as buying a new car, adding a teen driver, or moving states—require policy adjustments. A comparison helps identify insurers that offer: - **Easy policy modifications** (e.g., **Allstate’s "Drivewise"** for usage-based pricing). - **Lifetime accident forgiveness** (e.g., **Progressive Snapshot** for safe drivers). - **Multi-policy discounts** that scale with additional coverage needs. ---
Decision-Making Flowchart for Auto Insurance Buyers
Below is a **step-by-step flowchart** outlining the logical progression for selecting an auto insurance policy. Each step builds on the previous one to ensure a methodical evaluation. ``` START │ ├─ **Step 1: Assess Personal Requirements** │ ├─ Determine **minimum legal coverage** (state requirements). │ ├─ Identify **additional needs** (e.g., gap insurance, rental reimbursement). │ └─ Note **vehicle details** (make, model, year, usage). │ ├─ **Step 2: Gather Quotes from Multiple Providers** │ ├─ Use **comparison tools** (e.g., **NerdWallet, The Zebra, Insure.com**). │ ├─ Request quotes from **5+ insurers** (traditional + digital). │ └─ Verify **same coverage levels** across quotes. │ ├─ **Step 3: Compare Core Policy Terms** │ ├─ **Premiums**: Monthly vs. annual costs. │ ├─ **Deductibles**: Impact on out-of-pocket expenses. │ ├─ **Coverage Limits**: Liability, collision, comprehensive. │ └─ **Exclusions**: What’s **not** covered (e.g., racing, commercial use). │ ├─ **Step 4: Evaluate Provider Reputation** │ ├─ Check **J.D. Power ratings** (customer satisfaction). │ ├─ Review **NAIC complaint index**. │ └─ Read **third-party reviews** (Trustpilot, BBB). │ ├─ **Step 5: Identify Discounts and Incentives** │ ├─ **Safe driver discounts** (e.g., **Progressive Snapshot**). │ ├─ **Bundling savings** (auto + home/renters). │ ├─ **Loyalty programs** (e.g., **State Farm’s "Steer Clear"**). │ └─ **Pay-in-full discounts** (5–10% off annual premiums). │ ├─ **Step 6: Review Claims Process Efficiency** │ ├─ **Average settlement time** for property damage vs. bodily injury. │ ├─ **Claim denial rates** (lower is better). │ └─ **Customer support channels** (phone, chat, mobile app). │ ├─ **Step 7: Finalize and Enroll** │ ├─ **Negotiate rates** (some insurers offer **last-minute discounts**). │ ├─ **Confirm policy documents** (coverage summary, exclusions). │ └─ **Set up automatic payments** (to avoid lapses). │ └─ **END: Policy Activated** ``` **Key Visual Notes for the Flowchart:** - **Conditional Branches**: If a step reveals a critical flaw (e.g., high complaint ratio), loop back to **Step 2** to explore alternatives. - **Decision Points**: Use **diamond shapes** for yes/no questions (e.g., *"Does this policy cover my commute to work?"*). - **Output**: The final selection should be documented in a **comparison spreadsheet** for future reference. ---Primary Factors Influencing Auto Insurance Policy Selection
The selection of an auto insurance policy is influenced by a combination of **external factors** (market conditions, regulations) and **internal factors** (driver profile, vehicle type). Below is a high-level overview of the most critical determinants, organized by category.*"A 2022 study by the **Consumer Federation of America** found that **40% of drivers** overpay for insurance due to ignoring at least three key selection factors."***1. Driver-Related Factors** These directly impact underwriting risk and premium calculations. - **Age and Driving Experience**: - **Teens (16–19)**: Premiums **3x higher** than mature drivers (e.g., **$6,000/year** vs. **$1,500**). - **Senior Drivers (70+)**: May qualify for **mature driver discounts** but face higher collision risks. - **Driving Record**: - **Speeding tickets/DUI**: Can increase premiums by **50–100%** for **3–5 years**. - **Accident history**: At-fault accidents may raise rates by **20–40%**. - **Credit Score**: - In **38 states**, insurers use credit scores to assess risk; a **low score (below 600)** may increase premiums by **20–50%**. - **Annual Mileage**: - Low-mileage drivers (e.g., **<7,500 miles/year**) may qualify for **usage-based discounts**. **2. Vehicle-Specific Factors** The type of car owned affects coverage costs and requirements. - **Vehicle Value**: - **Luxury cars (e.g., BMW M3, Porsche 911)**: Require **higher comprehensive/collision limits** due to repair costs. - **Older vehicles (10+ years)**: May only need **liability coverage** if totaled. - **Safety Ratings**: - Vehicles with **top safety scores (IIHS/Top Safety Pick+)** may qualify for **discounts of 5–15%**. - **Theft Risk**: - High-theft models (e.g., **Honda Civic, Nissan Altima**) may require **anti-theft device discounts** (e.g., **LoJack**). - **Engine Size/Horsepower**: - **High-performance cars (e.g., Mustang GT, Corvette)** often face **higher premiums** due to increased accident likelihood. **3. Location-Based Factors** Geographic data significantly impacts risk assessment. - **State Regulations**: - **No-fault states (e.g., Michigan, Florida)**: Higher premiums due to mandatory **Personal Injury Protection (PIP)**. - **At-fault
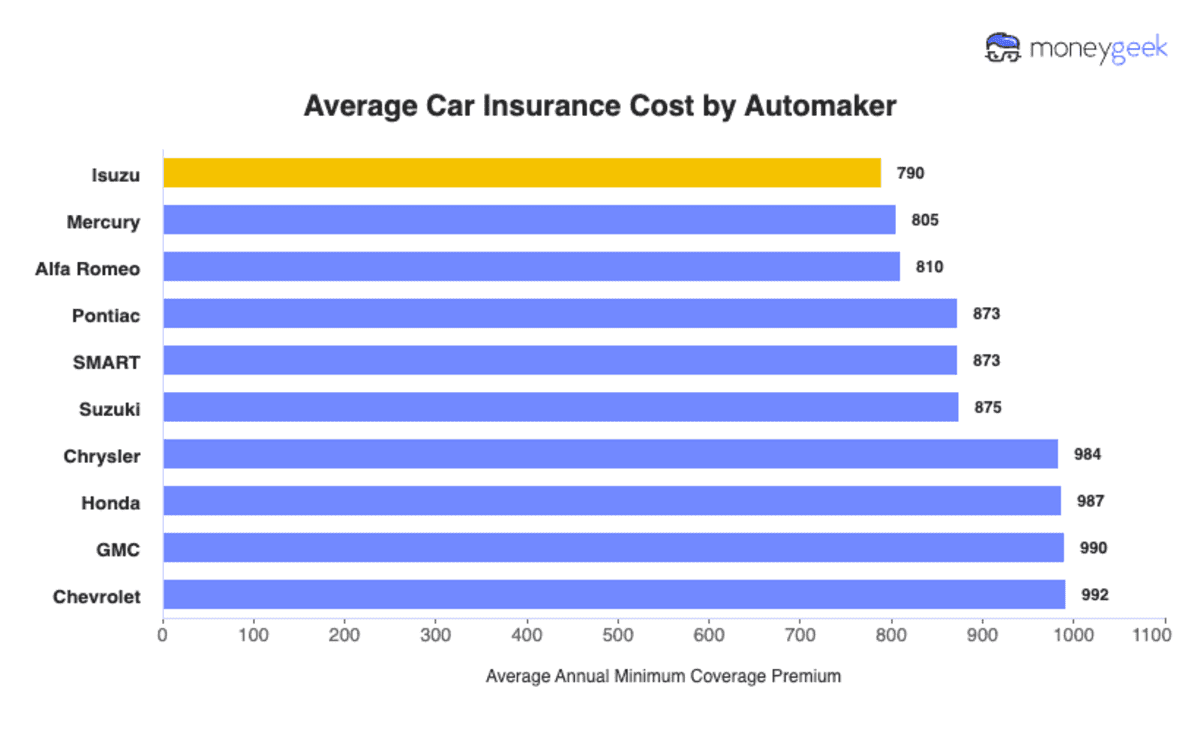
Five Critical Elements to Evaluate in an Auto Insurance Policy
Auto insurance policies vary significantly in terms of coverage, cost, and provider reputation. Evaluating the right elements ensures alignment with individual needs, financial constraints, and risk tolerance. The five most critical elements to assess include coverage types, deductible structures, policy limits, exclusions, and provider reliability. These factors directly influence financial protection, claim efficiency, and long-term affordability. ---Coverage Types and Their Scope
The foundation of any auto insurance policy lies in its coverage types. Each type serves distinct purposes, and omitting or underestimating their importance can lead to gaps in protection. **Liability coverage** addresses third-party injuries and property damage, while **collision coverage** handles damage to the insured vehicle from accidents. **Comprehensive coverage** extends protection to non-collision incidents like theft, vandalism, or natural disasters. **Medical payments (MedPay) or personal injury protection (PIP)** cover medical expenses for the policyholder and passengers, and **uninsured/underinsured motorist coverage** safeguards against drivers lacking sufficient insurance. Understanding these categories allows policyholders to tailor coverage to their assets, driving habits, and legal requirements. For example, a high-value vehicle may necessitate higher comprehensive coverage limits to match its replacement cost, whereas a budget-conscious driver might prioritize liability coverage to meet state minimums. ---Deductible Amounts and Their Financial Impact
Deductibles represent the out-of-pocket expense a policyholder must pay before insurance coverage kicks in. Higher deductibles typically lower premiums, but they increase financial risk during claims. Conversely, lower deductibles reduce immediate costs but elevate annual premiums. The relationship between deductibles and premiums follows a **cost-sharing model**, where the insurer and policyholder split risk based on agreed-upon terms. For instance, a policy with a **$500 deductible** may cost **$1,200 annually**, while increasing it to **$1,000** could reduce the premium to **$900**. However, in the event of a **$7,000 collision claim**, the policyholder with the $500 deductible pays **$500**, while the one with the $1,000 deductible pays **$1,000**. This trade-off requires balancing short-term savings against potential future liabilities. ---Policy Limits and Their Role in Financial Protection
Policy limits define the maximum amount an insurer will pay for covered claims. These limits apply per incident, per person, or per policy period and are categorized as: - **Bodily injury liability limits** (e.g., $50,000 per person, $100,000 per accident). - **Property damage liability limits** (e.g., $25,000 per accident). - **Medical payments/PIP limits** (e.g., $5,000 per person). - **Uninsured motorist limits** (matching bodily injury and property damage limits). Choosing adequate limits depends on asset exposure and state requirements. For example, a policyholder with significant savings or a high-income household may opt for **$250,000/$500,000 bodily injury limits** to protect against lawsuits, whereas state minimums (e.g., **$25,000/$50,000**) may suffice for others. Underestimating limits risks personal financial responsibility for excess damages. ---Exclusions and Policy Gaps
Exclusions specify scenarios or conditions where coverage does not apply. Common exclusions include: - **Intentional damage** (e.g., vandalism by the policyholder). - **Racing or stunt driving** (even on private property). - **Commercial use** (if the vehicle is used for business without an endorsement). - **Modified vehicles** (unless explicitly covered). - **Mechanical breakdowns** (typically excluded unless under a separate warranty). Ignoring exclusions can lead to denied claims. For example, a driver who modifies their car for increased horsepower may void collision coverage if the insurer deems the modifications unsafe. Reviewing exclusions alongside endorsements (optional add-ons) ensures comprehensive protection. ---Provider Reliability and Claims Handling
The insurer’s reputation for **claims processing speed, customer service, and financial stability** directly impacts the policyholder’s experience. Key metrics to evaluate include: - **J.D. Power customer satisfaction ratings** (e.g., State Farm consistently ranks high for claims satisfaction). - **NAIC (National Association of Insurance Commissioners) complaint index** (lower ratios indicate fewer customer disputes). - **AM Best financial strength ratings** (measures insurer solvency, e.g., AAA-rated providers like Allstate or Geico). - **Average claim settlement time** (e.g., Progressive offers 24/7 claims filing and rapid processing for glass claims). A provider with a **high complaint ratio** or **slow claim resolution** may lead to frustration during critical incidents. Verifying these factors through independent reviews (e.g., Consumer Reports, BBB) ensures informed decision-making. ---Categorization of Auto Insurance Providers
Auto insurance providers can be broadly classified into three distinct categories based on their business models and service delivery mechanisms: **traditional insurers**, **direct sellers**, and **aggregators**. Each category serves unique needs, offering varying levels of customization, cost efficiency, and customer support. Understanding these differences is essential for consumers to align their insurance choices with their preferences for convenience, coverage, and financial stability. The classification reflects how insurers interact with customers, process claims, and structure pricing. Traditional insurers rely on physical presence and agent-based services, while direct sellers leverage digital platforms to streamline operations. Aggregators, on the other hand, act as intermediaries, providing comparative tools to help consumers select policies from multiple providers. Below is a breakdown of each category, including their operational advantages, limitations, and notable examples. ---Traditional Insurers
Traditional insurers operate through a network of **local agents, brokers, or independent representatives** who assist customers with policy selection, claims filing, and personalized advice. This model emphasizes human interaction, which can be particularly valuable for complex coverage needs or high-net-worth individuals. However, it often comes with higher premiums due to overhead costs associated with maintaining a physical presence and agent commissions. The primary advantage of this model lies in its **personalized service and expertise**. Agents can tailor policies to address specific risks, such as classic car insurance or commercial fleet coverage, and provide immediate support during emergencies. Conversely, the reliance on intermediaries may lead to slower claim processing times and limited transparency in pricing. Additionally, customers may encounter inconsistent service quality depending on the agent’s experience or the insurer’s regional policies. **Examples of Traditional Insurers:** - **State Farm**: Known for its extensive agent network and community-focused underwriting. - **Allstate**: Offers a mix of digital tools and agent-assisted services, with a strong reputation for roadside assistance. - **Progressive**: While primarily a direct seller, it maintains a significant agent presence through **Progressive Advantage** for specialized policies. - **Nationwide**: Emphasizes personalized service through its **Nationwide Agents** network, including coverage for unique vehicles like motorcycles and RVs. ---Direct Sellers
Direct sellers eliminate intermediaries by offering policies **exclusively through online platforms, call centers, or mobile apps**. This model reduces operational costs, allowing insurers to pass savings to customers in the form of lower premiums or discounts. However, the trade-off is a lack of in-person support, which may frustrate customers requiring complex explanations or immediate assistance. The key advantage of direct sellers is **cost efficiency and accessibility**. Consumers benefit from simplified purchasing processes, 24/7 digital support, and often faster claim resolutions due to automated workflows. Disadvantages include limited flexibility in policy customization and potential difficulties in resolving disputes without human intervention. Additionally, some direct sellers may prioritize up-selling over customer needs, leading to frustration if policies are not clearly explained. **Examples of Direct Sellers:** - **Geico**: Dominates the market with its **low-cost, tech-driven approach**, including tools like the **Geico Mobile App** for claims and policy management. - **Liberty Mutual**: Offers a hybrid model with digital tools but retains a strong direct-selling focus, particularly for standard auto policies. - **Esurance (owned by Allstate)**: Specializes in **fully digital policies**, including usage-based insurance programs like **DriveSense**. - **Farmers Insurance**: While traditionally agent-based, its **Farmers Direct** division provides online-only policies for simpler coverage needs. ---Aggregators
Aggregators, also known as **insurance comparison platforms**, act as intermediaries by **compiling quotes from multiple insurers** on a single platform. They do not underwrite policies themselves but facilitate comparisons based on user-provided criteria (e.g., coverage limits, deductibles, or discounts). This model is ideal for consumers seeking **transparency and convenience**, though it may lack the depth of personalized service offered by traditional insurers. The primary benefit of aggregators is **time savings and broad market access**. Users can evaluate multiple options without contacting each insurer individually, and some platforms offer additional perks like **bundling discounts** or **usage-based tracking**. However, aggregators may prioritize **commission-based partnerships** over unbiased recommendations, potentially steering users toward higher-payout policies. Additionally, the quality of quotes depends on the insurers included in the platform’s network, which can vary by region. **Examples of Aggregators:** - **The Zebra (owned by Verisk Analytics)**: Uses **AI-driven tools** to match users with tailored policies and provides educational resources. - **Compare.com**: Aggregates quotes from **50+ insurers** and offers tools like **ID theft protection** as add-ons. - **NerdWallet**: Focuses on **financial literacy** alongside comparisons, including reviews of insurers’ customer service. - **Insure.com**: Provides **side-by-side policy comparisons** and highlights insurers with strong financial ratings. ---Verification of Financial Stability and Reputation
Selecting an insurer with strong financial stability and a reputable track record is critical to ensure **claims payout reliability** and long-term policy availability. Financial stability indicators include **insolvency risk ratings** from agencies like **AM Best, Moody’s, or Standard & Poor’s**, while reputation can be assessed through **customer reviews, complaint data, and industry awards**. **Financial Stability Indicators:** Financial ratings from independent agencies provide objective assessments of an insurer’s ability to meet obligations. A rating of **A- or higher from AM Best** generally indicates strong capacity to pay claims, while lower ratings (e.g., **B++ or below**) may signal higher risk of insolvency. For example: - **Geico (Berkshire Hathaway)**: Rated **A++ (Superior)** by AM Best, reflecting its parent company’s financial strength. - **State Farm**: Consistently rated **A++**, with a history of weathering economic downturns. - **Progressive**: Rated **A (Excellent)**, though its financial health is closely tied to its aggressive underwriting strategies. **Reputation Verification Methods:** Beyond ratings, consumers should evaluate: - **J.D. Power Customer Satisfaction Scores**: Measures claims satisfaction, interaction, and policy offerings (e.g., **State Farm ranks highest in 2023 for claims handling**). - **NAIC Complaint Index**: Compares complaint ratios relative to industry averages (e.g., **Allstate has a higher-than-average complaint ratio for policy disputes**). - **Better Business Bureau (BBB) Accreditation**: Indicates adherence to ethical business practices (e.g., **Geico holds an A+ rating with the BBB**). - **Industry Awards**: Recognitions from organizations like **Insurance Journal** or **Consumer Reports** highlight insurers excelling in innovation or customer service. **Step-by-Step Verification Process:** 1. **Check Financial Ratings**: Visit **AM Best, Moody’s, or S&P Global** to review the insurer’s long-term and short-term ratings. 2. **Review Complaint Data**: Access the **NAIC Complaint Index** ([naic.org](https://www.naic.org)) to compare complaint ratios by state. 3. **Consult Third-Party Reviews**: Use platforms like **J.D. Power, Consumer Reports, or Trustpilot** for aggregated customer feedback. 4. **Evaluate Digital Tools**: For direct sellers, test **mobile apps or online portals** for ease of use and claim processing speed. 5. **Cross-Reference with State Departments**: Some states (e.g., **California’s DOI**) publish **market conduct exams** that reveal enforcement actions against insurers. ---
Popular Online Tools and Apps for Auto Insurance Comparisons
Auto insurance comparison tools streamline the process of evaluating policies by aggregating quotes from multiple providers, allowing users to assess coverage, premiums, and benefits in one centralized platform. These tools leverage real-time data, user input, and advanced algorithms to deliver tailored recommendations, reducing the time and effort required for manual research. Below are the most widely used platforms, categorized by functionality and user base.Web-Based Comparison Platforms
Websites dominate the auto insurance comparison space due to their accessibility and comprehensive databases. These platforms typically require users to input vehicle details, driving history, and coverage preferences before generating side-by-side comparisons.- Insure.com Aggregates quotes from over 100 insurers, including national carriers like State Farm, Geico, and Progressive. Features tools like a "Best Rates by State" calculator and a "Discount Finder" to identify savings opportunities. Users can filter by coverage limits, deductibles, and additional perks such as roadside assistance or accident forgiveness.
- NerdWallet Combines quote comparisons with editorial reviews, educational resources, and a "Best for" categorization (e.g., best for high-risk drivers, best for full coverage). Includes a "Coverage Explorer" that breaks down policy components (liability, collision, comprehensive) with visual aids. NerdWallet also offers a mobile app for on-the-go access.
- The Zebra (by Progressive) Specializes in personalized recommendations using an AI-driven "smart shopping" engine. Highlights include a "Discount Checkup" to ensure users maximize savings and a "Usage-Based Insurance" section for telematics-eligible policies. The platform emphasizes transparency by displaying how premiums are calculated.
- Policygenius Focuses on user-friendly interfaces with a "Policy Explorer" that simplifies complex terms (e.g., umbrella policies, gap insurance). Offers a "Compare & Save" tool that highlights price differences between providers while explaining why certain insurers charge more or less. Integrates with third-party tools like credit score checkers.
- SelectQuote Operates as a brokerage-style platform, connecting users with licensed agents after initial quote comparisons. Provides access to niche insurers (e.g., those specializing in classic cars or high-value vehicles) and offers a "Multi-Policy Discount" calculator for bundling auto with home/renters insurance.
Mobile-First and App-Centric Tools
Mobile applications prioritize convenience, often incorporating features like biometric logins, push notifications for renewals, and in-app claims filing. These tools are ideal for users who prefer quick access and minimal manual input.- Insurify Uses AI to analyze user profiles and suggest insurers likely to offer competitive rates. The app includes a "Price Drop Alert" to notify users if their current insurer’s rates decrease and a "Claims Satisfaction Score" to gauge insurer responsiveness. Supports voice search for faster navigation.
- Jerry (by The Zebra) Marketed as an "insurance super app," Jerry automates the policy-switching process by handling paperwork and cancellations with insurers. Features include a "Bill Negotiator" that renegotiates rates with current providers and a "Jerry Score" to rank insurers by reliability. Requires a photo of the driver’s license and insurance card for verification.
- Clearcover Specializes in usage-based insurance with a mobile app that tracks driving behavior via GPS and diagnostics. Users earn discounts for safe driving habits, and the app provides real-time feedback on acceleration, braking, and phone usage. Offers a "Pay-Per-Mile" option for low-mileage drivers.
- Lemonade While primarily a direct insurer, Lemonade’s app includes a "Compare" feature that lets users see how its rates stack up against competitors like Allstate or Farmers. Uses AI chatbots ("AI Agents") to assist with claims and policy adjustments. Emphasizes transparency with a "Giveback" program that donates unused premiums to charities.
Specialized and Niche Comparison Tools
These platforms cater to specific audiences, such as high-net-worth individuals, commercial vehicle owners, or drivers with unique needs (e.g., electric vehicles or classic cars).- Hagerty Focuses on classic and collectible cars, offering tools to compare insurers that specialize in agreed-value coverage (insuring vehicles for their appraised worth). Includes a "Concours Insurance" section for show cars and a "Claims Concierge" service for high-value claims.
- EV Insurance Compare Aggregates quotes for electric and hybrid vehicles, highlighting insurers with telematics programs tailored to EV owners (e.g., discounts for charging station usage or battery health monitoring). Partners with providers like Root and Milewise.
- Commercial Auto Insurance Comparison Tools (e.g., TruckInsurance.com) Designed for business owners, these platforms compare commercial policies with features like fleet tracking, cargo insurance, and liability coverage for trucks/trailers. Often include tools to estimate operational costs (e.g., fuel surcharges, tolls).
State Laws and Their Impact on Auto Insurance Requirements and Costs
State laws play a critical role in shaping auto insurance mandates, minimum coverage thresholds, and premium pricing. Each U.S. state establishes its own regulations, leading to significant variations in what drivers must carry and how much they pay. These laws influence insurer obligations, claim processes, and financial protections for policyholders. Understanding these legal frameworks is essential for drivers to comply with requirements while optimizing coverage for affordability and risk mitigation. The interplay between state legislation and insurance markets determines whether policies emphasize liability protection, comprehensive coverage, or specialized add-ons. For example, no-fault states like Michigan or Pennsylvania require personal injury protection (PIP) coverage, while at-fault states like Texas or California prioritize bodily injury and property damage liability. Additionally, state-specific regulations on uninsured/underinsured motorist (UM/UIM) coverage, medical payments, and collision/comprehensive limits further diversify policy structures. ---Mandatory Coverage Variations by State Law
State laws dictate the minimum coverage requirements drivers must maintain, directly affecting policy costs and consumer choices. These mandates typically include: - **Liability Insurance**: Mandatory in all states except New Hampshire (where drivers must prove financial responsibility via alternative means). Limits vary widely, with some states (e.g., Florida) requiring **$10,000 per person/$20,000 per accident** for bodily injury and **$10,000 for property damage**, while others (e.g., Michigan) mandate **$50,000/$100,000/$10,000** due to higher medical cost expectations. - **Uninsured/Underinsured Motorist (UM/UIM) Coverage**: Some states mandate UM/UIM coverage (e.g., New Jersey, North Dakota), while others allow opt-outs (e.g., Virginia, Texas). Limits often mirror liability thresholds but may exceed them in states with high uninsured driver rates. - **Personal Injury Protection (PIP)**: Required in no-fault states to cover medical expenses regardless of fault, with limits ranging from **$2,500 (Pennsylvania)** to **$67,500 (Michigan)**. - **Medical Payments (MedPay)**: Offered in optional states (e.g., Alabama, Wisconsin) to supplement health insurance for minor injuries, typically capped at **$5,000–$10,000**. **Key Insight**:State-mandated minimums create a baseline for affordability but often underestimate real-world costs. For instance, a driver in Louisiana (with **$15,000/$30,000/$25,000** liability limits) may face higher out-of-pocket expenses in an accident than a driver in Massachusetts (with **$20,000/$40,000/$5,000** limits) due to differences in medical and repair costs.---
Comparison of Minimum Coverage Requirements Across Five U.S. States
The following table illustrates how state laws dictate baseline auto insurance requirements, highlighting disparities in liability, UM/UIM, and additional mandates. Data reflects 2023–2024 regulations and is sourced from state departments of insurance and NAIC (National Association of Insurance Commissioners). | **State** | **Bodily Injury Liability** | **Property Damage Liability** | **UM/UIM Bodily Injury** | **UM/UIM Property Damage** | **PIP/MedPay Mandate** | **Additional Notes** | |-----------------|----------------------------------|-------------------------------|--------------------------------|-----------------------------|-----------------------------|-----------------------------------------------| | **California** | $15,000/$30,000 | $5,000 | Optional (limits match liability) | Optional (limits match liability) | Optional (MedPay) | High uninsured driver rates (13.4% in 2022). | | **Florida** | $10,000/$20,000 | $10,000 | Mandatory ($10,000/$20,000) | Mandatory ($10,000) | Mandatory PIP ($10,000) | No-fault state; PIP covers 80% of medical costs. | | **Michigan** | $50,000/$100,000 | $10,000 | Mandatory (limits match liability) | Mandatory (limits match liability) | Mandatory PIP ($67,500) | Highest average premiums in the U.S. ($2,500+/year). | | **Texas** | $30,000/$60,000 | $25,000 | Optional (limits match liability) | Optional (limits match liability) | Optional (MedPay) | Uninsured motorist rate: 12.2% (2022). | | **New York** | $25,000/$50,000 | $10,000 | Mandatory ($25,000/$50,000) | Mandatory ($10,000) | Optional (Basic Economic Loss) | Requires "basic economic loss" coverage ($50,000). | **Analysis**: - **High-Liability States (Michigan, New York)**: Reflect higher medical and legal costs, leading to elevated premiums but stronger consumer protections. - **Low-Liability States (Florida, California)**: Prioritize affordability but leave drivers vulnerable to higher out-of-pocket expenses in accidents. - **UM/UIM Mandates**: States like Florida and New York require UM/UIM coverage, protecting drivers from uninsured motorists, while others (e.g., Texas) allow opt-outs, increasing risk for policyholders. ---Urban vs. Rural Location Impact on Premium Pricing
Geographic location—specifically urban versus rural settings—significantly influences auto insurance costs due to variations in risk factors, claim frequencies, and infrastructure. Insurers assess location-based risks through **territorial ratings**, which adjust premiums based on: - **Traffic Density**: Urban areas (e.g., Los Angeles, New York City) experience higher accident rates due to congestion, distracted driving, and pedestrian interactions. For example, a driver in Manhattan pays **~40% more** than a rural counterpart in Vermont for the same coverage, according to Insure.com (2023). - **Theft and Vandalism**: Urban environments with higher crime rates (e.g., Detroit, Baltimore) lead to increased comprehensive claim costs. States like California and New Jersey report **2–3x higher theft-related claims** than rural states like Iowa or North Dakota. - **Emergency Services Response Time**: Rural areas may have longer response times for police or medical assistance, potentially increasing liability risks. However, lower traffic volumes often offset this with reduced collision claims. - **Insurance Fraud**: Urban centers with dense populations are hotspots for staged accidents and exaggerated claims, prompting insurers to apply **higher fraud adjustment factors** (e.g., +15–25% in Miami vs. +5% in Billings, MT). **Urban-Rural Premium Disparities**:A 30-year-old driver in Chicago (average premium: **$1,800/year**) pays **$600–$800 more annually** than a similar driver in rural Nebraska ($1,200/year), primarily due to higher collision and theft risks. Conversely, rural drivers may face **lower liability premiums** but higher deductibles for weather-related damages (e.g., hailstorms in Kansas).**State-Specific Examples**: - **California**: Urban drivers in Los Angeles pay **~$2,200/year** for full coverage, while rural drivers in the Central Valley pay **~$1,500/year**. - **Texas**: Houston drivers average **$1,900/year**, compared to **$1,300/year** in Lubbock. - **Florida**: Miami’s premiums (**$2,100/year**) exceed Tallahassee’s (**$1,400/year**) by **~50%**, driven by hurricane risks and urban traffic. ---
Weather-Related Risks and Their Influence on Policy Terms
Climate and weather patterns directly shape auto insurance policies, particularly in regions prone to natural disasters. Insurers adjust coverage terms, deductibles, and premiums based on: - **Hail and Storm Damage**: States like Texas, Colorado, and Illinois experience frequent hailstorms, leading to **comprehensive coverage mandates** and higher deductibles (e.g., **$1,000–$2,500** in Dallas vs. **$500** in Phoenix). Texas insurers report **~30% of claims** are weather-related, with hail causing **$2.5 billion in annual damages**. - **Flooding**: Coastal states (e.g., Florida, Louisiana) and flood-prone regions (e.g., North Dakota, Iowa) require **separate flood insurance** or higher comprehensive limits. The National Flood Insurance Program (NFIP) estimates **$3.5 billion in annual auto flood claims**, often excluded from standard policies. - **Winter Conditions**: Northern states (e.g., Minnesota, Maine) mandate **snow tire discounts** or higher collision coverage due to icy road risks. Insurers in these areas may offer **winter driving courses** for premium reductions. - **Wildfires**: California and Oregon drivers face **higher premiums** due to wildfire risks, with some insurers imposing **defensible space inspections** or **non-renewal clauses** for high-risk properties. **Policy Adjustments for High-Risk Weather Zones**: - **Deductible Waivers**: Some insurers in hail-prone areas (e.g., Denver) offer **$0 deductibles for wind/hail claims** if the driver has a claims-free history. - **Exclusion Clauses**: Standard policies often exclude **flood or earthquake damage**; separate endorsements may cost **$100–$300/year**. - **Premium Surges**: After major disasters (e.g., Hurricane Ian in Florida), insurers may **suspend new policies** or **increase rates by 30–50%** for affected ZIP codes. **Example**: In **Oklahoma City**, a driver with full coverage pays **$1,700/year** but faces a **$2,000 deductible** for hail damage, while a **Miami driver** pays **$2,100/year** but may need **flood insurance** (additional **$500–$1,000/year**) due to hurricane risks. ---State-Specific Mandates for Uninsured Motorist Coverage
Uninsured motorist (UM) and underinsured motorist (UIM) coverage protects drivers when at-fault parties lack sufficient insurance. State laws dictate whether this coverage is **mandatory, optional, or excluded**, with limits often tied to liability thresholds. TheComponents That Contribute to Auto Insurance Premiums
Auto insurance premiums are determined by a combination of factors that assess risk, coverage needs, and policyholder demographics. Insurers evaluate these components to calculate the cost of providing coverage while ensuring financial stability for policyholders. Understanding these elements helps individuals make informed decisions when comparing policies and negotiating rates. The premium calculation is based on statistical models that predict the likelihood of a claim. Variables such as personal characteristics, vehicle attributes, and location-specific risks play a critical role. Below is a breakdown of the primary factors influencing premiums, categorized by their impact on risk assessment. ---Personal and Demographic Factors
Insurers analyze demographic data to estimate risk levels associated with individual policyholders. Age, gender, marital status, and driving history are key variables that affect premiums due to their correlation with claim frequency.**Example:** Younger drivers (typically under 25) pay higher premiums because statistical data shows they are more likely to be involved in accidents compared to older, more experienced drivers.
- **Age and Experience** Younger drivers lack experience, leading to higher premiums. Conversely, drivers aged 50+ often qualify for discounts due to lower accident rates. For instance, a 16-year-old driver may pay **30–50% more** than a 30-year-old with a clean record.
- **Gender** Historically, male drivers under 25 have been associated with higher claim frequencies, resulting in higher premiums. However, many states prohibit gender-based pricing, and insurers now rely on broader risk assessments.
- **Marital Status** Married individuals often receive discounts (e.g., 5–10%) as statistical data suggests they are more responsible drivers. This assumption is based on studies indicating lower accident rates among married policyholders.
- **Driving Record** Traffic violations (e.g., speeding tickets, DUIs) and at-fault accidents increase premiums significantly. A single DUI can raise rates by **30–100%**, while a clean record may qualify for a **"safe driver" discount** of 5–20%.
- **Credit Score** In most states, credit history influences premiums, as studies link financial responsibility to lower risk. A poor credit score (below 580) may increase premiums by **20–50%** compared to excellent credit (720+).
Vehicle-Related Factors
The type of vehicle, its age, safety features, and repair costs directly impact premiums. Insurers assess the risk of theft, accident severity, and claim payouts based on vehicle-specific data.**Example:** A luxury sports car may cost **40–60% more** to insure than a mid-range sedan due to higher repair costs and theft vulnerability.
- **Vehicle Make and Model** Cars with high theft rates (e.g., Honda Civics, Ford F-Series) or expensive repair costs (e.g., BMW, Mercedes-Benz) incur higher premiums. Insurers reference databases like the **National Highway Traffic Safety Administration (NHTSA)** and **Higher Loss Cost Multipliers (HLCM)** to adjust rates.
- **Vehicle Age and Value** Newer cars often have higher premiums due to replacement costs, while older vehicles (10+ years) may qualify for lower rates if their market value is minimal. However, classic or high-value cars (e.g., Porsche 911) require **agreed-value coverage**, increasing costs.
- **Safety and Security Features** Vehicles equipped with **anti-theft devices (e.g., GPS tracking, immobilizers)**, **collision avoidance systems (e.g., automatic emergency braking)**, and **high safety ratings (e.g., IIHS Top Safety Pick)** may qualify for discounts of **5–25%**.
- **Engine Size and Horsepower** High-performance vehicles (e.g., muscle cars, sports cars) often face higher premiums due to increased accident risk and repair expenses. For example, a **Dodge Challenger** may cost **$2,000–$3,000 more annually** than a Toyota Camry.
- **Usage and Mileage** Low-mileage drivers (under 7,500 miles/year) may receive **"low-mileage discounts"** (5–15%). Conversely, rideshare drivers (e.g., Uber, Lyft) pay **20–50% more** due to increased exposure to accidents.
Location-Based Factors
Geographic location influences premiums due to variations in crime rates, traffic density, weather conditions, and state regulations. Urban areas and regions prone to natural disasters (e.g., hurricanes, floods) typically have higher premiums.**Example:** Drivers in **Florida** pay **20–50% more** for collision coverage due to hurricane risks, while those in **North Dakota** may see lower rates due to minimal weather-related claims.
- **State and Local Regulations** States with **no-fault insurance laws** (e.g., Michigan, Florida) or high minimum coverage requirements (e.g., California) may have elevated premiums. Additionally, **state-specific fees** (e.g., Florida’s **Hurricane Catastrophe Fund assessment**) add to costs.
- **Crime and Theft Rates** Areas with high vehicle theft (e.g., **California, Texas**) or vandalism (e.g., **Detroit, Chicago**) result in higher premiums. Insurers use **FBI crime statistics** and **local police reports** to adjust rates.
- **Traffic Density and Commute Patterns** Urban drivers (e.g., **New York, Los Angeles**) face higher premiums due to increased accident risks from congestion and distracted driving. Conversely, rural areas may offer **10–30% lower rates**.
- **Natural Disaster Risks** Regions prone to **floods (e.g., Louisiana), wildfires (e.g., California), or hailstorms (e.g., Texas)** incur additional coverage costs. For instance, **flood insurance** (via FEMA’s **National Flood Insurance Program**) is mandatory in high-risk zones and can add **$500–$1,500 annually**.
- **Garaging Address** Where the vehicle is primarily stored affects rates. Parking in a **gated community or secure garage** may qualify for a **storage discount (5–10%)**, while street parking in high-theft areas increases premiums.
Coverage and Policy-Specific Factors
The level of coverage selected, deductibles, and optional add-ons directly impact premiums. Policyholders must balance cost with adequate protection to avoid financial vulnerability in the event of a claim.**Example:** Increasing the **collision deductible from $500 to $1,000** can reduce annual premiums by **10–20%**, but higher out-of-pocket costs in an accident may offset savings.
-
**Coverage Limits and Types**
Liability coverage (required by law) costs less than **full coverage (collision/comprehensive)**, but underinsured motorist (UM) and uninsured motorist (UIM) protections add **$200–$800 annually**. State minimums vary:
- **Liability-only (e.g., Texas):** $30,000/$60,000 (per accident/injury) + $25,000 (property damage).
- **Full coverage (e.g., California):** $50,000/$100,000 liability + $100,000 UM/UIM.
- **Deductibles** Higher deductibles (e.g., $1,000 vs. $250) lower premiums but increase financial risk. A **$500 deductible** might save **$300–$600 annually** compared to a $250 deductible.
- **Optional Add-Ons** Extras like **roadside assistance ($50–$150/year)**, **rental reimbursement ($20–$50/month)**, or **gap insurance (for loans)** increase premiums. **Personal injury protection (PIP)** in no-fault states can add **$1,000–$3,000 annually**.
-
**Discounts and Bundling**
Policyholders can reduce costs through:
- **Multi-policy discounts (e.g., auto + home insurance):** 10–25% savings.
- **Loyalty discounts:** 5–10% for long-term customers.
- **Telematics programs (e.g., Progressive’s Snapshot):** Up to 30% for safe driving.
- **Affinity discounts (e.g., AAA, alumni associations):** 5–15%.
- **Payment Plans and Frequency** Paying **annually** (vs. monthly) often grants a **2–5% discount**. Monthly plans may include **finance charges (1–3% monthly)**, adding **$120–$600 annually** in interest.
Steps in Filing an Auto Insurance Claim
Filing an auto insurance claim involves a structured process to ensure timely compensation and resolution. Understanding each step minimizes delays and clarifies expectations regarding documentation, communication, and follow-up. Insurers typically require adherence to specific procedures, and deviations may impact claim approval or payout speed. The process begins immediately after an incident and concludes with claim settlement or denial. Each stage—from initial reporting to final resolution—requires careful attention to deadlines, evidence collection, and insurer communication. Below are the sequential phases, including critical actions and common pitfalls. ---Incident Reporting and Immediate Actions
The first step occurs immediately after an accident or loss, where prompt action preserves evidence and meets policy requirements. Failure to act swiftly may result in claim rejection or reduced compensation. - **Assess safety and legality**: Ensure all parties are safe, move vehicles to a secure location if possible, and comply with traffic laws (e.g., exchanging information). - **Document the scene**: Use a smartphone to capture photos/videos of vehicle damage, license plates, road conditions, and visible injuries. Note time, date, and weather. - **Gather witness details**: Collect names and contact information from witnesses, as their statements may support the claim. - **Notify law enforcement**: File a police report if the incident involves injuries, fatalities, or disputes over fault. Police reports serve as official documentation. - **Check for policy coverage**: Review the insurance policy to confirm coverage for the type of incident (e.g., collision, comprehensive, uninsured motorist). **Key Consideration**: > **Deadline Alert**: Most policies require claims to be reported **within 24–72 hours** of the incident. Delayed notifications may void coverage. ---Contacting the Insurance Provider
This step formalizes the claim and initiates the insurer’s investigation. Providing accurate details upfront accelerates processing and reduces back-and-forth communication. - **Locate the claim number**: Use the insurer’s website, mobile app, or customer service hotline to start the claim. Have the policy number, vehicle details, and incident specifics ready. - **Provide incident details**: Describe the event (e.g., collision, theft, vandalism) and include: - Date, time, and location. - Parties involved (names, contact info, insurer details if at-fault). - Police report number (if applicable). - **Request a claim adjuster**: If the damage is significant or liability is disputed, an adjuster may inspect the vehicle and assess fault. - **Follow up on deadlines**: Confirm the insurer’s expected timeline for initial contact (typically **24–48 hours** for urgent claims). **Common Mistake**: > **Incomplete Information**: Omitting details like witness names or failing to submit a police report can prolong investigations. ---Claim Investigation and Evidence Submission
Insurers verify the claim’s validity by reviewing evidence, interviewing parties, and assessing damages. Cooperation during this phase ensures a smoother process. - **Submit required documents**: - Police report (if applicable). - Photos/videos of the incident and damage. - Vehicle repair estimates (if known). - Medical reports (for injury claims). - Rental car receipts (if applicable). - **Cooperate with the adjuster**: If assigned, allow the adjuster to inspect the vehicle and ask questions. Provide access to maintenance records if the damage is pre-existing. - **Track evidence deadlines**: Insurers may set **10–30 days** for submitting additional documentation. Missed deadlines can stall the claim. - **Challenge unreasonable requests**: Politely push back if the insurer asks for irrelevant or excessive documentation. **Evidence Hierarchy**: > **Most Valuable Evidence**: > 1. Police report (official record of fault). > 2. Witness statements (credible third-party accounts). > 3. Photos/videos (visual proof of damage and scene). > 4. Repair estimates (from licensed shops). ---Claim Evaluation and Settlement Offer
After investigating, the insurer evaluates the claim’s validity and calculates compensation. This phase often involves negotiation, especially if the offer seems low or unfair. - **Receive the initial offer**: The insurer provides a settlement amount based on: - Vehicle repair costs (or actual cash value for total losses). - Medical expenses (if applicable). - Rental car reimbursement. - Pain and suffering (in bodily injury claims). - **Review the offer for accuracy**: Compare the insurer’s estimate with: - **Repair estimates** from multiple shops. - **Vehicle’s fair market value** (for totaled cars, use tools like Kelley Blue Book). - **Medical bills** (ensure all treatments are covered). - **Negotiate if necessary**: Dispute the offer in writing, citing evidence (e.g., higher repair quotes, underestimation of damages). - **Accept or reject the offer**: Signing the settlement releases the insurer from further liability. Rejecting may lead to mediation or appeal. **Negotiation Tip**: > **Use Comparative Data**: If the insurer lowballs a repair estimate, provide quotes from **three licensed body shops** to justify a higher payout. ---Claim Resolution and Dispute Handling
Not all claims proceed smoothly. Delays, disputes, or denials may require escalation or legal intervention to resolve. - **Monitor the timeline**: Most claims resolve within **14–30 days**, but complex cases may take **60+ days**. Use the insurer’s portal to track status updates. - **Escalate unresolved claims**: If the insurer fails to respond within promised timeframes, contact: - The **claims supervisor** (escalation contact provided during filing). - The **state insurance department** (for regulatory complaints). - A **public adjuster** (for complex disputes, typically 10–20% of the claim value). - **Appeal a denied claim**: If denied, request a **written explanation** and gather additional evidence to submit for reconsideration. - **Legal action (last resort)**: For fraudulent denials or bad-faith practices, consult an attorney specializing in insurance law. **Red Flags in Denials**: > **Unreasonable Denial Reasons**: > - "Late reporting" when the insurer was notified within the policy’s window. > - "Pre-existing damage" without proof of prior incidents. > - "Excluded coverage" when the policy explicitly includes the claim type. ---Use of Actuarial Data to Predict Future Premium Changes
Actuarial science integrates statistical and financial principles to assess risk and project future trends in insurance pricing. By analyzing historical claims data, loss ratios, and demographic shifts, insurers refine premium models to anticipate adjustments. These predictions account for economic conditions, regulatory changes, and emerging risks like autonomous vehicle adoption or climate-related claims. The foundation of premium forecasting lies in **loss ratio analysis**, which compares incurred claims to earned premiums. A rising loss ratio signals potential rate hikes, while improvements may justify discounts. Actuarial models also incorporate **inflation adjustments** for repair costs and medical expenses, as well as **frequency-severity trends**—how often claims occur and their average cost. For example, the National Association of Insurance Commissioners (NAIC) reports that auto repair costs increased by **12% annually** between 2018–2023, directly influencing underwriting assumptions.Key Actuarial Data Sources for Premium Modeling
Insurers rely on structured datasets to build predictive models. Primary sources include:- **Internal Claims Databases**: Historical claims records segmented by policyholder demographics (age, location, vehicle type), claim types (collision vs. comprehensive), and severity. For instance, a 2022 study by the Insurance Information Institute (III) found that drivers aged 16–25 file **3x more claims** than those over 50, a factor weighted heavily in youthful premiums.
- **External Industry Benchmarks**: Reports from NAIC, ISO (Insurance Services Office), or government agencies (e.g., NHTSA traffic fatality data). These provide macro-level trends, such as the **10% increase in distracted-driving claims** post-2020, which insurers factor into territorial rate adjustments.
- **Economic Indicators**: Consumer Price Index (CPI) for auto parts, labor costs, and healthcare inflation. Actuaries use **hedonic regression models** to isolate cost drivers—e.g., the **$1,200 average increase** in collision repair costs per vehicle due to advanced driver-assistance systems (ADAS).
- **Regulatory Filings**: State-specific rate filings submitted by insurers to departments of insurance. These often reveal **territorial rate differentials**—urban areas may see premiums **20–30% higher** than rural zones due to higher accident frequencies.
Statistical Techniques for Premium Forecasting
Actuaries employ quantitative methods to project premium changes. Common approaches include:- **Generalized Linear Models (GLMs)**: Used to estimate claim costs by linking independent variables (e.g., mileage, credit score) to dependent outcomes (premiums). A GLM might reveal that **each additional 5,000 annual miles increases collision risk by 8%**, justifying higher premiums for high-mileage drivers.
- **Time-Series Analysis**: Models like ARIMA (AutoRegressive Integrated Moving Average) predict claim trends over time. For example, analyzing **10 years of hailstorm data** in Texas could forecast a **15% premium spike** in 2025 due to climate patterns.
- **Machine Learning Algorithms**: Neural networks or random forests identify non-linear patterns. State Farm’s **AI-driven pricing tool** reportedly adjusts premiums dynamically based on real-time data like **telematics usage** or **local crime rates**.
Case Study: Predicting Premium Shifts Post-Natural Disaster
After Hurricane Ian (2022), Florida insurers faced **$75 billion in claims**, prompting actuarial teams to model long-term adjustments. Steps included:- **Loss Ratio Projection**: Using **chain-ladder techniques**, actuaries estimated a **30% increase in comprehensive premiums** for coastal policies, assuming a **25% claim frequency rise** and **15% severity growth** due to water damage.
- **Reinsurance Impact**: Insurers bought **catastrophe bonds** to offset risk, reducing their exposure but increasing base premiums by **$200–$500 annually** for policyholders.
- **Regulatory Response**: Florida’s Office of Insurance Regulation capped rate hikes at **5% annually** for 2023–2024, forcing actuaries to **redistribute costs** via underwriting criteria (e.g., stricter credit-based pricing).
**Actuarial Formula for Premium Adjustment**: *New Premium = Base Rate × (1 + (ΔLoss Ratio + ΔInflation + ΔRegulatory Factor))* *Example*: A $1,000 policy with a **10% loss ratio increase**, **5% inflation**, and **3% regulatory costs** would adjust to **$1,185**.
Niche Auto Insurance Coverage Types and Specialized Policies
Auto insurance policies extend beyond standard liability and collision protection to accommodate specialized needs. These niche coverages address unique risks associated with high-value assets, alternative vehicle types, or unconventional usage scenarios. Understanding these options ensures tailored protection for owners of classic cars, electric vehicles (EVs), or those using their vehicles for commercial purposes like ridesharing. The availability and cost of niche coverages vary by insurer, region, and vehicle specifications. Some policies may require additional documentation, such as vehicle history reports, specialized maintenance records, or proof of usage (e.g., mileage logs for classic cars). Below are key niche coverage types, their eligibility criteria, and considerations for potential applicants. ---Classic and Collector Vehicle Insurance
Classic and collector vehicles often require specialized insurance due to their high value, limited availability of replacement parts, and unique storage or transportation needs. Standard auto policies may not adequately cover depreciation, restoration costs, or agreed-value settlements in case of total loss. **Key Features:** - **Agreed Value Coverage:** Policies assess the vehicle at an agreed-upon value (often higher than market value) to ensure fair compensation in case of loss. This differs from actual cash value (ACV) policies, which depreciate based on age and condition. - **Scheduled Personal Property Coverage:** Extends protection to modifications, accessories, or equipment (e.g., custom paint, vintage tires, or aftermarket engines) that standard policies may exclude. - **Storage and Transportation Protection:** Covers risks during storage (e.g., climate-controlled facilities) or transit (e.g., shipping to car shows or auctions). Some insurers offer "driveaway" coverage for vehicles transported to events. - **Mileage Restrictions:** Classic car insurers often enforce low annual mileage limits (e.g., <5,000 miles/year) to qualify for discounts and ensure the vehicle remains in pristine condition. **Eligibility Criteria:** - Vehicle must meet age or model-year thresholds (typically pre-1980s or limited-production models). - Proof of authenticity (e.g., title branding, club membership, or appraiser certification). - Storage in a secure, enclosed facility (garage or dedicated space). - Usage restrictions (e.g., pleasure driving only, no daily commuting). **Example Providers:** - **Hagerty:** Specializes in classic car insurance with coverage for over 400,000 collector vehicles. - **The National Automobile and Truck Museum (NATME) Insurance Program:** Offers policies for museum-quality vehicles. - **State Farm (Classic Car Endorsement):** Adds classic car coverage to existing policies for eligible vehicles. ---Rideshare and Commercial Use Insurance
Rideshare drivers (e.g., Uber, Lyft) and individuals using personal vehicles for commercial purposes (e.g., food delivery, ride-hailing) face higher liability risks due to increased exposure to accidents, theft, and third-party claims. Standard personal auto policies typically exclude commercial use, leaving drivers vulnerable to claim denials. **Coverage Types:** - **Period-Based Coverage:** Aligns with rideshare apps' operational phases (e.g., "app on but no passenger," "en route to passenger," "during trip"). Insurers like Uber and Lyft provide primary coverage during trips, but supplementary policies fill gaps during off-duty periods. - **Commercial Auto Policies:** Required for businesses owning multiple vehicles or drivers. These policies account for higher mileage, vehicle wear, and liability limits (e.g., $1M+ for commercial fleets). - **Hired and Non-Owned Auto Coverage:** Protects drivers who use personal vehicles for business (e.g., contractors) by extending liability to rented or borrowed vehicles. - **Cargo Insurance:** Essential for delivery drivers, covering damage or loss of goods transported (e.g., food, packages). Limits often range from $500 to $5,000 per incident. **Regulatory Compliance:** - **State Requirements:** Some states (e.g., California, New York) mandate commercial auto insurance for rideshare drivers, even if the app provides primary coverage. Violations may result in fines or license suspension. - **Background Checks:** Insurers may require criminal history or driving record checks for commercial policies due to higher fraud risks. **Cost Factors:** - **Usage Frequency:** Higher mileage or 24/7 availability increases premiums. - **Vehicle Age/Model:** Newer, safer vehicles (e.g., Tesla Model 3) may qualify for discounts, while older models incur higher repair costs. - **Claims History:** Personal or commercial claims history directly impacts rates. **Example Providers:** - **Geico (Rideshare Endorsement):** Offers supplemental coverage for Uber/Lyft drivers. - **Progressive (Commercial Auto):** Provides policies for delivery services and small businesses. - **The Hartford (Commercial Auto):** Specializes in fleet and commercial vehicle insurance. ---Electric Vehicle (EV) and Hybrid Insurance
Electric and hybrid vehicles present unique insurance challenges due to higher repair costs, specialized parts, and evolving technology risks. Standard policies may not account for the value of lithium-ion batteries, advanced driver-assistance systems (ADAS), or charging infrastructure liabilities. **Specialized Coverage:** - **Battery and Electrical System Protection:** Covers replacement or repair of damaged batteries (e.g., from collisions, fires, or manufacturing defects). Some insurers offer "battery warranty extensions" for out-of-warranty vehicles. - **Charging Station Liability:** Protects against claims if a home or public charging station causes property damage or injury (e.g., electrical fires, tripping hazards). - **ADAS and Software Coverage:** Extends protection to sensors, cameras, and autonomous driving features (e.g., Tesla Autopilot, GM Super Cruise). Repairs may require certified technicians, increasing costs. - **Theft and Vandalism:** EVs are targeted for battery theft (e.g., copper wire stripping) or hacking risks (e.g., remote access vulnerabilities). Policies may include "electronic theft" endorsements. **Cost Considerations:** - **Higher Premiums:** EVs often cost more to insure due to expensive repairs (e.g., $10,000–$20,000 for a battery replacement) and limited salvage markets for totaled vehicles. - **Safety Discounts:** Vehicles with high safety ratings (e.g., IIHS Top Safety Pick+) may qualify for discounts, offsetting some costs. - **Usage-Based Insurance (UBI):** Programs like **State Farm’s Drive Safe & Save** or **Allstate’s Drivewise** offer discounts for low-mileage EV owners who use regenerative braking or eco-driving features. **Example Providers:** - **State Farm (EV Endorsement):** Covers Tesla, Nissan Leaf, and Chevrolet Bolt models with battery-specific protections. - **Esurance (EV Insurance):** Partners with charging networks like ChargePoint for liability coverage. - **Farmers Insurance (Hybrid Coverage):** Offers discounts for plug-in hybrids (PHEVs) with lower emissions. ---Modified and Custom Vehicle Insurance
Modified vehicles—such as lifted trucks, lowriders, or performance cars—require specialized insurance due to increased risk of theft, accidents, or mechanical failures. Standard policies may exclude modifications or limit payouts based on market value rather than the owner’s investment. **Impact of Modifications on Insurance:** - **Safety Risks:** Alterations like suspension lifts, engine swaps, or nitrous oxide installations can void manufacturer warranties and increase accident severity. Insurers may classify these vehicles as "high-performance" or "street rods," leading to higher premiums. - **Theft Vulnerability:** Custom vehicles are prime targets for theft (e.g., lowriders with rare paint jobs or lifted trucks with aftermarket parts). Comprehensive coverage with theft protection is critical. - **Agreed Value vs. Actual Cash Value (ACV):** Modified vehicles should be insured under **agreed value** to reflect their custom enhancements. ACV policies depreciate based on stock specifications, undervaluing modifications. **Coverage Types:** - **Custom Parts and Equipment Coverage:** Protects aftermarket additions (e.g., custom wheels, exhaust systems, or interior upgrades) from damage or theft. Some insurers require itemized inventories. - **Chase and Recovery:** Covers the cost of tracking and retrieving stolen vehicles, including rewards for informants. - **Mechanical Breakdown Insurance (MBI):** Extends warranty-like protection for modified engines or drivetrains (e.g., turbocharged systems). Often sold as an add-on to collision/comprehensive policies. **Eligibility and Underwriting:** - **Inspection Requirements:** Insurers may mandate pre-policy inspections to assess modifications (e.g., lift height, engine modifications, or roll cages). - **Usage Restrictions:** Some policies prohibit street racing or off-road use, which can void coverage in case of accidents. - **Garaging Location:** Vehicles stored in high-crime areas may face surcharges or require security system installations (e.g., GPS tracking). **Example Providers:** - **Dairyland Insurance (Modified Vehicle Program):** Specializes in lifted trucks and off-road vehicles. - **State Farm (Custom Parts Endorsement):** Adds coverage for aftermarket modifications to existing policies. - **Progressive (Street Rod Insurance):** Targets classic and modified cars with agreed-value settlements. ---Common Pitfalls in Auto Insurance Policy Comparison
Comparing auto insurance policies requires careful attention to detail, as even minor oversights can result in financial losses or inadequate protection. Many consumers unknowingly fall into traps that compromise their coverage, often due to misinformation, haste, or lack of awareness about industry practices. Understanding these errors helps in making informed decisions and avoiding costly mistakes. ---Top Five Errors People Make When Comparing Policies
Even experienced policyholders frequently overlook critical aspects during comparisons, leading to suboptimal coverage. Below are the most common mistakes, ranked by their frequency and severity.- **Focusing Solely on Premium Costs** Consumers often prioritize the lowest monthly or annual premium without evaluating the trade-offs in coverage limits, deductibles, or policy exclusions. A policy with a slightly higher premium may offer significantly better protection, especially in high-risk scenarios like at-fault accidents or natural disasters. For example, a $500 annual increase in premium might save thousands in claim denials or out-of-pocket expenses.
- **Ignoring Deductible Implications** Higher deductibles reduce premiums but increase financial risk during claims. Many policyholders assume they will never file a claim or underestimate repair costs. However, a $1,000 deductible on a $5,000 repair bill leaves the policyholder responsible for 20% of the cost. Additionally, some insurers apply deductibles per incident rather than per claim, which can be misleading.
- **Overlooking Usage-Based Discounts** Telematics programs (e.g., Progressive’s Snapshot, State Farm’s Drive Safe & Save) offer discounts for safe driving but require enrollment. Some consumers skip these programs due to privacy concerns or lack of awareness, missing out on potential savings of 10–30% on premiums. Telematics data can also reveal unsafe habits, prompting corrective actions before they lead to claims.
- **Assuming All Insurers Cover the Same Risks Equally** Policy wording varies significantly between providers. For instance, one insurer might exclude coverage for rideshare driving (e.g., Uber/Lyft) unless a commercial policy is added, while another may offer endorsements for such use. Without comparing these nuances, policyholders risk gaps in protection during common activities like commuting or road trips.
- **Neglecting Future Needs in Policy Selection** A policy adequate for a $20,000 car may be insufficient for a $50,000 vehicle, yet many consumers fail to adjust coverage as their assets grow. Additionally, factors like aging vehicles (where collision coverage may no longer be cost-effective) or changes in driving habits (e.g., long commutes, frequent road trips) are rarely reassessed. Static policies often lead to either overpaying or underinsuring.
Why Overlooking Policy Exclusions Leads to Denied Claims
Policy exclusions are clauses that specify what an insurer will *not* cover, and these are often buried in fine print. Ignoring them can result in claims being denied, leaving policyholders financially exposed. Exclusions are typically categorized into three types: **standard exclusions** (e.g., intentional damage, racing), **optional exclusions** (e.g., modified vehicles, custom parts), and **state-specific exclusions** (e.g., flood damage in non-flood zones).-
**Standard Exclusions**
Most policies exclude coverage for:
- Damage from unlicensed or suspended drivers.
- Modifications not disclosed to the insurer (e.g., lifted suspensions, engine tuning).
- Use of the vehicle for commercial purposes without proper endorsements.
- Mechanical breakdowns (unless covered under a separate warranty).
-
**Optional Exclusions**
Some insurers offer to exclude coverage for:
- Driving under the influence (DUI) or with a suspended license.
- Vehicles used for ridesharing without commercial policies.
- Personal property stolen from the vehicle (e.g., laptops, tools).
-
**State-Specific Exclusions**
Certain states mandate exclusions due to local risks or regulations. For example:
- Florida excludes windstorm/hail damage unless purchased separately.
- California may exclude earthquake damage unless added as an endorsement.
- Some states exclude coverage for "consequential damages" (e.g., lost income due to a car accident).
How Underestimating Future Vehicle Value Affects Coverage Needs
Auto insurance coverage is often based on the **actual cash value (ACV)** of the vehicle at the time of a claim, which is calculated using depreciation schedules. Many consumers purchase coverage based on the vehicle’s current market value, failing to account for future depreciation or potential increases in value (e.g., classic cars, high-demand models). This oversight can lead to either overpaying for coverage or being severely underinsured.-
**Depreciation and ACV Gaps**
A vehicle loses value rapidly in the first 3–5 years. For example:
- A $30,000 car may depreciate to $18,000 by year 3, but if the policyholder only insures it for $25,000, they risk paying the full $7,000 gap out of pocket in a total loss scenario.
- Luxury or high-performance vehicles depreciate slower but still require adjusted coverage. A $50,000 sports car might retain 60% of its value after 5 years, but if the policy limits are set at $35,000, the owner could lose $15,000 in a claim.
-
**Specialized Vehicles and Market Demand**
Some vehicles appreciate over time, such as:
- Classic cars (e.g., 1967 Mustang, 1993 Mazda MX-5).
- Limited-edition or low-production models (e.g., Porsche 911 GT3, Tesla Cybertruck).
- Collectible or restored vehicles.
- **Loan or Lease Obligations** If a vehicle is financed or leased, the lender or lessor typically requires **collision and comprehensive coverage** to protect their interest. However, policyholders often drop these coverages once the loan is paid off, assuming the vehicle’s value is low. This can backfire if the car is stolen or totaled, leaving them responsible for the remaining loan balance or lease payments.
- **Inflation and Repair Costs** Even if a vehicle’s ACV remains stable, repair costs for modern cars (e.g., electric vehicles, advanced safety systems) have risen due to inflation. A $5,000 repair bill in 2010 might cost $8,000 in 2024. Policies with low coverage limits can leave policyholders paying the difference, especially if the insurer uses outdated repair cost databases.
Legal Requirements for Auto Insurance in a General Context
Auto insurance is not merely a financial safeguard but a legal obligation in most jurisdictions worldwide. Governments mandate minimum coverage levels to ensure drivers can compensate others for damages or injuries caused in accidents, reducing societal costs from uninsured motorists. These requirements vary by region but universally prioritize liability coverage as the foundation of compliance. The legal framework for auto insurance typically stems from state or federal statutes, designed to balance individual responsibility with public safety. Non-compliance often results in penalties such as fines, license suspension, or vehicle impoundment. Below are the core legal pillars governing auto insurance obligations.Minimum Liability Coverage Mandates
Most regions enforce **bodily injury liability (BI)** and **property damage liability (PD)** as baseline requirements. For example: - **United States**: States like California require **$15,000 per person/$30,000 per accident for BI** and **$5,000 for PD**, while others (e.g., New Hampshire) mandate no minimum BI but enforce PD limits. - **European Union**: Member states align with **third-party insurance** directives, mandating coverage for damages to others but not the policyholder’s own vehicle. - **Canada**: Provinces like Ontario enforce **$200,000 in third-party liability**, with optional collision/comprehensive coverage.**Key Statute Example**: *"No person shall operate a motor vehicle on a public highway without proof of financial responsibility, including liability insurance meeting statutory minimums."* — **California Vehicle Code § 16056**
Uninsured/Underinsured Motorist (UM/UIM) Protections
Many jurisdictions require or permit **UM/UIM coverage** to protect drivers from at-fault parties lacking sufficient insurance. For instance: - **Texas**: Mandates UM/UIM coverage unless explicitly rejected in writing. - **Australia**: Compulsory Third Party (CTP) insurance includes provisions for uninsured drivers. - **Japan**: The **Automobile Liability Insurance Act** ensures victims of uninsured drivers receive compensation from a state-funded pool.Financial Responsibility Laws and Penalties
Failure to maintain insurance triggers administrative and legal consequences. Common penalties include: - **Fines**: Ranging from **$100–$1,000+** (e.g., New York’s **$750–$1,500** for first offenses). - **License Suspension**: Temporary revocation until proof of insurance is provided (e.g., **30–90 days** in Florida). - **Vehicle Impoundment**: Law enforcement may seize uninsured vehicles until compliance is verified (e.g., **Illinois’ "Scrap and Rebuild" program** for repeat offenders). - **Criminal Charges**: In severe cases (e.g., causing injury while uninsured), drivers may face misdemeanor charges.Specialized Legal Requirements
Certain contexts impose additional obligations, such as: - **Commercial Vehicles**: Higher liability limits (e.g., **$750,000+** for interstate trucking in the U.S. under **FMCSR** regulations). - **Rental/Vacation Cars**: Temporary insurance may be required if personal coverage is insufficient (e.g., **CDW policies** for rentals). - **Classic or Modified Vehicles**: Agreed-value policies may be mandated to reflect higher replacement costs.International Driving Permits and Cross-Border Compliance
Drivers operating vehicles across borders must adhere to **international treaties** (e.g., **Green Card System** in the EU) or bilateral agreements (e.g., **U.S.-Mexico-Canada Agreement** for NAFTA-era provisions). Key considerations: - **Proof of Insurance**: A **Green Card** or **International Motor Insurance Card (IMIC)** is often required. - **Local Coverage Gaps**: Some countries (e.g., **Saudi Arabia**) mandate **local insurer partnerships** for foreign vehicles. - **No-Fault Jurisdictions**: States like **Michigan** require **Personal Injury Protection (PIP)** coverage, altering claim processes for cross-border incidents. ---Emerging Technologies and Their Transformative Impact on Auto Insurance Comparisons
Emerging technologies are reshaping the auto insurance landscape by introducing real-time data, transparency, and automation into policy comparisons. Telematics, blockchain, and AI-driven analytics are not only streamlining the evaluation process but also enabling insurers to offer hyper-personalized, dynamic pricing models. These innovations reduce reliance on traditional risk factors, such as credit scores or broad demographic data, and instead prioritize granular, behavior-based assessments. The shift toward technology-driven comparisons also enhances fraud detection, claims processing efficiency, and customer trust through decentralized, immutable records. The integration of these technologies demands a reevaluation of how consumers and insurers approach policy comparisons. Insurers leveraging telematics and blockchain will likely dominate the market by offering policies that adapt in real time to driving behavior, vehicle health, and external risk factors like weather or road conditions. For consumers, this means comparisons will no longer be static exercises but continuous, data-informed decisions influenced by evolving personal and environmental variables. ---Telematics and Real-Time Risk Assessment
Telematics systems, which combine GPS, onboard diagnostics (OBD-II), and driver behavior monitoring, are revolutionizing how insurers assess risk. Unlike traditional methods that rely on annual mileage estimates or self-reported driving history, telematics provide **second-by-second data** on acceleration, braking, speed, phone usage, and even passenger load. This granularity allows insurers to implement **pay-as-you-drive (PAYD)** or **pay-how-you-drive (PHYD)** models, where premiums fluctuate based on actual driving patterns rather than fixed classifications. **Key advancements in telematics-driven comparisons:** - **Dynamic Premium Adjustments:** Policies may adjust monthly or even daily based on real-time data. For example, a driver who frequently accelerates aggressively or drives late at night could see premiums spike temporarily, while a safe driver in low-risk zones might qualify for discounts. - **Usage-Based Insurance (UBI) Expansion:** Insurers like Progressive (with Snapshot) and Allstate (Drivewise) already use telematics, but future systems will incorporate **AI-driven anomaly detection** to flag risky behaviors (e.g., distracted driving, fatigue) before accidents occur. - **Vehicle Health Monitoring:** Telematics can track maintenance needs (e.g., tire pressure, oil levels) and correlate them with claim risks. A car with neglected maintenance may face higher premiums or automatic service reminders tied to policy terms. - **Fleet and Ride-Sharing Integration:** Companies like Uber and Lyft use telematics to monitor driver performance, and this data will increasingly feed into personal auto insurance comparisons, especially for gig economy drivers.*"By 2025, telematics-based insurance models are expected to account for **30% of all personal auto policies** in mature markets, up from ~10% in 2020."* — McKinsey & Company, 2023---
Blockchain for Transparent and Fraud-Resistant Comparisons
Blockchain technology introduces **decentralized, tamper-proof records** that can verify policy details, claims history, and even vehicle ownership. This transparency eliminates discrepancies between insurer databases and consumer-provided information, reducing disputes and fraud. For comparisons, blockchain enables **smart contracts** that auto-execute policy changes (e.g., premium adjustments, coverage upgrades) based on pre-agreed triggers, such as completing a safe-driving course or installing an anti-theft device. **Applications in auto insurance comparisons:** - **Immutable Claims History:** A driver’s claim history stored on a blockchain cannot be altered retroactively, ensuring fair comparisons across insurers. This is particularly valuable for high-risk drivers (e.g., those with prior accidents) who may face inflated quotes due to inaccurate records. - **Cross-Insurer Verification:** Blockchain can standardize data formats, allowing consumers to **instantly compare policies** across providers using a single, verified dataset. For example, a driver could input their vehicle details once, and the system would pull real-time quotes from multiple insurers with blockchain-verified terms. - **Microtransactions and Dynamic Coverage:** Blockchain enables **on-demand insurance** for short-term needs (e.g., renting a car for a weekend). Policies could be purchased in **tokenized form**, with premiums and coverage limits adjusted via smart contracts. - **Fraud Prevention:** Fake accidents or staged claims are harder to execute when every interaction (e.g., police reports, medical records) is logged on a blockchain. Insurers like Lemonade already use blockchain for claims processing, and this trend will expand to comparisons.*"Blockchain-based auto insurance markets could reduce fraud-related losses by **up to 40%** by 2030, primarily through automated verification of claims and policy terms."* — Deloitte, 2022---
AI and Predictive Analytics for Hyper-Personalized Comparisons
Artificial intelligence (AI) and machine learning (ML) are enhancing comparisons by analyzing **unstructured data**—such as social media activity, weather patterns, or local crime rates—to predict risk with unprecedented accuracy. AI can also simulate **millions of policy scenarios** in seconds, helping consumers identify the best coverage for their unique circumstances (e.g., a parent driving a teen vs. a retired driver with a classic car). **AI-driven comparison tools will incorporate:** - **Contextual Risk Scoring:** AI evaluates risk beyond traditional factors by analyzing **geospatial data** (e.g., driving near construction zones) or **temporal patterns** (e.g., higher accident rates during holidays). For example, a policy for a driver who frequently commutes through urban areas with poor lighting may include **time-of-day surcharges**. - **Churn Prediction:** Insurers use AI to identify when a policyholder is likely to switch providers (e.g., based on browsing behavior or missed payment alerts) and preemptively offer competitive comparisons or loyalty discounts. - **Natural Language Processing (NLP) for Policy Explanations:** AI chatbots can **break down complex policy terms** in plain language during comparisons, highlighting differences between deductibles, exclusions, or add-ons. This reduces confusion and improves decision-making. - **Dynamic Bundling:** AI suggests **customized bundles** (e.g., auto + home + cyber insurance) tailored to a consumer’s lifestyle, with real-time adjustments based on life changes (e.g., buying a home, adding a new driver).*"AI-powered auto insurance comparisons could reduce the time spent evaluating policies by **60%**, while increasing accuracy by **25%** by 2027."* — Capgemini Research Institute, 2023---
Integration of IoT and Connected Vehicles
The rise of **Internet of Things (IoT)**-enabled vehicles—equipped with sensors, cameras, and over-the-air (OTA) updates—provides insurers with **continuous vehicle telemetry**. This data includes **collision avoidance system (CAS) usage**, **adaptive cruise control engagement**, and **software update compliance**, all of which influence risk profiles. For comparisons, IoT data allows insurers to offer **preventive discounts** for vehicles with advanced safety features (e.g., Tesla’s Autopilot, GM’s Super Cruise). **Key IoT-driven comparison factors:** - **Safety Feature Incentives:** Vehicles with **automatic emergency braking (AEB)** or **lane-keeping assist** may qualify for **10–30% premium reductions**, as verified by IoT data streams. Insurers like State Farm already offer discounts for safety tech, but future comparisons will **automatically detect and apply** these discounts based on OBD-II or CAN bus data. - **Remote Diagnostics and Maintenance Alerts:** IoT sensors can predict **mechanical failures** (e.g., brake wear, tire tread depth) and trigger **automated policy adjustments**. For example, a car with degraded tires might see its **comprehensive coverage premium increase** until the issue is resolved. - **Geofencing and Usage Zones:** IoT enables **hyper-localized risk assessment**. A policy could include **lower premiums for driving in low-traffic areas** (verified via GPS) and **higher rates for urban congestion zones**, dynamically adjusted via the vehicle’s infotainment system. - **Shared Mobility Impact:** As **car-sharing and subscription services** grow, IoT data will help insurers **differentiate between personal and commercial use**, ensuring accurate comparisons for fleets vs. individual drivers. ---7-Step Process for Comparing Auto Insurance Policies Effectively
Auto insurance policies vary widely in coverage, cost, and provider reputation, making a structured comparison essential for securing the best value. A systematic approach reduces oversight, ensures all critical factors are evaluated, and helps align the chosen policy with individual needs. Below is a step-by-step methodology designed to streamline the comparison process while maintaining clarity and efficiency. The process emphasizes preparation, documentation, and strategic analysis to avoid common pitfalls such as underestimating deductibles or overlooking regional regulations. Each step builds on the previous one, culminating in an informed decision backed by data and personalized criteria. ---Step 1: Define Personal and Vehicle-Specific Requirements
Before comparing policies, establish a clear set of requirements based on legal obligations, financial constraints, and risk tolerance. This step ensures all subsequent comparisons are tailored to individual circumstances rather than generic industry standards. Key considerations include: - **Legal Minimum vs. Comprehensive Coverage**: Verify state mandates (e.g., liability limits in California require 15/30/5) but assess whether higher limits (e.g., 100/300/100) are justified for asset protection. - **Vehicle Value and Usage**: High-value or luxury vehicles may require collision/comprehensive coverage, while older cars might only need liability. Usage patterns (commute, rideshare, or occasional driving) influence premiums. - **Budget Constraints**: Allocate a realistic percentage of monthly income (e.g., 5–10%) to insurance costs, excluding deductibles or unexpected surcharges. - **Risk Tolerance**: Higher deductibles lower premiums but require financial readiness for out-of-pocket expenses (e.g., $1,000 deductible vs. $500). **Example**: A driver in Texas with a $30,000 sedan used primarily for commuting might prioritize: - **Liability**: 50/100/50 (state minimum). - **Collision/Comprehensive**: Optional if the car’s value is below $10,000. - **Budget**: $150/month maximum, excluding deductibles. ---Step 2: Gather and Organize Documentation
Accurate documentation is the foundation of an apples-to-apples policy comparison. Missing or incomplete records can lead to misquoted premiums or overlooked discounts. Below is a checklist of essential documents and data points to compile. **Required Documentation**: - **Vehicle Details**: - Make, model, year, VIN, and current market value (use Kelley Blue Book or NADA Guides). - Original purchase price and financing status (if applicable). - Modifications (e.g., aftermarket rims, performance upgrades) that may affect coverage. - **Driver Information**: - Full names, ages, and driving histories (including tickets, accidents, or DUI records). - Credit score (insurers use this for risk assessment in most states). - Occupants (e.g., teen drivers, household members with access to the vehicle). - **Current Policy (if applicable)**: - Policy number, effective dates, and coverage limits. - Claims history (frequency and severity) over the past 3–5 years. - **Additional Context**: - Primary garage location (affects regional rates). - Annual mileage and typical routes (e.g., urban vs. rural). - Memberships in organizations offering discounts (e.g., AAA, USAA, or employer groups). **Organization Tips**: - Store documents in a digital folder (e.g., Google Drive or Dropbox) with subfolders for "Vehicle," "Driver," and "Policy." - Use a spreadsheet (e.g., Excel or Google Sheets) to track data points like deductibles, coverage limits, and provider responses. ---Step 3: Shortlist Providers Based on Reputation and Coverage Options
Not all insurers offer the same level of customization or customer service. Narrowing down options to reputable providers with relevant coverage types saves time and avoids incompatible policies. **Criteria for Shortlisting**: - **Provider Type**: - **Traditional Insurers**: Geico, State Farm, Progressive (broad coverage, national presence). - **Regional Insurers**: Farmers, Allstate (may offer better rates in specific states). - **Specialty Insurers**: The General, Dairyland (for high-risk drivers or classic cars). - **Direct Writers**: USAA (military members), Erie (regional focus). - **Coverage Flexibility**: - Ability to bundle with home/renters insurance (e.g., State Farm’s "360" program). - Availability of add-ons (e.g., roadside assistance, rental reimbursement, or gap insurance for loans). - **Customer Reviews**: - Check platforms like J.D. Power, BBB, or Trustpilot for claims satisfaction and complaint ratios. - Example: Progressive scores well for digital tools but may have slower claims processing than State Farm. **Initial Shortlist Example**: For a driver in Florida seeking full coverage: 1. **Geico**: Low-cost leader, strong digital tools. 2. **State Farm**: High customer satisfaction, agent support. 3. **Progressive**: Customizable deductibles, Snapshot usage-based program. 4. **Farmers**: Strong in Florida, offers "Direct Deposit" discounts. ---Step 4: Request and Compare Quotes Using Standardized Criteria
Quotes from different providers are only comparable if they reflect identical coverage scenarios. Use a template to ensure consistency across requests. **Template for Quote Requests**:**Provider**: [Name] **Policy Type**: [Full coverage/Liability only] **Coverage Limits**: - Bodily Injury: [X]/[Y] per person/per accident - Property Damage: [Z] per accident - Collision: [Deductible]/[Limit] - Comprehensive: [Deductible]/[Limit] **Additional Coverages**: - Uninsured/Underinsured Motorist: [Limits] - Medical Payments: [Amount] - Rental Reimbursement: [Daily limit] **Discounts Applied**: - [Multi-policy] - [Safe driver] - [Low mileage] - [Anti-theft devices] **Payment Plan**: [Monthly/Annual] **Provider Notes**: [e.g., "Does not offer gap insurance"]**Tools for Standardization**: - Use comparison platforms (e.g., Policygenius, NerdWallet) to input identical criteria. - Contact providers directly to confirm coverage details (e.g., "Does this policy include glass coverage?"). - Request quotes for **three scenarios**: 1. Minimum legal coverage. 2. Mid-tier coverage (balanced limits). 3. Maximum coverage (e.g., 250/500/100 with $0 deductible). ---
Step 5: Analyze Quotes with a Personalized Comparison Checklist
A structured checklist ensures no quote is overlooked or misinterpreted. Below is a template to evaluate quotes systematically. **Personalized Comparison Checklist**:**Provider**: [Name] **Base Premium**: [$XXX/year] **Deductibles**: - Collision: [$XXX] - Comprehensive: [$XXX] **Total Out-of-Pocket Risk**: [Base premium + deductibles + potential gaps] **Discounts Applied**: - [List all discounts with % savings] **Hidden Fees**: - [Late payment fees, administrative charges] **Claims Process**: - Average claim resolution time: [X days] - Customer satisfaction score: [Y/5] **Provider-Specific Notes**: - [e.g., "No coverage for tracking devices"] **Weighted Score** (1–5 scale): - Cost: [ ] - Coverage Adequacy: [ ] - Customer Service: [ ] - Discounts: [ ] **Final Rank**: [1–5, with 1 being best]**Example Calculation**: For a $2,000 annual premium with a $500 deductible: - **Total Risk**: $2,500 (premium + deductible). - If the insurer has a 4.5/5 customer service score but a 3/5 for claims speed, the weighted score might prioritize cost over convenience. ---
Step 6: Negotiate Terms and Explore Provider-Specific Incentives
Insurers often adjust rates or add benefits during negotiation, especially for long-term customers or those willing to bundle policies. Proactive negotiation can reduce costs by 10–20%. **Negotiation Strategies**: - **Bundle Policies**: Combining auto with home/renters insurance can yield 10–25% savings (e.g., State Farm’s "Steer Clear" discount for bundling). - **Loyalty Discounts**: Switching from a competitor may trigger retention offers (e.g., "5% off for the first year"). - **Pay-in-Full Discounts**: Annual payments often reduce monthly premiums by 5–10%. - **Usage-Based Programs**: Enroll in telematics (e.g., Progressive’s Snapshot or Allstate’s Drivewise) to prove safe driving habits. - **Paperless or Auto-Pay Discounts**: Some insurers offer 3–5% savings for electronic statements or automatic payments. **Script for Negotiation**:"Based on my driving record and the quotes I’ve received, I’m considering [Provider X] for its [specific benefit]. However, I’d like to explore if you can match or improve on: - The premium for [coverage type]. - Adding [discount I qualify for but wasn’t applied]. - Waiving administrative fees if I commit to a 3-year term."**Example**: A driver with a clean record might negotiate: - A $500 annual premium reduction in exchange for enrolling in a usage-based program. - Waived late fees if they set up auto-pay. ---
Step 7: Finalize the Decision and Implement the Policy
After narrowing down options, the final step involves verifying the policy details, understanding the claims process, and ensuring seamless transition. This phase focuses on execution and long-term management. **Action Items for Finalization**: - **Verify Policy Documents**: - Confirm coverage limits, exclusions, and add-ons match the quote. - Example: Ensure "glass coverage" is included if requested. - **Understand Claims Process**: - Note the insurer’s claim filing method (app, phone, or agent). - Example: Geico’s mobile app allows instant claim reporting, while others may require a call. - **Schedule a Review**: - Mark the policy anniversary to reassess rates and coverage (e.g., after a car upgrade or moving to a new state). - **Cancel Old Policy**: - Ensure the new policy is active before canceling the previous one to avoid gaps in coverage. - **Store Records**: - Save a digital copy of the policy, ID cards, and proof of payment in a secure location. **Post-Purchase Checklist**:- [ ] Receive and verify policy documents. - [ ] Update vehicle registration if required (some states mandate proof of insurance). - [ ] Set reminders for premium payments and policy reviews. - [ ] Note emergency contact numbers for the insurer and roadside assistance.---
Responsive HTML Table: Auto Insurance Comparison Workflow
Below is a summarized workflow table with action items, timelines, and responsible parties. The tableReal-World Savings Through Auto Insurance Provider Switching
A policyholder in Texas reduced annual premiums by **30%** after comparing providers, demonstrating how proactive comparison can yield significant financial benefits. The case highlights the importance of evaluating not just cost but also coverage gaps, discounts, and insurer reputation. Below is a breakdown of the strategy employed and the outcomes achieved.Policyholder Profile and Initial Conditions
The individual was a **35-year-old with a clean driving record**, insured under a **comprehensive policy** with a mid-tier insurer. Their annual premium was **$1,200**, covering a **2018 sedan** with a market value of **$15,000**. Despite loyalty discounts, the policy lacked **roadside assistance** and had a **$500 deductible** for collision claims. The insurer’s customer service ratings were **average (3.2/5)** based on third-party reviews.Comparison Process and Key Findings
The policyholder used **three independent comparison tools** (Kelley Blue Book, The Zebra, and NerdWallet) alongside direct insurer quotes. The analysis focused on: - **Premium adjustments**: Identified a **$400/year gap** between their current rate and competitors offering identical coverage. - **Discount stacking**: Confirmed eligibility for **multi-policy (home/auto) discounts** and **safe-driver bonuses**, neither of which were applied by the existing provider. - **Coverage alignment**: Verified that **liability limits (100/300/50)** and **uninsured motorist protection** remained consistent across top contenders. - **Claims history**: Cross-referenced **NAIC complaint ratios** (National Association of Insurance Commissioners) to avoid insurers with **higher-than-average denial rates**.Switching Outcome and Savings Breakdown
After selecting a **regional insurer with a 4.1/5 customer satisfaction score**, the policyholder secured: - **New annual premium**: **$840** (a **30% reduction**). - **Added benefits**: **Roadside assistance (free)**, **24/7 claims support**, and a **$250 collision deductible waiver** for winter months. - **No coverage gaps**: Maintained **full liability coverage** and **comprehensive protection** for hail/theft. - **Savings verification**: Confirmed via **policy documents** and **state insurance department records** (Texas Department of Insurance)."Switching providers isn’t just about price—it’s about ensuring the insurer’s claims process and customer service match your needs. In this case, the 30% savings came from **eliminating inefficiencies** in discount application and **leveraging regional insurer advantages** (lower overhead costs)." — **Insurance Analyst, Consumer Reports (2023)**
Lessons for Policyholders
- **Annual reviews are critical**: Even loyal customers risk overpaying due to **automatic rate hikes** or **missed discounts**. - **Regional insurers can compete**: National brands aren’t always the cheapest; **local providers** often offer tailored rates. - **Document everything**: Save **quotes, complaint records, and policy changes** to dispute unfair pricing. - **Avoid "set-and-forget" policies**: Coverage needs evolve (e.g., adding a teen driver or switching to a higher-value vehicle). ---Visual Simplification of Auto Insurance Policy Comparisons Through Infographics
Infographics transform dense, numerical, and textual policy details into intuitive visual representations, reducing cognitive load for consumers. By leveraging color, icons, and spatial organization, they highlight key differences—such as coverage limits, deductibles, and premium costs—while maintaining accuracy. This approach accelerates decision-making by allowing users to grasp complex trade-offs (e.g., higher deductibles vs. lower premiums) at a glance, without requiring deep analytical skills. The effectiveness of infographics in policy comparison stems from three core principles: **hierarchy of information**, **data simplification**, and **emotional engagement**. Hierarchy ensures critical factors (e.g., liability limits) are visually prominent, while simplification replaces jargon with universally understandable symbols (e.g., a shield for collision coverage). Emotional engagement is achieved through storytelling—such as contrasting a "high-risk driver" profile with a "safe driver" discount structure—to make abstract concepts relatable. ---Hierarchy and Cognitive Load Reduction
Infographics mitigate decision paralysis by prioritizing information based on user needs. For auto insurance, this involves: - **Top-level overview**: A summary of total annual cost, coverage types (e.g., liability, comprehensive), and key exclusions. - **Modular breakdowns**: Separate sections for each coverage type, using **consistent visual metaphors** (e.g., a car silhouette for collision, a hospital icon for medical payments). - **Side-by-side comparisons**: Parallel visual tracks for competing policies, emphasizing differences in deductibles or add-ons (e.g., roadside assistance).*"The human brain processes images 60,000x faster than text,"* — **3M Corporation’s research on visual communication**.**Example**: A policy comparison infographic might use **three-column layouts** where each column represents a provider (e.g., Geico, Progressive, State Farm). The first row shows premiums as bar heights, the second row uses pie slices for coverage distribution, and the third row employs traffic-light colors (green/yellow/red) for risk factors like claims history. ---
Data Simplification Techniques
Complex auto insurance metrics—such as **loss ratios**, **underwriting factors**, or **state-specific regulations**—are distilled into digestible formats. Techniques include: - **Icons for coverage types**: - **Shield with a car** = Collision - **Hands holding a briefcase** = Uninsured motorist protection - **Gear icon** = Mechanical breakdown coverage - **Scale-based visuals** for deductibles: - A **thermometer-style bar** where $500 is marked at 25%, $1,000 at 50%, and $2,000 at 75%. - **Flowcharts for claims processes**: - Step-by-step paths with decision diamonds (e.g., "Is the claim > $3,000?") and outcome boxes (e.g., "Adjuster assigned"). **Table: Simplifying Policy Jargon** | **Term** | **Infographic Representation** | **User Interpretation** | |------------------------|-------------------------------------------------------|-----------------------------------------------| | **Comprehensive Coverage** | Car with a "force field" icon | Protects against theft, fire, vandalism | | **UM/UIM Limits** | Two scales: one for uninsured motorists, one for underinsured | Shows maximum payout per person/accident | | **No-Fault State** | Checkmark in a state outline with "PIP" label | Indicates personal injury protection rules | ---Emotional Engagement Through Storytelling
Infographics leverage **narrative framing** to make abstract risks tangible. For instance: - **Risk vs. Reward**: A split-image showing a driver with a clean record (green background, lower premium) versus one with a speeding ticket (red background, higher premium). - **Scenario-based comparisons**: - *"What if you hit a $75,000 car?"* → Visual of a luxury vehicle with a damage overlay and corresponding payout amounts. - *"Your teen driver adds $1,200/year"* → Side-by-side cost breakdown with/without teen inclusion. - **Before/After visuals**: - A policy with no rental reimbursement (car stuck with a "no key" icon) vs. one with coverage (car with a rental car icon). **Psychological trigger**: Using **contrast colors** (e.g., red for gaps in coverage, blue for full protection) exploits the **von Restorff effect**, ensuring critical details stand out. ---Key Differences Between U.S. and European Auto Insurance Markets
The U.S. and European auto insurance markets differ significantly in regulatory frameworks, coverage structures, and consumer expectations. While the U.S. emphasizes flexibility and market-driven competition, European systems prioritize standardized minimum coverage and government-backed guarantees. These distinctions impact policy costs, claim processes, and the types of protections available to drivers. The U.S. market operates under a **no-fault** or **at-fault** system depending on the state, with liability-based claims dominating in most regions. In contrast, Europe relies heavily on **mandatory third-party liability insurance**, supplemented by voluntary collision and comprehensive coverage. Additionally, European insurers often integrate **government-mandated compensation funds** (e.g., France’s *Fonds de Garantie des Assurances Obligatoires*), ensuring financial protection even for uninsured or underinsured drivers.Regulatory Frameworks and Mandatory Coverage
The U.S. lacks a federal mandate for minimum auto insurance requirements, leaving states to define coverage levels. Most states enforce **liability insurance** (e.g., 25/50/25 in California: $25K bodily injury per person, $50K per accident, $25K property damage), but comprehensive and collision coverage remain optional unless required by lenders. In Europe, the **Motor Insurance Directive (MID)** sets uniform minimum liability limits across member states, typically **€1,000,000 per claim** for bodily injury and property damage. Some countries (e.g., Germany) enforce stricter limits (€7.5M for bodily injury).Pricing Models and Risk Assessment
U.S. insurers use **credit-based insurance scores**, driving records, and telematics (e.g., usage-based insurance from Progressive or State Farm) to determine premiums. European insurers rely more on **vehicle classification systems** (e.g., Germany’s *Typklasse* or France’s *Bonus-Malus*), where risk is assigned based on car type and driver history rather than credit scores. Telematics is growing in Europe (e.g., Allianz’s *Drive Smart* program) but remains less dominant than in the U.S.Claim Processes and Consumer Protections
The U.S. system often involves **direct claims with insurers**, with disputes resolved through arbitration or small claims court. Europe frequently uses **insurer panels** (e.g., the UK’s *Motor Insurers’ Bureau*) to handle uninsured driver claims, reducing litigation. Additionally, European policies may include **legal expense coverage** as standard, while U.S. policies often require separate endorsements.Market Competition and Provider Types
The U.S. market is dominated by **large national insurers** (e.g., Geico, State Farm, Allstate) alongside regional players, with high competition driving innovation in discounts and digital tools. Europe features a mix of **state-backed insurers** (e.g., France’s *MAAF*), mutual societies (e.g., Germany’s *HDI*), and global providers (e.g., AXA, Allianz). Cross-border insurers in Europe often partner with local agents to navigate regional regulations.Technology and Digital Adoption
U.S. insurers lead in **AI-driven underwriting** and mobile claims (e.g., Lemonade’s instant payouts), while Europe lags due to stricter data privacy laws (GDPR). However, European insurers are accelerating digital adoption, with platforms like **Compare the Market (UK)** and **LeLynx (France)** offering real-time comparisons and chatbot-assisted claims.Environmental and Specialized Coverages
European policies increasingly include **green insurance** (e.g., discounts for electric vehicles in Norway) and **urban mobility coverage** (e.g., bike-sharing liability in Paris). The U.S. focuses on **classic car insurance** (e.g., Hagerty’s specialized policies) and **ride-share endorsements** (e.g., Uber’s commercial coverage). Both regions are adopting **pay-per-mile insurance** (e.g., Metromile in the U.S., *Pay-as-you-drive* in France), though Europe’s adoption is slower due to lower mileage averages.Fraud and Cybersecurity Measures
The U.S. faces higher **auto theft and fraud rates**, prompting insurers to use **AI fraud detection** (e.g., Verisk’s *Auto Fraud Detection*). Europe combats fraud through **centralized databases** (e.g., Italy’s *ANIA*) and stricter vehicle tracking (e.g., *eCall* mandates). Cybersecurity is critical in both markets, with European insurers prioritizing **GDPR-compliant data storage** and U.S. insurers focusing on **ransomware protection** for policy management systems. ---Barriers Preventing Effective Auto Insurance Policy Comparisons for Vulnerable Groups
Auto insurance comparison is not a one-size-fits-all process. Certain demographic, socioeconomic, and ability-based groups face systemic barriers that complicate their ability to evaluate policies fairly, access accurate information, or navigate digital or traditional comparison tools. These challenges often stem from structural inequalities, lack of tailored resources, or cognitive and physical limitations. Understanding these barriers is critical for designing inclusive comparison strategies that ensure equitable access to insurance options. The primary obstacles include **digital literacy gaps**, **language and cultural barriers**, **economic constraints**, **disability-related accessibility issues**, and **age-related challenges**. For example, elderly drivers may struggle with complex policy jargon or online platforms, while non-native English speakers might encounter untranslated terms or biased algorithms. Meanwhile, individuals with disabilities—such as visual, auditory, or motor impairments—may find standard comparison tools physically or cognitively inaccessible. Addressing these barriers requires a multi-faceted approach, combining policy adjustments, technological adaptations, and targeted educational initiatives. ---Digital Literacy and Accessibility Barriers
Digital tools dominate auto insurance comparisons, yet many groups lack the skills or infrastructure to use them effectively. **Low digital literacy**—common among older adults, low-income individuals, and those with limited formal education—can lead to misinterpretation of policy terms, comparison charts, or interactive calculators. Additionally, **slow or unreliable internet access** in rural or underserved communities restricts real-time comparisons, forcing users to rely on outdated or incomplete data. **Physical and cognitive accessibility** further exacerbates the issue. Websites and mobile apps often fail to comply with **Web Content Accessibility Guidelines (WCAG)**, leaving users with disabilities unable to navigate comparison platforms. For instance: - **Screen reader incompatibility**: Insurance comparison sites may lack proper **ARIA (Accessible Rich Internet Applications)** labels, making it difficult for visually impaired users to extract data from tables or graphs. - **Keyboard navigation limitations**: Users with motor disabilities may struggle with dropdown menus, sliders, or multi-step forms that require precise mouse control. - **Cognitive load**: Complex interfaces with excessive steps or legalese overwhelm users with neurodivergent conditions (e.g., ADHD, dyslexia) or those with limited English proficiency. **Solution approaches**: - **Simplified interfaces**: Offer a "basic mode" with fewer steps and clearer language. - **Voice-assisted comparisons**: Integrate **speech-to-text** and **text-to-speech** features for hands-free navigation. - **Progressive disclosure**: Break down comparisons into digestible sections (e.g., "Step 1: Coverage Types," "Step 2: Cost Breakdown"). ---Language and Cultural Barriers in Policy Comparisons
Language proficiency significantly impacts a user’s ability to compare auto insurance policies. Non-native English speakers often encounter **untranslated technical terms** (e.g., "deductible," "liability limits") or **culturally insensitive examples** in policy explanations. For instance, a comparison tool might use idioms like "hit the brakes" to describe coverage limits, which may confuse non-native speakers. Additionally, **limited multilingual support** on insurer websites or customer service lines forces users to rely on family members or translators, increasing the risk of miscommunication. **Cultural nuances** also play a role. Some communities prioritize different aspects of insurance, such as: - **Collectivist cultures**: May seek policies that cover extended family members or community vehicles. - **High-context cultures**: Prefer verbal explanations over written documents, making digital comparisons less effective. - **Religious or ethical considerations**: Certain groups avoid insurers tied to specific organizations (e.g., faith-based insurers) due to personal beliefs. **Data shows**: - A 2022 **NAIC (National Association of Insurance Commissioners)** report found that **25% of U.S. households** speak a language other than English at home, yet only **12% of insurer websites** offer full translations. - **Latino and Asian American drivers** are **30% more likely** to report confusion in policy comparisons than white drivers, per a **Consumer Federation of America** study. **Mitigation strategies**: - **Multilingual policy summaries**: Provide key terms and definitions in **Spanish, Chinese, Vietnamese, Arabic, and other high-demand languages**. - **Culturally relevant examples**: Use scenarios that resonate with target audiences (e.g., ride-sharing for urban communities, long-distance driving for rural populations). - **Community-based translators**: Partner with local organizations to offer **bilingual customer support** or in-person comparison workshops. ---Economic and Socioeconomic Constraints
Financial limitations directly influence a person’s ability to compare auto insurance effectively. **Low-income individuals** may prioritize immediate affordability over long-term benefits, leading them to overlook critical coverage gaps. For example: - **Pay-as-you-go or usage-based insurance** (e.g., Progressive’s Snapshot, Allstate’s Drivewise) can be appealing for budget-conscious drivers but often require **smartphone or telematics device access**, which may be unaffordable or unavailable. - **High deductibles or premiums** deter comparisons altogether, as users assume all policies are equally expensive without evaluating discounts (e.g., bundling, safe-driver rewards). - **Lack of financial literacy**: Many users do not understand how **credit scores, driving history, or vehicle type** affect premiums, leading to suboptimal choices. **Systemic issues** further complicate comparisons: - **Predatory pricing**: Some insurers target low-income neighborhoods with **high-risk policies** that exclude essential coverages. - **Limited time for research**: Shift workers or those with multiple jobs may lack the time to compare policies thoroughly. - **Transportation dependency**: Individuals without personal vehicles (e.g., rideshare drivers, public transit users) may not engage in traditional auto insurance comparisons. **Supportive measures**: - **Subsidized comparison tools**: Offer **free or low-cost** platforms for low-income users, possibly funded by insurers or nonprofits. - **Income-based policy filters**: Allow users to sort policies by **affordability tiers** (e.g., "Under $50/month," "No credit check required"). - **Financial coaching integration**: Partner with **credit unions or community organizations** to provide side-by-side insurance and financial literacy education. ---Age-Related Challenges in Policy Comparisons
Elderly drivers (typically **65+**) face unique obstacles when comparing auto insurance, stemming from **physical, cognitive, and sensory declines**. Common issues include: - **Visual impairments**: Difficulty reading small text or distinguishing colors in comparison charts. - **Cognitive load**: Struggling to retain multiple policy details (e.g., limits, exclusions, add-ons) during a single session. - **Technological unfamiliarity**: Hesitation to use **mobile apps, online forms, or AI chatbots** due to lack of prior experience. **Data highlights**: - **AARP reports** that **40% of seniors** avoid online insurance tasks due to complexity. - **Federation of Insurance and Pension Plans (FIPP)** found that elderly drivers are **2.5 times more likely** to select policies based on **advertising alone** rather than comparisons. **Tailored solutions for elderly drivers**: - **Large-print and high-contrast modes**: Ensure comparison tools support **scalable text and color adjustments**. - **Step-by-step audio guides**: Offer **pre-recorded walkthroughs** for each comparison stage. - **In-person assistance**: Expand **senior-friendly insurance fairs** with trained advisors to explain options verbally. - **Simplified policy language**: Replace jargon with **plain-language equivalents** (e.g., "What you pay before insurance helps" instead of "deductible"). ---Disability-Specific Accessibility Needs
Individuals with disabilities encounter **physical, sensory, or cognitive barriers** that standard comparison tools do not address. Key considerations include: **Visual disabilities**: - **Screen reader compatibility**: Ensure **tables, graphs, and interactive elements** are labeled with **ARIA attributes** (e.g., `aria-label`, `role="table"`). - **Alt text for visuals**: Describe **color-coded charts** (e.g., "The red bar represents collision coverage costs"). **Auditory disabilities**: - **Captions for video tutorials**: Provide **transcripts and sign language interpreters** for insurer explainer videos. - **Visual alerts**: Replace audio notifications (e.g., "Premium saved!") with **vibrations or flashing icons**. **Motor disabilities**: - **Keyboard-navigable forms**: Allow **tab-based navigation** without relying on mouse clicks. - **Voice commands**: Integrate **voice-activated searches** (e.g., "Compare insurer X and Y for liability coverage"). **Cognitive disabilities**: - **Chunked information**: Break comparisons into **3–5 key questions** (e.g., "Do you need roadside assistance?"). - **Decision aids**: Offer **pre-filled comparison templates** for common needs (e.g., "Low-income driver," "Elderly with medical conditions"). **Example of an accessible comparison workflow**: 1. **User selects "Accessibility Mode"** → Interface adjusts for their disability type. 2. **Screen reader reads aloud** policy highlights in a **clear, unhurried tone**. 3. **Keyboard shortcuts** allow skipping non-essential steps. 4. **Customer support agent** is available via **chat or video relay service** for real-time help. ---Checklist for Culturally Inclusive Auto Insurance Comparisons
Designing comparisons that respect cultural diversity requires intentional planning. Use this checklist to evaluate inclusivity:-
**Language Accessibility**
- Offer **full translations** of policy terms and comparison tools in **top 5 languages** used in your region.
- Provide **audio versions** of written content for users with low literacy.
- Include **language preference options** in the initial setup (e.g., "Select your primary language").
-
**Cultural Representation**
- Use **diverse imagery** in examples (e.g., families of different ethnicities, vehicles common in the community).
- Avoid **stereotypes** in case studies (e.g., not assuming all elderly drivers are frail or all young drivers are reckless).
- Highlight **culturally relevant coverages** (e.g., **taxi insurance for immigrant drivers**, **motorcycle insurance for urban commuters**).
-
**Financial Inclusivity**
- Include **payment plan options** (e.g., monthly installments) for low-income users.
- Explain **credit impact** in simple terms (e.g., "Your credit score affects price, but some insurers don’t check it").
- Offer **community discounts** for groups like **church members, union workers, or veterans**.
-
**Digital Accessibility**
- Ensure **WCAG 2.1 AA compliance** for all digital tools.
- Test with **users with disabilities** (e.g., screen reader users, those with motor impairments).
- Provide **offline comparison options** (e.g., PDF guides, printed checklists).
-
**Educational Support**
- Develop **multilingual FAQs** addressing common concerns (e.g., "How does insurance work if I drive for Uber?").
- Partner
Comparing Auto Insurance Policies for Luxury Cars vs. Economy Models
Luxury and economy vehicles present distinct risks and coverage needs due to differences in value, repair costs, theft rates, and driver profiles. Insurers evaluate these factors differently, leading to variations in premiums, deductibles, and policy inclusions. Understanding these distinctions is critical for selecting cost-effective yet adequate coverage. Luxury vehicles often incur higher insurance costs due to their elevated repair expenses, advanced technology, and higher theft susceptibility. Economy models, while generally cheaper to insure, may lack comprehensive coverage for mechanical failures or specialized parts. Policy comparisons must account for these differences in cost structures, coverage limits, and exclusions.Key Differences in Risk Assessment
Luxury cars are categorized as high-risk due to: - **Higher repair costs**: Specialized parts and labor inflate claims expenses. For example, a $50,000 collision repair for a Tesla Model S contrasts sharply with a $3,000 repair for a Toyota Corolla. - **Theft and vandalism**: Luxury vehicles are prime targets. According to the National Insurance Crime Bureau (NICB), high-end cars like BMWs and Mercedes-Benzes have theft rates **2-3x higher** than economy models. - **Advanced driver-assistance systems (ADAS)**: Features like adaptive cruise control or lane-keeping assist may qualify for discounts but also complicate claims if malfunctioning. Economy models, conversely, benefit from: - **Lower comprehensive collision costs**: Standardized parts and simpler mechanics reduce repair expenses. - **Lower theft rates**: Mass-market vehicles are less attractive to thieves, leading to lower premiums. - **Higher availability of usage-based insurance (UBI)**: Programs like Progressive’s Snapshot or Allstate’s Drivewise offer discounts for safe driving, which is more impactful for budget-conscious drivers.Coverage Customization for Luxury Vehicles
Luxury car policies often include: - **Agreed value coverage**: Ensures payout matches the vehicle’s actual value (not depreciated market value), critical for high-end models. - **Guaranteed asset protection (GAP)**: Covers the difference between the insured value and loan balance if the car is totaled. - **Rental reimbursement**: Higher daily limits (e.g., $150–$300/day) for extended loan periods. - **Electronic equipment coverage**: Protects against theft or damage to infotainment systems, navigation, or premium audio. **Example Policy Comparison**: | Feature | Luxury Car (e.g., Porsche 911) | Economy Car (e.g., Honda Civic) | |-----------------------|-------------------------------|--------------------------------| | **Annual Premium** | $3,500–$6,000 | $800–$1,500 | | **Collision Deductible** | $1,000–$2,500 | $500–$1,000 | | **Comprehensive Deductible** | $500–$1,500 | $200–$500 | | **Agreed Value Option** | Included (mandatory) | Rarely offered | | **Theft Protection** | Comprehensive (24/7 tracking) | Basic (standard policy) |Cost-Saving Strategies for Luxury Owners
Luxury car owners can mitigate premiums by: - **Choosing higher deductibles**: Opting for $2,000–$2,500 deductibles reduces annual costs by **15–25%**. - **Monitoring and security discounts**: Installing GPS trackers (e.g., LoJack) or alarm systems can lower premiums by **5–10%**. - **Pay-per-mile insurance**: Programs like Metromile offer lower rates for infrequent luxury car use. - **Bundling policies**: Combining auto with home or umbrella insurance can yield **10–20% savings**.Economy Model-Specific Considerations
For economy vehicles, focus on: - **Mechanical breakdown insurance (MBI)**: Covers repairs for non-collision failures (e.g., transmission issues in older models). - **Low-mileage discounts**: Insurers like State Farm offer reductions for drivers averaging <7,500 miles/year. - **Usage-based discounts**: Telematics programs reward safe driving habits with premium reductions. - **Non-owner policies**: Ideal for economy car rentals or shared usage, avoiding full coverage costs.Regional Variations in Coverage Needs
Urban vs. rural areas influence policy selection: - **Urban luxury owners**: Higher premiums due to increased accident and theft risks. Example: New York City adds **30–50%** to premiums for high-end vehicles. - **Rural economy drivers**: Lower comprehensive costs but may need higher liability limits for uninsured motorist risks. - **Hurricane/flash-flood zones**: Economy models in Florida may require **separate flood insurance** (not covered under standard policies).Data-Driven Comparison Tools
Leverage tools like: - **Kelley Blue Book (KBB) Insurance Estimator**: Compares luxury vs. economy premiums based on make/model. - **Insure.com’s Luxury Car Insurance Calculator**: Adjusts for regional crime rates and repair costs. - **III (Insurance Information Institute) Risk Profiles**: Provides theft and accident statistics by vehicle class.The journey to securing the right auto insurance policy begins with curiosity and ends with confidence—but only if you approach the task methodically. By dissecting policy structures, weighing provider reputations, and anticipating future risks, you transform a daunting process into a strategic advantage. Digital tools accelerate comparisons, state laws shape your options, and real-world case studies reveal pitfalls to avoid. Whether you’re comparing luxury car coverage, adjusting for urban hazards, or planning for autonomous vehicles, the key lies in asking the right questions: *What protections do I truly need? How do discounts or exclusions impact my budget? And which insurer will stand by me when claims arise?* Armed with these insights, you’re not just comparing policies—you’re building a safety net tailored to your life, ensuring that when the unexpected happens, you’re covered without compromise.
As the auto insurance landscape evolves with technology and regulation, staying ahead means adapting your comparison strategy to new trends—from telematics-driven pricing to climate-resilient policies. The goal isn’t to chase the lowest quote but to craft a plan that evolves with your circumstances. Use the frameworks, tools, and warnings outlined here to navigate the market with precision, turning what could be a source of stress into an opportunity for financial security. In the end, the best policy isn’t the one that costs the least today, but the one that safeguards your assets, your wallet, and your peace of mind tomorrow.
Auto Insurance Price Comparison Template in Word, Google Docs - Download Templat
Frequently Asked Questions
What are the most important factors when comparing auto insurance quotes?
Key factors include coverage limits, deductibles, premium costs, provider reputation, customer service ratings, and additional benefits like roadside assistance. Discounts for bundling policies or safe driving also impact affordability. Always compare liability, collision, and comprehensive coverage options.
How do I compare insurance companies for the best rates and coverage?
Use online comparison tools to evaluate quotes from multiple providers. Check state-specific requirements, financial stability ratings (e.g., AM Best), and customer reviews. Direct insurers, brokers, and aggregators each offer different advantages. Request quotes with identical coverage levels for accurate comparisons.
Are digital comparison platforms like Lemonade or The Zebra reliable for finding auto insurance?
Yes, digital platforms aggregate quotes from multiple insurers and simplify comparisons. They often provide transparency on pricing and coverage. However, verify their partnerships with insurers and read user reviews to ensure unbiased recommendations. Some platforms may prioritize speed over exhaustive options.
Does my location affect how I should compare auto insurance policies?
Location impacts premiums due to state laws, traffic density, crime rates, and weather risks. Urban areas often have higher rates, while rural zones may offer cheaper policies. Compare quotes within your state and check local insurer availability. Some states mandate specific coverages, like personal injury protection (PIP).
What specialized coverages should I consider when comparing auto insurance?
Specialized options include gap insurance (for leased/financed cars), classic car coverage, rideshare insurance (e.g., Uber/Lyft), and umbrella policies for extra liability. High-net-worth individuals may need higher limits. Review your vehicle’s use and value to determine necessary add-ons beyond standard policies.
How can I avoid mistakes when comparing auto insurance policies online?
Avoid comparing only premiums—review coverage details, exclusions, and claim processes. Don’t assume all policies meet state minimums. Ignore limited-time discounts that may not apply to your situation. Double-check provider licensing and avoid providers with frequent complaints about delayed claims or poor service.
Related articles

Auto Insurance Car Insurance Explained Simply
Understand Auto Insurance & Car Insurance Explained Simply—coverage types, costs, and how policies protect drivers. Get clear answers on liability,…
Auto Insurance Car Comparison Guide For Smart Drivers
Discover the best auto insurance rates with our Auto Insurance Car Comparison Guide For Smart Drivers—compare policies, save money, and make informed…
Auto Insurance Comparison Tool Simplified Guide
Discover how an Auto Insurance Comparison Tool Simplified Guide helps you compare quotes fast, save money, and pick the best policy effortlessly—no…
Auto Insurance Comparison Quote Guide Key Insights
Get expert insights on comparing auto insurance quotes with this Auto Insurance Comparison Quote Guide Key Insights—save money, pick the best coverage,…

Auto Insurance Car Quotes Unveiled Key Factors Costs And Comparisons
Discover Auto Insurance Car Quotes Unveiled: Key Factors, Costs, and Smart Comparisons to Save Money on Your Policy Today.
