Auto Insurance Price Compare Reveals Smart Savings Strategies
Table of Contents
- Core Concept of Comparing Auto Insurance Prices and Its Importance for Consumers
- Top 5 Factors Influencing Auto Insurance Pricing
- Online Quote Tools vs. Agent Consultations for Auto Insurance Price Assessment
- State-by-State Average Premium Differences for a Mid-Range Sedan, Highlighting Outliers
- Common Auto Insurance Discounts and Their Typical Savings Percentages
- Legal and Privacy Risks of Sharing Personal Data Across Multiple Insurers During Comparisons
- Reputable Sources for Validating Auto Insurance Pricing Data
- Step-by-Step Auto Insurance Price Comparison for a 30-Year-Old with a Clean Record Driving a Hybrid SUV in a High-Theft City
- Comparison of Auto Insurance Providers Using Key Financial Metrics
- Common Mistakes Consumers Make When Comparing Auto Insurance Quotes
- A/B Testing with Insurers to Secure Better Auto Insurance Rates
- Emerging Technologies Transforming Auto Insurance Price Comparison Dynamics
Finding the right auto insurance price doesn’t have to be a guessing game—it’s a strategic process where small adjustments in coverage, provider selection, or discount application can yield significant savings. With premiums varying by hundreds or even thousands of dollars for identical coverage, consumers who master price comparison techniques gain leverage to secure fairer rates while avoiding costly oversights. This guide breaks down the mechanics behind auto insurance pricing, from the hidden factors that inflate quotes to the tools and tactics that expose the best deals, ensuring you navigate comparisons with confidence and precision.
The journey begins with understanding why prices fluctuate—whether due to regional risk profiles, vehicle theft rates, or insurer algorithms that weigh credit scores differently across states. Traditional methods of comparison, like calling agents or visiting local offices, often miss the granularity of digital tools that parse thousands of variables in seconds. Yet even online quotes can be misleading if discounts aren’t applied consistently or if providers manipulate data to favor their own products. By dissecting the components of a premium—from liability limits to pay-per-mile programs—readers will learn how to standardize inputs, spot discrepancies, and leverage negotiation scripts to turn comparisons into tangible savings.
Core Concept of Comparing Auto Insurance Prices and Its Importance for Consumers
Auto insurance price comparison involves evaluating quotes from multiple providers to identify the most cost-effective and suitable coverage options. This process empowers consumers to make informed decisions, ensuring they pay a fair price while meeting their legal and financial protection needs. Without comparison, drivers risk overpaying for policies that may not align with their requirements or market standards. The importance of this practice lies in transparency and financial efficiency. Insurance premiums can vary significantly based on provider policies, risk assessments, and regional factors. A thorough comparison helps consumers avoid hidden fees, unnecessary coverage, or suboptimal deductibles. For example, a driver in a high-theft urban area may find that comprehensive coverage from one provider is significantly cheaper than another due to differences in claims processing or regional risk models.Consumers who compare auto insurance quotes save an average of 15–30% on annual premiums compared to those who renew without evaluating alternatives.Key benefits of price comparison include:
- Cost savings: Identifying the lowest premiums for equivalent coverage.
- Tailored coverage: Selecting policies that match specific needs (e.g., high-mileage drivers opting for pay-per-mile plans).
- Avoiding penalties: Ensuring compliance with state minimum requirements without overpaying.
- Long-term financial planning: Aligning insurance costs with budget constraints while maintaining adequate protection.
Factors Influencing Price Variations Across Providers
Auto insurance premiums are not standardized; they fluctuate based on a combination of provider-specific and consumer-specific variables. Understanding these factors allows consumers to anticipate discrepancies and negotiate better terms. Providers use proprietary algorithms, historical data, and regional trends to determine pricing, leading to variations even for identical driver profiles.Price variation formula: Premium = Base Rate + (Risk Factors × Provider Multiplier) – DiscountsProviders assess risk differently, often prioritizing certain attributes over others. For instance:
- Underwriting models: Some insurers penalize young drivers more heavily, while others offer lower rates for drivers with short commutes.
- Claims history: Providers in states with high fraud rates may adjust premiums upward for all customers.
- Coverage tiers: A provider offering limited liability coverage may charge less than one with full collision/comprehensive options.
- Geographic location: Urban areas with higher accident or theft rates typically incur higher premiums. Rural regions may offer lower rates but could lack comprehensive coverage options.
- Vehicle specifications: Luxury cars or models prone to theft (e.g., certain SUVs) attract higher premiums due to repair/replacement costs. Safety features like anti-lock brakes or adaptive cruise control may qualify for discounts.
- Driver demographics: Age, gender, and marital status influence pricing. For example, insurers may charge higher rates for single males under 25 due to statistically higher claim frequencies.
- Driving history: Traffic violations (e.g., DUIs, speeding tickets) or prior claims increase premiums. Some providers offer accident forgiveness programs to mitigate long-term penalties.
- Credit scores: In most states, insurers use credit-based insurance scores to predict risk. A lower score may result in higher premiums, though this practice is banned in states like California and Hawaii.
- Usage-based programs: Telematics (e.g., usage-based insurance) track driving behavior. Safe drivers may receive discounts of 5–30% through programs like pay-per-mile or mileage-based pricing.
- Provider profitability and market share: Larger insurers may offer competitive rates to retain customers, while smaller providers might charge premiums based on niche specializations (e.g., high-risk drivers).
Comparative Overview of Traditional vs. Digital Methods for Price Assessment
The method used to compare auto insurance prices significantly impacts accuracy, convenience, and the potential for savings. Traditional approaches rely on manual processes, while digital tools leverage automation and real-time data to streamline comparisons.Traditional methods rely on:Limitations of traditional methods:
- Agent consultations (in-person or phone).
- Paper-based quotes from multiple providers.
- Limited access to discounts or regional variations.
- Time-consuming: Requires scheduling appointments with agents or mailing request forms, delaying decision-making.
- Limited scope: Agents may prioritize policies from their own companies or affiliated providers, reducing objectivity.
- Static data: Quotes are based on outdated information (e.g., credit scores, vehicle values) unless manually updated.
- Human error: Miscommunication or oversight in transferring details (e.g., mileage, coverage limits) can lead to inaccurate quotes.
Digital methods offer:Advantages of digital tools:
- Instantaneous, multi-provider comparisons via online platforms or mobile apps.
- Dynamic data integration (e.g., real-time traffic patterns, vehicle recall alerts).
- Access to usage-based discounts and personalized recommendations.
- Speed and efficiency: Consumers receive quotes in minutes by inputting details once, eliminating repetitive data entry.
- Comprehensive coverage: Aggregator websites (e.g., comparison portals) pull quotes from dozens of providers, including regional and niche insurers.
- Transparency: Digital platforms display side-by-side comparisons of premiums, deductibles, and coverage limits, highlighting disparities.
- Customization: Tools like chatbots or AI-driven assistants adjust quotes based on real-time inputs (e.g., adding a teen driver or switching vehicles).
- Access to discounts: Digital methods often uncover provider-specific discounts (e.g., bundling home and auto insurance) that may not be offered through traditional channels.
- Agent-assisted digital tools: Consumers use online comparison platforms but consult an agent for complex scenarios (e.g., classic car insurance).
- Mobile apps with human support: Apps provide instant quotes but include live chat or callback options for clarification.
Typical Cost Components Requiring Comparison
Auto insurance premiums are composed of multiple elements, each contributing to the total cost. Consumers must evaluate these components individually to ensure they are paying for necessary protections without overpaying for redundant or unnecessary features.Core cost components: 1. Premium: The base price paid for coverage, billed annually, semi-annually, or monthly. 2. Deductible: The out-of-pocket amount paid before insurance covers a claim (e.g., $500 deductible for collision damage). 3. Coverage limits: Maximum payouts for bodily injury, property damage, or medical expenses (e.g., $100,000 per person for liability). 4. Additional fees: Administrative charges, late payment penalties, or fees for optional add-ons (e.g., roadside assistance).Key components to compare:
-
Premium structures:
- Annual vs. monthly payments: Monthly plans may include service fees (e.g., $3–$5 per month), increasing total costs.
- Discounts and credits: Providers offer varying discounts (e.g., safe driver, multi-policy, military service) that can reduce premiums by 10–50%.
- Loyalty programs: Some insurers reward long-term customers with premium reductions, while others penalize policyholders who switch frequently.
-
Deductible tiers:
- Higher deductibles lower premiums but increase financial risk in the event of a claim. For example, raising a $500 deductible to $1,000 might reduce annual premiums by 15–25%.
- Split deductibles: Some policies allow separate deductibles for collision and comprehensive coverage, offering flexibility.
-
Coverage types and limits:
- Liability coverage: Mandatory in most states, covering bodily injury and property damage to others. Limits are typically expressed as three numbers (e.g., 100/300/50), representing:
- $100,000 per person for bodily injury.
- $300,000 per accident for bodily injury.
- $50,000 for property damage.
- Collision coverage: Pays for damage to the policyholder’s vehicle in accidents, regardless of fault. Full coverage policies often bundle this with comprehensive coverage.
- Comprehensive coverage: Protects against non-collision events (e.g., theft, vandalism, natural disasters). Required for leased or financed vehicles.
- Optional coverages: Includes gap insurance (covers the difference between a car’s value and loan balance), rental reimbursement, or new car replacement.
-
State-specific requirements:
- Minimum coverage varies by state (e.g., New Hampshire has no mandatory auto insurance, while California requires higher liability limits).
- No-fault states: Some states (e.g., Michigan, Florida) require personal injury protection (PIP) coverage, increasing premiums.
-
Additional costs:
- Paperwork fees: Some providers charge for printed policy documents or certified copies.
- Lapse fees: Penalties for missed payments or policy cancellations.
- Usage-based surcharges: Fees for exceeding mileage limits in pay-per-mile programs.
Comparative Table of Major Auto Insurance Models
The choice of insurance model depends on individual needs, budget, and driving habits. Below is a structured comparison of three common models, including price ranges and ideal user profiles.Note: Price ranges are approximate and vary by location, provider, and driver profile. Actual costs should be verified through personalized quotes.
| Model | Description | Typical Price Range (Annual Premium) | Ideal User Profile | Key Features | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Full Coverage | Includes liability, collision, and comprehensive coverage. Required for financed or leased vehicles. | $1,200 – $3,500+ |
|
 Top 5 Factors Influencing Auto Insurance PricingAuto insurance premiums are determined by a combination of risk-based variables that insurers evaluate to assess the likelihood of a claim. These factors are categorized into demographic, behavioral, vehicle-related, and environmental attributes. Understanding these categories helps drivers anticipate how adjustments in their profiles may affect pricing. Insurers use actuarial models to weigh these factors, often prioritizing those with the highest correlation to claim frequency and severity. The five most significant categories include driver demographics, vehicle characteristics, geographic location, driving history, and coverage selection. Each category carries distinct weight depending on regional regulations and insurer policies. ---Driver DemographicsAge, gender, marital status, and occupation collectively influence risk assessment. Younger drivers (under 25) typically face higher premiums due to statistically higher accident rates, while older drivers (65+) may qualify for senior discounts. Gender-based pricing varies by state, with some regions applying higher rates for male drivers under 25 due to higher claim frequencies. Married individuals often receive lower premiums, as studies suggest they exhibit more cautious driving behavior. Occupation can also play a role, particularly for high-risk professions like commercial drivers or those with long commutes.Key Insight: A 20-year-old male driver in an urban area may pay 30-50% more than a 40-year-old female with the same vehicle and coverage limits.--- Vehicle Type and SpecificationsThe make, model, year, engine size, and body style of a vehicle directly impact insurance costs. Luxury or high-performance cars (e.g., Porsche, BMW) often incur higher premiums due to repair costs and theft risk. SUVs and trucks may face elevated rates if they are frequently involved in rollover accidents. Vehicle safety ratings, anti-theft features, and crash test scores can mitigate premiums, as insurers reward low-risk attributes. Additionally, the cost of parts and labor in a region affects pricing—for example, repairing a European car in a rural area may be cheaper than in a city with specialized mechanics.Example Metrics:--- Geographic Location and Environmental FactorsLocation is a primary determinant of auto insurance costs, influenced by traffic density, crime rates, weather conditions, and local laws. Urban areas with heavy traffic (e.g., Los Angeles, New York) often have higher premiums due to increased accident risks. Regions prone to severe weather (e.g., Florida for hurricanes, Texas for hailstorms) may see elevated rates for collision and comprehensive coverage. State regulations also play a role—no-fault states (e.g., Michigan) typically have higher premiums due to mandatory personal injury protection (PIP) coverage. Additionally, areas with high theft or vandalism rates (e.g., certain neighborhoods in Chicago) may increase comprehensive coverage costs.Regional Example:--- Driving History and Claim RecordsA driver’s history of accidents, traffic violations, and prior claims is one of the most critical factors in pricing. Insurers categorize drivers into risk tiers:
Coverage Limits and Policy SelectionThe extent of coverage—including liability limits, collision, comprehensive, uninsured motorist protection, and optional add-ons (e.g., roadside assistance, rental reimbursement)—directly impacts premiums. Higher liability limits (e.g., 100/300/100 vs. state minimum) increase costs but provide greater financial protection. Deductible amounts also play a role: opting for a higher deductible (e.g., $1,000 vs. $500) lowers monthly premiums but requires more out-of-pocket expenses in the event of a claim. Discounts for bundling (e.g., combining auto with homeowners insurance) or usage-based programs (e.g., telematics) can offset some of these costs.Coverage Trade-offs: Online Quote Tools vs. Agent Consultations for Auto Insurance Price AssessmentOnline quote tools and agent consultations serve as the two primary methods for evaluating auto insurance pricing, each offering distinct advantages and trade-offs. Online tools provide immediate, transparent comparisons with standardized inputs, while agent consultations deliver personalized insights and human support. Understanding these differences helps consumers choose the approach that aligns with their needs—whether prioritizing speed, customization, or trust. The choice between the two methods hinges on factors such as convenience, accessibility to specialized knowledge, and the ability to negotiate or clarify complex policy terms. Below is a structured comparison of their pros and cons, followed by guidance on when each method may be preferable.Advantages and Limitations of Online Quote ToolsOnline quote tools streamline the comparison process by aggregating data from multiple insurers in real time. They are ideal for consumers who value efficiency, transparency, and the ability to assess quotes independently. However, these tools may lack depth in explaining nuanced coverage options or addressing unique risk profiles.
Advantages and Limitations of Agent ConsultationsAgent consultations provide a human touch, offering expertise in navigating complex policies, identifying discounts, and resolving disputes. This method is particularly valuable for consumers with intricate needs or those who prefer guided decision-making. However, it may involve longer wait times, potential for bias, and higher costs due to commission structures.
When to Use Each MethodThe optimal approach depends on the consumer’s priorities and circumstances. Online tools are best suited for straightforward comparisons where transparency and speed are critical, such as evaluating basic liability coverage for a standard vehicle. Agent consultations shine when dealing with complex scenarios, including:
 State-by-State Average Premium Differences for a Mid-Range Sedan, Highlighting OutliersAuto insurance premiums vary significantly across states due to differences in traffic density, regulatory environments, and claims frequency. For a mid-range sedan (e.g., Toyota Camry) with full coverage (100/300/100 bodily injury/property damage limits, $500 deductible, and collision/comprehensive), premiums range from less than $800 annually in low-cost states to over $2,500 in high-cost regions. These disparities reflect regional risk profiles, legal frameworks, and insurer competition. The following analysis highlights state-specific averages and identifies outliers where premiums deviate sharply from national trends. Factors such as urbanization, weather-related risks, and state-mandated coverage minimums play pivotal roles in shaping these variations.Regional Premium Averages and Key OutliersPremiums for the same coverage tier exhibit a clear geographic pattern, with Midwestern states generally offering the lowest rates due to lower population density and fewer claims, while coastal and Northeastern states face higher costs from congestion, theft, and litigation risks. Below are the top 5 most and least expensive states for this sedan profile, based on 2023-2024 data:Note: Premiums are annual averages for a 40-year-old driver with a clean record, driving 12,000 miles/year.
Factors Driving Outliers in Premium CostsThree primary drivers explain the most extreme deviations from the national average (~$1,600):
Visualizing Premium Disparities: A Heatmap OverviewA hypothetical heatmap of the contiguous U.S. would show:
Example: A driver in rural Iowa ($1,200/year) pays half the premium of a driver in urban Miami ($2,500/year) for identical coverage, despite similar driving habits. Common Auto Insurance Discounts and Their Typical Savings PercentagesAuto insurance discounts reduce premiums by applying percentage-based reductions or tiered credits, often tied to driver behavior, policy bundling, or loyalty. Savings vary by insurer, location, and risk profile but typically range from 5% to 30% per eligible discount. Some discounts stack multiplicatively, while others are applied sequentially—understanding their structure helps maximize total savings. Below are the most frequently offered discounts, categorized by driver behavior, policy configuration, and external factors, along with their average savings ranges. ---Discounts Based on Driver BehaviorThese discounts reward low-risk driving habits or enrollment in monitoring programs. Insurers verify eligibility through claims history, telematics data, or defensive driving course certificates.
Discounts Based on Policy ConfigurationBundling policies or customizing coverage triggers automatic discounts, reducing administrative costs for insurers. Multi-policy discounts are among the most lucrative for households with multiple insurable assets.
Discounts Based on External FactorsThese discounts reflect demographic advantages, professional affiliations, or community involvement. Eligibility is often verified through third-party organizations or employer partnerships.
Discount Stacking Rules and LimitationsMost insurers allow stacking discounts, but the order of application and maximum combined savings vary. Some discounts are mutually exclusive (e.g., safe driver and defensive driving), while others cap total savings at 30%–50% of the base rate. Below are common stacking scenarios:
Note: Discounts are not guaranteed and may vary by state regulations, insurer underwriting guidelines, and individual risk profiles. Always request a personalized quote to confirm eligible savings. Legal and Privacy Risks of Sharing Personal Data Across Multiple Insurers During ComparisonsSharing personal data across multiple insurers during auto insurance price comparisons introduces significant legal and privacy risks for consumers. While comparison tools streamline the process of finding affordable coverage, they often require sensitive information—such as driving history, financial records, and location data—to generate quotes. This exchange raises concerns about unauthorized access, data breaches, and compliance with privacy regulations, which may vary by jurisdiction. The primary risks stem from data aggregation practices, where third-party platforms collect and store personal information without explicit consent or transparency. Insurers and comparison sites may not always disclose how long data is retained, how it is secured, or whether it is sold to third parties for marketing purposes. Additionally, cross-border data transfers—common in global comparison tools—can expose consumers to weaker privacy protections under foreign laws, increasing the likelihood of misuse.Regulatory Compliance and Jurisdictional VariationsAuto insurance data handling is governed by a patchwork of regulations, including the California Consumer Privacy Act (CCPA), General Data Protection Regulation (GDPR) in the European Union, and state-specific insurance laws in the U.S. Each framework imposes distinct obligations on insurers and comparison platforms regarding data collection, consent, and breach notification.Under GDPR, consumers have the right to access, correct, or delete their personal data, while CCPA grants similar rights but with narrower applicability. State laws in the U.S., such as those in Massachusetts and Vermont, further restrict how insurers can use telematics data (e.g., GPS tracking) without explicit consent.Failure to comply with these regulations can result in fines, lawsuits, or reputational damage. For example, in 2021, a major insurer faced a class-action lawsuit for allegedly sharing policyholder data with third-party vendors without proper disclosure. Consumers must verify whether the comparison tool adheres to local laws, particularly if their data is processed outside their home country. Data Breach and Unauthorized Access RisksThe centralized storage of personal data in comparison platforms creates a single point of failure. If a breach occurs—whether through hacking, insider threats, or accidental exposure—consumers may face identity theft, fraudulent claims, or unauthorized price discrimination. Historical breaches in the insurance sector highlight these risks:
Lack of Transparency in Data Sharing AgreementsMany comparison platforms operate under non-disclosure agreements (NDAs) with insurers, which often obscure how data is shared, stored, or monetized. Consumers may unknowingly consent to:
Reputable Sources for Validating Auto Insurance Pricing DataAccurate auto insurance pricing comparisons require validation from authoritative sources to ensure transparency and reliability. These sources provide benchmark data, regulatory oversight, and industry standards that help consumers and analysts cross-check quotes against market averages, regional trends, and compliance with insurance laws. Reputable organizations and databases offer structured datasets, reports, and tools to verify pricing consistency. Below are five key sources recognized for their credibility in auto insurance data validation.National Association of Insurance Commissioners (NAIC)The NAIC serves as the U.S. standard-setting and regulatory support organization for state insurance departments. Its databases, such as the NAIC Annual Statement Data, include financial filings from insurers, allowing users to compare premiums, loss ratios, and underwriting practices across providers. The NAIC Insurance Research Library also publishes studies on rate adequacy and consumer protection policies. Key resources:
State Insurance DepartmentsEach U.S. state maintains an insurance department responsible for licensing insurers, approving rates, and investigating consumer complaints. These departments publish rate filings, market conduct reports, and complaint ratios that directly impact pricing comparisons. Key resources:
Federal Insurance Office (FIO)
Part of the U.S. Treasury, the FIO monitors the insurance industry for systemic risks, including pricing fairness. Its Insurance Information Institute (III) Partnership and Market Conduct Reports provide macro-level insights into national pricing trends, such as the impact of natural disasters or economic shifts on premiums.
Key resources:
Regional Adjustments for High-Theft CitiesInsurers apply theft risk surcharges (10–25% on comprehensive coverage) in cities with high theft rates. For example:
Final Recommendation and CustomizationAfter comparing, Provider C offers the lowest premium ($2,130) when:
Comparison of Auto Insurance Providers Using Key Financial MetricsAuto insurance pricing varies significantly across providers based on base premiums, optional coverage costs, and available discounts. A structured comparison table allows consumers to evaluate insurers objectively by examining core financial components such as accident forgiveness, roadside assistance, and loyalty rewards. This table highlights differences in pricing strategies and helps identify cost-saving opportunities or hidden fees.HTML Table Structure for Insurer ComparisonBelow is a sample HTML table comparing six major insurers based on four key metrics: base annual premium, accident forgiveness add-on cost, roadside assistance fee, and loyalty discount percentage. Values are hypothetical but reflect realistic pricing tiers observed in the market.Example: A loyalty discount of 10% means a $1,200 base premium becomes $1,080 after 3 years of continuous coverage.`html
Interpreting the TableThe table reveals trade-offs between base costs and optional features. For instance:
Common Mistakes Consumers Make When Comparing Auto Insurance QuotesComparing auto insurance quotes requires precision and awareness of hidden factors that can distort perceived savings or coverage adequacy. Consumers often overlook critical details due to time constraints or lack of expertise, leading to misinformed decisions. These errors can result in underinsurance, unexpected premium spikes, or policy gaps that surface only after claims are filed. Below are seven frequent mistakes that undermine the effectiveness of price comparisons.Ignoring Policy Exclusions and LimitationsMany comparison tools prioritize price over fine print, leading consumers to overlook exclusions that void coverage under specific conditions. For example:
Always request a full policy document or summary of exclusions before committing to a quote. Exclusions can negate perceived savings if a claim arises under an excluded scenario. Failing to Update Driving Records or Personal DetailsInsurance pricing depends on accurate risk assessment, which relies on up-to-date information. Consumers who don’t refresh their records before comparing quotes may receive outdated or misleading rates. Key oversights include:
Use tools like Motor Vehicle Records (MVR) from state departments of motor vehicles to verify all driving history details before inputting data into comparison platforms. Comparing Apples to Oranges: Inconsistent Coverage LimitsPrice comparisons lose meaning if coverage levels vary between quotes. Consumers often accept lower liability limits (e.g., state minimums) to secure a cheaper rate, unaware that higher limits may be necessary for asset protection. Common inconsistencies include:
Standardize inputs across all quotes using identical coverage tiers (e.g., 100/300/50 with $500 deductibles) to ensure fair comparisons. Use a coverage worksheet to track limits uniformly. Overlooking Discounts That Aren’t Automatically AppliedMany insurers offer discounts (e.g., bundling, safe driver, low-mileage) that aren’t reflected in initial quotes unless explicitly requested. Consumers may miss savings of 10–30% by not probing for eligibility. Commonly overlooked discounts include:
Contact insurers directly to verify all applicable discounts. Some discounts (e.g., anti-theft device) require proof of installation, which may not be captured in automated tools. Assuming Online Quotes Are Final or BindingOnline quotes often serve as estimates only, subject to underwriting adjustments upon full application. Consumers who lock in based on these estimates may face:
Treat online quotes as preliminary. Always request a binding quote or pre-underwriting approval before finalizing a policy. Neglecting Regional or Provider-Specific Rate VariationsInsurance rates fluctuate by ZIP code, insurer market share, and local claim trends. Consumers comparing quotes across providers may miss:
Use regional rate lookup tools or consult local agents to compare how providers price policies in your exact area. Skipping the Fine Print on Cancellation PoliciesCheap policies may include punitive cancellation clauses that trap consumers. Hidden terms can include:
Review the policy cancellation section and ask for a non-cancellation guarantee if switching providers later is a concern. A/B Testing with Insurers to Secure Better Auto Insurance RatesA/B testing in auto insurance involves systematically comparing how different policy configurations—such as deductible levels, coverage tiers, or provider discounts—impact final premiums. By isolating variables, consumers can identify the optimal balance between cost and risk mitigation. This method is particularly effective when insurers offer dynamic pricing based on self-selected parameters, allowing for data-driven adjustments to secure lower rates without compromising protection. The core principle of A/B testing in this context is to treat each quote request as an independent variable, where slight modifications yield measurable outcomes. For example, a 25% increase in the deductible might reduce premiums by 15%, but only if the consumer can afford the higher out-of-pocket expense in the event of a claim. Insurers often apply tiered pricing models, where higher deductibles or lower coverage limits directly correlate with lower monthly costs. However, the trade-off must align with the consumer’s risk tolerance and financial capacity.Step-by-Step Process for A/B Testing Deductible LevelsTo systematically test deductible adjustments, follow this structured approach:
Advanced Tactics for A/B Testing Beyond DeductiblesWhile deductibles are the most straightforward variable to test, other policy configurations can yield significant savings when adjusted methodically. These include:
The optimal deductible level is not solely determined by premium savings but by the expected loss ratio—the ratio of claims paid to premiums collected. If an insurer’s average claim payout for a demographic is 60% of premiums, increasing the deductible to reduce premiums by 20% may still leave the consumer at higher risk of catastrophic losses. Always cross-reference with local claim frequency data. Emerging Technologies Transforming Auto Insurance Price Comparison DynamicsEmerging technologies are reshaping auto insurance pricing models, shifting from static risk assessments to dynamic, data-driven evaluations. AI underwriting, telematics, and autonomous vehicle integration are introducing real-time risk factors, forcing insurers to adapt comparison frameworks. These innovations not only alter how quotes are generated but also redefine consumer expectations for transparency and personalization in insurance markets. The evolution of these technologies will compress the gap between insurers and consumers, enabling more granular risk segmentation and context-aware pricing. Traditional comparison tools, which rely on static driver profiles, will become obsolete as insurers incorporate behavioral data, predictive maintenance metrics, and environmental variables. Below are key areas where technological advancements will disrupt comparison dynamics. ---AI Underwriting and Real-Time Risk AssessmentAI-driven underwriting systems analyze vast datasets—including driving behavior, vehicle diagnostics, and external risk indicators—to generate dynamic quotes. Unlike legacy models that rely on historical data, AI adjusts premiums based on real-time inputs such as:
AI underwriting will enable insurers to offer hourly or daily rate adjustments based on a driver’s current risk profile, rather than annual static pricing.--- Autonomous Vehicles and the Decline of Driver-Centric PricingThe rise of autonomous vehicles (AVs) will fundamentally alter how insurers assess risk, shifting liability from drivers to manufacturers, software providers, and cybersecurity firms. Key implications for price comparisons include:
By 2030, up to 30% of new vehicles sold may feature autonomous capabilities, forcing insurers to redesign comparison tools to account for non-driver risk factors.--- Blockchain for Transparent and Immutable Policy RecordsBlockchain technology is being explored to enhance transparency in insurance comparisons by creating tamper-proof policy histories. Key applications include:
Blockchain could reduce insurance fraud by 40% by providing immutable proof of policy compliance and claim validity.--- Biometric and Health Data IntegrationInsurers are increasingly incorporating biometric and health data to assess risk beyond traditional driving records. Examples include:
By 2025, 25% of insurers are expected to integrate biometric data into underwriting, necessitating new privacy safeguards in comparison tools.--- Augmented Reality for On-Demand Insurance ComparisonsAR and VR technologies are enabling interactive insurance comparisons, allowing consumers to visualize policy impacts in real time. Applications include:
AR-driven comparisons could increase consumer engagement by 50% by making abstract insurance concepts tangible. Auto insurance price comparison isn’t just about finding the lowest number—it’s about aligning coverage with your risk profile, budget, and long-term needs while avoiding the pitfalls of incomplete data or deceptive practices. From the 30-year-old hybrid SUV driver in a high-theft city to the high-mileage commuter weighing pay-per-mile options, real-world case studies demonstrate how tailored comparisons can slash premiums by 30% or more. As technology reshapes underwriting—with AI-driven quotes and climate risks altering regional pricing—staying ahead means mastering both the art of manual verification (cross-checking state databases, auditing financial health ratings) and the science of algorithmic transparency. The future of auto insurance pricing favors those who treat comparisons as an ongoing dialogue with providers, not a one-time transaction. Armed with the right tools—from NAIC-validated benchmarks to discount negotiation templates—consumers can transform price comparisons from a chore into a competitive advantage. The key lies in consistency: ensuring every quote uses identical inputs, spotting hidden fees, and recognizing when to prioritize brand reliability over price—or vice versa. Whether you’re a first-time buyer, a policyholder due for renewal, or a high-risk driver seeking alternatives, this guide equips you to approach comparisons with the precision of an insider, turning confusion into control and uncertainty into savings. 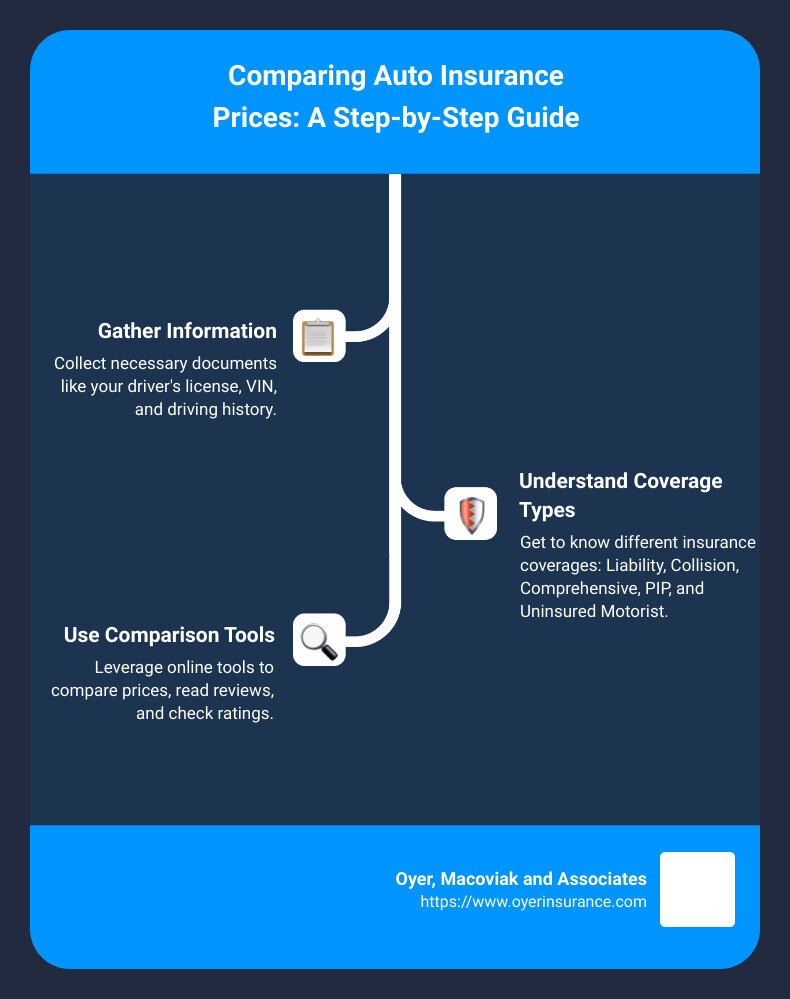 Frequently Asked QuestionsHow do I compare auto insurance prices accurately?Use online comparison tools or direct quotes from providers. Input identical details (vehicle, coverage, location) to ensure fair comparisons. Verify discounts and provider reputation. Cross-check with independent reviews for unbiased results. What factors make my auto insurance rates higher?Driving record, age, location, vehicle type, coverage limits, and credit history influence pricing. High-risk profiles (e.g., young drivers) or expensive cars in urban areas typically face higher premiums. Are auto insurance prices the same across all companies?No, prices vary by provider due to underwriting practices, regional market competition, and risk assessment models. Some insurers specialize in discounts or niche markets, affecting costs. Can bundling policies lower my auto insurance cost?Yes, bundling auto with home or renters insurance often qualifies for multi-policy discounts (10-25% off). Always compare standalone vs. bundled quotes to confirm savings. How often should I compare auto insurance rates?Review rates annually or after major life changes (e.g., moving, marriage, or vehicle purchase). Market conditions and personal risk factors evolve, so periodic comparisons ensure optimal pricing. What discounts can I get to reduce auto insurance costs?Common discounts include safe driver, low-mileage, anti-theft device, student, and loyalty discounts. Insurers also offer bundling, paperless billing, or usage-based programs (e.g., telematics). Ask providers about eligibility. Related articlesAuto Insurance Price Comparison Key Factors And Smart Savings Discover how to compare auto insurance prices wisely by analyzing key factors like age, location, and coverage. Learn smart savings tips to lower…  Auto Insurance Quotes Explained Key Factors Tips Understand Auto Insurance Quotes Explained Key Factors Tips to save money. Learn how coverage, deductibles, and discounts impact rates and find the best… 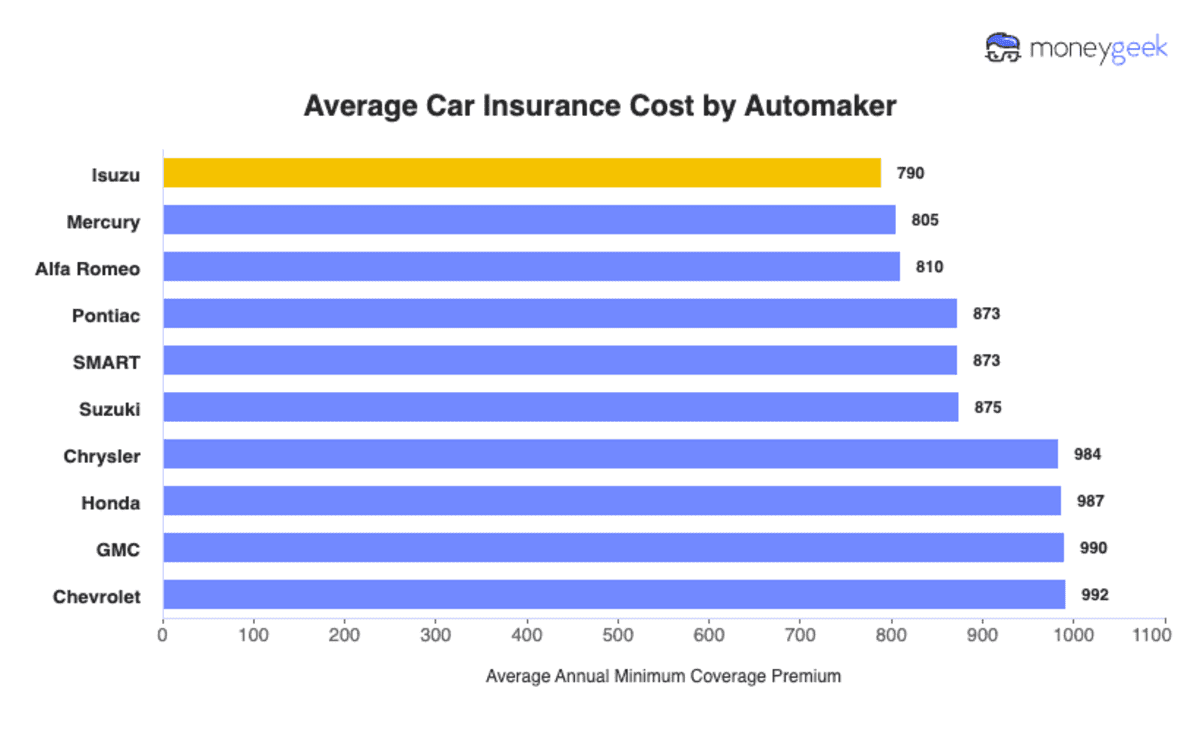 Compare Auto Insurance Rates Smartly Today Find the best auto insurance deals by comparing rates smartly—save money without sacrificing coverage. Compare Auto Insurance Rates Smartly Today for… Compare Auto Insurance Rates Effectively Today Compare Auto Insurance Rates Effectively Today with our free, side-by-side tools. Save time and money by finding the best coverage tailored to your needs.  Auto Insurance Car Insurance Explained Simply Understand Auto Insurance & Car Insurance Explained Simply—coverage types, costs, and how policies protect drivers. Get clear answers on liability,… 
|