Compare Auto Insurance Rates Effectively Today
Table of Contents
- Fundamental Components of Auto Insurance Policies
- Primary Variables Influencing Auto Insurance Premium Costs
- Comparing Auto Insurance Quotes: A Structured Approach to Finding the Best Rates
- Auto Insurance Cost Differences: Urban vs. Rural Area Analysis
- Impact of Vehicle Make/Model/Year on Auto Insurance Costs
- Common and Underutilized Auto Insurance Discounts: Maximizing Savings
- How Online Auto Insurance Comparison Tools Function
- Decade-Long Trends in Auto Insurance Pricing and Claim Dynamics
- How Insurers Communicate Rate Changes to Policyholders
- Visualizing Premium Allocation: Claims, Administration, and Profit Distribution in a $100 Auto Insurance Premium
- Anti-Discrimination Laws in Auto Insurance Rate Setting
- Emerging Technologies and Hyper-Personalized Auto Insurance Rates
Auto insurance rates can feel like a maze of variables—from driving history to location—each influencing how much you pay for protection. Yet understanding these factors isn’t just about saving money; it’s about securing the right coverage without overpaying. Whether you’re a first-time buyer or reviewing an existing policy, knowing how insurers calculate premiums and where to find the best deals can save hundreds annually. This guide breaks down the core elements of auto insurance, the hidden drivers behind rate differences, and actionable strategies to compare quotes like a pro. With regional trends, vehicle-specific costs, and digital tools reshaping the market, smart shoppers can navigate this landscape with confidence—without falling for common pitfalls that inflate premiums unnecessarily.
The complexity of auto insurance stems from its dual role: a legal requirement and a financial safeguard. A policy’s structure—whether full-coverage or liability-only—directly impacts both your out-of-pocket costs and long-term protection. Meanwhile, insurers weigh thousands of data points to assess risk, from your credit score to the neighborhood you drive through. This system isn’t static; economic shifts, technological advances, and even climate patterns alter how rates are set. By dissecting these components, you’ll recognize patterns that explain why two identical drivers might pay vastly different premiums for the same coverage. The goal isn’t just to find the cheapest rate but to align your policy with your needs while maximizing discounts and leveraging tools designed to simplify comparisons.
Fundamental Components of Auto Insurance Policies
Auto insurance policies serve as a financial safety net for vehicle owners, covering costs associated with accidents, theft, or damage. These policies are structured around core components that define coverage scope, ensuring policyholders understand what risks are mitigated and which are excluded. The primary components of an auto insurance policy include **liability coverage**, **collision coverage**, **comprehensive coverage**, **uninsured/underinsured motorist protection**, and **medical payments or personal injury protection (PIP)**. Each component addresses distinct financial risks, from third-party liability to direct vehicle damage.Liability Coverage
Liability coverage is mandatory in most regions and addresses the financial responsibility of the policyholder for damages or injuries they cause to others. It consists of two key subcategories: - **Bodily Injury Liability (BI):** Covers medical expenses, lost wages, and legal fees for others injured in an accident caused by the policyholder. Limits are typically expressed as per-person and per-accident maximums (e.g., 100/300/50). - **Property Damage Liability (PD):** Pays for damage to another person’s property, such as a vehicle, fence, or building, resulting from the policyholder’s negligence. Limits are often stated as a single amount (e.g., $50,000)."Liability coverage does not protect the policyholder’s own vehicle or medical bills but instead safeguards third parties from financial claims."
Collision Coverage
Collision coverage reimburses the policyholder for vehicle repairs or replacement if the car is damaged in a collision with another vehicle or object, regardless of fault. This coverage is optional but highly recommended for financed or leased vehicles. Key considerations include: - **Deductible:** The out-of-pocket amount the policyholder pays before insurance coverage kicks in (e.g., $500, $1,000). - **Actual Cash Value (ACV):** The depreciated value of the vehicle at the time of the claim, which may result in lower payouts for older cars. - **Replacement Cost:** Optional add-ons that cover the full cost of replacing a vehicle with a similar new one, minus the deductible.Comprehensive Coverage
Comprehensive coverage protects against non-collision-related damages, such as theft, vandalism, fire, natural disasters (e.g., hail, floods), or falling objects. It is often bundled with collision coverage under a **"full-coverage"** policy. Factors influencing premiums include: - **Vehicle Value:** Higher-value cars incur higher premiums due to increased repair/replacement costs. - **Geographic Risk:** Areas prone to theft or natural disasters (e.g., coastal regions for hurricanes) may increase rates. - **Security Features:** Anti-theft devices or GPS tracking can reduce premiums by mitigating risk.Uninsured/Underinsured Motorist Coverage
This coverage addresses scenarios where the at-fault driver lacks insurance (uninsured) or carries insufficient coverage (underinsured). It compensates the policyholder for medical expenses, lost wages, or property damage not fully covered by the other party’s policy. State laws vary: - **No-Fault States (e.g., Michigan, New York):** Require uninsured motorist coverage to cover medical expenses regardless of fault. - **Fault States (e.g., Texas, Florida):** May mandate uninsured motorist bodily injury (UMBI) coverage but not property damage.Medical Payments or Personal Injury Protection (PIP)
Medical payments coverage (common in fault states) or PIP (mandated in no-fault states) pays for the policyholder’s and passengers’ medical expenses regardless of fault. PIP often includes additional benefits like lost wages or funeral costs. Key distinctions: - **PIP:** Broader coverage, typically covering 80% of medical bills, lost income, and essential services (e.g., childcare). - **Medical Payments:** Limited to medical expenses only, with lower maximum payouts (e.g., $5,000 per person).Additional Optional Coverages
Beyond core components, policyholders may add: - **Gap Insurance:** Covers the difference between the vehicle’s loan/lease amount and its depreciated value in case of total loss. - **Rental Reimbursement:** Pays for a rental car while the policyholder’s vehicle is being repaired. - **Roadside Assistance:** Provides towing, jump-starts, or lockout services. - **Custom Equipment Coverage:** Extends protection to aftermarket modifications (e.g., sound systems, rims).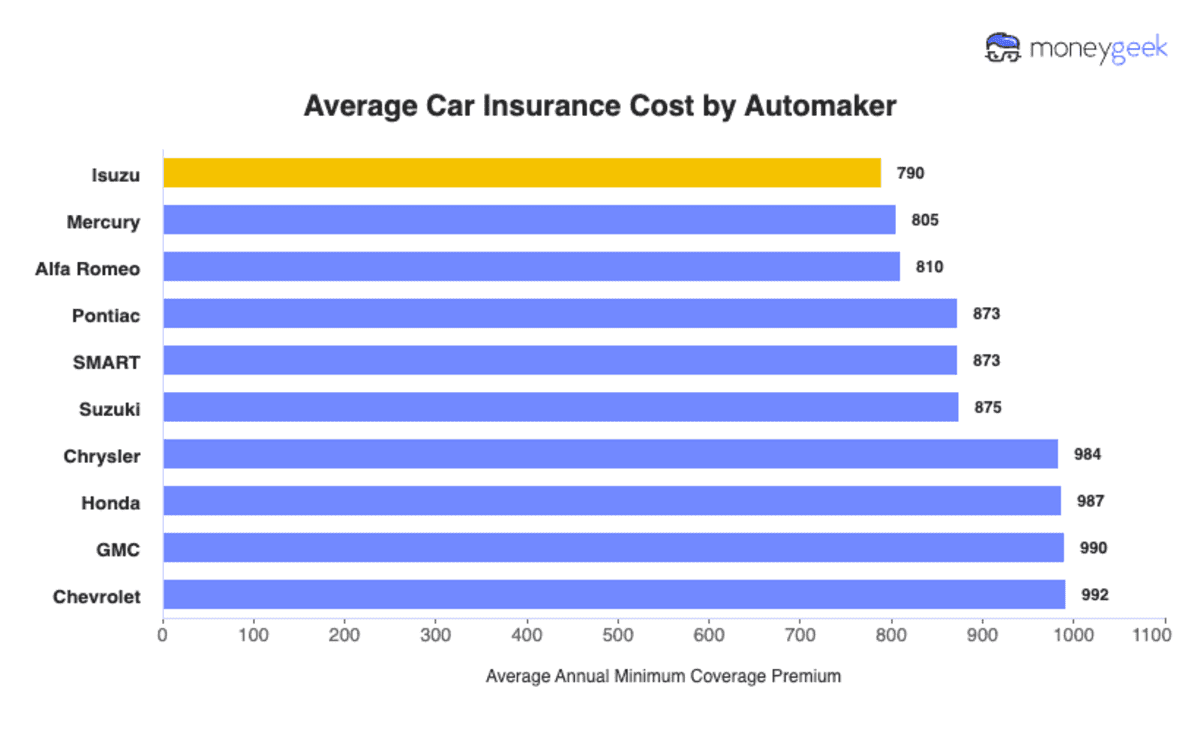
Primary Variables Influencing Auto Insurance Premium Costs
Auto insurance premiums are determined by a complex interplay of risk factors evaluated by insurers to assess the likelihood of a claim. These variables serve as foundational elements in pricing models, directly correlating with statistical data on accident frequency, severity, and financial loss potential. Understanding these factors enables drivers to make informed decisions to mitigate costs and optimize coverage. The most significant variables include demographic attributes, behavioral history, vehicle specifications, and geographic location. Each factor carries weighted importance, with some variables—such as driving record—holding greater influence than others, like vehicle age. Insurers leverage actuarial science and predictive analytics to quantify these risks, translating them into premium adjustments.Age and Driver Experience
Age is a primary determinant of insurance risk due to established trends in accident rates. Younger drivers (under 25) typically face higher premiums due to limited experience and statistically higher collision frequencies. Conversely, drivers aged 30–60 often enjoy lower rates, reflecting a period of relative stability in accident risk. Senior drivers (over 65) may see premium increases tied to potential declines in reflexes or vision, though some insurers offer discounts for mature drivers with clean records. The relationship between age and risk is further nuanced by experience. For instance, a 20-year-old with a perfect driving record may pay less than a 50-year-old with a history of at-fault accidents, despite both falling into "high-risk" age brackets. Insurers cross-reference age with other variables, such as vehicle type and location, to refine risk assessments.Driving History and Claims Record
A driver’s history of at-fault accidents, traffic violations (e.g., speeding, DUI), and previous claims directly impacts premium calculations. Each violation or accident typically adds 20–50% to annual premiums, with severe offenses (e.g., reckless driving) resulting in multi-year surcharges. For example, a driver with a single speeding ticket might see a 20–30% increase, while a DUI conviction could double premiums for three years. Insurers also analyze claim frequency and severity. Drivers with frequent minor claims (e.g., fender benders) may face higher rates than those with a single major claim, as the latter suggests a one-time event rather than a pattern of risk. Some states implement "good driver discounts" for policyholders without violations for a set period (e.g., 3–5 years), incentivizing safe behavior.Vehicle Type and Model Specifications
The vehicle’s make, model, age, and safety features are critical in determining risk exposure. High-performance or luxury vehicles often incur higher premiums due to elevated repair costs and higher theft rates. For instance, a 2023 Tesla Model 3 may cost 30–50% more to insure than a 2015 Honda Civic, primarily because of its advanced technology and higher replacement value. Safety ratings from organizations like the **National Highway Traffic Safety Administration (NHTSA)** or **Insurance Institute for Highway Safety (IIHS)** significantly influence rates. Vehicles with top safety scores (e.g., IIHS "Top Safety Pick+") may qualify for discounts of 10–20%, as they correlate with lower claim frequencies. Additionally, anti-theft devices (e.g., alarms, GPS tracking) and collision avoidance systems (e.g., automatic emergency braking) can reduce premiums by 5–15%.Geographic Location and Local Risk Factors
Location-based risk factors, including crime rates, weather patterns, and urban density, play a pivotal role in premium pricing. Cities with high traffic congestion (e.g., Los Angeles, New York) and theft rates (e.g., Miami, Chicago) often have higher insurance costs due to increased exposure to accidents and vehicle damage. Conversely, rural areas with lower accident rates may offer cheaper premiums, though limited access to emergency services can offset some savings. Weather-related risks also vary by region. States prone to severe storms (e.g., Florida, Texas) or heavy snowfall (e.g., Minnesota, New York) see higher premiums due to increased claim frequencies for windshield damage, flooding, or winter-related collisions. Insurers adjust rates based on historical claim data, with some companies offering discounts for drivers in low-risk zones (e.g., suburban areas with below-average accident rates). ---Comparing Auto Insurance Quotes: A Structured Approach to Finding the Best Rates
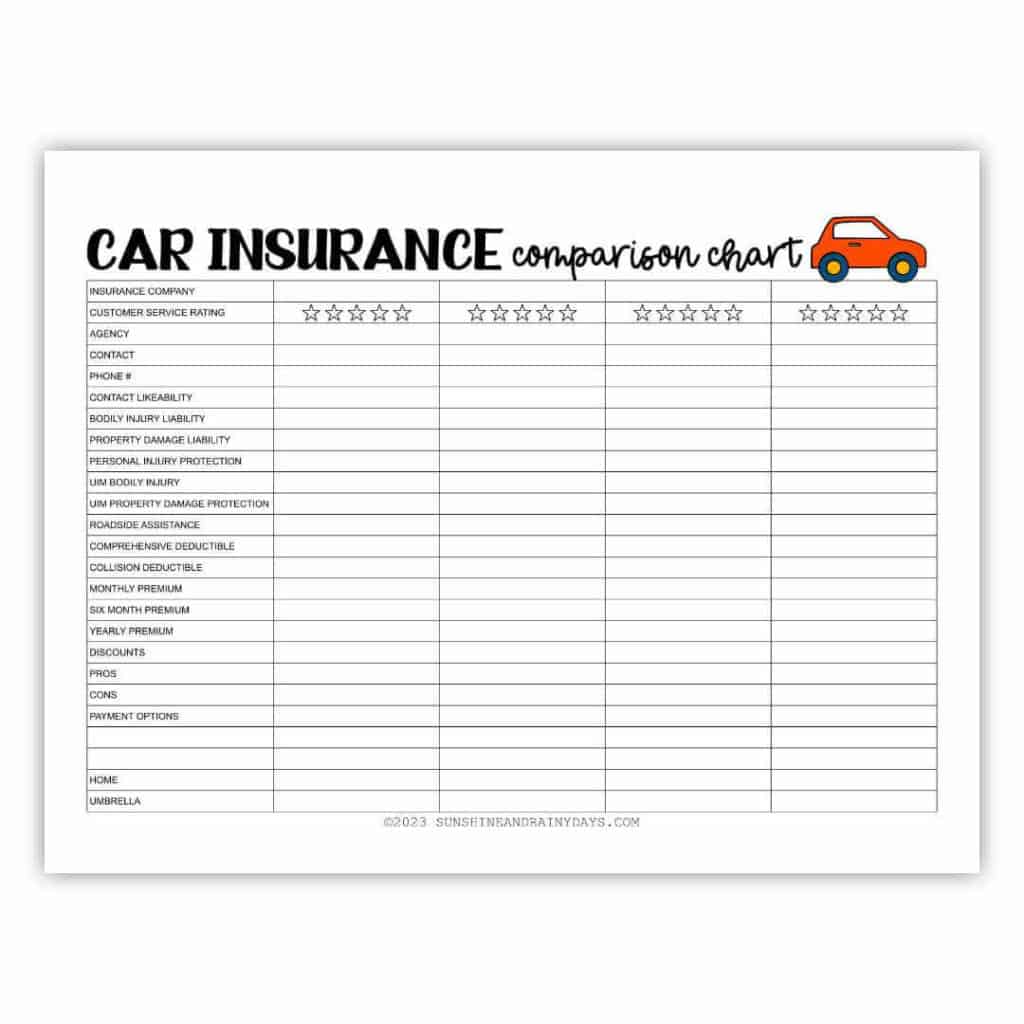
Securing the most competitive auto insurance policy requires a systematic comparison of quotes from multiple providers. This process involves understanding both online and agent-based methods, standardizing key variables, and interpreting variations in pricing. By following a disciplined approach, consumers can avoid common pitfalls—such as overlooking hidden fees or misaligned coverage—and make an informed decision grounded in accurate data. The comparison process begins with gathering quotes, where digital tools and human intermediaries each offer distinct advantages. Online platforms provide speed and accessibility, while agents offer personalized guidance tailored to specific needs. Standardizing criteria like deductible amounts and coverage limits ensures apples-to-apples comparisons, while interpreting discrepancies—such as differences in premiums for identical policies—requires knowledge of underwriting nuances and regional pricing factors. Emerging technologies like telematics further complicate comparisons by introducing usage-based pricing models, demanding an understanding of how real-world driving behavior impacts costs. ---Gathering Quotes: Online vs. Agent-Based Methods
The method chosen to obtain quotes significantly influences efficiency and the depth of information received. Online platforms streamline the process by allowing users to input personal and vehicle details through user-friendly interfaces, often yielding instant comparisons across multiple insurers. This approach is ideal for consumers who prioritize convenience and transparency, as digital tools typically display clear breakdowns of premiums, deductibles, and discounts. However, online quotes may lack contextual explanations for pricing variations or policy exclusions, leaving consumers to interpret results without guidance. Agent-based methods, conversely, provide a more interactive experience. Insurance agents—whether independent or tied to specific companies—offer personalized service, clarifying complex terms and negotiating coverage tailored to individual circumstances. This method is particularly valuable for high-net-worth individuals or those with unique risk profiles (e.g., classic car owners or commercial drivers), where nuanced policy adjustments may be necessary. Agents also have access to non-digital discounts or bundling opportunities that may not be visible through online portals. **Online Quote Collection Process** Consumers can follow this step-by-step approach to gather online quotes efficiently:- Compile Personal and Vehicle Information: Prepare details such as driver’s license number, vehicle identification number (VIN), annual mileage, and driving history. Accuracy at this stage prevents quote discrepancies caused by incomplete or incorrect data.
- Select a Comparison Platform: Use reputable aggregators (e.g., Policygenius, The Zebra) or insurer websites directly. Aggregators consolidate quotes from multiple providers, while direct insurer sites may offer proprietary discounts or loyalty incentives.
- Standardize Coverage Parameters: Ensure all quotes reflect the same coverage limits, deductibles, and optional add-ons (e.g., roadside assistance, gap insurance). Tools like the National Association of Insurance Commissioners (NAIC) coverage calculator can help align these variables.
- Input Additional Factors: Account for factors like credit score (where legally permitted), safety features (e.g., anti-theft devices), and claims history. Some platforms allow users to adjust these variables to simulate hypothetical scenarios.
- Review and Export Quotes: Save or print quotes for side-by-side comparison. Note the effective date of each quote, as premiums may fluctuate based on market conditions or insurer promotions.
- Schedule a Consultation: Contact local or online agents (e.g., through platforms like Insure.com or by referral). Independent agents can shop multiple insurers, while captive agents represent a single company.
- Provide Comprehensive Details: Disclose all relevant information, including past claims, modifications to the vehicle, and lifestyle factors (e.g., commute patterns). Transparency avoids policy cancellations or claim denials later.
- Discuss Coverage Priorities: Agents can explain how different coverage tiers (e.g., collision vs. comprehensive) impact premiums and liability protection. For example, a 500-dollar deductible may reduce premiums by 10–15% compared to a 250-dollar deductible.
- Negotiate Discounts: Agents may offer bundling discounts (e.g., combining auto and home insurance), safe driver incentives, or loyalty rewards. Ask about less common discounts, such as those for completing defensive driving courses.
- Receive Written Quotes: Ensure quotes include a detailed breakdown of costs, coverage limits, and exclusions. Request a comparison of 3–5 insurers to maximize options.
Best Practices for Accurate Quote Comparisons
Accurate comparisons hinge on standardizing critical variables to avoid misleading price differences. Premiums vary based on coverage levels, deductibles, and optional endorsements, so consumers must align these factors across quotes. For instance, a policy with a 100-dollar deductible for collision and a 500-dollar deductible for comprehensive will not be directly comparable to one with uniform 500-dollar deductibles, even if the total premium appears lower. **Standardizing Coverage Levels**Key Principle: Compare policies with identical coverage limits for liability (e.g., 25/50/25 in most states), uninsured motorist protection, and property damage liability. Adjust for state minimums if applicable, as these vary (e.g., California requires 15/30/5, while Texas mandates 30/50/25).Common coverage tiers to standardize:
- Liability Coverage: Ensure each quote includes at least the state minimum, but consider higher limits (e.g., 100/300/100) for better protection against lawsuits.
- Collision and Comprehensive: Decide whether to include these add-ons. Collision covers damage to your vehicle; comprehensive covers non-collision incidents (e.g., theft, vandalism).
- Uninsured/Underinsured Motorist: This protects you if the at-fault driver lacks sufficient coverage. Standardize this to 25/50 or higher.
- Medical Payments/Personal Injury Protection (PIP): PIP (required in no-fault states like Florida) covers medical expenses regardless of fault. Align this with your health insurance limits.
- Deductibles: Choose a consistent deductible (e.g., 500 dollars for collision and comprehensive) to compare apples-to-apples. Higher deductibles lower premiums but increase out-of-pocket costs at claim time.
- Roadside Assistance: Costs typically range from 50–150 dollars annually. Compare this to your existing memberships (e.g., AAA).
- Gap Insurance: Relevant if you lease a vehicle or owe more on a loan than the car’s depreciated value. Premiums average 10–20 dollars per month.
- Rental Reimbursement: Covers rental car costs after a claim. Standardize limits (e.g., 30 dollars per day) to compare.
- Towing and Labor: Often bundled with roadside assistance. Ensure the limit (e.g., 100 dollars) matches your needs.
- Safe Driver Discounts: Requires a clean driving record (typically 3+ years without at-fault accidents or violations).
- Bundling Discounts: Combining auto and home insurance with the same provider (e.g., State Farm, Allstate) often yields 10–25% savings.
- Low Mileage Discounts: Applies to drivers with <12,000 miles annually. Some insurers (e.g., Geico) offer this for <7,500 miles.
- Anti-Theft/Advanced Safety Discounts: Vehicles with anti-lock brakes, airbags, or tracking devices (e.g., OnStar) qualify. Example: A 2022 Honda Civic with Honda Sensing may receive a 5% discount.
- Payment Method Discounts: Automatic payments or paperless billing can reduce premiums by 1–3%.
Interpreting Quote Discrepancies: Why Identical Policies Have Different Prices
Even when comparing policies with identical coverage limits and deductibles, premiums may vary due to underwriting methodologies, regional pricing, and insurer-specific risk assessments. Understanding these factors clarifies why one insurer charges 10% more than another for the same policy. **Underwriting and Risk Assessment** Insurers use proprietary algorithms to assess risk, incorporating factors beyond standard variables:- Credit-Based Insurance Scores: In most states, insurers use credit scores to predict claim likelihood. A driver with a 750+ credit score may pay 20–30% less than one with a 600 score. Example: Progressive’s 2023 data showed credit scores explaining 20% of rate variation.
- Driving Behavior Data: Some insurers (e.g., State Farm, Allstate) use telematics to monitor speeding, hard braking, or night driving. A policyholder with aggressive driving habits may see a 15–25% premium increase.
-
Vehicle Make and Model:
Insurers classify vehicles into risk groups based on repair costs, theft rates, and crash statistics. A 2022 Tesla Model 3 may cost 30% more to insure than
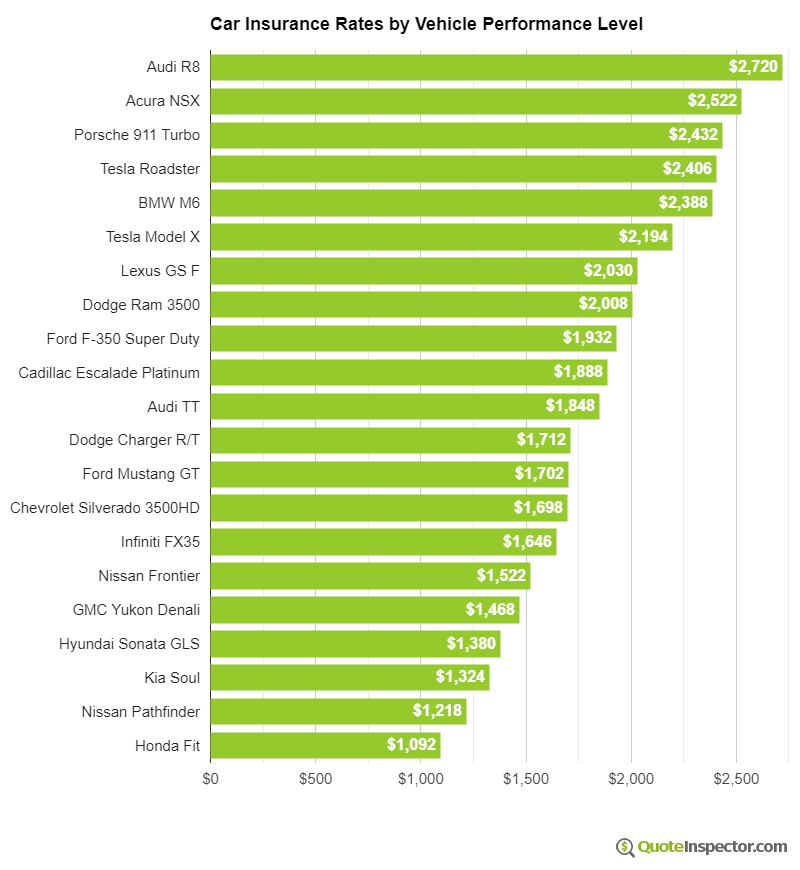
Cheapest Car Insurance Rates by Vehicle Type in 2026 QuoteInspector.com Auto Insurance Cost Differences: Urban vs. Rural Area Analysis
Urban and rural areas exhibit stark contrasts in auto insurance premiums, driven primarily by variations in risk exposure, infrastructure density, and regulatory environments. Urban centers, with their higher population concentrations, increased traffic density, and greater incidence of accidents, typically command significantly higher premiums. Conversely, rural regions benefit from lower accident rates, reduced traffic congestion, and broader spacing between vehicles, which translates to comparatively lower costs. These disparities are further amplified by differences in crime rates, emergency response times, and the availability of repair facilities. The pricing gap stems from insurers’ risk assessment models, which factor in historical claims data, repair costs, and the likelihood of theft or vandalism. Urban drivers often face premiums 20–40% higher than their rural counterparts, though regional exceptions exist based on local crime statistics, weather vulnerabilities, and economic factors.Traffic Density and Accident Risk in Urban Centers
High-traffic urban areas like New York City or Los Angeles experience collision rates 3–5 times greater than rural regions due to congested roadways, distracted driving, and limited visibility. Insurers adjust premiums accordingly, with urban drivers paying an average of **$1,800 annually** (per LexisNexis Risk Solutions) compared to **$1,200 in rural areas**. The concentration of high-value assets (luxury vehicles) in cities also elevates theft and vandalism risks, further driving up costs. Key contributing factors include:- **Density of vehicles**: More cars on roads increase collision probabilities, particularly during peak hours.
- **Emergency response delays**: Urban emergency services may take longer to reach accident sites, raising liability risks for insurers.
- **Parking-related incidents**: Theft from parked vehicles in high-crime urban zones (e.g., downtown Chicago) spikes premiums for owners of high-theft models like the Honda Civic.
- **Infrastructure wear**: Aging urban roads and bridges contribute to higher repair costs after accidents.
Lower Costs in Rural Areas: Spacing and Lower Claims
Rural drivers benefit from broader road spacing, fewer intersections, and lower population density, resulting in fewer accidents and claims. For example, premiums in states like Iowa or Nebraska average **$1,100–$1,300**, with some insurers offering discounts for "low-density driving" as a policy feature. The reduced need for extensive roadside assistance and lower repair costs (due to fewer high-speed collisions) further mitigate expenses. Notable advantages include:- **Fewer high-severity accidents**: Rural drivers are less likely to experience multi-vehicle pileups or fatal crashes.
- **Lower theft rates**: Vehicles in rural areas are less targeted, reducing comprehensive coverage claims.
- **Simpler claims processing**: Remote locations often mean quicker damage assessments and repairs.
- **State-specific incentives**: Some rural states (e.g., Wyoming) offer "rural driver discounts" for policies with clean records.
Regional Exceptions and Outliers
While urban areas generally pay more, exceptions exist where rural regions face elevated costs due to unique risks:- **Alaska and Montana**: High auto theft rates in rural areas (e.g., Fairbanks) push premiums above urban benchmarks due to limited law enforcement presence.
- **Florida’s rural counties**: Flood-prone regions like Polk County see premiums spike despite low traffic, driven by climate-related claims.
- **Urban-adjacent rural zones**: Areas like suburban Houston or Phoenix (e.g., Katy, TX) mirror urban costs due to commuter traffic and infrastructure ties.
*"Insurance premiums reflect not just where you drive, but where you live—and the cumulative risks of your environment. Urban drivers pay for density; rural drivers pay for isolation-related vulnerabilities like poor road maintenance or remote emergency access."*
Impact of Vehicle Make/Model/Year on Auto Insurance Costs
Insurance premiums for automobiles are heavily influenced by the vehicle’s specifications, as insurers assess risk based on factors like repair costs, theft rates, and accident frequency. A car’s make, model, and year determine its perceived risk profile, which directly translates to higher or lower premiums. Luxury vehicles, for instance, often carry significantly higher costs due to specialized parts and labor-intensive repairs, while economy cars benefit from lower replacement value and widespread availability of parts. The relationship between vehicle attributes and insurance costs stems from insurers’ need to balance risk exposure with profitability. Older models may have lower premiums due to depreciation, but they also lack modern safety features, increasing collision and injury risks. Below are key considerations:Luxury vs. Economy Vehicle Cost Differences
Luxury vehicles command premiums 20–50% higher than comparable economy models due to: - **Specialized Parts**: High-end materials (e.g., carbon fiber, titanium) and proprietary components (e.g., BMW’s N20 engine) drive up repair costs. For example, replacing a Lexus LS 500’s turbocharged engine can exceed $10,000, compared to a $2,000 repair for a Toyota Corolla. - **Theft Vulnerability**: Cars like the Porsche 911 or Mercedes-Benz S-Class are prime targets for theft, increasing comprehensive coverage costs by 15–30%. - **Depreciation Rates**: Luxury cars lose value faster (e.g., a 2023 Rolls-Royce Phantom may depreciate 30% in 3 years), but their high replacement value necessitates higher collision coverage limits. Economy vehicles, conversely, benefit from: - **Lower Repair Costs**: Generic parts (e.g., Honda Civic’s engine) reduce labor and material expenses by 40–60% compared to luxury counterparts. - **Higher Theft Deterrence**: Models like the Toyota RAV4 or Honda CR-V have lower theft rates, lowering comprehensive premiums by 10–20%. - **Extended Warranty Synergies**: Many insurers offer discounts for vehicles with factory or extended warranties, reducing out-of-pocket repair costs.Year of Manufacture and Insurance Trends
The age of a vehicle introduces trade-offs between risk and cost: - **Newer Models (0–3 Years)**: Premiums are elevated due to: - **Advanced Safety Tech**: Features like automatic emergency braking (AEB) reduce collision claims by 30%, but the cost of integrating such systems into claims processing increases overhead for insurers. - **Higher Replacement Value**: A 2023 Tesla Model 3 with full self-driving hardware may require $50,000 in coverage, compared to $15,000 for a 2010 model. - **Mid-Aged Models (4–10 Years)**: Often the most cost-effective, as: - **Depreciation Balances Risk**: Repair costs are lower than new cars, but safety ratings may lag behind newer models. - **Insurer Discounts**: Some companies offer "older vehicle" discounts for models with proven safety records (e.g., Subaru Outback 2015–2019). - **Aged Models (>10 Years)**: Premiums drop significantly, but coverage gaps emerge: - **Limited Parts Availability**: Repairing a 1998 Honda Accord may require sourcing vintage parts, increasing labor costs. - **Higher Injury Risk**: Older cars lack modern safety features, leading to higher bodily injury liability claims.Regional Popularity and Rate Variations
Vehicle popularity in a region amplifies or mitigates insurance costs: - **High-Theft Zones**: In cities like Detroit or Los Angeles, models like the Ford F-150 or Chevrolet Impala see premiums inflated by 25–40% due to theft and vandalism risks. - **Urban vs. Rural**: Compact cars (e.g., Hyundai Elantra) in densely populated areas (New York) face higher collision rates, increasing liability premiums by 15%, while the same model in rural areas (e.g., Montana) may see a 10% reduction due to lower traffic density. - **Climate Impact**: Snow-belt regions (e.g., Minnesota) increase premiums for SUVs (e.g., Jeep Wrangler) by 20% due to winter-related damage claims, whereas desert regions (e.g., Arizona) reduce costs for the same models by 12%.Common and Underutilized Auto Insurance Discounts: Maximizing Savings
Auto insurance discounts serve as financial incentives for policyholders to adopt safer behaviors, maintain certain vehicle features, or demonstrate loyalty to an insurer. These savings can accumulate significantly, especially when combined with other cost-reduction strategies. Below is a breakdown of widely offered discounts alongside lesser-known opportunities that often go overlooked. Discounts are typically applied as percentage reductions to premiums, with some requiring proof of eligibility (e.g., documentation, verification) and others automatically applied based on policy terms. Understanding these options empowers consumers to negotiate better rates or qualify for savings they may not have realized exist.Widely Offered Discounts
The most common discounts are standardized across insurers and often promoted through marketing campaigns. These include:These discounts are frequently bundled or stacked, allowing policyholders to reduce premiums by multiple percentages simultaneously. For example, combining a pay-in-full discount with a good driver discount could yield savings of 15–30% annually, depending on the insurer’s policies and state regulations.
- Pay-in-Full (Cash Discount) Insurers often reward customers who pay their annual premium upfront rather than in monthly installments. This discount can range from 5–15%, as it reduces administrative costs for the insurer. Example: A policy with an annual premium of $1,200 could see a $60–$180 reduction by paying in full.
- Good Driver Discount Maintaining a clean driving record—free of at-fault accidents or traffic violations (e.g., speeding tickets)—qualifies drivers for this discount. Some insurers offer tiered discounts: 10% for minor infractions, 20% for no violations in 3+ years, and up to 30% for accident-free driving. Verification may require proof of a SR-22 (for high-risk drivers) or a clean driving history report.
-
Anti-Theft/Alarm Discount
Vehicles equipped with certified anti-theft devices (e.g., factory-installed alarms, GPS trackers, or steering wheel locks) qualify for discounts of 5–15%. Examples of recognized systems include:
- OnStar (General Motors)
- LoJack (vehicle recovery system)
- Alarm systems certified by the Car Care Council
- Multi-Policy (Bundling) Discount Bundling auto insurance with other policies (e.g., homeowners, renters, or umbrella insurance) typically results in a 10–25% discount on the combined premiums. Example: A homeowner with auto insurance through the same provider might see their auto premium reduced by $150–$300 annually if they add their home policy to the bundle.
- Low Mileage Discount Drivers who log fewer than 7,500–10,000 miles annually (e.g., remote workers, retirees, or students) may qualify for discounts of 5–15%. This discount reflects lower risk exposure due to reduced driving frequency. Some insurers require mileage verification via odometer readings or GPS data.
- Good Student Discount Full-time students maintaining a B average (3.0 GPA or higher) or enrolled in an accredited driving safety course (e.g., AAA Traffic Safety Course) can earn discounts of 5–25%. Parents or guardians must provide proof of enrollment and grades. Example: A 19-year-old with a 3.5 GPA could save $100–$300 per year on their auto policy.
- Defensive Driving Course Discount Completing a state-approved defensive driving course (e.g., through the AAA or local DMV) can reduce premiums by 5–10%. These courses often address risk mitigation, accident prevention, and defensive techniques. Some states (e.g., Florida, Texas) offer additional benefits, such as ticket dismissal or insurance credit.
- Vehicle Safety Features Discount Modern vehicles equipped with advanced safety technologies (e.g., automatic emergency braking, lane departure warnings, or blind-spot monitoring) may qualify for discounts of 5–20%. Example: A 2022 Toyota Camry with Toyota Safety Sense 2.0 could receive a 15% discount from certain insurers. Proof of installation (e.g., vehicle manual or dealer records) is typically required.
- Paperless Billing Discount Opting for electronic billing (e.g., PDF statements via email) can yield a 5–10% discount. This discount reflects reduced printing and mailing costs for the insurer. Example: A policy with a $1,500 annual premium could save $75–$150 by switching to digital billing.
Underutilized Discounts
Many discounts exist but are rarely discussed or promoted, often due to insurers’ focus on high-volume savings opportunities. These discounts require proactive research or specific qualifications but can lead to significant savings when combined with other strategies.Underutilized discounts are particularly valuable for niche demographics or professions. Qualifying for these may involve providing proof of affiliation, employment, or lifestyle choices. Below are lesser-known but highly effective discounts:
- Military Discount Active-duty military personnel, veterans, and their families often qualify for discounts ranging from 10–25% through programs like the National Association of Insurance Commissioners (NAIC) or insurer-specific initiatives. Example: USAA offers exclusive discounts to military members, including a 15% auto policy discount for bundling home and auto insurance. Proof of service (e.g., military ID or DD Form 214) is required.
- Alumni Discount Graduates of certain universities or colleges may receive discounts through partnerships with insurers. Example: State Farm partners with over 1,000 colleges to offer alumni discounts of 5–15%. Proof of graduation (e.g., diploma, transcript, or alumni association membership) is typically needed. Some insurers also offer discounts to parents of current students.
-
Professional Affiliation Discounts
Certain professions or memberships in organizations qualify for discounts. Examples include:
- AAA Membership Discount: AAA members may receive 5–10% off auto insurance through partnerships with insurers like Progressive or Geico. Proof of membership (e.g., AAA card) is required.
- Teacher/Nonprofit Worker Discount: Some insurers (e.g., Farmers, State Farm) offer 5–15% discounts to educators or nonprofit employees. Proof of employment (e.g., pay stubs, employer verification letter) is necessary.
- Physician/Healthcare Provider Discount: Insurers like Liberty Mutual or Nationwide offer discounts to doctors, nurses, or other healthcare professionals, often ranging from 10–20%. Example: A physician with a clean driving record could save $200–$400 annually.
- Rural/Remote Area Discount Drivers in low-population areas or rural zones may qualify for discounts due to lower accident rates and reduced claims risk. Example: Insurers in states like Montana or Wyoming may offer 5–15% discounts to rural residents. Proof of residence (e.g., utility bills, property tax records) may be required.
- Senior Discount Older drivers (typically 55+) who complete a state-approved defensive driving course (e.g., AARP’s Safe Driver Course) may receive discounts of 5–10%. Some insurers also offer age-based discounts for drivers over 65 with no recent accidents. Example: A 68-year-old completing the course could save $50–$150 annually.
- Pay-As-You-Drive (PAYD) or Usage-Based Insurance (UBI) Discounts Programs like Progressive’s Snapshot or Allstate’s Drivewise track driving habits (e.g., speed, braking, mileage) and offer discounts to safe drivers. Example: A driver who maintains a "safe" score (e.g., <50% hard braking) could earn a 10–25% discount. These programs require installing a telematics device or using a mobile app.
- New Car Discount Purchasing a new vehicle within a certain timeframe (e.g., 12–24 months) may qualify for discounts of 5–15%. Example: Buying a new Honda Civic within 6 months of its model year launch could result in a 10% discount from certain insurers. Proof of purchase (e.g., dealer invoice) is often required.
- Loyalty Discount Staying with the same insurer for a prolonged period (e.g., 3–5 years) can unlock loyalty discounts of 5–20%. Example: A policyholder with 5 years of continuous coverage might receive a 15% discount on their next renewal. Some insurers also offer "referral" discounts for bringing new customers to the company.
Bundling Policies: Reducing Costs Through Multi-Policy Discounts
Bundling auto insurance with other policies (e.g., homeowners, renters, or umbrella insurance) is one of the most effective ways to reduce overall premiums. Insurers offer multi-policy discounts to encourage customer loyalty and streamline administrative processes, often resulting in savings of 10–25% or more.The savings from bundling extend beyond the percentage discount. Consolidating policies with a single provider simplifies billing, claim filing, and customer service interactions. Additionally, insurers may offer exclusive discounts to bundled policyholders, such as priority claims processing or access to specialized coverage options.
<How Online Auto Insurance Comparison Tools Function
Online auto insurance comparison tools streamline the process of finding the best policy by leveraging technology to analyze market data, user inputs, and insurer offerings. These platforms collect and process vast amounts of information—ranging from personal details to vehicle specifications—to generate tailored quotes within seconds. The underlying mechanics involve proprietary algorithms that match user profiles against insurer databases, factoring in regional regulations, risk models, and historical claim data. Data collection forms the backbone of these tools. Users input core details such as age, driving history, location, and vehicle make/model, while some platforms integrate additional data points like credit scores (where legally permitted) or telematics data from connected devices. Algorithmic matching then cross-references this information with insurer pricing models, adjusting for variables like coverage tiers, deductibles, and optional endorsements. However, bias considerations loom large: historical biases in underwriting—such as racial or geographic profiling—can skew results if not mitigated by diverse training data or regulatory oversight. Transparency in algorithmic decision-making remains a critical gap, with some tools failing to disclose how risk scores are calculated or how discounts are applied.Data Collection Mechanisms
The accuracy and fairness of comparison tools hinge on the quality and breadth of data inputs. Most platforms rely on a combination of: - **User-provided data**: Directly entered via forms, including personal identifiers, driving records, and vehicle details. - **Third-party integrations**: APIs connecting to DMVs, credit bureaus (e.g., Experian, Equifax), or telematics providers (e.g., OBD-II devices tracking driving behavior). - **Public records**: Access to accident histories or traffic violations via state databases, though legal restrictions vary by jurisdiction. A notable example is the use of **zip code-level data** to estimate regional risk factors, though critics argue this can inadvertently penalize low-income or minority neighborhoods due to systemic biases in historical claim patterns. Some advanced tools now incorporate **geospatial analytics** to refine risk assessments by analyzing traffic density, crime rates, or road conditions within specific blocks, rather than relying solely on broader geographic averages.Algorithmic Matching and Risk Scoring
The core functionality of comparison tools lies in their ability to translate user inputs into risk profiles that insurers can evaluate. Proprietary scoring models—often developed in collaboration with actuaries—assign weights to variables such as: - **Demographics**: Age (young drivers face higher premiums due to inexperience), gender (historically, male drivers were statistically riskier in some regions, though this is being phased out in many markets). - **Driving behavior**: Miles driven annually, at-fault accidents, or DUI convictions, which directly correlate with claim likelihood. - **Vehicle characteristics**: Year, model, safety ratings (e.g., IIHS Top Safety Pick), and anti-theft features, which influence repair costs and theft risk.The **Fair Credit Reporting Act (FCRA)** in the U.S. requires insurers to obtain explicit consent before accessing credit-based insurance scores, which can impact premiums by up to 20% in some states. Tools that integrate this data must comply with FCRA guidelines to avoid legal repercussions.
Bias mitigation strategies vary by platform. Some employ **differential privacy techniques** to anonymize sensitive data during processing, while others conduct **audits of their scoring models** to identify and correct discriminatory patterns. For instance, a tool might flag if premiums for a specific postal code disproportionately increase due to a lack of representation in training data for that area.Bias Considerations and Ethical Challenges
Ethical concerns arise when algorithmic bias perpetuates historical inequities. A 2021 study by the **Consumer Financial Protection Bureau (CFPB)** found that credit-based insurance scores disproportionately affected minority groups, leading to higher premiums for similar risk profiles. Comparison tools must address: - **Data representation**: Ensuring training datasets include diverse populations to avoid generalizing from skewed samples. - **Explainability**: Providing users with insights into how their score was calculated, such as which factors contributed most to their premium. - **Regulatory compliance**: Adhering to laws like the **California Insurance Code § 10118.1**, which prohibits insurers from using arrest records in underwriting decisions. Tools that fail to address bias risk reinforcing systemic discrimination. For example, a tool that defaults to higher premiums for urban areas without accounting for socioeconomic factors may unfairly penalize residents of cities with higher crime rates but also lower income levels.Decade-Long Trends in Auto Insurance Pricing and Claim Dynamics
Over the past decade, auto insurance premiums have experienced significant volatility, driven by shifting risk factors, economic pressures, and technological disruptions. The average annual cost of auto insurance in the U.S. rose by **133%** from 2012 to 2023, according to the Insurance Information Institute (III), with regional disparities widening due to factors like urbanization, climate change, and legislative changes. Claim frequency and severity have also evolved, reflecting broader societal trends—such as increased distracted driving, higher medical inflation, and supply chain disruptions in vehicle repairs. The interplay between rising costs and claim behavior has forced insurers to recalibrate rate structures, often leading to higher deductibles, narrower coverage options, and more stringent underwriting criteria. Below, the key drivers behind these trends are examined, including economic influences, technological shifts, and regulatory shifts that have reshaped the industry. ---Rising Premiums and Claim Frequency Shifts
The trajectory of auto insurance costs has been marked by three distinct phases: **2012–2016 (stable growth)**, **2017–2019 (sharp increases)**, and **2020–present (volatile spikes)**. During the first phase, premiums grew at a steady **3–5% annually**, aligned with inflation and modest claim increases. The 2017–2019 surge was precipitated by: - **Distracted driving**: The rise of smartphones and social media led to a **14% increase in distracted driving fatalities** between 2010 and 2019 (NHTSA), elevating liability claims. - **Hailstorm damage**: Severe weather events, exacerbated by climate change, caused **$15 billion in insured losses in 2018 alone** (CoreLogic), pushing property damage claims upward. - **Medical inflation**: Hospital costs for auto-related injuries surged by **47% from 2010 to 2020** (Health Care Cost Institute), inflating bodily injury liability payouts. The pandemic period (2020–2021) introduced unique distortions: **premiums dropped by 10% in 2020** due to reduced mileage and fewer accidents, but rebounded sharply in 2021 as traffic resumed and supply chain bottlenecks drove repair costs to **20–30% above pre-pandemic levels** (AAA). By 2023, the average annual premium in the U.S. reached **$1,771**, with states like **Florida ($2,400)** and **Michigan ($3,500)** experiencing premiums **nearly double the national average**. ---How Insurers Communicate Rate Changes to Policyholders
Insurers use structured communication channels to inform policyholders about rate adjustments, blending regulatory requirements with strategic transparency to maintain trust. These notices serve dual purposes: legal compliance (e.g., adhering to state-specific notice periods) and risk management (mitigating policyholder dissatisfaction). The method and timing of communication vary by jurisdiction, insurer policies, and the nature of the rate change (e.g., general market adjustments vs. individual risk assessments). The justification for rate changes often hinges on three core pillars: **underwriting data**, **market conditions**, and **regulatory mandates**. Insurers provide supporting evidence through actuarial analyses, claims history, or external factors like inflation or legislative changes. For example, a 2022 study by the Insurance Information Institute (III) found that 60% of rate increases stemmed from inflation in repair costs, while 25% reflected higher frequency of claims in specific regions. Policyholders may receive these explanations via **mail notifications**, **digital portals**, or **in-app alerts**, with varying levels of detail.Notice Formats and Timing Requirements
Insurers typically follow state-specific rules for notifying policyholders of rate changes. In most U.S. states, a **30-day advance notice** is standard for individual policyholders, though some states (e.g., California) require **60 days** for significant adjustments. The notice must include: - **Effective date** of the change (e.g., "Your premium will increase by 12% effective January 15, 2024"). - **Reason for the change**, often categorized as: - *Claims experience*: Higher payouts in the insurer’s portfolio (e.g., a 30% spike in collision claims in your ZIP code). - *Market conditions*: Supply chain disruptions raising repair costs (e.g., a 20% increase in parts pricing for 2018–2020 model vehicles). - *Regulatory changes*: New laws altering coverage mandates (e.g., expanded uninsured motorist coverage in Texas). - *Individual risk factors*: Updated driving records or vehicle usage patterns (e.g., added nighttime driving or a DUI conviction). Notices may also reference **comparative benchmarks**, such as: > *"Your premium is 8% above the state average for drivers aged 25–34 with a clean record, due to higher theft rates in your county."*Digital vs. Physical Notices
Digital communication (emails, SMS, or insurer apps) dominates for efficiency, but physical mail remains critical for older demographics or policyholders with limited digital access. For instance: - **State Farm** sends digital notices via its app with a link to a **rate justification report**, while also mailing a condensed version to non-digital users. - **Geico** uses **automated phone calls** for urgent rate changes (e.g., a sudden claims surge in a policyholder’s area), followed by an email with detailed explanations.Common Gaps in Rate Justification Notices
Policyholders often cite three primary frustrations with rate change communications: 1. **Lack of granularity**: Notices may cite broad categories (e.g., "market conditions") without specifying how they apply to the individual policy. For example, a notice might state "inflation" without clarifying whether it pertains to labor costs, parts, or both. 2. **Inconsistent terminology**: Terms like "actuarial adjustments" or "risk-based pricing" lack plain-language explanations. A 2023 Consumer Federation of America report found that 42% of policyholders struggled to understand why their rates rose after a claim-free year. 3. **Retroactive explanations**: Some insurers provide justifications only after the rate change takes effect, leaving policyholders without time to seek alternatives. For instance, Progressive’s 2021 rate hikes for certain ZIP codes were justified post-facto via a **state filing**, not pre-notification.Regulatory Safeguards and Policyholder Rights
State insurance departments enforce transparency rules, such as: - **New York’s "Rate Filing Law"**: Requires insurers to submit detailed rate change proposals to the Department of Financial Services (DFS) for review, including actuarial memos and market data. - **California’s "Notice of Rate Change"**: Mandates insurers to explain how rate changes affect policyholders’ premiums, with penalties for non-compliance (up to $10,000 per violation). - **Federal Trade Commission (FTC) guidelines**: Prohibit insurers from using misleading terms like "standard premium" to obscure rate increases. Policyholders can request additional details from their insurer’s **state filing database** (e.g., [NAIC Rate Filing Search](https://www.naic.org/)) or file complaints with their state’s insurance regulator if notices are deemed insufficient.Visualizing Premium Allocation: Claims, Administration, and Profit Distribution in a $100 Auto Insurance Premium
Understanding how an auto insurance premium is structured provides clarity on where policyholder funds contribute most directly to coverage versus operational costs. A $100 premium is not uniformly distributed—it reflects the balance between claims payouts, administrative expenses, and insurer profitability, each serving distinct functions in the insurance ecosystem. The allocation of a $100 premium typically follows industry benchmarks, where claims adjusters, underwriting processes, and regulatory compliance absorb a significant portion. Below is a breakdown illustrating how these components interact to form the total premium, with variations depending on insurer efficiency and regional regulations.Claims Payouts: The Core Allocation
Claims processing constitutes the largest share of premium allocation, often ranging between **60% and 75%** of the total premium. This segment covers:- **Property damage claims** (e.g., collision repairs, comprehensive losses like theft or vandalism). For example, a $5,000 claim on a policy with a $100 monthly premium would theoretically require ~$60–$75 in premium revenue to cover the payout, adjusted for actuarial reserves and claim frequency.
- **Liability claims** (e.g., bodily injury or property damage to third parties). These are weighted higher in regions with stricter legal standards, such as no-fault states where insurers absorb broader liability risks.
- **Medical payments and personal injury protection (PIP)**. In states mandating PIP (e.g., Florida, New York), this category may account for **15–25%** of claims costs, reflecting healthcare inflation and administrative overhead for medical case management.
Administrative and Underwriting Costs: Operational Overhead
Administrative expenses encompass the operational infrastructure required to manage policies, assess risks, and process claims. These typically account for **15%–25%** of the premium and include:- **Underwriting and risk assessment** (e.g., evaluating driving records, vehicle history, and location data). Automated systems reduce costs but still require manual review for complex cases.
- **Customer service and policy management** (e.g., phone support, digital portals, and claims filing). Insurers with robust omnichannel support may allocate slightly higher percentages here to enhance customer retention.
- **Regulatory compliance and audits**. State-specific requirements (e.g., California’s Proposition 103) mandate transparency in rate filings, adding **3–8%** to administrative costs.
Profits and Contingency Reserves: Insurer Sustainability
The remaining **5–15%** of the premium funds insurer profitability, reinsurance costs, and reserves for future claims. This allocation varies by insurer type:- **Mutual insurers** (e.g., State Farm) may reinvest profits into policyholder dividends, reducing the profit margin to **5–10%** of the premium.
- **Stock insurers** (e.g., Allstate) typically retain **10–15%** as profit, reinvesting in market expansion or technology (e.g., AI-driven claims processing).
- **Reinsurance costs** (e.g., ceding a portion of high-risk policies to reinsurers) can absorb **3–7%** of premiums, especially in catastrophe-prone regions (e.g., hurricane zones in Florida).
**Actuarial Formula (Simplified):** *Premium = (Expected Claims Cost × Loss Ratio) + (Administrative Cost × Expense Ratio) + (Profit Margin × Reserve Factor)* Where: - **Loss Ratio** = Claims Payouts / Premiums (e.g., 70% in a stable market). - **Expense Ratio** = Administrative Costs / Premiums (e.g., 20% for efficient insurers). - **Reserve Factor** = Future claims reserves / Premiums (e.g., 10% for conservative insurers).
Regional Variations in Allocation
Premium allocation shifts based on geographic risk profiles:- **High-crime or urban areas** (e.g., Chicago) may see **claims costs rise to 80%** due to higher theft and collision frequencies, while administrative costs drop to **10%** as insurers streamline claims automation.
- **Rural areas** (e.g., Montana) might allocate **55% to claims** but **25% to administrative costs** due to lower claim volumes and higher per-policy service needs.
- **Natural disaster zones** (e.g., Texas) allocate **12–15%** to reinsurance, increasing the claims share to **75%** as insurers absorb catastrophic losses.
Anti-Discrimination Laws in Auto Insurance Rate Setting
Auto insurance pricing must adhere to strict legal frameworks to prevent discriminatory practices that could unfairly disadvantage certain groups. Insurers rely on actuarial data to assess risk, but these models must comply with federal and state laws prohibiting bias based on protected characteristics such as age, race, gender, or zip code. Courts and regulatory bodies scrutinize pricing algorithms for hidden discriminatory patterns, particularly when they disproportionately affect marginalized communities. The primary legal constraints include: - **Civil Rights Act of 1964**: Prohibits discrimination in insurance pricing based on race, color, religion, sex, or national origin. - **Fair Credit Reporting Act (FCRA)**: Regulates the use of credit scores and other consumer data to prevent unfair rate hikes tied to protected classes. - **State-specific fair access laws**: Many states (e.g., California, New York) mandate transparency in pricing methodologies to curb discriminatory outcomes.Regulatory Limits on Protected Characteristics
Insurers cannot directly use certain factors in rate calculations, even if statistically correlated with risk. For example: - **Age**: While younger drivers face higher premiums due to inexperience, insurers cannot apply age-based surcharges that disproportionately penalize older drivers (e.g., charging seniors more for medical claims). - **Race**: Courts have ruled that insurers cannot adjust rates based on zip codes that correlate with race, as seen in the *NAACP v. State Farm* case (2000), where State Farm’s geographic pricing was deemed discriminatory. - **Gender**: Some states (e.g., California) ban gender-based pricing, citing outdated actuarial assumptions about risk.Actuarial Justifications and Legal Scrutiny
Insurers argue that pricing models account for observable risk factors like driving history or vehicle type, not protected characteristics. However, regulators demand evidence that alternative methods exist to avoid bias. For instance: - **Credit scores**: Used as a proxy for risk, but insurers must prove no indirect discrimination occurs when credit-based models penalize lower-income groups disproportionately. - **Location-based pricing**: Insurers must demonstrate that geographic data reflects actual risk (e.g., crime rates) rather than demographic trends.Enforcement Mechanisms and Penalties
State insurance commissions investigate complaints and may impose penalties for discriminatory practices. Examples include: - **NAACP v. State Farm (2000)**: State Farm agreed to pay $1.5 million to settle claims that its pricing discriminated against African American and Hispanic drivers. - **New York’s Insurance Department (2021)**: Ordered insurers to review pricing algorithms for bias after finding that certain zip codes correlated with race led to higher premiums. - **California’s Fair Access to Insurance Requirements (FAIR) Plan**: Prohibits insurers from denying coverage or charging excessive rates based on protected characteristics.Indirect Discrimination and Mitigation Strategies
Even when insurers avoid direct discrimination, indirect practices can still violate anti-discrimination laws. For example: - **Zip code surcharges**: If a zip code’s high claim rates stem from socioeconomic factors (e.g., lack of maintenance due to financial constraints), insurers must justify that the data is risk-based, not discriminatory. - **Telematics data**: While usage-based insurance (UBI) tracks driving behavior, insurers must ensure the data collection does not disproportionately target or penalize certain groups (e.g., low-income drivers with older vehicles).Emerging Technologies and Hyper-Personalized Auto Insurance Rates
The integration of real-time telematics and artificial intelligence into auto insurance is accelerating the shift from static risk models to dynamic, behavior-based pricing. Insurers now collect vast datasets on driving habits, environmental conditions, and vehicle performance, enabling granular rate adjustments that reflect individual risk profiles with unprecedented precision. AI-driven predictive analytics will further refine this personalization by cross-referencing driving behavior with external factors like traffic patterns, weather forecasts, and even social media activity (e.g., location check-ins). This creates a feedback loop where premiums adjust in near real-time, incentivizing safer behavior while penalizing high-risk actions—such as aggressive acceleration or distracted driving—with immediate rate hikes. The result is a system where insurance costs become a dynamic reflection of both the insured’s individual risk and the evolving contextual risks of their environment.Real-Time Telematics and Behavioral Pricing
Telematics devices embedded in vehicles or mobile apps already track metrics like speed, braking patterns, and mileage, but future iterations will incorporate advanced sensors for physiological data (e.g., fatigue detection via steering wheel vibrations) and contextual awareness (e.g., detecting distracted driving via phone usage). Insurers will leverage machine learning to correlate these metrics with accident likelihood, adjusting rates intra-policy rather than annually. For example:- **Adaptive discounts**: Policies could offer real-time discounts for maintaining consistent, defensive driving habits, with rewards tied to milestones (e.g., "30 days of safe driving = 10% premium reduction").
- **Dynamic surcharges**: Sudden spikes in aggressive driving (e.g., rapid acceleration followed by hard braking) could trigger temporary rate increases until behavior stabilizes.
- **Contextual risk scoring**: AI might flag risks like driving in high-crash zones during peak hours, prompting insurers to offer temporary coverage adjustments or safety alerts.
AI and Predictive Risk Modeling
AI’s ability to process unstructured data—such as social media posts, credit scores, or even voice patterns—will introduce new variables into risk assessment. For instance:- **Psychometric risk profiling**: Voice analysis tools might detect stress or impulsivity in customer interactions, correlating these traits with higher accident risk. (Note: This requires explicit consumer consent and transparency about data usage.)
- **Predictive maintenance integration**: AI could analyze vehicle diagnostics to identify mechanical failures likely to cause accidents, prompting insurers to offer preventive maintenance discounts or adjust rates based on repair histories.
- **Micro-segmentation**: Policies might split into sub-categories like "urban commuters," "long-distance travelers," or "weekend recreational drivers," each with tailored rate structures and coverage options.
Auto insurance isn’t just a cost—it’s an investment in security, and the right policy can save you from financial strain in an accident. The key lies in demystifying how rates are determined, from the subtle impact of a rural vs. urban address to the long-term savings of bundling policies. By using digital tools wisely, negotiating discounts, and understanding regional and demographic factors, you can turn what feels like a daunting process into a strategic advantage. The future of auto insurance is evolving with technology, from AI-driven personalized rates to autonomous vehicles that may redefine liability. Staying informed today ensures you’re not just paying for coverage, but for the best possible value—now and as the industry changes. The right approach transforms confusion into control, turning every premium payment into a step toward smarter, more secure driving.

comprehensive car insurance comparison - YouTube
Note: California, Hawaii, Maryland, Massachusetts, and Oregon ban the use of credit scores for auto insurance pricing.
Frequently Asked Questions
How do I compare auto insurance rates online?
Use comparison websites like Policygenius or NerdWallet. Input vehicle details, coverage needs, and location. Request quotes from multiple insurers simultaneously for accurate rate comparisons. Ensure quotes reflect identical coverage limits for fair comparisons
Which factors most affect my auto insurance premium?
Key factors include driving record, age, gender, vehicle type, location, credit score, annual mileage, and coverage limits. Riskier profiles or high-value cars typically result in higher premiums due to insurer risk assessments
Are there discounts available when comparing auto insurance quotes?
Yes. Common discounts include safe driver, bundling policies, anti-theft devices, low mileage, and student/occupational discounts. Always ask insurers about available discounts during quote comparisons
How do regional differences impact car insurance costs?
Urban areas and high-crash regions often have higher rates due to increased risk. Rural areas or low-theft zones may offer lower premiums. Climate factors, like flood-prone areas, also influence regional pricing
Can my credit score lower my auto insurance rate?
In most states, yes. Insurers use credit-based insurance scores to assess risk. A higher score may qualify for lower rates, while a poor score can increase premiums. Check state laws, as some prohibit credit score use
How often should I compare auto insurance rates?
Compare rates annually or after major life changes (e.g., moving, marriage, or adding a driver). Rates fluctuate due to market trends, so periodic reviews ensure optimal coverage and cost efficiency
Related articles
Compare Auto Insurance Rates Smartly Today
Find the best auto insurance deals by comparing rates smartly—save money without sacrificing coverage. Compare Auto Insurance Rates Smartly Today for…

Auto Insurance Car Insurance Explained Simply
Understand Auto Insurance & Car Insurance Explained Simply—coverage types, costs, and how policies protect drivers. Get clear answers on liability,…

Auto Insurance For Business Vehicles Essentials And Solutions
Discover essential Auto Insurance For Business Vehicles Essentials And Solutions—coverage types, cost factors, and expert tips to protect your fleet…
Auto Insurance Comparison Tool Simplified Guide
Discover how an Auto Insurance Comparison Tool Simplified Guide helps you compare quotes fast, save money, and pick the best policy effortlessly—no…
Auto Insurance Comparison Quote Guide Key Insights
Get expert insights on comparing auto insurance quotes with this Auto Insurance Comparison Quote Guide Key Insights—save money, pick the best coverage,…
