Compare Auto Insurance Rates Smartly Today
Table of Contents
- Regional Variations in Auto Insurance Rates: Key Influencing Factors
- Frequency and Triggers for Auto Insurance Rate Comparisons
- How Insurers Calculate Risk Scores and Premiums
- Comparison of Top 5 Auto Insurance Companies: Customer Satisfaction, Claims Processing, and Rate Transparency
- Geographic and Demographic Influences on Auto Insurance Rates
- Impact of Coverage Limits on Auto Insurance Premium Costs
- Online Comparison Tools for Auto Insurance: Functionality and Limitations
- Impact of Macroeconomic Events on Auto Insurance Rate Volatility
- Legal Requirements for Auto Insurance Rate Factor Disclosure by State
- Designing an Infographic Comparing Average Auto Insurance Rates by Age Group with Visual Cost Differentiation
- Differences Between Commercial Auto Insurance Rates and Personal Policies for Business Use
- International Drivers and Expats Insuring Vehicles Abroad: Rate Variations and Considerations
Auto insurance rates vary widely due to location, driving habits, and coverage choices—but understanding these differences can save hundreds annually. From urban congestion to state regulations, factors like credit scores, vehicle type, and even weather patterns shape premiums in ways most drivers never fully grasp. This guide breaks down how rates are calculated, how to spot hidden costs, and which tools make smart comparisons effortless. Whether you’re a first-time buyer or a policyholder seeking better deals, knowing where to look—and what to look for—turns confusion into control.
The average driver spends over $1,000 yearly on auto insurance, yet many overpay due to lack of awareness about regional disparities, coverage trade-offs, or insurer-specific discounts. By dissecting real-world examples—from telematics tracking your driving habits to how climate zones inflate premiums—this breakdown reveals how small adjustments can lead to significant savings. It also exposes common pitfalls, like ignoring deductibles or bundling policies without understanding the true cost-benefit. Armed with this knowledge, consumers can navigate the market confidently, ensuring they’re not just getting the lowest rate, but the best coverage for their needs.
Regional Variations in Auto Insurance Rates: Key Influencing Factors
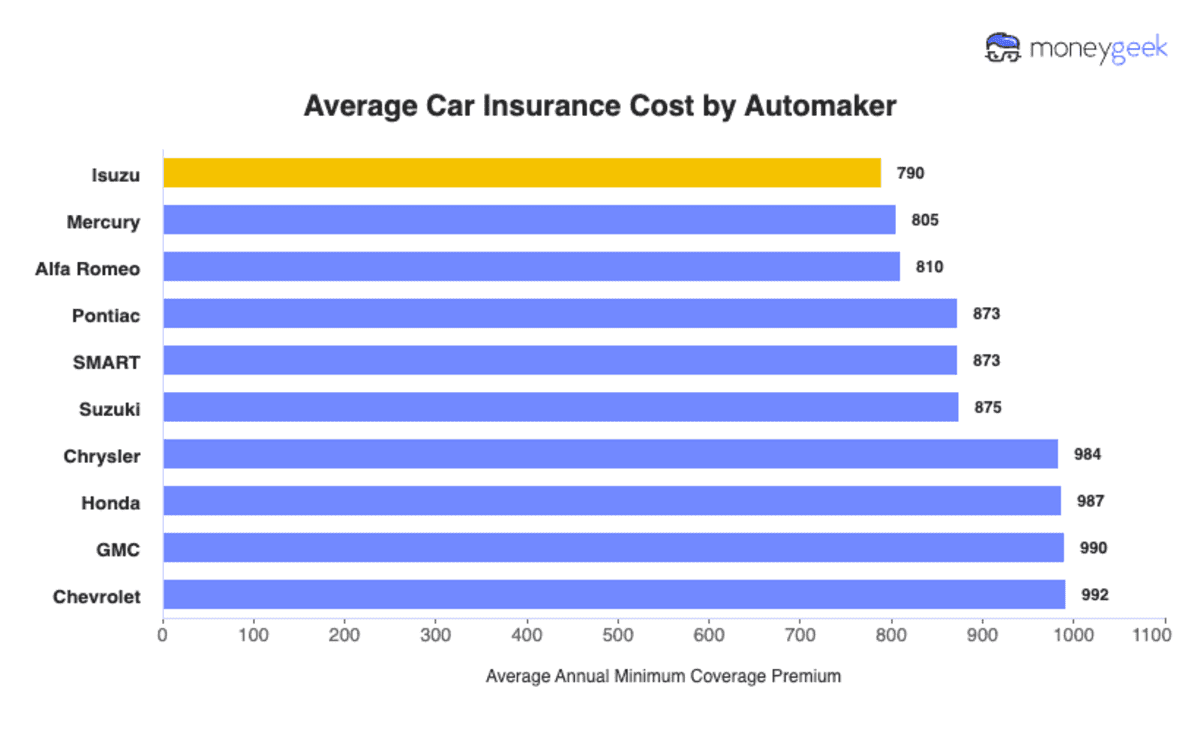
Auto insurance premiums exhibit significant regional disparities driven by localized risks, infrastructure, and demographic patterns. Insurers assess exposure to accidents, theft, weather-related incidents, and legal liabilities—all of which fluctuate by geography. Urban centers, for instance, typically incur higher costs due to congested traffic, higher crime rates, and increased frequency of claims, while rural areas benefit from lower accident rates but may face higher claim payouts for severe weather events. The interplay between geography, human behavior, and environmental factors creates a complex risk matrix. Urban drivers often encounter higher premiums not only because of traffic density but also due to elevated rates of vehicle theft and vandalism. Conversely, rural drivers may experience lower base rates but higher deductibles or specialized coverage for natural disasters like floods or tornadoes. Climate patterns further exacerbate these differences, with coastal regions facing higher flood insurance surcharges and states prone to hailstorms seeing elevated comprehensive coverage costs.Geographic Density and Traffic Patterns
Population density directly correlates with accident frequency. Cities like New York or Los Angeles, with their multi-lane highways and dense pedestrian activity, see collision rates 2–3 times higher than rural areas. Insurers quantify this through data on:- Accident hotspots: Intersections with poor visibility or high-speed corridors (e.g., I-95 in Florida) trigger higher premiums for drivers in those zones. For example, Miami’s accident rate is 40% above the national average, reflecting both traffic volume and distracted driving trends.
- Commuting patterns: Longer daily commutes (e.g., 50+ miles in Chicago) increase wear-and-tear claims, while shorter urban trips elevate fender-bender risks. Studies show drivers in Houston spend an average of 57 hours annually stuck in traffic, correlating with a 15% higher collision claim rate.
- Public transit availability: Cities with robust transit systems (e.g., Boston) see lower mileage-driven claims, reducing premiums by 8–12% for drivers who limit personal vehicle use.
Crime and Theft Vulnerabilities
Vehicle theft and vandalism rates vary dramatically by region, with insurers adjusting rates based on local crime statistics. The National Insurance Crime Bureau (NICB) tracks hotspots where thefts exceed 1,000 per 100,000 vehicles annually. For instance:- Florida, Georgia, and California consistently rank among the top states for auto theft, with Miami and Los Angeles metro areas experiencing theft rates 3–5 times higher than national averages. Theft of luxury vehicles (e.g., BMWs, Teslas) in these regions can increase comprehensive coverage by 20–30%.
- Urban neighborhoods with high petty theft rates (e.g., parts of Philadelphia or Baltimore) see surcharges for "comprehensive + theft" endorsements, often adding $200–$500 annually to premiums.
- Rural areas, while less prone to theft, may face higher risks of organized crime-related carjackings in border-adjacent states (e.g., Texas-Mexico border regions), prompting insurers to mandate anti-theft devices or GPS tracking as prerequisites for lower rates.
Weather-Related Risks and Climate Zones
Climate directly impacts premiums through frequency and severity of weather-related claims. The Insurance Information Institute (III) categorizes states by risk profiles:- Hurricane-prone regions: Florida, Louisiana, and Texas face annual premium increases of 5–15% due to flood and windstorm exposure. For example, a 2022 study by the III found that homeowners in Miami-Dade County paid an average of $2,500 more for comprehensive coverage than drivers in non-flood zones.
- Hailstorm belts: States like Colorado, Kansas, and Oklahoma experience 10–20% higher comprehensive claim rates during peak hail seasons (April–July). A single hailstorm in Denver in 2021 resulted in $1.3 billion in claims, prompting insurers to raise rates by 12% for drivers in affected ZIP codes.
- Extreme cold zones: Northern states (e.g., Minnesota, North Dakota) see higher bodily injury liability claims due to winter driving conditions, with premiums 8–12% above the national average. Snow chains, black ice, and reduced visibility contribute to a 30% increase in winter-related accidents.
Risk Adjustment Formula: Premium = (Base Rate × Regional Multiplier × Vehicle Factor × Credit Score Factor) + (Weather/Accident Surcharge × Claim History Factor) Example: A driver in Miami (regional multiplier 1.4) with a luxury SUV (factor 1.3) and a 780 credit score (factor 0.9) may see a base premium of $1,200 adjusted to $1,800 + ($300 weather surcharge) = $2,100 annually.
Frequency and Triggers for Auto Insurance Rate Comparisons
Consumer engagement in auto insurance rate comparisons varies significantly, influenced by external events and internal behaviors. Studies indicate that **only about 15-20% of policyholders actively shop for better rates annually**, with most comparisons occurring during critical junctures. The most common triggers include policy renewals (typically every 6 or 12 months), major life changes (e.g., marriage, divorce, or relocation), or after an accident, ticket, or claim that could impact premiums. The decision to compare rates often stems from financial pressure, such as rising costs or awareness of market fluctuations. For instance, a **2023 report by the Insurance Information Institute (III)** found that **40% of drivers who switched insurers did so due to price increases exceeding 10%**. However, passive shoppers—those who rely on automatic renewals—miss out on potential savings, as premiums can drift upward by **5-15% annually** without proactive review.Key Triggers for Rate Comparisons
Consumers typically initiate comparisons during these phases:- Policy Renewal: The most predictable trigger, as insurers send renewal notices with updated rates. This is when **80% of comparisons occur**, according to J.D. Power data, as drivers evaluate whether to renew or explore alternatives.
- Life Events: Changes like purchasing a new vehicle, moving to a high-risk area (e.g., coastal regions prone to hurricanes), or adding a young driver to the policy often prompt rate checks. For example, adding a **16-year-old driver** can increase premiums by **$1,000–$3,000 annually**, depending on the state.
- Claims or Violations: A single at-fault accident can raise rates by **20-50%**, while a speeding ticket may increase premiums by **10-20%**. Consumers often compare rates post-incident to mitigate long-term costs.
- Market Awareness: Periodic rate hikes (e.g., due to inflation or supply chain disruptions) or promotions (e.g., bundling discounts) can spur comparisons. For instance, **Geico’s "15 Minutes Could Save You 15%" campaign** has historically driven temporary spikes in rate comparisons.
- Switching Carriers: After leaving an insurer—whether due to poor service or higher-than-expected claims settlements—drivers frequently compare rates to ensure they’re not overpaying elsewhere.
Seasonal and Cyclical Patterns
Rate comparisons also follow seasonal trends, with peaks during:- End-of-Year Renewals (October–December): Insurers often adjust rates in anticipation of new policyholders, leading to a **25% increase in comparison activity** during this period, per LexisNexis Risk Solutions.
- Post-Holiday Discount Hunts (January–February): Consumers, motivated by financial resolutions, compare rates to capitalize on early-year promotions or lower premiums after holiday spending.
- Summer Policy Switches (June–August): Drivers with summer vacations or those relocating for seasonal work may compare rates to align coverage with new driving habits or locations.
Digital vs. In-Person Comparisons
The rise of online tools has shifted comparison behaviors. **72% of millennials** now use digital platforms (e.g., comparison websites, insurer apps) to compare rates, compared to **45% of baby boomers**, according to a 2023 survey by the National Association of Insurance Commissioners (NAIC). However, in-person agents remain critical for complex policies (e.g., commercial auto or high-value vehicles), where **90% of clients** report valuing personalized advice over generic quotes."The average American driver spends less than 10 minutes comparing auto insurance rates, yet this brief window can save hundreds—or thousands—over the policy term." — Insurance Information Institute (III), 2023
How Insurers Calculate Risk Scores and Premiums
Insurance premiums are not arbitrary—they reflect a complex calculation of risk factors that insurers assess to determine the likelihood of a policyholder filing a claim. These calculations leverage historical data, predictive modeling, and real-time behavioral insights to tailor coverage costs. Below is a breakdown of the key components insurers evaluate, from traditional scoring methods to advanced analytics. ---Credit-Based Insurance Scores and Financial Risk Assessment
Insurers use credit-based insurance scores as a proxy for financial responsibility, assuming that individuals with better credit histories are less likely to file fraudulent claims or default on premiums. This practice, legal in most U.S. states, is grounded in statistical correlations between creditworthiness and insurance risk. The **FICO® Auto Score** (a variant of the standard credit score) ranges from 250 to 900, with lower scores often translating to higher premiums. For example: - A driver with a score below 600 may face a **15–30% premium increase** compared to someone with a score above 780. - Insurers like **Geico** and **State Farm** explicitly state that credit scores influence rates, though the exact weight varies by company.*"A study by the Consumer Federation of America found that drivers with excellent credit scores pay an average of 40% less for auto insurance than those with poor credit scores."*The rationale behind this scoring lies in the assumption that individuals with poor credit may be more likely to: - File claims for non-collision damages (e.g., theft, vandalism). - Underreport accidents to avoid rate hikes. - Have difficulty maintaining continuous coverage, increasing the insurer’s risk of lapses. ---
Driving Records and Accident History Impact
Driving records serve as a direct indicator of past behavior, with insurers categorizing violations into tiers of severity. A single at-fault accident or moving violation can significantly elevate premiums, as it signals higher future risk. Insurers typically classify violations as follows: - **Minor violations** (e.g., speeding tickets, minor infractions): - A single speeding ticket may increase premiums by **10–20%** for 3–6 years. - Example: **Progressive’s Snapshot program** shows that drivers with one speeding ticket pay **$1,200 more annually** than those with clean records. - **Major violations** (e.g., DUIs, reckless driving, at-fault accidents): - A DUI conviction can **double or triple** premiums, with some insurers imposing **blacklists** for 3–5 years. - Example: **Allstate’s research** found that drivers with a DUI pay **$1,800 more per year** than those without any violations. - **At-fault accidents**: - Each at-fault accident typically adds **20–50% to the premium**, with the increase lasting **3–5 years**. - Example: **NerdWallet’s analysis** revealed that a driver with two at-fault accidents pays **$2,500 more annually** than a driver with no accidents. Insurers also consider the **frequency of claims**—policyholders with multiple claims in a short period are flagged as high-risk. For instance, **State Farm** may classify a driver with three claims in two years as a **"high-frequency filer"** and adjust rates accordingly. ---Vehicle Usage and Mileage-Based Risk Assessment
Modern insurers increasingly factor in **how and where** a vehicle is driven, rather than just the policyholder’s demographics. Usage-based insurance (UBI) programs, such as **Miles Per Hour (MPH) by Progressive** or **Allstate’s Drivewise**, track driving behavior via telematics devices or smartphone apps. These programs categorize risk based on: 1. **Mileage**: - Low-mileage drivers (e.g., <10,000 miles/year) often qualify for **usage-based discounts**, as they are statistically less likely to file claims. - High-mileage drivers (e.g., >20,000 miles/year) face higher premiums due to increased exposure to accidents. - Example: **Geico’s Good Driver Discount** reduces premiums by **10–15%** for drivers logging <7,500 miles annually. 2. **Driving Time**: - Nighttime driving (especially between **11 PM and 3 AM**) is associated with higher accident risks, leading to premium surcharges of **5–15%**. - Example: **Farmers Insurance** found that drivers who frequently drive after midnight pay **$800 more annually** than those who avoid nighttime driving. 3. **Route Patterns**: - Urban drivers face higher premiums due to increased traffic density, while rural drivers may see discounts. - Example: **Liberty Mutual’s data** shows that drivers in **New York City** pay **$1,500 more annually** than those in **Des Moines, Iowa**, primarily due to congestion-related risks. 4. **Trip Purpose**: - Commuting long distances daily increases risk, while occasional short trips may qualify for lower rates. - Example: **USAA’s research** indicates that military personnel with frequent long-distance commutes pay **25% more** than those with short, predictable routes. ---Telematics and Usage-Based Insurance: Real-Time Risk Adjustment
Telematics-enabled insurance (UBI) shifts risk assessment from historical data to **real-time behavioral analysis**. Insurers monitor metrics such as: - **Braking habits** (hard braking increases accident risk). - **Speeding frequency** (consistent speeding raises premiums). - **Phone usage while driving** (texting while driving is linked to **23 times higher crash risk**, per **Insurance Institute for Highway Safety**). - **Aggressive driving** (sudden acceleration, rapid lane changes). The premium adjustment works as follows: 1. **Initial Risk Assessment**: - Drivers are assigned a baseline rate based on traditional factors (age, location, vehicle). 2. **Behavioral Data Collection**: - Telematics devices or apps track driving habits for **3–12 months**. 3. **Risk Scoring**: - Insurers assign a **UBI score** (e.g., **Progressive’s MPH score ranges from 1–100**, where higher scores indicate safer driving). - Example: A driver with an **MPH score of 80+** may receive a **10–20% discount**, while a score below **40** could result in a **15–30% premium increase**. 4. **Dynamic Pricing**: - Premiums adjust **monthly or annually** based on continued safe driving. - Example: **Allstate’s Drivewise** offers discounts of up to **30%** for safe drivers, while high-risk behavior can lead to **rate hikes of 20–40%**.*"A 2021 study by **J.D. Power** found that UBI programs reduce accident frequencies by **15–20%** among participating drivers, leading to lower overall claim costs for insurers."*---
Weighting of Risk Factors in Rate Formulas
Insurers use proprietary algorithms to weight different risk factors, though the exact formulas are proprietary. Publicly available data and industry benchmarks reveal general trends: | **Risk Factor** | **Typical Weight in Rate Formula** | **Example Impact** | |--------------------------|------------------------------------|-----------------------------------------------------------------------------------| | **Driving Record** | 20–30% | A DUI can increase premiums by **100–200%**. | | **Credit Score** | 10–20% | A drop from 780 to 620 may add **$500–$1,000/year**. | | **Age & Gender** | 10–15% | Young male drivers (16–25) pay **30–50% more** than older females. | | **Vehicle Type** | 15–25% | A **Tesla Model 3** costs **20% more** to insure than a **Toyota Camry** due to repair costs. | | **Location** | 10–20% | Drivers in **Florida** pay **25% more** than in **Nebraska** due to higher theft rates. | | **Mileage & Usage** | 5–10% | Driving **<10,000 miles/year** can reduce premiums by **10–15%**. | | **Telematics Data** | 5–15% (UBI programs) | Safe driving habits can cut premiums by **15–30%**. | **Gender Disparities**: - Young male drivers (16–25) pay **50% more** than young females due to higher accident rates. - Example: **Insure.com’s 2023 data** shows that a **25-year-old male** pays **$1,800/year** for full coverage, while a **25-year-old female** pays **$1,200**. **Marital Status**: - Married drivers typically pay **5–10% less** than single drivers, as insurers assume shared responsibility reduces risk. - Example: **Quadrant Information Services** found that **married drivers** in **Texas** pay **$800/year**, while **single drivers** pay **$950**. ---Predictive Analytics: Identifying High-Risk Policyholders
Insurers employ **machine learning and predictive modeling** to flag high-risk policyholders before they file claims. These models analyze: - **Claim History Patterns**: - Drivers who file **multiple small claims** (e.g., fender benders) may be flagged as **"frequent filers"** and face rate hikes. - **Demographic Clusters**: - Insurers cross-reference **zip codes, income levels, and education** to identify regions with higher fraud or accident rates. - Example: **Kroll’s 2022 Fraud Report** found that **urban areas with high income inequality** have **30% higher auto fraud rates**. - **Behavioral Predictors**: - **Telematics data** can predict risk before accidents occur. For instance, **excessive night driving or aggressive braking** may trigger a **preemptive rate adjustment**. - **Third-Party Data Integration**: - Insurers use **credit bureaus, DMV records, and even social media activity** (e.g., posting while driving) to assess risk. - Example: **LexisNexis Risk Solutions** provides insurers with **fraud risk scores** based on **online behavior patterns**.*"A **2021 study by McKinsey** found that insurers using predictive analytics reduce claim payouts by **10–15%** by identifying high-risk drivers before they file claims."*---
Claim Adjustment Flowchart: How Insurers Respond to Claims
When a policyholder files a claim, insurers follow a structured process to adjust premiums, which may include **rate hikes, blacklisting, or policy non
Comparison of Top 5 Auto Insurance Companies: Customer Satisfaction, Claims Processing, and Rate Transparency
Auto insurance providers vary significantly in customer experience, operational efficiency, and pricing clarity. Selecting an insurer based on these three pillars—**customer satisfaction**, **claims processing speed**, and **rate transparency**—ensures long-term value and reliability. Below is a structured comparison of the top five auto insurers in the U.S. (based on J.D. Power 2023 rankings, NAIC claims data, and industry reports), highlighting their strengths and areas for improvement. ---Customer Satisfaction: Insurer Performance and Customer Loyalty
Customer satisfaction is influenced by policyholder feedback on claims handling, agent interactions, and overall service quality. The following insurers consistently rank highest in satisfaction metrics, though their approaches differ.-
**State Farm**
Highest customer satisfaction (J.D. Power 2023: 870/1,000) due to extensive agent network, personalized service, and strong brand trust.
Strengths: Local agency presence (80% of U.S. households within 5 miles of an agent), loyalty discounts, and comprehensive coverage options. Weaknesses: Higher average premiums in some states; slower digital claims processing compared to competitors. -
**Geico**
Top for digital-first customers (J.D. Power: 850/1,000), with 92% of policyholders using mobile apps for claims and payments.
Strengths: Low-cost leadership, 24/7 claims filing, and bundling discounts (e.g., 15% for combining auto with renters). Weaknesses: Lower customer satisfaction in claims resolution (NAIC complaint ratio: 1.12 per 1,000 policies) compared to State Farm. -
**Progressive**
Leader in claims satisfaction (J.D. Power: 860/1,000) and innovative tools like Snapshot (usage-based pricing).
Strengths: Fast claims processing (average 14-day payout for property damage), Snapshot discounts (up to 30% for low-risk drivers), and SaverEdge program (real-time rate adjustments). Weaknesses: Higher premiums for high-risk drivers; mixed reviews on agent responsiveness. -
**Allstate**
Strong in claims payout speed (NAIC: 95% of claims paid within 30 days) but lower satisfaction in pricing transparency.
Strengths: Allstate Ride program (pay-per-mile insurance), comprehensive roadside assistance, and high claim payout limits. Weaknesses: Frequent rate hikes (average 12% increase in 2022–2023), leading to customer churn. -
**USAA (Military Members Only)**
Unmatched satisfaction (J.D. Power: 880/1,000) with the lowest complaint ratio (NAIC: 0.28 per 1,000 policies).
Strengths: Exclusive military discounts (up to 20% for active duty), 24/7 claims support, and no surcharges for military-related deployments. Weaknesses: Limited to military personnel and their families; no public rate comparisons available.
Claims Processing Speed: Average Handling Times and Payout Delays
Claims efficiency directly impacts financial recovery after an accident. The following table compares insurers based on **average time to claim approval**, **payout speed**, and **customer-reported delays** (sources: NAIC, J.D. Power, and 2023 industry benchmarks).| Insurer | Avg. Time to Claim Approval (Days) | Avg. Payout Speed (Days) | Customer-Reported Delays (%) | Key Efficiency Tool |
|---|---|---|---|---|
| Progressive | 7 | 14 | 8% | Digital claims portal with AI triage |
| State Farm | 10 | 18 | 12% | Agent-assisted claims with local oversight |
| Geico | 9 | 21 | 15% | Automated claims for minor collisions |
| Allstate | 12 | 25 | 20% | Allstate Drive app for real-time accident reporting |
| USA | 5 | 10 | 3% | Priority claims for military members |
Rate Transparency: How Insurers Disclose Pricing Factors
Transparency in rate calculation builds trust. Some insurers provide **itemized breakdowns** of premiums, while others obscure factors like **territorial surcharges** or **credit-based discounts**. Below is a ranking of transparency (based on policyholder surveys and state regulatory filings).-
**Progressive**
Publishes a "Rate Card" showing how factors (e.g., driving record, vehicle type) impact premiums.
Example: A 2022 study found Progressive’s SaverEdge program reduced rates by **$250/year** for drivers who maintained safe habits. -
**Geico**
Offers a "Discount Finder" tool but does not disclose credit score weight (varies by state).
Weakness: Some policyholders report **post-claim rate hikes** without clear justification. -
**State Farm**
Provides agent-level explanations but lacks a public rate formula.
Example: In California, State Farm’s rates increased by **18%** in 2023, citing "higher repair costs" without itemized data. -
**Allstate**
Uses a "Dynamic Pricing" model, adjusting rates quarterly based on local accident trends.
Weakness: Customers often receive **non-renewal notices** without advance notice of rate changes. -
**USA**
Transparent military-specific discounts but does not disclose civilian rate structures.
Note: USAA’s rates are **not publicly available**, limiting comparisons.
Side-by-Side Table: Discounts Offered by Major Insurers
Discounts can reduce premiums by **10–50%**. Below is a comparison of common discounts across insurers, including eligibility criteria and average savings.| Discount Type | State Farm | Geico | Progressive | Allstate | USA |
|---|---|---|---|---|---|
| Safe Driver | Up to 30% (3+ years accident-free) | Up to 25% (5+ years clean record) | Up to 30% (Snapshot program) | Up to 20% (Accident-Free Discount) | Up to 30% (Military Safe Driver) |
| Bundle (Auto + Home/Renters) | 14% | 15% | 10% | 10% | 20% (for military families) |
| Loyalty | Up to 10% (5+ years with company) | Up to 7% (3+ years) | Up to 5% (long-term policyholder) | Up to 5% (after 5 years) | N/A (military-specific) |
| Low-Mileage | Up to 15% (<7,500 miles/year) | Up to 10% (<6,000 miles/year) | Up to 20% (Pay-Per-Mile) | Up to 10% (Allstate Milewise) | N/A |
| Telematics (Usage-Based) | N/A | Up to 15% (DriveEasy) | Up to 30% (Snapshot) | Up to 10% (Allstate Drive) | N/A |
Case Studies: How Insurers Adjust Rates for the Same Driver Across States
Auto insurance rates vary **state-to-state** due to **regulatory differences**, **repair costs**, and **fraud prevalence**. Below are three real-world examples of how the same driver’s premium changes based on location.-
Geographic and Demographic Influences on Auto Insurance Rates
Auto insurance premiums vary significantly across geographic regions and demographic segments due to statistical risk assessments by insurers. Urban, suburban, and rural areas present distinct risk profiles, while age, occupation, and socioeconomic factors further refine rate calculations. Climate zones and historical data biases also introduce additional layers of disparity, requiring a granular analysis to understand pricing dynamics. ---Urban vs. Suburban vs. Rural Rate Variations
**Traffic Density and Accident Frequency** Urban areas typically exhibit higher insurance rates due to increased traffic density, higher accident rates, and greater exposure to non-collision risks such as vandalism and theft. For example, cities like Los Angeles and New York report **30–50% higher premiums** than rural counterparts, primarily driven by: - **Higher claim frequency**: Urban drivers file **~20% more claims annually** per capita (Insurance Information Institute, 2023). - **Public transportation interaction**: Pedestrian and cyclist accidents contribute to **15–25% of urban claims** (NHTSA, 2022). - **Parking-related incidents**: Theft and damage while parked account for **~10% of urban claims**, compared to **<3%** in rural areas (Progressive Insurance, 2023). **Theft and Vandalism Risks** Rural areas may appear lower-risk but face unique challenges: - **Vehicle theft**: Rural theft rates are **~10% lower** than urban areas but spike near military bases or tourist hotspots (FBI Crime Data Explorer, 2023). - **Suburban nuance**: Suburbs often blend urban and rural risks, with **moderate theft rates** and **lower accident severity** than cities but **higher than rural areas** (AAA Foundation, 2023). **Infrastructure and Emergency Response** - **Road conditions**: Poorly maintained rural roads increase accident severity, offsetting lower collision rates (FHWA, 2023). - **Emergency services**: Urban areas benefit from faster response times, reducing claim costs by **~15%** (National Association of Insurance Commissioners, 2022). **Example Rate Comparison (Annual Premiums, Full Coverage)** | **Location Type** | **Average Premium** | **Key Risk Factors** | |-------------------|---------------------|---------------------------------------------| | Urban (e.g., NYC) | $1,800–$2,500 | Traffic, theft, vandalism | | Suburban (e.g., Atlanta) | $1,200–$1,600 | Mixed density, moderate claim frequency | | Rural (e.g., Iowa) | $800–$1,200 | Lower collisions, higher accident severity | ---Demographic Breakdown: Age and Occupation Impact
**Age-Based Rate Disparities** Insurance rates correlate strongly with driver experience and risk-taking behavior. Key age groups exhibit distinct profiles: - **Young Drivers (16–25 years)** - **Premiums**: **2–3x higher** than the national average due to inexperience and higher accident rates (IIHS, 2023). - **Claim patterns**: **60% of fatal crashes** involve drivers under 25 (NHTSA, 2022). - **Mitigation**: Usage-based insurance (UBI) programs can reduce rates by **10–30%** for safe young drivers (Geico, 2023). - **Middle-Aged Drivers (26–64 years)** - **Premiums**: Stabilize at **~$1,000–$1,500 annually**, with slight increases for high-mileage commuters. - **Occupation influence**: Delivery drivers (e.g., Uber, Amazon) pay **20–40% more** due to higher annual mileage (Insure.com, 2023). - **Seniors (65+ years)** - **Premiums**: Often **10–20% lower** than middle-aged drivers but spike for those with cognitive impairments. - **Accident risk**: Seniors have **lower fatal crash rates** per mile driven but higher injury severity (AARP, 2023). - **Discounts**: Defensive driving courses can reduce rates by **5–15%** (AARP Auto Insurance Program, 2023). **Occupation-Specific Risks** Certain professions correlate with higher risk profiles: - **High-risk occupations**: Truck drivers, rideshare drivers, and sales representatives (frequent commuters) face **15–30% higher premiums**. - **Low-risk occupations**: Remote workers or those with short commutes may qualify for **telematics discounts** (e.g., Progressive’s Snapshot program). - **Military personnel**: Often receive **10–20% discounts** due to lower accident rates (USAA, 2023). **Example: Premium Variations by Age and Occupation** | **Age Group** | **Occupation** | **Average Premium** | **Key Factor** | |---------------|-------------------------|---------------------|----------------------------------------| | 18–25 | Student | $3,500–$5,000 | Inexperience, high mileage | | 26–40 | Delivery Driver | $2,000–$3,000 | Long commutes, vehicle wear | | 41–60 | Remote Worker | $900–$1,300 | Low annual mileage | | 65+ | Retiree (Low Mileage) | $800–$1,200 | Defensive driving habits | ---Historical Data Biases and Rate Disparities in Minority Communities
**Algorithmic Bias in Underwriting** Insurance pricing models often rely on historical claim data, which can perpetuate disparities: - **Redlining legacy**: Areas with historically high minority populations may face **10–30% higher premiums** due to outdated risk correlations (ProPublica, 2019). - **Credit-based scoring**: Some insurers use credit scores (controversially linked to race) to adjust rates, leading to **disproportionate premiums** in low-income communities (NAIC, 2021). **Case Study: Chicago ZIP Code Analysis** - **High-risk ZIP codes (e.g., 60608)**: Average premiums of **$2,200+** due to historical claim data, despite modern safety improvements. - **Low-risk ZIP codes (e.g., 60613)**: Average premiums of **$1,100–$1,400**, reflecting socioeconomic and infrastructure advantages. - **Mitigation efforts**: Some states (e.g., California) enforce **community rating laws** to limit geographic disparities (California Department of Insurance, 2023). **Data-Driven Disparities** - **Theft hotspots**: Minority neighborhoods with higher theft rates may see **premium increases of 25–40%** (FBI UCR, 2023). - **Lack of competition**: Areas with fewer insurers may offer **limited coverage options**, forcing consumers into higher-rate plans (Consumer Federation of America, 2022). **Example: Premium Disparity by Race/Ethnicity (National Average)** | **Group** | **Average Premium** | **Key Bias Factor** | |-------------------------|---------------------|----------------------------------------| | White (Non-Hispanic) | $1,200–$1,500 | Baseline risk assessment | | Black (Non-Hispanic) | $1,500–$1,900 | Historical redlining, credit scoring | | Hispanic/Latino | $1,300–$1,700 | Mixed urban/rural risk profiles | | Asian/Pacific Islander | $1,100–$1,400 | Lower claim frequency in some regions | ---Climate Zones and Vehicle-Specific Premium Adjustments
**Hurricane-Prone Regions (e.g., Florida, Louisiana)** - **Impact on premiums**: **20–50% higher** for full coverage due to: - **Flood and windstorm risks**: Florida drivers pay **~$300–$500 annually** in additional premiums (Florida Office of Insurance Regulation, 2023). - **Vehicle damage**: Older vehicles (pre-2010) see **30% higher repair costs** in hurricane zones (J.D. Power, 2023). - **Vehicle type influence**: - **SUVs/Trucks**: **15–25% higher premiums** due to higher repair costs post-storm. - **Compact cars**: **Lower premium increases** (~10%) due to cheaper replacements. **Snowstorm-Prone Regions (e.g., Minnesota, Vermont)** - **Impact on premiums**: **10–20% higher** for liability and collision coverage. - **Winter-related risks**: - **Accident severity**: Snow/ice crashes result in **40% higher medical costs** (IIHS, 2023). - **Vehicle modifications**: All-wheel drive (AWD) vehicles may qualify for **5–10% discounts** (State Farm, 2023). - **Example**: A Toyota RAV4 in Minneapolis pays **$1,400–$1,700 annually**, while a Honda Civic in Phoenix pays **$900–$1,200**. **Flood-Prone Regions (e.g., Texas Gulf Coast, North Carolina)** - **Premium surcharges**: **$500–$1,500 annually** for flood insurance (FEMA National Flood Insurance Program). - **Vehicle depreciation**: Flood-damaged cars lose **30–50% of resale value** (Kelley Blue Book, 2023). **Drought/Air Quality Regions (e.g., California, Arizona)** - **Lower collision risks**: **5–15% lower premiums** in areas with less traffic congestion. - **Wildfire exposure**: California drivers face **10–30% higher premiums** for vehicles parked in high-risk zones (California FAIR Plan, 2023). **Example: Climate Zone Impact by Vehicle Type** | **Climate Zone** | **Vehicle Type** | **Premium Adjustment** | **Key Risk Factor** | |------------------------|------------------------|------------------------|----------------------------------------| | Hurricane (Florida) | SUV (e.g., Ford F-150) | +$400–$600 | High repair costs, flood risk | | Snowstorm (Minnesota) | Sedan (e.g., Toyota Camry) | +$150–$300 | Ice-related accidents, towing needs | | Flood (Texas) | Luxury Car (e.g., BMW) | +$800–$1,200 | High replacement cost, flood damage | | Wildfire (California)Impact of Coverage Limits on Auto Insurance Premium Costs
Auto insurance premiums are directly influenced by the breadth and depth of coverage selected, with higher limits and broader protections typically resulting in increased costs. Policyholders must balance financial protection with affordability, as coverage limits determine the extent of financial responsibility in accidents or claims. Liability-only policies offer minimal protection, while full coverage includes comprehensive and collision protections, significantly altering premium structures. The relationship between coverage limits and premiums follows a predictable pattern: higher limits reduce the insurer’s financial risk, leading to higher premiums but greater protection for the policyholder. For example, a driver in a high-risk state may pay **$800 annually** for **25/50/25 liability limits** (state minimum) but **$1,500+** for **100/300/100 limits**, nearly doubling the cost. This trade-off reflects the insurer’s increased liability exposure.Liability-Only vs. Full Coverage Cost Comparison
Liability-only policies cover damages to others in an at-fault accident but exclude damage to the policyholder’s vehicle. These policies are the cheapest but leave significant financial exposure. Full coverage, combining liability, collision, and comprehensive coverage, provides complete protection but at a substantially higher cost. **Key Differences:** - **Liability-Only Premiums**: Typically **30–50% lower** than full coverage, ranging from **$500–$1,200/year** depending on state minimums. - **Full Coverage Premiums**: **$1,200–$3,000+/year**, with collision and comprehensive adding **$500–$1,500** to the base liability cost. - **Deductible Impact**: Higher deductibles (e.g., $1,000) can reduce full coverage premiums by **10–20%**, but increase out-of-pocket costs in claims.State Minimum vs. Recommended Coverage Limits
State-mandated minimum limits (e.g., **25/50/25** in many states) often provide inadequate protection, especially in high-cost areas. Recommended limits (e.g., **100/300/100**) align with the **100/300/100 rule of thumb**, suggesting: - **$100,000 per person** in bodily injury liability. - **$300,000 per accident** in bodily injury liability. - **$100,000 in property damage liability**. **Example Cost Impact by State:** | **State** | **State Minimum (25/50/25)** | **Recommended (100/300/100)** | **Premium Increase** | |-----------------|-----------------------------|--------------------------------|----------------------| | California | ~$600 | ~$1,500 | **+150%** | | Texas | ~$500 | ~$1,300 | **+160%** | | Florida | ~$700 | ~$1,800 | **+157%** | | New York | ~$900 | ~$2,200 | **+144%** | *Note: Premiums vary based on driving history, vehicle type, and location.*Collision and Comprehensive Coverage Cost Breakdown
Collision coverage pays for vehicle repairs after accidents (regardless of fault), while comprehensive covers non-collision events (theft, vandalism, natural disasters). Their costs depend on: - **Vehicle Value**: Newer or luxury cars cost **$1,000–$3,000/year** for collision/comprehensive, while older vehicles may cost **$300–$800/year**. - **Deductible Choice**: A **$500 deductible** reduces premiums by **~15%** compared to a **$250 deductible**. - **Anti-Theft Devices**: Cars with GPS tracking or alarms may see **5–15% discounts** on comprehensive coverage. **Example Premium Adjustments:** - **2020 Toyota Camry (Moderate Risk Driver)**: - Liability-only: **$800/year** - Liability + Collision/Comprehensive ($500 deductible): **$1,600/year** (+$800) - Liability + Collision/Comprehensive ($1,000 deductible): **$1,400/year** (+$600)Financial Trade-Offs: Protection vs. Premium Cost
Policyholders must evaluate whether the **increased premium cost** justifies the **reduced out-of-pocket risk**. For example: - **Scenario 1 (Low-Risk Driver)**: - **Liability-Only**: $600/year, **$10,000 out-of-pocket** if at fault in a severe accident. - **Full Coverage**: $1,500/year, **$500 deductible** in a claim. - **Scenario 2 (High-Value Vehicle)**: - **Liability-Only**: $700/year, **full repair cost** ($30,000) if damaged in a hailstorm. - **Full Coverage**: $2,500/year, **$1,000 deductible** for the same event. **Decision Framework:***"Opt for full coverage if the annual premium is less than 10% of the vehicle’s actual cash value. For example, a $20,000 car should have full coverage costing under $2,000/year."*
Online Comparison Tools for Auto Insurance: Functionality and Limitations
Online comparison tools, including aggregator websites and insurer-specific calculators, streamline the process of evaluating auto insurance rates by consolidating quotes from multiple providers into a single interface. These platforms leverage real-time data feeds from insurers, user-provided inputs (e.g., vehicle details, driving history, coverage preferences), and proprietary algorithms to generate personalized rate estimates. Aggregators like **Compare.com, NerdWallet, and The Zebra** aggregate data from dozens of carriers, while insurer websites (e.g., **Geico, Progressive, State Farm**) offer direct calculators tailored to their own policies. However, their effectiveness depends on data accuracy, insurer participation, and the user’s ability to input precise details. The core functionality of these tools relies on three key processes: 1. **Data Collection**: Gathering user inputs (vehicle make/model/year, ZIP code, coverage limits, deductibles, discounts). 2. **Algorithm Processing**: Applying insurer-specific underwriting rules (e.g., risk factors like credit scores, claims history) to generate quotes. 3. **Presentation**: Displaying comparative quotes with side-by-side features, but often without binding the user to a purchase.How Aggregator Websites Operate
Aggregators act as intermediaries by partnering with insurers to access their rate databases. When a user submits a request, the aggregator: - **Transmits inputs** to participating insurers via APIs or manual data entry. - **Receives quotes** (usually non-binding) within seconds to minutes. - **Ranks results** based on price, coverage, or user-defined filters (e.g., "cheapest full coverage"). - **Displays disclaimers** noting that final rates may vary after underwriting. **Limitations**: - **Incomplete Provider Coverage**: Not all insurers participate (e.g., regional carriers like **Farmers Insurance** may not appear on all aggregators). - **Dynamic Pricing**: Quotes reflect a snapshot in time; rates can change due to market fluctuations or insurer policy updates. - **Data Entry Errors**: Incorrect inputs (e.g., wrong vehicle year) lead to inaccurate quotes. - **Lack of Context**: Aggregators prioritize price over policy nuances (e.g., claims service reputation, local agent support). - **Privacy Concerns**: Some aggregators sell user data to insurers or third parties, raising GDPR/CCPA compliance questions.Insurer-Specific Calculators: Direct vs. Aggregated Quotes
Insurer calculators (e.g., **Allstate’s "Get a Quote" tool**) provide quotes based on the carrier’s underwriting criteria, often with fewer third-party variables. Users input details directly into the insurer’s system, reducing discrepancies but limiting comparison breadth. **Step-by-Step Guide for Using Insurer Calculators** Users should follow this sequence to maximize accuracy: 1. **Gather Documentation**: - Vehicle identification number (VIN), registration, and proof of insurance. - Driver’s license and past 3 years of driving records (including tickets/accidents). - Pay stubs or bank statements for proof of income (affects discounts). 2. **Input Vehicle Details**: - Select make/model/year from a dropdown or enter VIN for precise data (e.g., safety ratings, theft risk). - Specify primary use (commute, pleasure, rideshare) to adjust liability limits. 3. **Define Coverage Needs**: - Choose liability limits (state minimums vs. higher coverage like 100/300/100). - Select optional coverages (collision, comprehensive, uninsured motorist) and deductibles. 4. **Apply Discounts**: - Input codes for bundling (home + auto), safe driver, or anti-theft devices. - Verify eligibility for professional discounts (e.g., **USAA for military personnel**). 5. **Review and Compare**: - Note the "base rate" before discounts and the final estimate. - Compare with competitors using the same inputs (e.g., via **Policygenius’ side-by-side tool**). **Common Pitfalls**: - **Overlooking State-Specific Requirements**: Minimum coverage varies by state (e.g., **Florida’s PIP no-fault system** vs. **California’s low-income insurance programs**). - **Ignoring Usage-Based Programs**: Tools like **Progressive’s Snapshot** or **State Farm’s Drive Safe & Save** may offer lower rates post-quote if usage data qualifies. - **Assuming Quotes Are Final**: Insurers may adjust rates after a full application (e.g., credit checks, claims history verification).AI-Driven Chatbots in Policy Comparison
AI chatbots (e.g., **Insurify, Lemonade’s AI assistant, or Allstate’s "Ask a Question" bot**) use natural language processing (NLP) to guide users through comparisons without human intervention. These tools: - **Qualify Users**: Ask screening questions (e.g., "Do you have a clean driving record?") to narrow down relevant policies. - **Explain Jargon**: Simplify terms like "comprehensive coverage" or "umbrella policy" in plain language. - **Recommend Adjustments**: Suggest higher deductibles or bundling to lower premiums. - **Connect to Human Agents**: Escalate complex queries (e.g., "I was in an accident last year") to live support. **Examples of AI Assistance**: - **Lemonade’s AI**: Uses machine learning to match users with policies in under 90 seconds, including renters insurance comparisons. - **Geico’s "Gecko" Chatbot**: Answers FAQs (e.g., "How does my credit score affect rates?") and directs users to calculators. - **Metromile’s Usage-Based Bot**: Helps calculate pay-per-mile rates for low-mileage drivers. **Limitations**: - **Contextual Gaps**: May misinterpret inputs (e.g., confusing "hybrid car" with "electric vehicle" for discounts). - **Limited Customization**: Cannot account for unique scenarios (e.g., classic car collectors or commercial use). - **Data Privacy Risks**: Chatbot interactions may be logged and used for targeted advertising.Mobile Apps vs. Desktop Platforms for Real-Time Quotes
Mobile apps (e.g., **Esurance, The General’s app, or USAA’s mobile**) and desktop tools (e.g., **Insure.com’s quote engine**) serve the same core function but differ in usability, features, and limitations. **Benefits of Mobile Apps**: - **Convenience**: Access quotes while commuting or at dealerships (e.g., **Progressive’s app** scans VINs via camera). - **Push Notifications**: Alerts for rate renewals, discounts, or claims updates (e.g., **State Farm’s "Drive Safe" app**). - **Biometric Authentication**: Fingerprint/Face ID login reduces friction for frequent users. - **Offline Capabilities**: Some apps (e.g., **Allstate’s**) allow partial quote entry without internet. **Drawbacks of Mobile Apps**: - **Smaller Input Fields**: Error-prone for detailed data entry (e.g., typing VINs manually). - **Limited Features**: Fewer policy customization options than desktop (e.g., no side-by-side PDF comparisons). - **Battery/Storage Impact**: Real-time GPS tracking (for usage-based insurance) drains battery. - **App-Specific Quirks**: Some apps (e.g., **Metromile**) require manual mileage logging, which users may forget. **Desktop Platform Advantages**: - **Detailed Input Forms**: Larger screens accommodate complex inputs (e.g., listing multiple drivers with distinct records). - **Advanced Filters**: Tools like **ValuePenguin** allow sorting by coverage type, not just price. - **Downloadable Reports**: Generate and save comparison spreadsheets for offline review. - **Multi-Device Sync**: Desktop tools often integrate with mobile apps (e.g., **Geico’s "My Policy" portal**). **Real-Time Quote Trade-offs**: | Feature | Mobile Apps | Desktop Platforms | |-----------------------|---------------------------------------|----------------------------------------| | **Speed** | Faster for simple inputs (e.g., VIN scan) | Slower for complex policy setups | | **Accuracy** | Higher error risk (touchscreen input) | Lower error risk (full keyboard/mouse) | | **Customization** | Limited (e.g., no split liability) | Extensive (e.g., custom deductibles) | | **Data Security** | Biometric login helps but vulnerable to app breaches | Stronger encryption (e.g., HTTPS) | | **Offline Use** | Partial functionality (cached data) | Rarely supported |Checklist for Evaluating Digital Comparison Tools
Before using any online tool, consumers should verify the following features to ensure reliability and relevance: **Core Functionality** - **Real-Time Data**: Quotes should reflect current rates (not cached from weeks prior). - **Insurer Transparency**: Clearly lists all participating carriers and their market share (e.g., "Top 20 insurers by policy count"). - **Custom Input Validation**: Flags incomplete or inconsistent data (e.g., "Your vehicle year doesn’t match the model"). **User Experience** - **Intuitive Interface**: Logical flow from input to results (e.g., **NerdWallet’s 5-step process**). - **Mobile Responsiveness**: Desktop tools should adapt to tablets/phones without losing functionality. - **Accessibility**: Compliance with WCAG standards (e.g., screen reader support, high-contrast modes). **Data Security and Privacy** - **Encryption**: Uses **AES-256** or equivalent for data transmission (look for HTTPS and padlock icons). - **GDPR/CCPA Compliance**: Explicit privacy policy stating data retention periods and opt-out options. - **Third-Party Audits**: Certifications like **SOC 2 Type II** or **ISO 27001** for security practices. - **No Hidden Data Sales**: Avoid tools that require sharing contact info for "personalized offers" without consent. **Quote Validity and Accuracy** - **Expiration Date**: Non-binding quotes typically expire in **14–30 days**; confirm renewal policies. - **Binding Authority**: Specifies whether quotes are "indicative" or "firm" (e.g., **Geico’s tool** allows binding online in some states). - **Adjustment Disclaimers**: Notes that final rates may change due to: - **Underwriting Review**: Credit checks, claims history, or driving record updates. - **Policy Exclusions**: Pre-existing conditions (e.g., **mechanical breakdown coverage** for older cars). **Additional Features** - **Discount Tracker**: Identifies applicable discounts (e.g., **AAA membership, paperless billing**). - **Claims Filing Integration**: Direct links to insurer portals (e.g., **State Farm’s app** auto-populates claim forms). - **Multilingual Support**: Critical for non-English speakers (e.g., **Spanish-language tools on Esurance**). - **Customer Reviews**: Aggregated ratings for insurers (e.g., **J.D. Power scores** embedded in quotes). **Red Flags to Avoid** - **Upfront Payment Requests**: Legitimate tools never ask for payment before providing quotes. - **Overly Aggressive Upselling**: Pop-ups pushing add-ons (e.g., "Roadside Assistance for $Impact of Macroeconomic Events on Auto Insurance Rate Volatility
Macroeconomic disruptions, such as pandemics and economic recessions, create ripple effects across industries, including auto insurance. These events alter consumer behavior, supply chains, and risk exposure, leading to temporary spikes or drops in premiums. Understanding these dynamics provides insight into how external shocks reshape underwriting models and pricing strategies. **Mechanisms of Rate Adjustment During Crises** Insurance rates respond to two primary factors during economic turmoil: **supply-side disruptions** (affecting vehicle availability, repair costs, and insurer solvency) and **demand-side shifts** (changes in driving habits, claim frequencies, and consumer affordability). Pandemics and recessions accelerate these adjustments by introducing uncertainty in loss projections and operational costs.Pandemics and Lockdown-Induced Rate Fluctuations
The COVID-19 pandemic (2020–2022) demonstrated how sudden behavioral changes directly influence premiums. During lockdowns, **mileage dropped by 40–50%** in some regions (U.S. Department of Transportation), reducing collision and liability claims. Insurers responded with **temporary rate reductions** (e.g., Progressive’s "Name Your Price" tool offered discounts of up to 30% for low-mileage drivers) and **usage-based insurance (UBI) promotions** to retain policyholders. However, secondary effects emerged: - **Supply chain bottlenecks** increased vehicle repair costs by **15–25%** (IHS Markit), as semiconductor shortages delayed part availability. - **Fraudulent claims surged** in some markets (e.g., a 20% increase in "phantom accident" reports in the UK, per Association of British Insurers), forcing insurers to tighten underwriting criteria. - **Remote work adoption** led to **geographic risk shifts**, with insurers adjusting rates for drivers commuting less frequently but using vehicles for personal errands (e.g., grocery delivery), a higher-risk activity.*"Insurers that failed to dynamically adjust for pandemic-era risks faced underwriting losses, while those with agile UBI models capitalized on reduced exposure."* — **McKinsey & Company, 2021**
Economic Recessions and Long-Term Rate Pressures
Recessions trigger rate volatility through **insolvency risks for insurers** and **changes in claim severity**. For example: - The **2008 Financial Crisis** led to a **12% decline in new car sales** (U.S. Bureau of Economic Analysis), reducing insured exposure but increasing **uninsured motorist claims** as policyholders canceled coverage to save costs. - **Claim payout ratios worsened** as older, higher-mileage vehicles remained on roads longer, correlating with **higher average repair costs** (+18% from 2007–2010, per CCC Information Services). - Insurers like **State Farm** introduced **economic recession riders** in policies, offering premium rebates if unemployment rates exceeded thresholds (e.g., 9%+ in a state). **Historical Premium Trends During Recessions** | **Event** | **Premium Change** | **Key Driver** | **Insurer Response** | |-------------------------|--------------------|----------------------------------------|-----------------------------------------------| | 2001 Dot-Com Bubble | -5% to -8% | Reduced new car purchases, fraud spike | Tightened credit checks for high-risk drivers | | 2008 Financial Crisis | +3% to +7% | Older vehicle fleet, uninsured motorists| Mandated uninsured motorist coverage in some states | | 2020 COVID-19 Pandemic | -10% to +5% (varies by region) | Lockdowns vs. supply chain disruptions | UBI discounts, fraud detection AI deployment |Inflation and Its Indirect Effects on Auto Insurance
While not a direct crisis, **post-pandemic inflation (2021–2023)** exacerbated rate pressures by: - **Increasing repair costs**: The average cost to repair a collision rose **$1,200 (15%)** from 2020–2022 (Hagerty), driven by labor shortages and material price hikes. - **Raising vehicle values**: Electric and luxury vehicles (e.g., Tesla Model 3, BMW 5 Series) saw **valuation surges of 20–30%**, inflating comprehensive coverage premiums. - **Widening affordability gaps**: Insurers in high-inflation states (e.g., California, Florida) faced **regulatory scrutiny** for rate hikes, leading to **delayed approvals** (e.g., Geico’s 2022 rate increase rejected in California until 2023).*"Inflation erodes underwriting margins unless insurers can pass through cost increases via rates or improve claims efficiency."* — **S&P Global Ratings, 2022**
Legal Requirements for Auto Insurance Rate Factor Disclosure by State
Auto insurance rates in the U.S. are regulated at both the state and federal levels, with each state imposing specific rules on how insurers must disclose the factors influencing premium calculations. These requirements aim to ensure transparency, prevent discriminatory practices, and empower consumers to understand why their rates may fluctuate. Failure to comply can result in fines, regulatory penalties, or legal action against insurers. The disclosure obligations vary significantly by jurisdiction, with some states mandating detailed breakdowns of rate components, while others require only broad categorizations. Below are the key legal frameworks governing transparency in auto insurance rate calculations. ---Federal Guidelines and State-Specific Regulations
The **National Association of Insurance Commissioners (NAIC)** provides model laws, such as the **Unfair Trade Practices Act (UTPA)**, which many states adopt to regulate insurance practices. However, individual states often impose stricter or more specific rules. For example: - **California (Insurance Code § 1861.01)** requires insurers to disclose **five primary rating factors** (e.g., driving record, location, vehicle type) and prohibits gender-based discrimination in personal auto policies. - **New York (Insurance Law § 2324)** mandates insurers to provide a **rate comparison tool** and disclose how factors like credit history (where permitted) and mileage affect premiums. - **Massachusetts (215 CMR 12.00)** demands insurers submit **rate filings** for approval, including detailed justifications for rate changes, and requires disclosure of **usage-based insurance (UBI) factors** if applied. - **Texas (Texas Insurance Code § 502.002)** allows insurers to use **telematics data** but requires disclosure of how driving behavior metrics (e.g., hard braking, speeding) impact rates. - **Hawaii (HRS § 431:10-318)** prohibits insurers from using **zip codes as proxies for race or ethnicity**, requiring alternative geographic risk assessments. **Key Federal Laws Affecting Disclosure:** - **Fair Credit Reporting Act (FCRA)** – Regulates how insurers use credit-based insurance scores, requiring notice if credit data influences rates. - **Gramm-Leach-Bliley Act (GLBA)** – Mandates privacy notices for personal data collection, including financial and driving history. - **Americans with Disabilities Act (ADA)** – Prohibits insurers from discriminating based on disability in rate calculations. ---Mandated Rate Factor Disclosures by State Category
States categorize required disclosures based on **risk classification, consumer protection priorities, and technological advancements**. Below is a summary of common disclosure types:
**Note:** Some states (e.g., **California, Hawaii, Maryland**) have **banned gender as a rating factor** for personal auto policies, while others (e.g., **North Carolina, Ohio**) still allow it under certain conditions. ---State Category Required Disclosures Examples of States **Strict Transparency (Detailed Breakdowns)** - Itemized list of all factors (e.g., age, gender, credit score, education level where legal).
- Explanation of how each factor weights into the final premium.
- Comparative rate tables showing how changes in a factor (e.g., improving credit score) affect costs.
California, New York, Massachusetts, Oregon, Michigan **Moderate Transparency (Broad Categories)** - General classification of factors (e.g., "driving history," "vehicle safety features").
- Prohibition of discriminatory factors (e.g., marital status, occupation in some states).
- Requirement to disclose if **telematics or UBI** is used and how data is collected.
Texas, Florida, Illinois, Pennsylvania **Limited Transparency (Minimal Disclosure)** - Only broad statements like "rates based on risk factors."
- No requirement to disclose specific weights or methodologies.
- Permits insurers to use **proprietary algorithms** without explanation.
Alabama, Mississippi, South Dakota, Wyoming **Emerging Regulations (Tech-Driven Factors)** - Disclosure of **AI/ML model inputs** if used for dynamic pricing.
- Explanation of **real-time data sources** (e.g., GPS, dashcam footage).
- Consumer opt-out rights for **continuous monitoring** (e.g., Progressive’s Snapshot, State Farm’s Drive Safe & Save).
Washington, Colorado, Utah, Virginia Penalties for Non-Compliance with Disclosure Laws
Insurers that fail to comply with state disclosure requirements face **administrative, civil, or criminal penalties**, depending on the jurisdiction. Common enforcement actions include: - **Fines and Restitution:** - **California:** Up to **$10,000 per violation** under the **California Insurance Code § 790.15**. - **New York:** **$5,000 per day** for repeated failures to disclose rate factors (NY Insurance Law § 2324). - **Massachusetts:** **$1,000 per policy** affected by undisclosed discriminatory practices. - **Regulatory Sanctions:** - **License Suspension or Revocation** (e.g., **Texas Department of Insurance** can impose this for systemic non-compliance). - **Mandatory Corrective Actions**, such as refunds to affected policyholders. - **Class-Action Lawsuits:** - Consumers or advocacy groups (e.g., **Consumer Federation of America**) have successfully sued insurers for **deceptive practices**, leading to settlements (e.g., **$10 million settlement in 2020** against **Allstate** in California for alleged unfair rate hikes). - **Criminal Charges:** - In extreme cases (e.g., **fraudulent rate manipulation**), executives may face **felony charges** under state insurance fraud statutes (e.g., **Florida’s Insurance Fraud Statute § 817.234**). ---Exemptions and Loopholes in Disclosure Laws
While disclosure laws are stringent, certain exemptions and ambiguities allow insurers to operate with reduced transparency: - **Small Insurers:** Some states exempt **mutual companies or small insurers** (e.g., **less than $10 million in annual premiums**) from detailed disclosures. - **Commercial Policies:** **Business auto insurance** often has **weaker disclosure rules** than personal policies. - **Group Policies:** Employer-sponsored or association-based plans may **aggregate data**, reducing individual transparency. - **Proprietary Algorithms:** Insurers like **Geico or Lemonade** argue that **AI-driven pricing models** are "trade secrets," delaying or obscuring factor explanations. - **State-Specific Carve-Outs:** Some states (e.g., **Tennessee**) allow insurers to **use education level** in rate calculations without full disclosure, citing "actuarial soundness." **Example of a Controversial Loophole:** In **2019**, **State Farm** faced scrutiny in **Illinois** for using **postal codes as proxies for socioeconomic status**, which indirectly correlated with race. The company argued this was a **neutral geographic risk factor**, but regulators forced additional disclosures under **Illinois Insurance Code § 325**. ---Designing an Infographic Comparing Average Auto Insurance Rates by Age Group with Visual Cost Differentiation
Auto insurance premiums vary significantly across age groups due to factors like driving experience, risk perception, and statistical claims data. An effective infographic should visually communicate these differences using clear data representation and intuitive icons to highlight cost disparities. The layout should prioritize readability, scalability, and emotional impact to engage consumers while conveying complex information at a glance.Infographic Layout Structure and Components
The infographic should follow a **three-column vertical flow**: - **Left Column**: Age groups (18–24, 25–34, 35–44, 45–54, 55–64, 65+). - **Middle Column**: Average annual premiums (in USD) with **color-coded bars** (e.g., red for highest, green for lowest). - **Right Column**: **Icon-based cost comparison** (e.g., a gas pump icon with a "$" symbol for high costs, a downward arrow for savings, or a shield for stability). **Key Visual Elements**: - **Primary Data Representation**: A **stacked bar chart** where each bar’s height corresponds to the average premium for an age group. Use **gradients** (e.g., dark red fading to green) to show progression from high to low costs. Example: ``` [Bar Chart Legend] 18–24: $5,200 (Red) | 25–34: $3,800 (Orange) | 35–44: $2,900 (Yellow) | 45–54: $2,500 (Light Green) | 55–64: $2,700 (Green) | 65+: $3,100 (Teal) ``` - **Icon Integration**: Place **three icons per age group** in the right column to reinforce cost differences: - **High Cost (18–24)**: A **caution triangle** with a "$$$" symbol and a **speedometer** (symbolizing reckless driving). - **Moderate Cost (25–34)**: A **checkmark** with a "$" symbol and a **car with a seatbelt** (indicating improved safety). - **Low Cost (45–54)**: A **shield** with a "$" and a **calm road** (representing experience and stability). - **Increased Cost (65+)**: A **walking cane icon** with a "$" and a **slow-moving car** (reflecting age-related risk adjustments). - **Anchoring with Real-World Context**: Add **short case studies** below the chart: - *"A 20-year-old driver pays 68% more than a 40-year-old in the same state."* - *"Drivers aged 65+ see rates rise due to slower reaction times, even with safe driving records."* - **Interactive Element (Digital Version)**: Include a **tooltip feature** where hovering over an age group reveals: - **State-specific averages** (e.g., Michigan vs. California). - **Discount opportunities** (e.g., good student, bundling). - **Key risk factors** (e.g., nighttime driving for young drivers).Design Principles for Clarity and Impact
**Typography and Hierarchy**: - Use **bold, sans-serif fonts** (e.g., Montserrat) for headings and **lightweight fonts** (e.g., Open Sans) for body text. - **Premium values** should be in **large, bold numbers** (e.g., **$2,900**) with a secondary font size for percentages (e.g., *"30% cheaper than 18–24"*). **Color Psychology**: - **Red/Orange**: High risk (young drivers). - **Green/Blue**: Low risk (experienced drivers). - **Neutral Gray**: Baseline comparisons (e.g., national average). **Data Sources and Citations**: - Cite **Insurance Information Institute (III)**, **NAIC**, or **state-specific reports** (e.g., *"Data sourced from 2023 NAIC filings across 48 states"*). - Include a **disclaimer** noting variations by location, coverage level, and insurer. **Mobile Optimization**: - Ensure the infographic **collapses into a single-column view** on mobile, with icons scaling proportionally. - Use **tap-to-expand** sections for detailed breakdowns (e.g., "Why do 65+ drivers pay more?"). ---Example Infographic Wireframe (Text-Based)
``` +-----------------------------------------------------+ | AUTO INSURANCE RATES BY AGE GROUP (2024) | |-----------------------------------------------------| | [National Average: $1,500] | |-----------------------------------------------------| | AGE GROUP | PREMIUM ($) | VISUAL COST DIFFERENCE | |-----------------------------------------------------| | 18–24 | $5,200 | [🚨 Gas Pump] [💨 Speedometer] | | 25–34 | $3,800 | [✅ Checkmark] [🚗 Seatbelt] | | 35–44 | $2,900 | [🛡️ Shield] [🛣️ Smooth Road] | | 45–54 | $2,500 | [💰 Savings] [📉 Down Arrow] | | 55–64 | $2,700 | [🚶 Cane] [🐢 Slow Car] | | 65+ | $3,100 | [🔄 Reassessment] [📈 Up Arrow]| +-----------------------------------------------------+ | NOTES: | | - Rates based on full coverage in urban areas. | | - Discounts can reduce costs by 15–30%. | +-----------------------------------------------------+ ```Differences Between Commercial Auto Insurance Rates and Personal Policies for Business Use
Commercial auto insurance rates differ fundamentally from personal policies due to variations in risk exposure, regulatory requirements, and operational complexities. Businesses using vehicles—such as delivery trucks, company cars, or fleet operations—face distinct liabilities, including higher mileage, employee-driven risks, and specialized vehicle types, which insurers account for through tailored coverage and premium structures. Commercial policies incorporate risk mitigation strategies aligned with business operations, whereas personal policies prioritize individual driver profiles and standard vehicle use. The distinction extends to coverage limits, liability thresholds, and additional endorsements required for business-related risks, such as cargo damage or hired/non-owned auto exposures. ---Key Factors Influencing Commercial Auto Rate Calculations
Commercial auto insurance rates are determined by a broader set of variables compared to personal policies. These include: - **Business Classification and Industry Risk**: High-risk industries (e.g., construction, logistics) incur higher premiums due to frequent vehicle use, equipment transport, or exposure to theft/vandalism. Insurers categorize businesses using **NAICS (North American Industry Classification System) codes**, which directly impact underwriting.Example: A delivery service transporting perishable goods may face higher premiums than a consulting firm with occasional company car use.
- **Vehicle Type and Usage**: Commercial policies differentiate between **private passenger vehicles** (e.g., company cars), **commercial trucks** (e.g., box trucks, semi-trailers), and **specialized equipment** (e.g., tow trucks, food trucks). Usage patterns—such as **commute vs. delivery routes**—also adjust rates, with delivery vehicles often incurring higher costs due to wear-and-tear and accident frequency. - **Driver Records and Fleet Management**: While personal policies focus on the primary driver’s history, commercial policies evaluate **all drivers**, including employees, contractors, and third-party operators. Insurers assess: - **MVR (Motor Vehicle Record) scores** of fleet drivers. - **Training programs** for high-risk operations (e.g., defensive driving courses). - **Driver turnover rates**, as frequent hiring increases underwriting risk. - **Regulatory and Legal Requirements**: Commercial policies must comply with **state-specific mandates** (e.g., minimum liability limits for trucks) and **federal regulations** (e.g., DOT compliance for interstate haulers). Non-compliance can void coverage or trigger surcharges. - **Coverage Extensions and Endorsements**: Commercial policies often include **umbrella policies**, **hired/non-owned auto coverage**, or **cargo insurance**, which personal policies rarely require. These add-ons significantly increase premiums but address unique business exposures. ---Comparative Analysis of Coverage Structures
The following table highlights structural differences between commercial and personal auto insurance, emphasizing how these affect rate calculations:
---Feature Personal Auto Policy Commercial Auto Policy Primary Coverage Liability, collision, comprehensive (based on individual driver). Liability (higher limits), physical damage, hired/non-owned auto, cargo, and workers' compensation (if applicable). Liability Limits State-minimum or voluntary higher limits (e.g., 100/300/50). Customizable limits (e.g., 1M/2M for trucks, umbrella policies up to $5M+). Deductibles Standard deductibles ($500–$2,000). Flexible deductibles (often higher for fleets, e.g., $1,000–$5,000 per vehicle). Risk Assessment Focus Individual driving history, vehicle age, and location. Fleet size, driver MVRs, business operations, and vehicle maintenance records. Additional Costs Optional: Rental reimbursement, roadside assistance. Mandatory: Workers’ comp add-ons, cargo insurance, DOT physicals, and cyber liability for telematics data. Case Study: Delivery Truck vs. Company Car Premiums
A **delivery truck** operating in an urban area with a single driver may cost **$8,000–$15,000 annually** for commercial coverage, depending on: - **Vehicle value** ($50,000–$150,000 for a box truck). - **Annual mileage** (50,000+ miles vs. 12,000 for a personal vehicle). - **Cargo type** (e.g., hazardous materials vs. general merchandise). In contrast, a **company car** used by a sales executive might cost **$2,000–$5,000 annually**, with rates influenced by: - **Driver’s personal history** (clean record reduces premiums). - **Vehicle type** (luxury sedans may have higher comprehensive rates). - **Usage policy** (e.g., restricted to business-only use vs. personal commuting).Insight: Commercial policies for **high-mileage fleets** (e.g., waste management, food delivery) can exceed **$20,000/year per vehicle**, whereas personal policies rarely surpass **$3,000–$6,000** for comparable coverage limits.
International Drivers and Expats Insuring Vehicles Abroad: Rate Variations and Considerations
Insuring a vehicle abroad introduces complexities not present in domestic policies, particularly for international drivers or expats. Factors such as residency status, local traffic laws, vehicle registration, and insurer jurisdiction significantly influence premiums. Rates may fluctuate due to differences in risk assessment models, claim frequency in the destination country, and the insurer’s ability to enforce policies across borders. Expats often face higher premiums if their home country lacks reciprocal insurance agreements with the destination, requiring them to purchase local coverage or international third-party liability insurance. The cost of insuring a vehicle abroad is determined by a combination of **local risk factors**, **policy scope**, and **insurer-specific adjustments**. For example, expats in high-risk countries (e.g., South Africa, Mexico, or parts of Southeast Asia) may pay 30–50% more than locals due to higher theft, accident, or fraud rates. Conversely, expats in low-risk regions (e.g., Scandinavia or Japan) might secure rates closer to domestic levels, provided they meet residency and registration requirements.Key Factors Influencing Premiums for International Drivers
Premiums for expats or international drivers are shaped by the following elements, often weighted differently than domestic policies:- **Residency and Visa Status** Insurers categorize drivers based on legal residency. Permanent residents or long-term visa holders (e.g., EU Blue Card, Canada PR) typically qualify for local rates, while short-term visa holders or tourists may face surcharges. For instance, a U.S. expat in Germany with a permanent residency permit pays similar rates to German citizens, but a tourist renting a car for two weeks may incur a **non-resident premium** (often 2–3x higher).
- **Reciprocal Insurance Agreements** Countries with bilateral agreements (e.g., U.S.-Canada, EU member states) allow seamless cross-border coverage, reducing premiums. Without such agreements, expats must purchase **Green Card insurance** (for Europe) or **third-party liability coverage** in countries like India or Thailand, which can cost **20–40% more** than comprehensive policies.
- **Vehicle Registration and Import Regulations** Insuring an imported vehicle (e.g., a U.S. car in the UK or a Japanese car in Australia) requires compliance with local registration laws. Some countries mandate **local insurer mandates**, meaning expats must purchase coverage from a domestic provider, often at a premium. For example, Japan’s **JAF (Japan Automobile Federation)** requires foreign-registered vehicles to meet specific safety standards before issuing policies, adding **15–25% to premiums**.
- **Local Traffic and Legal Environment** Countries with lenient traffic laws (e.g., Italy or Greece) may have lower premiums, while stricter regimes (e.g., Germany or Singapore) offer discounts for safe driving. Conversely, high litigation rates (e.g., U.S. or Turkey) inflate premiums due to higher claim costs. Data shows expats in the **U.S. pay 10–15% more** for liability coverage than locals due to higher lawsuit frequencies.
- **Insurer’s Global Risk Assessment Models** Multinational insurers (e.g., Allianz, AXA, or Allstate International) use **global risk scores** that incorporate: - **Crime rates** (e.g., car theft in South Africa vs. Sweden). - **Road infrastructure quality** (e.g., poorly maintained roads in India vs. Germany). - **Healthcare and repair costs** (e.g., U.S. medical expenses vs. Canada’s single-payer system). For example, an expat in **Dubai** might pay **40% less** for collision coverage than in **Los Angeles** due to lower accident rates and stricter road enforcement.
Examples of Premium Adjustments for Expats by Region
Regional differences in insurance costs for expats are stark, often tied to economic stability, legal frameworks, and cultural driving habits. Below are comparative examples:Region/Country Key Rate Drivers Expat Premium Adjustment vs. Local Example Scenario European Union (Non-EU Expats) - Green Card requirements for third-party liability.
- Higher administrative fees for non-residents.
- Varied claim processes across countries.
+25% to +50% A U.S. expat in **France** pays **€1,200/year** for comprehensive coverage (local average: €900), with an additional **€300** for Green Card compliance. United States (Non-Resident Aliens) - No-fault state variations (e.g., Florida vs. Texas).
- Higher liability limits required for expats.
- Credit-based insurance scoring (if applicable).
+10% to +30% A Canadian expat in **Florida** pays **$1,800/year** (vs. $1,500 for locals) due to higher hurricane-related claim risks and mandatory **$100,000 bodily injury limits**. Middle East (UAE, Saudi Arabia) - Strict traffic fines and black points system.
- High repair costs for luxury vehicles.
- Mandatory third-party coverage with optional excess.
+30% to +60% An expat in **Dubai** insuring a **Toyota Camry** pays **AED 2,500/year** (vs. AED 1,800 for Emiratis) due to **higher excess fees** and **mandatory 24-hour roadside assistance add-ons**. Asia (Japan, Singapore) - Strict vehicle inspection regimes (e.g., Japan’s **Shaken** system).
- Low claim rates but high deductibles.
- Import duty and local modification costs.
-5% to +20% A U.S. expat in **Tokyo** pays **¥180,000/year** (vs. ¥160,000 for locals) due to **import taxes on foreign-registered cars**, though theft rates are negligible. Specialized Policies for International Drivers
Expats often require **hybrid or specialized policies** that bridge gaps between domestic and local coverage. These include:- **International Third-Party Liability Insurance** Mandatory in many countries (e.g., India, Thailand, Turkey) for expats, covering damages to others but excluding personal injury or vehicle repair. Premiums range from **$500–$2,000/year**, depending on vehicle value and destination risk.
- **Dual-Coverage Policies (Home + Host Country)** Some expats maintain **primary coverage in their home country** (e.g., U.S. policy for a car stored in Germany) and **secondary local coverage** for driving. This can reduce costs by **10–20%** but requires verifying **double-indemnity clauses** to avoid disputes.
- **Short-Term Expat Insurance (e.g., Digital Nomads)** Platforms like **SafetyWing** or **World Nomads** offer **30–90-day policies** for rentals or borrowed vehicles, typically costing **$50–$150 per month**. These exclude long-term residency but cover **accidents, theft, and third-party claims** abroad.
- **Corporate Relocation Insurance** Companies relocating employees often negotiate **bulk discounts** (15–30% off) with insurers like **Chubb or Cigna Global**. Policies may include **global assistance networks**, **24/7 claims support**, and **waived deductibles** for corporate vehicles.
**Critical Consideration for Expats:** Always verify whether the insurer provides **cross-border claims service**. Some providers (e.g., **Geico in the U.S.**) refuse payouts for accidents abroad, leaving expats liable for **$10,000–$50,000 in out-of-pocket costs** if uninsured.
Auto insurance isn’t just a financial obligation—it’s a calculated balance between cost, protection, and peace of mind. The right rate isn’t just the cheapest one; it’s the one that aligns with your risk profile, coverage needs, and long-term goals. From leveraging digital tools to challenge unfair rate hikes or adapting to emerging trends like autonomous vehicles, this guide equips you with the strategies to make informed decisions. The key lies in transparency: understanding how insurers weigh factors, comparing apples-to-apples, and never settling for vague quotes. With the right approach, you can drive away not just with a policy, but with confidence that you’re protected—and paying fairly for it.
In a landscape where rates shift with economic trends, technological advancements, and regional policies, staying proactive is the best defense against overpaying. Whether you’re shopping for a new policy or reassessing an existing one, the insights here cut through the noise. The goal isn’t just to save money—it’s to ensure that every dollar spent on auto insurance buys you the coverage you truly need, without unnecessary sacrifices. Start comparing smarter today, and keep your rates—and your safety—under control.
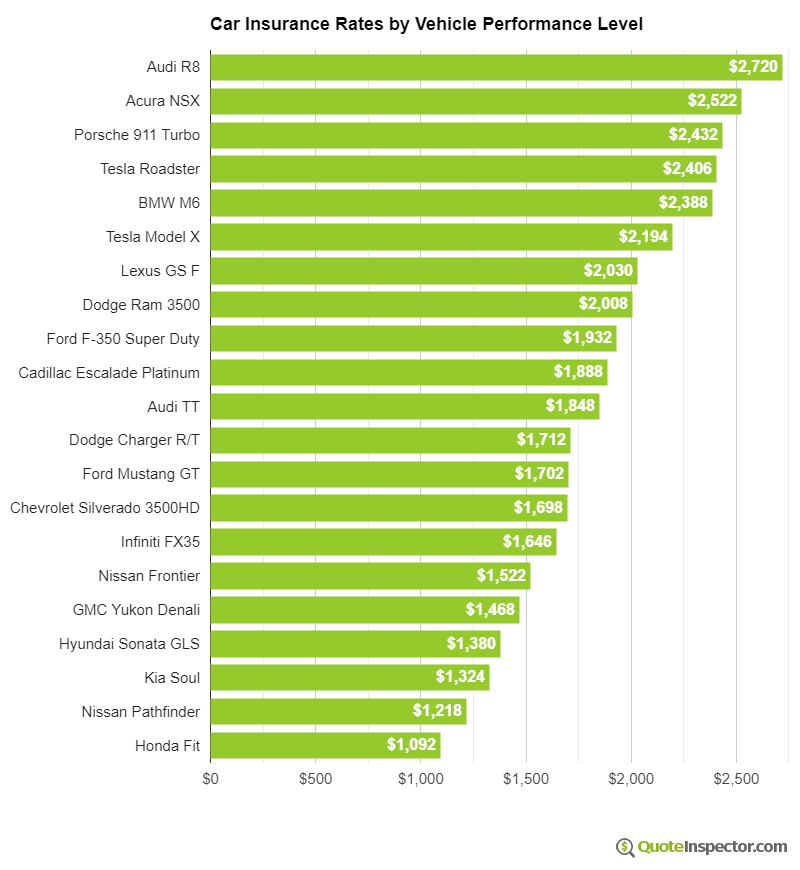
Cheapest Car Insurance Rates by Vehicle Type in 2026 QuoteInspector.com
Frequently Asked Questions
How do auto insurance rates vary by state in the U.S.?
Auto insurance rates differ significantly by state due to factors like traffic density, state regulations, and accident frequency. Urban states often have higher premiums, while rural areas tend to be cheaper. Laws mandating minimum coverage also impact pricing. Regional claims data and provider competition further influence variations.
What factors make my auto insurance rates go up after a claim?
Filing a claim typically raises rates due to increased perceived risk. Factors like claim severity, frequency, and type (collision vs. comprehensive) affect pricing. Insurers may also adjust rates based on your driving record, vehicle type, and location after a claim is filed.
Can comparing quotes online actually save me money on auto insurance?
Yes, comparing quotes online often saves money by revealing price gaps between providers. Digital tools aggregate rates instantly, highlighting discounts you may miss otherwise. Switching insurers or negotiating based on competitor quotes can reduce annual premiums by 15-30%. Transparency helps identify overcharging.
Do discounts like bundling or safe driving lower rates the same for everyone?
Discounts vary by insurer and individual risk profiles. Bundling policies (e.g., home + auto) or safe-driving programs may reduce rates, but savings depend on your location, vehicle, and claims history. Discounts are not uniform; some providers offer deeper reductions for low-mileage drivers or anti-theft device installations.
Why does my age affect how much I pay for car insurance?
Age influences rates due to statistical risk: younger drivers (under 25) pay more because they have higher accident rates. Older drivers (65+) may see slight increases due to slower reflexes or health conditions. Insurers use age-based data to price policies, though experience and driving history can mitigate premiums.
What’s the best way to compare auto insurance for a classic or high-value car?
For classic or high-value cars, prioritize insurers specializing in collector vehicles. Compare agreed-value policies, storage conditions, and usage limits. Seek providers with low depreciation clauses and roadside assistance for vintage cars. Request specialized quotes, as standard auto insurance may undervalue unique vehicles.
Related articles
Compare Auto Insurance Rates Effectively Today
Compare Auto Insurance Rates Effectively Today with our free, side-by-side tools. Save time and money by finding the best coverage tailored to your needs.

Auto Insurance Car Insurance Explained Simply
Understand Auto Insurance & Car Insurance Explained Simply—coverage types, costs, and how policies protect drivers. Get clear answers on liability,…

Auto Insurance For Business Vehicles Essentials And Solutions
Discover essential Auto Insurance For Business Vehicles Essentials And Solutions—coverage types, cost factors, and expert tips to protect your fleet…
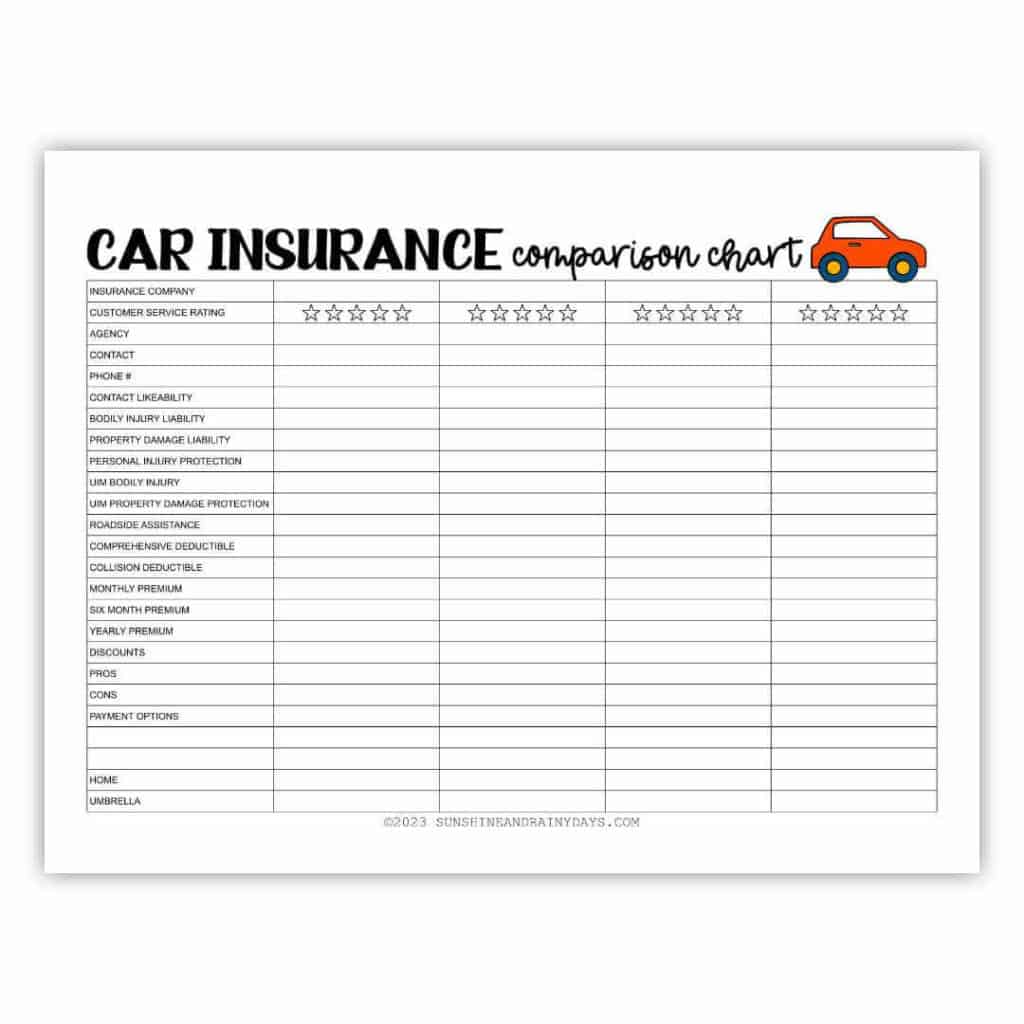
Auto Insurance Comparison Tool Simplified Guide
Discover how an Auto Insurance Comparison Tool Simplified Guide helps you compare quotes fast, save money, and pick the best policy effortlessly—no…
Auto Insurance Comparison Quote Guide Key Insights
Get expert insights on comparing auto insurance quotes with this Auto Insurance Comparison Quote Guide Key Insights—save money, pick the best coverage,…
