17+ Smart Ways to Get Auto Insurance for a Month Without Breaking the Bank
Table of Contents
Auto insurance for a month refers to temporary coverage designed for drivers who need protection for a limited period—whether renting a vehicle, borrowing a friend’s car, or covering a gap between policies. For example, a traveler renting a car in Europe for a month might purchase a short-term policy to comply with local laws and avoid liability risks. This type of insurance balances affordability with essential protection, making it ideal for scenarios where long-term commitments aren’t practical.
The rise of auto insurance for a month reflects broader trends in flexibility and cost-consciousness. Historically, insurance was sold in annual or six-month blocks, but digital innovation and niche providers now offer granular options tailored to specific needs. Benefits include lower upfront costs, no long-term commitment, and the ability to adjust coverage as circumstances change. However, it’s crucial to understand that such policies may carry higher per-month rates or limited coverage compared to traditional plans.
This guide explores the nuances of auto insurance for a month, from pricing dynamics to eligibility requirements, and provides actionable strategies to secure the best deal. Whether navigating a temporary driving situation or seeking a budget-friendly alternative, the insights here ensure informed decision-making.
1. Pricing Dynamics
Short-term auto insurance for a month pricing varies significantly based on several factors, including duration, coverage limits, and the insurer’s risk assessment. Unlike annual policies, which benefit from discounts for longer commitments, monthly plans often reflect higher per-month costs due to administrative overhead and underwriting complexity. For instance, a 30-day policy might cost 20–50% more per month than the same coverage annually.
Providers like Geico, Progressive, and specialized short-term insurers (e.g., ShortTerm.com) offer tools to estimate costs. A driver renting a luxury car for a month in the U.S. could pay $500–$1,500, depending on deductibles and liability limits. Understanding these dynamics helps avoid surprises when comparing quotes.
2. Coverage Types
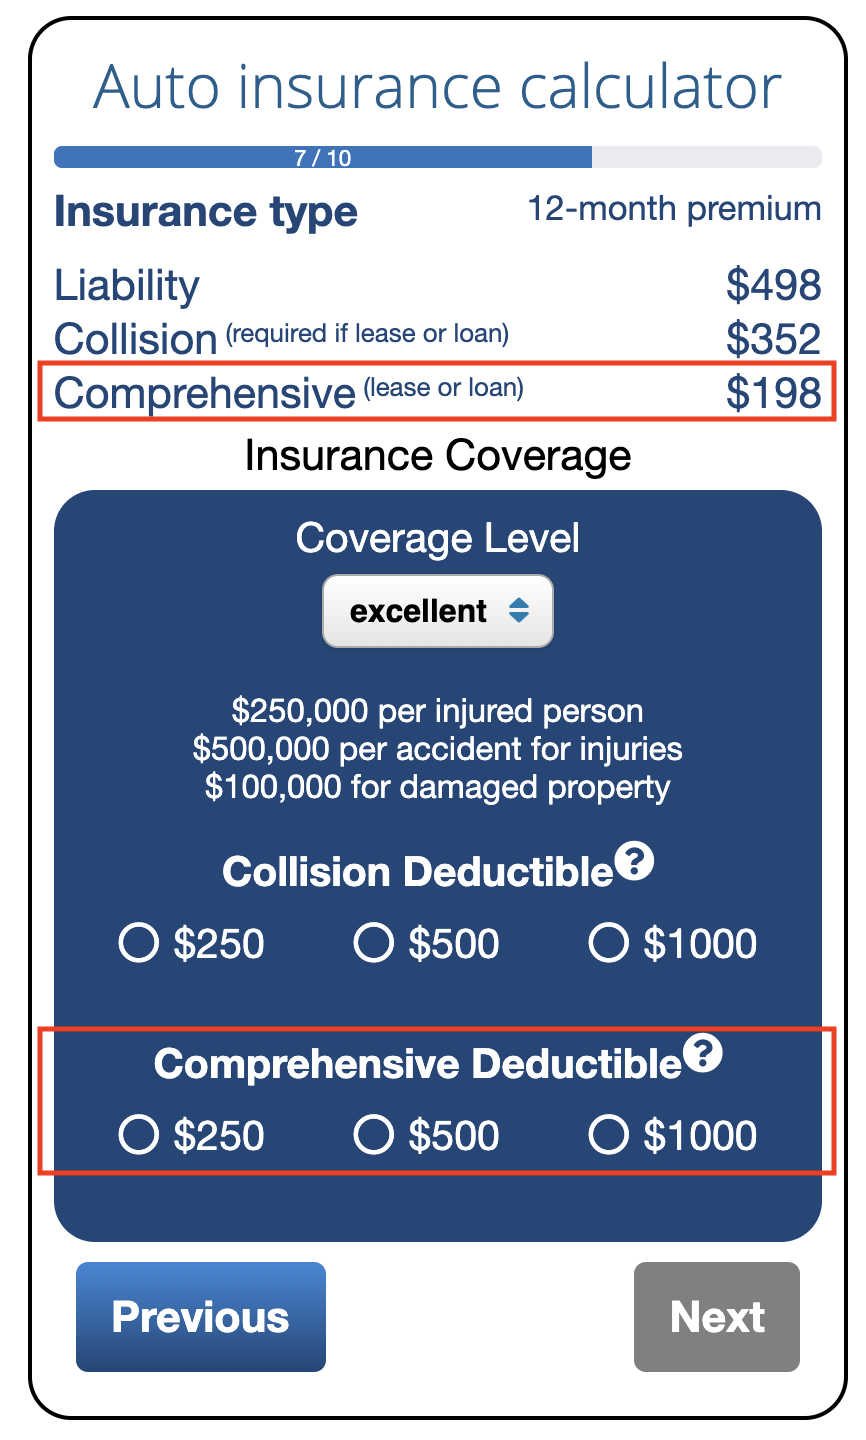
Auto insurance for a month typically includes liability, collision, and comprehensive coverage, but options vary by provider. Liability is mandatory in most states and covers damages to others; collision addresses vehicle repairs from accidents, while comprehensive covers theft or natural disasters. Some insurers offer non-owner policies, which are ideal for renters or drivers borrowing cars frequently.
For example, a driver in California borrowing a friend’s car for a month might opt for a non-owner policy with $50,000 bodily injury liability and $10,000 property damage coverage. This avoids gaps in protection while keeping costs lower than a full policy. However, exclusions—such as off-road use or commercial driving—can void coverage, so reviewing policy details is critical.
3. Eligibility Factors
- Driving History: Insurers assess past violations or claims. A driver with a clean record may qualify for lower rates, while a history of accidents or tickets could lead to higher premiums or denials. For example, a driver with one at-fault accident in the past three years might pay 30% more for monthly coverage.
- Vehicle Type: Luxury or high-performance cars incur higher premiums due to repair costs. Renting a Tesla for a month could cost double that of a Toyota Corolla, even with identical coverage limits.
- Usage Limits: Policies may restrict coverage to personal use, commuting, or rental scenarios. A policy for a rideshare driver (e.g., Uber) would require commercial coverage, which is rarely offered as a short-term option.
- Residency and Location: Urban areas with higher accident rates or theft risks may see increased premiums. A policy in New York City could be 25% pricier than one in a rural area, even for the same vehicle.
- Credit Score: Some insurers factor credit into pricing, though this is less common for short-term policies. A lower score might exclude certain discounts or increase costs by 10–15%.
4. Provider Options
Specialized insurers dominate the auto insurance for a month market, offering tailored solutions unavailable through traditional carriers. Companies like ShortTerm.com, Hive Insurance, or AutoOwners provide policies for rentals, borrowed cars, or temporary driving needs. For example, Hive Insurance offers 1-day to 30-day policies for renters, while AutoOwners caters to drivers with unique situations, such as those relocating or testing a new vehicle.
Traditional insurers like State Farm or Allstate may also offer short-term add-ons, but these are often less flexible. Comparing providers ensures access to the best rates and coverage terms. For instance, a driver in Florida might find a 30% discount by switching from a traditional insurer to a short-term specialist.
5. Common Mistakes
Avoiding pitfalls is key when securing auto insurance for a month. One frequent error is assuming a rental car’s insurance covers personal use—most policies exclude damage or liability for non-drivers. Another mistake is underestimating coverage limits; a $25,000 bodily injury limit might be insufficient in an at-fault accident with severe injuries.
Additionally, failing to disclose all drivers or vehicle modifications can void coverage. For example, adding a teen driver without notifying the insurer could lead to claim denials. Always review policy exclusions and confirm that all parties are listed.
6. Discounts and Savings
- Bundling with Rental Agreements: Some car rental companies (e.g., Hertz, Enterprise) partner with insurers to offer bundled auto insurance for a month at a discount. For example, renting through Avis and purchasing coverage through their preferred provider might save 15% compared to buying separately.
- Pay-Per-Mile Programs : Insurers like Milewise or Metromile offer pay-as-you-go policies, ideal for infrequent drivers. A driver using a borrowed car only on weekends could pay as little as $5–$10 per day, significantly reducing monthly costs.
- Loyalty or First-Time Discounts: Some providers offer discounts for first-time customers or referrals. ShortTerm.com, for instance, may waive fees for referrals, lowering the effective cost by 10–20%.
- Group or Affinity Programs: Organizations like AAA or professional associations (e.g., bar associations) often negotiate group rates for short-term coverage. A member of the American Bar Association might access a 20% discount on monthly policies.
- Deductible Adjustments: Increasing deductibles from $500 to $1,000 can reduce premiums by 20–30%. However, this strategy only makes sense if the driver can afford higher out-of-pocket costs in an accident.
7. State-Specific Rules
Auto insurance for a month requirements vary by state, with some mandating minimum liability limits and others allowing flexible terms. For example, Virginia requires $25,000 bodily injury per person and $50,000 per accident, while California’s minimums are higher ($15,000/$30,000). Drivers in no-fault states (e.g., Michigan) may face additional costs for personal injury protection (PIP).
Additionally, some states (e.g., New York) impose stricter underwriting for short-term policies, making it harder to qualify without a U.S. driver’s license or proof of residency. Always verify local laws to ensure compliance and avoid penalties.
8. Claim Process Tips
Filing a claim for auto insurance for a month follows similar steps to long-term policies but may involve faster turnarounds due to the temporary nature of coverage. Start by documenting the incident with photos, witness statements, and police reports (if applicable). For example, a driver involved in a rental car accident in Miami should file a claim within 24 hours to meet the insurer’s deadline.
Short-term policies often require direct communication with the insurer rather than third-party adjusters. Providing accurate details—such as the exact date, location, and parties involved—streamlines the process. Delays or discrepancies can lead to denied claims, so thoroughness is critical.
17 Tips to Save on Auto Insurance for a Month
Securing affordable auto insurance for a month requires strategy and awareness. Here are 17 actionable tips to minimize costs without sacrificing protection.
Tip 1: Compare at least 3 short-term providers. Rates vary by insurer, with some offering 20–40% lower premiums for identical coverage. Use comparison tools like The Zebra or NerdWallet to identify the best deal.
Tip 2: Opt for liability-only coverage if the vehicle isn’t yours. Borrowing a friend’s car? Liability-only policies meet legal requirements and cost 50% less than full coverage. Ensure the owner’s policy doesn’t void coverage for additional drivers.
Tip 3: Check for rental company insurance waivers. Many rental agreements include basic coverage for a fee. If your personal policy covers rentals, declining the rental’s insurance can save $20–$30 per day.
Tip 4: Use pay-per-mile insurance for infrequent use. Drivers logging fewer than 5,000 miles monthly can save with programs like Milewise, which charge based on actual mileage rather than fixed rates.
Tip 5: Ask about group or professional discounts. Memberships in organizations like AAA, AARP, or industry groups often unlock short-term discounts. A bar association member might access a 15% reduction on monthly policies.
Tip 6: Increase deductibles to lower premiums. Raising the deductible from $500 to $1,000 can cut costs by 25–30%. Only do this if you can afford higher out-of-pocket expenses in an accident.
Tip 7: Avoid adding unnecessary drivers. Each additional driver increases premiums by 10–20%. If the policy is for a borrowed car, confirm the owner’s consent to avoid claim denials.
Tip 8: Confirm coverage for modified vehicles. Aftermarket modifications (e.g., lifted suspension, custom paint) may void coverage. Disclose changes upfront to prevent denied claims, even for short-term policies.
Tip 9: Use telematics for safe driver discounts. Insurers like Progressive offer discounts (5–15%) for drivers who agree to usage-based tracking. Safe driving habits can lower monthly costs significantly.
Tip 10: Purchase insurance through a rental agreement bundle. Companies like Hertz or Enterprise offer discounted coverage when booked directly. This can save 10–20% compared to third-party providers.
Tip 11: Verify coverage for international rentals. U.S. policies often exclude foreign rentals. Specialized insurers like Cuvva or World Nomads provide global short-term coverage for drivers in Europe or Asia.
Tip 12: Check for first-time customer discounts. Some providers (e.g., ShortTerm.com) waive fees or offer 10% off for new customers. Signing up with a referral code can further reduce costs.
Tip 13: Ensure the policy covers your intended use. Personal use policies exclude commercial driving (e.g., rideshare) or off-road activities. Clarify usage limits to avoid claim rejections.
Tip 14: Review state minimum requirements. Some states (e.g., Florida) mandate higher liability limits for short-term policies. Meeting minimums ensures legal compliance and claim validity.
Tip 15: Document all policy details. Save confirmation emails, coverage summaries, and provider contact information. This simplifies claims and resolves disputes if coverage is disputed.
Tip 16: Cancel promptly if no longer needed. Short-term policies often allow pro-rated refunds within 14 days. Canceling early avoids unnecessary payments for unused coverage.
Tip 17: Reassess coverage needs monthly. Life circumstances change—relocating, changing vehicles, or modifying driving habits may require policy adjustments. Reviewing coverage ensures it remains cost-effective and comprehensive.
Conclusion
Auto insurance for a month offers a practical solution for drivers needing temporary coverage without the commitment of annual plans. Key considerations include pricing dynamics, eligibility factors, and provider options, all of which influence affordability and protection. By leveraging discounts, comparing providers, and understanding state-specific rules, drivers can secure cost-effective coverage tailored to their needs.
As flexibility becomes increasingly important in insurance, short-term policies will continue to evolve, offering even more tailored solutions. Staying informed ensures that drivers balance cost, coverage, and convenience—no matter how long they need protection on the road.
Related articles

Auto Insurance For Business Vehicles Essentials And Solutions
Discover essential Auto Insurance For Business Vehicles Essentials And Solutions—coverage types, cost factors, and expert tips to protect your fleet…
10 Essential Facts About Auto Insurance for Business Owners
Auto insurance for business protects vehicles, drivers, and profits. Learn key coverage types, cost factors, and real-world examples to safeguard…

11 Essential Facts About Auto Insurance Estimate Calculators
Discover how an auto insurance estimate calculator simplifies premium comparisons, reveals hidden discounts, and cuts research time by 70%. Learn its…

17 Essential Tips for Smart Auto Insurance Cost Comparison
Discover how to master auto insurance cost comparison with expert insights. Learn to save hundreds on premiums by comparing quotes, understanding rates,…
Auto Insurance Comparison Tool Simplified Guide
Discover how an Auto Insurance Comparison Tool Simplified Guide helps you compare quotes fast, save money, and pick the best policy effortlessly—no…
