17 Essential Tips for Smart Auto Insurance Cost Comparison
Table of Contents
- 1. Pricing Dynamics Explained
- 2. Key Factors in Cost Comparison
- 3. Common Mistakes to Avoid
- 4. Tools and Technology for Comparison
- 5. State-Specific Considerations
- 6. When to Recompare Your Policy
- 7. The Role of Credit Scores
- 8. Coverage vs. Cost Trade-offs
- Frequently Asked Questions
- 17 Actionable Tips for Smarter Comparison
- Conclusion
Auto insurance cost comparison refers to the process of evaluating multiple insurance quotes, coverage options, and policy features to identify the most affordable yet reliable plan. For example, a driver in Texas might find that one insurer charges $120/month for full coverage, while another offers the same protection for $95—just by comparing three quotes. This practice isn’t just about saving money; it’s about balancing premiums with coverage quality, deductibles, and customer service.
The importance of auto insurance cost comparison lies in its ability to prevent overpaying for policies that may not meet individual needs. Historically, insurance was a one-size-fits-all product, but today’s market offers customizable plans, discounts, and usage-based pricing. A 2023 study by the Insurance Information Institute found that drivers who compared at least three quotes saved an average of $368 annually. Beyond savings, comparison ensures compliance with state minimums and protects against financial risks like accidents or theft.
This guide explores the critical aspects of auto insurance cost comparison, from understanding pricing dynamics to leveraging technology for smarter decisions. It covers common mistakes to avoid, how to evaluate coverage depth, and practical tips to maximize savings without compromising protection.
1. Pricing Dynamics Explained
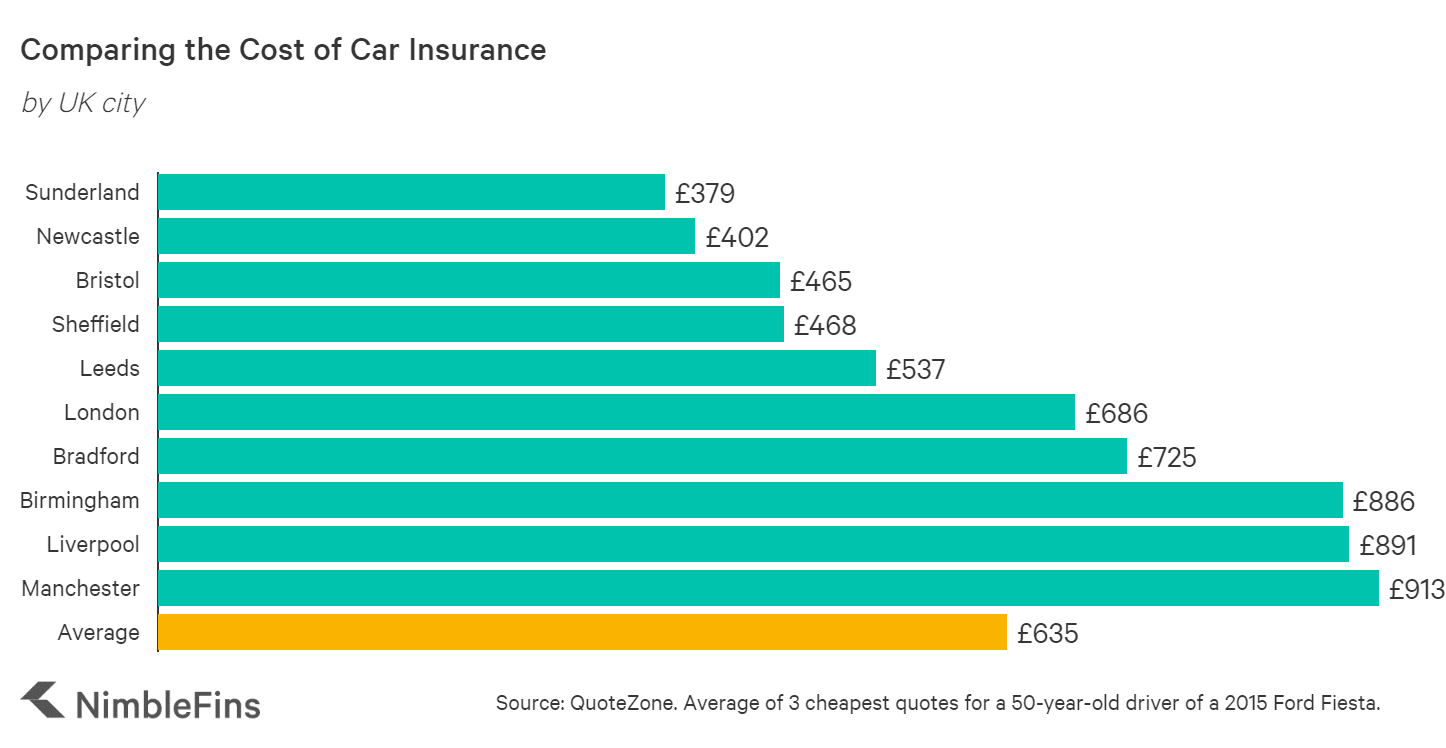
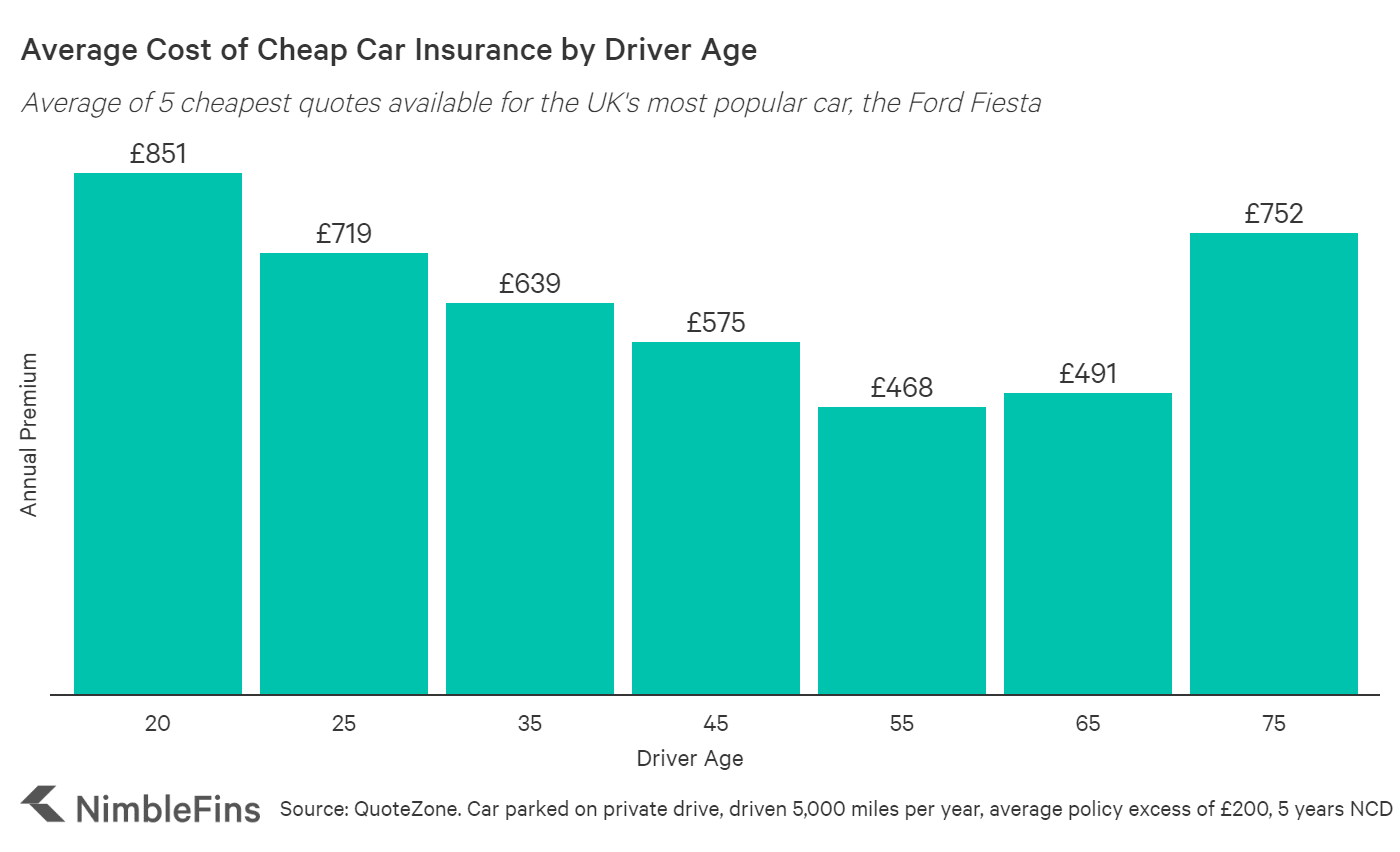
Auto insurance premiums are influenced by a mix of personal, vehicle, and market factors. Core elements include the driver’s age, location, driving record, and the car’s make/model. For instance, a 30-year-old in a suburban area with a clean record may pay significantly less than a 70-year-old in an urban center with prior claims. Market conditions, such as regional accident rates or insurer competition, also shift costs. Understanding these variables helps drivers anticipate quotes and negotiate better rates.
Insurers use actuarial data to calculate risk profiles. A high-performance sports car, for example, typically incurs higher premiums due to theft and accident risks, while a hybrid SUV might qualify for discounts. External factors like natural disaster zones or urban congestion further impact pricing. By recognizing these dynamics, drivers can strategically adjust their policies—for instance, choosing a higher deductible to lower monthly costs.

2. Key Factors in Cost Comparison
- Coverage Limits and Types
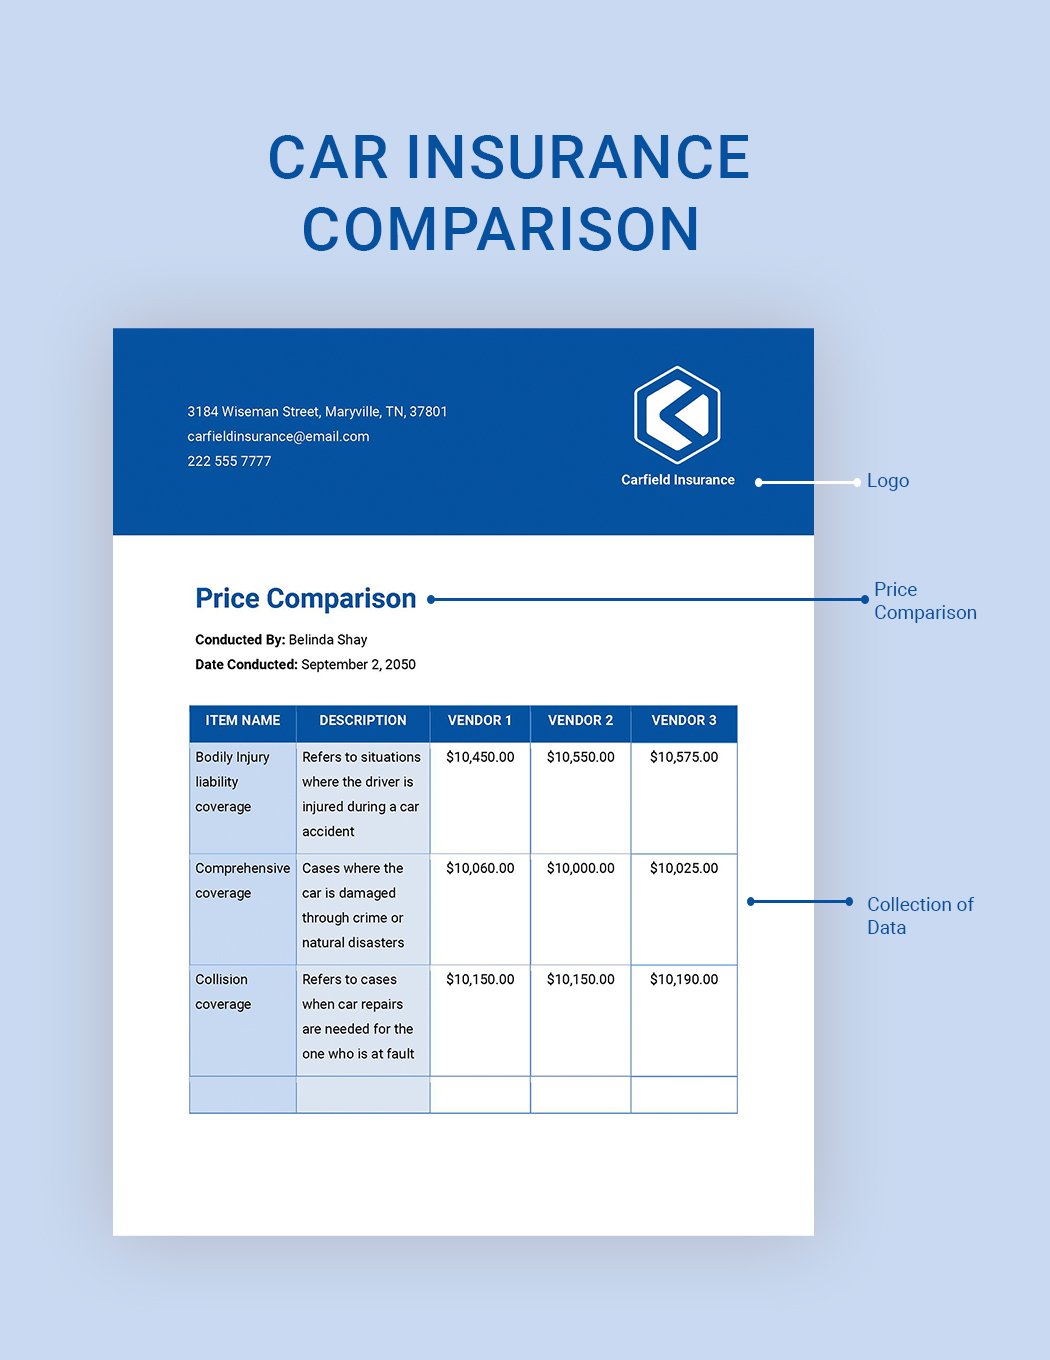
Full coverage (collision, comprehensive, liability) costs more than state-minimum policies but offers broader protection. A driver in Florida might pay $150/month for full coverage versus $80 for basic liability. Assessing personal risk tolerance—such as the likelihood of filing a claim—helps determine the optimal balance.
- Deductibles and Out-of-Pocket Costs
Higher deductibles reduce premiums but require more upfront payment after an accident. A $1,000 deductible could save $50/month but demands significant cash reserves. For example, a policyholder with a $500 deductible might pay $200 less annually than one with a $250 deductible.
- Discounts and Bundling
Insurers offer discounts for safe driving, low mileage, or bundling auto with home insurance. A driver who combines policies might save 10–20% annually. Multi-car discounts or loyalty programs further reduce costs, making comparison tools essential to uncover these perks.
- Insurer Reputation and Claims Handling
Low premiums are meaningless if an insurer denies claims or provides poor customer service. Checking reviews on platforms like J.D. Power or the National Association of Insurance Commissioners (NAIC) reveals how insurers handle payouts. A company with a 4.2-star rating may justify a slightly higher quote.
- Usage-Based Insurance
Telematics programs, like Progressive’s Snapshot or State Farm’s Drive Safe & Save, monitor driving habits to adjust rates. A cautious driver might earn a 30% discount, while aggressive braking or speeding could increase costs. This real-time data offers personalized pricing unavailable through traditional quotes.
3. Common Mistakes to Avoid
One frequent error is comparing only the monthly premium without reviewing the full policy. A seemingly cheap quote might exclude critical coverages, such as uninsured motorist protection or gap insurance for leased vehicles. Another mistake is ignoring regional differences; a policy priced in California may not apply in New York due to varying state laws and risk factors. Additionally, drivers often overlook the importance of updating their profiles—marital status, credit score, or even a new roof on their home can lower rates.
Relying on a single insurer’s quote without exploring alternatives is another pitfall. Insurers prioritize different risk factors, so one may offer better rates for young drivers while another specializes in high-risk profiles. Skipping the comparison process can result in paying 20–30% more than necessary. Always request quotes from at least three insurers to benchmark pricing.
4. Tools and Technology for Comparison
Digital tools streamline auto insurance cost comparison by aggregating quotes, analyzing coverage gaps, and identifying discounts. Platforms like The Zebra, NerdWallet, and Policygenius allow users to input their details once to receive tailored recommendations. These tools often highlight hidden savings, such as paperless billing discounts or affiliation perks (e.g., AAA members). For those who prefer hands-on research, insurer websites and mobile apps provide side-by-side comparisons of plans.
Advanced features, like AI-driven recommendations, suggest optimal coverage levels based on usage patterns. For example, a driver who rarely uses their car for work might benefit from a low-mileage discount, which automated tools can flag. However, users should verify tool accuracy by cross-checking with direct insurer quotes, as some platforms may prioritize partnerships over unbiased rankings.
5. State-Specific Considerations
Auto insurance requirements and costs vary significantly by state due to differences in traffic laws, accident rates, and minimum coverage mandates. In no-fault states like Michigan or Florida, personal injury protection (PIP) is mandatory, increasing premiums by 20–40%. Conversely, states with lower population densities, such as North Dakota, tend to have cheaper average rates. Understanding these nuances is critical; a driver moving from New York to Texas might see premiums drop by $1,000 annually due to lower state minimums and fewer urban risks.
Additionally, some states regulate premium pricing more strictly, capping how insurers can adjust rates based on factors like credit history or gender. In others, insurers have more flexibility, leading to wider price variations. Researching state-specific insurer rankings and legal requirements ensures compliance and cost efficiency during comparisons.
6. When to Recompare Your Policy
Life changes—such as marriage, buying a new car, or moving—can significantly impact insurance costs. For example, adding a teenage driver to a policy might increase premiums by 100% or more, necessitating a recomparison to explore usage-based programs or higher deductibles. Similarly, improving credit scores (a factor in many states) or completing a defensive driving course can lower rates, making it worthwhile to re-evaluate options annually.
Market fluctuations also warrant periodic comparisons. Economic downturns or insurer mergers can shift pricing dynamics, while new laws—like those expanding coverage for electric vehicles—may introduce cost-saving opportunities. Setting a calendar reminder every 6–12 months ensures policies remain competitive without overhauling the entire process.
7. The Role of Credit Scores
In most states, credit-based insurance scores influence premiums by predicting claim likelihood. A driver with a 750+ credit score might pay 20–30% less than someone with a 600 score, as insurers associate better credit with responsible behavior. However, some states, like California and Hawaii, prohibit this practice, making credit history irrelevant for comparisons. To improve scores—and potentially rates—drivers can pay down debt, dispute errors on credit reports, or use tools like Experian Boost to factor in utility payments.
This factor underscores the importance of holistic comparisons. A driver with average credit might find an insurer that weighs driving history more heavily than credit, offering a better rate. Always request quotes from insurers known for fair credit practices, such as USAA (for military members) or State Farm, which often provide more lenient underwriting.
8. Coverage vs. Cost Trade-offs
Balancing coverage depth with affordability requires evaluating personal risk exposure. A driver in a high-theft area might prioritize comprehensive coverage, while one with an older car may opt for collision waivers to save on premiums. For instance, dropping collision coverage on a 15-year-old car could reduce annual costs by $300–$500, but only if the car’s value doesn’t exceed the deductible. Similarly, increasing liability limits from the state minimum to $500,000/1M might add $20–$50/month but protects against catastrophic lawsuits.
Another trade-off involves gap insurance for leased or financed vehicles. While it covers the difference between a car’s depreciated value and loan balance, it can add $15–$30/month. Drivers should compare this cost against the potential loss—often thousands of dollars—in a total loss scenario. Using comparison tools to model these scenarios ensures informed decisions without sacrificing essential protection.
17 Actionable Tips for Smarter Comparison
Conducting a thorough auto insurance cost comparison requires strategy. Here are 17 proven tips to optimize the process:
Tip 1: Gather accurate vehicle details. Include the VIN, make, model, year, and mileage to ensure precise quotes. Even small discrepancies can lead to overcharging.
Tip 2: Standardize coverage levels across quotes. Compare apples to apples by selecting identical limits (e.g., 100/300/50) and deductibles ($500) for each insurer.
Tip 3: Use independent comparison tools. Platforms like NerdWallet or Policygenius aggregate quotes from multiple insurers, saving time and reducing bias.
Tip 4: Request quotes from direct insurers too. Online-only insurers like Geico or Lemonade often offer lower rates than traditional agents, but verify their state availability.
Tip 5: Check for multi-policy discounts. Bundling auto with home or renters insurance can reduce premiums by 10–25%. Ask insurers about bundling perks during comparison.
Tip 6: Compare usage-based programs. Enroll in telematics programs like State Farm’s Drive Safe & Save to earn discounts for safe driving habits.
Tip 7: Review state-specific requirements. Ensure all quotes meet your state’s minimum coverage laws to avoid legal penalties or denied claims.
Tip 8: Ask about loyalty discounts. Some insurers reward long-term customers with discounts after 3–5 years, so inquire during comparisons.
Tip 9: Consider higher deductibles for savings. Increasing deductibles from $250 to $1,000 can lower premiums by $30–$100/month, but only if you can afford the out-of-pocket cost.
Tip 10: Compare customer service ratings. Use J.D. Power or NAIC complaint indexes to evaluate insurers’ claims handling and support quality.
Tip 11: Explore regional or niche insurers. Companies like USAA (military) or Farmers (rural areas) may offer tailored rates not available from mainstream providers.
Tip 12: Review add-ons like roadside assistance. Some insurers bundle roadside coverage for $5–$10/month, adding value beyond basic policies.
Tip 13: Factor in payment plan flexibility. Insurers offering quarterly or annual payments (with discounts) can reduce overall costs compared to monthly billing.
Tip 14: Check for new driver or student discounts. Programs like Progressive’s “Good Student Discount” or Allstate’s “Smart Student” can cut rates for young drivers.
Tip 15: Compare gap insurance for leased cars. If financing a vehicle, ensure quotes include gap coverage to avoid paying off a loan on a depreciated car.
Tip 16: Review insurer financial stability. Use AM Best ratings to confirm insurers can pay claims, especially for high-risk drivers.
Tip 17: Recompare after major life changes. Events like marriage, divorce, or buying a home can alter insurance needs, making it critical to reassess quotes.
Conclusion
Mastering auto insurance cost comparison involves more than just finding the lowest premium; it requires balancing coverage, discounts, and insurer reliability. By understanding pricing dynamics, leveraging technology, and avoiding common pitfalls, drivers can secure policies that align with their budgets and protection needs. The key takeaway is to treat insurance as an ongoing process—one that adapts to life changes and market trends to ensure both savings and security.
As insurers continue to innovate with usage-based pricing and AI-driven recommendations, the tools for smarter comparisons will only improve. Staying informed and proactive ensures that every policy renewal is an opportunity to optimize costs without compromising peace of mind.
Related articles

11 Essential Facts About Auto Insurance Estimate Calculators
Discover how an auto insurance estimate calculator simplifies premium comparisons, reveals hidden discounts, and cuts research time by 70%. Learn its…
16 Proven Ways to Compare Auto Insurance Prices Like a Pro
Save hundreds on auto insurance by mastering how to compare prices effectively. Discover expert tips, common pitfalls, and step-by-step strategies to…
13+ Ways to Get the Best Auto Ins Quotes Online Insurance in 2024
Discover how to compare auto ins quotes online insurance for maximum savings. Learn expert tips, avoid hidden fees, and find the right policy…

10 Essential Facts About Auto and Insurance Quote You Need to Know
Understand how auto and insurance quotes work, why they matter, and how to get the best rates. Learn key tips to save money and avoid common pitfalls in…
8 Smart Ways to Get an Affordable Car Insurance Quote in 2024
An affordable car insurance quote saves hundreds yearly. Learn how to compare rates, avoid hidden costs, and secure the best deal without sacrificing…
