16 Proven Ways to Compare Auto Insurance Prices Like a Pro
Table of Contents
- 1. Understanding Pricing Dynamics
- 2. When to Compare Auto Insurance Prices
- 3. Key Factors Affecting Price Comparisons
- 4. Tools and Platforms for Comparing Prices
- 5. Common Mistakes to Avoid
- 6. How to Leverage Discounts
- 7. Negotiating with Insurers
- 8. State-Specific Considerations
- 9. The Role of Credit Scores
- 10. Comparing Bundled vs. Standalone Policies
- 11. The Impact of Deductibles
- 12. Seasonal and Location-Based Adjustments
- 13. How Technology Changes Comparisons
- 14. Comparing Full Coverage vs. Liability-Only
- 15. The Hidden Costs of Switching Insurers
- 16. Future Trends in Auto Insurance Comparison
- Frequently Asked Questions
- 16 Proven Tips to Compare Auto Insurance Prices
- Conclusion
When searching for the best deal on auto insurance, the phrase **auto insurance compare prices** becomes the gateway to significant savings. Imagine two drivers with identical coverage needs: one spends hours manually calling agents, while the other uses an online comparison tool to find a policy costing $300 less annually. The difference isn’t just in time saved but in the financial burden lifted. Auto insurance pricing varies widely due to factors like location, driving record, and vehicle type, making comparison a necessity rather than an option.
Comparing auto insurance prices isn’t just about finding the lowest premium—it’s about balancing cost with coverage quality. A cheaper policy might skimp on liability limits or exclude essential protections like comprehensive coverage. Historically, consumers relied on word-of-mouth recommendations or local agents, but today’s digital landscape empowers shoppers with real-time data and AI-driven tools. This shift has democratized access to fair pricing, enabling even first-time drivers to negotiate better terms.
This guide breaks down the science behind **auto insurance compare prices**, from decoding pricing algorithms to spotting hidden discounts. Whether leveraging comparison websites, negotiating with insurers, or understanding policy jargon, these strategies ensure informed decisions. By the end, readers will know exactly how to navigate the market—without falling for common traps.
1. Understanding Pricing Dynamics
Auto insurance rates are calculated using complex algorithms that weigh risk factors like age, gender, credit score, and claim history. For example, a 25-year-old in a high-theft neighborhood might pay 30% more than a 50-year-old in a low-crash area. Insurers also adjust premiums based on seasonal trends—rates often spike after holidays due to increased driving risks. Transparency in these dynamics helps consumers anticipate costs and advocate for fairer quotes.
2. When to Compare Auto Insurance Prices
The optimal time to **compare auto insurance prices** is during annual renewals, but proactive shoppers should also review rates after major life changes, such as moving to a new ZIP code or adding a teen driver. A 2022 study by the Insurance Information Institute found that switching insurers mid-term could save drivers up to 25% on average. Even small changes—like upgrading safety features in a vehicle—can trigger lower premiums. The key is to avoid lapses in coverage, which can void discounts or lead to higher rates upon renewal.
3. Key Factors Affecting Price Comparisons
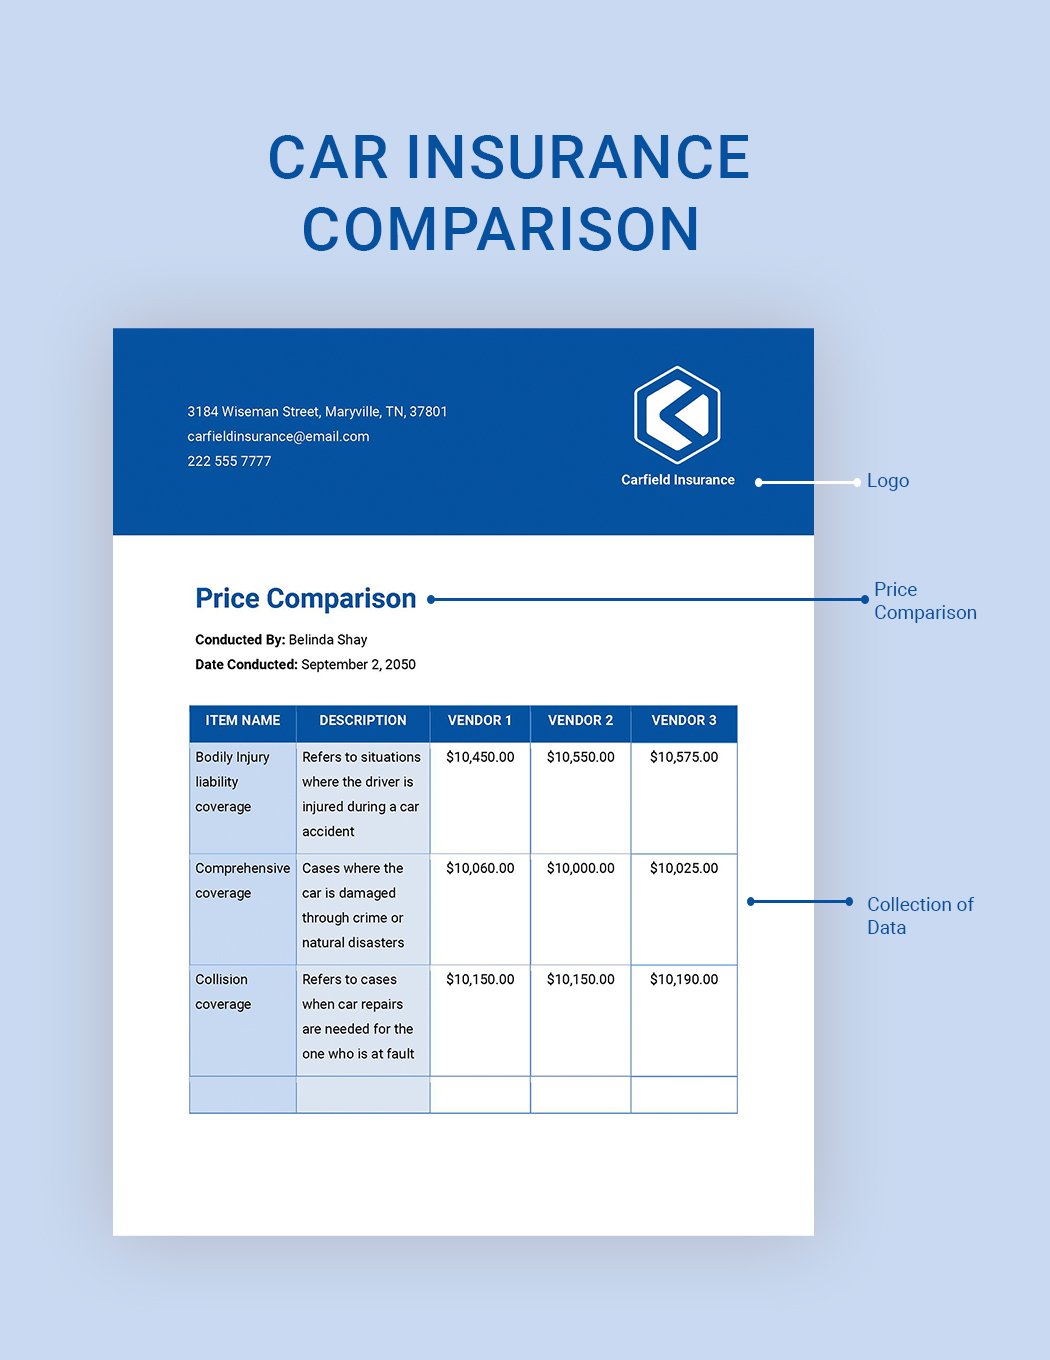
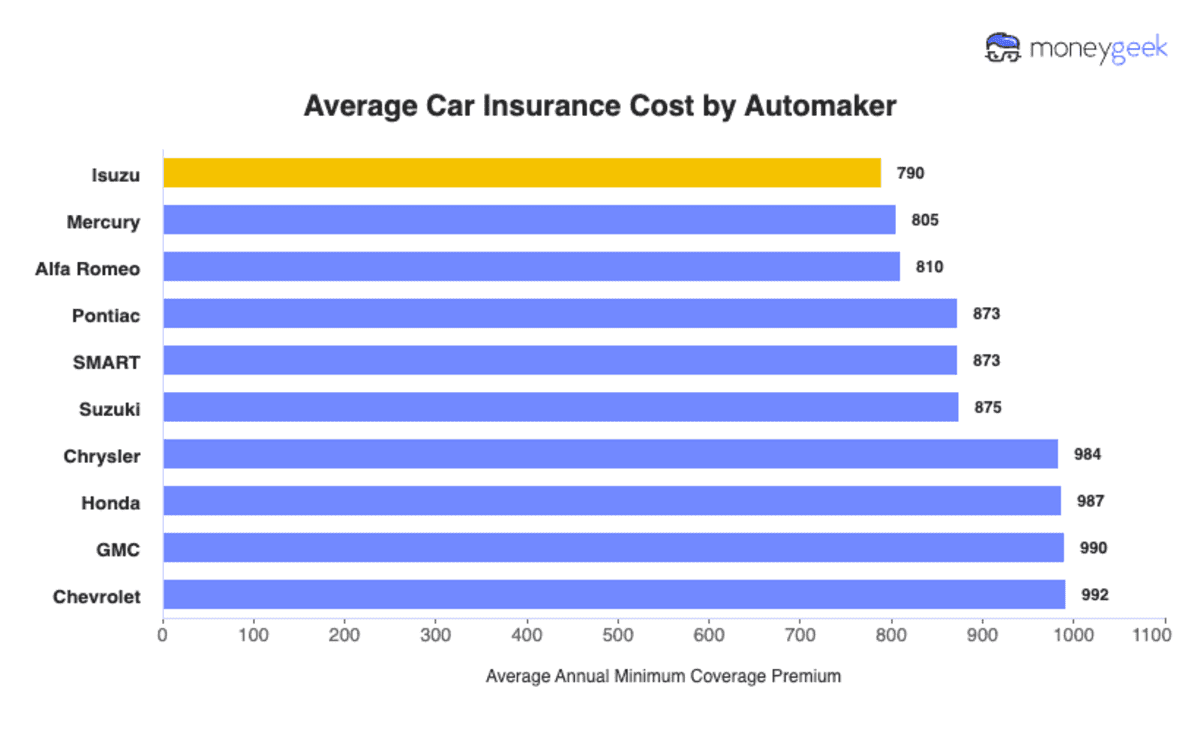
Several immutable variables influence auto insurance costs, but understanding their interplay is critical. Driving history: A single at-fault accident can increase premiums by 20-50% for three years. For instance, a driver with a clean record in Texas might pay $1,200 annually, while one with a speeding ticket could see rates jump to $1,800. Vehicle specifications: A 2019 Honda Civic with anti-theft devices costs less to insure than a 2015 Ford Mustang with a V8 engine. Coverage limits: Liability-only policies are cheaper but leave drivers vulnerable to lawsuits. States like Florida mandate higher limits, which directly impact quotes.
4. Tools and Platforms for Comparing Prices
Online comparison tools like NerdWallet and The Zebra aggregate quotes from multiple insurers in minutes. These platforms use proprietary algorithms to match users with the best rates based on their inputs. Mobile apps like Lemonade further simplify the process by offering instant quotes and claims filing. However, not all tools are equal—some prioritize speed over accuracy, leading to misleading results. Always cross-reference with official insurer websites for verification.
5. Common Mistakes to Avoid
One of the biggest errors is comparing only premium costs without examining deductibles or coverage gaps. For example, a policy with a $250 deductible might seem cheaper upfront but could leave a driver paying out-of-pocket for a $1,500 repair. Ignoring bundling options: Combining auto and home insurance with the same provider often yields discounts of 10-15%. Skipping the fine print: Exclusions for rental cars or roadside assistance can add unexpected costs. Assuming loyalty pays off: Insurers rarely reward long-term customers with better rates unless they’ve maintained a clean record.
6. How to Leverage Discounts
Insurers offer discounts for behaviors like safe driving, low mileage, or completing defensive driving courses. For instance, Progressive’s Snapshot program tracks driving habits via a mobile app and can reduce premiums by up to 30% for cautious drivers. Other overlooked discounts include military service, student away-at-school status, or even installing anti-theft devices like OBD-II locks. Proactively asking insurers about available savings can uncover hidden benefits worth hundreds annually.
7. Negotiating with Insurers
Direct negotiation with insurers is underutilized but effective. After receiving quotes, call the provider and mention competing offers. A polite but firm approach—such as, *“I’ve found a policy at $800, but I’d like to explore options with you at $750”—can prompt adjustments. Insurers may also offer temporary discounts to retain customers during renewal periods. This tactic works best when armed with concrete data, like side-by-side quote comparisons.
8. State-Specific Considerations
Auto insurance regulations vary by state, impacting both pricing and coverage requirements. In no-fault states like Michigan, drivers must carry Personal Injury Protection (PIP), which increases premiums by an average of 15%. Conversely, states like Texas offer more competition, leading to lower rates. Understanding local laws—such as Florida’s strict no-fault rules—helps avoid legal pitfalls while shopping. Always verify state mandates before finalizing a policy to ensure compliance.
9. The Role of Credit Scores
Credit scores are a controversial but widely used factor in auto insurance pricing. In most states, insurers assume higher credit scores correlate with lower risk. A driver with a score of 750 might pay 10% less than one with a score of 650. However, this practice is banned in California, Hawaii, and Massachusetts. Even in states where it’s allowed, improving credit—through timely bill payments or debt reduction—can gradually lower insurance costs. TransUnion reports that a 30-point credit score increase can reduce premiums by up to 5%.
10. Comparing Bundled vs. Standalone Policies
Bundling auto and home insurance often results in multi-policy discounts, but standalone policies might offer better rates for high-risk drivers. For example, a renter in New York could save $500 annually by bundling with State Farm but might find cheaper standalone auto coverage with Geico. The decision depends on individual circumstances—assess total annual costs across all policies to determine the best strategy. Many insurers also offer umbrella policies for additional liability coverage, which can be cost-effective for drivers with significant assets.
11. The Impact of Deductibles
Deductibles directly affect out-of-pocket expenses and premium costs. A higher deductible—such as $1,000 instead of $250—lowers monthly payments but increases financial risk in case of a claim. For instance, a driver with a $500 deductible might pay $150/month, while a $2,500 deductible could reduce that to $80/month. The ideal deductible balances affordability with risk tolerance. Always consider the vehicle’s value and repair costs when choosing this option.
12. Seasonal and Location-Based Adjustments
Insurance rates fluctuate by season and location due to varying risk factors. Urban areas like New York City have higher premiums due to congestion and theft, while rural regions in Montana may offer lower rates. Additionally, rates often spike during holiday weekends when driving increases. Using tools like Insure.com’s rate heatmaps can reveal regional disparities. Adjusting coverage temporarily—such as lowering comprehensive insurance during winter months—can also yield savings.
13. How Technology Changes Comparisons
AI and machine learning are revolutionizing auto insurance comparisons by personalizing quotes in real time. Companies like Allstate use predictive analytics to assess risk beyond traditional factors, such as driving patterns or even weather data. Telematics devices, like those from Usage-Based Insurance (UBI) programs, track speed and braking habits, offering discounts to safe drivers. While these innovations improve accuracy, they also raise privacy concerns. Consumers should weigh the benefits against potential data-sharing risks.
14. Comparing Full Coverage vs. Liability-Only
Full coverage policies include collision and comprehensive insurance, protecting against repairs or theft, while liability-only covers third-party damages. A 2023 study by the Insurance Information Institute found that full coverage adds 20-30% to premiums but is often required by lenders for financed vehicles. For older cars worth less than the deductible, liability-only may suffice. Always calculate the potential out-of-pocket costs of repairs versus the premium savings to determine the best option.
15. The Hidden Costs of Switching Insurers
Switching insurers can save money but may come with hidden costs, such as early termination fees or gaps in coverage. Some policies require a 30-day notice before cancellation, and lapses in coverage can lead to higher rates upon renewal. Additionally, new insurers may conduct credit checks or require medical history disclosures, which could indirectly raise premiums. Always review cancellation policies and ensure seamless transitions to avoid disruptions.
16. Future Trends in Auto Insurance Comparison
The future of **auto insurance compare prices** lies in hyper-personalization and blockchain technology. Insurers are exploring usage-based insurance models that adjust rates in real time based on driving behavior, while blockchain could streamline claims processing and reduce fraud. Emerging platforms like Insurtech startups are also integrating with telematics and IoT devices to offer dynamic pricing. As these technologies mature, consumers will benefit from even more tailored and transparent comparisons.
16 Proven Tips to Compare Auto Insurance Prices
Before diving into comparisons, gather all relevant documents, including your driver’s license, vehicle registration, and recent quotes. Organized information speeds up the process and ensures accuracy.
Tip 2: Use multiple comparison tools. Relying on a single tool may limit your options. Combine platforms like NerdWallet with The Zebra to cross-reference results and identify the best deals.
Tip 3: Check for state-mandated coverage requirements. Each state has minimum liability limits; ignoring these can lead to fines or voided policies. Verify requirements on your state’s Department of Insurance website before finalizing a quote.
Tip 4: Compare apples to apples. Ensure all quotes include the same coverage limits, deductibles, and riders. A cheaper policy might lack essential protections like uninsured motorist coverage.
Tip 5: Ask about hidden fees. Some insurers charge administrative fees or require add-ons like roadside assistance. Always review the policy’s fine print to avoid unexpected costs.
Tip 6: Consider usage-based insurance. Programs like Progressive’s Snapshot track driving habits and reward safe behavior with discounts. This can be cost-effective for cautious drivers.
Tip 7: Review your coverage needs annually. Life changes—like adding a teen driver or upgrading your car—may require adjusting your policy. Reassessing coverage ensures you’re not over- or under-insured.
Tip 8: Bundle policies for discounts. Combining auto and home insurance with the same provider often yields 10-15% savings. Even if one policy is cheaper elsewhere, bundling may offset the difference.
Tip 9: Increase your deductible if possible. Raising your deductible from $500 to $1,000 can lower premiums by 15-25%. Just ensure you can afford the out-of-pocket cost in case of a claim.
Tip 10: Ask about loyalty discounts. Some insurers reward long-term customers with discounts after 3-5 years. Even if rates haven’t changed, inquire about retention bonuses.
Tip 11: Compare independent agents vs. direct insurers. Independent agents can shop multiple providers for you, while direct insurers (like Geico) offer lower overhead costs. Weigh the convenience of one against the expertise of the other.
Tip 12: Look for discounts you qualify for. Common discounts include safe driver, student away-at-school, and anti-theft device incentives. Always ask insurers to list all applicable savings.
Tip 13: Avoid canceling mid-term. Switching insurers mid-policy can void discounts or lead to higher rates upon renewal. Plan transitions around renewal dates to maintain coverage continuity.
Tip 14: Use price comparison apps. Apps like Lemonade offer instant quotes and claims processing. They’re convenient for quick comparisons but may lack the depth of desktop tools.
Tip 15: Negotiate with insurers. If you’ve found a better quote elsewhere, call your current insurer and ask if they can match it. Many will adjust rates to retain customers, especially if you’ve had no claims.
Tip 16: Stay informed about industry trends. Follow insurance news to stay updated on new discounts, regulatory changes, or technological advancements. Knowledge empowers better decision-making during comparisons.
Conclusion
Mastering **auto insurance compare prices** transforms a daunting task into a strategic opportunity for savings and peace of mind. The process hinges on understanding pricing dynamics, leveraging technology, and avoiding common pitfalls like ignoring discounts or comparing unrelated policies. From negotiating with insurers to bundling coverage, each step refines the search for the best balance of cost and protection. As insurers embrace AI and usage-based models, consumers will gain even more transparency and control over their premiums.
The future of auto insurance comparisons lies in personalization and efficiency. By adopting these strategies today, drivers can secure policies that align with their needs—and budgets—while staying ahead of industry shifts. The key is to approach the process proactively, armed with knowledge and tools designed to simplify the search for the best rates.
Related articles

17 Essential Tips for Smart Auto Insurance Cost Comparison
Discover how to master auto insurance cost comparison with expert insights. Learn to save hundreds on premiums by comparing quotes, understanding rates,…
8+ Ways to Secure the Best Auto Insurance Rates in 2024
Discover proven strategies to unlock the best auto insurance rates and save hundreds annually. Learn how to compare policies, avoid hidden fees, and…
13+ Ways to Get the Best Auto Ins Quotes Online Insurance in 2024
Discover how to compare auto ins quotes online insurance for maximum savings. Learn expert tips, avoid hidden fees, and find the right policy…

9+ Ways to Find the Best Auto Car Insurance Near Me for Savings and Coverage
Discover how to locate top-rated auto car insurance near me with expert tips on pricing, coverage, and local providers. Compare quotes and save today!

10 Essential Facts About Auto and Insurance Quote You Need to Know
Understand how auto and insurance quotes work, why they matter, and how to get the best rates. Learn key tips to save money and avoid common pitfalls in…
