8+ Ways to Secure the Best Auto Insurance Rates in 2024
Table of Contents
- 1. Understanding Pricing Dynamics
- 2. How Credit Scores Impact Rates
- 3. Leveraging Discounts for Savings
- 4. Comparing Quotes Across Insurers
- 5. Adjusting Coverage and Deductibles
- 6. Avoiding Common Pitfalls
- 7. The Role of Location and Vehicle Type
- 8. Seasonal and Market Trends
- Frequently Asked Questions
- 8 Proven Tips to Secure the Best Auto Insurance Rates
- Conclusion
Securing the best auto insurance rates demands a blend of informed decision-making and strategic negotiation. For instance, a driver in California switching from a mid-tier provider to a top-rated insurer like Geico could reduce annual premiums by $800 while maintaining full coverage. Auto insurance best rates aren’t just about finding the lowest price—they involve balancing affordability with adequate protection, leveraging discounts, and understanding how insurers calculate premiums. Over the past decade, technological advancements like telematics and usage-based insurance have reshaped the industry, enabling drivers to earn rewards for safe behavior while reducing costs.
The importance of identifying the best auto insurance rates extends beyond immediate savings. High-quality coverage mitigates financial risks from accidents, theft, or natural disasters, preserving assets and peace of mind. Historically, bundling policies (e.g., auto and home insurance) has been a proven method to achieve discounts of 10–20%, but modern tools now allow for granular comparisons across insurers. This article explores the key factors influencing auto insurance best rates, common pitfalls, and actionable steps to optimize coverage while minimizing expenses.
The following sections dissect the mechanics of auto insurance pricing, highlight overlooked discounts, and reveal how small changes—like adjusting deductibles or improving credit scores—can yield significant savings. By the end, readers will understand how to navigate the market with confidence, ensuring they’re not overpaying for essential protection.
1. Understanding Pricing Dynamics
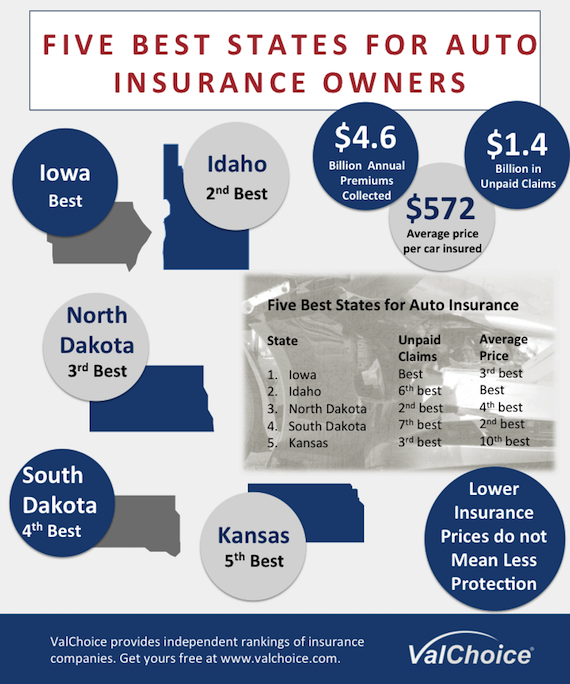
The best auto insurance rates are determined by a complex interplay of risk factors, market trends, and insurer algorithms. Core variables include driving history, vehicle type, location, and demographic data. For example, a 30-year-old with a clean record driving a Honda Civic in a low-theft neighborhood will pay far less than a 25-year-old with a DUI record driving a luxury SUV in a high-crime area. Insurers use actuarial science to quantify these risks, translating them into premiums. Understanding this system empowers drivers to address high-risk factors proactively, such as enrolling in defensive driving courses or installing anti-theft devices to reduce premiums.
2. How Credit Scores Impact Rates
Credit scores are a critical yet often underestimated factor in determining auto insurance best rates. Insurers treat creditworthiness as a proxy for financial responsibility, with studies showing that drivers with excellent credit scores (720+) pay an average of 30% less than those with poor scores (below 620). In states like California, insurers can legally use credit-based insurance scores, meaning a low score could inflate premiums by hundreds annually. Improving credit—by paying bills on time or reducing debt—can therefore unlock substantial savings. For instance, a driver with a 650 credit score might see their premium drop by $400 after raising it to 750 through disciplined financial habits.
3. Leveraging Discounts for Savings
Insurers offer a vast array of discounts that, when combined, can slash premiums by 25% or more. Many drivers overlook these perks, leaving money on the table. Below are key discount categories and their practical implications:
- Safe Driver Discounts
Insurers reward low-mileage drivers or those who avoid accidents. For example, Progressive’s Snapshot program tracks driving habits via a plugin device, offering discounts of up to 30% for safe behavior. A driver logging consistent safe miles could save $600 annually on a $2,000 premium policy.
- Bundling Policies
Combining auto insurance with homeowners or renters insurance often yields multi-policy discounts of 10–20%. State Farm, for instance, provides a 15% discount for bundling, which for a $1,500 auto policy translates to $225 in annual savings. This strategy consolidates coverage while reducing administrative hassles.
- Low Mileage Discounts
Drivers who log fewer than 7,500 miles annually may qualify for reduced rates. Allstate’s low-mileage discount, for example, applies to commuters or retirees, potentially cutting premiums by 5–10%. A part-time worker driving 5,000 miles yearly could save $150 by qualifying for this discount.
- Anti-Theft and Safety Devices
Installing approved safety features—like airbags, anti-lock brakes, or GPS tracking—can lower rates. The Insurance Institute for Highway Safety reports that vehicles with top safety ratings often qualify for discounts of 5–15%. A driver upgrading to a Toyota Camry with advanced safety tech could see a $200 annual reduction on a $2,500 policy.
- Good Student Discounts
Dependent students maintaining a B average or higher may qualify for discounts through insurers like Farmers or USAA. This discount, often 10–25%, extends to drivers aged 16–25. A college student with a 3.8 GPA could save $300 on a $1,200 policy by providing proof of grades.
4. Comparing Quotes Across Insurers
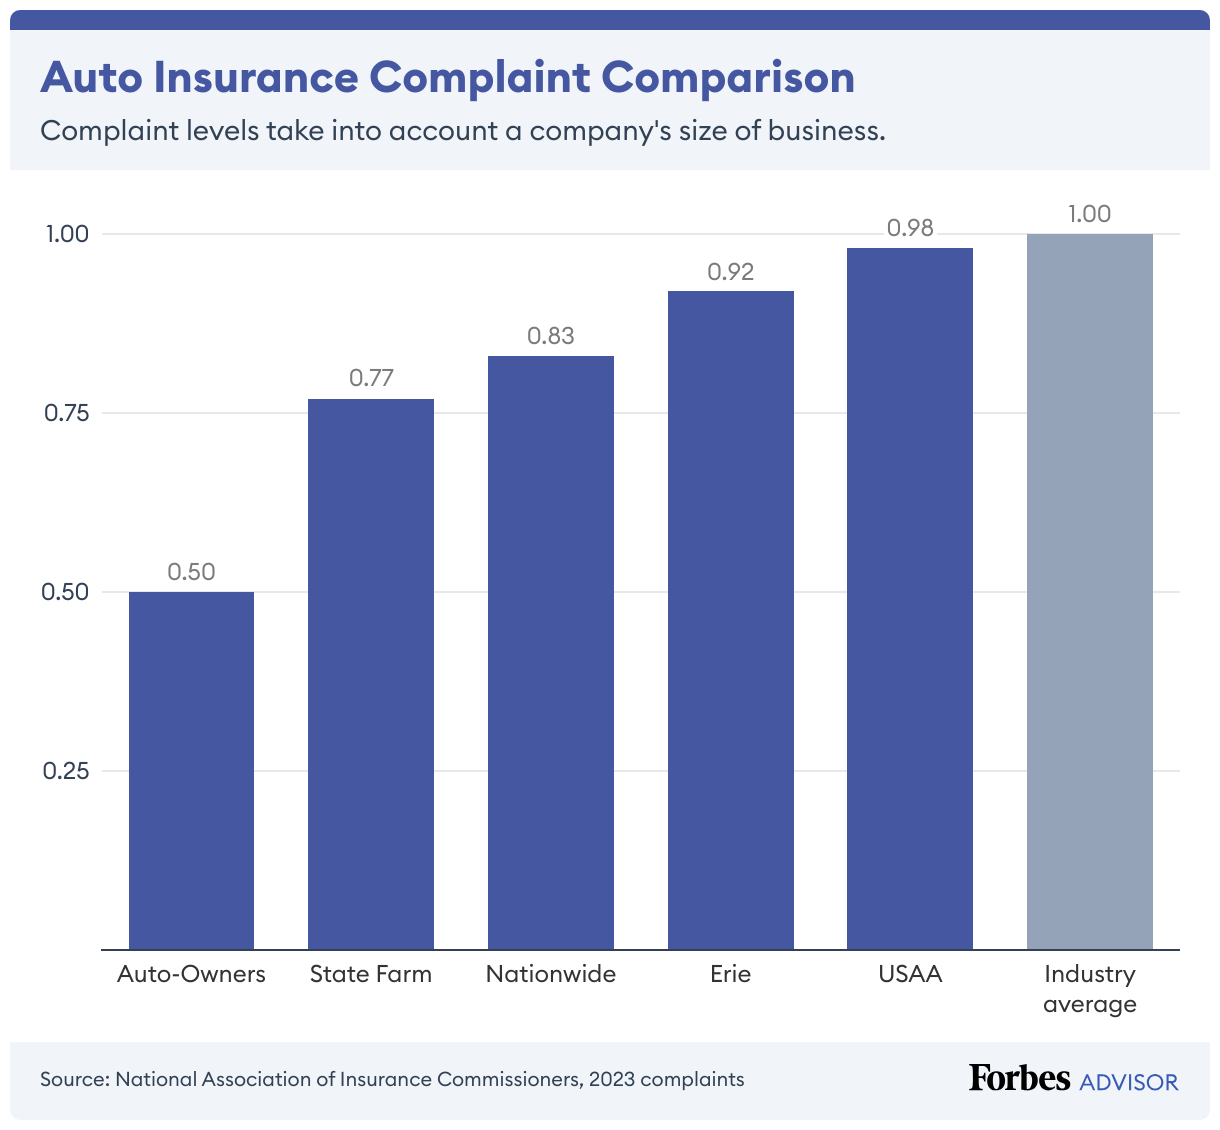
Securing the best auto insurance rates requires comparing quotes from multiple providers, as premiums can vary by 50% or more for identical coverage. A 2023 study by the National Association of Insurance Commissioners found that drivers who shopped around saved an average of $800 annually. However, this process is often time-consuming, which is why tools like Policygenius or The Zebra automate comparisons by aggregating quotes from top insurers. For example, a driver in Texas might find that Lemonade offers a $1,200 policy for $600, while State Farm charges $950 for the same coverage. The key is to evaluate not just price but also customer reviews, claim satisfaction ratings, and financial stability.
5. Adjusting Coverage and Deductibles
Tailoring coverage to individual needs can significantly impact auto insurance best rates. Over-insuring a low-value car—such as a 5-year-old sedan with comprehensive coverage—can inflate premiums unnecessarily. Conversely, under-insuring a luxury vehicle leaves it vulnerable to costly repairs. A balanced approach involves assessing the car’s actual value, local theft rates, and personal financial capacity to cover out-of-pocket expenses. For instance, raising a $500 deductible to $1,000 could cut premiums by 15–20%, saving $300 annually on a $2,000 policy. Drivers should also consider liability limits, ensuring they meet state minimums while avoiding excessive exposure.
6. Avoiding Common Pitfalls
Several missteps can sabotage efforts to achieve the best auto insurance rates. One prevalent error is neglecting to update policies after life changes, such as moving to a new city or purchasing a new car. For example, a driver relocating from a low-crime suburb to a high-theft urban area might see premiums spike by 30% without adjusting coverage. Another pitfall is ignoring no-claim discounts, which reward policyholders for accident-free years. Insurers like USAA offer discounts of up to 50% after 5 years without claims. Additionally, drivers often overlook the impact of optional add-ons, such as roadside assistance or rental reimbursement, which can inflate premiums by 10–25% without providing tangible benefits.
7. The Role of Location and Vehicle Type
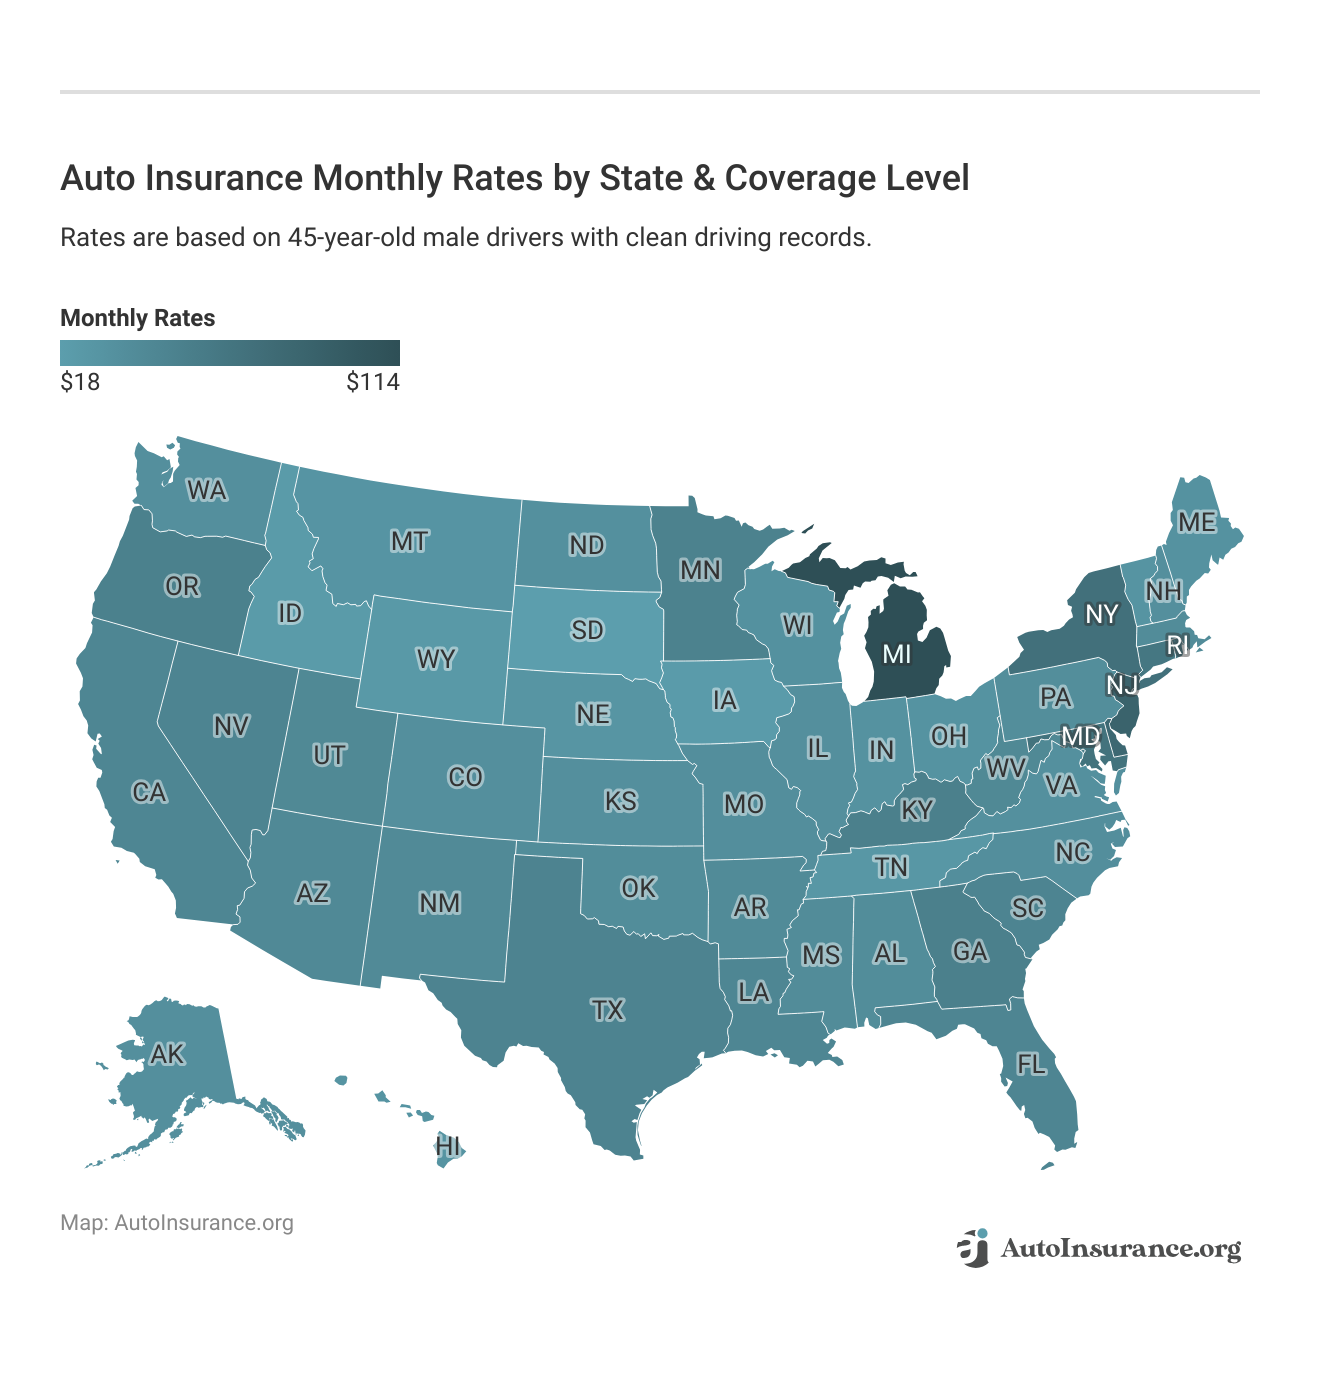
Geographic location and vehicle specifications are two of the most influential factors in determining auto insurance best rates. Urban areas with higher accident rates, such as New York City or Miami, typically command premiums 20–40% higher than rural regions. For example, a driver in Manhattan might pay $2,500 annually for full coverage, while a comparable policy in Boise could cost $1,500. Similarly, vehicle type plays a pivotal role; sports cars or luxury vehicles are statistically riskier, leading to premiums 50–100% above average. A 2023 report by Kelley Blue Book highlighted that a Tesla Model 3 in California averaged $2,200 in annual premiums, whereas a Honda Accord paid $1,200 for identical coverage. Drivers can mitigate these costs by choosing safer, lower-profile vehicles or opting for higher deductibles on high-value cars.
8. Seasonal and Market Trends
Auto insurance best rates fluctuate with seasonal trends and broader market conditions, offering strategic opportunities for savvy shoppers. For instance, premiums often dip in the spring and summer as insurers adjust for lower claim frequencies during favorable weather. Conversely, rates may rise in the fall and winter due to increased accident risks from poor road conditions. Additionally, economic factors like inflation or supply chain disruptions can drive up repair costs, indirectly increasing premiums. Drivers should monitor industry reports from organizations like the Insurance Information Institute to time their policy renewals during periods of lower rates. For example, renewing a policy in May rather than December could yield savings of $100–$300, depending on regional trends.
8 Proven Tips to Secure the Best Auto Insurance Rates
Optimizing for auto insurance best rates requires a mix of proactive habits and strategic decisions. Below are eight actionable steps to maximize savings:
Tip 1: Shop around annually. Rates fluctuate, and insurers adjust premiums based on risk profiles. Using comparison tools like The Zebra or NerdWallet ensures you’re not locked into a suboptimal policy. A driver in Florida could save $500 by switching from State Farm to Geico after a year.
Tip 2: Bundle policies for discounts. Combining auto insurance with homeowners or renters insurance often yields multi-policy discounts of 10–20%. State Farm, for example, offers a 15% discount for bundling, which could save $225 on a $1,500 auto policy.
Tip 3: Maintain a clean driving record. Accidents and traffic violations increase premiums by 20–50%. Enrolling in defensive driving courses or using safe-driving apps like Snapshot can earn discounts of up to 30%, potentially saving $600 annually.
Tip 4: Choose the right vehicle. Opting for a safer, lower-profile car reduces risk and lowers rates. For example, a Honda Civic typically costs $1,200 annually in premiums, while a BMW 3 Series may exceed $2,500 for identical coverage.
Tip 5: Review coverage needs annually. Adjusting deductibles or liability limits can align premiums with your budget and risk tolerance. Raising a deductible from $500 to $1,000 might cut costs by 20%, saving $300 on a $1,500 policy.
Tip 6: Leverage loyalty and retention discounts. Staying with an insurer for multiple years can unlock loyalty rewards. USAA, for instance, offers discounts of up to 20% for long-term customers, potentially saving $400 on a $2,000 policy.
Tip 7: Install safety and anti-theft devices. Equipping your car with approved features like airbags or GPS tracking can earn discounts of 5–15%. A driver installing a theft-deterrent system might reduce premiums by $200 on a $2,500 policy.
Tip 8: Negotiate with insurers. If you’ve been a loyal customer or improved your risk profile, call your insurer to ask for a review. Some companies will reduce premiums by 5–10% without switching providers. A policyholder with a clean record might negotiate a $150 discount on a $1,200 policy.
Conclusion
The pursuit of auto insurance best rates hinges on understanding the interplay of risk factors, market dynamics, and insurer policies. From leveraging discounts like safe driving rewards to strategically adjusting coverage and deductibles, small changes can yield substantial savings. Location, vehicle type, and credit history remain foundational, but proactive measures—such as annual quote comparisons and bundling policies—further optimize affordability. By adopting these strategies, drivers can balance cost and coverage, ensuring they’re neither overpaying nor underprotected.
As the auto insurance landscape continues to evolve with technological advancements and regulatory shifts, staying informed and adaptable will remain key. Future trends, such as AI-driven pricing models and expanded usage-based programs, promise even greater opportunities to secure competitive rates. For now, armed with the insights from this guide, drivers can navigate the market with confidence, prioritizing both value and peace of mind.
Related articles
10 Ways to Find Affordable Insurance Car Insurance Without Sacrificing Coverage
Discover how to secure **affordable insurance car insurance** with smart strategies, avoid common pitfalls, and keep premiums low while maintaining…
16 Proven Ways to Compare Auto Insurance Prices Like a Pro
Save hundreds on auto insurance by mastering how to compare prices effectively. Discover expert tips, common pitfalls, and step-by-step strategies to…
15 Key Insights Into Allstate Insurance Quote Auto: A Comprehensive Guide
Get an Allstate insurance quote auto fast with these expert insights. Learn pricing, coverage, and tips to save money while securing top-rated protection…
10 Key Insights About Allstate Insurance Car Insurance
Discover how Allstate Insurance car insurance works, its benefits, pricing, and coverage options. Learn why millions trust it for reliable auto…
12+ Ways to Find Affordable Car Insurance in Georgia
Discover proven strategies to secure cheap yet reliable car insurance in Georgia without sacrificing coverage. Learn how to cut costs legally and…
