11 Essential Facts About Auto Insurance Estimate Calculators
Table of Contents
- 1. How Calculators Determine Premiums
- 2. Key Inputs That Impact Estimates
- 3. Accuracy vs. Final Quotes: What to Expect
- 4. Common Mistakes That Skew Results
- 5. When to Use a Calculator vs. Agent Consultation
- 6. Advanced Features: Telematics and Usage-Based Insurance
- 7. How to Maximize Savings with a Calculator
- Frequently Asked Questions
- 11 Pro Tips to Get the Best Auto Insurance Quote
- Conclusion
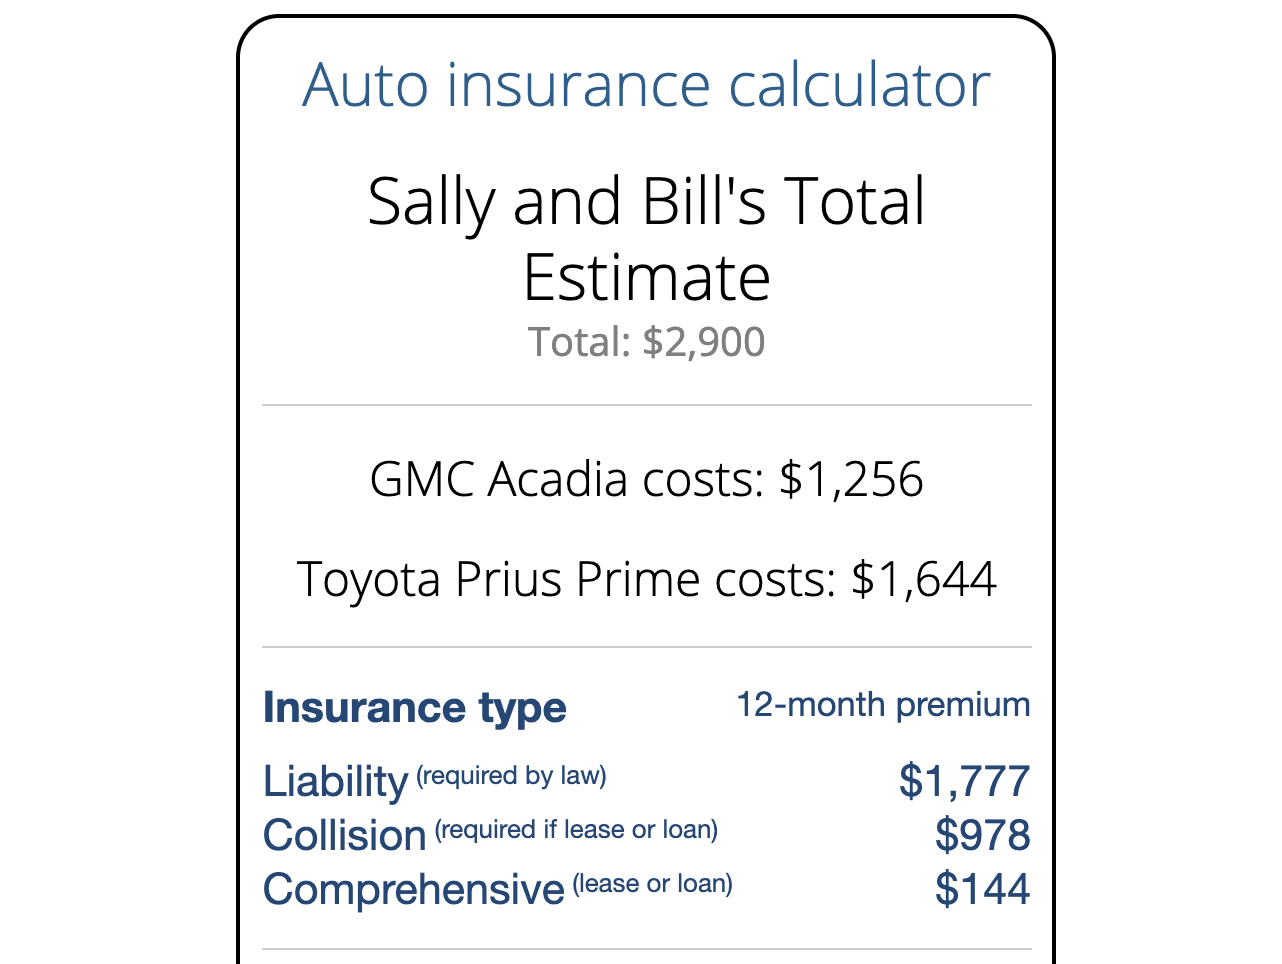
An **auto insurance estimate calculator** is an online tool that provides a preliminary projection of insurance premiums based on user inputs like vehicle details, driving history, and location. For example, entering a 2020 Toyota Camry with 15,000 miles, a clean driving record, and a zip code in Austin, Texas, might yield an estimated annual premium range of $1,200–$1,800—before discounts or final underwriting. These calculators bridge the gap between raw data and actionable insights, offering transparency in an industry often criticized for opaque pricing.
The importance of an auto insurance estimate calculator lies in its ability to democratize access to pricing information. Historically, securing quotes required calling multiple insurers or visiting agents—a time-consuming process prone to human error. Today, these digital tools leverage algorithms trained on millions of policyholder datasets to deliver near-instant estimates. Benefits include identifying affordable coverage options, spotting overlooked discounts (e.g., bundling home and auto policies), and avoiding overpayment by up to 30% compared to sticking with a single provider’s initial quote.
This article explores the mechanics, limitations, and strategic uses of an auto insurance estimate calculator. Topics include how these tools factor in risk variables, their accuracy compared to final quotes, and practical steps to maximize savings. Whether preparing for a new policy or reassessing current coverage, understanding the calculator’s role empowers drivers to make informed decisions.
1. How Calculators Determine Premiums
Auto insurance estimate calculators use a weighted algorithm that combines inputs into a risk profile. Core factors include the vehicle’s make/model/year (a 2023 Tesla Model 3 typically costs more to insure than a Honda Civic due to repair costs and theft rates), the driver’s age and gender (young male drivers under 25 often face higher rates), and location (urban areas with higher accident frequencies increase premiums). For instance, a driver in Miami might see a 20% premium increase compared to one in Des Moines, Iowa, due to higher claims frequency.
Underwriting models also incorporate driving history—even a single at-fault accident can elevate premiums by 40–60% for three years. Some advanced calculators now factor in telematics data (e.g., hard braking frequency) or credit scores (in states where legal), though the latter remains controversial. The calculator’s output is not a binding quote but a probabilistic estimate, typically accurate within ±15% of the final premium.

2. Key Inputs That Impact Estimates
- Vehicle Details
The make, model, year, and trim level directly influence replacement costs and theft risk. For example, a 2021 Jeep Wrangler with a $40,000 market value will have higher collision/comprehensive premiums than a 2021 Honda Fit valued at $18,000. Anti-theft devices (like OnStar or LoJack) can reduce premiums by 5–10%. Always input the exact trim and optional features, as a base model may lack safety tech that lowers rates.
- Driving HistoryA single speeding ticket might add $300–$500 annually, while a DUI can double premiums for five years. Some calculators allow users to input past violations and show how long it takes for rates to normalize. For instance, a minor moving violation’s impact diminishes after three years in most states, but severe offenses (e.g., hit-and-run) may persist longer.
- Coverage Limits and Deductibles
Higher liability limits (e.g., 100/300/50 vs. 25/50/25) increase premiums but offer greater asset protection. A $500 deductible for collision might save 10–15% compared to a $250 deductible. Calculators often default to state minimums; adjusting these can reveal significant cost trade-offs. For example, in Florida, raising collision coverage from $10,000 to $50,000 might add $200/year but protect against total losses in a hurricane.
- Discounts and Bundling
Many calculators include dropdowns for common discounts, such as safe driver (5–15% off), multi-policy (10–20% off), or low-mileage (up to 5% off). Overlooking these can mean missing savings. For example, a driver with a 15-mile daily commute might qualify for a low-mileage discount but won’t see it unless explicitly selected. Some insurers (like Progressive) offer discounts for paying annually or installing usage-based devices.
- Location and CommuteZip codes trigger localized data on accident rates, theft, and weather risks. Urban drivers in cities like Los Angeles or Chicago often pay 20–30% more than rural counterparts due to congestion-related claims. Commute distance also matters—a 45-minute daily drive may increase premiums by 10% compared to a 10-minute trip, as longer commutes correlate with higher exposure to accidents.
3. Accuracy vs. Final Quotes: What to Expect
The gap between an auto insurance estimate calculator’s output and a final underwritten quote stems from two key differences: the calculator’s reliance on averages and the insurer’s assessment of individual risk. For instance, a calculator might estimate a premium of $1,500 for a 30-year-old driver in Boston, but the insurer could adjust this to $1,700 after reviewing the driver’s credit score (in Massachusetts) or discovering a prior claim not disclosed in the initial input. On average, calculator estimates deviate from final quotes by 10–20%, with higher discrepancies for high-risk profiles.
Accuracy improves when users input precise details. Rounding up age or downplaying mileage can lead to significant overestimates, while underreporting prior claims may result in denied coverage later. Some insurers (like Geico) allow users to compare calculator estimates to actual quotes side by side, highlighting where assumptions differed. For example, a calculator might not account for a driver’s occupation (e.g., truck drivers or rideshare users face higher rates), so manual verification remains critical.
4. Common Mistakes That Skew Results
- Ignoring Vehicle Modifications
Aftermarket upgrades like lifted suspensions or performance chips can void manufacturer warranties and increase premiums by 15–40%. A calculator may default to stock vehicle specs, leading to underestimates. For example, a 2022 Ford F-150 with a $10,000 lift kit could see collision premiums rise by $500/year if not disclosed, as insurers classify it as a modified vehicle with higher risk.
- Using Outdated Driver Information
Entering an incorrect age (e.g., rounding down from 29 to 25) or failing to update a recent marriage (which may qualify for spouse discounts) can distort estimates. Some calculators auto-fill past data, so users must verify details. For instance, a newlywed who bundles policies might save $400/year but miss the discount if the marriage isn’t reflected in the inputs.
- Overlooking State-Specific Rules
No-fault states (like Michigan or New York) have mandatory coverage requirements that calculators may not highlight. For example, Michigan’s no-fault law requires personal injury protection (PIP) with minimum limits of $250,000, which can add $1,000–$2,000 annually to premiums. Ignoring these rules can lead to non-compliance penalties or denied claims.
- Assuming All Discounts Apply Automatically
Some discounts (e.g., good student for young drivers) require proof, while others (like paperless billing) are opt-in. A calculator might list 10 potential discounts, but only 3 may apply after verification. For example, a student with a 3.8 GPA might qualify for a 15% good student discount, but failing to submit a transcript could mean losing the savings.
- Comparing Apples to Oranges
Not all calculators use the same risk models. Progressive’s tool may emphasize telematics, while State Farm’s leans on credit scores. Cross-referencing three tools (e.g., from Progressive, Allstate, and Lemonade) can reveal a 10–20% range in estimates for the same driver. For instance, a driver with excellent credit might see a $1,200 estimate from State Farm but $1,500 from USAA, due to differing underwriting priorities.
5. When to Use a Calculator vs. Agent Consultation
An auto insurance estimate calculator excels at providing a baseline for comparison shopping, especially for standard policies with straightforward risk profiles. It’s ideal for drivers with clean records, average vehicles, and no complex coverage needs (e.g., classic cars or high-net-worth assets). For example, a 40-year-old insuring a 2019 Subaru Outback with no prior claims can efficiently compare quotes from 5–10 insurers in under 30 minutes using tools like The Zebra or NerdWallet.
However, consultation with an agent becomes necessary for nuanced scenarios. High-value vehicles (e.g., a 1967 Mustang with a $250,000 appraisal) require specialized coverage like agreed value or scheduled personal effects. Similarly, drivers with complex histories (e.g., multiple at-fault accidents or commercial use) benefit from an agent’s ability to negotiate terms or explore non-standard insurers. For instance, a rideshare driver using Uber Full may need an agent to clarify whether personal auto policies exclude gig-related incidents.
6. Advanced Features: Telematics and Usage-Based Insurance
Modern auto insurance estimate calculators increasingly integrate telematics, where drivers opt into programs that track behavior via smartphone apps or plug-in devices. Examples include Progressive’s Snapshot or Allstate’s Drivewise, which monitor speed, braking, and mileage. These tools can adjust premiums dynamically—rewarding safe drivers with discounts of 10–30% or penalizing risky behavior. For instance, a driver who hard-brakes frequently might see a 15% premium hike, while one who drives mostly at night (a lower-risk time) could earn a 10% discount.
Usage-based insurance (UBI) is reshaping the industry by shifting from static risk models to real-time data. Calculators now include UBI opt-in prompts, explaining how data sharing could lower costs. For example, a driver in a high-theft area might pay $1,800 annually under traditional pricing but drop to $1,400 with UBI if their telematics show low nighttime driving (a common theft risk factor). However, privacy concerns persist, as some drivers hesitate to share location or driving habits, even when it could save money.
7. How to Maximize Savings with a Calculator
Leveraging an auto insurance estimate calculator for savings requires strategic input and follow-up. Start by entering all eligible discounts, even if they seem minor. For example, a driver who pays six months’ premium upfront might save 5–7%, but this option is often buried in the calculator’s advanced settings. Another tactic is to compare quotes across insurers using the same calculator platform (e.g., Compare.com aggregates multiple tools), as this controls for input consistency. A side-by-side comparison might reveal that Insurer A offers a 20% discount for bundling, while Insurer B doesn’t mention it until after the quote.
Timing also plays a role. Shopping for quotes within a 30-day window typically doesn’t hurt credit scores (thanks to insurance score exemptions), and some states mandate insurers to offer discounts for completing a defensive driving course. For instance, California drivers can save up to 10% by completing an approved course, but this must be manually entered into the calculator. Finally, annual reviews are critical—life changes like moving, marriage, or adding a teen driver can unlock new discounts or necessitate higher coverage limits, both of which the calculator can help reassess.
11 Pro Tips to Get the Best Auto Insurance Quote
An auto insurance estimate calculator is just the first step—these tips ensure the most accurate and cost-effective outcome.
Tip 1: Input Exact Vehicle Specs. Avoid generic selections like “SUV” or “sedan.” Specify the exact trim, engine type, and optional safety features (e.g., blind-spot monitoring), as these directly impact repair costs and theft risk.
Tip 2: Compare Across Three Insurers. Use calculators from insurers with distinct underwriting priorities (e.g., Progressive for telematics, State Farm for credit-based discounts). This reveals a broader range of potential rates and discounts.
Tip 3: Request Quotes Within a 14-Day Window. Multiple inquiries in this period typically count as a single credit check, minimizing score impact. Use this window to compare formal quotes, not just calculator estimates.
Tip 4: Disclose All Driver Details. Include all household members who drive the vehicle, even occasionally. Omitting a teen driver or part-time rideshare user can void coverage if an accident occurs, and it may inflate premiums later.
Tip 5: Check for State-Specific Discounts. Some states (e.g., California, New York) offer unique programs like low-income discounts or earthquake coverage add-ons. Enter your state in the calculator’s advanced settings to uncover these.
Tip 6: Opt for Higher Deductibles. Raising the collision/comprehensive deductible from $500 to $1,000 can reduce premiums by 15–25%. Ensure you can afford the deductible in case of a claim—balance cost savings with financial risk.
Tip 7: Bundle Policies. Combining auto with home, renters, or life insurance can slash premiums by 10–20%. Most calculators include a bundling prompt, but verify the exact savings with the insurer.
Tip 8: Explore Usage-Based Programs. Enroll in telematics programs (e.g., Allstate’s Drivewise) to earn discounts for safe driving. Even if the calculator doesn’t highlight this, proactive enrollment can yield savings of 5–30%.
Tip 9: Review Coverage Limits Annually. Inflation and life changes may require higher liability limits. A calculator can show how adjusting limits (e.g., from 50/100/50 to 100/300/100) affects premiums while protecting assets.
Tip 10: Ask About Loyalty Discounts. Some insurers offer 5–10% discounts for policyholders with 5+ years of continuous coverage. This isn’t always visible in calculators, so inquire directly after getting an estimate.
Tip 11: Recalculate After Major Life Events. Changes like marriage, divorce, or buying a home can unlock new discounts (e.g., spouse or multi-policy) or necessitate higher coverage. Use the calculator to reassess within 30 days of such events.
Conclusion
An auto insurance estimate calculator serves as a powerful tool for demystifying premiums, identifying savings opportunities, and streamlining the quote comparison process. By understanding how these tools weigh factors like vehicle details, driving history, and location, drivers can make data-driven decisions rather than relying on guesswork or agent assumptions. The key lies in precise input, cross-insurer comparisons, and leveraging advanced features like telematics or bundling—all of which the calculator facilitates.
As the insurance industry continues to embrace real-time data and personalized pricing, mastering the use of an auto insurance estimate calculator will remain essential for securing fair, tailored coverage. Regularly revisiting estimates ensures policies evolve with changing risks and life circumstances, ultimately safeguarding both finances and peace of mind.

Related articles

17 Essential Tips for Smart Auto Insurance Cost Comparison
Discover how to master auto insurance cost comparison with expert insights. Learn to save hundreds on premiums by comparing quotes, understanding rates,…

17+ Ways to Find the Best Cheap Auto Insurance for Your Budget
Discover how to get **cheap auto insurance** without sacrificing coverage. Learn proven strategies, common pitfalls, and expert tips to save hundreds on…
13+ Ways to Get the Best Auto Ins Quotes Online Insurance in 2024
Discover how to compare auto ins quotes online insurance for maximum savings. Learn expert tips, avoid hidden fees, and find the right policy…

10 Essential Facts About Auto and Insurance Quote You Need to Know
Understand how auto and insurance quotes work, why they matter, and how to get the best rates. Learn key tips to save money and avoid common pitfalls in…

14 Key Facts About AAA Insurance Quote Online You Need to Know
Get accurate AAA insurance quote online insights: pricing, coverage types, and expert tips to save time and money. Learn how to compare quotes like a pro.
