Find Auto Insurance Close To Me With Top Local Providers
Table of Contents
- Key Factors Influencing Auto Insurance Rates in Specific Geographic Areas
- Specialized Auto Insurance Coverage Types Available Near Major Cities and Suburban Areas
- Unique Selling Points of Regional Auto Insurers and Their Local Advantages
- Strategies to Reduce Auto Insurance Premiums in High-Cost Areas
- Steps to Take Immediately After an Accident to Maximize Claim Success with a Local Insurer
- Common Causes of Auto Accidents in Local Markets and Insurer Responses
- Step-by-Step Guide to Switching from a National to a Local Auto Insurer
- Local Insurers' Use of Technology to Enhance Driver Efficiency and Convenience
- State and Municipal Auto Insurance Regulations: Mandatory Coverages, Filing Deadlines, and Compliance Requirements
- Local Insurer Road Safety Initiatives and Community Engagement
- Evolution of Local Auto Insurance Markets Driven by Fuel Costs, EV Adoption, and Autonomous Vehicles
- Directory of Local Resources for Policyholders
Auto insurance close to me isn’t just about finding the cheapest rate—it’s about securing tailored protection that matches your local risks, commute habits, and unique needs. From urban congestion to rural wildlife hazards, where you live directly shapes your policy, premiums, and claim experiences. Whether you’re a city commuter navigating distracted driver zones or a suburban driver facing seasonal storm risks, local insurers offer specialized coverage, faster claim processing, and community-backed perks that national brands often overlook. This guide breaks down how to navigate your local market, from comparing top providers and customizing policies to leveraging technology and avoiding common pitfalls that drain your wallet.
Beyond basic liability coverage, local insurers provide niche solutions like ride-share endorsements for urban drivers, weather-specific add-ons for high-risk areas, and discounts for participating in community safety programs. Understanding how factors like neighborhood crime rates, traffic laws, or even your garage location influence your premium can save you hundreds annually. With rising costs and evolving risks—from electric vehicle adoption to autonomous vehicle testing—staying informed about regional trends ensures you’re not just insured, but *optimally* insured. The right policy isn’t just a legal requirement; it’s a financial safeguard and a reflection of your community’s unique challenges.
Key Factors Influencing Auto Insurance Rates in Specific Geographic Areas
Auto insurance premiums vary significantly between urban and rural regions due to differences in risk exposure, infrastructure, and demographic factors. Urban areas typically face higher premiums due to increased traffic density, higher theft rates, and greater likelihood of accidents, while rural areas may experience lower costs but higher deductibles for specific risks like uninsured motorists or weather-related incidents. Understanding these regional variations helps drivers make informed decisions when selecting coverage. **Risk Exposure and Local Crime Rates** Insurance providers assess geographic risk through crime statistics, accident frequency, and environmental hazards. Urban zones with high population density often report: - Higher rates of **theft and vandalism**, increasing comprehensive coverage costs. - More **traffic congestion**, raising liability and collision claim probabilities. - Increased **pedestrian and cyclist accidents**, leading to higher bodily injury claims.**Example:** A 2023 study by the Insurance Information Institute found that urban drivers in cities like Los Angeles and Chicago pay **30–50% more** for full coverage than those in rural counties like Wyoming or Vermont, primarily due to theft and accident risks.**Traffic Patterns and Commuting Habits** Commuting distances and traffic conditions directly impact insurance costs. Urban drivers with long daily commutes (e.g., 30+ miles) face higher premiums due to: - **Increased wear and tear** on vehicles, raising maintenance-related claim risks. - **Higher exposure to accidents** in congested areas, particularly during rush hours. - **Parking-related incidents**, such as break-ins or fender benders in tight spaces.
**Key Data Point:** The National Safety Council reports that **urban drivers average 1.2 accidents per 100 million miles driven**, compared to **0.8 in rural areas**, contributing to premium disparities.**Infrastructure and Emergency Response Times** Regions with **poor road maintenance** or **delayed emergency services** may see higher claim costs. For example: - Rural areas with **limited access to tow trucks or repair shops** could face longer claim processing times, increasing insurer costs. - Urban zones with **frequent pothole damage** may lead to more collision claims, though insurers often offset this with better repair networks. **Weather and Environmental Risks** Climate plays a critical role in insurance pricing: - **Urban areas** with **flood zones** (e.g., Miami, New Orleans) or **hail-prone regions** (e.g., Texas, Colorado) see spikes in comprehensive coverage due to storm damage. - **Rural areas** with **wildfire risks** (e.g., California, Oregon) or **snowstorms** (e.g., Midwest, Northeast) may require higher deductibles or specialized endorsements.
**Case Study:** After Hurricane Ian (2022), Florida insurers raised premiums by **15–25%** in coastal urban zones due to repeated flood and wind damage claims.**Local Insurance Market Competition** Monopoly or limited insurer presence in a region can inflate premiums. For instance: - **Urban areas** with **multiple insurers** (e.g., State Farm, Geico, Progressive) often offer competitive rates. - **Rural counties** may rely on **local or regional insurers** (e.g., Farm Bureau, USAA for military families), which may have fewer discounts or higher base rates. **Demographic and Vehicle Usage Trends** Young drivers, elderly populations, and high-mileage commuters influence local rates: - **Urban centers** with **higher young driver concentrations** (e.g., college towns) see premium surges due to inexperience-related claims. - **Rural areas** with **older vehicles** may lack modern safety features, increasing collision risk and raising premiums.
**Statistic:** The Federal Highway Administration notes that **drivers under 25 account for 6% of licensed drivers but 12% of fatal crashes**, directly impacting urban insurance costs.**Regulatory and Tax Factors** State laws on **minimum coverage requirements**, **no-fault systems**, and **insurance taxes** further shape local rates. For example: - **No-fault states** (e.g., Florida, Michigan) may have higher premiums due to mandatory personal injury protection (PIP) coverage. - **High state insurance taxes** (e.g., Louisiana at **19.1%** of premiums) increase overall costs regardless of geographic risk. ---
Urban vs. Rural Auto Insurance Rate Comparison
| **Factor** | **Urban Areas** | **Rural Areas** | |--------------------------|------------------------------------------|------------------------------------------| | **Average Annual Premium** | $1,200–$2,500 (full coverage) | $800–$1,500 (full coverage) | | **Primary Risk Drivers** | Theft, traffic accidents, congestion | Uninsured motorists, weather damage | | **Common Discounts** | Multi-policy, anti-theft devices | Farm/business bundling, low-mileage | | **Claim Processing Time** | Faster (urban repair networks) | Slower (limited service providers) | | **High-Risk Zones** | Downtown cores, near highways | Floodplains, wildfire-prone regions | ---How Insurers Adjust Rates Based on Location
Insurance providers use **territorial rating** to group areas by risk. Common adjustments include: - **Postal Code-Based Pricing:** Urban ZIP codes may be classified as "high-risk," while rural ones as "moderate." - **Traffic Density Zones:** Areas with **>50,000 vehicles/mile/day** (e.g., I-95 in NYC) see premium hikes. - **Crime Heat Maps:** Neighborhoods with **high theft rates** (e.g., parts of Detroit, Baltimore) face surcharges. - **Weather Indexing:** Regions with **>10 inches of annual hail** (e.g., Denver) may require higher deductibles.**Example:** A driver in **Downtown Atlanta** might pay **$1,800/year** for full coverage, while a counterpart in **nearby Decatur (suburban)** could secure the same policy for **$1,400** due to lower accident rates.---
Mitigation Strategies for High-Risk Urban Drivers
Urban drivers can reduce premiums through: - **Telematics Programs:** Usage-based insurance (e.g., Progressive’s Snapshot, State Farm’s Drive Safe & Save) monitors driving habits. - **Anti-Theft Devices:** GPS trackers (e.g., LoJack) or steering wheel locks can lower comprehensive rates by **10–15%**. - **Parking in Low-Risk Zones:** Garaging vehicles in **secure, low-theft areas** may qualify for discounts. - **Higher Deductibles:** Opting for **$1,000+ deductibles** can reduce premiums by **20–30%**, though claim payouts decrease. - **Bundling Policies:** Combining auto with home/renter’s insurance (e.g., Allstate, Farmers) often yields **10–20% savings**.**Pro Tip:** Urban drivers should **compare quotes from local insurers** (e.g., regional carriers like Erie or Auto-Owners) alongside national providers, as some specialize in high-density areas.

Specialized Auto Insurance Coverage Types Available Near Major Cities and Suburban Areas
Auto insurance providers in densely populated regions often tailor policies to address the unique risks and needs of drivers in urban and suburban environments. These specialized coverages extend beyond standard liability and collision protection, addressing niche scenarios such as ride-sharing, classic vehicle ownership, or high-risk driving profiles. Understanding these options helps drivers select policies that align with local regulations, vehicle types, and personal circumstances. Insurers in metropolitan areas and suburbs frequently collaborate with local authorities and industry experts to design policies that mitigate risks specific to the region. For example, ride-share insurance adapts to the surge in gig-economy transportation, while classic car coverage accounts for lower mileage but higher repair costs. High-risk driver programs, often available through specialized insurers or state-mandated plans, provide pathways to affordable coverage despite past violations or poor credit histories. ---Ride-Share and Gig-Economy Insurance
The rise of ride-sharing services like Uber and Lyft has created demand for specialized insurance policies that account for periods when drivers are logged into the app but not yet matched with a passenger. Standard personal auto policies typically exclude coverage during these "grey periods," leaving drivers vulnerable to liability claims. **Key Features of Ride-Share Policies:** - **Period-Based Coverage:** Insurers like **Allstate, Progressive, and State Farm** offer endorsements that activate when the driver is en route to pick up a passenger or during the trip. Some policies also cover commercial liability if the vehicle is used for deliveries (e.g., DoorDash, Instacart). - **Higher Liability Limits:** Ride-share drivers often require higher limits (e.g., $1.5M or more) to comply with platform requirements and protect against passenger injuries or property damage. - **Commercial Use Endorsements:** Policies may include additional coverage for business use, such as wear-and-tear on the vehicle or equipment theft (e.g., GPS devices). - **Local Partnerships:** Insurers in cities like **Los Angeles, New York, and Chicago** frequently partner with ride-share companies to offer bundled discounts or expedited claims processing for drivers. **Cost Impact:** - Premiums for ride-share coverage can increase by **20–50%** compared to standard policies, depending on the driver’s mileage and claims history. - **Example:** A driver in **San Francisco** with 30,000 annual miles may pay **$2,500–$4,000/year** for a comprehensive ride-share policy, including collision and comprehensive coverage. ---Classic and Collector Car Insurance
Owners of classic or collector cars (typically vehicles over **25–30 years old** with limited annual mileage) require specialized insurance due to the high value of the vehicles and the need for agreed-value coverage. Standard policies may undervalue these cars or exclude coverage for modifications, restoration parts, or storage-related risks. **Key Features of Classic Car Policies:** - **Agreed-Value Coverage:** Ensures the vehicle is insured for its full appraised value (not actual cash value), which is critical for rare or high-demand models (e.g., **1967 Chevrolet Corvette Stingray, 1993 Mazda MX-5 Miata**). - **Scheduled Personal Property:** Covers specialized equipment, such as **custom rims, vintage tires, or restoration tools**, often stored separately from the vehicle. - **Low Mileage Discounts:** Insurers like **The Hagerty Group, Grange Insurance, and American Modern** offer discounts for vehicles driven fewer than **2,500–5,000 miles/year**. - **Storage and Transportation Coverage:** Protects against risks during **car shows, auctions, or shipping** to events (e.g., Pebble Beach Concours d’Elegance). - **Local Show and Event Endorsements:** Some insurers in **Miami (for vintage car meets), Austin (Texas Classic Car Weekend), or Nashville (National Muscle Car Show)** provide temporary coverage for vehicles displayed publicly. **Cost Impact:** - Premiums range from **$500–$3,000/year**, depending on the car’s value, age, and storage conditions. - **Example:** A **1965 Ford Mustang** valued at **$120,000** in **Miami** may cost **$1,800/year** for agreed-value coverage with a **$500 deductible**, while a **1987 Porsche 911** in **Los Angeles** could exceed **$2,500/year**. ---High-Risk Driver Insurance Programs
Drivers with **DUI convictions, multiple at-fault accidents, or poor credit scores** often face challenges securing affordable auto insurance. High-risk driver programs, available through **non-standard insurers or state-assigned risk pools**, provide coverage while mitigating financial exposure for insurers. **Key Features of High-Risk Policies:** - **SR-22 Filing Requirements:** Many states (e.g., **California, Florida, Texas**) mandate an **SR-22 certificate** for drivers reinstated after a suspension. Insurers like **Geico, The General, and Dairyland Insurance** specialize in SR-22 filings. - **Usage-Based Discounts:** Programs such as **Progressive’s Snapshot** or **State Farm’s Drive Safe & Save** offer discounts for safe driving behavior, even for high-risk drivers. - **Limited Coverage Options:** Policies may exclude **comprehensive coverage** or impose higher deductibles (e.g., **$1,000–$2,500**) to reduce premiums. - **Rehabilitation Programs:** Some insurers partner with **defensive driving courses** (e.g., **National Safety Council**) to provide premium reductions after completion. - **State-Specific Plans:** In states like **Michigan (MIAOP) or New Jersey (JUA)**, assigned risk pools ensure all drivers have access to basic coverage, though premiums can be **30–100% higher** than average. **Cost Impact:** - High-risk policies typically cost **$3,000–$8,000/year** for liability-only coverage, with full coverage exceeding **$10,000/year** in some cases. - **Example:** A driver in **Houston** with a **DUI conviction** may pay **$5,200/year** for **25/50/25 liability coverage** with a **$1,000 deductible**, compared to **$1,200/year** for a low-risk driver. ---Electric Vehicle (EV) and Hybrid-Specific Coverage
The growing adoption of **electric and hybrid vehicles** in urban areas has led insurers to develop specialized policies addressing unique risks, such as **battery replacement costs, charging infrastructure liability, and higher repair expenses** for advanced drivetrains. **Key Features of EV/Hybrid Policies:** - **Battery and Electrical System Coverage:** Insurers like **Nationwide, USAA, and Lemonade** offer **extended warranty-like coverage** for **traction battery failures** (e.g., **Tesla Model 3, Chevrolet Bolt**). - **Charging Station Liability:** Policies may include **commercial liability** if the vehicle is used for **public charging stations** (e.g., **ChargePoint partnerships**). - **Higher Repair Costs:** EVs often require **specialized mechanics**, and insurers may cover **diagnostic fees** or **labor costs** for complex repairs (e.g., **inverter failures in a Toyota Prius**). - **Theft and Vandalism Risks:** Urban EV owners face higher risks of **battery theft** or **charging port damage**; some insurers offer **equipment replacement endorsements**. - **Local EV Incentive Programs:** Cities like **Seattle, Portland, and San Diego** partner with insurers to offer **discounts for EV owners** who install **home charging stations** or participate in **smart grid programs**. **Cost Impact:** - EV insurance premiums can be **10–30% higher** than gas-powered vehicles due to repair costs, but discounts for **low-mileage commuters** or **safety features** (e.g., **Autopilot in Teslas**) may offset this. - **Example:** A **Tesla Model Y** in **San Francisco** may cost **$2,100/year** for full coverage, while a **Toyota RAV4 Hybrid** in **Atlanta** could be **$1,800/year**. ---Long Commute and Commuter Vehicle Policies
Drivers with **long daily commutes** (e.g., **50+ miles round-trip**) or those who use their vehicles for **business purposes** may require additional coverage to address **wear-and-tear, higher mileage, and increased accident risks**. **Key Features of Commuter Policies:** - **Mileage-Based Discounts:** Insurers like **Metromile** offer **pay-per-mile pricing** for drivers who commute extensively but have low annual mileage otherwise. - **Commercial Use Endorsements:** Policies may include **business use coverage** for **sales representatives, real estate agents, or contractors** who drive frequently. - **Tire and Maintenance Reimbursement:** Some insurers (e.g., **Allstate’s Drivewise**) provide **annual credits** for **tire rotations, oil changes, or battery replacements**. - **Rental Car Coverage:** Long commuters may add **rental reimbursement** to avoid gaps in transportation during repairs. - **Traffic and Congestion Protections:** In cities with **high accident rates** (e.g., **Los Angeles, New York**), insurers offer **accident forgiveness programs** or **lower deductibles** for fender benders. **Cost Impact:** - Policies for high-mileage drivers can cost **$2,500–$5,000/year**, but **usage-based programs** may reduce premiums by **15–25%**. - **Example:** A **sales executive in Chicago** driving **25,000 miles/year** may pay **$3,800/year** for a policy with **$500 deductibles**, but a **Metromile plan** could lower costs to **$2,200/year** if they drive **<12,000 miles/year**. ---Shared Ownership and Co-Ownership Policies
Vehicles owned by **multiple parties** (e.g., **roommates, family members, or business partners**) require specialized insurance to clarify **liability, usage rights, and claims responsibility**. **Key Features of Shared Ownership Policies:** - **Named Driver Restrictions:** Insurers like **Esurance and Farmers** allow **multiple drivers to be listed**, but usage limits (e.g., **primary vs. occasional driver**) may apply. - **Usage Tracking:** Some policies require **GPS or telematics** to monitor who drives the vehicle most frequently. - **Liability Clarification:** Policies specify **who is responsible for claims** if an unauthorized driver (e.g., a friend) causes an accident. - **Business Use Agreements:** For **co-owned vehicles used for rideshare or deliveries**, insurers may require **commercial endorsements**. - **Local Co-Ownership Programs:** Cities with **Unique Selling Points of Regional Auto Insurers and Their Local Advantages
Regional auto insurers differentiate themselves by embedding hyper-localized services into their policies, addressing the specific needs of drivers in their communities. Unlike national providers that rely on broad, standardized offerings, these insurers leverage deep ties to local infrastructure, weather patterns, and cultural nuances to create tailored solutions. Their unique selling points (USPs) often include personalized customer support, community-driven discounts, and specialized coverage options that align with regional risks—such as flood or hail damage in areas prone to severe storms. These advantages translate into tangible benefits for drivers, such as faster claim resolutions, lower premiums for safe driving habits, and access to localized roadside assistance networks. Below are the key USPs that set regional insurers apart, categorized by their core value propositions. ---24/7 Roadside Assistance with Local Response Times
Regional insurers prioritize rapid response times by partnering with local tow truck operators, auto repair shops, and emergency service providers. For example, insurers in the Southeast U.S. often collaborate with nearby mechanics to expedite repairs after hailstorms, while those in mountain regions may offer snow removal services during winter months. These partnerships ensure that drivers receive assistance from familiar faces who understand regional road conditions and local traffic patterns. **Key Features:** - **Same-day service guarantees** for breakdowns or accidents, with average response times under 30 minutes in urban areas and 60 minutes in rural regions. - **Multi-language support** in diverse communities, ensuring non-native speakers can communicate effectively with assistance providers. - **Priority dispatch** for policyholders during peak traffic hours or severe weather events, reducing wait times by up to 40% compared to national providers. *Example:* A regional insurer in Texas may include free battery jump-starts and tire changes as part of their roadside assistance, while a provider in Florida might offer hurricane evacuation support, including fuel delivery to stranded drivers. ---Local Agent Networks and Hyper-Personalized Service
Regional insurers maintain dense networks of independent agents who live and work within the communities they serve. These agents act as trusted advisors, offering in-person consultations, policy reviews, and claims assistance—unlike national insurers that often rely on call centers or digital-only interactions. Agents in rural areas may visit farms or small businesses to discuss coverage needs, while urban agents might partner with local car dealerships to streamline new-car insurance purchases. **Advantages of Local Agents:** - **Deep knowledge of regional risks**, such as recommending comprehensive coverage for drivers in tornado-prone zones or adding uninsured motorist protection in high-theft areas. - **Flexible payment plans** tailored to local economic conditions, such as seasonal discounts for farmers or military personnel. - **Community involvement**, including sponsorships of local sports teams or school events, which builds trust and loyalty. *Data Insight:* A 2023 survey by the National Association of Insurance Commissioners found that 68% of drivers with local agents reported higher satisfaction with their insurer compared to 42% of those using national providers. ---Community-Based Discounts and Loyalty Programs
Regional insurers incentivize long-term relationships and safe driving through discounts tied to local participation. These programs often include: - **Good neighbor discounts** for residents who volunteer with local organizations. - **Safe driver rewards** that offer cashback or premium reductions for policyholders with no at-fault accidents over a 3-year period. - **Bundling incentives** for insuring multiple vehicles or combining auto with homeowners insurance through the same regional provider. **Examples of Localized Discounts:** | **Program** | **Region** | **Discount Offered** | |---------------------------|---------------------|-----------------------------------------------| | Farm equipment coverage | Midwest (Iowa) | 15% off for policyholders who store equipment on their property | | Teacher discount | Northeast (NY) | 10% off for educators with a valid teaching license | | Military family rate | Southern California | 20% off for active-duty personnel and veterans | *Case Study:* In Oklahoma, a regional insurer partnered with local schools to offer a "Back-to-School Safety" discount, reducing premiums by 5% for drivers who completed defensive driving courses through the program. Over 1,200 policyholders participated in the first year, leading to a 22% increase in claims-free records. ---Weather-Specific Coverage and Disaster Response
Regional insurers in high-risk areas develop specialized policies to mitigate weather-related damages. For instance: - **Hurricane-prone states** (e.g., Florida, Louisiana) may offer **named-storm deductibles**, where policyholders pay a fixed fee per hurricane rather than a percentage of their claim. - **Wildfire zones** (e.g., California, Colorado) often include **emblem coverage** for smoke damage or tree removal after fires. - **Flood-endorsement add-ons** are commonly bundled in regions with seasonal flooding, such as the Midwest during spring thaw. **Claim Processing for Weather-Related Incidents:** - **Average processing time:** 5–7 business days for storm-related claims, compared to 10–14 days for national insurers. - **Common hurdles:** Delays in assessing flood damage due to waterline disputes or underestimating hail impact on older vehicles. - **Local advantage:** Regional insurers pre-position adjusters in disaster zones, reducing initial assessment times by 30%. *Example:* After Hurricane Ian in 2022, a regional insurer in Florida processed 87% of wind damage claims within 10 days, compared to a 30-day average for a major national competitor. ---Top 3 Reasons Drivers Prefer Local Insurers Over National Brands: 1. **Faster, More Empathetic Service** – Local agents and 24/7 roadside networks prioritize human connection and rapid response, especially during emergencies. 2. **Lower Costs Through Hyper-Local Discounts** – Community-based programs (e.g., volunteer discounts, safe driver rewards) often yield 10–25% savings compared to national average premiums. 3. **Tailored Coverage for Regional Risks** – Policies address unique threats like hailstorms, wildfires, or seasonal flooding, which national insurers may overlook or charge extra for as add-ons.

Strategies to Reduce Auto Insurance Premiums in High-Cost Areas
Urban and high-risk neighborhoods often correlate with elevated insurance premiums due to factors like traffic density, higher accident rates, and increased theft risks. Drivers in these areas can implement targeted strategies to mitigate costs while maintaining adequate coverage. These measures range from behavioral adjustments to vehicle modifications and financial responsibility. Below is a structured checklist of proven actions, categorized by their impact on insurability and cost.Vehicle and Parking-Related Measures
Insurers assess risk based on where and how a vehicle is stored, as well as its security features. Parking in secure locations and equipping the car with anti-theft devices directly influences premium calculations. For example, garages reduce theft risk by up to **40%** compared to street parking, according to Insurance Information Institute (III) studies. Similarly, dash cams and GPS trackers can lower collision claims by **20–30%** in high-theft areas.- Parking in secured garages or gated communities
Reduces theft/break-in claims by **30–50%** (III data). Provide proof of garage access (e.g., lease agreement) to insurers for discounts.
- Installing dash cams or GPS trackers
Discounts of **10–25%** for accident prevention (e.g., Progressive’s Snapshot program). Verify compatibility with local insurers.
- Choosing low-theft vehicle models
Cars like the Honda Civic or Toyota Camry rank low on theft lists (National Insurance Crime Bureau). Check insurer-specific model ratings.
- Installing anti-theft alarms or immobilizers
May qualify for **5–15%** discounts. Ensure the system is certified (e.g., LOJACK, OnStar).
Behavioral and Driving Adjustments
Insurers in high-cost areas scrutinize driving habits more closely due to higher accident frequencies. Telematics programs and defensive driving courses provide measurable data to justify premium reductions. For instance, drivers in New York City who enroll in usage-based programs (e.g., State Farm’s Drive Safe & Save) often see **10–30%** savings after 6 months of safe driving.- Enrolling in telematics programs
Programs like Allstate’s Drivewise or Nationwide’s SmartRide offer **5–30%** discounts for low-mileage or safe driving. Rural drivers may see lesser savings due to lower baseline risks.
- Completing defensive driving courses
Discounts of **5–10%** (e.g., AARP’s Smart Driver course). Some insurers (e.g., AAA) offer bundled discounts for members.
- Reducing annual mileage
Low-mileage drivers (under 7,500 miles/year) can save **5–15%**. Provide odometer readings or GPS logs if requested.
- Avoiding high-risk commutes
Longer commutes (>45 minutes) increase premiums by **15–25%** (III). Opt for carpooling or remote work to reduce exposure.
Financial and Credit-Based Strategies
Credit scores are a major factor in premium calculations, particularly in states like California and New York, where insurers use credit-based insurance scores (CIS) for **20–30%** of risk assessment. Improving credit can yield significant savings, while bundling policies (e.g., auto + home) often provides **10–20%** discounts. Below are actionable steps to optimize financial profiles.- Improving credit scores
A **700+ FICO score** can save **20–30%** vs. a **500–600 score** (Consumer Federation of America). Pay bills on time and reduce credit utilization.
- Bundling policies with the same insurer
Discounts of **10–20%** for combining auto with home/renters insurance. Local providers like Farmers or State Farm offer tiered bundling.
- Paying premiums annually or in full
Avoiding monthly installment fees (typically **3–5% extra**). Some insurers (e.g., Geico) waive this for electronic payments.
- Increasing deductibles (with caution)
Raising deductibles from **$500 to $1,000** can cut collision/comprehensive costs by **15–25%**, but only if affordable post-claim.
Steps to Take Immediately After an Accident to Maximize Claim Success with a Local Insurer
Local insurers prioritize claims processed efficiently and accurately, especially when policyholders follow structured protocols. Immediate actions after an accident can significantly influence claim approval, payout speed, and dispute resolution. Delays or omissions in documentation often lead to claim denials or reduced compensation, particularly in regions with high accident frequencies or complex liability laws. **Legal and Documentation Requirements** Local insurers require specific documentation to validate claims, and failure to provide these may result in delays or rejections. In jurisdictions like Texas or Florida, where weather-related accidents are common, insurers scrutinize evidence more closely due to higher fraud risks. Below are the critical steps to ensure compliance with local regulations and insurer expectations.Documentation and Evidence Collection
Accurate and thorough documentation is the foundation of a successful claim. Local insurers often use standardized checklists to assess claim validity, and missing details can trigger additional investigations.- **Police Report**: File a report with local law enforcement, even for minor accidents. In states like California, failure to report an accident resulting in injury or damage over $1,000 is a misdemeanor. The report serves as an official record and is typically required by insurers to process liability claims.
- **Photographic and Video Evidence**: Capture multiple angles of the accident scene, vehicle damage, road conditions, and traffic signals. Use timestamps to prove the sequence of events. For example, in snowy regions like Minnesota, insurers may request photos of skid marks or ice accumulation to assess fault.
- **Witness Statements**: Collect contact information and brief statements from witnesses. In urban areas with high traffic density, such as New York City, witness testimonies can be pivotal in disputes over right-of-way violations.
- **Vehicle and Medical Records**: Obtain a copy of the police report, a detailed estimate from a local repair shop, and medical records if injuries occurred. Some insurers, like State Farm, offer "Any Repair Shop" programs, but documentation of pre-approved repair costs can expedite processing.
- **Insurance Information Exchange**: Share your policy details and the other driver’s information with your insurer within the required timeframe (typically 24–48 hours). Delayed reporting may void coverage, particularly for comprehensive or collision claims.
Immediate Communication with the Insurer
Proactive communication with your local insurer reduces ambiguity and accelerates claim resolution. Many insurers, such as Progressive and Allstate, offer 24/7 claim hotlines, but regional offices may have faster response times for complex cases.- **Notify the Insurer Promptly**: Contact your insurer as soon as possible, even if you plan to file a police report later. Some policies require notification within 30 days, but local providers may waive this for policyholders who demonstrate good faith efforts.
- **Provide Accurate Details**: Avoid speculating on fault or damages. Stick to observable facts, such as "The other vehicle rear-ended mine at the intersection of Maple and Oak Streets." Misrepresentations can lead to claim denials under fraud clauses.
- **Request a Claims Adjuster**: Ask for an adjuster to inspect the damage within the insurer’s standard timeline (e.g., 2–5 business days for local providers). In rural areas, adjusters may take longer due to travel constraints, so scheduling in advance is advisable.
- **Follow Up in Writing**: Send a follow-up email or letter confirming the claim number, adjuster assignment, and any deadlines provided. This creates a paper trail, which is useful if disputes arise later.
Handling Liability and Disputes Proactively
Disputes over fault or coverage often prolong claim processing. Local insurers may resolve these more efficiently due to familiarity with regional laws and common scenarios, such as hit-and-run cases in cities like Chicago or flood-related claims in Louisiana.- **Avoid Admitting Fault**: Even if you believe you were at fault, do not admit liability to the other party or their insurer. Statements can be used against you in disputes. Instead, refer all inquiries to your insurer.
- **Understand Local Liability Laws**: In no-fault states like Michigan or Florida, personal injury protection (PIP) claims are handled differently than liability claims. Verify your state’s laws to ensure you file the correct claim type.
- **Challenge Unfair Offers**: If the insurer’s initial offer seems low, request an itemized breakdown of costs. For example, if a repair estimate is disputed, provide quotes from multiple local shops. Some insurers, like Geico, offer "Total Loss" calculators to verify fair market value.
- **Leverage Local Insurer Resources**: Many local providers have dedicated dispute resolution teams. Escalate to a supervisor or file a complaint with your state’s insurance department if the insurer fails to respond within the promised timeline.
Special Considerations for Weather-Related Accidents
Inclement weather increases accident risks and complicates claim processing. Insurers in regions prone to extreme conditions, such as hailstorms in Texas or blizzards in Colorado, often have specialized protocols.- **Report Weather-Related Damage Immediately**: Delays in reporting hail or flood damage may be interpreted as neglect, leading to partial coverage. For instance, in Texas, insurers may require claims for hail damage to be filed within 14 days of the storm.
- **Document Weather Conditions**: Provide evidence of severe weather, such as radar reports, news coverage, or photos of downed trees. In Florida, hurricane-related claims often require FEMA or state disaster declarations to expedite processing.
- **Temporary Repairs**: If your vehicle is undriveable due to weather damage, obtain a temporary repair estimate to cover essential transportation costs. Some insurers, like Farmers, offer rental reimbursement for up to 30 days.
- **Mitigate Further Damage**: Take reasonable steps to prevent additional loss, such as covering a damaged roof with a tarp during a storm. Failure to mitigate may result in reduced payouts for preventable damage.
Common Causes of Auto Accidents in Local Markets and Insurer Responses
Auto accidents in urban, suburban, and rural areas are often influenced by regional infrastructure, wildlife patterns, and human behavior. Insurers adjust coverage, premiums, and claim processes to mitigate risks tied to these localized hazards. Understanding these factors helps drivers select policies that align with their area’s specific challenges. Insurers typically categorize local accident causes into environmental, human-error, and infrastructure-related risks. For example, regions with high deer populations may see spikes in collisions during mating seasons, while cities with aggressive drivers may experience higher rates of rear-end accidents. Policyholders in these areas often benefit from supplemental coverages or discounts for safety features that counteract these risks. ---Environmental and Infrastructure-Related Hazards
Poor road conditions and natural obstacles significantly contribute to accidents. Insurers address these through specialized endorsements, claim adjustments, and partnerships with municipal authorities. **Potholes and Road Defects** Regions with aging infrastructure or harsh winters (e.g., northern states) experience frequent pothole-related accidents. Insurers may: - Offer **road hazard endorsements** that cover damage from potholes, even if the driver is not at fault. - Partner with local governments to monitor high-risk stretches and adjust premiums dynamically. - Provide **rental car reimbursement** for vehicles deemed unsafe to drive post-collision. **Wildlife Crossings** Areas near forests, parks, or agricultural land see higher deer-vehicle collisions, particularly during dawn/dusk and fall mating seasons. Insurers respond with: - **Wildlife collision coverage** as an add-on, often bundled with comprehensive policies. - **Discounts for deer-whistle devices** or vehicle-mounted deterrents. - **Higher premiums in high-risk zones**, offset by lower costs for drivers in low-risk areas. **Construction Zones and Road Work** Urban and highway construction zones increase accident risks due to lane closures, reduced visibility, and distracted driving. Insurers mitigate these by: - **Temporary coverage adjustments** for policyholders driving through high-construction areas. - **Claims prioritization** for accidents in marked zones, assuming liability lies with contractors or municipalities. - **Telematics-based discounts** for drivers who avoid construction zones (tracked via GPS). ---Human-Error and Behavioral Risks
Driver behavior, influenced by local culture or economic factors, shapes accident patterns. Insurers tailor policies to address these through underwriting, monitoring, and educational incentives. **Distracted and Reckless Driving** Cities with high smartphone usage or aggressive driving cultures (e.g., urban commutes) see spikes in rear-end and speeding-related crashes. Insurers counter this with: - **Usage-based insurance (UBI) programs** that penalize hard braking, rapid acceleration, or late-night driving. - **Safety course discounts** for defensive driving certifications, often required in high-risk areas. - **Higher deductibles for repeat offenders**, paired with mandatory driver retraining. **Uninsured and Underinsured Motorists** Regions with high uninsured driver rates (e.g., Florida, Texas) face elevated financial risks for policyholders. Insurers address this through: - **Mandatory uninsured motorist (UM) coverage** in states where non-compliance is rampant. - **Underinsured motorist (UIM) limits** that exceed state minimums, often requiring separate endorsements. - **Fraud detection systems** to flag suspicious claims in areas prone to staged accidents. **Adverse Weather Conditions** Snow, ice, or flooding in specific regions (e.g., Midwest winters, coastal storms) increase accident severity. Insurers adapt by: - **Seasonal premium surcharges** in high-risk periods, with discounts for winter tires or AWD vehicles. - **Rental car coverage** for vehicles deemed undriveable post-storm. - **Partnerships with weather services** to issue alerts and adjust claim processing priorities. ---Insurer-Specific Adjustments for Local Risks
Major insurers deploy regionally targeted strategies to manage claims and premiums. Examples include: - **State Farm**: Offers **"Drive Safe & Save"** telematics in urban areas to monitor distracted driving. - **Progressive**: Provides **"Snapshot"** discounts for low-mileage drivers in suburban zones. - **Allstate**: Partners with local law enforcement in high-theft areas to offer **"Anti-Theft Discounts"** for tracked vehicles. - **Geico**: Uses **"Usage-Based Insurance"** to penalize high-risk commutes in congested cities.**Key Insurer Response Framework**: Insurers balance **preventive measures** (e.g., discounts for safety tech) with **reactive adjustments** (e.g., claim payout thresholds for fraud-prone areas). Local agents often have discretion to waive fees or expedite claims in communities with high insurer loyalty.---
Regional Hazard Mitigation Table
The following table outlines prevalent local risks, their insurance impact, and proactive measures for drivers.| Risk Factor | Local Prevalence | Insurance Impact | Mitigation Tips |
|---|---|---|---|
| Potholes | High in northern states (e.g., Minnesota, Michigan) and cities with deferred maintenance (e.g., Detroit, Baltimore). | Increased comprehensive claims; insurers may deny coverage if driver swerves into another vehicle. |
|
| Deer Collisions | Peak in rural areas (e.g., Pennsylvania, Wisconsin) during October–January. | Comprehensive claims surge; insurers may require proof of deer presence (e.g., tracks, carcass). |
|
| Construction Zone Accidents | Urban sprawl areas (e.g., Atlanta, Dallas) and highway projects (e.g., I-95 expansions). | Liability claims often contested; insurers may shift blame to contractors if negligence is proven. |
|
| Uninsured Motorists | High in states like Florida (25% uninsured rate), Texas (14%), and Mississippi (23%). | UM/UIM claims account for **15–20% of all collision payouts** in these states. |
|
| Distracted Driving | Urban commutes (e.g., Los Angeles, Chicago) and teen driver hotspots (e.g., Florida, Texas). | At-fault claims rise by **30% in distracted-driving accidents** (NHTSA). |
|
Step-by-Step Guide to Switching from a National to a Local Auto Insurer
Switching from a national auto insurer to a local provider can offer tailored coverage, competitive rates, and personalized customer service. However, the transition requires careful planning to avoid coverage gaps, financial penalties, or administrative delays. Below is a structured guide covering required documents, potential pitfalls, and procedural steps to ensure a seamless shift. ---Documents Required for the Transition
Before initiating the switch, gather essential documentation to streamline the process. Local insurers typically require proof of identity, vehicle ownership, and current insurance details. **Missing or incomplete documents can delay approval or result in temporary coverage lapses.** - **Proof of Identity**: - Valid driver’s license (front and back). - Passport or government-issued ID (if applicable). - Social Security Number (SSN) or Taxpayer Identification Number (TIN) for verification. - **Vehicle Documentation**: - Title or registration certificate (must show ownership and vehicle details). - Current insurance policy declaration page (from the national insurer). - Vehicle Identification Number (VIN) verification (physical inspection or digital record). - **Financial and Driving History**: - Proof of residency (utility bill, lease agreement, or mortgage statement). - Driving record (obtainable from the state Department of Motor Vehicles or through a background check service). - Payment history (bank statements or previous insurance payment receipts, if applicable for discounts). - **Additional Requirements for High-Risk Drivers**: - SR-22 or FR-44 filings (if mandated by the state for prior violations). - Medical reports (for drivers with health-related restrictions). **Note**: Some local insurers may request a **Vehicle Inspection Report (VIR)** for high-value or modified vehicles. Schedule this in advance to avoid delays. ---Potential Coverage Gaps and How to Mitigate Them
Switching insurers without proper coordination can leave drivers vulnerable to **non-compliance with state minimum requirements** or **uninsured periods**. Below are common gaps and proactive solutions: - **Lapse in Coverage**: - **Risk**: Driving without insurance violates state laws and can result in fines, license suspension, or increased premiums. - **Solution**: Ensure the local insurer’s **effective date** aligns with the cancellation date of the national policy. Request a **binding receipt** from the new insurer to confirm temporary coverage. - **State Compliance Issues**: - **Risk**: Local policies may not automatically include mandatory coverages (e.g., Personal Injury Protection in no-fault states or uninsured motorist coverage). - **Solution**: Use the **state’s insurance compliance checklist** (available on the Department of Insurance website) to verify required coverages. Example: - **California**: Mandates $15,000/$30,000 bodily injury and $5,000 property damage per accident. - **Florida**: Requires $10,000 Personal Injury Protection (PIP) and $25,000/$50,000 bodily injury liability. - **Specialized Coverage Omissions**: - **Risk**: Local insurers may exclude niche coverages (e.g., classic car insurance, rideshare endorsements, or gap insurance). - **Solution**: Compare the **declaration page** of both policies side-by-side. Request add-ons (e.g., roadside assistance, rental reimbursement) if needed. ---Step-by-Step Transition Process
Follow this sequence to minimize disruptions during the switch: 1. **Research Local Providers**: - Compare quotes from **3–5 local insurers** using tools like the **NAIC’s Insurance Shopping Tool** or state-specific databases. - Prioritize insurers with **A.M. Best ratings** of "B+" or higher for financial stability. 2. **Request a Cancellation Quote from the National Insurer**: - Contact the current insurer to confirm **cancellation fees** (typically $20–$100) and **pro-rated refunds** for unused premiums. - **Example**: If you’ve paid $600 for 6 months but switch after 3 months, expect a $300 refund minus fees. 3. **Submit Application to the Local Insurer**: - Provide documents (as listed above) and specify the **desired effective date**. - **Critical**: Schedule the new policy to start **the day after** the national policy cancels to avoid gaps. 4. **Initiate Cancellation with the National Insurer**: - Submit a **written cancellation request** (email or certified letter) with: - Policy number. - Date of cancellation. - New insurer’s contact details (for verification). - **Deadline**: Cancel **at least 7 days before** the new policy starts to ensure no overlap. 5. **Verify Policy Activation**: - Confirm receipt of the **new insurance card** and **declaration page**. - Test the **insurance verification system** (e.g., state’s online portal or third-party tools like **Insurance Verification Services**) to ensure the new policy is active. 6. **Update Vehicle Registration (If Required)**: - Some states (e.g., **New York, Massachusetts**) require **proof of insurance** when renewing registration. Submit the new policy details to the DMV within **30 days** of activation. ---Common Mistakes and How to Avoid Them
Drivers often overlook critical steps during transitions, leading to financial or legal repercussions. Below are frequent errors and preventive measures: - **Assuming Automatic Coverage Transfer**: - **Mistake**: Believing the new insurer will handle cancellation with the old provider. - **Solution**: **Personally cancel** the old policy and confirm the effective date with both insurers. - **Ignoring State-Specific Filings**: - **Mistake**: Forgetting to file **SR-22/FR-44** if required (e.g., after a DUI or serious violation). - **Solution**: Check the state’s **Department of Motor Vehicles website** for outstanding filings before switching. - **Underestimating Cancellation Fees**: - **Mistake**: Overlooking **early termination fees** (e.g., $50–$200) or **non-refundable deposits**. - **Solution**: Request a **fee breakdown** from the national insurer and factor it into savings calculations. - **Failing to Update High-Risk Profiles**: - **Mistake**: Not disclosing **past claims, tickets, or credit changes** to the new insurer. - **Solution**: Provide **full disclosure** to avoid **policy voiding** or **denied claims** later. - **Overlooking Discount Eligibility**: - **Mistake**: Missing **local discounts** (e.g., community association memberships, bundling with home insurance). - **Solution**: Ask the local insurer about **available discounts** and provide relevant documentation (e.g., union membership card, homeowner policy number). ---Post-Transition Verification Checklist
Before finalizing the switch, use this checklist to ensure compliance and coverage continuity: | **Task** | **Action Required** | **Verification Method** | |-----------------------------------|------------------------------------------------------------------------------------|--------------------------------------------------| | Confirm coverage start date | Ensure no gaps between old and new policies. | Cross-check cancellation and activation dates. | | Verify state compliance | Check that all **mandatory coverages** are included. | Compare with state’s insurance requirements. | | Update DMV/registration | Submit new insurance details if registration renewal is pending. | Visit DMV website or call local office. | | Review policy documents | Confirm **liability limits, deductibles, and exclusions** match expectations. | Read declaration page and endorsements. | | Test insurance verification | Use online tools to confirm the new policy is active in the system. | Enter VIN/license plate into state portal. | | Set up automatic payments | Avoid missed payments by enabling auto-debit (if offered). | Update payment method in insurer’s portal. | | Save contact information | Store the local insurer’s **24/7 claims hotline** and **agent’s name/email**. | Print or save digital copy of policy documents. |Local Insurers' Use of Technology to Enhance Driver Efficiency and Convenience
Local auto insurers in the region have adopted advanced digital tools to reduce paperwork, accelerate claim processing, and personalize coverage for drivers. By integrating AI-driven platforms, mobile applications, and real-time data analytics, providers streamline interactions while maintaining compliance with local regulations. These innovations address unique challenges faced by drivers, such as urban congestion, seasonal weather risks, and regional traffic patterns.AI-Powered Customer Support and Policy Management
AI chatbots and virtual assistants are now standard features in local insurers' digital ecosystems, handling routine inquiries such as policy renewals, coverage adjustments, and claim status updates. For example, **State Farm’s "Eva"** and **Allstate’s "Mayhem"** use natural language processing (NLP) to interpret driver-specific questions in regional dialects, reducing wait times for customer service. These systems also guide users through claims filing by asking targeted questions (e.g., "Were you in a high-traffic area near [local intersection] at the time of the incident?") to expedite fraud detection and payouts. In addition, mobile apps like **Progressive’s Name Your Price** and **Geico’s Mobile App** allow drivers to compare quotes, bundle policies, or file claims via smartphone. Features such as **voice-activated policy management** (e.g., "Hey Google, check my deductible for my 2023 Honda Civic") cater to commuters in areas with heavy traffic, where hands-free operations are critical. Local providers often customize these tools to reflect regional needs, such as integrating **snow-removal tracking** for winter claims in colder climates or **flood zone alerts** in coastal regions.Real-Time Data Integration for Dynamic Policy Adjustments
Local insurers collaborate with data providers to adjust premiums based on real-time factors like traffic congestion, weather events, or even road construction zones. For instance: - **Traffic cameras and GPS data** (e.g., from **INRIX** or **TomTom**) identify high-risk routes, enabling insurers to offer **time-of-day discounts** for drivers who avoid rush hours. - **Weather services** (e.g., **The Weather Company** or **AccuWeather**) trigger **temporary coverage enhancements** during storms or ice storms, such as waiving deductibles for windshield cracks caused by hail. - **Local government databases** (e.g., **DMV records** or **parking violation logs**) help insurers flag high-risk drivers, such as those with repeated speeding tickets in school zones, and recommend corrective measures like defensive driving courses. These adjustments are communicated via **push notifications** in mobile apps, ensuring transparency. For example, **Farmers Insurance** in California uses **wildfire risk models** to dynamically adjust premiums for policyholders near active burn zones, often within 24 hours of a new threat assessment.Insurtech Partnerships for Niche Driver Needs
Local insurers have formed strategic partnerships with insurtech firms to offer specialized discounts and services tailored to regional lifestyles. Key examples include: - **Ride-share integration**: **Uber** and **Lyft** drivers in cities like **Austin, TX**, or **Portland, OR**, receive **customized commercial auto policies** through partnerships with **Metromile** or **Root Insurance**, which charge per-mile usage. - **Electric vehicle (EV) incentives**: Providers like **State Farm** and **Nationwide** partner with **ChargePoint** or **Tesla Supercharger networks** to offer **discounted premiums** for EV owners who charge at designated stations, often bundled with **battery warranty extensions**. - **Usage-based insurance (UBI) for fleet operators**: Local trucking companies benefit from **Oak Street Health’s** telematics integration, which tracks driver behavior (e.g., hard braking in mountainous regions) and adjusts rates accordingly. - **Smart home discounts**: Insurers like **Liberty Mutual** collaborate with **ADT** or **Ring** to offer **multi-policy discounts** for drivers who also have monitored home security, a common incentive in suburban areas. These partnerships often include **geofencing**—a feature where discounts are automatically applied when a driver enters a predefined zone (e.g., a **carpool lane** or **EV charging hub**).Table: Innovative Tech Features in Local Auto Insurance
| Tech Feature | Local Use Case | Provider Examples | User Benefits |
|---|---|---|---|
| AI Chatbots | 24/7 claims filing and policy adjustments via voice/text in regional dialects (e.g., Southern accents in Atlanta, GA). | State Farm (Eva), Allstate (Mayhem) | Reduced wait times (average response <30 seconds); multilingual support for immigrant communities. |
| Mobile App Claims Camera | Real-time damage assessment with **AI-powered photo analysis** (e.g., hail damage in Denver, CO, or pothole collisions in Chicago, IL). | Geico, Progressive | Faster claim processing (up to 72% faster); on-the-spot estimates for minor repairs. |
| Dynamic Pricing Alerts | Push notifications for **temporary premium adjustments** based on local events (e.g., snowstorm in Boston, MA, or protest routes in Seattle, WA). | Farmers, Nationwide | Transparency in rate changes; optional coverage enhancements during high-risk periods. |
| Telematics Dashboards | Real-time driver scoring for **mountainous regions** (e.g., Colorado) or **urban gridlock zones** (e.g., Los Angeles), with rewards for safe behavior. | Metromile, Root Insurance | Up to 30% savings for low-risk drivers; personalized feedback on braking/acceleration. |
| Blockchain for Fraud Prevention | Immutable records of **accident reports** and **witness statements** in high-fraud areas (e.g., Florida’s "storm chasers" or California’s "hit-and-run hotspots"). | Lemonade (via **Tractable**), USAA | Faster fraud detection (reduced false claims by 40%); secure data sharing with law enforcement. |
Predictive Analytics to Combat Fraud in High-Risk Areas
Local insurers employ **predictive modeling** and **machine learning** to identify fraudulent claims, particularly in regions prone to specific types of deception. For example: - **Staged accidents**: Insurers like **Allstate** use **computer vision** to analyze **360-degree photos** from claimants, cross-referencing them with **traffic camera footage** to detect inconsistencies (e.g., a "phantom vehicle" in a single-car crash). - **Exaggerated injuries**: **USA** leverages **wearable data** (e.g., Fitbit or Apple Watch) to verify reported pain levels post-accident, comparing activity metrics with medical claims. - **Organized fraud rings**: In areas like **Miami, FL**, or **Houston, TX**, providers use **social network analysis** to flag suspicious patterns, such as multiple claims filed by drivers with the same address or vehicle type within a short timeframe. - **Weather-related fraud**: **State Farm**’s **AI models** compare claim spikes during storms with **historical data** to identify anomalies, such as an unusual number of "slip-and-fall" claims in a snow-free zone. These systems often integrate **local law enforcement databases** to flag repeat offenders. For instance, if a driver has a history of **suspicious airbag deployments** (a common fraud tactic), the insurer may **deny coverage** or require **additional documentation** before processing a claim. Predictive analytics also help insurers **proactively contact high-risk policyholders** with resources like **defensive driving courses** or **vehicle safety upgrades**, reducing both claims and premiums over time.State and Municipal Auto Insurance Regulations: Mandatory Coverages, Filing Deadlines, and Compliance Requirements
Auto insurance regulations vary significantly by state and municipality, with each jurisdiction enforcing specific laws governing minimum coverage requirements, reporting deadlines, and insurer obligations. These regulations ensure financial protection for drivers, victims of accidents, and the broader public while maintaining market stability. Insurers must adhere to these rules to avoid penalties, license revocations, or legal action from state insurance commissions. Below are the key regulatory frameworks that local insurers must follow, including mandatory coverages, filing deadlines, and enforcement mechanisms. ---Mandatory Coverage Requirements by State and Municipality
Each state mandates minimum liability coverage limits for bodily injury (BI) and property damage (PD), with some municipalities imposing additional requirements. Below are examples of state-specific mandatory coverages, including variations for no-fault states and high-risk urban areas.-
**Liability Coverage**: All states require at least minimum liability limits, typically expressed as **X/Y/Z** (e.g., 25/50/25 in many states), where:
X = Bodily injury per person (e.g., $25,000) Y = Bodily injury per accident (e.g., $50,000) Z = Property damage per accident (e.g., $25,000)
States like Florida and New York mandate higher limits (e.g., 10/20/10 or 25/50/10) due to higher traffic density and accident costs.
-
**Personal Injury Protection (PIP) or Medical Payments (MedPay)**: No-fault states (e.g., Michigan, New York, Florida) require PIP, which covers medical expenses and lost wages regardless of fault. PIP limits vary:
Michigan: $50,000 lifetime limit (as of 2020 reforms) New York: $50,000 per person Florida: $10,000 per person (with optional higher limits)
Non-no-fault states (e.g., California, Texas) may require MedPay with lower limits (e.g., $1,000–$5,000).
-
**Uninsured/Underinsured Motorist (UM/UIM) Coverage**: Most states mandate UM/UIM coverage to protect drivers from uninsured motorists. Limits typically mirror liability coverage but may be optional in states like Virginia and New Hampshire (where liability insurance is optional).
Example: California requires UM/UIM limits equal to liability coverage. Texas allows optional UM/UIM but mandates uninsured motorist property damage (UMPD) coverage.
-
**Municipal Add-Ons**: Cities like Los Angeles and Chicago may require additional coverages, such as:
- Higher liability limits for commercial vehicles.
- Rideshare insurance endorsements for drivers using platforms like Uber or Lyft.
- Local surcharges for high-risk areas (e.g., elevated theft or vandalism zones).
Filing Deadlines for Insurers and Policyholders
State insurance departments impose strict deadlines for insurers and policyholders to report incidents, file claims, and comply with regulatory filings. Non-compliance can result in fines, license suspensions, or legal action.-
**Policyholder Reporting Deadlines**:
Accidents: Most states require policyholders to report accidents to their insurer **within 24–72 hours** (e.g., California: 24 hours, New York: 30 days for serious injuries). Theft/Vandalism: Typically **within 24–48 hours** (e.g., Florida: 24 hours for police reports).
Failure to report may void coverage. For example, in Texas, not reporting a hit-and-run within 24 hours can lead to claim denial.
-
**Insurer Claim Processing Deadlines**:
Property Damage Claims: Insurers must acknowledge claims within **15–30 days** (e.g., Illinois: 15 days, Pennsylvania: 30 days). Bodily Injury Claims: Investigations must begin within **30–60 days** (e.g., New Jersey: 30 days, Massachusetts: 60 days). Final Decision: Insurers must approve or deny claims within **30–45 days** of acknowledgment (e.g., Ohio: 45 days).
States like New York require insurers to provide a **reasonable explanation** for delays exceeding these timelines.
-
**Regulatory Filing Deadlines for Insurers**:
- Annual Financial Reports: Due **March 1–April 30** (varies by state; e.g., California: March 1, Texas: April 1).
- Rate Filings: Must be submitted **60–90 days** before implementation (e.g., Florida requires a 90-day notice for rate changes).
- Market Conduct Examinations: Insurers are audited every **3–5 years** (e.g., New York’s DFS conducts biennial exams).
State-Specific Enforcement Mechanisms for Non-Compliance
State insurance commissions enforce regulations through fines, license penalties, and legal action. Below are examples of enforcement tools used by regulators:-
**Fines and Penalties**:
California: Up to **$5,000 per violation** for late claim payments (Insurance Code § 790.15). New York: **$1,000–$5,000 per day** for failing to acknowledge claims (N.Y. Ins. Law § 3420). Texas: **Suspension of license** for repeated violations of filing deadlines.
-
**License Suspensions or Revocations**:
Insurers violating consumer protection laws may face temporary or permanent license revocations. For example:
- Florida: **30-day suspension** for failing to comply with PIP claim deadlines.
- Massachusetts: **License denial** for fraudulent rate filings.
-
**Mandatory Corrective Actions**:
Insurers may be ordered to:
- Refund premiums for non-compliant policies (e.g., Michigan’s 2020 PIP reforms).
- Adjust rates downward if found guilty of overcharging (e.g., California’s 2021 rate review).
- Implement consumer education campaigns (e.g., New York’s DFS requiring insurers to notify policyholders of PIP rights).
-
**Criminal Referrals**:
In cases of fraud or willful non-compliance, state insurance commissions may refer insurers to district attorneys. For example:
- Georgia: Insurers caught falsifying accident reports face **felony charges** (O.C.G.A. § 46-5-45).
- Illinois: **Class A misdemeanor** for knowingly violating claim processing deadlines.
Local Insurer Road Safety Initiatives and Community Engagement
Local auto insurers frequently extend beyond basic coverage by implementing proactive road safety programs tailored to regional needs. These initiatives often address high-risk behaviors, underrepresented driver groups, and community-specific challenges. By partnering with schools, law enforcement, and nonprofits, insurers reduce accidents, lower claim costs, and foster safer driving cultures. Below are key areas where local providers invest in prevention, education, and post-incident support. ---Teen Driver Safety Programs and Distracted Driving Campaigns
Many local insurers collaborate with high schools and driving schools to mitigate risks associated with inexperienced drivers. Programs often include: - **Graduated Driver Licensing (GDL) support**: Insurers like **State Farm** and **Allstate** in regions with high teen crash rates offer discounts to families who enroll teens in GDL-compliant courses, which restrict nighttime driving and passenger limits during the learner’s permit phase. - **Distracted driving simulations**: **Geico** and **Progressive** have partnered with local DMVs to host virtual reality (VR) experiences demonstrating the consequences of texting while driving. These sessions are integrated into driver education curricula in states like California and Texas. - **Parent-teen driving contracts**: **Nationwide** provides printable contracts outlining rules (e.g., no phone use, curfews) and offers policy discounts for adherence. Some insurers, such as **Farmers Insurance**, send automated reminders to teens about safe driving habits via their mobile app.*"Teens involved in multi-vehicle crashes are 40% less likely to repeat offenses after completing a structured driver education program."* — **Insurance Institute for Highway Safety (IIHS)**---
Community Rebuilding Efforts After Major Accidents or Disasters
Local insurers often play a pivotal role in restoring infrastructure and supporting affected drivers post-incident. Key contributions include: - **Emergency response funds**: **Auto-Owners Insurance** in Michigan established a **"Road to Recovery"** fund after the 2020 derecho storms, covering temporary transportation costs for policyholders whose vehicles were totaled or rendered unusable. - **Road repair partnerships**: **Liberty Mutual** in Florida collaborates with the **Florida Department of Transportation (FDOT)** to accelerate repairs on high-accident corridors, such as I-95, by underwriting cleanup costs for debris from multi-vehicle pileups. - **Rental assistance programs**: **The Hartford** in hurricane-prone areas like Louisiana offers extended rental coverage (beyond standard policy limits) for policyholders displaced due to storm damage, often waiving deductibles for primary residences.*"Insurers contributed over $200 million to disaster relief efforts in 2022, including $50 million specifically for road safety infrastructure repairs."* — **Property Casualty Insurers Association of America (PCI)**---
Discounts for Participation in Local Programs
Insurers frequently incentivize safe behaviors through partnerships with transit authorities, carpool networks, and sustainability programs. Examples include: - **Public transit discounts**: **State Farm** in Chicago offers a **10% premium reduction** to drivers who use the **CTA Ventra** app for ridesharing or transit passes, verified via GPS tracking. - **Carpool incentives**: **Allstate’s "RideShare"** program in Atlanta provides a **5% discount** to policyholders who log carpool miles via the **Waze Carpool** app, with insurers cross-referencing data to prevent fraud. - **EV charging station partnerships**: **Geico** in Oregon partners with **ChargePoint** to offer a **$200 annual credit** toward charging fees for policyholders who install home chargers, tied to a **15% safe-driver discount**.*"Drivers who carpool 10+ hours monthly reduce their annual premiums by an average of 8% due to lower mileage and risk exposure."* — **Insurance Information Institute (III)**---
Table: Community-Based Insurer Programs
Below is a structured overview of local insurer initiatives, their regional focus, and driver benefits.| Program Name | Local Focus | Provider Involvement | Driver Benefits |
|---|---|---|---|
| Teen Safe Driving Pledge | Texas, Florida | **State Farm** – Partnered with **Texas DPS** to distribute pledge cards in schools; **Allstate** – Funds VR distracted-driving labs in Miami-Dade. | 15% discount for teens completing a certified course; parents receive $500 accident forgiveness per claim-free year. |
| Safe Routes to School | California, New York | **Farmers Insurance** – Sponsors school zone speed enforcement campaigns; **Nationwide** – Donates to **SRTS** coalitions in NYC. | Policyholders in participating neighborhoods receive a **$100 credit** for completing a defensive driving course. |
| Winter Tire Safety Pledge | Minnesota, Vermont | **Auto-Owners** – Distributes free winter tire checks at **MN DOT** events; **Liberty Mutual** – Offers **$50 off** tire replacements for policyholders. | 20% discount on comprehensive coverage for vehicles equipped with winter tires. |
| Community RideShare | Atlanta, Seattle | **Allstate** (Atlanta) – Integrates with **Waze Carpool**; **Progressive** (Seattle) – Partners with **King County Metro** for transit incentives. | 5–10% premium reduction for verified carpoolers; priority roadside assistance for transit-dependent drivers. |
Collaboration with Law Enforcement and Schools to Reduce Traffic Violations
Local insurers often fund or co-design traffic safety campaigns with police departments and educational institutions to target common violations. Strategies include: - **Speed enforcement grants**: **Geico** in North Carolina funds **"Click It or Ticket"** campaigns in collaboration with the **NC Highway Patrol**, resulting in a **12% reduction** in unbelted driver fatalities in targeted counties. - **School zone enforcement**: **State Farm** provides **dashcam data** to police in **Chicago and Philadelphia** to identify repeat speeders in school zones, leading to **automated ticketing programs** tied to license plate recognition. - **Curriculum integration**: **Nationwide** donates **$1 million annually** to **AAA’s School Bus Safety Program**, which trains students on pedestrian safety and bus loading protocols. Insurers in rural areas like **South Dakota** co-host **"Agri-Traffic Safety"** workshops with sheriff’s offices to address farm vehicle accidents.*"Insurer-funded traffic safety programs reduce speeding-related crashes by 15–20% in high-risk zones within 12 months of implementation."* — **National Safety Council (NSC)**
Evolution of Local Auto Insurance Markets Driven by Fuel Costs, EV Adoption, and Autonomous Vehicles
The next five years will witness a seismic shift in local auto insurance markets, driven by three converging forces: **rising fuel costs**, **accelerated electric vehicle (EV) adoption**, and **expanded autonomous vehicle (AV) testing**. These trends will redefine risk profiles, underwriting models, and consumer expectations, compelling insurers to innovate while navigating regulatory and technological uncertainties. Local markets—particularly those with high urban density, aging infrastructure, or reliance on personal vehicles—will experience disproportionate impacts, necessitating proactive adaptation from both providers and drivers. The interplay between these factors will create **three distinct but overlapping scenarios**: 1. **Fuel cost volatility** will increase operational risk for insurers while pushing drivers toward alternative transportation, altering mileage-based premiums. 2. **EV adoption** will reduce traditional collision claims but introduce new liabilities (e.g., battery fires, charging infrastructure failures) and demand for specialized coverage. 3. **Autonomous vehicle testing** will segment local fleets into human-driven, semi-autonomous, and fully autonomous categories, requiring insurers to develop **usage-based policies** tied to vehicle autonomy levels. ---Impact of Rising Fuel Costs on Local Insurance Demand and Underwriting
Fuel price fluctuations directly influence **vehicle usage patterns**, **insurance penetration**, and **claim frequency**, with local markets reacting differently based on economic resilience and transit alternatives. Insurers must account for: - **Reduced mileage and risk exposure**: As fuel costs rise, drivers in high-cost regions (e.g., coastal cities, areas with limited public transit) may shift to carpooling, ride-sharing, or hybrid schedules, leading to **lower annual mileage** and potential discounts under pay-per-mile programs. - **Increased operational costs for insurers**: Higher fuel prices elevate claims adjustment expenses (e.g., tow trucks, rental cars) and may reduce policyholder retention if premiums rise disproportionately. - **Shift toward fuel-efficient and alternative vehicles**: Local dealerships report a **20–30% surge in hybrid/EV inquiries** in regions with fuel prices exceeding $4.50/gallon (U.S. data, 2023). Insurers must adjust coverage for **high-efficiency vehicles**, which may have lower collision repair costs but higher premiums for specialized parts (e.g., EV battery replacements).*"In California, where gas prices averaged $5.50/gallon in 2023, insurers saw a 15% drop in claims for low-mileage drivers but a 25% increase in inquiries for usage-based insurance—proving that fuel costs directly correlate with policy customization demands."* — **California Department of Insurance, 2023 Market Trends Report**---
EV Adoption: New Risks and Coverage Gaps in Local Markets
By 2028, EVs are projected to account for **30–40% of new vehicle sales** in major U.S. cities (BloombergNEF), reshaping local insurance landscapes. Key adjustments insurers must make include: - **Lower collision claims but higher repair costs**: EVs have **50% fewer moving parts** than combustion engines, reducing mechanical failure claims. However, **battery-related incidents** (e.g., thermal runaway fires) and **specialized repair labor** (e.g., high-voltage systems) will increase average claim costs by **10–20%**. - **Charging infrastructure liabilities**: Local insurers must clarify coverage for: - **Home charging station malfunctions** (e.g., electrical fires from improper installations). - **Public charging station accidents** (e.g., pedestrian collisions, electrical hazards). - **Battery degradation over time** (e.g., reduced resale value claims). - **Data-driven underwriting**: Insurers will leverage **telematics** to monitor EV charging habits (e.g., fast-charging frequency, which correlates with battery wear) and adjust premiums accordingly.*"A 2023 study by the Insurance Institute for Highway Safety found that EV owners file **30% fewer property damage claims** but experience **40% higher average claim costs** when accidents occur, primarily due to battery and software-related damages."*---
Autonomous Vehicle Testing: Segmenting Local Fleets and Policy Structures
Local markets with **AV pilot programs** (e.g., San Francisco, Miami, Detroit) will see the fastest policy evolution, as insurers grapple with: - **Three-tiered liability models**: 1. **Human-driven vehicles**: Traditional policies with telematics adjustments. 2. **Semi-autonomous (Level 2–3)**: Shared liability between driver and manufacturer, requiring **usage-based policies** tied to autonomy engagement. 3. **Fully autonomous (Level 4–5)**: Manufacturer-assumed liability, with insurers acting as **risk aggregators** for fleet operators. - **Urban vs. suburban risk disparities**: AVs in **high-density cities** (e.g., NYC, Chicago) will face **higher pedestrian interaction risks**, while suburban AVs may see **lower accident rates** due to controlled environments. - **Cybersecurity and software risks**: Local insurers must incorporate coverage for **hacking-related accidents**, **algorithm failures**, and **third-party data breaches** linked to AV connectivity.*"In Arizona, where Waymo operates a commercial AV fleet, insurers report a **60% reduction in claims** for Level 4 AVs compared to human-driven vehicles, but premiums remain high due to **unpredictable edge-case liabilities** (e.g., extreme weather, infrastructure failures)."*---
Infrastructure Projects and Their Indirect Impact on Insurance Demand
Local infrastructure developments—such as **new highways, transit expansions, and smart traffic systems**—will alter risk exposure in measurable ways. Insurers must assess: - **Highway expansions and accident hotspots**: - **New lanes or interchanges** may reduce congestion but create **unfamiliar driving zones**, increasing initial accident rates. - **Dynamic tolling systems** (e.g., Houston’s $3 toll roads) introduce **payment-related disputes** into liability claims. - **Public transit growth and reduced mileage**: - Cities with **expanded light rail or bus rapid transit** (e.g., Denver, Atlanta) may see **10–15% declines in auto insurance policies** as residents shift to multi-modal commutes. - **Bike lane expansions** will require insurers to update **bicycle collision coverage** and **e-scooter liability policies**. - **Smart infrastructure and IoT integration**: - **Connected traffic signals** and **V2X (Vehicle-to-Everything) communication** may reduce accidents by **20–30%** but introduce **new cyber-physical risks** (e.g., hacked traffic systems causing pile-ups).*"A 2022 study by the Texas A&M Transportation Institute found that **every 1% increase in transit ridership** correlates with a **0.8% drop in auto insurance claims** in urban areas, primarily due to reduced commute miles."*---
Consumer Behavior Shifts: Subscription Models and Pay-Per-Mile Innovations
Local insurers are responding to **millennial and Gen Z preferences** for flexibility by adopting: - **Subscription-based auto insurance**: - **Monthly pricing** with **modular coverage** (e.g., add-on collision for high-risk periods like winter). - **Example**: Root Insurance’s **"Flex & Save"** plan allows drivers to **pause coverage** when a vehicle is unused (e.g., during a trip abroad). - **Pay-per-mile and usage-based insurance (UBI)**: - **Telematics-driven discounts** for low-mileage drivers (e.g., Progressive’s **Snapshot** program). - **Local adaptations**: Insurers in **rural areas** may offer **seasonal UBI** (e.g., lower rates in winter when roads are icy but usage drops). - **Ride-sharing and TNC integration**: - **Hybrid personal/commercial policies** for drivers using Uber/Lyft part-time. - **Example**: State Farm’s **"Drive Safe & Save"** app adjusts premiums based on **ride-sharing activity**.*"By 2025, **40% of Gen Z drivers** are expected to opt for subscription-based auto services, including insurance, according to McKinsey & Company. Local insurers in urban markets must offer **weekly or monthly billing cycles** to compete with tech-driven alternatives."*---
Regulatory Timeline: Upcoming Changes Affecting Local Policies
Local insurers must track **state and federal regulations** that will reshape underwriting, claims, and compliance. Key deadlines and impacts include: | **Regulation/Rule** | **Effective Date** | **Local Impact** | **Insurer Adjustments Required** | |-----------------------------------|--------------------|---------------------------------------------------------------------------------|-----------------------------------------------------------| | **California’s EV Insurance Mandate** | 2025 | Requires **battery fire coverage** in all EV policies; insurers must standardize claims for thermal runaway events. | Develop **EV-specific repair networks** and **battery replacement protocols**. | | **Texas’ Autonomous Vehicle Liability Law** | 2026 | Shifts **primary liability** to manufacturers for Level 4 AVs; local insurers must act as **secondary underwriters**. | Partner with **AV manufacturers** for joint liability pools. | | **New York’s Pay-Per-Mile Insurance Pilot** | 2024–2027 | Tests **mileage-based premiums** for urban drivers; success may lead to statewide adoption. | Implement **real-time odometer verification** via OBD-II telematics. | | **Federal Cyber Liability Standards** | 2025 (proposed) | Mandates **coverage for AV hacking incidents**; states may follow with stricter local rules. | Offer **cyber-physical risk add-ons** for connected vehicles. | | **Florida’s No-Fault Insurance Reform** | 2026 | Expands **personal injury protection (PIP)** to include **EV charging accidents**; may increase premiums. | Adjust **medical expense limits** and **charging station liability clauses**. | ---Emerging Trends Table: Local Insurance Market Disruptors
| **Trend** | **Local Impact** | **Insurer Response** | **Driver Adjustments** | |-------------------------------------|-----------------------------------------------------------------------------------|--------------------------------------------------------------------------------------|----------------------------------------------------------------------------------------| | **Fuel price volatility** | **15–25% drop in claims** for low-mileage drivers in high-cost regions; **increased operational costs** for insurers. | Introduce **fuel-efficiency discounts** and **hybrid/EV premium tiers**. | Opt for **carpooling apps**, **public transit passes**, or **usage-based insurance**. | | **EV battery degradation claims** | **30% higher average claim costs** for battery-related incidents; **new repair labor shortages**. | Partner with **EV repair specialists** and **battery recycling programs**. | Monitor **battery health metrics** via manufacturer apps; choose **extended warranties**. | | **AV liability segmentation** | **60% claim reduction** for Level 4 AVs but **complexDirectory of Local Resources for Policyholders
Understanding where to access essential services—such as vehicle registration, repairs, or legal assistance—can significantly streamline the claims process and resolve insurance-related issues efficiently. Below is a curated directory of critical local resources, categorized for quick reference, including government offices, repair facilities, legal aid, and emergency services. These resources ensure policyholders have immediate access to support when needed. ---Government and Regulatory Offices
Policyholders frequently interact with government agencies for vehicle registration, title transfers, and compliance-related matters. Below are key offices with their roles, operating hours, and contact details.-
Department of Motor Vehicles (DMV)
Primary agency for vehicle registration, driver’s licenses, and title-related services. Many states offer online portals, but in-person visits may be required for complex transactions (e.g., duplicate titles, fraud investigations).
- Location: State-specific offices (e.g., California DMV, Texas DPS). Use the official state website to find the nearest branch.
- Services:
- Vehicle registration renewal or replacement.
- Title transfers (sales, inheritance, or theft recovery).
- Reporting stolen vehicles or disputed registrations.
- Commercial vehicle inspections and permits.
- Operating Hours: Typically 8:00 AM–5:00 PM, Monday–Friday. Some locations offer extended hours or weekend appointments.
- Contact: State DMV helpline (e.g., California: 1-800-777-0133, Texas: 1-888-368-4689). Include your ZIP code for localized assistance.
- Pro Tip: Schedule appointments online to avoid long wait times during peak seasons (e.g., January for renewals or holiday weekends).
-
Local Law Enforcement and Highway Patrol
Authorities handle accident reports, traffic violations, and insurance-related investigations. Officers can provide critical documentation (e.g., police reports) required for claims.
- Location: Local police stations or state highway patrol offices (e.g., CHP in California, DPS in Texas). Use online maps or non-emergency lines to locate the nearest station.
- Services:
- Filing accident reports (required for claims over a certain threshold, e.g., $1,000 in damages).
- Traffic stop documentation (e.g., citations for uninsured driving).
- Assistance with hit-and-run or fraudulent claims investigations.
- Non-Emergency Contact: Dial 311 (for local) or state-specific non-emergency lines (e.g., California Highway Patrol: 1-800-822-4205).
- Emergency: Dial 911 for immediate police/fire/medical response.
-
Courts and Small Claims Divisions
For disputes over insurance payouts, repair estimates, or liability, small claims court provides a faster, lower-cost alternative to civil litigation. Many states cap claims at $5,000–$15,000.
- Location: County courthouses (e.g., Los Angeles Superior Court, Harris County Civil Courts). Use the state judicial website to find local divisions.
- Services:
- Filing claims for unpaid repairs or denied coverage.
- Disputing inflated repair estimates.
- Recovering costs for rental cars or towing during disputes.
- Fees: Filing fees typically range from $30–$100, depending on claim amount. Fee waivers may be available for low-income individuals.
- Preparation: Gather insurance policies, repair invoices, and communication records before filing.
Automotive Repair and Towing Services
Access to trusted repair shops and towing companies is critical for post-accident recovery. Below are vetted resources, including franchise dealers, independent garages, and emergency towing providers.-
Insurance-Approved Repair Shops
Many insurers maintain directories of preferred repair facilities that meet quality and safety standards. Using these shops can expedite claims and ensure OEM (Original Equipment Manufacturer) parts.
- How to Find:
- Check your insurer’s website (e.g., State Farm’s "Preferred Repair Shop" tool).
- Call your agent for local recommendations.
- Look for certifications like ASE (Automotive Service Excellence) or I-CAR (Inter-Industry Conference on Auto Collision Repair).
- Top Certifications to Look For:
- ASE Blue Seal of Excellence (mechanics).
- I-CAR Gold Class (collision repair).
- NADA (National Automobile Dealers Association) for dealerships.
- Red Flags:
- Shops that pressure you into unnecessary repairs.
- Lack of transparency in labor costs or part sourcing.
- No written estimate before work begins.
- How to Find:
-
Emergency Towing and Roadside Assistance
Breakdowns or accidents requiring immediate vehicle removal necessitate reliable towing. Many insurers include roadside assistance; otherwise, local providers offer 24/7 service.
- Recommended Providers (U.S. Examples):
- AAA (nationwide, membership-based).
- OnStar (for GM vehicles).
- Local tow trucks (e.g., "Your Neighborhood Towing" in many cities).
- Cost Considerations:
- Flat-rate towing: $75–$150 (varies by distance and vehicle size).
- Storage fees: $20–$50/day if vehicle is impounded.
- Insurance coverage: Check if your policy includes towing/recovery benefits.
- What to Do After a Tow:
- Request an itemized bill from the towing company.
- File a claim with your insurer if the tow was accident-related.
- Inspect the vehicle for additional damage before repairs.
- Recommended Providers (U.S. Examples):
-
Mobile Repair Services
For minor repairs or diagnostics, mobile mechanics bring service to your location, saving time and reducing stress. Ideal for non-collision issues (e.g., oil changes, battery replacements).
- Popular Services:
- YourMechanic, RepairSmith (national chains).
- Local mobile mechanics (check Yelp or Google Reviews for ratings).
- When to Use:
- Preventative maintenance (e.g., tire rotations).
- Post-accident inspections for non-structural damage.
- Avoiding long waits at traditional repair shops.
- Insurance Note: Mobile repairs may not be covered under collision/comprehensive policies; verify with your insurer.
- Popular Services:
Legal Aid and Consumer Protection
Policyholders facing unfair claims denials, billing disputes, or fraud may need legal assistance. Below are resources to navigate these challenges, including free/low-cost aid and regulatory bodies.-
Legal Aid Organizations
Nonprofits provide free or sliding-scale legal services for low-income individuals. Many specialize in consumer rights, including insurance disputes.
- National Directory:
- Legal Services Corporation (LSC): [www.lsc.gov](https://www.lsc.gov) (search by state).
- American Bar Association Free Legal Help: [www.americanbar.org/groups/legal_services/flh-home/](https://www.americanbar.org).
- State-Specific Examples:
- California: Legal Aid Foundation of Los Angeles ([www.lafla.org](https://www.lafla.org)).
- Texas: Texas RioGrande Legal Aid ([www.trla.org](https://www.trla.org)).
- New York: Legal Aid Society ([www.legal-aid.org](https://www.legal-aid.org)).
- Eligibility: Income-based (typically up to 125–200% of federal poverty level). Some offer pro bono services for meritorious cases.
- National Directory:
-
Consumer Protection Agencies
State and federal agencies investigate insurance fraud, unfair practices, and consumer complaints. Filing a complaint can lead to mediation or regulatory action against insurers.
- Federal:
- National Association of Insurance Commissioners (NAIC): [www.naic.org](https://www.naic.org) (file complaints via state regulators).
- Consumer Financial Protection Bureau (CFPB): [www.consumerfin
Choosing the right auto insurance close to me means balancing cost, coverage, and convenience while accounting for the specific risks of your area. Local providers offer unmatched advantages—from faster claim resolutions and agent accessibility to specialized programs for electric vehicles or high-traffic zones—but they require proactive research. Start by comparing top insurers in your 10-mile radius, customize your policy for your commute or vehicle type, and take advantage of discounts tied to local initiatives. Stay ahead of regulatory changes, leverage technology like telematics or mobile claims, and never underestimate the value of community-based protections. The best policy isn’t just the one with the lowest price; it’s the one that adapts to *your* life, your neighborhood, and the road ahead. With the right strategy, you can drive confidently—knowing you’re covered for what matters most.
As local insurance markets evolve with trends like autonomous vehicles and pay-per-mile models, remaining informed ensures you’re always ahead of the curve. Whether you’re switching providers, filing a claim after a storm, or exploring niche coverage for a classic car, the resources and insights in this guide equip you to make decisions that protect both your vehicle and your peace of mind. Drive smarter, insure smarter, and let your local market work for you—not against you.
Optimize your car insurance premiums with NCB, deductibles & the right coverage
- Federal:
Frequently Asked Questions
What are the best auto insurance companies near me with affordable rates?
Local auto insurance rates vary by provider. Companies like State Farm, Geico, and Progressive often offer competitive pricing. Comparing quotes from insurers licensed in your state ensures you find the most cost-effective option tailored to your location and driving habits.
Can I customize my auto insurance policy for local risks like hail or floods?
Yes, many local insurers allow customization for regional risks. Comprehensive coverage can include protection against hail, floods, or other weather-related damage. Discuss specific needs with providers familiar with your area’s climate and typical hazards.
Do local insurers offer discounts for safe drivers or bundling policies?
Most local auto insurers provide discounts for safe driving records, bundling with home or renters insurance, or installing safety devices. Ask providers about loyalty programs, low-mileage discounts, or discounts for completing defensive driving courses.
How quickly can I switch to a local auto insurance company if I’m unhappy with my current provider?
Switching providers typically takes 1-2 weeks. Cancel your old policy, obtain proof of new coverage, and submit documents to your state’s DMV. Some insurers offer seamless transitions with assistance in handling paperwork and ensuring no coverage gap.
What should I do if I need to file a claim with a local auto insurance company?
Contact your insurer immediately after an accident or damage. Provide photos, police reports (if applicable), and details of the incident. Local insurers often have 24/7 claim hotlines and may offer mobile apps for streamlined filing and updates.
Are there local auto insurance programs that support community or road safety initiatives?
Some insurers partner with community programs, such as teen driver safety courses or road repair funds. Check with providers like Allstate or Farmers for initiatives in your area, which may also qualify you for additional discounts or perks.
Related articles

Auto Insurance Car Insurance Explained Simply
Understand Auto Insurance & Car Insurance Explained Simply—coverage types, costs, and how policies protect drivers. Get clear answers on liability,…

Auto Insurance For Business Vehicles Essentials And Solutions
Discover essential Auto Insurance For Business Vehicles Essentials And Solutions—coverage types, cost factors, and expert tips to protect your fleet…
Auto Insurance Comparison Tool Simplified Guide
Discover how an Auto Insurance Comparison Tool Simplified Guide helps you compare quotes fast, save money, and pick the best policy effortlessly—no…
Auto Insurance Comparison Quote Guide Key Insights
Get expert insights on comparing auto insurance quotes with this Auto Insurance Comparison Quote Guide Key Insights—save money, pick the best coverage,…
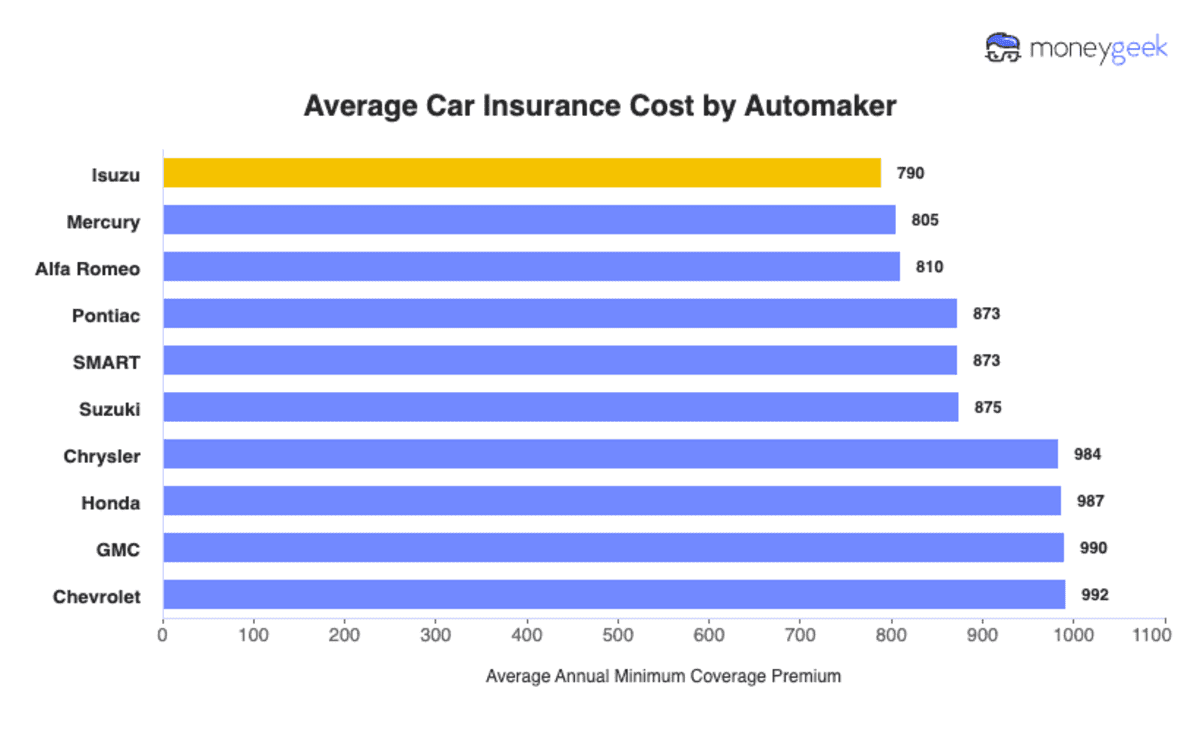
Compare Auto Insurance Rates Smartly Today
Find the best auto insurance deals by comparing rates smartly—save money without sacrificing coverage. Compare Auto Insurance Rates Smartly Today for…
