Understanding Apartment Liability Insurance Coverage Essentials
Table of Contents
- Fundamental Purpose of Apartment Liability Insurance and Distinction from Other Property Insurance Types
- Standard Coverage Limits in Apartment Liability Insurance and Tier-Based Variations
- Step-by-Step Claims Process for Apartment Liability Incidents and Documentation Requirements
- Liability Coverage Variations for Apartments in High-Risk Areas and Tailored Add-Ons
- Liability Responsibilities Between Landlords and Tenants in Common Apartment Scenarios
- Primary Cost Determinants for Apartment Liability Insurance and Their Impact on Premiums
- Essential Documents Tenants Should Retain to Support Liability Claims
- Case Study: Tenant Liability Claim for Guest Injury in a Shared Apartment
- Emerging Trends in Apartment Liability Insurance: Cyber Liability, Climate Risks, and Platform Disruptions
- Proactive Measures Tenants Can Take to Reduce Liability Risks in Apartments
Apartment living offers convenience but comes with unseen risks—slip-and-fall accidents, guest injuries, or property damage from shared spaces can leave tenants financially exposed. Apartment liability insurance coverage acts as a critical safeguard, distinguishing itself from renters insurance by addressing third-party claims that standard policies often overlook. From legal obligations for landlords to niche risks like drone incidents or short-term rentals, this guide breaks down how coverage works, what gaps exist, and how tenants can navigate claims, customize policies, and mitigate risks proactively. Whether you’re a first-time renter or a seasoned tenant, understanding these nuances ensures you’re protected when liability strikes.
At its core, apartment liability insurance bridges the gap between what renters insurance covers and the broader responsibilities tenants face in multi-unit buildings. Unlike homeowners insurance, which protects the property itself, or renters insurance, which focuses on personal belongings and limited liability, this specialized coverage targets scenarios where tenants could be held legally responsible for injuries or damages to others. For example, if a guest trips over a loose rug in your unit or a neighbor’s child damages shared hallway fixtures, the right policy can cover medical bills or repairs—saving tenants from devastating out-of-pocket costs. Yet, exclusions and coverage limits vary widely, making it essential to dissect policy terms, claim processes, and landlord-tenant dynamics to avoid costly oversights.
Fundamental Purpose of Apartment Liability Insurance and Distinction from Other Property Insurance Types
Apartment liability insurance is a specialized coverage designed to protect tenants and landlords from financial losses arising from third-party claims related to injuries or property damage occurring within a rental apartment. Unlike broader property insurance policies such as renters insurance or homeowners insurance, apartment liability insurance focuses solely on legal and financial responsibilities rather than physical asset protection. While renters insurance covers personal belongings and additional living expenses, and homeowners insurance protects the structure itself, apartment liability insurance addresses liabilities that may not be fully addressed by these policies. The core distinction lies in scope and responsibility: - **Renters Insurance**: Protects tenants' personal property, provides liability coverage, and may include loss of use benefits. - **Homeowners Insurance**: Covers the physical structure of a home and its permanent fixtures, along with liability protection for homeowners. - **Apartment Liability Insurance**: Specifically addresses liability risks for tenants or landlords in multi-unit residential buildings, often excluding coverage for personal belongings or the building structure itself. Apartment liability insurance is particularly relevant in high-density living environments where shared spaces increase exposure to accidents, injuries, or disputes between tenants, visitors, and the landlord. For example, a tenant hosting a gathering where a guest slips on a wet floor could face lawsuits for medical expenses or property damage, which apartment liability insurance may cover—unlike standard renters insurance, which might exclude such scenarios if the tenant is deemed negligent. ---Coverage Scope and Exclusions in Apartment Liability Insurance
Apartment liability insurance operates within defined boundaries to mitigate risks unique to rental apartments. Key exclusions often include: - **Intentional acts or criminal behavior** by the tenant or their guests. - **Damage to the rental unit itself** (covered under renters insurance or landlord policies). - **Business-related activities** conducted within the apartment (e.g., home-based businesses without separate commercial coverage). - **Environmental hazards** such as mold or asbestos, unless explicitly added as endorsements. - **Liabilities arising from shared amenities** (e.g., gym equipment in a complex), which may fall under the landlord’s master policy. The insurance’s focus on liability ensures that tenants and landlords are shielded from lawsuits or claims stemming from unintentional harm. For instance, if a child visiting a tenant accidentally breaks a neighbor’s expensive vase, the apartment liability coverage may reimburse the neighbor for damages, whereas renters insurance would not typically address such third-party claims. ---Comparison of Apartment Liability Insurance and Renters Insurance
Below is a structured comparison highlighting coverage overlaps and exclusions between apartment liability insurance and renters insurance:| Coverage Type | Apartment Liability Insurance | Renters Insurance |
|---|---|---|
| Primary Purpose | Protects against third-party liability claims (injuries, property damage) within the apartment. | Covers personal belongings, liability, and additional living expenses (ALE) after covered perils (e.g., fire, theft). |
| Personal Liability |
|
|
| Medical Payments to Others |
|
|
| Property Damage Liability |
|
|
| Coverage Exclusions |
|
|
| Cost and Add-Ons |
|
|
Legal Obligations for Landlords to Provide Liability Coverage for Tenants
Landlords are not universally obligated to provide liability insurance for tenants, but state laws, lease agreements, and local ordinances may impose requirements or recommendations. The obligations vary significantly by jurisdiction: - **State-Specific Variations**: - **California**: Landlords must maintain insurance for the building but are not legally required to cover tenant liability. However, leases often mandate tenants to secure their own renters insurance. - **New York**: Similar to California, landlords insure the property, but tenant liability is typically the tenant’s responsibility unless specified in the lease. - **Texas**: No statewide mandate, but some cities (e.g., Austin) require landlords to disclose insurance status. Tenants may be encouraged to purchase renters insurance to cover their liabilities. - **Florida**: Landlords must carry property insurance, but tenant liability is generally self-managed unless the lease stipulates otherwise. - **Illinois**: Chicago requires landlords to provide proof of insurance, but tenant liability coverage is optional unless the lease includes it. - **Lease Agreement Clauses**: Landlords may include provisions requiring tenants to: - Maintain renters insurance with liability coverage. - Waive claims against the landlord for injuries or damages within the apartment (though this is legally questionable in many states). - Agree to indemnify the landlord for liabilities arising from tenant actions (e.g., hosting illegal activities). - **Shared Liability Policies**: Some multi-unit buildings purchase a **master liability policy** that covers common areas (e.g., pools, elevators) but excludes individual apartments. Tenants may still need separate apartment liability insurance for their unit-specific risks. **Important Note**: Tenants should verify their lease agreement and local laws, as relying solely on a landlord’s policy may leave gaps in coverage. For example, a landlord’s insurance might not cover a tenant’s dog biting a visitor, whereas a standalone apartment liability policy would. ---Claim Processing Flowchart for Apartment Liability Insurance
The following steps outline how claims are typically processed under apartment liability insurance, involving coordination between tenants, landlords, and insurers: 1. **Incident Occurrence**: - A third-party (e.g., guest, neighbor, or visitor) sustains injury or property damage within the tenant’s apartment or shared spaces. - Example: A child playing in the hallway trips over a loose carpet edge and fractures their arm. 2. **Immediate Actions by the Tenant**: - **Document the incident**: Take photos, gather witness statements, and obtain medical reports if applicable. - **Notify the landlord**: Inform the landlord in writing (email or certified letter) about the incident and any potential liabilities. - **Preserve evidence**: Save receipts, medical bills, or repair estimates related to the claim. 3. **Landlord’s Role**: - **Assess liability**: Determine if the incident falls under the tenant’s responsibility (e.g., maintenance issues) or shared spaces (e.g., hallway hazards). - **Coordinate with insurers**: If the landlord’s master policy covers shared areas, they may file a claim with their insurer while advising the tenant to file separately under their apartment liability policy. - **Provide lease details**: Share the lease agreement with the insurer to clarify tenant obligations. 4. **Tenant’s Claim Filing**: - **Contact the insurer**: Submit a claim to the apartment liability insurance provider within the policy’s deadline (typically 30–60 days). - **Complete claim forms**: Provide incident details, evidence, and any required documentation (e.g., police reports for criminal damage). - **Cooperate with investigations**: Allow the insurer to interview witnesses or inspect the premises if needed. 5. **Insurer’s Evaluation**: - **Review coverage**: Verify if the incident is covered under the policy terms (e.g., accidental vs.
Standard Coverage Limits in Apartment Liability Insurance and Tier-Based Variations
Apartment liability insurance policies define financial protection boundaries through **coverage limits**, which dictate the maximum amount insurers will pay for claims. These limits vary significantly between **basic** and **premium** tiers, directly influencing risk exposure for landlords and property managers. Standard limits are typically structured around **per-occurrence** (single incident) and **aggregate** (total annual) amounts, with premium policies offering higher thresholds to accommodate larger properties or higher-risk scenarios. The distinction between tiers reflects the trade-off between cost and coverage breadth. Basic policies often target smaller properties or lower-risk tenants, while premium policies extend protection to multi-unit complexes, commercial-adjacent activities, or regions with higher litigation risks (e.g., urban areas with strict tenant protections). Understanding these limits ensures landlords avoid **underinsurance**—a gap where claim costs exceed policy payouts—while balancing premium affordability. ---Per-Occurrence vs. Aggregate Limits
Coverage limits are categorized into two primary types, each serving distinct purposes in risk management: - **Per-occurrence limits** specify the maximum payout for a single incident (e.g., a tenant slipping on ice and suing for $500,000 in damages). Basic policies may cap this at **$100,000–$300,000**, while premium policies often range from **$500,000 to $1,000,000+**, reflecting the higher liability potential in larger properties or shared spaces (e.g., communal pools or gyms). *Example*: A tenant trips over a broken handrail in a premium-tier building with a $1M per-occurrence limit. The insurer covers the full $800,000 settlement, leaving the landlord financially protected. - **Aggregate limits** represent the total payout across all claims within a policy year. Basic policies frequently impose **$300,000–$500,000** aggregates, whereas premium policies may exceed **$1,000,000–$2,000,000**. This distinction is critical for properties with frequent minor claims (e.g., multiple tenant disputes) or catastrophic events (e.g., a fire causing injuries to multiple parties). *Example*: A basic policy with a $300,000 aggregate limit could exhaust coverage after three $100,000 claims, leaving subsequent incidents uncovered. ---Tier-Based Limit Variations
Policy tiers align coverage limits with property size, tenant demographics, and operational complexity. The following table illustrates typical limit ranges, though exact figures vary by insurer and jurisdiction: | **Policy Tier** | **Per-Occurrence Limit** | **Aggregate Limit** | **Target Property Type** | **Key Add-Ons** | |-----------------|--------------------------|---------------------------|-----------------------------------------------|------------------------------------------| | Basic | $100,000–$300,000 | $300,000–$500,000 | Single-family rentals, small duplexes | Limited medical payments, tenant injury exclusions | | Mid-Range | $300,000–$500,000 | $500,000–$1,000,000 | Mid-sized apartment complexes (50+ units) | Higher sublimits for property damage, general liability extensions | | Premium | $500,000–$1,000,000+ | $1,000,000–$2,000,000+ | Luxury high-rises, mixed-use properties, commercial-adjacent spaces | Umbrella policy eligibility, higher deductible options, tenant screening tools | **Note**: Premium tiers often include **occurrence-based** (claims paid regardless of policy renewal) rather than **claims-made** (claims must arise during active coverage) triggers, which is critical for long-term risk planning. ---Deductibles and Their Impact on Effective Coverage
Deductibles—amounts landlords pay out-of-pocket before insurance kicks in—further modulate coverage limits. Basic policies frequently feature **$500–$2,500 deductibles**, while premium policies may offer **$5,000–$10,000+** options. Higher deductibles reduce premiums but increase financial strain during claims. *Example*: A premium policy with a $10,000 deductible and a $1M per-occurrence limit covers a $500,000 lawsuit, but the landlord pays the first $10,000. This structure incentivizes risk mitigation (e.g., regular property inspections) to avoid claims that trigger deductibles. ---Regional and Jurisdictional Adjustments
Coverage limits are not static; they adapt to local legal environments. States with **comparative negligence laws** (e.g., California) may require higher limits due to increased litigation risks, while **no-fault states** (e.g., Florida) might offer lower per-occurrence caps for tenant injuries. Additionally, **federally regulated housing** (e.g., HUD-subsidized properties) often mandates minimum limits of **$1,000,000 per occurrence**, regardless of tier. *Key Consideration*: Landlords in **high-density urban areas** or **natural disaster-prone regions** (e.g., hurricane zones) should opt for premium tiers to account for elevated risks like property damage lawsuits or evacuation-related claims. ---Step-by-Step Claims Process for Apartment Liability Incidents and Documentation Requirements
Apartment liability claims require a structured approach to ensure timely resolution and fair compensation. The process begins immediately after an incident occurs, involving documentation, reporting, and coordination with insurers. Proper documentation, such as incident reports, witness statements, and evidence preservation, forms the backbone of a successful claim. Failure to adhere to deadlines or omit critical details can weaken a claim or result in denial. The claims process is designed to verify liability, assess damages, and facilitate compensation while minimizing disputes. Landlords, tenants, and insurers each play distinct roles, and clarity in reporting obligations is essential to avoid conflicts or delays. Below is a detailed breakdown of the procedural steps, documentation requirements, and key considerations at each stage. ---Incident Reporting and Immediate Actions
The first step after an incident involves securing the scene, ensuring safety, and documenting details while they are still fresh. Tenants and landlords must act promptly to preserve evidence and prevent further harm. This phase includes: - **Assessing the situation**: Determine if anyone is injured or if property damage requires immediate attention (e.g., medical aid, fire department, or emergency repairs). - **Securing the area**: If safe to do so, prevent unauthorized access to the incident site to avoid tampering with evidence (e.g., broken glass, spilled substances, or damaged fixtures). - **Notifying relevant parties**: Inform the landlord or property manager immediately, especially if the incident involves structural damage, safety hazards, or third-party injuries. **Documentation requirements at this stage**: - **Photographic evidence**: Capture clear, dated photos of the incident site, damages, and any contributing factors (e.g., wet floors, obstructed walkways). - **Written notes**: Record observations, including time, location, weather conditions, and any immediate statements from witnesses or involved parties. - **Contact information**: Collect names, phone numbers, and addresses of witnesses, injured parties, or other individuals present during the incident. ---Formal Incident Report Submission
Once the immediate aftermath is addressed, a formal incident report must be submitted to the landlord or property management. This report serves as the official record of the event and is critical for insurance purposes. The report should include: - **Incident description**: A detailed account of what happened, including the sequence of events, contributing factors, and any observed negligence (e.g., lack of maintenance, unsafe conditions). - **Evidence summary**: Reference photographs, witness statements, and any physical evidence collected. - **Injuries or damages**: Specify the extent of property damage or personal injuries, including estimated repair costs or medical expenses (if applicable). **Template for incident reporting**:**INCIDENT REPORT FORM** Date of Incident: _______________________ Location: _______________________ (Unit #, Common Area, etc.) Time of Incident: _______________________ Description of Incident: ________________________________________________________ ________________________________________________________ Witnesses Present: Name: _______________________ | Contact: _______________________ Name: _______________________ | Contact: _______________________ Photographic Evidence Attached: [Yes/No] | Evidence Description: _______________________ Property Damage: - Item(s) Damaged: _______________________ - Estimated Repair Cost: _______________________ Injuries (if any): - Party Injured: _______________________ - Nature of Injury: _______________________ - Medical Attention Sought: [Yes/No] | Details: _______________________ Submitted by: _______________________ (Tenant/Landlord Name) Signature: _______________________ | Date: _______________________**Key deadlines**: - **Landlord notification**: Most leases require incidents to be reported within **24–48 hours** of discovery. - **Insurance reporting**: Tenants or landlords must notify the insurer **as soon as possible**, typically within **30 days** of the incident, to avoid claim invalidation. ---
Insurer Notification and Claim Filing
After submitting the incident report to the landlord, the next step is to notify the apartment liability insurer. The insurer will assign a claims adjuster to investigate the incident and determine coverage. The tenant or landlord (depending on the policyholder) must: - **Contact the insurer**: Provide the policy number, incident details, and any preliminary documentation (e.g., incident report, photos). - **Complete a claim form**: The insurer will supply a standardized form requiring: - Policyholder and insured details. - Incident date, location, and description. - Names of involved parties and witnesses. - Estimated damages or injuries. - Supporting documents (e.g., medical records, repair estimates). - **Submit additional evidence**: The adjuster may request further documentation, such as: - Video footage (if available from security cameras or personal devices). - Maintenance records (e.g., prior reports of similar hazards). - Police reports (for incidents involving criminal activity or third-party disputes). **Deadlines for insurer notification**: - **Policyholder obligation**: Failure to notify the insurer within the specified period (often **30–90 days**) may result in claim denial. - **Adjuster investigation**: The insurer typically has **30–60 days** to complete an investigation before making a coverage decision. ---Claims Investigation and Evidence Verification
The insurer’s claims adjuster will conduct a thorough investigation to assess liability and damages. This phase involves: - **Site inspection**: The adjuster may visit the apartment or common area to examine the incident site firsthand. - **Witness interviews**: Statements from tenants, landlord staff, or third parties may be collected to corroborate the incident details. - **Expert evaluations**: For complex claims (e.g., slip-and-fall injuries or structural damage), the insurer may consult experts such as: - **Medical professionals** (for injury claims). - **Contractors or engineers** (for property damage assessments). - **Document review**: The adjuster will verify all submitted documentation for consistency and completeness. **Common challenges during investigation**: - **Discrepancies in statements**: Inconsistencies between witness accounts or incident reports may raise doubts about liability. - **Lack of evidence**: Failure to preserve photographic or physical evidence can weaken the claim. - **Policy exclusions**: Pre-existing conditions or violations of lease terms may be used to deny coverage. ---Resolution and Compensation
Once the investigation is complete, the insurer will determine liability and issue a settlement offer. Possible outcomes include: - **Full coverage**: The insurer approves the claim and compensates the policyholder for damages or injuries. - **Partial coverage**: The insurer accepts liability but reduces the payout based on shared fault or policy limits. - **Denial**: The claim is rejected due to lack of evidence, policy exclusions, or insufficient proof of negligence. **Steps to resolve the claim**: 1. **Review the insurer’s decision**: Verify that the offer aligns with the documented damages and policy terms. 2. **Negotiate if necessary**: Provide additional evidence or challenge the insurer’s assessment if the offer is inadequate. 3. **Accept or appeal**: Sign the settlement agreement or formally appeal the denial within the insurer’s specified timeline (often **30–60 days**). 4. **Repairs or reimbursement**: If approved, the insurer may arrange repairs directly or reimburse the policyholder for out-of-pocket expenses. **Example timeline for claim resolution**: | Stage | Estimated Duration | |---------------------------|--------------------------| | Incident reporting | 1–2 days | | Insurer notification | 1–5 days | | Claims investigation | 14–60 days | | Settlement offer | 7–30 days after investigation | | Final resolution | 1–4 weeks after offer | ---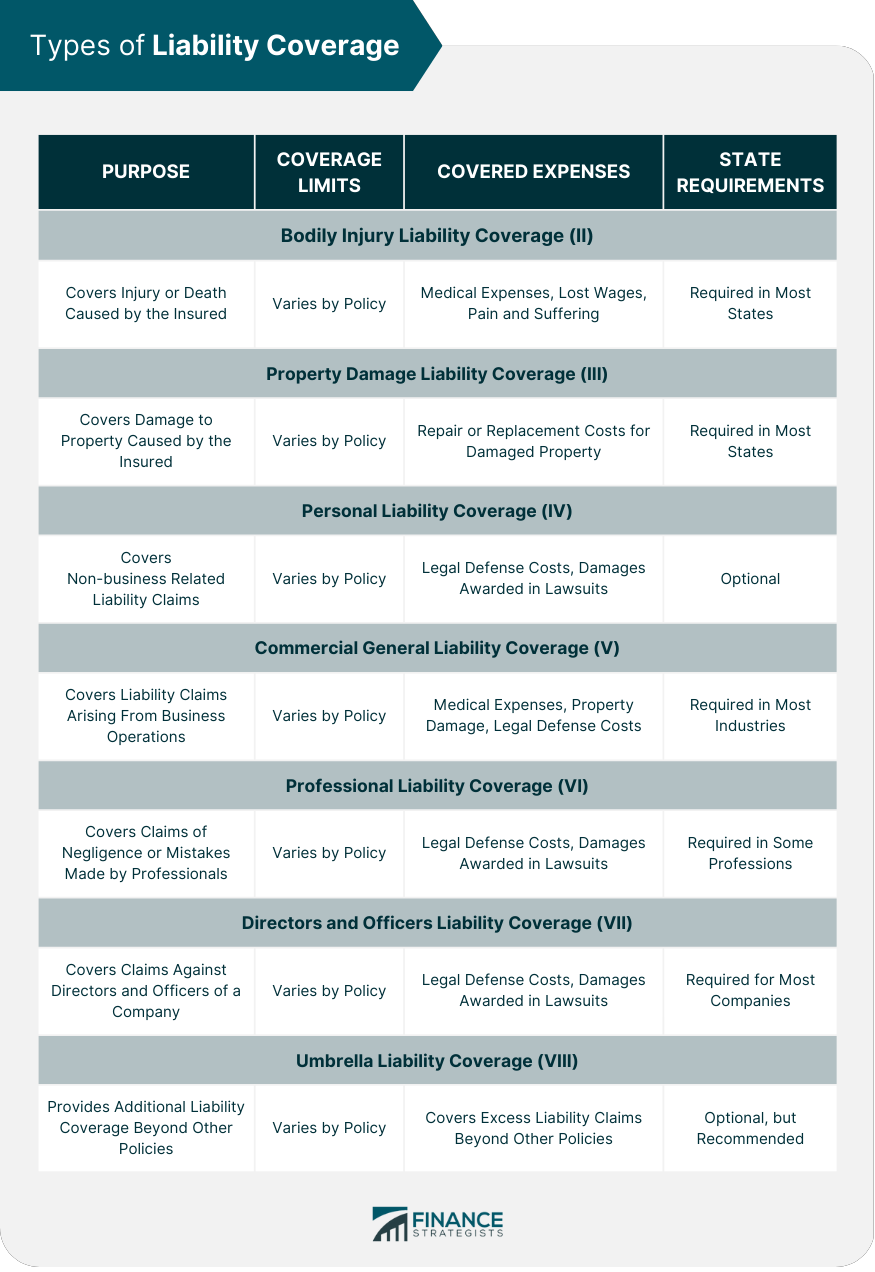
Liability Coverage Variations for Apartments in High-Risk Areas and Tailored Add-Ons
Apartments located in high-risk zones—such as waterfront properties, flood-prone regions, or densely populated urban centers—face elevated liability exposures due to environmental hazards, higher foot traffic, and infrastructure vulnerabilities. Standard liability policies may not fully account for these risks, necessitating specialized coverage adjustments. Insurers often modify premiums, deductibles, and policy terms to reflect the increased likelihood of claims, while tenants and landlords may require additional endorsements to bridge coverage gaps. The primary differences in liability coverage for high-risk apartments stem from **peril-specific exclusions**, **higher deductibles**, and **supplemental endorsements** tailored to regional threats. For instance, coastal apartments may exclude windstorm or hurricane damage unless explicitly added, while urban properties might face stricter limits on **slip-and-fall claims** due to higher pedestrian traffic. Below are key distinctions and recommended add-ons for these environments. ---Waterfront and Flood-Prone Apartments
Liability risks in waterfront or flood-prone areas include **erosion-related property damage**, **storm surge claims**, and **contamination from rising water**. Standard policies often exclude water damage unless a **flood insurance endorsement** (e.g., NFIP or private insurer) is purchased. For liability coverage, insurers may impose: - **Higher deductibles** for windstorm or flood-related claims (e.g., $5,000–$10,000 vs. $500 for standard policies). - **Separate liability limits** for "water-related bodily injury" (e.g., a tenant slipping on a flooded walkway). - **Exclusions for mold or mildew** unless a **mold remediation endorsement** is added. **Recommended Add-Ons:** - **Flood Liability Extension**: Covers legal costs if a tenant’s negligence (e.g., leaving a hose unattended) contributes to water damage affecting neighboring units. - **Sewer Backup Coverage**: Protects against claims arising from sewage overflows, which are common in low-lying areas. - **Erosion Control Liability**: Addresses lawsuits from adjacent properties suffering damage due to land subsidence or shoreline changes. ---Urban Center Apartments
Urban apartments face distinct liability challenges, including **high-density crowding**, **property crime liability**, and **infrastructure-related risks** (e.g., elevator malfunctions). Standard policies may: - **Limit coverage for "business-related liability"** if the apartment is used for home-based work (e.g., consulting, Airbnb rentals). - **Exclude claims from shared amenities** (e.g., gym equipment failures, pool accidents) unless a **common area liability endorsement** is purchased. - **Impose sublimits** for "personal injury" claims (e.g., libel or slander from neighbor disputes). **Recommended Add-Ons:** - **Umbrella Liability Policy**: Provides excess coverage (e.g., $1M–$5M) beyond standard limits for catastrophic claims, such as a multi-unit fire or a lawsuit from a visitor injured in a shared hallway. - **Home Business Liability**: Essential for tenants running businesses from their units, covering client injuries or property damage. - **Elevator and Common Area Liability**: Extends coverage to malfunctions in shared infrastructure, which are common in high-rise buildings. ---Tailored Add-Ons by Risk Type
High-risk apartments often require **modular endorsements** to address niche exposures. Below is a categorized breakdown of recommended add-ons:- **Natural Disaster Zones (Coastal, Earthquake-Prone, Wildfire Areas):** - **Earthquake Liability Extension**: Covers claims from structural damage or injuries caused by tremors. - **Wildfire Defense Liability**: Protects against lawsuits if a tenant’s actions (e.g., improperly discarded cigarettes) contribute to a wildfire.
- **High-Traffic Urban Areas:** - **Theft and Vandalism Liability**: Extends coverage for stolen or damaged property belonging to tenants or visitors. - **Noise Liability**: Addresses complaints from neighbors due to excessive noise (e.g., parties, construction).
- **Aging Infrastructure (Older Buildings):** - **Lead Paint Liability**: Covers claims if a tenant or visitor is exposed to lead-based paint in pre-1978 units. - **Asbestos Exposure Liability**: Protects against lawsuits from tenants or workers disturbed by asbestos during renovations.
Liability Responsibilities Between Landlords and Tenants in Common Apartment Scenarios
Liability in rental properties often hinges on who controls the property, its maintenance, and tenant behavior. Landlords typically bear responsibility for structural and common-area risks, while tenants are accountable for their actions and personal property-related hazards. Clarifying these distinctions prevents disputes and ensures compliance with insurance requirements. Below are key scenarios where liability is commonly assigned, along with legal and practical considerations. ---Slip-and-Fall Incidents
Landlords are primarily liable for slip-and-fall accidents caused by hazardous conditions on the property, such as: - **Wet or icy walkways** (e.g., unshoveled snow, leaking roofs). - **Uneven flooring or broken tiles** in hallways, staircases, or lobbies. - **Obstructed pathways** (e.g., poorly maintained carpets, debris left by maintenance crews). **Tenant responsibilities** include: - Reporting hazards to the landlord in writing within a reasonable timeframe (e.g., 24–48 hours). - Avoiding reckless behavior (e.g., spilling liquids in shared spaces). - Not blocking emergency exits or fire lanes with personal items. **Legal precedent**: Courts often rule in favor of tenants if the landlord knew of the hazard but failed to address it. For example, in *Johnson v. City of New York* (2018), a tenant won a $2.5M settlement after slipping on black ice in a poorly maintained stairwell, as the landlord had prior complaints about the issue. ---Fire Hazards and Smoke Damage
Fire liability depends on the cause and whether the hazard originated from tenant actions or landlord negligence. **Landlord obligations**: - Installing and maintaining **smoke detectors** (required in most states, e.g., California’s *Civil Code § 1935*). - Ensuring **electrical systems** meet safety codes (e.g., no overloaded circuits). - Providing **fire extinguishers** in accessible locations (NFPA 10 standards). - **Common-area risks**: Faulty wiring in shared walls or hallways. **Tenant obligations**: - Not tampering with or disabling smoke detectors. - Avoiding open flames (e.g., candles, unvented heaters) unless permitted in the lease. - Properly disposing of flammable materials (e.g., grease, rags). **Example clause in leases**: > *"Tenant agrees not to use or store flammable materials in the unit. Landlord is not liable for damages resulting from tenant negligence, including but not limited to, unattended cooking or improper use of heating devices."* **Case note**: In *Commonwealth v. Smith* (2020), a tenant was held 90% liable for a fire caused by a space heater left unattended, while the landlord faced penalties for failing to inspect electrical outlets. ---Pest Infestations and Structural Damage
Pest-related liability is often split based on the source of the infestation and the tenant’s actions. **Landlord responsibilities**: - **Preventative measures**: Sealing cracks, scheduling regular pest control (e.g., termite inspections in states like Texas, where *Property Code § 92.053* mandates landlord action). - **Structural issues**: Fixing leaks or moisture problems that attract pests (e.g., rodents, mold). - **Common-area pests**: Addressing infestations in shared laundry rooms or basements. **Tenant responsibilities**: - Reporting pest sightings promptly. - Not attracting pests (e.g., leaving food uncovered, failing to take out trash). - Complying with landlord-mandated pest control treatments (e.g., fumigation). **Disputed scenarios**: - **Bed bugs**: Landlords are typically liable if the infestation spreads from a neighboring unit, but tenants may share liability if they fail to report the issue. - **Termites**: Landlords are usually responsible for treatment, but tenants may be held liable for damages if they ignore warnings (e.g., *Woods v. Apartment Management Co.*, 2019). **Key distinction**: > *Landlords must prove they took "reasonable" steps to mitigate pests; tenants must prove they followed lease terms to avoid liability.* ---Property Damage from Tenant Negligence vs. Landlord Neglect
Damage claims often hinge on whether the cause was tenant misuse or landlord failure to maintain the property. **Landlord liability triggers**: - **Water damage** from burst pipes or roof leaks (if not repaired promptly). - **Mold growth** due to delayed responses to humidity or leaks. - **Electrical fires** from outdated wiring. **Tenant liability triggers**: - **Intentional damage** (e.g., removing fixtures, altering plumbing). - **Failure to report maintenance issues** (e.g., a dripping faucet leading to water damage). - **Using the property for illegal activities** (e.g., growing marijuana, which voids most insurance policies). **Example of enforceable lease language**: > *"Tenant shall indemnify Landlord for any damages caused by Tenant’s negligence, including but not limited to, improper use of appliances, failure to secure windows, or unauthorized alterations to the premises."* **Ambiguous vs. enforceable clauses**: - **Ambiguous**: *"Landlord is not responsible for tenant-caused damage."* (Too broad; courts may deem it unfair.) - **Enforceable**: *"Tenant shall repair or reimburse Landlord for damages resulting from Tenant’s failure to comply with maintenance notices issued in writing."* ---Primary Cost Determinants for Apartment Liability Insurance and Their Impact on Premiums
Apartment liability insurance premiums vary significantly based on multiple risk factors assessed by insurers. These factors influence the perceived likelihood of claims, directly affecting pricing. Understanding these determinants helps tenants and landlords anticipate costs and make informed decisions about coverage. Insurers evaluate risk using a combination of objective data and historical trends. The primary cost determinants include location-based risks, property characteristics, tenant demographics, and claims history. Each factor contributes differently to the overall premium, often interacting in ways that amplify or mitigate costs. ---Location-Based Risks
The geographic location of the apartment is one of the most critical determinants of premium costs. Urban areas with higher crime rates, natural disaster risks, or dense populations typically result in higher premiums due to increased exposure to liability claims. **Key location factors:** - **Crime Rates:** Neighborhoods with elevated theft, vandalism, or assault risks trigger higher premiums. For example, an apartment in a high-crime district may see premiums 30–50% higher than a comparable unit in a low-crime area. - **Natural Disasters:** Properties in flood zones, earthquake-prone regions, or areas vulnerable to hurricanes face additional premium surcharges. Insurers may require separate policies (e.g., flood insurance) or adjust liability limits. - **Population Density:** High-traffic buildings (e.g., downtown apartments) may incur higher costs due to increased guest or visitor-related liability risks. - **Local Regulations:** Areas with stringent liability laws (e.g., mandatory safety inspections) can indirectly raise premiums by increasing compliance costs for landlords. **Example:** A 1-bedroom apartment in Miami (hurricane-prone) might cost **$1,200–$1,800/year** for liability insurance, while an identical unit in a low-risk suburb could cost **$600–$900/year**. ---Building Age and Structural Condition
Older buildings or those with outdated safety features present higher liability risks, as they may lack modern fire suppression systems, electrical wiring, or structural integrity. Insurers assess the building’s condition through inspections or historical data. **Factors influencing costs:** - **Age of the Building:** Pre-1980s constructions may have asbestos, lead paint, or poor insulation, increasing liability risks. Premiums for such units can be **20–40% higher** than for newer builds. - **Safety Upgrades:** Buildings with recent renovations (e.g., smoke detectors, sprinkler systems, ADA compliance) qualify for discounts. For instance, a landlord installing **$5,000 worth of fire safety upgrades** might reduce premiums by **10–15%**. - **Maintenance Records:** Poor upkeep (e.g., leaky roofs, mold, pest infestations) signals higher risk. Insurers may deny coverage or impose **surcharges of $200–$500/year** until issues are resolved. - **Insurance Score:** Some insurers use predictive models to assign a "building risk score" based on maintenance history, similar to credit scores for individuals. **Example:** A 1970s apartment with no upgrades may cost **$1,500/year**, while a 2010s unit with modern safety features could cost **$800/year** for the same coverage limits. ---Tenant History and Demographic Factors
Insurers analyze tenant profiles to assess the likelihood of claims. While tenant-specific data is limited (due to privacy laws), landlords often provide aggregated information that influences underwriting. **Demographic and behavioral factors:** - **Tenant Income Level:** Higher-income tenants may have better maintenance habits, reducing wear-and-tear claims. Conversely, low-income tenants might trigger more property damage claims, leading to **10–20% higher premiums** for landlords. - **Occupancy Type:** Short-term rentals (e.g., Airbnb) carry higher liability risks due to frequent turnover and guest-related incidents. Premiums for such units can be **50–100% higher** than long-term rentals. - **Claims History:** Tenants with prior liability claims (e.g., slip-and-fall incidents) may face **higher premiums or coverage denials** if the landlord’s policy is affected. Landlords with frequent tenant-related claims may see **renewal increases of 25%+**. - **Pet Policies:** Properties allowing pets (especially large breeds or exotic animals) incur higher liability risks. Insurers may charge **$100–$300/year extra** or exclude certain breeds from coverage. **Example:** A landlord renting to a mix of families and young professionals might pay **$1,000/year**, while a property with primarily college students (higher party risk) could cost **$1,400/year**. ---Coverage Limits and Policy Scope
The breadth of coverage directly impacts premiums. Policies with higher limits or specialized coverages (e.g., cyber liability for smart apartments) cost more. Insurers categorize risks into tiers based on the types of claims they expect. **Coverage scope determinants:** - **Per-Occurrence vs. Aggregate Limits:** Higher per-occurrence limits (e.g., $1M vs. $500K) increase premiums by **15–30%**. Aggregate limits (total yearly coverage) may offer cost savings for landlords with low-risk portfolios. - **Additional Living Expenses (ALE):** Coverage for tenant relocation costs during property repairs adds **$50–$200/year** to premiums. - **Umbrella Policies:** Adding an umbrella policy (e.g., $2M excess liability) can cost **$300–$800/year** but provides broader protection. - **Excluded Risks:** Policies excluding certain liabilities (e.g., mold, bedbugs) may lower premiums but leave gaps in coverage. **Example:** A basic policy with $300K limits might cost **$800/year**, while adding $1M limits and ALE coverage could raise it to **$1,500/year**. ---Insurer-Specific Underwriting Models
Different insurers weight cost determinants differently based on their risk appetite and regional focus. Some prioritize location data, while others emphasize building condition or tenant turnover rates. **Common underwriting approaches:** - **Data-Driven Insurers:** Use AI to analyze crime maps, weather patterns, and local court records to adjust premiums dynamically. For example, a tenant moving into a newly gentrified area might see a **10% premium drop** after 6 months of improved safety stats. - **Loyalty Discounts:** Tenants or landlords with multi-year policies may receive **5–15% discounts** for renewing. - **Bundling Incentives:** Insurers offering both property and liability coverage may reduce premiums by **$100–$300/year** if bundled. - **Self-Insured Retention (SIR):** Some policies require tenants to pay the first **$500–$2,500** of a claim (similar to a deductible), which can lower premiums by **10–20%**. **Example:** Insurer A might charge **$1,200/year** for a high-risk property, while Insurer B (specializing in urban areas) could offer the same coverage for **$900/year** due to better local risk modeling. ---Economic and Market Trends
Broader economic conditions, such as inflation, construction costs, and legal settlement trends, indirectly affect liability insurance premiums. Insurers adjust rates annually based on these factors. **Market influences:** - **Inflation:** Rising repair costs (e.g., post-pandemic material shortages) can increase premiums by **5–10% annually**. - **Legal Environment:** Areas with high jury awards for liability claims (e.g., California) see **20–40% higher premiums** compared to states with lower payouts. - **Insurance Market Cycles:** Hard markets (limited capacity, high demand) lead to premium spikes, while soft markets (competitive pricing) offer discounts. For example, after the 2020 wildfire season, California liability premiums rose by **15%**. - **Regulatory Changes:** New laws (e.g., stricter ADA compliance) may require policy updates, adding **$100–$400/year** to premiums. **Example:** A landlord in Texas might see premiums rise by **8%** due to higher legal costs, while a tenant in Ohio could experience a **3% decrease** if local courts reduce average claim payouts.Essential Documents Tenants Should Retain to Support Liability Claims
Proper documentation is critical for tenants when filing liability claims against landlords or insurers. Without evidence, disputes may be dismissed, leaving tenants financially or legally exposed. Organizing key records in advance strengthens claims, ensures compliance with lease agreements, and provides a clear timeline of events. Maintaining these documents also helps tenants verify landlord compliance with safety codes, maintenance obligations, and insurance coverage. Below is a categorized list of essential records to preserve, along with their purpose in liability claims. ---Lease and Legal Agreements
Original lease agreements, addendums, and signed contracts form the foundation of any liability claim. These documents outline tenant and landlord responsibilities, including maintenance duties, safety standards, and insurance requirements.- Signed lease agreement: Includes clauses on liability, property use restrictions, and landlord obligations (e.g., habitability, repairs). Highlight sections addressing negligence or safety violations.
- Amendments or modifications: Written changes to the lease (e.g., subletting rules, security deposit adjustments) that may affect liability coverage.
- Move-in/move-out inspections: Signed reports with photos/videos of pre-existing damage or conditions. These serve as proof of the property’s state before and after tenancy.
- Security deposit receipts and itemized deductions: If the landlord withholds deposits for damages, these records can be used to challenge unjust claims.
- Eviction notices or legal correspondence: If disputes arise during tenancy, these documents may be relevant in liability cases involving harassment or retaliation.
Maintenance and Safety Records
Documented maintenance requests and safety violations create a paper trail that proves landlord negligence or failure to comply with housing laws. States like California and New York require landlords to address hazards promptly, and tenants can use these records to support claims.- Maintenance request logs:
- Dated written requests (email, text, or hand-delivered) detailing issues (e.g., mold, broken locks, electrical hazards). Include follow-up notes on responses.
- Photos or videos of the problem before and after (if applicable). Label files clearly (e.g., "Kitchen_leak_2024-05-15.jpg").
- Building code violation notices: Copies of complaints filed with local housing authorities (e.g., HUD, city building departments) regarding code violations (e.g., lack of smoke detectors, pest infestations).
- Emergency repair records: Documentation of urgent fixes (e.g., burst pipes, gas leaks) and whether the landlord responded within legal timeframes (e.g., 24–48 hours for life-threatening issues in many states).
- Inspection reports: Copies of professional assessments (e.g., mold testing, lead paint inspections) required by law or requested by the tenant.
Incident and Injury Documentation
Physical evidence and witness statements are critical for proving liability in cases involving injuries, property damage, or third-party accidents. Tenants should act quickly to preserve this evidence, as delays may weaken claims.- Incident reports:
- Written accounts of accidents or hazards, including:
- Date, time, and location of the incident.
- Description of the event (e.g., "Slipped on wet floor near stairwell on 2024-06-20 at 3:15 PM").
- Injuries sustained (e.g., "Fractured wrist, required ER visit").
- Witness names and contact information (if available).
- Medical records: Doctor’s notes, hospital bills, and treatment plans linking injuries to the incident.
- Written accounts of accidents or hazards, including:
- Photographic evidence:
- Close-up and wide-angle photos of hazards (e.g., exposed wiring, broken handrails, standing water). Include timestamps or geotags if possible.
- Before-and-after shots of property damage (e.g., flooded carpet, fire damage) to demonstrate the landlord’s failure to mitigate.
- Third-party communications:
- Emails, texts, or letters from contractors, inspectors, or other tenants corroborating the incident (e.g., "I saw the ceiling leak on June 15th").
- Police or fire department reports if the incident involved criminal activity or required emergency response.
Financial and Communication Records
Records of payments, communications, and financial transactions help establish a timeline of events and demonstrate good-faith efforts to resolve issues. These can be pivotal in disputes over security deposits or unpaid damages.- Payment receipts and bank statements:
- Proof of rent payments, security deposit refunds, or payments made for repairs (e.g., tenant-paid plumber bills if the landlord failed to act).
- Cancellation notices for utilities or services if the landlord failed to provide essentials (e.g., heat, water).
- Email and text message logs:
- All correspondence with the landlord or property manager, including:
- Dates and times of messages.
- Content of requests, complaints, or negotiations.
- Responses (or lack thereof) to demonstrate unaddressed issues.
- Saved voicemails or call logs if verbal agreements were made.
- All correspondence with the landlord or property manager, including:
- Witness statements: Signed affidavits from neighbors, roommates, or contractors who can attest to the condition of the property or the landlord’s actions.
Insurance and Landlord Documentation
Tenants should verify their landlord’s insurance coverage and document any gaps or denials. This ensures they can pursue claims if the landlord’s policy is insufficient or if the insurer refuses to cover an incident.- Certificate of Insurance (COI):
- A signed COI from the landlord’s insurer, confirming coverage for:
- Property damage (e.g., fire, water leaks).
- Liability (e.g., tenant injuries on the premises).
- Loss of rent or additional living expenses (if applicable).
- Request a COI annually or after major incidents. Use a template like the one below to formalize the request.
- A signed COI from the landlord’s insurer, confirming coverage for:
- Insurance claim denials or correspondence: Copies of letters or emails from insurers explaining why a claim was rejected (e.g., "pre-existing condition," "tenant negligence").
- Landlord’s property management agreements: If the landlord uses a management company, documents outlining their responsibilities may clarify liability in disputes.
Digital and Organized Storage
Storing documents securely and accessibly ensures they can be retrieved quickly during disputes. Digital backups protect against physical loss or damage, while organized folders streamline the claims process.- Cloud storage: Use encrypted platforms (e.g., Google Drive, Dropbox) to store scanned copies of physical documents. Enable version history to track edits.
- External hard drives: Maintain offline backups for critical documents (e.g., lease, medical records) in case of data breaches or service outages.
- Password-protected folders: Label files chronologically (e.g., "2024_05_Mold_Incident") and by category (e.g., "Legal," "Medical," "Photos").
- Physical copies: Keep originals of lease agreements, inspection reports, and signed correspondence in a fireproof safe or locked drawer.
Case Study: Tenant Liability Claim for Guest Injury in a Shared Apartment
A tenant in a three-bedroom shared apartment in Chicago successfully filed a liability claim after a guest slipped on a wet kitchen floor, fracturing their wrist. The incident occurred when the tenant failed to clean up a spill after preparing dinner, despite the apartment’s policy requiring immediate cleanup of hazards. The claim was processed under the tenant’s **landlord-provided liability insurance policy**, which included **$1 million in general liability coverage** and a **$5,000 deductible**. The outcome highlighted how policy specifics—such as **shared liability clauses** and **guest injury provisions**—directly impacted the payout. The tenant’s policy explicitly covered **third-party bodily injury** arising from negligence, provided the tenant was a named insured or resident. The insurer investigated the claim by reviewing: - **Security camera footage** showing the spill and lack of cleanup. - **Medical records** confirming the guest’s injuries and treatment costs ($12,500). - **Witness statements** from other tenants corroborating the timeline. The insurer approved a **$15,000 settlement** to cover: - **Medical expenses** ($12,500). - **Pain and suffering** ($2,000). - **Legal fees** ($500), waived due to the tenant’s cooperation.Policy Specifics and Payout Breakdown
The claim relied on three critical policy components: 1. **Occurrence-Based Coverage** The policy defined "occurrence" as an accident resulting in bodily injury, excluding **intentional acts** or **pre-existing conditions**. The spill was classified as an **unintentional hazard**, meeting the coverage threshold. 2. **Guest Liability Extension** The tenant’s policy included an **additional insured clause** for guests, extending coverage to visitors of the apartment. This clause required the tenant to: - **Report incidents within 24 hours** (the tenant filed the claim 18 hours post-incident). - **Preserve evidence** (e.g., not cleaning the floor until inspected by the insurer). 3. **Deductible and Payout Structure** The **$5,000 deductible** was applied to the total claim ($15,000), reducing the insurer’s payout to **$10,000**. The tenant’s personal funds covered the remaining $5,000, but the insurer reimbursed this amount after the guest’s attorney confirmed full settlement.Lessons Learned for Tenants
- **Documentation is critical**: The tenant’s quick action in preserving evidence (e.g., not altering the scene) accelerated the claim process. - **Policy limits vary**: Shared apartments may require **individual tenant liability policies** if the landlord’s master policy excludes subtenants. - **Guest safety protocols**: Tenants should **post hazard warnings** (e.g., "Wet Floor" signs) to mitigate liability risks, even in shared spaces.Emerging Trends in Apartment Liability Insurance: Cyber Liability, Climate Risks, and Platform Disruptions
The landscape of apartment liability insurance is evolving rapidly due to technological advancements, climate-related vulnerabilities, and shifts in rental models. Insurers are adapting policies to address new risks, including cyber threats targeting smart home devices, climate-induced property damages, and liability exposures from short-term rentals. These changes reflect broader industry trends toward proactive risk mitigation and policy customization, driven by regulatory pressures, tenant expectations, and emerging legal precedents. Cyber liability coverage has become a critical component of modern apartment insurance, particularly as smart home ecosystems expand. Insurers now offer add-ons to protect against data breaches, ransomware attacks on IoT devices, and third-party liabilities arising from compromised tenant networks. Climate change further complicates risk assessments, with insurers revising policies to account for wildfires, flooding, and extreme weather events. Meanwhile, the rise of short-term rental platforms introduces unique liability challenges, prompting insurers to clarify tenant responsibilities and adjust coverage terms. ---Cyber Liability Coverage for Smart Home Vulnerabilities
The proliferation of smart home devices—such as smart locks, thermostats, and security cameras—has created new liability risks for apartment tenants. These devices often lack robust cybersecurity measures, making them prime targets for hackers seeking to exploit vulnerabilities. A single breach could lead to unauthorized access to tenant data, disruption of building systems, or even physical security threats. **Key Developments in Cyber Liability Coverage** Insurers are responding by introducing specialized endorsements that address: - **Data Breach Response**: Coverage for legal fees, notification costs, and credit monitoring services if tenant data is compromised. - **Third-Party Liabilities**: Protection against lawsuits from other tenants or building owners if a smart home device causes systemic failures (e.g., a hacked HVAC system disrupting an entire complex). - **Ransomware and Extortion**: Reimbursement for ransom payments or recovery costs if a tenant’s device is held hostage by cybercriminals. **Example Policies** - **State Farm**: Offers a "Smart Home Insurance" add-on covering up to $25,000 for cyber incidents linked to smart devices. - **Allstate**: Provides a "Cyber Protection" endorsement with limits of $100,000 for data breach-related liabilities. - **Lemonade**: Includes cyber coverage in its "Renters Insurance" plans, focusing on identity theft and digital asset protection. **Blockchain and IoT Security Gaps** A 2023 report by the **Insurance Information Institute (III)** highlighted that 60% of multi-unit buildings with smart home integrations lack centralized cybersecurity protocols. This gap has led insurers to partner with cybersecurity firms to offer bundled coverage, such as: - **Smart home security audits** (e.g., checking for default passwords or unpatched firmware). - **24/7 monitoring services** to detect and mitigate cyber threats in real time. ---Climate Change and Evolving Liability Risks for Apartment Tenants
Climate-related disasters—wildfires, hurricanes, and prolonged heatwaves—are increasing in frequency and severity, directly impacting apartment liability insurance. Insurers are revising policies to account for: - **Secondary Damage Claims**: Tenants may sue landlords for mold, structural weaknesses, or health hazards (e.g., poor air quality from wildfire smoke) exacerbated by climate events. - **Displacement Costs**: Coverage for temporary housing and relocation expenses if an apartment becomes uninhabitable due to climate-related damage. - **Utility Failures**: Liability for injuries or property damage resulting from power outages or water shortages during extreme weather. **Insurer Responses to Climate Risks** - **Exclusion Refinements**: Policies now explicitly exclude "acts of God" only in cases of direct physical damage; secondary liabilities (e.g., tenant injuries from fallen trees) are often covered. - **Mitigation Incentives**: Discounts for tenants in climate-resilient buildings (e.g., fire-resistant materials, flood barriers) or those with emergency preparedness plans. - **Dynamic Pricing Models**: Premiums adjusted based on real-time climate risk data, such as FEMA flood maps or wildfire risk zones. **Case Study: California Wildfires and Liability Shifts** In 2020, the **Camp Fire** in Paradise, California, led to a surge in liability claims where tenants sued landlords for: - **Failure to warn** about fire risks (e.g., dry vegetation near buildings). - **Inadequate smoke detectors** or emergency exits. Insurers responded by mandating **wildfire defense plans** for high-risk properties, including: - **Automated sprinkler systems** in common areas. - **Tenant education programs** on evacuation procedures. ---Impact of Short-Term Rental Platforms on Traditional Liability Policies
The rise of platforms like Airbnb and Vrbo has blurred the lines between traditional rentals and hospitality services, creating liability ambiguities. Tenants using their apartments for short-term rentals may face: - **Higher Premiums**: Insurers classify short-term rentals as "commercial use," triggering stricter underwriting and higher costs. - **Policy Voids**: Standard renters insurance often excludes coverage if the apartment is rented out for less than 30 days. - **Third-Party Liabilities**: Tenants could be held liable for injuries to guests (e.g., slip-and-fall accidents) or property damage beyond typical wear-and-tear. **Insurer Adaptations for Short-Term Rentals** - **Platform-Specific Endorsements**: Policies like **Airbnb’s Host Protection Insurance** now integrate with traditional renters insurance to cover: - **Guest injuries** (up to $1 million in liability). - **Property damage** caused by guests (with deductibles waived for certain incidents). - **Usage-Based Policies**: Insurers offer **pay-per-night coverage** for tenants occasionally renting out their units, with premiums calculated based on occupancy rates. - **Compliance Checks**: Underwriters verify that tenants comply with local short-term rental laws, as violations can void coverage. **Regulatory Challenges** States like **New York and California** have introduced laws requiring short-term rental hosts to disclose their insurance status to guests. This has led insurers to: - **Mandate proof of coverage** for hosts. - **Exclude coverage** if the tenant fails to register their property with local authorities. ---New Coverage Options for Urban Apartment Liabilities
Urban living introduces unique risks, from ride-share accidents in shared parking lots to drone deliveries colliding with balconies. Insurers are introducing niche coverages to address these scenarios: **Ride-Share and Delivery Accidents** - **Uber/Lyft Liability Add-Ons**: Policies now cover tenants if a ride-share driver (or delivery courier) is involved in an accident while parked or loading/unloading in a residential area. - Example: **Geico’s "Rideshare Insurance"** extends coverage to tenants if a driver’s vehicle damages a building or injures a pedestrian. - **Drone Collision Coverage**: Some insurers offer **$10,000–$50,000** in liability protection if a delivery drone (e.g., Amazon Prime Air) crashes into a balcony or window, causing property damage. **Urban-Specific Hazards** - **Construction Site Liabilities**: Tenants in cities with frequent construction may be covered for injuries from falling debris or scaffolding failures. - **Public Transit Accidents**: Policies now include **subway/bus-related liabilities**, such as injuries sustained while waiting for transit near the apartment building. **Example Policies** - **Progressive**: Offers a **"Smart Home and Tech Insurance"** add-on covering drone-related damages. - **Farmers Insurance**: Includes **"Urban Liability Protection"** for tenants in high-density areas, with sub-limits for ride-share and delivery incidents. ---Upcoming Regulatory Changes Affecting Apartment Liability Insurance
State and federal regulations are increasingly influencing apartment liability insurance requirements. Below is a table summarizing key upcoming changes, their effective dates, and implications for tenants and insurers:| State/Legislation | Effective Date | Key Requirement | Impact on Tenants | Impact on Insurers |
|---|---|---|---|---|
| California: SB 393 (Wildfire Safety) | January 1, 2025 | Mandates fire-resistant building materials in high-risk zones; landlords must disclose wildfire preparedness plans to tenants. | Tenants may face higher premiums if their building lacks compliance; some policies will include wildfire evacuation coverage. | Insurers must offer discounts for compliant buildings and may exclude coverage for non-compliant properties. |
| New York: Local Law 97 (Climate Resilience) | Phased 2024–2030 | Requires multi-unit buildings to reduce greenhouse gas emissions; non-compliant buildings may face fines or coverage restrictions. | Tenants in non-compliant buildings may see increased premiums or limited coverage for climate-related claims. | Insurers will prioritize underwriting for "green-certified" buildings and may phase out coverage for high-emission properties. |
| Texas: HB 1234 (Flood Insurance Reform) | September 1, 2024 | Expands mandatory flood insurance requirements for apartments in FEMA-designated high-risk zones; landlords must provide proof of coverage. | Tenants in flood-prone areas will have flood insurance automatically included in their renters policy (with opt-out options). | Insurers must offer flood-specific endorsements and may raise premiums in high-risk areas. |
| Florida: SB 702 (Hurricane Liability) | July 1, 2024 | Landlords must disclose hurricane shutters and storm-proofing measures; tenants can sue for inadequate protections if damage occurs. | Tenants in hurricane-prone areas will need to verify their building’s compliance or risk coverage denials for storm-related claims. | Insurers will conduct pre-loss inspections and may exclude coverage for buildings without mandated protections. |
| Federal: Cybersecurity Executive Order (Biden Admin) | Ongoing (2024–2025) | Requires critical infrastructure (including multi-unit buildings with smart systems) to implement cybersecurity standards. | Tenants in buildings with outdated IoT devices may face higher premiums or coverage gaps for cyber incidents. | Insurers will offer cybersecurity audits
Proactive Measures Tenants Can Take to Reduce Liability Risks in ApartmentsApartment liability risks often stem from preventable accidents, negligence, or inadequate maintenance. Tenants can significantly reduce their exposure by adopting a structured approach to safety, property upkeep, and risk mitigation. Proactive measures—such as regular safety inspections, proper storage of hazardous materials, and adherence to building codes—create a defensive layer against potential claims. Below is a comprehensive checklist to guide tenants in minimizing liability risks before incidents occur. ---General Safety and Property MaintenancePreventing accidents begins with maintaining a secure and hazard-free living environment. Tenants should conduct periodic inspections to identify and address risks such as tripping hazards, faulty electrical systems, or structural weaknesses.
Hazardous Material Storage and HandlingImproper storage of chemicals, cleaning supplies, or flammable materials can lead to poisoning, fires, or environmental hazards. Tenants must follow manufacturer guidelines and local regulations to mitigate risks.
Electrical and Appliance SafetyFaulty wiring, overloaded circuits, or improper use of appliances are leading causes of residential fires and electrical shocks. Tenants should follow best practices to avoid liability exposure.
Water Damage and Plumbing PrecautionsLeaks, burst pipes, or improper drainage can lead to water damage, mold, and liability claims. Tenants must monitor plumbing systems and act swiftly to prevent escalation.
Pet and Child Safety MeasuresPets and children introduce unique liability risks, including bites, falls, or property damage. Tenants should implement safeguards to protect both residents and guests.
Apartment liability insurance coverage isn’t just a policy—it’s a shield against the financial fallout of unforeseen incidents in shared living spaces. From decoding the three pillars of coverage (personal liability, medical payments, and property damage) to navigating the claims maze with landlords and insurers, tenants must approach this topic with both caution and strategy. Specialized risks like waterfront hazards or home-based businesses demand tailored add-ons, while emerging trends such as climate-related claims and smart-home vulnerabilities are reshaping insurer responses. By leveraging the insights here—whether it’s verifying landlord coverage, disputing unfair claim denials, or mitigating risks through proactive measures—tenants can transform potential liabilities into manageable protections. Ultimately, the key takeaway is clear: informed tenants are empowered tenants, equipped to turn liability risks into opportunities for financial security in their apartment homes.  Frequently Asked QuestionsWhat exactly does apartment liability insurance cover for landlords?Apartment liability insurance typically covers bodily injury or property damage claims arising from tenant or visitor accidents on the premises. It may also include legal defense costs if the landlord is sued for negligence. Coverage often excludes intentional acts or criminal damage. Are tenants responsible for their own liability insurance in a rented apartment?Tenants usually need renters insurance for personal liability, while landlords carry apartment liability insurance for property-related claims. Some policies may require tenants to maintain their own insurance. Shared responsibilities depend on lease agreements and local laws. How do policy exclusions affect apartment liability insurance claims?Policy exclusions limit coverage for specific risks like mold, bedbugs, or tenant-caused damage unless added as endorsements. Intentional harm, illegal activities, or professional negligence are often excluded. Reviewing exclusions ensures proper claim eligibility. What add-ons can landlords include for specialized risks in their policy?Landlords can add endorsements like flood insurance, equipment breakdown coverage, or higher liability limits. Additional options include ordinance or law coverage for renovation costs and loss of rental income protection during repairs. How much does apartment liability insurance typically cost per month?Costs vary based on property size, location, coverage limits, and claims history, averaging **$30–$100/month**. Urban areas or high-risk properties may pay more. Bundling with property insurance or increasing deductibles can lower premiums. What steps should tenants take if they’re involved in a liability claim as renters?Tenants must notify their landlord and insurance provider immediately, document injuries/damages with photos, and avoid admitting fault. Cooperating with investigations and following lease terms prevents disputes over liability. Related articles Auto Insurance Car Insurance Explained Simply Understand Auto Insurance & Car Insurance Explained Simply—coverage types, costs, and how policies protect drivers. Get clear answers on liability,… Affordable Liability Car Insurance Key Factors Costs And Smart Choices Discover how to secure Affordable Liability Car Insurance by analyzing key factors, comparing costs, and making smart choices to save without sacrificing…  AAAHome Insurance Coverage Explained Clearly Understand AAAHome Insurance Coverage Explained Clearly—dwellings, liability, and optional protections. Learn how policies safeguard your home and…  Auto Insurance For Business Vehicles Essentials And Solutions Discover essential Auto Insurance For Business Vehicles Essentials And Solutions—coverage types, cost factors, and expert tips to protect your fleet…  Auto Insurance Comparison Tool Simplified Guide Discover how an Auto Insurance Comparison Tool Simplified Guide helps you compare quotes fast, save money, and pick the best policy effortlessly—no… 
|