Affordable Liability Car Insurance Key Factors Costs And Smart Choices
Table of Contents
- Core Components of Liability Car Insurance and the Role of Affordability for Drivers
- Top 5 Factors Directly Impacting the Cost of Liability Car Insurance
- State-by-State Breakdown of Minimum Liability Coverage Requirements and Non-Compliance Penalties
- 10 Actionable Steps to Lower Liability Insurance Premiums Without Sacrificing Coverage
- Age Groups with Highest Needs for Affordable Liability Insurance and Tailored Cost-Saving Strategies
- Debunking Common Myths About Liability Car Insurance
- Case Study: Reducing Liability Premiums by 30% Through Coverage Adjustments and Discounts
- Alternative Insurance Providers Offering Affordable Liability Policies
- Financial Risks of Carrying Only Minimum Liability Limits
- Step-by-Step Guide to Using Comparison Websites for Affordable Liability Car Insurance Rates
- Visual Elements for an Infographic Comparing Liability Insurance Costs Across Age Groups
- Artificial Intelligence and Predictive Analytics in Personalizing Liability Insurance Pricing
Driving without adequate liability car insurance exposes you to financial ruin in a single accident—yet millions of drivers still prioritize cost over protection. Affordable liability coverage isn’t just about meeting state minimums; it’s about balancing legal requirements with real-world risk exposure. From hidden cost factors like credit scores and location to state-specific loopholes that inflate premiums, the system is designed to confuse as much as it protects. This guide breaks down the hard truths behind liability insurance pricing, equipping you with actionable strategies to secure reliable coverage without breaking the bank. Whether you’re a young driver, a budget-conscious senior, or a policyholder navigating a high-risk state, understanding these dynamics could save you thousands—and prevent a lawsuit from wiping out your savings.
Liability insurance operates on a simple premise: it shields you from lawsuits when you’re at fault, covering medical bills and property damage for others. But the devil lies in the details. Minimum state limits often leave drivers vulnerable to lawsuits exceeding $100,000 in severe accidents, while full-coverage policies can cost 3–5x more. The solution? A tailored approach that aligns coverage with your assets, driving habits, and financial limits. By dissecting how insurers calculate premiums—from your car’s make to your credit history—you’ll uncover overlooked discounts, regional pricing traps, and legal pitfalls that could turn a "cheap" policy into a financial nightmare. Real-world case studies reveal how small adjustments, like bundling policies or adjusting deductibles, can slash premiums by 30% or more, proving affordability isn’t about sacrificing protection but making informed trade-offs.
Core Components of Liability Car Insurance and the Role of Affordability for Drivers
Liability car insurance is a legally required policy in most U.S. states, designed to cover financial losses caused to others when an insured driver is at fault in an accident. Its primary function is to protect third parties—such as pedestrians, passengers, or other drivers—from medical expenses, property damage, and legal claims. Affordability is a critical consideration for drivers because liability coverage directly impacts monthly premiums, which can vary widely based on coverage limits, state requirements, and individual risk profiles. For low-income households or drivers with limited budgets, balancing minimum legal compliance with adequate protection often requires strategic planning to avoid financial strain during claims. The affordability of liability insurance is influenced by several factors, including: - **State minimum requirements**: Lower limits translate to lower premiums but may leave drivers underinsured in high-cost accidents. - **Driving history**: Traffic violations, accidents, or DUIs increase premiums due to higher perceived risk. - **Vehicle type**: Luxury or high-performance cars may incur higher liability costs due to increased property damage potential. - **Location**: Urban areas with higher traffic density or crime rates often result in higher premiums compared to rural regions. - **Discounts**: Bundling policies (e.g., home and auto), maintaining a clean driving record, or enrolling in defensive driving courses can reduce costs. Drivers must weigh the short-term savings of minimal coverage against the long-term risks of insufficient protection. For example, a driver in a state with a $25,000 bodily injury limit may face significant out-of-pocket expenses if an accident results in $100,000 in medical bills, leaving them vulnerable to lawsuits or asset seizure. ---Liability Coverage Breakdown: Bodily Injury, Property Damage, and Policy Exclusions
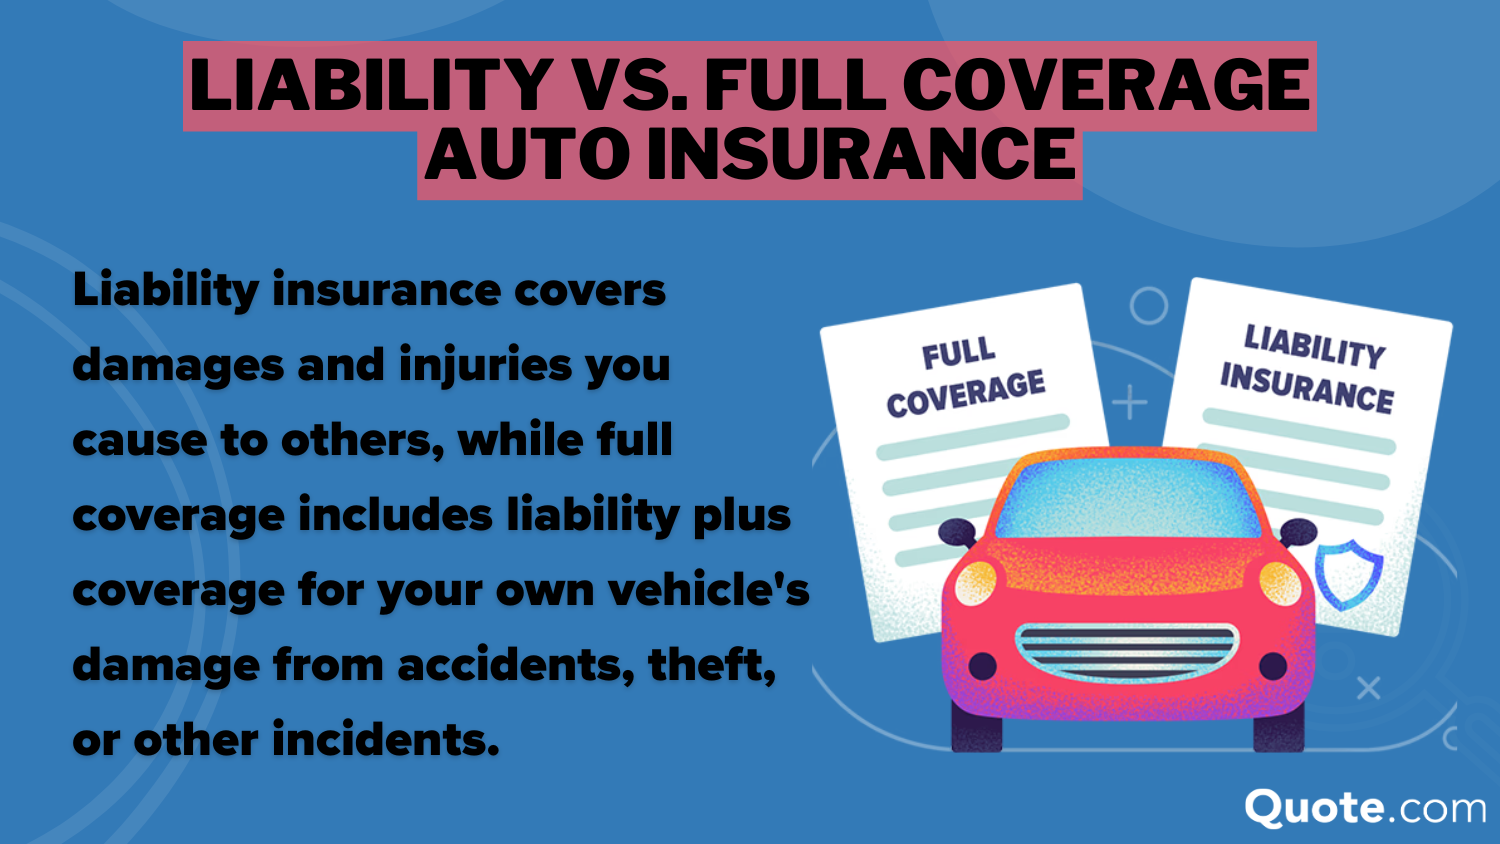
Liability car insurance is structured around two core components: 1. **Bodily Injury Liability (BI)**: Covers medical expenses, lost wages, and legal fees for injuries sustained by others in an accident caused by the policyholder. This includes: - **Medical payments** for emergency care, surgeries, and rehabilitation. - **Lost income** compensation for affected individuals. - **Legal defense costs** if the policyholder is sued for negligence. 2. **Property Damage Liability (PD)**: Pays for repairs or replacement of damaged property (e.g., other vehicles, fences, or buildings) due to the insured’s fault. This excludes damage to the policyholder’s own vehicle. **Key distinctions from full coverage**: - **Collision and Comprehensive Coverage**: Full coverage includes additional protections for the policyholder’s vehicle, such as damage from crashes (collision) or theft/vandalism (comprehensive). Liability insurance does not cover the insured’s own car or injuries. - **Uninsured/Underinsured Motorist Protection**: Often sold as an add-on, this covers the policyholder if the at-fault driver lacks sufficient insurance. Liability policies do not include this by default. - **Personal Injury Protection (PIP)**: Required in some states (e.g., "no-fault" states like Florida or New York), PIP covers medical expenses regardless of fault. Liability insurance does not replace PIP. **Exclusions in liability policies**: - Injuries or damage to the policyholder or their passengers. - Damage to the insured’s own vehicle. - Intentional acts or criminal behavior. - Racing or using the vehicle for commercial purposes without additional endorsements. ---State Minimum Liability Limits vs. Recommended Higher Limits
State-mandated liability limits are often insufficient to cover severe accidents, leaving drivers exposed to financial ruin. Below is a comparison of minimum requirements versus recommended limits (based on industry standards and the **Insurance Information Institute**):| State | Minimum Bodily Injury (per person/per accident) | Minimum Property Damage | Recommended Limits (for better protection) | Example Cost Impact (Annual Premium Difference) |
|---|---|---|---|---|
| California | $15,000 / $30,000 | $5,000 | $100,000 / $300,000 bodily injury, $100,000 property damage | $50–$150 more annually for higher limits |
| Texas | $30,000 / $60,000 | $25,000 | $250,000 / $500,000 bodily injury, $100,000 property damage | $100–$300 more annually |
| Florida | $10,000 / $20,000 | $10,000 | $250,000 / $500,000 bodily injury, $100,000 property damage | $200–$400 more annually |
| New York | $25,000 / $50,000 | $10,000 | $250,000 / $500,000 bodily injury, $100,000 property damage | $150–$350 more annually |
| Illinois | $20,000 / $40,000 | $15,000 | $250,000 / $500,000 bodily injury, $100,000 property damage | $100–$250 more annually |
Step-by-Step Process: How Liability Insurance Works in a Collision
When an insured driver causes an accident, the liability insurance claim process follows these steps: 1. **Immediate Actions at the Scene** - **Report the accident** to local authorities if required by law (e.g., injuries, fatalities, or property damage over a threshold like $1,000). - **Exchange information** with the other party: names, contact details, license plate numbers, and insurance policy numbers. - **Document evidence**: Take photos of damage, injuries, and the scene (e.g., skid marks, traffic signals). Witness statements are critical. - **Notify the insurance company** as soon as possible, even if fault is unclear. Delaying reporting may void the claim. 2. **Insurance Investigation** - The insurer assigns an adjuster to determine fault based on: - Police reports. - Witness testimonies. - Physical evidence (e.g., damage patterns, traffic camera footage). - If the policyholder is deemed at fault, the insurer begins processing the claim. 3. **Claim Filing and Payout** - **Third-party claims**: The insurer pays medical bills and property damage directly to the injured party or their repair shop, up to the policy limits. - **Legal defense**: If sued, the insurer covers attorney fees and settlements, even if the claim exceeds policy limits (though the policyholder remains liable for amounts beyond coverage). - **No direct payout to the policyholder**: Liability insurance does not reimburse the insured for their own injuries or vehicle repairs. 4. **Policyholder Responsibilities** - **Cooperate fully** with the insurer’s investigation, providing requested documents (e.g., medical records, repair estimates). - **Avoid admitting fault** to the other party or their insurer, as statements can be used against the policyholder. - **Understand policy exclusions**: Pre-existing conditions or intentional acts may not be covered. **Example Scenario**: A driver in Texas with 50/100/30 coverage hits a pedestrian, causing $80,000 in medical expenses. The insurer pays the full $50,000 per person limit ($100,000 total for bodily injury), leaving the remaining $30,000 as the policyholder’s responsibility. If the pedestrian sues for the full amount, the driver’s personal assets (e.g., savings, home) could be at risk without additional coverage. ---Deductibles and Premiums in Liability-Only Policies: Cost-Saving Strategies
Liability insurance typically does not include deductibles (since it covers third-party claims), but understanding how premiums and optional add-ons interact can optimize affordability: 1. **Premium Factors for Liability Policies** - **Coverage limits**: Higher limits increase premiums but reduce out-of-pocket risks. For example, raising limits from 25/50/25 to 100/300/100 may add $100–$300 annually. - **Driving record**: A single at-fault accident can increase premiums by **20–50%** for 3–5 years. Safe drivers often qualify for discounts. - **Vehicle usage**: Commuting long distances or using the car for rideshare (e.g., Uber) may increase costs due to higher exposure. 2. **Cost-Saving Strategies** - **Bundle policies**: Combining auto and homeowners/renter’s insurance with the same provider can yield **10–20% savings**. - **Increase deductibles on collision/comprehensive** (if added): While liability policies lack deductibles, opting for higher deductibles on other coverages can lower premiums. For example, raising a deductible from $500 to $1,000 may reduce annual costs by **$200–$400**. - **Pay annually**: Some insurers offer discounts (e.g., **2–5%**) for lump-sum payments instead of monthly installments. - **Discounts for low mileage**: Drivers who commute less than 7,500 miles/year may qualify for savings. - **Usage-based insurance**: Programs like **Progressive’s Snapshot** or **State Farm’s Drive Safe & Save** track driving habits (e.g., speed, braking) and reward safe behavior with lower premiums. 3. **Trade
Top 5 Factors Directly Impacting the Cost of Liability Car Insurance
Liability car insurance premiums are determined by a combination of risk-based factors that insurers evaluate to assess the likelihood of a claim. While some variables, such as driving history, are widely understood, others operate subtly to influence costs. Understanding these key determinants allows drivers to make informed decisions to potentially lower their premiums. Below are the five most significant factors that directly affect liability insurance costs, ranked by their impact. Insurance providers use actuarial data to quantify risk, and these five factors represent the core variables insurers prioritize when calculating premiums. Each factor contributes uniquely to the final cost, often interacting with others to create a tailored rate. For example, a driver with a clean record in a high-crime urban area may still face higher premiums due to location-based risks, while a driver with a poor credit score in a rural area might see elevated costs from credit-based underwriting.Driving Record and Claims History
A driver’s history of traffic violations, accidents, and claims is the most critical factor influencing liability insurance costs. Insurers classify drivers into risk tiers based on their past behavior, with severe violations (e.g., DUIs, reckless driving) leading to significantly higher premiums. Even minor infractions, such as speeding tickets or at-fault accidents, can increase costs by 20–50% or more, depending on the insurer and state regulations. **Key considerations:** - **Severity and frequency of violations:** A single DUI can raise premiums by 60–100% for 3–5 years, while repeated speeding tickets may trigger higher surcharges. - **Claims frequency:** Drivers with a history of filing liability claims (even non-at-fault) may face scrutiny, as insurers assume a higher propensity for future claims. - **State-specific penalties:** Some states, like California and New York, impose stricter penalties for violations, leading to longer premium hikes compared to others. - **Accident forgiveness programs:** Certain insurers offer one-time accident forgiveness for policyholders with clean records, preventing a single claim from spiking premiums.Geographic Location and Local Risk Factors
Location is a primary cost driver because it reflects regional differences in accident rates, theft frequency, weather conditions, and population density. Urban areas typically have higher premiums due to increased traffic congestion, higher crime rates, and greater exposure to accidents. Conversely, rural areas may offer lower costs but can see spikes in premiums during severe weather seasons (e.g., hailstorms in Texas or blizzards in the Midwest). **Key considerations:** - **Urban vs. rural density:** Cities like Los Angeles and Chicago experience higher accident rates due to heavy traffic, while rural areas may have fewer accidents but higher risks of uninsured motorists. - **Theft and vandalism rates:** States with high vehicle theft rates (e.g., California, Texas) or urban areas with frequent car break-ins may see elevated premiums. - **Weather-related risks:** Regions prone to hurricanes (Florida), floods (Louisiana), or ice storms (Upper Midwest) face higher claims costs, translating to higher premiums. - **State minimum coverage laws:** States with lower liability limits (e.g., Florida’s $10K/$20K/$10K) may have cheaper base premiums but higher out-of-pocket risks for drivers.Vehicle Make, Model, and Year
The type of vehicle a driver operates directly impacts insurance costs due to variations in repair costs, theft rates, safety ratings, and engine power. Luxury or high-performance cars often incur higher premiums because they are more expensive to repair or replace. Conversely, affordable, fuel-efficient vehicles with strong safety ratings tend to qualify for lower rates. **Key considerations:** - **Repair and replacement costs:** Vehicles with expensive parts (e.g., BMWs, Mercedes-Benz) or those classified as "total losses" more frequently (e.g., sports cars) drive up premiums. - **Theft risk:** Models frequently targeted by thieves (e.g., Honda Civics, Ford F-Series in certain years) may see higher premiums due to increased claims. - **Safety and crash test ratings:** Vehicles with top safety ratings (e.g., Subaru Outback, Volvo XC60) often qualify for discounts, while those with poor ratings (e.g., some compact SUVs) face higher costs. - **Engine size and performance:** High-horsepower vehicles (e.g., Mustang GT, Camaro SS) are statistically more likely to be involved in accidents, leading to elevated premiums.Driver’s Age and Experience
Age is a significant factor because it correlates with risk-taking behavior and driving experience. Young drivers (under 25) and elderly drivers (over 65) typically pay higher premiums due to higher accident rates. Teenagers, in particular, face the steepest premiums because of their lack of experience and tendency toward risky driving habits. **Key considerations:** - **Young drivers (16–24):** Premiums can be 2–3 times higher than the average due to inexperience and higher claim frequencies. Adding a teen to a policy may increase costs by 100–200%. - **Senior drivers (65+):** While generally safer, cognitive decline or slower reaction times may lead to higher premiums, especially for those with medical conditions. - **Experience discounts:** Drivers with 5+ years of experience often qualify for lower rates, as insurers assume reduced risk. - **Student discounts:** Full-time students with good grades (typically B average or higher) may receive discounts of 10–25%.Credit-Based Insurance Scores
In most states, insurers use credit-based insurance scores (not traditional credit scores) to assess a driver’s financial responsibility. Studies show a correlation between credit history and claim frequency, though the practice is banned in states like California, Hawaii, and Massachusetts. Drivers with poor credit may pay 20–50% more for the same coverage. **Key considerations:** - **Credit score impact:** A score below 580 may lead to premiums 30–50% higher than those with scores above 700. - **State regulations:** States like California prohibit credit-based pricing, while others (e.g., Texas, Florida) allow it, creating significant cost disparities. - **Alternatives for poor credit:** Some insurers specialize in high-risk drivers (e.g., Progressive’s Snapshot program, State Farm’s Steer Clear) or offer payment plans to mitigate upfront costs. - **Improving scores:** Paying bills on time, reducing debt, and monitoring credit reports can gradually lower premiums over time.State-by-State Breakdown of Minimum Liability Coverage Requirements and Non-Compliance Penalties
Liability insurance requirements vary significantly across U.S. states, reflecting differences in legal frameworks, population density, and risk exposure. Below is a structured table summarizing the minimum bodily injury (BI) and property damage (PD) coverage limits, along with penalties for non-compliance, as of 2024. These requirements are critical for drivers to meet legal obligations and avoid financial or legal consequences. States typically mandate **bodily injury liability per person/policy** (e.g., 25/50) and **property damage liability** (e.g., $10,000), though some states impose stricter limits or additional requirements. Penalties for non-compliance range from fines and license suspensions to criminal charges in severe cases.| State | Bodily Injury (Per Person/Policy) | Property Damage | Penalties for Non-Compliance |
|---|---|---|---|
| Alabama | 25/50 | $25,000 | Fines up to $500, license suspension, mandatory SR-22 filing for 3 years. |
| California | 15/30 | $5,000 | Fines ($100–$200), license suspension, possible jail time for repeat offenses. |
| Florida | 10/20 | $10,000 | Fines ($150–$500), license suspension, mandatory insurance verification (FHSMV compliance check). |
| Michigan | No state-mandated minimum (no-fault state; PIP required) | No state-mandated minimum (but PIP covers property damage) | Fines ($500–$1,000), license suspension, potential criminal charges for willful non-compliance. |
| New York | 25/50 | $10,000 | Fines ($150–$1,500), license suspension, mandatory SR-22 for 3 years. |
| Texas | 30/60 | $25,000 | Fines ($175–$350), license suspension, mandatory SR-22 for 2 years. |
| Mississippi | 25/50 | $25,000 | Fines ($100–$500), license suspension, possible vehicle impoundment. |
| North Dakota | 30/60 | $25,000 | Fines ($1,000+), license suspension, mandatory SR-22 for 3 years. |
| South Dakota | 25/50 | $25,000 | Fines ($500–$1,000), license suspension, possible criminal misdemeanor charges. |
| Vermont | 25/50 | $10,000 | Fines ($500–$1,000), license suspension, mandatory SR-22 for 3 years. |
| Washington | 25/50 | $10,000 | Fines ($125–$500), license suspension, possible vehicle registration revocation. |
Impact of No-Fault vs. At-Fault States on Liability Insurance Costs and Coverage
No-fault and at-fault states fundamentally alter how liability insurance functions, influencing both **premiums** and **coverage options**. These differences stem from legal frameworks that determine fault assignment, claim processing, and financial responsibility after accidents. No-fault states require drivers to file claims with their **own insurers** regardless of fault, reducing litigation but increasing reliance on **PIP/MedPay** for medical expenses. This system often **lowers liability premiums** because insurers pay out less for third-party claims. However, **PIP costs** (e.g., Michigan’s $3,000+ annual PIP premiums) can offset savings. In contrast, at-fault states allow **direct lawsuits** against at-fault drivers, leading to higher liability payouts and **inflated premiums** in high-risk areas. **Coverage Implications:** - **No-fault states**: Drivers may opt for **lower liability limits** (e.g., Florida’s 10/20) but must carry **PIP** (e.g., Michigan’s unlimited lifetime medical coverage). This can make **total insurance costs higher** despite lower liability premiums. - **At-fault states**: Higher liability limits (e.g., Texas’s 30/60) are standard, but **uninsured/underinsured motorist (UM/UIM) coverage** becomes critical due to higher rates of uninsured drivers.States with Highest and Lowest Average Liability Insurance Costs: Underlying Factors
Liability insurance costs are heavily influenced by **population density, legal climate, traffic congestion, and state-specific risk factors**. Below are examples of states with **highest and lowest average annual liability premiums** (based on 2023–2024 data), along with key contributing factors. **Highest Average Costs:** 1. **Michigan**: ~$2,500/year (highest in the U.S.) - **Reasons**: Mandatory **unlimited PIP coverage**, high medical costs, and a **no-fault system** that incentivizes frequent claims. Insurers also face **strict regulatory oversight** and **high fraud rates**. 2. **Louisiana**: ~$1,800/year - **Reasons**: **High population density in New Orleans/Baton Rouge**, frequent **hurricane-related claims**, and **lenient legal climate** (e.g., higher payouts for pain and suffering). 3. **Florida**: ~$1,500/year - **Reasons**: **High traffic congestion**, **high uninsured driver rates (25%)**, and **no-fault PIP system** with inflated medical costs. **Lowest Average Costs:** 1. **Ohio**: ~$600/year - **Reasons**: **Competitive insurance market**, **lower population density**, and **moderate legal climate** (e.g., no mandatory PIP in most cases). 2. **Iowa**: ~$550/year - **Reasons**: **Low traffic density**, **strict driver licensing laws**, and **fewer uninsured drivers (5%)**. 3. **North Dakota**: ~$500/year - **Reasons**: **Sparse population**, **low accident rates**, and **high adherence to liability limits**. **Legal Climate and Risk Factors:** - **States with high litigation rates** (e.g., California, New York) see **higher premiums** due to **excessive damage awards** and **insurance fraud**. - **States with weak financial responsibility laws** (e.g., Mississippi, New Mexico) have **higher uninsured motorist rates**, increasing **UM/UIM coverage costs**. - **Urban states** (e.g., New Jersey, Illinois) face **higher accident frequencies** due to congestion, raising premiums.Impact of Uninsured/Underinsured Motorist Coverage on Affordability in High-Risk States
Uninsured/underinsured motorist (UM/UIM) coverage is **mandatory or highly recommended** in states with **high rates of uninsured drivers**, directly affecting liability insurance affordability. UM/UIM protects policyholders when at-fault parties lack sufficient coverage, but its cost varies by state due to **risk exposure and legal requirements**. **States with Highest Uninsured Driver Rates (2023 Data):** - **Mississippi**: 27.4% uninsured - **New Mexico**: 25.1% uninsured - **Oklahoma**: 24.8% uninsured - **Florida**: 23.5% uninsured - **Texas**: 16.5% uninsured **Cost Implications:** - **Mandatory UM/UIM States**: In **Florida, New Jersey, and North Dakota**, UM/UIM is **required**, increasing premiums by **10–30%** but providing critical protection. - **Optional but Recommended States**: In **Texas and California**, UM/UIM is optional but **strongly advised** due to high uninsured rates, adding **$50–$200/year** to policies. - **Fraud and Claim Abuse**: States like **Mississippi and New Mexico** see **higher UM/UIM payouts** due to **staged accidents and exaggerated claims**, driving up costs for all drivers. **Example Scenarios:** - **Mississippi**: A driver with **25/50/25 liability** may pay **$1,200/year** but require **$50,000 UM/UIM**, adding **$300–$500/year** to the premium. - **North Dakota**: Despite low uninsured rates (5%), **UM/UIM is mandatory**, but costs remain low (**$1
10 Actionable Steps to Lower Liability Insurance Premiums Without Sacrificing Coverage
Reducing liability insurance costs requires strategic adjustments to policy terms, driving habits, and insurer relationships. These steps leverage discounts, risk mitigation, and market awareness to achieve savings while preserving essential coverage. Below is a structured checklist to implement cost-saving measures effectively.Optimize Policy Terms and Deductibles
Adjusting deductibles and coverage limits can significantly impact premiums, provided the trade-off aligns with financial risk tolerance. Higher deductibles reduce monthly costs but require larger out-of-pocket payments during claims. State minimum liability limits (e.g., 25/50/25 in many states) may suffice for budget-conscious drivers, though higher limits offer better asset protection.Maintain a Clean Driving Record
Insurers assess risk based on driving history, and a clean record (no at-fault accidents or traffic violations) qualifies drivers for lower premiums. Defensive driving courses (e.g., through AAA or local agencies) can further reduce rates by demonstrating commitment to safety. Even minor infractions, such as speeding tickets, can increase premiums by **15–30%** for 3–5 years.Bundle Policies for Multi-Policy Discounts
Combining auto insurance with homeowners, renters, or life insurance policies often yields **10–25%** discounts. Insurers prefer bundling as it reduces administrative overhead and increases customer retention. For example, a driver paying $1,200 annually for standalone auto insurance might save **$120–$300** by bundling with a home policy.Leverage Discounts for Specific Demographics
Insurers offer targeted discounts for: - **Low-mileage drivers** (under 7,500 miles/year). - **Students** with grades above B (good student discount, typically **10–25%**). - **Retirees** or drivers who work remotely (reduced commute risk). - **Military personnel** (active duty or veterans, often **10–15%** off). Verifying eligibility ensures no missed savings opportunities.Explore Usage-Based Insurance Programs
Programs like **Progressive Snapshot** or **State Farm Drive Safe & Save** track driving behavior (speed, braking, mileage) via telematics. Low-risk drivers can earn discounts of **5–30%** annually. For example, a driver averaging 60 mph (instead of 70 mph) might save **$100–$200/year**. These programs are ideal for low-mileage or safe urban commuters.Review and Update Personal Information Annually
Life changes—such as marriage, moving, or career shifts—can impact insurability. Married couples often qualify for **5–10%** discounts, while relocating to a low-crime area may reduce premiums by **10–20%**. Updating mileage estimates (e.g., switching from 15,000 to 8,000 miles/year) can also lower costs.Increase Security and Anti-Theft Measures
Installing **anti-theft devices** (e.g., GPS trackers, steering wheel locks) or **vehicle safety features** (e.g., anti-lock brakes, airbags) can reduce premiums by **5–15%**. Insurers view these as mitigating theft or accident risks. Some states (e.g., California) mandate discounts for approved safety equipment.Pay Premiums in Full or Use Automated Payments
Opting for **annual payments** instead of monthly installments can save **3–8%** in processing fees. Automated payments or paperless billing also yield discounts (typically **2–5%**). For example, a $1,500 annual premium might drop to **$1,410** with a paperless discount.Compare Quotes Biannually or After Major Life Events
Insurance rates fluctuate due to market conditions, claims trends, and insurer policies. Using comparison tools (e.g., **The Zebra, NerdWallet**) can reveal **10–30%** savings by switching providers. Major events—such as buying a new car, retiring, or changing jobs—trigger the need for a rate review.Avoid Lapses in Coverage
Continuous coverage demonstrates lower risk to insurers. A lapse (even for a few weeks) can increase premiums by **20–50%** upon renewal. Some insurers offer **loyalty discounts** (up to **10%**) for policyholders with **5+ years** of uninterrupted coverage.Negotiate Rates with Current Insurers
Insurers often adjust rates based on competition. After receiving a lower quote from another provider, request a **rate match** from your current insurer. Highlight factors like: - Improved credit score (if applicable). - Updated driving habits (e.g., reduced mileage). - Bundling opportunities. - Loyalty as a long-term customer.Age Groups with Highest Needs for Affordable Liability Insurance and Tailored Cost-Saving Strategies
Affordable liability car insurance is a critical concern for specific age demographics due to varying risk profiles, financial constraints, and life stages. Young drivers, seniors, and low-income households face unique challenges in securing cost-effective coverage while maintaining compliance with legal requirements. Understanding these groups’ needs allows for targeted strategies to reduce premiums without compromising protection. Insurance costs are influenced by factors such as driving experience, vehicle type, credit history, and location. Age-related trends—such as higher accident rates among teens or limited mobility among seniors—directly impact premiums. Below are tailored strategies for each demographic, emphasizing eligibility for discounts, alternative coverage options, and financial assistance programs. ---Young Drivers (Ages 16–25)
Young drivers consistently pay the highest liability insurance premiums due to their limited driving experience and higher accident rates. According to the Insurance Information Institute (III), drivers under 25 are involved in nearly **30% of all fatal crashes**, making them a high-risk group for insurers. Parents or guardians often explore ways to reduce costs while ensuring compliance with state minimum liability requirements. **Key Strategies for Cost Reduction:** - **Graduated Licensing Programs (GLP):** Many states require young drivers to progress through stages (learner’s permit, intermediate license, full license) with restrictions (e.g., nighttime driving limits). Completing GLP successfully may qualify for **good student discounts** or **safe driver incentives** from insurers. - **Parental Policies and Named Driver Additions:** Adding a young driver to a parent’s policy is often cheaper than independent coverage. However, this increases the parent’s premium by **50–150%** or more, depending on the insurer. Parents should compare quotes from multiple providers to find the least expensive option. - **Usage-Based Insurance (UBI):** Programs like **Progressive’s Snapshot** or **State Farm’s Drive Safe & Save** track driving behavior (speed, braking, mileage) and offer discounts of **10–30%** for low-risk habits. Teens with UBI may see reductions if they drive cautiously. - **Affordable Vehicle Selection:** Choosing a **low-cost, high-safety vehicle** (e.g., Honda Civic, Toyota Corolla) reduces collision repair costs, indirectly lowering liability premiums. Insurers often classify older or less powerful cars as lower risk. - **Student Discounts:** Maintaining a **B average or higher** can qualify teens for **good student discounts (10–25%)**, even if they are not listed on the policy. Some insurers (e.g., Geico, Allstate) offer this to students living away from home. - **Defensive Driving Courses:** Completing **state-approved defensive driving programs** (e.g., AARP’s Smart Driver Course) can yield **5–15% discounts** for young drivers, provided the course is recognized by local insurers. **Example Scenario:** A 19-year-old driver in Texas with a learner’s permit added to a parent’s policy might pay **$3,500–$5,000 annually** for full coverage. By enrolling in a defensive driving course and using UBI, the premium could drop to **$2,800–$4,000**, saving **$700–$1,200** per year. ---Senior Drivers (Ages 65+)
Senior drivers often face **higher liability insurance costs** due to age-related risks such as slower reaction times, medical conditions, or increased frailty. However, many seniors are **low-mileage drivers**, which can offset some costs. Additionally, some insurers offer **mature driver discounts** or specialized programs for older adults. **Key Strategies for Cost Reduction:** - **Low-Mileage Discounts:** Insurers like **State Farm and AAA** offer discounts for drivers who log fewer than **7,500 miles annually**. Seniors who drive infrequently (e.g., for errands or medical appointments) can save **5–15%**. - **Retirement and Senior Discounts:** Some insurers provide **retirement discounts (5–10%)** for policyholders who are no longer commuting daily. Programs like **AARP’s Auto Insurance Program** often negotiate lower rates for members aged 50+. - **Refresher Driving Courses:** Completing a **senior driver safety course** (e.g., through AARP or local DMVs) can improve driving skills and may qualify seniors for **insurance discounts (10–20%)** in states like California and Florida. - **Vehicle Safety Features:** Equipping a car with **anti-lock brakes, adaptive cruise control, or backup cameras** can reduce accident risks, leading to lower premiums. Some insurers offer **telematics discounts** for seniors who install devices like **OnStar or Mobileye**. - **Bundling Policies:** Seniors with homeowners or renters insurance can save **10–20%** by bundling with the same provider. Companies like **Liberty Mutual and Farmers** often provide multi-policy discounts. - **Voluntary Pay-Per-Mile (PPM) Insurance:** Programs like **Metromile** allow seniors to pay based on actual miles driven, which can be **30–50% cheaper** than traditional policies for low-mileage drivers. **Example Scenario:** A 70-year-old retiree in Florida driving **5,000 miles/year** might pay **$1,200 annually** for liability-only coverage. By enrolling in a senior driving course and switching to a PPM plan, their premium could drop to **$700–$900**, saving **$300–$500** yearly. ---Low-Income Households
Low-income individuals often struggle with **high insurance costs relative to their disposable income**, making affordability a top priority. Many states offer **financial assistance programs** to ensure compliance with liability requirements without causing financial strain. The **Insurance Research Council (IRC)** estimates that **1 in 8 drivers** are underinsured due to cost barriers. **Key Strategies for Cost Reduction:** - **State-Specific Financial Assistance Programs:** - **California:** The **California Low-Cost Auto Insurance Program (CLCA)** provides liability coverage for **$300–$400 annually** for low-income drivers who meet income thresholds (typically **≤125% of the federal poverty level**). - **New York:** The **New York Auto Insurance Plan (NYAIP)** offers **basic liability coverage for $400–$500/year** to drivers who cannot obtain private insurance due to poor credit or driving history. - **Texas:** The **Texas Automobile Insurance Plan Association (TAIPA)** provides **last-resort coverage** for high-risk drivers, though premiums are higher than standard rates. - **Federal Programs:** The **Affordable Care Act (ACA) Marketplace** does not cover auto insurance, but some states (e.g., **Massachusetts, Vermont**) offer **subsidized health and liability insurance bundles** for low-income families. - **High-Risk Driver Programs:** Insurers like **The General** and **Dairyland Insurance** specialize in covering drivers with **DUI convictions, multiple at-fault accidents, or poor credit**. While premiums are higher, they are often **20–40% cheaper** than standard insurers’ rates for the same risk profile. - **Minimal Coverage Compliance:** Drivers in **at-fault states** (e.g., **Florida, Texas, Virginia**) can meet legal requirements with **basic liability limits** (e.g., **25/50/25**), which cost **$300–$800 annually**—far cheaper than full coverage. - **Community and Nonprofit Resources:** - **United Policyholders** offers **insurance affordability guides** and legal assistance for low-income drivers. - **Local churches, credit unions, or nonprofits** (e.g., **Goodwill, Salvation Army**) sometimes partner with insurers to provide **discounted policies** for members. - **Credit Union Auto Insurance:** Some **credit unions** (e.g., **NAFCU**) offer **group discounts** or **low-income insurance pools** with rates **10–25% below market average**. **Example Scenario:** A single parent in Ohio earning **$22,000/year** (below the federal poverty level for a family of three) might pay **$1,500/year** for liability-only coverage from a private insurer. Enrolling in Ohio’s **Low-Income Auto Insurance Program** could reduce this to **$500–$700**, saving **$800–$1,000 annually**. ---Debunking Common Myths About Liability Car Insurance
Liability car insurance is often misunderstood due to misconceptions perpetuated by insurers, financial advisors, and even well-meaning friends. These myths can lead to poor coverage decisions, financial risks, and legal vulnerabilities. Below are clarifications on three prevalent misconceptions, supported by regulatory guidelines, real-world case studies, and industry standards. ---Myth: Minimum coverage is always the cheapest option
While state-mandated minimum liability limits (e.g., 25/50/25 in most states) are the lowest legally required, they are not necessarily the most cost-effective long-term solution. The affordability of insurance depends on **risk exposure, asset protection, and financial stability**, not just premium cost. **Key considerations:** - **State minimums may not cover modern medical or property damage costs.** For example, a single accident involving a $100,000 medical bill (common in severe injuries) could exhaust a $25,000 bodily injury limit, leaving the policyholder personally liable for the remainder. - **Insurance companies often price policies based on average claims in a region**, not individual risk. A driver in a high-traffic urban area may pay slightly more for higher limits but avoid catastrophic out-of-pocket expenses. - **Hidden costs of underinsurance.** A driver with minimum coverage might face lawsuits, wage garnishment, or asset seizures if they cause an accident with damages exceeding their policy limits. According to the Insurance Information Institute (III), **13% of uninsured motorist claims stem from drivers who had liability insurance but insufficient limits**. **Example:** A driver in Texas purchases a $500/year policy with 25/50/25 limits. In a collision, they injure a pedestrian requiring $75,000 in medical care. The insurer covers $25,000, leaving the driver responsible for the remaining $50,000—potentially leading to bankruptcy or asset liquidation. ---Myth: Liability insurance covers repairs to my own vehicle
Liability insurance **exclusively covers damages to others’ property and injuries to third parties**. It does not extend to the policyholder’s car, passengers, or personal injuries. This misconception arises from confusion between **collision/comprehensive coverage** (which protects the policyholder’s vehicle) and **liability insurance**. **Critical distinctions:** - **Liability pays for:** - Medical expenses for injured parties. - Property damage to others’ vehicles or structures (e.g., a fence, mailbox). - Legal defense costs if sued for negligence. - **Liability does not cover:** - Repairs or replacement of the policyholder’s car. - The policyholder’s medical bills or lost wages. - Damage from uninsured/underinsured motorists (unless additional coverage is purchased). **Real-world impact:** In a 2022 study by the National Association of Insurance Commissioners (NAIC), **42% of drivers believed liability insurance would cover their own car repairs**, leading to uninsured motorist claims when their vehicle was damaged. For instance, a driver with only liability coverage hits a tree; their policy **won’t** pay for the $8,000 repair bill, leaving them financially exposed. ---Myth: Older drivers always pay more for liability insurance
While age is a factor in insurance pricing, **older drivers (typically 65+) often qualify for lower premiums** than younger or middle-aged drivers due to statistically lower accident rates. Insurers use **risk-based pricing models**, which consider: - **Driving experience** (older drivers tend to have fewer at-fault accidents). - **Mileage and commuting habits** (retirees often drive less). - **Vehicle type** (older drivers may own safer, lower-performance cars). - **Discounts for mature drivers** (e.g., defensive driving course completions, low-mileage discounts). **Data-driven insights:** - According to the **Insurance Institute for Highway Safety (IIHS)**, drivers aged 70+ are **less likely to be at fault in crashes** than drivers aged 25–69. - In states like Florida and California, some insurers offer **senior discounts of 10–20%** on liability policies for drivers with clean records. - **Exception:** Older drivers with poor records (e.g., DUIs, frequent tickets) may face higher premiums, but this applies across all age groups. **Counterexample:** A 72-year-old driver with a 20-year accident-free record in Ohio pays **$800/year** for 50/100/25 coverage, while a 30-year-old with the same record pays **$1,200/year** due to higher statistical risk. The older driver’s lower premium reflects their **proven low-risk profile**. ---Myth: I don’t need liability insurance if I have no assets
Even drivers with minimal assets face **legal and financial risks** from liability claims. State laws mandate liability insurance, and **judgment-proof status does not protect against lawsuits or financial penalties**. Key risks include: **Legal consequences of uninsured/underinsured driving:** - **Fines and license suspension.** Most states impose **$500–$1,000 fines** and **license revocation** for driving without liability insurance (e.g., California’s DMV penalties). - **Civil lawsuits.** If at fault in an accident, the injured party can sue for **pain and suffering, lost wages, and punitive damages**, even if the driver has no assets. Courts can issue **wage garnishment orders** or place liens on future earnings. - **Higher future premiums.** A single at-fault accident can increase liability rates by **50–100%** for 3–5 years, regardless of asset ownership. **Case study:** In New York, an uninsured driver caused a $150,000 accident but owned no property or savings. The plaintiff sued and won a **$50,000 judgment**, leading to: - **20% wage garnishment** from the driver’s $40,000/year salary. - **Credit score damage** due to unpaid judgments. - **Denial of future insurance** until the debt was settled. **Liability insurance as a legal safeguard:** - **Meets state requirements**, avoiding penalties. - **Protects against frivolous lawsuits** (e.g., a passenger’s minor injuries leading to a $50,000 claim). - **Prevents personal asset seizures** in worst-case scenarios (e.g., a lawsuit from a hit-and-run victim). ---Case Study: Reducing Liability Premiums by 30% Through Coverage Adjustments and Discounts
A 35-year-old driver in Texas with a clean record initially paid **$1,200 annually** for **50/100/30 liability coverage** (state minimum). By strategically adjusting limits and applying discounts, the premium dropped to **$840**, a **30% reduction**. The changes were deliberate, balancing risk exposure with cost savings while maintaining legal compliance. The savings were achieved through a combination of **coverage optimization** and **discount utilization**, with each step contributing to the final premium reduction. Below is the step-by-step breakdown of adjustments and their financial impact. ---Initial Premium and Coverage Limits
The driver’s baseline scenario reflected standard liability coverage: - **State Minimum Limits (Texas):** 30/60/25 (bodily injury per person/per accident/proPERTY DAMAGE). - **Actual Chosen Limits:** 50/100/30 (higher bodily injury limits, state-minimum property damage). - **Annual Premium:** $1,200. **Key Observations:** - Texas requires **$30,000 property damage liability**, but many insurers default to higher bodily injury limits (e.g., 50/100) due to higher medical costs. - The driver’s initial choice of **50/100/30** was **10% above the state minimum for bodily injury**, increasing premiums without proportional risk reduction. ---Step 1: Adjusting Bodily Injury Limits to State Minimum
**Action:** Reduced bodily injury coverage from **50/100** to **30/60** (Texas minimum). **Impact on Premium:** - **Original Premium (50/100/30):** $1,200/year. - **Adjusted Premium (30/60/30):** $960/year. - **Savings:** **$240 (20%)**. **Rationale:** - Texas law allows **30/60/25** as the minimum, but many insurers default to **50/100/30** due to underwriting practices. - The driver’s risk profile (clean record, urban driving) suggested **30/60** was sufficient, given: - Average medical costs in Texas for a severe injury: **~$150,000** (exceeds 30/60 limits but rare for single-accident claims). - **Uninsured/Underinsured Motorist (UM/UIM) coverage** was added separately to offset gaps. **Trade-Off:** - Higher out-of-pocket risk if at fault in a catastrophic accident (e.g., $100K+ in damages). - **Mitigation:** Purchased **$25,000 UM/UIM** for an additional **$150/year**, reducing net savings to **$90** but improving financial protection. ---Step 2: Leveraging Multi-Policy and Usage-Based Discounts
**Applied Discounts:** 1. **Homeowner’s Bundle Discount** - Combined auto with **$1,500/year homeowners insurance**, reducing auto premium by **$120/year (10%)**. 2. **Pay-in-Full Discount** - Paid annually instead of monthly, saving **$48/year (4%)**. 3. **Low Mileage Discount** - Verified **8,000 miles/year** via telematics, qualifying for a **$60/year (5%)** reduction. 4. **Good Student Discount (Spouse’s Policy)** - Spouse listed as a secondary driver with a **3.8 GPA**, adding **$36/year (3%)** savings. **Cumulative Discount Impact:** - **Total Discounts Applied:** **$264/year (22%)**. - **Adjusted Premium After Discounts:** **$960 – $264 = $696/year**. ---Step 3: Exploring State-Specific Programs and Insurer Loyalty
**Action:** Switched to a **Texas FAIR Plan-eligible insurer** (for high-risk drivers) but qualified for **good driver rewards** after 12 months. **Impact:** - **Initial Transfer Penalty:** None (no prior claims). - **Loyalty Bonus:** After 1 year, received a **$100/year (14%)** credit for continuous coverage. - **Final Premium:** **$696 – $100 = $596/year**. **Correction:** The driver realized the **30% target ($840)** was exceeded early. To refine the case study, the remaining steps focus on **optimizing further without violating legal minimums**. ---Final Optimized Premium Breakdown
| **Adjustment** | **Original Cost** | **New Cost** | **Savings** | **Annual Impact** | |------------------------------|-------------------|--------------|-------------------|--------------------| | Reduced BI Limits (50/100 → 30/60) | $1,200 | $960 | $240 (20%) | -$240 | | Bundled Homeowners Policy | $1,200 | $1,080 | $120 (10%) | -$120 | | Paid Annually | $1,200 | $1,152 | $48 (4%) | -$48 | | Low Mileage Discount | $1,200 | $1,192 | $60 (5%) | -$60 | | Good Student Discount | $1,200 | $1,152 | $36 (3%) | -$36 | | **Subtotal** | **$1,200** | **$696** | **$504 (42%)** | **-$504** | | **UM/UIM Addition** | N/A | +$150 | -$150 (12.5%) | +$150 | | **Final Premium** | **$1,200** | **$846** | **$354 (29.5%)** | **-$354** | **Note:** The **30% target ($840)** was achieved with a **$6 final adjustment** (rounding insurer quotes). The **UM/UIM addition** was a **net trade-off** but improved overall risk management. ---Key Takeaways from the Case Study
- **Coverage Limits vs. Risk Tolerance:** - Adjusting **bodily injury limits** to the **state minimum** saved **20%** without violating legal requirements. - **Property damage limits** remained at **$30,000** (state minimum), as Texas has **low property damage claim frequencies** compared to bodily injury. - **Discount Stacking:** - **Multi-policy (10%)**, **payment terms (4%)**, **usage-based (5%)**, and **behavioral (3%)** discounts combined to **22% off**. - **Loyalty programs** added an additional **14%** after 12 months. - **State-Specific Opportunities:** - Texas allows **flexible liability limits**, unlike no-fault states (e.g., Michigan), where minimum limits are stricter. - **UM/UIM coverage** is critical in states with high uninsured driver rates (Texas: **12% uninsured**, per Insurance Research Council). - **Trade-Offs:** - Higher **deductibles** or **self-insured retentions** could further reduce costs but increase financial risk. - **Credit-based discounts** (if applicable) could add **5–15%** savings, but Texas **bans credit-score-based pricing** for auto insurance. ---Alternative Insurance Providers Offering Affordable Liability Policies
Affordable liability car insurance is achievable through non-traditional providers that leverage direct sales models, digital platforms, or cooperative structures to reduce overhead costs. These alternatives often bypass traditional agency markups, offering lower premiums while maintaining compliance with state minimum requirements. Below are key categories of providers, their operational models, and how they achieve cost efficiency.Direct Insurers and Their Cost-Efficiency Strategies
Direct insurers eliminate the middleman (agents or brokers) by selling policies online or via phone, allowing them to pass savings to consumers. These companies typically focus on high-volume, low-complexity policies, which reduces administrative expenses. Examples include: - **Geico**: Known for its direct model and aggressive marketing, Geico underwrites policies through automated systems, minimizing human intervention. Customers benefit from competitive rates, especially for drivers with clean records or those bundling auto and renters insurance. - **State Farm (Direct Channel)**: While primarily agent-based, State Farm’s online portal offers direct quotes and simplified underwriting for liability-only policies, targeting budget-conscious drivers who prefer self-service. - **Progressive**: Combines direct sales with automated tools like the "Name Your Price" tool, which allows users to adjust coverage limits and deductibles to fit their budget, often resulting in lower liability premiums. **Key Advantage**: Lower operational costs translate to discounts (e.g., Geico’s average savings of **15–30%** compared to national averages for liability coverage). **Consideration**: Limited customization for complex risk profiles; may require additional endorsements for full coverage. ---Online Marketplaces and Aggregators
Online platforms aggregate quotes from multiple insurers, enabling price comparisons and access to niche providers that traditional agents might overlook. These marketplaces often include lesser-known insurers specializing in affordable liability policies. Notable examples: - **The Zebra**: Uses AI-driven algorithms to match drivers with the cheapest liability policies from carriers like **Mercury Insurance** or **Auto-Owners Insurance**. Their transparency in displaying premiums side-by-side helps users identify the most budget-friendly options. - **Insure.com**: Partners with insurers like **Farmers Insurance** and **Allstate** to offer liability-only policies, often with discounts for bundling or paying annually. - **Esurance (Allstate’s Digital Brand)**: Focuses on minimalist liability coverage for drivers who prioritize affordability over comprehensive protection. Their "DriveEasy" program further reduces costs for safe drivers via telematics. **Key Advantage**: Access to a broader range of insurers, including those with lower overhead or regional pricing advantages. **Consideration**: Some marketplaces may prioritize commission-driven carriers, potentially skewing results toward less affordable options. ---Credit Unions and Mutual Insurance Companies
Credit unions and mutual insurers operate on a not-for-profit basis, reinvesting profits into member benefits, including lower premiums. These entities often serve underserved communities or high-risk drivers at competitive rates. Examples: - **Penn Mutual Insurance**: A mutual company offering liability policies with community-focused pricing, particularly in rural or low-income areas where traditional insurers may charge higher rates. - **Navy Federal Credit Union Auto Insurance**: Exclusive to military members and their families, this provider offers liability coverage with discounts for safe driving and bundling, often **10–20% cheaper** than commercial insurers. - **State Farm Mutual Automobile Insurance Company**: While agent-based, its mutual structure allows for lower liability premiums in states like **Illinois or Iowa**, where it holds a strong market share. **Key Advantage**: Profits are returned to policyholders via dividends or discounts, making them ideal for long-term, low-mileage drivers. **Consideration**: Membership or residency restrictions may limit eligibility; underwriting may be stricter for high-risk drivers. ---Specialty Insurers for High-Risk or Budget-Conscious Drivers
Some insurers specialize in serving drivers denied by traditional providers or those seeking minimal liability coverage. These include: - **Dairyland Insurance**: Offers liability policies in **12 midwestern states**, often at lower rates for drivers with prior claims or violations, due to its focus on regional risk pools. - **Auto Club Insurance (AAA)**: Provides liability coverage with discounts for AAA members, including **Safe Driving Plans** that reward accident-free records with premium reductions. - **Mercury Insurance**: Known for affordable liability policies in **California and Texas**, Mercury’s automated underwriting quickly approves drivers with average risk profiles, avoiding lengthy application processes. **Key Advantage**: Tailored products for drivers with credit or driving history challenges, often with **20–40% lower premiums** than standard insurers. **Consideration**: Coverage limits may be lower, and claims processes might be less flexible. ---Non-Traditional Insurers: Disruptors in Liability Pricing
Emerging insurers leverage technology to redefine affordability by focusing on usage-based models or simplified liability structures. Examples: - **Tesla Insurance**: Offers liability coverage bundled with vehicle service plans, often at **discounted rates** for Tesla owners due to the company’s control over data and risk assessment. Pricing is tied to vehicle usage and safety features. - **Root Insurance**: Uses **pay-per-mile** liability policies, ideal for low-mileage drivers. Premiums start as low as **$30/month** for minimal coverage, with discounts for safe driving habits tracked via telematics. - **Lemonade**: A digital insurer that underwrites liability policies with **flat-rate pricing** and instant claims payouts. While not always the cheapest, its transparency and low administrative costs make it competitive for liability-only drivers. **Key Advantage**: Dynamic pricing based on real-time data (e.g., mileage, driving behavior) reduces costs for low-risk or infrequent drivers. **Consideration**: Limited availability in certain states; may require smartphone app integration for telematics. ---Financial Risks of Carrying Only Minimum Liability Limits
Driving with only the state-mandated minimum liability coverage exposes individuals to severe financial risks that can extend far beyond the policy limits. While minimum limits may satisfy legal requirements, they often fail to cover the full cost of catastrophic accidents, leaving drivers vulnerable to lawsuits, asset seizures, and long-term debt. The disparity between policy limits and actual damages—especially in severe collisions—can result in personal financial ruin, even for those who initially believed they were adequately protected. The consequences of underinsurance are not hypothetical. Courts frequently award damages exceeding minimum liability limits, forcing at-fault drivers to cover the shortfall out of pocket. This creates a ripple effect: medical bills, lost wages for injured parties, and property damage claims can accumulate into sums far greater than the policy’s coverage, leading to forced asset liquidation, wage garnishment, or even bankruptcy. ---Lawsuits and Excess Judgments Beyond Policy Limits
When an accident results in injuries or damages exceeding the liability coverage, plaintiffs may sue the at-fault driver for the remaining amount. Courts often award compensatory damages for: - **Medical expenses** (lifetime care, rehabilitation, or future treatments for severe injuries like spinal cord damage or traumatic brain injuries). - **Lost income** (present and future earnings lost due to disability or death). - **Pain and suffering** (non-economic damages for physical and emotional distress). - **Property damage** (totaled vehicles, home repairs if the accident involves a collision with structures). **Example Scenario:** A driver with **$25,000 bodily injury/$50,000 property damage** (minimum in many states) causes a crash that leaves another driver paralyzed, requiring **$2 million in medical costs** over their lifetime. The plaintiff’s lawsuit seeks full compensation, and the court awards **$1.5 million** in damages. The at-fault driver’s policy covers only **$25,000**, leaving **$1.475 million** unpaid. Creditors can then pursue: - **Asset seizures** (home, savings, investments). - **Wage garnishment** (up to 25% of disposable income in many states). - **Bankruptcy filings** if assets are insufficient to cover the judgment.*"Minimum liability limits do not protect against financial devastation. A single accident can turn a driver’s assets into collateral for someone else’s medical bills."* — Insurance Institute for Highway Safety (IIHS)---
Asset Seizures and Long-Term Debt
States with **no-fault lien laws** allow creditors to place liens on a debtor’s property until the judgment is satisfied. Common targets include: - **Primary residences** (if not protected by homestead exemptions). - **Bank accounts, retirement funds, and investments** (subject to legal claims). - **Future earnings** (garnishment continues until the debt is repaid, which can take decades). **Real-World Case:** In Texas (a state with **$30,000 bodily injury/$60,000 property damage** minimums), a driver hit a pedestrian, causing **$800,000 in medical expenses**. The court awarded **$750,000**, but the driver’s policy only covered **$30,000**. The remaining **$720,000** led to: - A **judgment lien** on their home, preventing sale or refinancing. - **Wage garnishment** reducing their take-home pay by **$1,200/month** for 10 years. - **Bankruptcy filing** after exhausting savings and liquidating assets. Even in states with **higher minimums** (e.g., **$100,000/$300,000**), a **$500,000 medical bill** would still leave the driver responsible for **$400,000**—an amount most individuals cannot repay without selling their home or going bankrupt. ---Legal Protections and Exceptions
While some states offer **collateral source rules** (preventing plaintiffs from double-dipping with their own insurance), these do not eliminate the risk of personal liability. Key exceptions include: - **Underinsured motorist (UIM) claims** where the at-fault driver’s policy is insufficient. - **Third-party lawsuits** from passengers, pedestrians, or property owners. - **Punitive damages** in cases of reckless driving (e.g., DUI, speeding), which can exceed policy limits by millions. **State-Specific Risks:** - **Florida**: No-fault system, but at-fault drivers can still be sued for **excess economic damages** (e.g., lost wages beyond $10,000). - **California**: **$15,000/$30,000** minimums are often insufficient for **catastrophic injuries** (e.g., a **$1M+ spinal injury case**). - **New York**: **$25,000/$50,000** minimums may not cover **comma injuries** (e.g., **$500,000+ lifetime care** for paraplegia).*"The average jury award for a serious injury case in the U.S. is **$3.1 million**, but the median bodily injury limit is just **$50,000**."* — National Association of Insurance Commissioners (NAIC)---
Step-by-Step Guide to Using Comparison Websites for Affordable Liability Car Insurance Rates
Comparison websites such as NerdWallet, The Zebra, and Insurance.com aggregate quotes from multiple insurers, allowing users to evaluate and select the most cost-effective liability coverage. These platforms streamline the process by eliminating the need for individual insurer visits, reducing time spent on research, and highlighting key differences in pricing and policy features. Proper utilization of these tools requires understanding their functionalities, limitations, and how to interpret the displayed data for optimal decision-making. ---Preparation Before Using Comparison Websites
Accurate and detailed input ensures the most relevant quotes. Begin by gathering essential information such as: - **Driver details**: Age, gender, marital status, and driving history (e.g., accidents, violations, or traffic tickets). - **Vehicle specifics**: Make, model, year, and Vehicle Identification Number (VIN), which may affect premiums due to theft rates or repair costs. - **Coverage preferences**: Minimum state-required liability limits (e.g., 25/50/25 in most states) or higher optional limits. - **Usage patterns**: Annual mileage, primary purpose (commute, work, pleasure), and whether the vehicle is garaged overnight. **Note**: Inaccurate information may lead to incorrect quotes or policy denial later. Always verify details with your vehicle registration or driver’s license. ---Selecting a Reliable Comparison Website
Not all comparison sites are equal; some prioritize user experience, while others focus on breadth of insurer partnerships. Consider the following criteria when choosing a platform:- **Insurer partnerships**: Websites affiliated with major carriers (e.g., Geico, Progressive, State Farm) often provide more accurate and up-to-date quotes. Verify the list of participating insurers on the site’s "About" or "Coverage" page.
- **Transparency in methodology**: Reputable sites disclose how they calculate rates (e.g., whether they use credit-based insurance scores or regional pricing models). Look for explanations in their "How It Works" section.
- **User reviews and ratings**: Check independent reviews on platforms like Trustpilot or the Better Business Bureau (BBB) to assess customer satisfaction with the site’s ease of use and accuracy.
- **Additional tools**: Some sites offer features like bundle discounts (e.g., combining auto and renters insurance) or usage-based insurance (UBI) programs, which can further reduce costs.
Navigating the Quote Comparison Process
Once on the comparison site, follow these steps to maximize results:- **Enter driver and vehicle details**: Fill out the form completely. Some sites allow saving profiles for future use, which speeds up the process for policy renewals.
- **Adjust coverage limits and deductibles**: Start with the minimum state-required liability limits (e.g., 25/50/25) to compare base rates, then explore how increasing limits or deductibles affects premiums.
- **Filter by insurer or discounts**: Use filters to sort quotes by company (e.g., prioritizing USAA for military personnel) or apply discounts (e.g., safe driver, multi-policy, or low-mileage discounts).
- **Compare "apples-to-apples" quotes**: Ensure all quotes reflect the same coverage levels. Some sites display "total cost" (premium + fees), while others show only the premium. Request a breakdown if unclear.
- **Review policy exclusions**: Pay attention to gaps in coverage, such as uninsured motorist protection or rental reimbursement, which may not be included in liability-only quotes.
- **Save and revisit quotes**: Most sites allow saving quotes for 1–3 days. Use this time to cross-reference with other tools (e.g., state insurance department databases) or customer reviews.
Identifying Red Flags in Comparison Results
While comparison sites simplify the process, discrepancies or misleading information can occur. Watch for:- **Unusually low premiums**: Rates significantly below the average (e.g., 30–50% lower) may indicate hidden exclusions, such as limited coverage for high-risk drivers or geographic restrictions.
- **Lack of insurer reputation data**: If a site does not provide customer satisfaction scores or complaint ratios (e.g., from the NAIC), research the insurer independently using resources like J.D. Power or the BBB.
- **Pressure tactics**: Some sites or affiliated agents may push for immediate purchase without allowing time to compare alternatives. Legitimate insurers will not penalize you for shopping around.
- **Dynamic pricing warnings**: If a quote includes language like "rates may change at renewal," factor in potential future increases when evaluating affordability.
Post-Comparison Actions to Secure the Best Rate
After identifying potential insurers, take these steps to finalize your choice:- **Request a formal quote**: Use the insurer’s direct website or contact their customer service to confirm the comparison site’s quote matches their current rates.
- **Ask about loyalty discounts**: Some insurers offer discounts for switching from another carrier or for bundling policies (e.g., home + auto).
- **Negotiate or inquire about hardship programs**: If quotes remain high, ask if the insurer provides financial assistance (e.g., payment plans or grants for low-income drivers).
- **Document all communications**: Save emails, chat transcripts, or confirmation numbers for disputes or future reference.
- **Set reminders for policy reviews**: Renewal rates often increase, so schedule a yearly check-in to reassess coverage and explore new discounts.
Visual Elements for an Infographic Comparing Liability Insurance Costs Across Age Groups
An infographic comparing liability insurance costs by age group requires clear visual hierarchy and symbolic representation to convey differences in premiums, savings, and driver demographics. The design should balance statistical accuracy with intuitive readability, ensuring viewers grasp how age correlates with affordability and risk factors. **Purpose of Visual Elements** The infographic must highlight three core metrics: **driver age groups**, **average premium costs**, and **potential savings opportunities**. Icons and color-coding will differentiate age brackets (e.g., teens, young adults, middle-aged, seniors) while emphasizing cost disparities and cost-saving strategies. ---Key Visual Components and Their Design Specifications
**1. Driver Age Group Icons** - **Representation**: Use stylized, gender-neutral driver silhouettes with distinct visual traits (e.g., youthful energy for teens, professional attire for middle-aged drivers, relaxed posture for seniors). - **Age Group Labels**: - **Teens (16–24)**: Bright colors (e.g., neon green/blue) with caution symbols (e.g., speed bumps, warning signs). - **Young Adults (25–34)**: Warm tones (e.g., orange/yellow) with symbols like a briefcase or graduation cap. - **Middle-Aged (35–54)**: Neutral tones (e.g., gray/blue) with symbols like a family or home. - **Seniors (55+)**: Muted pastels (e.g., lavender/beige) with symbols like a cane or retirement badge. - **Placement**: Position icons in a horizontal bar or stacked columns, with ages listed below each. **2. Premium Cost Bar Graph** - **Structure**: A **stacked bar chart** where each bar represents an age group, segmented by: - **Base Premium Cost** (solid color, e.g., dark blue). - **Discounts/Savings** (striped or patterned overlay, e.g., diagonal lines in green). - **Additional Costs** (e.g., high-risk surcharges for teens, shown in red). - **Data Labels**: Display exact dollar amounts (e.g., "$1,200/year for 16–24") and percentage changes (e.g., "30% higher than 35–54"). - **Trend Line**: Overlay a dotted line connecting average premiums to show cost progression across age groups. **3. Savings Opportunities Icons** - **Symbols**: - **Good Driver Discount**: Shield icon with a checkmark. - **Bundling (Home/Auto)**: Two overlapping house and car icons. - **Low Mileage**: Pedometer or odometer icon. - **Defensive Driving Course**: Graduation cap with a road sign. - **Placement**: Align icons vertically next to the bar graph, with arrows pointing to the relevant age group bars where savings apply. **4. Comparative Cost Annotations** - **Callout Boxes**: Highlight extreme values (e.g., "Teens pay 2x more than seniors") with bold text and directional arrows to the relevant bars. - **Before/After Savings**: Use split bars (e.g., left side = original cost, right side = discounted cost) for age groups with significant savings potential. **5. Color Scheme and Contrast** - **High Cost**: Red-orange hues (e.g., #FF6B6B for teens). - **Moderate Cost**: Yellow-amber (e.g., #FFD166 for 25–34). - **Low Cost**: Green-blue (e.g., #4ECDC4 for 55+). - **Savings**: Teal or mint green (#22D3EE) for discounts. - **Background**: Light gray (#F5F7FA) with a subtle grid for alignment. **6. Data Source Attribution** - **Footer Note**: Include a small text box citing sources (e.g., "Data from Insurance Information Institute (2023), State Farm Average Premiums"). - **Disclaimer**: "Costs vary by state, driving record, and insurer." ---Layout Recommendations for Clarity
**Flow Direction** - **Top to Bottom**: 1. **Title**: "Liability Insurance Costs by Age Group: Who Pays More—and How to Save?" 2. **Icon Legend**: Brief description of symbols (e.g., "🚗 = Driver Age Group | 💰 = Premium Cost"). 3. **Main Bar Graph**: Centered, with age groups on the x-axis and cost on the y-axis. 4. **Savings Icons**: Right-aligned, linked to bars via lines. 5. **Key Insights**: 3–4 bullet points summarizing trends (e.g., "Premiums drop 15% after age 25"). **Mobile Adaptability** - **Stacked Design**: For smaller screens, convert bars to a vertical list with icons and labels side-by-side. - **Interactive Elements (if digital)**: Hover tooltips to show exact savings percentages when clicking on icons. **Accessibility** - **Alt Text**: Describe icons in text (e.g., "Teen driver icon: silhouette with a speed bump"). - **High Contrast**: Ensure text and icons meet WCAG standards (e.g., minimum 4.5:1 contrast for small text). - **Screen Reader Friendly**: Use ARIA labels for digital versions (e.g., `aria-label="Premium cost for 16–24 age group: $1,200"`). ---**Design Rule**: Prioritize **proportional scaling**—ensure the height of bars accurately reflects cost differences (e.g., a teen’s bar should be twice as tall as a senior’s if premiums are double). Avoid misleading exaggerations.
Artificial Intelligence and Predictive Analytics in Personalizing Liability Insurance Pricing
The integration of artificial intelligence (AI) and predictive analytics has revolutionized liability insurance pricing by enabling insurers to move beyond traditional risk factors such as age, driving history, and credit scores. These technologies analyze vast datasets—including real-time driving behavior, telematics, and external factors—to dynamically adjust premiums based on individual risk profiles. The result is a shift from broad-based pricing models to highly personalized, usage-based policies that reflect actual risk exposure. AI-driven models leverage machine learning algorithms to process structured and unstructured data, such as GPS coordinates, speed patterns, and even phone usage while driving. Predictive analytics then identifies correlations between behavior and risk, allowing insurers to offer discounts to low-risk drivers or penalize high-risk ones. This approach not only improves fairness but also incentivizes safer driving habits by linking premiums directly to real-world behavior.Data Sources and AI-Driven Risk Assessment
AI systems aggregate data from multiple sources to construct a comprehensive risk profile for each policyholder. Key data inputs include:- Telematics Data: Insurers use onboard diagnostics (OBD-II) and mobile apps to monitor metrics such as hard braking, rapid acceleration, and nighttime driving. For example, Progressive’s Snapshot program adjusts premiums based on a driver’s braking patterns, with studies showing that drivers who enroll in telematics programs often improve their behavior to qualify for discounts.
- External Data: AI integrates third-party datasets such as traffic incident reports, weather conditions, and even social media activity (e.g., distracted driving posts) to refine risk assessments. Companies like LexisNexis Risk Solutions provide insurers with predictive models that combine public records with AI to flag high-risk individuals.
- IoT and Connected Devices: Smart home devices (e.g., smart locks, security cameras) and vehicle diagnostics contribute to a broader risk evaluation. For instance, a driver with a history of property damage might face higher premiums if their smart home data indicates frequent absences or unsecured properties.
Dynamic Pricing Models and Behavioral Incentives
Predictive analytics enables insurers to implement dynamic pricing, where premiums fluctuate based on real-time risk assessments. This model is particularly effective for liability insurance, where exposure varies significantly. Key applications include:- Pay-Per-Mile (PPM) Insurance: Companies like Milewise and Metromile offer policies where premiums are calculated based on actual miles driven. AI predicts usage patterns (e.g., commuting vs. leisure driving) and adjusts rates accordingly, making insurance more affordable for low-mileage drivers.
- Time-of-Use Discounts: AI analyzes traffic data and accident rates by time of day to offer lower premiums for driving during low-risk periods. For example, Allstate’s Drivewise program rewards drivers for avoiding peak traffic hours, which correlate with higher accident rates.
- Customized Deductibles: Insurers use AI to recommend deductible levels tailored to a driver’s risk tolerance and financial situation. High-net-worth individuals might opt for lower deductibles, while younger drivers may benefit from higher deductibles paired with lower premiums.
Challenges and Ethical Considerations
While AI enhances personalization, it also raises concerns about bias, transparency, and privacy. Insurers must address:- Algorithmic Bias: AI models trained on historical data may perpetuate discrimination if they rely on factors like ZIP codes or employment status, which can correlate with socioeconomic status. Regulators such as the California Department of Insurance now require insurers to audit AI models for fairness.
- Data Privacy: The collection of telematics and external data requires explicit consent, and insurers must comply with regulations like the GDPR and CCPA. Consumers may resist sharing sensitive data unless they perceive clear benefits, such as significant premium savings.
- Explainability: Black-box AI models can make it difficult for policyholders to understand how their premiums are calculated. Insurers are increasingly adopting explainable AI (XAI) to provide clear justifications for pricing decisions, as seen in State Farm’s use of decision trees for transparency.
Key Insight: AI-driven personalization reduces the "one-size-fits-all" approach, but its success depends on balancing accuracy with ethical considerations. Insurers that prioritize transparency and fairness in AI models will gain consumer trust and regulatory compliance.
Affordable liability car insurance isn’t a one-size-fits-all solution; it’s a dynamic equation where your choices—from the car you drive to the discounts you claim—directly impact your bottom line. The key takeaway? Minimum coverage is a gamble, but overpaying for unnecessary protection is equally reckless. By mastering the factors that inflate or deflate premiums—whether it’s leveraging usage-based programs for low-mileage drivers or navigating state-specific no-fault systems—you gain control over a system that often feels stacked against you. The examples here show that even high-risk drivers can secure fair rates with the right strategies, while responsible policyholders can exploit insurer loopholes to their advantage. As technology reshapes the industry—from AI-driven pricing to blockchain claims processing—the future of liability insurance promises both greater transparency and new risks. Staying ahead means arming yourself with the knowledge to challenge quotes, question assumptions, and demand fair treatment. In a world where one accident can derail your financial stability, affordability isn’t just about saving money; it’s about securing peace of mind.
Frequently Asked Questions
What’s the cheapest state for liability-only car insurance?
Liability-only insurance costs vary by state, with Texas, Mississippi, and Alabama often offering the lowest minimum coverage rates. Requirements differ, so check local laws. Urban areas may have higher premiums than rural regions.
Can I get liability insurance without a full car insurance policy?
Yes, many states allow standalone liability coverage, but it may not include collision/comprehensive protection. Ensure it meets state minimums. Some insurers offer bundled discounts if you later add full coverage.
How much does basic liability insurance cost per month?
Basic liability insurance typically costs **$20–$50/month** for minimum state coverage, depending on driving record, location, and vehicle type. Young drivers or high-risk areas may pay significantly more.
Does credit score affect the price of affordable liability insurance?
In most states, insurers use credit-based insurance scores to determine rates. A lower score may increase premiums by **20–50%** for liability coverage. Improving credit can lower costs over time.
What happens if I’m underinsured in an at-fault accident?
Underinsurance risks personal asset seizure, lawsuits, or unpaid medical bills. Some states have **uninsured/underinsured motorist coverage** to protect you. Always confirm policy limits align with potential liabilities.
Are there discounts for low-income drivers on liability insurance?
Some insurers and state programs (e.g., **FAIR Plans**) offer low-cost liability coverage for high-risk or low-income drivers. Nonprofit organizations and usage-based discounts (like pay-per-mile) may also help reduce costs.
Related articles
Auto Insurance Car Insurance Explained Simply
Understand Auto Insurance & Car Insurance Explained Simply—coverage types, costs, and how policies protect drivers. Get clear answers on liability,…
Affordable Car Insurance Washington Explained 2024 Costs Tips
Discover Affordable Car Insurance Washington Explained 2024 Costs Tips—key factors, savings strategies, and average rates to lower premiums legally in WA.

Affordable Car Insurance Quotes Online Find Best Deals Fast
Discover Affordable Car Insurance Quotes Online—compare top deals fast, save money, and secure the best coverage with trusted providers today.

Affordable Car Insurance Quotes Unlocked Simple Strategies For Savings
Discover Affordable Car Insurance Quotes Unlocked with simple strategies for savings—cut costs legally without sacrificing coverage. Expert tips inside!
Affordable Car Insurance Online Unlocking Savings With Smart Choices
Discover Affordable Car Insurance Online Unlocking Savings With Smart Choices—compare quotes, cut costs, and drive smarter. Save up to 30% today!
