Allstate Car Home Insurance Quote Explained Fully
Table of Contents
- Core Features of Allstate’s Car Insurance Policies
- Factors Influencing Allstate Car Insurance Quotes and Their Impact on Premiums
- Popular Add-Ons for Allstate Car Insurance and Their Cost Implications
- Allstate’s Claims Filing Process for Car Accidents: Documentation, Steps, and Resolution Timelines
- Comparison of Allstate’s Car Insurance Pricing, Coverage, and Competitor Performance Against State Farm, Geico, and Progressive
- Allstate’s Telematics Programs: Personalized Insurance Through Data-Driven Policies
- Key Customer Segments for Allstate Car Insurance and Tailored Coverage Recommendations
- Allstate’s Safety Programs for Car Insurance: Defensive Driving, Vehicle Maintenance, and Anti-Theft Discounts
- Allstate’s Compliance with State-Specific Insurance Regulations for Car and Home Policies
- Allstate’s Customer Support Channels and Response Time Benchmarks
Navigating the complexities of car and home insurance can feel overwhelming, but Allstate’s tailored policies simplify the process with transparent options and customizable coverage. Whether you’re seeking protection for your vehicle, home, or both, understanding how Allstate’s quote system works—from pricing factors to add-ons—can help you secure the right plan without overpaying. This guide breaks down the core features, hidden discounts, and smart strategies to maximize savings while ensuring comprehensive protection for your assets.
Allstate stands out as a leader in the insurance industry by blending traditional policy structures with cutting-edge technology, such as usage-based programs that reward safe driving or home upgrades. From bundling car and home policies to leveraging AI-driven tools for claims, the company’s approach prioritizes both affordability and reliability. By analyzing real-world examples—like how a family reduced premiums by 20% through safety programs—this breakdown reveals actionable insights for every type of policyholder, from young drivers to luxury homeowners.
Core Features of Allstate’s Car Insurance Policies
Allstate’s car insurance policies are designed to provide financial protection against accidents, theft, and other unforeseen events while offering flexibility through customizable coverage options. The foundation of these policies lies in **collision, comprehensive, and liability coverage**, with additional optional add-ons to enhance protection. Below is a detailed breakdown of the standard and customizable features available to policyholders. ---Standard Coverage Types
Allstate’s car insurance policies include three primary coverage categories, each addressing distinct risks: - **Collision Coverage** This protects against damage to the policyholder’s vehicle resulting from a collision with another vehicle or object, such as a guardrail or tree. It covers repair or replacement costs **minus the deductible**, regardless of fault. For example, if a driver rear-ends another car, collision coverage would help pay for repairs to their own vehicle. - **Comprehensive Coverage** Comprehensive coverage addresses non-collision-related damage, including theft, vandalism, fire, hail, or hitting an animal. It also covers **falling objects** (e.g., a tree branch damaging the windshield) and **glass damage**. Unlike collision coverage, it applies even if the incident is not the policyholder’s fault. - **Liability Coverage** Mandatory in most states, liability coverage pays for **bodily injury and property damage** caused to others in an at-fault accident. Allstate offers **split limits** (e.g., 100/300/50), where: - **100** = $100,000 per person for bodily injury. - **300** = $300,000 per accident for bodily injury. - **50** = $50,000 for property damage. Policyholders can opt for higher limits (e.g., 250/500/100) to better protect assets in lawsuits.**Note:** Minimum state requirements vary; Allstate recommends higher liability limits (e.g., 250/500/100) to align with personal asset protection needs.---
Optional Add-Ons for Enhanced Protection
Policyholders can tailor their coverage with optional add-ons to address specific needs, such as roadside emergencies or temporary transportation: - **Roadside Assistance** Provides 24/7 support for services like **towing, flat tire changes, lockout assistance, and fuel delivery**. Some plans include **jump-starts** or **battery replacement**. Allstate’s standard plan covers up to **4 calls per year**, while premium plans may offer unlimited service. - **Rental Reimbursement** Covers the cost of a rental car while the insured vehicle is being repaired due to a covered claim. Coverage limits typically range from **$20 to $100 per day** and **$600 to $3,000 per year**, depending on the plan. Higher limits are available for frequent travelers or those with long commutes. - **Accident Forgiveness** Prevents a single at-fault accident from increasing premiums for **3 to 5 years**, depending on the state. This feature is particularly valuable for new drivers or those with minor violations. - **New Car Replacement** Replaces a **totaled vehicle** with a **new model of similar value** within the first **2 years** of ownership (varies by state). This eliminates the depreciation gap when replacing a car after an accident. - **Umbrella Insurance Integration** Extends liability coverage beyond standard auto and home policies, providing an additional **$1 million to $5 million** in protection for catastrophic claims (e.g., lawsuits exceeding policy limits). ---Deductible and Premium Flexibility
Allstate allows policyholders to adjust deductibles to balance premium costs and out-of-pocket expenses. Common deductible tiers include: - **$250, $500, $1,000, or $2,500** for collision/comprehensive coverage. - Higher deductibles **lower premiums** but increase immediate costs after a claim. For example, a $500 deductible may reduce annual premiums by **10–20%** compared to a $250 deductible.**Example:** A policyholder with a $1,000 deductible might pay **$1,200 annually** for full coverage, while raising it to $2,500 could drop the premium to **$900/year**, saving $300 annually but requiring higher upfront payments after a claim.Policyholders can also explore **pay-per-mile** or **usage-based** programs (e.g., **Allstate Drivewise**) to customize premiums based on driving habits, such as mileage or safe driving behaviors.
Factors Influencing Allstate Car Insurance Quotes and Their Impact on Premiums
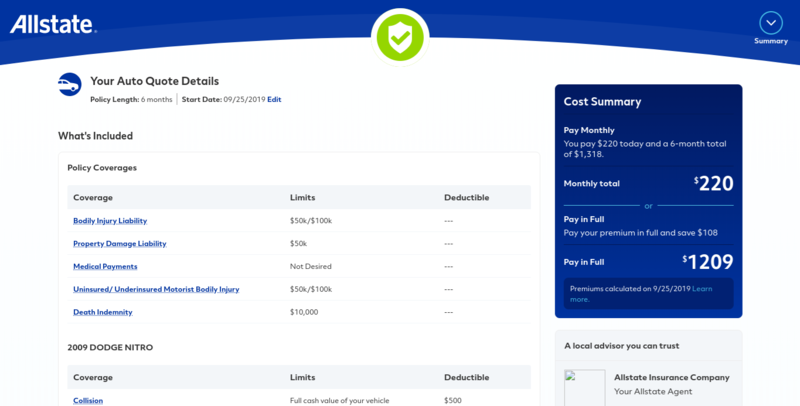
Allstate car insurance premiums are determined by a combination of risk factors that assess the likelihood of a claim. These variables are categorized into driver-specific, vehicle-specific, and external factors, each contributing differently to the final quote. Understanding how these elements interact allows policyholders to anticipate adjustments in pricing and strategize for cost savings. The calculation of car insurance premiums follows an actuarial model where insurers evaluate statistical probabilities of accidents, theft, or liability claims. Allstate’s proprietary algorithms weigh these factors differently based on regional trends, claim histories, and underwriting policies. Below are the primary categories of influence, ranked by their typical impact on premiums. ---Driver History and Personal Profile
Allstate assigns risk scores based on a driver’s historical behavior, which directly correlates with claim frequency. The most significant contributors include: - **Driving Record**: Violations such as speeding tickets, DUIs, or at-fault accidents increase premiums by **20–50%** or more, depending on severity. A single DUI can elevate rates by **30–100%** for 3–5 years, while repeated offenses compound the penalty. Allstate’s "Safe Driving Bonus" rewards accident-free records with discounts of **5–25%** after 3–5 years. - *Example*: A driver with a clean record in Texas may pay **$1,200/year** for full coverage, while a peer with two at-fault accidents in the past 24 months could see premiums rise to **$2,100/year** (a **75%** increase). - **Age and Gender**: Younger drivers (under 25) and males under 25 face higher premiums due to higher accident rates. Teen males pay **up to 300% more** than middle-aged females. Allstate offers **Good Student Discounts (25% off)** for drivers under 25 with a GPA of 3.0 or higher. - *Data Source*: Allstate’s 2023 rate comparison shows a 20-year-old male pays **$4,500/year** for full coverage, while a 50-year-old female pays **$1,400/year** in the same state. - **Credit Score**: In most states, Allstate uses credit-based insurance scores (a separate metric from FICO) to assess financial responsibility. A low score (below 570) can increase premiums by **20–50%**, while a high score (above 720) may qualify for discounts of **5–15%**. - *Note*: States like California, Massachusetts, and Hawaii prohibit credit score use in car insurance pricing. - **Marital Status**: Married drivers often receive a **5–10% discount** due to statistical correlations with lower risk-taking behavior. Allstate’s "Married Driver Discount" applies automatically in most states. ---Vehicle Model, Age, and Safety Features
The type of vehicle insured is one of the most impactful factors, as it influences repair costs, theft risk, and accident severity. Allstate categorizes vehicles into risk tiers based on: - **Make and Model**: Luxury or high-performance cars (e.g., Porsche 911, BMW M Series) incur **20–40% higher premiums** due to expensive repairs and higher theft rates. Conversely, affordable sedans (e.g., Honda Civic, Toyota Camry) qualify for **10–25% discounts** on collision/comprehensive coverage. - *Example*: Insuring a **2023 Tesla Model 3** in California costs **$2,800/year** for full coverage, while a **2020 Honda Accord** costs **$1,500/year** (a **46%** difference). - **Vehicle Age**: Newer cars (under 3 years old) often have higher premiums due to full replacement value coverage, while older vehicles (over 10 years) may see reduced collision coverage costs. Allstate’s "New Car Replacement" option adds **5–15%** to premiums for vehicles under 2 years old. - **Safety and Anti-Theft Features**: Cars equipped with advanced safety tech (e.g., automatic braking, lane-keeping) or anti-theft systems (e.g., OnStar, LoJack) qualify for discounts of **5–20%**. Allstate’s "Drivewise" program offers **up to 30% off** for policyholders who agree to usage-based tracking. - **Engine Size and Horsepower**: Vehicles with high horsepower (e.g., Ford Mustang GT, Dodge Challenger) face **15–30% higher premiums** due to increased accident risk. Allstate’s "Performance Vehicle Surcharge" applies in states with high claim rates for these models. ---Location and Environmental Risks
Geographic factors account for **20–40%** of premium variations, as urban areas, crime rates, and weather conditions directly affect claim frequencies. Allstate evaluates: - **State and City**: Urban areas (e.g., Los Angeles, New York) have **30–50% higher premiums** due to traffic congestion and higher theft rates. Rural areas may see lower rates but higher deductibles for weather-related claims (e.g., hail, flooding). - *Example*: Full coverage in **Miami** averages **$3,200/year** (high hurricane risk), while **Des Moines, Iowa**, averages **$1,800/year**. - **Garaging Address**: If the vehicle is parked in a high-crime neighborhood, Allstate may apply a **10–25% surcharge**. Conversely, garaging in a low-risk area can yield a **5% discount**. - **Commute Distance**: Long commutes (over 30 miles daily) increase premiums by **10–20%** due to higher exposure to accidents. Allstate’s "Commuter Discount" applies if the primary driver commutes less than 15 miles/day. - **Weather and Natural Disasters**: States prone to hurricanes (Florida), wildfires (California), or tornadoes (Missouri) see **20–40% higher premiums** for comprehensive coverage. Allstate offers **disaster mitigation discounts** for homes/vehicles with reinforced structures or flood-resistant features. ---Coverage Limits and Deductibles
Policyholders’ chosen coverage levels and deductibles are the most controllable factors affecting premiums. Allstate structures quotes based on: - **Liability Limits**: Minimum state-required limits (e.g., 25/50/25 in most states) are the cheapest but offer limited protection. Increasing limits to **100/300/100** adds **15–30%** to premiums but reduces out-of-pocket risk in lawsuits. - *Example*: A driver in Texas with **25/50/25** pays **$900/year**, while **100/300/100** costs **$1,500/year** (a **67%** increase). - **Collision and Comprehensive Coverage**: Optional coverages add **$500–$1,500/year** depending on vehicle value. Allstate’s "Agreed Value" option (for classic cars) increases premiums by **10–20%** but ensures full payout for total losses. - **Deductible Amount**: Higher deductibles (e.g., $1,000 vs. $500) lower premiums by **15–30%**. Allstate’s "Pay-Per-Mile" deductible option allows policyholders to choose deductibles based on annual mileage. - **Additional Coverages**: Options like **roadside assistance ($5–$20/month)**, **rental reimbursement ($10–$30/month)**, or **new car replacement ($100–$300/year)** incrementally raise premiums but provide specific benefits. ---Popular Add-Ons for Allstate Car Insurance and Their Cost Implications
Allstate offers a range of optional add-ons to enhance standard car insurance policies, allowing drivers to tailor coverage to their needs. These add-ons address specific risks or provide additional protections beyond basic liability and collision/comprehensive coverage. The cost of these add-ons varies based on factors such as location, vehicle type, and driving history, but they typically range from **$5 to $50 per month** or a one-time premium. Below are the most sought-after options, including their descriptions and approximate cost ranges.Accident Forgiveness
This add-on prevents a single at-fault accident from negatively impacting a driver’s claims history, which can help maintain lower premiums. It is particularly valuable for drivers with clean records who want to avoid rate increases after an accident. The cost is generally **$25–$50 per year** or **$2–$4 per month**, depending on the state and insurer policies.New Car Replacement
If a totaled vehicle is less than two years old (or within a specified mileage limit), this coverage ensures the insurer pays for a replacement of similar value, rather than the depreciated amount. Ideal for drivers with newer or high-value cars, the cost typically ranges from **$15–$40 per month** or **$180–$480 annually**.Rental Reimbursement
Covers the cost of a rental car while the insured vehicle is being repaired after a covered claim. Limits range from **$20 to $100 per day** with a maximum of **$600–$1,200 per claim**. The add-on costs **$10–$30 per year** or **$1–$3 per month**.Roadside Assistance
Provides 24/7 support for services like towing, flat tires, lockout assistance, and fuel delivery. Basic plans cost **$10–$25 per year**, while premium plans with additional perks (e.g., trip interruption coverage) may reach **$30–$50 annually**.Gap Insurance
Covers the difference between a vehicle’s actual cash value and the remaining loan balance if it’s totaled, preventing the insured from owing more than the car is worth. Critical for leased or financed vehicles, the cost is usually **$15–$30 per year** or **$1.25–$2.50 per month**.Custom Equipment Coverage
Extends protection to aftermarket modifications (e.g., stereo systems, rims, or performance upgrades) not covered by standard policies. The cost depends on the value of the equipment, typically **$5–$20 per month** or **$60–$240 annually**.Umbrella Insurance Integration
Links to an Allstate umbrella policy to provide excess liability coverage for at-fault accidents beyond standard auto limits (e.g., $1 million or more). While not a standalone add-on, it may reduce out-of-pocket costs for high-severity claims. Umbrella policies start at **$250–$500 per year**.**Note:** Costs are approximate and vary by policy, location, and underwriting. Always review the policy declaration page for exact terms.

Allstate’s Claims Filing Process for Car Accidents: Documentation, Steps, and Resolution Timelines
Filing a car insurance claim after an accident involves a structured process to ensure smooth handling by Allstate. Understanding the required documentation, procedural steps, and typical resolution timelines helps minimize delays and ensures a fair payout. Allstate emphasizes transparency, providing clear guidelines for claimants to follow while leveraging digital tools to streamline the experience. The claims process begins immediately after an accident and involves multiple stages, from initial reporting to final settlement. Allstate’s approach prioritizes safety, evidence collection, and efficient communication to resolve claims within industry-standard timelines. Below are the key components of the process, including documentation requirements and expected durations for resolution. ---Initial Steps After an Accident
Before contacting Allstate, claimants must prioritize safety and gather essential information. This includes: - **Ensuring safety**: Move vehicles to a secure location if possible, turn on hazard lights, and assist injured parties if safe to do so. - **Exchanging information**: Collect the other driver’s name, contact details, license plate number, and insurance information. - **Documenting the scene**: Use a smartphone to capture photos or videos of vehicle damage, road conditions, and any visible injuries. Note the time, date, and location of the accident. - **Reporting to authorities**: If the accident results in injuries, fatalities, or significant property damage (typically exceeding $1,000), a police report is mandatory in most states. Allstate recommends filing a report even for minor incidents to protect against disputes. ---Required Documentation for Filing a Car Insurance Claim
Allstate requires specific documentation to process a claim accurately and fairly. Submitting these materials upfront accelerates the review process. The following are critical documents: - **Police report**: A copy of the official accident report, which serves as an objective record of the incident. Police reports often include details such as fault determination, witness statements, and environmental factors. - **Photos and videos**: Clear images of vehicle damage from multiple angles, as well as close-ups of license plates, skid marks, and traffic signs. Videos can provide context not captured in still images. - **Witness statements**: Names and contact information of any witnesses, along with their written or verbal accounts of the incident. Witnesses can corroborate the claimant’s version of events. - **Medical records**: If injuries are involved, claimants should submit medical reports, bills, and receipts for treatment. Allstate covers medical payments (MedPay) or personal injury protection (PIP) as part of the claim. - **Repair estimates**: For property damage claims, obtain written estimates from licensed auto repair shops. Allstate may direct claimants to its preferred repair network, **Allstate Preferred Providers**, for expedited service. - **Vehicle inspection reports**: If Allstate requires an assessment, a claims adjuster may inspect the vehicle. Alternatively, digital tools like **Allstate’s Mobile App** allow claimants to upload photos for preliminary review. ---Filing the Claim with Allstate
Claimants can file a car insurance claim through multiple channels, including: - **Mobile App**: The **Allstate Mobile App** offers a seamless way to file claims 24/7. Users can submit photos, provide accident details, and track the claim’s status in real time. - **Phone**: Allstate’s claims hotline (1-800-ALLSTATE or 1-800-255-7828) connects claimants with a representative who guides them through the process. - **Agent or Local Office**: For complex claims, claimants can visit a local Allstate agent or office to file in person. This option is useful for those who prefer face-to-face assistance. Once filed, Allstate assigns a claims adjuster to evaluate the claim. The adjuster reviews documentation, assesses damages, and determines liability. Claimants receive updates throughout the process via email, app notifications, or phone calls. ---Timeline for Claim Resolution
Allstate aims to resolve claims efficiently, though timelines vary based on complexity, documentation completeness, and external factors. Below are typical durations for each stage: | **Stage** | **Estimated Timeline** | **Factors Affecting Duration** | |--------------------------------|-----------------------------|--------------------------------------------------------| | **Initial Reporting** | Instant to 24 hours | Time taken to file claim and submit documentation. | | **Adjuster Assignment** | 1–3 business days | Claim volume and adjuster availability. | | **Damage Assessment** | 3–10 business days | Need for vehicle inspection or repair estimates. | | **Liability Determination** | 5–14 business days | Disputes between parties or pending police reports. | | **Approval and Payout** | 7–30 business days | Complexity of repairs, third-party involvement. | | **Total Resolution** | 14–45 business days | Ranges from simple claims to those requiring litigation.| For **straightforward claims** (e.g., minor fender benders with clear liability), resolution may occur within **2–3 weeks**. **Disputed claims** or those involving **bodily injury** can extend beyond **60 days**, especially if legal proceedings are required. ---Accelerating the Claims Process
Claimants can reduce processing times by: - **Submitting documentation promptly**: Delays in providing photos, police reports, or medical records prolong the review. - **Cooperating with adjusters**: Responding to adjuster requests within **48 hours** ensures timely progress. - **Choosing Allstate’s repair network**: Vehicles repaired through **Allstate Preferred Providers** often see faster turnaround times. - **Using digital tools**: Leveraging the **Allstate Mobile App** for real-time updates and document submission streamlines communication. ---Handling Disputes or Delays
If a claim is denied or delayed without explanation, claimants should: - **Request a detailed reason**: Allstate provides written explanations for denials or delays. Common causes include missing documentation or disputes over liability. - **Appeal the decision**: Claimants can submit additional evidence or request a review by a senior adjuster or ombudsman. - **Escalate to legal channels**: For unresolved disputes, consulting an attorney or filing a complaint with state insurance regulators may be necessary. Allstate’s **Customer Advocate Team** assists with unresolved issues, offering mediation or further investigation. ---Comparison of Allstate’s Car Insurance Pricing, Coverage, and Competitor Performance Against State Farm, Geico, and Progressive
Allstate’s car insurance offerings are shaped by a balance of competitive pricing, extensive coverage options, and customer-centric features. To provide context, this comparison evaluates average premiums, coverage limits, customer satisfaction scores, and key differentiators across Allstate, State Farm, Geico, and Progressive—four of the largest insurers in the U.S. The analysis highlights where Allstate excels, where it lags, and how its positioning aligns with consumer needs. Data sources for this comparison include industry reports (J.D. Power, Insurance Information Institute), 2023 NAIC (National Association of Insurance Commissioners) filings, and third-party customer reviews (Trustpilot, Consumer Affairs). Average premiums reflect national averages for full-coverage policies (liability, collision, comprehensive) for a 40-year-old driver with a clean record and a 2020 midsize sedan. Coverage limits are based on standard state minimums and optional add-ons. ---Average Premiums and Financial Strength Ratings
**Note:** Premiums vary significantly by location, driving history, and vehicle type. The table below reflects national averages for a policyholder with moderate risk.
| Metric | Allstate | State Farm | Geico | Progressive |
|---|---|---|---|---|
| Average Annual Premium (Full Coverage) | $1,650 | $1,620 | $1,550 | $1,750 |
| Average Liability-Only Premium | $550 | $530 | $480 | $600 |
| Financial Strength Rating (A.M. Best) | A+ (Superior) | A++ (Superior) | A++ (Superior) | A (Excellent) |
| Discounts Offered (Max Potential Savings) |
|
|
|
|
Coverage Limits and Optional Add-Ons
Coverage limits and add-ons define the risk protection provided by each insurer. Below is a comparison of standard and optional coverages, including unique offerings like **Allstate’s "Accident Forgiveness"** and **Progressive’s "Rental Reimbursement."**| Coverage Type | Allstate | State Farm | Geico | Progressive |
|---|---|---|---|---|
| Liability Limits (State Minimum) | $25,000/$50,000/$25,000 (varies by state) | $25,000/$50,000/$25,000 (varies by state) | $25,000/$50,000/$25,000 (varies by state) | $25,000/$50,000/$25,000 (varies by state) |
| Collision/Deductible (Standard) | $500 | $500 | $300 | $500 |
| Comprehensive/Deductible (Standard) | $500 | $100 | $100 | $500 |
| Uninsured Motorist Coverage (UM/UIM) | Up to policy liability limits | Up to policy liability limits | Up to $250,000 (optional) | Up to $250,000 (optional) |
| Rental Car Reimbursement | $20–$50/day (optional) | $20–$50/day (optional) | $20–$40/day (optional) | $30–$100/day (optional, higher limits available) |
| Roadside Assistance | Included with policy (24/7) | Included with policy (24/7) | Optional ($10–$20/year) | Optional ($7–$15/year) |
| Unique Add-Ons |
|
|
|
|
Customer Satisfaction and Claims Experience
Customer reviews and claims satisfaction scores (J.D. Power 2023) reveal strengths and weaknesses in each insurer’s service quality. Allstate’s customer experience is bolstered by its **local agent network** and **24/7 claims support**, but it trails Geico in overall satisfaction due to higher premiums.| Metric | Allstate | State Farm | Geico | Progressive | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| J.D. Power 2023 U.S. Auto Claims Satisfaction (1,000-point scale) | 841 | 856 | 863 | 829 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Average Claim Settlement Time (Days) | 28 | 25 | 22 | 30 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Customer Review Rating (Trustpilot, 2023) | 3.8/5 | 3.9/5 | 4.2/5 | Allstate’s Telematics Programs: Personalized Insurance Through Data-Driven Policies Allstate’s telematics initiatives, **Drivewise for auto insurance** and **Homewise for home insurance**, represent a paradigm shift in how insurers use real-time data to tailor coverage, pricing, and risk management. By leveraging connected devices and behavioral analytics, Allstate transforms generic policies into dynamic, customer-centric solutions. These programs collect, analyze, and apply data to reward safe behaviors, optimize premiums, and enhance preventive measures—ultimately fostering a proactive insurance ecosystem. The core of Allstate’s telematics strategy lies in **voluntary data sharing**, where policyholders opt into programs that monitor driving habits (for cars) or home activity (for residences). Data is anonymized, aggregated, and used to identify trends rather than individual risks, ensuring privacy compliance while enabling personalized rewards. ---
| Metric | Pros | Cons | Response Time Benchmark |
|---|---|---|---|
| Human Interaction | Immediate, personalized assistance; ideal for urgent or emotionally sensitive issues (e.g., accidents, medical emergencies). | Wait times can exceed 30 minutes during peak hours (e.g., weekends, holidays). | Average hold time: 5–15 minutes (varies by call volume). Critical claims escalated to specialists within 24 hours. |
| Accessibility | No internet or app required; accessible to all demographics, including seniors. | Language barriers may require transfer to specialized agents (e.g., Spanish-speaking support available but with longer wait times). | Multilingual support: 24/7 for Spanish; limited hours for other languages (e.g., ASL interpreters by appointment). |
| Complexity Handling | Agents can resolve disputes, adjust coverage, or connect customers to legal/financial advisors. | Policy jargon may overwhelm non-technical users; requires patience for detailed explanations. | Escalation to senior agents for complex claims: <1 hour for priority cases. |
Live Chat Support
Available via the Allstate website and mobile app, live chat is designed for quick policy-related queries, such as billing, coverage details, or claim status updates. Chat agents can also initiate calls if needed.| Metric | Pros | Cons | Response Time Benchmark |
|---|---|---|---|
| Speed | Faster than phone for routine inquiries; average response time of 1–2 minutes. | Limited to text-based interaction; complex issues may require phone escalation. | Instant replies for simple queries; complex issues routed to phone within 5 minutes. |
| Convenience | No hold music; multitasking-friendly (e.g., checking emails while chatting). | Requires digital literacy; not suitable for customers without internet access. | 24/7 availability on mobile app; website chat hours: 8 AM–11 PM ET (Mon–Fri), 9 AM–7 PM ET (Sat–Sun). |
| Documentation | Chat transcripts saved for reference; agents can share links to policies or FAQs. | No audio/visual aids for claims involving physical damage (e.g., photos require separate upload). | Policy documents shared via chat within 1–2 minutes; claim photos processed in <10 minutes. |
Email Support
Best suited for non-urgent inquiries, such as general policy questions, feedback, or documentation requests. Email support is processed in batches during business hours.| Metric | Pros | Cons | Response Time Benchmark |
|---|---|---|---|
| Thoroughness | Allows detailed explanations; ideal for complex or sensitive topics (e.g., legal disputes). | Slowest channel; not suitable for urgent issues. | Initial acknowledgment: <24 hours; full response: 1–3 business days. |
| Record-Keeping | Email threads serve as audit trails for future reference. | Risk of miscommunication without follow-up calls. | Escalation to phone/chat if unresolved after 3 business days. |
| Accessibility | No time constraints; customers can draft responses at their convenience. | Requires email access; may not be accessible for all users (e.g., those without email accounts). | Business hours: 8 AM–10 PM ET (Mon–Fri), 9 AM–6 PM ET (Sat–Sun). |
Social Media Support
Allstate monitors Twitter, Facebook, and Instagram for customer inquiries, particularly for viral issues (e.g., weather-related claims, policy changes). Responses are public, which can deter private discussions.| Metric | Pros | Cons | Response Time Benchmark |
|---|---|---|---|
| Visibility | Public responses can resolve issues for multiple customers simultaneously (e.g., outage notifications). | Lack of privacy; sensitive issues may be avoided. | Initial reply: <1 hour for urgent tweets; 24–48 hours for non-urgent posts. |
| Engagement | Faster for trending topics; demonstrates transparency. | Limited to 280-character responses; complex issues require redirects to email/phone. | Escalation to DMs for private follow-ups; phone callback offered within 24 hours. |
| Community Trust | Builds brand loyalty by showcasing responsiveness during crises (e.g., hurricanes, pandemics). | Negative public replies can harm reputation if not handled carefully. | Peak crisis response: <30 minutes for verified accounts. |
Choosing the right insurance doesn’t have to be a guessing game. Allstate’s combination of flexible coverage, innovative tools, and customer-focused services empowers you to make informed decisions tailored to your lifestyle and risks. Whether you’re comparing standard vs. premium plans, exploring add-ons like accident forgiveness, or optimizing discounts through smart home devices, this guide equips you with the knowledge to navigate Allstate’s offerings confidently. The key to securing the best quote lies in understanding your unique needs, leveraging available resources, and taking proactive steps—like bundling policies or participating in safety programs—to keep costs low while maximizing protection.

Frequently Asked Questions
How do I get an accurate Allstate car insurance quote online?
Allstate’s quote tool requires basic vehicle and driver details. Enter your ZIP code, car make/model, annual mileage, and driving history. Compare quotes instantly for coverage levels like liability, collision, or comprehensive. Adjust deductibles and add-ons to refine pricing.
What home insurance discounts does Allstate offer for bundled policies?
Bundling car and home insurance with Allstate typically reduces premiums by 10-25%. Additional discounts include claims-free rewards, new home/roof upgrades, early signing, and loyalty programs. Multi-policy holders also access exclusive safety and security device rebates.
Can I customize Allstate’s home insurance coverage for flood or earthquake risks?
Allstate’s standard home policies exclude flood/earthquake damage. Separate policies or endorsements are available for these risks. Quote tools let you add optional coverage, but premiums vary by location and risk level. FEMA maps or local hazard assessments may influence pricing.
How long does the Allstate claims process take for car accidents?
Allstate’s average claim processing time for car accidents ranges from 1-3 weeks, depending on damage severity and repair shop availability. Straightforward claims (e.g., minor fender benders) may resolve faster. Complex cases or disputes can extend timelines. Mobile app updates track progress.
Does Allstate offer usage-based car insurance for low-mileage drivers?
Yes, Allstate’s Drivewise program tracks driving habits via a plug-in device or app. Safe drivers with low annual mileage (e.g., <7,500 miles) can earn premium discounts of up to 30%. Data includes hard braking, speed, and phone use, with real-time feedback.
How does Allstate’s home insurance compare to State Farm or Geico?
Allstate ranks among top insurers for customer service and claims satisfaction. It often offers competitive rates for bundled policies but may charge more for high-risk properties. State Farm excels in local agent support, while Geico typically provides lower quotes. Coverage breadth and add-ons vary by provider.
Related articles
Auto Home Insurance Exploring Global Trends Coverage And Future
Discover global trends in Auto Home Insurance, from evolving coverage options to future outlook. Learn how policies adapt to risks, technology, and…
Smart Ways to Compare Auto and Home Insurance Quotes
Save money and get the best coverage with Smart Ways to Compare Auto and Home Insurance Quotes—learn how to evaluate rates, coverage limits, and…

Finding Auto Home Insurance Near Me Explained Clearly
Finding Auto Home Insurance Near Me Explained Clearly: Discover how to compare quotes, check coverage options, and save on bundled policies for your car…
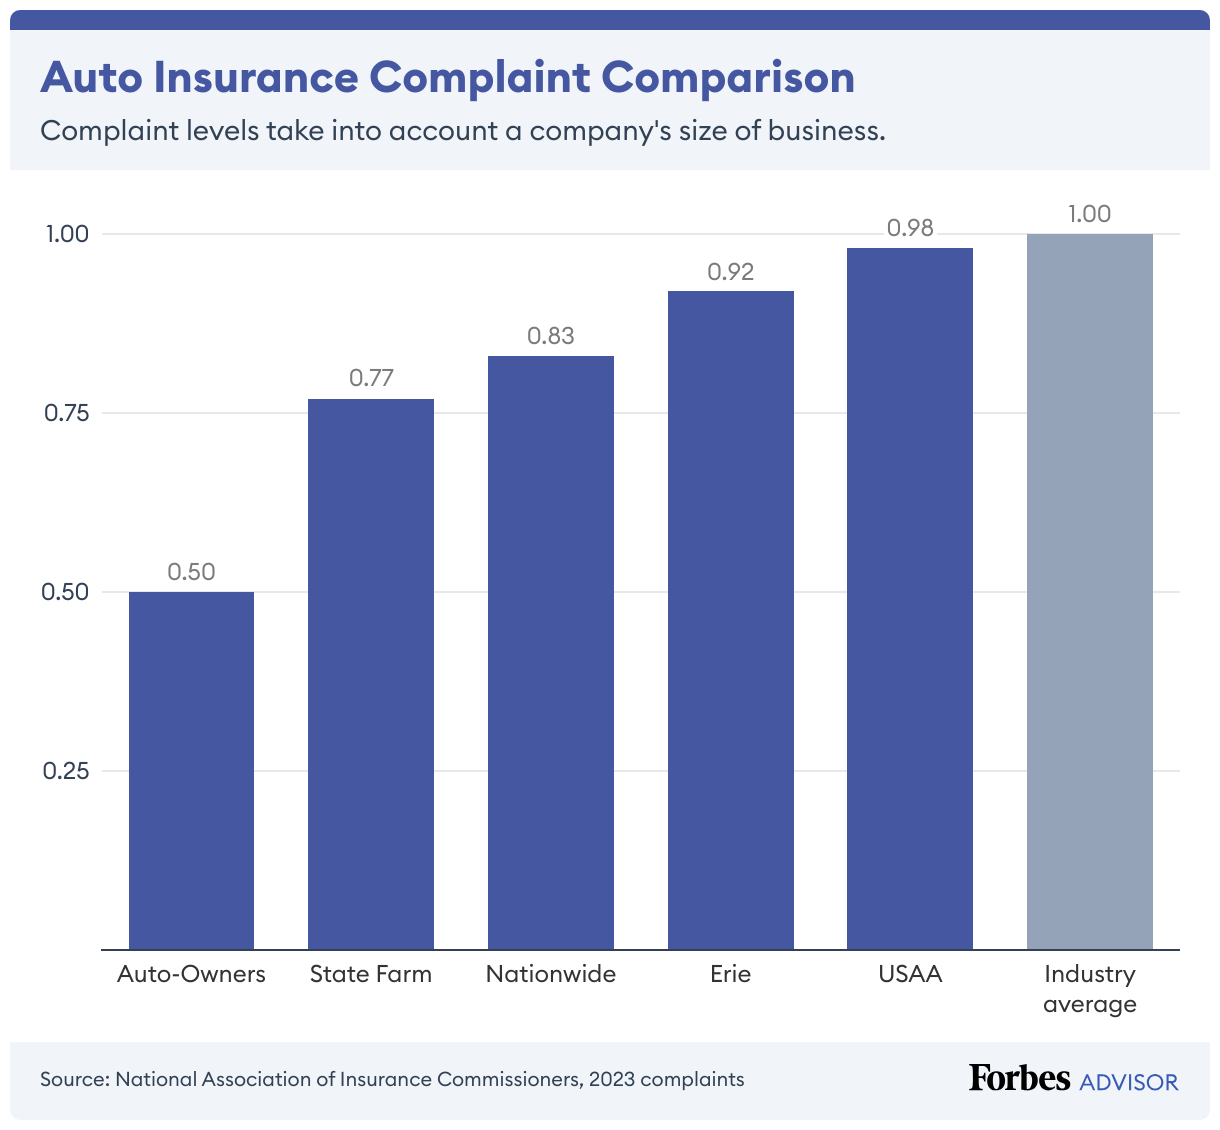
Auto Home Insurance Companies Global Market Insights And Trends
Discover the latest insights on the Auto Home Insurance Companies Global Market Insights And Trends, including key players, growth drivers, and regional…

Auto Home Insurance Unveiled Global Trends Tech And Future
Discover the latest Auto Home Insurance Unveiled Global Trends Tech And Future, from AI-driven claims to smart home policies reshaping coverage worldwide.
