Auto Home Insurance Companies Global Market Insights And Trends
Table of Contents
- Current Market Trends in Auto and Home Insurance: Growth Drivers and Regional Disparities
- Mandatory and Optional Coverage Options in Auto Insurance Policies Across Countries
- Primary Demographics for Auto Insurance Purchases and Their Preferred Policy Types
- Step-by-Step Claims Process for Auto and Home Insurance with Documentation and Timelines
- Telematics and Usage-Based Insurance (UBI) Transforming Auto Insurance Pricing Models
- Key Regulations Governing Auto Insurance by Country: No-Fault Laws and Minimum Coverage Requirements
- Risk Assessment in Auto Insurance: Key Factors and Methodologies
- Elements of a Seamless Digital Customer Journey in Auto and Home Insurance, from Quote to Claim
- Financial Breakdown of Auto and Home Insurance Revenue Streams
- Cyber Insurance as a Complement to Home and Auto Policies: Emerging Trends and Market Integration
- Business Model and Market Positioning of AXA as a Global Auto Insurer
- A Typical Day in the Life of an Auto Insurance Underwriter
- Unique Challenges and Opportunities in Auto Insurance for Emerging Economies (India, Brazil, and Beyond)
- Integration of Environmental, Social, and Governance (ESG) Criteria in Underwriting Decisions
The auto and home insurance sectors stand at the intersection of technology, regulation, and shifting consumer demands, reshaping how risks are assessed and managed worldwide. With global premiums exceeding $2 trillion annually, these industries balance innovation—like AI-driven underwriting and telematics—with traditional underwriting models while navigating regional disparities in coverage access and fraud vulnerabilities. From the rise of cyber insurance to the challenges posed by climate change, insurers must adapt policies to evolving threats while maintaining profitability and customer trust.
This exploration delves into the dynamics of leading providers, from their market dominance and coverage offerings to the technological advancements and regulatory hurdles defining their operations. By examining customer segmentation, claims fraud prevention, and sustainability initiatives, the discussion highlights how insurers are not only mitigating risks but also redefining the future of protection in an increasingly complex landscape. Whether through bundled policies, predictive analytics, or peer-to-peer models, the evolution of auto and home insurance reflects broader trends in financial services—where data, ethics, and resilience converge.
Current Market Trends in Auto and Home Insurance: Growth Drivers and Regional Disparities
The global insurance market, particularly in auto and home segments, is undergoing rapid transformation driven by technological advancements, shifting consumer behaviors, and evolving regulatory landscapes. Auto insurance premiums are projected to reach **$815.5 billion by 2027**, growing at a **CAGR of 3.5%**, while home insurance is expected to exceed **$1.1 trillion by 2025**, fueled by rising property values and climate-related risks. Regional disparities remain pronounced, with North America and Europe leading in digital adoption and Asia-Pacific emerging as a high-growth market due to urbanization and vehicle penetration. **Key growth drivers** include: - **Telematics and Usage-Based Insurance (UBI):** Integration of IoT devices and AI-driven risk assessment tools, such as Progressive’s **Snapshot** and Allstate’s **Drivewise**, reduces premiums for low-risk drivers by **10–30%**. - **Climate Change and Catastrophic Risks:** Wildfires, hurricanes, and floods have increased home insurance claims in the U.S. by **40%** since 2017, prompting insurers to adopt **parametric models** for faster payouts (e.g., Swiss Re’s **Catastrophe Bonds**). - **Insurtech Disruption:** Fintech partnerships (e.g., Lemonade’s **AI chatbots**) and blockchain for fraud prevention (e.g., **Etherisc**) are reshaping underwriting and claims processing. - **Regional Shifts:** China’s auto insurance market is expanding at a **CAGR of 8%** due to EV adoption, while emerging markets like India and Brazil face challenges from **informal vehicle registrations** and low penetration rates. **Regional Disparities:** - **North America:** Highest premiums (**$1,200–$2,500/year for auto**; **$1,500–$3,000/year for home**) due to litigation risks and high repair costs. **Texas and Florida** dominate claims from hurricanes and hailstorms. - **Europe:** Mandatory **third-party liability coverage** in most countries, with Germany and France leading in **telematics adoption**. **Brexit** has increased compliance costs for UK insurers. - **Asia-Pacific:** Rapid growth in **China (30% CAGR)** and **India (15% CAGR)**, but underinsurance persists—only **4% of Indian homes** have insurance despite **$1 trillion in annual property exposure**. - **Latin America:** High fraud rates (**25–40% of claims**) and limited digital infrastructure hinder growth, though **Mexico and Brazil** are prioritizing **microinsurance** for low-income populations.Technology-Driven Innovations Reshaping Underwriting
The adoption of **AI, big data, and predictive analytics** is reducing underwriting costs by **20–30%** while improving accuracy. Insurers now leverage: - **Computer Vision:** Cameras in vehicles (e.g., **State Farm’s Drive Safe & Save**) detect distracted driving, reducing claims by **15%**. - **Predictive Maintenance:** Home insurers like **Allianz** use **smart home sensors** to monitor pipe leaks and fire risks, cutting claims by **25%**. - **Dynamic Pricing:** **Usage-based models** adjust premiums in real-time (e.g., **Nationwide’s SmartRide**). - **Blockchain for Fraud Prevention:** **IBM and Maersk** pilot blockchain to verify claim authenticity, reducing fraud losses by **up to 50%** in test cases.Regulatory and Compliance Pressures by Region
Regulatory frameworks significantly impact market dynamics, with **GDPR in Europe** and **NAIC model laws in the U.S.** setting benchmarks. Key examples: - **U.S.:** **California’s Proposition 103** caps rates and mandates **low-cost auto insurance** for high-risk drivers. **Florida’s Citizens Property Insurance** faces insolvency risks due to **$100B in unpaid claims** from Hurricane Ian. - **Europe:** **Solvency II** requires insurers to hold **€450B in capital** for climate risks. **France’s Macron’s Reform** limits natural disaster payouts to **€120M/year** without government backstop. - **Asia:** **China’s Cyber Insurance Mandate** for state-owned enterprises and **India’s Motor Third-Party Insurance** (mandatory since 1988) cover **100% of bodily injury claims**. - **Latin America:** **Mexico’s Condusef** enforces **transparency in premiums**, while **Brazil’s Susep** regulates **reinsurance markets** to stabilize claims payouts.Emerging Risks and Market Responses
**Cyber Liability:** Home insurance policies now include **$250K–$1M in cyber coverage** (e.g., **Chubb’s Smart Home Insurance**) due to **rising ransomware attacks** (costing **$457K/incident** on average). **EV-Specific Policies:** **Tesla Insurance** (via **Tesla Insurance Services**) offers **$1,500–$3,000/year** for EVs, covering **battery replacement** and **software updates**. **Social Inflation:** Jury awards in the U.S. have increased **claims costs by 30%** since 2010, prompting insurers to **limit payouts** or **shift to alternative dispute resolution**.Market Share Dynamics and Consolidation Trends
Consolidation is accelerating, with **top 10 global insurers controlling 40% of the auto market**. Examples: - **Allianz and AXA** dominate Europe with **25% combined market share**, leveraging **cross-border reinsurance**. - **Ping An (China)** and **ICBC (India)** are expanding via **digital-first models** and **government partnerships**. - **U.S. mega-mergers** (e.g., **Allstate’s acquisition of Esurance**) aim to offset **rising claims costs** from **distracted driving and climate events**.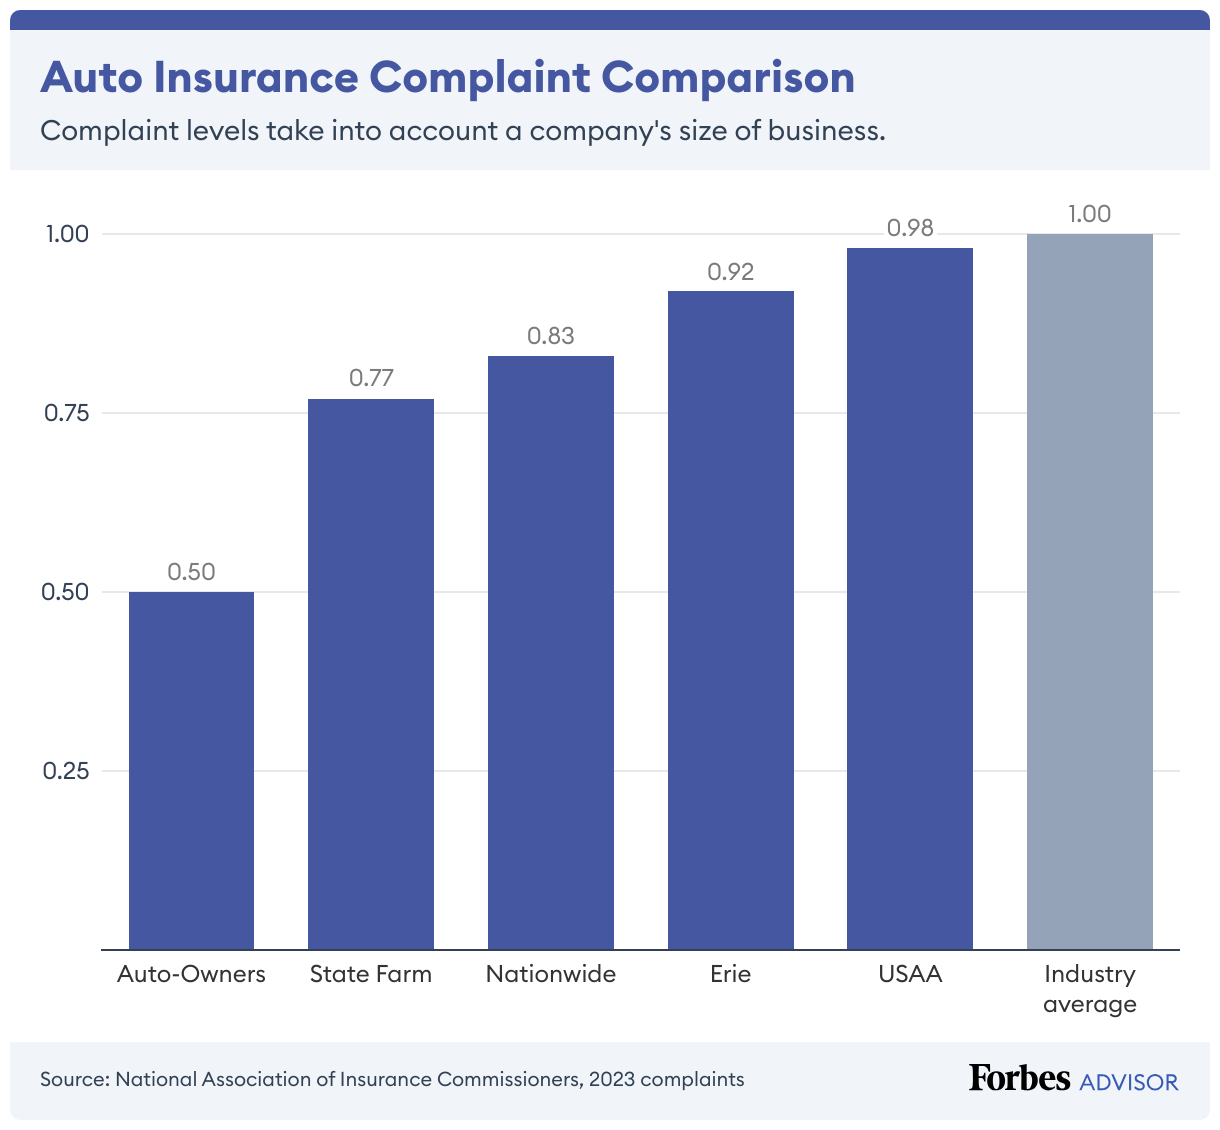
Mandatory and Optional Coverage Options in Auto Insurance Policies Across Countries
Auto insurance regulations vary significantly by country, with mandatory coverages designed to protect third parties (e.g., bodily injury, property damage) while optional coverages address driver-specific risks. The structure of these policies reflects legal requirements, economic factors, and local driving conditions. Below is a breakdown of mandatory and optional coverages in key regions, highlighting how legal frameworks influence policy design. ---Mandatory Coverages by Region
Mandatory auto insurance requirements are enforced by law to ensure financial responsibility in case of accidents. These typically cover **third-party liability**, which includes bodily injury and property damage to others. Some countries also mandate **uninsured/underinsured motorist protection** or **personal accident coverage**.-
United States
- **Liability Coverage**: Required in all states (minimum limits vary by state, e.g., 25/50/25 in most states: $25K per person/$50K per accident for bodily injury, $25K for property damage).
- **Uninsured/Underinsured Motorist (UM/UIM)**: Mandatory in 22 states (e.g., New York, Florida) to cover costs if the at-fault driver lacks insurance.
- **Personal Injury Protection (PIP)**: Required in "no-fault" states (e.g., Michigan, New York) to cover medical expenses regardless of fault.
Note: States like Virginia and New Hampshire allow drivers to self-insure or post cash bonds instead of purchasing liability insurance.
-
European Union
- **Third-Party Liability**: Mandatory across all EU member states, with minimum coverage defined by the Motor Insurance Directive (e.g., €1,000,000 for bodily injury in most countries).
- **Bodily Injury to Passengers**: Some countries (e.g., France, Germany) require additional coverage for passengers in the insured vehicle.
- **Compulsory Excess**: Certain countries (e.g., Italy) mandate a deductible (franchise) to reduce premiums.
Example: In the UK, the Motor Insurance Bureau (MIB) enforces minimum third-party coverage of £2,000,000, with additional protections for uninsured drivers.
-
Canada
- **Third-Party Liability**: Mandatory in all provinces (minimum $200,000 in Ontario, $1,000,000 in Quebec).
- **Accident Benefits**: Required in provinces like Ontario and British Columbia to cover medical and rehabilitation costs.
- **Direct Compensation Property Damage (DCPD)**: Mandatory in Ontario to allow claims against one’s own insurer for collision damage.
-
Australia
- **Compulsory Third-Party (CTP) Insurance**: Mandatory in all states/territories to cover injuries to others (e.g., $5,000,000 minimum in New South Wales).
- **Green Slip (NSW) / CTP Certificate**: Required for registration, with premiums varying by risk factors (e.g., urban vs. rural areas).
-
Japan
- **Automobile Liability Insurance (JALI)**: Mandatory for all vehicles, covering third-party bodily injury and property damage (minimum ¥10,000,000 for injury, ¥300,000 for property).
- **Personal Accident Insurance**: Often bundled with JALI to cover driver/passenger injuries.
Optional Coverages and Their Global Variations
Optional coverages allow policyholders to customize protection based on vehicle value, usage, and risk tolerance. These often include **collision, comprehensive, medical payments, and specialized add-ons**. Premiums and availability depend on local market dynamics.-
Collision Coverage
- Pays for damage to the insured vehicle from accidents with other vehicles or objects (e.g., guardrails).
- Common in the US (average cost: $300–$800/year), but less prevalent in countries with high public transport use (e.g., Japan, where only ~30% of drivers opt for it).
- Exclusions: Intentional damage, racing, or driving under the influence.
-
Comprehensive Coverage
- Covers non-collision events (e.g., theft, vandalism, natural disasters, fire).
- In the US, ~50% of policies include comprehensive coverage, with premiums averaging $150–$500/year. In Australia, it’s often bundled with CTP as "compulsory excess" coverage.
- Exclusions: Wear and tear, mechanical breakdowns, or damage from unauthorized modifications.
-
Medical Payments/Personal Injury Protection (PIP)
- Covers medical expenses for the driver and passengers, regardless of fault.
- Mandatory in no-fault states (e.g., Michigan) but optional elsewhere (e.g., US average cost: $50–$200/year). In Canada, accident benefits are often included in mandatory provincial plans.
- Exclusions: Pre-existing conditions (unless aggravated by the accident) or injuries sustained while driving commercially.
-
Rental Reimbursement and Roadside Assistance
- Covers rental costs while the insured vehicle is repaired (e.g., $20–$50/day limit in US policies). Roadside assistance includes towing, battery jump-starts, and fuel delivery.
- Popular in regions with harsh climates (e.g., Canada, Nordic countries) or long commutes (e.g., US, Australia).
- Exclusions: Off-road use, commercial towing, or mechanical failures not covered under warranty.
-
Glass Coverage
- Specialized add-on for windshield or window damage, often with a low deductible (e.g., $0–$100 in the US).
- Common in Europe (e.g., Germany, France) where glass claims account for ~15% of all auto claims.
- Exclusions: Damage from improper installation or neglect (e.g., leaving windows open in hail).
-
Classic and Antique Car Insurance
- Designed for vehicles over 20–30 years old, with agreed-value coverage (pays the pre-determined value in case of total loss).
- Premiums vary widely (e.g., $500–$3,000/year in the US) based on storage conditions, usage (e.g., only for shows vs. daily driving), and restoration costs.
- Exclusions: Modifications not approved by the insurer or use in professional competitions.
Regulatory and Cultural Influences on Coverage Options
The availability and structure of optional coverages reflect cultural attitudes toward risk, legal frameworks, and economic conditions. For example:- High-Deductible Policies: Popular in cost-conscious markets (e.g., India, where third-party premiums are subsidized, but comprehensive insurance is optional and expensive). Deductibles can reach ₹10,000–₹25,000 (~$120–$300).
- Telematics-Based Insurance: Mandatory or incentivized in countries with high traffic congestion (e.g., UK’s Black Box Insurance, where discounts of 10–30% are offered for safe driving).
- Environmental Risks: In flood-prone areas (e.g., Netherlands, Bangladesh), insurers offer optional "flood coverage" with higher premiums (e.g., +20–50% in the US for high-risk zones).
- Government Subsidies: In some countries (e.g., South Africa), basic insurance is heavily subsidized, but optional coverages are rarely taken up due to affordability constraints.
Key Insight: Optional coverages often serve as loss leaders for insurers, with bundled policies (e.g., auto + home) offering discounts of 10–25% to encourage uptake.
Primary Demographics for Auto Insurance Purchases and Their Preferred Policy Types
Auto insurance adoption varies significantly across demographics, influenced by factors such as age, income, and geographic location. Younger drivers, despite higher accident risks, represent a critical segment due to legal requirements, while middle-aged professionals prioritize comprehensive coverage for asset protection. Urban populations, with higher vehicle density and theft risks, often opt for full-coverage policies, whereas rural residents may lean toward liability-only plans with lower premiums. Income levels further refine preferences—higher earners invest in premium tiers with added perks, while budget-conscious buyers seek cost-effective, minimalist coverage.Age-Based Segmentation and Policy Preferences
Age directly correlates with driving experience, risk tolerance, and financial stability, shaping policy choices.- Young Adults (16–25 years):
Highest accident rates due to inexperience, leading insurers to classify them as high-risk. Preferred policies include:
- **Liability-only coverage** (minimum state-required limits) to minimize costs, though this leaves them vulnerable to high out-of-pocket expenses in at-fault accidents.
- **Usage-based insurance (UBI)** programs (e.g., Progressive’s Snapshot, State Farm’s Drive Safe & Save) that monitor driving behavior via telematics to reward safe habits with discounts.
- **Parental policies** where young drivers are added as secondary drivers to leverage lower premiums under a parent’s established policy.
**Key Insight:** 20% of fatal crashes involve drivers aged 15–20, yet only 7% of licensed drivers fall into this group (NHTSA, 2022). Insurers mitigate risk by offering graduated licensing discounts or requiring completion of defensive driving courses.
- Millennials (26–40 years):
Balancing affordability with comprehensive protection, this group often seeks:
- **Collision/comprehensive bundles** with moderate deductibles ($500–$1,000) to cover theft or weather-related damage.
- **Rideshare insurance** (e.g., Uber/Lyft endorsements) due to the rise of gig economy driving.
- **Pay-per-mile insurance** (e.g., Milewise) for low-mileage urban commuters or remote workers.
- Gen X (41–55 years) and Boomers (56–70 years):
Prioritize long-term asset protection and lower premiums through loyalty discounts.
- **Full-coverage policies** with higher liability limits (e.g., 100/300/100) to safeguard savings and property.
- **Multi-policy discounts** (bundling auto with home/renters insurance) to reduce costs.
- **Anti-theft discounts** for vehicles equipped with GPS tracking or immobilizers.
- Seniors (71+ years):
Lower accident rates but higher medical costs post-collision. Preferred options include:
- **Senior-specific discounts** for completing refresher courses (e.g., AARP’s Smart Driver program).
- **Low-mileage discounts** if driving is limited to essential trips.
Income and Policy Complexity Correlation
Income determines both affordability and willingness to pay for premium features. Insurers categorize customers into tiers based on disposable income and risk appetite.- Low-Income Households ($25K–$50K):
- Opt for **minimum coverage** to meet state requirements, often lacking collision/comprehensive protection.
- Rely on **high deductibles** ($1,000+) to lower premiums, increasing financial risk in accidents.
- Utilize **government assistance programs** (e.g., state-run high-risk pools) or non-profit insurers (e.g., USAA for military families).
**Statistic:** 12% of uninsured motorists are underinsured due to cost barriers (Insurance Information Institute, 2023).
- Middle-Income Families ($50K–$100K):
Seek **balanced coverage** with customizable add-ons:
- **Roadside assistance** (e.g., AAA memberships bundled with policies).
- **Rental reimbursement** for short-term vehicle use post-accident.
- **Gaps insurance** for leased vehicles to cover depreciation differences.
- High-Net-Worth Individuals ($100K+):
Invest in **premium tiers** with:
- **Umbrella policies** extending liability coverage beyond state limits (e.g., $1M–$5M).
- **Classic car insurance** with agreed-value coverage for vintage vehicles.
- **Telematics premiums** for fleet management or executive protection services.
Geographic Location and Policy Customization
Urban, suburban, and rural areas present distinct risk profiles, influencing coverage preferences and pricing strategies.- Urban Areas (e.g., NYC, LA, Chicago):
- **Higher premiums** due to theft, vandalism, and traffic-related risks. Average annual cost: **$1,200–$2,500** (vs. $800 nationally).
- **Preferred policies:**
- Collision/comprehensive coverage with **low deductibles** ($250–$500) for rapid claim processing.
- **Anti-theft discounts** for vehicles with alarms or tracking systems.
- **Rideshare endorsements** for gig workers.
- Suburban Areas (e.g., Dallas, Atlanta):
Moderate risks with a mix of commuting and residential exposure.
- **Mid-tier premiums** ($900–$1,500/year) with emphasis on **liability and medical payments**.
- **Family discounts** for multi-vehicle households.
- Rural Areas (e.g., Midwest, Appalachia):
Lower accident rates but higher risks from weather (e.g., hail, deer collisions).
- **Lower premiums** ($600–$1,000/year) with **higher liability limits** to cover medical costs in uninsured motorist scenarios.
- **Farm/equipment coverage** for rural professionals.
- High-Risk Zones (e.g., Florida, Louisiana):
Vulnerable to hurricanes, flooding, and high uninsured motorist rates.
- **Mandatory comprehensive coverage** with **wind/hail endorsements** (e.g., Florida’s "hurricane deductible" options).
- **Non-standard insurers** (e.g., Geico, Progressive) dominate due to traditional insurers exiting high-risk markets.

Step-by-Step Claims Process for Auto and Home Insurance with Documentation and Timelines
The claims process for auto and home insurance involves structured steps to ensure fair and efficient resolution for policyholders. Understanding the procedural flow, required documentation, and expected timelines helps policyholders navigate claims smoothly while minimizing delays or disputes. Insurers adhere to regulatory guidelines to balance speed with thoroughness, ensuring claims are processed transparently and accurately. **Auto Insurance Claims Process** The auto insurance claims process begins immediately after an incident and involves multiple stages, from initial reporting to final settlement. Each step requires specific documentation to validate the claim and determine liability.Incident Reporting and Initial Assessment
Policyholders must report the incident to their insurer as soon as possible, typically within **24 to 72 hours**, depending on the policy terms. Failure to report promptly may void coverage. During this stage: - **Documentation required**: - Police report (for accidents involving bodily injury or significant property damage, especially in no-fault states). - Photos/videos of vehicle damage, road conditions, and the accident scene (including license plates, street signs, and skid marks). - Witness statements (names and contact details). - Driver’s license and proof of insurance. - **Insurer actions**: - Assigns a claims adjuster to evaluate the claim. - Verifies policy details and coverage limits. - May request additional information if the incident is unclear.Claims Investigation and Damage Assessment
Adjusters conduct a detailed investigation to assess liability and damages. This stage may involve: - **For collision claims**: - Inspection of the vehicle by an adjuster or a repair shop affiliated with the insurer. - Estimation of repair costs using industry tools (e.g., **Mitchell 1** or **CCC Intellichoice**). - Determination of fault (if applicable) based on police reports, witness statements, and traffic laws. - **For non-collision claims (e.g., theft, vandalism, weather damage)**: - Verification of the incident through police reports, surveillance footage, or security systems. - Assessment of property damage using standardized valuation methods (e.g., **replacement cost** vs. **actual cash value**). - **Timelines**: - Adjusters typically complete investigations within **7 to 14 days** for straightforward claims, though complex cases may take **30+ days**.Repair or Settlement Approval
Once the adjuster approves the claim, policyholders have two primary options: - **Repair through an insurer-approved shop**: - The insurer arranges repairs and pays the shop directly (less common for comprehensive/collision claims). - Policyholders may choose their own repair shop but must provide estimates for approval. - **Cash settlement for total loss or agreed repairs**: - For totaled vehicles, insurers calculate **actual cash value (ACV)** based on depreciation and market value. - Policyholders receive a check minus any deductible, and the insurer may retain the vehicle (if applicable). - **Timelines**: - Approval and payment typically occur within **15 to 30 days** after investigation completion.Dispute Resolution and Appeals
If a policyholder disputes the insurer’s decision, they can escalate the claim through: - **Internal review**: Requesting a second adjuster or supervisor to re-evaluate. - **State insurance department**: Filing a complaint if the insurer acts in bad faith (e.g., unreasonable delays or denial without justification). - **Mediation/arbitration**: Binding or non-binding processes to resolve disagreements. - **Legal action**: Filing a lawsuit as a last resort (rare, as litigation is costly and time-consuming). --- **Home Insurance Claims Process** The home insurance claims process follows a similar structure but adapts to property-specific complexities, such as structural damage, liability, or personal belongings losses.Initial Claim Notification and Documentation
Policyholders must report home insurance claims promptly, often within **14 days** of discovering damage. Required documentation includes: - **For property damage (fire, storm, vandalism)**: - Photos/videos of affected areas, including before-and-after shots if possible. - Police reports (for theft or criminal damage). - Receipts for temporary repairs (e.g., tarping a roof) to prevent further damage. - Inventory of damaged personal belongings (with receipts or appraisals for high-value items). - **For liability claims (e.g., guest injuries)**: - Medical records, witness statements, and incident reports. - Legal documentation if a lawsuit is filed.Inspection and Damage Assessment
Adjusters or contractors inspect the property to determine coverage and repair costs. Key steps include: - **Structural damage assessment**: - Evaluation of foundation, roof, walls, and electrical systems for storm or fire damage. - Use of **Xactimate** or similar software to estimate repair costs. - **Personal property claims**: - Itemized lists with proof of purchase (receipts, appraisals, or serial numbers for electronics). - Adjusters may sample-check items (e.g., inspecting 10% of a damaged inventory). - **Timelines**: - Inspections typically occur within **3 to 7 days** of claim filing, with full assessments completed in **10 to 21 days**.Settlement and Restoration
Insurers issue payments based on the policy type: - **Actual Cash Value (ACV)**: Pays for depreciated items (common for older policies). - **Replacement Cost**: Covers full repair/replacement without depreciation deductions (requires documentation like receipts). - **Additional Living Expenses (ALE)**: Covers hotel costs or meals if the home is uninhabitable. - **Timelines**: - Partial payments may be issued within **7 to 14 days** for urgent repairs (e.g., roof leaks). - Final settlements for major claims take **30 to 60 days**.Special Considerations for Catastrophic Events
Natural disasters (e.g., hurricanes, wildfires) trigger expedited but complex processes: - **Declared disasters**: Insurers may deploy **catastrophe response teams** to accelerate claims. - **Government assistance**: Policyholders may coordinate with FEMA or state agencies for parallel aid. - **Fraud monitoring**: Increased scrutiny of claims due to higher fraud rates during disasters (e.g., exaggerated damage reports). ---Telematics and Usage-Based Insurance (UBI) Transforming Auto Insurance Pricing Models
Telematics and usage-based insurance (UBI) are revolutionizing auto insurance by shifting pricing from static risk profiles to dynamic, behavior-driven models. Traditional underwriting relies on broad demographic and historical data, but telematics—combined with real-time driver behavior tracking—enables insurers to offer personalized premiums based on actual usage patterns. This shift improves fairness, reduces premiums for safe drivers, and incentivizes safer driving habits through gamification and feedback mechanisms. The integration of telematics devices (e.g., OBD-II ports, smartphone apps) captures data on speed, braking, acceleration, mileage, and even phone usage while driving. Insurers like **Progressive’s Snapshot**, **Allstate’s Drivewise**, and **State Farm’s Drive Safe & Save** leverage this data to adjust premiums monthly or annually. Studies show UBI adopters reduce claims by **5–15%** due to heightened driver awareness, while insurers achieve **10–30% cost savings** by aligning risk with real-world behavior rather than generalized assumptions.Key Mechanisms of Telematics-Driven Pricing
Telematics enables **pay-as-you-drive (PAYD)** and **pay-how-you-drive (PHYD)** models, which directly correlate premiums to individual risk profiles. The core components include:- **Real-Time Data Collection**: Devices or apps monitor driving habits continuously, transmitting data to insurers via cellular or Bluetooth. Metrics like hard braking (indicating recklessness) or excessive idling (suggesting poor vehicle maintenance) trigger risk adjustments.
- **Behavioral Scoring**: Algorithms assign scores based on predefined risk thresholds (e.g., speeding over 10 mph above limit may deduct points). Insurers like **Nationwide’s SmartRide** use tiered scoring to offer discounts (e.g., 10–30% for safe drivers).
- **Dynamic Premium Adjustments**: Unlike annual policies, UBI allows **monthly or quarterly premium recalculations** based on updated behavior. For example, **Milewise (Allstate)** adjusts rates based on annual mileage, benefiting low-mileage drivers.
- **Gamification and Feedback**: Drivers receive real-time alerts or app notifications (e.g., Progressive’s **Snapshot Coach**) to improve habits. **Root Insurance** uses a "safety score" displayed in their app, with rewards for sustained safe driving.
Impact on Insurance Market Dynamics
The adoption of UBI is reshaping competition, regulation, and consumer expectations. Traditional insurers face pressure to innovate, while insurtech disruptors leverage data to undercut legacy players. Key market shifts include:- **Reduced Adverse Selection**: UBI mitigates the problem of high-risk drivers self-selecting into cheap policies. Data transparency ensures fairer pricing, as insurers can identify and manage risk proactively.
- **Regulatory Challenges**: Privacy concerns and data security laws (e.g., **GDPR in Europe**, **CCPA in California**) require insurers to anonymize data and obtain explicit consent. Some states (e.g., **Massachusetts**) restrict telematics use without driver opt-in.
- **Insurtech Disruption**: Startups like **Oscar Insurance** and **Lemonade** use UBI as a core differentiator, offering **instant quotes** and **AI-driven discounts** based on telematics. Traditional insurers (e.g., **Geico’s DriveEasy**) now partner with insurtechs to integrate UBI features.
- **Expansion of Usage-Based Models**: Beyond personal auto, UBI is extending to **commercial fleets** (e.g., **Zego’s telematics for trucks**) and **ride-sharing drivers** (e.g., **Uber’s partnership with Root**). Commercial UBI can reduce fleet insurance costs by **20–40%** through driver training programs.
Case Study: Progressive’s Snapshot and Industry Benchmarks
Progressive’s **Snapshot program**, launched in 2010, serves as a benchmark for UBI adoption:- **Participation Growth**: Over **4.5 million drivers** (as of 2023) use Snapshot, with **30% of new Progressive customers** opting for UBI. The program covers **40+ states** and offers discounts up to **30%** for safe drivers.
- **Claims Impact**: Drivers using Snapshot file **20% fewer claims** on average, with **35% fewer at-fault accidents** compared to non-participants (Progressive internal data).
- **Profitability**: Snapshot contributes **$1.5 billion annually** to Progressive’s revenue, with a **3:1 return on investment** due to reduced claims and improved risk selection.
**"Telematics is no longer a niche offering—it’s becoming the standard. Insurers that don’t adopt it risk losing market share to competitors who leverage real-time data for precision pricing."** — *McKinsey & Company, 2023 Insurance Disruption Report*
Key Regulations Governing Auto Insurance by Country: No-Fault Laws and Minimum Coverage Requirements
Auto insurance regulations vary significantly by country, with some jurisdictions enforcing strict no-fault systems while others mandate minimum coverage levels to ensure financial protection for policyholders. These rules are designed to balance affordability, accessibility, and compensation fairness, though their implementation reflects cultural, economic, and legal priorities. **No-fault insurance systems** require insurers to cover policyholders' medical expenses and property damage regardless of fault, reducing litigation but often increasing premiums. Conversely, **at-fault systems** allow victims to sue negligent drivers, which can lead to higher legal costs but may incentivize safer driving. Minimum coverage requirements also differ, with some countries mandating bodily injury liability, property damage, and uninsured motorist protection.United States: State-Specific No-Fault and Minimum Coverage Rules
The U.S. operates under a **federal framework** but delegates auto insurance regulations to **state insurance departments**, resulting in diverse rules. Twelve states (e.g., Florida, Michigan, New York) enforce **no-fault laws**, requiring insurers to cover medical expenses and lost wages up to a threshold before lawsuits are permitted. Michigan’s no-fault system, for example, mandates **personal injury protection (PIP) coverage** with limits of **$468,000 per accident** (as of 2023), while Florida requires **$10,000 in PIP benefits**. Minimum liability coverage varies widely: - **Liability Limits**: Most states require **25/50/25** (e.g., $25,000 per person/$50,000 per accident for bodily injury, $25,000 for property damage), but some (e.g., New Hampshire) have no state-mandated minimums. - **Uninsured/Underinsured Motorist (UM/UIM) Coverage**: 22 states mandate UM/UIM protection, with limits often mirroring liability requirements. - **Medical Payments (MedPay)**: Optional in most states but required in **New York ($50,000 minimum)** and **Massachusetts ($8,000 minimum)**.European Union: Mandatory Third-Party Liability and Bodily Injury Coverage
The EU mandates **third-party liability insurance** under the **Third Non-Life Insurance Directive (2005/26/EC)**, requiring coverage for: - **Bodily injury** to others (minimum **€12 million per accident**). - **Property damage** (varies by country; e.g., **€1 million in Germany**, **£2 million in the UK**). - **Legal expenses** for policyholders sued by third parties. **No-fault systems** exist in **France (since 1985)** and **Sweden (for medical costs)**, but most EU countries rely on **fault-based compensation**, with victims suing at-fault drivers. **Germany** requires **full coverage** (including collision and comprehensive) for vehicles over **12 years old**, while **Italy** mandates **mandatory third-party insurance** with optional **collision coverage**.Canada: Provincial Variations in Minimum Coverage and No-Fault Exemptions
Canada’s auto insurance system is **province-specific**, with **Quebec** operating under a **public no-fault model** (Société de l’assurance automobile du Québec, or SAQ) covering medical, rehabilitation, and income replacement costs. Other provinces mandate: - **Ontario**: **$200,000 in third-party liability** (statutory accident benefits cover medical expenses up to **$65,000**). - **British Columbia**: **$200,000 liability limit** with optional **collision/comprehensive coverage**. - **Alberta**: **$200,000 liability limit**, but **no mandatory accident benefits** (unlike Ontario or BC).Australia: Compulsory Third-Party (CTP) Insurance and State-Based Schemes
Australia requires **Compulsory Third-Party (CTP) insurance** (also called "green slip" insurance) for bodily injury claims, managed by **state-based schemes**: - **Queensland**: Covers **$5 million per claim** (administered by **QCIC**). - **New South Wales**: **$5 million limit** (managed by **State Insurance Regulatory Authority, SIRA**). - **Victoria**: **$5.1 million limit** (via **Transport Accident Commission, TAC**). **Comprehensive and collision coverage** are optional but heavily marketed, with insurers offering **usage-based discounts** (e.g., telematics programs).Japan: Liability-Based System with Strict Enforcement
Japan enforces a **strict liability system** under the **Automobile Liability Insurance Act**, requiring: - **Bodily injury liability**: **¥120 million per accident** (capped at **¥3,000 per day** for medical expenses). - **Property damage liability**: **¥30 million per accident**. - **Personal injury insurance**: Optional but widely purchased (covers **¥30 million per accident**). **No-fault elements** exist for medical costs, but lawsuits for pain and suffering are common. **Uninsured motorist coverage** is mandatory, reflecting Japan’s high compliance rate (**>99%**).Brazil: Mandatory Liability Insurance with Low Penetration Challenges
Brazil’s **Denatran (National Department of Traffic)** mandates **mandatory liability insurance (DPVAT)**, covering: - **Bodily injury**: **R$13,500 per victim** (capped at **R$27,000 per accident**). - **Death benefits**: **R$13,500 per victim**. **Penetration remains low (~30%)**, partly due to **high premiums** and **informal vehicle registration**. Comprehensive coverage is optional but rarely purchased due to **high theft rates** and **poor claims processing**. ---Risk Assessment in Auto Insurance: Key Factors and Methodologies
Auto insurers evaluate risk using a combination of quantifiable and qualitative factors to determine premiums, coverage eligibility, and policy terms. The assessment process balances statistical probability with individual behavior, vehicle characteristics, and external influences to minimize financial exposure while ensuring fair pricing. Credit scores, driving history, and vehicle type are foundational elements, but advanced analytics now incorporate telematics, geographic data, and even social determinants to refine risk profiles. The core of auto insurance underwriting revolves around predicting the likelihood of claims, particularly collision, comprehensive, and liability claims. Insurers prioritize factors that correlate with higher claim frequencies or severity, such as reckless driving patterns or exposure to theft. Below are the primary components of risk assessment, structured by their impact and measurability.Credit-Based Insurance Scores
Credit scores serve as a proxy for financial responsibility and risk tolerance, with studies indicating a correlation between creditworthiness and claim behavior. Insurers use proprietary models (e.g., **CLUE reports** or **Insurance Information Institute (III) frameworks**) to analyze credit history, payment timeliness, and debt-to-income ratios. Higher credit scores often translate to lower premiums, as they suggest disciplined financial behavior, which may extend to safer driving habits. **Key credit-related metrics:** - **Payment history (35% weight)**: Late payments or defaults signal potential financial stress, which may increase policy lapses or fraud risk. - **Credit utilization (30% weight)**: High revolving debt (e.g., credit cards) may indicate impulsive decisions, including riskier driving. - **Length of credit history (15% weight)**: Longer histories provide more stable data points for risk prediction. - **Credit mix and inquiries (10% weight)**: Multiple hard inquiries or diverse credit types may reflect higher financial volatility.*According to the Federal Trade Commission (FTC), insurers in states allowing credit-based scoring (e.g., California, New York) may see a **15–30% variance in premiums** between top-tier and subprime credit applicants, though bans on credit use (e.g., Hawaii, Massachusetts) require alternative underwriting methods.*
Driving History and Behavioral Patterns
Driving records are the most direct indicator of risk, capturing violations, accidents, and traffic infractions over a defined period (typically 3–5 years). Insurers categorize drivers into tiers based on **accident frequency**, **severity**, and **type of violations** (e.g., DUIs, speeding). Telematics data—collected via **onboard diagnostics (OBD-II) devices** or **mobile apps**—further refines this assessment by monitoring real-time behaviors like hard braking, speeding, and nighttime driving. **Driving history components:** - **At-fault accidents**: A single at-fault collision can increase premiums by **20–50%** for 3–5 years, depending on severity. - **Moving violations**: Speeding tickets or reckless driving may lead to **10–30% premium hikes**, with DUIs causing **50–100%+ increases**. - **Claims history**: Frequent claims (especially liability) may trigger **non-renewal** or higher deductibles. - **Telematics insights**: - **Hard braking/spinning**: Indicates aggressive driving; may adjust premiums dynamically. - **Mileage and routes**: High-mileage drivers or urban commuters face higher exposure to theft/collision. - **Phone usage**: Distracted driving detected via app usage correlates with **2x higher accident risk** (AAA Foundation for Traffic Safety).Vehicle Characteristics and Exposure Factors
The type of vehicle directly influences risk due to **crash test ratings**, **theft vulnerability**, and **repair costs**. Insurers classify vehicles using databases like **HLDI (Highway Loss Data Institute)** or **IIHS (Insurance Institute for Highway Safety)**. Key attributes include: - **Make/model/year**: Luxury or sports cars (e.g., Porsche 911, Ford Mustang) often have **higher collision claims** due to performance bias. - **Safety ratings**: Vehicles with **top IIHS safety picks** may qualify for **5–15% discounts**. - **Theft risk**: Models like the **Honda Accord (2010–2012)** or **Ford F-Series** appear frequently in theft reports (NISSAN database). - **Repair costs**: High-end or specialty vehicles (e.g., Tesla Model S) incur **20–40% higher repair costs** than mainstream sedans. - **Engine size/horsepower**: Vehicles with **>300 HP** are **30% more likely to be involved in fatal crashes** (NHTSA).*The **HLDI** reports that **pickup trucks** (e.g., Ford F-150) have **20% higher fatality rates per mile** than sedans, partly due to rollover risk and larger blind spots.*
Geographic and Environmental Risk Factors
Location-based risks include **crime rates**, **weather patterns**, and **traffic density**. Insurers use **postal codes** or **geographic information systems (GIS)** to assign risk scores. Urban areas with high theft rates (e.g., **Detroit, St. Louis**) may see premiums **10–25% higher**, while hurricane-prone zones (e.g., **Florida, Louisiana**) face **windstorm/hail deductibles**. **Environmental influences:** - **Urban vs. rural**: Cities have **3x higher theft rates** but **lower accident severity** than rural areas (Insurance Information Network of California). - **Weather exposure**: Hail-prone regions (e.g., **Colorado, Texas**) see **20–40% higher comprehensive claims**. - **Parking habits**: Vehicles parked on streets (vs. garages) in high-theft zones incur **additional premiums**. ---Elements of a Seamless Digital Customer Journey in Auto and Home Insurance, from Quote to Claim
A seamless digital customer journey in auto and home insurance transforms fragmented interactions into a cohesive, intuitive experience that aligns with modern consumer expectations. Insurers leveraging digital-first strategies reduce friction at every stage—quote, purchase, policy management, claims filing, and renewal—while enhancing transparency, speed, and personalization. This approach not only drives acquisition but also fosters loyalty by eliminating pain points such as complex paperwork, unclear communication, or delayed responses. The journey begins with **discovery and engagement**, where potential customers seek quotes or explore coverage options. It progresses through **purchase and onboarding**, where seamless digital tools streamline policy selection and documentation. Post-purchase, **policy management** ensures easy access to policy details, payments, and updates. During claims, **digital claims processing** accelerates resolution with automated workflows and real-time updates. Finally, **renewal and retention** strategies leverage data-driven insights to personalize offers and prevent churn. Below are the critical components that define each stage of this journey. ---Discovery and Engagement: Intuitive Quote Tools and Transparent Comparisons
The first touchpoint for most customers is the **quote generation process**, where insurers must provide instant, accurate estimates while educating users about coverage options. Leading insurers integrate **AI-driven quote engines** that adjust recommendations based on real-time data (e.g., vehicle make/model for auto, home square footage and location for home insurance). These tools should: - **Support multi-device accessibility**: Mobile-responsive design with minimal load times, as 68% of insurance shoppers begin their journey on smartphones (McKinsey, 2022). - **Offer interactive comparisons**: Side-by-side breakdowns of deductibles, premiums, and add-ons (e.g., roadside assistance, equipment coverage) to highlight value. - **Leverage chatbancements**: AI chatbots that guide users through questions (e.g., "Do you have a security system?") to refine quotes dynamically, reducing drop-offs by up to 40% (Accenture, 2023). **Example**: Progressive’s **Name Your Price Tool** allows users to input their desired premium, and the system adjusts coverage limits accordingly, demonstrating transparency and flexibility. ---Purchase and Onboarding: Digital Contracts and Instant Issuance
Traditional paper-based onboarding creates delays and frustration. Digital-first insurers replace manual processes with: - **Electronic signatures and e-contracts**: Platforms like DocuSign or Adobe Sign enable policy issuance within minutes, with e-signature adoption rising to 70% in the insurance sector (Forrester, 2023). - **Automated document collection**: Mobile apps or portals that pull data from connected sources (e.g., DMV records for auto insurance, utility bills for home insurance) to pre-fill applications, reducing errors by 30% (Capgemini, 2022). - **Instant policy delivery**: SMS or email notifications with embedded policy documents, including coverage summaries and next steps (e.g., "Your deductible is $500—here’s how to adjust it"). **Example**: Lemonade’s **AI-powered underwriting** issues home insurance policies in under 90 seconds, with customers receiving digital certificates via Slack or email, aligning with Gen Z/Millennial preferences for speed and digital-native interactions. ---Policy Management: Self-Service Portals and Proactive Notifications
Post-purchase, customers expect **24/7 access to policy details**, with minimal need for agent intervention. Key features include: - **Centralized dashboards**: Real-time views of coverage, claims history, and payment schedules, accessible via web or app. - **Automated alerts**: Push notifications for renewals, policy changes, or potential savings (e.g., "Your driving score improved—eligible for a 15% discount"). - **Customizable alerts**: Users can opt into notifications for specific events (e.g., claims updates, roadside assistance requests) to reduce anxiety. **Example**: Allstate’s **Mobile App** includes a **"Policy Health Score"** that rates coverage adequacy (e.g., "Your liability limits are below state requirements") and suggests upgrades. ---Claims Processing: End-to-End Digital Workflows and Real-Time Tracking
Claims are the most emotionally charged touchpoint. Digital transformation here involves: - **Mobile claims filing**: Apps that allow customers to upload photos/videos of damage (e.g., via **Lemonade’s "Snap" feature**) and receive instant claims numbers. - **Automated triage**: AI models assess claim validity (e.g., fraud detection for staged accidents) and route legitimate claims to adjusters within hours. - **Transparent progress tracking**: Real-time dashboards showing claim status, estimated payouts, and required documentation, reducing customer service inquiries by 25% (Deloitte, 2023). **Example**: State Farm’s **"Drive Safe & Save"** app integrates with telematics to auto-file claims after accidents, with adjusters notified immediately via GPS data. ---Renewal and Retention: Personalized Offers and Churn Prevention
Renewal is where digital engagement directly impacts retention. Strategies include: - **Predictive renewal reminders**: AI analyzes behavior (e.g., low claims frequency, safe driving) to trigger personalized emails/SMS (e.g., "You’re eligible for a loyalty discount—lock in now"). - **Dynamic pricing transparency**: Tools like **Geico’s "Pay Less" calculator** show how discounts (e.g., bundling, paperless billing) reduce premiums, increasing renewal rates by 20% (J.D. Power, 2023). - **Feedback loops**: Post-renewal surveys with incentives (e.g., entry into a prize draw) to gather insights and address pain points proactively. **Example**: USAA’s **"Relationship Manager"** program assigns a dedicated advisor to high-value customers, offering tailored coverage reviews and exclusive benefits (e.g., free identity theft protection). ---Financial Breakdown of Auto and Home Insurance Revenue Streams
The insurance industry generates revenue through multiple streams, with **premiums**, **investment income**, and **fees** forming the core components. Auto and home insurance segments exhibit distinct revenue dynamics due to differences in risk exposure, policy structures, and regulatory environments. Premiums constitute the largest share of revenue, while investment income and ancillary fees provide additional profitability drivers. Understanding these streams is critical for insurers to optimize pricing, manage underwriting risks, and sustain long-term financial health. Revenue streams in auto and home insurance can be categorized into three primary sources: - **Premium Income**: Direct payments from policyholders for coverage. - **Investment Income**: Earnings from float capital (premiums collected but not yet paid out as claims). - **Fees and Ancillary Revenue**: Charges for add-ons, late payments, or administrative services. ---Premium Income Structure
Premiums represent the primary revenue source for insurers, accounting for **70-85%** of total revenue in both auto and home insurance. The breakdown varies by region and insurer strategy, but direct written premiums (DWP) and earned premiums (EP) are key metrics. - **Auto Insurance Premiums**: - **Direct Written Premiums (DWP)**: Reflects the total premiums collected before deducting cancellations or adjustments. - **Earned Premiums (EP)**: Represents the portion of premiums recognized as revenue for the period covered (e.g., monthly or annual policies). - **Example**: In the U.S., auto insurance DWP exceeded **$250 billion in 2023**, with earned premiums stabilizing around **$230 billion** after accounting for lapses and cancellations. - **Home Insurance Premiums**: - Homeowners and renters insurance premiums are less volatile than auto but influenced by property values and catastrophe risks. - **DWP for home insurance in the U.S. reached ~$60 billion in 2023**, with earned premiums typically **5-10% lower** due to policy cancellations or non-renewals.**Key Formula**: *Earned Premium Ratio (EPR) = (Earned Premiums / Direct Written Premiums) × 100* A healthy EPR for insurers ranges between **90-95%**, indicating efficient premium utilization.---
Investment Income and Float Management
Insurers hold a significant portion of premiums (float) in investments to generate returns before claims are paid. This **investment income** can account for **10-30%** of total revenue, depending on market conditions and underwriting cycles. - **Auto Insurance Investment Income**: - Historically, auto insurers earn **$15-25 per policy annually** from investments, with returns varying by portfolio composition (bonds, stocks, real estate). - **Example**: State Farm, one of the largest U.S. auto insurers, reported **$12.3 billion in net investment income in 2022**, equivalent to **~15% of total revenue**. - **Home Insurance Investment Income**: - Home insurers benefit from longer policy terms (e.g., 1-3 years), allowing for greater investment returns. - **Example**: Allstate generated **$5.1 billion in investment income in 2022** (~12% of revenue), with a portfolio heavily weighted toward high-grade bonds and mortgage-backed securities.**Float Utilization**: *Insurers aim for a **net investment yield of 4-6%** to offset underwriting losses, especially in high-risk segments like auto insurance.*---
Fees and Ancillary Revenue Sources
While premiums dominate revenue, insurers generate additional income through fees for: - **Policy Add-Ons**: Rental car reimbursement, roadside assistance, or identity theft protection. - **Late Payment Fees**: Charges for missed premium payments (regulated by state laws). - **Administrative Charges**: Processing fees for policy amendments or claim-related services. - **Auto Insurance Fees**: - Ancillary revenue from add-ons can contribute **5-10%** of total premiums. - **Example**: Progressive’s **Snapshot program** (usage-based insurance) generates **$1 billion+ annually** through data-driven pricing adjustments. - **Home Insurance Fees**: - Fees for optional endorsements (e.g., flood or earthquake coverage) add **3-8%** to premiums. - **Example**: Insurers like Chubb charge **$500-$2,000 annually** for high-net-worth homeowners’ additional liability coverage. ---Regional Revenue Disparities
Revenue streams vary significantly by region due to: - **Market Penetration**: Higher car ownership in the U.S. vs. Europe’s public transport reliance. - **Claims Frequency**: Higher auto theft rates in urban areas (e.g., South Africa, Mexico) vs. rural regions. - **Regulatory Environment**: States like California impose stricter rate filings, affecting profitability.**Regional Premium Trends (2023)**: - **U.S.**: Auto DWP = **$250B**, Home DWP = **$60B**. - **Europe**: Auto DWP = **€180B**, Home DWP = **€120B** (higher home insurance due to stricter building codes). - **Asia-Pacific**: Auto DWP = **$120B**, Home DWP = **$80B** (rapid growth in China and India).---
Profitability Metrics by Product Line
Profit margins in insurance are influenced by **underwriting efficiency**, **claims ratios**, and **investment performance**. Below is a comparative table of key financial metrics for auto and home insurance:| Financial Metric | Auto Insurance | Home Insurance | Industry Average |
|---|---|---|---|
| **Combined Ratio (Underwriting + LAE)** | **100-105%** (U.S.), **95-102%** (Europe) | **90-98%** (U.S.), **85-95%** (Europe) | **98%** (Global average, including P&C) |
| **Net Profit Margin** | **3-7%** (U.S.), **5-10%** (Europe) | **5-12%** (U.S.), **8-15%** (Europe) | **6%** (Global P&C average) |
| **Investment Yield on Float** | **4-6%** (U.S.), **3-5%** (Europe) | **5-7%** (U.S.), **4-6%** (Europe) | **4.5%** (Global average) |
| **Reinsurance Cessions (as % of Premiums)** | **15-25%** (Catastrophe-prone regions) | **10-20%** (Higher for wildfire/hurricane zones) | **12%** (Global average) |
| **Ancillary Revenue as % of Total Revenue** | **5-10%** (Add-ons, fees) | **3-8%** (Endorsements, service charges) | **7%** (Global average) |
**Combined Ratio Interpretation**: *A ratio below 100% indicates profitability from underwriting; above 100% suggests losses offset by investment income.*
Cyber Insurance as a Complement to Home and Auto Policies: Emerging Trends and Market Integration
The digital transformation of households and vehicles has expanded the attack surface for cyber threats, making cyber insurance an essential add-on for traditional auto and home policies. Cyberattacks targeting connected devices—such as smart home systems, telematics-enabled vehicles, and IoT-enabled insurance claims portals—have surged by **600% since 2018**, according to the *Cybersecurity Ventures 2023 Report*. Insurers now recognize that standalone cyber policies are insufficient; bundling coverage with home and auto plans addresses gaps in liability, data breaches, and ransomware risks while improving customer retention. Cyber insurance is increasingly positioned as a **value-added service** rather than a standalone product. For instance, **State Farm’s "Cyber Liability" add-on** for homeowners covers identity theft recovery, extortion payments, and legal fees from data breaches linked to smart home devices. Similarly, **Progressive’s "Cyber Safety" program** for auto policies reimburses customers for hacked vehicle systems (e.g., keyless entry vulnerabilities) or stolen personal data from insurance claim filings. The **average premium for bundled cyber coverage** remains low (under **$20/year**), but insurers project a **15% annual growth rate** in adoption due to rising ransomware demands (e.g., the **2022 Colonial Pipeline attack**, which cost $4.4 million in ransom).Key Drivers of Demand for Bundled Cyber Insurance
The integration of cyber coverage into auto and home policies is driven by three primary factors: - **Connected Ecosystems**: Smart homes (e.g., **Amazon Alexa, Google Nest**) and autonomous vehicles rely on cloud-based systems vulnerable to exploits. A **2023 Ponemon Institute study** found that **45% of homeowners** with IoT devices experienced at least one cyber incident in the past year, up from 22% in 2020. - **Regulatory Pressures**: States like **California (SB-327)** and **New York (NY DFS Cybersecurity Regulation)** now mandate breach notifications for insurers, increasing liability exposure. Bundled cyber policies help insurers mitigate fines and reputational damage. - **Customer Expectations**: **72% of millennials** (a primary target demographic) expect insurers to offer cyber protection, per **J.D. Power’s 2023 Insurance Shopping Study**. Insurers like **Allstate** leverage this demand by promoting **"CyberSmart" bundles** that include identity theft monitoring.Challenges in Underwriting and Risk Assessment
Despite growth, underwriting cyber risks for bundled policies presents hurdles: - **Data Fragmentation**: Insurers lack standardized frameworks to assess a customer’s cyber hygiene (e.g., password strength, software updates). **Guidewire’s 2023 report** highlights that **60% of insurers** struggle to integrate cyber risk scores into underwriting models. - **Exclusion Ambiguities**: Policies often exclude **supply chain attacks** (e.g., SolarWinds breach) or **third-party vendor liabilities**, leading to disputes. For example, **Chubb’s 2022 cyber claim data** showed **30% of denied claims** stemmed from unclear exclusions. - **Affordability vs. Coverage Limits**: Low premiums correlate with **$1 million policy limits**, which may be insufficient for high-profile ransomware attacks (e.g., **2021 Kaseya attack: $70 million ransom**). Insurers are testing **tiered pricing** based on cybersecurity investments (e.g., discounts for customers using **Bitdefender or Norton**).Case Study: Auto Insurance and Vehicle Hacking Liability
Autonomous and semi-autonomous vehicles (e.g., **Tesla, Waymo, Ford BlueCruise**) introduce unique cyber risks. A **2023 MIT study** estimated that **by 2030, 80% of auto insurance claims** could involve cyber-related incidents, including: - **Remote Vehicle Takeovers**: Hackers exploiting **OBD-II port vulnerabilities** (e.g., **2015 Jeep Cherokee hack**) could lead to liability lawsuits against insurers for **physical damage or bodily injury**. - **Data Privacy Breaches**: Insurers collect **telematics data** (e.g., location, driving behavior) to adjust premiums. A breach (e.g., **2021 State Farm data leak**) could trigger **class-action lawsuits** under **GDPR or CCPA**, forcing insurers to offer bundled cyber coverage. - **Software Updates as Liability Triggers**: A faulty **over-the-air (OTA) update** (e.g., **2021 Toyota unintended acceleration flaw**) could shift blame to insurers if cyber policies don’t cover **software-related accidents**. Insurers like **Geico** are piloting **"CyberSafe Driving" add-ons** that cover: - **Ransomware payments** for hacked infotainment systems. - **Legal defense costs** for lawsuits arising from vehicle hacking. - **Reimbursement for stolen data** from insurance claim portals.Business Model and Market Positioning of AXA as a Global Auto Insurer
AXA, a French multinational insurance group, ranks among the world’s largest insurers with a diversified portfolio spanning auto, home, life, and health insurance. In the auto insurance sector, AXA combines a **multi-channel distribution strategy**, **risk-based underwriting**, and **digital transformation** to maintain a competitive edge. Its market positioning emphasizes **customer-centricity**, **global scalability**, and **innovative risk management**, allowing it to operate in over 60 countries while adapting to regional nuances. AXA’s auto insurance business model integrates **direct-to-consumer (D2C) sales**, **agent networks**, and **partnerships with digital platforms** (e.g., telematics providers, insurtech startups). The company leverages **big data analytics** for dynamic pricing, **AI-driven fraud detection**, and **personalized policy recommendations** to enhance efficiency and customer satisfaction.Revenue Streams and Pricing Strategy
AXA generates revenue through **premium income**, **investment returns**, and **ancillary services** (e.g., roadside assistance, usage-based insurance). Its pricing model employs: - **Risk-based tiering**: Policies are priced based on driver behavior, vehicle type, and geographic risk factors. - **Dynamic pricing**: Real-time adjustments using **telematics data** (e.g., mileage, braking patterns) to incentivize safe driving. - **Bundling**: Discounts for combining auto with home or life insurance policies, increasing cross-selling opportunities. AXA’s **global underwriting approach** ensures consistency while allowing local adaptations. For example, in **North America**, it focuses on **usage-based insurance (UBI)** via partnerships with **Allstate’s Drivewise** and **Milewise**, while in **Europe**, it emphasizes **comprehensive coverage** with add-ons like **legal protection** and **extended warranty**.Distribution Channels and Customer Acquisition
AXA employs a **hybrid distribution model** to balance digital efficiency with human touchpoints: - **Direct sales**: Online portals and mobile apps (e.g., AXA’s **AXA France** and **AXA USA** platforms) handle ~60% of new policies in mature markets. - **Agent networks**: Local agents in **emerging markets** (e.g., **India, Brazil**) provide personalized advice and claims support. - **Partnerships**: Collaborations with **car manufacturers** (e.g., **BMW, Renault**) and **insurtech firms** (e.g., **Lemonade, Root**) expand reach and enhance digital engagement. In **Asia-Pacific**, AXA’s **micro-insurance models** (e.g., **AXA Singapore’s** pay-as-you-go plans) cater to low-income drivers, while in **North America**, its **superagent programs** (e.g., **AXA’s "Agent of the Year"** incentives) drive agent productivity.Technology and Innovation in Risk Management
AXA invests heavily in **AI, IoT, and predictive analytics** to optimize underwriting and claims: - **AI underwriting**: Machine learning models (e.g., **AXA’s "AI Factory"**) assess risk in real-time, reducing manual processes by **40%** in some regions. - **Telematics integration**: Devices like **AXA’s "DriveSafe"** (partnered with **Otonomo**) track driving behavior to offer **discounts of up to 30%** for low-risk drivers. - **Blockchain for claims**: Pilot programs in **Switzerland and France** use blockchain to **automate fraud detection** and **accelerate payouts** by **20-25%**. - **Chatbots and virtual assistants**: **AXA’s "Aya"** (AI assistant) handles **~70% of basic customer queries**, reducing call center costs.Competitive Advantages and Market Share
AXA’s global auto insurance market share (2023 estimates): - **Europe**: ~5% (strong in **France, Italy, Spain**). - **North America**: ~3% (growing via **Allstate partnerships**). - **Asia-Pacific**: ~2% (expanding in **India, Southeast Asia**). Key differentiators include: - **Global scale with local agility**: Standardized underwriting frameworks with regional customization. - **Strong brand trust**: AXA ranks in the **top 10% for customer loyalty** in **Europe (J.D. Power, 2023)**. - **Sustainability focus**: **AXA’s "Paris Agreement Commitment"** includes **green underwriting** (e.g., discounts for electric vehicles). AXA’s **2025 strategy** prioritizes: - **Expanding UBI in the U.S.** (targeting **20% of auto policies**). - **Deepening insurtech collaborations** (e.g., **AXA Ventures** investments in **Neos, Shift Technology**). - **Regional dominance in Asia** via **joint ventures** (e.g., **AXA India’s tie-up with HDFC Ergo**).A Typical Day in the Life of an Auto Insurance Underwriter
Auto insurance underwriters evaluate risk, assess policy applications, and determine premiums while ensuring compliance with company policies and regulatory standards. Their daily workflow blends data analysis, communication with stakeholders, and adherence to underwriting guidelines to balance profitability with customer service. Tools like **Insurance Information Exchange (III) databases, credit scores, Motor Vehicle Reports (MVRs), and predictive analytics platforms** are central to their decision-making, alongside internal underwriting rules and actuarial models. **Core Responsibilities and Workflow** Underwriters begin their day by reviewing pending applications, claims, or policy renewals flagged for reassessment. Priority is often given to high-risk cases or those requiring expedited decisions to meet customer deadlines.Morning: Application and Policy Review
Underwriters start by pulling **Motor Vehicle Reports (MVRs)** from state databases to verify driving records, including violations, accidents, or license status. They cross-reference this with **credit-based insurance scores** (e.g., from Experian Auto or TransUnion) to assess financial responsibility, as studies show a correlation between credit history and claim frequency. **Example**: A driver with a recent DUI may trigger a manual underwriting review, while a clean record with a high credit score could qualify for an automated approval.Midday: Risk Assessment and Decision-Making
For applications requiring manual underwriting, underwriters analyze: - **Vehicle details** (make, model, year, safety ratings, anti-theft devices) using tools like **National Motor Vehicle Title Information System (NMVTIS)** to check for salvage titles or flood damage history. - **Usage patterns** (commute distance, primary driver age, annual mileage) to adjust risk profiles. - **Coverage requests** (liability limits, collision/comprehensive deductibles) against company underwriting limits. **Decision Matrix Example**:A 25-year-old driver with a 0.85 credit score and a 2018 Honda Civic (safety rating: "Good") applying for $100,000 bodily injury/$300,000 property damage coverage may receive: - **Automated approval** if no prior at-fault accidents. - **Conditional approval** with a higher premium if a minor moving violation exists in the last 3 years. - **Decline** if the MVR shows a recent reckless driving charge.Underwriters also review **renewals** for policyholders with updated risk factors (e.g., a teen learner added to the policy) and adjust premiums accordingly using **rate filings** submitted to state regulators.
Afternoon: Claims and Fraud Monitoring
Underwriters collaborate with claims adjusters to flag suspicious activity, such as: - **Inflated repair estimates** for total-loss vehicles. - **Multiple claims** from the same policyholder within a short period. - **Inconsistent timelines** between accident reports and claim submissions. Tools like **fraud detection algorithms** (e.g., LexisNexis Risk Solutions) and **geospatial analytics** help identify patterns. For instance, a claim filed for a "hit-and-run" in a low-traffic area may trigger a manual review.End of Day: Reporting and Compliance
Underwriters compile daily reports on: - **Approval/denial rates** to ensure alignment with company targets. - **Regulatory changes** (e.g., new state laws on distracted driving penalties) that may impact underwriting criteria. - **Training needs** for agents handling high-risk applications. They also participate in **peer reviews** to ensure consistency in underwriting decisions across teams. For example, if one underwriter frequently approves high-risk applicants while others deny similar cases, a calibration session may be scheduled to standardize practices. ---Unique Challenges and Opportunities in Auto Insurance for Emerging Economies (India, Brazil, and Beyond)
The auto insurance market in emerging economies presents a paradox: rapid motorization drives demand, yet underdeveloped infrastructure, regulatory complexities, and economic volatility create significant operational hurdles. While these markets offer untapped growth potential—with India’s auto insurance penetration at ~4.5% (vs. ~95% in the U.S.) and Brazil’s fleet expanding by 6% annually—insurers must navigate fragmented distribution networks, high claims fraud rates, and evolving consumer behaviors shaped by digital adoption and informal financing.*"In emerging markets, auto insurance is not just a risk transfer mechanism but a critical enabler of financial inclusion—bridging the gap between uninsured drivers and formalized protection."* — **McKinsey & Company, 2023**---
Challenges in Market Penetration and Distribution
Emerging economies face structural barriers that suppress insurance adoption, despite high accident fatality rates (e.g., India’s road deaths exceed **150,000 annually**, per WHO). Key obstacles include: - **Informal Vehicle Financing**: In Brazil, ~40% of cars are purchased through *leasing* or *informal credit*, often bypassing mandatory insurance requirements. Insurers must partner with banks and fintechs to embed coverage in loan agreements. - **Fragmented Distribution Channels**: India’s auto insurance relies heavily on **agent-based networks** (70% of policies), but rural penetration remains low due to literacy gaps and distrust of formal institutions. Digital-first insurers (e.g., **Acko, Digit**) leverage **WhatsApp-based agents** and **UPI payments** to bridge this divide. - **Low Awareness and Misunderstood Value**: Surveys reveal that **60% of Indian drivers** believe insurance is optional, despite legal mandates. Campaigns like **IRDAI’s "Insurance Sahi Hai"** (2021) used regional languages and celebrity endorsements to improve literacy.*"The top three reasons for non-purchase in India are: 1) Cost (45%), 2) Lack of awareness (30%), 3) Distrust in claims settlement (25%)."* — **IRDAI Annual Report, 2022**---
Regulatory and Compliance Hurdles
Emerging markets impose **unconventional regulatory demands** that reshape underwriting and claims processes. Examples include: - **Mandatory Third-Party Coverage with Variations**: - **India**: Requires **TPPL (Third-Party Property Liability)** with a **₹7.5 lakh** minimum limit, but **own-damage policies** are voluntary. Insurers must comply with **IRDAI’s Solvency II-like norms** while grappling with **underpriced TP premiums** (subsidized by the government). - **Brazil**: **DPVAT (Danos Pessoais causados por Veículos Automotores de via Terrestre)** mandates **R$1,200 (~$240) per vehicle** for bodily injury, funded via a **1% tax on fuel sales**. This distorts private insurers’ risk pools, as **80% of claims** are for medical expenses, not property damage. - **Dynamic Pricing Restrictions**: - Brazil’s **ANCORD (National Association of Private Insurers)** caps premium increases to **10% annually** to prevent market exploitation, forcing insurers to optimize **telematics-based discounts** within tight margins. - India’s **Motor Vehicles Act (2019)** allows **usage-based pricing** (e.g., **Pay-As-You-Drive** for commercial fleets) but lacks standardized data-sharing frameworks between insurers and **Aadhaar-linked KYC systems**. - **Fraud and Moral Hazard**: - **Brazil**: **Stage accidents** (e.g., "crash-for-cash") account for **30% of bodily injury claims**, with **Rio de Janeiro** and **São Paulo** hotspots. Insurers use **AI-driven video analytics** (e.g., **Allianz’s "ClaimSense"**) to detect anomalies in claim timings and medical reports. - **India**: **Ashram fraud** (fake accidents near temples) persists, with **Gujarat and Maharashtra** as epicenters. **IRDAI’s Fraud Detection Unit** mandates **biometric verification** for claimants and **GPS tracking** for recovery vehicles. ---Opportunities in Digital Transformation and Niche Segments
Emerging markets are fertile grounds for **innovative product designs** and **tech-driven efficiency gains**, particularly in: - **Microinsurance and Pay-Per-Use Models**: - **Brazil**: **Seguro Popular** (low-cost policies for low-income drivers) and **hourly rental insurance** (e.g., **Geico’s partnership with Uber**) target gig economy workers. - **India**: **Acko’s "Drive Safe" app** offers **real-time driving scores** with discounts up to **30%**, while **ICICI Lombard’s "Bike Safe"** bundles two-wheeler insurance with **mechanic cashless services**. - **Telematics and IoT Integration**: - **Brazil**: **Bradesco Seguros** uses **OBD-II devices** to monitor **hard braking/acceleration** and adjust premiums dynamically. **Penetration remains <5%**, but **fleet insurers** (e.g., **Volkswagen’s Caminhoneiro program**) adopt it for **logistics trucks**. - **India**: **Bajaj Allianz’s "DriveWise"** leverages **AI-powered dashcams** to auto-generate **first-notice-of-loss (FNOL)** reports, reducing **claim processing time by 40%**. - **Parametric Insurance for High-Risk Scenarios**: - **Brazil**: **Flood and landslide coverage** (e.g., **Mapfre’s "Seguro Desastre Natural"**) triggers payouts based on **government-declared disaster zones**, avoiding lengthy claim assessments. - **India**: **Monsoon-linked crop transport insurance** (e.g., **HDFC ERGO’s "Kisan Suraksha"**) covers **delayed deliveries** due to weather, critical for **perishable goods**. ---Economic and Socio-Political Risks
Macroeconomic instability and policy shifts create **operational volatility** for insurers: - **Currency Fluctuations**: - Brazil’s **real (BRL) depreciation** against the USD (2023: **-12%**) increases **reinsurance costs**, while **India’s rupee (INR) volatility** affects **foreign reinsurer partnerships** (e.g., **Swiss Re’s joint ventures**). - **Fuel Price Subsidies**: - India’s **subsidized diesel** (₹80/liter vs. global ₹100+) reduces **maintenance costs** but increases **accident severity** due to **overloaded vehicles**. - Brazil’s **ethanol blending mandates** (45% in gasoline) lower emissions but create **new risks** for **flex-fuel vehicle fleets**. - **Insolvency of Anchor Partners**: - **Brazil**: The collapse of **BMG Seguros (2020)** left **50,000 policyholders** stranded, prompting **ANCORD’s "Insurance Guarantee Fund"** reforms. - **India**: **Kingfisher Airlines’ bankruptcy (2012)** exposed **fleet insurers’ exposure to unpaid premiums**, leading to **IRDAI’s "Insurer Liability Pool"** for corporate defaults. ---Integration of Environmental, Social, and Governance (ESG) Criteria in Underwriting Decisions
Insurers are increasingly adopting **Environmental, Social, and Governance (ESG)** criteria as core factors in underwriting to align with sustainability goals, regulatory demands, and shifting customer expectations. ESG integration reduces long-term risks, enhances portfolio resilience, and supports insurers in meeting net-zero commitments while fostering trust with environmentally and socially conscious consumers. The shift reflects broader industry trends toward **impact investing** and **responsible risk management**, where insurers evaluate not just financial viability but also the **environmental footprint** and **social equity** of insured assets. The adoption of ESG in underwriting varies by region and risk type, with some insurers applying stricter criteria for high-exposure sectors (e.g., fossil fuels, deforestation) while others incentivize sustainable practices through premium adjustments. Data-driven underwriting models now incorporate **carbon emission scores**, **biodiversity risk assessments**, and **community impact metrics** to refine risk profiles. Regulatory pressures, such as the **EU Taxonomy for Sustainable Activities** and **Task Force on Climate-related Financial Disclosures (TCFD)**, further accelerate this transition, requiring insurers to disclose ESG-related risks and opportunities in their financial reporting. ---Environmental Criteria in Underwriting: Carbon Footprint and Climate Risk Assessments
Insurers are prioritizing **climate-related risks** by evaluating the **carbon intensity** of insured properties and vehicles. For example: - **Auto Insurance**: Underwriters may adjust premiums based on a vehicle’s **fuel efficiency**, **electric/hybrid status**, or **manufacturing emissions**. Insurers like **Allianz** and **AXA** offer discounts for low-emission vehicles, while **Lemonade** provides telematics-based pricing that rewards eco-friendly driving behaviors. - **Home Insurance**: Policies for properties with **solar panels**, **energy-efficient HVAC systems**, or **green building certifications** (e.g., LEED) often qualify for **premium reductions** of 5–15%. **State Farm** and **USAA** have programs that incentivize homeowners to adopt **smart thermostats** or **storm-resistant roofing** to mitigate wildfire and flood risks. - **Commercial Underwriting**: Insurers like **Chubb** and **Swiss Re** exclude or penalize businesses with high **Scope 1/2 emissions** or poor **water management practices**, particularly in drought-prone regions. Some require **climate risk disclosures** from insured entities as a condition for coverage. **Data Sources for Environmental Underwriting**: Insurers leverage **third-party ESG ratings** (e.g., MSCI ESG, Sustainalytics) and **satellite imagery** (e.g., **NASA FIRMS** for wildfire risk) to assess exposure. **AI-driven models** from firms like **Climate X** and **Risk Management Solutions (RMS)** simulate future climate scenarios to predict **asset depreciation** and **insurance payout volatility**. ---Social Criteria: Community Impact and Equity in Underwriting
Social factors in underwriting focus on **reducing systemic risks** and **promoting equitable access to insurance**. Key applications include: - **Affordable Housing Programs**: Insurers like **Liberty Mutual** and **Farmers Insurance** partner with **nonprofits** to offer **subsidized policies** for low-income households in high-risk areas, ensuring they are not priced out of coverage. **The Nature Conservancy** collaborates with **Allstate** to provide **flood insurance discounts** for homeowners who implement **natural flood barriers** (e.g., wetlands restoration). - **Workplace Safety Discounts**: Businesses with **certified safety programs** (e.g., OSHA compliance, **ISO 45001**) receive **lower workers’ compensation premiums**. **Travelers Insurance** offers **group discounts** to companies with **diversity and inclusion initiatives**, recognizing that socially responsible workplaces have lower turnover and liability risks. - **Disaster Resilience Initiatives**: In **hurricane-prone** areas, insurers like **Florida Citizens Property Insurance Corporation** fund **community hardening projects** (e.g., **hurricane-resistant retrofits**) in exchange for **premium reductions**. Similarly, **California’s FAIR Plan** partners with **Cal Fire** to subsidize **defensible space** clearings around homes to lower wildfire claims. **Challenges in Social Underwriting**: Balancing **profitability with equity** requires insurers to avoid **redlining** (denying coverage to marginalized communities) while ensuring **actuarially sound pricing**. Some critics argue that **low-income discounts** may inadvertently **undermine safety-net programs** if they reduce government subsidies. Insurers counter this by **bundling coverage** with **financial literacy programs** (e.g., **Progressive’s "Savings Bank"** for policyholders). ---Governance Criteria: Ethical Underwriting and Transparency
Governance in underwriting emphasizes **ethical risk assessment**, **data privacy**, and **stakeholder accountability**. Insurers are adopting: - **Anti-Corruption Clauses**: Policies for **government contracts** or **high-risk industries** (e.g., mining, construction) now include **ESG compliance requirements**, such as adherence to the **UN Global Compact** or **OECD Anti-Bribery Guidelines**. **AIG** and **Zurich Insurance** have **exclusionary clauses** for entities linked to **modern slavery** or **environmental crimes**. - **Cybersecurity Governance**: With **ransomware attacks** rising, insurers like **Chubb** and **Hiscox** require **cyber insurance applicants** to demonstrate **governance frameworks** (e.g., **NIST CSF, ISO 27001**) before approval. Poor governance (e.g., **lack of multi-factor authentication**) can lead to **higher premiums or coverage denials**. - **Transparency in Pricing Algorithms**: Regulators (e.g., **UK’s FCA, EU’s GDPR**) demand **explainable AI** in underwriting to prevent **discriminatory pricing**. Insurers like **Lemonade** publish **open-source risk models** to build trust, while **State Farm** uses **community advisory boards** to review pricing adjustments in underserved areas. **Ethical Dilemmas in Governance**: - **Data Exploitation**: Insurers must avoid **surveillance capitalism** by ensuring **consent-based data collection** (e.g., **telematics for auto insurance**). - **Greenwashing Risks**: Overstating ESG commitments can **damage credibility**. **AXA** faced backlash in 2021 for **contradictory policies** (funding fossil fuels while promoting green initiatives), leading to stricter **ESG exclusion lists**. - **Conflict of Interest**: Insurers investing in **renewable energy projects** must disclose potential **conflicts** if they also underwrite **fossil fuel assets**. ---Case Study: AXA’s ESG-Linked Underwriting Framework
AXA, a global insurer, implemented a **three-tier ESG underwriting approach**: 1. **Exclusions**: No coverage for **coal mining**, **deforestation-linked agriculture**, or **illegal fishing**. 2. **Incentives**: **20% discounts** for **electric vehicles** and **10% for homes with solar panels**. 3. **Partnerships**: Collaborates with **The Nature Conservancy** to fund **coastal erosion mitigation** in **Miami**, reducing flood risks for policyholders. **Impact**: - **€1.5 billion** in **green bonds** issued to finance **climate-resilient infrastructure**. - **15% reduction** in **carbon-intensive portfolio exposure** since 2015. - **Customer retention** increased by **8%** in markets where ESG discounts were promoted. ---Blockquote: The Role of Insurers in Sustainable Urban Development
Insurers are **architects of resilient cities** by embedding **risk mitigation** into urban planning. Through **premium incentives for green infrastructure**, **disaster-proofing subsidies**, and **community-based resilience programs**, they reduce **systemic vulnerabilities** while creating **economic value**. Sustainable urban development relies on insurers to: - **Decarbonize transportation** via **EV incentives** and **public transit partnerships**. - **Future-proof housing** with **flood-resistant designs** and **wildfire-defense zoning**. - **Foster circular economies** by underwriting **recycling initiatives** and **renewable energy microgrids**. The most innovative insurers treat **urban sustainability** not as a cost center but as a **growth engine**, aligning financial returns with **long-term societal benefits**.
The auto and home insurance industries are undergoing a transformation driven by digital disruption, regulatory shifts, and the growing influence of climate and cyber risks. As insurers leverage AI, IoT, and usage-based pricing to refine underwriting, they must also address equity gaps and fraud while fostering transparency to retain customers in a crowded market. The future belongs to those who balance innovation with ethical practices, ensuring coverage remains accessible, adaptive, and aligned with global challenges—from autonomous vehicles to sustainable urban development. By understanding these trends, stakeholders can navigate the evolving landscape with confidence, positioning themselves at the forefront of a more resilient and customer-centric insurance ecosystem.

Frequently Asked Questions
What types of coverage do auto insurance policies typically include?
Auto insurance policies usually cover **liability** (bodily injury/property damage), **collision** (vehicle repair/replacement), **comprehensive** (theft/vandalism/nature damage), **personal injury protection (PIP)**, and **uninsured/underinsured motorist**. Optional add-ons include roadside assistance and gap coverage.
How do home insurance policies differ based on customer demographics?
Young homeowners often prioritize **affordability** and **renters insurance**, while families focus on **liability** and **personal property coverage**. High-net-worth individuals seek **umbrella policies** and **art/collectibles endorsements**. Seniors may opt for **senior-specific discounts** or **medical payment coverage**.
What are common red flags indicating auto insurance fraud?
Red flags include **staged accidents**, **exaggerated injuries**, **fake witnesses**, **unexplained gaps in claims history**, and **vehicles with inconsistent damage patterns**. Insurers use **AI analytics** and **telematics data** to detect suspicious patterns during claims processing.
How is technology like AI and telematics changing home insurance?
AI **automates claims processing**, **personalizes premiums** via smart home data, and **detects fraud**. Telematics (e.g., **smart sensors**) monitor home security, water leaks, or fire risks in real-time, offering **discounts for proactive risk mitigation** and **faster payouts** for covered events.
What regulations must auto and home insurers comply with in the U.S.?
Insurers must adhere to **state-specific laws** (e.g., **no-fault vs. tort systems** for auto), **NAIC model regulations**, **data privacy laws** (e.g., **CCPA, GDPR for global operations**), **anti-discrimination rules** (e.g., **Fair Credit Reporting Act**), and **solvency requirements** set by state departments of insurance.
Why do some insurers offer discounts for bundling auto and home policies?
Bundling reduces **operational costs** for insurers by streamlining customer service and underwriting. It also **lowers administrative overhead** and **encourages policy retention**. Customers typically save **10–25%** by combining policies, while insurers gain **cross-selling opportunities** and **longer customer relationships**.
Related articles
Auto Home Insurance Exploring Global Trends Coverage And Future
Discover global trends in Auto Home Insurance, from evolving coverage options to future outlook. Learn how policies adapt to risks, technology, and…
Smart Ways to Compare Auto and Home Insurance Quotes
Save money and get the best coverage with Smart Ways to Compare Auto and Home Insurance Quotes—learn how to evaluate rates, coverage limits, and…

Finding Auto Home Insurance Near Me Explained Clearly
Finding Auto Home Insurance Near Me Explained Clearly: Discover how to compare quotes, check coverage options, and save on bundled policies for your car…

Auto Home Insurance Unveiled Global Trends Tech And Future
Discover the latest Auto Home Insurance Unveiled Global Trends Tech And Future, from AI-driven claims to smart home policies reshaping coverage worldwide.

Auto Insurance Car Insurance Explained Simply
Understand Auto Insurance & Car Insurance Explained Simply—coverage types, costs, and how policies protect drivers. Get clear answers on liability,…
