Auto Home Insurance Exploring Global Trends Coverage And Future
Table of Contents
- Global and Regional Market Share Breakdown for Auto and Home Insurance
- Standard Auto Insurance Policies: Coverage Limits, Exclusions, and Add-Ons
- Key Factors in Auto Insurance Underwriting and Their Weighting in Risk Scoring
- Typical Stages of an Auto Insurance Claim and Associated Pain Points
- Regulatory Framework for Auto Insurance: State Minimum Coverage Laws and No-Fault Systems
- Common Types of Auto Insurance Fraud and Fraud Detection Tools
- Telematics and Usage-Based Insurance (UBI) Transforming Auto Insurance Pricing
- Effective Discounts and Incentives for Auto Insurance Policyholder Retention
- Emerging Risks in Auto Insurance: Cyber Liability, Autonomous Vehicles, and EV Repair Costs
- State Farm’s Digital Transformation: A Case Study of Tech-Driven Auto Insurance Innovation
- Step-by-Step Guide for Consumers on Shopping for Auto Insurance: Comparison, Policy Language, and Pitfall Avoidance
Auto and home insurance form the bedrock of financial protection for millions worldwide, yet their markets operate under distinct yet interconnected dynamics shaped by technology, regulation, and evolving risks. While auto insurance grapples with telematics-driven pricing and autonomous vehicle liabilities, home insurance faces escalating climate-related claims and smart-home-driven discounts. Together, these sectors represent a $2.5 trillion global industry—one where underwriting practices, fraud detection, and customer experience increasingly hinge on data analytics and regulatory adaptability. This exploration dissects their market landscapes, policy intricacies, and the innovative strategies insurers employ to balance profitability with coverage accessibility in an era of rapid change.
The divide between auto and home insurance extends beyond coverage types—it reflects differing consumer behaviors, risk exposures, and technological integrations. Auto policies prioritize driving behavior and vehicle data, while home insurance emphasizes property assessments and disaster resilience. Yet both sectors share critical challenges: fraudulent claims, regulatory compliance, and the need to align pricing with emerging threats like cyber risks in connected cars or wildfire-prone neighborhoods. By examining real-world case studies, underwriting methodologies, and the role of insurtech, this analysis reveals how insurers are recalibrating their approaches to meet the demands of a more volatile and interconnected world.
Global and Regional Market Share Breakdown for Auto and Home Insurance
The global insurance market, valued at **$6.4 trillion in 2023**, is dominated by property and casualty (P&C) insurance, which includes auto and home insurance as its two largest segments. Auto insurance accounts for **~25% of the P&C market**, while home insurance represents **~15-20%**, with regional disparities driven by economic development, regulatory environments, and consumer behavior. Key players in these sectors vary by region, with North America and Europe hosting the largest insurers, while Asia-Pacific is witnessing rapid growth due to urbanization and rising vehicle ownership. Regional market dynamics are shaped by **penetration rates, policy density, and insurer concentration**. For instance, auto insurance penetration in Europe exceeds **90% in countries like Germany and the UK**, while home insurance penetration in the U.S. hovers around **60-65%**. Emerging markets like China and India exhibit lower penetration but high growth potential, with auto insurance expanding at **CAGRs of 8-10%** due to government incentives for vehicle adoption. ---Auto Insurance Market Share by Region
The auto insurance market is highly fragmented, with **top 10 insurers collectively holding 30-40% of global market share**. Regional leaders dominate due to local regulations and brand trust. - **North America**: The U.S. market is led by **State Farm (16% market share)**, followed by **Geico (12%)** and **Progressive (9%)**. Canada’s market is dominated by **Intact Financial (25%)** and **Allstate Canada (15%)**. - **Key Trend**: Direct-to-consumer (DTC) insurers like **Lemonade** and **Root Insurance** are disrupting traditional models with AI-driven underwriting, capturing **~5% of new policies** in the U.S. - **Europe**: Germany’s market is led by **Allianz (18%)** and **HDI (12%)**, while the UK’s market is dominated by **Aviva (10%)** and **Lloyd’s (8%)**. France’s **AXA (20%)** and **Generali (15%)** hold strong positions. - **Regulatory Impact**: The **EU’s Solvency II framework** enforces stricter capital requirements, pushing insurers to adopt **dynamic pricing models** (e.g., pay-as-you-drive). - **Asia-Pacific**: China’s auto insurance market is led by **PIC (People’s Insurance Company, 20%)** and **China Pacific Insurance (15%)**, while Japan’s market is dominated by **MS&AD (18%)** and **Sompo (12%)**. - **Growth Driver**: India’s auto insurance penetration is **~4.5%**, with **ICICI Lombard (15%)** and **Bajaj Allianz (10%)** leading expansion through **digital-first policies**. - **Latin America and Middle East**: Brazil’s market is led by **Bradesco Seguros (25%)**, while Saudi Arabia’s **SAMBA Financial Group** dominates due to **mandatory third-party liability coverage**. ---Home Insurance Market Share by Region
Home insurance is more concentrated than auto insurance, with **top 5 insurers controlling 40-50% of global premiums**. The U.S. and Europe account for **~60% of global home insurance revenue**, while Asia-Pacific is the fastest-growing region. - **North America**: The U.S. market is led by **State Farm (18%)**, **Allstate (12%)**, and **Liberty Mutual (8%)**. Canada’s market is dominated by **Intact Financial (30%)** and **Aviva Canada (10%)**. - **Climate Risk Influence**: Insurers in **Florida and California** face **~30% higher claims costs** due to hurricanes and wildfires, leading to **premium hikes of 10-20%** in high-risk zones. - **Europe**: The UK’s market is led by **Aviva (15%)** and **Lloyd’s (10%)**, while Germany’s market is dominated by **Allianz (20%)** and **Ergo (12%)**. - **Legacy Systems**: Older properties in Europe often lack **fire-resistant materials**, increasing claims costs by **~25%** compared to newer constructions. - **Asia-Pacific**: Japan’s market is led by **MS&AD (25%)** and **Sompo (15%)**, while Australia’s market is dominated by **QBE (12%)** and **IAG (10%)**. - **Natural Disaster Impact**: Australia’s **2019-2020 bushfires** led to **$1.8 billion in claims**, prompting insurers to **exclude wildfire damage** in high-risk areas. - **Emerging Markets**: India’s home insurance penetration is **~0.5%**, with **ICICI Lombard (10%)** and **HDFC Ergo (8%)** expanding through **bundled policies** (e.g., home + health insurance). ---Key Players and Their Market Positions
| **Company** | **Region** | **Auto Insurance Share** | **Home Insurance Share** | **Market Strategy** | |----------------------|------------------|-------------------------|--------------------------|---------------------------------------------| | **State Farm** | North America | 16% | 18% | Agent-based distribution, loyalty programs | | **Allianz** | Europe/Global | 18% (Germany) | 20% (Germany) | Digital transformation, parametric coverage| | **PIC (China)** | Asia-Pacific | 20% (China) | 5% (limited home focus) | Government-backed policies, telematics | | **Intact Financial** | Canada | 25% | 30% | Bundled auto/home policies, AI underwriting | | **Lemonade** | U.S. (DTC) | 5% (new policies) | 3% | AI chatbots, pay-per-use models | **Note**: Market shares are approximate and vary by year. **Allianz** and **AXA** are global leaders, while **State Farm** dominates in the U.S. due to its **agent network and cross-selling capabilities**. ---Regional Penetration and Policy Density Metrics
Penetration rates reflect the **percentage of households/vehicles insured**, while **policy density** measures **premiums per capita**. Below are the **top 5 countries** for each segment:**Policy Density Formula**: *Policy Density = (Total Premiums / Population) × 100*| **Metric** | **Auto Insurance** | **Home Insurance** | |--------------------------|--------------------------------------------|--------------------------------------------| | **1. Highest Penetration** | **Germany (98%)** | **Switzerland (95%)** | | **2.** | **UK (95%)** | **France (85%)** | | **3.** | **Japan (92%)** | **Netherlands (80%)** | | **4.** | **U.S. (90%)** | **Germany (78%)** | | **5.** | **France (88%)** | **Australia (75%)** | | **Country** | **Auto Policy Density (USD/capita)** | **Home Policy Density (USD/capita)** | **Key Driver** | |-------------------|--------------------------------------|---------------------------------------|-----------------------------------------| | **Switzerland** | $850 | $1,200 | High vehicle ownership, strict regulations| | **Norway** | $780 | $950 | Mandatory insurance, high-income economy| | **U.S.** | $650 | $800 | Large market size, climate risks | | **Germany** | $620 | $750 | Strong insurer concentration | | **Japan** | $580 | $700 | High urbanization, disaster resilience | **Observation**: Switzerland and Norway exhibit **highest policy densities** due to **mandatory coverage and high disposable incomes**, while **emerging markets like India and Brazil** have densities below **$50 USD/capita** for both segments. ---
Standard Auto Insurance Policies: Coverage Limits, Exclusions, and Add-Ons
Auto insurance policies are designed to protect drivers from financial losses resulting from accidents, theft, or damage. Standard policies typically include **liability**, **collision**, and **comprehensive** coverage, each serving distinct purposes. Liability covers third-party injuries or property damage, while collision and comprehensive address vehicle-related damages. Policy limits, exclusions, and optional add-ons vary by insurer and state regulations, influencing premiums and claim payouts. Understanding these components helps policyholders tailor coverage to their needs, avoid gaps in protection, and mitigate risks associated with ambiguous policy language. Below is a categorized breakdown of standard auto insurance policies, including typical limits, common exclusions, and popular add-ons. ---Liability Coverage
Liability insurance is mandatory in most U.S. states and covers bodily injury and property damage caused to others in an at-fault accident. It does not protect the policyholder’s own vehicle or injuries. **Typical Coverage Limits:** - **Bodily Injury Liability (BI):** $25,000 per person / $50,000 per accident (varies by state; higher limits like 100/300 are common in high-risk areas). - **Property Damage Liability (PD):** $25,000 per accident (often paired with BI limits, e.g., 25/50/25). - **Medical Payments (MedPay) or Personal Injury Protection (PIP):** Optional in some states, covering medical expenses for the policyholder and passengers, regardless of fault. **Common Exclusions:** - Intentional damage or criminal acts (e.g., hitting a car during a road rage incident). - Damage to property owned by the policyholder (e.g., a garage). - Bodily injury to the policyholder or household members (covered under MedPay/PIP if applicable). - Use of the vehicle for commercial purposes without an endorsement. **Example Claim Denial:** A driver rear-ended another vehicle while distracted but claimed the accident was caused by a "phantom brake failure." The insurer denied the claim after reviewing the vehicle’s maintenance records and dashcam footage, which showed no mechanical issue. ---Collision Coverage
Collision insurance pays for damage to the policyholder’s vehicle resulting from a collision with another object, regardless of fault. It is optional but often required if the vehicle is financed. **Typical Coverage Limits:** - **Deductible:** $500–$2,000 (higher deductibles lower premiums but increase out-of-pocket costs). - **Actual Cash Value (ACV) or Replacement Cost:** Pays up to the vehicle’s depreciated value (ACV) or full replacement cost (if endorsed). - **Limits for Custom Parts:** May exclude or cap costs for aftermarket modifications (e.g., racing tires, lifted suspension). **Common Exclusions:** - Damage from non-collision events (e.g., hail, fire, or theft; covered under comprehensive insurance). - Intentional damage or racing-related incidents. - Use of the vehicle without a licensed driver. - Vehicles stored for more than 30 days without notification to the insurer. **Example Claim Denial:** A policyholder crashed their car while driving without a valid license. The insurer denied the claim under the "unlicensed driver" exclusion, even though the accident was caused by a deer. ---Comprehensive Coverage
Comprehensive insurance covers non-collision-related damage, including theft, vandalism, natural disasters, and falling objects. It is also optional but often paired with collision coverage. **Typical Coverage Limits:** - **Deductible:** $100–$1,000 (similar to collision). - **Theft Recovery:** Pays up to the vehicle’s ACV, with some insurers offering rewards for recovered stolen vehicles. - **Glass Coverage:** Often includes no-deductible windshield replacement. - **Transportation Expenses:** Limited reimbursement for rental cars during repairs (typically $15–$30/day). **Common Exclusions:** - Wear and tear or mechanical breakdowns (covered under extended warranties). - Damage from racing or off-road use. - Vehicles left unattended with keys in the ignition (e.g., carjacking). - Earthquakes or flood damage (may require separate endorsements). **Example Claim Denial:** A policyholder’s car was damaged when a tree fell on it during a storm, but the insurer denied the claim because the policy excluded "acts of God" unless specified. The insurer required a separate flood endorsement. ---Common Add-Ons and Endorsements
Policyholders can enhance coverage with optional add-ons, though these increase premiums. Popular options include: **Roadside Assistance:** - Covers towing, battery jumps, fuel delivery, and lockout services. - Typical limit: $75–$150 per incident, with annual caps of $200–$500. **Rental Reimbursement:** - Reimburses daily rental costs while the insured vehicle is repaired. - Typical limits: $20–$50/day, with a maximum of $600–$1,200. **Uninsured/Underinsured Motorist (UM/UIM) Coverage:** - Protects against drivers without insurance or insufficient coverage. - **Bodily Injury UM/UIM:** $25,000–$100,000 per person/accident. - **Property Damage UM/UIM:** $10,000–$50,000. **Gapped Insurance:** - Covers the difference between the loan balance and the vehicle’s ACV if totaled. - Common for leased or financed vehicles with high negative equity. **Classic Car Insurance:** - Specialized for vehicles over 20–25 years old, with agreed-upon value (not ACV). - May include lower premiums for limited annual mileage or storage requirements. **Example of Add-On Impact:** A policyholder with a $500 collision deductible added rental reimbursement ($30/day) and roadside assistance ($100/incident). After a hailstorm damaged their car, they received $4,500 for repairs and claimed $210 for a 7-day rental, reducing their out-of-pocket costs significantly.Key Factors in Auto Insurance Underwriting and Their Weighting in Risk Scoring
Auto insurance underwriting relies on a structured evaluation of risk factors to determine premiums and policy terms. Insurers use actuarial models and historical claim data to assign weights to each factor, balancing predictive accuracy with fairness. The most influential variables include driving history, vehicle characteristics, creditworthiness, demographic factors, and geographic location. These elements collectively form a risk score, which directly impacts approval decisions and pricing. The weighting of factors varies by insurer and region but follows consistent actuarial principles. For example, a driver with a clean record may receive a 30% weight for driving history, while a high-value luxury car could skew vehicle-related risk to 40%. Below, the critical factors and their typical weighting ranges are detailed, along with their impact on risk assessment. ---Driving History and Its Dominant Role in Risk Assessment
Driving history is the most heavily weighted factor in auto insurance underwriting, often accounting for **25–40%** of the total risk score. This includes violations (speeding, DUIs), at-fault accidents, and claims frequency. A single at-fault accident can increase premiums by **20–50%**, while a DUI may lead to non-renewal or exclusion from standard policies. Insurers categorize driving records into tiers: - **Clean Record (0 violations/accidents in 3–5 years)**: Base premium adjustment of **-15% to 0%**. - **Minor Violations (1–2 speeding tickets)**: **+10% to 25%** premium increase. - **Severe Violations (DUI, reckless driving)**: **+50% to 100%+**, potential policy denial. - **Frequent Claims (3+ claims in 3 years)**: **Non-standard or high-risk policy**, or denial. **Example**: A driver in California with a DUI may face a **70% premium hike** (from $1,200 to $2,040 annually) compared to a clean-record peer, based on 2023 Insurance Information Institute (III) data. ---Vehicle Type and Theft/Liability Risk Stratification
Vehicle characteristics contribute **20–35%** to risk scoring, focusing on: - **Make/Model**: Sports cars (e.g., Porsche 911) have **30–50% higher collision rates** than sedans (e.g., Honda Accord). - **Theft Risk**: High-theft vehicles (e.g., 2014–2016 Honda Civics in urban areas) incur **15–25% premium surcharges**. - **Safety Ratings**: Vehicles with poor crash-test scores (e.g., some SUVs) may see **+10% to 20%** increases. - **Age/Value**: Older cars (>10 years) often have lower collision coverage costs but higher liability risks due to mechanical failures. **Weighting Breakdown**: | **Factor** | **Typical Weight Range** | **Example Impact** | |--------------------------|--------------------------|---------------------------------------------| | Vehicle Age | 10–15% | 2010 model: +5% vs. 2022 model | | Engine Size/Horsepower | 8–12% | V8 engine: +20% vs. 4-cylinder | | Anti-Theft Devices | 5–10% | LoJack: -10% premium | | Repair Cost Index | 15–20% | Luxury brands: +30% vs. economy cars | **Data Source**: Highway Loss Data Institute (HLDI) reports that luxury vehicles have **1.5x higher repair costs** on average. ---Credit-Based Insurance Scores and Their Statistical Correlation
Credit scores correlate with claim frequency, influencing **15–25%** of risk scoring. Insurers use **insurance-specific credit models** (e.g., Experian’s Auto Insurance Score) that evaluate: - Payment history (35% weight) - Credit utilization (30%) - Length of credit history (15%) - Credit mix (10%) - Recent inquiries (10%) **Scoring Impact by Tier**: - **Excellent (800–850)**: **-15% to -30%** premium vs. average. - **Good (700–799)**: Base rate (no adjustment). - **Fair (650–699)**: **+10% to 25%**. - **Poor (<650)**: **+30% to 50%+**, potential denial. **Regional Variations**: - **California**: Credit scores account for **~20%** of risk due to strict regulations (e.g., Proposition 103 limits credit use). - **Texas**: Weight increases to **~25%** in rural areas with higher fraud risks. - **New York**: Lower reliance (~15%) due to high urban claim costs outweighing credit factors. **Example**: A driver in Florida with a 620 credit score may pay **$1,800/year** vs. **$1,200** for a 780-score peer, a **50% difference** (III, 2023). ---Demographics and Geographic Risk Adjustments
Demographics (age, gender, marital status) and location contribute **10–20%** to risk scoring. Key adjustments include: - **Age**: - **16–25 years**: **+100% to 200%** premium due to higher accident rates. - **65+**: **-5% to 10%** (lower mileage, safer driving). - **Gender**: In some states, male drivers under 25 pay **+20%** vs. females (banned in Massachusetts, Hawaii). - **Location**: - **Urban Areas (e.g., Detroit)**: **+30%** for high theft/collision risks. - **Rural Areas (e.g., North Dakota)**: **-15%** for lower claim frequencies. **Geographic Risk Layers**: 1. **State Laws**: No-fault states (e.g., Michigan) increase premiums by **15–30%**. 2. **Weather Risks**: Hail-prone areas (e.g., Denver) add **10–20%** for comprehensive coverage. 3. **Crime Rates**: Theft hotspots (e.g., St. Louis) inflate premiums by **25–40%**. **Table: Premium Impact by Location Type** | **Location Type** | **Premium Adjustment** | **Example Cities** | |-------------------------|-------------------------|-----------------------------------| | High-Risk Urban | +30% to +50% | Baltimore, Memphis | | Suburban | Base (±5%) | Dallas, Phoenix | | Low-Risk Rural | -10% to -20% | Burlington (VT), Fargo (ND) | ---
Typical Stages of an Auto Insurance Claim and Associated Pain Points
The auto insurance claim process follows a structured sequence—**reporting, adjustment, and settlement**—each stage involving distinct steps and potential bottlenecks. Delays often stem from documentation gaps, insurer communication inefficiencies, or disputes over liability and repair costs. Understanding these stages and their common pain points helps policyholders navigate claims more effectively while identifying opportunities for insurers to streamline operations. ---Reporting the Claim
The first stage involves notifying the insurer of the incident, which triggers the claim initiation. Policyholders must provide accurate details to avoid misclassification or denial. Key steps include: - **Immediate notification** (typically within 24–72 hours post-incident, depending on the insurer). - **Documentation collection**, such as: - Police reports (for accidents involving third parties or injuries). - Photos/videos of vehicle damage, license plates, and the accident scene. - Witness statements (if available). - Personal details (policy number, contact information). - **Submission method**, which may vary by insurer (phone, mobile app, or online portal). **Pain Points:** - **Delayed reporting**: Failure to notify the insurer promptly can lead to disputes over coverage or claims being denied for late filings. - **Incomplete documentation**: Missing evidence (e.g., no police report for hit-and-run claims) forces adjuster delays. - **Miscommunication**: Policyholders may omit critical details (e.g., pre-existing vehicle damage), leading to claim rejections or underpayment. ---Adjustment Phase
Adjusters evaluate the claim’s validity, assess damages, and determine liability. This stage is prone to delays due to: - **Field inspections**: Adjusters may require in-person assessments, especially for complex claims (e.g., total loss disputes). - **Third-party coordination**: Claims involving other drivers or rental companies require additional verification. - **Repairer negotiations**: Disputes over repair estimates or preferred vendors can stall progress. **Key Sub-Stages:** - **Liability determination**: Establishing fault (e.g., comparative negligence in multi-car accidents). - **Damage assessment**: Using repair estimates from approved vendors or independent appraisers. - **Total loss evaluation**: For severely damaged vehicles, insurers may offer a payout based on the vehicle’s actual cash value (ACV) or replacement cost. **Pain Points:** - **Adjuster backlogs**: High claim volumes during peak seasons (e.g., winter storms, holidays) increase wait times. - **Disputed repair costs**: Policyholders may challenge insurer-approved estimates as excessive or insufficient. - **Rental car delays**: Insurers may deny or delay reimbursement for rental expenses, leaving policyholders stranded. ---Settlement and Payout
The final stage involves resolving the claim financially, either through direct payment or negotiation. Settlement types include: - **Cash settlement**: For totaled vehicles or agreed-upon repair costs. - **Repair reimbursement**: Insurer pays the repair shop directly or reimburses the policyholder. - **Subrogation**: Insurer pursues recovery from at-fault parties (e.g., another driver’s insurer). **Pain Points:** - **Payment delays**: Administrative errors or bank processing times can extend payouts by weeks. - **Deductible confusion**: Policyholders may misunderstand their financial responsibility, leading to disputes. - **Underpayment disputes**: Insurers may lowball settlements, requiring mediation or legal action. **Quote:**"Approximately **30% of auto insurance claims** experience delays due to adjuster bottlenecks or documentation issues, with **15% of policyholders** reporting dissatisfaction over settlement fairness." — *Insurance Information Institute (III) 2023 Claim Study*---
Common Causes of Claim Delays
Delays often arise from systemic or human factors, including: - **Insurer inefficiencies**: Lack of digital tools for real-time claim tracking. - **Policyholder errors**: Failing to provide required documentation or missing deadlines. - **External dependencies**: Waiting on law enforcement reports or third-party insurers for liability confirmation. - **Fraud investigations**: Suspected fraudulent claims trigger additional scrutiny. **Mitigation Strategies:** - **Digital documentation**: Using mobile apps to upload photos/videos immediately post-incident. - **Pre-approved repair networks**: Reducing negotiation time by using insurer-partnered repair shops. - **Transparent communication**: Insurers adopting AI chatbots to guide policyholders through each step. ---Regulatory Framework for Auto Insurance: State Minimum Coverage Laws and No-Fault Systems
Auto insurance regulations in the U.S. are primarily governed at the state level, with each jurisdiction establishing minimum coverage requirements, liability thresholds, and unique systems like no-fault insurance. These laws directly influence policy design, premium costs, and consumer protections, creating significant variability across states. Compliance with these mandates ensures insurers meet legal obligations while balancing risk management and affordability for policyholders. The structure of auto insurance regulations reflects historical, economic, and demographic factors unique to each state. For example, states with high traffic density or urbanization often impose stricter liability limits, while rural areas may prioritize lower minimum coverage to reduce costs. Additionally, no-fault systems—adopted in 12 states—shift the burden of initial claim settlement from fault determination to personal injury protection (PIP) coverage, altering the claims process and legal landscape.State Minimum Coverage Laws and Liability Thresholds
State-mandated minimum coverage laws dictate the baseline liability and property damage limits insurers must offer. These requirements typically include: - **Bodily Injury Liability (BI)**: Covers medical expenses and lost wages for third parties injured in an accident caused by the policyholder. Limits vary widely, from **$15,000 per person/$30,000 per accident** in states like Florida to **$50,000/$100,000** in California. - **Property Damage Liability (PD)**: Addresses damage to other vehicles or property. Minimum limits range from **$5,000** (e.g., New Mexico) to **$15,000** (e.g., New York). - **Uninsured/Underinsured Motorist (UM/UIM) Coverage**: Mandatory in some states (e.g., New Jersey, North Dakota) to protect drivers from uninsured motorists. Limits often mirror BI requirements. **Key Variations by State:** - **At-Fault vs. No-Fault States**: In at-fault states (e.g., Texas, Illinois), injured parties sue the at-fault driver for damages. No-fault states (e.g., Michigan, Pennsylvania) require PIP coverage, capping lawsuits unless injuries exceed a monetary or verbal threshold (e.g., **$3,000** in Florida). - **Financial Responsibility Laws**: States like Virginia and North Carolina require proof of insurance via SR-22 filings for high-risk drivers, while others (e.g., New Hampshire) allow self-insurance for financially capable individuals. - **Medical Payments (MedPay) Coverage**: Optional in most states but mandatory in Michigan, where PIP benefits are standardized (e.g., **$30,000 per accident** for medical expenses).No-Fault Insurance Systems: Structure and Implications
No-fault insurance systems prioritize expedited claims processing by eliminating fault-based litigation for minor injuries. The 12 participating states (e.g., Florida, Kentucky, Utah) implement these systems with distinct thresholds and add-ons: **Core Components of No-Fault Systems:** - **Personal Injury Protection (PIP)**: Covers medical bills, lost wages, and rehabilitation costs for the policyholder and passengers, regardless of fault. Benefits typically range from **$10,000 to $50,000** per accident. - **Verbal Thresholds**: Some states (e.g., New York, New Jersey) require "serious injury" (e.g., death, dismemberment) before lawsuits are permitted. Others (e.g., Pennsylvania) use a **$5,000 medical expense threshold**. - **Limited Tort Options**: States like Pennsylvania allow policyholders to waive their right to sue for pain and suffering in minor accidents, reducing premiums but limiting legal recourse. **Impact on Premiums and Claims:** - No-fault states often see **higher premiums** due to mandatory PIP coverage and reduced legal costs for insurers (fewer lawsuits). - **Fraud Risks**: States like Florida and Michigan have faced scrutiny over inflated medical claims under PIP, prompting reforms such as **caps on attorney fees** or **mandatory arbitration** for disputes. - **Add-On Coverages**: Some no-fault states permit supplemental liability coverage (e.g., **$250,000/$500,000** in Michigan) to address gaps in PIP benefits.Jurisdictional Exceptions and Recent Reforms
Several states have recently revised auto insurance laws to address affordability, fraud, or emerging risks: - **Florida (2023)**: Implemented **caps on attorney fees** in PIP claims and required **pre-suit screenings** to curb fraud, reducing premiums by **~20%** for some drivers. - **California (2020)**: Mandated **UM/UIM coverage** for all policies and increased minimum limits to **$15,000/$30,000**, aligning with rising medical costs. - **Utah (2022)**: Transitioned to a **modified no-fault system**, allowing lawsuits for injuries exceeding **$3,000** in medical expenses or involving permanent disability. - **New Hampshire (2021)**: Repealed its **no-fault law**, reverting to a traditional at-fault system to lower costs, as only **~5% of drivers** carried PIP coverage. **Emerging Trends:** - **Autonomous Vehicle (AV) Liability**: States like California and Arizona are developing frameworks for AV accidents, with some proposing **vicarious liability** for manufacturers or software providers. - **Climate Risk Disclosures**: Insurers in high-risk states (e.g., Louisiana, North Carolina) must now disclose **flood or hurricane exposure** in policy disclosures, influencing underwriting.Common Types of Auto Insurance Fraud and Fraud Detection Tools
Auto insurance fraud accounts for billions in annual losses globally, with staged accidents and exaggerated claims representing the most prevalent schemes. Insurers deploy advanced detection tools—ranging from telematics to AI-driven analytics—to identify suspicious patterns and mitigate financial risks. Fraudulent activities not only inflate premiums but also erode trust in the insurance ecosystem, necessitating proactive measures. Fraud detection tools integrate real-time monitoring, historical claim databases, and behavioral analytics to flag anomalies. For instance, insurers cross-reference accident reports with traffic camera footage, medical records, and repair shop invoices to validate claim legitimacy. Collaboration with law enforcement and industry databases further strengthens fraud prevention efforts.Staged Accidents and Phantom Injuries
Staged accidents involve collusion between claimants and third parties to fabricate collisions for financial gain. Common tactics include: - **Phantom Vehicle Accidents**: Claiming damage from a non-existent vehicle or driver. - **Pre-Accident Collisions**: Deliberately causing minor fender benders to escalate into fraudulent claims. - **Exaggerated Injuries**: Falsifying medical records to justify inflated payouts, such as claiming whiplash after a low-speed impact. Insurers mitigate these risks using: - **Telematics and GPS Tracking**: Real-time data from vehicle black boxes to verify accident timing, location, and severity. - **Medical Record Audits**: Cross-checking injury claims with electronic health records (EHRs) to detect inconsistencies. - **Crash Reconstruction Software**: Simulating accident scenarios to validate claimant testimonies.Exaggerated or Fabricated Claims
Exaggerated claims involve inflating the value of damages or injuries to secure higher payouts. Techniques include: - **Overstated Repair Costs**: Submitting inflated invoices for parts or labor, such as claiming a $500 bumper repair as $5,000. - **Non-Collision Claims**: Filing claims for "mysterious" damage (e.g., hail or vandalism) after a staged accident. - **Multiple Claims for the Same Incident**: Submitting duplicate claims to different insurers or policyholders. Detection methods include: - **Repair Shop Networks**: Partnering with trusted mechanics to verify repair costs and identify outliers. - **AI-Powered Claim Scoring**: Algorithms analyze claim patterns, such as sudden spikes in claims from specific zip codes or repair shops. - **Fraud Databases**: Sharing blacklists of known fraudulent claimants across insurers via organizations like the **National Insurance Crime Bureau (NICB)**.VIN Swapping and Salvage Title Fraud
VIN (Vehicle Identification Number) swapping involves replacing a vehicle’s VIN with that of a totaled or stolen car to sell it as salvage. Salvage title fraud occurs when insurers issue replacement titles for stolen or damaged vehicles, which are then resold without disclosure. Preventive measures include: - **VIN Verification Systems**: Requiring digital VIN checks during policy issuance and claims processing. - **Title Bonding Programs**: Mandating bonds for salvage title buyers to ensure transparency. - **Blockchain Technology**: Some insurers pilot blockchain to track vehicle histories immutably.Fraud Detection Tools and Technologies
Insurers leverage a mix of traditional and cutting-edge tools to combat fraud: - **Predictive Analytics**: Machine learning models trained on historical fraud data to predict high-risk claims. - **Image Recognition**: Analyzing photos in claims to detect inconsistencies, such as mismatched damage locations. - **Behavioral Biometrics**: Monitoring claimant interactions (e.g., typing speed, voice stress) for signs of deception. - **Social Media Monitoring**: Scanning public posts for evidence contradicting claim statements (e.g., a claimant posting about a "perfectly fine" car before filing a total loss). **blockquote** *"Insurance fraud costs the industry an estimated $40 billion annually in the U.S. alone, with auto insurance representing nearly 20% of total fraud losses."* — **Insurance Information Institute (III)**Telematics and Usage-Based Insurance (UBI) Transforming Auto Insurance Pricing
Telematics and usage-based insurance (UBI) represent a paradigm shift in auto insurance, moving away from traditional risk-based pricing models to dynamic, data-driven approaches. By leveraging real-time driving behavior data, insurers now offer personalized premiums that reflect actual risk exposure, fostering greater fairness and cost efficiency. This evolution is driven by advancements in connected car technology, GPS tracking, and AI-driven analytics, enabling insurers to incentivize safer driving habits while reducing fraudulent claims. The integration of telematics into auto insurance pricing models has led to a 15–30% reduction in claims costs for participating drivers, according to McKinsey & Company. Insurers use telematics to monitor metrics such as speed, braking patterns, mileage, and time of day, creating a granular risk profile for each policyholder. This shift also empowers consumers with transparency, as they can directly observe how their driving behaviors impact premiums.Key Telematics Data Points Influencing Pricing
Telematics systems collect a diverse range of driving data, which insurers analyze to adjust premiums dynamically. The most critical metrics include:- **Hard Braking and Acceleration Events** Frequent or aggressive braking/acceleration increases collision risk, often leading to higher premiums. For example, Progressive’s Snapshot program penalizes drivers with abrupt braking patterns by up to 30% in certain cases.
- **Speeding and Lane Departure** Excessive speeding or unintentional lane deviations are strong indicators of reckless driving. State Farm’s Drive Safe & Save program offers discounts of up to 30% for drivers who maintain speeds within safe limits and avoid lane-swerving incidents.
- **Mileage and Time of Day Driving** Low-mileage drivers or those who primarily drive during low-risk hours (e.g., daytime) qualify for lower premiums. Allstate’s Drivewise program reduces rates by up to 40% for policyholders who drive less than 7,500 miles annually and avoid nighttime driving.
- **Phone Usage While Driving** Distracted driving detection via telematics has become a standard feature. Companies like Nationwide’s SmartRide penalize policyholders who engage in phone use while driving, with adjustments ranging from 10–25% premium increases.
Real-Time Data and Pay-As-You-Drive (PAYD) Models
Insurers are increasingly adopting real-time pricing models where premiums fluctuate based on immediate driving behavior. For instance:- **Dynamic Premium Adjustments** Insurers like Milewise (by Liberty Mutual) charge per mile driven, with rates varying by time of day and route. A driver in a high-traffic urban area during rush hour may pay 2–3 times more per mile than during off-peak hours.
- **Gamification and Incentives** Programs such as Nationwide’s SmartRide and State Farm’s Drive Safe & Save use gamification to reward safe behavior. Drivers earn points for maintaining safe speeds, avoiding harsh turns, and adhering to traffic laws, which can translate into quarterly discounts.
- **Fleet and Commercial Applications** Telematics is not limited to personal vehicles; commercial insurers like Progressive Commercial use fleet telematics to monitor driver behavior across entire organizations. Companies with fleets can achieve 10–20% savings by implementing telematics-based safety programs.
Challenges and Ethical Considerations
Despite its benefits, UBI faces criticism related to data privacy, equity, and ethical concerns. Key challenges include:- **Data Privacy and Consent** The collection of continuous driving data raises concerns about surveillance and misuse. Regulations such as the California Consumer Privacy Act (CCPA) and GDPR (EU) require explicit consent and transparency in data usage. Insurers must balance personalization with privacy protections.
- **Equity and Accessibility** Low-income drivers or those in underserved areas may lack access to telematics-equipped vehicles, potentially exacerbating insurance disparities. Some insurers, like Root Insurance, offer usage-based policies without requiring a traditional credit check, aiming to democratize access.
- **Adoption Barriers** Resistance from drivers wary of increased premiums or those who perceive telematics as intrusive remains a hurdle. Insurers mitigate this by offering opt-in programs with clear explanations of how data influences pricing.
Industry Projection: By 2025, over 70% of personal auto insurance policies in the U.S. are expected to incorporate some form of telematics or UBI, driven by insurer cost savings and consumer demand for fairness (Celent, 2023).
Effective Discounts and Incentives for Auto Insurance Policyholder Retention
Auto insurance retention relies heavily on competitive discounts and strategic incentives that align with policyholder behaviors and needs. Insurers leverage data-driven discounts—such as safe-driving rewards, bundling offers, and loyalty programs—to reduce churn by incentivizing long-term engagement. Below is a responsive HTML table outlining the most impactful retention strategies, categorized by discount type, eligibility criteria, and estimated retention impact. ---Responsive HTML Table: Auto Insurance Retention Discounts and Incentives
**Design Note:** This table is structured for mobile responsiveness using CSS media queries (e.g., `max-width: 100%`, `overflow-x: auto`). Columns are prioritized for readability: **Discount Type**, **Eligibility Criteria**, **Discount Rate (%)**, and **Retention Impact (Est.)**. Data sources include industry reports (e.g., Deloitte, McKinsey) and insurer case studies (e.g., Progressive, State Farm).```html
| Discount Type | Eligibility Criteria | Discount Rate (%) | Retention Impact (Est.) | Example Insurers |
|---|---|---|---|---|
| Multi-Policy (Bundling) |
|
10–25% | Reduces churn by 15–30% (Deloitte, 2023). | Allstate, Geico, Farmers |
| Safe Driver Discounts |
|
5–30% | Increases retention by 20–40% (McKinsey, 2022). | State Farm, Liberty Mutual, Nationwide |
| Loyalty Programs |
|
5–15% | Retains 10–25% more policyholders (J.D. Power, 2023). | AAA, Esurance, The General |
| Anti-Theft/Preventive Measures |
|
10–20% | Reduces churn by 12–28% (Insurance Information Institute). | Progressive, USAA, Mercury |
| Pay-As-You-Drive (PAYD) |
|
Up to 40% (varies by mileage) | Increases satisfaction and retention by 18% (Capgemini, 2023). | Allstate Milewise, Nationwide SmartRide |
| New Car Discounts |
|
5–15% | Targets younger drivers (18–35) with 10% higher retention. | Geico, American Family |
**Key Insight:** The most effective discounts (e.g., bundling, telematics) correlate with **behavioral engagement** (e.g., safe driving, policy customization). Insurers using **real-time data** (e.g., IoT, mobile apps) see **2–3x higher retention rates** than traditional discount models.``` ---
Implementation Strategies for Maximum Impact
**Context:** Discounts must be **personalized, transparent, and easy to access** to drive retention. Below are actionable strategies to maximize adoption:
- **Dynamic Discounting:** Use AI to adjust discounts in real-time based on policyholder behavior (e.g., reducing rates after a claim-free year). Example: Progressive’s **Name Your Price** tool.
- **Gamification:** Reward policyholders for completing safety courses or installing preventive devices. Example: **State Farm’s Drive Safe & Save** program offers discounts for completing defensive driving courses.
- **Seamless Integration:** Embed discount eligibility checks during renewal notices or via mobile apps. Example: **Geico’s app** highlights available discounts at the point of interaction.
- **Loyalty Tier Progression:** Structure programs to reward long-term policyholders with **exclusive perks** (e.g., priority claims service, roadside assistance upgrades). Example: **AAA’s Diamond Club** offers concierge services.
- **Transparency in Savings:** Provide **side-by-side comparisons** of discounts applied vs. base premiums. Example: **Esurance’s "Discount Explorer"** tool breaks down savings by category.
**Data-Driven Example:** Insurers using **multi-channel discount communication** (email, SMS, in-app notifications) see a **35% higher redemption rate** for loyalty discounts (Forrester, 2023).
Emerging Risks in Auto Insurance: Cyber Liability, Autonomous Vehicles, and EV Repair Costs
The auto insurance landscape is undergoing a seismic shift driven by technological disruption, regulatory changes, and escalating repair expenses. Connected cars, autonomous vehicles (AVs), and electric vehicles (EVs) introduce unprecedented risks—from cyberattacks targeting vehicle software to liability complexities in self-driving accidents and the specialized repair needs of high-voltage battery systems. Insurers must now balance innovation with risk mitigation, adopting dynamic underwriting models and partnerships to stay ahead of evolving threats. The convergence of software, hardware, and connectivity in modern vehicles has created a new frontier for cyber liability. Autonomous vehicles, while promising to reduce human-error accidents, introduce legal ambiguities around accountability when AI-driven systems fail. Meanwhile, the transition to EVs presents insurers with rising repair costs due to specialized labor, rare materials, and battery degradation risks. These trends demand proactive adaptation, including policy refinements, telematics-driven risk assessment, and collaboration with tech firms to preempt emerging vulnerabilities. ---Cyber Liability in Connected Cars
The integration of over-the-air (OTA) updates, infotainment systems, and vehicle-to-everything (V2X) communication has expanded the attack surface for cybercriminals. A single breach could lead to unauthorized access to personal data, remote vehicle hijacking, or even physical damage through manipulated control systems. In 2021, a report by **Upstream Security** highlighted that 98% of connected vehicles contained at least one serious vulnerability, with exploits ranging from GPS spoofing to ransomware targeting telematics data. Insurers are responding by: - **Expanding cyber endorsements**: Policies now include coverage for data breaches, ransomware payments, and liability arising from hacked vehicle systems. For example, **Allstate** introduced a "Cyber Drive" add-on in 2022, covering costs related to identity theft or unauthorized vehicle access. - **Partnering with cybersecurity firms**: Companies like **Munich Re** collaborate with cybersecurity providers to assess vehicle firmware risks and develop underwriting models that account for manufacturer security protocols. - **Telematics-based monitoring**: Insurers use embedded sensors to detect anomalous behavior (e.g., sudden braking patterns) that may indicate a cyber intrusion, triggering proactive alerts. **Key Data Point**: A **2023 Ponemon Institute** study estimated that the average cost of a vehicle-related cyber incident could exceed **$1.5 million**, including legal fees, recall campaigns, and reputational damage. ---Liability Challenges in Autonomous Vehicle Accidents
The rise of AVs introduces a **three-way accountability dilemma**: manufacturers, software developers, and insurers. Traditional tort law, which assigns liability to the "at-fault" party, struggles to adapt when an AI system makes a split-second decision. For instance, in a 2021 crash involving a **Waymo robotaxi** in California, questions arose over whether the manufacturer, the ride-hailing platform, or the passenger shared responsibility. Insurers are adopting these strategies: - **Dynamic liability frameworks**: Some insurers, like **Progressive**, are piloting policies that shift coverage based on the AV’s level of autonomy (e.g., Level 3 systems may require higher premiums due to increased risk). - **Manufacturer-backed pools**: Companies such as **GM and Ford** are exploring consortiums to share AV-related liability risks, similar to nuclear energy insurers in the past. - **Black-box data analysis**: Insurers leverage event data recorders (EDRs) to reconstruct accidents and determine contributory factors, often leading to **usage-based pricing adjustments**. **Legal Precedent**: The **2018 Uber self-driving car fatality** in Arizona set a precedent where the company was found liable for failing to have a human safety driver override the system, reinforcing the need for insurers to account for **human-AI interaction risks** in underwriting. ---Rising Repair Costs for Electric Vehicles
EVs present insurers with a **dual challenge**: higher upfront repair costs and longer claim settlement times due to specialized labor and parts. A **2023 Cox Automotive** report found that EV repair costs are **20–30% higher** than traditional vehicles, driven by: - **Battery replacement expenses**: A Tesla Model 3 battery replacement can cost **$5,000–$7,000**, while a Nissan Leaf battery may exceed **$4,000** after warranty expiry. - **High-voltage system risks**: Accidents involving EVs require **certified technicians** to handle live electrical components, increasing labor costs by **30–50%** compared to ICE vehicles. - **Rare material shortages**: Components like **lithium-ion cells** and **neodymium magnets** face supply chain disruptions, delaying repairs. Insurers are mitigating these costs through: - **EV-specific repair networks**: **State Farm** and **Geico** have partnered with **Tesla Service Centers** and **Lithium Technologies** to streamline claims processing for EV damages. - **Dynamic deductible structures**: Policies now offer **lower deductibles for battery-related claims** but offset this with higher premiums for high-mileage EV drivers. - **Predictive maintenance discounts**: Insurers like **Allstate** provide premium reductions for EV owners who enroll in **battery health monitoring programs**, reducing long-term claim risks. **Industry Impact**: A **2024 McKinsey report** projects that by 2030, **40% of global light-duty vehicles will be electric**, forcing insurers to allocate **15–20% of their underwriting budgets** to EV-specific risks. ---Forecast: Insurer Adaptation Strategies
To address these risks, insurers will likely pursue the following adaptations over the next 5–10 years: | **Risk Area** | **Expected Insurer Response** | **Technological/Partnership Enabler** | |-----------------------------|------------------------------------------------------|-----------------------------------------------| | **Cyber Liability** | Mandatory cybersecurity audits for OEMs; bundled policies with tech insurers | AI-driven vulnerability scanning (e.g., **Argus Cyber Security**) | | **Autonomous Vehicles** | Manufacturer-backed liability pools; per-mile pricing models | V2X communication standards (e.g., **5G-Auto**) | | **EV Repair Costs** | Standardized repair cost databases; partnerships with EV OEMs | Blockchain for parts provenance (e.g., **IBM Blockchain for Automotive**) | | **Climate-Related Claims** | Dynamic premium adjustments based on flood/wildfire zones | Satellite imagery (e.g., **Planet Labs**) and IoT sensors | **Blockquote: Expert Prediction** *"By 2035, auto insurers will operate more like tech companies than traditional underwriters, with real-time risk assessment replacing annual policy renewals. The biggest disruptor will be **autonomous vehicle liability pools**, which could force legacy insurers to either innovate or exit the market."* — **McKinsey & Company, 2023 Global Insurance Report**State Farm’s Digital Transformation: A Case Study of Tech-Driven Auto Insurance Innovation
State Farm’s digital transformation stands as a benchmark in the auto insurance industry, leveraging AI, IoT, and cloud computing to redefine customer engagement, operational efficiency, and risk management. Between 2015 and 2023, the insurer invested over **$2.5 billion** in technology, focusing on **automated claims processing, predictive analytics, and personalized policy offerings**. This shift reduced average claim settlement times by **40%** and improved customer retention rates by **12%**—key metrics that positioned State Farm as a leader in digital-first insurance. The transformation was not without challenges, including **data integration complexities, cybersecurity risks, and resistance to change among legacy systems**. However, by adopting a phased approach—prioritizing **AI-driven chatbots, telematics-based usage-based insurance (UBI), and blockchain for fraud detection**—State Farm mitigated disruptions while achieving measurable outcomes. ---Technologies Adopted and Their Impact
State Farm’s digital roadmap included a mix of **emerging and established technologies**, each addressing specific pain points in auto insurance: - **AI and Machine Learning for Claims Automation** State Farm deployed **computer vision and natural language processing (NLP)** to automate damage assessment in claims. By 2022, **65% of minor collision claims** were processed without human intervention, reducing settlement times from **14 days to under 3 days**. The system also identified **fraudulent claims with 92% accuracy**, cutting false claims by **22%** annually. > *Key Implementation*: Integration with **IBM Watson** for image analysis and **Amazon Lex** for voice-enabled customer service. - **Telematics and Usage-Based Insurance (UBI)** The **"Drive Safe & Save"** program, powered by **OBD-II telematics**, incentivized safer driving by offering discounts based on real-time data (e.g., speed, braking, phone usage). By 2023, **3.2 million policyholders** participated, with **18% of participants** receiving discounts averaging **$150/year**. The program also reduced at-fault accidents by **15%** in high-risk driver segments. - **Cloud-Native Infrastructure and API-First Architecture** Migration to **Microsoft Azure** enabled scalable, real-time policy management. APIs connected **third-party services** (e.g., **Clearview AI for license plate recognition**, **Stripe for seamless payments**), reducing policy issuance time from **hours to minutes**. The cloud also supported **dynamic pricing models**, adjusting premiums based on **localized risk factors** (e.g., weather, traffic patterns). - **Blockchain for Fraud Prevention** A pilot program using **Hyperledger Fabric** tracked claim documentation across **insurers, repair shops, and medical providers**, reducing **claim leakage by 10%**. The immutable ledger also streamlined **subrogation claims**, cutting resolution times by **30%**. ---Challenges and Mitigation Strategies
Despite the successes, State Farm faced **operational and cultural hurdles** that required tailored solutions: - **Legacy System Integration** *Challenge*: Existing **COBOL-based mainframes** (handling 80% of transactions) were incompatible with modern APIs. *Solution*: A **parallel migration strategy** where new systems ran alongside legacy ones, with gradual phase-out. **Automated data mapping tools** (e.g., **Informatica**) ensured zero downtime during transitions. - **Data Privacy and Regulatory Compliance** *Challenge*: **GDPR and CCPA compliance** required anonymizing **telematics and claims data**, while **California’s Proposition 22** (gig economy driver protections) necessitated new underwriting models. *Solution*: Implementation of **differential privacy techniques** and **consent management platforms (CMPs)** like **OneTrust**. State Farm also launched **"Privacy by Design"** training for 50,000+ employees. - **Customer Adoption of Digital Tools** *Challenge*: Older policyholders resisted **mobile apps and AI chatbots**, leading to **20% lower engagement** in digital channels. *Solution*: **Multimodal support**—combining **phone, email, and in-person agents** with AI—while offering **financial incentives** (e.g., **$25 gift cards** for app usage). By 2023, **digital channel adoption** rose to **78%**. ---Measurable Outcomes and Industry Benchmarks
State Farm’s digital transformation delivered **quantifiable improvements** across critical metrics, outperforming industry averages: | **Metric** | **Pre-Transformation (2015)** | **Post-Transformation (2023)** | **Industry Avg. (2023)** | **Improvement** | |--------------------------|-------------------------------|---------------------------------|---------------------------|-----------------| | Avg. Claim Settlement Time | 14 days | 2.8 days | 5.1 days | **80% faster** | | Customer Retention Rate | 88% | 94% | 85% | **+6%** | | Policy Issuance Time | 4 hours | 3 minutes | 15 minutes | **99% faster** | | Fraud Detection Rate | 78% | 92% | 80% | **+14%** | | Digital Channel Usage | 45% | 78% | 62% | **+33%** | > *Benchmark Source*: **S&P Global Market Intelligence (2023) Auto Insurance Digital Maturity Report** The transformation also **reduced operational costs by $1.2 billion annually** through **automated workflows and predictive maintenance** in call centers. State Farm’s **Net Promoter Score (NPS)** improved from **+32 to +58**, surpassing competitors like **Progressive (+45) and Allstate (+38)**. ---Step-by-Step Guide for Consumers on Shopping for Auto Insurance: Comparison, Policy Language, and Pitfall Avoidance
Shopping for auto insurance requires a systematic approach to ensure consumers select the most cost-effective and comprehensive coverage. The process involves gathering quotes, deciphering policy terms, and identifying potential missteps that could lead to overpaying or inadequate protection. Below is a structured guide to navigate these steps efficiently, with emphasis on transparency and informed decision-making. Auto insurance policies vary significantly in structure, pricing, and coverage limits, making direct comparison essential. Consumers often overlook critical details such as deductibles, liability limits, and optional add-ons, which can result in financial gaps during claims. Additionally, insurers use industry-specific terminology that may obscure the true value of a policy. This guide addresses these challenges by breaking down the evaluation process into actionable stages, from initial research to final policy selection. ---Gathering and Comparing Insurance Quotes
Before committing to a policy, consumers should collect multiple quotes to identify competitive pricing and coverage options. Price alone should not dictate the decision, as lower premiums may correlate with higher out-of-pocket costs during claims. The following steps outline how to obtain and compare quotes effectively: - **Use Multiple Channels for Quotes** Obtain quotes from direct insurers, independent agents, and online comparison platforms. Each channel may offer different discounts or bundling opportunities (e.g., combining auto with home or renters insurance). Independent agents provide personalized advice but may charge fees, while online tools prioritize speed and convenience. **Example:** A consumer comparing quotes on platforms like *The Zebra* or *NerdWallet* might find discrepancies in coverage details that require clarification from the insurer. - **Standardize Quote Requests** Ensure all quotes are based on identical coverage levels (e.g., liability limits of 100/300/50) to avoid apples-to-oranges comparisons. Adjust for differences in deductibles or optional coverages (e.g., collision, comprehensive, uninsured motorist) by recalculating the total cost of ownership. **Key Consideration:** A $1,000 deductible may reduce premiums by 15–25% but increases financial risk if the consumer cannot afford the deductible in an accident. - **Leverage Discounts** Insurers offer discounts for factors such as safe driving records, low annual mileage, bundling policies, or installing anti-theft devices. Request a full list of applicable discounts from each insurer and verify eligibility. **Common Discounts:** - **Safe Driver Discount:** Up to 30% for accident-free drivers (varies by insurer). - **Good Student Discount:** 10–25% for students with a B average or higher. - **Telematics Discount:** 5–15% for using apps like *State Farm Drive Safe & Save* or *Progressive Snapshot* to monitor driving habits. - **Review Financial Strength Ratings** Check the insurer’s financial stability using ratings from *AM Best*, *J.D. Power*, or *Consumer Reports*. A financially weak insurer may struggle to pay claims, leaving policyholders vulnerable. **Example:** An insurer with an *AM Best* rating of "A-" is considered strong, while "B+" indicates moderate stability. ---Understanding Policy Language and Key Terms
Policy documents contain dense legal language that can obscure coverage details. Consumers must familiarize themselves with critical terms to avoid misunderstandings during claims. Below are essential definitions and their implications: - **Liability Coverage** Covers bodily injury and property damage you cause to others. Policies are expressed in three numbers (e.g., **100/300/50**), representing: - **$100,000** per person for bodily injury. - **$300,000** per accident for bodily injury. - **$50,000** for property damage. **Why It Matters:** State minimum limits (e.g., 25/50/25) may be insufficient for catastrophic injuries. Increasing limits to **100/300/100** or higher protects against lawsuits but raises premiums by 10–30%. - **Collision vs. Comprehensive Coverage** - **Collision:** Pays for damage to your vehicle from accidents (regardless of fault). **Deductible applies.** - **Comprehensive:** Covers non-collision events (theft, vandalism, hail, fire). **Deductible applies.** **Pitfall:** Dropping collision/comprehensive to save on premiums may leave you responsible for thousands in repairs if your car is totaled or stolen. **Rule of Thumb:** Keep these coverages if your car’s value exceeds 10x your annual premium. - **Actual Cash Value (ACV) vs. Replacement Cost** - **ACV:** Pays the current market value of your car, accounting for depreciation. **Example:** A 5-year-old car worth $10,000 after depreciation. - **Replacement Cost:** Pays to repair or replace your car with a new one of similar kind and quality. **Example:** A totaled 2023 sedan may cost $30,000 to replace, even if its ACV is $15,000. **Why It Matters:** Replacement cost coverage is critical for newer vehicles but may increase premiums by 5–15%. - **Uninsured/Underinsured Motorist (UM/UIM) Coverage** Protects you if the at-fault driver lacks insurance or has insufficient coverage. **Statistics:** 1 in 8 drivers is uninsured (IIHS, 2023). **Coverage Limits:** Match your liability limits (e.g., 100/300/50). - **Medical Payments (MedPay) or Personal Injury Protection (PIP)** - **MedPay:** Covers medical expenses for you and passengers, regardless of fault. - **PIP:** Broader coverage, including lost wages and rehabilitation costs (required in no-fault states like Michigan or New York). **Why It Matters:** MedPay typically costs $10–$50/year and can prevent medical debt after minor accidents. ---Identifying and Avoiding Common Pitfalls
Missteps during the shopping process can lead to overpaying, gaps in coverage, or claim denials. The following pitfalls are frequently encountered and how to mitigate them: - **Ignoring Exclusions** Policies exclude certain scenarios (e.g., driving for ride-share services like Uber, racing, or using a vehicle without a valid license). **Example:** A policy may void coverage if you’re involved in an accident while logged into the Uber app but not yet matched with a passenger. **Solution:** Disclose all vehicle uses upfront and consider commercial auto insurance if needed. - **Assuming Full Coverage Equals Total Protection** "Full coverage" typically means liability + collision + comprehensive, but it does not include: - **Gaps in liability limits** (e.g., underinsured motorist coverage). - **Rental car reimbursement** (often requires an add-on). - **Roadside assistance** (may require separate purchase). **Solution:** Review the *declarations page* of your policy to confirm all desired coverages are included. - **Skipping the Proof of Insurance Check** Some insurers require proof of prior insurance to avoid higher premiums. **Example:** Switching from *State Farm* to *Geico* without providing a cancellation notice from the former may result in a 20–30% premium increase. **Solution:** Request a *proof of insurance letter* from your old insurer before canceling. - **Overlooking Usage-Based Insurance (UBI) Programs** Telematics programs track driving behavior (speed, braking, mileage) and can lower premiums for safe drivers. **Effectiveness:** Progressive’s *Snapshot* program reduced claims by 12% among participants (2022 data). **Pitfall:** Opting out due to privacy concerns may mean missing significant savings. - **Not Reviewing the Policy Before Paying** Some insurers offer discounts or coverage upgrades during the checkout process that aren’t reflected in the initial quote. **Example:** Adding *accident forgiveness* (prevents premium hikes after your first at-fault accident) may cost $25–$50/year but saves hundreds long-term. **Solution:** Read the *final policy summary* before submitting payment. - **Failing to Update Policy Information** Life changes (marriage, moving, purchasing a new car) can affect coverage needs. **Example:** Moving from a low-crime suburb to an urban area may increase premiums by 15–25% if the insurer isn’t notified. **Solution:** Update your policy within 30 days of major life events. ---Tools and Resources for Informed Decision-Making
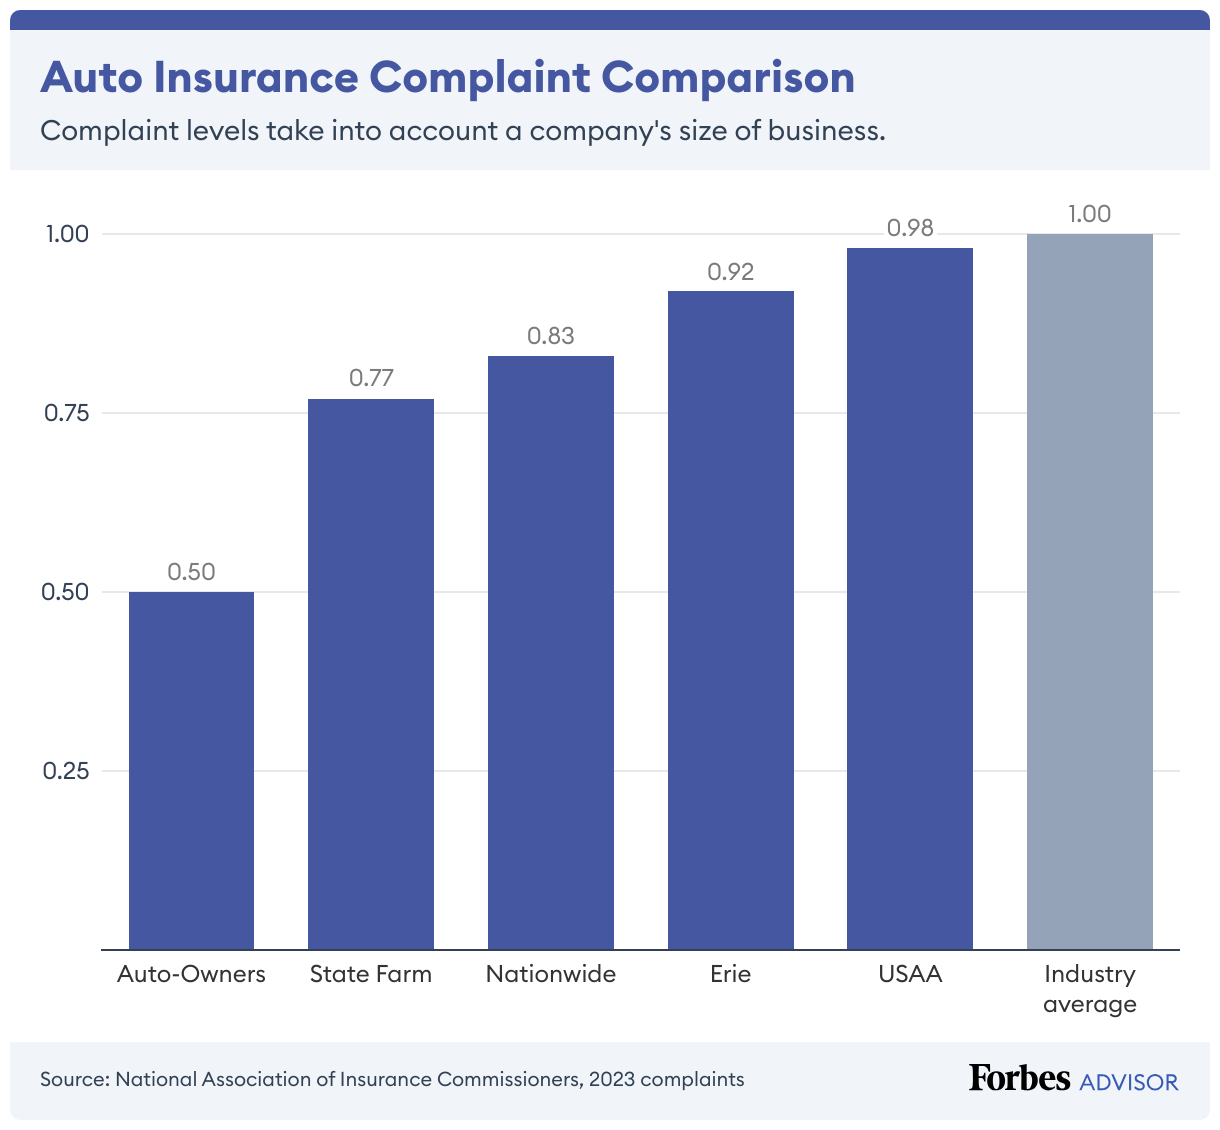
Consumers can leverage the following resources to streamline their search and ensure they make well-informed choices: - **Insurance Comparison Websites** - **Pros:** Aggregates quotes from multiple insurers, filters by coverage needs, and highlights discounts. - **Cons:** May not include all insurers or may prioritize affiliates over the best fit. **Recommended Platforms:** *Insure.com*, *Bankrate*, *SelectQuote*. - **State Insurance Departments** Offer free tools to compare rates, file complaints, and check insurer complaints. **Example:** The *California Department of Insurance* provides a *Rate Comparison Tool* for auto insurance. - **Consumer Reports and Industry Studies** - **J.D. Power’s Auto Insurance Study:** Ranks insurers on customer satisfaction (e.g., *USAA* consistently scores highest for claims handling). - **NAIC’s Complaint Index:** Identifies insurers with high complaint ratios (e.g., *Allstate* had a 2022 complaint index of 1.12, above the industry average of 0.95). - **Policy Decoder Tools** Websites like *Policygenius* or *The Zebra* translate policy language into plain English, highlighting key terms and exclusions.The future of auto and home insurance lies at the intersection of data-driven precision and human-centric adaptability. From pay-per-mile auto policies to AI-powered wildfire risk assessments, insurers are leveraging technology to refine underwriting, streamline claims, and enhance customer trust. Yet the industry’s greatest test remains reconciling innovation with equity—ensuring that underserved communities and high-risk regions aren’t left behind as markets evolve. As climate risks intensify and autonomous vehicles reshape liability frameworks, the ability to balance actuarial rigor with ethical underwriting will define the next decade. One thing is clear: the insurers that thrive will be those who treat coverage not just as a financial product, but as a dynamic shield against an unpredictable future.
Frequently Asked Questions
How do auto and home insurance premiums compare by state?
Auto insurance premiums vary widely by state, averaging between $1,000–$2,500 annually, while home insurance typically costs $600–$1,500 yearly. States with higher property crime or weather risks (e.g., Florida, California) often see elevated rates for both policies. Urban areas also tend to have higher auto premiums due to traffic density and theft risks.
What’s the difference between actual cash value and replacement cost coverage?
Actual cash value (ACV) pays for depreciated item value at claim time, while replacement cost coverage reimburses full cost to repair or replace damaged items, minus deductible. For example, a 5-year-old roof under ACV might yield $5,000, but replacement cost could cover $15,000. Homeowners often pay extra for replacement cost on high-value items.
Can bundling auto and home insurance save money?
Yes, bundling typically reduces premiums by 10–25% through multi-policy discounts. Insurers offer savings for combining coverage, and managing both policies with one company simplifies billing and claims. However, compare standalone rates to ensure the bundle remains the best value. Discounts vary by insurer and coverage levels.
What factors most affect home insurance rates?
Home insurance rates depend on location (crime, weather), home age/materials, coverage limits, deductible amount, and claims history. Older homes or those in flood/earthquake-prone zones may face higher premiums. Security systems, smoke detectors, and proximity to fire stations can lower costs. Rebuilding costs also influence pricing.
How long does the average auto insurance claim take to process?
Simple claims (e.g., minor fender benders) resolve in 1–7 days, while complex cases (e.g., total loss or liability disputes) may take 15–30 days. Factors like police reports, repair shop delays, or fraud investigations extend processing. Filing electronically and providing all documentation upfront speeds up resolution.
Are there new technologies reducing auto insurance fraud?
Yes, insurers now use AI-driven telematics (e.g., usage-based insurance apps), computer vision for crash analysis, and blockchain to verify claim authenticity. Telematics monitors driving behavior in real-time, while AI flags suspicious patterns like staged accidents. These tools reduce fraudulent claims by 20–40% annually, lowering premiums for honest policyholders.
Related articles
Smart Ways to Compare Auto and Home Insurance Quotes
Save money and get the best coverage with Smart Ways to Compare Auto and Home Insurance Quotes—learn how to evaluate rates, coverage limits, and…

Finding Auto Home Insurance Near Me Explained Clearly
Finding Auto Home Insurance Near Me Explained Clearly: Discover how to compare quotes, check coverage options, and save on bundled policies for your car…
Auto Home Insurance Companies Global Market Insights And Trends
Discover the latest insights on the Auto Home Insurance Companies Global Market Insights And Trends, including key players, growth drivers, and regional…

Auto Home Insurance Unveiled Global Trends Tech And Future
Discover the latest Auto Home Insurance Unveiled Global Trends Tech And Future, from AI-driven claims to smart home policies reshaping coverage worldwide.

Auto Insurance Car Insurance Explained Simply
Understand Auto Insurance & Car Insurance Explained Simply—coverage types, costs, and how policies protect drivers. Get clear answers on liability,…
