8 Ways to Get a Cheap Auto Insurance Quote Without Sacrificing Coverage
Table of Contents
- 1. Pricing Dynamics Explained
- 2. Common Mistakes to Avoid
- 3. How Discounts Lower Your Quote
- 4. Coverage Optimization Strategies
- 5. Provider Comparison Best Practices
- 6. The Role of Credit Scores
- 7. Regional Rate Variations
- 8. When to Reassess Your Policy
- Frequently Asked Questions
- 8 Tips to Secure a Cheap Auto Insurance Quote
- Conclusion
A **cheap auto insurance quote** refers to a competitively priced policy that balances affordability with adequate coverage. For example, a driver in Texas might receive a quote for $1,200 annually for full coverage on a Honda Civic, compared to $1,800 from a less optimized provider. This gap highlights how pricing varies based on insurer strategies, risk assessment, and policy customization.
The importance of securing a **cheap auto insurance quote** extends beyond immediate savings. Lower premiums free up disposable income, reduce financial stress, and allow policyholders to allocate funds toward other priorities like vehicle maintenance or emergency funds. Historically, insurance costs have risen alongside medical and repair expenses, making affordability a critical factor in long-term financial planning. Without proactive measures, drivers risk overpaying by hundreds or thousands over a policy term.
This guide explores how to obtain a **cheap auto insurance quote** without compromising essential protections. It covers key aspects like pricing dynamics, discount eligibility, coverage optimization, and provider comparisons—equipping readers with actionable insights to navigate the market effectively.
1. Pricing Dynamics Explained
Auto insurance premiums are influenced by a mix of objective and subjective factors. Objective elements include the insured vehicle’s make, model, and safety ratings, while subjective factors encompass driving history, location, and credit score. For instance, a Toyota Camry typically yields a **cheap auto insurance quote** due to its strong safety record, whereas a sports car may incur higher rates because of increased accident risk.
Insurers also use actuarial data to predict claims frequency. A driver in a high-theft urban area will face steeper premiums than one in a rural suburb. Understanding these dynamics helps in negotiating better rates or identifying opportunities for discounts.

2. Common Mistakes to Avoid
Many drivers unknowingly inflate their premiums by overlooking critical details. The following pitfalls can lead to overpaying for coverage:
- Skipping the annual review.
Auto insurance rates fluctuate based on market conditions, driving behavior, and policy updates. A driver who hasn’t reviewed their policy in five years may miss out on lower rates due to improved credit scores or a cleaner driving record. For example, a policyholder in Florida who renewed without comparison found their premium had increased by 20% due to rising state fees.
- Ignoring bundling opportunities.
Combining auto insurance with homeowners or renters insurance often yields significant discounts. State Farm, for instance, offers up to 15% off when bundling policies. Failing to explore this option can cost hundreds annually. Always ask providers about multi-policy discounts during the quoting process.
- Overlooking usage-based programs.
Telematics programs like Progressive’s Snapshot or Allstate’s Drivewise track driving habits (speed, braking, mileage) to reward safe behavior. A driver who enrolls and maintains a clean record could see a **cheap auto insurance quote** reduced by 30% or more. These programs are particularly beneficial for young or high-mileage drivers.
- Assuming all discounts apply automatically.
Discounts for low mileage, anti-theft devices, or good student status aren’t applied unless explicitly requested. A policyholder in California saved $400 annually after proactively mentioning their vehicle’s alarm system to their insurer. Always inquire about all potential discounts during the application process.
- Not comparing quotes regularly.
Loyalty penalties can cost drivers dearly. A study by Bankrate found that switching providers can save up to 15% on average. Even a small rate increase from one insurer may be offset by a lower quote from a competitor. Set a reminder to compare **cheap auto insurance quotes** every 6–12 months.
3. How Discounts Lower Your Quote
Discounts are one of the most effective ways to secure a **cheap auto insurance quote** without altering coverage. These reductions stem from reduced risk profiles or cost-saving measures implemented by the policyholder. For example, insurers like Geico offer discounts for paperless billing, while Farmers Insurance rewards drivers who complete defensive driving courses.
The most valuable discounts often correlate with behaviors that lower claim risks. A safe driver discount, for instance, may reduce premiums by 10–20% if no at-fault accidents or violations occur in three years. Similarly, vehicles equipped with advanced safety features—such as automatic braking or lane-keep assist—can qualify for tech-based discounts, sometimes cutting costs by 5–10%.

4. Coverage Optimization Strategies
Not all coverage is equal, and optimizing policy limits can lead to substantial savings without exposing drivers to undue risk. For example, a driver in a low-liability-risk state might reduce bodily injury coverage from $100,000 to $50,000 per person while staying compliant with state minimums. This adjustment could lower annual premiums by $150–$300.
However, optimization requires balancing savings with potential out-of-pocket expenses. Dropping collision coverage on an older vehicle (e.g., a 10-year-old sedan) might save money, but repairing or replacing the car after an accident could cost more than the premium savings. Tools like the National Association of Insurance Commissioners’ (NAIC) coverage calculator can help strike the right balance.
5. Provider Comparison Best Practices
Comparing **cheap auto insurance quotes** from multiple providers is non-negotiable for securing the best deal. Direct insurers like State Farm and Allstate often undercut traditional agents by eliminating overhead costs, while regional providers may offer niche advantages, such as lower rates for specific demographics. For instance, USAA consistently ranks as the cheapest for military members, while Farmers Insurance excels in rural areas.
To streamline comparisons, use independent rating platforms like NerdWallet or The Zebra, which aggregate quotes from dozens of insurers. These tools allow filtering by coverage type, discounts, and customer reviews. Always request quotes from at least three providers to identify outliers—some insurers specialize in high-risk drivers or specific vehicle types, offering tailored **cheap auto insurance quotes**.
6. The Role of Credit Scores
Credit-based insurance scores (CBIs) are a major determinant of premiums in most states, accounting for up to 20% of rate calculations. A driver with a poor credit score (below 580) might pay 70–100% more than someone with excellent credit (720+). For example, a policyholder in New York with a 650 credit score could receive a quote 40% higher than a counterpart with a 780 score for the same coverage.
Improving a credit score—by paying down debt, correcting errors on credit reports, or becoming an authorized user on a family member’s card—can lead to immediate savings. Some insurers, like American Family, offer credit monitoring services to help policyholders track and improve their scores, indirectly reducing long-term costs.
7. Regional Rate Variations
Insurance costs vary dramatically by state and even by ZIP code due to differences in traffic density, crime rates, and state regulations. Urban areas like Detroit or Los Angeles typically have higher premiums because of increased accident and theft risks, while rural states like North Dakota offer some of the lowest rates in the nation. For instance, the average annual premium in Michigan exceeds $2,500, whereas in Maine, it hovers around $800.
State-mandated minimums also impact affordability. No-fault states like Florida require Personal Injury Protection (PIP) coverage, which can add $500–$1,000 annually to premiums. Drivers in these states should explore optional add-ons, such as umbrella policies, to mitigate costs while maintaining protection.
8. When to Reassess Your Policy
Life changes—such as marriage, moving, or purchasing a new vehicle—can significantly alter insurance needs and eligibility for discounts. For example, getting married may qualify a driver for a spouse discount, while moving to a suburban area could lower premiums due to reduced traffic risks. Similarly, switching to a hybrid or electric vehicle might unlock eco-friendly discounts from insurers like Nationwide.
External factors, such as legislative changes or economic shifts, can also warrant a policy review. After a major hurricane season, for instance, insurers in Florida may adjust rates upward, prompting drivers to explore alternative coverage options. Setting calendar reminders or tying reassessments to major life events ensures policies remain aligned with current circumstances and budget constraints.
8 Tips to Secure a Cheap Auto Insurance Quote
Obtaining an affordable policy requires strategy and persistence. Here are eight actionable steps to maximize savings:
Tip 1: Request quotes from at least three insurers. Prices vary widely—one provider might offer a **cheap auto insurance quote** while another charges 20% more for identical coverage. Use comparison sites like Compare.com to streamline the process and identify outliers.
Tip 2: Bundle policies for multi-line discounts. Combining auto with home or renters insurance can reduce premiums by 10–25%. Providers like Liberty Mutual offer up to 30% off when bundling, making it a low-effort way to cut costs without sacrificing protection.
Tip 3: Enroll in usage-based programs. Telematics tools like Allstate’s Drivewise or State Farm’s Drive Safe & Save track driving habits to reward safe behavior. Maintaining a clean record for six months could earn a 10–30% discount on renewal, effectively lowering the **cheap auto insurance quote** over time.
Tip 4: Increase deductibles strategically. Raising the collision or comprehensive deductible from $500 to $1,000 might save $200–$400 annually. However, ensure the deductible remains affordable in case of a claim. This tactic works best for drivers with emergency savings.
Tip 5: Ask about all available discounts. Insurers often overlook discounts like those for military service, alumni affiliations, or even being a homeowner. Geico, for example, offers a discount for having a college degree. A quick phone call to the insurer can uncover unapplied savings.
Tip 6: Shop around after major life events. Changes like marriage, moving, or buying a house can qualify drivers for new discounts or lower rates. For instance, moving from an urban to a rural area might reduce premiums by 20% due to lower claim risks.
Tip 7: Consider paying annually for savings. Many insurers offer a 5–10% discount for paying the premium upfront. While this requires larger cash outlays, it can translate to hundreds in annual savings. Compare the discount against interest earned on the funds to determine the best approach.
Tip 8: Review and update your policy annually. Life changes—such as a new job, vehicle, or credit score improvement—can impact eligibility for discounts or lower rates. Setting a calendar reminder ensures policies remain optimized for affordability without gaps in coverage.
Conclusion
Securing a **cheap auto insurance quote** hinges on understanding pricing dynamics, leveraging discounts, optimizing coverage, and comparing providers strategically. By avoiding common mistakes—such as skipping annual reviews or overlooking bundling opportunities—drivers can save hundreds annually without compromising protection. Regional variations, credit scores, and vehicle choices further influence costs, emphasizing the need for personalized approaches.
As the insurance landscape evolves with new technologies and regulatory changes, proactive policy management remains key. Staying informed and reassessing coverage periodically ensures long-term savings while maintaining the safety net essential for any driver.

Related articles

13 Essential Facts About Auto Insurance Free Quotes You Need to Know
Discover how to get an accurate **auto insurance free quote**, compare providers, and avoid costly mistakes. Learn the hidden factors affecting your…
10 Essential Facts About Auto Insurance Auto Insurance Quote
Get smarter about auto insurance quotes: how they work, what affects them, and how to save. Learn the hidden factors behind your premiums and secure the…
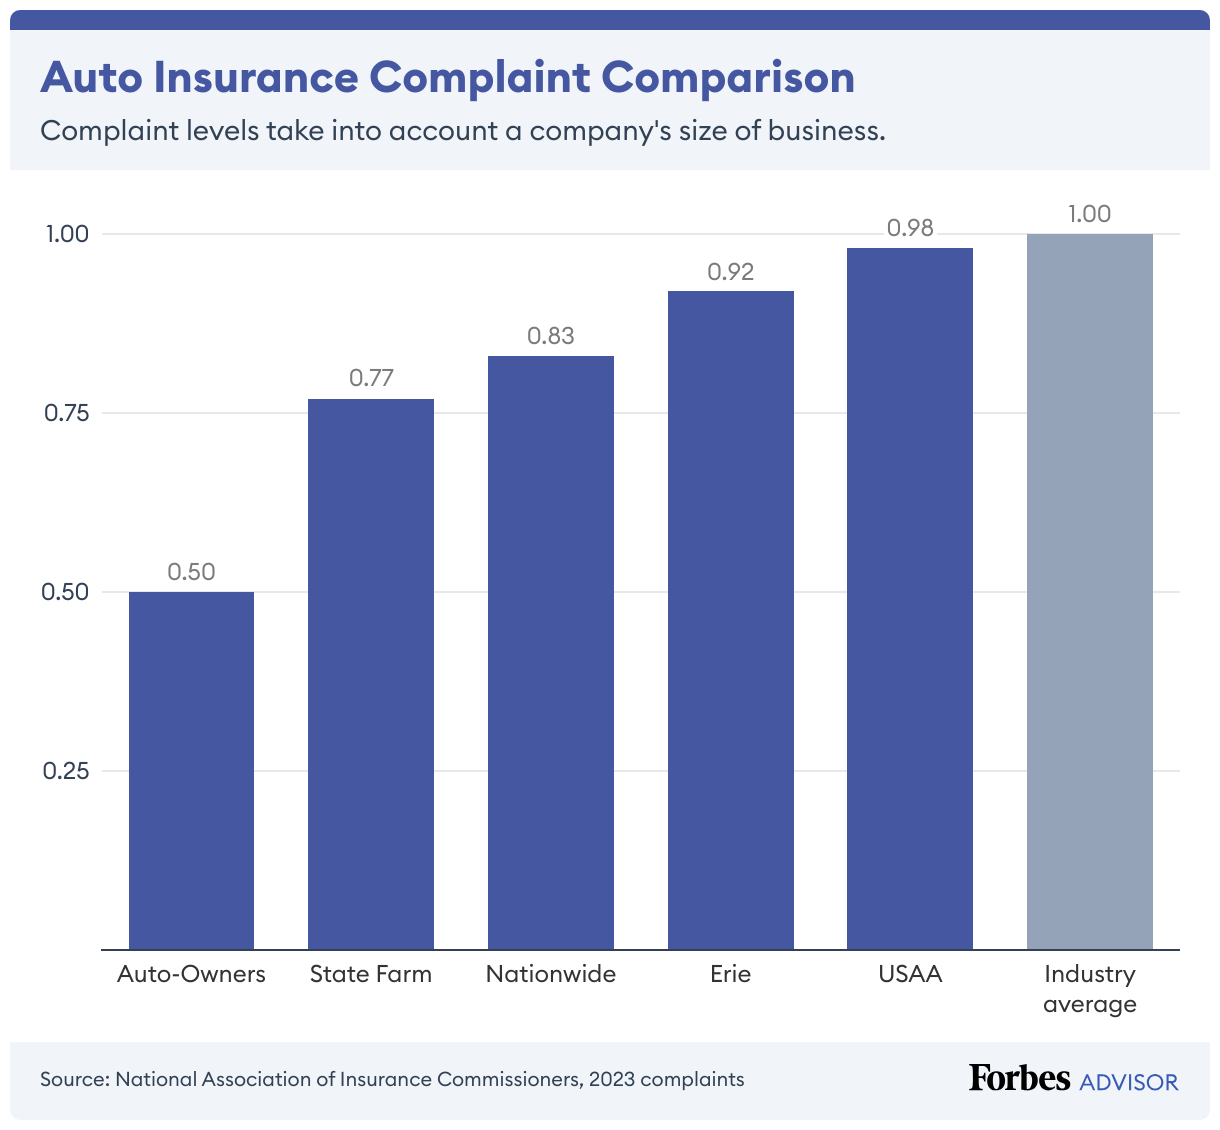
16+ Smart Ways to Save with Auto and Home Insurance Bundles
Discover how auto and home insurance bundles cut costs while boosting coverage. Learn key strategies, common pitfalls, and expert tips to maximize…
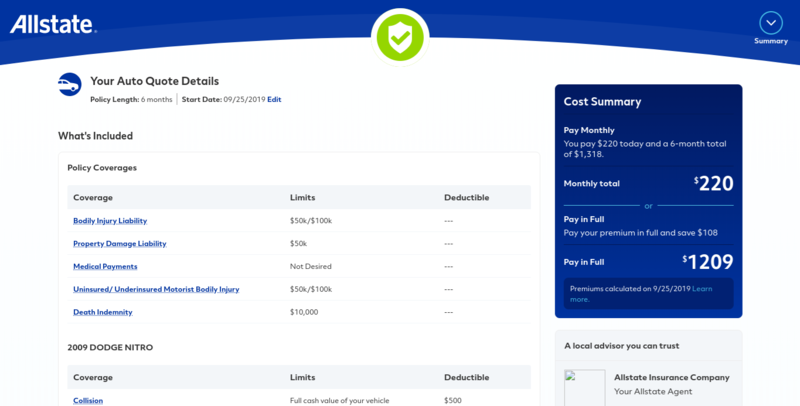
15 Key Insights Into Allstate Insurance Quote Auto: A Comprehensive Guide
Get an Allstate insurance quote auto fast with these expert insights. Learn pricing, coverage, and tips to save money while securing top-rated protection…

14+ Smart Ways to Find Affordable Online Auto Insurance in 2024
Discover how to cut auto insurance costs without sacrificing coverage. Compare quotes, avoid hidden fees, and unlock savings with these proven strategies…
