16+ Smart Ways to Save with Auto and Home Insurance Bundles
Table of Contents
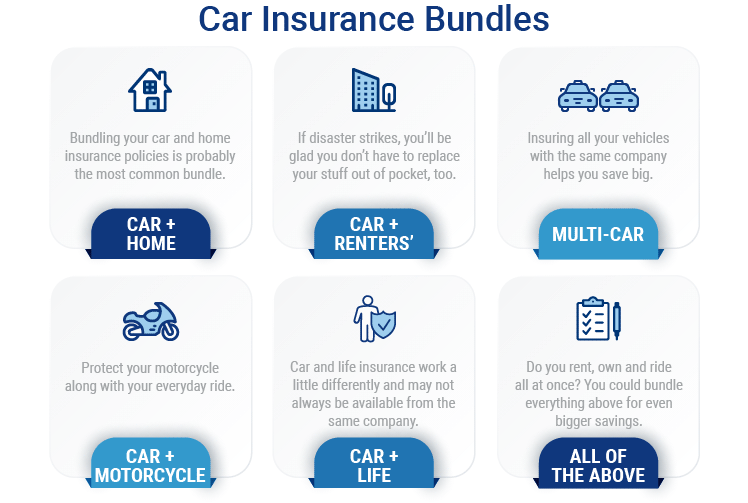
Auto and home insurance bundles combine policies from the same provider into a single package, offering discounts and simplified management. For example, State Farm’s bundling option might reduce premiums by 10-25% for a driver with both a car and home policy. This approach leverages the provider’s risk assessment tools to reward loyalty while streamlining claims and payments.
The importance of bundling lies in its dual benefits: financial savings and convenience. Historically, insurers introduced these packages to encourage long-term customer relationships, but today’s digital tools—like automated policy reviews—make bundling more efficient. Data from the Insurance Information Institute shows that bundled policies account for over 40% of new insurance sales, proving their practical appeal.
This article explores how auto and home insurance bundles work, their financial and practical advantages, and critical factors to evaluate before committing. It also addresses common misconceptions, cost-saving strategies, and real-world examples to help readers make informed decisions.
1. How Bundling Works
Auto and home insurance bundles consolidate two or more policies under one insurer, creating a discount incentive. The insurer reduces the total premium by 10-30% (varies by provider) in exchange for managing both risks. For instance, Allstate’s “Home and Auto Package” automatically applies a 10% discount when both policies are active, with additional savings for bundling additional lines like renters or umbrella insurance.
The mechanics involve shared underwriting data. When a customer applies for a bundle, the insurer assesses combined risk factors—such as a home’s security features or a driver’s claims history—rather than evaluating policies separately. This holistic approach can lower premiums further if the combined profile is low-risk. However, the discount’s size depends on the insurer’s bundling policy and the customer’s eligibility.
2. Key Benefits Explained
- Cost Efficiency
Bundling typically reduces annual premiums by 10-25%. A 2023 study by J.D. Power found that drivers paying $1,200 for auto insurance alone could save $120–$300 yearly by bundling with home insurance. The savings compound over time, especially for long-term policyholders.
- Simplified Claims
Single providers streamline claims processes. Progressive’s “Snapshot” program, for example, allows bundled customers to file claims through one portal, reducing paperwork and response times. This is critical during emergencies, like a hailstorm damaging both a car and roof.
- Enhanced Coverage
Bundles often include perks like roadside assistance or identity theft protection. Geico’s “Insurance Plus” bundle adds $500 in annual roadside assistance for auto policyholders, a benefit not available in standalone plans.
- Loyalty Rewards
Insurers like Farmers offer tiered discounts for multi-year commitments. A customer with a 5-year auto policy might qualify for an additional 5% discount when bundling home insurance, incentivizing long-term retention.
- Convenience
One policy renewal date and a single customer service contact reduce administrative hassle. USAA’s bundled customers report spending 30% less time managing policies compared to those with separate insurers.
3. Pricing Dynamics
Premium calculations for bundles differ from standalone policies. Insurers use algorithms to weigh combined risk factors, such as the home’s location (e.g., flood zones) or the driver’s age. A 30-year-old in a suburban area might see a 15% discount for bundling, while a 65-year-old in an urban center could receive only 5%. Transparency is key: providers like Lemonade publish bundling discount ranges upfront to manage expectations.
External factors also influence pricing. Economic trends, such as rising repair costs for vehicles or homes, can erode discount margins. In 2022, the average auto insurance premium increased by 6% nationwide, but bundled policies with inflation protection clauses (e.g., State Farm’s “Price Lock”) mitigated some of these increases for loyal customers.

4. Common Mistakes to Avoid
Misjudging coverage gaps is a frequent error. Some bundled policies exclude high-value items (e.g., jewelry) unless additional riders are purchased. A homeowner might assume their $5,000 engagement ring is covered under a standard bundle, only to discover it requires a separate scheduled personal property endorsement.
Another mistake is overlooking deductible implications. Bundling can lower premiums but may increase deductibles for one or both policies. For example, an insurer might offer a 20% premium discount for a bundle but raise the auto deductible from $500 to $1,000. Weighing these trade-offs requires comparing the annual savings against potential out-of-pocket costs during a claim.
5. Provider Comparisons
Not all insurers offer equal bundling benefits. Progressive’s “360° Smart Home” bundle, for example, includes smart home device discounts (e.g., 10% off Ring doorbells), while Nationwide’s “SmartRide” bundle focuses on telematics-based auto discounts. Comparing providers involves evaluating:
- Discount Structures
Some insurers cap discounts at 15%, while others (like USAA) offer up to 30% for military families. Always request a bundling quote to compare.
- Additional Perks
Chubb’s “Chubb Smart Home” bundle includes 24/7 cybersecurity monitoring, a feature absent in competitors’ basic bundles.
- Customer Service Ratings
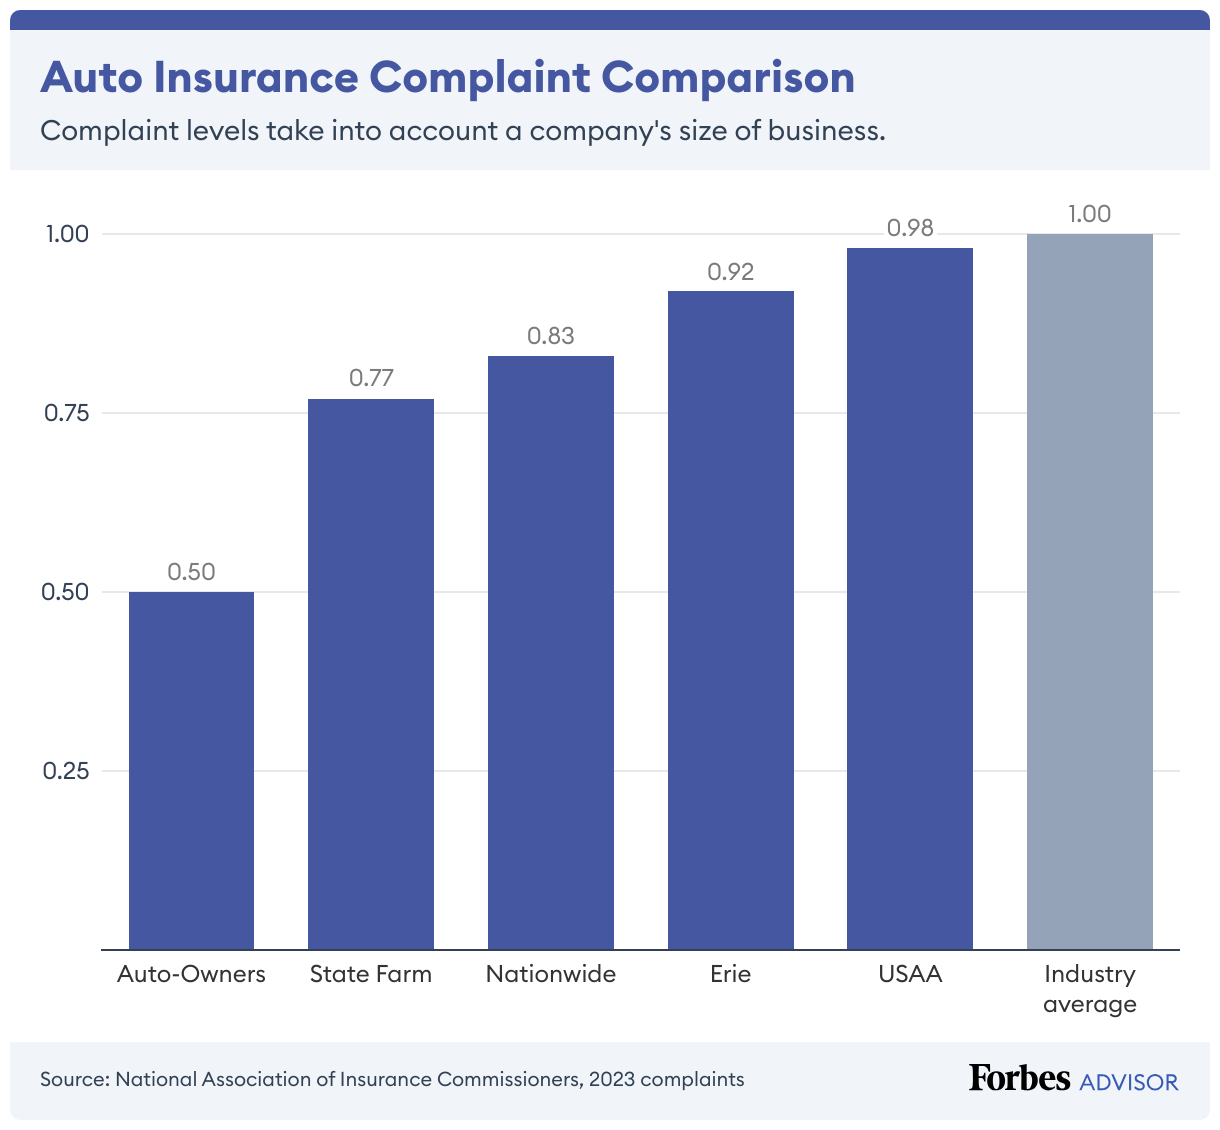
Bundled policies require reliable support. J.D. Power’s 2023 rankings show State Farm and USAA lead in customer satisfaction for bundled claims handling.
Tools like Policygenius or NerdWallet’s bundling calculators can simplify comparisons by aggregating quotes from multiple providers.
6. When to Bundle (or Not)
Bundling is ideal for homeowners or drivers with stable, low-risk profiles. A family with a mortgage, a mid-range sedan, and no recent claims will likely benefit most. Conversely, high-risk scenarios—such as a driver with multiple DUIs or a home in a wildfire-prone area—may not qualify for significant discounts, making separate policies more cost-effective.
Timing also matters. New homebuyers or those refinancing a mortgage should explore bundling immediately, as insurers often offer introductory discounts. Conversely, those nearing policy renewal with a provider offering minimal bundling incentives may find better rates by switching.
7. Tax and Legal Implications
Bundled insurance discounts are typically not tax-deductible, as they reduce premiums rather than providing a direct benefit like a charitable donation. However, some states (e.g., Texas) allow deductions for homeowners insurance premiums if itemized, which could indirectly benefit bundled policies. Consult a tax advisor to explore state-specific rules.
Legally, bundling contracts are governed by state insurance codes. For example, California’s Insurance Code § 790.15 requires insurers to disclose bundling discounts in plain language, preventing hidden fees. Always review the policy’s “Terms and Conditions” for exclusions or auto-renewal clauses that could affect future savings.
8. Future Trends
The rise of telematics and AI is reshaping bundling. Insurers like Allstate now offer “Drivewise” bundles, where auto policyholders earn discounts by sharing driving data, which can further reduce home insurance premiums if the profile remains low-risk. Similarly, smart home integrations—such as ADT’s partnership with American Family Insurance—are creating “connected home” bundles that monitor security and adjust premiums in real time.
Regulatory shifts may also impact bundling. Proposed federal rules aim to standardize discount transparency, which could level the playing field for small insurers. Staying informed about these trends ensures customers can leverage the most innovative bundling options.
16 Actionable Tips for Maximizing Savings
Optimizing auto and home insurance bundles requires strategy. Below are 16 practical steps to secure the best value.
Tip 1: Shop During Open Enrollment.Insurers often introduce limited-time bundling promotions in fall or spring. Set reminders to compare quotes during these periods.
Tip 2: Bundle with a High-Rated Provider.Prioritize insurers with strong financial stability (e.g., A.M. Best ratings) and customer service scores to avoid future headaches.
Tip 3: Ask About Multi-Policy Discounts.Some insurers offer additional savings for bundling three or more policies (e.g., auto, home, and umbrella insurance).
Tip 4: Install Safety Devices.Smart home security systems (e.g., ADT) or anti-theft devices in vehicles can qualify for bundling discounts of 5–15%.
Tip 5: Pay Annually for Extra Savings.Many insurers reduce premiums by 2–5% for annual payments, even with bundled policies.
Tip 6: Review Deductibles.Higher deductibles in one policy can lower overall premiums, but ensure the trade-off aligns with your financial comfort zone.
Tip 7: Check for Loyalty Programs.Providers like Nationwide offer increasing discounts for policyholders who renew annually without claims.
Tip 8: Compare Bundling vs. Standalone Rates.Use tools like Policygenius to compare bundled quotes with separate policies to confirm savings.
Tip 9: Bundle with a Provider Offering Telematics.Programs like Progressive’s “Snapshot” can further reduce auto insurance costs, which may trickle down to home insurance discounts.
Tip 10: Confirm Coverage Limits.Ensure bundled policies meet your needs—especially for high-value items or liabilities—before committing.
Tip 11: Ask About Group Discounts.Professional organizations (e.g., AAA, AARP) often negotiate bundling discounts with insurers.
Tip 12: Avoid Overlapping Coverage.Check for duplicate protections (e.g., rental car insurance in an auto policy and a credit card’s coverage).
Tip 13: Request a Policy Review.Insurers may adjust discounts after major life events (e.g., marriage, retirement) that lower risk profiles.
Tip 14: Explore State-Specific Programs.Some states (e.g., Florida’s “Homeowners’ Insurance Discount Program”) offer additional incentives for bundling.
Tip 15: Bundle with a Provider Offering Digital Tools.Features like mobile claims filing or AI chatbots can offset higher premiums with added convenience.
Tip 16: Reevaluate After Major Changes.Events like selling a home, switching cars, or changing jobs may warrant renegotiating your bundle.
Conclusion
Auto and home insurance bundles offer a compelling blend of cost savings, convenience, and enhanced coverage when approached strategically. The key aspects covered here—how bundling works, its financial and practical benefits, pricing dynamics, and common pitfalls—highlight the need for careful evaluation. By leveraging discounts, optimizing coverage, and staying informed about industry trends, customers can maximize the value of their bundled policies.
The future of bundling lies in technology and personalization. As insurers integrate telematics, AI, and smart home data, the potential for tailored discounts and seamless management will grow. For now, the best approach remains proactive: compare providers, review policies annually, and take advantage of every eligible discount to secure both protection and savings.
Frequently Asked Questions
Does bundling always save money?
Not necessarily. While most insurers offer discounts, the savings vary. A 2023 Consumer Reports analysis found that bundling could save up to 25% with top providers like USAA, but only 5% with others. Always compare standalone vs. bundled quotes to confirm cost-effectiveness.
Can I bundle with any insurer?
No. Only insurers that explicitly offer multi-policy discounts qualify. Major providers like State Farm and Geico market bundling, while smaller regional insurers may not. Verify eligibility by checking the provider’s website or contacting customer service.
Will bundling affect my credit score?
Indirectly, yes. Insurance premiums aren’t reported to credit bureaus, but late payments or policy cancellations tied to other financial obligations (e.g., mortgages) could impact credit. Bundling itself has no direct effect, but responsible payment management is key.
Are there penalties for canceling a bundle?
Potentially. Some insurers impose early termination fees or reduce future discounts if a bundle is canceled within the first 1–2 years. Review the policy’s cancellation clause or ask the provider about penalties before making changes.
Does bundling cover rental properties?
Generally, no. Most auto and home insurance bundles are designed for primary residences and personal vehicles. Rental properties typically require commercial or landlord-specific policies, which insurers do not bundle with personal auto policies.
How often should I review my bundle?
At least annually. Life changes—such as buying a new car, renovating a home, or adding a teen driver—can affect risk levels and discounts. Use this time to renegotiate terms or switch providers if better bundling options emerge.
Related articles

10 Essential Facts About Auto Insurance Auto Insurance Quote
Get smarter about auto insurance quotes: how they work, what affects them, and how to save. Learn the hidden factors behind your premiums and secure the…

17+ Smart Ways to Find Affordable Full Coverage Insurance Without Sacrificing Protection
Discover how to secure **affordable full coverage insurance** while keeping premiums low. Learn pricing strategies, policy tips, and real examples to…
