9 Essential Facts About Auto Insurance Quote California Drivers Must Know
Table of Contents
- 1. Pricing Dynamics in California
- 2. Minimum Coverage Requirements
- 3. How to Get an Accurate Quote
- 4. Discounts That Lower Premiums
- 5. Common Mistakes to Avoid
- 6. Comparing Insurers: Key Differences
- 7. Special Considerations for Renters and High-Risk Drivers
- 8. When to Requote Your Policy
- Frequently Asked Questions
- 9 Proven Tips to Secure the Best Auto Insurance Quote California
- Conclusion
An **auto insurance quote California** represents a personalized estimate of premiums for vehicle coverage within the state, tailored to factors like driving history, vehicle type, and location. For example, a 30-year-old driver in Los Angeles insuring a 2020 Toyota Camry might receive a quote ranging from $1,200 to $2,500 annually, depending on coverage limits and deductibles. These quotes serve as the foundation for securing legally compliant and financially protective policies, ensuring drivers meet California’s mandatory liability requirements while safeguarding against accidents, theft, or natural disasters.
The importance of obtaining an accurate **auto insurance quote California** cannot be overstated. California’s high population density, diverse road conditions, and frequent wildfires create unique risks that influence premiums. Beyond legal compliance, a well-researched quote can uncover cost-saving opportunities—such as bundling policies or leveraging usage-based discounts—while preventing overpayment for unnecessary coverage. Historically, the rise of digital platforms has democratized access to quotes, allowing drivers to compare options from insurers like State Farm, GEICO, and Progressive without visiting physical offices.
This guide explores the critical aspects of securing an **auto insurance quote California**, from understanding pricing dynamics to avoiding common pitfalls. Whether navigating minimum requirements, exploring discount eligibility, or comparing insurers, these insights ensure drivers make informed decisions that balance affordability and protection.
1. Pricing Dynamics in California
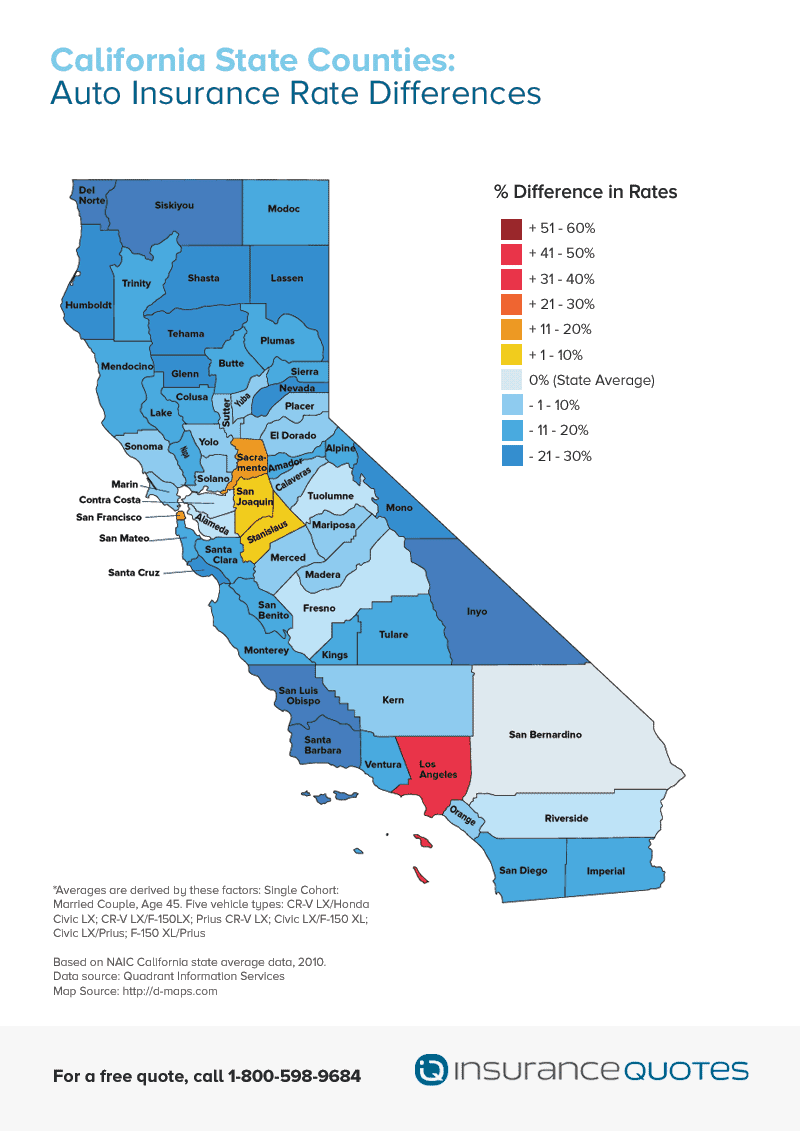
California’s auto insurance market operates under unique economic and regulatory pressures. Premiums reflect a combination of state-mandated minimum coverage, urban congestion, and high repair costs. For instance, drivers in San Francisco typically pay 20–30% more than those in rural areas due to higher accident rates and vehicle theft risks. Additionally, California’s no-fault system for medical expenses (via Personal Injury Protection, or PIP) adds complexity to liability calculations.
Three key factors dominate pricing:
- Location-based risks: Urban areas like Los Angeles and San Diego inflate quotes due to traffic density, while rural zones like Fresno may offer lower rates. A driver in Santa Monica might pay $1,800 annually for full coverage, whereas a counterpart in Bakersfield could secure the same for $1,300.
- Vehicle type and age: Luxury or high-theft vehicles (e.g., Tesla Model 3, Nissan Leaf) trigger higher premiums. A 2018 Honda Civic typically costs 15–20% less to insure than a 2022 BMW M3.
- Driver profile: Age, credit score, and prior claims directly impact quotes. A 25-year-old with a clean record may pay $1,500, while a 60-year-old with a single at-fault accident could see a $2,200 quote.
2. Minimum Coverage Requirements
California law mandates specific liability limits: $15,000 per person/$30,000 per accident for bodily injury and $5,000 for property damage. These minimums, while affordable (often under $500 annually), leave drivers vulnerable to lawsuits exceeding coverage. For example, a driver at fault in a $50,000 accident could face personal asset seizure if relying solely on state minimums.
Opting for higher limits—such as 100/300/50—typically adds $200–$500 annually but provides critical protection. Collision and comprehensive coverage, though optional, are wise in earthquake-prone regions like Orange County, where hail or quake damage could total a vehicle.
3. How to Get an Accurate Quote
Accuracy hinges on transparency and specificity. Drivers should gather details like VIN, annual mileage, and security features (e.g., anti-theft systems) before requesting an **auto insurance quote California**. Online tools from providers like Allstate or Farmers streamline this process, but discrepancies—such as omitting a speeding ticket—can void coverage or trigger rate hikes.
Three steps ensure precision:
- Use multiple insurers: Quotes vary by up to 40% across providers. Comparing State Farm ($1,600) vs. USAA ($1,100) for identical coverage highlights this disparity.
- Disclose all driver details: Adding a teen driver can increase premiums by 100–150%. A family in Sacramento might see their quote jump from $1,400 to $2,800 after listing their 17-year-old.
- Check for employer discounts: Companies like Google or Apple often partner with insurers to offer 10–15% savings to employees.
4. Discounts That Lower Premiums
California insurers offer discounts averaging 15–30% when drivers meet criteria like low mileage, bundling home/auto policies, or maintaining good grades (for students). For example, a driver in San Diego bundling with Farmers could save $400 annually, while a safe driver with a telematics program (e.g., Progressive’s Snapshot) might reduce premiums by $300.
Common discounts include:
- Safe driver programs: Insurers like Nationwide reward accident-free years with up to 40% off after five years.
- Anti-theft devices: Installing a LoJack system can cut comprehensive coverage costs by 10–15%. A driver in Oakland might save $250 annually.
- Paperless billing: Opting for electronic statements often yields a 5–7% discount, adding up to $100 in annual savings.
5. Common Mistakes to Avoid
Missteps during the quoting process can lead to overpaying or denied claims. Overestimating vehicle value inflates comprehensive coverage costs, while underreporting mileage may invalidate usage-based discounts. For instance, a driver in Fresno claiming 8,000 miles annually but actually driving 12,000 could face a $500 premium increase upon policy review.
Three critical errors include:
- Ignoring usage-based discounts: Telematics programs like Allstate’s Drivewise can reduce rates by monitoring safe driving habits, yet many eligible drivers overlook them.
- Skipping the shopping period: Rates fluctuate seasonally; quoting in January (post-holiday lull) often yields better deals than July (peak accident months).
- Assuming all insurers use the same data: Credit scores impact quotes differently by provider. A driver with a 700 score might pay $1,700 at GEICO but $2,000 at Liberty Mutual.
6. Comparing Insurers: Key Differences
California’s top insurers—State Farm, GEICO, and Farmers—differ in coverage breadth, customer service, and tech integration. State Farm, for example, excels in claims processing speed (average 24-hour turnaround), while GEICO leads in affordability for young drivers. Local insurers like Mercury Insurance cater specifically to California’s risks, offering tailored wildfire coverage in high-risk zones like Malibu.
Provider selection hinges on three factors:
- Claims handling: J.D. Power ratings show State Farm (4.1/5) outperforms Progressive (3.8/5) in customer satisfaction during claim resolutions.
- Digital tools: USAA’s mobile app allows instant quote adjustments, while Allstate’s “Mayhem” commercials reflect its aggressive marketing but not necessarily lower rates.
- Local expertise: Mercury Insurance’s “FireSafe” program provides discounts for fire-resistant home modifications, appealing to drivers in wildfire-prone areas.
7. Special Considerations for Renters and High-Risk Drivers
Renters or leaseholders often face higher premiums due to insurer assumptions about vehicle ownership stability. Meanwhile, high-risk drivers—those with DUIs or multiple violations—may need to explore non-standard insurers like The General or Dairyland. For example, a driver in Long Beach with a DUI might pay $3,500 annually with a standard insurer but find a non-standard policy for $2,800.
SR-22 filings, required for reinstated licenses, add $500–$1,000 annually but are non-negotiable. High-risk drivers should also consider usage-based programs to gradually improve their profiles.
8. When to Requote Your Policy
Life changes—marriage, moving, or purchasing a new vehicle—trigger the need for updated **auto insurance quote California** quotes. A move from San Francisco to Sacramento could lower premiums by 25% due to reduced traffic risks, while adding a hybrid vehicle might increase costs by 10% for higher repair expenses. Annual reviews ensure alignment with current market rates and personal circumstances.
Three triggers for requoting include:
- Anniversary dates: Insurers often adjust rates annually; comparing quotes on your policy anniversary can uncover savings.
- Credit score improvements: A 50-point credit score increase might reduce premiums by 5–10%. A driver in Riverside could save $200 annually after paying down debt.
- Vehicle modifications: Installing a new stereo or performance upgrades can void coverage or increase premiums if not disclosed.
9 Proven Tips to Secure the Best Auto Insurance Quote California
Optimizing an **auto insurance quote California** requires strategic planning and leveraging available resources.
Tip 1: Bundle home and auto policies. Combining policies with the same insurer (e.g., Allstate) can reduce premiums by 10–20%. A family in San Jose might save $500 annually.
Tip 2: Increase deductibles cautiously. Raising collision deductibles from $500 to $1,000 could lower annual costs by $300, but ensure the higher deductible is affordable in case of a claim.
Tip 3: Install anti-theft devices. Systems like OnStar or LoJack qualify for 10–25% discounts on comprehensive coverage. A driver in Oakland could save $300 yearly.
Tip 4: Maintain a high credit score. Scores above 720 often yield the lowest quotes. Paying down debt or correcting credit report errors can improve eligibility.
Tip 5: Compare quotes every 6–12 months. Loyalty discounts are rare; insurers like Progressive may offer new-customer incentives that existing clients miss.
Tip 6: Ask about group affiliations. Professional organizations (e.g., AAA, AARP) or employers often negotiate discounted rates with insurers.
Tip 7: Opt for paperless communications. Electronic billing and statements can secure 5–7% discounts, adding up to $100 in annual savings.
Tip 8: Monitor for usage-based discounts. Programs like State Farm’s Drive Safe & Save track driving habits and reward safe behavior with up to 30% off.
Tip 9: Review coverage limits annually. Inflation and vehicle depreciation may render old limits inadequate. Adjusting from 50/100/50 to 100/300/100 could add $400 annually but provide critical protection.
Conclusion
Securing an accurate **auto insurance quote California** demands attention to local regulations, provider differences, and personal risk factors. From understanding minimum coverage limits to leveraging discounts and avoiding common pitfalls, each step directly impacts affordability and protection. By comparing quotes, disclosing accurate information, and regularly reviewing policies, drivers can navigate California’s complex insurance landscape with confidence.
As risks evolve—whether through climate changes, technological advancements, or legislative updates—staying proactive ensures policies remain both compliant and cost-effective. The key lies in balancing thorough research with timely adjustments to reflect life’s inevitable shifts.
Frequently Asked Questions
Does California require full coverage auto insurance?
No, California only mandates liability insurance (15/30/5) for bodily injury and property damage. However, lenders typically require collision and comprehensive coverage if the vehicle is financed or leased.
How often should I update my auto insurance quote California?
Update quotes annually or after major life events—such as moving, marriage, or purchasing a new car—to ensure premiums reflect current risks and market rates.
Can I get a discount for driving an electric vehicle?
Some insurers like GEICO and State Farm offer discounts (5–15%) for EV owners due to lower accident rates and maintenance costs. Verify eligibility with your provider.
What happens if I don’t have insurance in California?
Driving uninsured in California results in fines ($100–$200), license suspension, and higher premiums if insured later. Repeat offenses can lead to jail time.
Do California insurers check credit scores for quotes?
Yes, most insurers use credit-based insurance scores to assess risk. A higher score (700+) often correlates with lower premiums, while poor credit can increase costs by 20–50%.
How do I lower my quote after a speeding ticket?
Mitigate impacts by completing a defensive driving course (e.g., DMV-approved programs) or requesting a rate review after three years of claim-free driving.
Related articles
11+ Ways to Find Affordable Car Insurance in California Without Sacrificing Coverage
California’s car insurance costs are high—but affordable options exist. Discover proven strategies to cut premiums legally, compare top providers, and…
12+ Ways to Find Affordable Car Insurance California Drivers Need in 2024
Discover proven strategies to secure **affordable car insurance in California** without sacrificing coverage. Learn how to slash premiums by up to 40%…

11 Essential Facts About Auto Insurance Get Quote
Learn how to secure the best auto insurance quote fast. Discover pricing factors, comparison tips, and how to avoid costly mistakes—plus expert…
