11+ Ways to Find Affordable Car Insurance in California Without Sacrificing Coverage
Table of Contents
- 1. Pricing Dynamics in California
- 2. Minimum Coverage vs. Full Coverage
- 3. Discounts and Savings Programs
- 4. Credit Score Impact
- 5. Regional Price Variations
- 6. State-Specific Programs
- 7. Common Mistakes to Avoid
- 8. How to Compare Quotes Effectively
- Frequently Asked Questions
- 11 Proven Tips to Lower Your Premiums
- Conclusion
Affordable car insurance in California refers to auto coverage plans that balance low monthly costs with adequate protection, tailored to the state’s unique regulatory and risk environment. For example, a 30-year-old driver in Los Angeles might pay $1,200 annually for full coverage with a 780 credit score, while a similar policy in rural Fresno could cost 20% less—demonstrating how location, credit, and coverage levels directly impact affordability. The term also encompasses strategies to legally reduce premiums without compromising safety or compliance.
Securing affordable car insurance in California is critical due to the state’s high cost of living, frequent traffic congestion, and elevated risk of accidents (California ranks among the top states for distracted driving fatalities). Benefits include financial protection against liabilities (e.g., a $150,000 claim for a multi-vehicle collision), compliance with minimum liability limits (15/30/5), and access to roadside assistance or rental reimbursement. Historically, California’s insurance market has faced volatility—spiking after wildfires or legislative changes, such as the 2019 SB 1060, which expanded coverage for low-income drivers but also increased average premiums by 12%.
This guide explores the key factors influencing affordable car insurance in California, from leveraging discounts to understanding regional price disparities. It covers eligibility for state programs, the role of credit scores, and how to compare quotes effectively—equipping drivers to make informed decisions without overpaying.
1. Pricing Dynamics in California
California’s car insurance market operates under strict regulations, including rate approval by the Department of Insurance, which caps annual premium increases at 8% without justification. However, costs vary dramatically by county due to factors like population density, crime rates, and repair shop availability. Urban areas like San Francisco see premiums 30–50% higher than rural regions, primarily because of higher claims frequency and medical expenses.
Insurance providers use algorithms to assess risk, factoring in driving history, vehicle type, and even education level (studies show drivers with advanced degrees file fewer claims). For instance, a Tesla Model 3 in Silicon Valley might cost $2,500/year for collision coverage, while a 2010 Honda Civic in Bakersfield could be insured for $1,000—highlighting how vehicle value and location interplay. Understanding these dynamics allows drivers to strategically adjust their policies to lower costs.
2. Minimum Coverage vs. Full Coverage
California mandates minimum liability coverage of 15/30/5 ($15,000 per person/$30,000 per accident for bodily injury, $5,000 for property damage), but this often leaves drivers underinsured. A single at-fault accident in Los Angeles could exceed these limits by $100,000+, exposing personal assets to lawsuits. Full coverage (adding collision and comprehensive) costs 50–100% more but protects against theft, vandalism, or weather-related damage—critical in a state prone to hailstorms and earthquakes.
For budget-conscious drivers, a middle-ground option is liability + uninsured motorist coverage, which adds protection against hit-and-run drivers (common in California, where 1 in 7 drivers lacks sufficient insurance). Example: A driver in Orange County might save $500/year by dropping collision on a 10-year-old car but adding $10,000 in uninsured motorist bodily injury coverage—a trade-off that reduces out-of-pocket risk.
3. Discounts and Savings Programs
- Good Driver Discounts: Insurers like State Farm and Progressive offer 10–25% off for drivers with no at-fault accidents in the past 3–5 years. A San Diego resident with a clean record could save $300/year by maintaining this status. Practical implication: Even a single ticket can erase these savings for 3–6 years.
- Bundling Policies: Combining auto with home or renters insurance (e.g., through Allstate or Farmers) often yields 15–20% discounts. A family in Sacramento might pay $1,800/year for bundled coverage instead of $2,200 separately. Note: Shop around—some insurers penalize bundling.
- Low Mileage Discounts: Programs like Progressive’s Snapshot or Nationwide’s SmartMiles reward drivers who log under 7,500 miles/year. A telecommuter in Palo Alto could save $200/year by opting for this discount. Caveat: Requires usage-based tracking via a plug-in device.
- Affinity Discounts: Employers, unions, or alumni associations (e.g., UC Berkeley alumni) partner with insurers to offer exclusive rates. A teacher in Fresno might access a 10% discount through their district’s program. Tip: Ask HR or local organizations about partnerships.
- Pay-in-Full Discounts: Paying annually instead of monthly can reduce costs by 2–5%. A driver in Long Beach might save $120/year by electing this option, though it requires upfront cash flow. Alternative: Some insurers offer bi-annual payment plans.
4. Credit Score Impact
California law permits insurers to use credit-based insurance scores (not FICO scores) to set premiums, though the practice is banned in states like Hawaii. A driver with a 720+ score may pay 30% less than someone with a 580 score, as statistical data shows a correlation between creditworthiness and claim frequency. For example, a driver in Oakland with a 650 score might pay $1,500/year for full coverage, while a peer with a 750 score pays $1,050—an annual difference of $450.
Improving a credit score by 50 points (e.g., paying down credit card debt or correcting errors on a credit report) can trigger automatic rate reductions from insurers like Geico or USAA. The California Department of Insurance recommends checking scores annually via free services like Credit Karma, as errors are common—30% of reports contain inaccuracies that could inflate premiums.
5. Regional Price Variations
California’s geography creates stark insurance price differences. Coastal cities (e.g., Santa Barbara, San Diego) face higher premiums due to theft risks and expensive repairs, while inland areas (e.g., Visalia, Hanford) offer lower rates. Data from the NAIC shows a $1,000/year difference between urban and rural policies for identical coverage. For instance, a driver in San Francisco might pay $2,200/year for full coverage, whereas a similar policy in Stockton costs $1,200.
Weather also plays a role: Drivers in wildfire-prone zones (e.g., Napa Valley) may see higher comprehensive coverage costs due to increased claims. Conversely, areas with lower crime rates (e.g., parts of Orange County) benefit from cheaper liability coverage. Understanding these regional trends helps drivers negotiate better rates or relocate to save.
6. State-Specific Programs
- California Low-Cost Auto Insurance Program: Offers liability-only policies starting at $17/month for eligible low-income drivers (household income under 250% of the federal poverty level). Example: A single parent in Riverside earning $30,000/year could qualify for this program, saving $1,200/year compared to private insurers. Limitation: Only covers state-minimum liability, not collision or comprehensive.
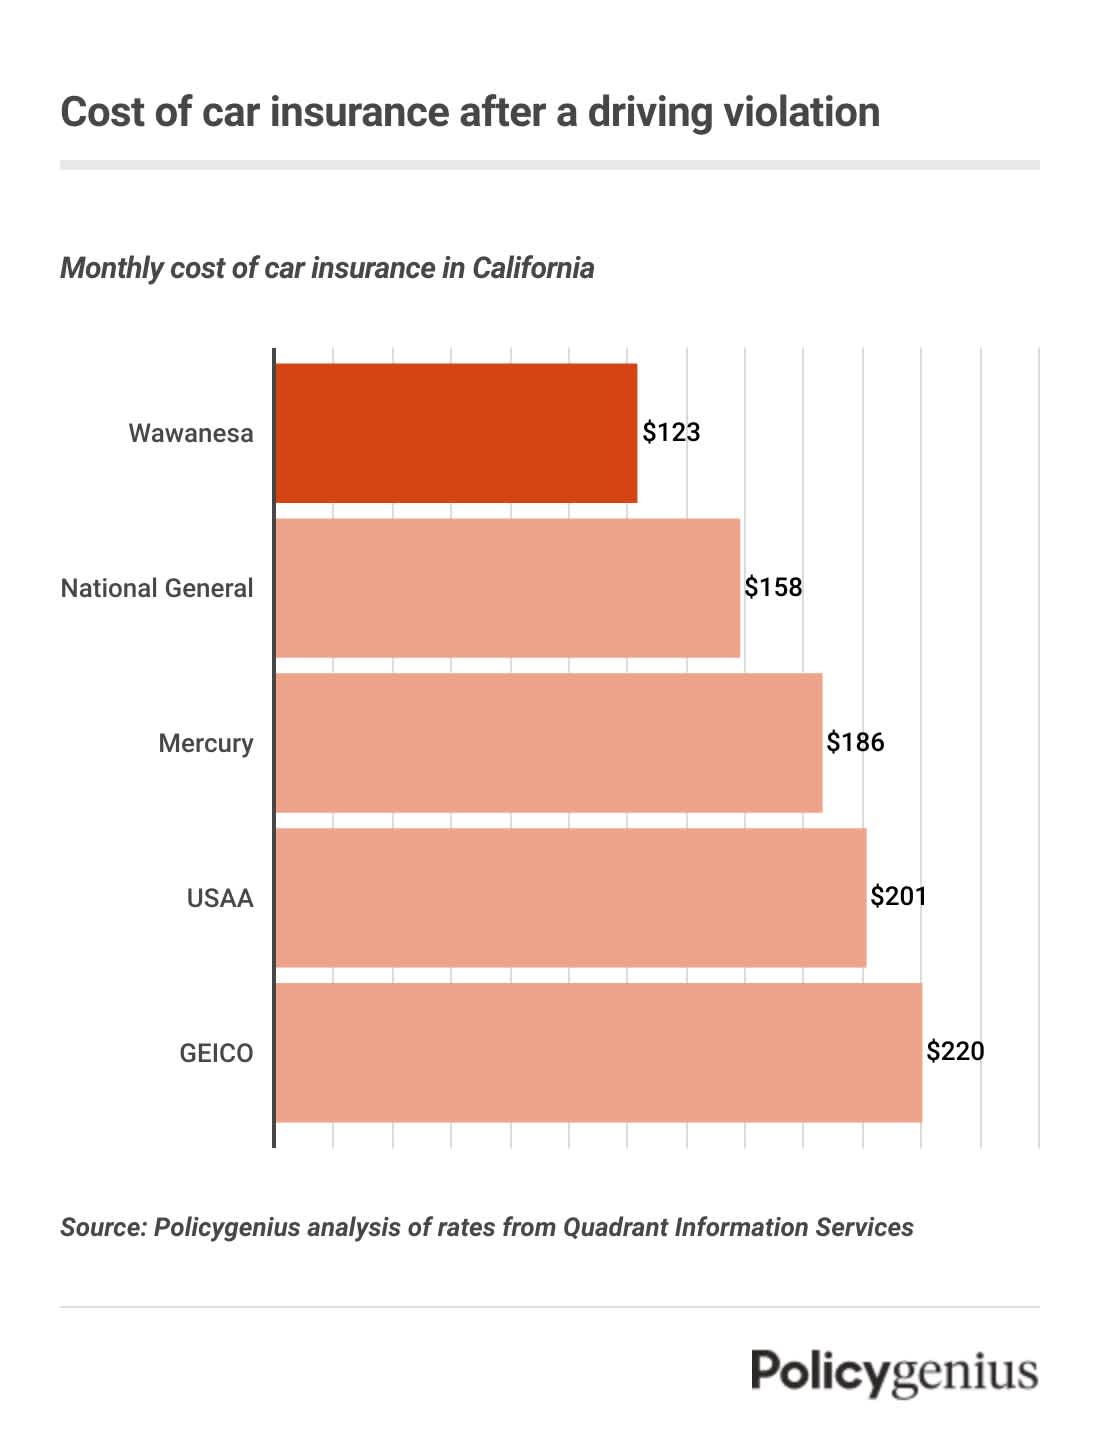
- Assigned Risk Pool (FAIR Plan): A last-resort option for drivers denied coverage due to DUIs, multiple violations, or poor credit. Premiums average $3,000–$5,000/year but provide basic liability protection. A driver in Los Angeles with a DUI might face this option, highlighting the need for SR-22 filings to regain standard rates after 3 years.
- Nonprofit Discounts: Organizations like AAA or AARP negotiate rates with insurers, offering members 5–15% off. A retiree in San Jose could save $400/year by joining AARP’s auto insurance program. Tip: Membership fees often offset savings within 1–2 years.
- Young Driver Programs: Companies like State Farm’s Steer Clear offer discounts to teens who complete driver education courses. A 16-year-old in Chula Vista might reduce premiums by $800/year by enrolling. Requirement: Courses must be state-approved (e.g., through local high schools).
- Military and Veteran Discounts: Insurers like USAA (exclusive to military) or Liberty Mutual (for veterans) offer 10–20% off. A Marine stationed in Camp Pendleton could access USAA’s $800/year discount, unavailable to civilians. Note: Discounts often require proof of service.
7. Common Mistakes to Avoid
Drivers often overlook critical factors that inflate affordable car insurance in California costs. One frequent error is underestimating deductibles: Choosing a $500 deductible instead of $1,000 might lower monthly premiums by $200/year, but a $3,000 hail damage claim would require $2,500 out-of-pocket—a risky trade-off. Another mistake is not shopping annually; premiums can drop 10–15% if a neighbor’s insurer offers a better rate due to updated risk models.
Additionally, drivers sometimes ignore usage-based programs like Progressive’s Snapshot, which can reduce costs by tracking safe driving habits. A study by the Insurance Institute for Highway Safety found that participants in telematics programs filed 20% fewer claims. Finally, skipping the SR-22 process after a DUI can lead to license suspension—costing more in fines ($300–$1,000) than the $50/month SR-22 fee.
8. How to Compare Quotes Effectively
Obtaining accurate quotes requires more than entering basic information into comparison tools like NerdWallet or The Zebra. Drivers must specify their annual mileage, garaging address, and vehicle’s safety features (e.g., anti-lock brakes, backup cameras), as these factors adjust rates by 10–30%. For example, a Tesla in San Francisco might qualify for a $500/year discount due to its low accident rate, while a Ford F-150 in Compton could see higher premiums due to higher theft risks.
Another critical step is requesting quotes from direct insurers and independent agents. Direct insurers (e.g., Geico, Esurance) often undercut agent-based quotes by 5–15%, but agents provide personalized advice—such as bundling options or little-known discounts. Cross-referencing three quotes (e.g., from a direct insurer, a local agent, and a broker like Insure.com) ensures the best rate. Additionally, drivers should ask about paperless billing discounts (5% savings) or loyalty discounts after 5+ years with the same insurer.
11 Proven Tips to Lower Your Premiums
Reducing costs for affordable car insurance in California requires strategic actions, from policy adjustments to lifestyle changes.
Tip 1: Increase Your Deductible. Raising the deductible from $500 to $1,000 can lower annual premiums by $300–$600, but ensure emergency savings cover the higher out-of-pocket cost in case of a claim.
Tip 2: Bundle with Home or Renters Insurance. Combining policies with the same insurer (e.g., Farmers or Liberty Mutual) typically yields 15–20% savings. Compare bundled rates with standalone quotes to confirm the discount.
Tip 3: Install Anti-Theft Devices. Systems like LoJack or OnStar can reduce comprehensive coverage costs by 5–15%. Provide proof of installation to your insurer for immediate rate adjustments.
Tip 4: Maintain a High Credit Score. A 720+ credit score can save 30% compared to a 600 score. Pay bills on time, reduce credit card balances, and dispute errors on your report via AnnualCreditReport.com.
Tip 5: Drive a Low-Risk Vehicle. Cars like the Honda Accord or Toyota Camry qualify for safety discounts, while sports cars (e.g., Nissan GT-R) face higher premiums. Check IIHS Top Safety Picks for eligible models.
Tip 6: Enroll in Defensive Driving Courses. Programs like California’s DMV-approved courses offer 10–15% discounts. Complete one every 3–5 years to maintain eligibility.
Tip 7: Ask About Pay-Per-Mile Discounts. Insurers like Milewise (by Nationwide) charge based on actual miles driven, saving urban drivers with short commutes up to $500/year.
Tip 8: Opt for Paperless Billing. Many insurers (e.g., Geico, Progressive) offer 5% discounts for electronic statements. Enable this in your account settings to trigger automatic savings.
Tip 9: Review and Update Your Policy Annually. Life changes (e.g., moving, marriage, or a new car) can lower rates. For example, relocating from San Francisco to Sacramento might reduce premiums by 20%.
Tip 10: Check for Affinity Group Discounts. Employers, unions, or alumni associations (e.g., UC System) often partner with insurers for exclusive rates. Ask your workplace or local community groups about available programs.
Tip 11: Compare Quotes Every 6 Months. Rates fluctuate due to market changes, claims history, or new discounts. Use tools like Insure.com or Bankrate to compare at least three insurers biannually.
Conclusion
Affordable car insurance in California hinges on understanding regional pricing, leveraging discounts, and avoiding common pitfalls like underinsurance or ignored state programs. By comparing quotes, maintaining a clean driving record, and optimizing coverage levels, drivers can achieve significant savings—often $500–$1,500 annually—without compromising protection. The key lies in proactive research and periodic policy reviews, ensuring long-term affordability in one of the nation’s most expensive insurance markets.
As California’s roads evolve with more EVs and autonomous vehicles, insurers will adapt their models—presenting new opportunities for savings. Staying informed and strategic remains the best path to balancing cost and coverage in the Golden State.