10 Key Facts About Auto Insurance Liability Coverage Only
Table of Contents
- 1. How Liability Coverage Works
- 2. Cost vs. Coverage Trade-offs
- 3. Legal Risks of Liability-Only Policies
- 4. When Liability Coverage Is Sufficient
- 5. Scenarios Where Liability Fails
- 6. State-Specific Minimum Limits
- 7. How to Supplement Liability Coverage
- 8. Common Misconceptions
- Frequently Asked Questions
- 10 Tips to Optimize Liability-Only Coverage
- Conclusion
**Auto insurance liability coverage only** refers to a policy that exclusively covers damages and injuries the policyholder causes to others in an at-fault accident, excluding coverage for personal vehicle damage or medical expenses. For example, if a driver rear-ends another car and is deemed responsible, liability-only insurance would pay for the other party’s vehicle repairs and medical bills—but not the policyholder’s own. This type of coverage is the legal minimum in most U.S. states, designed to protect victims rather than the at-fault driver.
The importance of liability-only policies stems from both legal requirements and financial pragmatism. All 50 states mandate minimum liability limits, which typically range from 25/50/25 (e.g., $25,000 per person/$50,000 per accident for bodily injury, $25,000 for property damage) to higher thresholds in states like California or New York. Choosing **auto insurance liability coverage only** often results in lower premiums, making it attractive for budget-conscious drivers or those with older vehicles. Historically, liability insurance emerged in the early 20th century as a way to shift financial risk from individuals to insurers, reducing the burden on accident victims.
This article explores the nuances of **auto insurance liability coverage only**, including its cost implications, legal risks, and scenarios where it may fall short. Readers will learn how to evaluate whether this coverage aligns with their needs, how to supplement it when necessary, and the potential consequences of underinsuring. Whether driving a paid-off sedan or a leased luxury car, understanding these dynamics ensures informed decisions.
1. How Liability Coverage Works
Liability coverage operates on a straightforward premise: it pays for third-party claims arising from an insured driver’s negligence. When an accident occurs, the insurer investigates fault; if the policyholder is at fault, the liability portion covers medical expenses and property damage for the other party up to the policy limits. For instance, if a driver with 50/100/50 limits causes a crash injuring two pedestrians ($40,000 in medical bills) and damaging a parked car ($15,000), the insurer would pay the full $55,000 without deductibles.
The coverage splits into two categories: bodily injury liability (BIL) and property damage liability (PDL). BIL addresses medical costs, lost wages, and legal fees for injured parties, while PDL covers repairs or replacement of damaged property (e.g., another vehicle, fence, or mailbox). Most states set minimum limits, but drivers can purchase higher limits—often called “umbrella policies”—to protect against lawsuits exceeding standard limits.
2. Cost vs. Coverage Trade-offs
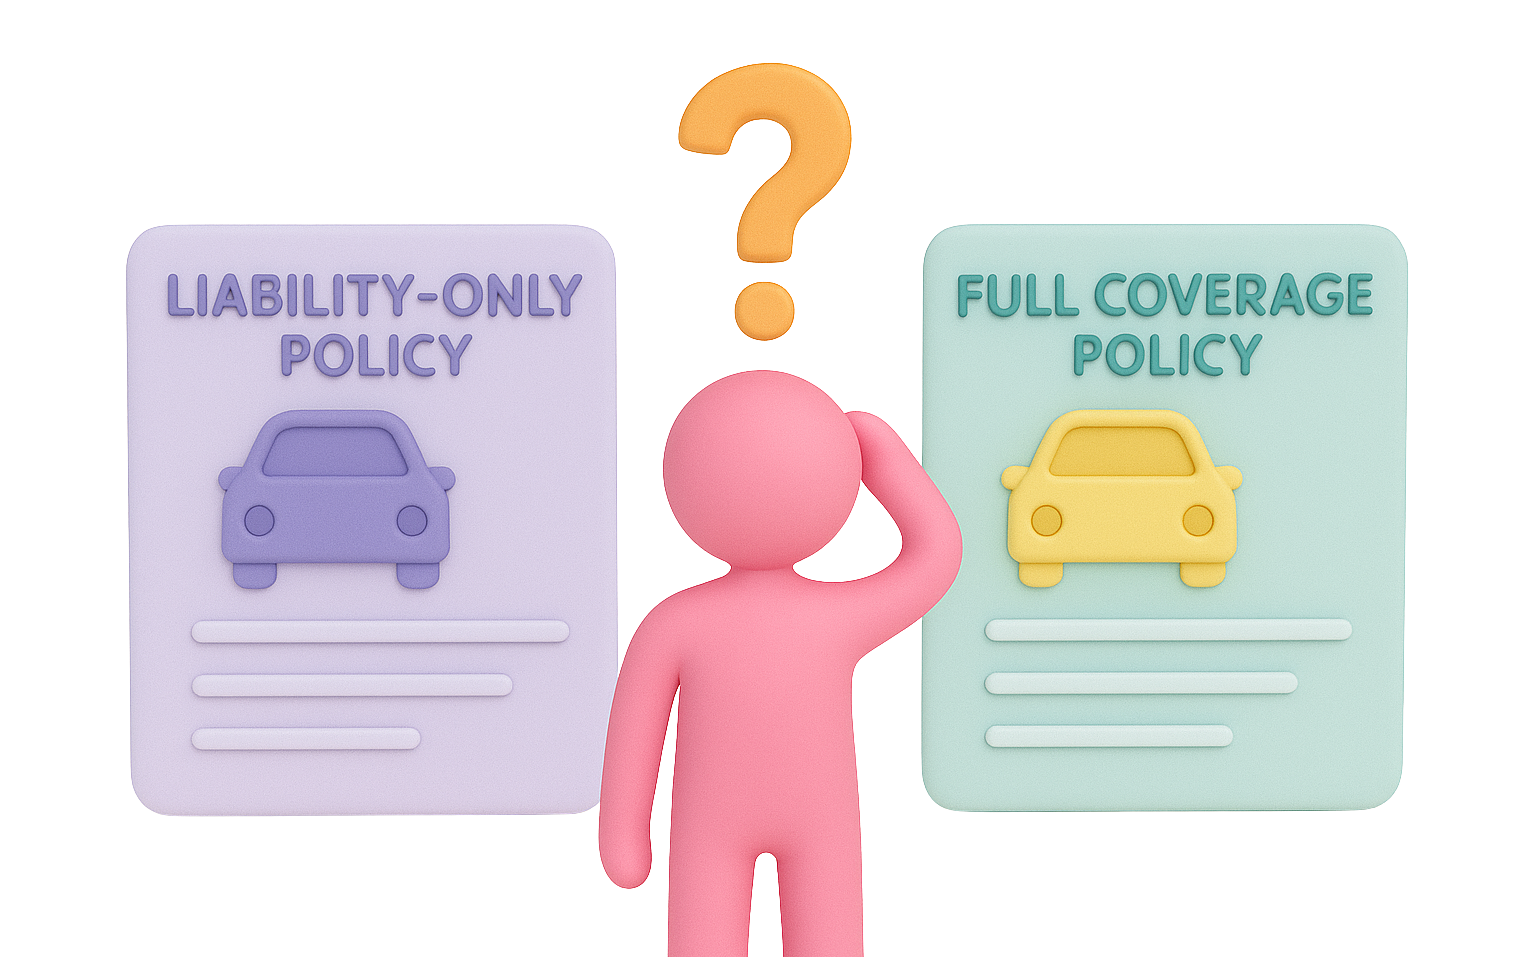
The primary appeal of **auto insurance liability coverage only** is its affordability, typically costing 30–50% less than full-coverage policies. For example, a driver in Texas with a 2015 Honda Civic might pay $800 annually for liability-only coverage compared to $1,500 for a policy including collision and comprehensive. However, this savings comes with critical trade-offs: no protection for the policyholder’s vehicle in accidents (regardless of fault) or from non-collision events like theft, vandalism, or hail damage.
Insurers calculate liability-only premiums based on factors like driving record, location, vehicle type, and credit score. Urban drivers in high-theft areas or those with prior at-fault accidents often face higher rates. While the upfront savings are tempting, the long-term risk of paying out-of-pocket for a totaled car or medical bills can outweigh initial cost benefits.
3. Legal Risks of Liability-Only Policies
Underinsuring with **auto insurance liability coverage only** exposes drivers to severe financial penalties and legal repercussions. If at-fault in an accident with damages exceeding policy limits, the driver remains personally liable for the difference. For example, a driver with $25,000 PDL limits who causes $100,000 in damage to a luxury SUV could face a lawsuit for the remaining $75,000, potentially leading to wage garnishment or asset seizure. Some states, like Florida, allow “no-fault” systems where personal injury protection (PIP) covers initial medical costs, but liability still applies for property damage.
Additionally, leasing or financing a vehicle often requires full coverage, including collision and comprehensive. Violating lender terms can result in forced insurance placement at higher rates or termination of the loan. Even in states with lower minimum limits (e.g., Mississippi’s 25/50/25), the average bodily injury claim costs $21,000, meaning standard limits may be insufficient for catastrophic injuries.

4. When Liability Coverage Is Sufficient
- Owned, paid-off vehicles. Drivers who no longer owe money on their cars can justify liability-only coverage if the vehicle’s value doesn’t justify collision insurance. For example, a 15-year-old sedan worth $2,000 might not warrant $500/year in collision premiums. The trade-off is accepting the risk of paying to repair or replace the car after an accident.
- Low-risk driving profiles. Individuals with clean records, short commutes, and minimal assets to protect may qualify for lower liability rates. A stay-at-home parent in a rural area with a 2010 Toyota Camry poses less risk to insurers than a high-mileage Uber driver in Los Angeles, making liability-only policies more feasible.
- Budget constraints. In households where car insurance competes with other essential expenses (e.g., healthcare, education), liability-only coverage allows reallocation of funds. However, this strategy requires disciplined savings to cover potential out-of-pocket costs, such as a $3,000 deductible for a non-covered accident.
5. Scenarios Where Liability Fails
Liability coverage has critical gaps that can leave drivers vulnerable. **Auto insurance liability coverage only** does not cover:
- Personal injuries or property damage to the policyholder. If a driver hits a deer and totals their car, or if their windshield shatters from a rock, these expenses are excluded. Without collision or comprehensive coverage, the driver must pay repair or replacement costs, which can exceed the vehicle’s value.
- Uninsured/underinsured motorist claims. Even if the other driver is at fault, liability-only policies won’t compensate for medical bills or vehicle damage if the at-fault party lacks insurance. Uninsured motorist coverage (UM) is required in some states (e.g., New Hampshire) but optional elsewhere, adding another layer of risk.
- Legal defense costs in lawsuits. Liability policies may offer limited coverage for legal fees, but complex cases—such as wrongful death lawsuits—can quickly exhaust policy limits. Drivers may need a separate umbrella policy (starting at $1 million) to bridge this gap.
6. State-Specific Minimum Limits
Minimum liability limits vary widely by state, reflecting differences in population density, healthcare costs, and legal environments. For example, New Hampshire has no mandatory liability insurance (though UM coverage is required), while California mandates 15/30/5. These disparities create significant coverage gaps. In states with low minimums (e.g., Mississippi’s 25/50/25), the average hospital stay for a car accident injury ($100,000+) can far exceed policy limits, leaving drivers exposed to lawsuits.
Drivers should compare their state’s minimums to the **100/300/100** benchmark (recommended by insurers for adequate protection). For instance, a driver in New York (25/50/10) might upgrade to 100/300/100 for an additional $200–$400 annually, reducing the risk of financial ruin from a severe accident.
7. How to Supplement Liability Coverage
To mitigate the risks of **auto insurance liability coverage only**, drivers can layer additional protections without full coverage. **Gap insurance** (for leased/financed vehicles) covers the difference between a car’s depreciated value and loan balance after a total loss. **Medical payments (MedPay) or personal injury protection (PIP)** covers policyholder medical expenses, regardless of fault, often for $1,000–$10,000 per accident. Umbrella policies extend liability limits to $1 million or more, providing a safety net for high-net-worth individuals or those facing potential lawsuits.
Another strategy is to self-insure for minor risks, such as setting aside $1,000–$2,000 annually in an emergency fund to cover small accidents. However, this approach requires rigorous risk assessment—e.g., avoiding high-risk activities like off-road driving or towing heavy loads.
8. Common Misconceptions
Many drivers mistakenly believe that liability-only coverage is “enough” because it meets state minimums. However, this assumption ignores real-world costs. For example, the average bodily injury claim in 2023 was $24,000, while property damage claims averaged $4,000—both within typical 50/100/50 limits. Yet, a single catastrophic injury (e.g., a spinal cord injury) can exceed $1 million, leaving liability-only policyholders financially devastated.
Another myth is that rental car insurance is redundant with personal auto policies. While some personal policies extend to rentals, others require separate coverage. Drivers should review their policy’s rental reimbursement limits, which often cap at $30–$50 per day. For long-term rentals or luxury vehicles, standalone rental insurance may be necessary.
10 Tips to Optimize Liability-Only Coverage
Drivers choosing **auto insurance liability coverage only** can reduce risks with these actionable strategies.
Tip 1: Calculate your net worth. If assets (home, savings) exceed liability limits, upgrade to higher coverage or purchase an umbrella policy to protect against lawsuits.
Tip 2: Set aside an emergency fund. Allocate $1,000–$3,000 annually to cover deductibles or minor accidents not addressed by liability insurance.
Tip 3: Review state-specific limits. Compare your state’s minimums to the 100/300/100 benchmark. Upgrading limits may cost $200–$500 more annually but significantly reduces exposure.
Tip 4: Document your driving habits. Low mileage, safe routes, and defensive driving courses can lower liability rates by 5–15%. Insurers like Progressive offer discounts for usage-based programs.
Tip 5: Check rental car policies. Ensure your personal auto policy covers rentals or purchase standalone coverage for trips exceeding 30 days, especially for luxury vehicles.
Tip 6: Bundle with homeowners insurance. Combining auto and home insurance with the same provider often yields 10–20% discounts, improving affordability without sacrificing coverage.
Tip 7: Understand your lender’s requirements. Leased or financed vehicles typically mandate collision/comprehensive coverage. Violating terms can void the loan or trigger forced insurance at higher rates.
Tip 8: Monitor credit score impacts. Some insurers factor credit into liability rates. Paying bills on time and reducing debt can lower premiums by 10–30% over time.
Tip 9: Evaluate ride-sharing risks. Drivers for Uber or Lyft need commercial liability coverage, as personal policies exclude income-generating trips. Supplemental policies cost $10–$20/month but prevent claim denials.
Tip 10: Reassess annually. Life changes (new car, marriage, higher net worth) may require adjusting liability limits or adding supplemental coverage to avoid gaps.
Conclusion
**Auto insurance liability coverage only** offers a cost-effective solution for drivers who prioritize affordability over comprehensive protection. Its role in meeting legal requirements and shielding victims from financial harm is undeniable, but the trade-offs—lack of personal coverage, exposure to lawsuits, and state-specific gaps—demand careful consideration. By supplementing liability with emergency savings, higher limits, or umbrella policies, drivers can strike a balance between budget and risk. As automotive technology evolves and medical costs rise, reassessing coverage needs annually ensures alignment with both legal obligations and personal financial security.
The future of auto insurance lies in personalized, modular coverage—allowing drivers to tailor policies to their risk tolerance and assets. Those who treat liability-only insurance as a starting point rather than an endpoint will navigate the road ahead with greater confidence and financial resilience.
Frequently Asked Questions
Does liability-only insurance cover hitting a pedestrian?
Yes, but only up to the policy’s bodily injury limits. If medical bills exceed those limits, the at-fault driver remains responsible for the difference. For example, a $25,000 BIL limit would cover a pedestrian’s $20,000 hospital bill but leave the driver liable for the remaining $5,000.
Can I add collision coverage later if I start with liability only?
Yes, but premiums may increase due to age or accident history. Insurers often charge more for retroactive coverage, so it’s wise to assess long-term needs upfront. Some companies offer ‘pay-as-you-go’ add-ons for collision, but these rarely match standalone rates.
What happens if I’m sued after an accident with liability-only insurance?
The insurer handles initial claims up to policy limits, but if damages exceed those limits, the driver’s assets (home, savings) can be seized. Umbrella policies or higher liability limits (e.g., 100/300) reduce this risk by extending coverage to $1 million or more.
Is liability insurance cheaper in states with no-fault laws?
Not necessarily. States like Florida or Michigan have higher average premiums due to extensive fraud and high medical costs. No-fault systems shift some liability to insurers but don’t lower base rates for at-fault accidents.
Does liability coverage apply if I borrow someone else’s car?
It depends on the policy. Most liability coverage extends to borrowed vehicles, but exclusions may apply for commercial use or drivers without a license. Always confirm with the insurer to avoid gaps.
Can I drop collision insurance and keep liability only?
Yes, but only if the vehicle is paid off and its value doesn’t justify collision costs. For example, a $3,000 car might not warrant $600/year in collision premiums. However, this requires accepting the risk of paying to repair or replace the car after an accident.
Related articles
14 Key Facts About Auto Full Coverage Insurance You Need to Know
Auto full coverage insurance protects drivers from financial ruin after accidents. Learn what it covers, how to save, and why it’s worth the cost—before…
15 Essential Facts About AAA Auto Insurance Quotes You Need to Know
Discover how AAA auto insurance quotes work, why they matter, and how to get the best rates. Learn pricing secrets, coverage tips, and real-life examples…
