14 Key Facts About Auto Full Coverage Insurance You Need to Know
Table of Contents
- 1. Core Components of Auto Full Coverage Insurance
- 2. What Isn’t Covered by Full Coverage?
- 3. How Pricing Works: Factors and Costs
- 4. Deductibles: The Trade-Off Between Cost and Coverage
- 5. When Full Coverage Is Worth the Investment
- 6. Common Mistakes to Avoid with Full Coverage
- 7. How to Save on Auto Full Coverage Insurance
- 8. Filing a Claim: Step-by-Step Process
- Frequently Asked Questions
- 14 Pro Tips to Maximize Your Auto Full Coverage Insurance
- Conclusion
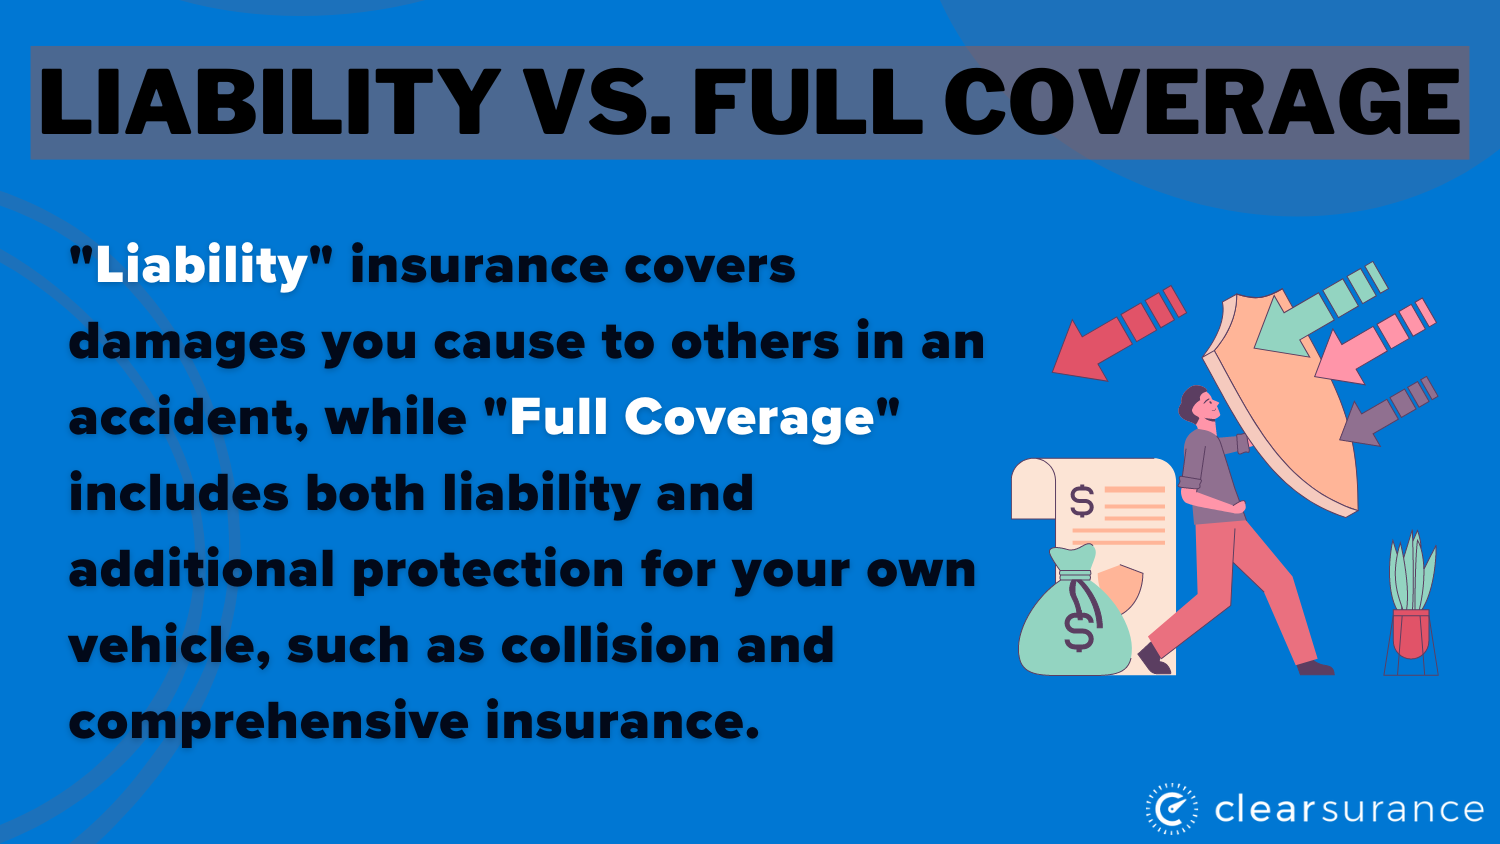
Auto full coverage insurance refers to a comprehensive car insurance policy that includes both collision and comprehensive coverage, alongside liability protection. For example, if a driver totals their 2022 Toyota Camry in a hailstorm or rear-ends another vehicle due to distracted driving, full coverage ensures repairs or replacement are covered—minus the deductible—while liability insurance handles damages to others.
This type of insurance is critical for safeguarding assets, especially for drivers with loans or leases on their vehicles. Without it, a single accident could leave someone responsible for thousands in out-of-pocket expenses. Historically, full coverage emerged as a response to rising vehicle costs and the need for broader financial protection, evolving from basic liability-only policies in the mid-20th century.
Understanding auto full coverage insurance involves exploring its components, cost factors, and how to maximize its value. This guide breaks down what’s included, how pricing works, and practical steps to secure the best policy.
1. Core Components of Auto Full Coverage Insurance
Auto full coverage insurance typically bundles three key coverages: liability, collision, and comprehensive. Liability covers damages to others, while collision and comprehensive address vehicle damage from accidents, theft, or natural disasters. For instance, a policyholder in Florida might file a comprehensive claim after a hurricane damages their windshield, while a collision claim could apply if they hit a guardrail.
Each component serves a distinct purpose. Liability is legally required in most states and protects against lawsuits, while collision and comprehensive are optional but highly recommended for newer or financed vehicles. The interplay between these coverages ensures financial protection in nearly any scenario.
2. What Isn’t Covered by Full Coverage?
Auto full coverage insurance does not cover everything. Common exclusions include intentional damage, mechanical breakdowns, or modifications not disclosed to the insurer. For example, a policyholder who crashes their car after racing it illegally would likely be denied a claim. Additionally, personal belongings inside the vehicle or damage from flooding in areas not classified as natural disasters may also fall outside coverage.
Understanding these gaps is crucial. Many drivers assume full coverage means unlimited protection, but exclusions can lead to unexpected out-of-pocket expenses. Reviewing the policy’s fine print or consulting an agent can clarify what’s excluded and whether supplemental coverage—like gap insurance or a mechanical breakdown policy—is needed.
3. How Pricing Works: Factors and Costs
The cost of auto full coverage insurance varies widely based on several factors, including the driver’s age, location, vehicle make/model, and claims history. Younger drivers or those in high-theft areas typically pay more, while older, low-risk drivers in rural regions often see lower premiums. For example, a 30-year-old in Los Angeles might pay $2,000 annually for a full coverage policy on a Honda Accord, whereas a 50-year-old in rural Iowa could pay half that for the same coverage.
Insurers also consider credit scores, driving records, and the vehicle’s safety ratings. A car equipped with anti-theft devices or advanced safety features may qualify for discounts, reducing the overall cost. Shopping around and comparing quotes from multiple providers can uncover significant savings.
4. Deductibles: The Trade-Off Between Cost and Coverage
- Low Deductibles: Choosing a $250 deductible means higher monthly premiums but minimal out-of-pocket expenses after a claim. For example, a driver who scratches their paint in a parking lot would pay only $250 to repair it, making it ideal for those who prioritize convenience over savings.
- High Deductibles: Opting for a $1,000 deductible lowers premiums but requires more upfront payment after an accident. This works well for drivers with emergency funds who rarely file claims, as the long-term savings often outweigh the higher deductible.
- Deductible Splitting: Some insurers allow splitting deductibles for collision and comprehensive claims separately. This flexibility lets policyholders tailor their coverage to their risk profile, such as lowering the comprehensive deductible if they live in an area prone to hailstorms.
- Impact on Claims: The deductible directly affects claim payouts. A driver with a $500 deductible who files a $3,000 claim will receive $2,500, whereas a $1,000 deductible reduces the payout to $2,000. Balancing deductible height with premium affordability is key.
- Discounts and Waivers: Some insurers offer deductible waivers for claims involving uninsured motorists or comprehensive losses from theft. Reviewing policy add-ons can reveal opportunities to reduce financial burden during claims.
5. When Full Coverage Is Worth the Investment
Auto full coverage insurance is particularly valuable for drivers who own or finance their vehicles. If a car is totaled in an accident, collision coverage ensures the insurer pays the vehicle’s actual cash value (ACV), minus the deductible, allowing the policyholder to replace it without financial strain. For example, a driver with a $25,000 loan on a 2-year-old SUV would avoid defaulting on payments if their insurer covers the vehicle’s full value.
Leased vehicles also mandate full coverage, as lease agreements typically require it to protect the lessor’s interest. Even for older cars, full coverage can be cost-effective if the premiums are lower than the potential repair costs. Drivers should compare the annual premium to the car’s replacement cost to determine if full coverage is justified.
6. Common Mistakes to Avoid with Full Coverage
- Assuming Full Coverage Means No Out-of-Pocket Costs: Many drivers overlook deductibles or exclusions, leading to surprises during claims. For instance, a policyholder who hits a deer might expect full reimbursement but forgets their $500 deductible, leaving them responsible for repairs.
- Skipping the Claims Process Review: Failing to document accidents or provide required details can delay or deny claims. A driver who doesn’t report a hit-and-run within 24 hours may lose coverage for damages, as most insurers have strict reporting windows.
- Ignoring Usage-Based Discounts: Not enrolling in telematics programs like Progressive’s Snapshot or State Farm’s Drive Safe & Save can mean missing out on premium reductions for safe driving. These programs often reward policyholders with discounts of 10–30%.
- Underinsuring for High-Value Vehicles: Drivers of luxury or high-performance cars may need additional coverage, such as agreed value or umbrella policies, to fully protect their assets. A $100,000 Porsche might only receive $50,000 in ACV payouts, leaving the owner undercompensated.
- Not Reassessing Coverage Annually: Life changes—like moving, adding a teen driver, or buying a new car—can impact insurance needs. A driver who doesn’t update their policy after purchasing a new home in a flood-prone area might discover their comprehensive coverage doesn’t extend to water damage.
7. How to Save on Auto Full Coverage Insurance
Reducing the cost of auto full coverage insurance involves strategic choices, such as bundling policies, maintaining a clean driving record, or selecting a higher deductible. Insurers like Geico and Allstate often offer discounts for bundling auto and homeowners insurance, potentially cutting premiums by 15–25%. Additionally, paying annually instead of monthly can yield savings, as insurers charge fees for monthly billing plans.
Another effective strategy is to shop during open enrollment periods or after major life events, such as marriage or retirement, which may qualify a driver for lower rates. Some insurers also reward policyholders for completing defensive driving courses or installing anti-theft devices. Even small adjustments, like improving credit scores or choosing a safer vehicle, can lead to significant long-term savings.
8. Filing a Claim: Step-by-Step Process
Filing a claim under auto full coverage insurance begins with notifying the insurer immediately after an accident. Policyholders should gather evidence, including photos, witness statements, and police reports, to support the claim. For example, a driver involved in a multi-car collision should document damage to all vehicles and exchange information with other parties to avoid disputes.
The insurer will then assign an adjuster to assess the damage and determine liability. If approved, the policyholder receives a settlement or repair estimate. Delays often occur due to missing documentation or disputes over fault, so thorough preparation is essential. Understanding the claims process upfront can streamline resolutions and minimize stress.
14 Pro Tips to Maximize Your Auto Full Coverage Insurance
Optimizing auto full coverage insurance requires proactive steps to lower costs and enhance protection. Here are 14 actionable tips:
Tip 1: Bundle Policies for Discounts. Combining auto and homeowners insurance with the same provider can reduce premiums by 10–25%. For example, insuring both a car and home with State Farm may save hundreds annually.
Tip 2: Maintain a Clean Driving Record. Avoiding tickets and accidents keeps premiums low. A single speeding ticket can increase rates by 15–30%, so defensive driving courses can help mitigate past infractions.
Tip 3: Choose a Higher Deductible. Increasing the deductible from $500 to $1,000 can lower annual premiums by 15–20%. This works best for drivers with emergency savings to cover higher out-of-pocket costs.
Tip 4: Opt for Usage-Based Insurance. Programs like Progressive’s Snapshot track driving habits and reward safe behavior with discounts. Policyholders who drive less than 12,000 miles yearly may qualify for additional savings.
Tip 5: Pay Annually Instead of Monthly. Insurers charge fees for monthly billing, often adding 5–10% to the premium. Paying annually can save $100–$300 per year on a $1,500 policy.
Tip 6: Install Anti-Theft Devices. Cars equipped with GPS trackers or alarms may qualify for theft prevention discounts. For example, LoJack systems can reduce comprehensive premiums by 5–15%.
Tip 7: Improve Your Credit Score. Insurers in most states use credit scores to determine rates. A score improvement from 650 to 750 could lower premiums by 20–30% over time.
Tip 8: Ask About Loyalty Discounts. Some insurers offer discounts for policyholders who renew annually. For instance, Allstate’s “Customer Loyalty Discount” rewards long-term clients with a 5% reduction after 5 years.
Tip 9: Compare Quotes Every 6 Months. Rates fluctuate based on market conditions and personal changes. Reevaluating quotes can uncover better deals, especially after major life events like marriage or retirement.
Tip 10: Select a Safe Vehicle. Cars with high safety ratings (e.g., Toyota Camry, Subaru Outback) often qualify for lower premiums. Insurers like USAA offer discounts for vehicles with top crash-test scores.
Tip 11: Take a Defensive Driving Course. Completing an approved course can earn a 5–10% discount. Programs like AARP’s Smart Driver Course are widely accepted and may also improve driving skills.
Tip 12: Review Coverage Limits Annually. Life changes—such as buying a new home or adding a teen driver—may require adjusting limits. For example, increasing liability coverage from $100K to $300K can protect assets in high-risk scenarios.
Tip 13: Use Paperless Billing. Opting for electronic statements can earn a 1–3% discount. This small change requires no effort but adds up over time.
Tip 14: Document Everything for Claims. Keeping a camera in the car and noting details (e.g., other drivers’ license plates) speeds up claim processing. For instance, photos of a fender bender taken at the scene can prevent disputes over fault.
Conclusion
Auto full coverage insurance provides essential financial protection against accidents, theft, and natural disasters, but its value depends on understanding its components, costs, and limitations. Key aspects include recognizing when full coverage is necessary, avoiding common pitfalls like underestimating deductibles, and leveraging discounts to reduce premiums. By comparing policies, maintaining a safe driving record, and staying informed about coverage options, drivers can secure the best protection without overpaying.
As vehicles and risks evolve, so too should insurance strategies. Regularly reviewing policies ensures alignment with changing needs, whether that means upgrading coverage after purchasing a new car or adjusting limits following a major life event. The goal remains clear: balance comprehensive protection with affordability to drive with confidence.
Frequently Asked Questions
Does auto full coverage insurance protect against uninsured motorists?
Yes, most full coverage policies include uninsured/underinsured motorist coverage as an add-on. This protects policyholders if an at-fault driver lacks insurance. For example, if an uninsured driver causes a $40,000 accident, this coverage would pay for repairs and medical bills up to the policy’s limits.
Can I drop full coverage on an old car?
Dropping full coverage on an older car can save money, but it’s only wise if the annual premium exceeds the car’s value. For instance, if a 10-year-old vehicle is worth $3,000 but the premium is $4,000, keeping full coverage may not be cost-effective. However, liability-only coverage leaves the policyholder responsible for repairs.
Will my rates increase after filing a claim?
Filing a claim can lead to higher premiums, but the impact varies by insurer and state. A single at-fault accident might raise rates by 20–50%, while a comprehensive claim (e.g., theft or hail) may have a smaller effect. Shopping around after a claim can help mitigate long-term cost increases.
Does full coverage include rental car reimbursement?
Rental reimbursement is typically an optional add-on, not standard in full coverage policies. If included, it covers the cost of a rental while the insured vehicle is being repaired, usually up to $30–$50 per day. For example, a policyholder with this coverage would receive $40 daily for a 10-day repair period.
Can I transfer my full coverage policy to a new car?
Transferring a full coverage policy to a new vehicle is possible but depends on the insurer’s rules. Some allow it if the new car is of similar value and meets safety standards. For example, replacing a 2019 Toyota Corolla with a 2020 Honda Civic might qualify for a seamless transfer, avoiding underwriting delays.
What’s the difference between actual cash value and agreed value?
Actual cash value (ACV) pays the depreciated value of a vehicle at claim time, while agreed value guarantees a pre-set payout, often the purchase price. Luxury or classic car owners prefer agreed value to avoid depreciation losses. For instance, a $50,000 Porsche might only receive $30,000 in ACV but $50,000 with agreed value coverage.
Related articles
9+ Key Insights Into Auto and Homeowners Insurance
Understand how auto and homeowners insurance works, its costs, and why it’s essential. Learn how policies protect assets and mitigate risks like a pro.
8 Ways to Get the Best Allstate Quote Car Insurance in 2024
Discover how to secure the most competitive **Allstate quote car insurance** with expert tips on pricing, discounts, and coverage. Start saving…
