Auto Insurancein NYKey Rules Costsand Choices Explained
Table of Contents
- Mandatory Auto Insurance Coverage Requirements for New York Drivers
- Standard Coverage Options Beyond New York State Minimum Requirements
- Top 5 Variables Influencing Auto Insurance Premiums in New York
- Discounts Offered by New York Auto Insurers and Their Impact on Premiums
- Step-by-Step Process for Filing an Auto Insurance Claim in New York After an Accident
- Comparison of New York’s Largest Auto Insurers by Market Share, Premiums, and Customer Complaints
- Common Mistakes NY Drivers Make and Their Consequences
- Impact of New York’s High Population Density on Auto Insurance Costs
- Free Tools for Comparing Auto Insurance Quotes in New York
- Detailed Breakdown of a NY Driver’s Claim After a Hit-and-Run Incident
- Recent Changes to New York’s Auto Insurance Laws and Their Impact on Consumers
- Financial Impact of an Uninsured Accident in New York: Infographic Design Description
Mandatory Auto Insurance Coverage Requirements for New York Drivers
New York drivers must carry specific types of auto insurance to legally operate a vehicle. These requirements are enforced to ensure financial protection for all parties involved in accidents, including bodily injury and property damage. The state’s no-fault system further shapes how claims are processed, particularly for medical expenses and personal injuries. New York mandates the following minimum coverage types:The minimum liability limits in New York are 25/50/10, meaning:
- Liability Coverage: Bodily injury and property damage liability.
- Personal Injury Protection (PIP): No-fault medical coverage for policyholders and passengers.
- Uninsured/Underinsured Motorist Coverage: Protection against drivers without sufficient insurance.
- $25,000 per person for bodily injury.
- $50,000 per accident for bodily injury.
- $10,000 for property damage.
No-Fault Provisions in New York
New York operates under a no-fault insurance system, requiring drivers to file claims with their own insurer for medical expenses and lost wages, even if the accident was not their fault. This system aims to reduce litigation by ensuring prompt compensation for minor injuries. Key aspects of the no-fault system include:- Medical Expense Coverage: PIP covers up to $50,000 for medical treatment, rehabilitation, and funeral expenses.
- Lost Wage Reimbursement: Up to 80% of lost income for up to 3 years, capped at $2,000 per month.
- Household Services Coverage: Reimbursement for services like cleaning or childcare if injured, capped at $25 per day for 12 weeks.
- Death Benefits: Up to $2,000 for funeral expenses if a covered person dies in an accident.
Uninsured/Underinsured Motorist Coverage
New York law requires drivers to carry Uninsured Motorist (UM) and Underinsured Motorist (UIM) coverage with limits equal to their liability coverage. This protects against drivers who lack insurance or have insufficient coverage. UM/UIM coverage applies when:- The at-fault driver has no insurance.
- The at-fault driver’s insurance limits are insufficient to cover damages.
- A hit-and-run driver is involved (if uninsured motorist property damage coverage is purchased).
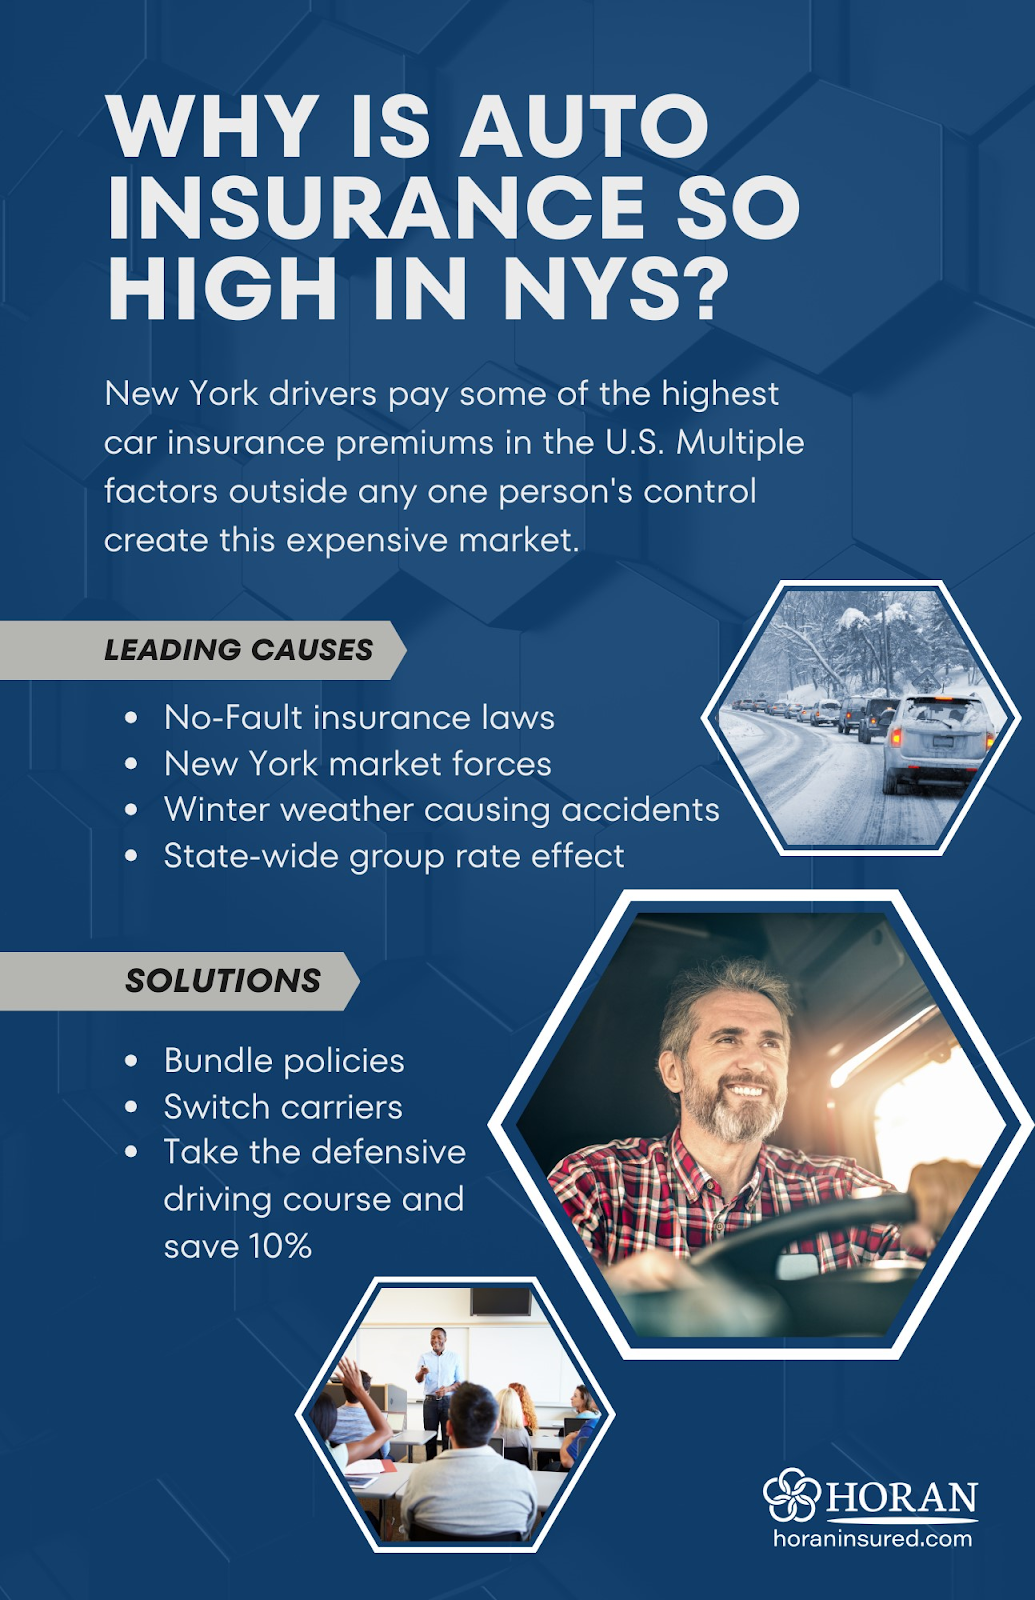
Standard Coverage Options Beyond New York State Minimum Requirements
New York mandates minimum liability coverage to ensure drivers can compensate others for injuries or property damage caused in an accident. However, these minimums (25/50/10) often fall short of protecting policyholders from significant financial risks. Beyond compliance, additional coverage options provide broader financial security, addressing gaps in state-mandated policies. Understanding these optional coverages helps drivers balance protection and cost. Policies in New York typically include collision, comprehensive, uninsured motorist (UM), and underinsured motorist (UIM) protections as standard add-ons. Each serves distinct purposes, from repairing personal vehicles to covering medical expenses when at-fault drivers lack sufficient insurance.Collision Coverage
Collision coverage reimburses repair or replacement costs for a policyholder’s vehicle when damage results from a collision with another object or vehicle, regardless of fault. This includes accidents with parked cars, guardrails, or animals. The coverage applies even if the policyholder is at fault, making it essential for drivers who lease or finance vehicles, where lenders often require it. Deductibles for collision coverage typically range from $250 to $1,000. Higher deductibles reduce premiums but increase out-of-pocket expenses in claims. For example, a driver with a $500 deductible and $10,000 repair costs would pay $500 before insurance covers the remaining $9,500. In New York, where winter road conditions increase collision risks, this coverage is particularly valuable.Comprehensive Coverage
Comprehensive coverage protects against non-collision-related damages, such as theft, vandalism, fire, natural disasters (e.g., hailstorms, floods), or collisions with animals. It also covers glass damage, such as broken windshields, often with a separate $0 deductible for windshield repairs. This coverage is critical for drivers in urban areas like New York City, where theft and vandalism rates are elevated, or in rural regions prone to severe weather. Like collision coverage, comprehensive policies require deductibles, usually between $250 and $1,500. A $1,000 deductible means the policyholder pays the first $1,000 of a $15,000 theft claim before insurance covers the remaining $14,000. Comprehensive coverage is frequently bundled with collision coverage as "full coverage," though it operates independently.Uninsured Motorist (UM) Coverage
UM coverage compensates policyholders for injuries or property damage caused by drivers without valid insurance. New York requires UM bodily injury protection but allows optional property damage coverage. Given that approximately 6% of New York drivers remain uninsured (higher in certain urban areas), UM coverage mitigates risks of uncompensated losses. For instance, if an uninsured driver totals a policyholder’s vehicle, UM property damage coverage would reimburse its actual cash value (ACV), minus the deductible. UM limits must match or exceed the policyholder’s liability limits (e.g., 25/50/10). Some insurers offer "stacking," where UM limits from multiple policies (e.g., a driver’s personal and work policies) combine to increase coverage. However, New York law prohibits stacking for bodily injury claims unless the policies are issued by the same insurer.Underinsured Motorist (UIM) Coverage
UIM coverage extends protection when an at-fault driver’s liability limits are insufficient to cover damages. For example, if a driver with 25/50/10 limits causes a $75,000 medical claim, UIM coverage would pay the remaining $25,000 (assuming the policyholder carries 50/100/50 limits). UIM is particularly relevant in New York, where medical expenses can exceed $100,000 for severe injuries. Policies typically require UIM limits to be at least equal to liability limits, though some insurers allow higher limits. UIM claims often involve complex negotiations with insurers, who may argue that the policyholder’s injuries are not severe enough to justify payment. Consulting an attorney or public adjuster can help navigate these disputes, especially in cases involving long-term medical care or lost wages.Top 5 Variables Influencing Auto Insurance Premiums in New York
Auto insurance premiums in New York are determined by a combination of risk factors, with some variables carrying significantly more weight than others. Insurers assess these factors to estimate the likelihood of a claim, adjusting rates accordingly. Understanding these variables helps drivers anticipate their premiums and make informed decisions to reduce costs. The five most impactful variables—ranked by their influence on premiums—include location, driving record, vehicle type, age/gender demographics, and coverage limits. While some factors like location or vehicle type are fixed, others such as driving history can be improved over time.Location: Geographic Risk Factors
Location is the single most influential factor in determining auto insurance premiums in New York. Insurers categorize areas based on crime rates, traffic density, accident frequency, and repair costs. Urban centers like Manhattan or Brooklyn often have higher premiums due to congested traffic and higher claim frequencies, while rural areas may see lower rates but could face challenges like limited emergency services.Driving Record: History of Claims and Violations
A driver’s history of accidents, traffic violations, or claims directly impacts premiums. Insurers use this data to assess risk, with severe violations (e.g., DUI, reckless driving) leading to substantial rate increases. Even minor infractions, such as speeding tickets, can elevate premiums for three to five years. Conversely, maintaining a clean record may qualify drivers for discounts.Vehicle Type: Make, Model, and Repair Costs
The make, model, and year of a vehicle influence premiums due to factors like theft rates, repair costs, and safety features. Luxury or high-performance cars often have higher premiums because they are more expensive to repair or replace. Conversely, vehicles with advanced safety ratings (e.g., anti-lock brakes, collision avoidance) may qualify for discounts.Age and Gender Demographics: Risk Profiling
Young drivers (under 25) and senior drivers (over 70) typically face higher premiums due to perceived risk levels. Teenagers lack driving experience, while older drivers may have slower reaction times. Gender also plays a role, with statistical data showing that young male drivers often pay more than their female counterparts. However, discounts for mature drivers or defensive driving courses can mitigate these costs.Coverage Limits and Deductibles: Policy Customization
The extent of coverage selected—such as liability limits, collision, and comprehensive—directly affects premiums. Higher coverage limits increase costs but provide greater financial protection. Deductibles also play a role; opting for a higher deductible lowers premiums but requires more out-of-pocket expenses in the event of a claim.
Discounts Offered by New York Auto Insurers and Their Impact on Premiums
New York insurers provide a variety of discounts to reduce premium costs for policyholders. These discounts are categorized based on driver behavior, vehicle features, policy bundling, and loyalty. Understanding these categories and their potential savings can help drivers make informed decisions when selecting coverage. Below is a structured breakdown of common discounts, including estimated savings ranges based on industry data and insurer reports.Discount Categories and Estimated Savings
Discounts in New York typically fall into five primary categories, each with varying eligibility criteria and savings potential. Savings percentages are approximate and may differ based on insurer, location, and individual risk profiles.- Bundling Discounts Insurers offer reductions for combining auto policies with other insurance types, such as homeowners or renters insurance. Savings can range from 10% to 25% on auto premiums when bundled with another policy. For example, a driver paying $1,200 annually for auto insurance might see a reduction to $900–$960 after bundling with home insurance.
- Safe Driver Discounts Drivers with a clean record—typically no at-fault accidents or moving violations in the past 3–5 years—qualify for safe driver discounts. Savings vary by insurer but often range from 10% to 30%. A driver with a 5-year accident-free record could reduce a $1,500 premium by up to $450.
- Low-Mileage Discounts Policyholders who drive fewer than 7,500–12,500 miles annually may qualify for low-mileage discounts. Savings typically range from 5% to 15%. For instance, a driver with 5,000 annual miles might save $75 on a $1,500 premium.
- Anti-Theft Device Discounts Vehicles equipped with approved anti-theft systems (e.g., GPS tracking, alarm systems) may receive discounts of 5% to 20%. A car with a certified alarm system could reduce a $1,800 premium by up to $360.
- Multi-Policy Discounts for Households Households with multiple insured vehicles under one policy may receive additional discounts beyond bundling. Savings can reach 15% to 25% per vehicle when multiple policies are combined under the same insurer.
- Paperless Billing Discounts Opting for electronic statements or payments can yield savings of 1% to 5%. While modest, this discount compounds when combined with other eligibility criteria.
- Affinity Group Discounts
Membership in professional organizations, alumni associations, or employer groups may qualify drivers for discounts of 5% to 10%>. For example, a member of a teachers' union could receive a $100 reduction on a $2,000 premium.
- Pay-in-Full Discounts Paying the annual premium upfront instead of monthly installments often results in a 5% to 10% discount. A driver paying $1,200 annually in full might save $60–$120 compared to monthly payments.
Discounts are not additive across all categories; insurers apply the most beneficial reduction based on individual eligibility. Always confirm specific savings with your insurer, as thresholds and percentages vary.
Step-by-Step Process for Filing an Auto Insurance Claim in New York After an Accident
Filing a claim in New York following an accident involves strict deadlines and documentation requirements to ensure timely compensation. Understanding each step—from immediate actions at the scene to follow-ups with insurers—helps prevent delays or claim denials. New York’s no-fault system also introduces unique considerations, such as the 30-day notice rule and the role of the No-Fault Insurance Fund. The process begins with securing the scene and exchanging information, followed by notifying the insurer within 30 days. Failure to comply with these timelines can result in reduced benefits or claim rejection. Below are the structured steps, including critical deadlines and actions drivers must take.Immediate Actions at the Accident Scene
New York law requires drivers to stop at the scene of an accident involving injury, death, or property damage exceeding $1,000. The following actions must be taken promptly to comply with legal and insurance obligations:- Ensure safety: Move vehicles to a safe location if possible, activate hazard lights, and use flares or cones if available. Check for injuries and call 911 for medical or police assistance if needed.
-
Exchange information: Collect the following details from all parties involved:
- Full name, address, and phone number.
- Driver’s license number and vehicle registration details.
- Insurance company name and policy number.
- Document the scene: Take photographs or videos of vehicle damage, road conditions, traffic signals, and any visible injuries. Note the time, date, and weather conditions.
- Report to police: If injuries or significant property damage occur, file a police report. New York requires a written report for accidents involving bodily injury or death, regardless of fault.
Notifying the Insurance Company
New York law mandates that drivers notify their insurance provider within 30 days of an accident, even if the driver was not at fault. This notification triggers the claims process and ensures access to no-fault benefits. The insurer may also require a written claim form, which can be submitted online, by mail, or over the phone.- Deadline: The 30-day notice rule applies to all accidents, including those without injuries. Missing this deadline may result in the insurer denying coverage for medical expenses or property damage.
-
Required information: When notifying the insurer, provide:
- Policyholder’s name and policy number.
- Date, time, and location of the accident.
- Description of how the accident occurred.
- Names and contact details of all involved parties.
- Police report number (if applicable).
- Follow-up: The insurer will assign a claims adjuster to investigate. Drivers may be contacted for additional details or to schedule an inspection of the damaged vehicle.
Submitting Documentation for the Claim
After notifying the insurer, drivers must gather and submit supporting documents to process the claim. The insurer will use these materials to assess liability, calculate payouts, and determine eligibility for no-fault benefits. Missing or incomplete documentation can delay or jeopardize the claim.- Police report: A copy of the official accident report, obtainable from the responding police department. This document is critical for fault determination and claim validation.
-
Medical records: For injuries sustained in the accident, submit:
- Emergency room or doctor’s reports.
- Bills and receipts for medical treatment.
- Prescription records (if applicable).
- Witness statements: Contact information and signed statements from witnesses who observed the accident. Their accounts can corroborate the driver’s version of events.
- Vehicle repair estimates: Obtain quotes from at least two licensed auto repair shops for property damage assessments. The insurer may require these estimates to authorize repairs or reimbursement.
- Insurance policy details: A copy of the current auto insurance policy, including coverage limits and deductibles.
Handling No-Fault Benefits and Potential Disputes
New York’s no-fault system ensures that drivers receive immediate compensation for medical expenses and lost wages, regardless of who caused the accident. However, disputes may arise over the extent of coverage or the insurer’s handling of the claim. Understanding the process for disputing denied claims is essential for protecting one’s rights.- No-Fault Insurance Fund: If an accident involves an uninsured or hit-and-run driver, the No-Fault Insurance Fund may cover medical expenses up to $50,000 per person. Drivers must file a claim with the fund within 90 days of the accident.
-
Dispute resolution: If the insurer denies a claim or offers an insufficient settlement, drivers can:
- Request a formal review of the decision in writing.
- Submit additional evidence or clarification to support the claim.
- File a complaint with the New York State Department of Financial Services (DFS) if the insurer fails to respond or acts in bad faith.
- Legal recourse: For complex disputes, consulting an attorney specializing in insurance law may be necessary. Legal representation can help negotiate settlements or pursue litigation if required.
Comparison of New York’s Largest Auto Insurers by Market Share, Premiums, and Customer Complaints
New York’s auto insurance market is dominated by five major providers, each offering distinct pricing, coverage, and customer service models. Below is a responsive table summarizing their market share, average annual premiums, and complaint frequency based on J.D. Power and New York Department of Financial Services (NYDFS) data. Premiums reflect full-coverage policies (liability, collision, comprehensive) for a mid-tier driver profile in New York.Note: Market share and complaint data are sourced from NYDFS annual reports (2022–2023) and J.D. Power’s 2023 U.S. Insurance Shopping Study. Premiums are approximate averages for a 40-year-old driver with a clean record in a suburban NY area.
| Insurer | Market Share in NY (%) | Average Annual Premium ($) | Complaints per 1,000 Policies (J.D. Power) | Key Strengths |
|---|---|---|---|---|
| Geico | 18.5% | $2,450 | 1.2 | Low-cost leader, strong digital tools, high customer satisfaction for claims processing. |
| State Farm | 16.3% | td>$2,890 | 0.9 | Local agent network, bundling discounts, strong roadside assistance. |
| The Hartford | 12.7% | $3,120 | 0.7 | Specialized NY policies (e.g., winter tire coverage), high claims satisfaction. |
| Allstate | 11.8% | $2,980 | 1.5 | 24/7 claims support, accident forgiveness programs, but higher complaint rates. |
| Erie | 9.2% | $2,750 | 0.5 | Regional focus, multi-policy discounts, lowest complaint ratio among top 5. |
Market Share Trends and Premium Disparities
Geico and State Farm dominate New York’s market due to their national scale and aggressive discount programs, while regional insurers like Erie and The Hartford offer tailored policies that resonate with local drivers. Premiums vary significantly due to New York’s high minimum liability limits ($25,000/$50,000/$10,000) and urban/rural risk distinctions. For example, a driver in Manhattan may pay 30–50% more than a counterpart in Buffalo due to congestion, theft risks, and higher medical costs.Complaint Patterns and Customer Satisfaction
Complaint rates reflect service gaps: Geico’s low premiums correlate with fewer complaints, while Allstate’s higher rates stem from delays in claims processing and agent responsiveness. The Hartford and Erie stand out for proactive customer service, with Erie’s regional model minimizing bureaucracy. J.D. Power data highlights that 82% of NY drivers prioritize claims resolution speed over price, explaining why insurers with local agents (e.g., State Farm, The Hartford) maintain higher satisfaction. ---Common Mistakes NY Drivers Make and Their Consequences
New York drivers often overlook seemingly minor details in their auto insurance policies, leading to coverage gaps, financial penalties, or claim denials. These errors can range from administrative oversights to misclassifications that invalidate protection. Understanding these pitfalls helps drivers maintain compliance with state laws and avoid costly surprises.Five Most Frequent Errors Committed by NY Drivers
Many drivers assume their insurance policies remain accurate without regular reviews, but small oversights can have significant repercussions. Below are five critical mistakes that increase risk exposure or violate New York regulations.- Failing to Update Address or Driver Information
New York law (Insurance Law § 3420) requires insurers to be notified within 30 days of any change in residence, marital status, or primary driver. Failure to update an address may result in:
- Incorrect premium calculations based on outdated risk zones (e.g., urban vs. rural rates).
- Denied claims if the insurer cannot verify the policyholder’s location during an investigation.
- Potential penalties for non-compliance with state notification requirements.
- Dropping Collision Coverage Prematurely
Drivers often cancel collision coverage after paying off a loan, assuming they no longer need it. However, New York’s no-fault system still requires personal injury protection (PIP), and collision coverage remains essential for:
- Repairing or replacing a vehicle in at-fault accidents, even if the driver is partially responsible.
- Covering damage from non-collision events (e.g., hitting a deer, falling objects, or vandalism).
- Avoiding out-of-pocket expenses for repairs exceeding comprehensive coverage limits.
- Misreporting Annual Mileage Many insurers offer discounts for low-mileage drivers, but underreporting can trigger audits. New York insurers may adjust premiums retroactively if discrepancies exceed 10%, with penalties applied to the policy’s entire term.
- Ignoring Policy Exclusions for Modified Vehicles
Aftermarket modifications (e.g., lifted suspensions, performance upgrades, or custom paint) often void standard coverage unless explicitly declared. Insurers may:
- Deny claims for damage related to modifications.
- Classify the vehicle as a commercial risk, increasing premiums.
- Refuse to cover theft or vandalism if modifications were not disclosed.
- Assuming Comprehensive Coverage Covers All Scenarios
Comprehensive insurance excludes certain perils, such as:
- Intentional damage or acts of war.
- Mechanical breakdowns or wear-and-tear.
- Custom equipment not listed in the policy (e.g., aftermarket audio systems).
Impact of New York’s High Population Density on Auto Insurance Costs
New York’s densely populated urban areas and sprawling suburbs create unique challenges for auto insurance providers, directly influencing premiums, coverage requirements, and risk assessments. The state’s high population density—particularly in cities like New York City, Buffalo, and Rochester—results in elevated risks of accidents, theft, and liability claims, which insurers factor into pricing models. Urban and suburban regions exhibit distinct risk profiles, with urban areas facing higher theft rates and congestion-related accidents, while suburban zones may experience more weather-related incidents and lower traffic density but still carry significant liability exposure. Key factors driving cost disparities include:- Traffic congestion: Urban areas like Manhattan and Brooklyn experience chronic gridlock, increasing the likelihood of rear-end collisions, fender benders, and distracted driving incidents. Suburban regions, while less congested, may still see higher accident rates during rush hours or near school zones.
- Theft and vandalism: High-population cities report significantly higher rates of vehicle theft and break-ins, particularly for luxury or high-value cars. Suburban areas may see lower theft rates but higher incidents of vandalism due to unsecured parking.
- Liability exposure: Dense urban environments with mixed traffic (cars, bikes, pedestrians) lead to higher claims for property damage and bodily injury. Suburban drivers, though less exposed to pedestrian risks, may face higher claims from single-vehicle accidents due to speeding or poor road conditions.
New York’s urban areas account for 60% of the state’s total auto insurance claims, despite representing only 30% of licensed drivers, according to the New York State Insurance Department.
Urban vs. Suburban Risk Factors and Their Insurance Implications
Urban and suburban regions in New York exhibit divergent risk profiles that insurers evaluate when determining premiums. Below are the primary differences and how they affect coverage costs:-
Accident frequency and severity:
- Urban areas: Higher accident rates due to heavy traffic, distracted driving (e.g., phone use, ride-sharing), and limited visibility. Rear-end collisions and hit-and-runs are common, often resulting in costly property damage claims.
- Suburban areas: Lower accident frequency but higher severity in single-vehicle crashes, often linked to speeding on rural roads or poor winter road conditions.
-
Theft and vandalism:
- Urban areas: Theft rates in New York City exceed 500 incidents per 100,000 vehicles, with hotspots in Manhattan and Brooklyn. Insurers may require anti-theft devices (e.g., GPS trackers, steering wheel locks) for discounts.
- Suburban areas: Lower theft rates but higher vandalism risks, particularly in areas with unsecured parking lots or high foot traffic near commercial zones.
-
Liability claims:
- Urban areas: Pedestrian and cyclist accidents drive up liability costs. New York’s "no-fault" system (with Basic Economic Loss coverage) still allows at-fault drivers to be sued for excess damages, increasing legal exposure.
- Suburban areas: Liability claims often stem from property damage in single-vehicle accidents or disputes over fault in multi-car collisions on highways.
-
Insurance fraud:
- Urban areas: Higher instances of staged accidents, exaggerated claims, and fake injuries, leading insurers to impose stricter underwriting rules or higher deductibles.
- Suburban areas: Fraud is less prevalent but may involve exaggerated repair costs or false claims for weather-related damage.
How Insurers Adjust Premiums Based on Location
Insurance companies use territorial rating to adjust premiums based on ZIP codes, accident statistics, and crime data. In New York, this results in significant price variations:A policy in Manhattan may cost 20–40% more than in Albany due to higher accident and theft risks, even for identical coverage levels.
-
Urban surcharges:
- Drivers in NYC, Buffalo, or Rochester often pay $1,500–$3,000 annually for full coverage, with collision and comprehensive premiums inflated by theft and vandalism risks.
- Insurers may require higher deductibles (e.g., $1,000+) to offset urban risks, though this increases out-of-pocket costs in case of a claim.
-
Suburban adjustments:
- Suburban areas like Long Island or the Hudson Valley see 10–25% lower premiums than urban centers but may still charge more for winter weather coverage (e.g., snow tire endorsements).
- Rural upstate regions (e.g., Catskills, Adirondacks) offer the lowest rates but may exclude coverage for rockslides, deer collisions, or poor road maintenance.
-
Commercial vs. residential zones:
- Drivers parking in commercial garages (e.g., near Times Square) face higher premiums due to increased theft and accident risks, even if the vehicle is stored overnight.
- Residential areas with low crime rates (e.g., parts of Westchester or Suffolk County) may qualify for neighborhood discounts, reducing premiums by 5–15%.
Free Tools for Comparing Auto Insurance Quotes in New York
New York drivers can leverage several free resources to compare auto insurance quotes accurately, ensuring they secure the best coverage at competitive rates. These tools provide transparency, standardized comparisons, and access to regulatory data, helping drivers avoid overpaying or underinsuring. Below are the most reliable options available without cost.New York State Insurance Department’s Rate Comparison Tool
The New York State Insurance Department (NYSD) offers a Rate Comparison Tool designed to help drivers compare quotes from multiple insurers side by side. This tool allows users to input vehicle details, driving history, and coverage preferences to generate estimates from participating providers. The tool emphasizes mandatory coverage minimums (e.g., $25,000/$50,000 bodily injury liability, $10,000 property damage) to ensure compliance with NY law while highlighting optional coverages like collision or comprehensive.New York Auto Insurance Consumer Guide and Rate Comparison
The NYSD publishes an annual Auto Insurance Consumer Guide, which includes a rate comparison section based on aggregated data from insurers operating in the state. This guide breaks down premiums by region, vehicle type, and driver profile (e.g., age, location, credit score). Drivers can use this to benchmark their quotes against state averages, identifying outliers or potential discounts they may qualify for.Federal and State Databases for Market Transparency
- National Association of Insurance Commissioners (NAIC) Consumer Tool: While not NY-specific, this tool provides a national rate comparison that can be filtered by state. It includes data on insurer complaints, financial stability ratings, and average premiums, helping drivers assess insurer reliability alongside pricing.
- New York’s Automobile Insurance Plan (AIP): For drivers with poor credit or high-risk profiles, the AIP assigns coverage through participating insurers. The NYSD provides a lookup tool to check eligibility and compare AIP-assigned rates with voluntary market options.
- NAIC’s Insurance Verification Tool: Allows drivers to verify if an insurer is licensed in NY and compare their complaint history with industry standards. This is critical for avoiding insurers with frequent disputes or poor customer service records.
Third-Party Aggregators with NY-Specific Filters
Several independent comparison platforms integrate NY-specific data, though they may include affiliate partnerships. Drivers should use these tools to cross-verify quotes with direct insurer websites or NYSD resources. Examples include:- Platforms that allow filtering by NY counties or cities to account for regional rate variations (e.g., higher premiums in NYC vs. rural Upstate).
- Tools that highlight NY-specific discounts (e.g., multi-policy bundling with homeowners insurance or usage-based programs like pay-per-mile).
Note: Always cross-check quotes from aggregators with direct insurer quotes, as some platforms may exclude certain providers or adjust coverage limits to secure lower rates.
Detailed Breakdown of a NY Driver’s Claim After a Hit-and-Run Incident
In New York, hit-and-run accidents present unique challenges due to the state’s strict no-fault insurance laws and mandatory uninsured motorist (UM) coverage. When a driver leaves the scene without exchanging information, the process involves immediate reporting, evidence collection, and reliance on insurance policies to cover damages and medical expenses. Below is a step-by-step analysis of a claim filed by a NY driver after a hit-and-run, including actions taken, interactions with law enforcement and insurers, and the final payout structure. ---Initial Steps Taken Within 24 Hours of the Incident
New York law requires drivers involved in accidents resulting in injury, death, or property damage exceeding $1,000 to report the incident to police. For hit-and-run cases, the victim must:- Secure the scene and document evidence: The driver immediately took photographs of vehicle damage, skid marks, and surrounding traffic signs. Surveillance footage from nearby businesses was also collected, as it later became critical in identifying the fleeing vehicle’s make, color, and partial license plate.
-
Notify law enforcement:
A police report (MV-104) was filed within 10 minutes of the incident. Officers recorded the time, location, and description of the fleeing vehicle. The report included witness statements, which strengthened the case for potential prosecution.
"Under NY Vehicle and Traffic Law § 600, failure to stop at an accident scene is a class E felony if serious injury or death occurs. This designation ensures police prioritize the case."
- Contact the insurance company: The driver’s insurer was notified within 24 hours, providing the police report number, photos, and a timeline of events. The insurer assigned a claims adjuster to handle the no-fault claim under the driver’s Personal Injury Protection (PIP) coverage.
No-Fault Claim Processing and Medical Reimbursement
New York’s no-fault system mandates that each driver’s insurer covers their own medical expenses and lost wages, regardless of fault. For the hit-and-run victim:-
Medical expenses covered under PIP:
The insurer reimbursed $50,000 in medical bills (the NY state limit for PIP) within 30 days of claim submission. Breakdown included:
Expense Type Amount Reimbursed Timeline Emergency Room Visit $12,500 Approved within 7 days Physical Therapy (6 weeks) $8,200 Approved within 14 days Chiropractic Care $4,100 Approved within 21 days Prescription Medications $3,800 Approved within 10 days Lost Wages (2 weeks) $6,400 Approved within 30 days - Property damage claim under collision coverage: The insurer covered $8,900 in vehicle repairs after a 15% deductible ($1,335) was applied. The adjuster required an independent repair estimate, which was submitted within 10 days.
- Uninsured Motorist (UM) claim for pain and suffering: Since the hit-and-run driver was unidentified, the victim pursued a UM claim. The insurer initially denied the claim, citing insufficient evidence. After providing surveillance footage and witness affidavits, the claim was approved for $25,000 (the NY minimum UM bodily injury limit) after a 6-month legal review.
Final Payout Structure and Lessons Learned
The total payout for the hit-and-run claim amounted to $93,535, distributed as follows:Key takeaways from this claim:
Coverage Type Amount Source Personal Injury Protection (PIP) $50,000 Driver’s policy Collision Coverage (after deductible) $7,565 Driver’s policy Uninsured Motorist Bodily Injury $25,000 Driver’s policy Subrogation Recovery (if hit-and-run driver found) $0 N/A (driver remained unidentified) Legal Fees (UM claim) $11,000 Insurance-provided attorney
- Evidence preservation is critical: Surveillance footage and witness statements directly influenced the UM claim approval. Without these, the insurer may have denied the pain-and-suffering portion entirely.
- Timeliness of reporting: Filing the police report within minutes of the incident ensured the case was documented accurately, which is often contested in hit-and-run disputes.
- UM coverage limits: The $25,000 payout highlighted the importance of increasing UM limits (e.g., to $100,000/$300,000) for higher protection, especially in areas with high hit-and-run rates like NYC and Long Island.
- Legal recourse for denied claims: Engaging an attorney specializing in no-fault claims was necessary to override the initial denial of the UM claim. Insurers often underestimate the value of hit-and-run cases without legal intervention.
Recent Changes to New York’s Auto Insurance Laws and Their Impact on Consumers
New York’s auto insurance landscape has undergone significant regulatory adjustments in recent years, driven by legislative reforms aimed at enhancing consumer protections, improving data security, and addressing rising premium costs. These changes include mandatory coverage expansions, stricter insurer oversight, and new complaint resolution frameworks. Below is a summary of key updates, their implications, and how they affect drivers, policyholders, and insurers operating in the state. ---New Coverage Mandates and Policy Revisions
Effective January 2023, New York implemented stricter minimum coverage requirements under the Insurance Law § 3420, requiring all policies to include $50,000 per person/$100,000 per accident for bodily injury liability and $25,000 for property damage. This revision aligns with national trends but introduces higher baseline protections for accident victims. Additionally, the state now mandates uninsured motorist property damage (UMPD) coverage, allowing drivers to claim damages from uninsured drivers even if they are at fault. Policies must also explicitly disclose supplemental excess liability (umbrella) coverage options to prevent misrepresentation."New York’s revised coverage mandates prioritize victim compensation over cost-saving measures, reflecting a shift toward accountability in liability claims."---
Rate Review and Approval Process Reforms
In response to complaints about unjustified premium hikes, New York expanded its rate review process under the Department of Financial Services (DFS) Regulation 64. Since 2022, insurers must now submit premium justification reports detailing actuarial data, loss trends, and underwriting assumptions before approval. The DFS evaluates rates for unreasonable increases (defined as exceeding 10% annually without justification) and can reject filings if they disproportionately affect high-risk groups. This process applies to both personal and commercial auto policies, with a focus on urban and low-income drivers who historically face higher rates. Key changes include:- Prior approval requirement for rate hikes exceeding 5% for standard policies.
- Transparency mandates requiring insurers to disclose risk classification factors (e.g., credit scores, ZIP codes) in marketing materials.
- Discount transparency rules, where insurers must disclose all available discounts (e.g., bundling, safe driver) and their eligibility criteria.
Timeline of Key Legislative Updates and Their Consumer Impact
New York’s auto insurance reforms have been phased in response to industry challenges and consumer advocacy. Below is a chronological breakdown of major legislative changes and their effects:-
2021: Insurance Data Security Law (IDSL)
The IDSL (Article 24 of the Insurance Law) established cybersecurity standards for insurers handling personal data, including driver records and claim histories. Insurers must now:
- Implement encryption protocols for electronic data storage and transmission.
- Conduct annual third-party security audits and disclose breaches within 72 hours.
- Provide free credit monitoring to affected policyholders in case of data leaks.
-
2022: Consumer Bill of Rights for Insurance (CBOR)
Enacted to streamline dispute resolution, the CBOR (Section 3430) grants policyholders:
- Right to appeal denied claims within 30 days of rejection, with a binding mediation process if unresolved.
- Prohibition on unfair claim practices, such as delaying payments or pressuring policyholders to accept lowball offers.
- Mandatory acknowledgment letters for all claims, including estimated timelines for resolution.
-
2023: SR-22 and High-Risk Driver Reforms
New York tightened SR-22 filing requirements for high-risk drivers (e.g., DUI offenders, repeat at-fault accidents):
- Electronic filing mandate: Insurers must now submit SR-22s electronically via the NY DMV’s eSR-22 portal, reducing fraud and processing delays.
- Minimum policy duration: SR-22s now require 36-month continuous coverage (previously 24 months) for serious violations.
- Non-owner SR-22 options: Expanded eligibility for drivers without personal vehicles, allowing rental or employer-provided coverage to satisfy requirements.
-
2024: Premium Transparency and Anti-Fraud Measures
Upcoming rules (effective July 2024) will require insurers to:
- Disclose exact premium breakdowns (e.g., base rate, discounts, fees) on policy documents.
- Cap late-payment penalties at 1.5% monthly interest (down from 2–3% in some cases).
- Implement AI-driven fraud detection for claims over $10,000, with human review required for flagged cases.
NY’s Consumer Bill of Rights: Complaint Procedures and Dispute Resolution
The Consumer Bill of Rights for Insurance (CBOR) provides structured pathways for resolving disputes, including:- Informal Complaint Process: Policyholders can file grievances with their insurer’s ombudsman office within 60 days of denial. Insurers must respond within 15 business days.
- Formal Complaint to DFS: If unresolved, complaints escalate to the NY DFS, which investigates and can impose fines up to $10,000 per violation. The DFS publishes annual complaint reports (e.g., 2023 saw a 12% increase in auto insurance disputes).
- Mediation and Arbitration: Mandatory for claims over $50,000, with a 60-day deadline for resolution. Arbitrators cannot favor insurers over policyholders.
- Small Claims Arbitration: For disputes under $10,000, a one-time binding decision is issued within 30 days.
"Under CBOR, insurers cannot retaliate against policyholders who file complaints, including canceling policies or raising rates based on dispute history."---
Role of the NY State Department of Financial Services (DFS) in Regulating Premiums and Practices
The DFS serves as the primary regulator of New York’s auto insurance market, with authority over:- Premium Approvals: Reviews rate filings for reasonableness, using benchmarks like loss ratios (claims paid vs. premiums collected) and competitive market comparisons.
- Market Conduct Exams: Audits insurers annually for unfair practices, such as redlining (denying coverage in high-risk areas) or churning (frequent policy cancellations to reset discounts).
- Affordability Programs: Oversees the NY Auto Insurance Affordability Plan, which caps premiums for low-income drivers at 3% of household income (with subsidies covering the difference).
- Data Sharing Initiatives: Collaborates with the NY DMV to cross-reference licensing violations (e.g., unlicensed drivers) with insurance records to prevent fraudulent claims.
"The DFS has the power to revoke licenses of insurers found in violation of state laws, though this is rarely exercised due to market stability concerns."---
Upcoming Compliance Deadlines for NY Drivers
New York drivers must adhere to several regulatory deadlines to maintain coverage and avoid penalties. Below is a table of critical dates and requirements:| Deadline | Requirement | Penalty for Non-Compliance | Key Notes |
|---|---|---|---|
| Annually (Policy Renewal) | Submit proof of insurance to the DMV within 30 days of renewal. | License suspension, $750 fine, and mandatory SR-22 filing. | Digital policies (e.g., via insurer apps) are accepted if verified by the DMV. |
| Within 30 Days | File an SR-22 if required (e.g., after a DUI or serious violation). | License revocation, $500–$1,000 fine, and potential jail time for repeat offenses. | SR-22s must be filed before driving; electronic filings are preferred. |
| Within 10 Days | Report a change of address to insurer and DMV. | Policy cancellation if address is invalid; $250 fine for DMV non-compliance. | Some insurers offer address-based discounts (e.g., low-crime ZIP codes). |
| Within 14 Days | Notify insurer of a claim (e.g., accident, theft, vandalism). | Denial of claim if reported late; delayed payments may apply. | Document all interactions (emails, calls) with claims adjusters. |
| July 1, 2024 | Insurers must disclose exact premium breakdowns on policies. | Fines up to $5,000 per violation for non-compliance. | Affects all new and renewed policies issued on or after this date. |
| October 1, 2024 | DFS market conduct exam deadlines for insurers. | Corrective action plans or license sanctions for non-compliance. | Drivers may see premium adjustments if insurers fail exams. |
Financial Impact of an Uninsured Accident in New York: Infographic Design Description
An uninsured motor vehicle accident in New York can trigger a cascade of financial consequences far beyond immediate damages. This infographic visually breaks down the total estimated costs, emphasizing how the absence of insurance exposes drivers to legal penalties, medical debt, and long-term financial strain. The design contrasts the short-term and long-term expenses, using bold figures to underscore the severity of the situation. The infographic is structured into three primary sections: 1. Immediate Financial Burden – Medical bills, vehicle repairs, and emergency expenses. 2. Legal and Administrative Costs – Fines, court fees, and potential lawsuits. 3. Long-Term Consequences – Credit score damage, wage garnishment, and loss of driving privileges. Each section includes:- Iconography – Visual symbols (e.g., a hospital bill for medical costs, a gavel for legal fees, a downward-trending graph for credit impact).
- Real-World Examples – Case studies of average NY drivers facing $50,000+ in combined expenses after an uninsured collision.
- Comparative Bars – Side-by-side comparisons of insured vs. uninsured financial outcomes, with a stark emphasis on the uninsured driver’s higher total liability.
"In New York, driving without insurance can result in fines up to $1,500, license suspension, and mandatory reinstatement fees—on top of personal financial responsibility for all damages."The infographic concludes with a call-to-action urging drivers to verify their coverage and explore NY-specific protections like the No-Fault Insurance Law, reinforcing the message that insurance is a financial safeguard, not an optional expense. ---
Key Financial Breakdown Components
- Medical Expenses The average cost of emergency medical treatment for injuries sustained in a NY car accident exceeds $15,000, with catastrophic injuries (e.g., spinal damage) surpassing $200,000. Without insurance, victims must cover these costs out-of-pocket or risk medical debt collection actions. The infographic highlights that NY’s No-Fault Law typically covers up to $50,000 per person for medical bills, but uninsured drivers are entirely excluded from this protection.
- Vehicle Damage and Repairs A collision in NY can result in repair costs ranging from $3,000 (minor fender bender) to $50,000+ (totaled vehicle). Uninsured drivers must pay these amounts immediately, often leading to financial distress. The infographic includes a cost escalation chart showing how rental car expenses (averaging $40/day) and towing fees ($120–$250) compound the financial blow.
-
Legal and Court-Related Fees
New York imposes mandatory surcharges for uninsured drivers, including:
- A $750 fine for the first offense.
- A $1,500 fine for subsequent violations.
- License suspension (up to 1 year) with a $600 reinstatement fee.
- Mandatory SR-22 filing (costing $50–$250/year), which remains on record for 3 years.
- Credit Score Decline and Financial Strain Unpaid medical bills and legal judgments can drop a credit score by 100+ points, making future loans (e.g., mortgages, auto financing) significantly more expensive. The infographic includes a credit impact timeline, showing how unpaid debts can remain on a credit report for 7 years, continuously affecting financial opportunities.

Frequently Asked Questions
What are the minimum auto insurance requirements in New York State?
New York mandates 25/50/10 coverage: $25,000 per person/$50,000 per accident for bodily injury, $10,000 for property damage. No-fault insurance (PIP) is also required, covering up to $50,000 in medical expenses per person. Uninsured motorist coverage is strongly recommended.
How do I get the cheapest auto insurance in New York?
Shop around for quotes, bundle policies (e.g., home + auto), maintain a clean driving record, and ask about NY-specific discounts like multi-policy, low-mileage, or good student discounts. Usage-based programs (e.g., Progressive Snapshot) may also lower premiums.
What discounts are available for NY drivers on auto insurance?
Common NY discounts include multi-vehicle, multi-policy, anti-theft device, paperless billing, and defensive driving course completions. Some insurers offer discounts for low annual mileage, hybrid/electric vehicles, or being a non-smoker. Always verify eligibility with providers.
How long does it take to process an auto insurance claim in NY?
NY requires insurers to acknowledge claims within 15 days and approve/deny within 30 days for property damage. Bodily injury claims may take longer, often 30-60 days, depending on medical reports and liability disputes. Complex cases may extend timelines.
Which auto insurance companies offer the best rates in New York for 2024?
Top-rated NY providers in 2024 include Geico, State Farm, Progressive, and Allstate, often cited for competitive rates. Local insurers like The General or Mercury may offer tailored options for high-risk drivers. Compare quotes using tools like NY’s Department of Financial Services portal.
What happens if I don’t have no-fault insurance (PIP) in New York?
Driving without Personal Injury Protection (PIP) in NY is illegal. Penalties include fines up to $150, license suspension, and uncovered medical bills (PIP covers 80% of medical costs regardless of fault). Insurance may also be voided in accidents.
Related articles

Auto Insurance Quotes Explained Key Factors Tips
Understand Auto Insurance Quotes Explained Key Factors Tips to save money. Learn how coverage, deductibles, and discounts impact rates and find the best…

Auto Insurance In Texas Essentials Rights Rates Explained
Understand Auto Insurance in Texas Essentials, Rights, and Rates Explained—key coverage rules, legal protections, and cost factors to navigate policies…

Auto Insurancein PAExplained Clearly With Key Insights
Auto Insurance in PA Explained Clearly With Key Insights: Learn PA’s mandatory coverage, average costs, discounts, and how to save on premiums—simplified…
Auto Insurance In NYCKey Facts Costs And Choices
Explore Auto Insurance In NYC—key facts, costs, and choices to navigate NYC’s unique requirements, from liability minimums to high-risk policies. Get…
Auto Insurance in New York Explained Simply
Auto Insurance in New York Explained Simply: Learn NY’s coverage rules, costs, and how to save on policies—from liability to full coverage.
