Auto Insurance in New York Explained Simply
Table of Contents
- New York’s Auto Insurance Market Structure: Key Players, Regulation, and Market Dynamics
- Mandatory Auto Insurance Requirements in New York: Liability Limits and Exceptions
- Filing a Complaint Against an Insurance Company in New York: Process and Deadlines
- Uninsured/Underinsured Motorist Coverage in New York: Mandates and Optional Upgrades
- Differences Between Collision, Comprehensive, and Uninsured Motorist Coverage in New York
- Impact of Driving Record on Auto Insurance Rates in New York
- Filing an Auto Insurance Claim in New York: Step-by-Step Procedure, Documentation, and Deadlines
- Common Discounts Offered by New York Auto Insurers and Qualification Criteria
- Telematics and Connected Car Technology Transforming Auto Insurance in New York
- Common Types of Auto Insurance Fraud in New York and Case Examples
- Unique Requirements for Commercial Auto Insurance in New York and Liability Limits for Business Vehicles
- New York’s Fair Credit Reporting Act Protections for Drivers with Poor Credit Histories
- Climate-Related Risks and Their Impact on Auto Insurance in New York
- Infographic: How Auto Insurance Premiums Are Calculated in New York
Driving in New York means navigating some of the highest auto insurance costs in the U.S., where dense urban traffic, strict regulations, and unique legal protections shape how policies work. From mandatory no-fault coverage to premiums influenced by everything from ZIP code to driving history, understanding the system is essential for both personal and commercial drivers. This guide breaks down the market structure, legal requirements, and hidden strategies to save money—helping you make informed decisions in a state where insurance choices directly impact your wallet and safety.
New York’s auto insurance landscape is defined by complexity, with premiums shaped by factors like population density, climate risks, and a no-fault system that differs from most states. Whether you’re a city commuter, a rural resident, or a business owner managing a fleet, the right coverage can mean the difference between financial security and unexpected burdens. This overview covers everything from how insurers calculate rates to how technology and fraud prevention are reshaping the industry—equipping you with the knowledge to navigate New York’s roads and policies with confidence.
New York’s Auto Insurance Market Structure: Key Players, Regulation, and Market Dynamics
New York’s auto insurance market operates within a highly regulated framework designed to balance consumer protection with market efficiency. The state’s system integrates private insurers, state-run programs, and stringent oversight by regulatory bodies to address unique risks tied to urban density, traffic congestion, and high accident frequencies. Major players dominate the market, with market share distribution influenced by policy volume, customer demographics, and compliance with New York’s mandatory coverage requirements. The market is structured around three primary components: private insurers, the New York State Insurance Fund (NY State Fund), and the Assigned Risk Plan. Private insurers account for the majority of policies, while the NY State Fund serves high-risk drivers and commercial fleets, and the Assigned Risk Plan ensures availability for drivers unable to obtain coverage in the voluntary market. Regulatory bodies such as the New York State Department of Financial Services (NYDFS) enforce compliance, set premium rates, and monitor solvency, ensuring stability amid the state’s complex risk landscape.Major Insurers and Market Share Distribution
Private insurers lead New York’s auto insurance market, with the top five providers collectively holding over 50% of the market share. These companies prioritize high-volume policies, often targeting suburban and rural areas where premiums are relatively lower. The NY State Fund and smaller regional carriers fill gaps in urban and high-risk zones, where accident rates and theft incidents elevate costs. The top insurers rely on proprietary underwriting models to assess risk, incorporating factors like driving history, vehicle type, and ZIP code-based risk scores. Urban areas, particularly Manhattan and the Bronx, contribute disproportionately to claims, influencing insurers’ pricing strategies and market positioning.Regulatory Bodies and Oversight
The New York State Department of Financial Services (NYDFS) serves as the primary regulator, overseeing solvency, rate filings, and consumer protections. Key functions include:- Approval of premium rates to prevent excessive pricing while ensuring profitability.
- Enforcement of the No-Fault Insurance Law, which mandates Personal Injury Protection (PIP) coverage for medical expenses.
- Monitoring of the NY State Fund and Assigned Risk Plan to prevent market collapse for high-risk drivers.
- Investigation of insurance fraud and unfair claims practices.
Historical Trends in Auto Insurance Premiums: 2013–2023
Over the past decade, New York’s auto insurance premiums have experienced significant volatility, driven by economic cycles, legislative changes, and shifts in risk exposure. From 2013 to 2016, premiums remained relatively stable, averaging a 2–3% annual increase, as insurers adjusted for modest inflation and gradual claim cost growth. However, the introduction of the 2017 No-Fault Insurance Reform—which raised PIP coverage limits to $50,000 per person—sparked a sharp upward trend, with premiums rising by approximately 15% in the following year. TheKey drivers of premium fluctuations:By 2020, premiums had risen by over 40% since 2013, reaching an average of $1,800 annually for full coverage. The COVID-19 pandemic temporarily reduced premiums in 2020–2021 due to decreased mileage, but rates rebounded sharply as traffic resumed and economic activity recovered. As of 2023, New York consistently ranks among the highest-cost states for auto insurance, with urban drivers paying 30–50% more than the national average.
- Economic downturns (e.g., 2008 financial crisis) led to higher uninsured motorist claims, pressuring rates.
- Urban congestion and increased traffic accidents in NYC contributed to higher bodily injury liability costs.
- Natural disasters, such as Hurricane Sandy (2012), temporarily spiked comprehensive coverage demands.
- Legislative changes, like the 2017 reform, directly increased PIP obligations.
Impact of Population Density and Urbanization on Auto Insurance Rates
New York’s extreme population density—particularly in NYC—directly correlates with higher auto insurance premiums, as urbanization amplifies risks such as:- Higher accident frequencies: Manhattan alone accounts for 20% of NYC’s traffic accidents, with intersections like Times Square and Midtown crossing points experiencing collision rates three times the state average.
- Increased theft and vandalism: NYC’s vehicle theft rate is 40% higher than the national average, driving up comprehensive coverage costs.
- Congestion and traffic enforcement: Speeding tickets and moving violations are 25% more common in urban areas, leading to higher surcharges for at-fault drivers.
- Limited parking and road conditions: Narrow streets and frequent construction zones increase liability risks, particularly for commercial insureds.
Top 5 Auto Insurance Providers in New York by Policy Volume and Performance Metrics
The following table ranks the top five insurers in New York by policy volume, customer satisfaction (J.D. Power 2023), and average claims settlement time, based on publicly available industry reports. Customer satisfaction scores are normalized to a 1–5 scale, and claims settlement times reflect the median processing duration in days.| Rank | Insurer | Policy Volume (2023) | Customer Satisfaction (1–5) | Avg. Claims Settlement Time (Days) | Key Strengths |
|---|---|---|---|---|---|
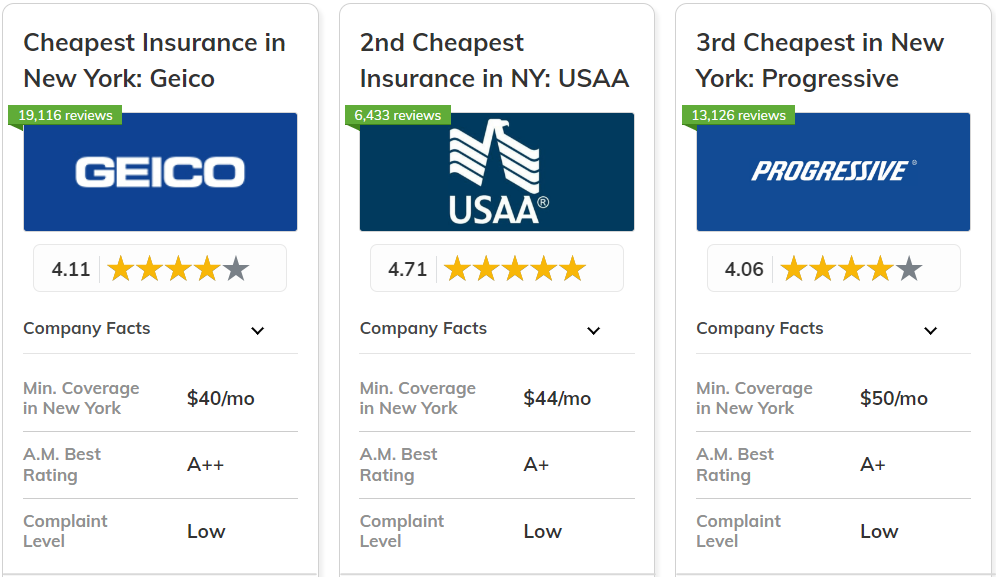
| 1 | Geico | 1,200,000+ | 4.5 | 12 | Low-cost policies, high digital adoption, strong claims efficiency in rural areas. |
| 2 | State Farm | 950,000+ | 4.3 | 15 | Broad coverage options, robust agent network, competitive rates for suburban drivers. |
| 3 | Allstate | 780,000+ | 4.0 | 18 | Customizable endorsements, strong urban claims handling, but higher premiums for high-risk ZIP codes. |
| 4 | Progressive | 650,000+ | 3.8 | 14 | Name Your Price tool for rate transparency, high satisfaction among young drivers, but slower urban claims resolution. |
| 5 | NY State Fund | 500,000+ | 3.5 | 22 | Mandatory for high-risk drivers, stable rates, but lower customer satisfaction due to perceived bureaucratic delays. |
Comparative Analysis: New York vs. California vs. Florida Auto Insurance Markets
The following table highlights key differences in premium costs, coverage mandates, and regulatory frameworks among New York, California, and Florida—three of the most populous and costly states for auto insurance. Data reflects 2023 averages, with regulatory distinctions sourced from state insurance departments.| Metric | New York | California | Florida | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Average Annual Premium (Full Coverage) | $1,850 | $1,900 | $2,100 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Minimum Liability Coverage | $25,000/$50,000/$10,000 (PIP: $50,000) | $15,000/$30,000/$5,000 (No PIP) | $10,000/$20,000/$10,000 (No PIP) | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Uninsured Motorist Coverage Mandate | Required ($25,000/$50,000/$10,000) | Required ($15,000/$30,000) | Required ($10,000/$20,000) | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Regulatory Body | New York State Department of Financial Services (NYDFS) | California Department of Insurance (CDI) | Florida Office of Insurance Regulation (OIR) | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Rate Filing Process | Prior approval required; NYDFS reviews rates for fairness. | File-and-use with limited prior approval; CDI focuses on market stability. | File-and-use; OIR emphasizes competition over strict oversight. |
| Action | Deadline/Timeframe | Notes |
|---|---|---|
| Filing complaint with DFS | No strict deadline, but prompt filing is recommended to preserve evidence. | Complaints older than 18 months may require additional documentation. |
| DFS acknowledgment | Within 30 days of submission | Failure to acknowledge may indicate a processing delay. |
| DFS investigation response | Within 45 days of acknowledgment | Complex cases may extend beyond this period with notice. |
| Legal action for breach of contract | Within 3 years of the alleged violation | Statute of limitations applies to contract disputes. |
| Legal action for statutory violations | Within 4 years of the alleged violation | Covers violations of New York Insurance Law. |

Uninsured/Underinsured Motorist Coverage in New York: Mandates and Optional Upgrades
New York’s uninsured/underinsured motorist (UM/UIM) coverage is a critical component of its no-fault insurance system, designed to protect drivers when at-fault parties lack sufficient insurance. The state mandates minimum UM/UIM limits that align with liability coverage, but policyholders have the option to purchase higher limits or additional endorsements to address gaps in protection. Understanding these requirements is essential for drivers seeking comprehensive coverage against financial exposure in accidents. The minimum uninsured motorist coverage in New York is $25,000 per person and $50,000 per accident, matching the state’s bodily injury liability limits. This coverage applies if the at-fault driver is uninsured, underinsured, or hit-and-run. Underinsured motorist coverage specifically covers scenarios where the at-fault driver’s liability limits are insufficient to cover the claimant’s damages. For example, if a driver with $25,000/$50,000 liability limits causes an accident resulting in $75,000 in medical bills, the policyholder’s UM/UIM coverage would cover the remaining $25,000.New York’s UM/UIM coverage is mandatory for all personal auto policies, but commercial vehicles must carry higher minimums as outlined in the liability section. Failure to maintain UM/UIM can result in voided coverage for uninsured motorist claims.Optional upgrades and additional protections:
- Higher UM/UIM limits: Policyholders may increase limits to $50,000/$100,000 or higher, which is advisable in high-cost areas like New York City, where medical expenses and property damage can exceed standard minimums.
- Stacked UM/UIM coverage: Available for multi-vehicle households, this endorsement allows policyholders to combine the limits of all covered vehicles in a single claim. For example, a family with two cars each carrying $50,000 UM/UIM limits could stack to $100,000 per person.
- Uninsured motorist property damage (UMPD): Optional coverage that reimburses policyholders for damage to their vehicle caused by an uninsured or hit-and-run driver. This is distinct from collision coverage and typically has a separate deductible.
- Medical payments coverage (MedPay): While not a UM/UIM upgrade, MedPay provides supplemental medical benefits for policyholders and passengers, regardless of fault. It is often bundled with UM/UIM policies.
- Hired and non-owned auto coverage: Endorsements for drivers who use vehicles not owned by the insured (e.g., rental cars or rideshare vehicles), extending UM/UIM protection to these scenarios.
- Commercial vehicles: Must carry UM/UIM limits of $50,000/$100,000, with no option to reduce coverage below these thresholds.
- Assigned risk pools: Drivers in the New York State Assigned Risk Plan (for high-risk individuals) may have UM/UIM coverage mandated at minimum levels, with no flexibility to upgrade.
- Hit-and-run coverage: Automatically included in UM/UIM policies, but policyholders must report the incident to law enforcement within 24 hours to maintain eligibility for coverage.
-
Differences Between Collision, Comprehensive, and Uninsured Motorist Coverage in New York
New York’s auto insurance system requires distinct coverage types to address specific risks drivers may face. Understanding these distinctions ensures policyholders select appropriate protections tailored to their vehicle value, driving habits, and financial exposure. Collision, comprehensive, and uninsured motorist coverage each serve unique purposes, with applicability tied to the nature of the incident and the parties involved. Collision coverage addresses direct physical damage to a policyholder’s vehicle resulting from a crash with another vehicle or object, such as a tree or guardrail. This coverage is optional but highly recommended for owned or financed vehicles, as it covers repairs or replacement costs minus the deductible. Comprehensive coverage, on the other hand, protects against non-collision incidents like theft, vandalism, fire, or natural disasters. Unlike collision, comprehensive does not require the vehicle to be in motion during the event. Both coverages operate on a first-party basis, meaning they pay out to the insured driver regardless of fault. Uninsured motorist coverage (UMC) and underinsured motorist coverage (UIMC) serve a different function by addressing third-party liability scenarios. UMC protects policyholders when they are hit by a driver without insurance or with insufficient coverage to fully compensate for damages or injuries. UIMC extends this protection when the at-fault driver’s liability limits are exceeded. These coverages are mandatory in New York under the state’s "no-fault" insurance law, which requires minimum limits of $25,000 per person and $50,000 per accident for bodily injury liability and property damage liability.Collision coverage applies to crashes involving another vehicle or fixed object. Comprehensive coverage covers non-collision incidents like theft or natural disasters. Uninsured/underinsured motorist coverage addresses liability gaps from at-fault drivers.
Applicability Scenarios for Each Coverage Type
The applicability of these coverages depends on the circumstances of the incident and the policyholder’s financial goals.- Collision Coverage is triggered when a vehicle is damaged in a crash with another car, a stationary object, or due to a rollover. For example, a driver rear-ending a parked car would rely on collision coverage to repair their vehicle, assuming the parked car’s owner does not have sufficient liability coverage to cover the damage.
-
Comprehensive Coverage activates in scenarios not involving a collision, such as:
- A vehicle being stolen and later recovered with damage.
- Hailstones damaging the windshield during a storm.
- Vandalism, such as broken windows or scratched paint.
- Uninsured/Underinsured Motorist Coverage becomes relevant when the policyholder is injured or suffers property damage by a driver who lacks insurance or whose policy limits are insufficient. For instance, if a hit-and-run driver causes $80,000 in damages and the policyholder’s UIMC limit is $100,000, the coverage would supplement the gap to cover the remaining $30,000 after the at-fault driver’s liability limits are exhausted.
Impact of Driving Record on Auto Insurance Rates in New York
New York’s auto insurance market heavily weighs driving history as a primary factor in determining premiums. A clean record reflects lower risk, while violations or accidents signal higher likelihood of future claims, directly influencing cost calculations. Insurers use a point-based system tied to state regulations to quantify risk, with consequences lasting years beyond the incident date. The New York Department of Financial Services (NYDFS) mandates insurers follow a standardized point system for traffic violations, where each infraction carries a specific penalty. Points accumulate over time and remain on a driver’s record for up to three years, though their impact on premiums diminishes gradually. At-fault accidents and DUIs carry the most severe penalties, often triggering surcharges that persist beyond the statutory retention period.Point System and Violation Penalties
New York assigns points to violations based on severity, with higher points correlating to steeper rate increases. Common violations and their point allocations include:-
Moving violations:
- Speeding (1–10 mph over limit): 3–6 points
- Speeding (11+ mph over limit): 6–11 points
- Running a red light or stop sign: 4 points
- Improper lane changes: 4 points
- Following too closely (tailgating): 4 points
-
Serious offenses:
- Reckless driving: 6 points
- DUI (driving under the influence): 6 points (first offense); 11 points (subsequent offenses)
- Leaving the scene of an accident: 6 points
- Hit-and-run: 6 points
Example: A driver accumulating 6 points from two speeding tickets (3 points each) will see their premium increase by approximately 20–40% annually, depending on the insurer. The surcharge may remain in effect for up to three years post-violation, though some insurers apply a tiered discount after 12–24 months of clean driving.
Timeframes for Rate Improvement
Insurance premiums begin to stabilize after a violation once the driver demonstrates consistent safe driving. Most insurers implement a good driver discount after 12–24 months without additional violations or claims. For DUIs or at-fault accidents, the timeline extends to 3–5 years, with some carriers offering safe driver programs that reward risk reduction through usage-based insurance (UBI) or telematics.At-Fault Accidents and Long-Term Consequences
At-fault accidents trigger immediate rate hikes, often doubling premiums for the first year. The impact varies by insurer but typically follows this progression:- First at-fault accident: 30–50% increase for 1–3 years
- Subsequent at-fault accidents: 50–100% increase for 3–5 years
- Multiple accidents within a short period: insurer may non-renew policy or classify driver as high-risk
Key Insight: Insurers in New York prioritize loss ratio—the ratio of claims paid to premiums collected—and penalize high-risk drivers disproportionately. A driver with three speeding tickets in two years may face rate exclusions from standard insurers, forcing them into high-cost assigned risk pools or non-standard markets.
Filing an Auto Insurance Claim in New York: Step-by-Step Procedure, Documentation, and Deadlines
Filing an auto insurance claim in New York requires adherence to a structured process, strict documentation protocols, and compliance with state-specific deadlines. Delays or incomplete submissions can lead to claim denials or reduced payouts, emphasizing the importance of meticulous preparation and timely action. Below is a detailed breakdown of the procedural steps, essential documentation, and critical deadlines policyholders must follow. The claim filing process begins immediately after an incident and extends through negotiation or dispute resolution phases. Each stage demands specific actions, from initial notification to final claim resolution. Documentation serves as the foundation for validating claims, while New York’s statutory timeframes enforce accountability for both insurers and policyholders.Immediate Actions Following an Incident
Never leave the scene of an accident in New York, as failure to do so may result in criminal charges under Vehicle and Traffic Law § 1217. This obligation applies regardless of fault or injury severity.
- Gather contact information from all parties involved, including drivers, passengers, and witnesses. Note vehicle details such as license plate numbers, makes, and models, along with any visible damage.
- Take photographs or videos of the scene, vehicle damage, injuries, and road conditions. Focus on angles that clearly show the position of vehicles, skid marks, traffic signs, and environmental factors (e.g., weather, lighting).
- Obtain police reports if law enforcement is notified. In New York, a police report is often required for claims involving injuries, fatalities, or disputes over fault. Reports are typically available within 24–48 hours via local precincts or online portals like NYPD’s Accident Reporting System.
- Exchange insurance information with other parties, including policy numbers, agent contacts, and coverage limits. Verify details aloud to avoid transcription errors.
Notifying Your Insurance Provider
New York Insurance Law § 3420 mandates that policyholders report accidents resulting in injury, death, or property damage exceeding $1,000 to their insurer within 30 days. Failure to comply may void coverage or result in claim denial.
- Contact your insurance company’s claims department via phone or their online portal. Provide a clear, concise summary of the incident, including the date, time, location, and a brief description of what occurred. Avoid speculative statements about fault or damages.
-
Follow the insurer’s instructions for claim submission, which may include:
- Filing a claim online or via a mobile app.
- Scheduling an appointment with an adjuster for an in-person inspection.
- Submitting a written claim via mail or email with attached documentation.
- Request a Claim Number and Adjusted’s Contact Information for future reference. Keep records of all communications, including dates, times, and names of representatives.
Submitting Required Documentation
The completeness and accuracy of submitted documents directly influence claim approval and payout amounts. Missing or inconsistent information is a leading cause of delays or denials.A 2022 study by the New York State Department of Financial Services found that 38% of denied claims in New York were due to insufficient or untimely documentation.
- Police Report: If filed, submit a copy of the report (e.g., NYPD Form FR-802 or equivalent). The report’s Narrative Section is critical, as it often reflects law enforcement’s assessment of fault.
-
Medical Records: For injury claims, provide documentation from healthcare providers, including:
- Diagnoses, treatment plans, and prescribed medications.
- Bills and receipts for medical services, rehabilitation, or therapy.
- Prescription records linking injuries to the accident.
-
Vehicle Repair Estimates: Obtain at least three written estimates from licensed repair shops for property damage claims. Include:
- The shop’s contact information and license number.
- A detailed breakdown of parts and labor costs.
- Photographic evidence of damage before and after repairs.
- Witness Statements: Collect written or recorded testimonies from witnesses, including their full names, addresses, and phone numbers. Statements should describe what they observed, such as vehicle positions, speeds, or actions of drivers.
- Maintenance and Vehicle History: Provide records of recent maintenance (e.g., oil changes, tire rotations) and any pre-existing damage to the vehicle. This helps distinguish between accident-related and pre-existing issues.
- Proof of Ownership: Submit a copy of your vehicle’s title or registration to confirm policyholder ownership.
Deadlines and Timeframes
New York imposes strict deadlines to ensure timely claim processing and prevent undue delays. Policyholders must be aware of these timelines to avoid losing rights to compensation.Under New York Insurance Law § 3420, insurers have 30 days to acknowledge receipt of a claim and 60 days to investigate and respond. Failure to comply may entitle the policyholder to additional damages.
-
Policyholder Deadlines:
- Report the claim to your insurer within 30 days of the incident (or as specified in your policy).
- Submit all requested documentation within 15–30 days of the insurer’s request, unless an extension is granted.
- For personal injury protection (PIP) claims, file a Notice of Claim within 30 days of treatment for injuries (NY Insurance Law § 5104).
-
Insurer Deadlines:
- Acknowledge receipt of the claim within 30 days of notification.
- Complete investigation and provide a written response (approval, denial, or counteroffer) within 60 days of claim filing.
- For disputes involving bodily injury or property damage, the insurer must notify the policyholder of its intent to deny within 60 days and provide a detailed reason for denial (NY Insurance Law § 3420).
-
Statute of Limitations:
- For property damage claims, file a lawsuit within 3 years of the incident (CPLR § 2001).
- For personal injury claims, file within 3 years of the accident (CPLR § 2001).
- For wrongful death claims, file within 2 years of the death (NY Estates, Powers and Trusts Law § 5-4.1).
Common Discounts Offered by New York Auto Insurers and Qualification Criteria
New York insurers provide a range of discounts to reduce premiums for policyholders who meet specific criteria. These discounts often reflect safer driving habits, loyalty, or demographic advantages. Understanding eligibility requirements ensures drivers maximize savings without missing out on applicable benefits. Insurers in New York typically categorize discounts into three primary groups: behavior-based, policy bundling, and demographic or lifestyle-related. Each category addresses different aspects of risk assessment, from driving behavior to financial stability. Below are the most frequently offered discounts and their qualification standards. ---Behavior-Based Discounts
Behavior-based discounts reward drivers who demonstrate lower risk profiles through consistent safe driving or technology-assisted monitoring. These discounts are among the most widely available and can significantly reduce annual premiums."Safe driving discounts are the most common behavior-based incentives, often requiring a clean driving record for three to five years."
Safe Driver Discount- Definition: Offered to drivers with no at-fault accidents, moving violations, or serious infractions (e.g., DUIs) within the past 3–5 years.
- Typical Savings: 5%–25% off premiums.
- Provider Examples:
- Geico: Automatic discount for drivers with no violations in the last 3 years.
- State Farm: Offers up to 30% for accident-free and ticket-free records.
- Progressive: "Accident-Free Discount" for no at-fault claims in 3 years.
- Verification: Insurers may pull Motor Vehicle Reports (MVR) from the New York DMV to confirm eligibility.
- Definition: Targets drivers who log fewer annual miles, reducing exposure to accident risks.
- Typical Savings: 5%–15% for mileages below 7,500–12,000 miles/year.
- Provider Examples:
- Nationwide: Offers up to 10% for drivers under 10,000 miles/year.
- Travelers: "Pay As You Drive" program discounts based on logged miles.
- Verification: Some insurers require odometer readings or GPS tracking for validation.
- Definition: Uses real-time driving data (e.g., speed, braking, phone use) to adjust premiums. Detailed under a later section.
Policy Bundling Discounts
Bundling multiple insurance policies (e.g., auto + homeowners) with the same provider often yields substantial savings. Insurers incentivize multi-policy customers by reducing administrative costs and fostering long-term loyalty."Bundling discounts can range from 10% to 25% on auto premiums when combined with home, renters, or life insurance."
Multi-Policy Discount- Definition: Applied when a driver insures more than one vehicle or combines auto with another policy (e.g., homeowners).
- Typical Savings: 10%–25% on auto premiums.
- Provider Examples:
- Allstate: Up to 25% for bundling auto with home or renters insurance.
- Liberty Mutual: 15% discount for multi-policy holders.
- Eligibility: Requires ownership of other insurable assets (e.g., home, condo).
- Definition: Reward for managing policies digitally (e.g., online bill pay, mobile app usage).
- Typical Savings: 5%–10% off premiums.
- Provider Examples:
- Farmers Insurance: 5% discount for paperless billing.
- American Family: Up to 10% for electronic statements and payments.
Demographic and Lifestyle Discounts
These discounts target specific groups, such as students, military personnel, or professionals, based on perceived lower risk or financial responsibility. While less common than behavior-based discounts, they can provide meaningful savings for eligible applicants. Student Discount- Definition: Offered to full-time students under 25 with a GPA of 3.0 or higher (varies by insurer).
- Typical Savings: 5%–15%.
- Provider Examples:
- Geico: "Good Student Discount" for grades B or better.
- The Hartford: Up to 10% for students with a 3.0+ GPA.
- Verification: Requires proof of enrollment (e.g., report card, university ID).
- Definition: Extended to active-duty military, veterans, and their families as a token of appreciation for service.
- Typical Savings: 5%–10%.
- Provider Examples:
- USAA: Exclusive to military members (not available to the general public).
- State Farm: 5% discount for active-duty personnel and veterans.
- Verification: Military ID or discharge papers.
- Definition: Applied for vehicles equipped with anti-theft systems (e.g., alarm, GPS tracking) or advanced safety features (e.g., automatic braking, lane departure warnings).
- Typical Savings: 5%–20%.
- Provider Examples:
- Progressive: Up to 10% for vehicles with anti-lock brakes (ABS) or airbags.
- Travelers: 5% for vehicles with theft-deterrent systems.
- Verification: Inspection reports or manufacturer certifications.
- Definition: Targets drivers aged 50+ who complete defensive driving courses or demonstrate low-risk profiles.
- Typical Savings: 5%–10%.
- Provider Examples:
- AARP (via partner insurers): Discounts for members aged 50+ with AARP-affiliated providers.
- Nationwide: "Mature Driver" discount for seniors with a clean record.
- Verification: Completion certificate for defensive driving courses (e.g., AARP Smart Driver).
Telematics and Connected Car Technology Transforming Auto Insurance in New York
Telematics and connected car technology are reshaping auto insurance in New York by enabling insurers to shift from traditional risk assessment models to dynamic, data-driven approaches. These technologies allow for real-time monitoring of driving behavior, vehicle performance, and environmental factors, leading to more accurate premium calculations and personalized coverage options. New York’s dense urban traffic, mixed driving conditions, and high accident rates make these innovations particularly impactful for both insurers and policyholders. The integration of telematics leverages onboard diagnostics (OBD-II ports), GPS tracking, and in-car sensors to collect granular data on speed, braking patterns, acceleration, mileage, and even road conditions. Insurers use this data to adjust premiums based on actual driving habits rather than broad demographic assumptions. For example, a driver who frequently navigates congested Manhattan streets with smooth braking may receive a lower premium compared to someone with aggressive driving patterns in suburban areas.Real-Time Risk Assessment and Usage-Based Insurance (UBI)
Real-time risk assessment through telematics enables insurers to implement Usage-Based Insurance (UBI), where premiums fluctuate based on live driving behavior. In New York, this model is gaining traction due to its alignment with the state’s diverse driving environments—from high-speed highways like the Thruway to tight city streets with frequent stops. Key components of real-time risk assessment include:- Behavioral Tracking: Systems like those offered by Progressive’s Snapshot or State Farm’s Drive Safe & Save monitor acceleration, hard braking, and cornering. For instance, a driver who consistently speeds on the Long Island Expressway may see their premium increase, while a cautious driver in Brooklyn could qualify for discounts.
- Geofencing and Location-Based Risks: Telematics can identify high-risk zones, such as areas near construction sites in Queens or flood-prone regions in Staten Island. Insurers may apply temporary surcharges or offer incentives for avoiding these areas during peak risk hours (e.g., rush hour in Manhattan).
- Vehicle Health Monitoring: Connected cars can detect mechanical issues (e.g., tire pressure, engine performance) before they lead to accidents. Insurers like Allstate partner with repair networks to offer maintenance discounts, reducing claim risks.
- Environmental Factors: Data from connected cars can adjust premiums based on weather conditions. For example, winter driving in upstate New York may trigger temporary premium adjustments due to increased slippery road risks.
Regulatory and Privacy Considerations in New York
While telematics offer significant benefits, New York’s regulatory environment imposes strict guidelines to protect consumer privacy and ensure fair practices. The New York State Department of Financial Services (DFS) requires insurers to:- Obtain explicit consent from policyholders before collecting telematics data.
- Provide clear explanations of how data is used to determine premiums.
- Ensure data security and prevent unauthorized access, aligning with New York’s Cybersecurity Regulation (23 NYCRR Part 500).
Challenges and Adoption Trends
Despite its potential, telematics adoption in New York faces challenges:- Digital Divide: Older drivers or those in low-income areas may lack access to connected vehicles or smartphones, limiting participation in UBI programs.
- Data Accuracy and Bias: Early telematics models were criticized for favoring certain demographics (e.g., younger, tech-savvy drivers). Insurers are now refining algorithms to mitigate bias, such as by normalizing data for urban vs. rural driving patterns.
- Consumer Skepticism: Some drivers fear "big brother" surveillance or believe premiums may rise based on unpredictable factors. Insurers counter this by emphasizing transparency, such as providing real-time driving scores via mobile apps.
Common Types of Auto Insurance Fraud in New York and Case Examples
Auto insurance fraud remains a significant challenge in New York, costing insurers and policyholders billions annually through deceptive practices. These schemes exploit vulnerabilities in claims processes, often involving collusion between claimants, medical providers, or repair shops. Staged accidents and policy misrepresentation are among the most prevalent fraud types, with high-profile cases exposing systemic risks. Understanding these patterns helps insurers and regulators implement targeted countermeasures. Fraudulent activities in New York’s auto insurance sector frequently target the state’s high-density urban areas and major highways, where opportunistic schemes thrive. Investigations by the New York State Department of Financial Services (NYDFS) and the New York State Insurance Fraud Prevention Unit (NYIFPU) have uncovered recurring tactics, including exaggerated injury claims, fake repair invoices, and coordinated crash-for-cash operations. Below are the most common fraud types, illustrated with documented cases.Staged Accidents and Crash-for-Cash Schemes
Staged accidents involve deliberate collisions orchestrated to fabricate claims, often with prearranged participants. These schemes exploit high-traffic intersections or congested roadways, where drivers can feign loss of control or sudden stops. In 2022, a case in Brooklyn involved a group of individuals using rental cars to stage rear-end collisions at red lights, targeting unsuspecting drivers. Investigators found that the ringleaders had prior convictions for similar fraud and used social media to recruit accomplices posing as "injured" victims. The NYIFPU recovered over $2 million in fraudulent payouts linked to this operation. Another prevalent variant is the "swoop and squat" tactic, where a driver suddenly brakes to force a rear-end collision. A 2021 case on the Long Island Expressway revealed a network of drivers with fake medical records, claiming whiplash or back injuries after being "swooped." Surveillance footage confirmed the accidents were premeditated, with participants using coded signals to identify targets. The NYDFS noted that these schemes disproportionately affect commuters during rush hours, when drivers are less likely to question minor fender benders.Policy Misrepresentation and Exaggerated Claims
Policy misrepresentation occurs when claimants provide false information about their driving history, vehicle condition, or accident details to secure higher payouts. This includes inflating repair costs, falsifying medical diagnoses, or misrepresenting prior claims. A 2020 investigation in Queens uncovered a ring of chiropractors who colluded with claimants to fabricate chronic pain diagnoses following minor accidents. The scheme involved falsified MRI reports and exaggerated treatment plans, with some patients receiving unnecessary surgeries. The NYIFPU prosecuted 15 individuals, leading to restitution of $3.5 million. Exaggerated damage claims are another common tactic, where policyholders or repair shops inflate the cost of repairs to justify higher compensation. In a 2019 case in Buffalo, a body shop was caught submitting duplicate invoices for the same parts and charging for "unseen" damage under the vehicle’s hood. Inspectors discovered that the shop had altered repair estimates to include non-existent labor hours. Such practices force insurers to raise premiums, indirectly penalizing honest policyholders.Medical and Repair Provider Collusion
Fraud often extends beyond claimants to include medical providers and repair shops that profit from inflated or fabricated services. In 2018, a Manhattan-based network of doctors and physical therapists was indicted for billing insurers for unnecessary treatments following low-impact accidents. The scheme involved claimants receiving "diagnoses" for soft-tissue injuries that required months of therapy, despite no visible trauma. The NYDFS estimated that this particular ring defrauded insurers of over $5 million before dismantling the operation. Similarly, repair shops may engage in "pad and flip" schemes, where they inflate repair costs by adding unnecessary services or using substandard parts. A 2023 case in Albany revealed that a chain of auto repair centers had installed aftermarket parts labeled as "OEM" (Original Equipment Manufacturer) to justify higher labor charges. Insurers detected the fraud through comparative pricing analysis, leading to criminal charges against the shop owners.Phantom Vehicles and Non-Owned Damage Claims
Phantom vehicle fraud involves claimants filing for damage to a car that does not exist or is not insured under their policy. This tactic is often used by individuals with poor driving records or those seeking quick cash. In 2021, a Bronx resident was arrested for filing multiple claims under a stolen vehicle’s VIN, using fake repair receipts to justify payouts. The NYIFPU traced the fraud through license plate cross-referencing, revealing that the vehicle had been reported stolen weeks before the "accident." Non-owned damage claims occur when a policyholder files for damage to another person’s vehicle without their consent. A 2020 case in Rochester involved a driver who staged a hit-and-run against a parked car, then filed a claim under the victim’s policy using a forged registration. The fraud was uncovered when the victim reported the theft of their vehicle, prompting an investigation into the timing of the "accident."High-Risk Behaviors and Fraud Hotspots in New York
Certain geographic areas and driving conditions in New York correlate with higher fraud incidence, often tied to economic disparities, traffic patterns, or lack of surveillance. Below is a table identifying fraud hotspots and associated risk factors, based on NYIFPU and NYDFS reports.Location High-Risk Behaviors Fraud Type Key Risk Factors Brooklyn (Intersections: Flatbush Ave, Nostrand Ave) Staged rear-end collisions at red lights Crash-for-cash High pedestrian traffic, poor surveillance, rental car availability Queens (Queens Boulevard, Grand Central Parkway) Exaggerated injury claims with chiropractor collusion Medical fraud High density of medical providers, commuter congestion Manhattan (Midtown, Times Square) Phantom vehicle claims using stolen VINs Non-existent vehicle fraud High theft rates, dense parking areas, anonymous reporting Buffalo (NY Route 19, I-90 near Niagara Falls) Inflated repair costs with duplicate invoices Repair shop fraud Rural repair shop clusters, limited insurer oversight Long Island (LIE, Northern State Parkway) "Swoop and squat" tactics during rush hour Staged accidents High-speed limits, low police presence at night Albany (Downtown, near State Capitol) Non-owned damage claims with forged registrations Hit-and-run fraud Low surveillance in parking garages, high tourist traffic Rochester (NY Route 5, I-490) Exaggerated whiplash claims with fake medical records Medical fraud High density of pain clinics, rural-urban commuter mix Note: Fraud hotspots often overlap with areas of economic distress, where claimants may face financial incentives to exploit insurance systems. Insurers should prioritize fraud detection in these regions using localized data analytics.
Unique Requirements for Commercial Auto Insurance in New York and Liability Limits for Business Vehicles
New York imposes strict regulations on commercial auto insurance to address the state’s high traffic density, diverse fleet operations, and legal obligations under tort law. Businesses operating vehicles in New York must comply with minimum liability coverage requirements, which exceed federal standards and vary based on vehicle type, cargo, and employee exposure. Understanding these mandates ensures compliance while mitigating financial risks from accidents, lawsuits, or regulatory penalties. The state mandates minimum liability limits for commercial vehicles under Insurance Law § 3420 and Vehicle and Traffic Law § 388. For most business-owned vehicles, the baseline is:- $25,000 per person for bodily injury
- $50,000 per accident for bodily injury
- $10,000 per accident for property damage
- $750,000 for for-hire carriers transporting passengers or property
- $1,000,000+ for hazardous materials or oversize loads
- $5,000,000 for nuclear energy materials (per 49 CFR Part 387)
Specialized Liability Requirements by Vehicle Type
New York’s regulations categorize commercial vehicles into distinct classes, each with tailored liability mandates. Businesses must verify coverage aligns with their fleet composition to avoid underinsurance risks.-
Private Passenger Vehicles Used for Business
Vehicles with a Gross Vehicle Weight Rating (GVWR) ≤ 10,000 lbs used for deliveries, employee commutes, or service calls must meet § 388 minimums. However, if the vehicle is primarily used for business (e.g., >50% of mileage), insurers may classify it as a commercial policy, requiring higher limits (e.g., $1,000,000 combined single limit for liability).
Example: A plumbing company with a van used for 70% business mileage must purchase a commercial policy, even if the van’s GVWR is under 10,000 lbs.
-
Commercial Trucks and Trailers
Vehicles with a GVWR > 10,000 lbs (e.g., box trucks, delivery vans, dump trucks) must comply with § 388 and federal FMCSR if transporting interstate. New York’s No-Fault Law also imposes $50,000 per person/$100,000 per accident for basic economic loss coverage (PEL/BEL) in addition to liability limits.
Example: A moving company with a 26,000-lb truck must carry $1,000,000 liability and $50,000/$100,000 PEL/BEL for all drivers, including employees and independent contractors.
-
Hazardous Materials and Oversize Loads
Vehicles transporting hazardous substances (e.g., flammable liquids, toxic chemicals) require $5,000,000 liability under 49 CFR § 387.9 and New York State Department of Environmental Conservation (DEC) permits. Oversize loads (e.g., construction equipment) may need escort vehicles and additional liability up to $2,000,000 for property damage.
Example: A waste management firm hauling industrial solvents must file DEC Route Permits and carry $5,000,000 liability + pollution cleanup coverage under Comprehensive General Liability (CGL).
Additional Legal Obligations Beyond Liability
New York imposes non-liability-related requirements that commercial policies must address to avoid fines or coverage denials. These include:-
Uninsured/Underinsured Motorist (UM/UIM) Coverage
New York’s No-Fault Law requires UM/UIM coverage for all commercial policies, with minimums of $25,000 per person/$50,000 per accident for bodily injury. For commercial vehicles, this extends to employees and hired drivers, even if the accident involves a non-owned vehicle.
Example: A rideshare driver (e.g., Uber for Business) must have UM/UIM on their personal policy if the vehicle is not insured under the business commercial policy, creating a coverage gap unless endorsed.
-
Workers’ Compensation Exclusions
While workers’ compensation is separate, commercial auto policies must exclude medical payments for employees if the business already carries a NY Workers’ Compensation Board (WCB) policy. However, non-employees (e.g., independent contractors, customers) must be covered under the commercial policy’s medical payments or liability sections.
Example: A landscaping business with employees covered under WCB must still ensure $5,000 medical payments for a customer injured in a work-related accident, as WCB does not apply to third parties.
-
Financial Responsibility Filings
New York requires annual filings with the New York State Department of Motor Vehicles (DMV) for commercial policies, including Proof of Financial Responsibility (MV-100) for all registered vehicles. Failure to file results in license suspension for the business and its drivers.
Example: A fleet of 10 delivery trucks must submit MV-100 forms for each vehicle annually, with penalties of $100–$500 per violation for late or missing filings.
New York’s Fair Credit Reporting Act Protections for Drivers with Poor Credit Histories
New York’s insurance regulations balance risk assessment with consumer protections, particularly for drivers whose credit histories may negatively impact their premiums. The Fair Credit Reporting Act (FCRA) and state-specific laws provide safeguards against unfair credit-based pricing, ensuring transparency and recourse for drivers who believe their credit is being misused or inaccurately reported by insurers. New York’s Insurance Department enforces strict guidelines under the Insurance Law § 2324 and General Obligations Law § 5-516, which prohibit insurers from using credit information in a discriminatory manner. Insurers must adhere to the New York State Department of Financial Services (DFS) regulations, which limit the weight of credit scores in determining premiums and require insurers to provide clear explanations if credit history is a factor in rate increases.Credit-Based Insurance Score Restrictions
Insurers in New York cannot use credit scores as the sole or primary factor in underwriting decisions. The DFS mandates that:Credit information may be considered only if it is statistically relevant to predicting risk, and insurers must demonstrate compliance with the New York State Insurance Law § 2324 to avoid unfair discrimination.
Additionally, insurers must provide policyholders with a credit-based insurance score notice if credit history influences their premium. This notice must include:- The insurer’s credit-based insurance score model.
- How the score was calculated.
- Contact information for disputing inaccuracies.
Disputing Inaccurate Credit Information in Insurance Ratings
Drivers who believe their credit history is being misrepresented or unfairly impacting their insurance rates have recourse under both federal FCRA protections and New York State Insurance Law. The process involves:- Obtain a Free Credit Report: Request a free annual credit report from the three major credit bureaus (Equifax, Experian, TransUnion). Discrepancies in these reports may affect insurance scores.
- Dispute Errors with Credit Bureaus: File a dispute directly with the credit bureaus if inaccurate information is found. The bureaus are legally required to investigate within 30 days under the FCRA.
- Request a Credit Report from the Insurer: Insurers must provide a copy of the credit report used to determine the policyholder’s score upon request. This allows for direct comparison with bureau reports.
- File a Complaint with the New York DFS: If the insurer fails to correct inaccuracies or unjustly uses credit history, file a complaint with the New York State Department of Financial Services via their online portal or by mail. The DFS investigates potential violations of insurance laws.
- Seek Mediation or Legal Assistance: For persistent issues, policyholders may consult consumer advocacy groups (listed later in this section) or legal aid organizations specializing in insurance disputes.
Appealing Credit-Based Rate Increases
If an insurer raises premiums based on credit history, policyholders can challenge the decision through a structured appeal process. New York law requires insurers to:Provide a written explanation of how credit information contributed to the rate increase, including the specific credit-based insurance score and its impact on the premium.
The appeal process includes:- Review the Insurer’s Justification: Policyholders must receive a detailed breakdown of how credit history influenced the rate. If the justification is unclear or based on outdated/inaccurate data, the appeal strengthens.
- Request Additional Documentation: Gather proof of improved credit (e.g., recent credit score reports showing improvement) or evidence of errors in the insurer’s credit assessment.
-
Submit an Appeal in Writing:
Send a formal letter to the insurer outlining the dispute, including:
- Policy number and effective date.
- Explanation of why the credit-based rate increase is unjustified.
- Supporting documents (e.g., corrected credit reports, payment history).
- Escalate to the New York DFS: If the insurer denies the appeal, file a complaint with the DFS Consumer Services. The DFS may intervene if the insurer violated § 2324 or failed to follow fair rating practices.
- Explore Alternative Insurance Options: If the appeal fails, consider shopping for quotes from insurers that do not use credit scores (e.g., some specialty or usage-based insurers). The New York Automobile Insurance Plan (NYAIP) may also provide coverage for high-risk drivers.
Climate-Related Risks and Their Impact on Auto Insurance in New York
New York’s auto insurance market faces growing challenges from climate-related risks, including severe storms, flooding, and extreme weather events. These hazards increase claim frequencies, elevate premiums, and force insurers to adjust coverage terms, exclusions, and underwriting criteria. Flooding alone accounts for nearly 40% of all natural disaster-related claims in the state, with coastal and low-lying regions bearing the highest exposure. Insurers respond by refining risk models, implementing stricter coverage limits, and introducing specialized policies to mitigate financial losses.Coverage Exclusions and Policy Adjustments Due to Climate Risks
Standard auto insurance policies in New York typically exclude damage caused by floods, hurricanes, or windstorms unless explicitly added as optional coverage. Most insurers treat these events as "acts of God," requiring separate endorsements such as:- Comprehensive Flood Coverage: Adds protection for water damage from storms or overflowing rivers, often limited to specific flood zones. Policies may exclude gradual seepage or rising groundwater unless specified.
- Hail and Windstorm Endorsements: Extends coverage for damage from high winds or falling debris, but deductibles may be higher for named storms (e.g., tropical cyclones). Some insurers cap payouts per event.
- Mold and Secondary Damage Exclusions: Many policies exclude mold growth or secondary water damage (e.g., from a burst pipe caused by storm-related power outages) unless purchased as an add-on.
Regional Variations in Premiums and Risk Exposure
New York’s geography creates stark differences in climate-related risks across regions, directly influencing insurance costs. A comparison of high-risk and low-risk areas reveals distinct patterns:Region Primary Climate Risks Impact on Premiums Coverage Challenges Long Island (Coastal) Flooding, storm surges, hurricanes Premiums 30–50% higher than state average; insurers may deny coverage in FEMA-designated flood zones. Frequent exclusions for wind-driven rain or saltwater corrosion; mandatory elevation certificates for flood claims. Western NY (Buffalo/Rochester) Severe thunderstorms, hail, winter ice storms Moderate premium increases (15–25%) due to hailstorm clusters; insurers offer storm chaser discounts. Limited coverage for ice dam damage unless bundled with homeowners’ policies. Upstate (Adirondacks/Catskills) Winter blizzards, flash flooding, rockslides Lower premiums but higher deductibles for seasonal risks; insurers may require off-road vehicle endorsements. Exclusions for mudslides or tree falls unless added as a separate peril. New York City (Urban) Subway flooding, power outages, extreme heat-related breakdowns Premiums reflect higher theft and liability risks; some insurers exclude coverage for vehicles parked in low-lying garages. Limited protection for water damage from sewer backups unless explicitly endorsed. Insurer Adaptations to Climate Change in New York
Insurers are implementing innovative strategies to address climate risks while maintaining profitability. Key adaptations include:- Dynamic Pricing Models: Some insurers use real-time weather data to adjust premiums during high-risk periods (e.g., hurricane season). For example, a driver in Suffolk County may see a temporary surcharge during a tropical storm warning.
- Flood Zone-Specific Policies
Insurers like Progressive and State Farm offer tiered flood coverage based on FEMA maps, with lower premiums for elevated properties. Allstate provides "FloodSmart" endorsements in high-exposure areas, including mandatory sandbagging discounts.
Note: Insurers with strong financial ratings (e.g., Amica, Farmers) are more likely to honor claims in climate-related disasters, while weaker carriers may impose stricter exclusions or deny payouts for "catastrophic events."
Infographic: How Auto Insurance Premiums Are Calculated in New York
New York’s auto insurance premiums are determined by a complex interplay of risk-based factors, regulatory mandates, and underwriting models. Unlike many states, New York operates under a no-fault system with strict coverage requirements, which directly influences pricing. The premium calculation process integrates driver behavior, vehicle characteristics, geographic location, and historical claim data, weighted differently based on risk severity. Below is a structured breakdown of the key components and their relative weighting in New York’s premium determination.Core Components of Premium Calculation
Auto insurers in New York rely on actuarial models and state-mandated guidelines to assign risk scores. The primary factors include:-
Driver Profile
Age, gender, driving history (violations, accidents, DUIs), and credit score (where legally permissible) are critical inputs. Younger drivers (under 25) or those with poor credit scores may face higher premiums due to statistically higher risk profiles.
- Age/Gender Weighting: 20-25% of total risk score (e.g., a 19-year-old male may pay 30-50% more than a 40-year-old female).
- Driving Record: 30-35% of risk score (e.g., a single at-fault accident increases premiums by 20-40%; a DUI can add 50-100%).
- Credit-Based Insurance Scores: 10-15% (where applicable; banned in some cases but still used by some insurers).
-
Vehicle Characteristics
The make, model, year, and repair cost of the vehicle directly impact premiums. High-performance or luxury cars (e.g., BMW, Tesla) incur higher theft/theft repair risks, while commercial vehicles face additional liability exposures.
- Vehicle Age/Value: 15-20% of risk score (newer/expensive cars cost more to repair or replace).
- Theft Risk: 5-10% (e.g., a 2023 Tesla Model 3 in NYC may add 15% to premiums vs. a 2015 Honda Civic).
- Safety Ratings: 5-8% (vehicles with top safety scores from NHTSA/IIHS may qualify for discounts).
-
Geographic Location
New York’s urban-rural divide creates stark premium disparities. Zip codes in NYC, Long Island, or Buffalo correlate with higher accident rates, traffic density, and crime, leading to elevated rates.
- Urban vs. Rural: 25-30% of risk score (e.g., a policy in Manhattan may cost 50% more than one in the Adirondacks).
- Traffic Density: 10-15% (areas with high congestion, e.g., I-95 corridors, see higher collision risks).
- Crime Rates: 5-10% (theft/vandalism risks in high-crime areas increase premiums).
-
Coverage Limits and Deductibles
New York mandates minimum liability limits (25/50/10), but higher limits or optional coverages (e.g., collision, comprehensive) increase premiums. Deductible selection inversely affects costs.
- Liability Limits: 10-12% (e.g., increasing from 25/50/10 to 100/300/50 may add 20-30% to premiums).
- Collision/Comprehensive: 15-20% (full coverage adds ~$1,000-$2,500/year vs. liability-only).
- Deductible Choice: 8-10% (higher deductibles reduce premiums by 10-25%).
-
Insurance History and Claims
Past claims, policy lapses, or switching insurers frequently can signal higher risk. Insurers use loss ratios (claims paid vs. premiums collected) to adjust rates.
- Claims Frequency: 20-25% (multiple claims in 3 years can increase premiums by 40-60%).
- Policy Lapses: 10-15% (a gap >60 days may void discounts or increase rates by 30%).
- Insurer Loyalty: 5-8% (long-term customers may receive 5-10% discounts).
Weighting and Actuarial Models
New York insurers use territorial rating (grouping areas by risk) and classification systems to standardize premiums. The New York State Department of Financial Services (DFS) oversees rate filings to ensure fairness. Key models include:-
Experience Rating
Adjusts premiums based on an individual’s claim history over 3-5 years. Frequent claimants face surcharges, while claim-free drivers receive credits.
- Example: A driver with no claims for 5 years may receive a 10-15% discount.
- Example: Two at-fault accidents in 2 years may increase premiums by 50-70%.
-
Schedule Rating
Manually adjusts premiums for unique risk factors (e.g., high-net-worth individuals, exotic vehicles). Common in commercial or specialty policies.
-
Merit Rating
Rewards safe driving via telematics (e.g., usage-based insurance programs like Progressive’s Snapshot or State Farm’s Drive Safe & Save).
- Discounts: 5-30% for low mileage, smooth braking, and avoiding night driving.
- Penalties: 10-20% increase for aggressive driving or high mileage.
Regulatory Overrides and Mandates
New York’s No-Fault Law and assigned risk plan (for high-risk drivers) introduce additional layers to premium calculation:-
No-Fault Add-Ons
Personal Injury Protection (PIP) and basic economic loss coverage are mandatory, adding ~$300-$800/year to premiums regardless of fault.
-
Assigned Risk Pool (JUA)
Drivers denied coverage by private insurers are assigned to the Joint Underwriting Association (JUA), which charges higher premiums (often 20-50% above market rates) to offset elevated risk.
-
Territorial Rate Variations
The DFS divides New York into 10 territorial rating areas, each with predefined base rates. For example, NYC’s rates are ~40% higher than Upstate regions due to density and risk.
Visual Representation of Weighting
The infographic would depict a pie chart or bar graph breaking down the average premium composition in New York, with approximate percentages:- Driver Profile: 35%
- Vehicle Characteristics: 20%
- Geographic Location: 25%
- Coverage Limits: 10%
- Claims History: 10%
Auto insurance in New York isn’t just about meeting legal minimums—it’s about balancing cost, coverage, and risk in a state where urban density, climate hazards, and strict regulations create unique challenges. By understanding how premiums are determined, how to appeal denials, and which discounts or endorsements could lower your costs, you can protect yourself without overpaying. Whether you’re shopping for personal coverage or managing a commercial fleet, the key lies in proactive decision-making: comparing providers, leveraging technology, and staying informed about changes in the law. In a state where accidents and claims are as much about location as they are about luck, preparation is your best asset on the road.
Frequently Asked Questions
What are the minimum auto insurance requirements in New York?
New York mandates 25/50/10 coverage: $25,000 per person for bodily injury, $50,000 per accident, and $10,000 for property damage. Uninsured Motorist coverage is also required unless rejected in writing. Violations may result in fines, license suspension, or vehicle impoundment.
How do I find the cheapest auto insurance in New York?
Compare quotes from multiple insurers, leverage discounts (e.g., bundling, good driver, low mileage), maintain a clean driving record, and consider usage-based programs. New York’s high premiums average $2,500/year, but rates vary significantly by location, age, and vehicle type.
What coverage types are available beyond the state minimum?
Common optional coverages include collision (repairs after accidents), comprehensive (theft/damage), medical payments (medical bills), uninsured/underinsured motorist (UM/UIM), and gap insurance (loan payoff for totaled cars). Full coverage typically combines collision and comprehensive.
How long does it take to process an auto insurance claim in New York?
Claims processing times vary: simple claims (e.g., minor fender benders) may resolve in days, while complex cases (e.g., injuries, disputes) can take weeks to months. Insurers have 30 days to acknowledge claims and 90 days to settle under New York regulations. Delays often stem from repair shop backlogs or liability disputes.
Are there discounts for electric or hybrid vehicles in New York?
Some insurers offer green vehicle discounts (5–15%) for EVs/hybrids due to lower repair costs and theft risks. Discounts may also apply for anti-lock brakes, safety tech (e.g., automatic emergency braking), or completing defensive driving courses. Always verify with providers like GEICO, State Farm, or Progressive.
What should I do if my New York auto insurance policy is canceled or non-renewed?
Insurers must provide 30–60 days’ notice for cancellation/non-renewal. If denied, request a written explanation and file a complaint with the New York Department of Financial Services (DFS). You can shop for new coverage immediately, but gaps may void future claims. High-risk drivers may need assigned risk plans like the New York Automobile Insurance Plan (NYAIP).
Related articles

Auto Insurance In NYCKey Facts Costs And Choices
Explore Auto Insurance In NYC—key facts, costs, and choices to navigate NYC’s unique requirements, from liability minimums to high-risk policies. Get…

Auto Insurance New Market Insights Explained
Discover the latest trends shaping auto insurance in New [market]—from rate hikes to tech innovations—with Auto Insurance New Market Insights Explained.

Auto Insurance New York City Essentials Drivers Must Know
Discover key Auto Insurance New York City Essentials Drivers Must Know—coverage rules, SR-22 requirements, and cost-saving tips for NYC roads.

Auto Insurance Quotes Explained Key Factors Tips
Understand Auto Insurance Quotes Explained Key Factors Tips to save money. Learn how coverage, deductibles, and discounts impact rates and find the best…

Auto Insurance In Texas Essentials Rights Rates Explained
Understand Auto Insurance in Texas Essentials, Rights, and Rates Explained—key coverage rules, legal protections, and cost factors to navigate policies…
