Understanding Auto Insurance Costs and Coverage in California
Table of Contents
- Historical Evolution of Auto Insurance Regulations in California
- Top 5 Factors Contributing to Higher Auto Insurance Premiums in California
- Purpose and Coverage Limits of California’s Personal Injury Protection (PIP) and Medical Payments (MedPay) Add-Ons
- Collision vs. Comprehensive Coverage Comparison in California
- Niche Add-Ons in California Auto Insurance and Their Typical Cost Ranges
- Role of the California Department of Insurance (CDI) in Auto Insurance Regulation
- Step-by-Step Process for Filing an Auto Insurance Claim in California
- Common Discounts Offered by California Insurers and Their Typical Savings
- Impact of Natural Disasters on Auto Insurance Risks in California and Insurer Adjustments in High-Risk Zones
- AI and Predictive Analytics in California Auto Insurance Underwriting: Adoption, Risks, and Ethical Considerations
- California’s 30-Day Cancellation Notice Requirement and Exceptions for Early Policy Termination
- Comparison Infographic: Auto Insurance Rate Variation by County in California with Color-Coded Heatmaps
California’s auto insurance market is one of the most complex and expensive in the U.S., shaped by dense urban traffic, strict regulations, and recurring natural disasters. From mandatory liability minimums to wildfire-driven premium spikes, drivers face unique challenges balancing affordability with comprehensive protection. This guide breaks down the key factors influencing rates, from urban congestion and vehicle type to emerging tech and climate risks, offering clear insights into how California’s system works—and how to navigate it effectively.
The state’s auto insurance landscape reflects a mix of historical policies, such as the FAIR Plan for high-risk drivers, and modern pressures like rising EV adoption and AI-driven underwriting. With average premiums exceeding national averages and regional disparities as extreme as coastal cities versus inland deserts, understanding these dynamics is critical. Whether you’re comparing collision vs. comprehensive coverage, appealing a denied claim, or weighing discounts for safe driving, this overview equips you with actionable knowledge to make informed decisions.
Historical Evolution of Auto Insurance Regulations in California
California’s auto insurance framework has evolved alongside the state’s population growth, economic shifts, and legal precedents. Early regulations focused on liability protection, but systemic risks like wildfires, urban density, and judicial rulings reshaped requirements. Key legislative milestones—such as the FAIR Plan and mandatory bodily injury coverage—were responses to rising accident costs and insurer financial instability. The state’s approach to auto insurance began in the 1920s with voluntary liability coverage, but catastrophic losses in the 1950s and 1960s necessitated stricter oversight. Judicial decisions, includingTorres v. Condor (1974),expanded liability for injuries, forcing insurers to adjust premiums and coverage limits. The California Automobile Assigned Risk Plan (FAIR Plan), established in 1967, was a critical intervention to ensure high-risk drivers could obtain basic insurance.
Early Mandates and the Rise of Liability Coverage
By the 1970s, California introduced mandatory bodily injury liability coverage to address rising medical costs from vehicle collisions. The state required$15,000 per person and $30,000 per accidentfor bodily injury, a minimum that remained static for decades despite inflation. Property damage liability was later added in 1975, setting a
$5,000 threshold. These mandates were designed to protect victims but did not account for escalating repair costs or urban congestion, leading to persistent underinsurance.
The FAIR Plan and High-Risk Driver Solutions
The Fair Access to Insurance Requirements (FAIR) Plan, activated in 1967, was created to provide basic coverage to drivers deemed uninsurable due to poor driving records or high-risk factors. Initially covering only fire and theft, the plan expanded to include collision and comprehensive coverage by the 1980s. Its role became critical during periods of insurer withdrawal from high-cost regions, such as after the 1994 Northridge earthquake, which disrupted policy availability in Los Angeles.Judicial Impact and the Expansion of Uninsured Motorist Protection
California’s courts played a pivotal role in shaping uninsured motorist (UM) coverage. The1975 ruling in Automobile Club v. Superior Courtmandated that insurers offer UM coverage unless explicitly rejected by policyholders. This decision reflected the state’s high rate of uninsured drivers, particularly in low-income areas. By the 1990s, UM coverage became standard, though its limits remained tied to liability thresholds, creating gaps in protection for severe injuries.
Modern Reforms and the 2000s Adjustments
The early 2000s saw incremental reforms to address affordability and claim disputes. The 2003 passage of SB 868 capped non-economic damages in personal injury lawsuits, aiming to reduce premiums by limiting jury awards. However, this did not offset rising medical costs or the impact of natural disasters. The 2010 wildfires in Southern California further strained insurers, leading to policy cancellations and rate hikes in fire-prone zones. Legislative responses included Assembly Bill 1193 (2012), which required insurers to justify rate increases transparently.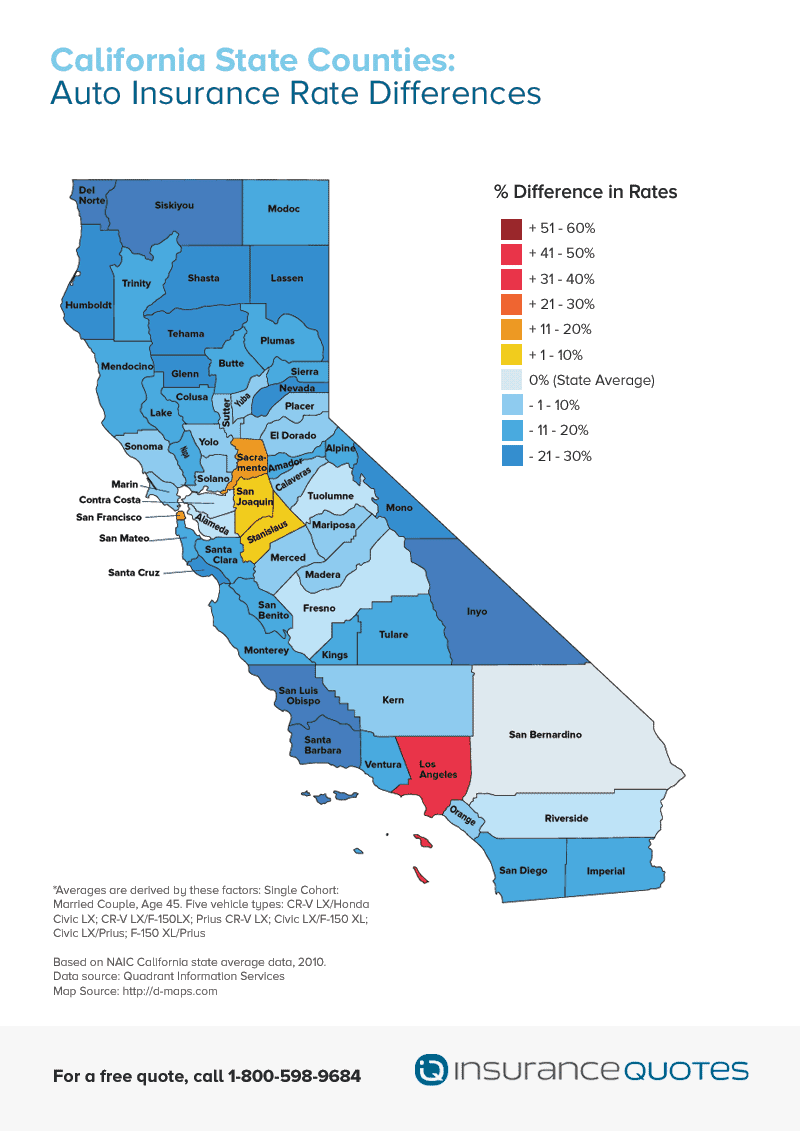
Top 5 Factors Contributing to Higher Auto Insurance Premiums in California
California’s auto insurance market is among the most expensive in the nation, driven by a complex interplay of economic, geographic, and regulatory factors. The state’s unique challenges—from dense urban traffic to high repair costs—create a premium environment where insurers weigh risk factors more heavily than in other states. Below are the five primary drivers of elevated premiums, ranked by their relative impact on policyholder costs. The most significant contributors stem from California’s infrastructure, legal landscape, and demographic trends. Insurers assess these factors through proprietary models that prioritize claims frequency, severity, and financial exposure. Understanding these drivers helps policyholders identify areas for mitigation and recognize why premiums remain elevated compared to national averages. Urban congestion and high collision rates dominate the ranking, followed by legal and regulatory costs, vehicle repair expenses, population density and theft risks, and weather-related claim volatility. Each factor interacts with others, amplifying the overall risk profile for insurers.Urban Congestion and Elevated Collision Rates
California’s cities, particularly Los Angeles, San Francisco, and the Bay Area, experience some of the highest traffic densities in the country. The California Department of Transportation (Caltrans) reports that Los Angeles alone has over 4,700 traffic signals, creating a web of intersections where rear-end collisions and minor fender benders occur daily. The“3-point intersection” phenomenon in Los Angeles—where three lanes merge into two—frequently leads to chain-reaction accidents, increasing liability claims.These urban patterns contribute to a 30% higher collision frequency in metropolitan areas compared to rural regions, according to the Insurance Information Institute (III).
California’s average annual collision claim cost exceeds $15,000, nearly double the national average, due to:
- Higher medical expenses from emergency room visits in densely populated areas.
- Increased property damage from multi-vehicle accidents in congested zones.
- Longer recovery times for insurers processing claims in high-traffic corridors.
Legal and Regulatory Costs Including Punitive Damages
California’s fault-based liability system and high jury award culture significantly inflate premiums. The state’s Civil Code §1714(a) allows for punitive damages in cases of gross negligence, which can multiply liability payouts. For example, a 2019 case in San Francisco awarded $1.3 billion in punitive damages to a pedestrian struck by a rideshare driver, setting a precedent for future claims. This legal environment encourages insurers to overcharge premiums to offset potential catastrophic losses.Key regulatory factors include:
- Uninsured/Underinsured Motorist (UM/UIM) coverage mandates, which require insurers to cover drivers hit by uninsured motorists—common in California due to 10% uninsured rate (higher than the national 12.6% average).
- Strict comparative negligence laws, where even partially at-fault drivers can face substantial liability.
- Assigned Risk Pool (CAFA) surcharges, which apply to high-risk drivers, further driving up base rates.
Vehicle Repair Costs and Parts Shortages
California’s auto repair landscape is uniquely expensive due to labor costs, parts scarcity, and environmental regulations. The average repair cost per claim in California is 40% higher than the national average, according to the AAA Foundation for Traffic Safety. Factors include:- Emissions compliance requirements for repairs, which mandate specific diagnostic tools and certified technicians.
- Supply chain disruptions post-pandemic, leading to 30-50% increases in parts pricing for certain vehicle models.
- High labor wages in urban repair shops, where mechanics earn 20-30% more than in other states.
Population Density and Theft Risks
California’s 39 million residents create a high-volume market for auto theft, with 120,000+ thefts annually (2022 data from the FBI). Urban areas like Los Angeles and Oakland rank among the top 5 most stolen vehicle cities in the U.S. due to:- High population mobility, increasing opportunities for carjackings and opportunistic theft.
- Luxury and high-tech vehicles (e.g., BMW 5 Series, Mercedes S-Class, electric SUVs) being prime targets for keyed or forced entry thefts.
- Insurance fraud rings exploiting gaps in reporting, leading to underreported theft claims that inflate premiums.
Weather-Related Claim Volatility
California’s wildfire season, heavy rainfall, and coastal storms contribute to 15-20% of annual auto insurance claims, according to the Property Casualty Insurers Association of America (PCI). For example:- Wildfires in Northern California (e.g., 2020 August Complex fires) caused $1.1 billion in property damage, including 12,000+ vehicles destroyed or damaged.
- Flooding in Southern California (e.g., 2023 atmospheric river events) led to 5,000+ water-damage claims in Los Angeles County alone.
- Earthquake risks in high-seismic zones (e.g., San Andreas Fault) require separate earthquake insurance policies, often bundled at higher rates.
Purpose and Coverage Limits of California’s Personal Injury Protection (PIP) and Medical Payments (MedPay) Add-Ons
California’s auto insurance market includes optional add-ons like Personal Injury Protection (PIP) and Medical Payments (MedPay) to supplement standard bodily injury liability coverage. These add-ons provide direct financial support for medical expenses and lost wages arising from accidents, regardless of fault. PIP and MedPay are particularly valuable in states with limited tort or no-fault systems, though California operates under a modified comparative fault framework. PIP and MedPay operate as first-party coverages, meaning they pay out directly to the insured or their passengers for medical and related expenses. Unlike third-party liability coverage, which covers damages paid to others, these add-ons ensure immediate access to funds for treatment and recovery costs. Their applicability extends beyond accidents involving other drivers, covering incidents like single-vehicle crashes, hit-and-run scenarios, or even non-vehicle-related injuries (e.g., slipping on ice while walking to a car).PIP typically covers 80% of medical bills up to policy limits, including ambulance services, hospital stays, and rehabilitation. MedPay, in contrast, reimburses 100% of eligible medical costs without deductibles, though it often has lower maximum limits.PIP also addresses lost wages and essential services (e.g., childcare or housekeeping) during recovery, with coverage caps varying by insurer. MedPay, however, is more limited in scope, focusing solely on medical expenses. Both add-ons exclude pre-existing conditions and injuries sustained while committing a felony. Key distinctions include:
- PIP covers medical bills, lost wages, and essential services, with a no-fault trigger—payments occur regardless of liability.
- MedPay reimburses medical costs only, with a fault-based or no-fault trigger depending on the insurer’s policy.
- PIP limits often range from $10,000 to $100,000 per person/per accident, while MedPay limits typically cap at $5,000 to $25,000 per person.
- Both exclude coverage for injuries sustained while operating a vehicle without a valid license or under the influence of drugs/alcohol.
Collision vs. Comprehensive Coverage Comparison in California
Collision and comprehensive coverage are two fundamental components of California’s physical damage coverage, each addressing distinct risks to a vehicle. Collision coverage pays for repairs or replacement when a covered vehicle collides with another object, including other cars, barriers, or even animals. Comprehensive coverage, meanwhile, covers non-collision incidents such as theft, vandalism, fire, natural disasters, or falling objects. The decision to include these coverages hinges on the vehicle’s value, financial resources, and risk tolerance. Collision is mandatory for financed or leased vehicles due to lienholder requirements, while comprehensive is optional but highly recommended for high-value or newer cars. Below is a detailed comparison of scenarios where each is most beneficial.Collision coverage applies when a vehicle hits another object or is hit by one, while comprehensive coverage covers all other perils not involving a collision.Scenarios favoring Collision coverage:
- Accidents with other vehicles: If a driver rear-ends a car or sideswipes a pole, collision coverage ensures repairs are covered, typically after a deductible (commonly $500–$2,000). For example, a $10,000 repair bill with a $1,000 deductible would result in $9,000 reimbursement.
- Single-vehicle accidents: Rolling the vehicle or hitting a stationary object (e.g., a guardrail) triggers collision coverage, as the damage stems from the vehicle’s movement.
- Financed/leased vehicles: Lienholders require collision coverage to protect their investment. Without it, the borrower remains liable for full repair costs.
- Theft or vandalism: If a vehicle is stolen or damaged by graffiti, comprehensive coverage reimburses the insured for the vehicle’s actual cash value (ACV), minus the deductible. For instance, a $30,000 car stolen with a $500 deductible would yield $29,500.
- Natural disasters: Hailstorms, floods, or wildfires (e.g., California’s 2018 Camp Fire) can total a vehicle, and comprehensive coverage ensures replacement or repair funds.
- Animal collisions: Hitting a deer or other wildlife is covered under comprehensive, not collision. A $5,000 repair bill with a $1,000 deductible would net $4,000.
- Glass damage: Some policies include glass coverage as part of comprehensive, covering windshield repairs or replacements (often with no deductible).
- Collision premiums typically range from $50 to $200/month for older vehicles, increasing to $200–$500/month for luxury or high-performance cars.
- Comprehensive premiums average $30 to $150/month, with higher costs for vehicles in high-theft or disaster-prone areas (e.g., coastal regions prone to flooding).
- Deductibles for both coverages usually range from $250 to $2,500, with higher deductibles lowering premiums but increasing out-of-pocket costs at claim time.
- Choose collision over comprehensive if the vehicle is older (e.g., 10+ years) and its ACV is low (e.g., <$3,000), as repair costs may exceed coverage limits.
- Opt for comprehensive over collision if the vehicle is high-value (e.g., a $50,000 Tesla) and parked in a high-theft area, where non-collision risks are more likely.
- Bundle both coverages for newer or financed vehicles to mitigate risks from collisions, theft, or natural disasters simultaneously.
Niche Add-Ons in California Auto Insurance and Their Typical Cost Ranges
California’s auto insurance market offers a variety of niche add-ons designed to address specific risks or enhance policyholder convenience. These optional coverages cater to drivers seeking broader protection beyond standard liability, collision, and comprehensive policies. Below are examples of popular add-ons, their purposes, and typical cost ranges as of 2023–2024.Niche add-ons are not mandatory but can provide financial relief in unforeseen scenarios, such as roadside emergencies or extended rental car expenses.Roadside Assistance
- Purpose: Provides towing, battery jump-starts, tire changes, fuel delivery, and lockout services 24/7. Many insurers offer this as a standalone add-on or bundle it with other coverages.
- Typical cost: $10–$30/month for basic coverage (e.g., 50 miles of towing) to $50–$80/month for premium plans (e.g., unlimited towing or coverage for multiple vehicles).
- Example: A driver stranded on Interstate 5 with a flat tire can request a tow to the nearest repair shop, with costs covered up to policy limits (often $100–$150 per incident).
- Common exclusions: Mechanical failures due to neglect, off-road recovery, or damage caused by the insured’s actions (e.g., improperly securing a trailer).
- Purpose: Covers the cost of renting a replacement vehicle while the insured’s car is being repaired after a covered claim. Limits typically range from $20–$70/day with a maximum of 10–30 days.
- Typical cost: $15–$50/month, depending on daily and total limits. Higher limits (e.g., $100/day) increase premiums to $70–$120/month.
- Example: After a collision, a driver’s sedan requires 14 days of repairs. With a $50/day limit and 21-day maximum, the insurer reimburses $1,050 ($50 × 21 days).
- Key considerations: Some policies require the insured to pay upfront and submit receipts, while others use a prepaid rental card. Exclusions often include commercial vehicles or rentals used for business purposes.
- Purpose: Bridges the gap between the vehicle’s actual cash value (ACV) and the remaining loan or lease balance if the car is totaled. Critical for newer or leased vehicles where depreciation outpaces loan payments.
- Typical cost: $10–$30/month, with some insurers offering it as part of a loan/lease bundle. Premiums may decrease as the loan balance diminishes.
- Example: A $30,000 car with a $25,000 loan is totaled in a fire. The insurer pays $18,000 (ACV), leaving a $7,000 gap. Gap insurance covers this difference, ensuring the driver isn’t responsible for the remaining balance.
- When to consider: Essential for vehicles with high depreciation rates (e.g., luxury cars or electric vehicles) or long loan terms (e.g., 72+ months). Often required by lenders for certain loan-to-value ratios.
Role of the California Department of Insurance (CDI) in Auto Insurance Regulation
The California Department of Insurance (CDI) serves as the primary regulatory body overseeing auto insurance policies within the state, ensuring fair practices, consumer protections, and compliance with state laws. Its mandate extends beyond mere oversight—it actively enforces regulations, investigates complaints, and educates consumers to promote transparency in the insurance marketplace. The CDI maintains authority over policy forms, rates, and marketing practices to prevent unfair discrimination or deceptive sales tactics. It also administers the state’s mandatory auto insurance requirements, including liability coverage minimums, and enforces penalties for non-compliance. Consumer protections are central to its mission, with mechanisms in place to address disputes, policy cancellations, and claims denials.Consumer Protections and Complaint Processes
The CDI provides multiple channels for drivers to report violations or seek resolution of disputes. Complaints regarding unfair premium hikes, policy exclusions, or denial of claims are systematically reviewed, and the department may intervene to mediate or enforce remedies. For instance, the CDI has issued guidance on non-renewal notices, requiring insurers to provide clear reasons and alternatives for policyholders facing cancellation. A structured complaint process includes:- Submission of a formal complaint through the CDI’s online portal or by mail, detailing the issue with supporting documentation (e.g., policy documents, correspondence with the insurer).
- Initial review by CDI staff to verify jurisdiction and gather preliminary evidence, which may involve contacting the insurer for clarification.
- Investigation phase, where the CDI may request additional records or conduct interviews with involved parties. Complex cases may be referred to the California Insurance Commissioner for further action.
- Resolution, which can range from mandatory mediation to legal enforcement actions, including fines or corrective orders against insurers.
Enforcement Actions and Public Disclosures
The CDI maintains a public database of enforcement actions against insurers, including penalties for violations of the California Insurance Code. For example, in 2022, the department imposed fines on a major insurer for denying claims without adequate investigation, citing failure to comply with state requirements for prompt claim processing. Such actions serve as deterrents and reinforce accountability in the industry. Additionally, the CDI collaborates with other state agencies, such as the Department of Motor Vehicles (DMV), to cross-reference insurance compliance with vehicle registration data. This integration helps identify uninsured drivers and ensures enforcement of the state’s mandatory financial responsibility law.Step-by-Step Process for Filing an Auto Insurance Claim in California
Filing an auto insurance claim in California requires adherence to a structured process to ensure timely resolution and fair compensation. Understanding each stage—from initial reporting to settlement—helps policyholders navigate the claims process efficiently while staying informed about deadlines and documentation requirements. The process begins with immediate notification to the insurer, followed by evidence collection, claim evaluation, and negotiation. Each phase includes specific timeframes and procedural steps that must be followed to avoid delays or denials.Immediate Reporting and Notification
The California Department of Insurance mandates prompt claim reporting within 30 days of an accident, though insurers may require notification sooner, particularly in cases involving injuries or significant property damage.Policyholders must contact their insurer as soon as possible after an accident, regardless of fault. This typically involves calling the insurer’s 24/7 claims hotline or using their mobile app if available. Key details to provide include:
- The date, time, and location of the accident, including road conditions.
- A brief description of what occurred, focusing on facts (e.g., "The other driver ran a red light").
- Names, license plate numbers, and insurance information of all parties involved.
- Photographic evidence or a description of vehicle damage and injuries.
- Police report details if one was filed (California’s SR-1 form is standard for accidents involving injuries or property damage over $750).
Evidence Collection and Documentation
Comprehensive documentation strengthens a claim and accelerates processing. Policyholders should gather:- Photographs of the accident scene, including vehicle positions, road signs, and skid marks.
- Videos (if available) from dashcams or nearby cameras.
- Witness statements with contact information.
- Medical records and bills for injuries sustained, including ER visits and follow-up care.
- A copy of the police report, if filed, as it may include witness accounts and officer observations.
- Maintenance records for the involved vehicles to demonstrate pre-existing conditions.
California’s Civil Code § 3333.5 requires insurers to investigate claims in good faith, including verifying evidence submitted by policyholders.
Claim Evaluation and Adjuster Assignment
After reporting, an adjuster will be assigned to assess the claim. This phase typically spans 10–30 days, depending on claim complexity. The adjuster may:- Inspect the damaged vehicle at a repair facility or your location.
- Review medical records if bodily injury is involved, consulting with medical experts if necessary. li>Assess liability by analyzing police reports, witness statements, and traffic laws.
- Request additional documentation if the claim lacks clarity.
Negotiation and Settlement Offer
Once the adjuster completes their assessment, the insurer will provide a settlement offer. This phase can take 30–90 days or longer for complex claims. Policyholders should:- Review the offer in detail, comparing it to repair estimates (e.g., from Independent Auto Body Association guidelines) or medical costs.
- Request a written explanation if the offer seems inadequate, citing gaps in evidence coverage.
- Consult an attorney if the insurer denies coverage or offers less than fair compensation, especially in cases of bad faith (see subsequent section).
- Consider mediation or arbitration if negotiations stall, as California’s Insurance Code § 10156 allows for dispute resolution before litigation.
California’s Unfair Insurance Practices Act (UIPA) prohibits insurers from making settlement offers without "reasonable consideration" of all relevant facts.
Final Settlement and Claim Closure
Upon agreement, the insurer will issue payment within 7–14 days for approved claims. Policyholders should:- Verify the payment amount matches the settlement terms.
- Submit receipts for repairs or medical expenses to ensure reimbursement.
- Request a written confirmation of claim closure from the insurer.
- Keep records of all communications and payments for future reference.
Common Discounts Offered by California Insurers and Their Typical Savings
California insurers provide a variety of discounts designed to incentivize safe driving, policy bundling, and vehicle security. These discounts can significantly reduce annual premiums, often by 10% to 30% or more, depending on eligibility and insurer policies. Understanding these discounts allows drivers to optimize their coverage while maintaining financial efficiency. Insurers in California frequently offer discounts tied to measurable risk reduction or policy consolidation. The most prevalent include safe driver programs, multi-policy bundling, and vehicle safety enhancements. Below are the primary categories and their estimated savings potential.Safe Driver Discounts
Safe driver discounts reward policyholders with clean driving records, typically reducing premiums by 10% to 25% annually. These discounts are often tiered, with longer claim-free periods yielding higher savings. For example, a driver with no at-fault accidents for three consecutive years may qualify for a 20% discount, while those with five years of clean records could see savings approaching 30%. Insurers also offer accident forgiveness programs, where the first at-fault accident does not increase rates. This is particularly valuable in California, where aggressive driving and high-traffic congestion contribute to frequent collisions. Discounts for defensive driving courses further incentivize safe behavior, often providing 5% to 15% savings upon completion of an approved program.Multi-Policy (Bundling) Discounts
Bundling auto insurance with other policies—such as homeowners, renters, or umbrella insurance—is a common strategy to lower premiums. California insurers typically offer 10% to 20% discounts for bundling, with some providers extending savings up to 25% for multiple policies. This discount reflects the reduced administrative costs and perceived lower risk for insurers managing multiple lines of coverage under one policyholder. For instance, a California homeowner with both auto and home insurance through the same provider may pay 15% less for their auto policy than if purchased separately. Bundling is particularly advantageous for families or individuals with multiple vehicles, as it can apply to each auto policy under the same household.Vehicle Safety and Security Discounts
Insurers provide discounts for vehicles equipped with advanced safety features or security systems. Anti-theft devices, such as OBD-II locks or GPS tracking, can reduce premiums by 5% to 10%, while modern safety technologies—such as automatic emergency braking, lane departure warnings, or adaptive cruise control—may yield savings of 10% to 20%. These discounts reflect the lower likelihood of theft or collision when safety systems are installed. California-specific examples include:- Anti-theft devices: Installing an approved system like OnStar or LoJack can qualify drivers for a 7% to 12% discount.
- Safety-rated vehicles: Vehicles earning top ratings from the Insurance Institute for Highway Safety (IIHS) may receive 10% to 15% savings.
- Electronic stability control (ESC): Mandatory in most new vehicles, ESC can provide a 5% discount if explicitly listed on the policy.
Low Mileage and Usage-Based Discounts
Drivers who log fewer annual miles—typically under 7,500 miles per year—often qualify for low mileage discounts, ranging from 5% to 15%. This discount acknowledges reduced wear and tear on vehicles, lowering the probability of accidents. For example, a California professional who works remotely and drives 5,000 miles annually may save 10% compared to a commuter driving 20,000 miles. Additionally, some insurers offer pay-per-mile programs, where premiums are calculated based on actual mileage rather than estimated usage. While not as common in California as usage-based insurance (UBI), these programs can benefit low-mileage drivers by reducing premiums by up to 30% for those driving under 5,000 miles annually.Good Student and Occupational Discounts
California insurers extend discounts to good students (typically those with a GPA of 3.0 or higher) and young drivers, offering savings of 5% to 20% depending on the insurer. These discounts reflect the lower risk associated with responsible young adults. For example, a college student maintaining a 3.5 GPA may qualify for a 15% discount, while a full-time student under 25 could see savings of 10%. Occupational discounts apply to professions with inherently lower risk, such as teachers, nurses, or government employees. These roles often qualify for 5% to 10% savings, as insurers associate them with disciplined driving habits. For instance, a California schoolteacher may receive a 7% discount for working in an educational setting.Paperless and Electronic Payment Discounts
Insurers increasingly offer paperless policy discounts (5% to 10%) for drivers who opt to receive documents electronically, as this reduces administrative costs. Similarly, automatic payment discounts (typically 2% to 5%) are provided for setting up recurring payments, ensuring timely premiums and minimizing risk for the insurer. For example, a California driver who enrolls in auto-pay and receives their policy digitally could accumulate 12% in combined savings from these two discounts alone.Impact of Natural Disasters on Auto Insurance Risks in California and Insurer Adjustments in High-Risk Zones
California’s geographic and climatic vulnerabilities significantly elevate auto insurance risks, prompting insurers to implement dynamic pricing models and coverage restrictions. Wildfires, earthquakes, and floods disrupt policyholder stability by increasing claim frequencies, repair costs, and total loss incidents. Insurers respond through geographic risk assessments, actuarial adjustments, and targeted exclusions for high-exposure areas, often resulting in premium surges of 20% to 50% or more in severely affected zones. Insurance companies systematically evaluate disaster risks by integrating historical claim data, climate models, and real-time hazard alerts. Premium adjustments are applied based on:- The frequency and severity of past disasters in a region.
- Infrastructure resilience and emergency response capabilities.
- Regulatory mandates and state-specific risk mitigation programs.
Insurers classify California into climate zones (e.g., coastal, inland, desert) and assign risk tiers, with premiums scaling proportionally to disaster exposure. For example, a policy in Santa Rosa (wildfire-prone) may cost 30% more than one in Sacramento (lower wildfire risk but higher flood exposure).---
Geographic Risk Zones and Auto Insurance Premium Variations by Disaster Type
Insurers stratify California into distinct climate zones, each influencing premium calculations differently. Below is a comparative analysis of cities with elevated rates due to natural disaster exposure, ranked by severity and claim frequency. Wildfire-Prone Regions (Highest Premium Increases)Wildfire zones (e.g., Northern California’s wine country, Southern California’s chaparral regions) experience premium hikes of 25% to 100% annually, with insurers imposing coverage limits or exclusions for total loss events.
- Santa Rosa, CA (Sonoma County): Post-2017 Tubbs Fire, premiums spiked 45% due to repeated burn scars and evacuation zone mandates.
- Los Angeles County (Malibu, Canoga Park): Coastal wildfire corridors see 30% premium increases, with insurers citing proximity to canyons and dry vegetation.
- Redding, CA (Shasta County): Wildfire risk factors (e.g., Klamath National Forest adjacency) contribute to 28% higher rates than state averages.
Earthquake-prone areas (e.g., Southern California’s San Andreas Fault zone) face premium adjustments of 15% to 35%, with insurers factoring in seismic retrofitting costs and structural vulnerability.
- Long Beach, CA: Located on the Newport-Inglewood Fault, policies include 22% earthquake endorsements, with total loss claims rising post-2019 Ridgecrest quakes.
- Palmdale, CA (San Bernardino County): High seismic activity and proximity to fault lines result in 25% premium surcharges for comprehensive coverage.
Flood risks in California are categorized under the National Flood Insurance Program (NFIP), with premiums varying by flood zone (e.g., Zone AE vs. Zone X). Coastal cities face 10% to 40% increases, while inland urban areas see 15% to 50% hikes.
- San Francisco Bay Area (Oakland, Richmond): Urban flood zones (e.g., near the San Francisco Bay) incur 35% premium hikes, with insurers citing storm surge and tidal inundation risks.
- Sacramento, CA: Inland flood exposure (Sacramento River basin) drives 20% to 45% rate increases, depending on proximity to levees.
Insurer Risk Assessment Methods for Floods and Wildfires
Insurers employ proprietary models and third-party tools to quantify flood and wildfire risks, which directly influence policy pricing and coverage terms. Wildfire Risk Assessment ToolsInsurers utilize Fire Peril Models (e.g., CoreLogic’s FireWatch, Verisk’s Wildfire Risk Index) to evaluate:Flood Risk Assessment ToolsThese tools generate risk scores that correlate with premium adjustments (e.g., a score of 8/10 may trigger a 30% rate increase).
- Vegetation density and fuel loads.
- Historical fire spread patterns.
- Evacuation route accessibility.
The National Flood Insurance Program (NFIP) classifies properties into flood zones (e.g., Zone AE for high-risk areas), with premiums tied to:---Private insurers supplement NFIP data with tools like Flood Factor (from CoreLogic), which adjusts rates based on flood depth and recurrence intervals.
- Elevation certificates (if available).
- Base flood elevation (BFE) and floodplain maps.
- Historical flood claim data.
Post-Disaster Claim Processes and Coverage Gaps for Totaled Vehicles in Wildfire Zones
California’s post-disaster claim landscape presents distinct challenges, particularly for totaled vehicles in wildfire-affected areas. Insurers implement accelerated claim processing for high-volume disasters but often impose coverage limitations. Wildfire Claim ProcessPost-wildfire claims follow a tiered approach:Coverage Gaps for Totaled Vehicles
- Initial Reporting: Policyholders submit claims via mobile apps or call centers, with insurers deploying claims adjusters to assess damage.
- Total Loss Determination: Vehicles deemed 70%+ damaged (or exceeding repair costs) are declared total losses, with payouts adjusted for actual cash value (ACV) minus deductibles.
- Replacement Cost Coverage: Insurers may offer replacement cost endorsements (e.g., +$2,000–$5,000) for newer vehicles, but exclusions apply in high-risk zones.
Insurers in wildfire zones often impose:---
- Deductible Increases: Wildfire-specific deductibles (e.g., $1,000–$5,000) may apply, reducing payouts for totaled vehicles.
- Exclusions for Secondary Perils: Some policies exclude coverage for smoke damage or debris cleanup unless purchased as add-ons.
- Non-Renewal Clauses: Insurers may non-renew policies in high-risk areas after repeated claims, forcing policyholders to seek FAIR Plan coverage (California’s assigned risk pool).
Visual Correlation of California’s Climate Zones and Auto Insurance Premium Variations
California’s climate zones—coastal, inland, desert, and mountain regions—exhibit distinct premium patterns due to disaster exposure. Below is a descriptive breakdown of how these zones influence auto insurance costs: Coastal Regions (e.g., San Francisco Bay Area, Los Angeles)Characteristics: High flood risk (storm surges, tidal inundation), moderate wildfire exposure (coastal chaparral), and earthquake vulnerability (fault lines like the Hayward Fault). Premium Impact: Flood endorsements add 10%–35% to base rates, while wildfire zones (e.g., Malibu) increase premiums by 20%–40%. Earthquake coverage is mandatory in high-risk areas, adding 15%–25%.Inland Regions (e.g., Sacramento Valley, Central Valley)
Characteristics: High flood risk (riverine zones), moderate wildfire exposure (dry climate), and low earthquake risk (except near fault lines). Premium Impact: Flood zones (e.g., Zone AE) spike premiums by 20%–50%, while wildfire-prone areas (e.g., Yuba County) add 15%–30%. Earthquake coverage is optional but recommended in proximity to active faults.Desert Regions (e.g., Palm Springs, Death Valley)
Characteristics: Low flood risk (arid climate), high wildfire exposure (sagebrush fuel loads), and moderate earthquake risk (San Andreas Fault adjacency). Premium Impact: Wildfire zones increase premiums by 25%–50%, while earthquake endorsements add 10%–20%. Flood coverage is rarely required but may be available via NFIP.Mountain Regions (e.g., Lake Tahoe, Sierra Nevada Foothills)
Characteristics: Moderate flood risk (mountain runoff), high wildfire exposure (pine forests), and low earthquake risk (except near fault lines). Premium Impact: Wildfire zones (e.g., South Lake Tahoe) add 30%–60% to premiums, while flood endorsements are optional but costly in high-elevation areas. Earthquake coverage is minimal unless near fault lines.
AI and Predictive Analytics in California Auto Insurance Underwriting: Adoption, Risks, and Ethical Considerations
California’s auto insurance market is increasingly leveraging artificial intelligence and predictive analytics to refine underwriting processes, enhance risk assessment, and personalize premiums. Insurers utilize machine learning algorithms to analyze vast datasets—including driving behavior, vehicle telematics, and even socioeconomic factors—to predict accident likelihood and tailor coverage. This shift toward data-driven underwriting aims to improve accuracy while reducing fraud and operational inefficiencies. However, the integration of AI raises critical ethical concerns, particularly regarding bias, transparency, and consumer privacy. The adoption of AI in underwriting has accelerated due to California’s complex risk landscape, where factors like urban density, climate-related hazards, and diverse driver demographics necessitate nuanced risk modeling. Predictive analytics enables insurers to detect patterns that traditional models might overlook, such as high-risk driving routes or weather-correlated claims. Yet, concerns persist over algorithmic bias, which could disproportionately penalize certain groups based on non-driving factors like ZIP codes or credit scores.Key Applications of AI in Underwriting
AI-driven underwriting in California encompasses several transformative applications that reshape how insurers evaluate risk and set premiums.AI-driven underwriting in California encompasses several transformative applications that reshape how insurers evaluate risk and set premiums.
- Telematics and Usage-Based Insurance (UBI): Insurers deploy in-vehicle telematics devices or smartphone apps to collect real-time driving data—such as speed, braking habits, and mileage—allowing for dynamic premium adjustments. For example, usage-based programs like Progressive’s Snapshot or State Farm’s Drive Safe & Save adjust rates based on observed behavior, incentivizing safer driving. In California, where aggressive urban driving is prevalent, telematics helps insurers distinguish between high-risk and low-risk drivers more precisely than traditional methods.
- Predictive Modeling for Claim Fraud: Machine learning algorithms analyze claim patterns to identify anomalies, such as exaggerated damage reports or staged accidents. Insurers like Allstate and Geico use AI to cross-reference claims data with historical trends, reducing fraudulent payouts. In California, where fraud costs insurers billions annually, these tools are critical for maintaining profitability while protecting honest policyholders.
- Personalized Risk Profiling: AI synthesizes data from multiple sources—including credit scores, vehicle history, and even social media activity—to create detailed risk profiles. While this enables hyper-personalized pricing, it also raises ethical questions about data privacy and the potential for discriminatory practices. For instance, insurers may indirectly penalize drivers in high-crime areas or those with certain employment histories, even if those factors are unrelated to driving ability.
- Automated Policy Issuance and Renewals: AI streamlines the underwriting process by automating initial risk assessments and renewals, reducing human error and speeding up approvals. Companies like Lemonade use AI to offer instant quotes and policy issuance, appealing to California’s tech-savvy consumers. However, this automation can lead to a lack of transparency, as policyholders may not fully understand how AI-driven decisions are made.
Ethical Concerns and Regulatory Challenges
The ethical implications of AI in auto insurance underwriting are multifaceted, particularly in California, where regulatory scrutiny is stringent. Key concerns include:The ethical implications of AI in auto insurance underwriting are multifaceted, particularly in California, where regulatory scrutiny is stringent.
- Algorithmic Bias and Discrimination: AI models trained on historical data may perpetuate biases, such as overcharging drivers in certain neighborhoods or penalizing minority groups. California’s Fair Employment and Housing Act (FEHA) and California Consumer Privacy Act (CCPA) impose strict requirements on data collection and usage, requiring insurers to ensure fairness in their algorithms. For example, if an AI model assigns higher premiums to drivers in low-income areas due to correlated risk factors, it could violate anti-discrimination laws.
- Lack of Transparency and Explainability: Many AI-driven decisions are opaque, making it difficult for consumers to understand why they were charged a higher premium or denied coverage. California’s Algorithmic Accountability Act (proposed legislation) aims to address this by requiring insurers to disclose how AI systems make decisions. Without such transparency, policyholders may face unjustified rate hikes without recourse.
- Data Privacy and Security Risks: The collection of sensitive driving data raises concerns about privacy violations and cybersecurity threats. California’s CCPA grants consumers significant control over their personal data, but enforcement remains a challenge. Insurers must implement robust cybersecurity measures to protect against data breaches, which could expose policyholders to identity theft or misuse of their driving records.
- Over-Reliance on Predictive Models: AI models are only as good as the data they are trained on. If historical data contains errors or is incomplete, AI-driven underwriting could lead to unfair or inaccurate risk assessments. For example, if a model relies heavily on credit scores—a factor that correlates with socioeconomic status rather than driving ability—it may disproportionately affect low-income drivers in California.
Regulatory and Industry Responses
In response to these challenges, California’s insurance regulators and industry stakeholders are taking proactive steps to ensure ethical AI use. The California Department of Insurance (CDI) has issued guidelines encouraging insurers to adopt fair lending practices and transparent AI systems. Additionally, industry consortia, such as the Insurance Information Institute (III), advocate for standardized AI ethics frameworks to prevent bias and ensure consumer protection. Insurers are also investing in explainable AI (XAI) tools that provide clearer insights into how decisions are made. For instance, Mercury Insurance has implemented AI-driven underwriting with built-in fairness checks to mitigate discriminatory outcomes. Meanwhile, startups like Tractable offer AI solutions designed to reduce bias by focusing on driving behavior rather than indirect risk factors.Insurers are also investing in explainable AI (XAI) tools that provide clearer insights into how decisions are made.
California’s 30-Day Cancellation Notice Requirement and Exceptions for Early Policy Termination
In California, auto insurance policies are subject to strict consumer protections designed to ensure continuity of coverage and prevent abrupt disruptions. One of the most critical provisions is the 30-day cancellation notice requirement, which mandates that insurers provide policyholders with advance written notice before terminating coverage. This rule applies to most standard auto insurance policies and is enforced to safeguard drivers from unexpected lapses in coverage, which could lead to fines, license suspension, or higher premiums upon reinstatement. The 30-day notice period is non-negotiable for insurers unless specific exceptions apply. These exceptions are narrowly defined to protect both the insurer’s interests and the policyholder’s rights. Below are the key scenarios where an insurer may terminate coverage before the standard notice period.Standard 30-Day Cancellation Notice Process
The 30-day notice requirement applies to most policy cancellations, including those initiated by either the insurer or the policyholder. Insurers must provide written notice via mail or email (if authorized by the policy) detailing the effective date of cancellation, the reason for termination, and any applicable refunds or reinstatement procedures. Failure to comply with this requirement can result in penalties for the insurer and may entitle the policyholder to reinstatement of coverage or financial compensation.Exceptions Where Insurers Can Terminate Coverage Early
While the 30-day rule is standard, California law allows for early termination under limited circumstances. These exceptions are typically tied to material misrepresentations, non-payment, or severe policy violations. The most common exceptions include:The California Insurance Code § 10211 outlines that an insurer may terminate coverage immediately or with reduced notice if:
- Non-payment of premiums: If a policyholder fails to pay a premium within the grace period specified in the policy (usually 10–30 days), the insurer may cancel coverage effective immediately upon the due date of the overdue payment. However, the insurer must still provide a written notice of cancellation detailing the amount owed and the effective date of termination.
- Material misrepresentation or fraud: If the insurer discovers that the policyholder provided false information on the application (e.g., misreporting driving history, vehicle usage, or location), the insurer may terminate coverage with immediate effect. This exception is subject to review by the California Department of Insurance (CDI) to ensure the insurer’s actions are justified.
- Conviction of a serious traffic violation: If a policyholder is convicted of a felony involving the use of a motor vehicle or a serious traffic offense (e.g., DUI, reckless driving), the insurer may terminate coverage with 10 days’ notice. The insurer must provide proof of the conviction to the policyholder.
- Non-renewal due to excessive claims or risk: If a policyholder files an excessive number of claims or poses an unusually high risk (e.g., repeated accidents or violations), the insurer may choose not to renew the policy at its expiration. However, the insurer must still provide the standard 30-day notice before the policy’s renewal date.
- Policyholder’s request for cancellation: While policyholders can cancel their coverage at any time, the insurer must still adhere to the 30-day notice period if the cancellation is initiated by the insurer (e.g., in response to a policyholder’s request to switch insurers).
Procedural Requirements for Early Termination
Even in cases of early termination, insurers must follow specific procedural requirements to ensure fairness. These include:- Written notice of cancellation: The insurer must provide a written explanation of the reason for termination, including any relevant policy provisions or legal grounds. This notice must be clear and unambiguous, avoiding vague language that could confuse the policyholder.
- Right to appeal or dispute: Policyholders have the right to challenge the insurer’s decision, particularly in cases of misrepresentation or fraud allegations. The insurer must provide contact information for the CDI or an internal appeals process within the notice.
- Refund of unearned premiums: If the policy is terminated early (e.g., due to non-payment), the insurer must calculate and refund any unearned premiums prorated to the date of termination. This ensures policyholders are not unfairly penalized for minor delays in payment.
- Continuation of coverage during disputes: In cases where the policyholder disputes the termination (e.g., alleging wrongful cancellation), the insurer may be required to continue coverage temporarily while the dispute is resolved, particularly if the policyholder can demonstrate a valid claim.
Enforcement and Remedies for Violations
Policyholders who believe their insurer violated the 30-day cancellation notice requirement or terminated coverage improperly can seek remedies through the following avenues:- Reinstatement of coverage: The CDI may order the insurer to reinstate the policy if the cancellation was found to be in violation of state law. This often includes reinstating coverage retroactive to the date of termination and waiving any late fees or penalties.
- Financial penalties for insurers: The CDI can impose fines on insurers that fail to comply with cancellation notice requirements. These penalties are intended to deter future violations and protect consumers.
- Consumer complaints and investigations: Policyholders can file complaints with the CDI, which may launch an investigation into the insurer’s actions. Evidence of repeated violations can lead to corrective actions, such as mandatory training for underwriting staff or changes to cancellation policies.
- Legal action for breach of contract: In extreme cases, policyholders may pursue civil litigation against the insurer for breach of contract or bad faith insurance practices. This is typically reserved for cases where the insurer acted in bad faith or made material misrepresentations.
Comparison Infographic: Auto Insurance Rate Variation by County in California with Color-Coded Heatmaps
California’s auto insurance market exhibits significant regional disparities, influenced by population density, risk factors, and local regulations. A well-designed infographic can visually communicate these variations, helping consumers identify high-cost and low-cost areas to make informed decisions. The infographic employs a color-coded heatmap to represent annual premium ranges across counties, using a spectrum from green (lowest premiums) to red (highest premiums). Each county is labeled with its average annual premium for a standard policy, with additional tooltips revealing key influencing factors like accident rates, urbanization, and claim frequency. Key elements of the design:- Color Gradient Scale: A legend at the top clarifies the premium ranges (e.g., green: <$1,200, yellow: $1,200–$1,800, orange: $1,800–$2,500, red: >$2,500).
- Geographic Placement: Counties are positioned on a simplified map of California, with borders colored according to their premium tier.
- Data Highlights: Pop-up boxes on hover display:
- Average premium for a 35-year-old driver with a clean record.
- Percentage increase/decrease compared to the state average.
- Notable risk factors (e.g., "High theft rates in Los Angeles" or "Low collision rates in rural areas").
- Trend Indicators: Arrows or icons show year-over-year rate changes, emphasizing volatility in urban vs. rural regions.
"Urban areas like Los Angeles and San Francisco consistently rank among the highest premium counties due to congestion-related collisions and higher repair costs, while rural counties like Modoc or Alpine often see the lowest rates due to lower population density and fewer claims."The heatmap visually reinforces that location is the single most influential factor in premium calculation, alongside vehicle type, driving history, and coverage limits. Consumers can cross-reference this with their specific ZIP codes to assess relative affordability.
California’s auto insurance system is a delicate balance of regulation, risk, and innovation—one that rewards proactive drivers while punishing those caught in high-cost zones or natural disaster hotspots. By leveraging discounts, disputing unfair denials, and adapting to climate-driven rate shifts, drivers can mitigate costs without compromising coverage. As AI and autonomous vehicles reshape the industry, staying ahead means combining traditional safeguards with emerging strategies. The bottom line: knowledge is the best tool to navigate a market where every mile—and every policy choice—counts.
Frequently Asked Questions
How much does average car insurance cost in California?
California’s average annual premium for full coverage auto insurance is around $2,000–$3,000, higher than the national average. Factors like location, vehicle type, and driving record significantly influence costs, with urban areas like Los Angeles often seeing premiums exceed $3,500 yearly
What are California’s minimum auto insurance requirements?
California mandates $15,000 bodily injury liability per person, $30,000 per accident, and $5,000 property damage liability. Underinsured/uninsured motorist coverage is optional but recommended due to high accident risks. Proof of financial responsibility is required for registration
Does California have mandatory personal injury protection (PIP)?
No, California does not require PIP. However, it offers no-fault insurance for medical expenses, meaning fault isn’t determined initially. Drivers must still carry liability coverage, and medical payments coverage can be added as an optional add-on for extra protection
How do natural disasters affect auto insurance rates in California?
Frequent wildfires, earthquakes, and floods increase premiums due to higher claim risks. Insurers may deny coverage in high-risk zones or impose mandatory deductibles for disaster-related repairs. Some policies exclude coverage for certain natural disasters unless explicitly added as endorsements
What discounts can lower my auto insurance in California?
Common discounts include safe driver, bundling with home/renter’s insurance, low mileage, anti-theft devices, and good student (for young drivers). Some insurers offer usage-based programs like telematics for tracking safe driving habits, potentially reducing costs by 10–20%
What should I do if my insurance denies a claim in California?
Request a written explanation of denial and file an appeal within 30–60 days. California’s Department of Insurance (CDI) mediates disputes; submit complaints online. Review policy exclusions and consider consulting a public adjuster or legal aid if unresolved, as California law requires fair claim handling
Related articles

Auto Insurance Quotes Explained Key Factors Tips
Understand Auto Insurance Quotes Explained Key Factors Tips to save money. Learn how coverage, deductibles, and discounts impact rates and find the best…

Auto Insurance In Texas Essentials Rights Rates Explained
Understand Auto Insurance in Texas Essentials, Rights, and Rates Explained—key coverage rules, legal protections, and cost factors to navigate policies…

Auto Insurancein PAExplained Clearly With Key Insights
Auto Insurance in PA Explained Clearly With Key Insights: Learn PA’s mandatory coverage, average costs, discounts, and how to save on premiums—simplified…
Auto Insurancein NYKey Rules Costsand Choices Explained
Auto Insurance in NY: Key Rules, Costs, and Choices Explained—Discover NY’s mandatory coverage, factors affecting premiums, and how to select the best…

Auto Insurance In NYCKey Facts Costs And Choices
Explore Auto Insurance In NYC—key facts, costs, and choices to navigate NYC’s unique requirements, from liability minimums to high-risk policies. Get…
