13 Essential Facts About Auto Insurance for Non Car Owners
Table of Contents
- 1. Who Needs Non-Owner Auto Insurance?
- 2. Key Coverage Types Explained
- 3. Pricing Dynamics and Cost Factors
- 4. Common Mistakes to Avoid
- 5. Legal Requirements by State
- 6. How to Purchase the Right Policy
- 7. Non-Owner Insurance vs. SR-22 Filings
- 8. Special Scenarios and Exceptions
- Frequently Asked Questions
- 13 Actionable Tips for Securing the Best Policy
- Conclusion
Auto insurance for non car owners refers to specialized coverage designed for individuals who don’t own a vehicle but still need liability protection—such as those who frequently borrow cars, lease vehicles occasionally, or require an SR-22 without owning a car. For example, a college student who relies on rideshares or a parent helping a teenager drive might purchase this policy to avoid personal liability risks. This type of insurance bridges gaps left by standard policies, offering financial safeguards without the costs of full coverage.
The importance of auto insurance for non car owners stems from legal and financial risks. In many states, drivers must prove financial responsibility, even if they don’t own a car. Without coverage, an accident could result in lawsuits, asset seizures, or suspended licenses. Historically, non-owner policies emerged to address these needs, evolving alongside changes in lending laws and shared-economy trends like ridesharing. Today, they serve as a practical solution for temporary drivers, expatriates, or those in the military who don’t maintain a vehicle.
This article explores how auto insurance for non car owners functions, its cost dynamics, and who benefits most. It also covers common misconceptions, legal nuances, and actionable tips to secure the right policy. Whether navigating a short-term driving need or fulfilling a court mandate, understanding these details ensures compliance and peace of mind.
1. Who Needs Non-Owner Auto Insurance?
Auto insurance for non car owners targets specific groups: individuals who drive occasionally but lack a vehicle, those required to file an SR-22 after a license suspension, or drivers who share cars frequently. For instance, a rideshare driver using a friend’s car or a military spouse relocating without a vehicle may need this coverage. The policy’s flexibility makes it ideal for temporary situations, such as borrowing a car for a road trip or assisting a family member with errands.
Legal requirements often drive the need. In states like California or New York, drivers must maintain continuous insurance coverage, even if they don’t own a car. An SR-22 filing, common after DUIs or multiple violations, typically mandates non-owner insurance for a set period. Without it, license reinstatement or court compliance becomes impossible. Practical scenarios—like driving a rental car or a company vehicle—also highlight the necessity, as personal policies may not extend to borrowed vehicles.
2. Key Coverage Types Explained
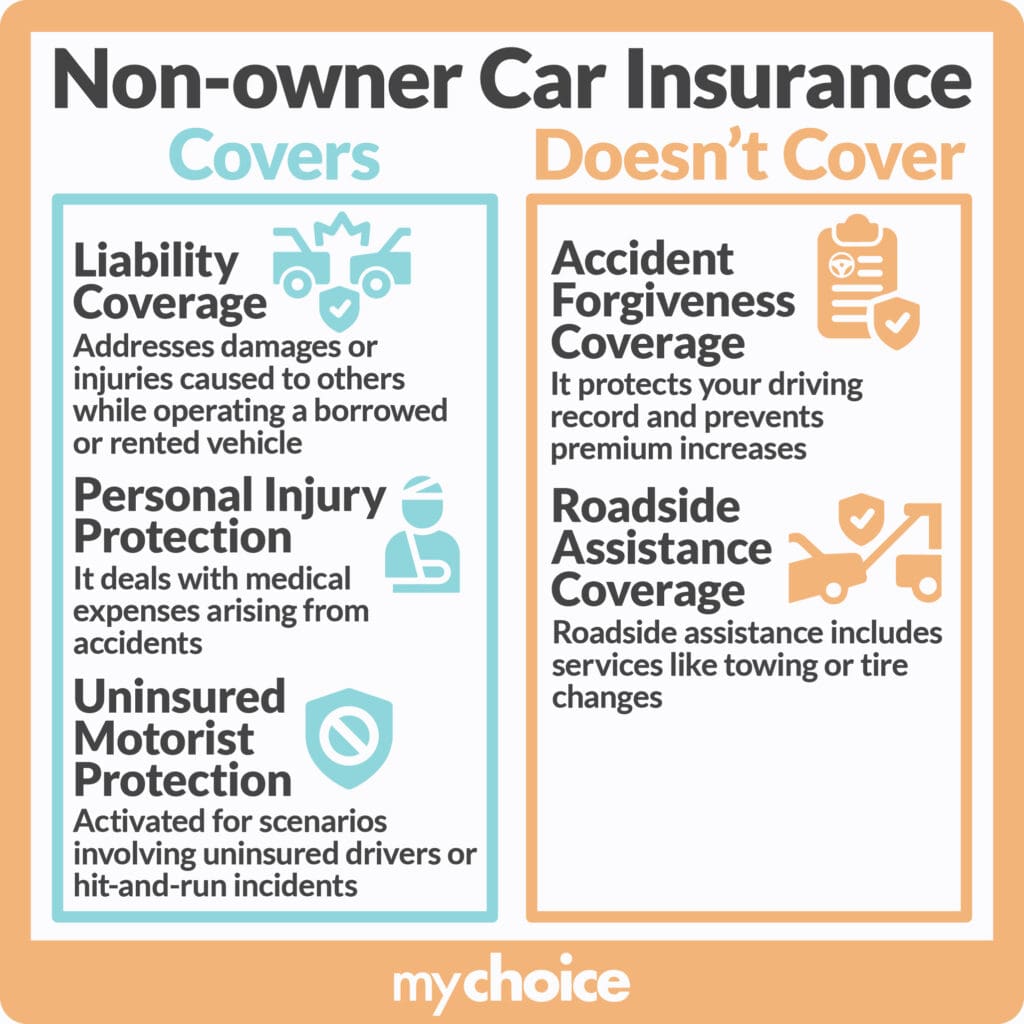
Auto insurance for non car owners primarily offers liability coverage, but policyholders can often add optional protections. Here’s what each facet entails:
- State-Minimum Liability: Covers bodily injury and property damage up to state-required limits. For example, in Texas, this might mean $30,000 per person/$60,000 per accident for injuries and $25,000 for property damage. Without it, a single accident could lead to out-of-pocket expenses exceeding $100,000.
- Collision and Comprehensive Add-Ons: Protects against damage to borrowed or rented vehicles. A policyholder driving a friend’s car in a hailstorm could file a claim under comprehensive coverage, avoiding personal liability for repairs costing thousands.
- Uninsured/Underinsured Motorist: Shields against at-fault drivers with insufficient coverage. In Florida, where uninsured motorists are prevalent, this add-on ensures medical bills or vehicle repairs aren’t absorbed by the policyholder.
- Medical Payments (MedPay): Covers medical expenses for injuries sustained by the driver or passengers, regardless of fault. A policyholder injured in a hit-and-run could use MedPay to pay for emergency room visits without waiting for a lawsuit settlement.
- Rental Reimbursement: Reimburses costs if the insured cannot use a vehicle due to a covered accident. For example, if a policyholder’s borrowed car is totaled, rental reimbursement might cover a week’s worth of Uber rides or a rental car.
While liability is standard, optional coverages depend on the insurer and state laws. Policyholders should assess their risk tolerance—balancing premium costs against potential financial exposure.
3. Pricing Dynamics and Cost Factors
The cost of auto insurance for non car owners varies widely, typically ranging from $300 to $1,000 annually, depending on location and coverage. Factors like driving history, credit score, and the state’s insurance regulations play a significant role. For instance, a driver in Michigan with a clean record might pay less than one in Louisiana due to differing state minimums and claim frequencies.
Insurance providers often charge higher premiums for non-owner policies because they lack data on the vehicle’s safety features or the driver’s commuting habits. However, discounts—such as bundling with a homeowners policy or completing a defensive driving course—can mitigate costs. A policyholder in New York might save 15% by combining non-owner auto insurance with a renters policy, reducing annual expenses from $800 to $680.
4. Common Mistakes to Avoid
Misunderstandings about auto insurance for non car owners can lead to gaps in coverage or legal trouble. One frequent error is assuming personal auto insurance extends to borrowed vehicles. Many policies exclude non-owned cars unless explicitly stated. For example, a driver with a personal policy might believe it covers a rental car, only to discover it doesn’t after an accident.
Another mistake involves underestimating the need for continuous coverage. Some policyholders cancel their non-owner insurance when they stop driving, unaware that lapses can trigger license suspensions or SR-22 requirements. A driver in Illinois who canceled coverage for six months might face a $500 reinstatement fee and a 60-day license revocation upon reapplying.
5. Legal Requirements by State
State laws dictate whether auto insurance for non car owners is mandatory, optional, or unnecessary. In no-fault states like Michigan, proof of financial responsibility is critical, even for non-owners. Conversely, states like Virginia allow non-owners to skip insurance unless they’re at fault in an accident. Understanding local regulations prevents fines or legal consequences.
For instance, California requires non-owners to carry liability insurance if they drive regularly, while Texas only mandates it for SR-22 filings. A policyholder in Arizona might face a $1,000 fine for driving without insurance, even if they don’t own a car. Researching state-specific rules ensures compliance and avoids unexpected penalties.
6. How to Purchase the Right Policy
Securing auto insurance for non car owners involves comparing quotes from providers like Geico, Progressive, or State Farm, each offering tailored options. Start by gathering personal details—driving history, credit score, and estimated annual mileage—then request quotes online or through an agent. Some insurers, like The General, specialize in high-risk non-owner policies, making them ideal for drivers with past violations.
Policyholders should review exclusions carefully. For example, a non-owner policy might exclude coverage for vehicles used in commercial activities, like ridesharing. A driver for Uber or Lyft would need a commercial policy instead. Reading the fine print ensures the policy aligns with individual needs and avoids claim denials.
7. Non-Owner Insurance vs. SR-22 Filings
Auto insurance for non car owners often overlaps with SR-22 requirements, but they serve distinct purposes. An SR-22 is a certificate proving financial responsibility, typically required after a DUI or serious traffic violation. Non-owner insurance fulfills this requirement but isn’t the same as an SR-22 itself. The insurance company files the SR-22 with the state on the policyholder’s behalf.
For example, a driver in Ohio with a suspended license might purchase non-owner insurance to reinstate their license. The insurer then files the SR-22, demonstrating continuous coverage. Without both, the license remains suspended, and the driver faces additional legal hurdles. Understanding this distinction prevents costly errors.
8. Special Scenarios and Exceptions
Unique situations—such as driving a company car or a family member’s vehicle—may require auto insurance for non car owners. Corporate policies often exclude personal use, leaving employees vulnerable. A sales representative using a company car for personal errands might need non-owner insurance to cover potential accidents. Similarly, military personnel stationed overseas may purchase non-owner policies to drive rental cars during temporary assignments.
Expatriates and international drivers also benefit from non-owner insurance. A foreign visitor renting a car in the U.S. might purchase a short-term non-owner policy to comply with local laws. This coverage ensures they’re not personally liable for damages while avoiding the complexities of a full auto policy.
13 Actionable Tips for Securing the Best Policy
Navigating auto insurance for non car owners requires strategy. Here are 13 practical steps to optimize coverage and costs:
Tip 1: Compare quotes from 3+ insurers. Prices vary significantly; Geico might offer a 20% discount compared to Allstate for the same coverage.
Tip 2: Bundle with renters or homeowners insurance. Insurers like State Farm provide multi-policy discounts, reducing annual premiums by 10–15%.
Tip 3: Check for high-risk insurers. Companies like The General specialize in non-owner policies for drivers with past violations, offering rates tailored to their profiles.
Tip 4: Request a defensive driving discount. Completing an approved course can lower premiums by 5–10%, as insurers view it as reduced risk.
Tip 5: Verify SR-22 filing requirements. Some states require the SR-22 upfront; others allow it after purchase. Confirm with the insurer to avoid delays in license reinstatement.
Tip 6: Disclose all driving activities. Failing to mention rideshare driving could void coverage. Transparency ensures claims are honored in case of accidents.
Tip 7: Ask about short-term policies. Insurers like Progressive offer 6-month non-owner policies for temporary needs, such as relocating without a car.
Tip 8: Review state minimums carefully. Some states, like New Hampshire, have no mandatory insurance, but non-owners may still need liability coverage to protect assets.
Tip 9: Consider usage-based discounts. Programs like Progressive’s Snapshot track driving habits; safe behavior can yield discounts of up to 30%.
Tip 10: Avoid canceling for short gaps. Even a 30-day lapse can trigger license suspension in states like New York. Maintain continuous coverage to stay compliant.
Tip 11: Clarify coverage for borrowed vehicles. Some policies exclude non-family members’ cars. Confirm with the insurer to prevent claim denials.
Tip 12: Store policy documents digitally and physically. Keep a copy in the car and on a secure cloud service. In an accident, quick access to proof of insurance speeds up claim processing.
Tip 13: Reevaluate annually. Life changes—like moving to a new state or improving credit—can lower premiums. Annual reviews ensure the policy remains cost-effective.
Conclusion
Auto insurance for non car owners serves as a critical safeguard for individuals who drive without owning a vehicle, offering liability protection, legal compliance, and financial security. Key aspects include understanding who needs this coverage, the types of protection available, and how pricing is determined. Legal requirements vary by state, and common mistakes—such as assuming personal insurance covers borrowed cars—can lead to costly oversights. By comparing policies, leveraging discounts, and staying informed about state laws, individuals can secure affordable and appropriate coverage.
As driving habits evolve—with ridesharing, car-sharing, and temporary relocations becoming more common—non-owner insurance will continue to play a vital role. Staying proactive about coverage ensures that drivers remain protected, compliant, and financially secure in an ever-changing landscape.