14+ Ways to Find the Cheapest Auto Insurance in Arizona Without Sacrificing Coverage
Table of Contents
- 1. How Arizona’s Insurance Market Affects Pricing
- 2. Key Factors That Raise or Lower Your Premium
- 3. Comparing Providers for the Best Rates
- 4. Discounts That Slash Premiums Dramatically
- 5. Common Mistakes That Inflate Costs
- 6. How to Qualify for Arizona’s High-Risk Pool
- 7. When to Raise Your Coverage Limits
- 8. The Role of Credit Scores in Arizona Rates
- Frequently Asked Questions
- 14 Proven Tips to Secure Cheaper Auto Insurance in Arizona
- Conclusion
Finding **auto insurance Arizona cheapest** options doesn’t mean compromising on quality or legal compliance. For example, a Phoenix resident with a clean driving record could pay as little as **$1,200 annually** for full coverage with a top-rated insurer—about 30% less than the state average—by comparing quotes and applying targeted discounts. The affordability of **auto insurance Arizona cheapest** plans hinges on understanding local pricing factors, such as Arizona’s no-fault insurance system, high urban traffic risks in cities like Tucson and Mesa, and the state’s minimum liability limits ($15,000 per person/$30,000 per accident). Historically, Arizona’s insurance costs have fluctuated due to legislative changes, such as the 2019 expansion of medical payment coverage, which indirectly increased premiums. However, proactive strategies—like bundling policies or exploring usage-based programs—can mitigate these expenses.
This guide explores how to navigate **auto insurance Arizona cheapest** options effectively, covering pricing dynamics, provider comparisons, and eligibility requirements. It also highlights common pitfalls and how to avoid them, ensuring drivers secure both affordability and adequate protection.
The following sections break down key considerations: how insurers calculate rates in Arizona, the role of credit scores and driving history, and the best discounts to pursue. Practical examples illustrate real-world savings, while actionable tips provide a roadmap for securing **auto insurance Arizona cheapest** without cutting essential coverage.
1. How Arizona’s Insurance Market Affects Pricing
Arizona’s **auto insurance Arizona cheapest** landscape is shaped by state-specific regulations, risk factors, and insurer competition. Unlike no-fault states with lower premiums, Arizona’s system requires personal injury protection (PIP) coverage, adding to costs. Urban areas like Phoenix and Scottsdale see higher rates due to traffic congestion and theft risks, while rural regions may offer lower premiums. For instance, a driver in Flagstaff could pay **$900–$1,100 annually** for minimum coverage, compared to **$1,500–$1,800** in Tempe.
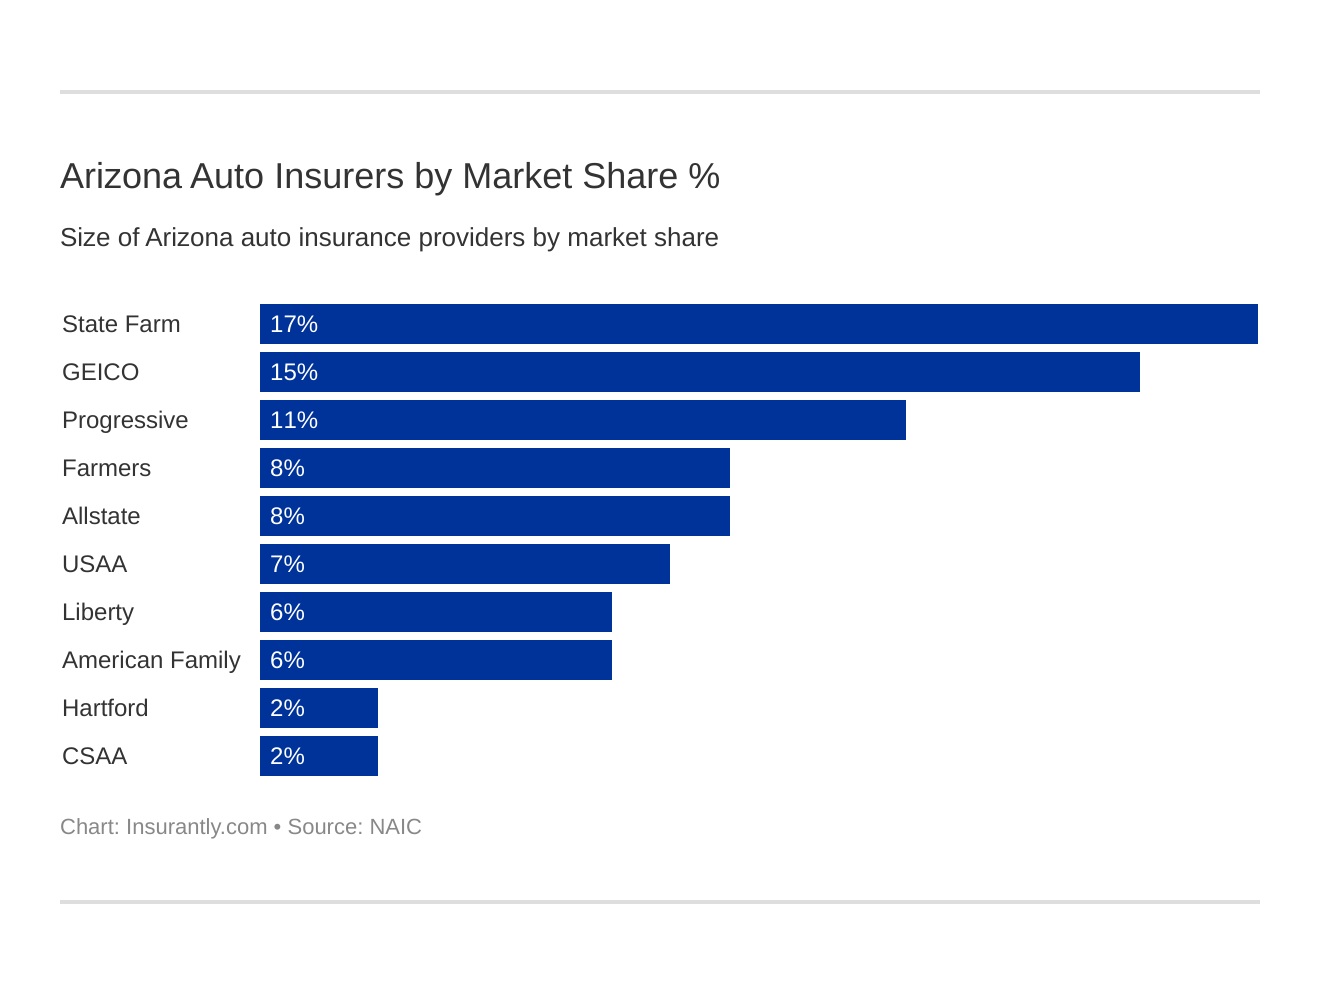
Insurers also weigh Arizona’s climate-related risks, such as monsoon floods or heatwave-related accidents. Providers like Geico and State Farm dominate the market, but local agencies (e.g., Arizona Farm Bureau Insurance) often undercut prices by **10–20%** for members. Understanding these variables is critical to finding **auto insurance Arizona cheapest** rates.

2. Key Factors That Raise or Lower Your Premium
Several variables influence whether a policy qualifies as **auto insurance Arizona cheapest**. The most impactful include:
- Driving Record: A single at-fault accident can spike rates by **40–60%**. For example, a Chandler driver with a minor violation might pay **$1,400/year**, while a clean record holder pays **$1,000**. Waiting periods (typically 3–5 years) can restore lower rates.
- Credit Score: Arizona allows insurers to use credit history, with poor scores increasing premiums by **20–30%**. A score of 650 could raise costs by **$300/year** compared to a 750+ score.
- Vehicle Type: Luxury or high-theft cars (e.g., Jeep Wranglers in Phoenix) cost more to insure. A Toyota Corolla, however, qualifies for **auto insurance Arizona cheapest** rates due to lower repair/replacement costs.
- Annual Mileage: Low-mileage drivers (under 7,500 miles/year) often secure discounts of **5–15%**. Commuters in Gilbert may save **$200/year** by opting for a hybrid vehicle.
- Coverage Limits: Choosing Arizona’s state minimums ($25,000 property damage) slashes premiums but leaves gaps. Raising limits to $50,000/$100,000 adds **$300–$500/year** but protects against lawsuits.
3. Comparing Providers for the Best Rates
Not all insurers offer **auto insurance Arizona cheapest** plans, and rates vary significantly. Independent agents can access **10–15 quotes** from carriers like Progressive, Allstate, and USAA (for military families), often uncovering savings of **$400–$800/year**. For example, Progressive’s Snapshot program rewards safe driving with up to **30% off**, while Farmers offers discounts for bundling home and auto policies. Local providers, such as Arizona’s Mercury Insurance, may also undercut national brands by **10–15%** for residents with average risk profiles.
Online comparison tools (e.g., The Zebra or NerdWallet) streamline this process, but direct quotes from agents ensure accuracy. Always verify whether a provider participates in Arizona’s **High-Risk Auto Insurance Pool**, which offers last-resort coverage for drivers with poor records.

4. Discounts That Slash Premiums Dramatically
Discounts are the fastest way to achieve **auto insurance Arizona cheapest** rates. The most valuable include:
- Bundling Policies: Combining auto with renters or home insurance can save **15–25%**. A Scottsdale family paying **$1,200/year** for separate policies might reduce costs to **$900** by bundling.
- Safe Driver Programs: Enrolling in telematics (e.g., State Farm’s Drive Safe & Save) can cut premiums by **10–30%** for low-risk drivers. A Tucson resident with steady speeds saved **$250/year** after 6 months.
- Low-Mileage Discounts: Drivers under 7,500 miles/year may qualify for **5–15% off**. A remote worker in Sedona saved **$180/year** by certifying their annual mileage.
- Anti-Theft Device Discounts: Installing GPS trackers (e.g., LoJack) or alarm systems can reduce rates by **5–10%**. Phoenix drivers report savings of **$150–$300/year** after installation.
- Affinity Group Discounts: Memberships in organizations like AAA or Costco can yield **10–20% off**. A Mesa Costco member paid **$1,000/year** instead of **$1,300** for identical coverage.
5. Common Mistakes That Inflate Costs
Overlooking critical details often leads to higher premiums when seeking **auto insurance Arizona cheapest** coverage. Common errors include:
- Ignoring Usage-Based Programs: Skipping telematics discounts costs drivers **$200–$500/year**. A Gilbert driver with steady habits could have saved **$400/year** by enrolling in Progressive’s Snapshot.
- Underestimating Deductibles: Choosing a **$500 deductible** instead of **$1,000** might save **$100/year** but risks financial strain after an accident. A Peoria resident with a **$250 deductible** paid **$150 more annually** but faced a **$750 out-of-pocket** claim.
- Not Shopping Annually: Rates fluctuate; failing to compare quotes can cost **$300–$600/year**. A Chandler driver stuck with the same insurer for 3 years overpaid by **$500** after switching to a cheaper provider.
- Mismatched Coverage: Dropping collision/comprehensive to save **$200/year** may leave a driver liable for **$5,000+** in repairs after a hailstorm. Tucson drivers often regret this after monsoon damage.
- Skipping Multi-Policy Bundles: Separate policies can cost **20–30% more**. A Flagstaff homeowner paid **$1,400/year** for unbundled insurance instead of **$1,050** after combining policies.
6. How to Qualify for Arizona’s High-Risk Pool
Drivers with DUI convictions, multiple at-fault accidents, or license suspensions may struggle to find **auto insurance Arizona cheapest** options through standard channels. Arizona’s **Assigned Risk Plan**, managed by the Arizona Automobile Insurance Fund, provides coverage as a last resort. To qualify, applicants must:
- Be Denied by Three Insurers: Standard carriers reject high-risk drivers, forcing them to apply through the state pool.
- Meet State Minimum Requirements: Coverage includes **$15,000 bodily injury/$30,000 per accident** and **$10,000 property damage**, but no collision/comprehensive unless added.
- Pay Higher Premiums: Rates in the pool average **$2,500–$4,000/year**, but drivers can transition to private insurers after **3–5 years** of clean records.
For example, a Mesa driver with a DUI paid **$3,200/year** in the pool but reduced costs to **$1,600** after 4 years of safe driving with a private insurer. Rebuilding credit and completing defensive driving courses can also improve eligibility.
7. When to Raise Your Coverage Limits
Opting for **auto insurance Arizona cheapest** minimum limits may seem cost-effective, but it exposes drivers to significant financial risk. Arizona’s **$15,000 bodily injury limit** is inadequate for severe accidents; medical costs alone can exceed **$50,000**. Raising limits to **$50,000/$100,000** adds **$300–$500/year** but provides critical protection. For instance, a Phoenix driver with minimum coverage faced a **$20,000 lawsuit** after a collision, depleting savings. Higher limits also prevent insurers from dropping policies after claims.
Uninsured/underinsured motorist (UM/UIM) coverage is another essential upgrade. Arizona requires UM coverage but allows optional UIM; adding **$50,000 in UIM protection** costs **$100–$200/year** but covers hits by drivers with insufficient insurance.
8. The Role of Credit Scores in Arizona Rates
Arizona law permits insurers to use credit scores to determine **auto insurance Arizona cheapest** eligibility, a practice tied to risk assessment. A **650 credit score** may increase premiums by **20–30%**, while a **750+ score** can secure discounts of **5–15%**. For example, a driver in Surprise with a 680 score might pay **$1,300/year**, whereas a neighbor with a 760 score pays **$1,050**. Improving credit—by paying down debt or correcting errors—can lower rates within **6–12 months**. Some insurers, like Geico, offer credit-based discounts for scores above **720**, further reducing costs.
This system underscores the importance of financial health in securing **auto insurance Arizona cheapest** rates. Even a **30-point credit score increase** can translate to **$100–$200 in annual savings**.
14 Proven Tips to Secure Cheaper Auto Insurance in Arizona
Finding **auto insurance Arizona cheapest** requires strategy. Here are 14 actionable steps:
Tip 1: Compare at least 5 quotes annually. Prices vary by **20–30%** between insurers. Use tools like The Zebra to streamline comparisons.
Tip 2: Ask about bundling discounts. Combining auto with home or renters insurance can cut costs by **15–25%**. Providers like USAA and Farmers offer the best savings.
Tip 3: Enroll in usage-based programs. Telematics like Progressive’s Snapshot or State Farm’s Drive Safe & Save can reduce premiums by **10–30%** for safe drivers.
Tip 4: Increase your deductible (if affordable). Raising it from **$500 to $1,000** can save **$100–$200/year**, but ensure you can cover the higher out-of-pocket cost.
Tip 5: Maintain a high credit score. A **750+ score** can secure discounts of **5–15%**. Paying down debt and correcting credit errors improves eligibility.
Tip 6: Install anti-theft devices. GPS trackers or alarms can lower rates by **5–10%**. Phoenix drivers report savings of **$150–$300/year** after installation.
Tip 7: Take a defensive driving course. Programs like Arizona’s **Traffic Survival School** can reduce rates by **5–10%** for 3 years.
Tip 8: Opt for a lower-mileage vehicle. Cars with **under 7,500 miles/year** qualify for **5–15% discounts**. Hybrid models often meet this criterion.
Tip 9: Avoid unnecessary coverage. Drop collision/comprehensive only if your car’s value is **under $3,000–$5,000**. Otherwise, keep it to protect against theft or accidents.
Tip 10: Join affinity groups. Memberships in AAA, Costco, or professional organizations can yield **10–20% off**. Always ask insurers about group discounts.
Tip 11: Pay annually instead of monthly. Avoiding installment fees can save **$20–$50/year**. Many insurers offer a **2–3% discount** for upfront payments.
Tip 12: Review your policy every 6 months. Life changes (e.g., moving, marriage) can affect rates. Update your insurer to reflect these to avoid overpaying.
Tip 13: Ask about loyalty discounts. Some insurers reward **3+ years of continuous coverage** with **5–10% off**. Geico and State Farm often offer these.
Tip 14: Consider Arizona’s High-Risk Pool if denied. Drivers with poor records can access coverage through the **Assigned Risk Plan**, though rates are higher. Rebuilding credit and driving history improves future eligibility.
Conclusion
Securing **auto insurance Arizona cheapest** hinges on leveraging discounts, comparing providers, and avoiding common pitfalls like underestimating coverage needs. Arizona’s unique insurance landscape—from urban traffic risks to credit-based pricing—demands a tailored approach. By applying the strategies outlined, drivers can balance affordability with comprehensive protection, ensuring financial security without overpaying.
As market conditions evolve, staying proactive with annual reviews and policy adjustments will continue to unlock savings. The key is to treat insurance as an investment in long-term financial stability, not just a mandatory expense.
Frequently Asked Questions
Can I get full coverage auto insurance in Arizona for under $1,500/year?
Yes, but it depends on factors like driving history, location, and vehicle type. Drivers in rural areas with clean records and high credit scores often secure full coverage for **$1,200–$1,400/year**. Urban dwellers may pay slightly more. Comparing quotes from Geico, State Farm, and local providers maximizes savings.
Does Arizona require full coverage auto insurance?
No, Arizona only mandates **liability insurance** (bodily injury and property damage). However, lenders typically require **collision/comprehensive** if you finance or lease a vehicle. Dropping full coverage to save money risks financial loss in accidents.
How much can I save by bundling auto and home insurance?
Bundling can reduce premiums by **15–25%**. For example, a family paying **$1,200/year** for separate policies might save **$200–$300/year** by combining them. Providers like Allstate and Farmers offer the deepest discounts for bundled policies.
Will my rates go up if I file a claim?
Filing a claim can increase rates by **20–50%**, depending on the insurer. Minor claims (e.g., fender benders) may have a smaller impact than at-fault accidents. Shopping around after a claim can help mitigate rate hikes.
Are there discounts for students in Arizona?
Yes, many insurers offer **good student discounts** (5–15% off) for drivers under 25 with a **B average or higher**. Programs like State Farm’s Steer Clear and Allstate’s Drivewise also provide savings for safe student drivers.
How often should I shop for cheaper auto insurance?
Comparing quotes **annually** ensures you’re not overpaying. Rates fluctuate due to market changes, driving history updates, or new discounts. Even a **10% rate drop** can save **$100–$300/year** without sacrificing coverage.
Related articles

10 Ways to Find the Best Auto Insurance Cheap Quote in 2024
Discover how to secure an affordable auto insurance cheap quote without sacrificing coverage. Learn expert tips, avoid costly mistakes, and compare…
13 Ways to Find Affordable Online Car Insurance Without Sacrificing Coverage
Cut car insurance costs online without risking protection. Discover 13 proven strategies to secure affordable online car insurance while keeping premiums…

14+ Smart Ways to Find Affordable Online Auto Insurance in 2024
Discover how to cut auto insurance costs without sacrificing coverage. Compare quotes, avoid hidden fees, and unlock savings with these proven strategies…
8 Smart Ways to Get an Affordable Car Insurance Quote in 2024
An affordable car insurance quote saves hundreds yearly. Learn how to compare rates, avoid hidden costs, and secure the best deal without sacrificing…
11+ Smart Ways to Find Affordable Car Insurance in New York
Discover proven strategies for securing **affordable car insurance in New York** without sacrificing coverage. Learn how to cut costs legally and protect…
