11+ Smart Ways to Find Affordable Car Insurance in New York
Table of Contents
- 1. New York’s Unique Insurance Rules
- 2. Key Factors Affecting Affordable Car Insurance in New York
- 3. Top Discounts for Affordable Car Insurance in New York
- 4. Comparing Providers for Affordable Car Insurance in New York
- 5. Common Mistakes That Raise Premiums
- 6. How to Lower Premiums Legally
- 7. The Role of Credit and Insurance Scores
- 8. Regional Variations in Affordable Car Insurance in New York
- Frequently Asked Questions
- 11 Actionable Tips for Affordable Car Insurance in New York
- Conclusion
Affordable car insurance in New York refers to policies that balance low premiums with mandatory coverage while complying with the state’s strict insurance laws. For example, a young driver in Brooklyn paying $1,800 annually for full coverage might find a comparable policy for $1,200 by adjusting deductibles or leveraging discounts. New York’s unique no-fault system—where personal injury protection (PIP) is mandatory—adds complexity, making cost-saving strategies critical.
The importance of affordable car insurance in New York extends beyond monthly savings. Skyrocketing premiums (often 20–50% higher than the national average) can strain budgets, especially in high-cost cities like NYC or Buffalo. Without proper coverage, drivers risk financial ruin from accidents, lawsuits, or uninsured motorists. Historically, New York’s insurance market has faced volatility, from rate hikes in the 2010s to legislative reforms like the 2021 PIP changes, which directly impacted affordability.
This guide breaks down how to navigate New York’s insurance landscape. It covers pricing factors, discount opportunities, provider comparisons, and legal nuances—equipping drivers to make informed choices without compromising protection.
1. New York’s Unique Insurance Rules
New York mandates higher minimum coverages than most states: $25,000 per person/$50,000 per accident for bodily injury liability, $10,000 for property damage, and $50,000 in PIP. These requirements drive up base premiums. For instance, a policy in Albany might cost $1,500 annually, while a similar one in Manhattan could exceed $3,000 due to urban risk factors.
Violating these rules carries severe penalties, including license suspension or fines up to $1,500. The no-fault system also shifts medical costs to insurers, reducing litigation but increasing premiums. Drivers must weigh compliance costs against potential savings from minimal coverage—though underinsurance risks catastrophic out-of-pocket expenses.
2. Key Factors Affecting Affordable Car Insurance in New York
Several variables influence premiums in New York, often beyond a driver’s control. Understanding these helps set realistic expectations:
- Location. Urban areas like Staten Island or Queens face higher theft and accident rates, inflating premiums by 30–50%. A driver in Syracuse might pay $900 annually for the same coverage as a NYC resident’s $2,200. Practical tip: Compare quotes across ZIP codes; even neighboring boroughs can yield $200+ differences.
- Driving Record. A single at-fault accident can increase rates by 40–60% for 3–5 years. For example, a clean record in Rochester averages $1,100/year, while a driver with a speeding ticket pays $1,600. Implication: Defensive driving courses (like NY’s approved programs) can mitigate increases.
- Vehicle Type. Luxury or high-theft cars (e.g., a 2020 BMW 3 Series) cost 2–3x more to insure than a Honda Civic. In Brooklyn, a Civic’s premium might be $1,200, while the BMW’s tops $3,500. Note: Older vehicles may qualify for “agreed value” policies, capping collision claims.
- Credit Score. New York allows insurers to use credit history, with poor scores adding 15–30% to premiums. A driver with a 750+ score in Buffalo pays ~$1,000, while one with 600+ pays ~$1,400. Action: Dispute errors on credit reports to improve rates.
- Coverage Limits. Opting for state minimums saves money but leaves gaps. A driver in Albany might save $300/year by dropping from $100K/$300K to $25K/$50K limits—but risk $75K in lawsuits from a multi-car crash.
3. Top Discounts for Affordable Car Insurance in New York
New York insurers offer discounts that can slash premiums by 20–40%. The most valuable are often overlooked:
- Bundling Policies. Combining auto with home or renters insurance (e.g., through Geico or State Farm) yields 10–20% savings. A family in Syracuse paying $1,800 for auto alone might reduce that to $1,400 by bundling. Caveat: Ensure the home policy’s insurer has strong auto claims service.
- Low Mileage. Drivers logging under 7,500 miles/year (common in NYC) can qualify for discounts of $100–$300 annually. Progressive’s “Usage-Based” program rewards such drivers with up to 30% off. Example: A Manhattan commuter with a 5-mile daily trip saves $250/year.
- Anti-Theft Devices. Installing a certified GPS tracker (e.g., OnStar or LoJack) can cut premiums by 5–15%. In Brooklyn, a driver with a tracker pays $1,500 vs. $1,800 without. Tip: Some insurers reimburse installation costs.
- Good Student Discounts. Full-time students with a B average under 25 qualify for 10–25% off. A college student in Ithaca might drop from $2,000 to $1,500 annually. Note: Proof of enrollment is required.
- Affinity Programs. Memberships in groups like AAA, AARP, or even employer associations (e.g., NY teachers) unlock 5–15% discounts. A driver affiliated with NY’s Civil Service Employees Association could save $200/year.

4. Comparing Providers for Affordable Car Insurance in New York
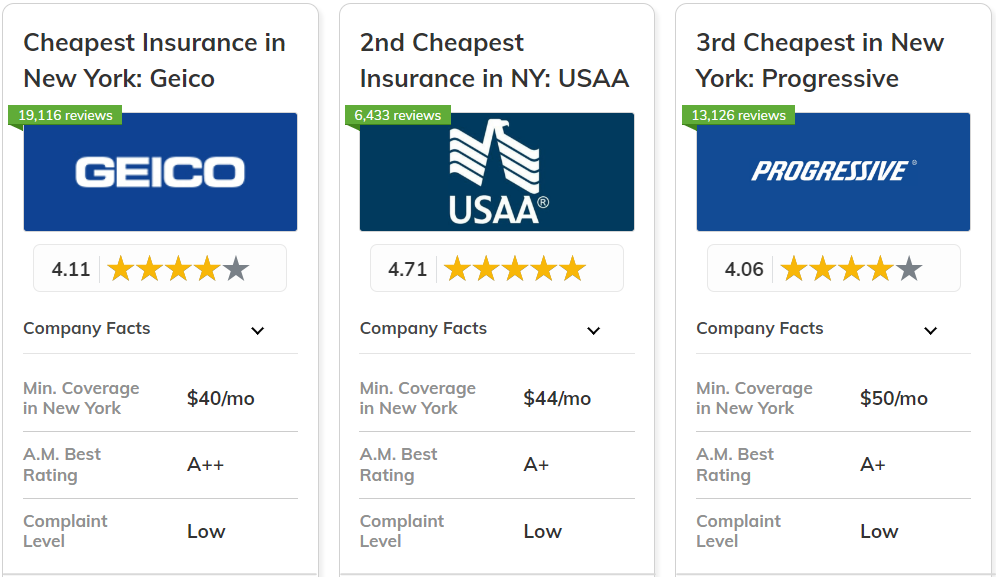
New York’s top insurers vary by region and driver profile. State Farm and Geico consistently rank as affordable for average drivers, while local providers like The General offer niche savings for high-risk applicants. A 2023 NAIC study found that switching providers can save New York drivers 15–35% annually.
Direct insurers (e.g., Progressive, Direct Auto) often undercut traditional agencies by cutting overhead, but their claims service may lag. For example, a driver in Rochester might pay $1,200 with Progressive vs. $1,500 with Allstate—but Progressive’s claims resolution time averages 45 days vs. Allstate’s 30. Local agents, however, provide tailored advice for complex situations like commercial vehicle use.
5. Common Mistakes That Raise Premiums
Oversights in policy selection or claims handling can inflate costs long-term. Three frequent errors stand out:
- Skipping the Uninsured Motorist Coverage (UM). New York requires UM protection, but drivers often underestimate its value. A hit-and-run in Albany could leave a driver with $50K in medical bills if UM limits are too low. Fix: Match UM limits to liability coverage.
- Filing Small Claims. Reporting a $1,500 fender bender might raise rates by 20% for 3 years. In NYC, where minor accidents are common, drivers should pay out-of-pocket for repairs under $2,000. Data: NY’s DMV reports 60% of claims under $2,500.
- Ignoring Usage-Based Programs. Telematics tools (e.g., State Farm’s Drive Safe & Save) can reward safe driving with up to 30% savings—but only 12% of New York drivers enroll. A Buffalo commuter averaging 60 mph might save $300/year by opting in. Warning: Privacy concerns may deter some.
- Not Shopping Annually. Loyalty discounts are rare in New York. A driver sticking with the same insurer for 5 years might overpay by $1,000+ compared to competitors. Example: A 2022 policy renewal in Brooklyn showed a 25% rate hike from the same provider.
6. How to Lower Premiums Legally
Beyond discounts, structural adjustments can reduce costs without violating laws. Two strategies stand out:
First, increasing deductibles from $500 to $1,000 can cut collision/comprehensive costs by 15–25%. For a driver in Syracuse with a $1,500 premium, this might save $250/year—but only if they can cover the higher deductible in an accident. Second, paying premiums annually (instead of monthly) avoids finance charges. A $1,200 policy paid monthly with a 3% fee costs $1,236; paid upfront, it’s $1,200.
For high-risk drivers (e.g., those with DUIs), exploring the New York Automobile Insurance Plan (NYAIP) can provide last-resort coverage at regulated rates. However, NYAIP policies are 30–50% pricier than standard plans and require proof of prior denial. Drivers should exhaust all other options before applying.
7. The Role of Credit and Insurance Scores
New York insurers use credit-based insurance scores (CBIS), distinct from traditional credit scores, to predict risk. A CBIS of 500–600 might add $300–$500 to annual premiums compared to a 700+ score. For example, a driver in Rochester with a 650 CBIS pays $1,400, while one with 750 pays $1,100.
Improving CBIS involves paying bills on time, reducing credit card balances (aim for under 30% utilization), and avoiding new loans. Disputing inaccuracies with credit bureaus (Experian, Equifax) can also help. Some insurers, like USAA, don’t use CBIS, making them ideal for drivers with poor credit—but membership is limited to military families.
8. Regional Variations in Affordable Car Insurance in New York
Premiums fluctuate drastically across New York’s 62 counties. Urban areas like New York City and Long Island face higher costs due to congestion, theft, and litigation risks, while rural Upstate regions offer 30–50% savings. For instance, a driver in Plattsburgh pays ~$900/year, while a similar driver in Queens pays ~$2,500.
Even within cities, ZIP codes matter. A 2023 study by the NY Department of Financial Services found that a driver in Staten Island pays 15% less than one in Manhattan for identical coverage. This disparity stems from differences in accident rates, traffic density, and local crime statistics. Drivers should compare quotes for their exact address, not just city names.
11 Actionable Tips for Affordable Car Insurance in New York
Cutting costs requires targeted strategies tailored to New York’s market.
Tip 1: Compare quotes from at least 5 insurers. Prices vary widely—request quotes from Geico, State Farm, Progressive, and local providers to spot discrepancies of $300–$800 annually.
Tip 2: Ask about all available discounts. Many drivers miss out on bundling, low-mileage, or anti-theft discounts. Call insurers to check eligibility for programs like AAA membership or employer groups.
Tip 3: Choose a higher deductible if you can afford it. Raising the deductible from $500 to $1,000 can reduce collision costs by 20%. Ensure emergency funds cover the higher out-of-pocket expense.
Tip 4: Pay annually to avoid finance fees. Monthly payments often include a 2–3% processing fee. A $1,500 policy costs $1,545 monthly vs. $1,500 upfront—a $45 annual difference.
Tip 5: Maintain a clean driving record. A single ticket can raise rates by 15–25% for 3 years. Defensive driving courses (approved by NY’s DMV) can offset minor infractions.
Tip 6: Install anti-theft devices. GPS trackers or alarms can earn 5–15% discounts. Some insurers reimburse installation costs—check with providers like Allstate or Nationwide.
Tip 7: Consider usage-based insurance. Programs like State Farm’s Drive Safe & Save reward safe driving with up to 30% savings. Enrollment is free and doesn’t affect privacy negatively.
Tip 8: Shop after major life changes. Moving, marriage, or a job change can qualify you for new discounts. Insurers often adjust rates based on updated risk profiles.
Tip 9: Review coverage limits annually. Inflation and rising medical costs may require higher liability limits. A $25K/$50K policy from 2015 might leave you underinsured today.
Tip 10: Explore regional insurers. Companies like The General or Dairyland specialize in high-risk drivers or rural areas, offering competitive rates in niche markets.
Tip 11: Check for NY-specific programs. The NY Automobile Insurance Plan (NYAIP) provides last-resort coverage for denied applicants. For young or high-risk drivers, state-mandated programs like “Young Driver” discounts can also help.
Conclusion
Affordable car insurance in New York demands a mix of strategic shopping, discount utilization, and adherence to state-specific rules. Drivers must balance cost savings with adequate coverage, leveraging tools like usage-based programs, regional comparisons, and credit management. New York’s no-fault system and high minimum requirements add complexity, but proactive measures—such as bundling policies, maintaining a clean record, and exploring high-risk insurers—can mitigate expenses.
As insurance markets evolve, staying informed about legislative changes (e.g., PIP reforms) and insurer innovations will be key to securing both affordability and protection. Regular policy reviews and open communication with agents ensure drivers remain prepared for New York’s unique challenges.
Related articles
8 Smart Ways to Get an Affordable Car Insurance Quote in 2024
An affordable car insurance quote saves hundreds yearly. Learn how to compare rates, avoid hidden costs, and secure the best deal without sacrificing…

10 Proven Ways to Find Affordable Car Insurance Near Me
Discover smart strategies to locate cheap, reliable car insurance near you—compare quotes, avoid hidden fees, and save hundreds annually without…
10 Ways to Get Affordable Car Insurance for New Drivers in 2024
Discover proven strategies to secure **affordable car insurance for new drivers** without sacrificing coverage. Learn how to cut costs legally while…
9 Essential Facts About Affordable Auto Insurance Quotes
Secure an affordable auto insurance quote without overspending. Learn how pricing works, tips to save, and common mistakes to avoid for smarter coverage…
