10 Key Insights About Auto Home Insurance Bundles
Table of Contents
- 1. How Pricing Works in Bundles
- 2. Coverage Customization Options
- 3. Provider Comparison Framework
- 4. Common Mistakes to Avoid
- 5. Claims Process Simplification
- 6. Tax and Legal Implications
- 7. When to Reevaluate Your Bundle
- 8. Future Trends in Bundling
- Frequently Asked Questions
- 10 Actionable Tips for Optimizing Your Auto Home Insurance Bundle
- Conclusion
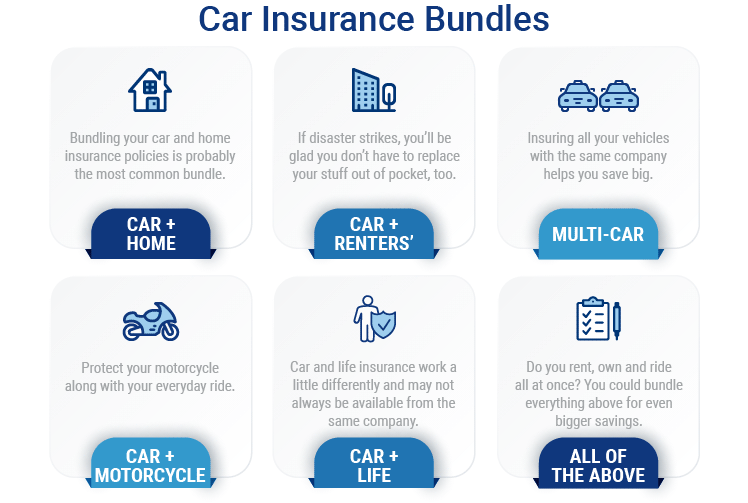
An auto home insurance bundle refers to a combined policy that covers both a vehicle and a homeowner’s property under a single insurer, often yielding discounts and streamlined management. For example, a driver insuring their SUV and suburban home through the same provider—like State Farm or Allstate—qualifies for a bundled rate, reducing premiums by 10–25% compared to separate policies. This approach isn’t new; insurers have long recognized that customers with multiple policies tend to stay longer, creating loyalty incentives.
The primary benefit of an auto home insurance bundle lies in its dual advantage: cost efficiency and convenience. Bundling eliminates the hassle of managing separate policies, claims, and renewals with different providers. Historically, insurers introduced bundling in the 1990s as a competitive edge, and today, it remains a cornerstone of customer retention strategies. The practical context is clear—homeowners and drivers with both assets stand to gain financially while simplifying their insurance portfolio.
This article explores the mechanics, advantages, and potential drawbacks of an auto home insurance bundle, along with actionable tips to secure the best deal. Topics include pricing dynamics, coverage customization, provider comparisons, and common missteps to avoid.
1. How Pricing Works in Bundles
Insurance bundles discount premiums based on risk aggregation and provider incentives. A bundled policy typically reduces costs by 10–25% compared to separate policies, though discounts vary by insurer and location. For instance, Progressive might offer a 15% discount for bundling auto and home, while Farmers Insurance could provide 20% in high-risk areas. The savings stem from insurers’ reduced administrative overhead and the assumption that bundled customers are less likely to switch providers.
Pricing also depends on combined risk factors. A home in a flood-prone zone paired with a high-mileage driver may offset discounts, while a low-risk homeowner with a safe vehicle could see greater savings. Real-world data from the Insurance Information Institute shows that bundled policies often result in net savings of $300–$800 annually, depending on coverage levels.
2. Coverage Customization Options
Bundling doesn’t limit flexibility—policyholders can tailor coverage to their needs. Key facets include:
- Deductible alignment: Matching deductibles across auto and home policies simplifies claims. For example, a $1,000 deductible on both policies ensures consistency in out-of-pocket costs during a hailstorm or fender bender. This alignment reduces confusion during claims processing and may qualify for additional discounts.
- Liability limits: Bundling allows adjusting liability coverage (e.g., $300,000 per incident) uniformly across policies. A family with significant assets might increase liability limits in both policies to protect savings, while a minimalist driver could opt for state minimums. Higher limits often come with bundled premium discounts.
- Rider additions: Bundles permit adding riders like equipment coverage for tools or electronics in the home policy and roadside assistance in the auto policy. A contractor bundling policies might add a $5,000 rider for tools stored in their truck, while a tech worker could bundle cyber liability coverage for home office equipment.
- Umbrella policy integration: Some insurers offer umbrella policies at discounted rates when bundled with auto and home. For instance, a $1 million umbrella policy might cost 20% less when paired with a home and auto bundle. This integration provides extra liability protection for lawsuits or judgments exceeding primary policy limits.
- Discount stacking: Bundles often stack with other discounts, such as multi-car, claims-free, or security system discounts. A homeowner with a monitored alarm system and two insured vehicles could see discounts compound, reducing premiums by up to 40%. Always confirm with the insurer which discounts are eligible for stacking.
3. Provider Comparison Framework
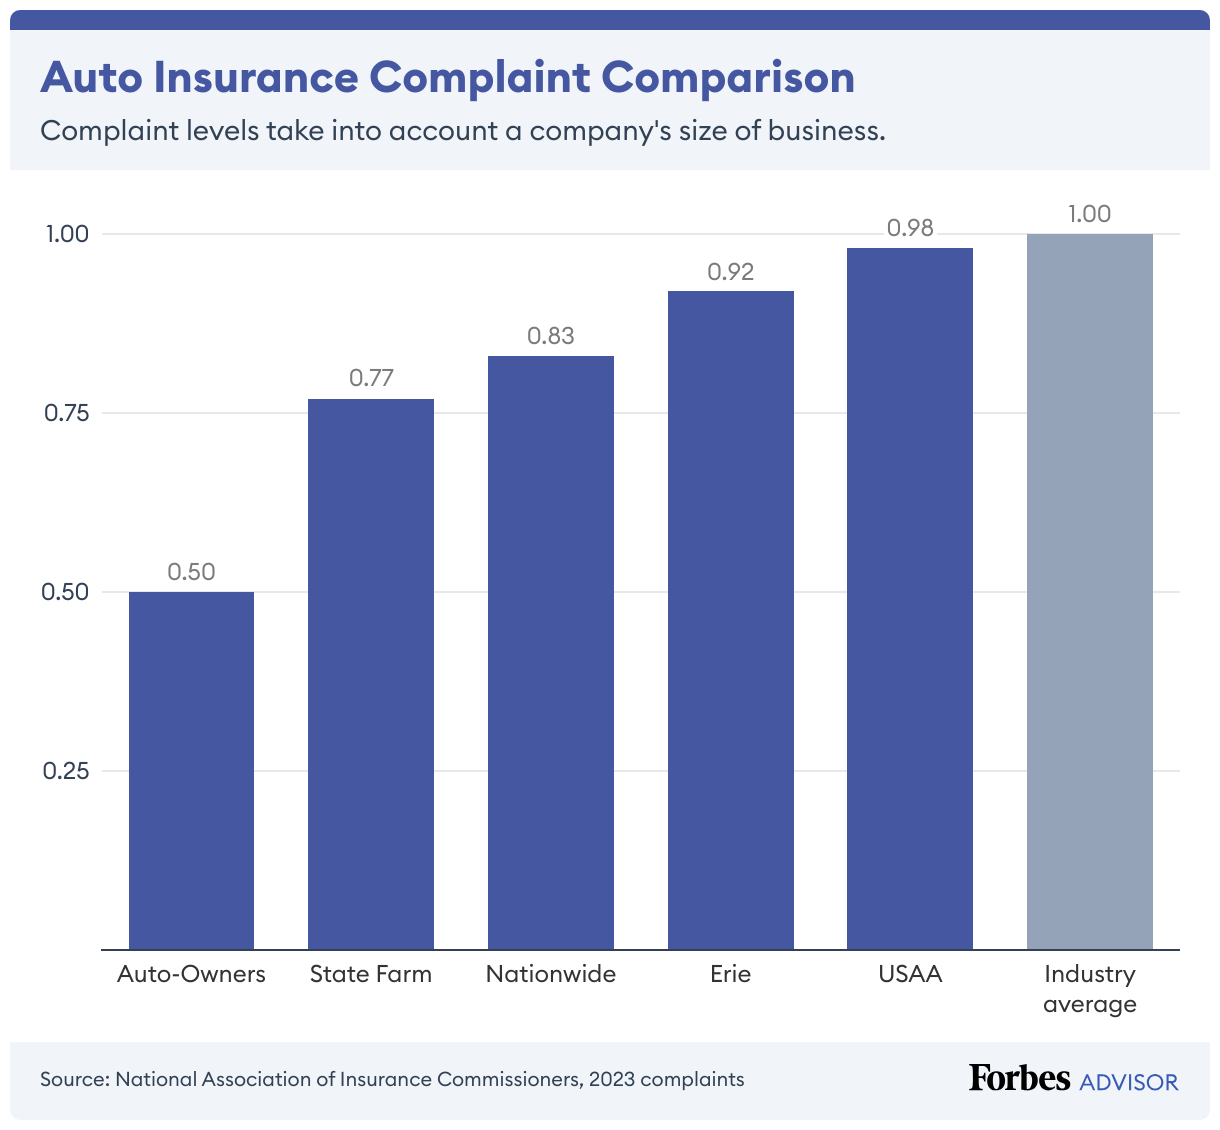
Not all insurers treat bundles equally. Major providers like Geico, USAA, and Nationwide offer competitive bundled rates, but their approaches differ. Geico, for example, emphasizes low base rates with modest bundled discounts (5–10%), while USAA—restricted to military families—provides deeper discounts (15–25%) due to its niche customer base. Nationwide’s SmartRide and SmartHome programs dynamically adjust rates based on driving habits and home safety features, making their bundles more customizable.
Independent agents can also access exclusive bundled deals from multiple carriers, offering flexibility unavailable through direct providers. For instance, an agent might match a client’s high-risk auto profile with a home insurer offering lenient underwriting. Comparing providers requires evaluating not just discounts but also claims service reputation, local availability, and digital tools. Tools like the Insurance Information Institute’s provider comparison guides can help narrow options.

4. Common Mistakes to Avoid
Overlooking coverage gaps is a frequent error. Bundling can create blind spots if policies don’t align—for example, excluding flood or earthquake coverage in a high-risk area. A homeowner in Florida bundling with a provider that doesn’t offer hurricane deductibles might face unexpected out-of-pocket costs. Always review exclusions in both policies to ensure comprehensive protection.
Another mistake is assuming all discounts apply automatically. Some insurers require proactive steps, such as installing a smart home device or enrolling in telematics for auto policies. A driver might miss a 5% discount if they don’t complete a defensive driving course or install a dash cam. Reading the fine print and confirming eligibility criteria with the insurer is critical.
5. Claims Process Simplification
Bundling streamlines claims by centralizing communication and documentation. A single insurer handles both auto and home claims, reducing paperwork and coordination efforts. For example, after a tree falls on a car and damages the garage, a bundled policyholder files one claim instead of two, with the insurer assessing both damages under the same policy terms. This efficiency is particularly valuable during disasters, where insurers prioritize bundled claims for faster processing.
However, bundling doesn’t eliminate the need for thorough documentation. Policyholders must still gather evidence (photos, police reports, repair estimates) for each claim. Some insurers offer mobile apps to expedite this process, but users must ensure consistency between auto and home claims to avoid delays. Real-world data from J.D. Power shows bundled claims are resolved 20% faster on average than separate policies.
6. Tax and Legal Implications
Bundled policies may affect tax deductions and legal liability. In some states, home insurance premiums are deductible on federal taxes if itemizing, but auto insurance is not. However, bundling doesn’t change this rule—tax benefits depend on individual circumstances. Consulting a tax advisor can clarify deductions, especially for self-employed individuals or those with rental properties.
Legally, bundled policies can impact liability in shared incidents. For instance, if a delivery driver’s bundled policy covers their vehicle and a rented storage unit, liability for a collision involving both assets is handled under the same terms. This consolidation reduces legal complexity but requires verifying that both policies’ liability limits are adequate for combined risks.
7. When to Reevaluate Your Bundle
Life changes—marriage, moving, or buying a new car—can render a bundled policy outdated. For example, a home purchase in a new state might require switching insurers due to coverage limitations, or a divorce could split assets, making separate policies more practical. Reevaluating annually or after major life events ensures the bundle remains cost-effective and comprehensive.
Insurers also adjust rates periodically. A policyholder who once received a 20% bundle discount might see it drop to 10% if their risk profile changes. Shopping around every 2–3 years can uncover better bundled rates. Tools like the National Association of Insurance Commissioners’ rate comparison database help identify competitive offers.
8. Future Trends in Bundling
Emerging trends like usage-based insurance (UBI) and smart home integration are reshaping bundles. UBI programs, such as Progressive’s Snapshot or Allstate’s Drivewise, adjust auto premiums based on driving behavior, which can further reduce bundled costs for safe drivers. Similarly, smart home devices (e.g., leak detectors, smart locks) may qualify for deeper discounts when paired with auto policies, creating dynamic bundles that adapt to real-time data.
Insurtech innovations are also enabling hyper-personalized bundles. Companies like Lemonade and Hippo use AI to tailor coverage and pricing based on individual risk factors, such as commute patterns or home square footage. These trends suggest that future bundles will offer even greater customization and savings, provided consumers stay informed about evolving options.
10 Actionable Tips for Optimizing Your Auto Home Insurance Bundle
Maximizing the benefits of an auto home insurance bundle requires proactive steps. Here’s how to ensure the best coverage and savings.
Tip 1: Shop during open enrollment periods. Insurers often introduce limited-time bundle discounts (e.g., 15% off for 6 months) during open enrollment or holiday seasons. Setting reminders for these periods can unlock additional savings.
Tip 2: Request a bundle quote before committing to separate policies. Many insurers offer bundled discounts even if you’re new to their services. Comparing bundled quotes upfront avoids the hassle of switching later.
Tip 3: Bundle with an insurer that offers umbrella policies. Umbrella policies provide extra liability coverage and are often discounted when bundled. This is ideal for high-net-worth individuals or those with significant assets.
Tip 4: Install smart home and vehicle safety devices. Devices like smart thermostats, leak detectors, or telematics (e.g., Progressive’s Snapshot) can qualify for additional discounts when bundled. These upgrades may also improve coverage terms.
Tip 5: Review and update coverage annually. Life changes—such as buying a new car, renovating a home, or adding a driver—can affect bundled rates. Annual reviews ensure coverage matches current needs and maximizes discounts.
Tip 6: Ask about multi-policy loyalty discounts. Some insurers reward long-term customers with deeper bundle discounts after 3–5 years. Inquiring about loyalty programs can reveal hidden savings.
Tip 7: Compare bundled rates across at least 3 providers. Discounts vary widely. Using tools like III’s comparison guides ensures you’re not leaving money on the table.
Tip 8: Check for stackable discounts. Bundles often combine with other discounts (e.g., claims-free, multi-car). Confirm with your insurer which discounts are eligible for stacking to maximize savings.
Tip 9: Use an independent agent for access to exclusive bundles. Agents can negotiate rates across multiple carriers, sometimes securing better bundled deals than direct providers. This is especially useful for complex or high-value policies.
Tip 10: Document all policy details and discounts. Keep records of bundled discounts, coverage limits, and exclusions. This simplifies claims and ensures you can justify rates during annual reviews or disputes.
Conclusion
An auto home insurance bundle offers a strategic way to reduce costs, simplify management, and enhance coverage. Key aspects include understanding pricing dynamics, customizing policies to fit individual needs, and avoiding common pitfalls like overlooked exclusions or missed discounts. Provider comparisons, claims efficiency, and tax implications further shape the bundled experience, while emerging trends like UBI and smart home integration promise even greater personalization.
As insurance markets evolve, staying informed about bundled options and life changes will ensure policyholders continue to benefit from this practical approach. Regular evaluations and proactive steps—such as leveraging smart devices or consulting independent agents—will keep bundles aligned with both financial and protective goals.