9 Key Insights into Auto and Home Insurance Bundles
Table of Contents
- 1. How Bundling Works: Mechanics and Savings
- 2. Financial Benefits: Discounts and Long-Term Value
- 3. Provider Comparisons: Top Insurers for Bundles
- 4. Common Mistakes to Avoid
- 5. When to Bundle: Ideal Scenarios
- 6. Negotiation Tips for Better Rates
- 7. Claims and Coverage: What Changes with Bundling?
- 8. Alternatives: When Not to Bundle
- Frequently Asked Questions
- 9 Actionable Tips for Maximizing Bundle Savings
- Conclusion
A **auto and home insurance bundle** combines liability, property, and vehicle coverage under a single policy or provider, creating a unified protection plan. For example, a family insuring a 2020 Honda Accord and a suburban home through Progressive’s *Home & Auto* package consolidates premiums while maintaining separate deductibles and claim processes. This approach is not new—insurers have long leveraged bundling to streamline risk assessment and customer management—but its modern relevance lies in cost efficiency and convenience.
The primary benefits of an **auto and home insurance bundle** include lower premiums (often 10–25% less than separate policies), simplified billing, and dedicated customer service. Historically, insurers offered discounts for bundling as early as the 1980s, but today’s digital tools—like online portals and AI-driven risk models—enhance personalization. For homeowners or drivers with multiple assets, bundling reduces administrative hassle while maintaining comprehensive coverage.
This article explores the mechanics, financial advantages, and practical considerations of **auto and home insurance bundles**, from provider comparisons to common pitfalls. Insights include how bundling affects claims, which insurers offer the best deals, and how to negotiate terms for optimal savings.
1. How Bundling Works: Mechanics and Savings
An **auto and home insurance bundle** operates by bundling policies under one insurer, which then applies a multi-policy discount. For instance, State Farm’s *Auto & Home* discount can cut premiums by up to 20% for bundling both coverages. The insurer’s risk assessment improves with consolidated data—e.g., a claim-free homeowner with a clean driving record may qualify for deeper discounts than separate policyholders.
Key mechanics include shared deductibles (sometimes), unified billing cycles, and streamlined claims filing. However, coverage limits and exclusions remain policy-specific. A bundled policy might still require separate deductibles for auto collisions and home damage, but the administrative overhead is reduced.
2. Financial Benefits: Discounts and Long-Term Value
- Multi-Policy Discounts: Insurers like Allstate and Farmers offer 10–25% savings for bundling. A 2022 study by the Insurance Information Institute found that bundling auto and home policies saved policyholders an average of $300 annually.
- Loyalty Rewards: Providers such as USAA and Nationwide reward long-term customers with additional discounts (e.g., 5% after 5 years). A military family with USAA might save $500/year by bundling after 3 years of continuous coverage.
- Lower Administrative Costs: Bundled policies reduce insurer overhead, which can translate to lower premiums. For example, a policyholder with separate insurers for auto and home may face higher fees for duplicate paperwork and claims processing.
Over time, these savings compound. A homeowner paying $1,200/year for separate policies could reduce that to $900 with a bundle, freeing up funds for higher coverage limits or additional protections like identity theft coverage.
3. Provider Comparisons: Top Insurers for Bundles
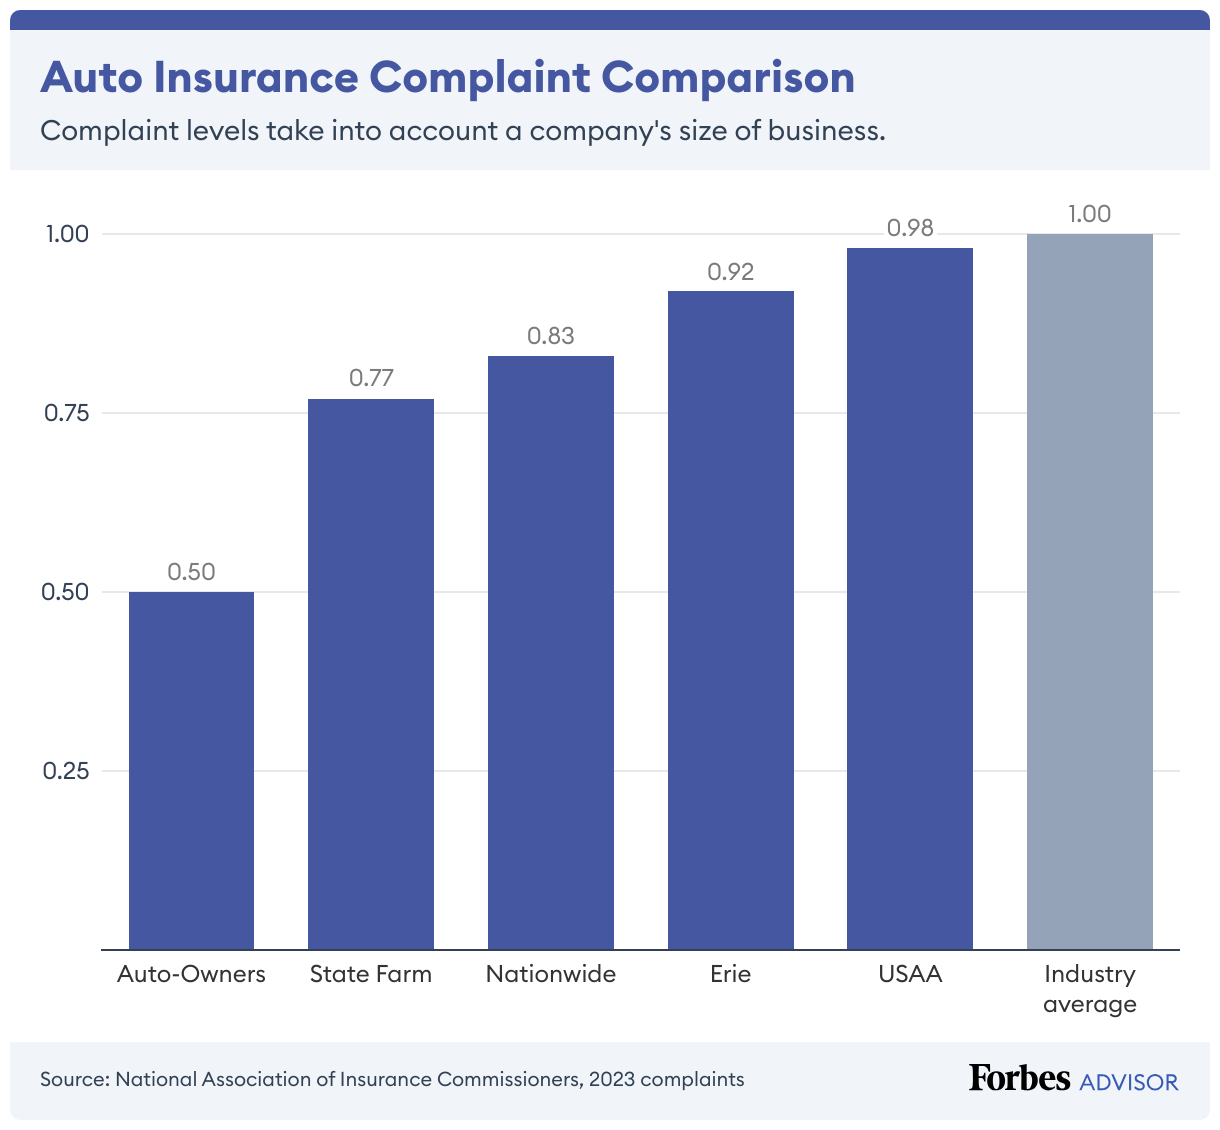
Not all insurers treat **auto and home insurance bundles** equally. State Farm and Progressive lead in bundling popularity, offering discounts up to 25% and user-friendly digital tools. Geico’s *Homeowners & Auto* bundle is notable for its competitive pricing, while regional providers like Erie Insurance (with a 20% bundle discount) excel in customer service.
Comparison criteria include:
- Discount Depth: State Farm’s average bundle discount is 18%, while Geico’s is 15%. Always compare apples-to-apples—some insurers exclude certain coverages (e.g., flood insurance) from discounts.
- Coverage Flexibility: USAA allows customizable bundles with optional riders (e.g., equipment coverage for tools). This is critical for high-value assets like jewelry or collectibles.
- Claims Efficiency: Progressive’s *Snapshot* program integrates auto and home claims data, potentially accelerating payouts for bundled policyholders.
For example, a California homeowner with a high-risk auto history might find better rates with Farmers Insurance, which offers tailored bundle discounts for drivers in certain ZIP codes.
4. Common Mistakes to Avoid
Missteps in bundling can negate savings or leave gaps in coverage. Overlooking **auto and home insurance bundle** terms—such as separate deductibles or excluded perils—is a frequent error. For instance, a policyholder might assume a bundled flood policy covers both home and vehicle, only to discover the auto portion is excluded.
Other pitfalls include:
- Ignoring Policy Limits: Bundling doesn’t automatically increase coverage limits. A homeowner with $300K dwelling coverage might assume their auto policy’s $100K liability limit applies to both, risking underinsurance in a lawsuit.
- Skipping Provider Reviews: Not all insurers honor bundle discounts for high-risk drivers or properties. A driver with a DUI might find their bundle discount reduced or revoked.
- Assuming One Claim Affects Both Policies: Filing an auto claim won’t trigger a home insurance rate hike, but bundling with the same provider may lead to higher premiums for both policies if claims frequency increases.
Proactive steps—such as reviewing policy declarations pages and comparing quotes annually—mitigate these risks.
5. When to Bundle: Ideal Scenarios
Bundling is most advantageous for individuals with multiple high-value assets or stable risk profiles. Families with a mortgage, a car loan, and no recent claims are prime candidates. For example, a suburban couple with a $400K home and a leased SUV could save $600/year by bundling through Allstate compared to separate policies.
Other ideal scenarios include:
- New Homeowners: First-time buyers often qualify for larger bundle discounts (e.g., 20% from Liberty Mutual) as they lack a claims history.
- Young Drivers with Parents’ Policies: Adding a teen driver to a parent’s bundled policy may cost less than a standalone auto policy, even with higher premiums.
- High-Net-Worth Individuals: Those with valuable assets (e.g., art, boats) can bundle umbrella policies for broader liability coverage at a reduced cost.
Conversely, renters or drivers with poor credit may find limited savings, as insurers weigh risk factors differently for bundles.
6. Negotiation Tips for Better Rates
Insurers often adjust bundle discounts based on negotiation. Policyholders can leverage loyalty, claims history, and competing offers to secure better terms. For example, a customer with 10 years of claims-free coverage might negotiate a 25% discount from their current provider by citing a competitor’s 20% offer.
Key negotiation tactics include:
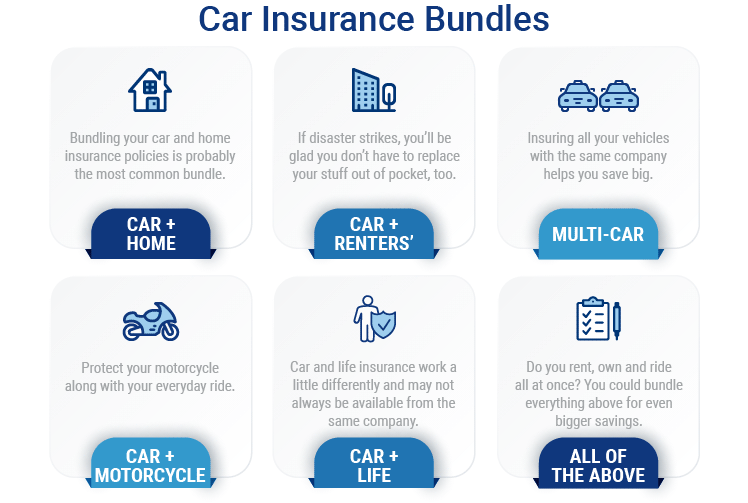
- Highlighting Long-Term Relationships: A 5-year customer with no claims could request a loyalty bonus, as insurers prioritize retention. Bundling Additional Policies: Adding renters, umbrella, or life insurance to an auto-home bundle can unlock further discounts (e.g., 5% from Nationwide).
- Comparing Quotes Annually: Rates fluctuate; a policyholder who hasn’t shopped in 2 years might save 10% by switching or renegotiating.
Documenting all interactions and quotes strengthens leverage. A written request for a discount—citing a competitor’s lower bundle rate—often yields results.
7. Claims and Coverage: What Changes with Bundling?
Bundling simplifies claims but doesn’t alter coverage fundamentals. For example, a hailstorm damaging a car and roof would require separate claims under a bundled policy, but the insurer’s claims adjuster might prioritize efficiency. However, some providers—like Progressive—offer combined deductibles for bundled policies, reducing out-of-pocket costs.
Critical considerations include:
- Deductible Structures: Bundled policies may allow a single deductible for related claims (e.g., a tree falling on a car and garage). Always confirm this in the policy.
- Claim Impact on Premiums: Filing an auto claim could raise home insurance rates if bundled with the same provider, as insurers view it as increased risk.
- Provider Response Times: Bundled claims may resolve faster due to streamlined processes. State Farm’s bundled policyholders report a 20% quicker claims resolution than non-bundled customers.
Reviewing the insurer’s claims service reputation (e.g., J.D. Power ratings) is essential before bundling.
8. Alternatives: When Not to Bundle
While bundling is often beneficial, certain situations warrant separate policies. High-risk drivers or properties—such as a home in a flood zone or a driver with multiple DUIs—may face higher bundled premiums than standalone rates. For example, a Florida homeowner with a hurricane-prone property might pay less for a separate flood policy than bundling it with auto insurance.
Other scenarios where unbundling makes sense:
- Specialized Coverage Needs: A collector of vintage cars may require an AGO (agreed value) policy, which isn’t compatible with standard auto-home bundles. Provider Limitations: Some insurers exclude certain coverages (e.g., earthquake insurance) from bundle discounts, making separate policies more cost-effective.
- Credit or Risk Profile Mismatches: Poor credit can disproportionately affect home insurance rates, making a separate auto policy more affordable.
Always run a cost-benefit analysis using tools like Policygenius or NerdWallet to compare bundled vs. separate premiums.
9 Actionable Tips for Maximizing Bundle Savings
Optimizing an **auto and home insurance bundle** requires strategy. Follow these steps to secure the best deal.
Tip 1: Compare Bundle Discounts Across Providers. State Farm’s average discount is 18%, while Geico’s is 15%. Use comparison tools like The Zebra to identify the highest savings.
Tip 2: Increase Deductibles to Lower Premiums. Raising deductibles from $500 to $1,000 can reduce auto and home premiums by 15–20%, freeing up funds for higher coverage limits elsewhere.
Tip 3: Bundle Additional Policies. Adding renters, umbrella, or life insurance to an auto-home bundle can unlock extra discounts (e.g., 5% from Nationwide).
Tip 4: Maintain a Claims-Free History. A 5-year claims-free record can boost bundle discounts by 10–15%. Even minor claims (e.g., a fender bender) may offset savings.
Tip 5: Negotiate Based on Loyalty. A 10-year customer with no claims could request a 20% bundle discount by citing competitor offers or referencing long-term loyalty.
Tip 6: Review Coverage Limits Annually. Inflation or home renovations may require higher limits. Adjusting coverage to match asset values prevents underinsurance.
Tip 7: Ask About Usage-Based Discounts. Progressive’s *Snapshot* program tracks driving habits, potentially reducing auto premiums by 30% for safe drivers. Pair this with a home bundle for compounded savings.
Tip 8: Consider Paying Annually. Some insurers (e.g., Erie Insurance) offer a 5% discount for annual payments. Weigh this against interest costs if paying upfront isn’t feasible.
Tip 9: Reassess After Major Life Changes. Moving to a new state, buying a second car, or retiring can alter insurance needs. Update bundles to reflect these changes within 30 days.
Conclusion
An **auto and home insurance bundle** simplifies coverage, reduces costs, and consolidates risk management under one provider. Key takeaways include the financial benefits of multi-policy discounts, the importance of comparing providers and coverage limits, and the necessity of avoiding common pitfalls like overlooked exclusions. Whether bundling saves money depends on individual risk profiles, but for most policyholders, the convenience and savings make it a strategic choice.
As insurance markets evolve with technology and climate risks, staying informed about bundle options—and negotiating proactively—will remain essential for long-term financial protection.

