9 Key Insights into Allstate Insurance Online Quote
Table of Contents
- 1. How an Allstate Online Quote Works
- 2. Key Factors Affecting Your Quote
- 3. Eligibility Requirements for Online Quotes
- 4. Common Mistakes to Avoid
- 5. How to Get the Best Allstate Quote
- 6. Understanding Quote vs. Policy Binding
- 7. Allstate’s Online Tools and Resources
- 8. When to Contact an Agent Instead
- Frequently Asked Questions
- 9 Proven Tips for a Faster, Cheaper Quote
- Conclusion
An **Allstate insurance online quote** refers to the digital process of estimating premiums for auto, home, renters, or other policies through Allstate’s website or mobile app. For example, a driver in Chicago requesting a quote for full coverage on a 2018 Honda Civic with a clean record might receive a preliminary estimate in under two minutes—complete with optional add-ons like roadside assistance or accident forgiveness. This system eliminates paperwork, reduces wait times, and provides transparency into factors like deductibles, discounts, and coverage limits.
The importance of an **Allstate insurance online quote** lies in its accessibility and efficiency. Traditional methods required in-person appointments or phone calls, which could take hours and lacked real-time adjustments. Today, the online quote system allows users to compare policies instantly, adjust parameters (e.g., liability limits or safety features), and even bundle auto and home insurance for potential savings. Historically, insurance shopping was a cumbersome process; now, technology has democratized access, empowering consumers to make informed decisions without agent dependency.
This article explores the mechanics, benefits, and nuances of obtaining an **Allstate insurance online quote**. It covers eligibility criteria, how pricing works, common pitfalls, and strategies to maximize discounts. Whether the goal is securing a policy, understanding coverage gaps, or leveraging loyalty programs, these insights ensure a smoother experience.
1. How an Allstate Online Quote Works
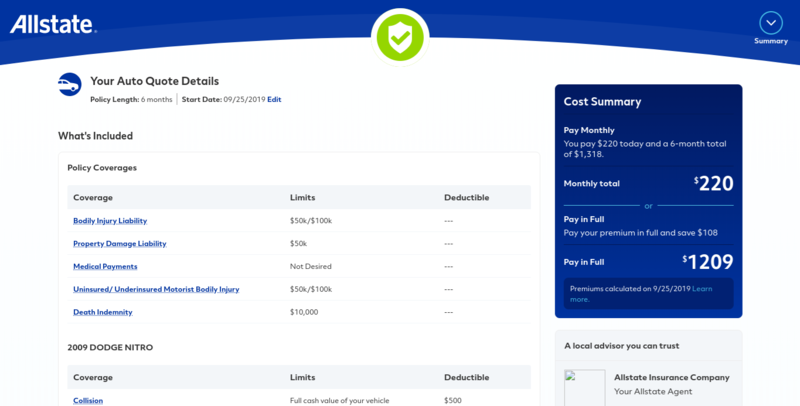
The process begins with selecting the policy type (auto, home, etc.) on Allstate’s website or app. Users input details like vehicle year/make, driving history, or home square footage. The system then generates a preliminary quote based on algorithms that weigh risk factors such as location, credit score (where permitted), and claims history.
For instance, a homeowner in Florida might see higher premiums due to hurricane risk, while a driver in a low-theft urban area could qualify for lower rates. The quote also highlights potential discounts—such as safe driver, multi-policy, or new home alerts—and allows users to customize deductibles or coverage tiers. This transparency ensures no surprises during policy purchase.
2. Key Factors Affecting Your Quote
- Location and ZIP Code
Premiums vary significantly by region due to local crime rates, weather risks, and traffic density. A quote in Miami may include higher windstorm coverage costs, while one in Des Moines might reflect lower auto theft statistics. Allstate’s system pulls data from federal and state sources to adjust rates accordingly.
- Vehicle Model and Safety Ratings
Cars with advanced safety features (e.g., automatic braking, lane-keep assist) often qualify for discounts. A 2022 Toyota Camry with top safety scores could receive a 5–10% reduction, whereas a sports car might see higher premiums. Allstate’s database cross-references models with crash test data and theft rates.
- Driving Record and Claims History
Tickets, accidents, or prior claims elevate risk profiles. A driver with a single at-fault accident in the past three years might pay 20–30% more than someone with a clean record. Allstate’s system flags these red flags but also offers accident forgiveness programs for long-term customers.
- Coverage Limits and Deductibles
Choosing higher liability limits or lower deductibles increases premiums but expands protection. For example, raising the bodily injury limit from $25K to $100K per person might add $10–$20/month but provide critical coverage in severe accidents.
- Credit Score (Where Applicable)
In most states, credit history influences auto insurance rates. A score above 700 could yield a 10–15% discount, while scores below 600 may result in higher quotes. Allstate’s underwriting models correlate creditworthiness with claim frequency, though this practice is banned in states like California.
3. Eligibility Requirements for Online Quotes
Not all users qualify for an instant **Allstate insurance online quote**. Auto policies typically require a valid driver’s license, vehicle registration, and proof of residency. Home insurance may demand ownership documents or rental agreements. Commercial policies often necessitate business licenses or loss histories.
For example, a college student using their parents’ policy might need their parent’s policy number to access a quote, while a first-time homebuyer could face additional verification steps. Allstate’s system flags incomplete applications and prompts users to contact an agent for clarification, ensuring compliance with state regulations.
4. Common Mistakes to Avoid
- Skipping the Discount Checklist
Users often overlook discounts like bundling, paperless billing, or anti-theft device installations. A policyholder with both auto and home insurance through Allstate could save 20–25% by combining them, yet many fail to select this option during the quote process.
- Entering Incorrect Vehicle Details
Mismatched VINs or incorrect model years can lead to inaccurate quotes. For instance, reporting a 2019 SUV as a 2020 model might trigger higher premiums based on newer vehicle data. Allstate’s system cross-checks with DMV records to minimize errors.
- Ignoring Usage-Based Programs
Programs like Allstate’s Drivewise (for auto) or HomeWatch (for home) offer discounts for safe behaviors or home monitoring. A driver who enrolls in Drivewise could reduce premiums by 10–30% if they maintain low mileage or avoid hard braking, yet many never explore these options.
- Assuming the First Quote Is Final
Online quotes are estimates. Final rates may differ after underwriting reviews claims history or credit updates. Users should compare multiple scenarios (e.g., higher deductibles) to find the best balance between cost and coverage.
5. How to Get the Best Allstate Quote
Strategies to optimize an **Allstate insurance online quote** include leveraging loyalty programs, such as the Allstate Better Car ID app, which rewards safe driving with discounts. Bundling policies or paying annually (instead of monthly) can also reduce costs. Additionally, users should request quotes from multiple providers—including Allstate’s competitors—to benchmark rates.
For example, a policyholder in Texas might find that State Farm offers a 15% discount for military service, while Allstate provides a 10% reduction for completing a defensive driving course. Comparing these incentives ensures the most competitive pricing. Allstate’s website also features a “Compare Rates” tool that pits their quotes against others in real time.
6. Understanding Quote vs. Policy Binding
An **Allstate insurance online quote** is not a binding contract. It serves as an estimate that expires after 15–30 days unless the user proceeds to purchase. During this window, factors like a new traffic ticket or home renovation could alter the final premium. Users must submit additional documentation (e.g., proof of insurance for a new driver) to bind the policy.
For instance, a quote for a $500 deductible might convert to a $600 deductible if the insured adds a teenage driver after the initial estimate. Allstate’s system alerts users to such changes before finalizing the purchase, ensuring transparency.
7. Allstate’s Online Tools and Resources
Beyond the basic quote, Allstate offers tools like the **Allstate Mobile App**, which allows users to file claims, pay bills, and receive instant quotes on the go. The **Allstate Agent Finder** connects users with local agents for complex needs, such as classic car insurance or high-value home policies. Additionally, the **Allstate Learning Center** provides guides on topics like gap insurance or umbrella policies, helping users refine their coverage.
For example, a user researching gap insurance for a leased vehicle can access a side-by-side comparison tool within the app, showing how adding this coverage affects their monthly premium. These resources reduce reliance on generic advice and empower users to tailor policies to their needs.
8. When to Contact an Agent Instead
While **Allstate insurance online quotes** handle straightforward cases, certain scenarios require human expertise. Complex claims, such as total loss disputes or liability lawsuits, benefit from an agent’s negotiation skills. Similarly, business owners or high-net-worth individuals may need specialized endorsements (e.g., flood insurance or jewelry coverage) that aren’t available online.
For instance, a homeowner with a vintage wine collection worth $50,000 would need an agent to add a scheduled personal property endorsement—something the online system cannot process. Allstate’s website directs users to contact an agent for these cases, ensuring proper protection.
9 Proven Tips for a Faster, Cheaper Quote
Optimizing an **Allstate insurance online quote** involves preparation and strategic input. These tips streamline the process and improve outcomes.
Tip 1: Gather Documentation First. Have your driver’s license, vehicle details (VIN, year), and policy numbers (if transferring) ready. This reduces errors and speeds up the quote.
Tip 2: Use the Same Device for Multiple Quotes. Cookies on your browser may store preferences (e.g., coverage types) that carry over, ensuring consistency across comparisons.
Tip 3: Select “Compare Rates” Early. Allstate’s tool pits their quote against competitors, helping identify the best deal before committing to a provider.
Tip 4: Opt for Paperless Billing. Enrolling in e-billing during the quote process can unlock a 1–2% discount on premiums.
Tip 5: Check for Usage-Based Discounts. Programs like Drivewise or HomeWatch may offer savings if you’re open to monitoring or safe-driving incentives.
Tip 6: Avoid Customizing Too Soon. Enter basic details first, then adjust coverage or deductibles after reviewing the initial quote to see the full impact on cost.
Tip 7: Request a Quote During Off-Peak Hours. Allstate’s servers may experience slower response times during high-traffic periods (e.g., weekends). Early mornings or weekdays often yield faster processing.
Tip 8: Use Allstate’s Mobile App for Quick Updates. If your circumstances change (e.g., new address), updating via the app can refresh your quote without restarting the process.
Tip 9: Save Your Quote Reference Number. This 8–10 digit code allows you to resume the process later, even if you close the browser. Keep it handy to avoid re-entering details.
Conclusion
An **Allstate insurance online quote** simplifies the insurance shopping experience by providing instant, customizable estimates tailored to individual needs. Key aspects include understanding how location, vehicle, and personal history influence pricing, avoiding common mistakes like missed discounts or incorrect details, and knowing when to seek agent assistance for complex scenarios. Tools like the Allstate app and comparison features further enhance transparency and control.
As technology evolves, online quotes will continue to offer deeper personalization and faster processing. Staying informed about these advancements ensures consumers can secure the most competitive and comprehensive coverage available.
Related articles
8 Ways to Get the Best Allstate Quote Car Insurance in 2024
Discover how to secure the most competitive **Allstate quote car insurance** with expert tips on pricing, discounts, and coverage. Start saving…

17+ Ways to Find the Best Allstate Insurance Company Near Me
Discover how to locate the top-rated Allstate insurance company near you, compare policies, and secure the best coverage—plus expert tips to avoid common…
16+ Essential Facts About Allstate Car Insurance Quote You Need to Know
Get an Allstate car insurance quote fast—compare rates, coverage, and discounts. Learn how to save money and avoid costly mistakes with expert insights.
