16+ Essential Facts About Allstate Car Insurance Quote You Need to Know
Table of Contents
- 1. How Allstate Car Insurance Quote Pricing Works
- 2. Key Factors That Influence Your Allstate Quote
- 3. Step-by-Step Guide to Getting an Allstate Quote
- 4. Allstate Discounts That Can Lower Your Quote
- 5. Comparing Allstate Quotes to Competitors
- 6. Common Mistakes When Requesting an Allstate Quote
- 7. How to Negotiate a Better Allstate Car Insurance Quote
- 8. Allstate Quote Tools and Resources
- Frequently Asked Questions
- 16 Tips to Optimize Your Allstate Car Insurance Quote
- Conclusion
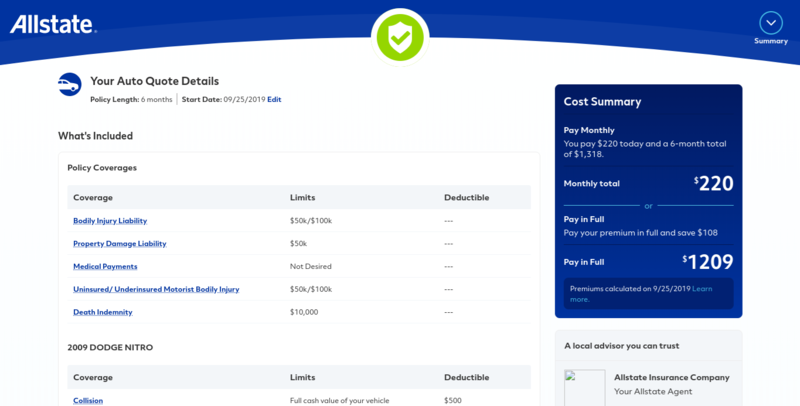
An **Allstate car insurance quote** is a personalized estimate of premium costs, coverage options, and potential discounts for auto insurance provided by Allstate, one of the largest insurers in the U.S. For example, a 35-year-old driver in Chicago with a clean record and a 2020 Honda Civic might receive a quote ranging from **$1,200 to $1,800 annually**, depending on factors like deductible choice, liability limits, and usage-based discounts. These quotes serve as the foundation for securing affordable, tailored auto insurance, balancing protection with financial feasibility.
The importance of an **Allstate car insurance quote** lies in its ability to demystify the complex world of auto insurance pricing. Without it, drivers risk overpaying for coverage or underinsuring themselves—both of which can lead to financial strain after an accident. Historically, insurers like Allstate have leveraged data analytics and telematics to refine quote accuracy, ensuring drivers pay for the risks they actually pose. Today, obtaining a quote is simpler than ever, with online tools and mobile apps streamlining the process while maintaining transparency.
This guide explores the key aspects of securing an **Allstate car insurance quote**, from understanding pricing dynamics to leveraging discounts and avoiding common pitfalls. Whether comparing quotes, optimizing coverage, or navigating the claims process, the insights here ensure a well-informed approach to auto insurance.
1. How Allstate Car Insurance Quote Pricing Works
Allstate’s pricing model for car insurance quotes is driven by a mix of actuarial data, real-time risk assessment, and proprietary algorithms. Unlike traditional insurers that rely solely on credit scores or driving history, Allstate incorporates **usage-based data** (e.g., mileage, braking habits) through programs like **Allstate’s Drivewise**. This dynamic pricing ensures quotes reflect individual risk profiles more accurately than static models.
For instance, a driver in a high-theft urban area may see a higher quote for comprehensive coverage, while a suburban commuter with a short daily commute might qualify for lower collision premiums. Allstate’s **Personal Auto Policy** also adjusts quotes based on vehicle type—luxury cars or modified vehicles typically incur higher quotes due to repair costs. Understanding these factors helps drivers anticipate quote ranges and negotiate better terms.
2. Key Factors That Influence Your Allstate Quote
- Driving Record: A single at-fault accident can increase a quote by **30–50%** for 3–5 years. Allstate’s quote system penalizes severe violations (e.g., DUI) more heavily than minor infractions like speeding tickets. For example, a driver with a recent DUI in Texas might see a quote jump from **$1,500 to $3,500** annually.
- Vehicle Make and Model: Safety ratings and repair costs directly impact quotes. A 2023 Toyota Camry with top safety scores may yield a **20% cheaper quote** than a similarly priced Jeep Wrangler, due to lower claim payouts for the Camry.
- Coverage Limits and Deductibles: Opting for higher deductibles (e.g., $1,000 instead of $500) can lower quotes by **15–25%**, but increases out-of-pocket risk. Allstate’s quote tool highlights how deductible changes affect premiums, helping drivers balance affordability and protection.
- Location and Commute: Urban drivers face higher quotes due to traffic risks, while rural drivers may pay more for limited emergency services. Allstate’s quote system cross-references ZIP codes with local accident statistics to tailor rates.
- Credit History: In most states, Allstate uses credit-based insurance scores to adjust quotes. A poor credit score can inflate a quote by **10–30%**, as statistical data links creditworthiness to claim frequency.
3. Step-by-Step Guide to Getting an Allstate Quote
Obtaining an **Allstate car insurance quote** begins with gathering essential details: driver’s license number, vehicle identification number (VIN), annual mileage, and coverage preferences. The process can be completed in **under 10 minutes** online via Allstate’s website or mobile app. Start by entering the VIN to pull vehicle details automatically, then select coverage types (liability, collision, comprehensive) and limits. Allstate’s quote tool will generate an initial estimate, which can be refined by adjusting deductibles or adding optional coverages like roadside assistance.
For a more precise quote, drivers can opt for a **customized consultation** with an Allstate agent. This step is crucial for complex scenarios, such as insuring a classic car or bundling with homeowners insurance. Agents can also explain how discounts—like **Allstate’s Safe Driving Bonus** or **Early Bird Discount**—apply to the quote. Saving the quote for comparison later ensures transparency when reviewing options.

4. Allstate Discounts That Can Lower Your Quote
- Bundling Policies: Combining auto with home or renters insurance can reduce a quote by **10–25%**. For example, a family paying **$2,000 for auto insurance** might see their quote drop to **$1,500** by adding a homeowners policy, thanks to Allstate’s **Multi-Policy Discount**.
- Usage-Based Programs: Enrolling in **Drivewise** can yield discounts of **10–30%** for safe driving habits. Data from the program shows drivers who maintain smooth acceleration and avoid hard braking often qualify for the highest savings.
- New Car Discount: Purchasing a new vehicle through an Allstate-partnered dealer may unlock a **10% discount** on the initial quote. This incentive encourages policyholders to bundle purchases with insurance.
- Student Discounts: Full-time students with a **B average or higher** can receive a **25% discount** on their quote. Allstate verifies grades annually to maintain the discount, ensuring it’s reserved for responsible drivers.
- Anti-Theft Device Discount: Installing an approved anti-theft system (e.g., OnStar, LoJack) can lower a quote by **5–15%**. Allstate’s quote tool prompts drivers to input such devices during the application process.
5. Comparing Allstate Quotes to Competitors
Allstate’s quotes often compete favorably with rivals like **State Farm, Progressive, and Geico**, but direct comparisons reveal nuanced differences. For instance, Progressive’s **Name Your Price** tool may offer lower initial quotes for high-risk drivers, while Allstate’s **Better Car Insurance** program emphasizes long-term loyalty discounts. A side-by-side comparison of quotes for a 40-year-old driver in Florida might show Allstate at **$1,600/year**, Progressive at **$1,500**, and Geico at **$1,700**, but Allstate’s superior claims service can justify the slight premium difference.
Independent agencies like **The Zebra** or **NerdWallet** aggregate quotes from multiple insurers, including Allstate, to provide benchmark data. These tools highlight where Allstate excels—such as in **customer service ratings**—and where it lags, like in **telematics program flexibility**. Drivers should weigh quote affordability against insurer reputation and additional perks, such as Allstate’s **24/7 claims support** or **Accident Forgiveness** for first-time offenders.
6. Common Mistakes When Requesting an Allstate Quote
One frequent error is providing outdated or inaccurate information during the quote process, such as an incorrect annual mileage or an expired driver’s license status. Allstate’s systems flag inconsistencies, which can delay approval or invalidate discounts. For example, a driver who underreports mileage by **1,000 miles/year** might receive a quote based on lower risk, only to face penalties if audited later. Another mistake is ignoring optional coverages, like **uninsured motorist protection**, which can leave drivers vulnerable in states with lax insurance laws.
Overlooking the **policy renewal date** is another pitfall. Allstate’s quotes are valid for **30–60 days**, and missing the window to finalize coverage can result in lapses. Additionally, drivers often forget to ask about **usage-based discounts** during the initial quote phase, missing out on potential savings. Reviewing the quote with an agent or using Allstate’s **policy review tool** can mitigate these oversights.
7. How to Negotiate a Better Allstate Car Insurance Quote
Negotiation tactics for securing a better **Allstate car insurance quote** begin with leveraging competitor quotes. If a rival insurer offers a **15% lower rate**, Allstate may match or beat it to retain the policyholder. Presenting this data during a phone or in-person consultation often prompts agents to adjust deductibles, coverage limits, or apply hidden discounts. For instance, a driver with a **clean record for 5+ years** might negotiate a **5% discount** by highlighting loyalty and safe driving.
Timing also plays a role. Requesting a quote **mid-policy term** (not during renewal) can reveal untapped discounts, such as **Allstate’s Homeowner Discount** if the driver recently purchased a home. Bundling unrelated policies, like a **motorcycle insurance**, can further reduce the quote. Documenting all interactions and quote adjustments ensures transparency and accountability.
8. Allstate Quote Tools and Resources
Allstate offers multiple tools to refine and manage quotes, including the **Allstate Mobile App**, which allows drivers to request quotes, pay premiums, and file claims on-the-go. The app’s **Quote Estimator** provides real-time adjustments when changing coverage levels, making it easier to compare scenarios. For example, a user can see how adding **$1,000 to collision coverage** affects their quote before committing.
The **Allstate Agent Finder** connects drivers with local agents who can provide personalized quote analyses, particularly useful for complex situations like insuring a **commercial vehicle** or navigating a **gap insurance** request. Additionally, Allstate’s **Online Account Center** lets policyholders track quote history, claims status, and discount eligibility, ensuring no opportunities for savings are overlooked.
16 Tips to Optimize Your Allstate Car Insurance Quote
Securing the best **Allstate car insurance quote** requires strategy and attention to detail. These actionable tips ensure maximum savings and coverage.
Tip 1: Gather accurate vehicle details. Enter the exact **VIN** and model year to avoid discrepancies that could inflate the quote.
Tip 2: Request quotes at different times. Prices fluctuate based on demand; requesting quotes on **weekdays** often yields better rates.
Tip 3: Bundle with home or renters insurance. Combining policies can reduce the quote by **10–25%** through Allstate’s **Multi-Policy Discount**.
Tip 4: Enroll in Drivewise for usage-based savings. Safe driving habits can lower the quote by **10–30%** over time.
Tip 5: Ask about all available discounts. Allstate offers over **20 discounts**; agents may overlook some without prompting.
Tip 6: Choose a higher deductible. Increasing the deductible from **$500 to $1,000** can cut the quote by **15–20%**. Ensure emergency funds cover the higher out-of-pocket cost.
Tip 7: Compare quotes from multiple insurers. Use **NerdWallet** or **Policygenius** to benchmark Allstate’s quote against competitors.
Tip 8: Avoid lapses in coverage. Even a **1-day gap** can spike the renewal quote by **20%**. Set reminders for policy renewals.
Tip 9: Install anti-theft devices. Systems like **LoJack** can lower the quote by **5–15%** when verified with Allstate.
Tip 10: Maintain a clean driving record. A single ticket can raise the quote by **20%** for 3 years; defensive driving courses may mitigate increases.
Tip 11: Negotiate with an agent. Present competitor quotes to leverage **5–15% discounts** during renewal.
Tip 12: Opt for paperless billing. Allstate offers a **3% discount** for electronic statements, adding up over time.
Tip 13: Review coverage annually. Life changes (e.g., retirement, new car) may warrant adjusting the quote for better rates.
Tip 14: Use Allstate’s online tools. The **Quote Estimator** and **Policy Review** features help identify untapped savings.
Tip 15: Ask about loyalty discounts. Policyholders with **5+ years** of continuous coverage may qualify for **5–10% savings**.
Tip 16: Check for employer or alumni discounts. Allstate partners with companies and universities to offer exclusive quote reductions.
Conclusion
An **Allstate car insurance quote** is more than a price estimate—it’s a gateway to customized, affordable coverage tailored to individual needs. Understanding the factors that shape quotes, from driving history to vehicle type, empowers drivers to make informed decisions. Leveraging discounts, comparing options, and avoiding common mistakes ensure the best possible outcome, whether securing a new policy or renewing an existing one.
As auto insurance evolves with technology and data-driven insights, staying proactive about quotes will remain key to balancing cost and protection. The next step is to request a personalized **Allstate car insurance quote** and explore the full range of coverage and savings opportunities available.

Related articles
8 Ways to Get the Best Allstate Quote Car Insurance in 2024
Discover how to secure the most competitive **Allstate quote car insurance** with expert tips on pricing, discounts, and coverage. Start saving…
15 Key Insights Into Allstate Insurance Quote Auto: A Comprehensive Guide
Get an Allstate insurance quote auto fast with these expert insights. Learn pricing, coverage, and tips to save money while securing top-rated protection…
9 Key Insights into Allstate Insurance Online Quote
Discover how an Allstate insurance online quote simplifies coverage shopping, cuts costs, and saves time. Learn pricing secrets, eligibility rules, and…
