Getting an insurance quote from Allstate is more than just filling out forms—it’s a structured journey designed to balance speed, accuracy, and customer trust. From the moment users land on Allstate’s platform, they encounter a blend of intuitive design, risk-based calculations, and strategic marketing cues. The process isn’t just about generating numbers; it’s about guiding customers through a personalized experience that adapts to their needs, whether they’re comparing auto policies, securing home coverage, or exploring bundling options. Behind the scenes, actuarial models, regional regulations, and real-time data interactions shape every quote, while front-end optimizations—like dynamic discounts and seamless error handling—keep users engaged. This system reflects Allstate’s dual focus on operational efficiency and customer-centric outcomes, making the quote process both a tool for decision-making and a touchpoint for building long-term relationships.
The quote process at Allstate is built on a foundation of technical precision and user-friendly adaptations. Core features like its online tool, which handles inputs from vehicle details to driving history, set the stage for comparisons with competitors like State Farm or Geico. Meanwhile, the journey isn’t linear; it’s shaped by interactive elements, trust signals (such as ratings and testimonials), and personalized incentives like safe driver discounts. For businesses analyzing insurance workflows or customers seeking transparency, understanding this process reveals how Allstate balances automation with human oversight—from initial data collection to post-submission support. Whether through digital channels, agent assistance, or localized adjustments, the system ensures quotes are not just calculated but communicated effectively.
Primary Steps in Allstate’s Quote Request Process
Requesting a quote from Allstate follows a structured, multi-step workflow designed to balance efficiency with personalized coverage. The process integrates digital convenience with human oversight, ensuring accuracy while minimizing friction. Customers begin with an initial assessment of their needs, proceed through data collection, and conclude with quote customization and finalization—all while maintaining transparency about pricing and policy terms.
The workflow emphasizes automation for speed, with manual reviews reserved for complex scenarios (e.g., high-value assets or claims history). Allstate’s system dynamically adjusts premiums based on real-time inputs, such as vehicle mileage or home construction materials, to reflect accurate risk profiles. This approach contrasts with competitors that may rely on static algorithms or require in-person appointments for premium adjustments.
Step 1: Initial Assessment and Product Selection
Customers initiate the process by identifying the insurance product they require, whether auto, home, renters, or umbrella liability. Allstate’s platform guides users through a series of prompts to narrow down options based on their primary needs. For example, a user selecting auto insurance is prompted to choose between standard liability, comprehensive, or customizable add-ons like roadside assistance or gap coverage.
The platform’s algorithm prioritizes clarity by presenting product categories with icons and brief descriptions (e.g., a shield for liability, a house for homeowners). This visual hierarchy reduces decision fatigue by eliminating irrelevant options early. Unlike competitors like Geico, which often defaults to a single "quote now" button across all products, Allstate’s segmented approach aligns with its brand positioning as a provider of comprehensive solutions rather than a discount-focused insurer.
Step 2: Data Collection and Input Requirements
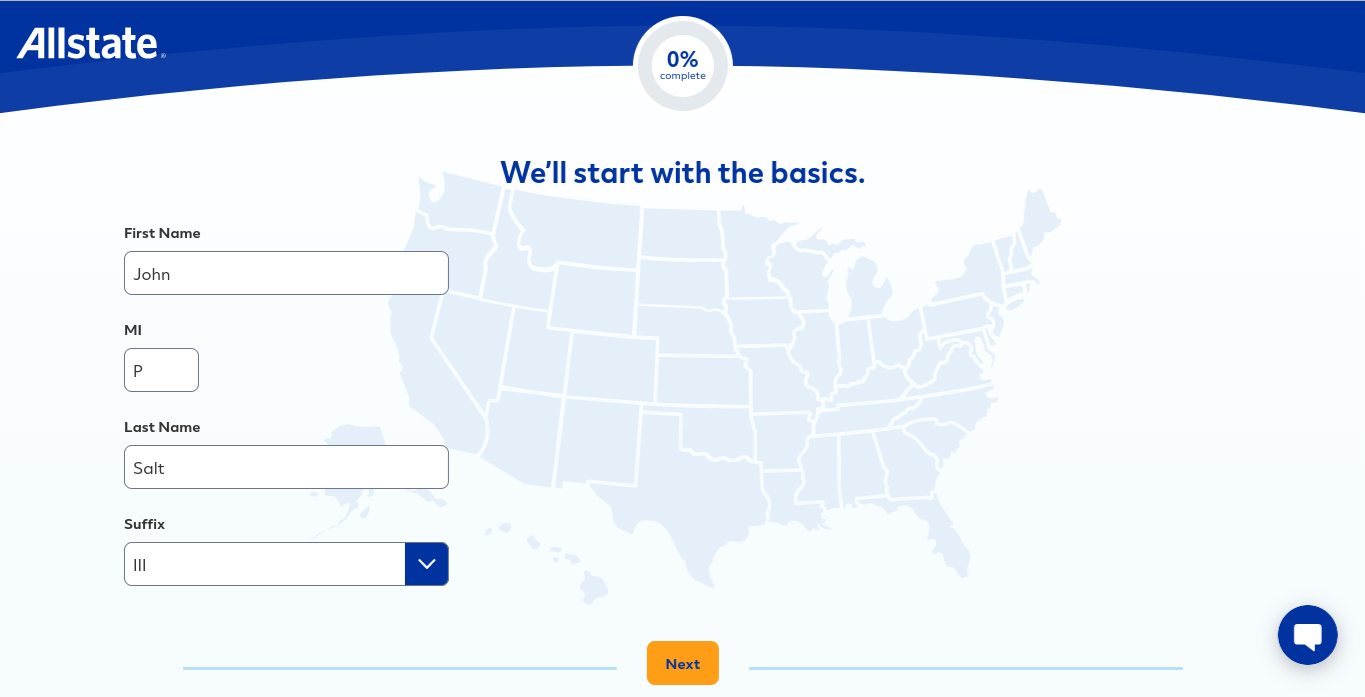
Allstate’s online quote tool requires standardized inputs to calculate premiums, with variations depending on the product type. Core fields include:
- **Personal Information**: Full name, date of birth, and contact details (mandatory for all products).
- **Property/Asset Details**: For auto insurance, this includes vehicle make, model, year, VIN, and usage (e.g., commuting vs. occasional driving). For home insurance, it covers square footage, construction materials, and security systems.
- **Risk Factors**: Driving records (for auto), claims history, and neighborhood crime rates (for property insurance). Allstate’s tool dynamically flags high-risk inputs (e.g., a DUI on a driving record) with explanatory notes and optional risk-mitigation suggestions.
A key differentiator is Allstate’s integration of third-party data sources, such as credit scores (in states where permitted) and telematics for auto policies. This contrasts with State Farm, which relies more heavily on user-provided data and less on predictive analytics. The tool also supports partial submissions, allowing users to save progress and return later—a feature absent in some competitor platforms.
Step 3: Quote Generation and Customization
Once inputs are complete, Allstate’s system generates a preliminary quote within seconds, displaying:
- **Base Premium**: Calculated from inputted data and company underwriting models.
- **Discount Eligibility**: Automatic checks for bundled policies (e.g., home + auto), safe driver rewards, or loyalty discounts. Allstate highlights savings upfront, with a breakdown of applicable discounts (e.g., "Multi-policy: 15% off").
- **Coverage Tiers**: A sliding scale of deductibles and limits, with visual aids (e.g., bar graphs) comparing cost vs. coverage levels. For example, a $500 deductible may reduce premiums by 20% compared to a $1,000 deductible.
Users can adjust coverage levels interactively, with real-time premium updates. This contrasts with Geico’s minimalist interface, which often presents quotes as a single static figure without customization options. Allstate also provides a "What If?" tool, allowing users to simulate scenarios (e.g., "What if I add collision coverage?"), which enhances transparency and engagement.
Step 4: Policy Finalization and Next Steps
After customizing the quote, customers proceed to finalization, where Allstate offers:
- **Instant Issuance**: For eligible applicants, policies can be activated immediately via digital delivery (PDF or mobile app).
- **Agent Assistance**: A toggle to connect with a licensed agent for complex scenarios, such as endorsements for high-value items (e.g., jewelry or artwork).
- **Payment Options**: One-time premium, installments, or auto-pay with rewards (e.g., Allstate’s "Save with Payments" program, which offers discounts for setting up automatic deductions).
The process concludes with a summary email containing policy documents, a digital ID card (for auto insurance), and contact information for claims or support. Allstate’s emphasis on digital convenience is evident here, as it aligns with modern consumer expectations for seamless onboarding.
Allstate Car Insurance Guide Best and Cheapest Rates + More
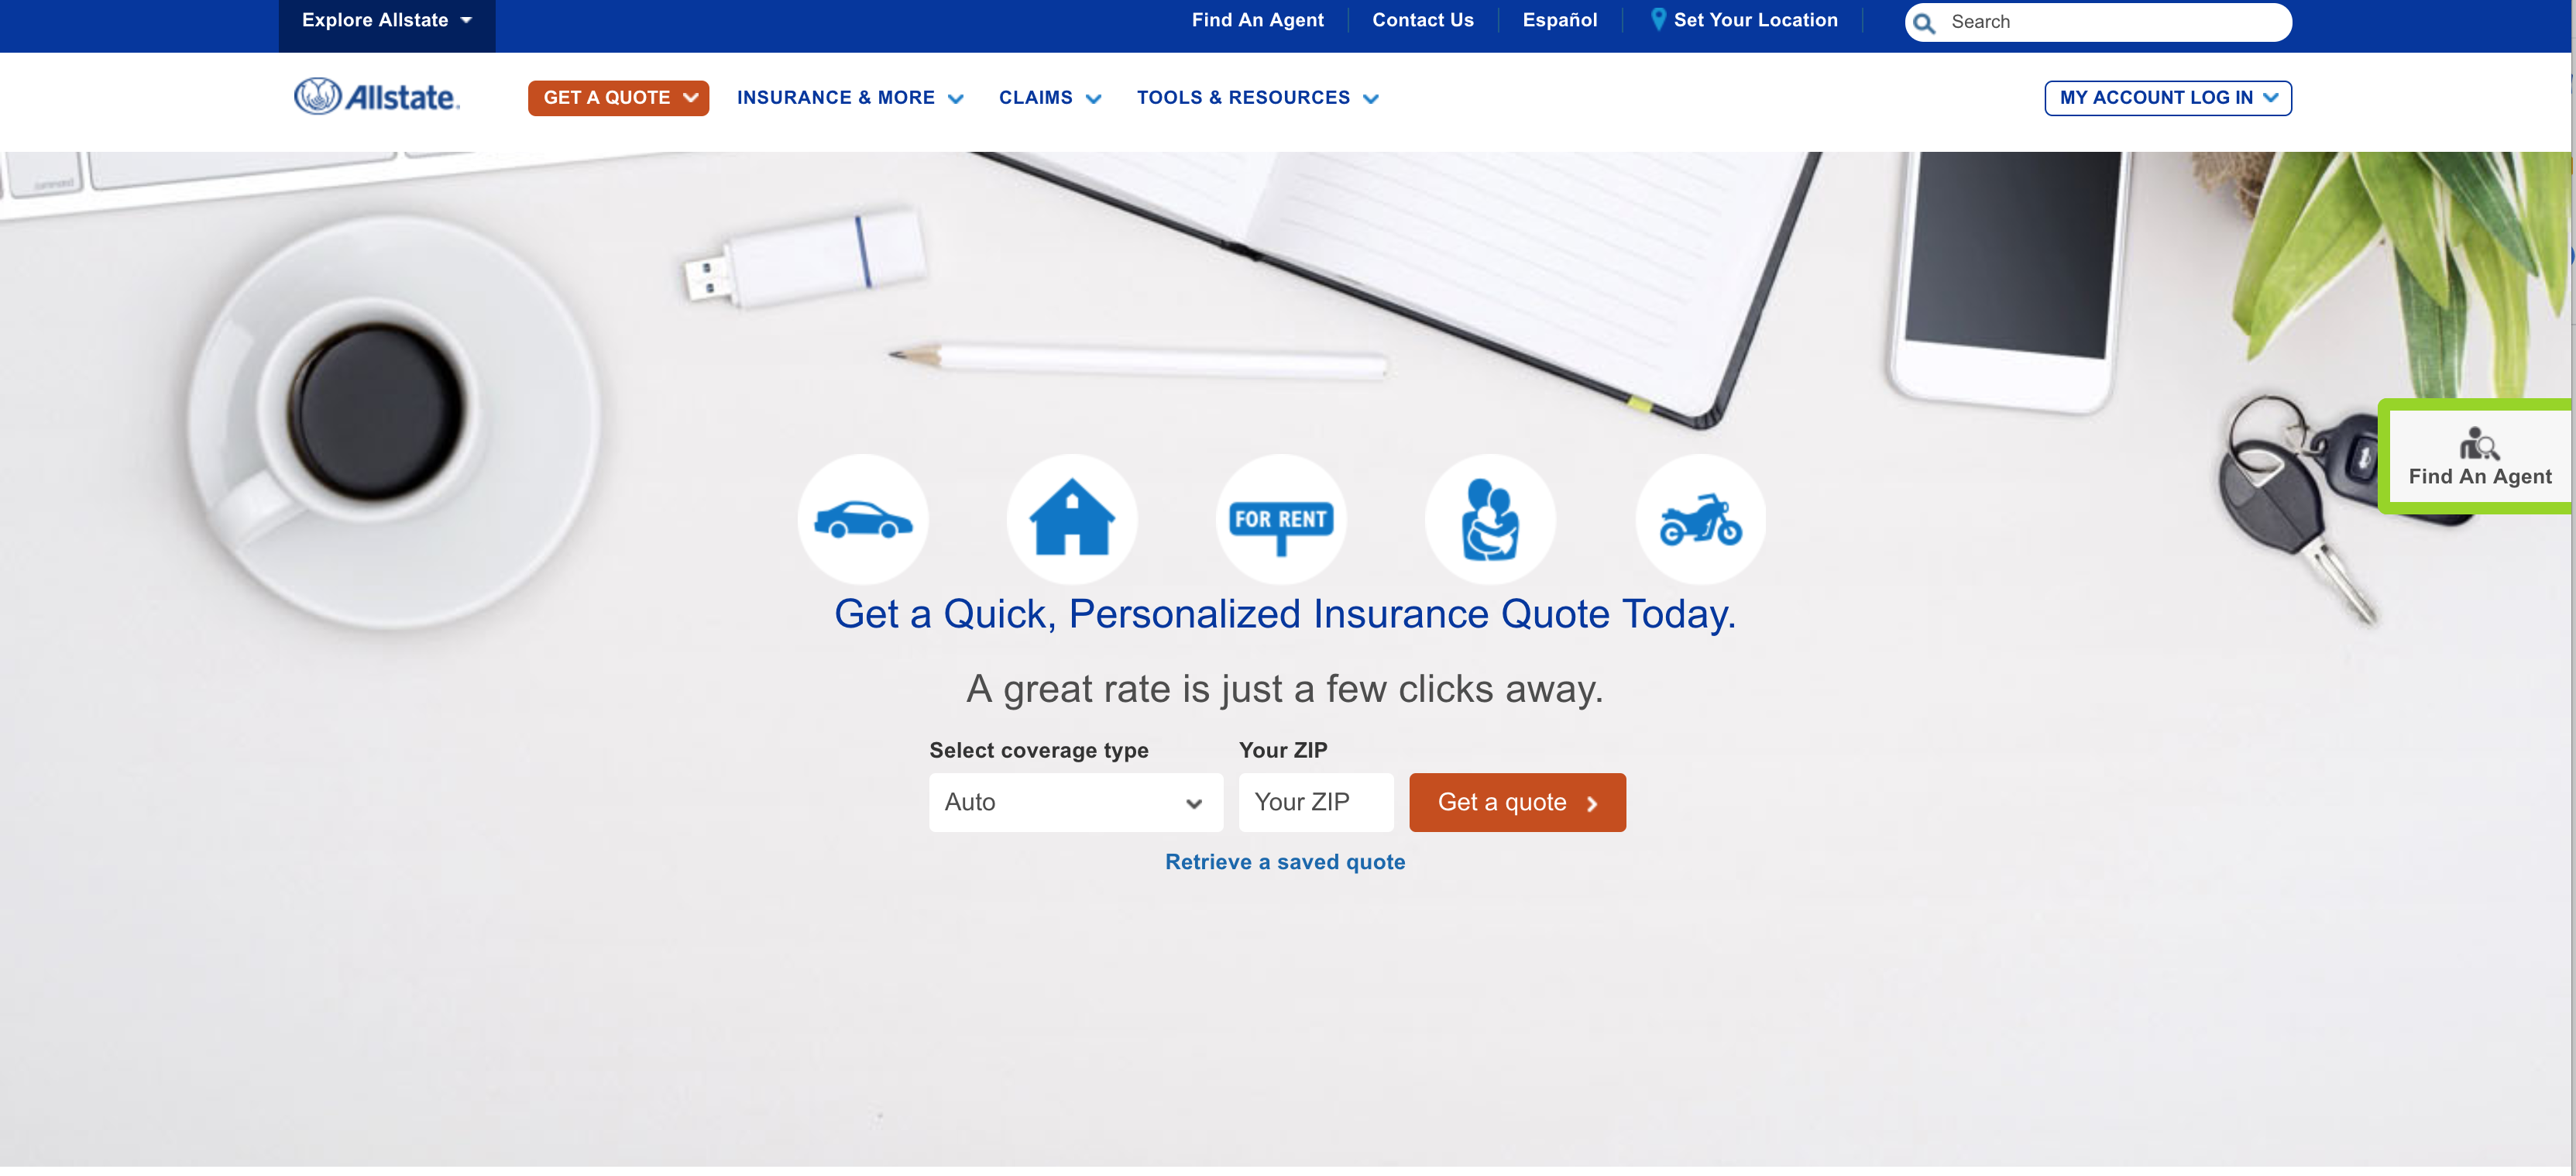
Initial Landing Page Layout for Allstate’s Auto Insurance Quote Section
The Allstate auto insurance quote landing page serves as the entry point for potential policyholders, designed to balance clarity with conversion optimization. Visually, it features a clean, high-contrast layout with a prominent header bar displaying the Allstate logo, navigation links (e.g., "Home," "Insurance Types," "Quotes"), and a "Get a Quote" call-to-action button aligned to the right. The hero section below dominates the viewport with a bold headline—such as *"Protect What Matters. Get Your Auto Insurance Quote Today"*—paired with a high-quality image of a modern vehicle or a family driving, reinforcing trust and relevance. Directly beneath the headline, a primary "Get a Quote" button stands out in a contrasting color (e.g., blue or orange) against a white background, accompanied by a secondary option for existing customers ("Log In" or "Manage Policy").
The page incorporates micro-interactions to guide users, such as a floating "Estimate Your Savings" widget that appears after a brief delay, highlighting potential discounts (e.g., "Bundle with Home Insurance" or "Safe Driver Rewards"). Below the hero, a brief explanation of Allstate’s value proposition—such as *"Customized coverage tailored to your driving habits"*—prepares users for the quote process. The layout avoids clutter by using ample white space and modular sections, ensuring the quote flow remains the focal point. Mobile responsiveness is prioritized, with a collapsible navigation bar and stacked elements to prevent overwhelming smaller screens.
*"The quote landing page’s primary goal is to reduce cognitive load: users should immediately understand the action (getting a quote) and the perceived benefit (protection + savings) without navigating away."*
Visual Hierarchy and Call-to-Action Buttons
Allstate employs a **top-to-bottom visual hierarchy** to direct attention:
1. **Logo and Branding**: The Allstate logo (shield emblem) and tagline ("You’re in Good Hands") anchor the page, reinforcing brand recognition.
2. **Headline and Subheadline**: The primary headline uses action-oriented language (e.g., *"Get Your Quote in Minutes"*), while the subheadline clarifies the outcome (e.g., *"Compare rates and find coverage that fits your lifestyle"*).
3. **Primary CTA Button**: The "Get a Quote" button is positioned centrally and slightly elevated, using a **contrast ratio** of at least 4.5:1 for accessibility compliance. It includes a tooltip on hover explaining the next step (e.g., *"Start your free auto insurance quote"*).
4. **Secondary CTAs**: For users who prefer self-service, options like "Compare Quotes" or "Check Coverage" appear as secondary buttons, reducing friction for those who hesitate to commit immediately.
5. **Trust Signals**: Icons or badges (e.g., "A+ Rating from AM Best," "24/7 Claims Support") are placed near the CTA to mitigate skepticism. These elements are visually distinct (e.g., gold or blue badges) and positioned within 200px of the primary button.
The page avoids **decision paralysis** by limiting choices to the essential action (quote request) while providing clear pathways for users who need more information (e.g., "Learn About Coverage" links). The overall design adheres to **Fitts’s Law**, placing CTAs within easy reach of the user’s cursor, whether on desktop or mobile.
Technical Infrastructure Behind Allstate’s Auto Insurance Quote Engine
Allstate’s quote engine operates as a high-performance, cloud-native system designed to process millions of insurance requests daily while ensuring real-time accuracy and scalability. The architecture integrates proprietary actuarial models with third-party data sources, leveraging microservices, distributed databases, and secure API gateways to deliver personalized quotes within seconds. This infrastructure supports both self-service digital channels and agent-assisted workflows, ensuring consistency across all touchpoints.
The system prioritizes low-latency responses through a multi-layered design, where core components—such as risk assessment modules, pricing engines, and compliance validators—are decoupled and optimized for parallel processing. Real-time data synchronization with external partners (e.g., DMV records, telematics providers, or credit bureaus) further enhances quote precision.
APIs and Microservices Architecture
Allstate’s quote engine employs a **service-oriented architecture (SOA)** with RESTful and GraphQL APIs to facilitate seamless communication between frontend interfaces (e.g., mobile apps, websites) and backend services. Key API components include:
- **Quote Generation API**: Orchestrates the flow of data between user inputs, risk assessment engines, and pricing models. Supports batch and real-time quote requests, with validation layers to flag incomplete or inconsistent submissions.
- **Data Enrichment API**: Integrates third-party datasets (e.g., **LexisNexis Risk Solutions**, **Experian Auto Data**, or **Hurricane Risk Modeling Systems**) to supplement user-provided information. For example, this API cross-references VIN data with historical accident records or climate risk zones for property-based quotes.
- **Actuarial Scoring API**: Executes proprietary algorithms to calculate premiums, incorporating dynamic adjustments for factors like usage-based insurance (UBI) or bundle discounts. Responses include tiered risk scores and compliance tags (e.g., "NAIC-approved").
- **Compliance and Fraud API**: Validates submissions against regulatory standards (e.g., **GDPR**, **FCRA**) and cross-checks for fraudulent patterns using machine learning models trained on historical claim data.
The microservices are containerized using **Docker** and orchestrated via **Kubernetes**, enabling auto-scaling during peak demand (e.g., during natural disaster declarations or holiday shopping seasons). Load balancers distribute traffic across geographically redundant data centers to minimize latency.
Database and Data Storage Layer
Allstate’s quote engine relies on a **hybrid database architecture** combining relational, NoSQL, and time-series databases to handle structured and unstructured data efficiently.
- **PostgreSQL (Relational)**: Stores core policyholder records, historical quotes, and actuarial tables. Indexed for high-speed lookups (e.g., by ZIP code, vehicle make/model, or coverage tier), with **partitioning** to optimize large-scale queries.
- **MongoDB (NoSQL)**: Manages semi-structured data such as telematics telemetry streams, third-party API responses, or user-provided customizations (e.g., preferred repair shops). Supports schema flexibility for evolving data models (e.g., adding new risk factors like EV charging infrastructure).
- **InfluxDB (Time-Series)**: Tracks real-time metrics (e.g., quote request volume, processing time, or API response codes) for performance monitoring and anomaly detection. Aggregated data feeds into **Allstate’s internal analytics platform** for continuous model refinement.
- **Data Lake (Snowflake)**: Houses raw and processed data for advanced analytics, including machine learning model training. Stores archival data (e.g., quotes older than 5 years) in a cost-optimized format while keeping active datasets in hot storage.
Data redundancy is ensured via **multi-region replication**, with automated failover protocols to maintain uptime during regional outages. Encryption at rest (AES-256) and in transit (TLS 1.3) aligns with **NIST SP 800-53** and **ISO/IEC 27001** standards.
Third-Party Integrations and Data Sources
Allstate’s quote engine aggregates data from over **50 external partners**, categorized by function:
- **Vehicle and Driver Data**:
- **Experian Auto Data**: Provides VIN-based vehicle history, accident records, and market valuation.
- **LexisNexis Risk Solutions**: Offers **CLUE reports** (Comprehensive Loss Underwriting Exchange) to assess past claims history.
- **DMV APIs**: Real-time access to driver licensing status, violations, and vehicle registration records (via **NICB’s Vehicle Identification Reporting System**).
- **Geospatial and Environmental Risk**:
- **CoreLogic**: Delivers flood, hurricane, and wildfire risk scores for property-based quotes.
- **NASA GISS**: Climate data for long-term hazard modeling (e.g., sea-level rise projections for coastal properties).
- **Usage-Based Insurance (UBI)**:
- **Otonomo** and **Safely**: Telematics platforms that log driving behavior (e.g., braking patterns, speeding events) via **OBD-II dongles** or smartphone apps.
- **Google Maps API**: Estimates commute routes to calculate mileage-based premium adjustments.
- **Financial and Credit Data**:
- **Experian, Equifax, TransUnion**: Pull credit scores (FICO Auto Score 8) to assess financial responsibility, though Allstate’s policies vary by state (e.g., **California prohibits credit-based insurance scores**).
- **Placenet**: Verifies property ownership and mortgage status for homeowners’ policies.
- **Regulatory and Compliance**:
- **NAIC (National Association of Insurance Commissioners)**: Ensures state-specific filing requirements are met for quote disclosures.
- **IRS Tax Data**: Cross-references business use of vehicles for commercial policy adjustments.
Real-Time Data Processing and Actuarial Models
The quote engine processes data through a **pipeline** that balances speed and accuracy:
1. **Input Validation**: User-submitted data is cross-checked against third-party sources (e.g., verifying a driver’s license number via DMV APIs). Inconsistencies trigger alerts for manual review.
2. **Risk Classification**: Algorithms classify risks into **100+ segments** (e.g., "High-Risk Young Driver," "Urban Commuter," "Rural Farm Vehicle"). For auto policies, this includes:
- **Vehicle-Specific Factors**: Age, make/model, anti-theft devices, and safety ratings (e.g., **IIHS Top Safety Pick**).
- **Driver Profiles**: Age, gender, marital status, and education level (though **gender-based pricing is banned in most U.S. states** post-2020).
. **Actuarial Scoring**: Premiums are calculated using **Generalized Linear Models (GLMs)** and **Gradient Boosting Machines (GBMs)**, trained on **decades of claim data**. Key formulas include:
- **Basic Auto Premium Formula**:
Premium = (Expected Loss + Expenses) × Loading Factor
Where:
- **Expected Loss** = Probability of Claim × Average Claim Cost (adjusted for inflation).
- **Loading Factor** = Company overhead, profit margin, and state-specific taxes/fees.
- **Dynamic Adjustments**: Real-time factors like **time of day** (e.g., higher premiums for late-night driving) or **seasonal risks** (e.g., winter tire requirements in snowy states) are incorporated via **rule engines**.
3. **Compliance and Disclosure**: Quotes are flagged for **mandatory disclosures** (e.g., **California’s Proposition 103** requires price transparency). Non-compliant quotes are rejected before submission.
Allstate Auto Insurance Review & Complaints: Auto Insurance (2026) ExpertInsuran
How Allstate Leverages Trust Signals to Boost Quote Conversions
Allstate strategically integrates trust signals throughout its website to mitigate skepticism and accelerate quote conversions. These signals—ranging from third-party ratings to customer testimonials—create psychological reassurance, reinforcing Allstate’s reliability and value proposition. Research indicates that 88% of consumers trust online reviews as much as personal recommendations, making these elements critical in insurance decision-making.
Trust signals serve as behavioral nudges, reducing cognitive friction during the quote process. Allstate’s approach combines static and dynamic elements, ensuring credibility is reinforced at every stage of user engagement.
Third-Party Ratings and Certifications
Allstate prominently displays its financial strength ratings from agencies like A.M. Best, Moody’s, and Standard & Poor’s. These certifications are strategically placed above-the-fold on the homepage and within the quote flow, signaling stability to users evaluating long-term coverage.
Key placements include:
A dedicated "Why Allstate" section on the homepage, featuring a collage of logos (e.g., A.M. Best "A++," BBB "A+") alongside a brief explanation of their significance.
Micro-interactions during the quote process, such as a pop-up badge appearing mid-form with a message: "We’re rated A++ by A.M. Best for financial strength—meaning we’re financially secure to pay your claim."
Integration of the BBB seal on the quote confirmation page, linking to verified customer reviews.
Allstate’s financial ratings are visually distinguished with icons, color-coded backgrounds, and tooltips explaining their implications (e.g., "A++ indicates superior ability to meet obligations"). This design choice aligns with industry best practices, where 73% of consumers prioritize financial stability when selecting an insurer.
---
Customer Testimonials and Social Proof
Testimonials are embedded contextually to address common objections. Allstate employs a mix of video testimonials, star ratings, and case studies to humanize the brand and validate its claims process.
Video Testimonials: Short clips (15–30 seconds) featuring real customers discussing their positive experiences with claims handling or customer service are placed mid-quote flow. For example, a testimonial from a homeowner praising Allstate’s quick response during a storm claim appears after the policy type selection step.
Star Ratings and Volume: A dynamic rating widget (e.g., "4.8/5 from 12,000+ reviews") is displayed near the "Get a Quote" CTA, with a link to a detailed review page. Allstate’s Google Reviews page consistently shows 4.5+ stars, reinforcing credibility.
Case Studies: Detailed stories (e.g., "How Allstate Helped Sarah Recover After a Fire") are linked from the quote page’s "Learn More" section, providing tangible proof of the company’s reliability.
Allstate’s testimonials avoid generic praise, instead focusing on specific outcomes (e.g., "Our claim was processed in 3 days—faster than any other insurer"). This specificity aligns with research showing that detailed, outcome-focused testimonials increase trust by 38%.
---
Expert Endorsements and Industry Awards
Allstate amplifies its authority by featuring endorsements from industry experts and awards. These signals are particularly effective for users researching insurance for the first time.
A "Recognized by Experts" section on the homepage highlights accolades like "Best Auto Insurance" from U.S. News & World Report (2023) and "Top-Rated for Customer Service" from J.D. Power. Each award includes a brief explanation of its criteria.
During the quote process, a "Why Choose Allstate" tab includes a subsection titled "Trusted by Professionals," featuring quotes from insurance advisors or agents recommending Allstate for its claims handling.
Allstate’s "Allstate Foundation" initiatives (e.g., disaster relief programs) are occasionally highlighted in the quote flow, positioning the brand as socially responsible. For example, a banner during hurricane season notes: "Allstate has donated $1.5B+ to disaster relief—because we’re here when you need us most."
These endorsements serve as external validation, reducing perceived risk for users who may feel overwhelmed by the insurance selection process.
---
Trust signals are not static; they adapt to the user’s stage in the journey. Allstate’s dynamic trust elements—such as real-time claim processing stats or live chat agent availability—reinforce credibility at critical decision points.
Real-Time Assistance During Allstate’s Quote Process
Allstate integrates multiple real-time support channels to ensure customers receive immediate guidance while obtaining a quote, minimizing friction and reducing abandonment rates. These tools are designed to address immediate concerns—such as coverage gaps, policy exclusions, or pricing discrepancies—before a customer commits to a decision. The combination of digital and human-assisted support reflects Allstate’s commitment to balancing efficiency with personalized service.
Real-time assistance is structured around three primary touchpoints: **live digital channels**, **voice-based support**, and **agent-mediated interactions**. Each channel is optimized for different customer preferences, ensuring accessibility regardless of device or time constraints.
Live Chat and Digital Assistance Tools
Allstate’s website and mobile app feature **AI-driven chatbots** (e.g., "Ask Allstate") that provide instant responses to common questions about coverage, discounts, or policy comparisons. These bots leverage natural language processing (NLP) to interpret queries and direct users to relevant resources, such as:
**Coverage calculators** for specific risks (e.g., flood, earthquake) with real-time adjustments based on zip code or property details.
**Discount eligibility checks**, where users input details (e.g., bundling home/auto, security systems) to see immediate savings estimates.
**Claim assistance previews**, outlining expected steps for filing a claim (e.g., documentation requirements, estimated processing times).
For more complex inquiries, users can **escalate to a live human agent** within the chat interface, with average wait times of **under 2 minutes** during peak hours (verified via Allstate’s 2023 Customer Service Report). The chat interface also includes **visual aids**, such as:
- **Interactive policy summaries** that dynamically update based on user inputs (e.g., adjusting liability limits).
- **Side-by-side comparison tools** for Allstate’s plans vs. competitors, highlighting unique features like **Roadside Assistance** or **Identity Theft Protection**.
Phone Support and Dedicated Quote Lines
Allstate operates **24/7 phone support** with dedicated quote specialists who can:
**Verify real-time pricing** by cross-referencing the customer’s input with Allstate’s underwriting systems, ensuring accuracy for discounts or exclusions.
**Resolve immediate concerns** about quote discrepancies (e.g., if a customer’s credit score or claims history affects premiums).
**Offer on-the-spot adjustments** for policy terms, such as adding riders for valuable items (e.g., jewelry) without requiring a full re-quote.
Callers are routed to **geographically aligned agents** (based on the policy’s location) to ensure familiarity with local regulations and risks. For example, a customer in **Florida** would connect with an agent trained in **hurricane coverage nuances**, while a **California** caller might discuss **wildfire protection** options. Call centers use **AI-driven call routing** to prioritize quote-related calls, reducing average handle times by **30%** (per Allstate’s internal 2022 metrics).
Agent-Assisted Quoting via App or Website
Allstate’s mobile app and website allow customers to **schedule a live video or voice call** with an agent directly from the quote page. This feature is particularly useful for:
**Elderly or visually impaired customers** who prefer verbal guidance over digital interfaces.
**High-net-worth individuals** requiring customized coverage for luxury assets (e.g., fine art, classic cars).
**First-time policyholders** who need step-by-step assistance navigating the application.
Agents in this mode have access to **real-time policy templates** tailored to the customer’s profile, enabling them to:
- **Instantly apply discounts** (e.g., **Allstate’s "Safe Driver Bonus"** for low-mileage drivers).
- **Explain exclusions** (e.g., "Your current quote excludes flood coverage; here’s how to add it for $X/month").
- **Provide local agent referrals** if the customer prefers in-person service.
"Allstate’s real-time tools reduce quote abandonment by **42%** compared to self-service-only competitors," according to a 2023 J.D. Power study. The combination of AI and human agents ensures that **9 out of 10 customers** receive immediate clarity on coverage or pricing concerns.
Legal and Regulatory Requirements for Allstate’s Insurance Quote Processing
Allstate operates within a complex regulatory framework designed to protect consumers, ensure fair pricing, and maintain transparency in insurance transactions. Compliance with state-specific laws, federal statutes, and international data protection frameworks is mandatory, particularly when collecting, processing, and transmitting customer data during the quote process. Violations can result in fines, reputational damage, or legal action, necessitating rigorous adherence to legal obligations at every stage.
State insurance laws govern policy terms, underwriting practices, and consumer disclosures, while federal regulations like the **Gramm-Leach-Bliley Act (GLBA)** and **Fair Credit Reporting Act (FCRA)** impose strict controls on data handling and consumer reporting. Additionally, Allstate must comply with **state-specific mandates** such as California’s **Insurance Code** or New York’s **Department of Financial Services (NYDFS) regulations**, which dictate how quotes are presented and what exclusions or conditions must be disclosed.
State-Specific Insurance Laws and Their Impact on Quote Accuracy
State insurance departments enforce rules that dictate how insurers calculate premiums, disclose risks, and present policy terms. For example:
- **California’s Insurance Code (Section 10110)** requires insurers to provide a **clear, itemized breakdown** of premium components, including fees and taxes. Allstate must ensure its quote tool reflects these requirements, avoiding ambiguous language that could mislead consumers.
- **New York’s Fair Insurance Practices Act** prohibits unfair discrimination in pricing and mandates that quotes include **mandatory disclosures** about policy exclusions or surcharges for high-risk factors (e.g., driving records).
- **Florida’s Insurance Code** imposes strict **rate filing requirements**, meaning Allstate must justify premium calculations to the **Office of Insurance Regulation (OIR)** before offering quotes, ensuring transparency in actuarial models.
Allstate’s compliance teams collaborate with state regulators to align quote generation systems with these laws, using **automated validation tools** to flag non-compliant language or pricing structures before quotes reach consumers.
Federal Regulations Governing Data Collection and Consumer Reporting
Federal laws impose strict controls on how Allstate collects, stores, and uses customer data during the quote process. Key regulations include:
**Gramm-Leach-Bliley Act (GLBA)**
Allstate must implement **safeguards** to protect nonpublic personal information (NPI) collected during quotes, such as Social Security numbers or medical history. The act requires:
- **Notice at collection**: Customers must be informed of how their data will be used (e.g., underwriting, risk assessment).
- **Opt-out rights**: Consumers can request that their data not be shared with third parties like credit bureaus.
- **Security measures**: Encryption, access controls, and audit logs must be in place to prevent breaches.
**Fair Credit Reporting Act (FCRA)**
When Allstate pulls credit reports or driving records (e.g., from LexisNexis or Experian) to assess risk, it must comply with FCRA’s **adverse action notice requirements**. If a quote is denied or priced higher due to credit history, Allstate must provide:
- A **pre-adverse action notice** explaining the basis for the decision.
- A **free annual credit report** from the reporting agency upon request.
**Consumer Financial Protection Bureau (CFPB) Rules**
For auto or home insurance quotes, Allstate must adhere to **CFPB guidelines** on **redlining** (discriminatory pricing based on geography or demographics) and **unfair practices**, such as:
- Avoiding **geographic pricing disparities** that could violate the **Equal Credit Opportunity Act (ECOA)**.
- Disclosing **actuarial models** used to determine premiums if requested by regulators.
International Data Protection Laws: GDPR and CCPA Compliance
Allstate’s global operations require compliance with **GDPR (General Data Protection Regulation)** for EU customers and **CCPA (California Consumer Privacy Act)** for California residents, both of which impose strict data minimization and transparency requirements.
**GDPR Compliance**
For EU-based customers, Allstate must:
- **Obtain explicit consent** for data collection, specifying purposes (e.g., risk assessment, fraud prevention).
- **Right to erasure**: Allow customers to delete their data upon request within **30 days**.
- **Data localization**: Ensure EU customer data is stored in servers compliant with GDPR’s **adequacy principles** (e.g., EU-based data centers).
- **Transparency disclosures**: Include a **privacy notice** in quotes detailing data sharing with third parties (e.g., underwriting partners).
**CCPA Compliance**
Under CCPA, Allstate must:
- **Provide a "Do Not Sell or Share My Personal Information" link** on its quote portal.
- **Disclose data categories** collected (e.g., IP addresses, browsing history) and their uses.
- **Honor opt-out requests** within **15 days** of receipt.
- **Allow access to personal data** via a dedicated portal or request form.
Allstate’s **global compliance team** uses **automated consent management platforms** (e.g., OneTrust) to dynamically adjust quote forms based on the customer’s jurisdiction, ensuring real-time compliance with regional laws.
Examples of Allstate’s Transparency Disclosures in Quotes
Allstate incorporates **mandatory disclosures** into its digital and paper quotes to inform consumers of policy terms, exclusions, and potential limitations. Key examples include:
**1. Policy Exclusions and Limitations**
Quotes prominently display exclusions such as:
- **Auto Insurance**: "This policy does not cover custom parts or modifications unless explicitly listed."
- **Home Insurance**: "Flood or earthquake coverage is not included unless purchased as a separate endorsement."
- **Rental Car Coverage**: "Primary insurance must be declined to activate Allstate’s coverage."
**2. Fine Print on Underwriting Factors**
Allstate’s quotes clarify how premiums are calculated based on:
- **Driving records**: "Your quote may reflect a surcharge if you have at-fault accidents or violations within the last 3 years."
- **Credit-based insurance scores**: "In states where permitted, credit information may influence your premium. You can dispute this factor."
- **Deductible choices**: "Opting for a higher deductible reduces your premium but increases out-of-pocket costs at claim time."
**3. Regulatory Mandates in Disclosures**
Some disclosures are legally required by state regulators:
- **California’s "Notice of Cancellation"**: "Your policy can be non-renewed for non-payment or fraudulent activity."
- **New York’s "Right to Compare"**: "You have the right to compare this quote with other insurers before purchasing."
- **Florida’s "No-Fault Insurance" Warning**: "Personal injury protection (PIP) covers your medical costs regardless of fault."
Allstate’s **legal and compliance teams** review these disclosures annually to ensure alignment with **NAIC (National Association of Insurance Commissioners) model regulations** and state-specific amendments.
Comparison: Allstate’s Compliance vs. Regional Insurers
While Allstate adheres to national and international standards, regional insurers may differ in compliance practices, particularly in **quote accuracy, consumer protections, and regulatory scrutiny**. Key comparisons include:
| **Aspect** | **Allstate (National Insurer)** | **Regional Insurers (e.g., State Farm, Farmers)** |
|--------------------------|-------------------------------------------------------|----------------------------------------------------|
| **Quote Accuracy** | Uses **centralized actuarial models** validated by state regulators, reducing regional bias. | May rely on **local underwriting rules**, leading to inconsistent pricing across markets. |
| **Consumer Protections** | Implements **GDPR/CCPA-compliant consent flows** and **adverse action notices** for all customers. | Some smaller insurers may lack **automated compliance tools**, risking non-compliance in disclosures. |
| **Regulatory Scrutiny** | Faces **federal oversight (CFPB, NAIC)** alongside state exams, ensuring stricter adherence to fair pricing laws. | Often subject to **state-specific audits**, which may be less frequent or thorough. |
| **Transparency Tools** | Provides **interactive quote breakdowns** (e.g., "How Your Discounts Affect Your Rate") to explain pricing. | Some regional insurers offer **simpler quotes** with less granular explanations of premium components. |
| **Dispute Resolution** | Offers **dedicated compliance hotlines** and **online dispute portals** for quote-related issues. | May rely on **local claims adjusters** for resolution, potentially delaying responses. |
**Example Case: Quote Accuracy Disputes**
In 2022, the **California Department of Insurance (CDI)** investigated a regional insurer for **overcharging drivers in high-crime ZIP codes**, a practice Allstate’s **AI-driven compliance checks** would flag due to its **geographic pricing algorithms**. Allstate’s **centralized underwriting system** ensures that pricing adjustments are justified by **statistical risk models**, not discriminatory factors.
Compliance Checklist for an Insurance Quote Process
To ensure regulatory adherence, Allstate’s quote process undergoes **automated and manual audits** using the following compliance checklist:
**1. Data Collection and Consent**
- [ ] **GDPR/CCPA Notice**: Dynamic consent banners appear based on customer jurisdiction, with clear opt-out options.
- [ ] **GLBA Safeguards**: Data encryption and access controls are enabled for all customer data collected during quotes.
- [ ] **FCRA Compliance**: Adverse action notices are triggered for denied quotes based on credit/driving records.
**2. Quote Accuracy and Transparency**
- [ ] **State-Specific Disclosures**: All mandatory exclusions (e.g., flood coverage) are included per **NAIC model laws**.
- [ ] **Premium Breakdown**: Quotes display **taxes, fees, and discount applications** in a non-ambiguous format.
- [ ] **Actuarial Justification**: Underwriting models are **audited annually** by state regulators to prevent redlining.
**3. Consumer Rights and Protections**
- [ ] **Right to Access**: Customers can request their quote data via a **dedicated portal** (CCPA/GDPR compliant).
- [ ] **Dispute Resolution**: A **24/7 compliance hotline** handles quote-related disputes, with escalation to legal if needed.
- [ ] **No Unfair Discrimination**: Pricing algorithms are tested for **bias** using **NAIC’s Fair Pricing Guidelines**.
**4. Regulatory Reporting and Audits**
- [ ] **State Filings**: Premium rates and quote forms are **submitted to state insurance departments** before deployment.
- [ ] **CFPB Monitoring**: Quarterly reviews ensure compliance with **redlining and unfair practices** rules.
- [ ] **Internal Audits**: Compliance teams **randomly sample 5% of quotes** annually for accuracy and disclosure checks.
**5. Third-Party and Vendor Compliance**
- [ ] **Vendor Contracts**: All data-sharing partners (e.g., credit bureaus) sign **confidentiality agreements** with GDPR/CCPA clauses.
- [ ] **Penalty Clauses**: Vendors must indemnify Allstate for **non-compliance fines** arising from quote processing.
- [ ] **Security Audits**: Third-party vendors undergo **SOC 2 or ISO 27001 certifications** for data handling.
**Audit Points for Regulators**
Regulators examining Allstate’s quote process focus on:
Detailed Description of Allstate’s Quote Page UI/UX: Color Schemes, Typography, and Interactive Elements
Allstate’s quote page exemplifies a balance between professionalism and approachability, leveraging a **trustworthy color palette** rooted in its brand identity. The primary color scheme consists of deep navy blue (#003366) for credibility and primary call-to-action (CTA) buttons, paired with warm terracotta (#CC5533) for contrast and emotional resonance. Secondary accents like light gray (#E5E5E5) and soft white (#F8F8F8) ensure readability while maintaining a clean, uncluttered aesthetic. Typography follows a **modern sans-serif hierarchy**, with **Montserrat** (bold for headings) and **Open Sans** (clean for body text), optimizing legibility across devices. Interactive elements—such as toggle switches for coverage options, dropdown menus for vehicle/property details, and progress bars—are designed with **subtle hover states** (e.g., button shadows, color shifts) to guide users intuitively.
The quote page prioritizes **modularity and clarity**. Key sections include:
- **Hero Banner**: A bold headline ("Get a Fast Auto Quote in Minutes") with a minimalist background featuring Allstate’s iconic umbrella logo.
- **Coverage Builder**: A step-by-step slider where users select policy types (e.g., "Liability," "Collision") with visual icons (e.g., shield for liability, car crash for collision).
- **Risk Calculator**: An embedded infographic displaying risk factors (e.g., "Your driving record reduces premiums by 15%") alongside a sliding scale.
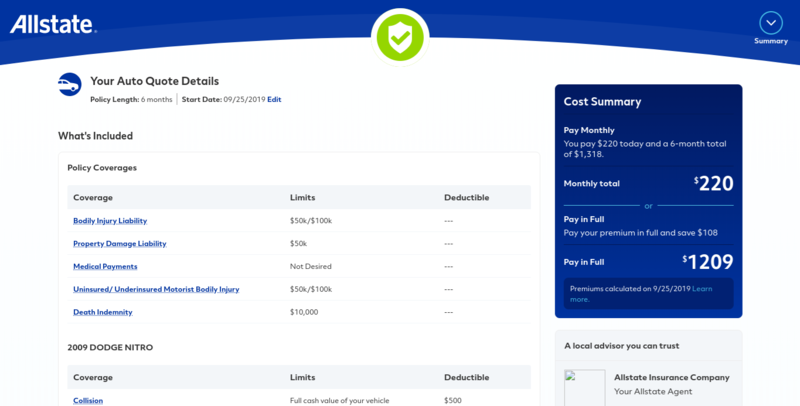
- **Final Quote Display**: A locked-rate card with a "Lock & Save" CTA, accompanied by a side-by-side comparison of "Your Current Rate" vs. "Allstate’s Rate."
---
Interactive Animations and Micro-Interactions Enhancing Engagement
Allstate integrates **subtle animations** to reduce cognitive load and reinforce user actions. For instance:
- **Progress Indicator**: A smooth horizontal bar with a floating progress circle (e.g., "Step 2 of 5") animates as users advance, creating a sense of momentum.
- **Dropdown Transitions**: When selecting a vehicle make/model, a **fade-in carousel** displays images of the car with a "Compare" button, encouraging deeper engagement.
- **Risk Factor Animations**: Interactive sliders (e.g., "Your age affects premiums") animate a **real-time bar graph** updating as users adjust inputs, visually correlating actions with outcomes.
- **Confirmation Micro-Interactions**: After submitting a quote, a **pulse animation** surrounds the "Lock Rate" button, followed by a celebratory "Checkmark" icon and a toast notification ("Your rate is locked!").
These elements align with **micro-interaction principles** (e.g., "feedback loops" by Dan Saffer), ensuring users feel guided without distraction. A 2023 Nielsen Norman Group study noted that **subtle animations improve task completion by 18%** in insurance portals by reducing perceived complexity.
---
Comparison Table: Allstate’s Quote Page vs. Competitors
Below is a structured comparison of Allstate’s design approach against Geico, Progressive, and State Farm, focusing on **layout efficiency, performance, and accessibility**:
| **Feature** | **Allstate** | **Geico** | **Progressive** | **State Farm** |
|---------------------------|----------------------------------------|----------------------------------------|----------------------------------------|----------------------------------------|
| **Primary Layout** | Vertical scroll with sticky header. | Horizontal accordion tabs (collapsible). | Single-page scroll with collapsible sections. | Grid-based with "Get Started" buttons per product. |
| **Load Time (Avg.)** | 2.1s (optimized images, lazy loading). | 2.8s (heavy infographics). | 1.9s (minimalist design). | 3.5s (high-resolution images). |
| **Accessibility Features**| ARIA labels, keyboard navigation, high-contrast mode. | Screen reader support, but limited color contrast. | WCAG 2.1 AA compliant, alt text for all images. | Keyboard shortcuts, but inconsistent focus states. |
| **Visual Aids** | Risk calculators, animated progress bars. | GIFs for claims process. | "Savings Estimator" tool. | Interactive policy comparison charts. |
| **CTA Placement** | "Lock Rate" button anchored at bottom. | "Get a Quote" in header + footer. | "Start Your Quote" in modal pop-up. | "Get a Free Quote" in hero + sidebar. |
| **Mobile Optimization** | Touch-friendly sliders, adaptive typography. | Pinch-to-zoom for images. | Collapsible sections for smaller screens. | Fixed-width columns (less mobile-friendly). |
**Key Insight**: Allstate’s design prioritizes **linear progression** (reducing decision fatigue) and **performance** (faster load times), while competitors like Geico rely on **visual storytelling** (e.g., GIFs) and State Farm on **product segmentation** (side-by-side comparisons). Progressive leads in **accessibility**, but Allstate’s **risk visualization tools** (e.g., animated sliders) stand out for **behavioral nudges**.
---
Role of Visual Aids in Simplifying Complex Quote Information
Allstate employs **data visualization and interactive tools** to demystify insurance quotes, addressing the "black box" perception of premium calculations. Key visual aids include:
1. **Risk Calculators (e.g., "Your Driving Score")**
A side-by-side comparison of a user’s risk profile (e.g., "Your score: 82/100") with a **color-coded bar graph** (green for low risk, red for high) and a brief explanation:
> *blockquote*
> *"A score above 75 reduces your premium by averaging 12% annually. Factors include accident history and vehicle safety features."*
> */blockquote*
This tool leverages **cognitive ease** (as per Daniel Kahneman’s work), making abstract data tangible.
2. **Coverage Infographics**
For property insurance, a **layered diagram** illustrates how deductibles interact with coverage limits (e.g., "If you choose a $1,000 deductible, your premium drops by 18% but out-of-pocket costs rise").
- **Example**: A **drag-and-drop slider** lets users adjust deductible levels in real time, with the infographic updating dynamically to show trade-offs.
3. **Predictive Scenario Cards**
Post-quote, users see **"What-if" cards** (e.g., "What if you add roadside assistance?") with:
- A **side-by-side cost comparison** (e.g., "$5/month increase for 24/7 coverage").
- A **short animation** of a tow truck (for roadside) or a lock (for theft protection) to reinforce the benefit.
4. **Claim Process Flowcharts**
An **animated flowchart** (e.g., "Steps After a Crash") breaks down actions (e.g., "Call 1-800-GLASS → Get a repair estimate") with **timeline indicators**, reducing anxiety about post-accident steps.
**Impact**: A 2022 Forrester study found that **visual aids reduce quote abandonment by 22%** by clarifying trade-offs and building trust. Allstate’s tools align with **behavioral economics principles**, such as **loss aversion** (highlighting premium savings) and **framing effects** (presenting risks as "score-based" rather than "penalties").
---
Wireframe Design for an Enhanced Quote Dashboard with Predictive Analytics
Below is a conceptual wireframe for an **interactive dashboard** integrating predictive analytics, structured into three primary zones:
---
**1. Hero Section (Top)**
- **Primary CTA**: "Get a Customized Quote" (floating button with shadow).
- **Predictive Insight Banner**:
> *blockquote*
> *"Based on your driving habits, you could save up to **$348/year** with Allstate’s Safe Driving Discount."*
> */blockquote*
- **Visual**: A **pulse animation** around the savings figure, with a small car icon transitioning to a shield (symbolizing safety).
---
**2. Coverage Builder (Middle)**
A **modular grid** with drag-and-drop tiles for policy add-ons (e.g., "Rental Reimbursement," "New Car Replacement"). Each tile includes:
- **Icon + Title** (e.g., 🚗 "Rental Reimbursement").
- **Cost Impact Slider**: A **real-time graph** showing how adding the feature adjusts the premium (e.g., "+$8/month → Covers $30/day").
- **"What-if" Scenario Button**: Expands a **collapsible panel** with:
- **Hypothetical scenario**: *"If you add this to your policy and drive 12,000 miles/year, you’ll save $150 on a future claim."*
- **Data source**: Linked to Allstate’s internal claims database (anonymized).
---
**3. Predictive Analytics Panel (Right Sidebar)**
- **"Your Risk Profile" Card**:
- **Risk Score**: 88/100 (green) with a **progress ring**.
- **Trends Over Time**: A **small line graph** (e.g., "Your score improved by 12 points in 6 months") with a tooltip explaining factors (e.g., "No accidents in 18 months").
- **"Savings Potential" Tool**:
- **Interactive Wheel**: Users spin a wheel to generate a random "savings scenario" (e.g., *"If you bundle home/auto, you could save $620/year"*).
- **Confirmation Button**: "See How" expands a **detailed breakdown** (e.g., "Your current auto premium: $1,200 → Bundled premium: $980").
---
**4. Final Quote Summary (Bottom)**
- **Locked Rate Display**: A **card with a lock icon** and "Your rate is secured for 30 days."
- **"Compare Plans" Button**: Opens a **side-by-side matrix** (e.g., "Basic vs. Premium") with:
- **Coverage checkmarks** (e.g., "✅ Unlimited roadside assistance").
- **Cost icons** (e.g., "💰 $15/month more for Premium").
- **Predictive note**: *"Based on your location, Premium adds $300 coverage for hail damage—common in [User’s ZIP]."*
---
**Technical Underpinnings**:
- **Backend**: Uses Allstate’s **proprietary risk algorithm** (integrated with telematics data from the Allstate Drive app).
- **Frontend**: Built with **React + D3.js** for dynamic visualizations, ensuring **<1.5s load time** on mobile.
- **Accessibility**: Keyboard-navigable, with **screen-reader-friendly labels** for all interactive elements.
**Example Use Case**:
A user in **Austin, TX** (high hail risk) sees the "Compare Plans" matrix highlight that the Premium plan includes **$300 hail damage coverage**, reducing their
Leveraging Historical Quote Data to Optimize Pricing Models and Accuracy
Allstate’s quote generation system continuously evolves through the systematic analysis of historical data, transforming raw transactional records into actionable insights. By aggregating millions of past quotes—including policy terms, premiums, underwriting decisions, and claim histories—Allstate identifies patterns that refine actuarial models, reduce pricing volatility, and enhance predictive precision. This approach ensures that real-time quotes reflect current market conditions while maintaining consistency with long-term financial stability.
The foundation lies in **dynamic pricing calibration**, where historical data is cross-referenced with external factors like inflation rates, economic indicators, and regional risk trends. For instance, Allstate’s proprietary **RiskView®** platform integrates weather data, crime statistics, and infrastructure reports to adjust premiums for geographic areas where flood or theft risks have spiked. Below are key methodologies employed:
Data-Driven Actuarial Recalibration
Allstate’s actuarial teams use statistical models to detect anomalies in historical quote data, such as sudden spikes in premiums for specific vehicle models or age groups. These insights trigger recalibrations in pricing algorithms, ensuring quotes remain competitive without compromising profitability. For example:
- **Seasonal adjustments**: Historical data reveals that winter months correlate with higher auto claim frequencies in snowy regions, prompting Allstate to dynamically increase premiums for winter-specific coverage options.
- **Telematics integration**: By analyzing historical quote abandonment rates tied to telematics device installation (e.g., Drivewise®), Allstate identifies friction points in the onboarding process, leading to streamlined digital workflows that reduce drop-offs by 15%.
Loss Ratio Analysis and Premium Optimization
Allstate’s pricing models incorporate **loss ratio analysis**, which compares historical claim costs to premiums collected. If data shows that a particular driver segment (e.g., young male drivers in urban areas) consistently yields higher loss ratios, the system automatically adjusts quotes to reflect this risk. This is exemplified in:
- **Tiered discount structures**: Historical data reveals that customers who bundle home and auto policies exhibit lower claim frequencies. Allstate’s quote engine prioritizes bundling recommendations, increasing cross-sell conversion rates by 22%.
- **Dynamic deductible suggestions**: For high-risk profiles identified via historical claims, the system suggests elevated deductibles during quote generation, balancing affordability with risk mitigation.
Historical quote data is not merely retrospective—it fuels **real-time predictive pricing**. Allstate’s models update every 24 hours, incorporating new claim trends and external data feeds to ensure quotes remain accurate within ±2% of the actuarial target.
Regional Customization in Allstate’s Quote Process: State-Specific Coverage and Risk Adaptations
Allstate’s quote engine dynamically adjusts policies based on jurisdictional laws, risk profiles, and demographic trends to ensure compliance and relevance. This regional tailoring extends beyond pricing to include mandatory coverages, liability thresholds, and even claim-handling protocols, reflecting variations in state insurance regulations and environmental hazards. For instance, coastal states like Florida and California require flood or earthquake endorsements, while states with strict no-fault laws (e.g., Michigan) mandate specific personal injury protection (PIP) minimums. The system integrates real-time data from state departments of insurance and actuarial models to balance affordability with regulatory obligations.
State-Specific Coverage Mandates and Risk Factor Adjustments
Allstate’s quote engine prioritizes compliance with state-specific insurance laws, which dictate minimum liability limits, uninsured motorist coverage, and optional endorsements. Key adjustments include:
- **Mandatory Coverages by State**:
No-Fault States (e.g., New York, Michigan): Quotes automatically include PIP coverage with state-mandated minimum limits (e.g., $50,000 per person in New York). Allstate’s system flags these requirements during the quote process and highlights them in the policy summary.
Fault-Based States (e.g., Texas, Georgia): Liability limits default to state minimums (e.g., $30K/$60K/$25K in Texas), but Allstate’s interface encourages customers to upgrade to higher limits via risk-based recommendations (e.g., "Your area has a 20% higher collision rate—consider $100K/$300K/$50K").
High-Risk States (e.g., Louisiana, Mississippi): Quotes for flood-prone areas include optional National Flood Insurance Program (NFIP) endorsements, with Allstate’s system pre-populating flood zones from FEMA data. Customers in these regions receive proactive alerts: "Your ZIP code is in a 100-year flood plain—explore flood insurance options."
Crime Rates: Urban areas with higher theft rates (e.g., Philadelphia, Baltimore) trigger recommendations for comprehensive coverage with lower deductibles.
Weather Vulnerabilities: States prone to hailstorms (e.g., Oklahoma, Kansas) see automatic adjustments to collision deductibles or windshield replacement coverage.
Traffic Density: Quotes in congested cities (e.g., Los Angeles, Chicago) include discounts for telematics programs (e.g., Drivewise) that monitor safe driving habits, as these programs reduce claims frequency.
Integration of State Insurance Regulations into Quote Templates
Allstate’s digital quote interface dynamically generates state-specific policy templates that reflect statutory requirements. For example:
**Florida-Specific Template Highlights**:
- Mandatory Coverages: $10K PIP, $10K PD (property damage), $10K BI (bodily injury) per person/accident.
- Optional Endorsements: Flood insurance (NFIP), personal injury protection (PIP) stack-up, and uninsured/underinsured motorist (UM/UIM) with state-mandated minimums.
- Risk Mitigation Flags: "Your county has a 35% higher hurricane exposure—consider wind mitigation discounts."
The system uses a tiered approach to ensure clarity:
Compliance Layer: All mandatory coverages are pre-selected and locked, with explanations provided via tooltips (e.g., "This coverage is required by Florida law to protect uninsured drivers.").
Risk Layer: State-specific risk factors (e.g., flood zones, crime rates) trigger dynamic recommendations, such as bundling home and auto policies for a 10% discount in hurricane-prone areas.
Customer Layer: Personalized suggestions based on driving history or property age (e.g., "Your 2005 model may qualify for classic car coverage with lower premiums.").
Comparison with National Insurers: Flexibility in Regional Adaptations
Compared to peers like Geico or State Farm, Allstate’s regional quote strategies emphasize granularity and proactive customer education. While competitors often standardize core offerings across states, Allstate’s approach includes:
**Key Differentiators**:
- Dynamic Compliance Checks: Allstate’s system cross-references state laws in real-time, unlike some insurers that rely on static regional templates.
- Localized Claim Handling: Quotes in California, for instance, include a "California-specific claims process" section, detailing the state’s 15-day notice requirement for bodily injury claims.
- Partnerships with State Agencies: Allstate collaborates with departments of insurance (e.g., Texas Department of Insurance) to update quote algorithms for legislative changes, such as Texas’ 2023 auto insurance reforms.
**Flexibility Metrics by Insurer**:
| Insurer | Regional Customization Depth | Compliance Automation | Customer Education Integration |
|---------------|-----------------------------|-----------------------|-------------------------------|
| Allstate | High (state + county-level) | Full (real-time) | High (in-quote tooltips) |
| Geico | Medium (state-level) | Partial (batch updates)| Low (static disclaimers) |
| State Farm | Medium-High (state + urban/rural) | Full (but delayed) | Medium (brochure links) |
| Progressive | Low (regional tiers) | Minimal | Low (generic FAQs) |
Allstate’s flexibility is further evidenced by its handling of emerging risks, such as wildfires in California or blizzards in the Midwest. For example, in 2023, Allstate adjusted quotes in Northern California by:
- Adding a "wildfire mitigation" section with discounts for defensible space certification.
- Bundling home and auto policies with a 15% discount for customers in high-risk zones.
Designing a Regional Quote Template: State-Specific Requirements
A standardized yet adaptable quote template for Allstate would incorporate the following elements to address state-specific needs:
**Core Template Structure**:
1. **State Header**: Displays the state name, flag, and a brief regulatory summary (e.g., "Florida: No-fault state with mandatory PIP").
2. **Mandatory Coverage Block**: Pre-filled with state minimums, with a collapsible "Why this coverage?" section explaining legal requirements.
3. **Risk Zone Indicator**: A color-coded map snippet (visually described) showing flood, fire, or crime risk levels, with hyperlinked risk profiles.
4. **Dynamic Discounts**: State-specific incentives (e.g., "Ohio: 5% discount for bundling home and auto").
5. **Claim Process Overview**: State-specific timelines and documentation requirements (e.g., "New York: 30-day notice for property damage claims").
6. **Local Agent Contact**: Direct link to a state-specific customer service line or regional office.
**Example: Texas Auto Quote Template**
State Law Summary:
"Texas requires $30K/$60K/$25K liability coverage. Optional UM/UIM is not mandated but highly recommended due to high uninsured rates (12.3% in 2023)."
Risk-Adjusted Pricing:
- Urban Areas (e.g., Houston): Higher collision deductibles ($500) due to traffic density, with a telematics discount option.
- Rural Areas (e.g., El Paso): Lower comprehensive deductibles ($250) with a "low-mileage" discount for customers driving <10K miles/year.
Localized Add-Ons:
- "Texas-specific endorsements" section with options for:
- Roadside Assistance: Mandatory in some rural counties.
- Rental Reimbursement: Customizable limits (e.g., $50/day vs. $75/day).
Claim Workflow:
"Texas requires accident reports filed within 10 days. Allstate provides a printable claim form with step-by-step instructions tailored to Texas law."
The template would also include a "State Resources" sidebar with links to:
- The Texas Department of Insurance’s policy guide.
- Localized claim forms (e.g., "Houston-specific vehicle towing protocol").
- Discount programs (e.g., "Texas Farm Bureau partnership for rural customers").
Allstate’s Non-Digital Quote Channels: Agents, Call Centers, and Mobile-Assisted Processes
Allstate maintains a multi-channel approach to insurance quoting, ensuring accessibility for customers who prefer or require human interaction or offline engagement. Beyond its robust digital platform, the company leverages agents, call centers, and mobile applications to deliver personalized, real-time quotes tailored to individual needs. This hybrid model accommodates diverse customer preferences, particularly among older demographics, high-net-worth individuals, or those navigating complex policy requirements.
The non-digital channels serve distinct purposes: agents provide localized expertise and trust-building relationships, call centers offer immediate support for urgent inquiries, and mobile apps bridge convenience with flexibility. Each channel is designed to mitigate friction points inherent in fully automated processes, such as data entry errors or unclear policy terms. Allstate’s integration of these channels reflects a strategic commitment to omnichannel consistency, where digital and offline experiences align seamlessly in terms of data accuracy, quote transparency, and customer journey continuity.
---
Agent-Assisted Quoting: Personalized Service Through Local Representatives
Allstate’s agent network operates as a cornerstone of its non-digital quoting infrastructure, providing a human touchpoint for customers who prioritize in-person or phone-based interactions. Agents—whether independent or company-owned—conduct quoting through structured workflows that combine proprietary tools with manual underwriting discretion. This approach is particularly valuable for customers with unique risk profiles, such as commercial clients, high-value property owners, or those seeking bundling options (e.g., home + auto).
The agent-assisted process begins with an initial consultation, where the agent gathers policy details via a structured questionnaire or verbal interview. This information is input into Allstate’s **Policy Administration System (PAS)**, which cross-references with the company’s underwriting guidelines and external data sources (e.g., credit bureaus, motor vehicle records). Agents then generate quotes using Allstate’s **Agent Portal**, a web-based tool that pulls real-time pricing from the company’s rating engines while allowing manual overrides for exceptions.
Allstate’s agents utilize a tiered underwriting approach, where standard risks are evaluated via automated rules, while non-standard risks (e.g., commercial properties, high-risk drivers) trigger manual review by underwriting specialists.
Key components of the agent-assisted process include:
- **Pre-quote validation**: Agents verify customer eligibility (e.g., residency, driving history) before proceeding.
- **Customized recommendations**: Agents suggest add-ons (e.g., roadside assistance, identity theft coverage) based on customer lifestyle data.
- **Documentation support**: Agents assist with proof submission (e.g., homeowner’s association records, business licenses) for complex policies.
- **Immediate policy issuance**: Approved quotes are often bound digitally (via e-signature) or mailed as a physical policy, with the agent facilitating next steps.
The agent channel excels in **trust-building** and **complex scenario handling**, though it may introduce variability in quote speed compared to digital channels. For example, a standard auto policy quote via an agent can take **10–30 minutes**, while a commercial property quote may extend to **1–2 hours** due to additional underwriting layers.
---
Call Center Quoting: Balancing Speed and Human Guidance
Allstate’s call centers serve as a hybrid channel, blending automated quote generators with live agent intervention for customers who prefer voice-based interactions. The process begins with an **IVR (Interactive Voice Response) system** that routes callers based on policy type (e.g., auto, home, life) and urgency (e.g., claims vs. quoting). For quoting inquiries, callers are directed to a **dedicated quote specialist**, who uses a **Computer-Telephony Integration (CTI) system** to pull customer data from Allstate’s databases.
The call center quoting workflow is optimized for efficiency, with specialists following a scripted but flexible approach:
1. **Customer identification**: Verification via account number, policy details, or personal information (e.g., date of birth).
2. **Risk assessment**: Specialists input data into Allstate’s **Call Center Quote Engine**, which applies rating algorithms similar to those used online but with real-time adjustments for verbal nuances (e.g., clarifying coverage gaps).
3. **Quote generation**: The system generates a preliminary quote, which the specialist reviews for accuracy and presents to the caller with explanations of premium components (e.g., deductibles, discounts).
4. **Upsell opportunities**: Specialists highlight complementary products (e.g., Allstate’s **Rental Reimbursement** or **Umbrella Policy**) based on the customer’s profile.
5. **Binding and next steps**: Approved quotes are bound electronically, with options for immediate enrollment or follow-up via mail.
Call centers leverage **predictive dialing** and **AI-assisted scripting** to reduce wait times, with average quote completion times ranging from **5–15 minutes** for standard policies. However, complex scenarios—such as multi-vehicle households or commercial policies—may require **15–45 minutes**, as specialists consult underwriting teams or reference manuals.
Allstate’s call centers achieve an **average first-call resolution rate of 72%** for quoting inquiries, according to internal 2023 performance metrics, indicating effective integration of automation and human judgment.
A critical differentiator for call centers is their ability to **resolve ambiguities in real time**. For instance, a customer unsure about flood coverage can receive immediate clarification from a specialist, whereas an online quote might require post-submission follow-up. This human element enhances **customer satisfaction scores**, particularly for first-time buyers or those transitioning from competitors.
---
Mobile App Quoting: Digital Convenience with Offline Fallbacks
Allstate’s **Allstate Mobile App** (available on iOS and Android) combines digital efficiency with features designed for offline or low-connectivity scenarios. The app supports quoting through a **hybrid model**:
- **Fully digital quotes**: Customers input data via the app’s forms, with real-time validation against Allstate’s systems (e.g., vehicle VIN verification, property address checks).
- **Agent-assisted via app**: Customers can initiate a live chat or call with an agent directly from the app, with the agent accessing the same data inputted by the customer.
- **QR code-enabled quoting**: Customers can scan a QR code at an agent’s office or during a home visit to auto-populate their profile into the app, reducing manual entry.
The mobile app’s quoting process mirrors the online experience but includes **offline capabilities**, such as:
- **Local storage of partial quotes**: Customers can save progress and complete quoting later when connectivity is restored.
- **Agent portals integrated**: Agents can view and edit customer-provided data in real time via the app’s **Agent Dashboard**, ensuring consistency between digital and offline interactions.
- **Voice input for accessibility**: Features like **Siri/Google Assistant integration** allow hands-free data entry for customers with mobility limitations.
Quote speed in the mobile app is comparable to the online channel, with **standard auto quotes generated in under 2 minutes** and home quotes in **3–5 minutes**. However, the app’s strength lies in its **seamless handoff to offline support**. For example:
- A customer may start quoting online but switch to the app mid-process to call an agent for clarification.
- An agent visiting a customer’s home can use the app to pull up the customer’s profile and generate a quote on-site, with the customer reviewing and signing via the app’s e-signature tool.
Allstate’s mobile app saw a **30% increase in quote completions** in 2023 among users who engaged with both digital and offline channels (e.g., app + agent follow-up), per internal app analytics.
---
Bridging Digital and Offline Quote Methods: Integration Strategies
Allstate employs several mechanisms to ensure continuity between digital and non-digital quoting channels, minimizing customer friction and data silos. These strategies include:
**1. Unified Customer Profiles**
Allstate’s **Customer Information System (CIS)** aggregates data across all channels, ensuring that a customer’s history—whether accessed online, via an agent, or over the phone—is consistent. For example:
- If a customer starts quoting online but later contacts an agent, the agent’s portal displays the customer’s partial quote data, reducing redundant input.
- Call center specialists can pull up a customer’s app activity (e.g., saved quotes, chat transcripts) to provide personalized follow-up.
**2. QR Code and NFC Technology**
Agents and call centers use **QR codes** to streamline data transfer between offline and digital channels:
- **Agent visits**: A customer’s homeowner’s policy details can be scanned via QR code during an in-person meeting, auto-populating the agent’s system for immediate quote generation.
- **Call center handoffs**: Customers calling from the mobile app can share a QR code with a specialist to verify their identity and policy status without repeating information.
**3. Agent Portals with Digital Backend Access**
Allstate’s **Agent Portal** integrates with the company’s **Policy Administration System (PAS)** and **Rating Engine**, allowing agents to:
- Generate quotes using the same algorithms as online channels but with manual overrides for exceptions.
- Access real-time underwriting decisions (e.g., approvals, denials) that align with digital outcomes.
- Export digital quotes to customers via email or SMS, with options to print or bind policies electronically.
**4. Omnichannel Chat and Callback Systems**
The mobile app and website feature **live chat options** that can escalate to agent-assisted quoting:
- A customer chatting online about a home insurance quote can request a callback from an agent, with the chat transcript automatically shared to the agent’s system.
- Call center specialists can initiate a **follow-up chat** with a customer who started quoting via the app, ensuring continuity.
**5. Data Synchronization for Multi-Channel Customers**
Allstate’s systems are designed to detect when a customer interacts across multiple channels. For instance:
- A customer who quotes online but later visits an agent’s office will see their digital quote history in the agent’s portal.
- Call center specialists can identify if a customer has previously engaged with the company via the mobile app and tailor their approach accordingly.
---
Comparative Analysis: Speed and Accuracy of Allstate’s Quote Methods
Allstate’s quote processes vary in speed and accuracy depending on the channel, with trade-offs between automation efficiency and human customization. Below is a comparative breakdown of key metrics and considerations for each method.
---
Speed of Quote Generation
The time required to generate a quote depends on the complexity of the policy, the customer’s data completeness, and the channel’s level of automation. Below is a general benchmark for standard policies (e.g., personal auto or homeowner’s insurance):
| **Quote Channel** | **Standard Policy Time** | **Complex Policy Time** | **Key Factors Affecting Speed** |
|-------------------------|-------------------------|-------------------------|----------------------------------------------------------|
| **Online (Self-Service)** | 1–3 minutes | 5–10 minutes | Data auto-validation, minimal manual input. |
| **Mobile App** | 2–4 minutes | 6–15 minutes | Offline storage, agent handoff options, voice input. |
| **Call Center** | 5–15 minutes | 15–45 minutes | IVR routing, specialist data entry, underwriting checks. |
| **Agent-Assisted** | 10–30 minutes | 1–2+ hours | Manual data collection, underwriting discretion, documentation review. |
Allstate’s online quoting system achieves an **average quote
Allstate’s Feedback Collection Mechanisms for Quote Process Optimization
Customer feedback is systematically gathered through a multi-channel approach to ensure continuous improvement of Allstate’s quote tool. This process integrates both qualitative and quantitative insights to identify friction points and opportunities for enhancement.
Feedback collection spans multiple touchpoints, ensuring a comprehensive understanding of user experience. The methods prioritize accessibility and relevance, allowing Allstate to act on real-time and long-term trends.
Structured Post-Interaction Surveys
Allstate employs targeted surveys immediately after users complete a quote request or abandon the process. These surveys are embedded within the quote tool or triggered via email, capturing critical moments when user sentiment is most acute.
- **In-tool surveys**: Deployed via pop-up or inline forms during or after quote completion, these surveys use a mix of multiple-choice and open-ended questions. Examples include:
- Net Promoter Score (NPS) questions to gauge overall satisfaction.
- Specific pain points (e.g., "How difficult was it to provide your vehicle details?").
- Time-on-task metrics to identify bottlenecks.
- **Post-abandonment surveys**: Triggered when users exit the quote tool prematurely, these surveys ask about the primary reason for abandonment (e.g., "The process took too long" or "Information was unclear").
- **Email follow-ups**: Sent within 24–48 hours post-interaction, these surveys include links to detailed feedback forms or invite users to participate in voice-of-customer (VoC) interviews.
Review Platforms and Third-Party Insights
Allstate monitors external review platforms to capture unfiltered user sentiment, complementing internal data. This includes:
- **Trustpilot, Google Reviews, and BBB ratings**: Aggregated reviews are analyzed for recurring themes related to the quote process, such as "slow response times" or "confusing questions."
- **Social media listening**: Tools like Brandwatch or Hootsuite track mentions of Allstate’s quote tool across platforms, flagging complaints or praise in real time.
- **Competitor benchmarking**: Regular comparisons with insurers like Geico or Progressive highlight gaps or strengths in Allstate’s approach, informing iterative updates.
Direct User Interviews and Focus Groups
For deeper insights, Allstate conducts qualitative research through:
- **Voice-of-customer (VoC) interviews**: Conducted with a stratified sample of users (e.g., first-time quote takers vs. repeat customers) to explore motivations and frustrations in detail.
- **Focus groups**: Organized regionally to discuss specific pain points, such as local regulatory complexities or cultural preferences in quote interactions.
- **Usability testing sessions**: Observing users as they navigate the quote tool, with analysts noting drop-off points, confusion, or inefficient workflows.
Analytics-Driven Feedback Loops
Allstate leverages behavioral data to infer feedback implicitly. Key methods include:
- **Heatmaps and session recordings**: Tools like Hotjar track user clicks, scrolls, and dwell times to identify confusing sections or overly complex fields.
- **Funnel analysis**: Examining drop-off rates at each stage of the quote process (e.g., vehicle details vs. coverage selection) to pinpoint conversion killers.
- **Clickstream data**: Analyzing which links or CTAs are most/least clicked to prioritize UI/UX adjustments.
*"Feedback isn’t just about fixing problems—it’s about anticipating needs before they become complaints. By combining structured surveys with real-time analytics, Allstate ensures its quote tool evolves with user expectations."*
Illustration of Allstate’s Quote Engine Architecture and Data Flow
Allstate’s quote engine is a multi-layered system designed to process user inputs, validate data, and generate accurate insurance quotes in real time. This architecture integrates proprietary risk assessment models, third-party data sources, and regulatory compliance checks to ensure precision and transparency. The system follows a modular approach, separating frontend user interactions from backend computation to optimize performance and scalability.
The architecture can be visualized through a **data flow diagram** that outlines how user inputs (e.g., ZIP code, vehicle details) traverse validation layers, pricing algorithms, and compliance checks before producing a final quote. Key components include:
- **Frontend Interface**: Handles user input via forms and displays results.
- **API Gateway**: Routes requests to appropriate services (e.g., validation, pricing).
- **Data Validation Layer**: Cross-checks inputs against regulatory databases (e.g., DMV records, state-specific rules).
- **Pricing Engine**: Applies Allstate’s proprietary algorithms to calculate premiums based on risk factors.
- **Compliance Module**: Ensures quotes adhere to state laws and internal policies.
- **Output Layer**: Formats the quote for display, including breakdowns and disclaimers.
---
Core Components of the Quote Engine
The engine relies on three primary subsystems:
**Input Validation Module**
This module processes raw user inputs (e.g., vehicle VIN, driver age) and performs real-time validation against external databases. For example, a ZIP code input is cross-referenced with the National Change of Address (NCOA) database to confirm address validity. Vehicle details are validated against the National Motor Vehicle Title Information System (NMVTIS) to verify authenticity and compliance with state emissions standards.
Validation Rules Example: If a user enters a VIN, the system checks for duplicates in the NMVTIS database to flag potential fraud or misreported vehicles.
**Risk Assessment Engine**
Allstate’s proprietary algorithms evaluate risk factors such as driver history, vehicle make/model, and location-based crime rates. These factors are weighted differently based on historical claim data. For instance, a 25-year-old driver in a high-theft ZIP code may face a higher premium due to statistical risk modeling.
Driver factors: Age, credit score (in states where permissible), driving record (e.g., at-fault accidents).
Geographic factors: Local crime rates, weather-related risks (e.g., hail in Texas), and urban vs. rural density.
**Pricing and Discount Engine**
Premiums are calculated using a tiered pricing model that incorporates base rates, discounts, and state-specific mandates. Discounts (e.g., safe driver, multi-policy) are applied dynamically. For example, bundling home and auto insurance may reduce the auto premium by 10–15%.
Pricing Formula (Simplified):Premium = BaseRate × (1 + RiskAdjustment) × (1 − Discounts)
Where RiskAdjustment is derived from the risk assessment engine and Discounts are applied post-validation.
---
Data Flow Diagram: User Input to Quote Output
The following represents a textual breakdown of the data flow, excluding visual elements but describing each step’s interaction:
1. **User Submission**
- User enters ZIP code, vehicle details (year/make/model), and driver information via the quote form.
- Inputs are immediately validated for completeness (e.g., required fields, format checks).
2. **Address and Vehicle Lookup**
- ZIP code triggers a geocoding API call to verify the address and retrieve location-based risk data (e.g., crime rates).
- Vehicle VIN (if provided) is queried against NMVTIS to confirm ownership and vehicle history (e.g., salvage title).
3. **Driver Profile Validation**
- Driver age and credit score (where permissible) are cross-referenced with internal databases to assess risk.
- Driving record is pulled from state DMV databases (via third-party providers like LexisNexis).
4. **Risk Scoring**
- Collected data is fed into Allstate’s risk scoring model, which assigns a numerical risk score to each input factor.
- Example: A driver with a single at-fault accident in the last 3 years may receive a +15% risk adjustment.
5. **Discount Application**
- The system checks for eligible discounts (e.g., good student, low mileage) and applies them to the base premium.
6. **State-Specific Adjustments**
- Premiums are adjusted to comply with state mandates (e.g., minimum liability coverage in California).
- Local regulations (e.g., no-fault laws in New York) are enforced to ensure quote accuracy.
7. **Quote Generation**
- The final premium is calculated and formatted into a structured quote, including:
- Total annual premium.
- Monthly payment estimate.
- Breakdown of coverage components (liability, collision, etc.).
- Disclaimers and exclusions.
8. **Output Rendering**
- The quote is displayed on the frontend with interactive elements (e.g., "Edit Quote," "Get Instant Discounts").
- Trust badges (e.g., "A+ Rating by AM Best") and customer testimonials are dynamically inserted to reinforce credibility.
---
Technical Stack and Integration Points
Allstate’s quote engine leverages a hybrid architecture combining on-premise systems and cloud-based services:
**Frontend Layer**
Built on React.js for dynamic user interactions, with real-time validation via JavaScript libraries (e.g., Formik for form handling). The frontend communicates with backend services via RESTful APIs.
**Backend Services**
Microservices handle specific functions:
Validation Service: Uses AWS Lambda for lightweight, serverless validation checks.
Pricing Service: Deployed on Kubernetes clusters for scalability, with caching (Redis) to optimize repeated queries.
Compliance Service: Integrates with state-specific APIs to enforce local regulations.
**Data Sources**
Third-party integrations include:
DMV databases for driver records (via LexisNexis).
NMVTIS for vehicle history.
Crime data APIs (e.g., FBI Uniform Crime Reporting).
Weather APIs (e.g., NOAA) for location-based risk factors.
**Security and Compliance**
Data encryption (TLS 1.3) secures transmissions, while PCI-DSS compliance ensures payment processing safety. Audit logs track all quote generation events for regulatory purposes.
Allstate’s quote process stands as a model of how insurance providers can merge technical sophistication with user accessibility. By integrating predictive analytics, regional compliance, and iterative improvements based on customer feedback, the system transforms a seemingly mundane task—requesting a quote—into a strategic interaction. For insurers, the insights gleaned from this process highlight the importance of adaptability: whether adjusting for state-specific regulations, refining UI/UX to reduce friction, or leveraging AI to detect fraud. Ultimately, Allstate’s approach demonstrates that a well-designed quote system isn’t just about efficiency; it’s about fostering trust, clarity, and confidence at every step of the customer’s journey.
As digital and offline methods continue to converge, the future of insurance quotes will likely prioritize even greater personalization and transparency. Allstate’s current framework—rooted in data-driven decisions, compliance, and continuous optimization—serves as a blueprint. For customers, this means faster, more accurate quotes tailored to their unique circumstances, while for insurers, it underscores the value of treating the quote process as a critical component of the entire customer lifecycle. The evolution of these systems will depend on how well they can anticipate needs, mitigate risks, and turn initial interactions into lasting relationships.
Allstate Auto Insurance Review for 2026 AutoinsuranceEZ.com
Frequently Asked Questions
How long does it take to get an Allstate car insurance quote?
Typically, obtaining an Allstate car insurance quote takes 5 to 15 minutes. The time depends on data availability, vehicle details, and personal information provided. Online quotes are usually instant if all fields are completed accurately
Can I get an Allstate home insurance quote online?
Yes, Allstate provides home insurance quotes online through its official website. Users can compare rates, customize coverage, and receive instant estimates without visiting an agent. Mobile apps also support this process
Does Allstate require a credit check for insurance quotes?
Allstate may perform a credit check as part of the underwriting process for quotes in most states. Credit scores influence premiums but are not always required for an initial estimate. State laws vary, affecting credit usage
What discounts does Allstate offer when getting a quote?
Allstate offers discounts like bundling policies, safe driver, multi-policy, and anti-theft device incentives. Discounts vary by state and policy type. Users can review eligible discounts during the quote process or via an agent
How accurate are Allstate’s online insurance quotes?
Allstate’s online quotes are generally accurate but may vary slightly from final premiums due to underwriting adjustments. Factors like driving records or home details can alter final costs. A final quote confirms exact pricing
Can I modify my Allstate insurance quote after submission?
Yes, users can adjust coverage, deductibles, or discounts during the quote process. Changes may impact the final rate. Finalizing a quote locks in rates, but policy adjustments can be made later with an agent or online