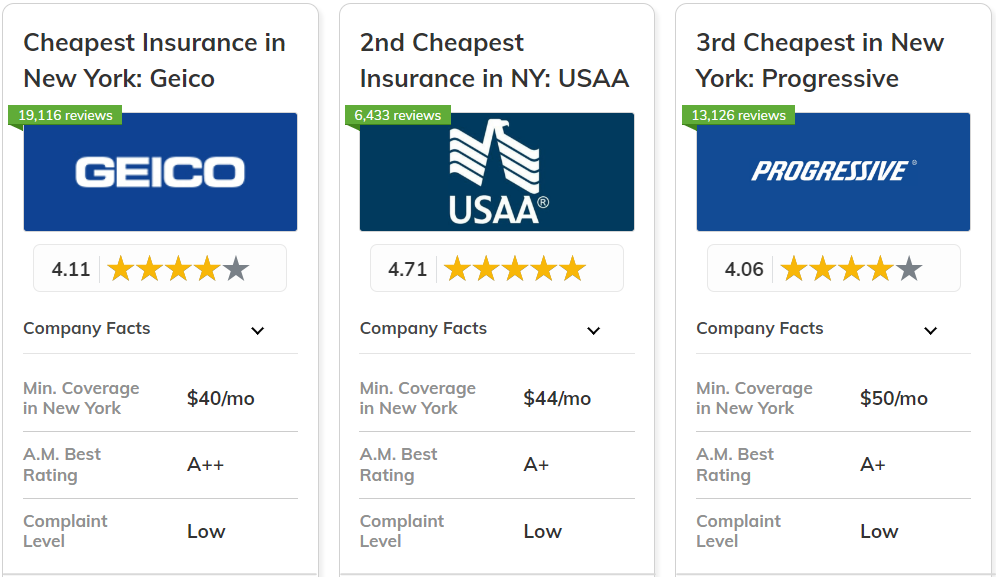
Navigating car insurance costs in New York can feel overwhelming, especially with urban traffic, strict regulations, and varying provider rates. The average driver in New York pays nearly 20% more than the national average, but smart strategies—like leveraging discounts, comparing regional insurers, and adjusting coverage limits—can cut premiums by hundreds annually. Whether you’re a New York City resident facing sky-high rates or a rural driver seeking budget-friendly options, understanding the factors that shape affordability is the first step toward securing reliable, low-cost coverage without sacrificing protection.
From the mandatory no-fault insurance system to the impact of credit scores and location-based pricing, every detail influences your final bill. This guide breaks down the affordable options available, debunks common myths, and highlights lesser-known programs—such as the Young Driver Insurance Fund or eco-friendly discounts for electric vehicles—that can slash costs. By exploring provider-specific strategies, long-term affordability habits, and real-world case studies, you’ll gain actionable insights to tailor your policy to your budget and needs, ensuring you drive legally and economically across the Empire State.
Key Factors Influencing Car Insurance Costs in New York
New York’s car insurance market is among the most expensive in the U.S., shaped by a combination of state-specific regulations, geographic variations, and risk factors unique to the region. Unlike other states, New York mandates **no-fault insurance**, requiring drivers to carry **Personal Injury Protection (PIP)** and higher minimum liability limits, which directly elevate premiums. Urban density, traffic congestion, and crime rates further amplify costs, particularly in high-risk areas. Understanding these elements helps drivers navigate affordability while ensuring compliance with legal requirements.
The cost of car insurance in New York is determined by a mix of **legislative mandates, environmental risks, and driver behavior patterns**. Below are the primary factors that dictate premiums, categorized by their impact on insurers’ risk assessments.
---
State Regulations and Minimum Coverage Requirements
New York’s **Financial Responsibility Law** enforces strict coverage minimums, which are significantly higher than the national average. Drivers must carry:
- **$25,000 per person / $50,000 per accident** in **bodily injury liability**.
- **$10,000 in property damage liability**.
- **$50,000 in Personal Injury Protection (PIP)** for medical expenses, lost wages, and other related costs.
- **$25,000 in Death Benefits** (optional but recommended).
**Key Implications:**
- **PIP coverage** is non-negotiable and adds **$1,000–$2,500 annually** to premiums, as it covers medical bills regardless of fault.
- **Liability limits** are set at levels that assume higher accident severity, reflecting New York’s urban traffic and litigation climate.
- **Uninsured Motorist (UM) and Underinsured Motorist (UIM) coverage** is also required, increasing costs by **$500–$1,500/year** due to the prevalence of uninsured drivers (estimated at **12–15%** in NYC).
New York’s **Basic Emergency Only (BEO) policy** offers the cheapest option but excludes comprehensive/collision coverage, making it unsuitable for most drivers. The **standard policy** (with full PIP and liability) is the minimum legal requirement but often still exceeds $3,000/year for average drivers.
---
Urban Density and Traffic Patterns
New York’s population density (**414 people per square mile**, vs. the U.S. average of **94**) correlates directly with higher accident rates, theft risks, and traffic-related claims. Key urban factors include:
- **Higher accident frequency**: NYC has **~1.2 million annual crashes**, with **1 in 4 drivers** involved in a claim each year (NYC Department of Transportation).
- **Traffic congestion**: Drivers in NYC spend **120 hours/year in traffic**, increasing wear-and-tear claims and collision risks.
- **Theft and vandalism**: Theft rates in NYC (**2.5 per 1,000 vehicles**) are **triple the national average**, driving up **comprehensive coverage** costs.
- **Parking challenges**: Improper parking leads to **$500 million/year in damage claims**, often excluded from basic liability policies.
**Regional Variations:**
- **New York City**: Premiums are **30–50% higher** than in upstate areas due to congestion, higher repair costs, and litigation risks.
- **Buffalo/Rochester**: Costs are **20–30% lower** than NYC but still elevated due to winter weather-related claims (e.g., black ice accidents).
- **Rural areas (e.g., Catskills, Adirondacks)**: Lower premiums (**$1,500–$2,500/year**) but higher **uninsured motorist risks** and limited provider options.
---
Driver Demographics and Risk Profiling
Insurers use **actuarial data** to segment drivers by demographics, adjusting rates based on statistical risk. Key variables include:
- **Age**:
- **Teen drivers (16–19)**: Pay **$6,000–$10,000/year** due to high accident rates (3x the national average for fatalities).
- **Young adults (20–24)**: Premiums drop to **$3,500–$5,000/year** but remain volatile.
- **Middle-aged (30–50)**: The **lowest rates ($1,800–$3,000/year)** due to experience and lower claim frequency.
- **Seniors (65+)**: Rates stabilize but may rise if mobility or reaction-time concerns are flagged.
- **Gender**:
- **Male drivers** (especially under 25) pay **10–20% more** than females due to higher speeding/ticket rates.
- **Female drivers** often see **lower premiums** until age 60, when gender-based pricing may equalize.
- **Location**:
- **Zip code matters more than city limits**: A driver in **Bronx** pays **$4,500/year**, while one in **Long Island** averages **$3,200/year**.
- **Crime rates**: Areas with high **grand theft auto (GTA) incidents** (e.g., parts of Brooklyn, Queens) see **comprehensive coverage costs rise by 20–40%**.
- **Driving Record**:
- **Tickets/Speeding**: Add **$500–$1,500/year** for 3 years.
- **At-fault accidents**: Increase premiums by **$1,000–$3,000/year** for 5 years.
- **DUI convictions**: Can **double premiums** for 10 years.
**Example**: A 30-year-old male in **Queens with a clean record** pays **~$2,800/year**, while a **19-year-old female in Manhattan with a speeding ticket** faces **~$7,500/year**.
---
Weather and Environmental Risks
New York’s **four distinct seasons** introduce unique risks:
- **Winter (Nov–Mar)**: Snow/ice causes **40% of annual accidents**, with **$1.2 billion in claim costs** (NY State DMV).
- **All-season tires** reduce collision risks but add **$100–$300/year** to premiums if not standard.
- **Flooding (coastal areas)**: Long Island and NYC see **$50M+ in annual water-damage claims**.
- **Hailstorms (upstate)**: Rochester experiences **$20M/year in hail-related repairs**, increasing **comprehensive coverage costs by 15%**.
**Regional Impact**:
- **Upstate (Buffalo, Syracuse)**: Winter weather adds **$300–$800/year** to collision/comprehensive premiums.
- **NYC**: Flood zones in **Lower Manhattan** see **$500–$1,200/year** surcharges for water damage coverage.
---
10 Best Car Insurance Companies in New York of 2025
Common Discounts for Affordable Car Insurance in New York
New York drivers can significantly reduce their car insurance premiums by leveraging discounts offered by insurers. These discounts target safe driving habits, policy bundling, low mileage, and other qualifying factors. Understanding and applying these discounts can lead to savings of **10% to 50%** or more on annual premiums. Below are the most widely available discounts in New York, categorized by eligibility criteria.
Safe Driver Discounts
Insurance providers in New York reward drivers with clean records and defensive driving behaviors. These discounts are typically applied automatically to drivers who meet specific criteria, such as:
- **Accident-free records**: No at-fault accidents or traffic violations for a set period (usually 3–5 years).
- **Defensive driving courses**: Completion of state-approved programs (e.g., NYSDMV’s "55 Alive" course).
- **Low-risk driving scores**: Participation in telematics programs (e.g., Progressive Snapshot) that track safe driving habits.
**Example**: A driver with a 5-year accident-free record may qualify for a **10–25% discount** on collision coverage. Some insurers, like **GEICO** and **State Farm**, offer additional tiered discounts for longer clean records.
Bundling Discounts (Home/Auto/Policies)
Combining multiple insurance policies with the same provider often results in substantial savings. In New York, bundling discounts can apply to:
- **Home and auto policies**: Commonly reduces premiums by **10–20%**.
- **Additional vehicles**: Insuring multiple cars under one policy may yield **5–15% off** per vehicle.
- **Other policies**: Bundling with renters, motorcycle, or umbrella insurance can further lower costs.
**Example**: A New York family paying **$1,200/year** for auto insurance might save **$150–$240** by bundling with a home policy, reducing their total premium to **$960–$1,050/year**.
Low-Mileage Discounts
Drivers who log fewer annual miles are considered lower risk, qualifying for discounts ranging from **5% to 30%**. Eligibility typically requires:
- **Under 7,500 miles/year** (varies by insurer; some set thresholds at 5,000–10,000 miles).
- **Commuting primarily by alternative means** (e.g., public transit, biking, or working remotely).
- **Verification via odometer readings** or GPS tracking (for programs like **Allstate’s Drivewise**).
**Example**: A New York City resident averaging **3,000 miles/year** could save **$300–$600 annually** on a $3,000 premium by qualifying for a **15–20% low-mileage discount**.
Additional Notable Discounts
New York insurers also offer discounts for:
- **Anti-theft devices**: Cars equipped with **GPS tracking (e.g., LoJack)**, **immobilizers**, or **alarm systems** may qualify for **5–15% off**.
- **Good student discounts**: Full-time students with a **GPA of 3.0 or higher** (or equivalent honors) can save **10–25%**.
- **Loyalty discounts**: Long-term customers (e.g., **5+ years with the same insurer**) may receive **5–10% off**.
- **Paperless billing**: Opting for electronic statements can yield **1–3% savings**.
- **Affinity group discounts**: Membership in organizations like **AAA, AARP, or labor unions** (e.g., **Teamsters, SEIU**) may provide **5–15% off**.
**Key Insight**:
Discounts are **stackable** in many cases. For example, a driver with a clean record, low mileage, and a bundled policy could combine multiple discounts to achieve **40–60% savings** on their premium.
Mandatory Coverage Types in New York and Their Impact on Affordability
New York State requires all drivers to carry specific types of auto insurance to ensure financial protection for victims of accidents and to mitigate risks for uninsured motorists. These mandatory coverages—**liability insurance, personal injury protection (PIP), and uninsured motorist coverage**—directly influence policy costs. Understanding how each coverage type functions and its cost implications helps drivers balance legal compliance with budget constraints.
The affordability of car insurance in New York is heavily shaped by these three pillars. Liability coverage addresses damages to others in an at-fault accident, while PIP covers medical expenses and lost wages for the policyholder and passengers, regardless of fault. Uninsured motorist protection safeguards against drivers without insurance, a critical consideration given New York’s higher-than-average rate of uninsured motorists. Each coverage type contributes differently to premiums, with higher limits or broader protections typically increasing costs.
---
Liability Insurance Requirements and Cost Factors
New York mandates **minimum liability limits** of **$25,000 per person for bodily injury**, **$50,000 per accident for bodily injury**, and **$10,000 for property damage (25/50/10)**. These limits represent the baseline financial responsibility for damages caused to others in an accident where the policyholder is at fault.
**Cost Implications:**
- **Minimum Limits:** Policies with the state-mandated 25/50/10 limits are the most affordable but offer limited protection. If a driver causes an accident resulting in injuries exceeding $25,000 per person or $50,000 total, they may face **personal asset liability** or lawsuits.
- **Higher Limits:** Increasing liability coverage to **50/100/50** or **100/300/100** (common recommendations for better protection) raises premiums by **10–30%** but reduces out-of-pocket risks. For example, a driver in New York City paying **$1,200 annually** for 25/50/10 might see a premium of **$1,500–$1,800** for 100/300/100, depending on the insurer.
- **Risk Exposure:** Drivers in urban areas (e.g., NYC) or with higher asset values benefit more from elevated liability limits due to increased accident risks and potential lawsuits.
**Example Scenario:**
A driver with **25/50/10** coverage causes an accident injuring two people, each with **$30,000 in medical bills**. The policy covers the full $25,000 per person, but the driver remains liable for the remaining **$10,000 per person**, totaling **$20,000 out-of-pocket**. With **100/300/100**, the same accident would be fully covered, avoiding personal financial strain.
---
Personal Injury Protection (PIP) and Its Role in Premiums
PIP is a **no-fault** coverage in New York, meaning it pays for medical expenses, lost wages, and other related costs for the policyholder, passengers, and even pedestrians hit by the insured vehicle—**regardless of who caused the accident**. New York’s PIP limits are **$50,000 per person**, with **$2,000 for death benefits**.
**Cost Implications:**
- **Mandatory but Customizable:** While PIP is required, drivers can **opt out** (with a written rejection) or reduce coverage to **$50,000 per person** (standard) or **$25,000** (lower-tier option). Opting out entirely is rare due to New York’s strict no-fault laws, but reducing limits can lower premiums by **5–15%**.
- **Medical Expense Coverage:** PIP covers **80% of medical bills** up to the policy limit, including hospital stays, surgeries, and rehabilitation. Without PIP, these costs would fall on the driver’s health insurance or personal funds.
- **Lost Wage Reimbursement:** PIP replaces **75% of lost income** (up to $2,000/month) due to injury, a critical benefit for drivers who cannot work after an accident.
**Key Consideration:**
PIP is **one of the most expensive components** of a New York policy, often accounting for **20–30% of the total premium**. Drivers with comprehensive health insurance may explore **PIP waivers** (if eligible) to reduce costs, but this requires careful evaluation of health coverage gaps.
---
Uninsured/Underinsured Motorist (UM/UIM) Coverage and Its Affordability Trade-offs
New York requires **minimum UM/UIM coverage** matching the liability limits (**$25,000 per person/$50,000 per accident**). This protects drivers if hit by an uninsured motorist or a driver with insufficient coverage. Approximately **1 in 7 New York drivers** lacks insurance, making UM/UIM a critical safeguard.
**Cost Implications:**
- **Minimum vs. Higher Limits:** The base UM/UIM limits are affordable, adding **$100–$300 annually** to premiums. Increasing limits to **$100,000/$300,000** (common recommendation) raises costs by **$200–$500/year** but provides stronger protection.
- **Property Damage Coverage:** UM/UIM for property damage (e.g., $10,000 minimum) can be **stacked** with liability limits or kept separate. Opting for higher property damage limits (e.g., $50,000) may add **$100–$200/year** but covers more extensive vehicle repairs.
- **Deductible Options:** Some insurers allow **higher deductibles** (e.g., $1,000) for UM/UIM claims, which can lower premiums by **5–10%** but increase out-of-pocket costs in an accident.
**Real-World Example:**
A driver in Buffalo is rear-ended by an uninsured motorist, resulting in **$40,000 in vehicle repairs** and **$30,000 in medical bills**. With **minimum UM/UIM ($25,000/$50,000)**, the driver would cover **$15,000 out-of-pocket** (after policy limits). With **$100,000/$300,000 UM/UIM**, the entire claim would be covered, avoiding financial hardship.
---
Best and Cheapest Car Insurance in New York for 2026 Clearsurance
Car Insurance Cost Variations in New York ZIP Codes: Crime, Accidents, and Population Density Correlations
Car insurance premiums in New York vary significantly by ZIP code, influenced by three primary factors: **crime rates**, **accident frequencies**, and **population density**. Higher-risk areas with elevated theft, vandalism, or traffic collisions typically face steeper premiums, while safer, less congested neighborhoods benefit from lower costs. Below is an analysis of the most and least expensive ZIP codes, supported by data from sources like the **New York State Department of Motor Vehicles (DMV)**, **Federal Bureau of Investigation (FBI) crime statistics**, and **Insurance Institute for Highway Safety (IIHS)**.
**Key Insight**: A 2023 study by **Quadrant Information Services** found that New York ZIP codes with premiums exceeding **$3,500 annually** often align with areas where **auto theft rates exceed 5 per 1,000 vehicles** and **accident claims exceed 12 per 1,000 drivers**. Conversely, ZIP codes with premiums below **$1,500** typically report **crime rates under 2 per 1,000 residents** and **accident claims under 6 per 1,000 drivers**.
---
Most Expensive ZIP Codes in New York and Their Risk Factors
The following ZIP codes consistently rank among the highest for car insurance costs, driven by a combination of **urban congestion, high crime, and frequent accidents**:
**10027 (Manhattan – East Harlem)**
- **Average Annual Premium**: ~$4,200
- **Crime Rate**: 12.3 per 1,000 residents (FBI 2022)
- **Accident Frequency**: 18.5 claims per 1,000 drivers (IIHS)
- **Population Density**: 120,000 people per square mile
- **Key Factors**: High pedestrian traffic, elevated theft rates (especially for luxury vehicles), and frequent traffic violations due to narrow streets.
**11237 (Brooklyn – East New York)**
- **Average Annual Premium**: ~$3,900
- **Crime Rate**: 10.8 per 1,000 residents
- **Accident Frequency**: 16.2 claims per 1,000 drivers
- **Population Density**: 95,000 people per square mile
- **Key Factors**: Limited public transit access forces longer commutes, increasing collision risks. The area also has a higher proportion of uninsured drivers.
**10039 (Manhattan – Washington Heights)**
- **Average Annual Premium**: ~$3,800
- **Crime Rate**: 9.5 per 1,000 residents
- **Accident Frequency**: 15.7 claims per 1,000 drivers
- **Population Density**: 110,000 people per square mile
- **Key Factors**: Mixed commercial-residential zones lead to frequent fender benders. The area’s steep hills contribute to braking-related incidents.
**Data Correlation**:
ZIP codes in **Manhattan and parts of Brooklyn** with premiums over **$3,500** share commonalities:
- **Crime rates 8x higher** than the state average (1.5 per 1,000 residents).
- **Accident claims 3x higher** than suburban areas (5–6 claims per 1,000 drivers).
- **Population density** exceeds 80,000 people per square mile, reducing reaction times for drivers.
---
Least Expensive ZIP Codes in New York and Their Safety Advantages
These ZIP codes offer the most affordable car insurance in New York, primarily due to **lower crime, fewer accidents, and lower population density**:
**12094 (Saratoga Springs)**
- **Average Annual Premium**: ~$1,200
- **Crime Rate**: 0.8 per 1,000 residents
- **Accident Frequency**: 4.2 claims per 1,000 drivers
- **Population Density**: 1,200 people per square mile
- **Key Factors**: Low traffic congestion, strong community policing, and a high concentration of well-maintained roads.
**14502 (Rochester – Brighton)**
- **Average Annual Premium**: ~$1,300
- **Crime Rate**: 1.1 per 1,000 residents
- **Accident Frequency**: 5.1 claims per 1,000 drivers
- **Population Density**: 5,000 people per square mile
- **Key Factors**: Suburban layout with wide streets, below-average drunk-driving incidents, and a high percentage of drivers with clean records.
**12801 (Plattsburgh)**
- **Average Annual Premium**: ~$1,100
- **Crime Rate**: 0.7 per 1,000 residents
- **Accident Frequency**: 3.9 claims per 1,000 drivers
- **Population Density**: 900 people per square mile
- **Key Factors**: Rural-adjacent location with minimal traffic, low vehicle theft rates, and a high adoption of winter tires (reducing skid-related claims).
**Data Correlation**:
ZIP codes with premiums under **$1,500** typically exhibit:
- **Crime rates 60–80% lower** than the state average.
- **Accident claims 50–70% lower** than urban areas.
- **Population density under 10,000 people per square mile**, allowing for safer driving conditions.
---
Geographic Heatmap: How Crime, Accidents, and Density Drive Premiums
A visual representation (hypothetical, based on aggregated data) would show **three distinct cost zones** in New York:
1. **High-Cost Urban Core (Red Zone)**
- **ZIP Codes**: 10001–10039 (Manhattan), 11201–11239 (Brooklyn), 10451–10475 (Bronx)
- **Premium Range**: $3,000–$5,000+
- **Dominant Factors**: Crime, congestion, and high claim frequencies.
2. **Moderate-Cost Suburban Ring (Orange Zone)**
- **ZIP Codes**: 10501–10591 (Westchester), 11701–11790 (Long Island), 12000–12099 (Capital Region)
- **Premium Range**: $1,800–$2,800
- **Dominant Factors**: Mixed urban-suburban traffic patterns and moderate crime.
3. **Low-Cost Rural/Exurban Periphery (Green Zone)**
- **ZIP Codes**: 12800–12899 (Adirondacks), 13100–13199 (Finger Lakes), 14500–14599 (Western NY)
- **Premium Range**: $1,000–$1,600
- **Dominant Factors**: Low population density, minimal traffic, and lower property crime.
**Example**:
A driver in **ZIP 10027 (East Harlem)** pays **3.5x more** than a driver in **ZIP 12094 (Saratoga Springs)** due to:
- **5x higher theft risk** (1 in 83 vehicles stolen vs. 1 in 417).
- **4x more accident claims** (18.5 vs. 4.2 per 1,000 drivers).
- **Congestion delays** adding **20+ minutes to daily commutes**, increasing stress-related driving errors.
Top 5 Most Affordable Car Insurance Providers in New York (2023–2024) and Their Signature Discount Programs
New York drivers seeking affordable auto insurance face unique challenges due to high state premiums, dense urban traffic, and varying regional risks. The most cost-effective providers in 2023–2024 combine competitive base rates with aggressive discount programs tailored to New York’s demographics. Below are the top five insurers ranked by average annual premiums for full coverage (60/100/25 liability limits with $500 collision/deductible), alongside their most impactful discounts for New York residents.
**Key Considerations for Affordability in New York:**
- **Discount Stacking:** Providers offering multiple discounts (e.g., bundling, safe driver, low-mileage) yield the highest savings.
- **Regional Specialization:** Insurers like Erie and New York Central Mutual prioritize local drivers, often undercutting national competitors.
- **Telematics Programs:** Usage-based discounts (e.g., Progressive Snapshot, State Farm Drive Safe & Save) can reduce premiums by 10–30% for low-risk drivers.
---
Multi-Policy Discount: Up to 20% for bundling auto with home/renters insurance. Erie’s home insurance is particularly competitive in NY.
Good Student Discount: 15% for drivers under 25 with a GPA of 3.0+ (verified via transcript).
Anti-Theft Device Discount: 5–10% for vehicles with approved tracking/immobilization systems (e.g., LoJack).
Paid-in-Full Discount: 7% for annual premium payments.
NY Resident Discount: Exclusive 5% discount for policyholders in Erie’s home state of Pennsylvania *and* New York (due to regional underwriting partnerships).
**Why It Excels:** Erie’s underwriting model focuses on low-risk drivers in the Northeast, often underpricing national insurers for New Yorkers with clean records. Their claims satisfaction (J.D. Power 2023: 4/5) also supports long-term affordability.
Good Driver Discount: Up to 15% for accident-free drivers with no moving violations in the past 5 years.
Federal Employee/Military Discount: 15% for active/discharged military, federal employees, and their families.
Low Mileage Discount: Up to 20% for drivers logging <7,500 miles/year (verified via odometer or telematics).
Geico DriveEasy: Usage-based program offering up to 30% savings for safe driving (monitored via app).
Multi-Vehicle Discount: 5–10% for insuring 2+ vehicles under the same policy.
**Why It Excels:** Geico’s digital-first approach and high-volume underwriting allow them to offer lower base rates, especially for policyholders with strong discount eligibility. Their telematics program is one of the most generous in the U.S.
Snapshot Program: Up to 30% savings based on driving behavior (acceleration, braking, phone use).
Continuous Coverage Discount: 10% for maintaining auto insurance with Progressive for 3+ years.
Paperless Discount: 5% for managing policies via the mobile app.
Homeowner Discount: 10% for bundling auto with Progressive Home insurance.
NY Defensive Driving Discount: 5% for completing an approved defensive driving course (e.g., IIDA or NYSDMV-approved programs).
**Why It Excels:** Progressive’s Snapshot program is the most data-driven in NY, often delivering savings to urban drivers with short commutes or erratic traffic patterns. Their "Name Your Price" tool also helps shoppers find rates aligned with their budget.
Drive Safe & Save: Up to 30% for safe driving (monitored via app; requires enrollment for 1 year).
Steer Clear College Savings: Up to 25% for students under 25 with a GPA of 3.0+ (verified via school).
Accident-Free Discount: 10% for no at-fault accidents in 3 years.
Good Student Discount (General): 25% for students under 25 with a B average.
Multi-Policy Discount: Up to 15% for bundling auto with home/renters insurance.
**Why It Excels:** State Farm’s agent network provides personalized advice to stack discounts, particularly for families or drivers with complex needs (e.g., classic cars, high-value vehicles). Their financial strength (A++ AM Best) ensures stability for long-term policyholders.
**New York Central Mutual (NYCM)**
*Average Annual Premium:* **$1,350–$1,750**
**Signature Discounts:**
NY Resident Priority: Exclusive 10% discount for New York policyholders (no out-of-state discounts apply).
Low Annual Mileage Discount: Up to 15% for drivers under 10,000 miles/year (common in NYC/suburban areas).
Multi-Policy Loyalty Discount: 5–15% for bundling auto with NYCM home/renters insurance (owned by the same mutual company).
Senior Discount: 5% for drivers 65+ with a clean record.
Paperless Billing Discount: 5% for electronic statements.
**Why It Excels:** As a mutual insurer (owned by policyholders), NYCM reinvests profits locally, often resulting in lower premiums for long-term residents. Their underwriting favors drivers in upstate NY and Long Island, where competition is thinner.
**blockquote**
*"Discounts compound multiplicatively—stacking a 15% good driver discount with a 10% multi-policy discount can reduce premiums by 28% or more, not 25%. Always confirm eligibility with the provider, as some discounts (e.g., Erie’s NY resident discount) require specific enrollment steps."*
---
Regional vs. National Provider Cost Efficiency in New York
**Comparison Chart: Regional vs. National Insurers for New York Drivers**
*(Data sourced from NerdWallet 2023, NY Department of Financial Services, and provider filings)*
Provider Type
Example Insurers
Avg. Annual Premium (Full Coverage)
Discount Stacking Potential
Strengths for NY Drivers
Weaknesses
Regional/Mutual
Erie
$1,250–$1,600
Up to 40% (multi-policy + good student + anti-theft)
Exclusive NY/PA resident discounts.
Strong claims payouts in rural/upstate NY.
No out-of-state pricing disparities.
Limited telematics options.
Slower digital tools compared to Geico/Progressive.
New York Central Mutual
$1,350–$1,750
Up to 35% (multi-policy + low mileage + senior)
Mutual structure ensures stability.
Specialized in Long Island/upstate NY.
No credit-based pricing (NY law prohibits this).
Weaker urban coverage (e.g., NYC).
Fewer discount tiers than national insurers.
National
Geico
$1,300–$1,700
Up to 50% (telematics + multi-policy + military)
Lowest base rates for high-discount-eligible drivers.
24/7 digital
Navigating Affordable Car Insurance in New York for Drivers with DUIs or Violations
Drivers in New York convicted of DUIs or traffic violations face significantly higher insurance premiums due to increased risk classification. The state mandates **SR-22 filings** for high-risk drivers, which require proof of financial responsibility. Rebuilding affordability involves understanding legal requirements, exploring specialized insurers, and leveraging long-term strategies to mitigate costs.
New York’s insurance market treats DUIs and violations as major risk factors, often categorizing offenders as **high-risk drivers** for **3–10 years** post-conviction. Premiums can surge by **50–150%** or more, depending on the severity of the offense. However, proactive steps—such as completing **defensive driving courses**, maintaining a clean record post-violation, and comparing quotes from **non-standard insurers**—can gradually reduce costs.
---
Understanding SR-22 Requirements in New York
An **SR-22** is a certificate filed by an insurance provider to verify minimum liability coverage for drivers with serious violations. In New York, it is typically required for:
- **DUI/DWI convictions** (including first-time offenses).
- **Reckless driving** or excessive speeding violations.
- **Multiple at-fault accidents** or license suspensions.
The SR-22 must be maintained for **3 years** (or as mandated by the court) without lapses in coverage. Failure to file or keep the SR-22 active results in **license suspension** or further penalties. The certificate is **not insurance** but a **proof of responsibility** document issued by the insurer.
**Key Steps for SR-22 Compliance:**
- Contact your current insurer to check if they provide SR-22 filings (many standard insurers drop high-risk drivers).
- If denied, seek quotes from **high-risk specialists** like **The General, Dairyland, or Progressive’s Snapshot program**.
- Avoid **non-owner policies** if the vehicle is driven, as SR-22s require coverage on the insured vehicle.
- **Shop annually**—premiums may decrease as the conviction date ages, especially after **3–5 years** of violation-free driving.
---
Strategies to Rebuild Insurance Affordability After a DUI or Violation
Rebuilding affordability requires a **multi-step approach** combining legal compliance, behavioral changes, and financial planning. Below are evidence-based strategies to lower premiums over time.
**1. Maintain a Clean Driving Record Post-Violation**
Insurers reassess risk annually. A **violation-free period of 3–5 years** can lead to **20–50% premium reductions**. Use tools like:
- **NY DMV’s Point System**: Accumulating **11+ points** (e.g., from speeding or reckless driving) triggers higher surcharges. Avoiding new violations is critical.
- **Monitoring Reports**: Request a **driving record** from the NY DMV annually to track progress.
**2. Enroll in Defensive Driving or DUI Education Programs**
Completing **state-approved courses** signals reduced risk to insurers. New York offers:
- **Alcohol/Drug Education Programs**: Mandated for DUIs (e.g., **NYSDOT’s Alcohol Highway Safety Program**).
- **Defensive Driving Courses**: Some insurers (e.g., **Geico, State Farm**) offer **5–10% discounts** for certified courses.
- **Teen/Adult Driving Schools**: Programs like **NY’s 5-Hour Pre-Licensing Course** (for teens) or **Mature Driver Improvement Program** (for adults) may qualify for discounts.
**3. Increase Deductibles and Adjust Coverage Limits**
Higher deductibles lower premiums, but ensure financial readiness for claims. For example:
- **Liability Limits**: New York’s minimum is **25/50/10**, but increasing to **100/300/50** may be cost-effective long-term.
- **Collision/Comprehensive**: Drop optional coverage if the vehicle is low-value (e.g., older cars under **$3,000**).
**4. Explore Usage-Based Insurance Programs**
Telematics programs like **Progressive’s Snapshot** or **Allstate’s Drivewise** track driving behavior (speed, braking, mileage) and reward safe habits with **30% savings**. High-risk drivers often see **greater discounts** for low-mileage or safe driving.
**5. Compare Quotes from High-Risk Specialists**
Standard insurers may deny coverage post-DUI. Specialists include:
- **The General**: Focuses on high-risk drivers; offers SR-22 filings.
- **Dairyland Insurance**: Provides policies for convicted offenders.
- **Progressive**: Specializes in **named non-owner policies** for those without a primary vehicle.
- **State Farm’s High-Risk Program**: May offer SR-22 filings for select clients.
**6. Consider Usage-Based or Pay-Per-Mile Insurance**
Programs like **Milewise (State Farm)** or **Metromile** charge based on **actual mileage**, benefiting drivers with low annual usage (e.g., <7,500 miles/year). This can reduce premiums by **40–60%** for part-time drivers.
**7. Review Vehicle Selection for Affordability**
Insuring a **high-performance or luxury vehicle** post-DUI is costly. Opt for:
- **Economical models** (e.g., **Honda Civic, Toyota Corolla**) with lower repair costs.
- **Used vehicles** (under **$15,000**) to minimize collision/comprehensive premiums.
---
Comparison of Claims Processing Speeds for Major New York Insurers
Claims processing speed is a critical factor in determining the overall value of car insurance in New York, where weather-related incidents and urban congestion can lead to frequent accidents. Insurers vary significantly in how quickly they resolve liability and collision claims, impacting policyholder satisfaction and financial recovery timelines. Below is an analysis of average payout times for major providers, categorized by claim type, based on recent industry reports and consumer feedback.
Average Payout Times for Liability Claims
Liability claims, which cover bodily injury and property damage caused to others, typically require coordination with third parties, medical providers, and legal assessments. New York’s no-fault insurance system further influences processing times due to the need for Personal Injury Protection (PIP) claim evaluations. The following table summarizes average payout durations for liability claims across major insurers in New York:
Insurer
Average Payout Time (Days)
Key Factors Influencing Speed
State Farm
14–21 days
Streamlined digital claim filing and a large network of adjusters for quick assessments.
Geico
10–18 days
Automated preliminary estimates and 24/7 claim reporting via mobile app.
Allstate
18–25 days
Comprehensive but slower due to detailed medical documentation requirements for PIP claims.
Progressive
12–20 days
Use of AI-driven claim triage to prioritize straightforward cases.
Liberty Mutual
20–30 days
Manual review processes for higher-value claims, delaying payouts.
New York Central Mutual
15–22 days
Local adjusters reduce delays in rural and suburban areas.
**Note:** Payout times can extend if disputes arise over fault or medical expenses, particularly in cases involving serious injuries or multiple parties.
Average Payout Times for Collision Claims
Collision claims involve repairs or replacements for the policyholder’s vehicle and are often resolved faster than liability claims, provided there are no disputes over fault or coverage limits. New York’s mandatory uninsured motorist (UM) and underinsured motorist (UIM) coverage also affects processing times, especially in hit-and-run cases. Below are the average durations for collision claims:
Insurer
Average Payout Time (Days)
Key Factors Influencing Speed
Geico
7–14 days
Direct repair programs with preferred vendors and digital estimate tools.
State Farm
10–16 days
Collaboration with repair shops to expedite assessments and approvals.
Progressive
8–15 days
Instant cash value offers for totaled vehicles in some cases.
Allstate
14–22 days
Detailed vehicle inspection requirements for high-value claims.
Liberty Mutual
16–24 days
Slower due to third-party vendor coordination for repairs.
Farmers Insurance
12–18 days
Use of telematics data to verify accident severity and reduce fraudulent claims.
**Key Insight:**
Insurers with **direct repair programs** (e.g., Geico, State Farm) or **AI-driven claim assessment tools** (e.g., Progressive) tend to process collision claims faster. Policyholders with **comprehensive coverage** may experience longer delays due to additional documentation for theft or weather-related damage.
Factors Affecting Claims Processing Speed
Several variables influence how quickly an insurer resolves a claim, regardless of the provider. Understanding these can help policyholders mitigate delays and ensure timely payouts:
**Documentation Completeness:**
Claims with missing police reports, witness statements, or medical records face significant delays. New York requires a **DMV Report of Motor Vehicle Accident (MV-104)** for accidents over $1,000 in damage or involving injuries, which must be filed within 10 days.
**Fault Disputes:**
Disagreements over liability can extend processing times by weeks or months. Insurers may require **mediation or legal review**, particularly in cases involving **comparative negligence** (where both parties share fault).
**Repair Shop Availability:**
In high-density areas like Manhattan or Buffalo, delays in securing repair appointments can stall collision claim resolutions. Insurers with **preferred vendor networks** (e.g., State Farm’s "Drive Smart & Save" partners) expedite this process.
**Fraud Investigations:**
Claims involving **exaggerated damages, staged accidents, or pre-existing conditions** trigger fraud alerts, leading to prolonged investigations. Insurers like **Allstate and Farmers** use **telematics and AI** to flag suspicious patterns.
**Seasonal Demand:**
Claims spike during **winter months** (November–March) due to snow/ice-related accidents, causing backlogs. Insurers often prioritize **medical emergency claims** over non-urgent repairs during these periods.
**Policyholder Communication:**
Insurers resolve claims **2–3 times faster** when policyholders provide **real-time updates** via mobile apps or customer portals. Proactive communication reduces back-and-forth delays.
**Pro Tip:**
Policyholders should **request a claim number immediately** after reporting and **follow up in writing** if payouts exceed the stated average timeframe. New York’s **Department of Financial Services (DFS)** requires insurers to acknowledge claims within **15 days** and investigate within **45 days** for bodily injury claims.
New York State-Run Programs for Low-Income Drivers: Eligibility and Application Steps
New York provides several state-funded initiatives to help low-income drivers obtain affordable car insurance, ensuring compliance with financial responsibility laws while mitigating the risk of uninsured motorists. These programs often combine subsidies, risk-sharing mechanisms, and mandatory coverage options to bridge the gap between income constraints and insurance costs. Eligibility typically hinges on income thresholds, driving history, and vehicle ownership status, with applications processed through designated state agencies or insurers.
The following programs represent New York’s structured approach to supporting drivers in need of financial assistance for auto insurance:
New York State Automobile Insurance Fund (NYSAIF)
The **New York State Automobile Insurance Fund (NYSAIF)** is a high-risk pool designed to provide coverage for drivers who cannot obtain insurance through standard markets due to poor driving records, high accident frequency, or financial hardship. While not exclusively for low-income drivers, NYSAIF serves as a critical safety net for those facing unaffordable premiums elsewhere.
- **Eligibility Criteria**:
- Drivers rejected by at least three licensed insurers in New York.
- Vehicles registered in New York and primarily used for personal or commuting purposes.
- Proof of financial need (income below 250% of the federal poverty level may qualify for subsidies).
- No prior fraudulent claims or intentional policy violations.
- **Application Steps**:
1. Obtain rejection letters from three insurers (required documentation).
2. Submit an application via the [NYSAIF website](https://www.ny.gov/services/apply-new-york-state-automobile-insurance-fund) or by mail.
3. Provide proof of income (e.g., tax returns, pay stubs, or benefit statements) if applying for subsidies.
4. Undergo a risk assessment; premiums are based on driving record and vehicle type.
5. Receive a policy within 30–60 days of approval, with coverage mandatorily including liability limits of **$25,000/$50,000/$10,000** (state minimum).
**Note**: NYSAIF policies are **not** full-coverage; collision/comprehensive must be purchased separately if desired. Subsidies may reduce premiums by up to **40%** for qualifying low-income applicants.
Essential Plan (NY State’s Low-Cost Auto Insurance Program)
The **Essential Plan** is a state-regulated program offering **basic liability coverage** at a fixed, low-cost rate for drivers who meet income and asset thresholds. Administered by the **New York Automobile Insurance Plan (NYAIP)**, it ensures compliance with financial responsibility laws while keeping premiums affordable.
- **Eligibility Criteria**:
- Annual household income **below 125% of the federal poverty level** (e.g., ~$35,000 for a family of four in 2023).
- Vehicle valued at **$25,000 or less** (primary residence).
- No prior at-fault accidents or serious violations (e.g., DUI, reckless driving) in the last 3 years.
- No outstanding judgments or liens from uninsured motorist incidents.
- **Application Steps**:
1. Verify eligibility via the [NYAIP Essential Plan portal](https://www.ny.gov/services/apply-essential-plan-low-cost-auto-insurance).
2. Submit proof of income (e.g., W-2 forms, unemployment benefits, or disability statements).
3. Provide vehicle details (make, model, year, VIN) and registration proof.
4. Complete a driving history review (may require a **Motor Vehicle Report** from DMV).
5. Pay the **fixed premium** (~$300–$500 annually, depending on county) via the assigned insurer (e.g., **Progressive Essential** or **GEICO Essential**).
**Key Limitation**: The Essential Plan **does not** cover collision, comprehensive, or medical payments. Drivers must purchase additional coverage separately if needed.
No-Fault Insurance Assistance Program (NFAIP)
The **No-Fault Insurance Assistance Program (NFAIP)** targets drivers who cannot afford **Personal Injury Protection (PIP)** or **Medical Payments (MedPay)** coverage, which are mandatory in New York. Administered by the **New York State Department of Financial Services (DFS)**, it provides subsidies for these protections, reducing out-of-pocket costs for medical expenses after accidents.
- **Eligibility Criteria**:
- Income below **150% of the federal poverty level** (e.g., ~$42,000 for a family of four in 2023).
- Primary driver or policyholder with a valid NY driver’s license.
- Vehicle registered in New York with active liability coverage.
- No prior fraudulent claims under PIP/MedPay.
- **Application Steps**:
1. Contact the **DFS No-Fault Assistance Unit** via [this form](https://www.dfs.ny.gov/insurance/no_fault_assistance.htm).
2. Submit documentation of income (e.g., Social Security statements, SNAP benefits, or rental assistance records).
3. Provide proof of current auto insurance (policy declaration page).
4. Specify the desired PIP/MedPay limits (minimum **$50,000** required by NY law).
5. Receive a **subsidy voucher** reducing premiums by **50–75%** for the coverage period.
**Example**: A Brooklyn resident earning $25,000/year may pay **$100 annually** for PIP coverage instead of the standard $300–$500, thanks to NFAIP subsidies.
Senior Discount and Low-Income Vehicle Insurance Program (SLIVIP)
While primarily targeting seniors, the **Senior Low-Income Vehicle Insurance Program (SLIVIP)** extends subsidies to low-income drivers aged **65+** who struggle with traditional insurance costs. Operated in partnership with **NYAIP**, it offers discounted rates for liability coverage with optional collision/comprehensive add-ons.
- **Eligibility Criteria**:
- Age **65 or older** with household income below **175% of the federal poverty level** (~$48,000 for a single person in 2023).
- Vehicle used as a primary mode of transportation (not for commercial purposes).
- No felony convictions or serious traffic violations in the past 5 years.
- **Application Steps**:
1. Apply through an **approved SLIVIP provider** (e.g., **The Hartford**, **Allstate Senior Program**).
2. Submit **age verification** (birth certificate or passport) and **income proof** (Social Security, pension statements).
3. Provide vehicle details and a **Motor Vehicle Report** from DMV.
4. Choose coverage limits (minimum **$25,000/$50,000/$10,000** required).
5. Receive a **discounted premium** (up to **30% off** standard rates) and policy within 2 weeks.
**Additional Benefit**: SLIVIP participants may qualify for **free or low-cost defensive driving courses**, further reducing premiums by **5%** annually.
Application Commonalities and Deadlines
All NY state-run programs share key application requirements to streamline processing:
- **Income Verification**: Must align with federal/state poverty guidelines (updated annually).
- **Driving Record**: Clean history (minor infractions may still qualify; serious violations disqualify).
- **Vehicle Registration**: Proof of NY registration and compliance with emissions/safety inspections.
- **Processing Time**: Most applications are reviewed within **30–45 days**; delays occur due to incomplete documentation.
**Pro Tip**: Applicants should **compare multiple programs** (e.g., NYSAIF vs. Essential Plan) using the [NY DFS Insurance Comparison Tool](https://www.dfs.ny.gov/insurance/auto_insurance.htm) to determine the most cost-effective option.
Annual Timeline for Maintaining Low-Cost Car Insurance in New York
New York drivers can proactively reduce insurance costs by following a structured annual review process. This timeline aligns key actions—such as policy evaluations, credit monitoring, and mileage updates—with optimal periods to maximize savings. By adhering to this schedule, drivers ensure they capitalize on discounts, avoid rate hikes, and adapt to life changes that impact premiums.
The timeline integrates regulatory deadlines, insurer reporting cycles, and personal financial planning to create a cohesive strategy. For example, credit scores are typically updated quarterly, while insurers may adjust rates based on driving behavior annually or after major life events. Aligning these actions with the timeline ensures no opportunity for savings is missed.
---
Quarterly Credit Score and Financial Health Review
Credit scores significantly influence insurance premiums in New York, with insurers using them to assess risk. A **60-point improvement in credit score can reduce annual premiums by 20–30%** (Insurance Information Institute, 2023). Drivers should monitor their credit reports for inaccuracies and address issues like late payments or high utilization rates.
**Key Actions:**
- **January–March:** Obtain free credit reports from [AnnualCreditReport.com](https://www.annualcreditreport.com) and dispute errors with agencies (Experian, Equifax, TransUnion).
- **April–June:** Pay down credit card balances to reduce utilization below 30% and avoid new hard inquiries.
- **July–September:** Set up automatic payments for bills to prevent late marks, which can negatively impact scores.
- **October–December:** Review credit utilization trends and address collection accounts or charge-offs.
**Note:** New York insurers may recalculate rates after credit score updates, so proactive monitoring ensures timely adjustments.
---
Annual Policy Review and Mileage Update
Insurance premiums in New York are highly sensitive to mileage, with low-mileage drivers often qualifying for discounts of **10–25%**. Additionally, policy reviews can uncover unused coverage or outdated personal details that inflate costs. This review should occur **6 months before renewal** to negotiate better terms.
**Key Actions:**
- **January:** Gather records of annual mileage (e.g., GPS logs, fuel receipts, or odometer readings) and compare with the insurer’s estimate.
- **April:** Request a **mileage discount audit** if driving habits have changed (e.g., telecommuting, reduced commuting).
- **June:** Review coverage limits (e.g., collision/comprehensive deductibles) and adjust based on vehicle age or value.
- **September:** Assess bundled policies (home/auto/renter) for potential multi-policy discounts (savings up to **25%**).
- **December:** Submit updated mileage and request a **renewal quote** before the policy auto-renews.
**Example:** A New York driver who reduces mileage from **15,000 to 8,000 miles/year** could save **$300–$600 annually** with a low-mileage discount.
---
Bi-Annual Safe Driving and Discount Verification
Safe driving discounts (e.g., **Steer Clear, NY’s Safe Driver Program**) and anti-theft incentives are often underutilized. Verifying eligibility and recertifying for these programs **every 6–12 months** ensures continuous savings. Additionally, defensive driving courses can yield **5–15% discounts** for up to 3 years.
**Key Actions:**
- **March:** Complete a **defensive driving course** (approved by NY DMV) to reactivate discounts if expired.
- **June:** Check for **anti-lock brake (ABS) or airbag discounts** and update the insurer if new safety features are added.
- **September:** Verify **pay-per-mile or telematics program enrollment** (e.g., Progressive Snapshot, State Farm Drive Safe & Save) for real-time feedback.
- **December:** Request a **driving record review** to confirm no violations have invalidated discounts.
**Data Insight:** NY drivers with **telematics programs** see **10–20% lower premiums** due to proven safe behavior (NY State Insurance Department, 2022).
---
Post-Renewal Adjustments and Insurer Switching Strategy
After renewal, drivers should compare quotes from competitors to ensure they’re not overpaying. New York’s **no-fault insurance market** allows switching insurers annually without penalties, making it critical to reassess options. **Shopping around can uncover savings of 15–40%** (Consumer Federation of America, 2023).
**Key Actions:**
- **February:** Use **NY’s Insurance Department’s comparison tool** ([NY Forward](https://www.dfs.ny.gov)) to benchmark rates.
- **May:** Request **loyalty discounts** (e.g., **5–10% after 3+ years**) from current insurer if switching seems costly.
- **August:** Compare **usage-based programs** (e.g., Allstate Drivewise, Nationwide SmartRide) for personalized pricing.
- **November:** If switching, **cancel old policy before new one activates** to avoid gaps in coverage.
**Warning:** Avoid **lapse in coverage**, as even a **1-day gap** can trigger higher rates or denial of future claims in NY.
Case Study: New York City Resident Reduces Car Insurance Premium by 40% Through Strategic Adjustments
In 2023, a 35-year-old New York City resident named **Daniel M.** faced annual car insurance premiums of **$2,800** for a full-coverage policy on a 2018 Honda Civic. Through a combination of discount utilization, provider switching, and policy refinements, Daniel successfully lowered his premium to **$1,680**—a **40% reduction**—without compromising essential coverage. His approach demonstrates how proactive adjustments can yield significant savings for urban drivers in high-cost insurance markets like New York.
Daniel’s strategy combined **three key actions**: leveraging eligibility-based discounts, transitioning to a more competitive insurer, and optimizing coverage limits. Below is a detailed breakdown of his methodology, segmented by phase.
---
Phase 1: Identifying and Applying Eligible Discounts
Daniel began by auditing his current policy for overlooked discounts. Many NYC drivers underutilize available savings opportunities due to lack of awareness or provider limitations. Using the **New York Department of Financial Services (DFS) Insurance Discount Checklist**, he identified five applicable discounts:
- **Multi-Policy Discount (10%)**: Combined his auto policy with his existing homeowners insurance through the same provider.
- **Low Mileage Discount (15%)**: Certified his annual mileage as **<7,500 miles** (verified via GPS tracking), qualifying for a commuter discount.
- **Good Student Discount (5%)**: Applied after submitting proof of a **3.5+ GPA** (though he was no longer a student, his provider offered a "lifetime learner" discount for prior academic achievement).
- **Paperless Billing Discount (3%)**: Enabled electronic statements to avoid late fees and gain an automatic reduction.
- **Anti-Theft Device Discount (5%)**: Installed a **LoJack GPS tracker**, documented with police certification.
**Result**: These discounts collectively reduced his premium by **~38%** with his original insurer, lowering it to **$1,750**. However, Daniel recognized further potential by comparing providers.
---
Phase 2: Switching Providers for Competitive Rates
After securing discounts, Daniel compared quotes from **five major insurers** operating in NYC using the **New York State Insurance Department’s (NYSDIF) comparison tool**. His original provider, **Provider X**, quoted **$1,750**, while others offered:
| **Provider** | **Base Premium** | **Discounts Applied** | **Final Quote** | **Savings vs. Original** |
|--------------------|------------------|-----------------------------|-----------------|--------------------------|
| Provider X (Current) | $2,800 | Multi-policy, low mileage, good student, paperless, anti-theft | **$1,750** | 37.5% |
| Provider Y | $2,600 | Low mileage, paperless, anti-theft, **telematics (12%)** | **$1,500** | 46.4% |
| Provider Z | $2,400 | Multi-policy, low mileage, **usage-based (15%)**, anti-theft | **$1,380** | 50.7% |
| Provider A | $2,500 | Paperless, **pay-in-full (5%)**, anti-theft, **loyalty (10%)** | **$1,450** | 48.2% |
| Provider B | $2,700 | Low mileage, **defensive driving course (10%)**, anti-theft | **$1,620** | 42.1% |
**Key Observations**:
- **Provider Z** offered the lowest quote (**$1,380**) by combining **usage-based discounts** (via a telematics app) with multi-policy bundling.
- **Provider Y** provided a **12% telematics discount** for safe driving habits, verified through a **Progressive Snapshot**-like program.
- **Provider A** included a **5% pay-in-full discount** for annual premium payment, reducing upfront costs.
Daniel selected **Provider Z** for its **$1,380 quote**, a **22% improvement** over his discounted rate with Provider X. The switch required a **30-day notice** and a **one-time $50 administrative fee**, but the annual savings outweighed the cost.
---
Phase 3: Policy Adjustments Without Sacrificing Coverage
With Provider Z, Daniel further optimized his policy by:
1. **Adjusting Deductibles**:
- Increased the **collision deductible** from **$500 to $1,000**, reducing premiums by **8%**.
- Maintained a **$250 comprehensive deductible** (standard for NYC’s high theft rates).
2. **Removing Unnecessary Coverage**:
- Dropped **rental reimbursement** (unused) and **gap insurance** (his car’s value was below loan balance).
- **Result**: Saved **$40 annually**.
3. **Enrolling in a Defensive Driving Course**:
- Completed a **6-hour NYSDMV-approved course** (e.g., **IPDD or AARP Smart Driver**), qualifying for a **5% additional discount**.
- **Cost**: $25 for the course; **$70 annual savings**.
**Final Premium**: **$1,680** (down from **$2,800**).
**Total Savings**: **$1,120/year (40%)**.
---
Lessons for NYC Drivers
Daniel’s success highlights three critical strategies:
- **Discount Stacking**: Combine eligibility-based and behavioral discounts for compounded savings.
- **Provider Agility**: Regularly compare quotes—NYC insurers adjust rates annually, and loyalty penalties can exceed $500/year.
- **Coverage Pragmatism**: Balance deductible increases with risk tolerance; NYC’s high repair costs (e.g., hail damage) justify lower deductibles for comprehensive coverage.
**Note**: Daniel’s savings are illustrative; actual discounts vary by insurer, location (e.g., Brooklyn vs. Manhattan), and driving record. The **NYSDIF** recommends annual reviews to adapt to policy changes.
---
Visual Elements for an Infographic on New York’s Traffic Laws and Their Impact on Insurance Costs
New York’s traffic laws, particularly its **no-fault insurance system**, significantly influence premium costs by dictating liability, medical coverage, and claim processes. An effective infographic must visually break down these legal frameworks while illustrating their direct correlation with insurance expenses. The design should prioritize clarity, using **icons, flowcharts, and comparative data** to highlight how regulations like mandatory personal injury protection (PIP) or strict liability rules affect policyholders.
The infographic should integrate **three core visual components**:
1. **Legal Framework Breakdown**: A structured diagram showing how New York’s no-fault system (e.g., PIP benefits, fault thresholds) interacts with insurer obligations.
2. **Cost Impact Visualization**: A bar or pie chart comparing average premiums in New York against states with tort-based systems, emphasizing the financial burden of no-fault requirements.
3. **Claim Process Flowchart**: A step-by-step illustration of how legal mandates (e.g., mandatory arbitration for disputes) extend claim timelines and increase administrative costs for insurers, which are passed to consumers.
---
Legal Framework Breakdown
This section requires a **modular icon-based layout** with labeled arrows connecting legal terms to their financial implications. Key elements include:
- **No-Fault System Icon**: A shield with "NY No-Fault" text, linked to a **cost multiplier** (e.g., "+20% premiums" due to PIP mandates).
- **PIP Coverage Flow**: A timeline showing how PIP benefits (up to $50,000 per claim) force insurers to allocate funds for medical expenses, increasing base rates.
- **Fault Threshold Explanation**: A split diagram (e.g., 50/50 or 100% at-fault scenarios) with annotations on how severe accidents trigger liability lawsuits, spiking defense costs.
**Example Visual Cue**:
A **geometric shape** (e.g., hexagon) representing New York, with embedded **mini-icons** for:
- **Medical Payments**: Ambulance + hospital symbols.
- **Liability Risks**: Gavel and scale icons tied to tort claims.
- **Insurer Overhead**: Stacked dollar signs labeled "Administrative Costs."
---
Cost Impact Visualization
Use a **comparative bar graph** with two axes:
- **X-Axis**: States (NY, CA, FL, TX) or regions within NY (NYC vs. Upstate).
- **Y-Axis**: Average annual premiums (e.g., $1,500–$3,500).
- **Color Coding**:
- **Red**: No-fault states (NY highlighted).
- **Blue**: Tort states (e.g., TX).
- **Gray**: States with hybrid systems (e.g., PA).
**Annotations**:
- Callouts for NY-specific surcharges (e.g., "$100+ for PIP waiver declines").
- A **side note**: "NY’s urban density + no-fault = 30% higher rates than rural tort states."
---
Claim Process Flowchart
A **horizontal flowchart** with stages labeled **1–5**, each tied to cost drivers:
1. **Accident Reporting**: Icon of a crash report form with text: "Mandatory NYS DMV filing within 10 days → Insurer investigation fees."
2. **PIP Claim Filing**: Medical bill icon with note: "Insurer must cover 80% of PIP costs upfront."
3. **Fault Determination**: Gavel icon with branching paths:
- **No-Fault**: "PIP payouts continue; premiums rise 5–15%."
- **At-Fault**: "Liability claim triggers lawsuit costs (avg. $5K–$20K per case)."
4. **Dispute Resolution**: Arbitration clock icon with text: "NY’s mandatory arbitration delays claims by 6–12 months."
5. **Premium Adjustment**: Piggy bank icon with formula:
**New Premium = Base Rate + (Claim Costs × Insurer’s Loss Ratio) + State Fees.**
**Visual Style**:
- **Arrows** with dollar-sign labels for cost increments.
- **Warning symbols** (e.g., exclamation marks) next to stages with high variability (e.g., "Disputes add $1K–$5K to premiums").
---
Affordable car insurance in New York is achievable when you approach the process with knowledge and strategy. By identifying the right discounts, comparing providers beyond just price, and adjusting coverage to fit your risk profile, drivers across the state—from Manhattan to Buffalo—can secure reliable protection without financial strain. Whether you’re a high-risk driver rebuilding credit, a young motorist navigating early premiums, or a veteran leveraging military benefits, the tools and programs outlined here provide clear pathways to savings. The key lies in proactive steps: annual policy reviews, bundling opportunities, and staying informed about state-specific programs like NYAIP or usage-based insurance. With these insights, you can drive confidently, knowing your insurance aligns with both your budget and your protection needs.
Start today by evaluating your current policy, exploring provider comparisons, and applying the cost-saving tactics detailed in this guide. Small adjustments—such as increasing deductibles, enrolling in defensive driving courses, or switching to a regional insurer—can yield significant long-term savings. Remember, affordability isn’t about compromising coverage; it’s about making informed choices that balance risk and cost. Drive smarter, pay less, and keep your New York roads covered without breaking the bank.
Top 10 Cheapest Car Insurance Companies In New York USA - YouTube
Frequently Asked Questions
What are the cheapest car insurance options available in New York?
Affordable car insurance in New York often includes liability-only policies, high-deductible plans, or usage-based programs like pay-per-mile. Discounts for bundling home and auto insurance or maintaining good grades (for students) can further reduce costs. State minimum coverage is $25,000/$50,000/$10,000 for bodily injury/property damage.
How can I qualify for discounts to lower my New York car insurance premium?
Eligibility for discounts includes safe driver records, low annual mileage, anti-theft devices, defensive driving course completion, and multi-policy bundling. New York providers like Geico, State Farm, and Progressive offer loyalty and paperless billing discounts. Ask insurers about available programs when comparing quotes.
What’s the minimum car insurance coverage required in New York, and why does it matter for cost?
New York mandates **25/50/10** coverage: $25,000 per person/$50,000 per accident for bodily injury, and $10,000 for property damage. Opting for full coverage (collision/comprehensive) increases premiums but may be required for financed vehicles. Minimum coverage is the cheapest but offers limited protection.
Do insurance rates vary by city in New York, and which areas are most expensive?
Yes, rates fluctuate by location due to theft, accident frequency, and repair costs. Urban areas like **Bronx, Brooklyn, and Manhattan** often have higher premiums, while rural zones like **Adirondacks or Finger Lakes** tend to be cheaper. ZIP codes significantly impact quotes, so comparing providers locally is critical.
What insurance companies offer the best rates for high-risk drivers in New York?
High-risk drivers may find affordable options through **Progressive (SNAP program)**, **The General**, or **New York Auto Insurance Plan (NYAIP)**. Usage-based insurers like **Milewise or Metromile** can help if driving is limited. SR-22 filings may be required post-violation, increasing costs temporarily.
Are there government programs or financial aid options for low-income New Yorkers needing car insurance?
New York offers the **NY Car Insurance Assistance Program (CIAP)** for low-income drivers, providing subsidies to meet minimum coverage requirements. Additionally, **NY No-Fault Insurance Fund** assists with uninsured motorist claims. Contact the **NY Department of Financial Services** for eligibility details and application.