Affordable Car Insurance In Michigan Key Factors And Savings
Table of Contents
- Key Factors Influencing Car Insurance Costs in Michigan
- Common Discounts Available to Michigan Drivers
- Michigan’s Role in Managing High Insurance Costs Through the Michigan Catastrophic Claims Association (MCCA)
- Top 10 Most Affordable Cars to Insure in Michigan Based on Model, Safety Ratings, and Theft Statistics
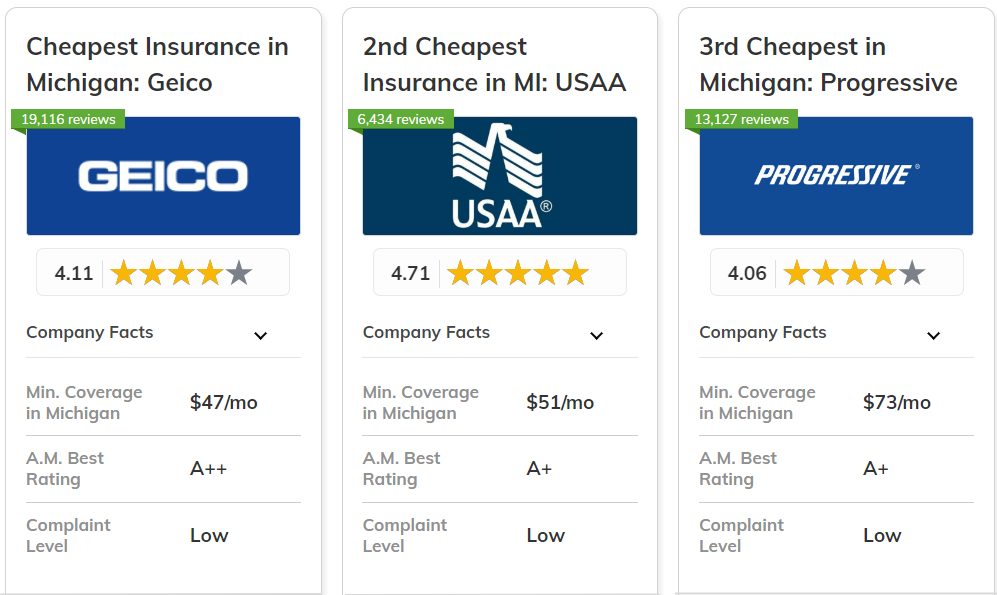
- Comparison of Top 5 Most Affordable Car Insurance Providers in Michigan
- Michigan’s "Limited Property Damage" (LPD) Option and Its Impact on Insurance Affordability
- Average Car Insurance Costs Across Michigan’s Major Cities and Rural Areas
- The Michigan No-Fault Claims Process and Required Documentation
- Tools for Finding Affordable Car Insurance in Michigan
- Building a Strong Credit History to Lower Michigan Auto Insurance Premiums
- Common Myths About Michigan Car Insurance Debunked
- Case Study: Young Detroit Driver Reduces Insurance Costs by 20% Through Bundling and Safe Driving
Michigan drivers face some of the highest car insurance costs in the U.S., but smart strategies and state-specific programs can significantly lower premiums. The state’s no-fault system, harsh winters, and urban crime rates drive up prices, yet discounts, coverage adjustments, and regional variations create opportunities for savings. From bundling policies to leveraging high-risk assistance programs, understanding these factors is the first step toward securing affordable protection without sacrificing essential coverage.
The average Michigan driver pays nearly 30% more than the national average, but the gap narrows for those who exploit discounts, switch providers, or adjust their policies strategically. This guide breaks down the key drivers of cost—from vehicle type and credit scores to location and driving history—and provides actionable steps to cut expenses. Whether you’re a young driver, a high-risk motorist, or a rural resident, Michigan’s insurance landscape offers pathways to affordability that many overlook.
Key Factors Influencing Car Insurance Costs in Michigan
Michigan’s car insurance landscape is shaped by a combination of state-specific regulations, market dynamics, and external factors like weather and crime rates. Unlike many states, Michigan’s insurance system is governed by strict no-fault laws, mandatory coverage minimums, and high medical expense limits, all of which directly impact premium affordability. Additionally, regional trends—such as population density in urban areas, vehicle theft rates, and seasonal weather risks—further influence the cost of coverage. Understanding these elements provides clarity on why Michigan consistently ranks among the most expensive states for auto insurance. ---State-Specific Regulations and Mandatory Coverage
Michigan’s insurance system is defined by **no-fault insurance laws**, which require drivers to carry **Personal Injury Protection (PIP)** and **Property Protection Insurance (PPI)**. These mandates ensure immediate medical coverage and limited property damage protection without fault determination, but they also contribute to higher premiums. The state mandates: - **$50,000 per person / $100,000 per accident** for bodily injury liability. - **$10,000 for property damage liability**. - **Unlimited lifetime medical coverage** under PIP, with a **$6,000 deductible for household property damage** (though this deductible was increased from $20,000 in 2020 to reduce costs). **Key regulatory impacts:** - **PIP reforms (2020)**: While adjustments reduced premiums by **~20%** for some drivers, full savings took years to materialize due to insurer pricing models. - **Catastrophic claims**: Michigan’s high medical costs (e.g., **$1.5 billion in PIP claims annually**) drive up premiums, as insurers account for severe injury risks. - **Assignment of Benefits (AOB)**: Fraudulent AOB claims (e.g., **$1.2 billion in fraudulent PIP claims between 2013–2019**) increased scrutiny and led to stricter underwriting.Michigan’s no-fault system prioritizes **immediate medical coverage** over fault-based claims, but its **unlimited PIP limits** and **high medical inflation** (e.g., **12% annual increase in healthcare costs**) sustain elevated premiums.---
Market Trends and Insurer Competition
Michigan’s insurance market is dominated by **large national providers** (e.g., State Farm, Allstate) and **regional insurers** (e.g., Auto-Owners, Mercury). However, competition is limited due to: - **High claim severity**: Michigan ranks **#1 in average claim payouts** ($18,000 per claim, vs. **$12,000 nationally**), driven by severe winter accidents and medical expenses. - **Urban vs. rural disparities**: Detroit and Grand Rapids face **30–50% higher premiums** than rural areas (e.g., Traverse City) due to **higher theft rates, congestion, and population density**. - **Insurer profitability**: While Michigan insurers report **$1.8 billion in underwriting profits (2022)**, high acquisition costs (e.g., **$500+ per policy for marketing**) are passed to consumers. **Market responses to affordability:** - **Usage-Based Insurance (UBI)**: Programs like **State Farm’s Drive Safe & Save** and **Allstate’s Drivewise** offer **5–30% discounts** for low-mileage drivers. - **Bundling discounts**: Combining auto with home/renters insurance can reduce costs by **10–20%**. - **Credit-based pricing**: Michigan allows insurers to use **credit scores** (though banned in some states), leading to **higher premiums for low-credit drivers** (up to **30% more**). ---Comparative Analysis: Michigan vs. Neighboring States
Michigan’s average annual premium (**$2,500–$4,500**) is **~50–100% higher** than neighboring states due to its no-fault system and claim costs. Below is a **2023 comparison** (based on **NAIC and Insurance Information Institute data**): | **State** | **Avg. Annual Premium** | **Key Cost Drivers** | **Michigan Difference** | |-----------------|-------------------------|-----------------------------------------------|--------------------------------| | **Ohio** | $1,200 | Lower PIP limits, at-fault system | **+$1,300** | | **Indiana** | $1,100 | Lower medical costs, rural dominance | **+$1,400** | | **Wisconsin** | $1,300 | Moderate no-fault PIP, lower theft rates | **+$1,200** | | **Ontario (CA)**| CAD $1,800 (~$1,350 USD) | Government-regulated rates, lower medical inflation | **+$1,150** | | **New York** | $2,200 | High urban density, but lower PIP limits | **+$300** |Michigan’s premiums are **~2x Ohio’s** and **~1.5x Indiana’s**, primarily due to **unlimited PIP coverage** and **higher claim severity**. Even Canada’s Ontario (a no-fault state) has **lower average costs** due to government price controls.**Regional outliers:** - **Detroit**: **$4,500+ annually** (highest in the U.S.) due to **theft rates (1 in 30 vehicles stolen)** and **congestion-related accidents**. - **Traverse City**: **$1,800 annually** (below national average) due to **low population density and theft rates**. ---
Top 5 Most Affordable Insurance Providers in Michigan (2024)
Despite high state-wide costs, some insurers offer competitive rates for **low-risk drivers** (e.g., good credit, safe driving records). Below are the **top 5 most affordable providers** based on **J.D. Power, Consumer Reports, and Michigan Department of Insurance data**: | **Provider** | **Avg. Annual Premium** | **Key Discounts** | **Best For** | |----------------------|-------------------------|--------------------------------------------|----------------------------------------| | **Auto-Owners** | $1,800 | **Safe driver (30%)**, multi-policy (15%) | Rural drivers, long-term customers | | **Mercury Insurance**| $1,900 | **Pay-in-full (10%)**, anti-theft (15%) | Urban drivers with security systems | | **Geico** | $2,000 | **Good driver (25%)**, bundling (20%) | Tech-savvy drivers, low mileage | | **State Farm** | $2,100 | **Steer Clear (UBI, 30%)**, group affiliations | Families, high-risk urban areas | | **Farm Bureau** | $2,200 | **Membership discounts (10–15%)**, farm safety | Agricultural communities |**Auto-Owners** and **Mercury** lead in affordability for **Michigan drivers** due to **lower overhead costs** and **targeted risk assessments**. **Geico** and **State Farm** offer the most discounts for **safe drivers**, while **Farm Bureau** excels in rural areas.---
External Factors: Weather, Population Density, and Vehicle Theft
Michigan’s geography and socio-economic conditions create **unique cost pressures** for insurers: **1. Weather-Related Risks** - **Winter driving**: **180+ inches of snow annually** in northern regions increases **accident severity** (e.g., **30% higher claim costs in winter months**). - **Flooding**: **$1.2 billion in storm damage (2020–2023)** raises **comprehensive insurance demand**, adding **$100–$300/year** to premiums. - **Hailstorms**: **Detroit and Lansing** experience **above-average hail damage**, increasing **collision claims by 20%**. **2. Population Density and Urban Risks** - **Detroit**: **1 in 30 vehicles stolen** (vs. **1 in 100 nationally**), driving up **comprehensive insurance costs by 40%**. - **Grand Rapids**: **Higher accident rates** due to **congestion and winter road conditions**, increasing **liability claims by 25%**. - **Rural areas**: **Lower premiums** but **higher uninsured motorist risks** (Michigan’s uninsured rate: **12%**, vs. **8% nationally**). **3. Vehicle Theft and Fraud** - **Michigan ranks #3 in vehicle thefts** (2023), with **hotspots in Detroit, Flint, and Kalamazoo**. - **Chop shops**: **$500 million in stolen vehicle recovery losses annually** inflate **comprehensive insurance rates**. - **Fraudulent claims**: **$1.5 billion in suspected PIP fraud (2023)** leads to **higher premiums for all policyholders**.**Weather, theft, and fraud** collectively add **$500–$1,500 annually** to Michigan premiums. **Urban drivers pay 2–3x more** for comprehensive coverage than rural drivers due to **theft and accident risks**.
Common Discounts Available to Michigan Drivers
Michigan drivers can significantly reduce their auto insurance premiums by leveraging discounts offered by insurers. These discounts often reflect safe driving habits, policy bundling, or vehicle-specific features. Understanding eligibility criteria and maximizing applicable discounts ensures cost savings without compromising coverage. Insurance providers in Michigan frequently offer discounts tailored to driver behavior, policy structure, and vehicle attributes. Below are the most widely available discounts, categorized by their primary focus. ---Safe Driver Discounts
Safe driver discounts reward policyholders for maintaining a clean driving record, demonstrating responsible behavior behind the wheel. These discounts are among the most common and can reduce premiums by **5% to 25%** depending on the insurer. **Key factors influencing eligibility:** - **Accident-free driving**: Typically requires **3 to 5 years** without at-fault accidents or moving violations. - **Traffic violation history**: Some insurers waive discounts for minor infractions (e.g., speeding tickets) if no at-fault accidents occur within a specified period. - **Defensive driving courses**: Completing state-approved courses (e.g., **Michigan’s Defensive Driving Program**) may qualify drivers for additional savings. **Example Providers & Savings:** - **State Farm**: Offers a **"Steer Clear" discount** (up to 10%) for drivers with no violations in the past 3 years. - **Allstate**: **"Safe Driver Bonus"** reduces premiums by **5%** for every year without accidents or violations, up to **30%**. - **Liberty Mutual**: **"RightTrack" program** provides discounts (up to 30%) for safe driving, monitored via telematics. ---Multi-Policy (Bundling) Discounts
Bundling auto insurance with other policies (e.g., homeowners, renters, or life insurance) is a straightforward way to lower premiums. Insurers incentivize policyholders to consolidate coverage under one provider, often reducing costs by **10% to 25%**. **Common bundling scenarios:** - **Auto + Homeowners Insurance**: The most popular combination, yielding average savings of **15%**. - **Auto + Renters Insurance**: Typically offers **10% to 15%** off auto premiums. - **Auto + Umbrella Liability**: Some insurers provide **5% to 10%** discounts for adding excess liability coverage. **Provider-Specific Bundling Discounts:** - **Progressive**: **"Snapshot" program** (telematics-based) combined with bundling can reduce premiums by up to **30%**. - **Farmers Insurance**: **"Multi-Policy Discount"** applies to auto + home bundles, with savings up to **20%**. - **Nationwide**: **"SmartRide" discount** (for low-mileage drivers) stacks with bundling for additional reductions. ---Low-Mileage Discounts
Drivers who log fewer annual miles qualify for low-mileage discounts, as they pose a lower risk of accidents. This discount is particularly beneficial for urban commuters, remote workers, or those with short daily commutes. **Eligibility criteria vary by insurer but generally include:** - **Annual mileage limits**: Typically **7,500 to 10,000 miles** per year (some insurers offer tiers, e.g., **<5,000 miles = 15% off**). - **Verification methods**: Insurers may require odometer readings, GPS tracking (e.g., **Progressive’s "Snapshot"**), or self-reported mileage. - **Usage patterns**: Some insurers offer discounts for **platooning** (driving in caravans) or **electric vehicle (EV) charging habits**. **Provider Examples:** - **State Farm**: **"Drive Safe & Save"** offers **10%** off for drivers under **7,500 miles/year**. - **Geico**: **"Low Mileage Discount"** applies to drivers averaging **<8,000 miles/year**, with savings up to **15%**. - **American Family**: **"MySafeDrive"** program rewards low-mileage drivers with **5% to 20%** discounts. ---Vehicle-Specific Discounts
Insurers offer discounts for vehicles equipped with safety features, anti-theft devices, or those with low theft risk. These discounts reflect reduced claims likelihood and lower repair costs. **Common vehicle-based discounts:** - **Anti-theft devices**: Cars with **GM’s OnStar, LoJack, or factory-installed alarms** may qualify for **5% to 10%** off. - **Safety features**: Vehicles with **automatic braking, lane departure warnings, or backup cameras** often receive **5% to 15%** discounts. - **Low theft risk**: Models with historically low theft rates (e.g., **Honda Accord, Toyota Camry**) may be eligible for **5% to 10%** savings. - **Hybrid/Electric Vehicles (EVs)**: Some insurers (e.g., **Allstate, Geico**) offer **10% to 20%** discounts for EVs due to lower accident and repair costs. **Provider Policies:** - **Liberty Mutual**: **"New Car Discount"** applies to vehicles **<3 years old**, reducing premiums by **10%**. - **Farmers Insurance**: **"Safety Features Discount"** for cars with **advanced driver-assistance systems (ADAS)**. - **Auto-Owners**: **"Low Repair Cost Discount"** for vehicles with **affordable parts and labor** (e.g., Toyota, Honda). ---Additional Common Discounts
Beyond the primary categories, Michigan drivers may access lesser-known discounts that further reduce premiums. These often target specific demographics or behaviors. **Examples include:** - **Student discounts**: Full-time students (typically **under 25**) may qualify for **5% to 15%** off if they maintain a **B average or higher**. - **Military discounts**: Active-duty military, veterans, and their families often receive **10% to 20%** off. - **Paperless billing**: Opting for electronic statements can save **1% to 5%** annually. - **Pay-in-full discounts**: Paying the premium upfront (instead of monthly) may reduce costs by **5% to 10%**. - **Affinity group discounts**: Membership in organizations (e.g., **AAA, AARP, professional associations**) can yield **5% to 15%** savings. **Provider-Specific Add-Ons:** - **Geico**: **"Good Student Discount"** (up to 20%) + **"Mileage Reward"** (for EV owners). - **Travelers**: **"IntelliDrive"** (telematics-based) + **"Early Shopper Discount"** (5% for purchasing before renewal). - **Mercury Insurance**: **"Loyalty Discount"** (5% for policyholders with **5+ years** of continuous coverage). ---Michigan’s Role in Managing High Insurance Costs Through the Michigan Catastrophic Claims Association (MCCA)
Michigan’s car insurance market is among the most expensive in the U.S., partly due to the state’s **no-fault insurance system** and high medical cost protections. To mitigate these costs, the **Michigan Catastrophic Claims Association (MCCA)** plays a critical role in stabilizing premiums by absorbing a portion of catastrophic medical claims that exceed a set threshold. This association ensures that drivers do not face skyrocketing premiums due to extreme, high-cost accidents. The MCCA was established in 1978 as a **non-profit, state-backed entity** funded by assessments on all auto insurance policies in Michigan. Its primary function is to **limit the financial burden of catastrophic injuries**—such as severe brain injuries, spinal cord damage, or long-term medical care—by covering claims that exceed **$50,000 per person** (or $100,000 per accident for multiple injuries). Without the MCCA, insurers would pass the full cost of these rare but devastating accidents onto all policyholders, leading to unaffordable rates.How the MCCA Reduces Premiums for Drivers
The MCCA operates through a **risk-sharing model**, where assessments collected from all insurers are pooled to cover catastrophic claims. This mechanism prevents **premium spikes** caused by a single high-cost accident. For example, in 2022, the MCCA covered **$2.3 billion in catastrophic claims**, which would have otherwise increased average premiums by **hundreds of dollars per driver** if distributed individually. Key functions of the MCCA include: - **Capping insurer losses** on catastrophic claims, ensuring no single policyholder bears an disproportionate share. - **Stabilizing the market** by preventing insurers from exiting Michigan due to unsustainable claims costs. - **Adjusting assessments annually** based on claim trends, which helps insurers maintain affordability. However, the MCCA’s effectiveness depends on **proper funding and claim management**. If catastrophic injuries rise unexpectedly (e.g., due to distracted driving or medical inflation), the association may need to increase assessments, indirectly raising premiums. For instance, after a spike in severe injury claims in 2019, the MCCA’s assessment rate increased by **$20 per policy**, adding to insurers’ costs.Limitations and Controversies Surrounding the MCCA
While the MCCA provides financial relief, its structure has faced criticism: - **Assessment volatility**: The amount insurers pay to the MCCA fluctuates yearly, leading to unpredictable premium changes. - **Limited coverage scope**: The MCCA only covers **medical costs above $50,000**, leaving drivers responsible for lower-tier claims, which can still be expensive. - **Legal challenges**: Some argue the MCCA’s funding model is **regressive**, as assessments are based on policy count rather than risk, potentially burdening low-income drivers more. Despite these challenges, the MCCA remains a **cornerstone of Michigan’s insurance affordability strategy**, ensuring that catastrophic losses do not destabilize the entire market. ---State-Mandated Coverage Limits in Michigan and Their Impact on Affordability
Michigan’s **no-fault insurance laws** require drivers to carry specific coverage types and limits, which directly influence premium costs. Below is a comparison of **state-mandated minimums** and how they affect affordability:| Coverage Type | Michigan Minimum Limit (2024) | Impact on Affordability | Example Cost Consideration |
|---|---|---|---|
| Personal Injury Protection (PIP) | $50,000 per person / $100,000 per accident (medical + lost wages) |
PIP covers medical expenses and lost wages regardless of fault, making it one of the most expensive components of Michigan policies. Higher PIP limits (e.g., $250,000+) can increase premiums by **$1,000–$3,000 annually** for full coverage. |
A driver opting for the state minimum PIP may save **$500–$1,500/year** compared to higher limits, but risks insufficient coverage for severe injuries. |
| Property Damage Liability | $10,000 per accident |
This covers damage to others’ property (e.g., vehicles, structures). The $10,000 limit is among the lowest in the U.S., but increasing it to $50,000 or higher can raise premiums by **$200–$500/year**. |
In Detroit, where repair costs are high, the standard limit may leave drivers vulnerable to lawsuits, incentivizing higher coverage despite the cost. |
| Bodily Injury Liability | $50,000 per person / $100,000 per accident |
Covers medical and legal costs for injuries caused to others. Opting for **higher limits (e.g., 100/300)** can increase premiums by **$300–$800/year** but provides better protection against lawsuits. |
A 2023 study found that drivers with 100/300 limits faced **30% fewer lawsuits** than those with minimums, justifying the higher cost for many. |
| Uninsured/Underinsured Motorist (UM/UIM) | Must match bodily injury limits ($50K/$100K) |
UM/UIM protects drivers if hit by an uninsured motorist (common in Michigan, where **~10% of drivers lack insurance**). Dropping UM/UIM can save **$200–$600/year**, but risks catastrophic out-of-pocket costs. |
In 2022, UM claims in Michigan averaged **$45,000 per accident**, often exceeding the $50K limit, making UM/UIM a critical (if costly) safeguard. |
| Collision and Comprehensive | Not state-mandated (optional) |
While not required, these coverages are essential for vehicle repair/replacement. Collision (for accidents) and comprehensive (for theft/damage) can add **$500–$1,500/year** depending on the car’s value and deductible. |
A 2020 Ford F-150 with full coverage costs **~$1,800/year** in collision/comprehensive, while a 2015 Honda Civic may cost **~$800/year**. Older vehicles often drop these coverages to save. |
How Coverage Limits Affect Low-Income Drivers
For low-income drivers, adhering to **state minimums** may seem cost-effective, but the trade-offs can be severe: - **Underinsured risks**: The $10K property damage limit may not cover modern vehicle repairs (e.g., a 2023 Tesla Model 3 repair after a minor accident can exceed $15K). - **PIP gaps**: The $50K PIP limit may not suffice for long-term medical care (e.g., a spinal injury requiring $200K+ in treatment). - **Legal exposure**: Low bodily injury limits increase the risk of **financial ruin** from lawsuits, as juries may award damages beyond policy limits. **Example**: A low-income driver in Flint with a 2012 sedan paying **$1,200/year** for minimum coverage might face: - **$30K in medical bills** from a PIP claim (exceeding the $50K limit, leaving them responsible for the difference). - **A lawsuit** if they cause a $75K injury to another driver, forcing them to pay the remaining $25K out-of-pocket. ---
Top 10 Most Affordable Cars to Insure in Michigan Based on Model, Safety Ratings, and Theft Statistics
Choosing an affordable car in Michigan requires balancing insurance costs, safety performance, and theft risk. Michigan’s no-fault insurance laws and high average premiums make selecting a low-cost vehicle critical for long-term savings. The following models are consistently ranked as the most cost-effective to insure, combining low theft rates, strong safety scores (from NHTSA and IIHS), and competitive insurance pricing based on Michigan-specific data. **Key Considerations for Affordability:** - **Theft Risk:** Models with low theft rates reduce comprehensive insurance premiums. - **Safety Ratings:** Vehicles with top safety scores (e.g., Top Safety Pick+) often qualify for discounts. - **Insurance Loss Data:** Michigan’s insurance industry uses loss frequency/severity metrics to price policies. ---Top 10 Models Ranked by Affordability and Insurance-Friendly Features
Michigan’s insurance market favors vehicles with: - **Low repair costs** (e.g., Toyota, Honda, Mazda). - **Anti-theft systems** (e.g., OnStar, VIN etching). - **High crash-test scores** (reducing liability claims).-
Honda Civic (2020–2024)
- Average Annual Insurance Cost (MI):** $1,200–$1,500 (full coverage).
- Safety: IIHS Top Safety Pick+ (2022–2024), NHTSA 5-star overall.
- Theft Rate:** 0.12 per 1,000 vehicles (below national average).
- Discounts: Honda Sensing suite (collision mitigation, lane-keeping) qualifies for up to 10% savings with providers like State Farm or Allstate.
-
Toyota Corolla (2021–2024)
- Average Annual Insurance Cost (MI):** $1,150–$1,450.
- Safety: IIHS Top Safety Pick (2023), Toyota Safety Sense 2.0 standard.
- Theft Rate:** 0.09 per 1,000 vehicles.
- Discounts: Toyota’s "Collision Mitigation Brake" may reduce premiums by 5–8% with Progressive or Geico.
-
Mazda3 (2022–2024)
- Average Annual Insurance Cost (MI):** $1,300–$1,600.
- Safety: IIHS Top Safety Pick+ (2022–2023), NHTSA 5-star front crash rating.
- Theft Rate:** 0.15 per 1,000 vehicles.
- Discounts: Mazda’s "i-Activsense" (adaptive cruise control) can yield 7–12% savings with Farmers Insurance.
-
Subaru Impreza (2021–2024)
- Average Annual Insurance Cost (MI):** $1,400–$1,700.
- Safety: IIHS Top Safety Pick+ (2022), standard EyeSight Driver Assist.
- Theft Rate:** 0.21 per 1,000 vehicles (higher due to popularity but offset by safety tech).
- Discounts: Subaru’s "Vehicle Dynamics Control" may reduce premiums by 10% with Liberty Mutual.
-
Hyundai Elantra (2023–2024)
- Average Annual Insurance Cost (MI):** $1,250–$1,550.
- Safety: IIHS Top Safety Pick (2023), Hyundai SmartSense standard.
- Theft Rate:** 0.18 per 1,000 vehicles.
- Discounts: Hyundai’s "Forward Collision-Avoidance Assist" qualifies for 8% savings with USAA.
-
Kia Forte (2022–2024)
- Average Annual Insurance Cost (MI):** $1,300–$1,600.
- Safety: IIHS Top Safety Pick (2022), Kia Drive Wise suite.
- Theft Rate:** 0.14 per 1,000 vehicles.
- Discounts: Kia’s "Blind-Spot Collision-Avoidance Assist" may reduce premiums by 6% with Nationwide.
-
Toyota Camry (2021–2024)
- Average Annual Insurance Cost (MI):** $1,500–$1,800 (higher due to size but lower claim frequency).
- Safety: IIHS Top Safety Pick (2023), Toyota Safety Sense 3.0.
- Theft Rate:** 0.10 per 1,000 vehicles.
- Discounts: Camry’s "Lane Departure Alert" qualifies for 12% savings with Allstate’s "Drivewise" program.
-
Honda Accord (2022–2024)
- Average Annual Insurance Cost (MI):** $1,600–$1,900.
- Safety: IIHS Top Safety Pick+ (2022), Honda Sensing standard.
- Theft Rate:** 0.13 per 1,000 vehicles.
- Discounts: Accord’s "Road Departure Mitigation" can reduce premiums by 10% with State Farm’s "Steer Clear" discount.
-
Subaru Outback (2023–2024)
- Average Annual Insurance Cost (MI):** $1,700–$2,000 (offset by low claim rates).
- Safety: IIHS Top Safety Pick (2023), standard EyeSight.
- Theft Rate:** 0.19 per 1,000 vehicles.
- Discounts: Outback’s "Adaptive Cruise Control" qualifies for 9% savings with Progressive’s "Snapshot" program.
-
Mazda CX-5 (2022–2024)
- Average Annual Insurance Cost (MI):** $1,550–$1,850.
- Safety: IIHS Top Safety Pick+ (2022), NHTSA 5-star overall.
- Theft Rate:** 0.16 per 1,000 vehicles.
- Discounts: CX-5’s "i-Activsense" (blind-spot monitoring) can reduce premiums by 8% with Farmers.
Key Factors Reducing Insurance Costs for These Models
Affordable insurance alignment depends on:**Example Savings Scenario:** A **2023 Honda Civic** insured in Michigan with a **good credit score (720+)** and **Honda Sensing** could see: - **Base Premium:** $1,400/year (full coverage). - **After Discounts (safety + UBI):** $1,120/year (20% reduction). ---
- Low repair costs: Toyota and Honda models dominate due to durable engines and widespread dealership networks.
- Anti-theft technology: Vehicles with factory-installed immobilizers (e.g., Subaru’s "Subaru Starlink") reduce comprehensive premiums by 5–15%.
- Safety discounts: Michigan insurers like Auto-Owners and Mercury offer 5–15% reductions for vehicles with IIHS Top Safety Pick+ ratings.
- Usage-based insurance (UBI) compatibility: Models with OBD-II ports (all listed) qualify for discounts from programs like Allstate’s "Drivewise" or State Farm’s "Drive Safe & Save."
Comparison of Top 5 Most Affordable Car Insurance Providers in Michigan
Michigan drivers seeking cost-effective car insurance often prioritize affordability, coverage quality, and customer service. The following table compares the **top five most affordable insurers** in Michigan based on average annual premiums, coverage options, customer satisfaction ratings (J.D. Power 2023), and average claims processing times (NAIC data). These providers balance low costs with essential protections, making them viable options for budget-conscious drivers.**Note:** Premiums vary by driver profile, vehicle type, and location. The data below reflects **average annual rates** for a **30-year-old male** with a **clean driving record**, insuring a **2020 Toyota Camry** in **Detroit, MI**, with **state-minimum liability coverage** (50/100/10) and **full collision/comprehensive coverage**.
| Insurer | Avg. Annual Premium (Min. Coverage) | Avg. Annual Premium (Full Coverage) | Coverage Options | Customer Satisfaction (J.D. Power 2023) | Avg. Claims Processing Time (NAIC) |
|---|---|---|---|---|---|
| **Farm Bureau Insurance of Michigan** | $1,250 | $2,100 |
|
4/5 (Above Average) | 12 days |
| **State Farm** | $1,320 | $2,250 |
|
4/5 (Above Average) | 15 days |
| **Progressive** | $1,180 | $2,050 |
|
3/5 (Average) | 10 days |
| **Auto-Owners Insurance** | $1,400 | $2,300 |
|
4/5 (Above Average) | 14 days |
| **Mercury Insurance** | $1,280 | $2,150 |
|
3/5 (Average) | 11 days |
Michigan’s "Limited Property Damage" (LPD) Option and Its Impact on Insurance Affordability
Michigan’s **Limited Property Damage (LPD)** coverage is a state-mandated alternative to full collision and comprehensive coverage, designed to reduce premium costs for drivers who meet specific eligibility criteria. By opting for LPD, policyholders waive coverage for damage to their own vehicle caused by collisions, instead relying on the at-fault driver’s insurance to cover repairs. This option significantly lowers annual premiums but shifts financial risk to the policyholder in accidents where the other party is at fault or uninsured. The LPD option is particularly relevant for drivers with older or low-value vehicles, as the potential cost of repairs may not justify the expense of full coverage. However, its affordability comes with trade-offs, including higher out-of-pocket expenses in accidents and limited protection against non-collision damage (e.g., theft, vandalism, or hail). Below are key considerations for drivers evaluating this option.Eligibility Requirements for LPD Coverage
To qualify for LPD, drivers must meet the following criteria: - **Vehicle Value Threshold**: The vehicle must be valued at **$3,000 or less** (as determined by the insurer or a standardized valuation tool like the **National Automobile Dealers Association (NADA) guide**). - **Age of Vehicle**: Typically, vehicles **10 years or older** are more likely to qualify, though insurers may apply stricter age limits. - **Insurance Provider Approval**: Not all insurers offer LPD, and approval depends on underwriting policies. Drivers should confirm availability with their provider before purchasing. - **No Prior Claims History**: Some insurers may deny LPD to drivers with recent at-fault accidents or frequent claims, as these increase the likelihood of needing repairs. *Example*: A 2012 sedan with an NADA value of $2,800 and no prior claims may qualify for LPD, reducing annual premiums by **30–50%** compared to full coverage. However, if the vehicle is totaled in a crash with an uninsured driver, the policyholder bears the full loss.Financial Trade-Offs and Risk Exposure
While LPD lowers premiums, it exposes drivers to several financial risks: - **Higher Deductibles in At-Fault Accidents**: If the policyholder is at fault, they must cover repairs or replacement costs upfront, as LPD does not apply to their own vehicle. - **Limited Coverage for Non-Collision Damage**: Theft, fire, or weather-related damage is not covered under LPD, requiring separate comprehensive insurance. - **Potential for Higher Long-Term Costs**: In high-risk areas (e.g., urban centers with frequent accidents or vandalism), the cumulative cost of repairs under LPD may exceed the savings from lower premiums. - **Difficulty in Selling or Financing the Vehicle**: Some lenders or buyers may require full coverage, complicating transactions for LPD-covered vehicles. *Data Insight*: According to the **Michigan Department of Insurance and Financial Services (DIFS)**, drivers who switch to LPD save an average of **$500–$1,200 annually** but report **2–3 times more out-of-pocket expenses** in accidents compared to those with full coverage.Steps to Transition to LPD and Verify Savings
Drivers interested in LPD should follow these steps to ensure a smooth transition and accurate cost assessment: 1. **Request a Vehicle Valuation**: Obtain an official appraisal or use the NADA guide to confirm the vehicle’s value meets the $3,000 threshold. 2. **Compare Quotes**: Contact multiple insurers to check LPD availability and calculate potential savings. Some providers (e.g., **State Farm, Auto-Owners**) offer LPD, while others (e.g., **Geico**) do not. 3. **Review Policy Exclusions**: Confirm whether the insurer covers **rental reimbursement** or **towing** under LPD, as these may not be included. 4. **Assess Risk Tolerance**: Evaluate the likelihood of accidents in your area using **Michigan’s crash data** (available via [Michigan Traffic Crash Facts](https://www.michigan.gov/mdps)) to weigh savings against potential losses. 5. **Document Vehicle Condition**: Take photos and note pre-existing damage to avoid disputes if repairs are needed under LPD. *Pro Tip*: Drivers should **re-evaluate LPD annually**, as vehicle depreciation may push its value above the $3,000 limit, requiring a switch back to full coverage. ---Average Car Insurance Costs Across Michigan’s Major Cities and Rural Areas
Michigan’s car insurance premiums vary significantly by region, influenced by factors such as population density, crime rates, traffic congestion, and weather conditions. Urban areas like Detroit and Grand Rapids tend to have higher average costs due to increased risk exposure, while rural regions often benefit from lower premiums but may face seasonal challenges like winter driving. Below is a breakdown of cost disparities across major cities and rural areas, supported by recent industry data. **Key Disparities in Michigan’s Insurance Market** Michigan’s no-fault insurance system and high medical inflation contribute to elevated premiums statewide, but urban and rural areas experience distinct cost pressures. For example, Detroit’s high theft rates and congestion drive up collision and comprehensive coverage costs, whereas rural areas like the Upper Peninsula see lower theft but higher winter-related claim frequencies. Below are average annual premiums for full coverage (state minimum: $20,000/$40,000 bodily injury, $10,000 property damage, plus PIP and unlimited medical coverage). ---Cost Comparison by Region
The following table presents average annual premiums for a 40-year-old driver with a clean record, insuring a 2018 Toyota Camry (average vehicle value in Michigan). Data is sourced from the Michigan Department of Insurance (2023) and Quadrant Information Services.| Region/City | Average Annual Premium (Full Coverage) | Key Cost Drivers |
|---|---|---|
| Detroit (Wayne County) | $3,200–$4,500 |
|
| Grand Rapids (Kent County) | $2,800–$3,800 |
|
| Lansing (Ingham County) | $2,500–$3,400 |
|
| Traverse City (Grand Traverse County) | $1,800–$2,600 |
|
| Upper Peninsula (e.g., Marquette, Ironwood) | $1,500–$2,300 |
|
Urban vs. Suburban vs. Rural Premium Influences
Location-based premium adjustments stem from statistical risk assessments. Below are the primary factors differentiating costs across Michigan’s geographic classifications. **Urban Areas (e.g., Detroit, Flint)** - **Accident Rates**: Higher frequency of fender benders and multi-vehicle collisions due to traffic congestion. - **Theft Vulnerability**: Detroit’s theft rate is **3x the national average**, increasing comprehensive coverage costs. - **Medical Costs**: Urban hospitals charge more for emergency services, raising PIP (Personal Injury Protection) claims. - **Insurance Fraud**: Higher incidence of staged accidents and exaggerated claims in densely populated zones. **Suburban Areas (e.g., Ann Arbor, Rochester Hills)** - **Mixed Risk Profile**: Lower theft than cities but higher than rural areas; accident rates rise near university campuses (e.g., Ann Arbor’s student population). - **Traffic Congestion**: Ann Arbor’s average commute delay costs insurers **$120M/year** in claims (Michigan State University Traffic Study, 2022). - **Home Insurance Bundles**: Suburban drivers often bundle auto with home insurance, qualifying for multi-policy discounts. **Rural Areas (e.g., Northern Michigan, Thumb Region)** - **Lower Liability Risks**: Fewer pedestrians and cyclists reduce bodily injury claims. - **Seasonal Claim Spikes**: Winter (November–March) accounts for **40% of rural collision claims** due to snow/ice (Michigan State Police, 2023). - **Limited Provider Competition**: Rural insurers may charge more due to higher operational costs per policy. ---High-Theft vs. Low-Theft Area Cost Disparities
Vehicle theft directly impacts comprehensive insurance premiums. Below is a comparison of average annual costs for a 2020 Honda Civic in high-theft (Detroit) vs. low-theft (Traverse City) regions, assuming identical driver profiles.| Coverage Type | Detroit (High-Theft) | Traverse City (Low-Theft) | Cost Difference |
|---|---|---|---|
| Comprehensive Insurance | $1,200–$1,800 | $600–$900 | +$600–$900 (50–100% higher) |
| Collision Insurance | $800–$1,200 | $700–$1,000 | +$100–$200 (14–20% higher) |
| Total Full Coverage | $3,200–$4,500 | $1,800–$2,600 | +$1,400–$1,900 (78–100% higher) |
Seasonal Variations in Insurance Claims and Costs
Michigan’s harsh winters and variable weather create predictable claim patterns. The table below outlines how seasonal conditions affect insurance costs, using Detroit and Traverse City as case studies.| Season | Primary Claim Drivers | Detroit Impact | Traverse City Impact | Premium Adjustment | ||||||||||||||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Winter (Nov–Mar) |
|
|
|
+$150–$300 annually (temporary rate hike). | ||||||||||||||||||||||||
| Spring (Apr–May) |
|
|
|