16 Essential Facts About Auto Insurance in NYC
Table of Contents
Auto insurance in NYC is a critical financial safeguard for drivers, legally mandating liability coverage to operate a vehicle in the city. For example, a taxi driver in Manhattan must carry at least $25,000 in bodily injury coverage per person, $50,000 per accident, and $10,000 in property damage—far above the state’s minimum requirements—to comply with both New York law and commercial fleet policies. Beyond legal compliance, auto insurance in NYC acts as a buffer against the city’s high accident rates, expensive repairs, and unpredictable weather, ensuring financial stability after collisions or theft.
The importance of securing the right policy cannot be overstated. NYC’s unique urban risks—dense traffic, frequent fender benders, and higher-than-average theft rates—demand tailored coverage. Historical data shows that uninsured motorist claims in NYC surged by 30% in the past decade, underscoring the need for robust uninsured motorist protection. Additionally, the city’s no-fault insurance system shifts medical costs to personal injury protection (PIP) coverage, adding another layer of complexity for drivers unfamiliar with local regulations.
This guide breaks down the core aspects of auto insurance in NYC, from navigating pricing dynamics to avoiding common pitfalls. It covers legal requirements, coverage types, cost-saving strategies, and real-world scenarios to help drivers make informed decisions.
1. Legal Requirements and NYC-Specific Rules
New York State mandates minimum liability coverage for all drivers, but NYC’s stricter regulations and commercial vehicle demands elevate the baseline. The state requires $25,000 per person/$50,000 per accident for bodily injury and $10,000 for property damage, but NYC’s high-risk environment often justifies higher limits. For instance, rideshare drivers like Uber or Lyft operators must carry commercial auto insurance during trips, which can cost 2-3 times more than personal policies.
Beyond liability, NYC drivers must carry no-fault insurance, which includes Personal Injury Protection (PIP) covering up to $50,000 per person for medical expenses, lost wages, and other related costs, regardless of fault. This system reduces lawsuits but requires drivers to file claims with their own insurer first. Violating these rules can result in fines up to $1,500 and license suspension.
2. Pricing Dynamics in a High-Cost City
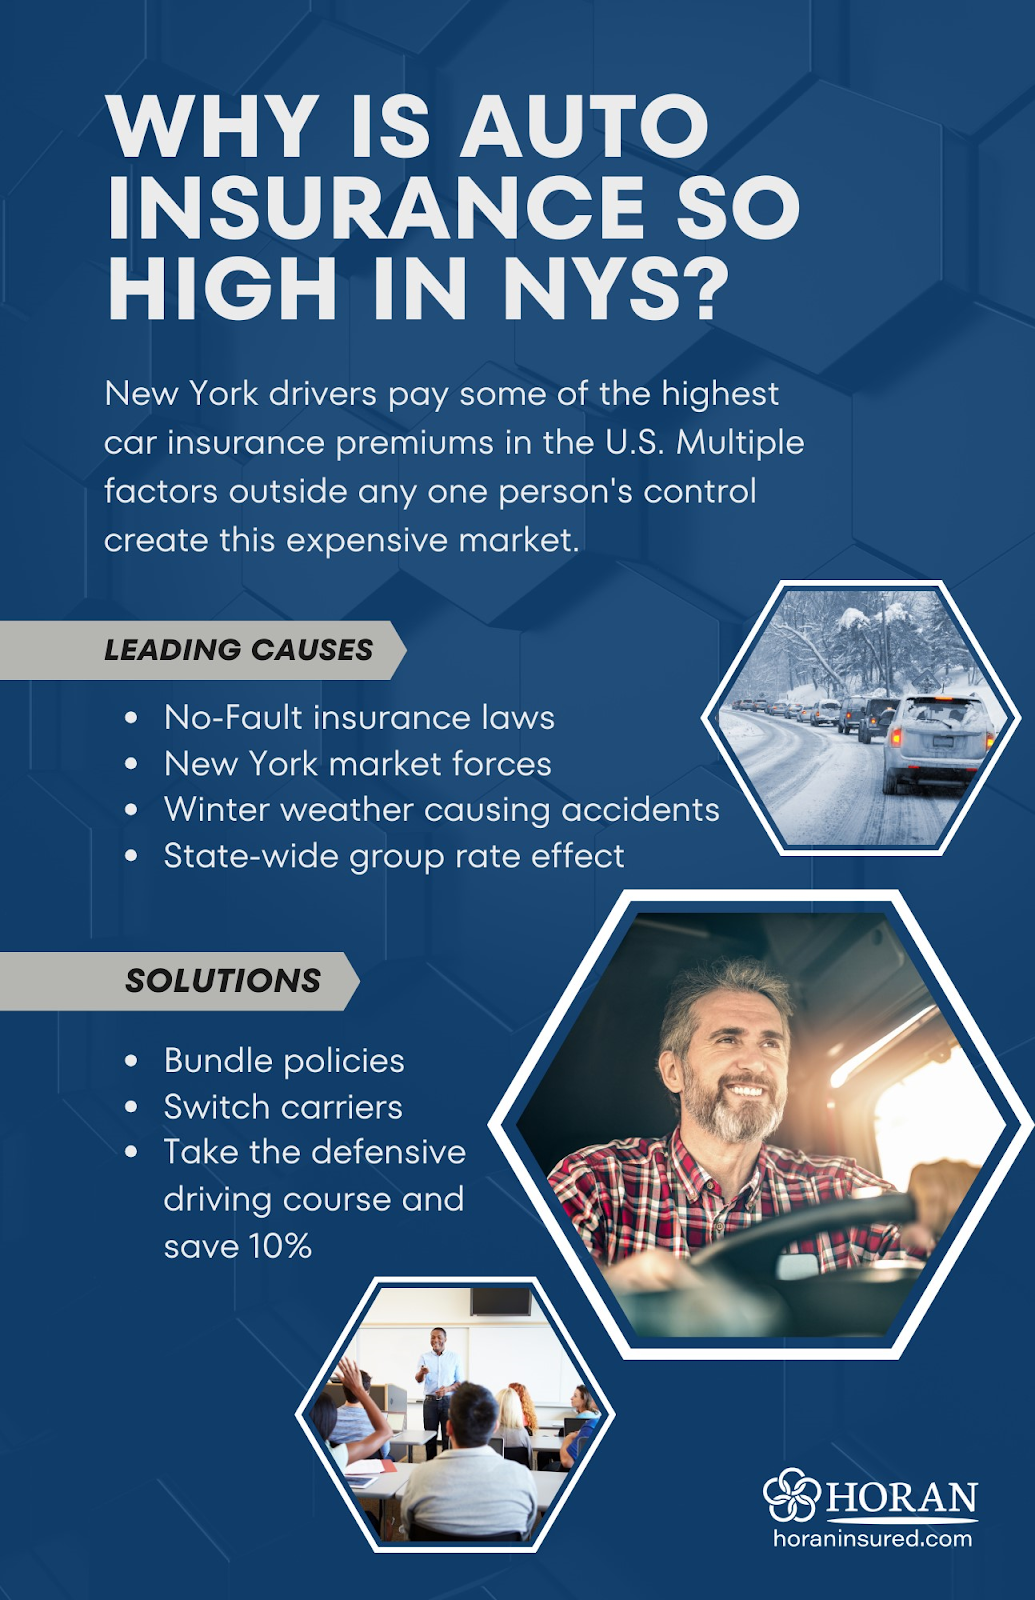
Auto insurance in NYC is notoriously expensive due to a combination of urban risks, high repair costs, and insurance fraud prevalence. The average annual premium in NYC hovers around $2,500—nearly double the national average—with rates varying significantly based on factors like vehicle type, driving history, and neighborhood. For example, a luxury car parked in Manhattan may see premiums exceeding $4,000 annually, while a compact car in Brooklyn could cost under $1,500.
Key factors influencing prices include:
- Vehicle Value and Repair Costs: High-end or imported vehicles with expensive parts (e.g., a Tesla Model 3) incur higher collision and comprehensive coverage costs. NYC’s limited parking and tight streets increase the risk of dents and scratches, raising repair expenses.
- Driving History and Credit Score: A single at-fault accident can increase premiums by 40-60% for 3-5 years. Meanwhile, a driver with a 750+ credit score might save 15-20% compared to someone with poor credit, as insurers use credit-based insurance scores in NY.
- Neighborhood and Parking Risks: Theft rates in areas like Harlem or parts of Queens can spike comprehensive coverage costs by 30%. Drivers in these zones may benefit from anti-theft device discounts or garage-parking incentives.
- Usage-Based Insurance Programs: Telematics programs like Progressive’s Snapshot or Allstate’s Drivewise track driving behavior (speed, braking, mileage) and offer discounts of 10-30% for safe drivers. A Brooklyn delivery driver reducing hard braking by 20% could see a $500 annual savings.
- Insurance Fraud Hotspots: Areas with higher fraud claims (e.g., parts of the Bronx) may lead insurers to adjust rates upward. Drivers in these zones should document incidents thoroughly to avoid false claims denials.
3. Coverage Types and What They Protect
Auto insurance in NYC typically includes six core coverage types, each serving distinct purposes. Liability coverage is the legal minimum but often insufficient for NYC’s high medical and repair costs. For example, a pedestrian accident in Times Square could easily exceed $50,000 in medical bills, leaving a driver underinsured. Collision coverage, which pays for vehicle damage from accidents, is essential for NYC’s narrow streets where minor impacts can total older cars.
Other critical coverages include:
- Comprehensive Insurance: Protects against non-collision events like theft, vandalism, or hail damage. NYC’s high theft rates—especially for high-value cars—make this a must-have. A stolen BMW in Midtown could cost $30,000 to replace without comprehensive coverage.
- Uninsured/Underinsured Motorist Coverage: Covers injuries or damages when the at-fault driver lacks insurance. NYC’s uninsured motorist rate is ~12%, so this coverage is vital. A hit-and-run victim in Queens might receive $25,000 in medical coverage under this policy.
- Personal Injury Protection (PIP): Mandatory in NYC, PIP covers medical bills, lost wages, and other expenses up to $50,000 per person, regardless of fault. A taxi driver injured in a no-fault accident could use PIP to cover $10,000 in hospital bills while their case is resolved.
- Rental Reimbursement: Pays for a rental car while the insured vehicle is being repaired. NYC’s public transit limitations make this coverage practical for drivers who rely on their car daily. A 4-week repair after a fender bender could cost $1,200 without this add-on.
- Roadside Assistance: Offers towing, battery jumps, or lockout services. In NYC, where AAA response times can be slow, this add-on provides peace of mind for $30-$50 annually.
4. How to Compare Quotes Like a Pro
Comparing quotes for auto insurance in NYC requires more than just price shopping; it involves evaluating coverage limits, deductibles, and insurer reputations. Drivers often overlook the fine print, such as how claims are handled or whether the insurer has a strong track record in NYC. For instance, State Farm and Allstate consistently rank highly for customer satisfaction in the city, while smaller regional insurers may offer lower rates but slower claim processing.
To compare effectively, drivers should:
- Use Multiple Quote Tools: Platforms like The Zebra or NerdWallet aggregate quotes from top insurers, including NYC specialists like HIPCO or MetLife. A driver inputting their details into three tools might find a 25% discrepancy in quoted premiums.
- Check Discount Eligibility: NYC insurers offer discounts for bundling homeowners insurance, low mileage, or safety features like anti-lock brakes. A Staten Island resident with a hybrid car and a homeowners policy could save $400 annually by bundling.
- Review Complaint Ratios: The NY Department of Financial Services publishes complaint data for insurers. A company with a high complaint ratio (e.g., 1 in 10 customers) may lead to delays in claim approvals.
- Ask About Claim Forgiveness: Some insurers (e.g., Progressive) offer one free accident without a premium increase. A first-time offender in Brooklyn could avoid a rate hike by choosing this policy.
- Verify Local Agent Expertise: Independent agents familiar with NYC’s no-fault system can tailor policies to specific needs, such as rideshare drivers or commercial fleets. An agent in Queens might recommend higher PIP limits for delivery drivers.
5. Common Mistakes to Avoid
Many drivers in NYC make avoidable errors that inflate costs or leave them underprotected. One frequent mistake is assuming the state’s minimum liability limits suffice. For example, a driver with only $25,000 bodily injury coverage could face a lawsuit for the remaining $75,000 if they cause a severe injury in a multi-car pileup on the FDR Drive. Another error is neglecting to update policies after major life changes, such as moving to a higher-theft neighborhood or purchasing a new vehicle.
Other pitfalls include:
- Skipping the Inspection: Some insurers require a vehicle inspection before issuing a policy, especially for older cars or modified vehicles. A 2010 Honda Civic with aftermarket rims might face a premium increase if not disclosed, leading to claim denials.
- Choosing the Lowest Deductible: A $250 deductible may seem affordable, but it can lead to higher premiums. A driver filing a $1,000 claim would pay $250 out-of-pocket, while a $1,000 deductible could save $300 annually in premiums.
- Ignoring Usage-Based Discounts: Drivers who rarely use their cars (e.g., a weekend-only driver in Brooklyn) may qualify for low-mileage discounts. A policyholder driving under 7,500 miles/year could save 10-15% by opting into a usage-based program.
- Assuming Full Coverage Equals Total Protection:
New York Motor Insurance - YouTube


