16+ Essential Facts About Auto Insurance Gap Protection You Need to Know
Table of Contents
- 1. How Gap Protection Works
- 2. Key Scenarios Where Gap Protection Matters
- 3. Eligibility and Common Exclusions
- 4. Cost Factors and Affordability
- 5. How to Purchase Gap Protection
- 6. Gap Protection vs. Other Coverage Types
- 7. Real-World Examples of Gap Protection in Action
- 8. Common Misconceptions About Gap Protection
- Frequently Asked Questions
- 16 Actionable Tips for Maximizing Gap Protection
- Conclusion
Auto insurance gap protection refers to a specialized coverage designed to bridge the financial gap between what an insurer pays after a total loss and the remaining balance on an auto loan or lease. For example, if a driver owes $25,000 on a financed vehicle but the insurer only reimburses $20,000 due to depreciation, gap protection covers the $5,000 shortfall, preventing the policyholder from owing money on a car they no longer own.
This type of coverage gained prominence in the 1990s as car depreciation accelerated and loan terms extended, leaving many drivers vulnerable to upside-down loans. Without gap protection, a total loss could force policyholders to pay off the remaining loan balance out of pocket, even after receiving a settlement from their insurer. Today, gap protection is widely offered as an add-on by lenders, dealerships, and insurance providers, particularly for newer vehicles or those financed for 60+ months.
This article explores the mechanics, benefits, and practical considerations of auto insurance gap protection, including how it integrates with standard policies, common misconceptions, and strategies to maximize its value. Key topics cover eligibility, cost factors, and real-world scenarios where gap protection proves critical.
1. How Gap Protection Works
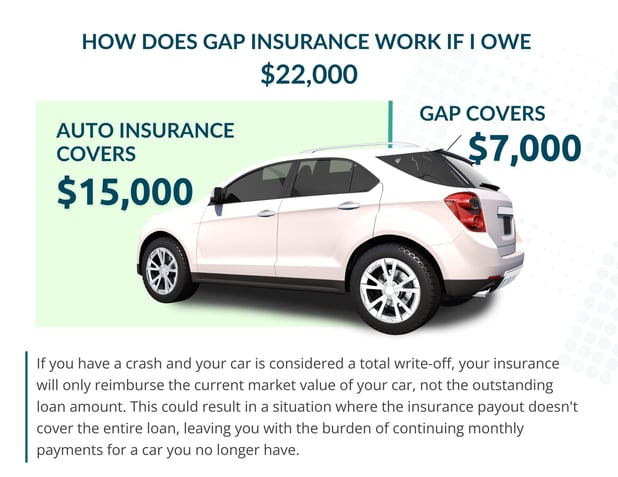
Auto insurance gap protection functions as a supplementary policy that activates when a primary auto insurance claim results in a total loss declaration. The primary insurer first pays the vehicle’s actual cash value (ACV) at the time of the loss, which is typically far less than the remaining loan balance due to rapid depreciation. Gap protection then covers the difference between the ACV and the outstanding loan amount, ensuring the policyholder isn’t left with a lingering debt.
For instance, a driver with a $30,000 loan on a 3-year-old car might receive a $15,000 payout from their insurer after a collision. Without gap protection, they’d still owe $15,000 to the lender. With it, the gap coverage would pay the remaining balance, eliminating the financial burden. This mechanism is especially valuable for vehicles that depreciate quickly, such as luxury cars or those with high-mileage guarantees.
2. Key Scenarios Where Gap Protection Matters
- Total Loss Claims
Gap protection is primarily triggered by total loss settlements, where repair costs exceed the vehicle’s ACV. In 2022, the Insurance Information Institute reported that total loss claims accounted for nearly 20% of all auto insurance claims, often due to severe accidents or natural disasters. Without gap protection, policyholders could face unexpected out-of-pocket expenses to settle their loan.
- Leased Vehicles
Lease agreements often require gap protection as a condition, given that lessees typically owe more than the vehicle’s depreciated value for most of the term. For example, a leaseholder with $22,000 remaining on a lease but only receiving a $17,000 payout from the insurer would owe the difference to the leasing company. Gap protection ensures the lessee isn’t financially responsible for the gap.
- Extended Loan Terms
Longer loan terms (e.g., 72 or 84 months) increase the risk of being upside-down on a loan. A vehicle financed for 7 years might lose 50%+ of its value within 3 years. Gap protection mitigates this risk by covering the difference between the loan balance and the insurer’s payout, which becomes more significant over time.
- Voluntary Total Loss
Some insurers offer a voluntary total loss option, where the policyholder accepts the ACV payout instead of repairing the vehicle. In such cases, gap protection ensures the remaining loan balance is fully covered, avoiding the need to liquidate personal assets or take on additional debt.
- Natural Disasters
Floods, hurricanes, or wildfires can destroy vehicles instantly, leaving owners with a total loss claim. Gap protection is critical here, as the ACV of a damaged vehicle may plummet, widening the financial gap. For example, a driver in a flood zone might receive a $10,000 payout for a car worth $25,000 in loans, with gap protection covering the $15,000 difference.
3. Eligibility and Common Exclusions
Eligibility for auto insurance gap protection typically depends on the vehicle’s age, loan status, and the policyholder’s driving history. Most providers require the vehicle to be less than 10 years old or have fewer than 100,000 miles, as older or high-mileage vehicles depreciate more rapidly. Additionally, gap protection is usually tied to the primary auto insurance policy, meaning the vehicle must be actively insured under that policy to qualify.
Common exclusions include pre-existing damage, mechanical failures, or losses due to unauthorized modifications. For example, a policyholder who modifies their car without notifying the insurer may void their gap protection in the event of a claim. Similarly, if a vehicle is stolen and not recovered, some gap protection policies exclude coverage for the deductible or additional fees. It’s essential to review the policy’s fine print to understand these limitations.

4. Cost Factors and Affordability
The cost of auto insurance gap protection varies based on several factors, including the vehicle’s purchase price, loan term, and the provider’s pricing model. Typically, gap protection costs between $200 and $600 for the duration of the loan, or it may be bundled into monthly payments of $10–$20. Some lenders or dealerships offer it for free or at a reduced rate as part of a financing package, particularly for newer or higher-priced vehicles.
For instance, a $40,000 car financed over 6 years might require gap protection costing $500 upfront or $15 per month. While this seems like an added expense, the potential savings in the event of a total loss—often thousands of dollars—can make it a cost-effective safeguard. Comparing quotes from multiple providers is advisable, as prices can differ significantly based on the insurer’s risk assessment and regional market conditions.
5. How to Purchase Gap Protection
Auto insurance gap protection can be purchased in several ways, each with distinct advantages. The most common methods include buying it directly from the auto insurer, through the lender or dealership at the time of financing, or as part of a comprehensive insurance package. Dealerships often promote gap protection as an add-on during the sales process, sometimes including it in promotional offers. However, purchasing it independently from an insurer may provide more flexibility and better terms.
Another option is to buy gap protection as a standalone policy from third-party providers, such as specialty insurers or credit unions. This approach allows policyholders to shop around for the best rates and coverage terms. Regardless of the purchase method, it’s crucial to confirm that the gap protection policy is transferable in case the vehicle is sold or the loan is assumed by another party. Some policies include this feature, while others may require additional documentation.
6. Gap Protection vs. Other Coverage Types
While auto insurance gap protection addresses the financial gap between a loan balance and an insurer’s payout, it differs from other types of coverage like collision, comprehensive, or loan/lease payoff protection. Collision and comprehensive insurance cover the cost of repairs or replacement up to the vehicle’s ACV but do not account for the loan balance. Loan/lease payoff protection, on the other hand, may cover the remaining loan balance in the event of death or disability but typically excludes total loss claims due to accidents or natural disasters.
For example, a policyholder with collision coverage might receive $22,000 to repair a totaled car, but if they owe $28,000, they’d still be responsible for the $6,000 difference. Gap protection fills this void by ensuring the loan is fully paid off, whereas other coverages may leave a financial shortfall. Understanding these distinctions helps policyholders tailor their insurance strategies to their specific needs, particularly for high-value or long-term financed vehicles.
7. Real-World Examples of Gap Protection in Action
Consider a scenario where a driver purchases a $35,000 SUV with a 6-year loan. After 3 years, the SUV is totaled in an accident. The insurer determines the ACV at $18,000, but the remaining loan balance is $27,000. Without gap protection, the driver would owe $9,000 out of pocket. With gap protection, the policy covers the $9,000 difference, allowing the driver to walk away from the loan without additional financial strain.
Another example involves a leased vehicle. A lessee with $15,000 remaining on their lease receives a $10,000 payout after a hailstorm damages the car beyond repair. The leasing company requires the lessee to pay the remaining $5,000, but gap protection reimburses this amount, preventing the lessee from incurring unexpected expenses. These real-world examples highlight how gap protection can provide peace of mind and financial security in unpredictable situations.
8. Common Misconceptions About Gap Protection
One prevalent misconception is that gap protection is only necessary for luxury or high-end vehicles. In reality, any vehicle with a loan or lease is at risk of depreciating faster than the loan balance is paid down, making gap protection relevant for a wide range of drivers. Even mid-range vehicles can experience significant depreciation, especially in the first few years of ownership.
Another myth is that gap protection is automatically included in standard auto insurance policies. This is rarely the case; it must be purchased separately or as an add-on. Additionally, some drivers assume that if they have a high deductible, gap protection won’t be worth the cost. However, the potential savings from a total loss claim often outweigh the upfront cost of the protection. Clarifying these misconceptions helps drivers make informed decisions about whether gap protection aligns with their financial goals.
16 Actionable Tips for Maximizing Gap Protection
Understanding how to leverage auto insurance gap protection can enhance its effectiveness and value. Here are 16 practical tips to consider:
Tip 1: Purchase gap protection at the time of financing. Securing gap protection early often results in lower costs and ensures full coverage from the start of the loan term.
Tip 2: Compare quotes from multiple providers. Prices for gap protection can vary significantly, so shopping around can lead to better rates and terms.
Tip 3: Review the policy’s exclusions carefully. Exclusions for modifications, theft, or mechanical failures can impact coverage, so understanding these upfront is critical.
Tip 4: Confirm whether gap protection is transferable. If planning to sell or trade in the vehicle, ensure the policy can be transferred or assume a new one is available.
Tip 5: Bundle gap protection with other insurance add-ons. Some insurers offer discounts for bundling gap protection with comprehensive or collision coverage, reducing overall costs.
Tip 6: Check if your lender offers free or discounted gap protection. Many lenders include gap protection as part of promotional financing deals, making it a cost-effective option.
Tip 7: Avoid rolling gap protection costs into the loan. While convenient, this can increase the total loan amount and interest paid over time.
Tip 8: Monitor your vehicle’s depreciation rate. Vehicles that depreciate rapidly may benefit more from gap protection, so tracking this can help determine its necessity.
Tip 9: Ensure gap protection covers the full loan balance. Some policies may only cover a portion of the gap, so verifying the coverage limits is essential.
Tip 10: Disclose all modifications to the insurer. Failing to disclose modifications can void gap protection in the event of a claim, so transparency is key.
Tip 11: Consider gap protection for leased vehicles. Leases often require gap protection due to the high risk of being upside-down on the loan.
Tip 12: Review your policy annually for updates. Life changes, such as refinancing or extending a loan, may require adjustments to gap protection coverage.
Tip 13: Ask about waiver options if you lose your job. Some gap protection policies offer waivers in cases of unemployment or disability, providing additional financial security.
Tip 14: Keep documentation of your vehicle’s value. Maintaining records of the car’s purchase price, loan terms, and appraisals can streamline claims processing.
Tip 15: Understand the claims process for gap protection. Knowing the steps to file a claim and the required documentation can expedite reimbursement after a total loss.
Tip 16: Reassess gap protection as your loan balance decreases. As the loan balance shrinks, the need for gap protection may diminish, allowing for potential cost savings by canceling the policy.
Conclusion
Auto insurance gap protection serves as a critical safeguard against the financial risks of being upside-down on an auto loan, particularly in the event of a total loss. By bridging the gap between an insurer’s payout and the remaining loan balance, it prevents policyholders from facing unexpected out-of-pocket expenses. Key aspects include understanding how gap protection works, identifying scenarios where it provides the most value, and navigating eligibility requirements and cost factors. Real-world examples demonstrate its practical benefits, while addressing common misconceptions ensures drivers make informed decisions.
As vehicles continue to depreciate rapidly and loan terms extend, gap protection remains a valuable tool for financial security. Evaluating its role in a comprehensive insurance strategy can provide peace of mind and protect against the uncertainties of the road ahead.
Related articles

Get Auto Insurance Online Quotes Fast Accurate And Smart
Compare Get Auto Insurance Online Quotes Fast Accurate And Smart—save time, money, and hassle with instant, tailored coverage options today.

Auto Insurance Online Purchase Transforms Driving Protection Today
Discover how Auto Insurance Online Purchase Transforms Driving Protection Today—fast quotes, digital policies, and 24/7 access simplify coverage. Learn…
Auto Insurance Online Cheap Unlocking Savings With Smart Choices
Discover how to get Auto Insurance Online Cheap Unlocking Savings With Smart Choices—compare quotes, leverage discounts, and optimize coverage for…

11+ Smart Moves to Master Auto Insurance in North Carolina
Auto insurance in North Carolina is a must—discover how to save, avoid pitfalls, and pick the right coverage. Learn pricing secrets, claim tips, and…

Auto Insurance New York City Essentials Drivers Must Know
Discover key Auto Insurance New York City Essentials Drivers Must Know—coverage rules, SR-22 requirements, and cost-saving tips for NYC roads.
