11+ Key Facts About Auto Insurance for Non Owners
Table of Contents
Auto insurance for non owners refers to a specialized policy designed for individuals who drive but do not own a vehicle. For example, a rideshare driver like Sarah, who uses her personal car for Uber trips but doesn’t own it outright, would need this type of coverage to meet legal requirements and protect against liability. This insurance fills a critical gap for those who rely on borrowed, leased, or rented vehicles or frequently drive cars they don’t own long-term.
The importance of auto insurance for non owners cannot be overstated. In the U.S., every state mandates minimum liability coverage for drivers, regardless of vehicle ownership. Without it, risks like accidents causing property damage or bodily injury expose individuals to lawsuits, fines, or license suspension. Historically, this coverage evolved to address the needs of drivers who lacked traditional auto policies but still faced legal and financial risks. It also serves as a safeguard for those who drive occasionally, such as family members borrowing a car or individuals renting vehicles for cross-country trips.
This article explores the mechanics, benefits, and practical considerations of auto insurance for non owners, including how pricing works, coverage options, and common pitfalls. Whether navigating legal requirements or seeking cost-effective solutions, understanding these aspects ensures compliance and financial protection.
1. What It Covers
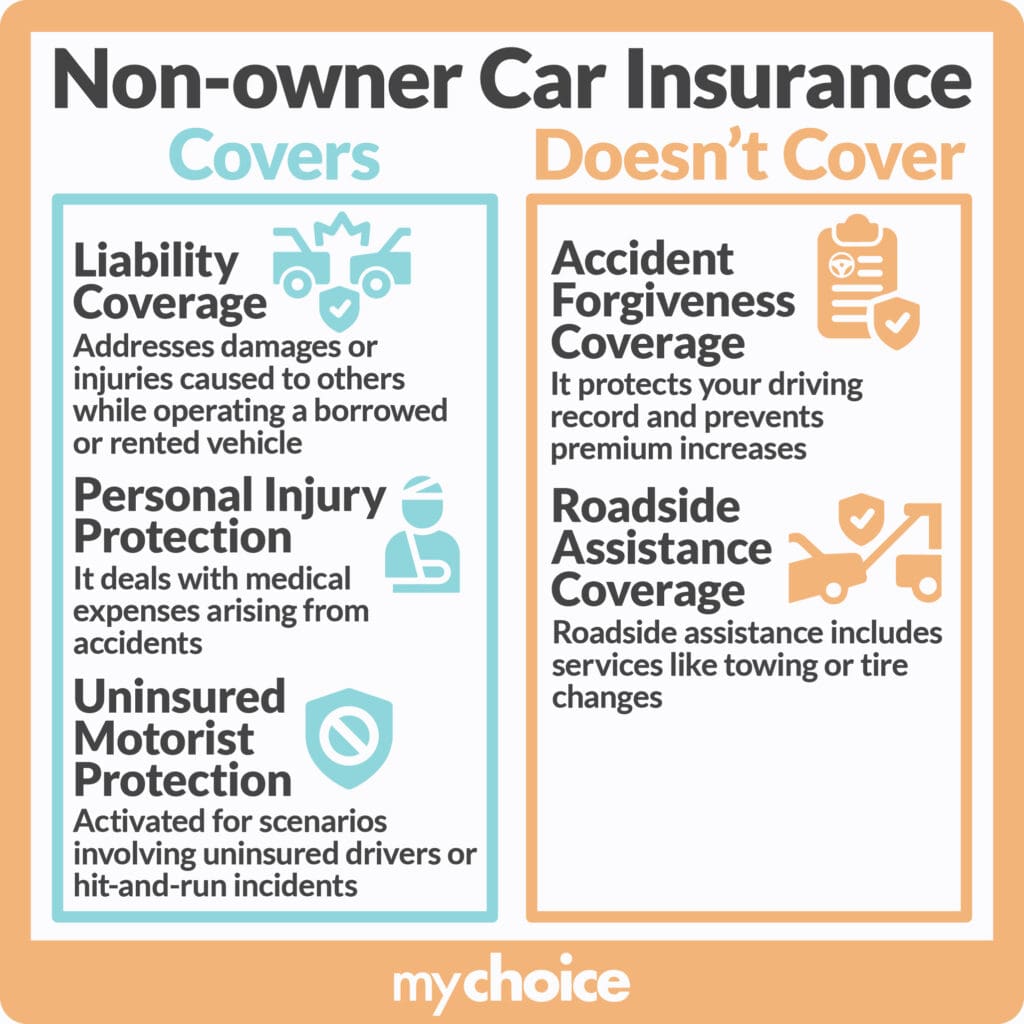
Auto insurance for non owners typically includes liability coverage, which pays for damages or injuries the insured causes while driving a vehicle they don’t own. Some policies extend to collision and comprehensive coverage, though these are less common and often require additional premiums. For instance, a policyholder using a leased car for daily commutes might opt for collision coverage to protect against accidents that damage the leased vehicle.
Liability limits vary by state and policy but generally cover bodily injury and property damage. In states like California, minimum limits are 15/30/5 (per person/per accident/property damage), while others mandate higher thresholds. Non-owner policies often exclude coverage for the vehicle itself, meaning the owner’s insurance (or a rental agreement) would handle physical damage claims.
Key distinctions arise when comparing non-owner policies to standard auto insurance. Non-owner policies are not tied to a specific vehicle, making them ideal for drivers who switch cars frequently. However, they may not cover medical payments or uninsured motorist protection unless explicitly added.
2. Pricing Dynamics
The cost of auto insurance for non owners hinges on several factors, including driving history, location, and coverage limits. On average, non-owner policies cost between $300 and $800 annually, though rates can spike for high-risk drivers. For example, a driver with a clean record in Texas might pay around $400 yearly, while someone with prior at-fault accidents could see rates exceed $1,200.
Insurers assess risk based on driving frequency, vehicle type (if specified), and credit history in some states. Urban drivers often face higher premiums due to increased accident rates and traffic congestion. Discounts may apply for bundling with homeowners insurance or maintaining a low annual mileage.
Shopping around is critical, as rates vary significantly between providers. Independent agents can compare quotes from multiple insurers, potentially uncovering savings. States like Virginia and North Carolina offer lower average costs due to competitive markets, while urban centers like Los Angeles tend to have higher premiums.
3. Who Needs It
Auto insurance for non owners is essential for specific groups, including:
- Rideshare and delivery drivers: Platforms like Uber and DoorDash require drivers to maintain insurance, but personal policies may not suffice. A non-owner policy bridges this gap, ensuring compliance with platform rules and state laws. For example, a Lyft driver using a friend’s car must carry liability coverage to meet the app’s insurance requirements.
- Leasees and borrowers: Individuals leasing vehicles or frequently borrowing cars from family members benefit from non-owner policies to avoid gaps in coverage. Without it, an accident could leave them personally liable for damages exceeding the vehicle owner’s policy limits.
- International students and expats: Many states mandate insurance for all drivers, including those without U.S. residency. An international student driving a rental car for a road trip would need a non-owner policy to comply with local laws and protect against unforeseen incidents.
- Occasional drivers: People who drive infrequently, such as those who rent cars for vacations or use car-sharing services, can secure temporary coverage through non-owner policies. This avoids the hassle of canceling and reinstating a traditional policy for short-term needs.
- High-risk drivers: Individuals with suspended licenses or prior DUIs may find non-owner policies more accessible than standard auto insurance. These policies can help rebuild driving records by demonstrating financial responsibility, though they often come at a higher cost.
4. Legal Requirements
Legal obligations for auto insurance for non owners vary by state but universally require proof of liability coverage. In states like New Jersey, drivers must carry at least $15,000 in bodily injury coverage per person and $30,000 per accident, along with $5,000 for property damage. Failure to maintain coverage can result in license suspension, fines, or vehicle impoundment.
Some states, such as Virginia, allow drivers to post cash bonds or securities as alternatives to insurance, but non-owner policies remain the most practical solution for compliance. For drivers with suspended licenses, an SR-22 certificate—often required for reinstatement—can be obtained through a non-owner policy, provided the insurer offers this service.
Understanding state-specific rules is crucial. For instance, no-fault states like Michigan require personal injury protection (PIP) coverage, which non-owner policies may exclude. Drivers must verify whether their policy aligns with local regulations to avoid legal repercussions.
5. Common Mistakes
Missteps when pursuing auto insurance for non owners often stem from misunderstandings about coverage limits, provider restrictions, or eligibility. One frequent error is assuming a non-owner policy covers a rented vehicle without checking the rental agreement. Many rental car contracts mandate the renter’s personal insurance, making the non-owner policy redundant unless explicitly required.
Another oversight involves underestimating the need for additional coverage. Drivers may opt for minimal liability limits, only to face financial strain from a severe accident. For example, a driver with $25,000 in bodily injury coverage could be personally liable for excess medical costs if injuries exceed this amount.
Provider restrictions also trip up policyholders. Some insurers exclude coverage for commercial use, leaving rideshare drivers vulnerable. Always review the policy’s fine print to ensure it aligns with intended usage, such as occasional personal driving versus frequent business use.
6. How to Get It
Obtaining auto insurance for non owners involves a straightforward process: assessing needs, comparing quotes, and selecting a provider. Start by identifying coverage requirements based on driving habits and state laws. For instance, a driver in Florida may need higher limits due to the state’s high traffic accident rates.
Next, gather necessary information, including a driver’s license, proof of residency, and vehicle details (if applicable). Some insurers offer online quotes, while others require agent assistance for complex scenarios, such as SR-22 filings. Bundling with other policies, like renters or homeowners insurance, can reduce costs.
Reputable insurers specializing in non-owner policies include Geico, Progressive, and The General. Each offers varying levels of customization, from basic liability to added perks like roadside assistance. Drivers should prioritize insurers with strong customer service ratings and a history of claims payouts.
7. Comparison with Other Policies
Non-owner policies differ from standard auto insurance in key ways, primarily in their flexibility and exclusions. Standard policies are tied to a specific vehicle and its VIN, making them unsuitable for drivers who switch cars frequently. In contrast, non-owner policies are vehicle-agnostic, covering any car the insured operates with permission.
Another distinction lies in coverage scope. Non-owner policies rarely include physical damage coverage for the vehicle itself, as the owner’s insurance typically handles such claims. However, they may offer optional add-ons like rental reimbursement or medical payments, depending on the insurer.
For drivers who occasionally rent cars, a non-owner policy can serve as a primary layer of protection, though rental agreements often require additional coverage. Comparing the two ensures drivers select the most cost-effective and comprehensive option for their needs.
11 Tips for Choosing Auto Insurance for Non Owners
Selecting the right auto insurance for non owners requires careful consideration of coverage, cost, and provider reputation. Here are 11 actionable tips to guide the decision:
Tip 1: Verify state minimum requirements. Confirm the liability limits mandated in your state to ensure compliance and avoid legal penalties.
Tip 2: Compare quotes from multiple insurers. Use online tools or independent agents to evaluate rates and coverage options from providers like Geico, Progressive, and The General.
Tip 3: Check for discounts. Ask about bundling discounts, low-mileage discounts, or safe driver incentives to reduce premiums.
Tip 4: Review policy exclusions. Ensure the policy aligns with your driving habits, especially if you use rental cars or drive for commercial purposes.
Tip 5: Consider an umbrella policy. For added liability protection, supplement your non-owner policy with an umbrella policy that covers excess claims.
Tip 6: Read customer reviews. Research insurers’ claims handling and customer service ratings on platforms like J.D. Power or the BBB.
Tip 7: Ask about SR-22 assistance. If you need an SR-22 for license reinstatement, confirm the insurer can file it on your behalf.
Tip 8: Avoid gaps in coverage. Ensure your non-owner policy doesn’t conflict with the vehicle owner’s insurance to prevent claim denials.
Tip 9: Update your policy annually. Review and adjust coverage as your driving needs or state laws change.
Tip 10: Consider usage-based insurance. Some insurers offer telematics programs that monitor driving behavior, potentially lowering premiums for safe drivers.
Tip 11: Consult an independent agent. For complex scenarios, such as international driving or high-risk profiles, an agent can tailor a policy to your specific needs.
Conclusion
Auto insurance for non owners serves as a vital safeguard for drivers who operate vehicles they don’t own, offering liability protection and legal compliance without the constraints of traditional policies. Key aspects include understanding coverage limits, navigating pricing dynamics, and avoiding common pitfalls like misaligned rental agreements or insufficient liability limits. Whether for rideshare drivers, leaseholders, or occasional borrowers, this insurance ensures financial security and adherence to state laws.
As driving habits evolve—with the rise of car-sharing, rideshare economies, and international travel—non-owner policies will continue to adapt. Staying informed about policy options, legal requirements, and cost-saving strategies empowers drivers to make confident, well-protected choices on the road.
Related articles

Get Auto Insurance Online Quotes Fast Accurate And Smart
Compare Get Auto Insurance Online Quotes Fast Accurate And Smart—save time, money, and hassle with instant, tailored coverage options today.

Auto Insurance Online Purchase Transforms Driving Protection Today
Discover how Auto Insurance Online Purchase Transforms Driving Protection Today—fast quotes, digital policies, and 24/7 access simplify coverage. Learn…
Auto Insurance Online Cheap Unlocking Savings With Smart Choices
Discover how to get Auto Insurance Online Cheap Unlocking Savings With Smart Choices—compare quotes, leverage discounts, and optimize coverage for…

11+ Smart Moves to Master Auto Insurance in North Carolina
Auto insurance in North Carolina is a must—discover how to save, avoid pitfalls, and pick the right coverage. Learn pricing secrets, claim tips, and…

Auto Insurance New York City Essentials Drivers Must Know
Discover key Auto Insurance New York City Essentials Drivers Must Know—coverage rules, SR-22 requirements, and cost-saving tips for NYC roads.
