10 Key Facts About Auto Insurance for Collector Cars
Auto insurance for collector cars is a niche but critical form of coverage tailored to vehicles valued for their rarity, historical significance, or performance rather than everyday use. For example, a 1967 Shelby GT500KR—one of only 1,000 produced—requires specialized protection beyond standard auto policies, which often exclude or undervalue such assets. This type of insurance addresses unique risks, from mechanical failures in vintage engines to theft targeting limited-edition models, while also accounting for depreciation patterns that differ sharply from mass-produced cars.
The importance of auto insurance for collector cars cannot be overstated, as these vehicles often represent decades of investment, cultural heritage, or family legacy. Without proper coverage, owners risk financial ruin from a single accident or restoration project gone wrong. Historically, classic car clubs and insurers collaborated to create tailored policies in the 1970s as enthusiasts recognized the need for protection beyond basic liability. Today, the market has expanded to include agile coverage options, from agreed-value policies to specialized roadside assistance for antique vehicles.
This guide explores the essential aspects of auto insurance for collector cars, from determining the right coverage type to navigating common pitfalls. Whether evaluating insurers, understanding claim processes, or optimizing storage solutions, the right approach ensures collectors preserve both their vehicles and their peace of mind.
1. Coverage Types and Agreed Value
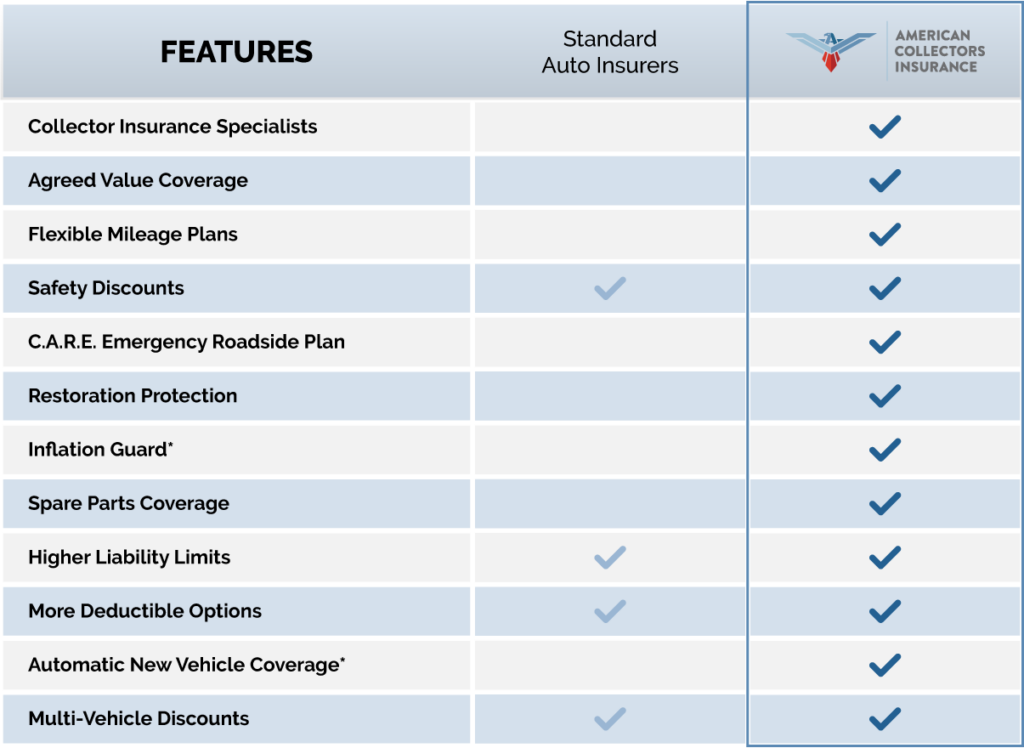
Auto insurance for collector cars typically falls into two primary categories: **agreed value** and **stated value**. Agreed value policies, the gold standard for enthusiasts, require the insurer and owner to mutually agree on the car’s worth upfront, ensuring payouts match the vehicle’s true market value in case of total loss. For instance, a 1955 Mercedes-Benz 300SL Gullwing, appraised at $4.5 million, would receive that full amount if destroyed, regardless of depreciation. Stated value policies, meanwhile, offer a declared value but may devalue the car over time, leaving owners vulnerable to undercompensated claims.
Another critical facet is **specialized endorsements**, which extend protection beyond collisions. These can include coverage for mechanical breakdowns in vintage engines, theft of rare parts, or even transportation risks during shows. For example, a policy for a 1993 McLaren F1 might cover the cost of a specialized transporter if the car is damaged during a cross-country haul. Understanding these endorsements helps collectors tailor their auto insurance for collector cars to their vehicle’s specific vulnerabilities.
2. Pricing Dynamics
Pricing for auto insurance for collector cars hinges on three core factors: **vehicle value, usage frequency, and storage conditions**. Unlike standard policies that prioritize driving records, collector car insurance emphasizes the car’s rarity, maintenance history, and how often it’s driven. A 1964 Ford Mustang fastback used exclusively for weekend cruises will command lower premiums than a 1970 Porsche 911S driven daily on winding roads. Insurers also scrutinize storage—garages with climate control and security systems reduce risk, while open-air parking in high-theft areas can spike costs.
**Appraisal accuracy** plays a pivotal role in pricing. An overinflated appraisal may lead to higher premiums, while an undervalued car could result in inadequate coverage. For example, a 1986 Ferrari Testarossa appraised at $120,000 might see premiums drop if reassessed at $150,000 due to restored documentation or rare color options. Regular appraisals ensure policies remain aligned with market fluctuations, a practice recommended every 2–3 years for vehicles worth over $50,000.
3. Common Mistakes to Avoid
Owners often overlook critical aspects of auto insurance for collector cars, leading to gaps in protection or financial exposure. Below are the most frequent missteps:
- Underestimating storage risks: Storing a collector car in an unsecured location or without environmental controls (e.g., humidity, temperature) invites damage from pests, weather, or theft. A 1969 Jaguar E-Type left in an uncovered barn for a year developed rust damage costing $20,000 to repair—a claim denied by standard policies. Climate-controlled, alarmed garages are non-negotiable for vehicles valued above $100,000.
- Skipping comprehensive appraisals: Relying on online valuation tools or outdated guides can lead to severe underinsurance. A 1971 Chevrolet Corvette Stingray, for instance, might be listed at $85,000 on a generic site but fetch $120,000 at auction due to its original paint and matching numbers. Professional appraisals from organizations like the Antique Automobile Club of America (AACA) ensure accuracy.
- Ignoring usage restrictions: Many policies assume collector cars are driven infrequently. Exceeding mileage limits or using the vehicle for daily commutes can void coverage. A policyholder driving a 1990 Mazda RX-7 240 miles monthly for track days saw their premiums quadruple when the insurer classified it as a
American Collectors - Best Collector Car Insurance - MrCarGeek 
Auto Insurance, Las Vegas, Reno -- Estrella Insurance Services -- Local commerci
Frequently Asked Questions
How does mileage affect premiums for collector cars?
Mileage is a top factor in pricing. Policies assume collector cars are driven fewer than 3,500 miles annually. Exceeding this—especially for daily use—can double premiums. Insurers like Hagerty offer discounts for cars driven under 1,500 miles/year, as lower mileage reduces wear-and-tear and accident risks.
Can I insure a modified collector car?
Modified collector cars require **full disclosure** of changes to avoid claim denials. Insurers may exclude coverage for non-period-correct modifications (e.g., modern engines in a 1960s muscle car). Documenting modifications with receipts and expert appraisals ensures accurate valuation and coverage.
What’s the difference between agreed and stated value?
Agreed value guarantees the pre-determined price if the car is totaled, while stated value may depreciate over time. For a $200,000 Ferrari, agreed value ensures a full payout; stated value might pay only $150,000 after 5 years. Agreed value costs 15–30% more but offers superior protection.
Do I need separate insurance for a trailer hauling my collector car?
Yes. Trailers require their own policy or endorsement, as standard auto insurance excludes them. A 1975 Land Rover used to tow a classic car needs **trailer liability coverage** (minimum $100,000) and **physical damage protection** for the trailer itself. Insurers like Progressive offer bundled policies for vehicles and trailers.
How often should I update my collector car’s appraisal?
Appraisals should be updated every **2–3 years** or after major events (restorations, auctions, market shifts). A 1992 Mazda RX-7’s value surged 40% post-restoration, but an outdated appraisal could leave the owner underinsured. Professional appraisers from organizations like the AACA provide market-accurate valuations.
What’s the best way to reduce storage-related risks?
Invest in **climate-controlled, alarmed storage** with 24/7 surveillance. Facilities like **Classic Car Storage** in Arizona or **The Vault** in New York offer fire suppression, humidity control, and GPS tracking. These measures can reduce premiums by 10–25% and prevent weather-related damage.
Related articles

Get Auto Insurance Online Quotes Fast Accurate And Smart
Compare Get Auto Insurance Online Quotes Fast Accurate And Smart—save time, money, and hassle with instant, tailored coverage options today.

Auto Insurance Online Purchase Transforms Driving Protection Today
Discover how Auto Insurance Online Purchase Transforms Driving Protection Today—fast quotes, digital policies, and 24/7 access simplify coverage. Learn…
Auto Insurance Online Cheap Unlocking Savings With Smart Choices
Discover how to get Auto Insurance Online Cheap Unlocking Savings With Smart Choices—compare quotes, leverage discounts, and optimize coverage for…

11+ Smart Moves to Master Auto Insurance in North Carolina
Auto insurance in North Carolina is a must—discover how to save, avoid pitfalls, and pick the right coverage. Learn pricing secrets, claim tips, and…

Auto Insurance New York City Essentials Drivers Must Know
Discover key Auto Insurance New York City Essentials Drivers Must Know—coverage rules, SR-22 requirements, and cost-saving tips for NYC roads.
