8 Key Insights into American Home Shield Plans: Coverage, Costs, and Comparisons
Table of Contents
- 1. Coverage Scope of American Home Shield Plans
- 2. Pricing Dynamics and Plan Options
- 3. How Claims Work with American Home Shield
- 4. American Home Shield vs. Competitors
- 5. Best Use Cases for American Home Shield Plans
- 6. Common Misconceptions About American Home Shield Plans
- 7. How to Choose the Right American Home Shield Plan
- 8. Pro Tips for Maximizing American Home Shield Benefits
- Tips for Optimizing American Home Shield Plans
- Conclusion
American Home Shield plans refer to a suite of home warranty programs designed to protect homeowners from unexpected repair costs for major home systems and appliances. For example, a policyholder with an American Home Shield plan might receive coverage for a malfunctioning HVAC system or a refrigerator breakdown, avoiding the full out-of-pocket expense. These plans typically cover essential systems like heating, cooling, plumbing, electrical, and built-in appliances, offering financial relief when repairs exceed $50 or more.
The importance of American Home Shield plans lies in their ability to mitigate financial strain caused by home repairs, which often exceed $1,000 per incident. According to industry data, nearly 50% of homeowners face unexpected repair costs annually, making these plans a practical safeguard. Historically, home warranties emerged as a response to the rising costs of home maintenance, providing an affordable alternative to homeowners insurance. Today, American Home Shield stands as one of the largest providers, offering tailored plans for single-family homes, condos, and even landlords.
This article explores the nuances of American Home Shield plans, from coverage specifics to cost considerations, and how they stack up against competitors. Whether evaluating a new policy or comparing options, understanding these key aspects ensures homeowners make informed decisions.
1. Coverage Scope of American Home Shield Plans
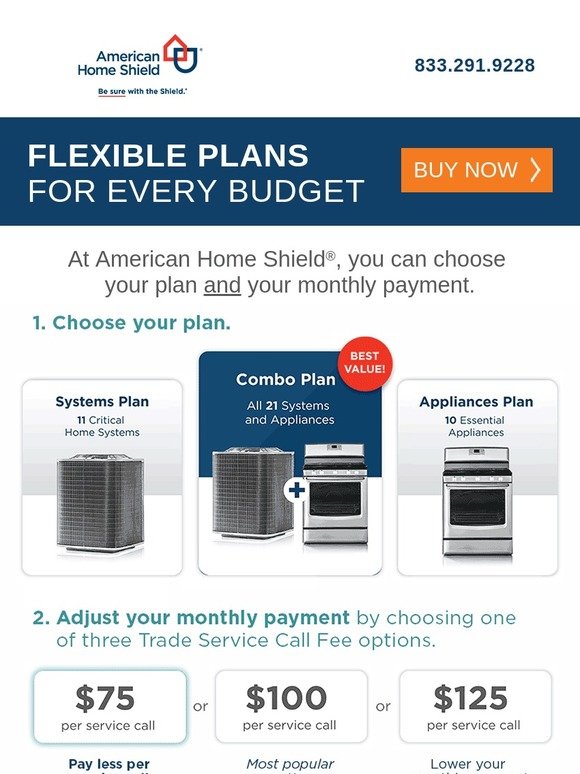
American Home Shield plans typically cover 11 major home systems and appliances, including heating, cooling, plumbing, electrical, and built-in appliances like refrigerators and ovens. Each plan—such as the Home Systems Protection Plan or the Appliance Protection Plan—targets specific needs, with the former focusing on structural systems and the latter on appliances. For instance, a homeowner with a Home Systems Protection Plan might receive coverage for a water heater replacement, while an Appliance Protection Plan would cover a dishwasher motor failure.
Coverage limits vary by plan, often ranging from $2,500 to $5,000 per incident, with annual limits of $10,000. Exclusions, such as pre-existing conditions or cosmetic damage, are critical to review. For example, a plan may not cover a furnace issue if it was malfunctioning before enrollment, highlighting the need for thorough policy reviews.
2. Pricing Dynamics and Plan Options
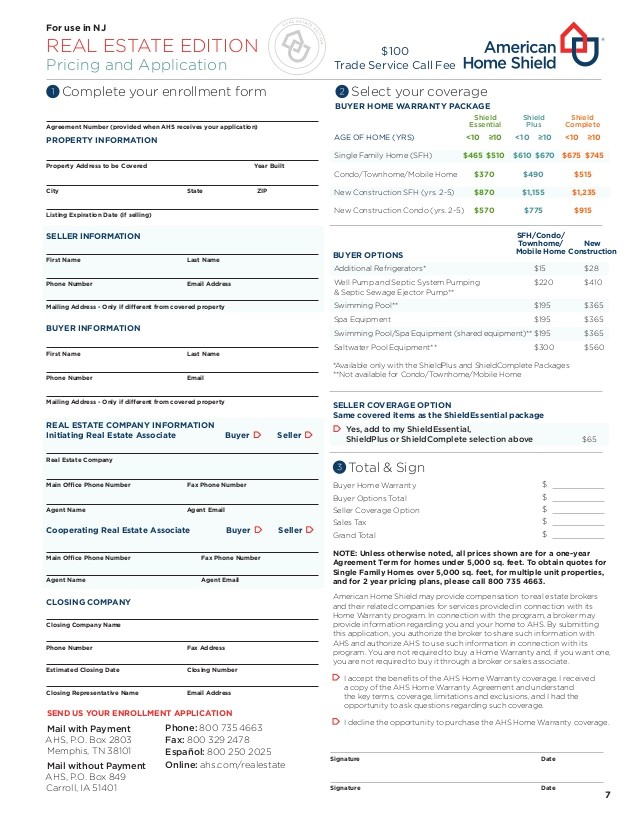
Pricing for American Home Shield plans depends on factors like home age, location, and coverage level. Basic plans start around $300 annually for appliances, while comprehensive systems coverage can exceed $600. Discounts are available for bundling plans or enrolling in automatic payments. For example, a homeowner in Florida might pay $450 for a full systems plan, while a similar policy in Texas could cost $550 due to regional repair cost variances.
Plan options include:
- Home Systems Protection Plan: Covers structural systems like HVAC, plumbing, and electrical. Ideal for homeowners prioritizing long-term system reliability, this plan often includes a 90-day parts labor coverage extension, reducing out-of-pocket costs for follow-up repairs.
- Appliance Protection Plan: Focuses on built-in appliances such as refrigerators, washers, and ovens. This is particularly useful for landlords or homeowners with older appliances, as it caps repair costs at the plan’s service call fee, typically $75-$125.
- Landlord Protection Plan: Tailored for rental properties, this plan covers tenant-caused damage to systems and appliances, provided the tenant is responsible for the deductible. For example, a landlord could avoid a $1,200 plumbing repair bill if a tenant accidentally clogs a drain.
- Add-On Coverage: Includes options like pool/spa equipment or well pump coverage. Adding pool equipment to a standard plan might increase annual costs by $150-$200 but ensures coverage for critical components like pumps or heaters.
- Deductible Flexibility: Plans offer deductible choices ranging from $0 to $250. A $100 deductible reduces premiums but increases out-of-pocket costs per claim. Homeowners with older homes may opt for a $0 deductible to avoid higher upfront expenses during repairs.
3. How Claims Work with American Home Shield
Filing a claim with American Home Shield involves contacting the company’s customer service to schedule a service call. A technician assesses the issue, and if covered, repairs or replacements are arranged. For example, a homeowner reporting a broken water heater would first call American Home Shield, who would dispatch a plumber. If the issue is covered, the homeowner pays a service call fee (e.g., $75), and the plan covers the rest up to the limit.
Processing times vary, but most claims are resolved within 24-48 hours. Homeowners should keep receipts and documentation of prior repairs, as pre-existing conditions are often excluded. For instance, a claim for a 10-year-old furnace might be denied if the policyholder didn’t disclose prior maintenance issues.

4. American Home Shield vs. Competitors
American Home Shield competes with providers like Choice Home Warranty, First American Home Warranty, and local insurers. Key differentiators include coverage breadth, customer service ratings, and pricing transparency. For example, American Home Shield’s Appliance Protection Plan may cover more appliance models than Choice Home Warranty, while First American offers lower premiums in some regions. Customer reviews highlight American Home Shield’s responsive service but note slower claim processing compared to competitors.
When comparing, homeowners should evaluate:
- Coverage Limits: American Home Shield’s $5,000 per incident limit may be higher than competitors’ $3,500 cap, offering better protection for high-cost repairs like HVAC replacements.
- Service Network: American Home Shield partners with over 10,000 contractors, ensuring faster response times in populated areas. In rural regions, smaller providers may have better local coverage.
- Customer Support: American Home Shield’s 24/7 claims service is a standout, but competitors like First American offer dedicated account managers for landlords, improving claim oversight.
- Add-On Flexibility: American Home Shield allows customizable add-ons, such as pool equipment or structural pest control, which some competitors bundle at higher costs.
- Renewal Policies: Unlike some providers, American Home Shield offers renewal discounts for long-term policyholders, incentivizing loyalty with reduced annual premiums.
5. Best Use Cases for American Home Shield Plans
American Home Shield plans are most beneficial for homeowners with older homes, landlords managing rental properties, or individuals facing high repair risks. For example, a homeowner with a 25-year-old HVAC system might save thousands by enrolling in a systems protection plan, as replacement costs can exceed $10,000. Similarly, landlords benefit from tenant-caused damage coverage, reducing liability risks.
First-time homebuyers may also find value in these plans, as they provide an affordable way to address unexpected repairs without draining savings. However, homeowners with new construction or comprehensive homeowners insurance may prioritize other financial protections, as warranty plans typically exclude pre-existing conditions.
6. Common Misconceptions About American Home Shield Plans
A prevalent misconception is that American Home Shield plans replace homeowners insurance. In reality, they serve as complementary coverage for systems and appliances, not structural damage or liability. Another myth is that all repairs are fully covered; deductibles, service call fees, and exclusions apply. For instance, a homeowner might assume a roof leak is covered, but structural damage is excluded unless specified in add-on policies.
Additionally, some believe enrollment guarantees immediate coverage, but there’s often a 30-day waiting period before claims are processed. Homeowners should also clarify whether routine maintenance (e.g., HVAC filter changes) is covered, as most plans exclude preventative care.
7. How to Choose the Right American Home Shield Plan
Selecting the right plan requires assessing home age, budget, and repair history. Homeowners with older systems should opt for comprehensive coverage, while those with newer appliances may choose a targeted appliance plan. For example, a 1980s home might benefit from a $600 systems plan, while a 2010s home could save with a $350 appliance-only plan.
Customization is key: reviewing add-ons like pool equipment or well pumps can tailor coverage to specific needs. Homeowners should also compare quotes from competitors, as regional pricing varies significantly. Using online calculators or consulting an insurance agent can streamline the decision-making process.
8. Pro Tips for Maximizing American Home Shield Benefits
Frequently Asked Questions
Understanding American Home Shield plans often raises specific questions. Here are concise answers to common inquiries:
Question 1: Are pre-existing conditions covered under American Home Shield plans?
No, pre-existing conditions—issues present before enrollment—are excluded from coverage. For example, a furnace with known inefficiencies before signing up won’t be covered for related failures. Regular maintenance records can help avoid disputes during claims.
Question 2: How long does it take to process a claim with American Home Shield?
Most claims are processed within 24-48 hours after initial contact, provided all documentation is complete. Complex repairs, like HVAC system replacements, may take longer due to contractor scheduling. Always follow up to expedite service.
Question 3: Can I cancel my American Home Shield plan and get a refund?
Cancellation policies vary, but American Home Shield typically offers a prorated refund if canceled before the policy term ends. For example, canceling after 6 months of a 12-month plan may yield a 50% refund. Review the policy terms for specific details.
Question 4: Do American Home Shield plans cover natural disaster damage?
No, plans exclude damage from natural disasters like floods or hurricanes. Homeowners insurance or separate disaster policies are required for such events. For instance, hurricane-related roof damage won’t be covered under a standard American Home Shield plan.
Question 5: Are there age restrictions for appliances covered under the plan?
Most plans cover appliances up to 10 years old, with some extending to 12 years for specific models. For example, a 9-year-old refrigerator is eligible, but a 15-year-old may be excluded. Age verification is done during the claim process.
Question 6: How do I find a contractor for repairs under my American Home Shield plan?
American Home Shield coordinates with licensed contractors in your area. After filing a claim, the company schedules a service call and provides contractor details. Homeowners can’t choose their own contractor, but the network includes vetted professionals.
Tips for Optimizing American Home Shield Plans
To get the most out of American Home Shield plans, follow these actionable steps:
Tip 1: Review the policy exclusions before enrolling. Skipping this step can lead to denied claims. For example, a plan may exclude septic system repairs, so homeowners with septic tanks should opt for add-on coverage.
Tip 2: Document all maintenance and repairs prior to enrollment. This prevents disputes over pre-existing conditions. Save receipts for HVAC tune-ups or appliance servicing to strengthen claim eligibility.
Tip 3: Enroll during the off-season for lower premiums. Pricing fluctuates, with discounts often available in winter months. For instance, signing up in January might reduce annual costs by 10-15%.
Tip 4: Combine plans for comprehensive coverage. Bundling a systems plan with an appliance plan can save money while expanding protection. A homeowner might pay $550 for separate plans but $700 for a bundled policy.
Tip 5: Understand the service call fee structure. Fees typically range from $75 to $125 per visit. Opting for a higher deductible can lower premiums but increases out-of-pocket costs per claim.
Tip 6: Check for regional discounts or promotions. American Home Shield occasionally offers discounts for specific states or military personnel. Monitoring their website or contacting customer service can uncover savings.
Tip 7: Schedule annual policy reviews. Needs change over time, and reviewing coverage ensures alignment with current home conditions. For example, adding pool equipment coverage may be necessary after installing a new spa.
Tip 8: Keep emergency contact information handy. Save American Home Shield’s 24/7 claims line and your policy number in your phone. Delays in reporting claims can void coverage, so quick action is critical during emergencies.
Conclusion
American Home Shield plans provide a practical solution for homeowners seeking financial protection against costly repairs. From coverage scope and pricing dynamics to claims processes and competitor comparisons, understanding these key aspects ensures informed decision-making. Whether addressing system failures, appliance malfunctions, or landlord liabilities, these plans offer a balance of affordability and reliability.
As home maintenance costs continue to rise, proactive measures—such as enrolling in a tailored home warranty—will remain essential. By leveraging the insights and tips outlined here, homeowners can navigate American Home Shield plans with confidence, safeguarding their investments for years to come.