11+ Key Insights About Allstate Renters and Auto Insurance
Table of Contents
- 1. Coverage Basics Explained
- 2. Bundling Discounts Demystified
- 3. Key Coverage Gaps to Watch For
- 4. How Location Impacts Premiums
- 5. Personalizing Your Coverage
- 6. Claim Filing Process Simplified
- 7. Comparing Allstate to Competitors
- 8. Common Mistakes to Avoid
- Frequently Asked Questions
- Tips for Optimizing Allstate Renters and Auto Insurance
- Conclusion
Allstate renters and auto insurance represents a strategic combination of two essential policies designed to safeguard tenants and drivers alike. For instance, a renter in Chicago might bundle personal property coverage—protecting a $10,000 laptop stolen during a break-in—with a comprehensive auto policy covering a 2019 Honda Civic after a fender bender. This dual protection not only mitigates financial risks but also simplifies management through a single provider. Historically, bundling policies has become a cornerstone of modern insurance strategies, offering both cost efficiencies and consolidated customer service. Below, the nuances of this coverage are explored to highlight its practical advantages and potential pitfalls.
The importance of Allstate renters and auto insurance lies in its ability to address two critical gaps in financial security: personal belongings and transportation. Renters insurance typically covers theft, fire damage, or liability claims, while auto insurance addresses accidents, vandalism, or medical expenses. Together, they form a safety net for individuals who may lack the resources to replace high-value items or repair vehicles outright. Beyond financial protection, these policies often include perks like roadside assistance or identity theft coverage, adding layers of convenience. Understanding these elements ensures tenants and drivers make informed choices tailored to their unique lifestyles.
This guide dives into the core aspects of Allstate renters and auto insurance, from pricing dynamics to coverage gaps, and provides actionable insights to optimize protection without overpaying. Whether comparing bundling discounts or evaluating policy exclusions, the following sections offer a structured approach to navigating these essential protections.
1. Coverage Basics Explained
Allstate renters and auto insurance policies are structured to address distinct but interconnected risks. Renters insurance generally includes liability coverage, personal property protection, and additional living expenses, while auto insurance encompasses collision, comprehensive, liability, and uninsured motorist coverage. For example, a renters policy might cover a water heater explosion damaging a tenant’s apartment, while an auto policy would handle a collision with an uninsured driver. Both policies often feature optional endorsements, such as scheduled personal property for high-value items or gap insurance for auto loans. These components collectively ensure comprehensive protection, though their interplay requires careful review to avoid overlaps or gaps.
2. Bundling Discounts Demystified
Bundling Allstate renters and auto insurance typically results in a multi-policy discount, often ranging from 10% to 25% off the total premium. This discount reflects the shared risk assessment by the insurer and the operational efficiencies gained from managing multiple policies under one umbrella. For instance, a policyholder in Los Angeles might save $300 annually by bundling a $1,200 renters policy with a $1,500 auto policy, reducing the total to $2,340 instead of $2,700. Beyond monetary savings, bundling simplifies policy management through a unified portal and customer service channel. However, the discount’s value depends on individual circumstances, as premiums vary based on location, coverage limits, and deductibles.
3. Key Coverage Gaps to Watch For
Despite their comprehensive design, Allstate renters and auto insurance policies contain exclusions that can leave policyholders vulnerable. For example, renters insurance often excludes flood or earthquake damage unless purchased as separate endorsements, while auto policies may not cover custom modifications unless explicitly listed. A tenant in Miami might assume their renters policy covers hurricane damage, only to discover flood exclusion unless a supplemental policy is added. Similarly, auto policies may exclude rental reimbursement unless an endorsement is purchased. Identifying these gaps early allows policyholders to tailor their coverage with additional riders or separate policies.
4. How Location Impacts Premiums
The geographic location of the insured property and vehicle plays a pivotal role in determining premiums for Allstate renters and auto insurance. High-risk areas, such as coastal cities prone to hurricanes or urban centers with higher theft rates, command higher premiums due to elevated claim frequencies. For example, a renters policy in New Orleans might cost 30% more than one in a low-crime suburban area, reflecting the increased likelihood of water damage or theft. Similarly, auto insurance premiums in cities with heavy traffic or high accident rates, like New York or Chicago, are significantly higher than in rural areas. Understanding these regional variations empowers policyholders to weigh the cost of coverage against the local risk landscape.
5. Personalizing Your Coverage
Customizing Allstate renters and auto insurance policies ensures alignment with individual needs and risk profiles. Personal property coverage can be adjusted to reflect the actual value of belongings, while liability limits can be increased for higher net worth or rental properties with multiple occupants. For instance, a freelancer with expensive equipment might opt for scheduled personal property coverage to ensure full replacement value. Similarly, drivers with high-performance vehicles or commuters with long daily routes may benefit from additional collision coverage or roadside assistance. Tailoring these elements mitigates underinsurance or overpayment, optimizing both protection and cost.
6. Claim Filing Process Simplified
Navigating the claim process for Allstate renters and auto insurance can be streamlined with proactive preparation. Policyholders are advised to document incidents with photos, police reports, and receipts for repairs or replacements. For renters, this might include photographing damaged furniture after a fire, while auto claimants should gather witness statements and repair estimates. Allstate’s mobile app facilitates this process by allowing claim initiation, damage assessment, and repair coordination in real time. Leveraging these tools reduces claim processing time and minimizes administrative burdens, ensuring faster resolutions and fewer disputes.
7. Comparing Allstate to Competitors
When evaluating Allstate renters and auto insurance, competitors like State Farm, Progressive, and GEICO offer distinct advantages and trade-offs. State Farm, for example, is often praised for its robust customer service and local agent network, while Progressive excels in competitive auto insurance rates through its Name Your Price tool. GEICO, on the other hand, is known for its affordability and straightforward online claims process. Allstate distinguishes itself with bundling flexibility and additional perks like identity theft protection. Policyholders should compare these factors alongside premiums, coverage limits, and customer reviews to determine the best fit for their needs.
8. Common Mistakes to Avoid
Several pitfalls can undermine the effectiveness of Allstate renters and auto insurance policies. Overlooking policy exclusions, such as flood or earthquake coverage, leaves policyholders exposed to catastrophic losses. Underinsuring personal property or vehicles due to cost-cutting measures can result in inadequate compensation during claims. For example, a tenant in Texas might assume their renters policy covers wildfire damage without realizing it requires a separate endorsement. Similarly, drivers may neglect to update their auto policy after modifying their vehicle, leading to denied claims for custom parts. Avoiding these errors requires thorough policy reviews and regular updates to reflect changes in lifestyle or assets.
Mistake 1: Ignoring Deductible Choices
The deductible is the out-of-pocket expense policyholders incur before insurance coverage kicks in. Choosing a higher deductible can lower premiums but increases financial risk in the event of a claim. For instance, a renter in Denver might opt for a $1,000 deductible to save $150 annually, but this could become costly if a $2,000 theft occurs. Conversely, a lower deductible provides greater financial protection but increases premiums. Balancing these choices depends on personal risk tolerance and financial capacity. Policyholders should assess their ability to cover deductibles before selecting this option.
Mistake 2: Skipping Renters Liability Coverage
Renters liability coverage protects against lawsuits if a policyholder accidentally injures a guest or causes property damage. For example, a tenant in Atlanta might accidentally start a fire in their apartment, leading to $20,000 in damages. Without liability coverage, the renter could face significant legal and financial repercussions. Allstate renters policies typically include $100,000 in liability protection, but higher limits can be purchased for an additional fee. Neglecting this coverage exposes policyholders to substantial financial liability, making it a critical component of any renters insurance policy.
Mistake 3: Not Updating Personal Property Inventory
Maintaining an updated inventory of personal belongings is essential for accurate claims processing. A renter in Seattle might lose a laptop, camera, and jewelry during a burglary but struggle to prove their value without receipts or photos. Allstate encourages policyholders to document their possessions annually, including serial numbers and purchase dates. This practice ensures claims are processed efficiently and fairly, minimizing disputes over coverage amounts. Without this documentation, policyholders risk undercompensation or claim denials.
Mistake 4: Assuming Auto Insurance Covers Rental Cars
Many drivers assume their auto insurance extends to rental vehicles, but this is rarely the case. For example, a business traveler in New York might rent a car for a week but discover their Allstate auto policy does not cover rental vehicles unless an endorsement is added. Most personal auto policies explicitly exclude rental cars, leaving policyholders responsible for full coverage costs. To avoid this gap, drivers should purchase rental car insurance through their credit card provider or add an endorsement to their auto policy. This precaution ensures uninterrupted protection during temporary vehicle use.
Mistake 5: Failing to Review Policy Annually
Life circumstances change—careers shift, vehicles age, and belongings accumulate—and these changes can render insurance policies obsolete. A policyholder in Chicago might have purchased a renters policy five years ago but now owns a $5,000 bicycle and drives a newer car. Without annual reviews, they may remain underinsured for these assets. Allstate recommends reviewing policies annually to adjust coverage limits, add new assets, or remove outdated items. This proactive approach ensures policies remain aligned with current needs and risks.
Tips for Optimizing Allstate Renters and Auto Insurance
Maximizing the value of Allstate renters and auto insurance requires proactive management and strategic adjustments. Below are 11 actionable tips to enhance protection and reduce costs.
Tip 1: Bundle policies to unlock discounts. Combining Allstate renters and auto insurance policies often yields a multi-policy discount, typically 10% to 25%. This savings can be substantial for policyholders managing multiple coverages. For example, bundling could reduce annual premiums from $2,700 to $2,340, providing both financial relief and simplified administration.
Tip 2: Increase liability limits for greater protection. Standard liability coverage may not suffice for high-net-worth individuals or those with rental properties. Increasing limits to $300,000 or $500,000 mitigates financial risk in the event of lawsuits. For instance, a tenant causing $200,000 in damages would face no out-of-pocket expenses with a $300,000 limit, unlike a $100,000 policy.
Tip 3: Document personal belongings annually. Maintaining an updated inventory of personal property ensures accurate claims processing. Take photos, note serial numbers, and store receipts for high-value items. This practice prevents disputes over coverage amounts, as seen in cases where stolen electronics lack proof of value. Allstate’s mobile app can streamline this documentation process.
Tip 4: Opt for higher deductibles to lower premiums. Selecting a higher deductible, such as $1,000 instead of $500, can reduce annual premiums by 10% to 20%. However, this increases out-of-pocket expenses during claims. For example, a renter might save $150 annually but pay $1,000 if a $2,000 theft occurs. Balance this choice based on financial capacity and risk tolerance.
Tip 5: Add scheduled personal property for high-value items. Standard renters insurance may not cover high-value items like jewelry or art fully. Adding scheduled personal property endorsements ensures these assets are protected up to their replacement value. For instance, a $10,000 watch stolen during a break-in would be fully reimbursed under this coverage, unlike a standard policy with limited coverage.
Tip 6: Review policies annually for updates. Life changes—careers, vehicles, and belongings evolve—requiring policy adjustments. For example, a policyholder who purchases a new laptop or upgrades their car should update their coverage limits. Allstate recommends annual reviews to ensure policies remain aligned with current needs and risks, preventing underinsurance or overpayment.
Tip 7: Consider additional endorsements for specific risks. Policies may exclude perils like flood, earthquake, or custom vehicle modifications. Adding endorsements addresses these gaps. For example, a renter in a flood-prone area should purchase flood insurance separately. Similarly, drivers with modified vehicles may need to add coverage for custom parts to avoid claim denials.
Tip 8: Leverage Allstate’s mobile app for claims. Allstate’s mobile app simplifies the claims process by allowing policyholders to initiate claims, document damage, and track repairs in real time. For instance, a renter can photograph fire damage and submit a claim within minutes, accelerating resolution. This tool reduces administrative burdens and minimizes claim disputes.
Tip 9: Compare bundling options with competitors. While Allstate offers strong bundling discounts, competitors like State Farm or Progressive may provide unique advantages. For example, Progressive’s Name Your Price tool allows drivers to set their budget and adjust coverage limits accordingly. Policyholders should compare bundling options across providers to ensure they’re getting the best value.
Tip 10: Ask about discounts for safety features. Installing safety devices like smoke detectors, burglar alarms, or anti-theft car systems can qualify policyholders for discounts. For example, a renter with a monitored security system might receive a 5% discount on their renters policy. Similarly, anti-theft devices in vehicles can reduce auto insurance premiums by 10% or more. Inquire with Allstate about available discounts to optimize savings.
Tip 11: Understand policy exclusions before filing claims. Familiarizing oneself with policy exclusions—such as mold damage or intentional acts—prevents claim denials. For example, a renter might assume their policy covers mold remediation but discover it’s excluded unless caused by a covered peril like a burst pipe. Reviewing exclusions upfront ensures policyholders file claims accurately and avoid costly surprises.
Conclusion
Allstate renters and auto insurance offers a robust framework for protecting personal belongings, vehicles, and financial stability. The coverage basics, bundling discounts, and customization options provide flexibility to address diverse risk profiles, while awareness of gaps and common mistakes ensures policyholders avoid costly oversights. Location, personalization, and proactive management further refine these protections, balancing cost and coverage effectively. By leveraging these insights, individuals can navigate their insurance needs with confidence, securing comprehensive protection tailored to their unique circumstances.
As insurance landscapes evolve, staying informed about policy updates, emerging risks, and cost-saving strategies remains critical. Whether adjusting coverage limits, exploring endorsements, or optimizing bundling options, the goal is to create a safety net that evolves alongside personal and financial changes. This proactive approach not only enhances protection but also fosters long-term financial resilience.
Frequently Asked Questions
How does bundling Allstate renters and auto insurance save money?
Bundling policies with Allstate typically results in a multi-policy discount, often reducing total premiums by 10% to 25%. This discount reflects shared risk assessment and operational efficiencies. For example, combining a $1,200 renters policy with a $1,500 auto policy might lower the total to $2,340 instead of $2,700. Beyond cost savings, bundling simplifies management through a unified portal and customer service channel, enhancing convenience.
What types of personal property are covered under renters insurance?
Allstate renters insurance typically covers personal belongings such as furniture, electronics, clothing, and appliances against perils like fire, theft, or vandalism. For instance, a stolen laptop or damaged TV would be covered up to the policy’s limits. However, exclusions may apply to high-value items like jewelry or artwork unless scheduled separately.
Does Allstate renters insurance cover flood or earthquake damage?
Standard Allstate renters insurance policies do not include flood or earthquake coverage, as these perils are considered high-risk and require separate endorsements. For example, a renter in California might need to purchase earthquake insurance to protect against seismic activity. Similarly, flood insurance is typically offered through the National Flood Insurance Program (NFIP).
How much liability coverage is recommended for renters insurance?
The recommended liability coverage for renters insurance is generally $100,000, which Allstate includes in most standard policies. However, higher net worth individuals or those with rental properties may opt for $300,000 or $500,000 in coverage to protect against lawsuits. For instance, a tenant causing $200,000 in property damage would be covered under a $300,000 policy but face out-of-pocket expenses with a $100,000 limit.
Can I add my roommate to my Allstate renters insurance policy?
Yes, Allstate renters insurance policies can typically include roommates as additional insureds, provided they are listed on the lease or live in the same household. This ensures all occupants are protected under the same policy. For example, a policy covering one roommate might need to be adjusted to include a second roommate to avoid coverage gaps.
How does Allstate determine auto insurance premiums?
Allstate auto insurance premiums are calculated based on factors like driving history, vehicle type, location, age, and coverage limits. For instance, a young driver in a high-theft area with a sports car may pay higher premiums due to increased risk. Additionally, factors like credit score and deductible choice influence costs. Policyholders can reduce premiums by maintaining a clean driving record, bundling policies, or increasing deductibles.
Related articles
9+ Ways to Get the Best Allstate Quote Home Insurance for Your Needs
Learn how to obtain the most accurate Allstate quote home insurance with expert tips, pricing insights, and comparison strategies to secure premium…
15+ Ways to Get the Best Allstate Insurance Quote for Homeowners
Discover how to secure the most competitive **Allstate insurance quote homeowners** need. Learn pricing strategies, coverage tips, and real-world…
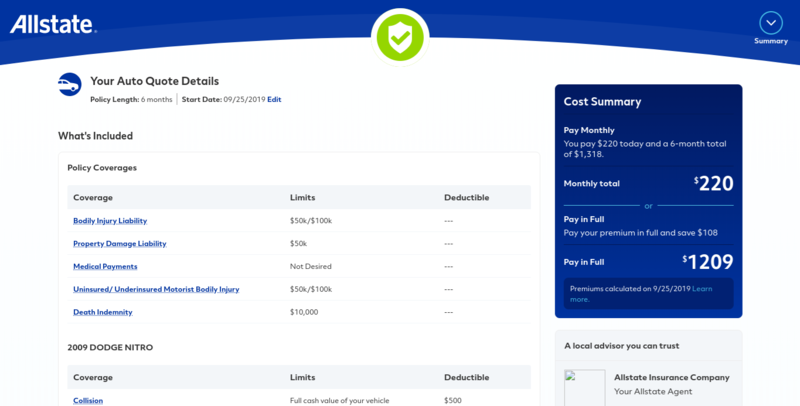
15 Key Insights Into Allstate Insurance Quote Auto: A Comprehensive Guide
Get an Allstate insurance quote auto fast with these expert insights. Learn pricing, coverage, and tips to save money while securing top-rated protection…
14+ Smart Ways to Find the Best Allstate Insurance Near Me
Discover how to locate reliable Allstate insurance near you, compare quotes, and maximize benefits. Learn local agent tips, coverage options, and…

16 Essential Facts About Affordable Renter’s Insurance
Discover how affordable renter’s insurance protects belongings and budgets—without breaking the bank. Learn pricing tips, coverage hacks, and real-world…
