8 Key Facts About Allstate Insurance Coverage Policy Explained
Table of Contents
- 1. Types of Allstate Insurance Coverage Policies
- 2. Key Components of an Allstate Policy
- 3. How Allstate Claims Work
- 4. Common Allstate Policy Exclusions
- 5. Allstate Discounts and Savings
- 6. Allstate Policy Limits and Coverage Gaps
- 7. Allstate’s Digital Tools and Customer Service
- 8. Updating an Allstate Insurance Coverage Policy
- Frequently Asked Questions
- 8 Tips for Maximizing Your Allstate Insurance Coverage Policy
- Conclusion
An **Allstate insurance coverage policy** is a legally binding contract that outlines the terms under which Allstate provides financial protection to policyholders in exchange for premium payments. For example, if a policyholder with an Allstate auto insurance policy is involved in a covered accident, the policy dictates how much Allstate will reimburse for repairs or medical expenses, up to the policy limits. This framework ensures clarity for both the insurer and the insured, reducing ambiguity during claims.
The importance of an Allstate insurance coverage policy lies in its ability to mitigate financial risks across various domains—from property damage and liability to health emergencies. Allstate, one of the largest insurers in the U.S., has been operational since 1931, evolving alongside societal needs, such as the rise of suburban homeownership in the 1950s or the digital transformation of claims processing today. Policies are designed to adapt to these changes, offering tailored coverage for modern lifestyles, whether it’s protecting a family’s home against natural disasters or covering a teen driver’s first car.
This article explores the critical aspects of an Allstate insurance coverage policy, from the types of coverage available to how claims are processed and what discounts might apply. Whether evaluating a new policy or reviewing an existing one, understanding these elements ensures informed decisions and optimal protection.
1. Types of Allstate Insurance Coverage Policies
Allstate offers a range of insurance products, each tailored to specific risks. The most common categories include auto, homeowners, renters, life, and umbrella insurance. Auto policies, for instance, may cover collision, comprehensive, liability, and uninsured motorist protection, while homeowners insurance typically addresses structural damage, personal property, and additional living expenses after a covered loss.
Umbrella insurance, another key offering, provides extra liability coverage beyond the limits of underlying policies. For example, if a policyholder is sued for $1.5 million due to an accident, but their auto policy only covers $500,000, the umbrella policy would cover the remaining $1 million. This layer of protection is particularly valuable for high-net-worth individuals or those with significant assets.
2. Key Components of an Allstate Policy
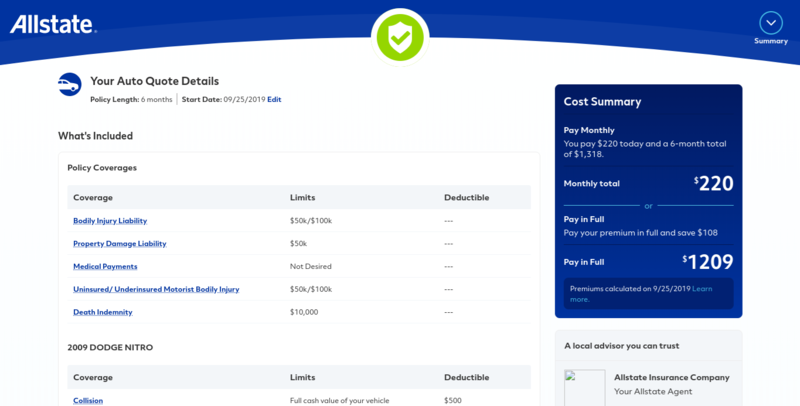
- Policy Limits: These define the maximum amount Allstate will pay for a covered claim. For instance, a homeowners policy might have a $300,000 dwelling limit, meaning structural repairs after a fire would not exceed this amount unless additional coverage is purchased. Understanding these limits helps policyholders avoid financial surprises during claims.
- Deductibles: This is the out-of-pocket amount the policyholder pays before Allstate covers the rest. A $1,000 deductible on an auto policy means the insured pays the first $1,000 of repair costs after an accident. Choosing a higher deductible can lower premiums but increases risk exposure.
- Exclusions: These are specific situations or items not covered by the policy. For example, a standard homeowners policy may exclude damage from floods or earthquakes unless additional endorsements are added. Reviewing exclusions ensures policyholders know where gaps in coverage exist.
- Endorsements/Riders: These are optional additions to a policy that expand or modify coverage. A scheduled personal property endorsement, for example, might provide higher limits for expensive items like jewelry or art. Adding these can be cost-effective for high-value assets.
- Liability Coverage: This protects against legal claims for bodily injury or property damage caused by the policyholder. In a slip-and-fall accident at a policyholder’s home, liability coverage would pay for the victim’s medical bills and legal fees, up to the policy’s limits.
3. How Allstate Claims Work
The claims process is a critical aspect of any insurance coverage policy, and Allstate’s approach is designed to be straightforward. After filing a claim—whether online, via the mobile app, or by phone—a dedicated claims adjuster is assigned to assess the damage or loss. For auto claims, this might involve inspecting the vehicle at a repair shop, while home claims may require an in-person assessment of structural damage.
Allstate’s digital tools, such as the **Allstate Mobile App**, allow policyholders to document damage with photos, estimate repair costs, and track claim status in real time. This transparency reduces friction and speeds up resolutions. For instance, a policyholder involved in a hailstorm could upload photos of their roof within minutes of filing a claim, accelerating the adjuster’s review process.

4. Common Allstate Policy Exclusions
While Allstate policies provide broad coverage, certain exclusions are standard across most plans. Auto policies, for example, typically exclude damage from intentional acts, racing, or driving under the influence. Similarly, homeowners policies often exclude damage from mold unless it stems from a covered peril like a burst pipe. These exclusions are not arbitrary; they reflect risks that are either difficult to insure or require specialized coverage.
Understanding these exclusions is vital. For instance, a policyholder in a flood-prone area might assume their homeowners policy covers water damage, only to discover that floods are excluded unless they purchase a separate flood insurance policy through the National Flood Insurance Program (NFIP). Proactively addressing these gaps can prevent costly out-of-pocket expenses.
5. Allstate Discounts and Savings
- Bundling Policies: Combining multiple policies, such as auto and homeowners insurance, with Allstate can yield significant discounts—often 10% to 25% off premiums. For example, a family paying $1,200 annually for auto insurance and $900 for homeowners insurance might save $300 by bundling, reducing their total annual cost to $1,800 instead of $2,100.
- Safe Driving Programs: Allstate’s **Drivewise** program rewards policyholders for safe driving habits by offering discounts based on mileage, braking patterns, and speed. A policyholder who consistently drives cautiously could see premium reductions of up to 30% over time.
- New Car Discounts: Purchasing a new vehicle may qualify for discounts, as insurers assume lower risk for well-maintained, modern cars. Allstate might offer a 5% discount on a new car policy for the first year, reflecting the vehicle’s safety features and lower depreciation risk.
- Claims-Free Discounts: Policyholders with a clean claims history often receive discounts for their responsible behavior. Allstate may reduce premiums by 5% to 10% for each claims-free year, incentivizing proactive risk management.
- Anti-Theft and Safety Device Discounts: Installing anti-theft systems, such as GPS tracking or alarm systems, can lower auto insurance premiums. Allstate might offer a 5% discount for approved safety devices, recognizing the reduced likelihood of theft or accidents.
6. Allstate Policy Limits and Coverage Gaps
Policy limits are a double-edged sword: they cap financial exposure for the insurer but may leave policyholders underinsured if not carefully selected. For instance, a standard homeowners policy might offer $100,000 in personal property coverage, which could be insufficient for a home filled with high-value items like electronics or collectibles. In such cases, a **scheduled personal property endorsement** can provide additional protection for specific items.
Similarly, liability limits on auto policies might not cover the full cost of a lawsuit. If a policyholder is sued for $2 million but their policy only covers $300,000, they could face personal asset seizure. This is where **umbrella insurance** bridges the gap, offering additional liability coverage starting at $1 million. Evaluating these limits annually ensures alignment with evolving asset values and risk profiles.
7. Allstate’s Digital Tools and Customer Service
Allstate has invested heavily in digital innovation to enhance policy management and claims processing. The **Allstate Mobile App** allows policyholders to view coverage details, pay bills, and file claims from anywhere. Features like **Allstate On Your Side®** provide 24/7 claims support, while tools like **Allstate Drivewise** offer real-time feedback on driving habits to improve safety and save on premiums.
Customer service is another strength, with Allstate maintaining a network of local agents who provide personalized assistance. Policyholders can schedule in-person meetings to review coverage, discuss endorsements, or address concerns. This hybrid approach—combining digital convenience with human expertise—ensures accessibility and support at every stage of the insurance lifecycle.
8. Updating an Allstate Insurance Coverage Policy
Life changes—marriage, home purchases, or the addition of a new driver—often necessitate updates to an Allstate insurance coverage policy. For example, purchasing a second car requires notifying Allstate to adjust coverage limits or add a new policy. Similarly, renovating a home might increase its value, prompting a review of dwelling coverage to ensure adequate protection.
Allstate simplifies updates through its online portal, where policyholders can modify coverage, add endorsements, or report changes in usage (e.g., switching from commuting to telecommuting). Proactive updates prevent coverage gaps and ensure policies remain aligned with current needs. For instance, a policyholder who starts a home-based business might need to add **business property coverage** to their homeowners policy to protect equipment and inventory.
8 Tips for Maximizing Your Allstate Insurance Coverage Policy
Optimizing an Allstate insurance coverage policy requires proactive steps. Here’s how to get the most value.
Tip 1: Review coverage limits annually. Life changes—like buying a new car or renovating a home—can outpace policy limits. Adjusting coverage ensures adequate protection without overpaying.
Tip 2: Bundle policies for savings. Combining auto, home, and life insurance with Allstate can reduce premiums by 10% to 25%. This strategy simplifies management while lowering costs.
Tip 3: Install safety devices for discounts. Anti-theft systems, smoke detectors, and smart home devices may qualify for premium reductions. Allstate often rewards proactive risk mitigation.
Tip 4: Leverage Allstate’s digital tools. Use the mobile app to track claims, pay bills, and monitor driving habits. Features like **Drivewise** provide real-time feedback to improve safety and save on premiums.
Tip 5: Understand exclusions before filing a claim. Review policy exclusions to avoid surprises. For example, a standard auto policy may not cover damage from a single-car accident if the policyholder was distracted.
Tip 6: Add endorsements for high-value items. Schedule personal property endorsements for expensive items like jewelry or electronics. This ensures full replacement value in case of loss or damage.
Tip 7: Take advantage of claims-free discounts. Each claims-free year may reduce premiums by 5% to 10%. Safe driving and proactive home maintenance can help maintain this discount.
Tip 8: Consult an Allstate agent for complex needs. Local agents provide personalized advice for unique situations, such as business use of a vehicle or rare collectibles. Their expertise ensures tailored coverage.
Conclusion
An Allstate insurance coverage policy is more than a contract—it’s a dynamic tool for managing risk and securing financial stability. From understanding policy limits and exclusions to leveraging discounts and digital tools, each element plays a role in optimizing protection. Whether safeguarding a family’s home, a driver’s vehicle, or a business’s assets, Allstate’s policies adapt to evolving needs, provided policyholders stay informed and proactive.
As risks and lifestyles continue to change, regularly reviewing and updating coverage ensures policies remain effective. By applying these insights, individuals and families can navigate the complexities of insurance with confidence, knowing their Allstate coverage policy is working as intended.

Frequently Asked Questions
What types of vehicles does Allstate cover under an auto insurance policy?
Allstate covers cars, trucks, SUVs, motorcycles, and classic cars. Coverage depends on the vehicle’s age, usage, and value. For example, a vintage car might need a collectible auto policy with agreed-upon value coverage to ensure proper reimbursement in a total loss.
Can I customize my Allstate homeowners insurance policy?
Yes, Allstate allows customization through endorsements or riders. Policyholders can add coverage for high-value items like jewelry or art, or opt for additional liability protection. For instance, a $50,000 engagement ring may require a scheduled personal property endorsement for full replacement value coverage.
How long does the Allstate claims process typically take?
Claim resolution times vary. Simple auto claims may take days, while major home damage claims—like a roof replacement—could take weeks. Allstate’s mobile app provides real-time updates to track progress and expedite resolutions.
Are there discounts for military personnel with Allstate?
Allstate offers military loyalty discounts of up to 15% for active personnel, veterans, and families. This reflects appreciation for service members’ dedication and lower perceived risk due to disciplined lifestyles.
What happens if I miss a payment on my Allstate policy?
Missing a payment can lapse coverage, leaving you uninsured until the premium is paid. Allstate offers autopay options and may provide a grace period. Contacting customer service immediately to arrange a payment plan can prevent coverage gaps.
Does Allstate cover natural disasters in its homeowners policy?
Standard policies exclude floods, earthquakes, and hurricanes unless additional coverage is purchased. For example, Florida homeowners may need a hurricane deductible endorsement. Reviewing local risks and endorsements ensures comprehensive protection.