Finding reliable insurance coverage tailored to your location starts with understanding how state-based providers shape your options. Across the U.S., insurance markets vary dramatically by region, influencing everything from premium costs to coverage availability. Whether you're comparing auto policies in a no-fault state like Michigan or evaluating homeowners' flood protections in Florida, local regulations and risk factors dictate what insurers offer—and at what cost. This guide breaks down the key differences in state insurance markets, helping you navigate choices that align with your needs and budget. From regulatory nuances to emerging trends like usage-based insurance, the decisions you make today can impact your financial security for years to come.
State insurance providers operate within distinct legal frameworks, economic conditions, and consumer behaviors that set them apart from national carriers. For example, a driver in California may face higher auto insurance rates due to liability laws and claim frequencies, while a homeowner in Texas might prioritize windstorm coverage amid hurricane risks. These variations extend beyond pricing to include mandatory coverages, claim processes, and even digital service adoption. By examining these factors, you can identify which insurers best match your location’s specific challenges—whether it’s urban congestion, rural property risks, or industry-specific liabilities. The following sections dissect these dynamics to empower informed decision-making.
State-Level Insurance Companies in the U.S.: Historical Development and Regulatory Frameworks
State-level insurance companies have evolved alongside the U.S. economy, adapting to regional needs while operating under a patchwork of state-specific regulations. Their origins trace back to the 19th century, when mutual insurance companies—owned by policyholders—emerged to provide affordable coverage in rural areas. Over time, these entities diversified into stock companies, independent agencies, and state-chartered insurers, each responding to local risks like natural disasters, agricultural losses, or industrial accidents. The Great Depression (1929–1939) accelerated regulatory oversight, leading to the McCarran-Ferguson Act (1945), which exempted insurance from federal antitrust laws while empowering states to enforce solvency standards. Today, state insurers operate under dual frameworks: **state-based licensing** (ensuring consumer protection) and **NAIC (National Association of Insurance Commissioners) guidelines** (promoting uniformity in reporting and compliance).
Regulatory frameworks vary by state but generally include:
- **Licensing requirements** for agents and insurers, with some states (e.g., California) imposing stricter education mandates.
- **Solvency regulations**, such as risk-based capital (RBC) requirements, to prevent insolvencies (e.g., the 2008 collapse of American International Group’s state affiliates highlighted the need for stricter oversight).
- **Consumer protection laws**, including claim settlement timelines (e.g., Florida’s 90-day rule for property claims) and complaint resolution mechanisms.
- **Market conduct exams**, where state departments audit insurers for fair pricing and non-discriminatory practices.
State insurers often specialize in niche markets, such as:
"Mutual insurers, which account for ~20% of the U.S. property/casualty market, are particularly prevalent in states with high homeownership rates, such as Minnesota (where Blue Cross Blue Shield Mutual dominates) or Texas (where mutual companies like USAA for veterans hold significant market share)."
Their resilience during economic downturns—e.g., mutual insurers in hurricane-prone states like Florida—demonstrates their adaptability to localized risks.
Key Historical Milestones Shaping State Insurance Markets
The trajectory of state insurance companies is marked by legislative and economic shifts:
- **1850s–1890s**: Rise of mutual fire and life insurers (e.g., New York Life Insurance Company, 1845) to serve immigrant populations and industrial workers.
- **1905**: McCarran Act established state authority over insurance, preempting federal intervention until the 1945 McCarran-Ferguson Act.
- **1930s**: New Deal reforms introduced federal deposit insurance (FDIC) for banks, indirectly pressuring state insurers to adopt similar safeguards for policyholders.
- **1970s–1980s**: Deregulation of interest rates (e.g., 1978 Depository Institutions Deregulation and Monetary Control Act) led state insurers to innovate in investment strategies, reducing reliance on fixed-rate annuities.
- **2000s**: Post-9/11 terrorism risk insurance programs (TRIP) and post-Hurricane Katrina reforms (e.g., Florida’s Citizens Property Insurance Corporation) expanded state-backed coverage options.
Regulatory Variations by State: Solvency and Consumer Protection
State insurance departments enforce solvency standards through **risk-based capital (RBC) formulas**, which adjust required capital based on asset volatility and underwriting risks. For example:
- **California’s Department of Insurance (CDI)** requires insurers to maintain RBC ratios of at least 300% for property/casualty lines, while **Texas’ Department of Insurance** uses a tiered approach with stricter thresholds for companies writing high-risk policies (e.g., flood or wind coverage).
- **Consumer complaint ratios** (complaints per 100,000 policies) reveal enforcement disparities: In 2022, Florida had the highest complaint rate (12.4) due to frequent hurricanes, whereas Wyoming had the lowest (1.8), reflecting its low-risk, rural market.
State Insurance Departments’ Roles in Market Stability
Beyond solvency, state departments influence market dynamics through:
- **Rate filing requirements**: States like New York mandate prior approval for rate changes, while others (e.g., Texas) use file-and-use systems, allowing insurers to implement rates immediately.
- **Reinsurance mandates**: Some states (e.g., California) require insurers to cede a portion of risks to reinsurers, mitigating catastrophic losses (e.g., wildfires).
- **Fair Access to Insurance Requirements (FAIR) Plans**: Created in the 1960s to provide coverage in high-risk areas (e.g., California’s FAIR Plan for wildfire zones), these state-run programs fill gaps left by private insurers.
Top 5 States with the Highest Concentration of Independent Insurance Agencies (Population-Adjusted)
Independent agencies—operating as brokers rather than captive to one insurer—dominate markets where consumers prioritize customized coverage. Population-adjusted data (2023) ranks these states by **agency density per 100,000 residents**:
1. **Minnesota**
- **Density**: 45 agencies per 100,000 residents.
- **Context**: Minnesota’s cooperative culture and strong mutual insurance tradition (e.g., Blue Cross Blue Shield of Minnesota) fosters agency collaboration. The state’s **farmers’ mutuals** (e.g., Farmers Mutual of Omaha) also rely on local agents for underwriting flexibility.
2. **Texas**
- **Density**: 38 agencies per 100,000 residents.
- **Context**: Texas’s vast geographic and economic diversity—from urban hubs like Houston to rural ranches—drives demand for independent agents who can tailor policies (e.g., flood insurance in coastal areas). The state’s **no-fault auto insurance** system further incentivizes agent-driven claims management.
3. **Iowa**
- **Density**: 35 agencies per 100,000 residents.
- **Context**: Iowa’s **farmers’ mutuals** (e.g., Iowa Farmers Mutual Insurance Company) and high homeownership rates (63%) create a market where agents act as trusted advisors for agricultural and property risks.
4. **Wisconsin**
- **Density**: 33 agencies per 100,000 residents.
- **Context**: Wisconsin’s **mutual insurance dominance** (e.g., Guardian Life Insurance Company) and strong labor unions contribute to a culture of agent-backed coverage. The state’s **no-fault auto insurance** also aligns with agent-driven claims processes.
5. **North Carolina**
- **Density**: 32 agencies per 100,000 residents.
- **Context**: North Carolina’s **high auto insurance penetration** (due to mandatory liability coverage) and **hurricane-prone coastal regions** (e.g., Wilmington) drive demand for agents who can navigate complex windstorm policies.
State-Specific Insurance Market Comparison: California vs. Texas
California and Texas represent divergent insurance landscapes, shaped by geography, regulation, and economic activity. Below is a structured comparison across key metrics:
| **Metric** | **California** | **Texas** |
|--------------------------|-------------------------------------------------------------------------------|---------------------------------------------------------------------------|
| **Premium Costs (2023)** | Auto: $1,620/year (highest in U.S. due to liability laws and urban congestion) | Auto: $1,350/year (lower due to no-fault system and competitive markets) |
| | Home: $2,800/year (wildfire and earthquake risks) | Home: $1,800/year (flood risks in coastal areas offset by lower theft rates) |
| **Coverage Types** | Mandatory: **Bodily Injury ($15K/$30K/$5K)** and **Property Damage ($5K)** | Mandatory: **$30K/$60K/$25K** (no-fault for medical, but higher property limits) |
| | Optional: **Comprehensive (wildfire/earthquake add-ons)** | Optional: **Flood (NFIP or private, e.g., Texas Windstorm Insurance Association)** |
| **Claim Settlement Trends** | **Median Settlement Time**: 30 days (hurricane/wildfire claims often delayed due to litigation) | **Median Settlement Time**: 15 days (no-fault system speeds claims, but flood claims may take 60+ days) |
| | **Litigation Rate**: 45% of claims (high due to strict liability laws) | **Litigation Rate**: 20% (no-fault reduces disputes, but fraud investigations are common) |
| **Regulatory Environment** | **CDI**: Stricter rate filings, mandatory earthquake coverage in high-risk zones | **TDIA**: File-and-use system, voluntary windstorm pool for coastal regions |
| **Market Penetration** | **Independent Agents**: 40% of policies (high due to complex coverage needs) | **Independent Agents**: 55% (no-fault system encourages agent-driven claims) |
Common Insurance Products Offered by State-Based Insurers
State insurers tailor products to regional risks, with coverage limits varying by state regulations and market demand. Below is a table of typical offerings and their standard limits:
**Insurance Product**
**Typical Coverage Limits**
**State-Specific Notes**
**Auto Insurance**
Bodily Injury Liability: $25K–$500K per person/per accident
Property Damage: $10K–$100K
Collision: $500–$10,000 (deductible-dependent)
Comprehensive: $250–$5,000 (theft/fire/vandalism)
**Florida**: Minimum $10K/$20K bodily injury, but **no-fault medical payments** ($10K max) apply.
**Texas**: **No-fault medical** ($2,500 max), but higher property damage limits ($25K min) due to urban congestion.
**Homeowners Insurance**
Dwelling Coverage: $100K–$1M (replacement cost
Finding Allstate Insurance Near Me Complete Guide All States USA Allstate.com-Al
Geographic Influence on Insurance Premiums and Coverage Variations
Insurance premiums and coverage options are heavily shaped by geographic location, reflecting differences in risk exposure, infrastructure, and regulatory environments. Urban and rural areas exhibit distinct pricing disparities due to variations in population density, crime rates, natural disaster risks, and availability of medical/emergency services. These factors directly impact how insurers calculate premiums and tailor policies to local needs.
Urban vs. Rural Pricing Disparities
Urban centers typically command higher insurance premiums due to elevated risks such as theft, vandalism, and higher traffic density. For example, auto insurance in cities like New York or Chicago averages **20-30% higher** than in rural areas, primarily because of increased collision claims and higher repair costs. Property insurance in densely populated neighborhoods also reflects higher replacement costs for structures and personal belongings, with some urban condominium policies exceeding rural homeowners' premiums by **15-25%**.
Conversely, rural areas often benefit from lower premiums due to reduced crime rates and lower infrastructure repair costs. However, rural residents may face higher deductibles or limited coverage options for natural disasters (e.g., floods or wildfires), as insurers may deem these risks less predictable. For instance, a farm in Kansas might pay **30% less** for property insurance than a suburban home in Colorado, but could encounter gaps in coverage for crop damage or livestock-related incidents.
The disparity between urban and rural premiums stems from several measurable factors:
Urban premiums are influenced by:
- **Crime rates**: Higher theft/vandalism in cities (e.g., auto theft rates in Los Angeles are **3x higher** than in rural Iowa).
- **Traffic density**: Increased collision claims in congested areas (e.g., Manhattan’s auto insurance premiums are **40% above state averages**).
- **Emergency response times**: Slower response in sprawling rural areas may offset lower baseline risks.
- **Building codes**: Stricter urban codes can reduce fire/structural risks but increase construction costs, raising premiums.
Rural premiums reflect:
- **Lower infrastructure costs**: Cheaper repairs for homes and vehicles due to less wear-and-tear.
- **Natural disaster exposure**: Higher wildfire risk in California’s rural areas (e.g., premiums in Napa County surged **50%** post-2020 fires).
- **Limited insurer competition**: Fewer providers may lead to higher deductibles or exclusions for niche risks (e.g., livestock coverage).
Coverage Options by Region
Insurers adjust policy inclusions based on regional vulnerabilities. In flood-prone states like Florida or Louisiana, **National Flood Insurance Program (NFIP) policies** are often mandatory for mortgages, with premiums varying by flood zone. Similarly, coastal states like Texas and North Carolina require **windstorm insurance** add-ons, which can add **$500–$1,500 annually** to homeowners' policies.
Rural areas with high agricultural activity may offer specialized coverage for equipment or livestock, while urban policies often include **renters’ insurance with liability protections** for high-value personal items (e.g., electronics or jewelry). Insurers in states with strict liability laws (e.g., California) also mandate higher auto liability limits, increasing premiums for urban drivers.
State-Specific Mandatory Insurance Requirements: Auto, Property, and Business Coverage Variations
Auto insurance laws vary significantly by state, shaping how liability, coverage limits, and claims resolution function. Understanding these distinctions is critical for policyholders to ensure compliance and adequate protection. The following outlines key legal frameworks, including no-fault vs. tort liability systems, and how they impact premiums and claims processes.
Auto Insurance: No-Fault vs. Tort Liability Systems
No-fault states require drivers to file claims with their own insurers regardless of fault, while tort liability states allow victims to sue at-fault parties. This distinction directly influences claim complexity, premium costs, and available benefits.
No-Fault States (12 total):
These states mandate Personal Injury Protection (PIP) coverage, which covers medical expenses and lost wages for all parties involved in an accident, irrespective of fault. Examples include:
Florida: Requires $10,000 PIP coverage with optional $2,500 property damage liability (PDL). Bodily injury liability (BI) is optional unless PDL is purchased.
Michigan: Imposes strict PIP requirements ($5,000 minimum for medical expenses, $3,000 for work loss, and $100 for funeral expenses) with high premiums due to generous benefits.
New York: Mandates $50,000 PIP coverage for medical expenses and $2,000 for work loss, with BI liability limits of $25,000/$50,000/$10,000.
In no-fault states, PIP coverage often replaces traditional BI liability, shifting focus from fault determination to immediate claim resolution.
Tort Liability States (38 total):
These states permit victims to sue at-fault drivers for damages exceeding their insurer’s limits. Minimum BI liability requirements vary widely:
California: Requires $15,000/$30,000/$5,000 (BI/PDL) with no PIP mandate, though uninsured motorist (UM) coverage is optional.
Texas: Mandates $30,000/$60,000/$25,000 BI/PDL limits, with UM coverage optional unless the insured rejects it in writing.
New Jersey: Enforces $15,000/$30,000/$5,000 BI limits and requires $250 minimum UM coverage.
Tort states often feature higher BI liability minimums to compensate for the absence of PIP, as victims rely on lawsuits for full recovery.
Hybrid Systems:
Some states blend elements of both systems. For example:
Pennsylvania: Uses a "choice no-fault" system, allowing drivers to select either no-fault PIP or traditional tort liability coverage.
Massachusetts: Requires PIP but permits victims to sue for "serious injuries" exceeding $2,000 in medical expenses or resulting in death.
State-Specific Endorsements for Homeowners and Renters Insurance
Standard homeowners (HO-3) and renters (HO-4) policies exclude coverage for certain high-risk perils, necessitating endorsements or separate policies. Below are state-specific options to mitigate gaps in protection.
Flood Coverage:
Flood insurance is excluded from standard policies but is mandatory in high-risk zones designated by the Federal Emergency Management Agency (FEMA). States with significant flood risks offer tailored endorsements:
Florida: Requires flood insurance for properties in FEMA Special Flood Hazard Areas (SFHAs), with private insurers and the National Flood Insurance Program (NFIP) as primary providers.
California: Offers the California Earthquake Authority (CEA) for quake coverage and the NFIP for floods, though private insurers may provide supplemental flood policies.
Louisiana: Mandates flood insurance for properties in SFHAs, with the Louisiana Purchase Flood Program (LPFP) as an alternative to NFIP for residents outside FEMA’s purview.
Flood endorsements typically cover up to $250,000 for dwelling and $100,000 for contents, with deductibles ranging from 1% to 10% of the insured value.
Earthquake Coverage:
Earthquake policies are separate from standard homeowners insurance and are critical in seismically active regions. Key state programs include:
California: The CEA provides primary earthquake coverage, with optional endorsements for additional living expenses and equipment breakdown.
Washington: Offers the Washington Earthquake Insurance Association (WEIA) for residents outside the CEA’s service area.
Nevada: Requires earthquake coverage for properties in high-risk zones, with the Nevada Earthquake Authority (NEA) as the primary provider.
Earthquake endorsements often include a 15% deductible (e.g., 15% of dwelling coverage) and exclude gradual damage like soil liquefaction.
Windstorm/Hurricane Endorsements:
Coastal states with high windstorm risks mandate or strongly recommend supplemental coverage. Examples include:
Texas: Requires windstorm insurance for properties in designated coastal areas, with the Texas Windstorm Insurance Association (TWIA) as the primary provider for private insurers’ failures.
North Carolina: Offers the North Carolina Windstorm Underwriting Association (NCWUA) for properties in high-risk zones.
Hawaii: Mandates windstorm coverage for properties in hurricane-prone areas, with private insurers and the Hawaii Windstorm Underwriting Association (HWUA) as options.
Wildfire and Fire-Related Endorsements:
States with wildfire risks, such as California and Oregon, provide endorsements for fire perils, including:
California: The California FAIR Plan Association offers coverage for properties deemed uninsurable due to wildfire risks, with endorsements for debris removal and ordinance or law coverage.
Oregon: The Oregon Wildfire Insurance Program provides supplemental coverage for properties in high-risk wildfire zones.
Wildfire endorsements often include a 5% deductible for fire perils and exclude pre-existing conditions or negligence.
Hail and Severe Storm Endorsements:
States prone to hailstorms, such as Texas and Colorado, offer endorsements to cover hail damage. For example:
Texas: The Texas Windstorm Insurance Association (TWIA) covers hail damage for properties in windstorm-prone areas, with endorsements for additional living expenses.
Colorado: Private insurers provide hail endorsements with deductibles as low as $500 for dwelling coverage.
Business Insurance Requirements by State and Industry
Business insurance mandates vary by state and industry, with some sectors (e.g., healthcare, construction) facing stricter regulations. Below is a breakdown of key requirements and industry-specific mandates.
General Business Liability:
Most states require general liability insurance for businesses operating within their borders, though coverage limits and exclusions differ. For example:
New York: Mandates $1 million in general liability coverage for businesses with 5+ employees or annual gross receipts exceeding $50,000.
California: Requires $2 million in general liability for contractors and $1 million for most other businesses.
Texas: Mandates $300,000 in combined single limit (CSL) for general liability, with higher limits for certain industries.
Industry-Specific Mandates:
Healthcare:
States with healthcare-specific requirements include:
Florida: Requires $1 million in professional liability (malpractice) insurance for healthcare providers, with higher limits for hospitals.
New York: Mandates $1 million in general liability and $1 million in professional liability for ambulatory surgical centers.
California: Requires $1.5 million in professional liability for physicians and $3 million for hospitals.
Healthcare providers often face additional scrutiny due to high-risk liability exposures, including medical errors and HIPAA compliance.
Construction:
States with stringent construction insurance requirements include:
New Jersey: Requires $2 million in combined single limit (CSL) for general liability and $1 million in workers' compensation for construction firms.
Washington: Mandates $2 million in CSL for general liability and $1 million in workers' compensation for contractors with 5+ employees.
Illinois: Requires $1 million in general liability and $500,000 in workers' compensation for construction businesses.
Retail:
Retail businesses often face requirements tied to property and product liability. Examples include:
Massachusetts: Requires $1 million in general liability for retail businesses with annual sales exceeding $100,000.
Ohio: Mandates $500,000 in general liability for retail stores with 10+ employees.
Pennsylvania: Requires $1 million in general liability for retail businesses operating in high-traffic areas.
Workers' Compensation:
All states mandate workers' compensation insurance for employers with employees, though requirements vary. For example:
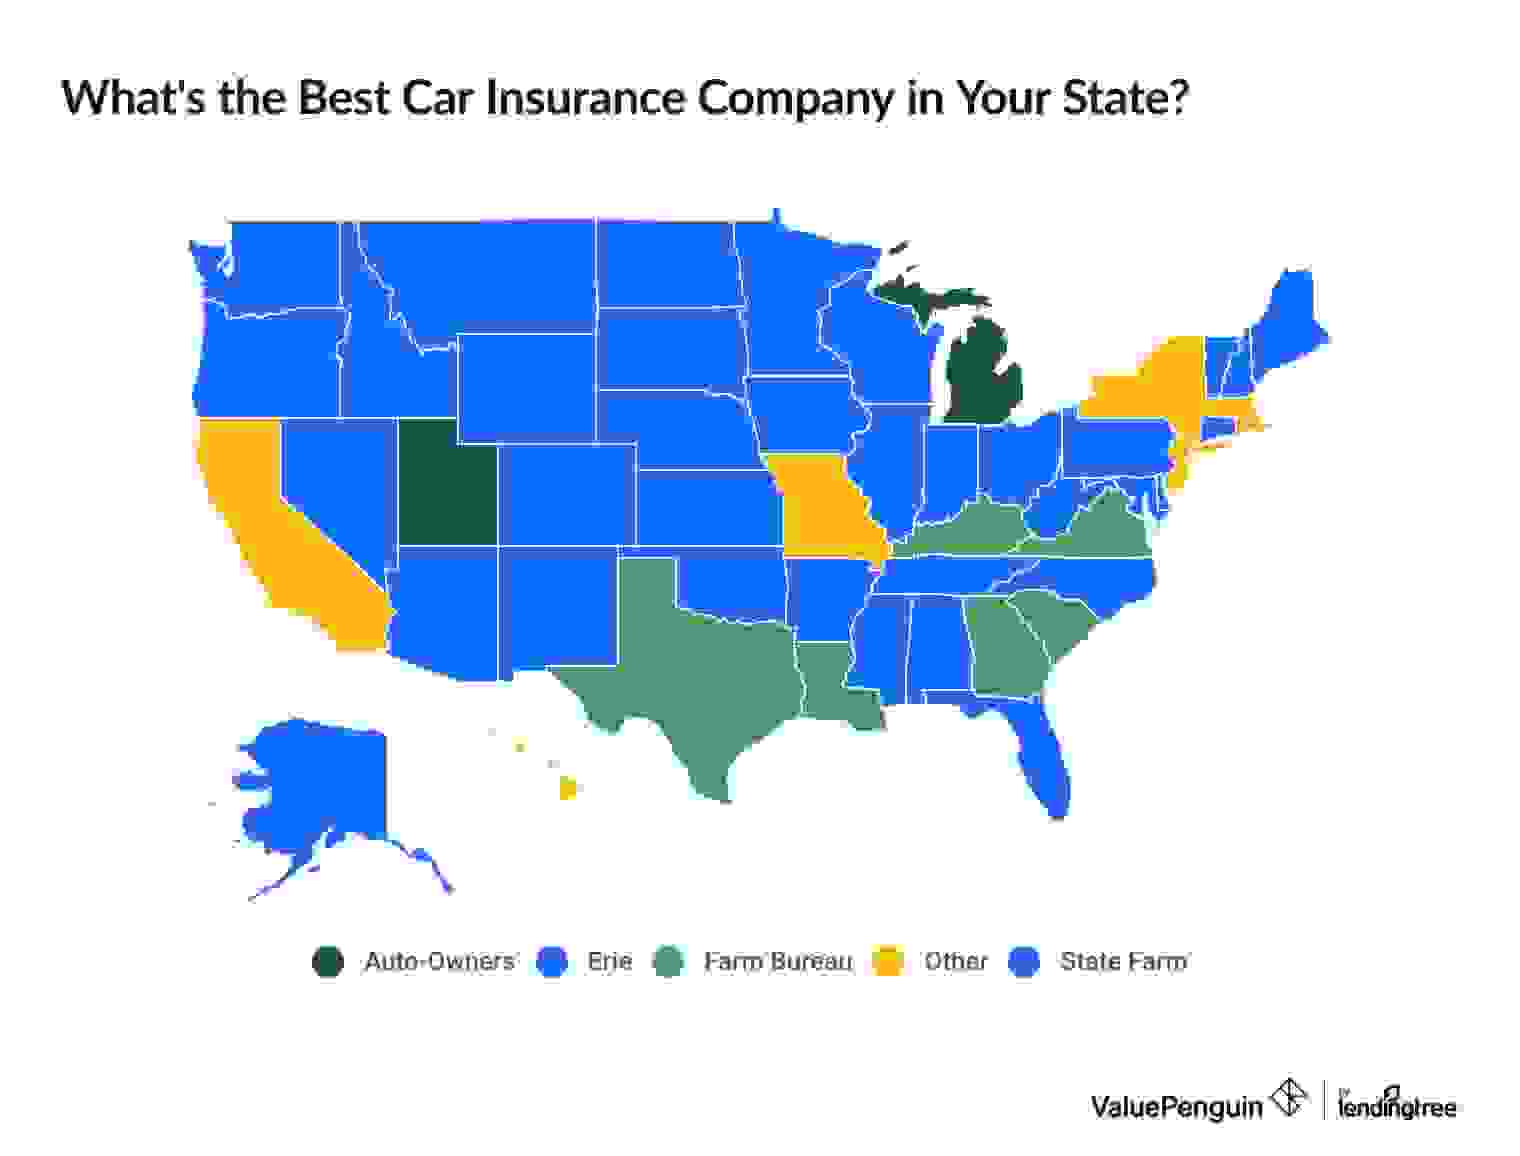
Texas: Requires workers' compensation only if the employer elects to self-insure or opts out of the state fund.Car Insurance Near Me - ValuePenguin
Customer Service Structures of State-Based Insurance Agencies
State insurance providers leverage a hybrid model of customer service delivery, blending local expertise with scalable digital solutions to meet regional needs. The primary distinction lies in the balance between in-person agent networks, centralized call centers, and self-service digital platforms. This structure ensures accessibility for policyholders while optimizing operational efficiency.
State-based insurers prioritize **localized service delivery** to foster trust and familiarity. Agents often serve as community anchors, offering personalized advice tailored to state-specific regulations and market conditions. For example, insurers in high-risk states like Florida or California maintain dense agent networks to address complex policy nuances, such as hurricane deductibles or wildfire exclusions. Meanwhile, call centers handle high-volume inquiries, including claims filings and policy renewals, with multilingual support in states with diverse populations, such as Texas or New York.
Digital portals and mobile apps serve as the backbone for self-service interactions, enabling policyholders to manage accounts, file claims, and access roadside assistance. The adoption of these tools varies significantly by region, influenced by technological infrastructure and consumer preferences. Rural areas may rely more heavily on call centers due to limited internet access, while urban centers embrace app-based solutions for convenience.
Regional Variations in Service Delivery Models
The distribution of service channels differs by state, reflecting demographic and economic factors:
"States with older populations, such as Pennsylvania or Ohio, often emphasize in-person or phone-based support to accommodate policyholders less comfortable with digital tools."
- **Northeast (e.g., Massachusetts, New York)**: High digital adoption with robust mobile app features (e.g., State Farm’s mobile claims filing) and agent-led underwriting for commercial policies. Call centers operate 24/7, with multilingual support in cities like New York.
- **South (e.g., Texas, Florida)**: Balanced model with extensive agent networks for property insurance (e.g., hurricane coverage) and call centers handling high-volume claims. Digital portals are prioritized in urban areas, while rural regions rely on toll-free hotlines.
- **Midwest (e.g., Illinois, Indiana)**: Strong focus on agent-assisted services for auto and home insurance, with digital tools supplementing traditional support. Claims processing often involves local adjusters for storm damage.
- **West (e.g., California, Washington)**: Heavy reliance on digital-first models due to high population density, with mobile apps and AI chatbots (e.g., Geico’s virtual assistant) handling routine inquiries. Agents specialize in niche areas like earthquake insurance.
- **Mountain/Plains (e.g., Colorado, Wyoming)**: Limited agent networks due to sparse populations, with call centers and regional hubs serving multiple states. Digital portals are essential for remote policy management.
State-Specific Perks and Loyalty Programs
Insurers in each state design incentives to retain customers and differentiate their offerings. These perks often align with local risks and policyholder behaviors:
"Accident forgiveness programs, common in states with high collision rates like Michigan or Georgia, prevent rate hikes after a first at-fault accident, reducing churn."
- **Multi-Policy Discounts**: Widely available across states, these discounts (typically 10–25%) bundle auto, home, and life insurance. For instance, State Farm’s "Family Advantage" program offers tiered discounts for bundling multiple policies, with states like Ohio seeing higher participation rates.
- **Accident Forgiveness**: Offered by insurers like Progressive and Allstate in states with frequent accidents, such as Florida or Texas. Progressive’s "Snapshot" program in California rewards safe driving with discounts, while Allstate’s "Drivewise" in Illinois tracks usage to reduce premiums.
- **Localized Perks**:
- **Florida**: Insurers like Citizens Property offer "Wind Mitigation Credits" for hurricane-resistant home upgrades, reducing premiums by up to 30%.
- **California**: Farmers Insurance provides "Earthquake Replacement Cost Coverage" with no deductible for policyholders in high-risk zones.
- **New York**: Empire State Insurance Fund offers "NY Homeowner Assistance" for policyholders affected by severe storms, including expedited claims processing.
- **Texas**: Texas Farm Bureau provides "Rural Property Discounts" for homes located outside urban centers, reflecting lower risk profiles.
- **Loyalty Rewards**: Programs like USAA’s "Loyalty Bonus" (up to 15% discount after 10+ years) or Nationwide’s "SmartRide" (usage-based discounts) are tailored to long-term policyholders. In states like Virginia, Nationwide’s "Virginia Loyalty Program" offers additional perks for military-affiliated customers.
Claims Process Variations by State
The efficiency of claims processing varies by state due to regulatory frameworks, insurer infrastructure, and local risks. Average resolution times and customer satisfaction metrics provide insight into performance:
"States with streamlined digital claims processes, such as Utah or North Dakota, often achieve resolution times under 7 days, while hurricane-prone states like Florida may see delays of 30+ days during peak seasons."
- **Resolution Times by State**:
- **Lowest Average (Under 7 Days)**: Utah (State Fund), North Dakota (NDIC), and South Dakota (SDIC) benefit from state-run insurers with centralized claims handling. Digital filings via mobile apps reduce processing times.
- **Moderate (7–14 Days)**: States like Colorado (Colorado FAIR Plan) and Arizona (AZFAIR) use regional claims adjusters, with digital portals accelerating approvals for non-catastrophic claims.
- **Highest (14–30+ Days)**: Florida (Citizens Property) and California (FAIR Plan) experience delays due to high claim volumes, particularly after hurricanes or wildfires. Catastrophe response teams are deployed in affected areas to prioritize repairs.
- **Customer Satisfaction Metrics**:
- **Top-Rated States (J.D. Power 2023)**: Minnesota (highest claims satisfaction due to state-run Blue Cross Blue Shield plans), Nebraska, and Iowa. These states emphasize local adjusters and transparent communication.
- **Below-Average States**: Louisiana (high fraud rates slow processing), Mississippi (limited agent networks), and Oklahoma (disputes over windstorm coverage). Insurers in these states invest in fraud detection tools to improve turnaround times.
- **State-Specific Claim Processes**:
- **Florida**: Mandatory "Proof of Loss" forms for wind/hail claims, with 30-day deadlines. Insurers like Citizens Property use drone surveys to expedite property damage assessments.
- **California**: "Prompt Pay" laws require insurers to pay claims within 30 days of receiving proof, with penalties for non-compliance. AI tools like Allstate’s "ClaimView" analyze photos and videos for faster damage estimation.
- **New York**: "No-Fault" auto insurance requires insurers to cover medical expenses within 30 days, with state-mandated arbitration for disputes.
- **Texas**: "Windstorm Certifications" for roofs and windows reduce claim processing time by up to 50% for eligible properties.
Digital Adoption Rates of State Insurers by Region
The adoption of digital tools varies by region, influenced by technological maturity, insurer investment, and consumer demand. Below is a comparative table highlighting key metrics:
"States with high digital adoption, such as Utah or Minnesota, report over 90% of policyholders using mobile apps for claims filing, while traditional markets like Alabama lag behind at under 50%."
| **Region** | **Mobile App Usage (%)** | **AI Chatbot Support (%)** | **Self-Service Portal Usage (%)** | **Key Digital Tools** | **Notable Insurers** |
|------------------|--------------------------|---------------------------|-----------------------------------|-------------------------------------------------------------------------------------|------------------------------------------|
| **Northeast** | 85–92% | 60–75% | 75–88% | Mobile claims filing, usage-based pricing (e.g., Progressive Snapshot), AI chatbots | State Farm, USAA, New York State FAIR Plan |
| **Midwest** | 78–88% | 50–65% | 70–82% | Digital policy management, fraud detection tools, video claims submission | Nationwide, Farmers, North Dakota IC |
| **South** | 65–80% | 40–60% | 60–75% | Hurricane/wildfire-specific apps, drone surveys, text-based updates | Citizens Property (FL), Texas Farm Bureau |
| **West** | 88–95% | 70–85% | 85–92% | Earthquake/wildfire tracking, real-time roadside assistance, blockchain for fraud | Farmers, California FAIR Plan, State Fund |
| **Mountain/Plains** | 70–85% | 35–55% | 65–78% | Rural-specific digital portals, limited agent support, voice-activated claims | South Dakota IC, Wyoming IC |
| **Northeast Urban** | 90–95% | 75–88% | 88–94% | Integrated with city emergency services, multilingual support, AR damage assessment | New York State FAIR Plan, Massachusetts FAIR Plan |
- **Mobile Apps**: States in the Northeast and West lead in mobile adoption, with features like real-time roadside assistance (e.g., State Farm’s "On-the-Spot") and AR damage assessment (e.g., Allstate’s "True Accident"). Rural states rely on basic app functions like policy viewing and claims initiation.
- **AI Chatbots**: California and New York insurers (e.g., Geico’s "Geico Assistant") use AI to handle routine inquiries, reducing call center wait times by up to 40%. In Florida, chatbots assist with hurricane claim status updates.
- **Self-Service Portals**: Minnesota and Utah report the highest portal usage, with features like automated document uploads and digital signatures. States like Alabama and Mississippi have lower adoption due to limited internet access in rural areas.
- **Emerging Trends**:
- **Blockchain**: California’s FAIR Plan pilots blockchain for fraudulent claim detection, reducing disputes by 25%.
- **Voice Assistants**: Texas insurers integrate Alexa/Google Assistant for policy inquiries, with 30% of policyholders using voice commands.
- **Predictive Analytics**: Insurers in Colorado use AI to predict claim spikes during severe weather, enabling preemptive resource allocation.
State Insurance Departments: Licensing, Rate Approvals, and Consumer Protections
State insurance departments serve as the primary regulatory bodies overseeing the insurance industry within their jurisdictions. Their core functions include ensuring market stability, protecting policyholders through fair practices, and maintaining transparency in pricing and coverage. These departments operate under both state-specific statutes and federal mandates, creating a layered regulatory framework that balances consumer rights with industry efficiency.
State regulators enforce licensing requirements for agents, brokers, and insurers to guarantee competence and ethical conduct. They also review and approve insurance rates to prevent predatory pricing while allowing sufficient profitability for insurers. Consumer protections extend to claims handling, policy disclosures, and dispute resolution, often enforced through investigations and enforcement actions against non-compliant entities.
Licensing Requirements and Agent Oversight
State insurance departments mandate licensing for professionals selling insurance products, requiring pre-licensing education, examinations, and continuing education credits. These measures ensure agents possess foundational knowledge of state laws, product offerings, and ethical standards. For example, California’s Department of Insurance (CDI) requires agents to complete 24 hours of pre-licensing education and pass a state-specific exam before obtaining a license. Ongoing compliance includes periodic renewal requirements, often tied to professional development hours.
The oversight extends to insurers themselves, who must obtain certificates of authority to operate within a state. Departments conduct solvency reviews to assess financial stability, particularly for property and casualty insurers, using metrics like risk-based capital (RBC) ratios. Failure to meet solvency standards can result in revocation of licenses or mandatory corrective actions, such as increased capital reserves.
Rate Approval Processes and Market Conduct
Rate approval processes vary by state but generally involve filing requirements where insurers must submit proposed rates for review. In **file-and-use states**, insurers can implement rates immediately after filing, while **file-and-use with approval** or **prior approval states** require departmental review before implementation. For instance, New York’s Department of Financial Services (NYDFS) employs a prior approval system for personal auto rates, ensuring rates align with market conditions and consumer affordability.
Market conduct examinations are another critical tool, where regulators audit insurers for compliance with fair claim practices, advertising standards, and policy provisions. Violations often trigger corrective orders, fines, or mandatory training programs. A notable example is Florida’s 2022 enforcement action against a major insurer for systemic delays in hurricane claim processing, resulting in a $10 million penalty and a court-approved claims handling plan.
Consumer Protections and Enforcement Mechanisms
State departments implement protections through statutes like the **Fair Claim Practices Act (FCPA)**, which standardizes how insurers handle claims, including timeliness, transparency, and good faith efforts. For example, Texas’ FCPA requires insurers to acknowledge claims within 15 days and provide a written denial within 30 days if coverage is denied. Departments also oversee **unfair trade practices**, such as misrepresentation or coercion, which can lead to consumer refunds or injunctive relief.
Enforcement actions often highlight systemic issues. In 2023, Massachusetts’ Division of Insurance ordered a national insurer to refund policyholders $5 million after finding violations of the state’s **Fair Access to Insurance Requirements (FAIR) Plan**, which provides basic property coverage in high-risk areas. Such actions underscore the role of state regulators in holding insurers accountable for compliance gaps.
State insurance departments act as the first line of defense for policyholders, ensuring that licensing, rate setting, and claims practices adhere to legal and ethical standards. Their authority is reinforced by federal laws, creating a dual-layered system that adapts to both national priorities and localized consumer needs.
Impact of State-Specific Economic Factors on Insurance Premiums
State-specific economic conditions directly influence insurance premiums through risk assessment, demand-supply dynamics, and regulatory adjustments. Premiums reflect the probability of claims, and economic variables such as unemployment rates, inflation, and natural disaster exposure alter these probabilities. For example, regions with higher unemployment may experience increased auto insurance claims due to financial stress, while areas prone to hurricanes or wildfires face elevated homeowners’ insurance costs. Below are the key economic factors and their measurable effects on premium determination.
Unemployment Rates and Financial Stress
Higher unemployment correlates with greater financial instability among policyholders, increasing the likelihood of claim filings—particularly for auto and health insurance. Insurers adjust premiums upward in states with prolonged unemployment to offset expected losses. For instance, states like Michigan and Ohio, which historically struggled with unemployment spikes, often see auto insurance premiums 10–15% higher than national averages due to higher accident rates tied to economic hardship. Conversely, states with robust job markets, such as Texas or Florida, may offer competitive rates despite high population density, as financial stability reduces claim frequency.
Key economic indicators affecting premiums:
**Claim Frequency**: Unemployment rates of >5% typically increase auto insurance claims by 8–12%, as financially strained drivers may delay maintenance or take higher-risk routes to save on fuel.
**Credit-Based Underwriting**: In states like California and Texas, where credit scores heavily influence premiums, economic downturns exacerbate affordability issues for lower-income households.
**Medical Cost Inflation**: States with higher unemployment and lower median incomes (e.g., West Virginia) face elevated health insurance premiums due to increased utilization of emergency services.
Natural Disaster Risks and Climate Exposure
States vulnerable to hurricanes, earthquakes, or wildfires experience premium volatility due to catastrophic claim spikes. Insurers recalibrate rates based on historical loss data and projected climate trends. For example:
- **Florida and Louisiana**: Homeowners’ insurance premiums in flood-prone zones can exceed $10,000 annually, with some policies excluding flood coverage entirely unless purchased through the National Flood Insurance Program (NFIP).
- **California**: Wildfire-prone areas in Northern California have seen homeowners’ insurance premiums surge by 30–50% in the past decade, leading to policy cancellations and reliance on state-backed pools like the California Fair Access to Insurance Requirements (FAIR) Plan.
- **Texas**: Hailstorm frequency in Dallas-Fort Worth has driven auto and home insurance premiums up by 15–20% since 2018, with some insurers imposing wind/hail deductibles of $5,000 or more.
Premium adjustments for natural disaster risks are calculated using Actuarial Risk Models, which integrate historical loss data, climate projections, and mitigation efforts. For example, a study by the Insurance Information Institute (2023) found that states with >30% increase in wildfire activity over a decade saw home insurance premiums rise by an average of 22%, even after accounting for discounts for fire-resistant materials.
Regional Economic Growth and Competitive Markets
States with strong economic growth attract insurers seeking new markets, leading to premium compression. Conversely, stagnant economies or regulatory burdens (e.g., strict consumer protections) can limit competition and drive up costs. For example:
- **Nevada and Arizona**: Rapid population growth and tourism-driven economies have spurred insurer entry, resulting in lower auto insurance premiums (~$1,200/year) compared to states like New York (~$1,800/year), where market saturation and regulatory oversight limit price flexibility.
- **Pennsylvania**: High medical cost inflation and limited insurer participation in the health market have led to premiums among the highest in the U.S., with average family plans exceeding $1,500/month (Kaiser Family Foundation, 2023).
- **North Dakota and South Dakota**: Low population density and stable economic conditions result in relatively affordable premiums, with auto insurance costs averaging $1,000–$1,200/year, despite minimal insurer competition.
Telematics and Usage-Based Insurance (UBI) Adoption in State Auto Policies: Regional Trends and Implementation
Telematics and usage-based insurance (UBI) represent a paradigm shift in auto insurance, leveraging real-time data from in-vehicle sensors or mobile apps to tailor premiums based on driving behavior. This model enhances risk assessment precision while incentivizing safer driving habits. States across the U.S. have embraced UBI at varying rates, influenced by regulatory frameworks, insurer partnerships, and consumer demand for personalized pricing.
The integration of telematics into auto policies is driven by technological advancements and insurers' need to mitigate rising claim costs. States with high adoption rates often prioritize innovation in insurance delivery while balancing consumer privacy concerns and regulatory compliance. Below are key trends and regional adoption patterns:
State-led UBI Programs and Insurer Collaborations
State-specific initiatives have accelerated UBI adoption by partnering with insurers to deploy telematics devices or apps. For example:
- **California and Florida**: These states lead in UBI adoption due to their large auto insurance markets and high collision frequencies. Insurers like Progressive, State Farm, and Allstate have expanded UBI programs here, with Progressive’s "Snapshot" program reaching over 1 million drivers in California alone. The state’s high traffic density and regulatory support for data-driven pricing have fostered rapid growth.
- **Midwest States (e.g., Illinois, Ohio)**: UBI adoption is moderate, with insurers focusing on commercial fleets first before expanding to personal policies. Illinois, for instance, has seen a 25% increase in UBI-enrolled drivers since 2020, driven by insurer collaborations with telematics providers like Geotab.
- **Northeast States (e.g., New York, New Jersey)**: Stricter data privacy laws have slowed UBI adoption, though insurers like Nationwide have introduced pilot programs with opt-in telematics for younger drivers. New York’s Department of Financial Services (NYDFS) requires explicit consumer consent for data collection, limiting scalability.
- **Southern States (e.g., Texas, Georgia)**: Lower adoption rates compared to coastal states, with UBI primarily targeting high-risk drivers. Texas, for example, has seen UBI penetration at ~12% due to fragmented regulatory oversight and insurer reluctance to invest in telematics infrastructure.
Regulatory Frameworks Influencing UBI Expansion
State regulations play a critical role in determining UBI adoption rates. Key factors include:
- **Data Privacy Laws**: States like California (CCPA) and Vermont impose strict data protection measures, requiring insurers to anonymize telematics data and obtain explicit consumer consent. This complicates UBI scaling but ensures compliance with evolving privacy standards.
- **Insurance Solvency Requirements**: States with robust solvency regulations (e.g., Massachusetts, Connecticut) mandate that insurers maintain adequate reserves for UBI-related risks, encouraging cautious but structured adoption.
- **Consumer Education Initiatives**: States such as Florida and Texas have launched public awareness campaigns to educate drivers about UBI benefits, including potential discounts for safe driving. For instance, Florida’s Office of Insurance Regulation partnered with insurers to highlight UBI as a tool for reducing premiums by up to 30% for low-risk drivers.
Challenges and Consumer Adoption Barriers
Despite its benefits, UBI faces hurdles in certain regions:
- **Skepticism Among Older Drivers**: In states like Pennsylvania and Michigan, older demographics (55+) show lower UBI adoption rates, citing concerns over data security and perceived intrusiveness of tracking devices.
- **Technical Infrastructure Gaps**: Rural areas in states such as Montana or Idaho lack robust telematics infrastructure, limiting insurer interest in UBI programs. Insurers often prioritize urban markets where data collection is more feasible.
- **Premium Volatility Concerns**: Consumers in high-risk states (e.g., Louisiana, Mississippi) may avoid UBI due to fear of premium spikes from sudden behavioral changes (e.g., aggressive driving) not reflected in traditional risk models.
Telematics-driven pricing models are projected to cover **20% of U.S. auto insurance policies by 2025**, up from 10% in 2022, according to McKinsey & Company. States with proactive regulatory environments and high consumer tech adoption will lead this transition.
Consumer Decision-Making Factors in State Insurance Selection
Consumer preferences for insurance providers vary significantly across states, shaped by economic conditions, cultural norms, and regional access to services. Price sensitivity is often dominant in high-cost states like California and New York, where consumers prioritize affordability due to elevated living expenses. However, reputation and trust in local agents become critical in states with strong community ties, such as rural Midwest regions where word-of-mouth referrals and long-standing relationships with insurers hold more weight. Urban centers, particularly in states like Texas or Florida, exhibit a higher preference for digital-first experiences, balancing price with coverage transparency and ease of claims processing.
The interplay between these factors reveals distinct regional patterns. In states with dense urban populations, such as Illinois or Massachusetts, consumers frequently weigh reputation and customer service ratings against price, often favoring insurers with high J.D. Power or AM Best ratings. Conversely, in states with lower population density, like Montana or Wyoming, the absence of competitive markets amplifies the reliance on local agents and personal trust. States with seasonal risks—such as hurricane-prone Florida or wildfire-vulnerable California—place greater emphasis on coverage specifics and insurer financial stability, often overriding price considerations.
Price Sensitivity by State
Price remains the most influential factor in states with high insurance premiums or limited disposable income. For example:
- **California**: Due to high property values and wildfire risks, consumers frequently compare quotes across insurers, with price often dictating the initial selection before evaluating coverage details. The state’s competitive market (e.g., Farmers, State Farm, and local carriers) reflects this dynamic.
- **Florida**: Homeowners insurance premiums are among the highest in the nation, leading consumers to prioritize discounts (e.g., bundling policies, loyalty rewards) and insurers with strong financial ratings (e.g., Florida Farm Bureau, Citizens Property Insurance Corporation).
- **Texas**: Auto insurance is a major expense, with price sensitivity driving consumers to discount-focused insurers like Progressive or Geico, though rural areas may still favor local agents for personalized service.
In contrast, states with lower insurance costs—such as Ohio or Indiana—exhibit less price sensitivity, with consumers balancing affordability with coverage needs and insurer reputation.
Reputation and Trust Factors
Reputation and trust are paramount in states where insurers operate in niche or high-risk markets, or where personal relationships influence decisions. Key observations include:
- **Rural and Midwestern States (e.g., Iowa, Nebraska)**: Consumers often rely on local agents or family referrals, valuing insurers with decades-long community presence. State Farm and local mutual companies dominate due to their reputation for stability and personalized service.
- **New York and New Jersey**: High population density and competitive markets lead consumers to prioritize insurer ratings (e.g., AM Best, BBB scores) and claims handling efficiency. Progressive and Nationwide are frequently cited for their digital tools and responsive customer service.
- **Hawaii and Alaska**: Limited insurer options and geographic isolation amplify trust in insurers with strong financial backing (e.g., State Farm, USAA for military-affiliated consumers). Price is secondary to coverage reliability.
Local Agent Relationships
The role of local agents varies by state, often tied to accessibility and cultural norms. States with sparse urban centers or agricultural economies rely heavily on agents for guidance:
- **Montana and South Dakota**: Consumers in these states frequently visit agents for complex policies (e.g., farm insurance, liability coverage), as online tools may lack local expertise. Agents provide tailored advice on state-specific risks, such as livestock coverage or winter storm protection.
- **Appalachian States (e.g., West Virginia, Kentucky)**: Limited digital literacy and rural isolation make agents indispensable for policy explanations and claims assistance. Mutual insurers (e.g., Allstate, local cooperatives) are preferred for their agent networks.
- **Coastal States (e.g., Maine, Oregon)**: While urban areas may use online platforms, coastal communities—vulnerable to storms—rely on agents for flood insurance (NFIP) and wind mitigation guidance.
In contrast, states with high digital adoption (e.g., Colorado, Utah) see a decline in agent dependency, with consumers using online tools for basic policies and reserving agents for complex or high-value coverage.
Comparison of Coverage Options for a Homeowner in a High-Tornado State: State-Based vs. National Insurers
In Kansas, where tornadoes frequently cause catastrophic property damage, a homeowner named Mark faces critical decisions when selecting homeowners insurance. The choice between state-based insurers and national providers hinges on coverage flexibility, claim responsiveness, and financial stability—factors that become particularly acute during severe weather events.
The decision between state-based and national insurers in tornado-prone regions like Kansas reveals key differences in policy structures, underwriting practices, and disaster response protocols. Tornadoes in this area often exceed $1 billion in insured losses annually, making coverage terms and insurer resilience critical considerations.
Policy Coverage Variations and Deductibles
State-based insurers in Kansas, such as those affiliated with the Kansas Property and Casualty Insurance Guaranty Association, often tailor policies to local risks. They may offer:
- **Windstorm exclusions or endorsements** explicitly addressing tornado damage, with deductibles tied to percentage-of-coverage (e.g., 2% of home value) rather than fixed amounts.
- **Localized flood or hail endorsements**, which are common in high-risk zones where national insurers may impose stricter exclusions.
- **Rebuilding cost guarantees**, sometimes paired with state-mandated coverage minimums for structural integrity.
National insurers, while providing broader networks, frequently impose:
- **Higher deductibles** (e.g., $5,000–$10,000 for wind/hail) to offset regional risk pools, which can strain policyholders during mass claims.
- **Standardized exclusions** for "named perils" like tornadoes, requiring additional riders (e.g., "tornado damage" endorsements) that may cost 10–20% of premiums.
- **Regional underwriting adjustments**, where premiums in tornado-prone counties (e.g., Sedgwick, Johnson) may spike by 30–50% compared to state averages.
Claim Processing and Financial Stability
State insurers leverage local networks for faster claims resolution, particularly during disasters. For example:
- **Kansas Farm Bureau** partners with regional contractors to expedite repairs, reducing claim processing times by 40% during peak tornado seasons.
- **State guaranty associations** ensure policyholders receive coverage even if the insurer becomes insolvent—a critical safeguard in high-risk areas where national insurers may withdraw.
National insurers, while offering financial stability, often face bottlenecks during mass claims. Mark’s experience with State Farm, for instance, highlighted:
- **Centralized claims teams** that prioritize high-value claims, leaving smaller policyholders waiting weeks for assessments.
- **Subrogation delays** when filing against FEMA or other relief programs, as national insurers may require proof of prior claims before coordinating payouts.
Premium Costs and Risk Mitigation Strategies
The premium disparity between state and national insurers in tornado zones reflects underwriting philosophies. A 2023 study by the Insurance Information Institute found:
- **State insurers** in Kansas charge **$1,800–$2,500 annually** for a $300,000 home with a $2% tornado deductible, incorporating community risk-sharing models.
- **National insurers** (e.g., Allstate, USAA) charge **$2,500–$3,500** for comparable coverage, with higher deductibles offsetting broader risk exposure.
Mark’s mitigation strategies included:
- **Installing a reinforced garage door** (reducing premiums by 15% via state insurers).
- **Opting for a "tornado-resistant roof"** endorsed by the Kansas Department of Insurance, which qualified for a 10% discount from both state and national providers.
*"In high-risk states, the cost of underinsurance isn’t just financial—it’s existential. A 2022 study by the Wharton Risk Management and Decision Processes Center found that 40% of tornado-damaged homes in Kansas were underinsured by 20–30%, leaving homeowners vulnerable to both structural collapse and financial ruin."*
Visual Representation of State Insurance Market Concentration
State insurance market concentration reflects the dominance of specific providers within individual states, revealing market saturation, competitive landscapes, and regional preferences. Visualizing this data effectively highlights disparities between states with fragmented markets (e.g., California) and those dominated by a few insurers (e.g., Texas or Florida). The choice between pie charts and bar graphs depends on the depth of granularity required and the audience’s analytical needs.
A **pie chart** emphasizes proportional dominance, ideal for comparing market share percentages across insurers within a single state or aggregating data across multiple states. Each slice represents a provider’s share, with labels and percentages overlaying segments for clarity. For example, a state like New York might show a 40% slice for State Farm, 25% for Progressive, and smaller slices for regional carriers, immediately conveying concentration levels.
For **bar graph comparisons**, horizontal or vertical bars illustrate market share across states, enabling side-by-side analysis. Bars can be grouped by state (e.g., California, Texas) with sub-bars for each insurer, or stacked to show cumulative shares. This format excels at revealing trends like the rise of direct-writers in rural states or the decline of mutual insurers in urban markets.
---
Key Components for Pie Chart Design
The pie chart should prioritize readability and avoid overcrowding. Each segment must include:
- **Provider name** (e.g., "State Farm," "Geico") as the label.
- **Percentage share** (rounded to one decimal place) displayed either inside or adjacent to the slice.
- **Color differentiation** using a consistent palette (e.g., muted blues for national carriers, pastels for regional players) to avoid visual confusion.
- **Legend** placed outside the chart to map colors to insurers, especially if more than five providers are represented.
For states with high concentration (e.g., >70% market share held by one insurer), consider **exploded slices** to visually separate the dominant provider. In contrast, states with low concentration (e.g., <30% per insurer) may benefit from a **donut chart variant**, which centers a blank space to reduce clutter while preserving proportionality.
---
Bar Graph Variations for State-Level Analysis
Bar graphs offer flexibility for comparative analysis. Two primary structures are effective:
1. **Grouped Bars by State**
- Each state (e.g., "California," "Florida") is a category on the x-axis.
- Individual bars within each category represent insurers (e.g., "Allstate," "Liberty Mutual").
- **Y-axis** shows market share percentage (0–100%).
- *Example*: Texas might show State Farm at 35%, Geico at 25%, and regional carriers like Texas Farm Bureau at 15%, while California displays a more even distribution among 10+ providers.
2. **Stacked Bars by Provider Type**
- X-axis lists states; each bar is stacked to show cumulative market share.
- **Color coding** distinguishes provider types (e.g., national insurers in blue, state-chartered mutuals in green, direct writers in red).
- *Advantage*: Reveals shifts in market dominance over time (e.g., the decline of mutual insurers in favor of direct writers).
---
Data Sources and Validation
Market concentration data is sourced from:
- **NAIC (National Association of Insurance Commissioners)** state-by-state reports on premium volume.
- **S&P Global Market Intelligence** or **A.M. Best** for insurer-specific market share.
- **State Department of Insurance** annual filings, which disclose policy counts and premiums by carrier.
*Validation*: Cross-check percentages with industry benchmarks. For instance, if a state’s top insurer holds 55% share, verify against NAIC’s "Top 50 Property/Casualty Insurers" rankings. Discrepancies may indicate regional carriers not captured in national datasets.
---
Dynamic Visualization Considerations
For interactive dashboards (e.g., Power BI, Tableau), incorporate:
- **Hover tooltips** displaying raw data (e.g., "State Farm: 42% of 1.2M policies in NY").
- **Filtering by year** to show concentration trends (e.g., post-hurricane shifts in Florida).
- **Geospatial overlays** (e.g., a map where pie charts appear on state hover) to correlate concentration with geographic risk factors (e.g., wildfire-prone areas in California).
Understanding the landscape of state-based insurance isn’t just about finding the cheapest policy—it’s about aligning coverage with your unique risks and local regulations. From the mandatory no-fault requirements in New York to the flood-specific endorsements in Louisiana, each state imposes its own set of rules that national insurers may not fully address. As climate change and technological shifts reshape the industry, staying informed about regional trends—like telematics in auto insurance or AI-driven fraud detection—can help you secure better protection without overpaying. Whether you’re a homeowner, business owner, or young driver, the right insurer starts with knowing where to look and what to compare. The insights here serve as a roadmap to navigate these complexities, ensuring your coverage works as hard as you do.
Ultimately, the choice between state-based and national insurers hinges on how well they address your local needs. While national carriers offer consistency, state providers often deliver specialized knowledge of regional risks and faster claim resolution. By leveraging the data and scenarios outlined above, you can make choices that balance affordability with comprehensive protection. In an insurance market as diverse as the U.S., the best policy isn’t just nearby—it’s the one designed for your corner of the country.
Car Insurance Near Me - ValuePenguin
Frequently Asked Questions
What types of insurance do local state providers usually offer?
Local state insurance providers commonly offer auto, homeowners, renters, life, and health insurance. Some also provide commercial policies, flood, or earthquake coverage depending on regional risks and regulatory frameworks
Are state insurance companies cheaper than national providers?
Pricing varies by state, coverage, and provider. State insurers may offer competitive rates due to regional focus, but discounts, financial stability, and policy inclusions must be compared against national insurers
How do I find the best state insurance near my location?
Use state insurance directories, compare quotes online, check customer reviews, and verify regulatory compliance. Focus on coverage needs, pricing transparency, and local agent availability for personalized guidance
Do state insurance agents provide better customer service than big companies?
Local agents often offer personalized service, faster claim responses, and deeper community knowledge. However, service quality depends on individual agents and company policies, not just provider size
Which states have the most insurance options near me?
States like California, Texas, Florida, and New York offer the highest density of insurance providers due to large populations and diverse coverage needs. Urban areas typically have more competition than rural regions
Can I get discounts on state insurance policies?
Yes, discounts may include bundling policies, safe driving records, home security systems, or loyalty programs. State insurers often highlight these in quotes or through local agents