10 Ways to Find Affordable Car Insurance in NYC
Table of Contents
- 1. Pricing Dynamics in NYC
- 2. Key Factors Affecting Affordability
- 3. Top Discounts NYC Drivers Overlook
- 4. Comparing Quotes Like a Pro
- 5. Common Mistakes That Inflate Costs
- 6. NYC-Specific Resources and Programs
- 7. How Driving Habits Impact Rates
- 8. When to Switch Providers
- Frequently Asked Questions
- 10 Tips to Secure Affordable Car Insurance in NYC
- Conclusion
Finding **affordable car insurance NYC** means securing reliable auto coverage at a price that fits a budget without compromising safety or legality. For example, a driver in Brooklyn paying $2,500 annually for full coverage might discover comparable protection for $1,800 by adjusting deductibles or exploring lesser-known insurers. The challenge lies in balancing premiums with New York’s strict liability laws and high accident rates, which often inflate costs.
Affordable car insurance in NYC isn’t just about saving money—it’s about smart risk management. With the city’s dense traffic, frequent fender benders, and elevated theft risks, drivers need policies that offer financial safeguards without draining their wallets. Historically, NYC’s insurance market has been volatile, reacting to spikes in claims, regulatory changes, and even seasonal trends like winter weather-related accidents. Understanding these dynamics allows drivers to navigate the system effectively.
This guide explores actionable strategies to slash premiums, common pitfalls to avoid, and how to leverage NYC-specific resources. From comparing quotes to optimizing driving habits, each section provides practical steps to secure **affordable car insurance NYC** without cutting corners.
1. Pricing Dynamics in NYC
New York City’s car insurance market operates on unique pricing factors that differ from other states. The average annual premium in NYC hovers around $2,200—nearly double the national average—due to high population density, elevated accident rates, and stringent state regulations. For instance, a driver in Manhattan might pay 30% more than one in the suburbs because of higher traffic congestion and repair costs.
Insurance providers use algorithms that weigh factors like location, driving history, vehicle type, and even credit scores. A 2022 study by the New York State Department of Financial Services found that drivers with clean records in lower-risk boroughs like Staten Island could save up to 25% compared to those in Queens or Brooklyn. Understanding these variables empowers drivers to negotiate better rates or qualify for discounts.
2. Key Factors Affecting Affordability
- Vehicle Type and Safety Ratings
Choosing a car with high safety ratings and low theft statistics directly impacts premiums. For example, a Honda Civic, frequently rated as one of the safest compact cars, typically costs 15–20% less to insure than a Jeep Wrangler in the same coverage tier. Insurers reward drivers for selecting vehicles with advanced safety features like automatic braking or lane-keeping assist, which can reduce collision claims.
- Credit History
New York allows insurers to use credit-based insurance scores to determine rates, meaning a lower credit score can inflate premiums by 30–50%. A driver with a 700 credit score might pay $1,900 annually, while someone with a 600 score could face a $2,800 bill. Improving credit—by paying bills on time or reducing debt—can yield significant savings within a year.
- Annual Mileage
NYC drivers who log under 7,500 miles annually often qualify for low-mileage discounts. For instance, a commuter who works remotely and drives only for errands could save $300–$500 by reporting reduced mileage. Insurers assume lower risk for drivers who spend less time on the road, particularly in high-traffic areas.
- Coverage Limits and Deductibles
Opting for higher deductibles (e.g., $1,000 instead of $500) can cut comprehensive/collision costs by 10–15%. However, this strategy only works if the driver can afford the out-of-pocket expense in case of a claim. A balance must be struck between upfront savings and long-term risk exposure.
- Bundling Policies
Combining auto insurance with renters or homeowners insurance through the same provider often unlocks discounts of 10–25%. For example, a driver paying $1,500 for car insurance might reduce that to $1,200 by bundling with a $1,200 renters policy, saving $300 annually without sacrificing coverage.
3. Top Discounts NYC Drivers Overlook
Many NYC drivers miss out on discounts that could lower their **affordable car insurance NYC** premiums by hundreds annually. For instance, the “paperless billing” discount—often 5–7%—is frequently overlooked because drivers assume it’s only for tech-savvy users. Similarly, discounts for completing defensive driving courses or installing anti-theft devices (like LoJack) can trim costs by 10–15%, yet fewer than 30% of NYC policyholders apply for them.
Insurers also offer loyalty discounts for long-term customers, but drivers who switch providers every few years forfeit these savings. A policyholder with Progressive who renews annually for five years might qualify for a 10% discount, whereas someone who switches to Geico after two years misses out entirely. Proactively inquiring about all available discounts—even those not advertised—can uncover hidden savings.
4. Comparing Quotes Like a Pro
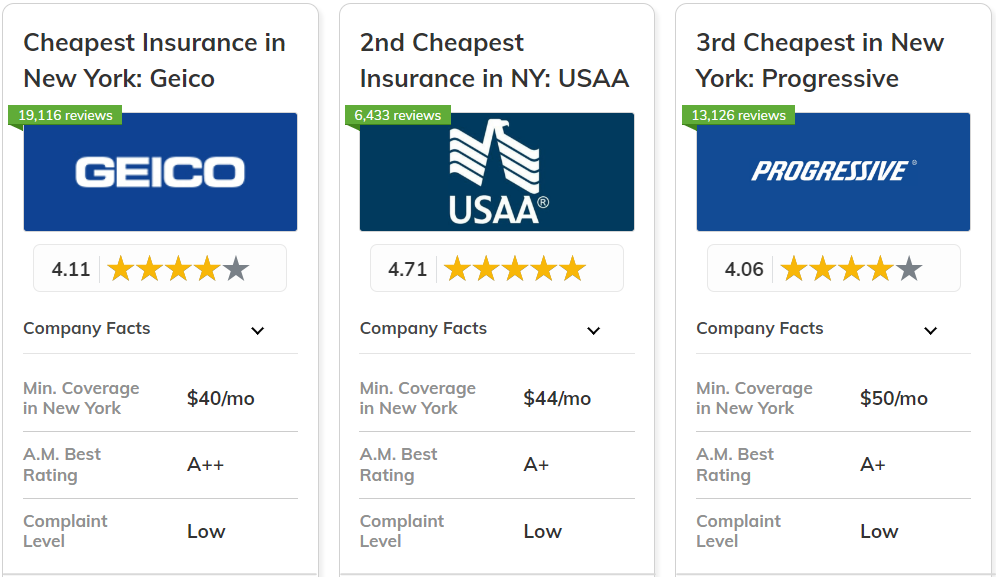
Obtaining quotes from at least three insurers is critical, but the process must be strategic. Simply inputting the same details into multiple provider websites can yield inconsistent results due to varying underwriting criteria. For example, State Farm might offer a lower rate for a Brooklyn driver with a speeding ticket if they also have a homeowners policy, while Allstate could provide a better deal if the driver’s commute is under 10 miles.
Tools like the New York State Department of Financial Services’ “Compare Insurance Rates” portal streamline this process by aggregating quotes from licensed providers. However, drivers should also contact independent agents who can access policies from smaller, regional insurers—often overlooked in online comparisons. A 2023 analysis found that drivers who used agents secured rates 8–12% lower than those relying solely on digital tools.
5. Common Mistakes That Inflate Costs
- Ignoring Usage-Based Insurance
Usage-based programs (like Progressive’s Snapshot or Allstate’s Drivewise) track driving habits via telematics and reward safe behavior with discounts of up to 30%. A driver in Queens who avoids hard braking and rapid acceleration could save $400 annually, yet many dismiss these programs due to privacy concerns or the hassle of installing a device.
- Skipping the Shopping Period
New York law mandates insurers notify policyholders 45 days before renewal. Failing to shop around during this window means accepting the insurer’s standard rate hike, which can be 5–15% annually. A driver who ignores this window might overpay by $200–$400 over three years.
- Underreporting Commute Details
Misrepresenting commute distance or frequency—even by a few miles—can void coverage or trigger claim denials. For example, a driver who claims a 5-mile commute but actually drives 12 miles risks higher premiums if discovered during a claim. Insurers verify commute data through GPS and traffic patterns, so accuracy is non-negotiable.
- Not Updating Policy After Life Changes
Major life events like marriage, moving, or purchasing a home can lower premiums if the insurer is notified. A newlywed in Manhattan might qualify for a 10% discount by combining policies, while a driver switching from a sports car to a hybrid could see a 20% reduction. Failing to update policies after such changes leaves money on the table.
- Choosing Minimum Coverage Only
New York’s minimum liability coverage ($25,000 per person/$50,000 per accident) is often insufficient given medical and repair costs. A driver at fault in a Brooklyn accident with $60,000 in damages could face personal liability for the excess. Upgrading to higher limits (e.g., $100,000/$300,000) adds $200–$400 annually but protects against catastrophic financial loss.
6. NYC-Specific Resources and Programs
New York offers unique programs to assist drivers in securing **affordable car insurance NYC**. The New York Auto Insurance Plan (NYAIP) ensures high-risk drivers—such as those with DUIs or frequent accidents—can obtain coverage, though premiums are elevated. For example, a driver with a DUI might pay $3,500 annually through NYAIP but could reduce this by 20% by completing a state-approved defensive driving course.
Additionally, nonprofits like the New York Common Benefit Fund provide financial assistance for low-income drivers facing unaffordable rates. Eligible drivers might qualify for subsidies covering 50–70% of their premiums. Exploring these resources can transform an unaffordable policy into a manageable one without compromising protection.
7. How Driving Habits Impact Rates
Safe driving habits are the most direct way to lower **affordable car insurance NYC** premiums. Insurers categorize drivers into risk tiers based on behavior: those with clean records in low-risk areas (e.g., Staten Island) pay 20–30% less than those in high-accident zones (e.g., parts of Brooklyn). For instance, a driver who avoids speeding tickets and fender benders over three years might see their premium drop from $2,200 to $1,600.
Telematics programs reinforce this by offering real-time feedback. A study by the Insurance Institute for Highway Safety found that drivers using telematics reduced their annual premiums by an average of 12% within six months by improving braking habits and avoiding distracted driving. Even small adjustments—like reducing nighttime driving—can yield noticeable savings.
8. When to Switch Providers
Switching insurers is a viable strategy when premiums rise by 15% or more without justification, or when better coverage becomes available elsewhere. For example, a driver whose premium jumps from $1,800 to $2,300 after a minor claim might find a comparable policy for $1,900 with a different provider. However, timing matters: switching mid-policy can void certain discounts or trigger gaps in coverage.
Loyalty discounts often phase out after five years, making it prudent to reassess options annually. Drivers should also switch if their current insurer denies a legitimate claim or fails to communicate clearly. A 2022 survey revealed that 40% of NYC drivers who switched providers cited poor customer service as their primary reason, highlighting the importance of both price and service quality.
10 Tips to Secure Affordable Car Insurance in NYC
Implementing these strategies can lead to significant savings on **affordable car insurance NYC** without compromising protection:
Tip 1: Shop During the Open Enrollment Window. New York law requires insurers to notify policyholders 45 days before renewal. Use this window to compare quotes and negotiate rates, as providers often offer incentives to retain customers.
Tip 2: Choose a High-Safety-Rated Vehicle. Cars with top safety ratings (e.g., Subaru Outback, Honda Accord) qualify for lower premiums. A vehicle with a 5-star safety rating can save 15–20% compared to a similarly priced car with average ratings.
Tip 3: Install Anti-Theft Devices. Devices like LoJack or OnStar can reduce premiums by 10–15%. NYC’s high theft rates make anti-theft measures particularly valuable, often paying for themselves within a few years.
Tip 4: Opt for Usage-Based Insurance. Programs like Progressive’s Snapshot or Allstate’s Drivewise track driving habits and reward safe behavior with discounts of up to 30%. Even minor improvements (e.g., reducing hard braking) can yield savings.
Tip 5: Increase Deductibles Strategically. Raising deductibles from $500 to $1,000 can cut comprehensive/collision costs by 10–15%. Ensure the deductible amount is affordable in case of a claim to avoid financial strain.
Tip 6: Bundle Policies with the Same Insurer. Combining auto insurance with renters or homeowners insurance often unlocks 10–25% discounts. For example, a driver paying $1,500 for car insurance might reduce that to $1,200 by bundling with a $1,200 renters policy.
Tip 7: Ask About All Available Discounts. Many discounts—such as paperless billing, loyalty rewards, or good student discounts—are underutilized. Proactively inquire about every possible discount, even those not advertised.
Tip 8: Maintain a Clean Driving Record. A single ticket or accident can increase premiums by 20–50% for 3–5 years. Avoiding infractions is the most reliable way to keep rates low long-term.
Tip 9: Reassess Coverage Needs Annually. Life changes (e.g., buying a home, adding a teen driver) may require adjusting coverage. For example, a driver who no longer commutes to Manhattan might reduce collision coverage if their car is parked most of the time.
Tip 10: Leverage NYC-Specific Programs. Resources like the New York Auto Insurance Plan (for high-risk drivers) or the Common Benefit Fund (for low-income individuals) can provide financial relief. Explore these options if standard policies are unaffordable.
Conclusion
Securing **affordable car insurance NYC** requires a mix of strategic shopping, leveraging discounts, and optimizing coverage. Key aspects include understanding pricing dynamics, avoiding common mistakes, and utilizing NYC-specific resources like usage-based programs or financial assistance initiatives. Small adjustments—such as bundling policies, choosing high-safety vehicles, or maintaining a clean record—can add up to substantial annual savings.
As NYC’s insurance landscape evolves, staying proactive and informed remains the best way to balance cost and protection. Regularly reviewing policies and exploring new options ensures drivers continue to benefit from the most competitive rates available.

Frequently Asked Questions
How much can I save by bundling car insurance with renters insurance?
Bundling typically saves 10–25% on auto premiums. For example, a driver paying $1,500 for car insurance might reduce that to $1,200 by adding a $1,200 renters policy, resulting in a $300 annual savings. Always confirm the exact discount with your insurer, as percentages vary.
Will my credit score significantly affect my NYC car insurance rate?
Yes, credit scores influence rates in New York. A driver with a 700 score might pay $1,900 annually, while someone with a 600 score could face a $2,800 bill—a 47% increase. Improving credit by paying bills on time or reducing debt can lower premiums within 12–18 months.
Are there discounts for electric or hybrid vehicles in NYC?
Some insurers offer discounts of 5–10% for electric or hybrid vehicles due to lower repair costs and reduced accident risks. For example, a Tesla Model 3 owner in Manhattan might pay 8% less than a comparable gas-powered car. Always ask providers about green vehicle incentives.
How often should I compare car insurance quotes in NYC?
Comparing quotes annually is ideal, but drivers should also reassess after major life changes—such as moving, marriage, or purchasing a new car. NYC’s competitive market means rates fluctuate, and a policy that was affordable last year might not be this year.
Can I get affordable car insurance in NYC with a speeding ticket?
Yes, but premiums may increase by 20–50% for 3–5 years. For example, a driver with a single speeding ticket might see their rate rise from $1,800 to $2,500. Completing a defensive driving course can mitigate this increase by 5–10% and may shorten the penalty period.
What’s the best way to lower my premium after an accident?
After an accident, review your policy for safe-driver discounts or accident forgiveness programs. Some insurers (like State Farm) waive rate increases for the first at-fault accident if the driver has a clean record. Additionally, increasing deductibles or removing unnecessary coverage (e.g., gap insurance) can reduce premiums.