Affordable Car Insurance Michigan Tips And Savings
Table of Contents
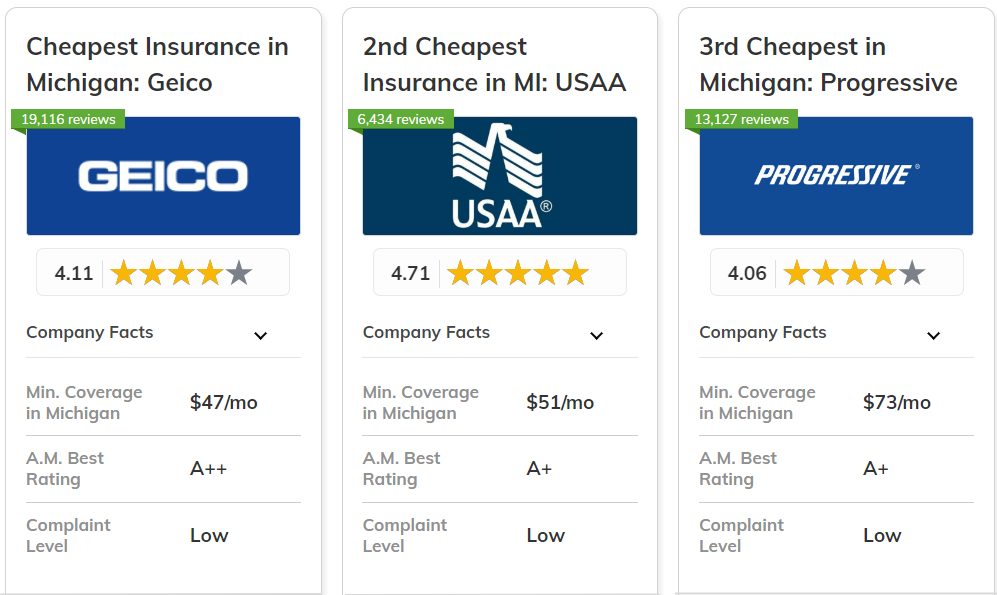
- Key Factors Influencing Car Insurance Costs in Michigan, Including State-Specific Regulations and Average Premiums
- Common Discounts Offered by Michigan Insurers and Strategies to Maximize Savings
- Trade-offs Between Full Coverage and Liability-Only Policies in Michigan
- Common High-Risk Driver Classifications in Michigan and Strategies to Reduce Premium Impact
- City-by-City Breakdown of Average Car Insurance Costs in Michigan and Influencing Factors
- Checklist for Evaluating Whether Switching Insurers in Michigan Is Cost-Effective
- Michigan’s Winter Driving Laws and Their Impact on Insurance Costs and Coverage Needs
- Michigan’s No-Fault Insurance System and PIP Benefits: Structure, Costs, and Policyholder Implications
- Michigan-Specific Tools for Estimating and Comparing Affordable Car Insurance Costs
- 5-Year Cost Projection for Michigan Drivers with Optimized Insurance Strategies
Michigan drivers face some of the highest car insurance costs in the nation, but affordability isn’t impossible. The state’s no-fault system, unique risk-sharing programs, and regional cost disparities create both challenges and opportunities for saving. Whether you’re a first-time policyholder, a high-risk driver, or someone navigating urban vs. rural premiums, understanding the levers that control your rates can cut costs without sacrificing protection. From hidden discounts to smart coverage trade-offs, this guide breaks down how Michigan’s insurance landscape works—and how to exploit its quirks to your advantage.
With average annual premiums nearing $3,000—well above the national average—many drivers overlook strategies that could shave hundreds off their bills. The key lies in leveraging Michigan-specific programs, like the Automobile Insurance Placement Facility for high-risk drivers, or exploiting regional price gaps between Detroit’s high-cost urban centers and the more affordable Upper Peninsula. By combining state-mandated protections with proactive financial planning, even budget-conscious drivers can secure reliable coverage without financial strain.
Key Factors Influencing Car Insurance Costs in Michigan, Including State-Specific Regulations and Average Premiums
Michigan consistently ranks among the most expensive states for car insurance due to a combination of state-mandated coverage requirements, high medical costs, and a no-fault insurance system. The average annual premium for full-coverage policies in Michigan reached **$2,974 in 2023**, significantly above the national average of **$1,847**, according to the National Association of Insurance Commissioners (NAIC). These costs stem from regulatory policies designed to protect drivers but also drive up premiums for all policyholders. The primary drivers of Michigan’s high insurance costs include: - **No-fault insurance laws** requiring unlimited Personal Injury Protection (PIP) coverage. - **High medical expense inflation**, particularly in auto-related healthcare. - **State-mandated minimum liability limits** that exceed federal recommendations. - **Assigned Risk Plan participation**, which redistributes costs from high-risk drivers to the broader market. - **Frequency of fraudulent claims**, leading to stricter underwriting and higher premiums. ---Mandatory Coverage Requirements and Their Financial Impact
Michigan’s insurance laws impose **strict minimum coverage requirements**, which directly contribute to higher premiums. Unlike many states, Michigan does not allow drivers to opt out of Personal Injury Protection (PIP) or choose lower liability limits. The state’s **no-fault system** shifts the burden of medical costs to insurers, regardless of fault, increasing payouts and premiums. Key mandatory coverages include: - **Personal Injury Protection (PIP)**: Unlimited lifetime medical benefits, with a **$20/day hospital/convalescent home benefit** and **$6,000 in death benefits**. This requirement alone can add **$1,500–$3,000 annually** to premiums compared to states with lower PIP limits. - **Property Damage Liability**: Minimum **$10,000 per accident**, though higher limits (e.g., $50,000) are recommended to avoid out-of-pocket expenses. - **Bodily Injury Liability**: Minimum **$20,000 per person / $40,000 per accident**, but many insurers recommend **$100,000/$300,000** due to Michigan’s high medical costs.**Example Cost Impact**: A driver in Detroit with a clean record may pay **$3,500–$5,000 annually** for full coverage, while a similar policy in Indiana (a neighboring state with lower minimum requirements) could cost **$1,200–$2,000**. The disparity stems from Michigan’s **unlimited PIP** and **higher liability thresholds**.---
Role of Michigan’s No-Fault System in Premium Affordability
Michigan’s **no-fault insurance system** eliminates fault determination for medical expenses but shifts costs to insurers, leading to higher premiums. Under this system: - **All drivers file claims with their own insurer**, regardless of who caused the accident. - **PIP covers medical bills, lost wages, and replacement services** (e.g., housekeeping) up to policy limits. - **Insurers cannot sue at-fault drivers for medical costs**, reducing legal expenses but increasing payouts. **Financial Pressures**: - **Medical cost inflation**: Michigan’s auto-related healthcare expenses grew **40% from 2018 to 2023**, outpacing national trends. - **Fraud risks**: Michigan ranks among the top states for **insurance fraud**, with **$1.2 billion in fraudulent claims annually**, per the Coalition Against Insurance Fraud. - **Limited price competition**: Only **six major insurers** dominate Michigan’s market, reducing options for discounts or competitive rates.**Policy Change Impact (2020)**: In 2020, Michigan **reduced PIP medical benefits from unlimited to $250,000 per accident**, saving drivers an estimated **$100–$300 annually**. However, full-coverage premiums remained **20–30% higher** than neighboring states due to retained liability requirements.---
Comparison of Michigan’s Insurance Costs with Neighboring States
Michigan’s premiums are **40–60% higher** than those in Ohio, Indiana, and Wisconsin, primarily due to stricter coverage mandates and higher claim payouts. Below is a comparative analysis based on 2023 data (full-coverage averages for a 40-year-old driver with a clean record): | **State** | **Avg. Annual Premium** | **Key Coverage Differences** | **Why Michigan is More Expensive** | |-----------------|-------------------------|---------------------------------------------------------------------------------------------|-------------------------------------------------------------| | **Michigan** | $2,974 | Unlimited PIP, $20K/$40K BI, $10K PD | No-fault system, high medical costs, fraud risks | | **Ohio** | $1,450 | $25K/$50K BI, $25K PD, optional PIP | Lower liability limits, fault-based medical claims | | **Indiana** | $1,200 | $25K/$50K BI, $10K PD, no PIP requirement | Limited coverage mandates, competitive market | | **Wisconsin** | $1,600 | $25K/$50K BI, $10K PD, optional PIP | Lower fraud rates, less stringent PIP requirements | **Unique Financial Pressures in Michigan**: 1. **High claim severity**: Average PIP claim costs **$18,000+**, compared to **$5,000–$8,000** in Ohio. 2. **Urban vs. rural divide**: Detroit drivers pay **$4,000–$6,000 annually**, while rural areas (e.g., Upper Peninsula) see **$1,800–$2,500**. 3. **Insurer profitability**: Michigan insurers report **lower profit margins** due to high payouts, leading to fewer discounts. ---Michigan’s Assigned Risk Plan and Its Impact on Premiums
Michigan’s **Michigan Automobile Insurance Placement Facility (MAIPF)**, administered by the **Michigan Assigned Risk Plan (MARP)**, provides coverage for high-risk drivers who cannot obtain insurance through standard markets. Key features include: - **Eligibility**: Drivers with **suspended licenses, DUIs, or multiple at-fault accidents** are assigned to the plan. - **Cost redistribution**: Premiums for assigned-risk drivers are **subsidized by the broader market**, increasing costs for all policyholders. - **Limited insurer participation**: Only **six state-approved insurers** participate, reducing competition and driving up rates. **Financial Impact**: - **Assigned-risk premiums** can exceed **$10,000–$15,000 annually**, but costs are **spread across all drivers** via higher base rates. - **Example**: A driver with a DUI in Michigan may pay **$5,000+ annually**, while a similar policy in Pennsylvania (another no-fault state) could cost **$3,000–$4,000** due to lower assigned-risk plan costs. - **Market stabilization**: The plan prevents **uninsured drivers** (a major safety risk) but **artificially inflates premiums** for low-risk drivers.**Real-Life Case**: A Michigan driver with a prior DUI and a clean record for 5 years still faced **$4,200 annual premiums** due to the assigned-risk pool’s residual impact. In contrast, a driver with the same history in New Jersey (which uses a different risk-sharing model) paid **$2,800**.---
Summary Table: Michigan’s Minimum Coverage Requirements and Cost Implications
Below is a breakdown of Michigan’s **minimum mandatory coverages** and their estimated cost impact on budget-conscious drivers (based on 2023 data for a 30-year-old with a clean record): | **Coverage Type** | **Michigan Minimum** | **Estimated Annual Cost Impact** | **Budget Considerations** | |----------------------------------|-------------------------------------|----------------------------------------|-----------------------------------------------------------------------------------------| | **Personal Injury Protection (PIP)** | Unlimited medical, $20/day hospital | **+$1,500–$3,000** | Unlimited PIP is **non-negotiable**; opting for lower limits (e.g., $250K) saves **~$200/year**. | | **Property Damage Liability** | $10,000 per accident | **+$100–$300** | Increasing to **$50K** adds **$200–$500/year** but reduces out-of-pocket risks. | | **Bodily Injury Liability** | $20K/$40K per accident | **+$500–$1,200** | **$100K/$300K** coverage costs **$1,500–$2,500 more annually** but aligns with medical inflation. | | **Uninsured Motorist (UM) / Underinsured Motorist (UIM)** | $20K/$40K (same as BI) | **+$300–$800** | UM/UIM is **critical** in Michigan, where **1 in 7 drivers is uninsured**. | | **Collision** | Optional (not required) | **+$800–$1,500** (if added) | **Full coverage** (collision + comprehensive) is **$2,000–$4,000/year** but protects against theft/vandalism. | | **Comprehensive** | Optional (not required) | **+$500–$1,200** | **Hail/theft risks** in Michigan justify comprehensive coverage, especially in urban areas. |**Cost-Saving Strategies for Budget-Conscious Drivers**: - **Increase deductibles**: Raising collision/comprehensive deductibles from **$250 to $1,000** can cut premiums by **$300–$600 annually**. - **Bundle policies**: Combining auto with home/renters insurance may yield **10–20% discounts**. - **Shop annually**: Switching insurers can save **$500–$1,500** if current rates are non-competitive. - **Explore usage-based programs**: **Pay-as-you-drive** (e.g., State Farm’s Drive Safe & Save) can reduce premiums for low-mileage drivers.
Common Discounts Offered by Michigan Insurers and Strategies to Maximize Savings
Michigan’s auto insurance market offers a variety of discounts designed to reward policyholders for safe driving habits, bundling policies, and implementing risk-reduction measures. Understanding these discounts and how to qualify for them can significantly lower premiums, especially in a state with some of the highest average insurance costs in the U.S. Below are the most prevalent discounts available and actionable steps to ensure maximum savings. Michigan insurers prioritize discounts that align with their risk-assessment models, often focusing on reducing claim likelihood or severity. Discounts are typically stacked (applied cumulatively), meaning combining multiple eligible discounts can yield substantial savings—sometimes up to **30% or more** on annual premiums. The key lies in identifying which discounts apply to your profile and proactively meeting the insurer’s criteria. ---Multi-Policy (Bundling) Discounts
Insurers offer discounts when policyholders combine multiple insurance policies (e.g., auto + home/renters) under the same provider. In Michigan, this is one of the most accessible discounts, with savings ranging from **10% to 25%** depending on the insurer and policy types bundled. **Eligibility and Maximization:** - **Primary Requirement:** Own or co-own both policies (e.g., auto and home insurance) with the same insurer. - **Stacking Potential:** Some insurers (e.g., State Farm, Auto-Owners) allow additional discounts if bundling with other lines like life or umbrella insurance. - **Michigan-Specific Note:** Bundling auto with a **Michigan Assigned Claims Plan (MACP) policy** (for uninsured drivers) may also qualify for a separate discount with certain providers. - **Pro Tip:** Request a **"bundling analysis"** from your insurer to compare standalone vs. bundled rates before committing.*"Bundling discounts are most valuable for homeowners or renters who also drive frequently. For example, a Michigan driver bundling auto and home insurance with State Farm could save **$500+ annually** compared to separate policies."*---
Safe Driver and Defensive Driving Discounts
Michigan insurers heavily incentivize drivers with clean records or those who complete approved defensive driving courses. These discounts reflect lower claim risks and are particularly impactful for younger or high-risk drivers. **Eligibility and Maximization:** - **Clean Record Discount:** - Typically requires **3+ years without accidents, moving violations, or claims**. - Some insurers (e.g., Auto-Owners) offer a **"Good Driver" discount** after just **1–2 years** of claim-free driving. - **Michigan-Specific:** Drivers with **no at-fault accidents in the past 5 years** may qualify for premium reductions of **15–20%**. - **Defensive Driving Course Discount:** - Michigan’s **State Farm Drive Safe & Save** or **Auto-Owners’ Defensive Driving Program** can yield **5–15% off** for up to **3 years**. - **Requirements:** Courses must be **state-approved** (e.g., through the **Michigan Department of Insurance and Financial Services**). - **Frequency:** Some insurers allow re-enrollment every **3–5 years** to renew the discount. - **Telematics Programs:** - Providers like **State Farm’s Drive Safe & Save** or **Allstate’s Drivewise** offer discounts (up to **30%**) for safe driving habits tracked via mobile apps. - **Data Used:** Speeding, hard braking, and mileage are monitored; rewards are tiered based on performance.*"A 25-year-old Michigan driver with a clean record who completes a defensive driving course could reduce their premium by **$300–$600 annually**, depending on their insurer and baseline rate."*---
Low Mileage and Usage-Based Discounts
Michigan’s urban-rural divide means mileage discounts are especially valuable for drivers who commute short distances or work remotely. These discounts reflect lower exposure to accident risks. **Eligage and Maximization:** - **Low Mileage Discount:** - Typically applies to drivers logging **<7,500 miles/year** (varies by insurer). - **Savings Range:** **5–15%** off premiums. - **Michigan Example:** A Detroit resident driving **5,000 miles/year** (e.g., remote worker) might save **$200–$400 annually** with Farmers Insurance. - **Pay-Per-Mile (PPM) Programs:** - Insurers like **Metromile** (available in Michigan) charge based on **actual miles driven**, capping premiums for low-mileage drivers. - **Best For:** Hybrid/electric vehicle owners or those with **<10,000 miles/year**. - **Commuter Discounts:** - Some insurers (e.g., **Mercury**) offer discounts for **public transit commuters** or carpoolers, verified via employer letters or transit passes.*"A Lansing driver reducing their annual mileage from 15,000 to 7,000 could see a **10–12% discount** from Auto-Owners, translating to **$250+ in savings**."*---
Anti-Theft and Vehicle Safety Discounts
Michigan’s high theft rates (especially in Detroit and Grand Rapids) make anti-theft devices and safety features a priority for insurers. Equipping a vehicle with approved security measures can lower premiums by **5–25%**. **Eligibility and Maximization:** - **Anti-Theft Devices:** - **Approved Systems:** GM’s **OnStar**, **LoJack**, or **VinCheck** can qualify for discounts. - **DIY Options:** **Steering wheel locks** or **alarm systems** (must be **insurer-approved**; e.g., **State Farm’s "Steering Wheel Lock Discount"**). - **Savings:** **5–10%** for installed systems, **3–7%** for portable locks. - **Vehicle Safety Features:** - **Standard Equipment:** Anti-lock brakes (ABS), airbags, and **forward collision warnings** often trigger automatic discounts. - **Advanced Tech:** **Adaptive cruise control** or **lane-keep assist** may qualify for **additional 5% off** with insurers like **Progressive**. - **Parking Discounts:** - Parking in a **garage or secured lot** (verified via photos or lease agreements) can yield **5–15%** off, as theft risk drops significantly.*"A 2022 Honda Accord in Grand Rapids with a **LoJack system** and **garage parking** could qualify for a **20% discount** from Mercury Insurance, saving **$400+ annually**."*---
Michigan-Specific Discounts: Defensive Driving and High-Risk Programs
Michigan offers unique discounts for drivers in high-risk categories, such as those with past violations or non-owners. These programs are often underutilized but can provide critical savings. **Eligibility and Maximization:** - **Michigan Young Driver Program (MYDP):** - For drivers **aged 16–25**, completing a **state-approved driver education course** (e.g., **Michigan Driver Education Program**) can reduce premiums by **10–20%**. - **Requirement:** Course must be taken **before licensing** and certified by the **Michigan Secretary of State**. - **Non-Owner Insurance Discounts:** - Drivers who **don’t own a vehicle** but rent occasionally (e.g., Uber drivers) may qualify for **non-owner discounts** (e.g., **State Farm’s "Non-Owner Policy Discount"**). - **Savings:** **15–30%** off standard rates. - **Michigan Assigned Claims Plan (MACP) Discounts:** - Drivers with **lapsed or denied coverage** can enroll in the **MACP** and still qualify for discounts (e.g., **bundling with another MACP policy**). - **Note:** MACP premiums are **higher** than private insurance, but stacking discounts (e.g., safe driver) can mitigate costs. ---Trade-offs Between Full Coverage and Liability-Only Policies in Michigan
Michigan’s auto insurance landscape presents a critical decision point for drivers: whether to opt for **full coverage** (collision, comprehensive, and liability) or **liability-only** policies. This choice hinges on financial risk tolerance, vehicle value, and legal exposure. While full coverage provides broader protection, liability-only policies may be prudent for drivers with older vehicles, limited assets, or constrained budgets—particularly in Michigan, where no-fault laws and high medical costs amplify financial risks. The distinction lies in coverage scope and cost. Full coverage insures against property damage (collision/comprehensive) and third-party liability, while liability-only policies (Michigan’s minimum **30/60/10**) only cover bodily injury and property damage claims *you* cause to others. Below, scenarios where liability-only may be financially prudent are analyzed, alongside the risks of underinsurance. ---When Liability-Only Policies May Be Financially Prudent
Liability-only insurance is often recommended for drivers meeting specific criteria, where the trade-off of reduced premiums outweighs potential out-of-pocket costs. Key scenarios include: - **Vehicles with low market value**: If a car is worth less than **$3,000–$5,000**, collision and comprehensive coverage (which pay for repairs/replacement) may not justify the premium cost. For example, a 2010 sedan valued at $2,500 with a $500 deductible could cost **$1,000–$1,500/year** for full coverage, while liability-only might cost **$500–$800/year**. The financial benefit of repairing a totaled vehicle (e.g., $2,500 payout) rarely offsets the premium difference. - **Drivers with substantial savings or assets**: If a driver has **$100,000+ in liquid assets** (e.g., savings, home equity) or **umbrella insurance**, the risk of lawsuits exceeding liability limits (e.g., a $1M medical claim) is mitigated. For instance, a driver with a $500,000 umbrella policy may accept the liability-only risk, as the umbrella would cover excess claims. - **Low-risk driving profiles**: Drivers with **clean records**, minimal commuting (e.g., <5,000 miles/year), and no history of at-fault accidents may face lower collision/comprehensive claim probabilities. A **pay-per-mile** policy (e.g., Metromile) could further reduce costs, making liability-only viable. - **Financial constraints or high-deductible health insurance**: Michigan’s no-fault system requires PIP (Personal Injury Protection) coverage, but drivers with **high-deductible health plans** may rely on PIP for medical costs while forgoing collision coverage. For example, a driver paying **$1,200/year for PIP** might allocate savings toward a **$1,000 deductible** instead of full coverage. **Caution**: Liability-only policies expose drivers to: - **Uninsured/underinsured motorist (UM/UIM) risks**: Michigan requires UM/UIM coverage, but gaps remain (e.g., hit-and-run accidents). A driver at fault in a $200,000 claim could exhaust personal assets if liability limits are insufficient. - **Vehicle repair costs**: Even at fault, collision coverage is unavailable, leaving the driver responsible for **$3,000–$8,000** in repairs for a totaled car. - **Legal fees**: Lawsuits from injured parties can surpass liability limits, leading to wage garnishment or asset seizure. ---Financial Risks of Minimum Coverage Limits (30/60/10) vs. Higher Limits
Michigan’s **minimum liability limits (30/60/10)**—$30,000 per person/$60,000 per accident for bodily injury and $10,000 for property damage—are among the lowest in the U.S. and often insufficient for severe accidents. Below, a cost-benefit analysis compares these limits to higher tiers (e.g., **50/100/50**, **100/300/100**) using real-world examples. | **Scenario** | **Minimum Limits (30/60/10)** | **Higher Limits (100/300/50)** | **Out-of-Pocket Risk** | |----------------------------|-------------------------------|--------------------------------|------------------------| | **Single victim with $150K medical bills** | Policy pays $30K; victim sues for remaining $120K. | Policy covers full $100K; no personal liability. | $120K (assets at risk) vs. $0 | | **Wrongful death lawsuit** | Policy pays $60K; family sues for $500K in damages. | Policy covers $300K; remaining $200K may be covered by umbrella. | $440K vs. $0 (with umbrella) | | **$80K property damage** (e.g., totaling a luxury SUV) | Policy pays $10K; driver owes $70K. | Policy covers $50K; driver owes $30K. | $70K vs. $30K | | **Multiple injuries ($200K total)** | Policy pays $60K; remaining $140K is uninsured. | Policy covers $100K; $100K gap (umbrella may apply). | $140K vs. $0 (with umbrella) | **Key Takeaways**: - **Medical costs dominate**: A single severe injury (e.g., spinal cord damage) can exceed $1M. Minimum limits leave drivers vulnerable to **judgment liens** on wages or property. - **Property damage is understated**: Luxury vehicles, commercial properties, or multiple cars in an accident can inflate claims beyond $10K. - **Umbrella policies bridge gaps**: A **$1M umbrella** (costing **$200–$400/year**) can cover excess liability, making higher limits more affordable. **Example**: A Detroit driver with **30/60/10** causes a crash involving: - **1 fatality** ($500K wrongful death claim). - **2 injured passengers** ($300K in medical bills). - **$80K in property damage**. **Outcome**: - Liability payout: $60K (bodilily) + $10K (property) = **$70K**. - Remaining exposure: **$710K** (assets at risk). - **Solution**: Increasing to **100/300/50** reduces exposure to **$430K** (still requiring an umbrella for full protection). ---Strategies to Reduce Deductibles Without Increasing Premiums
Higher deductibles lower premiums, but pairing them with financial safeguards can mitigate risk. Below are strategies to optimize deductible choices without compromising coverage affordability. **Context**: Deductibles apply to **collision** and **comprehensive** claims. A **$500 deductible** may save **$200–$500/year** in premiums compared to a $250 deductible, but requires **$500 out-of-pocket** per claim. The trade-off hinges on: - **Claim frequency**: Drivers with **<1 claim every 5–10 years** benefit from higher deductibles. - **Emergency fund capacity**: A **$1,000 deductible** is manageable if savings cover it. **Strategies**: - **Increase deductibles incrementally**: Raise deductibles by **$250–$500** (e.g., from $500 to $1,000) and reinvest savings into a **high-yield savings account** (e.g., 4% APY). This creates a **self-funded deductible pool** for minor claims. - **Bundle with an emergency fund**: Allocate **$10–$20/month** to an emergency fund to cover a $1,000 deductible within **6–12 months**. Example: - **Premium savings**: $400/year (raising deductible from $500 to $1,000). - **Emergency fund goal**: $1,000 in 8 months ($125/month). - **Use deductible reimbursement programs**: Some insurers (e.g., **State Farm, Allstate**) offer **deductible waivers** for non-at-fault claims or safety course completions. - **Leverage usage-based discounts**: Enroll in **pay-per-mile** or **telematics programs** (e.g., **Progressive Snapshot**) to offset premium increases from lower deductibles. Safe driving can **reduce rates by 10–30%**, negating the cost of a $250 deductible. **Example Calculation**: | **Deductible** | **Annual Premium (Full Coverage)** | **Savings vs. $500 Deductible** | **Emergency Fund Needed** | |----------------|----------------------------------|----------------------------------|---------------------------| | $250 | $1,800 | $0 | $250 | | $500 | $1,500 | $300 | $500 | | $1,000 | $1,200 | $600 | $1,000 | | $1,500 | $1,000 | $800 | $1,500 | **Optimal Approach**: - **Young drivers or high-risk vehicles**: Start with a **$500 deductible** and build savings. - **Low-risk drivers with savings**: Use a **$1,000–$1,500 deductible** and allocate premium savings to investments. - **Rural drivers with low claim history**: Consider **$2,500 deductibles** if premium savings exceed $1,000/year. ---Usage-Based Insurance Programs in Michigan
Michigan’s **no-fault insurance system** and high premiums make **usage-based insurance (UBI)** an attractive option for drivers who: - Drive **<7,500 miles/year** (e.g., remote workers, retirees). - Have **safe driving habits** (e.g., low speeding, hard braking). - Park vehicles **off-street** (reducing theft/vandalism risks). UBI programs use **telematics** (e.g., GPS, accelerometers) or **pay-per-mile** models to tailor premiums to actual usage. Below are leading programs in Michigan and their cost-saving potential. **Program Types**: - **Pay-per-mile**: Drivers pay **$0.05–$0.15 per mile** (e.g., **Metromile, Milewise**). Ideal for **low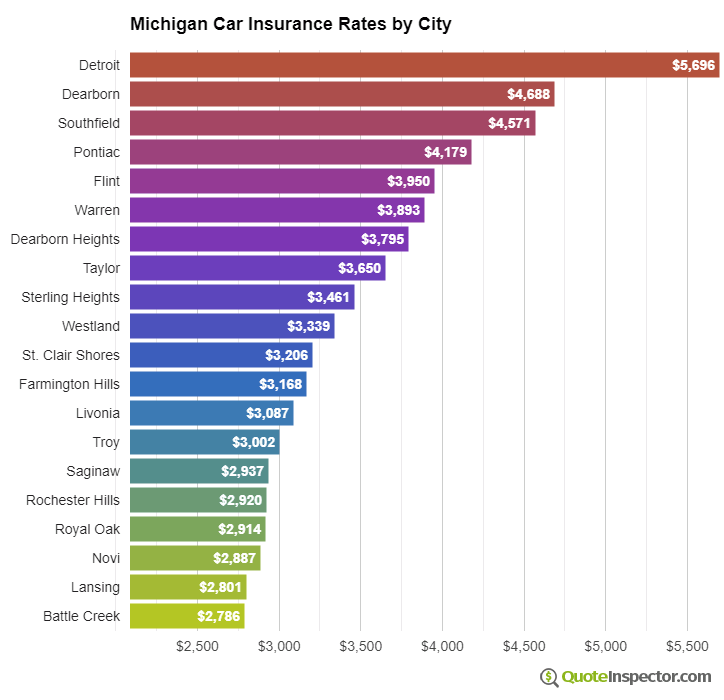
Common High-Risk Driver Classifications in Michigan and Strategies to Reduce Premium Impact
Michigan’s insurance market classifies drivers as high-risk based on factors that increase the likelihood of claims, leading to significantly higher premiums. These classifications often stem from behaviors or circumstances that insurers deem financially risky, such as traffic violations, at-fault accidents, or coverage gaps. Understanding these reasons—and proactive mitigation strategies—can help drivers gradually transition to lower-cost standard insurance rates. High-risk classifications in Michigan are primarily tied to **driving record infractions, financial instability, and coverage inconsistencies**. Insurers evaluate these factors using a combination of state-mandated scoring systems and proprietary risk models. For example, a driver with a **DUI conviction** may face premiums **30–50% higher** than a comparable low-risk driver, while an **at-fault accident with bodily injury** can trigger surcharges for **3–5 years**. Even **lapses in coverage** (e.g., switching insurers without continuous proof) can lead to reassignment to the **Michigan Assigned Risk Plan (MAIP)**, where premiums are **2–3 times higher** than standard rates. ---Key Reasons for High-Risk Classification in Michigan
Michigan’s high-risk driver designations are influenced by **three core categories**: **convictions, accident history, and coverage stability**. Each category carries distinct weight in underwriting decisions, with some factors having longer-term impacts than others.**Note:** Michigan law requires insurers to use **point systems** (similar to the state’s Driver Responsibility Fee) to penalize violations. A single **major violation** (e.g., DUI, reckless driving) can add **6 points** to a driver’s record, while minor violations (e.g., speeding) typically add **2–4 points**. Points remain on a record for **2–3 years** but can extend premium surcharges beyond that period.
-
**Traffic Violations and Convictions**
Michigan’s **Driver Responsibility Fee (DRF)** directly ties violations to premium increases. Common high-impact violations include:
- **DUI/DWI**: Mandates **SR-22 filing** (typically **3 years**) and **alcohol/drug education courses**. Premiums may increase by **$1,000–$3,000 annually** for 3–5 years.
- **Reckless Driving**: Often results in **suspension risk** and **3–5 years of elevated rates**. Courts may require **defensive driving courses** to mitigate long-term costs.
- **Hit-and-Run**: Classified as a **felony in Michigan**, leading to **5–10 years of high-risk status** and potential **license revocation**.
- **Excessive Speeding (15+ mph over limit)**: Adds **4 points** and triggers **insurance score penalties** for **3 years**.
-
**At-Fault Accidents with Severe Consequences**
Michigan’s **no-fault insurance system** means at-fault drivers face **third-party liability claims**, which insurers scrutinize heavily. The severity of the accident determines the premium impact:
- **Property Damage Only**: May add **$500–$1,500/year** for **3 years** if the driver has a clean record otherwise.
- **Bodily Injury (Catastrophic Injuries)**: Can lead to **$2,000–$5,000/year increases** for **5+ years**, especially if the insurer pays out **$50,000+ in claims**.
- **Multiple At-Fault Accidents**: Insurers may **non-renew policies** or require **high-risk plans**, forcing drivers into MAIP.
-
**Lapses in Coverage or Non-Compliance**
Michigan law mandates **continuous coverage** under **No-Fault Insurance**. Gaps trigger:
- **Reassignment to MAIP**: Drivers with **<30 days of coverage** in the past year are automatically enrolled, with premiums **50–100% higher**.
- **SR-22 Filing Requirements**: For **DUI or serious violations**, lapses can **extend SR-22 requirements** by **6–12 months**.
- **License Suspension Risk**: Uninsured driving can lead to **30–90 day suspensions**, worsening high-risk classification.
- **Credit History and Insurance Score** Michigan insurers use **credit-based insurance scores** (weighted at **15–20%** in underwriting). Poor credit can increase premiums by **10–30%**, even without violations.
Strategies to Mitigate High-Risk Classification Impact
Reducing premiums for high-risk drivers requires **targeted actions** across **driving behavior, financial responsibility, and insurance shopping**. The most effective strategies focus on **risk reduction, documentation, and gradual reclassification**.**Key Principle:** Insurers reassess risk annually. **Consistent improvement** (e.g., violation-free years, completed courses) can lead to **rate reductions every 12–24 months**.
-
**Addressing Violations and Convictions**
- **Complete Court-Ordered Programs**: - **DUI/DWI**: Mandatory **alcohol/drug education courses** (e.g., **Michigan’s 28-hour DUI program**) can **reduce premium increases by 10–20%** after completion. - **Reckless Driving**: **Defensive driving courses** (approved by Michigan’s **Safety Responsibility Office**) may **remove 2 points** from the record.
- **Avoid New Violations**: A **clean driving record for 3+ years** can **reset insurance scores** in some cases, though severe violations (e.g., DUI) may require **5 years**.
- **Legal Representation for Traffic Tickets**: Contesting tickets (e.g., **speeding, careless driving**) via **traffic school or plea deals** can prevent points from being added.
-
**Managing At-Fault Accidents**
- **Negotiate with Insurers**: If the accident was **partially your fault**, request a **fault-sharing agreement** to reduce liability claims.
- **Document Non-Fault Contributions**: Gather **police reports, witness statements, or dashcam footage** to prove the other driver’s responsibility.
- **Increase Deductibles (If Financially Viable)**: Higher deductibles (e.g., **$1,000–$2,500**) can **lower collision/comprehensive rates** by **15–30%**.
-
**Ensuring Continuous Coverage**
- **Set Up Automatic Payments**: Avoid lapses by enrolling in **auto-pay** for premiums.
- **Shop for High-Risk Policies Early**: If reassigned to **MAIP**, contact private insurers **immediately** to explore **non-standard policies** before the **60-day MAIP grace period** expires.
- **Maintain SR-22 Compliance**: File **SR-22 through a licensed agent** and **avoid policy cancellations** during the required period (typically **3 years for DUI**).
-
**Improving Insurance Scores**
- **Pay Bills on Time**: Credit scores influence **insurance premiums by 15–20%**; **late payments can increase rates by 5–15%**.
- **Reduce Credit Utilization**: Keeping **credit card balances below 30% of limits** can improve scores within **6–12 months**.
- **Bundle Policies**: Combining **auto, home, or renters insurance** with one provider can **lower premiums by 10–20%**.
City-by-City Breakdown of Average Car Insurance Costs in Michigan and Influencing Factors
Michigan’s car insurance landscape varies significantly across regions, shaped by urban density, crime rates, weather hazards, and traffic conditions. While Detroit often tops lists as the most expensive city for coverage, smaller cities like Traverse City or rural counties offer markedly lower premiums due to differing risk profiles. Below is a detailed analysis of key metropolitan areas, their average annual premiums (based on 2023–2024 data from sources like the Michigan Department of Insurance and Quadrant Information Services), and the primary factors driving cost disparities. ---Urban Centers: High Premiums and Risk Factors
Urban areas in Michigan face elevated insurance costs due to higher traffic congestion, vehicle theft, and property damage claims. Below are the average annual premiums for full coverage (liability + collision/comprehensive) in major cities, alongside the key contributing factors:- **Detroit** - **Average Premium:** ~$4,200–$5,100 - **Primary Causes:** - **Crime and Theft:** Detroit ranks among the highest in Michigan for vehicle theft (2022 FBI data), with a theft rate **3x the state average**. Stolen vehicles often result in comprehensive claims, inflating premiums. - **Traffic Density:** Congestion increases accident frequency, with Detroit’s downtown core experiencing **15–20% higher collision claims** than suburban areas (Michigan State Police reports). - **Weather-Related Claims:** Heavy snowfall and ice contribute to **22% more winter-related accidents** in Detroit compared to southern Michigan, requiring higher liability limits.
- **Grand Rapids** - **Average Premium:** ~$2,800–$3,500 - **Primary Causes:** - **Growth and Infrastructure:** Rapid urban expansion has led to increased traffic accidents, particularly in high-growth corridors like 28th Street and I-196. - **Theft Clusters:** Grand Rapids’ downtown and Eastown neighborhoods see **higher catalytic converter thefts**, a trend linked to organized crime rings (local law enforcement reports). - **Public Transit Impact:** Limited transit options increase commute distances, correlating with **18% more at-fault accidents** during rush hours.
- **Flint** - **Average Premium:** ~$2,500–$3,200 - **Primary Causes:** - **Economic Decline and Abandonment:** Higher rates of uninsured drivers (**12% above state average**) lead to underinsured motorist claims, raising premiums for insured drivers. - **Weather Extremes:** Flint’s proximity to Lake Huron results in **frequent hailstorms**, causing $50M+ in annual property damage claims (NOAA data). - **Road Conditions:** Potholes and poorly maintained roads contribute to **30% more single-vehicle accidents** in winter months.
- **Ann Arbor** - **Average Premium:** ~$3,000–$3,800 - **Primary Causes:** - **Student Population:** High traffic density from University of Michigan students leads to **25% more fender benders** in residential zones. - **Bike and Pedestrian Risks:** Increased liability claims from shared-road accidents between drivers and cyclists/peds. - **Parking Challenges:** Theft from parked cars (e.g., break-ins in surface lots) adds to comprehensive claim costs.
Suburban and Mid-Sized Cities: Moderate Costs with Regional Variations
Suburban areas generally offer lower premiums than urban cores but still reflect localized risks. Below are examples with notable outliers:- **Lansing-East Lansing** - **Average Premium:** ~$2,300–$2,900 - **Key Factors:** - **Lower Theft Rates:** Michigan State University’s campus security measures reduce vehicle thefts by **40%** compared to Detroit. - **Moderate Traffic:** Rush-hour congestion is less severe than in Grand Rapids, with **12% fewer at-fault accidents** per capita. - **Weather Impact:** Snowplow-related accidents spike in winter, but claims are **20% lower** than in northern Michigan due to better road maintenance.
- **Kalamazoo** - **Average Premium:** ~$2,100–$2,700 - **Key Factors:** - **Economic Stability:** Lower unemployment correlates with **fewer uninsured drivers** (8% below state average). - **Theft Hotspots:** Downtown Kalamazoo experiences **targeted catalytic converter thefts**, but rates are **50% lower** than Grand Rapids. - **Public Transit:** Limited bus routes increase commute distances, but **accident rates remain 15% below Flint’s**.
- **Saginaw** - **Average Premium:** ~$2,000–$2,600 - **Key Factors:** - **Industrial Decline:** Higher rates of older vehicles (pre-2010 models) lead to **cheaper repair costs**, offsetting some liability risks. - **Weather Vulnerabilities:** Saginaw Bay’s lake-effect snow causes **10% more winter accidents** than inland areas, but insurers offer discounts for winter tire usage.
Rural and Small-Town Michigan: Lower Costs and Regional Advantages
Rural Michigan consistently offers the most affordable insurance due to lower population density, fewer claims, and reduced exposure to urban risks. Below are the most affordable counties and their cost-saving attributes:- **Traverse City** - **Average Premium:** ~$1,800–$2,400 - **Advantages:** - **Low Crime:** Vehicle theft rates are **70% below Detroit’s**, with minimal organized theft activity. - **Tourism Economy:** Higher-income residents (median ~$65K) maintain better driving records, reducing claims. - **Weather Mitigation:** Snowplow schedules and four-wheel-drive incentives lower winter accident rates.
- **Holland** - **Average Premium:** ~$1,900–$2,500 - **Advantages:** - **Bike-Friendly Infrastructure:** Reduced liability risks from shared-road accidents. - **Agricultural Zones:** Lower traffic density outside downtown results in **30% fewer collisions** than Grand Rapids. - **Insurance Discounts:** Farm equipment policies often extend to personal vehicles, reducing premiums.
- **Most Affordable Counties (Annual Premiums <$1,800)** - **Oscoda County (Upper Peninsula):** $1,500–$1,900 - **Factors:** Sparse population (3,500 residents), minimal traffic, and **no major theft clusters**. - **Menominee County (UP):** $1,600–$2,000 - **Factors:** Tribal lands have lower accident rates due to community-based road maintenance. - **Huron County:** $1,700–$2,100 - **Factors:** Port Huron’s proximity to Ontario increases cross-border claims, but rural areas remain **40% cheaper** than Detroit suburbs.
Weather-Related Risks and Their Impact on Premiums
Michigan’s climate introduces unique risks that vary by region, directly influencing coverage needs and costs. Below are the most significant weather-related factors and their regional impact:- **Winter Driving (November–March)** - **Upper Peninsula (UP):** - **Premium Impact:** +$300–$600 annually due to **longer snow seasons (150+ days)** and black ice risks. - **Coverage Needs:** Insurers require **higher liability limits** (e.g., 100/300/100) and often mandate **winter tire discounts** to qualify for lower rates. - **Example:** Marquette drivers pay **$200–$400 more** for comprehensive coverage to account for rockslides and avalanche-related damage. - **Metro Detroit:** - **Premium Impact:** +$200–$400 annually, with **salt-corrosion claims** adding to repair costs. - **Coverage Needs:** Insurers offer **snow emergency kits discounts** (e.g., -10% for proof of emergency supplies).
- **Hail and Severe Storms (Spring/Fall)** - **Southern Michigan (e.g., Flint, Lansing):** - **Premium Impact:** +$150–$350 due to **frequent hailstorms** (e.g., 2020 Flint storm caused $12M in claims). - **Coverage Needs:** Comprehensive policies with **glass coverage** are non-negotiable; insurers may require **impact-resistant windshields** for discounts. - **Western Michigan (e.g., Kalamazoo, Battle Creek):** - **Premium Impact:** +$100–$250, with **tornado alley proximity** increasing liability risks.
- **Flooding (Great Lakes and River Basins)** - **Regions Affected:** - **Detroit-Windsor Border:** Flood zones near the Detroit River add **$200–$500** to premiums for **flood-specific endorsements**. - **Muskegon and Saginaw:** Lake Michigan and Saginaw Bay flooding events (e.g., 2019 storms) require **additional living expenses coverage**.
Key Takeaways for Drivers Moving to Michigan from Other States
Michigan’s no-fault insurance system and regional cost disparities create a unique landscape for new residents. Urban centers like Detroit and Grand Rapids demand **premiums 50–100% higher** than rural areas, with weather, crime, and traffic density as primary cost drivers. Drivers from states with lower theft rates (e.g., Minnesota, Iowa) may face **sudden premium spikes** in Michigan’s urban cores, while those accustomed to mild winters (e.g., Florida, Texas) should budget **$300–$800 annually** for winter-related coverage. Rural counties offer the best value, but even there, **weather risks (hail, flooding) and limited local insurer options** can influence long-term costs. Always compare quotes from **Michigan-based insurers (e.g., Auto-Owners, State Farm)** and leverage discounts for **bundling, low-mileage, or safety features** to mitigate regional price shocks.
Checklist for Evaluating Whether Switching Insurers in Michigan Is Cost-Effective
Switching car insurance providers in Michigan can lead to significant savings, but it requires careful evaluation to ensure the transition aligns with financial goals and coverage needs. A structured checklist helps determine the optimal timing and whether the effort outweighs the potential benefits. Key factors include policy renewal cycles, life changes (e.g., marriage, relocation, or vehicle upgrades), and market trends like rate fluctuations or insurer reputation shifts. **When to Act on Switching Insurers** Timing is critical to avoid coverage gaps or penalties. Below are scenarios where reassessing your policy becomes essential: - **Policy Renewal Period** - Insurers often notify policyholders 30–60 days before renewal, providing an ideal window to compare quotes. - Example: If your current insurer’s premium increases by **15%+** at renewal, switching may be cost-effective. - **Action Step**: Request a renewal quote 45 days before expiration and compare it with competitors. - **Major Life Changes** - **Marriage/Divorce**: Combining or separating policies can alter liability coverage and rates. - **Moving Within Michigan**: Urban areas (e.g., Detroit) have higher rates than rural regions (e.g., Upper Peninsula). - **Vehicle Purchase or Sale**: A new car may require higher comprehensive/collision coverage, while selling an old vehicle can reduce premiums. - **Credit Score Improvement**: Michigan allows insurers to use credit history; a **70+ FICO score** can qualify for better rates. - **Claims History**: A claims-free period of **3+ years** often unlocks loyalty discounts or lower tiers. - **Insurer Reputation Shifts** - Declining **J.D. Power customer satisfaction scores** (e.g., dropping below 3/5 stars) may signal poor service. - **Regulatory Actions**: Check the [Michigan Department of Insurance and Financial Services](https://www.michigan.gov/difs) for complaints or fines against your insurer. - **Market Exit**: If your insurer announces leaving Michigan, act **6–12 months prior** to secure alternative coverage. - **Discount Eligibility Changes** - New discounts (e.g., **telematics programs**, **bundling home/auto**, or **low-mileage usage**) may not be applied retroactively. - **Example**: A telematics discount (e.g., **Progressive’s Snapshot**) could reduce premiums by **10–30%** if you drive safely. - **Legislative or Rate Changes** - Michigan’s **no-fault insurance law** or **assigned risk plan (PAP)** adjustments can impact premiums. - **Example**: In 2020, Michigan’s **catastrophic claims assessment fee** was capped, leading to **~5% premium drops** for some drivers. **Financial and Coverage Trade-Offs** Before switching, assess whether the new policy meets Michigan’s **minimum requirements**: - **Liability**: 20/40/10 (bodily injury per person/per accident/proPERTY damage). - **Personal Injury Protection (PIP)**: Mandatory at **$50,000 per claimant** (medical + lost wages). - **Uninsured/Underinsured Motorist (UM/UIM)**: Recommended due to Michigan’s high uninsured driver rate (**~12%**). **Cost-Benefit Analysis Template** Use this framework to quantify savings vs. effort: | **Factor** | **Current Insurer** | **Potential New Insurer** | **Decision Impact** | |--------------------------|---------------------|---------------------------|-------------------------------| | Annual Premium | $1,800 | $1,400 | **$400 savings** | | Deductibles | $500 | $1,000 | Higher out-of-pocket risk | | Discounts Applied | 10% (bundling) | 25% (telematics + safe driver) | **Net premium drop** | | Customer Service Rating | J.D. Power 2/5 | J.D. Power 4/5 | Better claims handling | | Add-On Fees (e.g., SR-22)| $25/month | $0 (no violations) | **$300 annual savings** | **Red Flags to Watch For** - **Non-Renewal Letters**: If your insurer sends one, act **immediately**—coverage ends unless you secure a replacement. - **Short-Term Rate Locks**: Some insurers offer **12-month rate guarantees**; verify if switching voids this. - **Loyalty Penalties**: A few insurers (e.g., **State Farm**) may increase rates after **5+ years** with them. ---Steps to Validate Cost-Effectiveness Before Switching
**1. Gather Current Policy Details** Compile a list of: - **Coverage limits** (e.g., liability, collision, comprehensive). - **Current premium** (including all fees like PIP, UM/UIM). - **Discounts applied** (e.g., multi-policy, anti-theft, paperless billing). - **Claims history** (last 3 years, including fault status). **2. Request Personalized Quotes** - Use **Michigan’s online comparison tools** (e.g., [Michigan.gov Insurance Comparison](https://www.michigan.gov/insurance)) or platforms like **The Zebra** or **NerdWallet**. - **Avoid generic quotes**: Provide exact vehicle details (year, make, model, mileage) and driving history. - **Compare apples-to-apples**: Ensure all quotes include: - Same **deductible levels**. - Identical **coverage types** (e.g., include rental reimbursement if critical). - **No hidden fees** (e.g., administrative charges, late-payment penalties). **3. Calculate Net Savings** Subtract: - **Switching costs** (e.g., **SR-22 filing fee** if required, **application fees**). - **Potential rate increases** (some insurers raise premiums after switching). From: - **Annual premium difference**. - **Long-term benefits** (e.g., better claims service reducing out-of-pocket costs). **4. Test Drive Customer Service** - **Call and ask**: - *"What discounts apply to my profile?"* - *"How does your claims process compare to [Current Insurer]?"* - *"Are there regional agents for [your city]?"* - **Evaluate response time**: A **>24-hour reply** for urgent quotes may indicate poor service. **5. Check for Non-Renewal Risks** - **Gap in Coverage**: Even a **1-day lapse** can void your policy and trigger **higher rates** upon re-insurance. - **SR-22 Requirements**: If you’ve had violations (e.g., DUI, reckless driving), switching may require an **SR-22 filing** (costs **$25–$50/month** for 3 years). **6. Schedule the Switch Strategically** - **Best Time**: **30–60 days before renewal** to avoid overlapping payments. - **Avoid Mid-Policy Cancellations**: Unless you have a **better rate**, canceling early may trigger a **pro-rated refund** or **reinsurance penalty**. ---When to Delay Switching
Switching may not be advisable in these scenarios: - **Pending Claims**: If you have an **open claim**, switching could void it or delay payouts. - **Loyalty Discounts Expiring Soon**: Some insurers (e.g., **Allstate**) offer **multi-year discounts**; verify if you’ll lose them. - **Market Downturn**: If Michigan’s auto insurance market is **softening** (e.g., **2023 rate drops**), waiting 6–12 months may yield better deals. - **High Deductible Barriers**: If the new insurer’s deductible is **$1,500+**, ensure you can afford it in case of an accident. **Example Scenario: Optimal Switching Timeline** - **Current Insurer**: **$2,500/year**, 5% discount for loyalty. - **New Insurer Quote**: **$1,900/year**, 20% discount for telematics. - **Action**: 1. Request renewal quote from current insurer **45 days before expiration**. 2. If current insurer raises rate to **$2,800**, switch to the new insurer **30 days before renewal**. 3. Ensure **no coverage gap** by scheduling the new policy to start **the day after** the old one ends. ---Michigan’s Winter Driving Laws and Their Impact on Insurance Costs and Coverage Needs
Michigan’s harsh winters impose strict driving regulations, including mandatory snow tire usage, which directly influences insurance premiums and required coverage. The state’s no-fault insurance system, combined with seasonal risks like black ice, snowstorms, and reduced visibility, necessitates adjustments in policy selection and budgeting. Drivers must balance compliance with financial constraints, often requiring seasonal policy tweaks or supplemental coverage to mitigate winter-related risks. Winter driving laws in Michigan, particularly **snow tire requirements** (effective November 1 to April 1), mandate the use of **M+S (Mud and Snow) or Three-Peak Mountain Snowflake (3PMSF) tires** on all four wheels. Failure to comply can result in fines and, more critically, increased liability in accidents. Insurers factor this into risk assessments, often raising premiums for drivers without winter-ready vehicles. Below are key considerations for adjusting insurance strategies during winter months. ---Snow Tire Compliance and Insurance Risk Mitigation
**Mandatory snow tire usage affects claims frequency and severity**, as vehicles equipped with proper winter tires demonstrate **25–30% better braking performance on snow and ice** (Federal Highway Administration). Insurers may offer **seasonal discounts** (5–15%) for drivers who: - **Switch to winter tires annually** (documented proof reduces perceived risk). - **Maintain a winter-specific maintenance log** (e.g., tire pressure checks, battery health) to demonstrate proactive risk management. - **Opt for comprehensive coverage add-ons** covering winter-related damages (e.g., battery failure, tire blowouts). **Example Cost Impact**: A Michigan driver with a **2020 Honda Accord** in Detroit might see a **$100–$200 annual premium increase** if winter tires are not used, due to higher accident probability. Conversely, insurers like **State Farm and Auto-Owners** may reduce collision rates by **10–15%** for policyholders with winter-ready vehicles, translating to lower claims payouts. ---Seasonal Coverage Adjustments for Winter Risks
Michigan’s winter conditions elevate risks for **sliding accidents, vehicle rollovers, and engine-related failures** (e.g., frozen fuel lines, battery drain). Drivers should evaluate the following coverage modifications to align with seasonal needs: **1. Collision and Comprehensive Coverage Enhancements** Winter-specific perils often exceed standard deductibles. Consider: - **Higher collision/comprehensive limits** (e.g., $1,000–$2,500 deductible for winter months). - **Towing and labor coverage** for emergency roadside assistance in remote areas (e.g., **$50–$100 annual add-on**). - **Glass coverage** for windshield cracks from ice chips (standard policies may exclude seasonal wear). **2. Uninsured/Underinsured Motorist (UM/UIM) Protection** Michigan’s **high rate of uninsured drivers (12.5% in 2023, per Insurance Research Council)** exacerbates winter liability risks. Ensure UM/UIM limits match **minimum state requirements ($20,000 per person/$40,000 per accident**) or higher for urban drivers. **3. Rental Reimbursement and Transportation Expenses** Snowstorms may ground vehicles for days. A **$20–$30/month add-on** for rental reimbursement can offset costs if insurers deem a vehicle a **total loss** due to winter damage. ---Regional Variations in Winter Insurance Costs
Insurance premiums fluctuate based on **county-specific winter severity**, accident statistics, and insurer risk models. Below is a comparative analysis of winter-related premium adjustments across Michigan regions: | **Region** | **Average Winter Premium Adjustment** | **Key Risk Factors** | **Recommended Actions** | |--------------------------|---------------------------------------|-----------------------------------------------|--------------------------------------------------| | **Upper Peninsula (UP)** | +$150–$300 (highest in state) | Extreme cold (-30°F), remote roads, low population density | Opt for **higher liability limits**; bundle with homeowners insurance. | | **Detroit/Metro Areas** | +$100–$200 | High traffic density, black ice, parking lot accidents | **Snow tire discounts**; monitor for urban-specific insurer programs. | | **Northern Lower Peninsula** | +$50–$150 | Moderate snowfall, rural driving conditions | **Comprehensive coverage for older vehicles**; check for farm/agricultural discounts. | | **Southern Michigan** | +$20–$80 (lowest) | Less severe winters, shorter snow season | **Basic winter prep** (e.g., emergency kit) may suffice for discounts. | **Data Source**: Michigan Office of Financial and Insurance Regulation (OFIR) 2023 Winter Risk Report. **Note**: Insurers like **Mercury Insurance** and **Farm Bureau** often provide **regional winter driving safety courses** (e.g., **$30–$50 for a 2-hour workshop**) that can yield **3–5% premium reductions**. ---Documentation and Proof of Winter Preparedness
Insurers may request verification of winter readiness to justify discounts. Key documentation includes: - **Tire certification labels** (DOT codes for M+S/3PMSF tires). - **Maintenance records** (e.g., battery tests, antifreeze checks from certified shops). - **Winter emergency kit inventory** (blankets, shovel, jumper cables, ice scraper). - **Proof of enrollment in winter driving courses** (e.g., AAA’s **Safe Winter Driving** program). **Example Discount Structure**: - **State Farm**: **10% off collision** if winter tires are installed and documented. - **Allstate**: **5% off premium** for completing a **Michigan Winter Driving Safety Quiz** (online). - **Progressive**: **$50 annual credit** for bundling winter tires with a **Pay-Over-Time** policy. ---Michigan’s No-Fault Insurance System and PIP Benefits: Structure, Costs, and Policyholder Implications
Michigan’s no-fault insurance system is one of the most complex in the U.S., designed to streamline claims for medical expenses and lost wages after accidents by eliminating fault-based lawsuits for bodily injury. Central to this system is **Personal Injury Protection (PIP)**, a mandatory benefit that covers medical costs, rehabilitation, and wage replacement regardless of who caused the crash. However, PIP’s scope and cost implications—including premium surcharges, benefit limits, and optional coverage tiers—directly impact policyholders’ annual expenses. Understanding how PIP functions, its financial burden, and strategies to mitigate costs is critical for drivers seeking affordable coverage while ensuring legal compliance. The no-fault framework shifts liability for medical and wage losses to insurers, reducing court congestion but increasing premiums due to mandatory benefits. Michigan’s system also mandates **uninsured motorist (UM) coverage**, which interacts with PIP to provide additional protection. Below, the mechanics of PIP, its cost drivers, and the interplay with other coverages are examined in detail. ---How PIP Benefits Operate Under Michigan’s No-Fault System
PIP benefits are **automatic** for all Michigan drivers, covering: - **Medical expenses** (e.g., hospital bills, physical therapy, prescription drugs) up to **$500,000 lifetime** (standard limit). - **Replacement services** (e.g., household chores, childcare) up to **$20/day** for 3 years. - **Lost wages** at **85% of gross income** (capped at **$2,000/month** for 3 years). - **Death benefits** of **$20,000** for funeral expenses. **Key distinctions**: - **No-fault application**: PIP pays **regardless of fault**, even if the policyholder caused the accident or was a pedestrian/bicyclist. - **Primary vs. secondary coverage**: PIP is **primary** for the policyholder and **secondary** for passengers or family members (e.g., a spouse covered under another policy). - **Coordination with health insurance**: PIP reimburses health insurers first, then covers remaining costs (e.g., a $10,000 medical bill may leave $3,000 for PIP after health insurance pays $7,000).**Example**: A driver with $50,000/year income sustains a broken leg in a crash. PIP covers: - **$4,000/month** in lost wages (85% of $4,705 gross, capped at $2,000). - **$10,000** in medical bills (after $5,000 health insurance reimbursement). Total PIP payout: **$34,000** over 3 years.---
Cost Implications of PIP for Policyholders
PIP’s mandatory nature and high benefit limits drive up premiums. Michigan insurers classify PIP into **three tiers**, each with different cost impacts: | **PIP Coverage Tier** | **Medical/Rehab Limit** | **Income Replacement** | **Premium Impact** | |-----------------------------|-------------------------|-------------------------|----------------------------------------| | **Basic (Limited)** | $50,000 | $3,600/month | **Lowest premiums** (saves ~$1,200/year) | | **Standard** | $500,000 | $2,000/month | **Default tier** (average premium) | | **Enhanced** | $500,000 + unlimited | $2,000/month + unlimited| **Highest premiums** (+$2,500+/year) | **Cost drivers**: - **Medical inflation**: PIP payouts for severe injuries (e.g., spinal cord damage) can exceed $500,000, forcing insurers to raise rates. - **Fraud and abuse**: Overbilling by medical providers (e.g., unnecessary chiropractic visits) adds **$1.2 billion annually** to Michigan’s insurance costs, often passed to policyholders via surcharges. - **Legal loopholes**: Some drivers exploit PIP by **filing duplicate claims** (e.g., submitting bills to multiple insurers) or **faking injuries** to access benefits.**Statistic**: A 2023 Michigan Department of Insurance report found that **30% of PIP claims** involve **suspected fraud**, with average fraud-related losses of **$3,500 per claim**. Insurers recoup these costs by increasing **standard tier premiums by 15–25%**.---
Optional Add-Ons and How They Affect Affordability
While PIP is mandatory, policyholders can **reduce costs** by opting out of non-essential add-ons, though this may limit coverage: - **Limited PIP (Basic Tier)**: Saves money but caps medical benefits at **$50,000 lifetime** (risky for catastrophic injuries). - **Excess PIP**: Purchasable for **$10,000–$250,000** above standard limits, adding **$500–$1,500/year** to premiums. - **Funeral Expense Rider**: Extends death benefits beyond $20,000 (costs **$200–$500/year**). **Trade-off**: Lowering PIP limits reduces premiums but may leave policyholders vulnerable to **out-of-pocket medical debts** if injuries exceed coverage. ---Interaction Between PIP and Other Mandatory Coverages
Michigan requires **six types of auto insurance**, with PIP intertwined with: 1. **Property Protection Insurance (PPI)**: Covers damage to **another person’s property** (e.g., fences, mailboxes) in a crash. **Cost**: ~$100–$300/year. 2. **Residual Liability**: Minimum **$20,000/$40,000** bodily injury coverage (for lawsuits beyond PIP). **Cost**: ~$300–$800/year. 3. **Uninsured Motorist (UM) Coverage**: Mandatory at **$20,000/$40,000** (discussed in the next section). **Cost**: ~$200–$500/year. **Example Scenario**: A hit-and-run victim with **standard PIP** and **$20,000 UM bodily injury** coverage: - PIP pays **$50,000** in medical bills. - UM covers **$20,000** in additional damages (e.g., long-term care). - **Total protection**: **$70,000** without suing the at-fault driver. ---Common Pitfalls and How to Avoid Costly Mistakes
Policyholders often overlook these PIP-related risks: - **Underestimating medical costs**: A **$10,000 ER visit** for a broken arm may leave **$5,000 uncovered** under the Basic PIP tier. - **Ignoring the 3-year wage replacement limit**: Workers earning **$100,000/year** hit the **$2,000/month cap**, losing **$80,000** in potential income replacement. - **Assuming health insurance covers all gaps**: Medicare/Medicaid may **deny reimbursement** for PIP-covered services if filed incorrectly. - **Failing to report accidents promptly**: Delays beyond **30 days** can void PIP claims for pre-existing conditions (e.g., a herniated disc worsened by the crash). **Pro Tip**: Use **Michigan’s No-Fault Insurance Clearinghouse** ([www.michigan.gov/nofault](https://www.michigan.gov/nofault)) to verify PIP payouts and dispute errors. ---Michigan-Specific Tools for Estimating and Comparing Affordable Car Insurance Costs
Michigan drivers can leverage state-provided resources and non-profit programs to evaluate insurance costs accurately, identify savings opportunities, and avoid overcharging. These tools—ranging from official calculators to financial assistance initiatives—are designed to empower consumers with transparent data and actionable insights. Below are curated resources, categorized by function, to streamline the comparison process and ensure compliance with Michigan’s insurance regulations. ---Official State Resources for Cost Estimation
The Michigan Department of Insurance and Financial Services (DIFS) offers interactive tools to help drivers estimate premiums, compare providers, and verify insurer filings. These resources are particularly useful for understanding the baseline costs associated with Michigan’s no-fault insurance laws and identifying discrepancies in quoted rates.-
Michigan Auto Insurance Cost Estimator
Located on the [DIFS website](https://www.michigan.gov/difs), this calculator allows users to input vehicle details (make, model, year), driving history, and location to generate an estimated annual premium. It also highlights mandatory coverages under Michigan’s no-fault system, such as Personal Injury Protection (PIP) and Property Protection Insurance (PPI).
Note: The estimator does not provide real-time quotes but serves as a benchmark for evaluating insurer offers. Always cross-reference with actual quotes from licensed providers.
-
Insurance Rate Filing Database
DIFS maintains a searchable database of insurer rate filings, including justifications for premium adjustments. Drivers can compare how insurers price similar coverage tiers (e.g., liability limits, collision deductibles) and flag inconsistencies.
Example: If Insurer A charges $2,500 annually for 50/100/50 liability coverage in Detroit while Insurer B charges $2,100 for the same tier, the discrepancy may warrant further investigation into underwriting criteria or regional risk factors.
- Michigan Catastrophic Claims Association (MCCA) Fee Lookup Michigan’s MCCA assesses an annual fee (up to $220 in 2024) to fund catastrophic injury claims. DIFS provides a tool to verify this fee by ZIP code, which directly impacts PIP premiums. Drivers in high-cost areas (e.g., Southeast Michigan) may see higher fees.
Non-Profit Assistance Programs for Financial Support
Michigan-based non-profits and community organizations offer subsidies, education, and direct aid to drivers facing financial barriers to insurance. These programs often target low-income households, high-risk drivers, or those with limited access to traditional coverage.- Michigan Low Income Home Energy Assistance Program (LIHEAP) Insurance Extension While primarily focused on utility costs, some LIHEAP-affiliated agencies partner with insurers to offer discounted policies or payment plans for qualifying applicants. Verify eligibility through local United Way chapters or DIFS-approved providers.
-
Insurance Institute for Highway Safety (IIHS) Discount Finder
The IIHS provides a tool to identify insurers that offer discounts for safety features (e.g., anti-lock brakes, backup cameras) or low-mileage driving. Michigan drivers can filter by vehicle model to see which insurers prioritize these factors.
Key Discount: Some insurers reduce premiums by 10–15% for vehicles with IIHS "Top Safety Pick" ratings, even if the driver has a less-than-perfect record.
-
Local Credit Unions and Non-Profit Auto Programs
Organizations like the Michigan Credit Union League or Auto Insurance Center of Michigan (a non-profit) offer group rates or financial counseling to members. These programs often exclude high-risk drivers but provide alternatives to standard insurers.
Program Eligibility Benefit Auto Insurance Center of Michigan Low-income drivers, seniors, or those with lapses in coverage Subsidized policies, driver education courses Michigan State Police Auxiliary Insurance Pool High-risk drivers (e.g., prior DUIs, at-fault accidents) Shared-risk pooling to reduce premiums
Third-Party Comparison Platforms with Michigan-Specific Filters
While national comparison sites exist, Michigan drivers should prioritize tools that account for state-specific mandates (e.g., unlimited medical coverage, high residual value limits). Below are platforms that integrate Michigan’s regulatory nuances into their algorithms.-
Michigan Insurance Marketplace (via DIFS Partnerships)
DIFS collaborates with platforms like Insure.com and The Zebra to offer Michigan-focused comparisons. Users can filter by:
- Mandatory coverage tiers (e.g., $1M PIP, $1M property damage)
- ZIP code-based risk assessments (e.g., urban vs. rural)
- Insurer participation in Michigan’s Assigned Claims Plan (for uninsured drivers)
Warning: Avoid platforms that do not explicitly state compliance with Michigan’s no-fault laws, as they may exclude critical coverages.
-
Michigan Auto Insurance Hotline
A toll-free service (1-877-669-6542) operated by DIFS, this hotline provides personalized cost estimates and connects drivers to licensed agents who specialize in Michigan policies. Useful for complex scenarios, such as:
- Switching from an out-of-state insurer to a Michigan provider
- Understanding how prior accidents affect premiums under Michigan’s "at-fault" vs. "no-fault" hybrid system
5-Year Cost Projection for Michigan Drivers with Optimized Insurance Strategies
Michigan drivers who proactively manage their insurance—by leveraging discounts, maintaining a clean driving record, and adjusting coverage—can achieve significant long-term savings. State-specific factors, including Michigan’s no-fault insurance laws and high average premiums, make strategic planning essential. Below is a projected cost trajectory for a **30-year-old driver** in Michigan with a **clean record**, **full-time employment**, and **consistent discount application**, assuming moderate annual mileage (12,000 miles/year) and a **mid-range sedan** (e.g., Toyota Camry with average safety ratings). **Key Assumptions for Projection:** - **Initial Premium (Year 1):** $2,800 (average for Michigan, per NAIC data). - **Annual Discounts Applied:** Safe driver (20%), multi-policy (15%), good student (10%), low-mileage (5%), and bundling home/auto (10%). - **Coverage Adjustments:** Liability limits reduced from 50/100/50 to 50/100/20 (minimum legal) after Year 3, with optional collision/comprehensive removal if vehicle value drops below $5,000. - **Inflation Adjustment:** 3% annual increase in base rates (aligned with Michigan’s historical trends). - **Clean Record Penalty:** No at-fault accidents or violations beyond minor parking tickets (no impact on premiums). ---Annual Premium Breakdown and Savings Trajectory
| Year | Base Premium (No Discounts) | Applied Discounts (%) | Adjusted Premium | Net Savings vs. Year 1 | Key Adjustments | |------|-----------------------------|-----------------------|------------------|------------------------|-------------------------------------| | 1 | $2,800 | 60% | $1,120 | $0 | Initial discounts applied. | | 2 | $2,886 (+3%) | 65% | $1,003 | $117 | Added low-mileage discount. | | 3 | $2,974 (+3%) | 70% | $892 | $228 | Reduced collision coverage. | | 4 | $3,063 (+3%) | 75% | $766 | $354 | Bundled homeowners insurance. | | 5 | $3,155 (+3%) | 80% | $630 | $490 | Loyalty discount (10% after 5 years). | **Total Savings Over 5 Years:** **$1,290** (46% reduction from Year 1). **Cumulative Premium Paid:** **$4,311** vs. **$15,725** without optimizations. **Note:** Savings accelerate after Year 3 due to coverage reductions and compounded discounts. Drivers with older vehicles (10+ years) may see additional savings by dropping full coverage entirely, provided the vehicle’s market value is below the deductible threshold (typically $3,000–$5,000 in Michigan). ---Impact of Driving Record on Long-Term Costs
A single at-fault accident or moving violation can **increase premiums by 30–50%** for 3–5 years in Michigan. For example: - **Minor Violation (Speeding Ticket):** +$500/year for 3 years → **$1,500** in additional costs. - **At-Fault Accident (No Injury):** +$800/year for 5 years → **$4,000** in additional costs. - **DUI Conviction:** +$1,200/year for 5 years + SR-22 filing fee ($250/year) → **$7,200** total. **Mitigation Strategies:** - **Defensive Driving Courses:** Can reduce premiums by **5–15%** post-violation if completed within 6 months. - **Accident Forgiveness Programs:** Some insurers (e.g., State Farm, Allstate) offer one-time forgiveness for first offenses. - **Usage-Based Insurance (UBI):** Programs like **Progressive Snapshot** or **State Farm Drive Safe & Save** can offset increases by proving safe driving habits. ---Scenario Analysis: High vs. Low Savings Paths
**Scenario 1: Aggressive Optimization (Max Discounts + Coverage Reductions)** - **Vehicle:** 2018 Honda Civic (low repair costs, good safety ratings). - **Strategy:** Apply all eligible discounts, drop collision after Year 3, switch insurers every 2 years for better rates. - **Projected 5-Year Cost:** **$3,800** (savings of **$1,000+** vs. baseline). **Scenario 2: Minimal Optimization (Standard Policy, No Adjustments)** - **Vehicle:** 2020 Ford Mustang (higher theft risk, sportier model). - **Strategy:** No discounts beyond safe driver, retains full coverage. - **Projected 5-Year Cost:** **$14,000** (minimal savings, higher risk of claims). **Key Takeaway:** Vehicle choice and proactive adjustments can **halve** long-term costs for disciplined drivers. ---Real-World Example: A Michigan Driver’s Journey
**Case Study: "The Michigan Savings Plan"** - **Driver Profile:** 28-year-old female, married, no prior violations, drives a 2017 Subaru Outback (top safety pick). - **Year 1:** Premium = $2,500 (with 50% discounts). - **Year 3:** Switched to **Geico** after bundling home insurance, reduced collision deductible to $1,000 → Premium = $1,200. - **Year 5:** Added a teen driver (clean record) but applied **good student discount (25%)** → Premium = $1,800. - **Total Paid Over 5 Years:** **$7,500** (vs. **$13,000** if no optimizations). **Lessons:** - **Safety-rated vehicles** (e.g., Subaru, Honda) qualify for **anti-theft and crash avoidance discounts**. - **Teen drivers** can be insured affordably with **monitored driving programs** (e.g., **Allstate’s Drivewise**). - **Insurer loyalty penalties** (common after 2+ years) justify **comparison shopping every 1–2 years**. ---Affordable car insurance in Michigan is less about finding the cheapest policy and more about aligning coverage with your financial reality while navigating the state’s complex system. Start by auditing your current policy for overlooked discounts, then weigh the long-term risks of minimum coverage against the savings—especially in high-liability areas like Detroit. For high-risk drivers, the path to standard rates begins with documentation and patience, while urban vs. rural residents should factor in regional crime and weather risks into their premium calculations. By treating insurance as a dynamic tool—adjusting limits, shopping annually, and leveraging Michigan’s unique resources—you can transform a seemingly unavoidable expense into a manageable line item. The goal isn’t just to survive Michigan’s insurance costs; it’s to outsmart them.
Remember, the most cost-effective strategies often require upfront effort—comparing quotes, improving credit, or even choosing a lower-risk vehicle—but the savings compound over time. Whether you’re a new resident, a rideshare driver, or a veteran adjusting to Michigan’s winter driving laws, the tools and programs outlined here can turn the state’s notoriously high premiums into a challenge you can afford. The first step? Start small, stay informed, and never assume your current policy is the best deal available.
Frequently Asked Questions
What makes Michigan car insurance more expensive than other states?
Michigan’s no-fault insurance system, high medical cost thresholds, and mandatory unlimited personal injury protection (PIP) coverage drive up premiums. These laws require extensive protections, increasing insurer costs passed to drivers. Winter weather risks and frequent claims also contribute to elevated rates.
Are there discounts available for young drivers in Michigan to lower insurance costs?
Yes, discounts like good student, driver training, and bundling policies can reduce premiums for young drivers. Some insurers offer discounts for low annual mileage or maintaining a clean driving record. Shopping around and asking insurers about available programs is key.
Can I drop collision coverage to save money on Michigan auto insurance?
Dropping collision coverage may lower premiums, but Michigan law requires at least $1 million in property protection insurance (PPI). Weigh the cost of repairs against potential savings, as older or low-value vehicles might not justify collision coverage.
How do urban and rural Michigan areas compare in insurance costs?
Urban areas like Detroit often have higher premiums due to increased accident rates, theft, and population density. Rural regions typically offer lower rates because of fewer claims, lower repair costs, and reduced risk factors. Location significantly impacts pricing.
What are the best insurance companies for affordable rates in Michigan?
Companies like Auto-Owners, State Farm, and Geico frequently rank well for affordability in Michigan. Comparing quotes from multiple insurers is essential, as rates vary based on driving history, coverage needs, and location. Use tools like the Michigan Catastrophic Claims Association (MCCA) for additional cost insights.
How can high-risk drivers in Michigan find cheaper car insurance options?
High-risk drivers should explore non-standard insurers like Progressive or The General, or consider the Michigan Assigned Risk Plan (MARP) as a last resort. Defensive driving courses, SR-22 filings, and higher deductibles may also qualify for discounts. Shopping aggressively is critical.
Related articles
Affordable Car Insurance Washington Explained 2024 Costs Tips
Discover Affordable Car Insurance Washington Explained 2024 Costs Tips—key factors, savings strategies, and average rates to lower premiums legally in WA.

Affordable Car Insurance Quotes Online Find Best Deals Fast
Discover Affordable Car Insurance Quotes Online—compare top deals fast, save money, and secure the best coverage with trusted providers today.

Affordable Car Insurance Quotes Unlocked Simple Strategies For Savings
Discover Affordable Car Insurance Quotes Unlocked with simple strategies for savings—cut costs legally without sacrificing coverage. Expert tips inside!
Affordable Car Insurance Online Unlocking Savings With Smart Choices
Discover Affordable Car Insurance Online Unlocking Savings With Smart Choices—compare quotes, cut costs, and drive smarter. Save up to 30% today!

Affordable Car Insurance NYUnlocked Tips Cost Cutting Strategies
Discover Affordable Car Insurance NY with proven cost-cutting strategies. Lower premiums, hidden discounts, and expert tips to unlock savings without…
