Affordable Car Insurance Full Coverage Explained Simply
Table of Contents
- Core Components of Full Coverage Car Insurance and Their Differences from Liability-Only Policies
- Key Factors Influencing Full Coverage Insurance Premiums
- Negotiating Lower Full Coverage Insurance Rates: Timing and Tactics
- Securing Affordable Full Coverage Insurance for High-Risk Drivers with DUIs, Speeding Tickets, or Accidents
- Affordable Full Coverage Insurance Strategies for Young Drivers (Ages 16–25)
- Affordability Comparison: Full Coverage for Electric Vehicles vs. Gas-Powered Cars of Similar MSRP
- Step-by-Step Process for Filing a Full Coverage Claim
- Additional Coverage Options for Full Coverage Policies: Benefits, Costs, and Strategic Considerations
- Securing Full Coverage for Leased or Borrowed Vehicles: Temporary Policies and Non-Owner Insurance
- Full Coverage Insurance for International Drivers in the U.S.: Policies, Temporary Solutions, and SR-22 Compliance
- How Full Coverage Insurance Prevents Financial Ruin in Catastrophic Scenarios
- Telematics and Connected Car Data Impact on Full Coverage Affordability
- Legal Minimum Coverage Requirements by State and Full Coverage Exceeding Baselines
Navigating the complexities of full coverage car insurance doesn’t have to drain your wallet or overwhelm your understanding. With premiums varying widely based on factors like location, driving history, and vehicle type, many drivers assume full protection is out of reach—until they discover targeted strategies to balance cost and coverage. This guide breaks down the essential components of affordable full coverage, from the four core policy types to lesser-known discounts that could slash hundreds off annual bills. Whether you’re a young driver, a high-risk motorist, or a senior looking to optimize protection, understanding these nuances transforms insurance from a mandatory expense into a smart financial safeguard.
At its core, full coverage insurance combines collision, comprehensive, liability, and uninsured motorist protections to shield you from financial devastation in accidents, theft, or natural disasters. Unlike liability-only policies, which only cover damages you cause to others, full coverage ensures your vehicle and medical expenses are covered regardless of fault. Yet, the term "affordable" is subjective—what’s a reasonable premium for a 20-year-old in an urban area may differ drastically from a 60-year-old in a rural zone. This exploration dives into real-world cost comparisons, actionable savings tactics, and the hidden factors that inflate or deflate premiums, empowering drivers to make informed choices without sacrificing security.
Core Components of Full Coverage Car Insurance and Their Differences from Liability-Only Policies
Full coverage car insurance combines multiple protection layers beyond the legally required minimum, safeguarding drivers from financial losses due to accidents, theft, or damage. Unlike liability-only policies, which cover only damages and injuries caused to others, full coverage includes additional protections for the policyholder’s vehicle and medical expenses. This distinction is critical for drivers seeking comprehensive financial security, as liability insurance alone may leave significant out-of-pocket costs in the event of a collision or theft. The primary difference lies in scope and risk transfer. Liability insurance adheres to state-mandated minimums (e.g., 25/50/25 in most states, meaning $25,000 per person/$50,000 per accident for bodily injury and $25,000 for property damage). Full coverage, however, extends to **collision** (damage from accidents) and **comprehensive** (non-collision events like theft or weather), along with optional coverages like **uninsured/underinsured motorist protection** and **medical payments**. While liability policies are affordable and legally compliant, they fail to address the policyholder’s own vehicle repairs, medical bills, or legal liabilities exceeding policy limits.Key Coverage Types in Full Coverage Policies
Full coverage policies typically bundle four core components, each addressing distinct risks. Understanding their roles and cost implications helps drivers balance protection and affordability. Below are the primary coverages and their financial considerations:Collision Coverage
Collision coverage reimburses damages to the policyholder’s vehicle resulting from accidents, regardless of fault. This includes collisions with other vehicles, objects (e.g., guardrails), or rollovers. The cost is influenced by the vehicle’s **actual cash value (ACV)**, repair costs, and the driver’s claims history. For example, a 2023 Toyota Camry with a $20,000 ACV and a $500 deductible may incur higher premiums in high-theft areas, reflecting increased risk.Comprehensive Coverage
Comprehensive coverage protects against non-collision incidents such as theft, vandalism, fire, hail, or animal collisions. Premiums vary based on geographic risks (e.g., flood-prone Florida vs. low-theft Texas) and vehicle type (luxury cars often cost more to replace). A 2022 Honda Civic in Miami might see higher comprehensive rates due to hurricane risks, while the same model in Phoenix could have lower premiums despite theft risks.Liability Coverage
Liability coverage is legally required in most states and covers bodily injury and property damage to others in an accident where the policyholder is at fault. State minimums differ: - **Texas**: 30/60/25 - **California**: 15/30/5 - **Florida**: 10/20/10 Higher liability limits (e.g., 100/300/100) increase premiums but provide broader protection against lawsuits. For instance, a driver in California with $100,000 bodily injury limits may pay 20–30% more than someone with state minimums.Uninsured/Underinsured Motorist Coverage
This coverage compensates the policyholder for damages caused by drivers without insurance or insufficient coverage. It is optional in some states but required in others (e.g., New Jersey). Costs are modest compared to other coverages but critical in high-risk states like Florida, where 1 in 5 drivers is uninsured. A policy with $50,000 per accident limits might add $10–$30 annually to premiums.Deductibles, Premiums, and Policy Limits: Budget Impact Analysis
Deductibles, premiums, and policy limits directly influence affordability, particularly for drivers with varying financial constraints. Higher deductibles reduce premiums but increase out-of-pocket expenses during claims. Conversely, lower deductibles raise premiums but minimize immediate costs. Policy limits affect both premiums and long-term financial security. **Example Scenarios for a Mid-Range Sedan (Toyota Camry, 2022 Model):** - **Budget-Conscious Driver (Annual Income: $35,000)** - **Liability-Only Policy**: $800/year (Texas), $1,200/year (California), $1,500/year (Florida). - **Full Coverage with $1,000 Deductible**: $2,200/year (Texas), $3,000/year (California), $3,500/year (Florida). - **Trade-off**: Saving $1,400 annually by dropping collision/comprehensive but risking $10,000+ in repairs if totaled. - **Moderate-Income Driver (Annual Income: $60,000)** - **Full Coverage with $500 Deductible**: $1,800/year (Texas), $2,500/year (California), $2,800/year (Florida). - **Higher Limits (100/300/100 + UM)**: Adds $300–$600/year but covers catastrophic medical bills. - **High-Income Driver (Annual Income: $100,000+)** - **Full Coverage with $250 Deductible + Roadside Assistance**: $2,500–$3,500/year, with optional add-ons like rental reimbursement ($20–$50/month). **Cost-Saving Strategies:** - **Increase Deductibles**: Reduces premiums by 15–30% but requires emergency funds for claims. - **Bundle Policies**: Combining auto with home/renters insurance can yield 10–20% discounts. - **Usage-Based Insurance**: Programs like Progressive’s Snapshot or State Farm’s Drive Safe & Save offer discounts for low-mileage drivers (up to 30% savings).Full Coverage vs. Minimum Coverage Cost Comparison (2023 Data)
Below is a comparative table illustrating the average annual costs for a 35-year-old driver with a clean record, insuring a 2022 Toyota Camry across three states. Data reflects standard policy limits and average deductibles ($500 for full coverage, none for liability-only).| Coverage Type | Texas (Annual Cost) | California (Annual Cost) | Florida (Annual Cost) |
|---|---|---|---|
| Liability-Only (State Minimums) | $800 | $1,200 | $1,500 |
| Full Coverage (Collision + Comprehensive + Liability + UM) | $2,200 | $3,000 | $3,500 |
| Difference (Full - Liability) | $1,400 | $1,800 | $2,000 |
| Full Coverage with $1,000 Deductible | $1,800 | $2,500 | $2,900 |
| Full Coverage with Higher Limits (100/300/100 + UM) | $2,500 | $3,300 | $3,800 |
Average Annual Cost of Full Coverage Insurance by Driver Age Group (U.S. National Averages, 2023)
Age significantly impacts insurance costs due to risk profiles. Younger drivers face higher premiums due to inexperience and higher accident rates, while older drivers benefit from lower claims frequencies. Below are national averages for a mid-range sedan (e.g., Toyota Camry) with full coverage, including collision, comprehensive, and liability (100/300/50).| Age Group | Average Annual Premium | Key Cost Drivers |
|---|---|---|
| 18–25 | $4,500–$6,500 |
|
| 26–40 | $2,200–$3,500 |
|
| 41+ | $1,500–$2,800 |
|
Key Factors Influencing Full Coverage Insurance Premiums
Full coverage auto insurance premiums vary widely based on a combination of driver-specific, vehicle-specific, and external factors. While some elements like age or driving history are widely understood, others—such as credit scores or regional crime rates—play a more nuanced role. Below are the **top 5 factors** that most significantly impact premium costs, either by increasing or reducing them, depending on individual circumstances. Understanding these factors allows drivers to make informed decisions, such as choosing safer vehicles, improving credit scores, or selecting lower-risk locations. Insurers weigh these variables using proprietary algorithms, often resulting in premiums that can differ by **hundreds or even thousands of dollars annually** for the same coverage level. ---Driver Demographics and Personal History
Age, gender, and driving experience directly correlate with risk assessment. Younger drivers (under 25) and older adults (75+) typically face higher premiums due to statistically higher accident rates or slower reflexes. Gender-based pricing is legal in most states, with young male drivers often paying **30–50% more** than their female counterparts for the same policy. **Marital status** also influences costs, as married individuals are statistically less likely to file claims. **Driving history** is the most critical factor: a single at-fault accident can increase premiums by **20–50%**, while a clean record may qualify drivers for **safe-driver discounts (5–15%)**.**Example:** A 25-year-old male with a clean record in Texas may pay **$2,500/year** for full coverage, while a 40-year-old married female with the same vehicle and history could pay **$1,800/year**—a **$700 annual difference**.---
Credit-Based Insurance Scores
Insurance companies in most states use **credit-based insurance scores** (not full credit scores) to predict claim likelihood. Studies show a **strong correlation** between credit scores and claim frequency: drivers with **poor credit (300–579)** pay **up to 90% more** than those with **excellent credit (720+)**. Below is the tiered impact by credit range (based on average premium differences): | **Credit Tier** | **Score Range** | **Premium Impact** | **State Regulations** | |-----------------------|-----------------|-----------------------------------------------------------------------------------|----------------------------------------------------------------------------------------| | Poor | 300–579 | **+60–90% higher** than excellent credit | Banned in **California, Hawaii, Massachusetts, Michigan, and Washington** (use alternative scoring). | | Fair | 580–669 | **+30–50% higher** | Allowed in **40+ states**, including Texas, Florida, and New York. | | Good | 670–739 | **+5–15% higher** or **neutral** (varies by insurer) | Some insurers (e.g., State Farm) offer **credit-based discounts** for scores ≥700. | | Excellent | 740+ | **Baseline or 5–20% lower** (best rates) | States like **Ohio and Maryland** allow insurers to use credit but cap its influence. | **State-Specific Notes:** - **California** prohibits credit-based pricing entirely, relying instead on **driving records and location**. - **Texas** allows credit scoring but limits its weight to **20% of the risk assessment**. - **New York** permits credit use but requires insurers to disclose its impact on premiums.**Real-World Example:** In Florida, a driver with **poor credit (550 score)** might pay **$3,200/year** for full coverage on a Toyota Camry, while one with **excellent credit (780 score)** pays **$1,900/year**—a **$1,300 annual saving**.---
Vehicle Age, Make, and Model
The **year, brand, and model** of a vehicle directly affect repair costs, theft risk, and safety ratings—all of which insurers factor into premiums. Newer cars (under 5 years old) often cost **20–40% more** to insure due to higher replacement values, while older vehicles (10+ years) may qualify for **cheaper premiums** but risk **higher out-of-pocket costs** in accidents. **Key Model-Specific Factors:** - **Safety Ratings:** Vehicles with **top safety scores (IIHS Top Safety Pick+)** may qualify for **5–15% discounts**. - **Theft Risk:** Luxury cars (e.g., **BMW, Mercedes**) and high-end SUVs (e.g., **Jeep Wrangler**) are **3x more likely to be stolen** than sedans like the **Honda Accord**. - **Repair Costs:** **Tesla Model 3** repairs can exceed **$10,000**, while a **Toyota Corolla** averages **$3,500**—leading to **$500–$1,200 annual premium differences**. **Most Expensive Cars to Insure (Full Coverage, 30-Year-Old Driver):** 1. **Land Rover Range Rover** – **$3,500–$4,500/year** (high repair costs, theft risk). 2. **BMW M3** – **$2,800–$3,800/year** (sports car performance = higher accident rates). 3. **Tesla Model S** – **$2,500–$3,500/year** (high replacement value, expensive repairs). 4. **Mercedes-Benz AMG GT** – **$3,000–$4,000/year** (luxury + performance risks). 5. **Porsche 911** – **$2,700–$3,600/year** (similar to BMW M3 in risk profile). **Least Expensive Cars to Insure (Full Coverage, 30-Year-Old Driver):** 1. **Honda Fit** – **$1,200–$1,500/year** (affordable repairs, low theft risk). 2. **Toyota Corolla** – **$1,300–$1,600/year** (reliable, low accident claims). 3. **Mazda3** – **$1,400–$1,700/year** (similar to Corolla in safety/repair costs). 4. **Hyundai Elantra** – **$1,350–$1,650/year** (budget-friendly, decent safety ratings). 5. **Kia Soul** – **$1,400–$1,700/year** (low repair costs, good crash test scores).**Cost-Saving Tip:** Older vehicles (15+ years) with **low market value** may be insured for **collision/comprehensive coverage limits** (e.g., **$2,000–$3,000**) instead of full replacement cost, reducing premiums by **30–50%**.---
Negotiating Lower Full Coverage Insurance Rates: Timing and Tactics
Insurance premiums are not fixed; they are negotiable, especially when strategic timing and proactive communication align with market conditions. Drivers can leverage policy renewal cycles, claim-free histories, or even insurer competition to secure discounts or lower rates. Understanding these opportunities—such as bundling policies, adjusting coverage limits, or switching providers—requires planning and persistence. Below are actionable steps to maximize savings without compromising protection.Optimal Timing for Rate Negotiations
Insurers often adjust rates based on external factors (e.g., inflation, claims frequency) and internal policies (e.g., loyalty discounts). Drivers should capitalize on these moments to renegotiate: - **Policy Renewal (Every 6–12 Months):** Insurers may increase premiums annually, but they also evaluate driver behavior (e.g., safe driving scores, claims history). Request a review 30–60 days before renewal, comparing quotes from competitors. - **After a Claim-Free Year:** Insurers reward long-term customers with loyalty discounts (typically 5–15% after 3–5 years). Use this as leverage to ask for a better rate or additional perks (e.g., roadside assistance). - **Following a Traffic Violation or At-Fault Accident:** While rates may spike temporarily, some insurers offer "accident forgiveness" programs or gradual rate reductions after 3–5 years of clean driving. Ask about rehabilitation discounts. - **Market Shifts or Insurer Promotions:** Economic downturns or insurer profit margins may lead to temporary discounts. Use tools like [Bankrate’s Insurance Comparison](https://www.bankrate.com/insurance/) to identify providers offering promotions.Proactive Negotiation Strategies
Direct communication with insurers can yield unexpected savings. Drivers should: - **Bundle Policies:** Combining auto with home/renters insurance can reduce premiums by **10–20%** (e.g., State Farm averages $1,200/year for bundled policies vs. $1,500 separately). - **Request a Multi-Policy Discount:** Even if bundling isn’t possible, ask for a "loyalty discount" or "paperless billing" credit (often **5–10%**). - **Compare Competitor Quotes:** Obtain quotes from at least 3 insurers (use tools like [The Zebra](https://www.thezebra.com/)) and mention a competitor’s lower offer. Insurers may match or beat it to retain customers. - **Adjust Coverage Limits Temporarily:** Reduce comprehensive/collision coverage on older vehicles (e.g., 10-year-old cars with $3,000 value) and reinstate it later if needed. - **Negotiate After a Rate Increase:** If an insurer raises your premium, ask for a **"grandfathered rate"** (keeping your old rate) or a **partial credit** for future discounts.Handling Claims Without Losing Discounts
Filing a claim can raise premiums by **20–50%** for 3–5 years, but drivers can mitigate this impact: - **Pay for Minor Repairs Out-of-Pocket:** If the repair cost is less than the deductible (e.g., $500), avoid filing a claim to preserve a clean record. - **Use an Umbrella Policy:** If at fault, an umbrella policy (starting at $1M) can cover liability claims, sparing your auto insurance from rate hikes. - **Ask for Claim Forgiveness:** Some insurers (e.g., Progressive, Allstate) offer **1–3 claim forgiveness** programs, resetting your history after a set period. - **Shop Around Post-Claim:** After a claim, rates may spike, but switching insurers can sometimes reset your history (e.g., moving from Geico to State Farm may start a new clean record). ---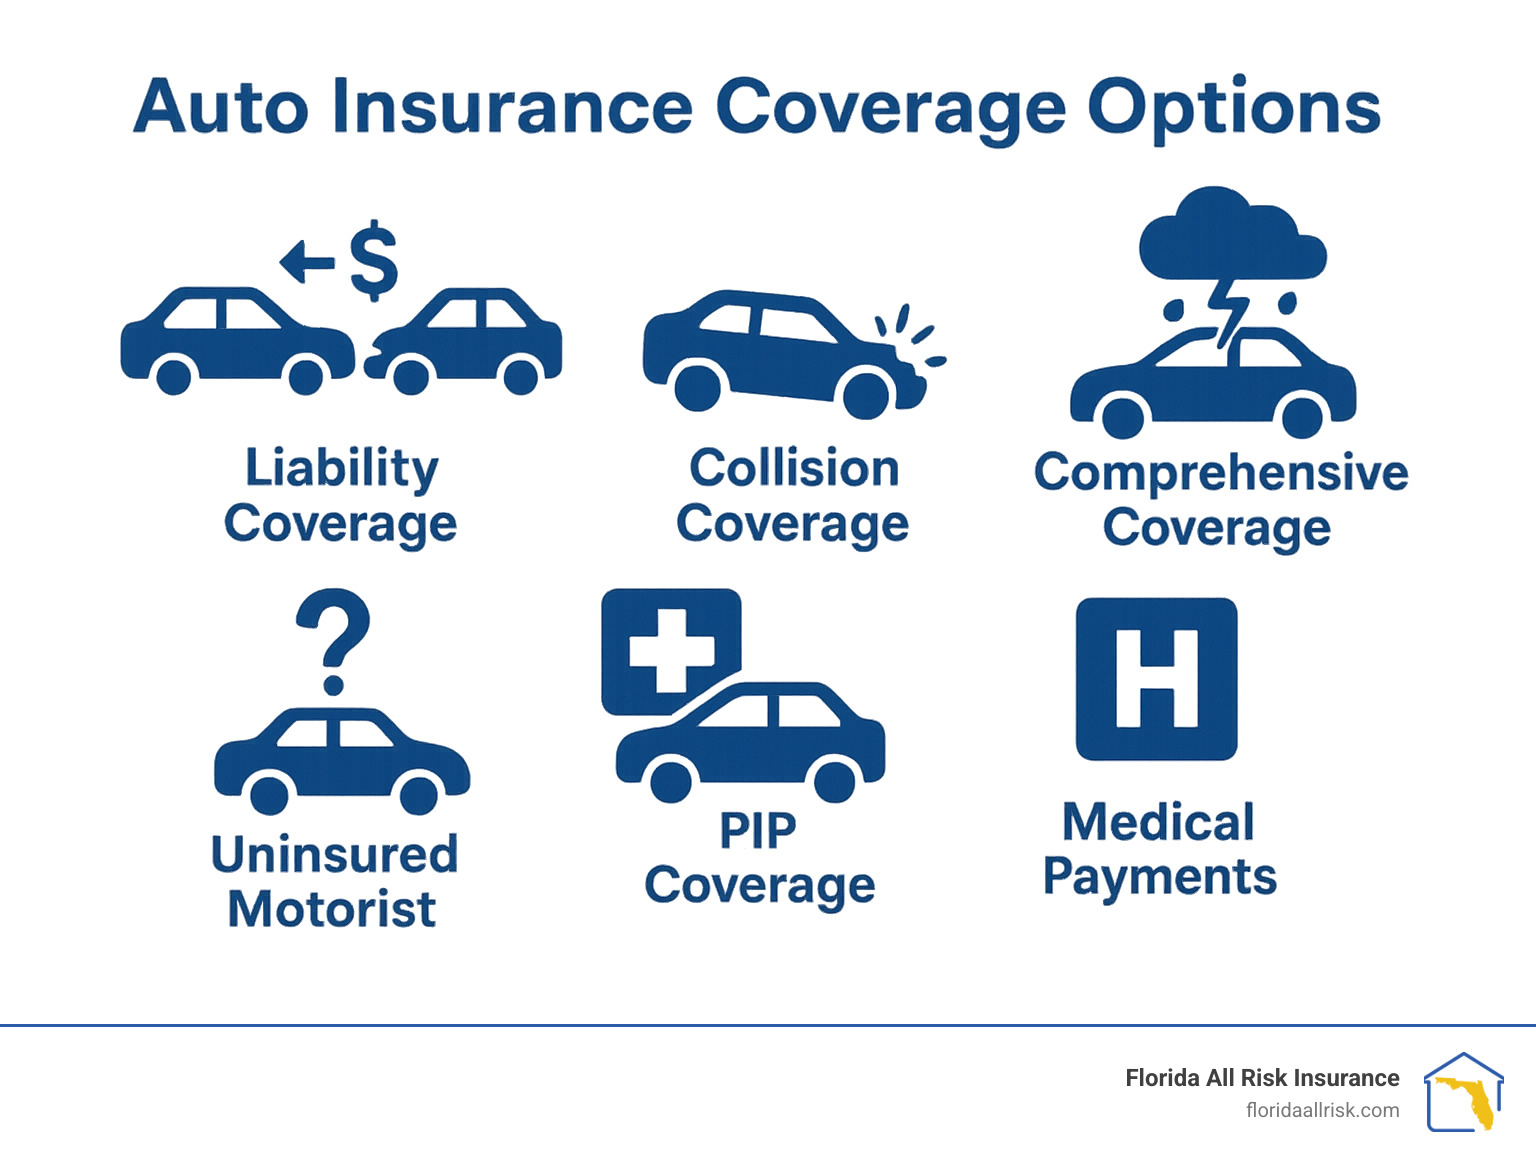
Securing Affordable Full Coverage Insurance for High-Risk Drivers with DUIs, Speeding Tickets, or Accidents
Drivers with DUIs, speeding tickets, or at-fault accidents often face significantly higher insurance premiums due to elevated risk profiles. However, affordable full coverage remains achievable through targeted strategies, state-specific programs, and insurers specializing in high-risk drivers. These approaches mitigate financial strain while ensuring compliance with legal coverage requirements. State laws and insurer policies vary widely, creating opportunities for cost savings. High-risk drivers can leverage **high-risk insurance pools**, **state-sponsored programs**, **non-standard insurers**, and **risk mitigation tools** to lower premiums. Below are structured methods tailored to different violations and state contexts. ---State-Specific Programs for High-Risk Drivers
Many states operate **assigned risk pools** or **shared market programs** to provide insurance for drivers rejected by standard carriers. These programs ensure coverage while often offering competitive rates compared to private high-risk insurers.**Assigned Risk Pools** are state-mandated programs where insurers contribute to a fund, ensuring coverage for drivers unable to secure insurance through traditional markets.**Key Programs by State:**
- **California Automobile Assigned Risk Plan (CAARP):** Drivers with severe violations (e.g., multiple DUIs) can qualify. Premiums are typically higher than standard rates but capped to prevent exploitation. Example: A driver with a DUI in CA may pay **$3,500–$5,000/year** for full coverage, compared to $1,200–$1,800 for a low-risk driver.
- **Texas Automobile Insurance Plan Association (TAIPA):** Covers drivers with poor records, including those with accidents or tickets. Texas law limits premiums to **150% of the average rate** for similar drivers in the standard market. A driver with a speeding ticket may see rates **20–50% lower** than private high-risk insurers.
- **Florida’s Residual Market (FAIR Plan):** Primarily for high-crime areas but includes drivers with violations. Full coverage through FAIR Plan can cost **$2,500–$4,500/year**, though coverage limits are lower (e.g., $25k/$50k bodily injury).
- **New York’s Joint Underwriting Association (JUA):** Serves as a last-resort option. Premiums are **non-negotiable** but often **10–30% cheaper** than private high-risk quotes. Example: A driver with a DUI in NY may pay **$4,200/year** vs. $6,000 from a private insurer.
- **Virginia’s Automobile Insurance Plan (VAIP):** Requires insurers to offer policies to high-risk drivers. Rates are **regulated** and may be **30–40% lower** than open-market high-risk quotes.
Insurance Discounts and Mitigation Strategies for High-Risk Drivers
Discounts and behavioral adjustments can offset the impact of violations. Below are actionable strategies categorized by violation type.**Discounts for High-Risk Drivers:** - **Defensive driving courses** (3–15% savings). - **Accident forgiveness programs** (e.g., State Farm’s "Steer Clear" for first-time offenders). - **Low-mileage discounts** (for drivers with limited annual usage). - **Bundling** (combining auto with home/renters insurance). - **Pay-in-full discounts** (5–10% reduction for annual payments).**Violation-Specific Strategies:**
- **DUIs:** - **SR-22 filing** (required in most states; some insurers offer **SR-22 discounts** after 3–5 years of clean driving). - **Ignition interlock devices** (IIDs) can reduce premiums by **10–20%** in states like CA, TX, and NY. - **Alcohol education programs** (e.g., MADD Victim Impact Panels) may qualify for **first-offense discounts**.
- **Speeding Tickets:** - **Point reduction programs** (e.g., NY’s Defensive Driving Course removes 4 points in 18 months). - **Traffic school completion** (can prevent rate hikes for minor violations in states like FL and GA). - **Safe driver discounts** (e.g., Progressive’s "Plus" program for ticket-free records).
- **At-Fault Accidents:** - **Accident forgiveness** (e.g., Allstate’s "Accident Forgiveness" for drivers with 5+ years of claims-free history). - **Claims-free bonuses** (e.g., Geico’s "Claims-Free Discount" after 5 years). - **Usage-based discounts** (e.g., State Farm’s "Drive Safe & Save" for low-risk driving behavior).
Non-Standard Insurers Specializing in High-Risk Drivers
Insurers like **The General**, **Dairyland**, and **Grange** cater to drivers with poor records. Below are their typical full coverage pricing structures and eligibility criteria.**Non-Standard Insurers vs. Standard Carriers:** | **Factor** | **Non-Standard Insurers** | **Standard Insurers** | |--------------------------|----------------------------------------------------|-----------------------------------------------| | **Eligibility** | Drivers with DUIs, accidents, or tickets | Clean driving records | | **Premium Range** | $2,500–$8,000/year (varies by state/violation) | $800–$2,500/year | | **Coverage Limits** | Often lower (e.g., 25/50/25 vs. 100/300/50) | Higher limits standard | | **SR-22 Filing** | Mandatory for DUIs in most states | Rarely required | | **Discounts** | Limited (focus on payment plans, IIDs) | Abundant (bundling, safe driving, etc.) |**Top Insurers for High-Risk Drivers:**
- **The General:** - **Best for:** Drivers with **1–2 DUIs or serious accidents**. - **Pricing:** Full coverage averages **$3,000–$6,000/year** (e.g., $4,200 in TX for a DUI). - **Key Programs:** - **DUI forgiveness after 3 years** (with no new violations). - **SR-22 filing assistance**. - **Payment plans** (monthly installments). - **States Served:** All 50 states.
- **Dairyland Insurance:** - **Best for:** Drivers with **multiple tickets or minor DUIs**. - **Pricing:** Full coverage ranges **$2,500–$5,000/year** (e.g., $3,500 in IL for a speeding ticket history). - **Key Programs:** - **Accident forgiveness for first offenses**. - **Defensive driving discounts (10%)**. - **Rural area discounts** (lower rates in non-urban zones). - **States Served:** 19 states (focus on Midwest/South).
- **Grange Insurance:** - **Best for:** **Young drivers or those with minor violations**. - **Pricing:** Full coverage **$2,000–$4,500/year** (e.g., $3,000 in OH for a teen with a ticket). - **Key Programs:** - **Good Student Discount (25%)** for drivers under 25. - **Safe driver monitoring** (usage-based discounts). - **Local agent support** for personalized quotes. - **States Served:** 12 Midwestern/Eastern states.
- **State Farm (High-Risk Policies):** - **Best for:** Drivers with **1–2 accidents or tickets**. - **Pricing:** Full coverage **$2,200–$5,500/year** (e.g., $3,800 in CA for an at-fault accident). - **Key Programs:** - **Steer Clear** (accident forgiveness after 5 years). - **Drive Safe & Save** (usage-based discounts up to 30%). - **SR-22 filing** (available in all states).
Affordable Full Coverage Insurance Strategies for Young Drivers (Ages 16–25)
Young drivers face the highest insurance premiums due to limited experience and higher accident risks. However, several strategies—such as leveraging parental policies, earning discounts, and participating in monitored driving programs—can significantly reduce costs while maintaining full coverage protection. Full coverage for young drivers typically includes **collision, comprehensive, and liability coverage**, with average annual premiums ranging from **$3,000 to $8,000+** depending on location, vehicle, and driving history. Below are structured approaches to mitigate expenses without compromising safety or legal compliance. ---Leveraging Parental Policies: Adding Young Drivers to Existing Plans
Parents with established auto insurance policies can add their teen or young adult children as secondary drivers, often at a fraction of the standalone premium cost. This method avoids the need for a separate policy while providing essential coverage. Key considerations: - **Cost Impact**: Adding a young driver may increase the parent’s premium by **30–100%**, but this remains cheaper than an independent policy. - **Policy Limits**: Ensure the parent’s coverage limits (e.g., liability, collision) are sufficient for the added driver’s vehicle, if applicable. - **Usage Restrictions**: Some insurers offer **usage-based discounts** if the young driver uses the vehicle less frequently (e.g., for commuting vs. daily driving). - **Example**: A 17-year-old added to a parent’s policy in Texas might see a **$1,200 annual increase** (from $1,500 to $2,700) compared to a standalone policy costing **$5,000+**. ---Good Student Discounts: Academic Performance as a Cost-Saver
Insurance providers often reward academic achievement with discounts of **5–25%** on full coverage premiums. This discount reflects the statistical correlation between higher grades and lower risk-taking behavior behind the wheel. Eligibility requirements typically include: - **Maintaining a B average (3.0 GPA) or higher** in high school or college. - **Submitting official transcripts** to the insurer annually. - **Coverage Scope**: Applies to both primary and secondary drivers under the policy. - **Example**: A young driver in California with a 3.5 GPA could save **$400–$800 annually** on a $3,500 premium, reducing it to **$2,700–$2,900**. ---Monitored Driving Programs: Telematics and Usage-Based Insurance
Telematics programs, such as **Progressive’s Snapshot, State Farm’s Drive Safe & Save, or Allstate’s Drivewise**, track driving behavior (speed, braking, mileage) to offer **real-time discounts**. Young drivers can benefit from these programs by demonstrating safe habits, with potential savings of **10–30%** on premiums. Key features of monitored driving programs: - **Data Collection**: GPS and onboard diagnostics record acceleration, hard braking, and distance driven. - **Behavioral Feedback**: Drivers receive alerts to improve habits, such as avoiding late-night driving or speeding. - **Pay-As-You-Drive (PAYD)**: Some programs adjust premiums based on **annual mileage**, ideal for young drivers with limited commuting needs. - **Example**: A 20-year-old in Florida using Snapshot might reduce their premium from **$4,500 to $3,200** after 6 months of safe driving, saving **$1,300**. ---Affordability Comparison: Full Coverage for Electric Vehicles vs. Gas-Powered Cars of Similar MSRP
Electric vehicles (EVs) like the **Tesla Model 3** often share similar manufacturer’s suggested retail prices (MSRP) with gas-powered sedans (e.g., Toyota Camry, Honda Accord). However, their insurance costs differ significantly due to variations in repair costs, technology risks, and claim frequency. Below is a detailed comparison of full coverage affordability between EVs and comparable gas-powered vehicles, focusing on premiums, deductibles, and long-term cost factors. ---Key Cost Drivers Differentiating EV and Gas-Powered Insurance Premiums
Several factors influence why EVs typically cost more to insure than gas-powered cars of similar value, despite lower fuel and maintenance expenses for owners.**Primary cost factors for EVs:** - **Higher repair costs:** Lithium-ion battery replacements or repairs can exceed **$10,000–$20,000**, while gas-powered car repairs rarely surpass **$5,000–$8,000** for comparable damage. - **Technology risks:** Advanced driver-assistance systems (ADAS) and software vulnerabilities increase claim complexity and frequency. - **Limited repair networks:** Specialized EV repair shops charge premium rates, unlike gas-powered cars with widespread service centers. - **Theft and vandalism:** High-value EVs (e.g., Tesla Model 3) are **2–3x more likely to be stolen** than gas-powered sedans, driving up comprehensive coverage costs.**Example Premium Comparison (Annual Full Coverage for a 35-Year-Old Driver, Good Credit, Low Mileage):** | Vehicle | MSRP (2024) | Avg. Annual Premium | Key Cost Factors | |------------------|------------|---------------------|-------------------------------------------| | Tesla Model 3 | $47,000 | **$2,500–$3,200** | Battery repairs, theft risk, ADAS claims | | Toyota Camry | $27,500 | **$1,200–$1,800** | Lower repair costs, fewer tech-related claims | | Honda Accord | $27,000 | **$1,100–$1,700** | Standard mechanical repairs, lower theft rates | ---
Repair Cost Disparities and Claim Trends
Insurance claims for EVs often involve **unique damage scenarios** that gas-powered cars avoid. Below are the most common claim types and their cost implications:- **Battery-Related Claims:** EVs account for **~15% of all collision claims** but contribute **~40% of repair costs** due to battery replacements. For example: - **Tesla Model 3 battery replacement:** $13,000–$18,000 (after deductible). - **Gas-powered sedan battery replacement:** $500–$1,200.
- **Software and ADAS Failures:** EVs with **Autopilot/Tesla Vision** or **Honda Sensing** may file claims for: - **Sensor recalibration:** $300–$800 per incident (common after minor collisions). - **Full ADAS system failure:** $1,500–$3,000 (rare but costly). Gas-powered cars rarely incur such costs unless equipped with advanced safety tech.
- **Theft and Vandalism:** EVs are **targeted for battery theft** (copper wiring in batteries sells for **$500–$1,500** on the black market). Comprehensive coverage for EVs includes: - **Theft recovery rewards:** Insurers may offer **$500–$2,000** for information leading to recovery. - **Vandalism spikes:** Parked EVs in urban areas see **30–50% higher vandalism claims** than gas cars.
Long-Term Affordability: Depreciation and Resale Value Impact
While EVs may have higher upfront insurance costs, their **depreciation rates** and **resale values** influence long-term affordability. Gas-powered cars often retain value better due to: - **Lower repair costs** reducing claim payouts. - **Wider aftermarket parts availability**, keeping maintenance affordable. **Depreciation Comparison (5-Year Ownership):** | Vehicle | MSRP (2024) | Estimated Value After 5 Years | Avg. Annual Depreciation | |------------------|------------|--------------------------------|---------------------------| | Tesla Model 3 | $47,000 | **$18,000–$22,000** | **12–15% annually** | | Toyota Camry | $27,500 | **$12,000–$15,000** | **8–10% annually** | **Insurance Impact:** - **Higher depreciation** on EVs means **lower actual cash value (ACV)** payouts in total-loss claims, increasing out-of-pocket costs for owners. - **Agreed-value policies** (common for luxury EVs) can mitigate this by guaranteeing payouts based on pre-depreciated values, but they **increase premiums by 20–40%**. ---Step-by-Step Process for Filing a Full Coverage Claim
Filing a full coverage insurance claim involves a structured sequence of actions to ensure timely compensation while adhering to policy terms. Understanding the documentation requirements, reporting timelines, and procedural steps minimizes delays and maximizes claim success. Below is a detailed breakdown of the process, including critical deadlines and supporting evidence needed for collision, comprehensive, and liability claims.Immediate Actions After an Incident
The first 24–48 hours following an incident determine the efficiency of the claim process. Prioritize safety, secure the scene, and gather essential details before contacting the insurer.- **Ensure Safety and Legality**: Move vehicles to a safe location if possible, activate hazard lights, and avoid discussing fault at the scene. In accidents, check for injuries and call emergency services if needed.
- **Document the Scene**: Use a smartphone or camera to capture:
- Vehicle damage angles (front, sides, rear) and surrounding context (road conditions, traffic signs, weather).
- License plates, vehicle makes/models, and driver information of all parties involved.
- Police report reference number (if law enforcement is called).
- Witness statements, including names and contact details.
- **Notify Authorities**: File a police report for accidents involving injuries, fatalities, or disputes over fault. Some states (e.g., California, Florida) require police reports for claims over a specific threshold (e.g., $1,000+ in damages).
- **Contact Your Insurer**: Report the claim promptly—most insurers require notification within **24–72 hours** for collision/comprehensive claims. Provide:
- Policy number, date/time of incident, and location.
- Brief description of the event (e.g., "single-vehicle hail damage in Denver, CO").
- Confirmation of prior police report (if applicable).
Documentation Requirements for Claim Validation
Insurers verify claims through a combination of evidence, which varies by claim type. Missing or incomplete documentation can lead to delays or claim denials. Below are the key requirements for common scenarios.- **Collision Claims (At-Fault or Not-at-Fault)**:
- **Police Report**: Mandatory for disputes or injuries. Include the report number in your claim submission.
- **Repair Estimates**: Obtain quotes from **at least two licensed auto repair shops** within 14 days of the incident. Insurers may require pre-authorization for repairs exceeding a threshold (e.g., $3,000).
- **Driver’s License and Proof of Insurance**: Submit copies of the at-fault driver’s license and insurance card (if applicable).
- **Witness Affidavits**: Statements from witnesses with contact information to corroborate fault.
- **Comprehensive Claims (Theft, Vandalism, Hail, Fire)**:
- **Police Report**: Required for theft or vandalism. Include the case number.
- **Photographic Evidence**: Close-up images of damage (e.g., hail dents, broken windows) with a ruler for scale.
- **Incident Details**: For theft, provide the last known location, time, and any security footage references. For hail, note the date/time and severity (e.g., "severe hailstorm in Dallas, TX, on May 10, 2024").
- **Receipts for Temporary Repairs**: If you cover immediate costs (e.g., a tarp for a damaged roof), save receipts for reimbursement.
- **Liability Claims (If You’re at Fault)**:
- **Other Party’s Insurance Information**: Name, policy number, and insurer details of the injured party or damaged property owner.
- **Medical Reports**: For bodily injury claims, submit medical records and bills linked to the accident.
- **Property Damage Inventory**: For damage to another’s vehicle or property, include photos and repair estimates.
Claim Processing Timeline and Insurer Responsibilities
Insurers adhere to state-mandated timelines for claim investigations and payouts. Understanding these deadlines helps manage expectations and identify delays.- **Initial Acknowledgement**: Insurers must acknowledge receipt of your claim within **15–30 days** of reporting. Some states (e.g., New York) require written confirmation.
- **Inspection Period**: An adjuster will inspect the vehicle within **5–14 business days** after claim submission. For comprehensive claims (e.g., hail), this may involve a scheduled appointment.
- **Decision Timeline**:
- **Standard Claims**: Insurers typically decide on approval/denial within **30–60 days** of inspection.
- **Complex Claims** (e.g., total loss disputes, fraud investigations): May extend to **90 days**, with periodic updates required.
- **Payout Timing**: Once approved, funds are disbursed within **5–10 business days** via check, direct deposit, or prepaid debit card. Some insurers (e.g., State Farm, Allstate) offer accelerated claims processing for minor repairs (e.g., 24–48 hours).
- **Denial Appeals**: If denied, request a written explanation and submit additional evidence within **30 days**. State laws vary—e.g., California allows 15 days to appeal.
Common Pitfalls and How to Avoid Them
Mistakes during the claims process can prolong resolution or reduce compensation. Proactively address these risks to streamline your claim.- **Delaying Reporting**: Failing to notify the insurer within the required window (e.g., 72 hours for collision) may void coverage. Example: A policyholder in Texas waited 10 days to report a stolen car, leading to a denied claim.
- **Underestimating Damage**: Skipping a professional inspection can result in lower payouts. For instance, a driver in Colorado received $2,500 for hail damage without an adjuster’s visit, but an independent estimate later revealed $5,000 in repairs.
- **Ignoring Policy Limits**: Full coverage policies often cap payouts for accessories or custom parts. Verify if your policy covers aftermarket modifications (e.g., stereo systems, spoilers) separately.
- **Mismatched Repair Shops**: Using a shop not approved by your insurer may delay reimbursement. Some insurers (e.g., Progressive) have preferred networks that expedite claims.
- **Assuming Full Coverage Covers Everything**: Exclusions apply—e.g., intentional damage, racing modifications, or vehicles used for commercial purposes without endorsements.
Additional Coverage Options for Full Coverage Policies: Benefits, Costs, and Strategic Considerations
Full coverage insurance provides comprehensive protection for drivers, but adding supplementary coverages can enhance financial security and convenience. Options like roadside assistance, rental reimbursement, and gap insurance introduce incremental costs but offer targeted benefits that vary significantly based on driving habits, vehicle age, and risk exposure. Evaluating these add-ons requires balancing their premium impact against real-world utility, particularly for high-mileage drivers, urban commuters, or those financing newer vehicles. The decision to include these add-ons depends on individual needs, budget constraints, and the likelihood of utilizing the coverage. Below, detailed breakdowns of each option—including cost implications, demographic relevance, and scenarios where they provide the most value—help drivers make informed choices. ---Roadside Assistance: Costs, Coverage Scope, and Best Use Cases
Roadside assistance provides emergency services such as towing, battery jumps, fuel delivery, and lockout assistance. While many insurers bundle this with full coverage policies, standalone plans or upgrades are available. The average annual cost for roadside assistance ranges from **$30 to $150**, depending on coverage limits and deductibles. **Key Benefits:** - **Convenience for Long-Distance Travelers:** Drivers frequently traveling on highways or rural areas benefit most, as breakdowns in remote locations can incur high towing costs (e.g., $75–$125 per mile for long-distance tows). - **Peace of Mind for Older Vehicles:** Vehicles over 10 years old or with known mechanical issues (e.g., transmission failures) see higher utilization rates, justifying the added cost. - **Mobile Repair Services:** Some plans include on-site diagnostics or fluid top-offs, reducing wait times and secondary expenses (e.g., hotel stays during repairs). **Cost vs. Value Analysis:** - **Urban Drivers:** May pay more for the coverage than they utilize it, as breakdowns in cities are less frequent and often resolved quickly via roadside service apps (e.g., AAA memberships or local towing services). - **Rural/Suburban Drivers:** Higher likelihood of breakdowns due to longer distances between service stations; the cost often offsets potential towing fees exceeding $200. - **Example Scenario:** A driver in Arizona with a 15-year-old SUV might spend **$100/year** for roadside assistance but save **$500+** in a single incident involving a dead battery in a remote desert area. ---Rental Reimbursement: When the Cost Justifies the Coverage
Rental reimbursement covers the cost of a rental car while the insured vehicle is being repaired after a covered claim. Premiums for this add-on typically range from **$15 to $50 per year**, with daily limits varying by insurer (commonly **$20–$50/day** and **$750–$1,500/year**). **Key Benefits:** - **Minimizing Downtime for Commuters:** Urban professionals relying on personal vehicles for work (e.g., sales representatives, contractors) face higher opportunity costs from being without a car. A **$30/day** rental reimbursement limit could cover a **$210/week** loss in productivity or transportation expenses. - **High-Mileage Drivers:** Those who drive **20,000+ miles annually** may incur **$1,000+ in Uber/Lyft costs** over a 30-day repair period, making rental reimbursement cost-effective. - **Avoiding Secondary Expenses:** Without coverage, drivers may face unexpected costs for public transit, taxis, or alternative transportation (e.g., **$500+** for a month of rideshares in a city like Los Angeles). **Demographic Prioritization:** - **Top 3 Groups for Rental Reimbursement:** 1. **Urban Commuter (e.g., New York, Chicago):** Daily reliance on personal vehicles for work; **$40/year** add-on saves **$1,200+ annually** in potential rideshare costs. 2. **Long-Distance Travelers (e.g., Truck Drivers, Road Warriors):** Frequent breakdowns in transit; **$30/year** covers **$900+** in rental costs for a 30-day repair in a non-local area. 3. **Parents with School-Aged Children:** Need reliable transportation for drop-offs/pickups; **$25/year** limits exposure to **$750+** in alternative transport expenses. ---Gap Insurance: Protecting Financed Vehicles from Depreciation Risks
Gap insurance covers the difference between a vehicle’s **actual cash value (ACV)** and the remaining balance on an auto loan if the car is totaled or stolen. This is critical for vehicles that depreciate rapidly (e.g., new cars losing **20–30% of value in the first year**). Annual costs average **$20–$50**, but the savings can be substantial. **Key Benefits:** - **New Car Owners:** A **2023 Toyota Camry** financed for **$25,000** may have an ACV of **$18,000** after 12 months, leaving a **$7,000 gap**. Without gap insurance, the driver would owe the remaining loan balance. - **Leased Vehicles:** Lessees often face **higher financial penalties** if the vehicle is totaled before the lease ends. Gap insurance ensures the lessee isn’t responsible for the remaining lease payments. - **High-Depreciation Vehicles:** Luxury or electric vehicles (e.g., Tesla Model 3) lose value faster; gap insurance mitigates the risk of owing more than the car is worth. **Cost-Effectiveness by Vehicle Age:** - **0–3 Years Old:** **Highest value** for gap insurance, as depreciation is steepest. Example: A **2022 Honda Civic** financed for **$20,000** could have a gap of **$5,000** after 2 years. - **3–5 Years Old:** Moderate value; depreciation slows, but loan balances may still exceed ACV in cases of accidents. - **5+ Years Old:** Typically **not cost-effective**, as the gap is minimal (e.g., a **2018 Ford F-150** with **$12,000 remaining** may only have a **$2,000 gap**). ---Ranked List of Most Valuable Add-Ons by Driver Demographics
The priority of add-ons varies based on driving patterns, vehicle age, and financial exposure. Below is a ranked list tailored to specific groups, balancing cost and utility. **1. Urban Commuters (High Daily Mileage, Work Dependence)** - **Top Add-On:** Rental Reimbursement ($25–$40/year) *Justification:* Minimizes lost income and productivity from vehicle downtime. - **Secondary Add-On:** Roadside Assistance ($50–$80/year) *Justification:* Breakdowns in congested areas can lead to long repair waits and secondary costs (e.g., parking fines, late fees). - **Least Critical:** Gap Insurance (unless driving a new/leased vehicle). **2. Long-Distance Travelers (High Annual Mileage, Frequent Trips)** - **Top Add-On:** Roadside Assistance ($60–$100/year) *Justification:* Remote breakdowns incur higher towing costs; mobile repair services reduce downtime. - **Secondary Add-On:** Rental Reimbursement ($30–$50/year) *Justification:* Rental costs in non-local areas (e.g., **$80–$120/day** in tourist-heavy states like Florida or California) justify the premium. - **Least Critical:** Gap Insurance (unless financing a new vehicle). **3. New Car Owners (0–3 Years Old, High Loan Balances)** - **Top Add-On:** Gap Insurance ($20–$40/year) *Justification:* Protects against depreciation risks; critical for leased or financed vehicles. - **Secondary Add-On:** Comprehensive/Collision Deductible Waiver (if available) *Justification:* Reduces out-of-pocket expenses for repairs on newer vehicles. - **Least Critical:** Rental Reimbursement (unless commuting for work). **4. High-Risk Drivers (Poor Credit, DUI History, or Frequent Claims)** - **Top Add-On:** Uninsured/Underinsured Motorist (UM/UIM) Coverage (discussed in next section) *Justification:* Higher exposure to uninsured drivers; UM/UIM limits protect against catastrophic medical/property costs. - **Secondary Add-On:** Roadside Assistance ($40–$70/year) *Justification:* Breakdowns may be more frequent due to older vehicles or maintenance neglect. - **Least Critical:** Gap Insurance (unless financing a vehicle). **5. Rural/Suburban Drivers (Lower Traffic Density, Older Vehicles)** - **Top Add-On:** Roadside Assistance ($50–$90/year) *Justification:* Longer distances to repair shops increase towing and repair costs. - **Secondary Add-On:** Rental Reimbursement ($20–$35/year) *Justification:* Limited public transit options; rental costs are higher in non-urban areas. - **Least Critical:** Gap Insurance (unless vehicle is new or financed). ---Uninsured/Underinsured Motorist Coverage: Affordability and Protection in High-Risk States
Uninsured/underinsured motorist (UM/UIM) coverage protects drivers when at-fault parties lack sufficient insurance. The **National Association of Insurance Commissioners (NAIC)** reports that **12.6% of drivers** were uninsured in 2022, with rates exceeding **20% in states like Florida, Mississippi, and New Mexico**. UM/UIM coverage costs **$50–$200 annually**, depending on coverage limits and state requirements. **Impact on Affordability:** - **States with Mandatory UM/UIM:** Some states (e.g., New Hampshire, Virginia) require UM/UIM coverage, reducing the need for optional add-ons. However, **minimum limits (e.g., $25,000 bodily injury per person)** may be insufficient for severe accidents. - **States with High Uninsured Rates:** Drivers in **Florida (26.7% uninsured)** or **Michigan (5.8% uninsured but high medical costs)** benefit most from **higher UM/UIM limits (e.g., $100,000–$500,000)**. - **Cost vs. Protection Tradeoff:** - **Low Limits ($25,000):** Adds **$30–$50/year** but may leave drivers vulnerable to **$100,000+ medical bills** from a severe accident. - **High Limits ($500,000+):** Adds **$100–$200/year** but ensures full coverage for catastrophic injuries or property damage. **RealSecuring Full Coverage for Leased or Borrowed Vehicles: Temporary Policies and Non-Owner Insurance
Leasing or borrowing a vehicle introduces unique challenges for securing full coverage insurance, particularly when the driver does not own the car. Temporary policies and non-owner insurance provide viable solutions, but their application depends on the vehicle’s ownership status, lease terms, and the driver’s insurance history. Understanding these options ensures compliance with legal requirements while minimizing financial risks. **Temporary insurance policies** are designed for short-term use, such as leasing a car for a few months or borrowing a vehicle for a weekend trip. These policies can be purchased directly from insurers or through rental agencies and typically cover liability, collision, and comprehensive risks for the duration of the lease or rental period. However, they often exclude modifications or commercial use unless explicitly endorsed. **Non-owner insurance** is tailored for individuals who frequently drive vehicles they do not own, such as leased cars, family members’ vehicles, or rental cars. This coverage provides liability protection and may include collision/comprehensive options, depending on the policy. Non-owner policies are particularly useful for drivers with clean records who need consistent coverage across multiple vehicles without the hassle of switching insurers. ---Temporary Insurance Policies for Leased Vehicles
Leasing a vehicle often requires proof of full coverage insurance, but traditional auto policies may not extend to leased cars unless explicitly stated. Temporary insurance policies bridge this gap by offering flexible coverage terms aligned with lease durations. Key considerations include: - **Policy Duration and Flexibility**: Temporary policies can range from 1 month to 12 months, making them ideal for short-term leases. Some insurers offer "gap insurance" to cover the difference between the car’s depreciated value and the remaining lease balance in case of a total loss. - **Coverage Limits and Deductibles**: Ensure the policy matches the lease agreement’s requirements for liability limits (e.g., 100/300/50 in the U.S.). Higher deductibles may lower premiums but increase out-of-pocket costs in claims. - **Lease-Specific Endorsements**: Some leasing companies mandate specific coverage types, such as guaranteed asset protection (GAP) or rental reimbursement. Verify these requirements with the lessor before purchasing temporary insurance. - **Cost Factors**: Premiums for temporary policies depend on the driver’s age, driving record, and the vehicle’s make/model. For example, a 30-year-old driver with a clean record leasing a Honda Civic might pay **$150–$300/month** for full coverage, while a 25-year-old with a minor violation could see costs rise to **$250–$400/month**. **Example Scenario**: A driver leases a Toyota Camry for 6 months. The lessor requires full coverage with $500 deductibles. A temporary policy from Progressive might cost **$220/month**, including liability ($50,000/$100,000), collision, and comprehensive coverage. Without this policy, the driver risks voiding the lease agreement or facing financial penalties. ---Non-Owner Insurance for Borrowed or Shared Vehicles
Non-owner insurance is a cost-effective solution for individuals who frequently drive vehicles they do not own, such as: - Family members’ cars during vacations. - Rental vehicles for business or personal trips. - Leased cars under a corporate or personal lease agreement. This coverage typically includes: - **Liability Protection**: Covers bodily injury and property damage to third parties, often up to state-minimum or higher limits (e.g., 100/300/50). - **Optional Collision/Comprehensive**: Some policies allow adding physical damage coverage for borrowed vehicles, though this may require proof of the owner’s permission. - **No Vehicle Registration Requirement**: Since the policy does not tie to a specific car, it avoids the need for vehicle registration or title transfers. **Cost Analysis**: Non-owner insurance premiums are generally **30–50% cheaper** than standard auto policies because they lack the risk associated with vehicle ownership. For instance: - A 28-year-old driver with a clean record might pay **$800–$1,200/year** for non-owner liability-only coverage. - Adding collision/comprehensive could increase costs to **$1,500–$2,500/year**, depending on the driver’s profile and the insurer’s underwriting guidelines. **Limitations**: - **Exclusions**: Non-owner policies may exclude coverage for vehicles used for rideshare, commercial purposes, or modified cars. - **Primary vs. Secondary Coverage**: If the borrowed vehicle has its own insurance, the non-owner policy acts as secondary coverage, meaning the primary policy pays first. - **State Regulations**: Some states (e.g., California, New York) require non-owner policies to meet the same liability limits as standard policies, while others allow lower minimums. **Example Scenario**: A college student borrows their parent’s SUV for a summer road trip. Their non-owner policy provides $100,000 bodily injury liability and $30,000 property damage coverage. If they cause an accident resulting in $40,000 in damages, their policy covers the amount up to the limit, avoiding personal asset risks. ---Key Differences Between Temporary and Non-Owner Policies
While both options serve drivers without permanent vehicles, their applications differ significantly:| Feature | Temporary Insurance Policy | Non-Owner Insurance |
|---|---|---|
| Primary Use Case | Leased vehicles, long-term rentals, or specific time-bound coverage. | Frequent borrowing of owned vehicles (e.g., family cars, rentals). |
| Coverage Duration | 1 month to 12 months (aligned with lease/rental terms). | Year-round, renewable annually (no vehicle-specific term). |
| Physical Damage Coverage | Often includes collision/comprehensive for the leased/rented vehicle. | May require separate endorsements for borrowed vehicles. |
| Cost Range (Annual) | $1,800–$4,800 (varies by vehicle value and lease terms). | $800–$2,500 (liability-only or with optional physical damage). |
| Underwriting Focus | Vehicle-specific risks (e.g., lease requirements, modifications). | Driver-specific risks (e.g., driving record, credit score). |
Common Pitfalls and How to Avoid Them
Misunderstandings or oversights in temporary or non-owner insurance can lead to denied claims or legal complications. Common pitfalls include: - **Assuming Personal Auto Policies Cover Leased Cars**: Many standard policies exclude leased vehicles unless explicitly endorsed. Always verify with the insurer. - **Ignoring Lease-Specific Requirements**: Lessors often mandate higher liability limits or additional coverages (e.g., GAP insurance). Non-compliance may void the lease. - **Overlapping Coverages**: Purchasing both a temporary policy and non-owner insurance for the same vehicle can create confusion during claims. Coordinate with the insurer to ensure proper priority. - **Underestimating Deductibles**: High deductibles lower premiums but increase financial risk. For leased vehicles, ensure deductibles align with the lease’s financial responsibility clauses. - **Failing to Disclose All Drivers**: Adding unauthorized drivers to a temporary policy can invalidate coverage. Always declare all potential drivers upfront. **Pro Tip**: Use insurers that specialize in **gap insurance** or **lease-specific policies**, such as Esurance, Allstate’s Lease Protection Program, or Progressive’s Lease Coverage. These providers offer tailored solutions to avoid common pitfalls. ---Non-owner insurance is not a substitute for a standard auto policy but a **supplemental liability shield** for drivers without permanent vehicles. Temporary policies, conversely, are **vehicle-specific safety nets** designed to meet lease or rental obligations. Both require careful alignment with the insured’s driving habits and financial constraints to ensure comprehensive protection without unnecessary costs.
Full Coverage Insurance for International Drivers in the U.S.: Policies, Temporary Solutions, and SR-22 Compliance
International drivers visiting or residing in the U.S.—such as tourists, expatriates, or seasonal workers—often face challenges securing full coverage insurance due to licensing restrictions, unfamiliarity with local regulations, or temporary residency status. While U.S. insurers typically require a valid driver’s license and Social Security Number (SSN) for standard policies, exceptions exist for non-residents through temporary policies, non-owner insurance, or SR-22 filings. Understanding these pathways ensures compliance with state laws while mitigating financial risks from accidents or vehicle damage. The process varies by state, insurer, and driver classification (e.g., tourists vs. long-term residents). Some states, like Florida or Texas, offer **non-owner policies** or **short-term visitor insurance**, while others mandate **SR-22 certificates** for high-risk foreign drivers. Below are structured pathways to obtain full coverage, including legal requirements and practical considerations. ---Temporary Full Coverage for Tourists and Short-Term Visitors
Tourists driving in the U.S. for vacations or business trips can obtain short-term full coverage through specialized insurers or rental car agreements. These policies typically range from **1 day to 30 days** and cover liability, collision, and comprehensive risks. Key providers include **Allstate’s "Short-Term Visitor Insurance"** or **Geico’s "Non-Owner Policy"** for tourists. **Requirements for Eligibility:** - Valid **foreign driver’s license** (translated if non-English). - **Passport or visa proof** of temporary stay. - **Rental car agreement** (if applicable), which may include primary insurance with a **loss damage waiver (LDW)**. - **Credit card** for deposits or deductibles (some insurers require a U.S. card). **Limitations:** - **No long-term residency** (policies expire with the visitor’s stay). - **Higher premiums** due to perceived risk (e.g., $3–$7 per day for liability-only coverage). - **Exclusions for commercial use** or driving without a rental car. **Example Costs (2024 Estimates):** - **1-week liability-only policy (Florida):** $150–$250. - **30-day full coverage (California):** $800–$1,500 (varies by vehicle age/value). - **Rental car LDW add-on:** $15–$30/day (often cheaper than standalone tourist insurance). ---SR-22 Requirements for Non-Resident Aliens and Expats
Non-resident aliens (e.g., Canadian snowbirds, EU expats) may need an **SR-22 certificate** if convicted of traffic violations (e.g., DUI, uninsured driving) or to comply with state residency requirements. An SR-22 is a **filing by the insurer** proving financial responsibility, not insurance itself. **Process for Obtaining SR-22 as a Foreign Driver:** 1. **Secure a U.S. Driver’s License:** - States like **Florida, Arizona, or Texas** allow license conversion for non-residents with proof of residency (e.g., utility bills, rental agreements). - **No license?** Some insurers (e.g., **Progressive, The General**) offer **non-owner SR-22 policies** for foreign license holders. 2. **Purchase an SR-22 Policy:** - **Minimum coverage** varies by state (e.g., **$30,000/$60,000 bodily injury liability** in most states). - **Premiums** are **20–50% higher** than standard rates (e.g., $1,200–$2,500/year for a clean record). - **SR-22 filing fee:** $15–$50 (paid to the insurer). 3. **Maintain Compliance:** - The SR-22 remains active for **3 years** (or until violations are cleared). - **Lapses in coverage** result in license suspension and reinstatement fees ($100–$500). **States with Stricter SR-22 Rules for Foreign Drivers:** - **California:** Requires a **U.S. license** and **proof of residency** before issuing an SR-22. - **New York:** Mandates **full coverage** (not just liability) for SR-22 filings. - **Texas:** Allows **non-owner SR-22** but may deny coverage if the driver has prior violations in the U.S. ---Extending Foreign Insurance for U.S. Driving: Limitations and Exclusions
Some international drivers attempt to extend their **home-country insurance** for U.S. driving, but this is **rarely valid** due to jurisdictional and coverage gaps. However, a few options exist with strict conditions: **1. Multi-Country Insurance Policies (e.g., Green Card, ACE European Cover)** - **Coverage Scope:** Designed for **EU drivers** traveling across borders (e.g., France → U.S.). - **Limitations:** - **No comprehensive/collision coverage** in the U.S. (only liability). - **Exclusions for rental cars** or vehicles not listed on the policy. - **Maximum stay:** Typically **90 days** (varies by provider). - **Example Providers:** - **ACE European Cover** (covers U.S. driving for EU residents). - **Allianz Green Card** (liability-only for short-term stays). **2. Umbrella Policies with U.S. Add-Ons** - Some **European insurers** (e.g., **AXA, Allianz**) offer **supplemental liability coverage** for U.S. trips. - **Requirements:** - Proof of **primary insurance** (e.g., rental car policy). - **Deductible limits** apply (e.g., $1,000–$2,500). - **Exclusions:** - **No coverage for uninsured motorist property damage** in most states. - **Void if driving without a rental car agreement**. **3. State-Specific Reciprocity Agreements** - **Canada/USA:** Some provinces (e.g., **Ontario, Quebec**) allow **temporary extension** of Canadian insurance for U.S. driving under **reciprocity rules**. - **Validity:** Up to **90 days** for tourists. - **Requirements:** - **Proof of residency** in Canada. - **Vehicle registration** in Canada (not always required for rentals). - **Exclusions:** - **No coverage for vehicles not registered in Canada** (e.g., U.S. rental cars). - **Higher deductibles** for claims. **Real-World Example:** A **Canadian snowbird** renting a car in Arizona for 3 months may use their **Ontario auto policy** for liability but must purchase **separate collision/comprehensive coverage** from a U.S. insurer (e.g., **State Farm, Farmers**) to comply with Arizona law. ---Top 5 U.S. Insurers Offering Full Coverage to International Drivers
Below is a comparative table of insurers that provide full coverage options for non-resident aliens, including eligibility criteria and coverage details. Pricing is approximate for a **2020 Toyota Camry** driven by a **45-year-old expat** in a border state (e.g., Florida). | **Insurer** | **Policy Type** | **Eligibility** | **Coverage Limits** | **Estimated Annual Premium (Full Coverage)** | **SR-22 Availability** | **Key Exclusions** | |-------------------|-------------------------------|---------------------------------------------------------------------------------|-----------------------------------------------|--------------------------------------------|------------------------|---------------------------------------------| | **Progressive** | Non-Owner / Tourist Policy | Foreign license + passport/visa; no U.S. license required. | 100/300/50 (liability), collision/comprehensive optional. | $1,500–$3,000 (tourist); $2,500–$4,500 (non-owner). | Yes (non-owner SR-22). | No coverage for commercial use; rental cars excluded unless added. | | **The General** | High-Risk / SR-22 Policy | Foreign drivers with violations or no U.S. license; proof of residency. | State-minimum liability + optional full coverage. | $3,000–$6,000 (SR-22 required). | Yes. | Prior U.S. violations may void policy. | | **Dairyland** | Short-Term Visitor Insurance | Tourists (up to 90 days); rental car or personal vehicle. | Liability + collision/comprehensive (deductible applies). | $800–$2,000 (30-day policy). | No. | No medical payments coverage. | | **Allstate** | International Driver Program | Expats with work visas or long-term stays; may require U.S. license conversion. | Full coverage with customizable deductibles. | $2,000–$5,000 (varies by state). | Yes (with U.S. license). | No coverage for vehicles not primarily garaged in the U.S. | | **Farmers** | Non-Resident Alien Policy | Canadian/Mexican snowbirds with proof of residency in border states. | Full coverage with optional umbrella liability. | $1,800–$4,000 (Florida/Arizona). | Yes (for violations). | No coverage for vehicles used for business. | **Notes:** - **Border States (e.g., Texas, Florida, Arizona):** Often have **lower premiums** for non-residents due to relaxed licensing rules. - **Canadian Snowbirds:** May qualify for **discounts** if they spend most of the year in Canada (e.g., **CANADA-U.S. Auto Insurance Reciprocity**). - **Mexican Drivers:** Typically **cannot** obtain full coverage without a U.S. license; liability-only policies are the norm. ---Risks and Affordability Challenges for Drivers with Foreign Licenses
Drivers holding **foreign licenses** in states requiring a **U.S. license** face **legal and financial risks**, including: - **License Suspension:** Police may **impound vehicles** or issue fines if a foreign license is invalid in the state (e.g., **California, New York**). - **Denied Claims:** Insurers may **void coverage** if the driver is unlicensed at the time of an accident. - **Higher Premiums:** Foreign drivers are classified as **high-risk**, leading to **20–100% higher rates** than U.S. residents. **State-Specific Risks:** - **California:** **No recognition** of foreign licenses for long-term residents; **mandatory U.S. license conversion** within 30 days of residency. - **New York:** **Full coverage required** for non-residents; **no non-owner policies** available. - **Texas:** Allows **foreign licenses**How Full Coverage Insurance Prevents Financial Ruin in Catastrophic Scenarios
Full coverage insurance acts as a financial shield against the most devastating outcomes of car accidents—total vehicle loss, multi-million-dollar liability lawsuits, and uninsured motorist collisions. Without it, a single accident could wipe out savings, force asset liquidation, or even lead to bankruptcy. The protection extends beyond repairs to cover medical bills, legal defense costs, and third-party damages, ensuring policyholders retain financial stability even in worst-case scenarios. The core components of full coverage—collision, comprehensive, liability, and uninsured/underinsured motorist coverage—work synergistically to mitigate risks. **Collision coverage** replaces or repairs the insured vehicle after crashes, while **comprehensive coverage** addresses non-collision events like theft or natural disasters. **Liability coverage** pays for injuries and property damage to others, and **uninsured/underinsured motorist coverage** fills gaps when at-fault drivers lack sufficient insurance. Together, these layers ensure no single financial blow becomes catastrophic. ---Protection Against Total Vehicle Loss and Replacement Costs
A total loss occurs when repair costs exceed the vehicle’s actual cash value (ACV), often due to severe collisions or fires. Without full coverage, policyholders must pay the ACV out-of-pocket—a sum that can exceed $20,000 for mid-range vehicles and $50,000+ for luxury or high-performance cars. **Full coverage replaces the vehicle’s value**, either by paying the ACV or providing a comparable replacement, depending on the policy terms. For example, a 2022 Tesla Model 3 with an ACV of $35,000 and a $1,000 deductible would cost the insured **$34,000** to replace without collision coverage. With full coverage, the insurer covers the **$35,000**, leaving the policyholder with only the deductible. **Blockquote:** *"Full coverage ensures you’re not stranded with a destroyed vehicle and a crippling bill—it’s the difference between walking away from an accident with a loaner car or facing financial paralysis."* ---Liability Coverage as a Safeguard Against Lawsuits and Medical Debt
Liability limits (e.g., 100/300/50) determine how much insurance will pay for third-party injuries and property damage. In states with no-fault laws (e.g., Florida, Michigan), medical costs are initially covered by personal injury protection (PIP), but **liability still applies if the at-fault driver is sued**. In at-fault states (e.g., California, Texas), liability is the primary defense against lawsuits. A **$150,000 liability claim** could stem from a single accident where: - A pedestrian suffers **$100,000 in medical bills** (surgery, rehabilitation, lost wages). - The insured’s vehicle causes **$50,000 in property damage** to another car and a light pole. Without liability coverage, the policyholder would face **personal asset seizure**, wage garnishment, or bankruptcy. **Full coverage liability limits absorb these costs**, preventing financial ruin. ---Case Study: Avoiding Bankruptcy After a $150,000 Liability Claim
**Scenario:** A 35-year-old driver in Texas with **$100,000/$300,000 bodily injury liability limits** rear-ended a vehicle carrying three passengers. One passenger suffered a spinal cord injury requiring **$120,000 in medical treatment** and lifetime care costs projected at **$300,000**. The other two passengers filed a **$30,000 property damage claim** for their totaled SUV. **Outcome Without Full Coverage:** - The policyholder’s **$100,000 bodily injury limit** was exhausted after paying the medical bills. - The remaining **$200,000** was sought through a lawsuit against personal assets (home, savings, investments). - The policyholder faced **bankruptcy filings** and asset liquidation to settle the claim. **Outcome With Full Coverage (Umbrella Policy Added):** - The **$300,000 bodily injury limit** covered the **$120,000 medical costs**, leaving **$180,000** for property damage. - An **additional $1 million umbrella policy** (costing **$300/year**) absorbed the excess, preventing any personal liability. - The policyholder retained **home equity, retirement funds, and creditworthiness**, avoiding financial collapse. **Key Takeaway:** *"Full coverage doesn’t just pay claims—it preserves your future. Without it, a single accident can unravel decades of financial planning."* ---How Umbrella Policies Complement Full Coverage for High-Net-Worth Individuals
Umbrella policies extend liability coverage beyond standard auto and home insurance limits, providing an additional **$1 million to $10 million** in protection. They are particularly valuable for individuals with: - **High-value assets** (e.g., homes worth $500K+, investments, business ownership). - **High-risk driving habits** (e.g., frequent long-distance travel, teen drivers in the household). - **Exposure to lawsuits** (e.g., hosting large gatherings, owning rental properties). **Cost Examples for Umbrella Policies:** | **Coverage Limit** | **Annual Premium (Estimate)** | **Best For** | |--------------------|-------------------------------|---------------------------------------| | $1 million | $150–$300 | Homeowners with $300K+ net worth | | $2 million | $250–$450 | Business owners or investors | | $5 million | $500–$1,000 | High-profile professionals (doctors, lawyers) | **Blockquote:** *"An umbrella policy costs pennies per day but can save millions in lawsuits. For a $300/year premium, you’re buying peace of mind against a $10 million judgment."* ---Comparison of Out-of-Pocket Costs in a $50,000 Accident (With vs. Without Full Coverage)
The following table illustrates the financial impact of a **$50,000 at-fault accident** (e.g., hitting a guardrail, causing $40K in property damage and $10K in injuries to another driver) across three states with varying liability laws and average insurance costs. | **State** | **Policy Type** | **Liability Limits** | **Deductible** | **Out-of-Pocket Cost** | **Total Paid by Insurer** | **Assets at Risk** | |------------------|-------------------------------|-----------------------|-----------------|-------------------------|---------------------------|-----------------------------| | **California** | **No Full Coverage** | 15/30/5 | N/A | **$50,000** | $0 | Home, savings, investments | | **California** | **Full Coverage (100/300/50)**| 100/300/50 | $1,000 | **$1,000** | $49,000 | None | | **Texas** | **No Full Coverage** | 30/60/25 | N/A | **$50,000** | $0 | Personal assets | | **Texas** | **Full Coverage (100/300/100)**| 100/300/100 | $500 | **$500** | $49,500 | None | | **Florida** | **No Full Coverage** | 10/20/10 | N/A | **$50,000** | $0 | Home equity, 401(k) | | **Florida** | **Full Coverage (250/500/100)**| 250/500/100 | $1,500 | **$1,500** | $48,500 | None | **Notes:** - **California** has higher minimum liability limits but lower average premiums due to competitive markets. - **Texas** requires higher minimum liability (30/60/25), but full coverage reduces exposure significantly. - **Florida’s** no-fault system complicates liability claims, but full coverage still mitigates personal financial risk. **Blockquote:** *"In all three states, full coverage reduces out-of-pocket costs by **98% or more**. Without it, a single accident can turn a policyholder into a defendant in a financial war."* ---Safeguarding Assets Through Full Coverage and Liability Protection
Full coverage insurance protects assets indirectly by preventing lawsuits from reaching personal holdings. When a policyholder is sued for damages exceeding their insurance limits, creditors may target: - **Primary residences** (home equity loans, mortgages). - **Retirement accounts** (IRAs, 401(k)s, if not protected by state laws). - **Investments** (stocks, bonds, business interests). - **Future earnings** (wage garnishment). **Strategies to Further Protect Assets:** - **Increase liability limits** to $500/1,000/100 or higher. - **Add an umbrella policy** for excess coverage. - **Consult an estate planner** to structure assets (e.g., trusts, LLCs) to limit liability exposure. - **Review state homestead exemptions**, which may shield primary residences from creditors in states like Texas or Florida. **Blockquote:** *"Assets aren’t just what you own—they’re your ability to earn, save, and provide for your family. Full coverage is the first line of defense in preserving that stability."* ---Telematics and Connected Car Data Impact on Full Coverage Affordability
Telematics and connected car technologies have revolutionized how insurers assess risk and price full coverage policies. By leveraging real-time data from onboard systems, insurers can move beyond traditional factors like credit scores or driving history to offer personalized, usage-based pricing. This shift reduces premiums for safe drivers while increasing costs for high-risk behavior, creating a more equitable and cost-effective insurance model. The integration of telematics—such as Apple CarPlay, Android Auto, and dedicated in-car systems—enables insurers to monitor driving habits continuously. Data points such as speed, braking patterns, phone usage, and even road conditions are analyzed to determine risk profiles. This data-driven approach allows insurers to reward policyholders for safe driving with discounts, often ranging from **10% to 40%** on full coverage premiums. The result is a dynamic pricing system where affordability is directly tied to observable behavior rather than static assumptions. ---Telematics Data Collection and Risk Assessment
Telematics systems collect data through onboard diagnostics (OBD-II ports), mobile apps, or integrated vehicle systems. Key metrics include: - **Speed and acceleration**: Aggressive driving (e.g., rapid acceleration or hard braking) triggers higher risk scores. - **Distraction detection**: Usage of phones or navigation while driving is flagged as a safety hazard. - **Geofencing and route analysis**: High-risk areas (e.g., urban congestion zones) or frequent night driving may increase premiums. - **Vehicle health monitoring**: Engine diagnostics can indicate maintenance needs, which may affect liability risk. Insurers use this data to categorize drivers into **risk tiers**, similar to credit scoring but with real-time updates. For example, a driver with a clean telematics record might qualify for a **"Safe Driver" discount**, while one with frequent speeding violations could face **surcharges or policy exclusions**. This granularity ensures that full coverage premiums reflect actual driving behavior, not just historical claims data. ---Integration with Apple CarPlay and Android Auto
Modern vehicles equipped with Apple CarPlay or Android Auto provide insurers with additional data streams through third-party apps. For instance: - **Apple’s CarPlay integration** allows insurers to access **Apple Maps data** (e.g., frequent detours in accident-prone areas) or **Siri voice command logs** (e.g., distracted driving alerts). - **Android Auto’s Google services** can track **navigation history**, **speed limits**, and **traffic violations** via Google Maps integration. - **Usage-based insurance (UBI) apps** (e.g., State Farm’s "Drive Safe & Save," Progressive’s "Snapshot") sync with these systems to provide **real-time feedback** and **instant discounts** for safe driving. **Example**: A policyholder using **Allstate’s "Drivewise"** app via CarPlay might receive a **20% discount** after 6 months of maintaining a **90%+ safe-driving score**, while a similar driver without telematics could pay **30% more** for the same coverage. ---Privacy and Data Security Considerations
While telematics enhance affordability, they raise concerns about **data privacy and consent**. Insurers must comply with regulations like the **California Consumer Privacy Act (CCPA)** and **GDPR (EU)**, ensuring: - **Explicit consent** from policyholders before data collection. - **Anonymization** of sensitive driving behavior to prevent discrimination. - **Transparent opt-out options** for those uncomfortable with continuous monitoring. **Best Practices for Insurers**: - Use **aggregated, not individual-specific**, data for underwriting where possible. - Offer **opt-in discounts** (e.g., "Earn a 15% discount by sharing anonymous driving data"). - Provide **clear explanations** of how data influences premiums (e.g., "Your hard braking reduced your discount by 5%"). ---Case Study: How Telematics Reduces Full Coverage Costs
**Progressive’s "Snapshot" Program**: - **Data Used**: GPS location, speed, braking, phone use, and time of day. - **Impact**: Drivers who enrolled in 2022 saw an **average savings of $146/year** on full coverage. - **Behavioral Insight**: Policyholders who reduced speeding by **10%** saw discounts increase by **12%** within 3 months. **Nationwide’s "SmartRide"**: - **Integration**: Works with **Apple CarPlay/Android Auto** and **OBD-II devices**. - **Discount Tier**: Drivers with **zero at-fault accidents** for 12 months can qualify for a **35% premium reduction**.Legal Minimum Coverage Requirements by State and Full Coverage Exceeding Baselines
State-mandated minimum auto insurance requirements vary significantly, often focusing on liability coverage to address bodily injury and property damage caused to others. These baselines typically exclude comprehensive and collision coverage, which are critical for protecting the policyholder’s own vehicle and financial assets. Full coverage policies, combining liability, collision, and comprehensive insurance, provide extensive protection beyond these legal minimums, addressing risks such as theft, natural disasters, and accidents involving uninsured drivers. Full coverage policies are structured to mitigate financial exposure in scenarios where minimum coverage would leave drivers vulnerable. While state laws dictate the least acceptable liability limits, full coverage ensures broader protection, often including higher liability limits, medical payments (MedPay), uninsured/underinsured motorist (UM/UIM) coverage, and additional optional endorsements.State-by-State Minimum Liability Coverage Requirements
Minimum auto insurance requirements are categorized into three primary components: bodily injury liability (BI), property damage liability (PD), and, in some states, personal injury protection (PIP) or MedPay. Below is a summary of the legal minimums by state, with full coverage typically exceeding these limits by offering additional layers of protection.- No-Fault States (e.g., Michigan, Florida, New York): Require PIP or no-fault coverage in addition to liability limits. For example, Michigan mandates a minimum of $50,000 per person/$100,000 per accident for bodily injury and $10,000 for property damage, but full coverage policies often include $100,000/$300,000 BI limits and higher PD thresholds.
- At-Fault States (e.g., California, Texas, Illinois): Focus on liability limits, such as California’s 15/30/5 requirement ($15,000 per person/$30,000 per accident for BI, $5,000 for PD). Full coverage here may include $100,000/$300,000 BI limits, $50,000 PD, and comprehensive/collision coverage with deductibles as low as $250.
- Modified No-Fault States (e.g., New Jersey, Kentucky): Combine no-fault benefits with liability requirements. New Jersey’s minimum is 15/30/5, but full coverage policies often include higher BI limits (e.g., 100/300/50) and additional PIP coverage.
- States with Lower Limits (e.g., Mississippi, Missouri): Mississippi’s minimum is 25/50/25, but full coverage policies may exceed this with 100/300/100 limits, ensuring better protection against lawsuits and medical expenses.
How Full Coverage Exceeds Minimum Requirements
Full coverage policies are designed to address gaps left by state-mandated minimums, particularly in the following areas:- Collision Coverage: Pays for damage to the policyholder’s vehicle in accidents, regardless of fault. Minimum coverage does not include this, leaving drivers financially exposed to repair or replacement costs.
- Comprehensive Coverage: Protects against non-collision incidents like theft, vandalism, or natural disasters. State minimums do not require this, making full coverage essential for asset protection.
- Higher Liability Limits: Full coverage often includes limits of 100/300/50 or higher, compared to state minimums like 25/50/25. This reduces out-of-pocket costs in lawsuits or medical claims.
- Uninsured/Underinsured Motorist (UM/UIM) Coverage: Compensates for injuries or damages caused by drivers without sufficient insurance. Many states mandate UM/UIM, but full coverage policies often provide higher limits.
- Medical Payments (MedPay) or Personal Injury Protection (PIP): Covers medical expenses for the policyholder and passengers, regardless of fault. While some states require PIP, full coverage extends these benefits with higher limits.
Financial Protection Beyond Legal Compliance
Driving with only the state-mandated minimum coverage can lead to severe financial consequences. For example: - A $50,000 medical bill for an at-fault accident in a state with 25/50 limits leaves the driver responsible for the remaining $25,000. - A $30,000 property damage claim in a state with $10,000 PD limits requires the driver to cover the excess. - Full coverage policies mitigate these risks by providing additional liability protection, ensuring the policyholder is not personally liable for excessive claims.Key Difference: State minimums ensure basic financial responsibility for others' injuries/damages, while full coverage protects the policyholder’s vehicle, health, and assets from a broader range of risks.
Securing affordable full coverage car insurance hinges on a mix of smart planning, leveraging discounts, and aligning your policy with your unique risks. From negotiating premiums at renewal to exploiting technology-driven discounts like telematics, the strategies outlined here demonstrate that comprehensive protection is within reach for nearly every driver. The key lies in understanding how insurers calculate rates—whether through credit scores, vehicle age, or driving habits—and using that knowledge to tailor coverage that fits both your budget and lifestyle. Whether you’re a high-risk driver rebuilding your record, a parent insuring a teen, or a luxury car owner seeking specialized protection, the insights provided here serve as a roadmap to balancing cost and coverage without compromise. In a world where unexpected accidents can derail finances, affordable full coverage isn’t just a luxury—it’s a necessity.

Frequently Asked Questions
What exactly does affordable full coverage car insurance include?
Affordable full coverage typically includes liability, collision, and comprehensive insurance. It protects against bodily injury, property damage, vehicle theft, and non-collision incidents like hail or vandalism. Deductibles and limits vary by policy and insurer.
How can I find the cheapest full coverage insurance rates?
Comparing quotes from multiple insurers, bundling policies (e.g., home and auto), maintaining a clean driving record, and raising deductibles can lower premiums. Discounts for safety features, low mileage, or student drivers may also help reduce costs.
Can I get full coverage insurance if I have a bad driving record?
Yes, but rates will be higher. High-risk drivers may qualify for specialized insurers or state-assigned risk pools. Defensive driving courses, SR-22 filings, or usage-based programs can sometimes improve affordability over time.
Does full coverage insurance pay off if my car is totaled?
Full coverage includes comprehensive insurance, which pays for a totaled car up to its actual cash value (ACV), minus your deductible. Collision coverage also applies if the loss results from a crash, depending on fault and policy terms.
What are the best optional coverages to add for extra protection?
Common add-ons include roadside assistance, rental reimbursement, gap insurance (for loans), and uninsured motorist coverage. Medical payments (MedPay) or increased liability limits may also provide broader financial protection for higher premiums.
How does technology like telematics affect my full coverage insurance cost?
Telematics programs track driving behavior (speed, braking, mileage) and can lower premiums for safe drivers. Some insurers offer discounts of 10-30% for enrolling. However, privacy concerns and data security are factors to consider before opting in.
Related articles

Affordable Full Coverage Car Insurance Unlocked Saving Money Without Sacrificing Protection
Discover Affordable Full Coverage Car Insurance Unlocked Saving Money Without Sacrificing Protection—smart tips to balance cost and premium coverage…
Affordable Car Insurance Washington Explained 2024 Costs Tips
Discover Affordable Car Insurance Washington Explained 2024 Costs Tips—key factors, savings strategies, and average rates to lower premiums legally in WA.

Affordable Car Insurance Quotes Online Find Best Deals Fast
Discover Affordable Car Insurance Quotes Online—compare top deals fast, save money, and secure the best coverage with trusted providers today.

Affordable Car Insurance Quotes Unlocked Simple Strategies For Savings
Discover Affordable Car Insurance Quotes Unlocked with simple strategies for savings—cut costs legally without sacrificing coverage. Expert tips inside!
Affordable Car Insurance Online Unlocking Savings With Smart Choices
Discover Affordable Car Insurance Online Unlocking Savings With Smart Choices—compare quotes, cut costs, and drive smarter. Save up to 30% today!
