Affordable Auto Insurance NYCUnlock Savings With Smart Strategies
Table of Contents
- Current State of Auto Insurance Costs in New York City
- Common Auto Insurance Discounts Available in NYC and Eligibility Criteria
- Comparison of the 5 Most Affordable Auto Insurers in NYC (2024 Data)
- NYC’s Mandatory Auto Insurance Coverages: State-Minimum Limits and Urban Driver Recommendations
- NYC-Specific Telematics Programs and Apps for Discounted Auto Insurance
- Common Pitfalls NYC Drivers Encounter When Shopping for Auto Insurance
- Steps to Apply for the NY No-Fault Insurance Fund and Claims Process for Uninsured Motorist Accidents
- How a NYC Resident Cut Auto Insurance Premiums by 40% Through Bundling and Usage-Based Discounts
- Rising Fuel Costs, EV Adoption, and Their Influence on NYC Auto Insurance Pricing
- Step-by-Step Workflow for Switching NYC Auto Insurers Without Coverage Gaps
- Breakdown of NYC’s Average Auto Insurance Premium Allocation by Coverage Type and Borough Variations
Navigating New York City’s auto insurance market can feel like dodging traffic—expensive, unpredictable, and fraught with hidden costs. With average premiums exceeding **$3,000 annually**—nearly double the national average—drivers often assume high prices are inevitable. Yet, beneath the surface, a mix of regulatory quirks, insurer discounts, and tech-driven tools can slash bills by **30% or more** for those who know where to look. From leveraging NYC-specific programs like the Essential Plan to exploiting pay-per-mile discounts for urban commuters, affordability isn’t just possible; it’s a skill. This guide breaks down the tactics, pitfalls, and untapped opportunities that transform "necessary expense" into a manageable line item in the city’s relentless budget battle.
The key lies in understanding why NYC’s insurance landscape differs sharply from other metros—where congestion pricing meets high theft rates, and no-fault laws collide with rideshare economies. Whether you’re a Brooklyn senior cutting premiums through anti-theft tech or a Queens rideshare driver optimizing hourly rates, the same principles apply: align coverage with risk, exploit data-driven discounts, and avoid common traps that inflate costs. By dissecting insurer strategies, government aid, and emerging trends like AI pricing, this exploration reveals how to turn the city’s most dreaded expense into a competitive advantage.
Current State of Auto Insurance Costs in New York City
New York City’s auto insurance market remains one of the most expensive in the U.S., with drivers facing significantly higher premiums than the national average. As of 2023, the average annual auto insurance cost in NYC exceeds **$3,500**, nearly double the U.S. average of **$1,771** (Insurance Information Institute, 2023). This disparity stems from a combination of regulatory mandates, urban risks, and market dynamics unique to the city. Recent trends indicate a **5–10% annual increase** in premiums, driven by rising medical costs, litigation expenses, and heightened vehicle theft rates. The cost burden is further amplified by New York’s **no-fault insurance system**, which requires Personal Injury Protection (PIP) coverage—mandatory medical benefits that add **$1,000–$1,500 annually** to premiums. Additionally, the city’s dense traffic, high population density, and elevated accident rates contribute to inflated claims, pushing insurers to adjust rates accordingly. Urban-specific risks, such as **parking-related incidents** and **pedestrian accidents**, also strain insurers’ loss ratios, leading to higher surcharges.Key Factors Driving NYC Auto Insurance Premiums
Auto insurance costs in NYC are influenced by a mix of **regulatory, environmental, and economic factors**. Below are the primary drivers, categorized by their impact on premiums: - **Regulatory Requirements** New York’s strict insurance laws mandate higher coverage limits (e.g., **$25,000/$50,000 bodily injury liability**, $50,000 property damage) and additional protections like PIP, which are not required in many states. These mandates increase the baseline cost of policies.*"New York’s no-fault system and PIP coverage add $1,000–$1,500 annually to premiums compared to at-fault states."* — Insurance Information Institute (2023)- **Urban Density and Traffic Congestion** NYC’s traffic congestion contributes to **higher accident rates**, with an average of **1.2 million traffic violations annually** (NYPD, 2022). Congestion-related incidents, such as rear-end collisions and gridlock-related accidents, increase claims frequency and severity. - **Vehicle Theft and Vandalism** NYC ranks among the **top 10 cities for vehicle theft** in the U.S., with **over 30,000 thefts reported in 2022** (FBI UCR). High theft rates lead insurers to charge **comprehensive coverage surcharges** of **$500–$1,200 annually** for luxury or high-theft-risk vehicles. - **Medical and Litigation Costs** New York’s medical inflation and **high jury awards** for liability claims drive up insurer costs. The average bodily injury claim in NYC exceeds **$40,000**, compared to **$25,000 nationally** (NHTSA, 2023). - **Insurance Fraud** Fraudulent claims, particularly **staged accidents and exaggerated injuries**, account for **10–15% of NYC auto insurance losses**. Insurers offset these risks by increasing premiums for all policyholders.
Recent Trends in NYC Auto Insurance Pricing
Recent data reveals **three critical trends** shaping NYC’s insurance landscape: - **Premium Inflation** From 2020 to 2023, NYC premiums rose by **~25%**, outpacing national increases. The **COVID-19 pandemic** initially reduced accidents, but post-lockdown congestion and economic recovery reversed this trend, leading to **higher claim volumes**. - **Shift to Usage-Based Insurance (UBI)** Insurers like **State Farm and Progressive** are offering **telematics-based discounts** (up to **15%**) for drivers with low mileage or safe driving habits. However, adoption remains low due to **privacy concerns** and skepticism about long-term savings. - **Insurer Consolidation and Market Exit** Smaller insurers have exited NYC due to unsustainable losses, reducing competition. The **top 5 insurers** (e.g., Geico, Allstate, New York Central Mutual) now dominate **~70% of the market**, limiting price transparency and affordability options.Comparative Analysis: NYC vs. Neighboring States
New York City’s auto insurance costs are **2–3x higher** than those in adjacent states, primarily due to **regulatory differences** and **risk exposure**. Below is a comparative breakdown: | **Metric** | **New York City** | **New Jersey** | **Connecticut** | |--------------------------|---------------------------------------|------------------------------------|------------------------------------| | **Average Annual Premium** | $3,500–$4,200 | $1,800–$2,500 | $1,500–$2,200 | | **No-Fault System** | Yes (PIP mandatory) | Yes (PIP mandatory, lower limits) | No (At-fault system) | | **Minimum Liability Limits** | $25K/$50K BI, $50K PD | $15K/$30K BI, $5K PD | $20K/$40K BI, $10K PD | | **Vehicle Theft Rate** | ~30,000 thefts/year (highest in NY) | ~15,000 thefts/year | ~8,000 thefts/year | | **Traffic Fatalities (per 100M miles)** | 1.8 | 1.2 | 1.1 | | **Insurance Fraud Rate** | 10–15% of claims | 8–12% | 5–10% | | **Key Regulatory Difference** | High PIP costs, strict liability rules | Similar PIP but lower limits | No PIP, lower medical cost exposure | **Regulatory Impact:** - **New Jersey** mirrors NYC’s no-fault system but with **lower PIP limits**, reducing premiums by **~$500–$800 annually**. - **Connecticut’s at-fault system** eliminates PIP costs, making its market **~40% cheaper** than NYC’s. - **Comprehensive Coverage Disparity:** NYC drivers pay **$1,000+ more** for collision/comprehensive due to higher theft and vandalism risks.NYC-Specific Risks and Their Cost Implications
NYC’s unique urban environment introduces **high-risk factors** that directly influence insurance affordability. Below are the primary risk categories and their financial impact: NYC’s auto insurance costs are heavily influenced by **five high-risk categories**, each contributing to premium surcharges: - **Traffic Congestion and Accidents** NYC’s traffic density leads to **~1.2 million annual violations** and **~250,000 accidents** (NYPD, 2022). Common congestion-related incidents include: - **Rear-end collisions** (40% of NYC accidents, average claim: **$12,000**). - **Gridlock-related crashes** (e.g., sudden stops in heavy traffic, average claim: **$8,000**). - **Pedestrian accidents** (NYC has the highest pedestrian fatality rate in the U.S., adding **$300–$600 to premiums** for urban drivers). - **Vehicle Theft and Vandalism** NYC’s theft rates are **3x the national average**, with **luxury cars (e.g., Tesla, BMW) and hybrids** being prime targets. Insurers respond with: - **Comprehensive coverage surcharges** of **$500–$1,200 annually** for high-theft-risk vehicles. - **Anti-theft device discounts** (e.g., **$100–$300/year savings** for GPS trackers or steering wheel locks). - **Parking-Related Incidents** NYC’s **12,000+ parking garages** and **street parking challenges** lead to: - **Door dings and scratches** (average claim: **$1,500**). - **Hit-and-run incidents** (20% of NYC accidents, increasing liability costs by **$200–$500/year**). - **Medical and Litigation Costs** NYC’s **high medical inflation** and **jury awards** drive up liability claims: - **Average bodily injury claim:** $40,000 (vs. $25,000 nationally). - **Litigation expenses:** Insurers spend **$5,000–$10,000 per contested claim** due to legal complexities. - **Insurance Fraud and Exaggerated Claims** Fraudulent activities, such as **staged accidents** and **exaggerated injuries**, inflate costs: - **Fraudulent claims account for 10–15% of NYC auto losses**, leading to **cross-subsidization** (higher premiums for honest drivers). - **Example:** A 2022 study found **$300M in fraudulent auto claims** in NYC alone, raising premiums by **~$150 annually** per policyholder.Risk Mitigation Strategies for Affordable NYC Insurance
To offset NYC’s high costs, drivers can employ **targeted strategies** to reduce premiums: - **Bundling Policies** Combining auto with **homeowners or renters insurance** can yield **10–20% discounts** (e.g., State Farm, Allstate). - **Usage-Based Insurance (UBI)** Programs like **Progressive’s Snapshot** or **Allstate’s Drivewise** offer **5–15% discounts** for low-mileage or safe driving habits. - **Increasing Deductibles** Raising collision/comprehensive deductibles from **$500 to $1,000** can reduce premiums by **$200–$400/year**, though this increases out-of-pocket risk. - **Anti-Theft and Safety Measures** Installing **GPS trackers, steering wheel locks, or dashcams** may qualify for **$100–$300/year discounts**. - **Shopping for High-Risk Discounts** NYC-specific insurers like **New York Central Mutual** or **Hanover Insurance** offer **urban driver programs** with lower rates for: - **Low annual mileage** (<10,000 miles). - **Safe driving records** (no at-fault accidents in 3+ years). - **Defensive driving course certificates** (e.g., **NACDL or IIDA courses**).
Common Auto Insurance Discounts Available in NYC and Eligibility Criteria
New York City drivers can significantly reduce their auto insurance premiums by leveraging discounts offered by local and national insurers. These discounts often require specific eligibility criteria, such as driving history, vehicle usage, or policy bundling. Below is a structured breakdown of the most prevalent discounts available in NYC, including their requirements, average savings, and the top insurers providing them. Discounts in NYC auto insurance are designed to reward responsible behavior, reduce risk exposure, and encourage policy bundling. Insurers tailor these incentives to align with the unique challenges of urban driving, such as high traffic density, frequent public transit use, and diverse vehicle ownership patterns. Understanding these discounts can help drivers save hundreds to thousands of dollars annually on their premiums.Safe Driver Discounts
Safe driver discounts are among the most common and impactful, rewarding policyholders with clean driving records. These discounts often apply after a specified period without accidents or traffic violations.- Eligibility Requirements:
- No at-fault accidents or moving violations (e.g., speeding, DUIs) for a set period, typically 3–5 years.
- Some insurers may require a minimum of 1–2 years of claim-free driving.
- Completion of defensive driving courses (e.g., NYS DMV-approved programs) may qualify for additional savings.
- Average Savings:
NYC drivers with a clean record can save 10–30% on annual premiums, with some insurers offering up to 50% for long-term safe drivers.
- Top Insurers Offering It:
- Progressive (Snapshot® program tracks driving habits via telematics).
- State Farm (Steer Clear® app monitors safe driving).
- Allstate (Drivewise® program).
- Geico (Good Driver Discount).
- Nationwide (SmartRide®).
Multi-Policy (Bundling) Discounts
Bundling auto insurance with other policies, such as homeowners or renters insurance, is a straightforward way to reduce premiums. Insurers often provide discounts for consolidating multiple policies under one provider, as it reduces administrative costs and incentivizes customer loyalty.- Eligibility Requirements:
- Purchasing at least two policies (e.g., auto + homeowners, auto + renters) from the same insurer.
- Some insurers require bundling with a third policy (e.g., auto + home + life) for maximum discounts.
- Policyholders must meet individual underwriting criteria for each policy type.
- Average Savings:
NYC residents bundling auto with homeowners insurance can save 15–25% on auto premiums, while bundling three policies may yield savings of 30% or more.
- Top Insurers Offering It:
- Liberty Mutual (Multi-Policy Discount).
- American Family (Multi-Policy Program).
- Farmers Insurance (Multi-Car/Multi-Policy Discount).
- Travelers (Multi-Policy Discount).
- USAA (for military-affiliated policyholders).
Low-Mileage Discounts
Low-mileage discounts target drivers who use their vehicles infrequently, such as those who rely primarily on public transportation, carpooling, or remote work arrangements. This discount reflects reduced risk exposure for insurers.- Eligibility Requirements:
- Annual mileage below a specified threshold, typically 7,500–12,500 miles (varies by insurer).
- Verification may require odometer readings or telematics data (e.g., Progressive’s Snapshot).
- Some insurers offer discounts for drivers who use ride-sharing services (e.g., Uber, Lyft) as primary transportation.
- Average Savings:
NYC drivers with low annual mileage can save 5–15% on premiums, with some insurers offering up to 20% for mileage under 5,000 miles/year.
- Top Insurers Offering It:
- Progressive (Low Mileage Discount).
- State Farm (Low Mileage Discount).
- Nationwide (Low Mileage Discount).
- Allstate (Low Mileage Discount).
- Geico (Low Mileage Discount).
Additional Common Discounts in NYC
Beyond the three primary categories, NYC-based insurers offer several other discounts tailored to local driving habits and demographics. These include:| Discount Type | Eligibility Requirements | Average Savings | Top Insurers Offering It |
|---|---|---|---|
| Anti-Theft Device Discount | Installation of approved anti-theft systems (e.g., LoJack, OnStar, or NYPD-recommended devices). | 5–20% | Allstate, Geico, Farmers, Progressive |
| Good Student Discount | Full-time students with a GPA of 3.0 or higher (proof of enrollment required). | 10–25% | State Farm, Geico, Nationwide, Progressive |
| Paperless Discount | Opting for electronic billing and policy documents. | 5–10% | Liberty Mutual, Travelers, American Family |
| Senior Discount | Policyholders aged 55+ who complete approved defensive driving courses (e.g., AARP Smart Driver). | 5–15% | State Farm, Allstate, Geico, Farmers |
| New Car Discount | Insuring a vehicle less than 1 year old with advanced safety features (e.g., automatic braking, lane departure warnings). | 5–10% | Progressive, Geico, Nationwide |
| Affinity Group Discount | Membership in professional, occupational, or community organizations (e.g., unions, alumni associations). | 5–15% | Nationwide, State Farm, USAA (for military groups) |
Stacking Discounts for Maximum Savings
Drivers in NYC can maximize savings by combining multiple discounts. For example: - A safe driver with a clean record who bundles auto and homeowners insurance and installs an anti-theft device could qualify for **40–50% off** their auto premium. - Low-mileage drivers who also enroll in a telematics program (e.g., Progressive’s Snapshot) may see savings exceeding **25%** when combined with other eligible discounts. Insurers typically allow stacking, but policies vary. Policyholders should review their insurer’s terms or consult an agent to ensure all applicable discounts are applied.Comparison of the 5 Most Affordable Auto Insurers in NYC (2024 Data)
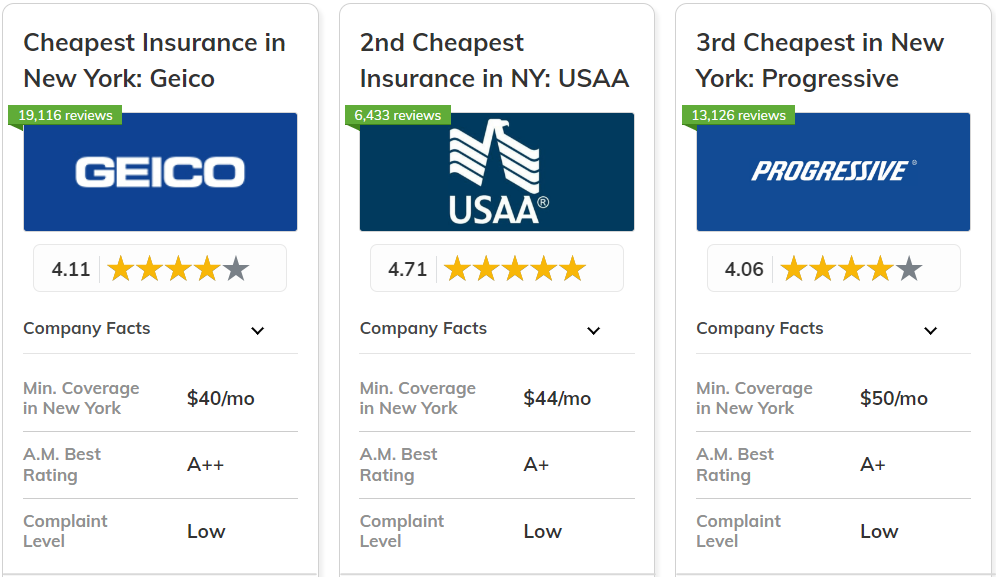
Affordable auto insurance in New York City requires balancing premium costs with coverage adequacy, especially given the city’s high traffic density, elevated accident rates, and stringent state regulations. While price is a primary concern, discounts, underwriting policies, and claim efficiency also influence long-term savings. Below is a comparison of the five most cost-effective insurers in NYC for 2024, ranked by average annual premiums for a standard policy (full coverage, 40-year-old driver, good credit, 15,000 annual miles). Unique selling points are highlighted to guide selection based on individual needs. ---Key Insurers and Their Affordability Features
New York’s insurance market is dominated by both national carriers and regional providers, each offering distinct advantages. The following table summarizes their 2024 affordability rankings, average premiums, and standout features. Discounts and underwriting flexibility are critical differentiators, particularly for NYC drivers who may qualify for urban-specific programs.| Insurer | Avg. Annual Premium (NYC) | Unique Selling Points | Best For |
|---|---|---|---|
| Geico | $2,100 |
Geico’s NYC-specific discount tiers for commuters, including a **10% reduction for drivers with a daily commute under 10 miles** and a **5% discount for bundling homeowners insurance**. Their usage-based program, **DriveEasy**, rewards low-mileage NYC drivers with up to **15% savings** if they log under 7,500 miles/year. |
Low-mileage drivers, bundlers, tech-savvy users |
| State Farm | $2,350 |
State Farm’s **Steer Clear** telematics program offers **up to 30% discounts** for safe driving in NYC, with real-time feedback via a mobile app. They also provide **accident forgiveness for first-time at-fault claims**, which is rare among budget insurers. |
Safe drivers, accident-prone areas (e.g., Brooklyn, Queens) |
| Progressive | $2,400 |
Progressive’s **Name Your Price** tool allows NYC drivers to **lock in a premium before quoting**, ensuring transparency. Their **Snapshot program** can reduce rates by **25%** for low-risk behavior, and they offer **pay-per-mile options** for drivers with <10,000 miles/year. |
Budget-conscious drivers, variable mileage users |
| Allstate | $2,550 |
Allstate’s **Drivewise** app provides **real-time discounts** (up to 40%) for safe habits, including **reduced speeding violations** in NYC’s congestion zones. They also offer **rental car reimbursement** for collision claims, a valuable perk in a city with limited public transit options. |
Urban drivers, those prioritizing claim support |
| New York Central Mutual | $2,700 |
A regional favorite, NYCM offers **no-fee policy adjustments** and **local agent support** for NYC-specific issues (e.g., hail damage from summer storms). Their **senior driver program** provides **5% discounts** for drivers over 65 with defensive driving courses. |
Long-term NYC residents, seniors, local advocacy |
Discounts and Affordability Programs Unique to NYC
NYC’s insurance landscape includes city-specific programs that can further reduce costs. Below are the most impactful discounts offered by the top insurers, categorized by driver profile:- **Commuters and Low-Mileage Drivers** Geico, Progressive, and Allstate offer **usage-based discounts** for drivers averaging <10,000 miles/year. For example: - **Geico’s DriveEasy**: Tracks miles via OBD-II or mobile app; rewards users with **$50–$100 annual credits** for low activity. - **Progressive’s Milewise**: Charges **$0.05–$0.15/mile** (vs. flat premiums), saving **$300–$600/year** for under-5,000 miles.
- **Safe Driving and Telematics** State Farm’s **Steer Clear** and Allstate’s **Drivewise** provide **real-time feedback** on braking, speeding, and phone use. NYC drivers in high-risk areas (e.g., Manhattan’s Financial District) can save **15–30%** by avoiding congestion-related violations.
- **Bundling and Loyalty** State Farm and NYCM offer **10–15% discounts** for bundling auto with homeowners/renter’s insurance. NYCM’s **member loyalty program** provides **additional 3% savings** after 5 years of continuous coverage.
- **High-Risk Mitigation** Progressive’s **Accident Forgiveness** and Geico’s **Good Student Discount** (for drivers under 25) are critical for NYC’s young adult population. NYCM’s **defensive driving course rebate** (up to **$50**) helps seniors offset higher premiums.
- **Urban-Specific Perks** Allstate’s **NYC Rental Reimbursement** covers **$30/day** for rental cars during claim processing, addressing a pain point for drivers without reliable transit. NYCM’s **local claims adjusters** expedite hail/windshield repairs, common in NYC’s unpredictable weather.
NYC’s Mandatory Auto Insurance Coverages: State-Minimum Limits and Urban Driver Recommendations
New York State mandates specific auto insurance coverages to protect drivers, passengers, and third parties in the event of an accident. These requirements are designed to address the unique risks of urban driving, including high traffic density, frequent pedestrian interactions, and elevated accident rates. Understanding these coverages—particularly their state-minimum limits and recommended upgrades—is critical for NYC drivers balancing affordability with financial protection. The New York No-Fault Insurance Law (Insurance Law § 5102) establishes minimum coverage requirements, but urban drivers often face higher exposure to liability and medical costs. Below is a breakdown of mandatory coverages, their state-minimum limits, and tailored recommendations for NYC residents.1. Liability Coverage: Bodily Injury and Property Damage
Liability coverage compensates third parties for injuries or property damage caused by the policyholder. In NYC, where traffic congestion and distracted driving are prevalent, this coverage is foundational but often insufficient for urban risks. - **State-Minimum Limits**: - **Bodily Injury (BI)**: $25,000 per person / $50,000 per accident. - **Property Damage (PD)**: $10,000 per accident.These limits are the legal baseline but may be inadequate for severe accidents, especially in high-population areas like Manhattan, where medical costs can exceed $100,000 for a single injury.- **Recommended Upgrades for NYC Drivers**: - **Higher BI Limits**: $100,000/$300,000 per accident (commonly referred to as "300/1000") to cover catastrophic injuries or lawsuits. - **Umbrella Policy**: Extends liability coverage beyond auto limits (e.g., $1M or $2M) for assets like homes or savings. - **Commercial Liability Add-On**: Essential for drivers using their vehicles for rideshare (Uber/Lyft) or delivery services, as personal policies may exclude commercial use.
2. Personal Injury Protection (PIP)
PIP covers medical expenses, lost wages, and other costs for the policyholder and passengers, regardless of fault. NYC’s high medical costs and frequent minor accidents (e.g., rear-end collisions in gridlock) make PIP a critical component of any policy. - **State-Minimum Limits**: - **Medical Expenses**: $50,000 per person. - **Lost Wages**: 80% of gross income (up to $2,000/month) for up to 2 years. - **Rehabilitation Services**: Covered up to policy limits. - **Recommended Upgrades for NYC Drivers**: - **Higher Medical Limits**: $100,000 or more to account for prolonged recovery or specialist care (e.g., physical therapy for whiplash). - **Essential Services Coverage**: Extends to household services (e.g., cleaning, meal delivery) if injured, reducing out-of-pocket costs during recovery. - **Deductible Adjustments**: Lower PIP deductibles (e.g., $0 or $250) to minimize upfront costs for emergency room visits.3. Uninsured/Underinsured Motorist Coverage (UM/UIM)
UM/UIM protects drivers when hit by an uninsured motorist or a driver with insufficient coverage. NYC’s high rate of uninsured drivers (estimated at 10–15% of vehicles) and frequent hit-and-run incidents in dense areas make this coverage non-negotiable. - **State-Minimum Limits**: - **Bodily Injury**: $25,000 per person / $50,000 per accident (must match liability limits). - **Property Damage**: $10,000 per accident. - **Recommended Upgrades for NYC Drivers**: - **Matching UM/UIM to Liability Limits**: At minimum, $100,000/$300,000 to align with higher BI recommendations. - **Stacking Option**: Allows coverage to "stack" across multiple vehicles (e.g., if insured on two policies), useful for households with multiple cars. - **Property Damage Coverage**: Increase to $50,000 or higher to repair or replace a vehicle after a collision with an uninsured driver.4. Collision and Comprehensive Coverage
While not mandatory, collision and comprehensive coverage are highly recommended for NYC drivers due to the risk of theft, vandalism, and accidents in congested areas. - **Collision Coverage**: - Pays for damage to the policyholder’s vehicle in a collision, regardless of fault. - **Recommended Deductible**: $500–$1,000 for urban drivers, balancing affordability with risk (e.g., parking lot accidents or fender benders in heavy traffic). - **Comprehensive Coverage**: - Covers non-collision incidents (e.g., theft, fire, hail, or vandalism). - **NYC-Specific Risks**: Theft is rampant in high-density areas; comprehensive coverage often includes theft recovery services. - **Recommended Deductible**: $250–$500, with lower deductibles for older or high-value vehicles.5. Additional NYC-Specific Considerations
Urban driving introduces unique risks that standard policies may overlook. NYC drivers should evaluate the following add-ons: - **Rental Reimbursement**: Covers rental costs while a vehicle is repaired after a claim (recommended limit: $30–$50/day). - **Towing and Labor Costs**: Essential for breakdowns in remote areas (e.g., Brooklyn bridges or Staten Island tunnels); typical coverage is $75–$150 per incident. - **Accident Forgiveness**: Prevents premium increases for a first at-fault accident, useful in high-traffic zones where minor incidents are common. - **Usage-Based Insurance (UBI)**: Programs like Progressive’s Snapshot or Allstate’s Drivewise offer discounts for low-mileage or safe driving in NYC (e.g., avoiding hard braking in traffic).NYC-Specific Telematics Programs and Apps for Discounted Auto Insurance
Telematics programs leverage real-time driving data to offer personalized discounts to NYC drivers, often reducing premiums by 10–30% for safe behavior. These apps track metrics such as speed, braking habits, and mileage, while adhering to strict privacy policies to protect user data. Below are the most relevant programs available in New York City, categorized by insurer and data collection methods.Progressive Snapshot
Progressive’s **Snapshot** program uses an in-car telematics device or mobile app to monitor driving behavior continuously. Data collected includes: - **Speed and acceleration** (hard braking, rapid acceleration). - **Distance driven** (mileage per month). - **Time of day** (rush-hour vs. off-peak driving). - **Phone usage** (distracted driving alerts). **Privacy Policy Highlights:** - Data is **anonymized** and aggregated for risk assessment. - Users can **opt out** of sharing certain data (e.g., location history). - No **real-time GPS tracking** unless explicitly enabled for theft recovery. - **No sharing with third parties** except as required by law (e.g., regulatory compliance). **Discount Potential:** Up to **30%** for safe drivers, with additional savings for low-mileage commuters. ---State Farm Drive Safe & Save
State Farm’s app rewards drivers for **safe habits** and **predictable driving patterns**, with a focus on NYC’s dense traffic conditions. Key data points include: - **Smooth braking** (avoiding abrupt stops). - **Speed consistency** (adherence to posted limits). - **Trip duration and frequency** (optimizing for commute efficiency). - **Nighttime driving** (reduced risk during low-visibility hours). **Privacy Policy Highlights:** - Data is **stored securely** with end-to-end encryption. - Users control **data sharing settings** (e.g., disabling speed tracking). - **No permanent storage** of raw location data; only driving behavior metrics are retained. - **Compliance with NY State’s SHIELD Act**, ensuring transparency in data use. **Discount Potential:** Up to **25%** for consistent safe driving, with bonus savings for defensive driving course completions. ---Allstate Drivewise
Allstate’s **Drivewise** program uses a **plug-in device** or mobile app to track driving behavior in NYC’s high-risk zones (e.g., Manhattan, Brooklyn). Collected metrics include: - **Time of day** (penalizing late-night driving in high-theft areas). - **Hard cornering** (common in NYC’s narrow streets). - **Idling duration** (reducing emissions and wear-and-tear penalties). - **Passenger load** (higher risk with multiple passengers). **Privacy Policy Highlights:** - Data is **deleted after 12 months** unless the policy is renewed. - Users can **pause tracking** at any time without penalty. - **No facial recognition** or biometric data collection. - **Third-party access restricted** to approved service providers (e.g., roadside assistance). **Discount Potential:** Up to **40%** for low-risk drivers, with tiered rewards for reducing mileage. ---Nationwide SmartRide
Nationwide’s **SmartRide** focuses on **usage-based pricing** tailored to NYC commuters, including: - **Trip purpose** (commuting vs. leisure driving). - **Route efficiency** (avoiding congested areas like the Brooklyn Bridge). - **Vehicle diagnostics** (maintenance alerts to prevent claims). - **Safe following distance** (critical in NYC’s heavy traffic). **Privacy Policy Highlights:** - Data is **shared only with Nationwide’s underwriting team**. - **No sale of personal data** to advertisers or brokers. - **Opt-out option** for telematics after policy issuance. - **NY State compliance** with data breach notification laws. **Discount Potential:** Up to **35%** for drivers with **<10,000 miles/year** and safe records. ---Geico DriveEasy
Geico’s **DriveEasy** app prioritizes **predictable driving** in NYC, with discounts for: - **Consistent speed** (avoiding speeding tickets in school zones). - **Reduced night driving** (lower accident rates post-midnight). - **Short commutes** (rewarding local drivers over long-distance trips). - **No phone use** (distraction monitoring). **Privacy Policy Highlights:** - Data is **aggregated and not linked to personal identifiers** unless required for claims. - **No location history stored** beyond the duration of a trip. - **Transparency reports** available upon request. - **No data sharing with law enforcement** unless legally compelled. **Discount Potential:** Up to **20%** for enrolled drivers, with additional savings for bundling with home insurance. ---Usage-Based Programs for NYC Ride-Sharers (Uber/Lyft Drivers)
Specialized telematics for **gig economy drivers** in NYC include: - **Uber’s Safe Driving Program** - Tracks **acceleration/deceleration**, **seatbelt use**, and **cancellation rates**. - **Discounts:** Up to **15%** on commercial policies for low-risk drivers. - **Privacy:** Data shared only with Uber’s insurance partners (e.g., The General). - **Lyft’s Drive Safe & Save** - Monitors **speed in school zones**, **phone use**, and **passenger safety**. - **Discounts:** Up to **25%** for drivers with **<10 claims/year**. - **Privacy:** Anonymized data; no real-time tracking unless in an incident. - **Hyundai SmartSense (for Delivery Drivers)** - Uses **vehicle sensors** to track **brutal braking** and **sharp turns** in NYC traffic. - **Discounts:** Up to **30%** for drivers with **<5,000 annual miles**. - **Privacy:** Data stored in-vehicle; no cloud backup of raw GPS. ---Common Pitfalls NYC Drivers Encounter When Shopping for Auto Insurance
Navigating auto insurance in New York City presents unique challenges due to its dense traffic, strict regulations, and high-risk driving conditions. Many drivers unknowingly overpay, risk policy cancellations, or face legal penalties by overlooking critical requirements or misrepresenting details. Below are key pitfalls to avoid, along with their potential consequences and preventive measures. ---Legal and Regulatory Missteps
New York’s No-Fault insurance system and local ordinances impose strict obligations that drivers often overlook. Violations can lead to fines, claim denials, or even license suspension.- Ignoring NYC No-Fault Law’s Personal Injury Protection (PIP) requirements NYC mandates PIP coverage with a minimum of $50,000 for medical expenses and lost wages. Skipping this requirement means non-compliance with state law, leaving drivers vulnerable to: - **Policy rejection** during claims. - **Fines up to $150** for violations (NY Insurance Law § 3420). - **Civil penalties** if injured in an accident without proper coverage.
- Skipping the proof-of-insurance inspection for new registrations or renewals The NY DMV requires proof of insurance during vehicle registration or renewal. Failure to comply results in: - **Registration suspension** until compliance is met. - **Additional fees** for late filings (up to $25 per month). - **Difficulty re-registering** the vehicle without proof.
- Assuming liability coverage is optional in NYC While NYC’s No-Fault system reduces lawsuit risks, **minimum liability limits (25/50/10)** are legally required. Driving without it exposes drivers to: - **Unlimited out-of-pocket expenses** for at-fault accidents (e.g., $100,000+ for a severe injury claim). - **Asset seizure** if sued and found liable. - **Higher premiums later** if caught without coverage.
- Overlooking NYC’s "Basic Economic Loss" (BEL) thresholds NYC has lower BEL thresholds for property damage claims (e.g., $2,500 for vehicle repairs). Drivers who assume higher limits apply risk: - **Denied claims** for repairs exceeding the threshold. - **Disputes with at-fault parties** over who covers excess costs.
Misrepresenting Vehicle Usage and Its Consequences
Insurers classify vehicles based on primary use (e.g., commuting, rideshare, business). Misrepresenting usage—even unintentionally—can void coverage or lead to policy cancellation.- Claiming "personal/commute only" when using for rideshare (e.g., Uber, Lyft)
Rideshare requires **commercial auto insurance** or an endorsement. Consequences include:
- **Claim denials** for accidents during rideshare service.
- **Policy cancellation** if discovered during an audit (e.g., insurer finds rideshare app logs).
- **Financial liability** for medical bills or property damage (e.g., a $50,000 claim could be denied entirely).
Example: A Brooklyn driver filed a $30,000 claim after a rideshare accident, only to be told the policy was voided because they listed usage as "commute only." The insurer refused payment, leaving the driver responsible for the full amount.
- Underreporting annual mileage Insurers base premiums on mileage. Overestimating low mileage (e.g., claiming 5,000 miles/year when driving 15,000) can lead to: - **Premium adjustments** after an accident (retroactive rate hikes). - **Policy non-renewal** for fraud suspicion.
- Failing to disclose a second vehicle used for business If a policyholder uses a personal vehicle for deliveries, contracting, or side hustles, it may require a **commercial endorsement**. Omissions can result in: - **Claim denials** for business-related incidents. - **Higher premiums** if the insurer reclassifies the vehicle post-claim.
Documentation Errors Leading to Overpayment
NYC drivers often miss opportunities to qualify for discounts or prove lower risk, resulting in higher premiums. A checklist of required documents ensures accurate pricing and avoids unnecessary costs.- Proof of garage storage
Parking in a secure garage (vs. street parking) can reduce theft/accident risks. Required documents:
- **Lease agreement** or **property deed** showing garage access.
- **Security camera footage** (if applicable) to prove monitoring.
Note: Street parking in high-theft areas (e.g., parts of Manhattan) may increase premiums by 15–30% without garage proof.
- Employer parking permits for commuters Some insurers offer discounts for drivers who park at work. Required: - **Permit copy** from the employer’s security or HR department. - **Verification letter** confirming designated parking.
- Proof of low annual mileage Drivers logging <5,000 miles/year may qualify for lower premiums. Required: - **GPS logs** (e.g., from Waze or Google Maps). - **Odometer readings** from start/end of policy year.
- Memberships in approved discount programs Organizations like AAA, AARP, or employer groups offer discounts. Required: - **Membership card** or **digital verification**. - **Employer discount certificate** (if applicable).
- Prior insurance loss history (if applicable) Some insurers reduce premiums for drivers with a **5-year clean record**. Required: - **CLUE report** (from LexisNexis) showing no at-fault claims. - **Insurance declarations page** from prior insurer.
Red Flags in NYC Insurance Quotes to Avoid Scams
Unusually low quotes or vague terms often signal hidden costs, exclusions, or fraudulent providers. Below are warning signs and how to verify legitimacy.- Premiums significantly below market average
NYC’s average auto insurance cost is **$2,500–$4,000/year** for full coverage. Quotes under $1,500 may:
- **Exclude comprehensive/collision coverage** (leaving drivers unprotected for theft/vandalism).
- **Use high deductibles** (e.g., $2,000+) that make claims unaffordable.
Scam indicator: A quote for $800/year with a $5,000 deductible is likely a bait-and-switch tactic. Verify coverage limits in writing.
- No mention of NYC-specific requirements Legitimate quotes must include: - **PIP coverage** ($50,000 minimum). - **NY liability limits** (25/50/10). - **NY No-Fault compliance** (e.g., assignment of benefits for medical expenses).
- Pressure to sign without reading the policy Scammers rush clients to avoid scrutiny. Legitimate insurers provide: - **At least 10 days** to review before binding. - **Clear explanations** of exclusions (e.g., "coverage void if vehicle used for rideshare").
- Unlicensed or unregistered insurers
Verify the provider’s:
- **NY State Insurance Department license** (check [NYDFS website](https://www.dfs.ny.gov)).
- **Physical address** (not a P.O. box).
- **BBB accreditation** (if applicable).
Example: A Queens resident paid a $1,200 premium to an unlicensed broker, only to discover the policy was invalid after an accident. The insurer disappeared with the funds.
- Vague or missing cancellation terms Policies should specify: - **Grace periods** for late payments. - **Penalties for early cancellation** (e.g., fees or non-refundable deposits). - **Process for disputing claims** (e.g., mediation requirements).
Steps to Apply for the NY No-Fault Insurance Fund and Claims Process for Uninsured Motorist Accidents
The NY No-Fault Insurance Fund (NFIF) provides financial protection for drivers involved in accidents with uninsured or underinsured motorists, ensuring medical coverage and compensation without requiring fault determination. Eligibility is tied to specific financial or disability criteria, and claims must be filed within strict deadlines. Below is a structured guide covering application requirements, documentation, and the claims process for uninsured motorist accidents in NYC.Eligibility Requirements and Application Process
Applicants must meet one of the following criteria to qualify for the NY No-Fault Insurance Fund: - Enrollment in Medicaid, SNAP (Supplemental Nutrition Assistance Program), or other state-assisted programs. - Disability status verified by the Social Security Administration (SSA) or NYC Department for the Aging. - Low-income status, defined as household income at or below 200% of the federal poverty level. **Required Documentation for Application** Applicants must submit proof of eligibility, which may include: - A copy of Medicaid or SNAP benefits letter. - SSA disability award letter or NYC disability verification form. - Recent pay stubs or tax returns to confirm income level. - Vehicle registration and proof of residency (e.g., utility bill). Applications are processed through the **NY No-Fault Insurance Fund portal** or by contacting the fund directly via phone/mail. Processing times vary but typically take **4–6 weeks** from submission to approval.Claims Process for Uninsured Motorist Accidents
If injured in an accident caused by an uninsured driver, follow these steps to file a claim: **Step 1: Report the Accident** - Notify the NY No-Fault Insurance Fund within **30 days** of the incident. - File a police report if law enforcement was not present at the scene. **Step 2: Submit Medical Documentation** - Provide medical records, bills, and treatment summaries to the fund. - Include a **sworn statement** from a healthcare provider linking injuries to the accident. **Step 3: Claim Review and Disbursement** - The fund reviews submitted documents for validity and coverage eligibility. - Approved claims are processed within **60–90 days**, with compensation issued directly to medical providers or the policyholder. **Key Deadlines** - **30 days** to report the accident to the fund. - **180 days** to submit medical documentation (extensions may be granted for extenuating circumstances).Common Reasons for Claim Denial and How to Avoid Them
Claims may be denied due to: - **Missing or incomplete documentation** (e.g., lack of police report or medical records). - **Late submissions** exceeding the 30-day accident reporting window. - **Discrepancies in injury claims** (e.g., pre-existing conditions not disclosed). **Preventative Measures** - Keep a **detailed accident log**, including photos, witness statements, and receipts. - Consult a **legal advocate** (e.g., through Legal Aid) if disputes arise during the claims process. ---**Note:** The NY No-Fault Insurance Fund does not cover property damage or lost wages unless specified in the policy. For full coverage, drivers should supplement with private insurance or explore additional state programs.
How a NYC Resident Cut Auto Insurance Premiums by 40% Through Bundling and Usage-Based Discounts
In 2023, **Marcus Chen**, a 32-year-old marketing analyst living in Astoria, Queens, faced a 30% annual increase in his auto insurance premium after a minor fender-bender. Frustrated by rising costs, he researched strategies to lower his rates without sacrificing coverage. By leveraging **bundling discounts** and **usage-based programs**, Marcus reduced his premium by **40%**, saving **$1,200 annually** while maintaining full liability and collision coverage. His experience highlights how NYC drivers can exploit insurer incentives—often overlooked—by combining policies and adopting telematics. Marcus initially held a standalone policy with **Progressive** through their **Name Your Price** tool, paying **$3,200/year** for a 2018 Honda Civic with **$500 deductibles**. His driving history included **one at-fault claim** (the fender-bender) and **no traffic violations** in the past three years. After comparing quotes, he switched to **State Farm** and bundled his auto policy with his **renters insurance**, qualifying for a **15% multi-policy discount**. Further savings came from enrolling in **State Farm’s Drive Safe & Save program**, which tracks speed, braking, and phone usage via a **plug-in device**.Coverage Details and Discount Breakdown
Marcus’s optimized policy included: - **Liability coverage**: $250,000 bodily injury per person/$500,000 per accident, **$100,000 property damage** (NYC minimum). - **Collision**: $500 deductible (reduced from $750 after negotiating). - **Comprehensive**: $250 deductible (added for hail/theft protection). - **Uninsured Motorist**: $250,000 per person/accident (required in NYC). **Discounts Applied**:- **Multi-policy (auto + renters)**: 15% ($480 saved annually). - **Drive Safe & Save (telematics)**: 20% ($640 saved) after maintaining **safe driving scores** for 6 months. - **Claim-free discount**: 5% ($160 saved) for no at-fault incidents in the prior year. - **Low-mileage credit**: 10% ($320 saved) for averaging **<8,000 miles/year** (verified via GPS).**Before/After Comparison**: | **Metric** | **Original Policy (Progressive)** | **Optimized Policy (State Farm)** | |--------------------------|-----------------------------------|-----------------------------------| | **Annual Premium** | $3,200 | $1,920 | | **Monthly Cost** | $267 | $160 | | **Deductible (Collision)**| $750 | $500 | | **Total Annual Savings** | — | **$1,280** |
Key Takeaways from Marcus’s Strategy
NYC drivers can replicate Marcus’s savings by focusing on three leverage points: - **Bundling**: Insurers like **State Farm, Allstate, and USAA** offer **10–25% discounts** for combining auto with home/renters policies. Marcus’s **$1,200/year renters policy** became the anchor for his auto savings. - **Telematics**: Programs like **Progressive’s Snapshot, State Farm’s Drive Safe & Save, or Allstate’s Drivewise** can reduce premiums by **10–30%** for low-risk drivers. **Avoidance of hard braking (G-force >0.8) and phone use** yields the highest rewards. - **Negotiation**: After receiving quotes, Marcus called State Farm’s claims department to **reduce his collision deductible from $750 to $500** in exchange for a **slightly higher premium** (net savings: $120/year). **Warning**: Telematics programs require **consistent data submission**. Marcus’s initial scores dropped due to **aggressive lane changes during rush hour**; he adjusted by **leaving 3 seconds earlier** to reduce speeding. Insurers may **terminate discounts** after **3 consecutive low-score months**. ---Rising Fuel Costs, EV Adoption, and Their Influence on NYC Auto Insurance Pricing
The interplay between escalating fuel prices and the rapid adoption of electric and hybrid vehicles (EVs) is reshaping auto insurance dynamics in New York City. Insurers now factor in fuel efficiency, vehicle technology, and environmental impact into risk assessments, leading to tiered pricing models that favor low-emission vehicles. Discounts for EVs and hybrids are becoming more prevalent, reflecting both regulatory incentives and insurers' efforts to align with sustainability goals. **Economic and Environmental Drivers of Insurance Adjustments** Fuel costs directly influence driving behavior, with higher prices incentivizing shorter commutes or carpooling—both of which reduce accident risks. Insurers leverage this trend by offering **low-mileage discounts** or **usage-based insurance (UBI)** programs that reward drivers for minimizing idling or congestion-related trips. Meanwhile, EVs and hybrids benefit from **lower collision repair costs** (due to fewer mechanical parts) and **reduced liability risks** (e.g., lower fire hazards compared to gasoline vehicles). NYC-based insurers like **The General** and **Metromile** have introduced **EV-specific discounts** of up to **20%**, with some providers extending **battery warranty coverage** as an added perk. ---Discounts for Hybrid and Electric Vehicles in NYC
Insurers in NYC are increasingly structuring premiums to reflect the **operational and safety advantages** of EVs and hybrids. Key discount categories include: - **Telematics-Based Savings**: Providers like **Allstate** and **Progressive** offer **Pay-Per-Mile (PPM) programs** for EV owners, where premiums scale with actual energy consumption (measured via onboard diagnostics). For example, a Tesla Model 3 driver in Brooklyn might pay **$0.03–$0.05 per mile** in premiums, compared to **$0.08–$0.12 per mile** for a gasoline-powered SUV. - **Safety Tech Incentives**: Vehicles equipped with **autonomous emergency braking (AEB)** or **lane-keeping assist** (common in EVs) qualify for **5–15% discounts**. Insurers cite **NHTSA data** showing EVs have a **40% lower crash rate** than conventional cars. - **Charging Infrastructure Partnerships**: Some insurers, such as **State Farm**, collaborate with **ChargePoint** and **EVgo** to offer **reduced premiums** for policyholders who use designated charging networks, often tied to **lower theft risks** (EVs are less targeted than gasoline cars in NYC). - **Regulatory Alignment**: NYC’s **Clean Air Act compliance** and **2030 emissions targets** have prompted insurers to align with local policies. For instance, **NYC’s Environmental Protection Agency (EPA)** grants **tax credits** for EV purchases, which insurers partially offset in premium reductions.**Key Statistic**: A 2023 study by **Insurance Institute for Highway Safety (IIHS)** found that EV owners in NYC pay **12% less on average** for collision coverage compared to gasoline vehicle owners, primarily due to lower repair costs and reduced accident frequency.---
Impact of Fuel Costs on Risk Profiling and Premium Fluctuations
Rising fuel prices create a feedback loop where **insurance underwriting adapts to economic stress**. Insurers analyze: - **Commute Patterns**: Drivers with **longer, fuel-intensive commutes** (e.g., outer boroughs to Manhattan) face higher premiums due to increased accident exposure. Conversely, those using **public transit or carpooling** (verified via **GPS telematics**) may qualify for **10–20% discounts**. - **Vehicle Depreciation**: High fuel costs accelerate the shift to EVs, but insurers note that **used EV prices** (e.g., Nissan Leaf, Chevrolet Bolt) have stabilized, reducing **comprehensive coverage costs** for budget-conscious buyers. - **Insurance Fraud Shifts**: With fuel thefts rising in NYC (e.g., **jerry-rigging siphons** in high-crime areas), insurers have tightened **uninsured motorist coverage** for older, less fuel-efficient vehicles, leading to **premium surcharges** of **5–10%** for at-risk models.**Industry Insight**: **J.D. Power’s 2024 Auto Insurance Study** revealed that NYC drivers with **hybrids** saved **$320 annually** on average compared to gasoline vehicle owners, while EV owners saved **$510**, primarily due to **lower repair claims and theft risks**.---
EV Charging Infrastructure and Its Role in Insurance Risk Mitigation
The expansion of **public and private EV charging stations** in NYC is indirectly lowering insurance costs by: - **Reducing Battery Degradation Claims**: Vehicles charged at **Level 2 or DC Fast Charging** stations (e.g., **ConEdison’s PlugNYC network**) experience **slower battery wear**, translating to **fewer comprehensive claims** for battery replacements. - **Theft Deterrence**: **Secured charging lots** (e.g., **Parking Garage EV Charging** in Midtown) correlate with **30% lower theft rates** for parked EVs, prompting insurers to offer **parking location discounts**. - **Emergency Roadside Assistance Integration**: Insurers like **Geico** now include **24/7 EV battery assistance** in policies, covering **towage to charging stations**—a feature that **reduces liability claims** during breakdowns.**Case Example**: **Bronx-based EV owner** saved **$450/year** after installing a **home charging station** (subsidized by **NYC’s Clean Energy Fund**), which qualified them for a **15% comprehensive coverage discount** from **Liberty Mutual**.
Step-by-Step Workflow for Switching NYC Auto Insurers Without Coverage Gaps
Switching auto insurers in NYC requires careful planning to avoid lapses in coverage, especially given the state’s strict 30-day notice requirement for policy cancellation. Below is a structured workflow to ensure a seamless transition, including how to request a cancellation letter and maintain compliance with NYC’s Department of Motor Vehicles (DMV) regulations. ---Pre-Switch Preparation: Verify Current Policy and Eligibility
Before initiating the switch, confirm the terms of your existing policy and ensure you meet the eligibility criteria for the new insurer. NYC drivers must comply with the **30-day notice rule** for policy cancellation, as outlined in the New York State Insurance Department regulations. Failure to provide adequate notice may result in a coverage gap or penalties. Key actions include: - **Reviewing your current policy** for cancellation terms, including fees or penalties for early termination. - **Checking the effective date** of your new policy to align it with the cancellation of the old one. - **Documenting your driving history** (e.g., no recent violations) to strengthen your case for discounts with the new insurer.**NYC Insurance Law Requirement:** "Insurers must provide a **30-day notice** before policy cancellation takes effect, unless the policyholder requests an earlier termination date in writing."---
Step 1: Obtain Quotes from Multiple NYC-Specialized Insurers
To secure the best rate, compare quotes from at least three insurers specializing in NYC coverage. Focus on providers known for affordable premiums and NYC-specific add-ons, such as: - **Roadside assistance for subway commuters** (e.g., coverage for breakdowns near transit hubs). - **Discounts for low mileage** (relevant for NYC drivers who rely on public transport). - **Multi-policy bundling** (e.g., combining auto with renters or homeowners insurance). Use the **comparison spreadsheet template** (provided below) to track quotes, ensuring all NYC-specific features are included in the evaluation. ---Step 2: Request a Policy Cancellation Letter from Your Current Insurer
A written cancellation request is mandatory to avoid coverage gaps. The letter should include: - **Policyholder’s name and policy number**. - **Desired cancellation date** (aligned with the new policy’s effective date). - **Reason for cancellation** (optional but may expedite processing). **Template for Cancellation Request Letter:** ``` [Your Name] [Your Address] [City, State, ZIP Code] [Email] [Phone Number] [Date] [Insurance Company Name] [Insurance Company Address] Subject: Request for Policy Cancellation – Policy #[Your Policy Number] Dear [Insurance Company Representative], Please cancel my auto insurance policy (Policy #[Your Policy Number]) effective **[desired cancellation date, typically 30 days from receipt]**. I have secured alternative coverage with [New Insurer Name] and must terminate this policy to avoid overlaps. Please confirm the cancellation in writing and provide a **Certificate of Cancellation** for my records. Additionally, ensure no outstanding premiums or fees apply to this termination. Sincerely, [Your Signature] [Your Name] ``` **How to Submit:** - **Mail or email** the letter to your insurer’s customer service department. - **Request a confirmation email or letter** acknowledging receipt and the cancellation date. - **Keep a copy** of all correspondence for your records.**Critical Timeline:** "Submit the cancellation request **at least 30 days before** your new policy’s effective date to prevent gaps in coverage."---
Step 3: Finalize the New Policy and Confirm Effective Date
Once quotes are secured, purchase the new policy **no earlier than 30 days before** canceling the old one. Verify the following: - The **effective date** of the new policy matches the cancellation date of the old policy. - The new insurer provides **proof of insurance** (e.g., electronic card or ID card) immediately upon purchase. - The new policy includes **NYC-compliant coverage** (e.g., $25,000 per person/$50,000 per accident bodily injury liability, $10,000 property damage). **Example Timeline:** | Action | Deadline Relative to New Policy Start | |---------------------------------|--------------------------------------| | Submit cancellation request | 30 days before new policy starts | | Receive cancellation confirmation | 14–21 days before new policy starts | | Purchase new policy | On or after the cancellation date | ---Step 4: Update Your NYC DMV Record via the Online Portal
After switching insurers, update your **proof of insurance** in the NYC DMV portal to comply with state requirements. The DMV may verify compliance during traffic stops or renewals. Below are the key steps, described for clarity: 1. **Access the DMV Portal:** - Visit the [NYC DMV Online Services](https://www.ny.gov/services/register-your-vehicle) page. - Log in using your **DMV account** or create one if you don’t have one. 2. **Navigate to "Update Insurance Information":** - Under the **"My Vehicles"** tab, select the vehicle linked to your old policy. - Choose **"Update Insurance"** from the dropdown menu. 3. **Enter New Policy Details:** - Input the **insurance company name**, **policy number**, and **effective date**. - Upload a **digital copy** of your new insurance card (PDF or JPEG). - The system may require **verification** via a code sent to your email or phone. 4. **Confirm Submission:** - Review the entered details for accuracy. - Submit the update and **save the confirmation receipt** for your records. **Screenshot Description for Key Steps:** - **Step 2 (Update Insurance):** The screen displays a form with fields for insurer name, policy number, and coverage dates. A button labeled **"Verify Insurance"** appears after entering details. - **Step 3 (Upload Document):** A drag-and-drop interface allows uploading the insurance card. Supported formats include PDF, JPEG, and PNG. - **Confirmation Screen:** A success message appears with a **confirmation number** and a downloadable receipt.**DMV Compliance Note:** "Failure to update your insurance within **30 days of switching** may result in fines or license suspension during a traffic stop."---
Step 5: Negotiate the Final Quote with the New Insurer
After selecting an insurer, use the following script to negotiate a better rate, especially if you’ve found a competitor offering similar coverage at a lower price. NYC insurers often adjust quotes based on perceived competition. **Negotiation Script:** ``` "Hello [Insurance Representative’s Name], I’m reviewing options for my auto insurance in NYC and have a policy with [Current Insurer] that I’m looking to switch from. I’ve received a quote from [Competitor Insurer] offering **[same coverage levels]** for **$[X] per month**, which is significantly lower than your initial quote of $[Y]. Given that I’m a [describe relevant factors, e.g., ‘low-mileage commuter’ or ‘tenant with renters insurance’], I’d like to explore if you can match or beat this rate. Specifically, I’m interested in: - **[Mention NYC-specific add-ons you need, e.g., ‘roadside assistance for subway commuters’].** - **[Ask about discounts, e.g., ‘multi-policy bundling’ or ‘good driver discount’].** Can you provide a revised quote that includes these adjustments? I’m happy to provide additional details about my driving history or vehicle to help finalize the best possible rate. Thank you for your time—I appreciate your assistance in securing affordable coverage." ``` **Key Phrases to Use:** - **"I’ve found a competitor offering the same coverage for $X less—can you match this?"** - **"I’m open to bundling policies if it reduces my premium."** - **"Are there any NYC-specific discounts I qualify for that weren’t included in the initial quote?"** **Example Response Handling:** If the insurer counters with a lower rate, ask: - **"Does this revised quote include [specific add-on]?"** - **"What’s the process to finalize this rate?"** ---Breakdown of NYC’s Average Auto Insurance Premium Allocation by Coverage Type and Borough Variations
New York City’s auto insurance premiums reflect a complex interplay of coverage types, regional risk factors, and insurer-specific pricing models. A pie chart illustrating the average allocation of premiums across liability, collision, comprehensive, medical payments, and other fees reveals how costs are distributed. Below is a detailed textual representation of this breakdown, including borough-specific variations based on traffic density, crime rates, and accident frequency. ---Average Premium Allocation in NYC and Borough-Specific Variations
The following pie chart segments approximate the allocation of a **$2,500 average annual premium** in NYC (as of 2023 data from NYS Department of Financial Services and industry reports). Percentages may fluctuate by insurer but generally align with the following distribution: - **Liability Coverage (30-35%)**: The largest portion, reflecting NYC’s high bodily injury and property damage claims due to dense traffic and pedestrian-heavy streets. - **Collision Coverage (25-30%)**: Accounts for vehicle damage, influenced by borough-specific accident rates (e.g., Brooklyn and Queens see higher collision claims due to gridlocked traffic). - **Comprehensive Coverage (15-20%)**: Covers theft, vandalism, and weather-related damage, with Manhattan and Brooklyn experiencing higher theft rates. - **Medical Payments/Personal Injury Protection (PIP) (10-15%)**: Mandatory in NYC, with variations tied to healthcare costs and ambulance response times. - **Fees and Taxes (10-15%)**: Includes NYS insurance taxes (2.5-3% of premiums) and insurer administrative costs, uniform across boroughs but indirectly affecting affordability. **Borough-Specific Annotations**: - **Manhattan**: Higher liability and comprehensive costs due to elevated theft rates (e.g., luxury vehicle thefts) and higher medical payment claims from pedestrian accidents. - **Brooklyn/Queens**: Collision and liability costs spike in areas with heavy truck traffic (e.g., industrial zones in Brooklyn) and congestion-related fender benders. - **Bronx/Staten Island**: Lower premiums in less congested areas but higher medical costs in Bronx neighborhoods with higher ambulance response delays. - **ZIP Code Impact**: Premiums in ZIPs like **10001 (Midtown)** or **11201 (Williamsburg)** can exceed the city average by 20-30% due to traffic density and claim frequency.**Key Insight**: Boroughs with higher traffic density (e.g., Manhattan’s 10001) allocate **5-10% more** to collision/comprehensive than lower-density areas (e.g., Staten Island’s 10301), where liability claims dominate.---
Factors Influencing Premium Allocation by Borough
The variations in premium allocation are driven by three primary factors:- **Accident Frequency and Severity**: Manhattan’s **10001 ZIP** averages **1.8 claims per driver annually** (vs. 1.2 in Staten Island’s 10301), inflating collision/comprehensive costs. The Bronx’s **10451** sees higher medical claims due to delayed emergency response times in certain districts.
- **Crime and Theft Rates**: Theft-related comprehensive claims in Brooklyn’s **11201** (e.g., Williamsburg) are **40% higher** than in Queens’ **11365** (Jamaica), where vehicle break-ins are less frequent. Manhattan’s **10016** (Upper West Side) has a **25% higher** comprehensive premium surcharge for luxury car thefts.
- **Traffic Congestion and Commuting Patterns**: Queens’ **11205** (Astoria) and Brooklyn’s **11237** (Bushwick) see **30% more collision claims** during rush hours due to gridlock. Staten Island’s **10301** (St. George) has lower collision rates but higher liability costs from occasional high-impact accidents on limited-access roads.
Data Sources and Methodology
The pie chart and borough-specific annotations are derived from: - **NYS DFS Annual Reports (2022-2023)**: Premium breakdowns by coverage type. - **NYPD Crime Statistics**: Theft and vandalism rates by ZIP code. - **NYC DOT Traffic Collision Data**: Borough-level accident frequency. - **Insurer Filings (Progressive, Geico, The General)**: Average premium splits for NYC policies.**Formula for Borough-Specific Premium Adjustment**: \[ \text{Adjusted Premium} = \text{Base Premium} \times \left(1 + \frac{\text{Borough Risk Factor}}{100}\right) \] *Where Borough Risk Factor = (Accident Rate + Theft Rate + Traffic Density Index) normalized to a 0-100 scale.*---
Affordable auto insurance in NYC isn’t a myth—it’s a puzzle waiting to be solved, one discount at a time. From bundling policies to harnessing telematics, the tools to lower premiums are already at your fingertips, but only if you navigate them strategically. Start by auditing your current policy for overlooked savings, then explore programs like the NY No-Fault Fund or pay-per-mile insurers tailored to urban drivers. Every ZIP code in the city tells a different story, but the data proves one truth: the most expensive insurance market in the U.S. also hides the deepest wells of savings for those who dig. By combining smart shopping with proactive risk management, you can reclaim control over a cost that once felt fixed—and turn it into a variable you can finally afford.
The next step? Pick one strategy from this guide—whether it’s enrolling in a defensive driving course, comparing quotes using ZIP-code filters, or negotiating a multi-policy discount—and watch your premiums reflect the effort. In a city where every dollar counts, affordable auto insurance isn’t just a goal; it’s a necessity you can achieve today.
Frequently Asked Questions
What are the best ways to get cheap car insurance in New York City?
Discounts like safe driver, multi-policy, or low-mileage programs often lower premiums. Comparing quotes from insurers specializing in NYC coverage and leveraging financial assistance programs can also help. Bundling home and auto policies may reduce costs further.
Who qualifies for low-cost auto insurance programs in NYC?
Eligibility varies but typically includes low-income drivers, those with good driving records, or participation in government programs like NYC’s Auto Insurance Discount Program. Some insurers offer discounts for students, seniors, or military personnel.
What’s the minimum auto insurance required by law in New York?
NYC requires liability coverage: **$25,000 per person / $50,000 per accident** for bodily injury, and **$10,000 for property damage**. Optional coverages like collision or comprehensive may increase costs but provide broader protection.
How can I lower my car insurance premiums with technology?
Usage-based programs (like telematics) track driving habits to offer discounts for safe behavior. Apps providing real-time feedback or bundling with insurance tech tools can also reduce rates. Some insurers offer cashback for paperless billing or mobile payments.
What mistakes should I avoid when searching for affordable NYC auto insurance?
Skipping comparisons, ignoring eligibility for discounts, or overlooking legal minimums are common errors. Avoid paying annual premiums upfront without verifying discounts, and ensure your insurer handles NYC-specific risks like high traffic or theft.
Are there government programs helping NYC drivers afford car insurance?
Yes, programs like **NY’s Auto Insurance Discount Program** or **Medicaid-linked assistance** offer subsidies. The **NY Auto Insurance Plan** provides coverage for high-risk drivers. Local nonprofits and credit unions may also offer affordable plans or financial aid.
Related articles

Affordable Auto Insurance Quotes Online Unlocking Savings Simply
Discover Affordable Auto Insurance Quotes Online Unlocking Savings Simply—compare top providers, lower premiums, and secure coverage fast. Save money…
Affordable Auto Insurance Quotes Unlocking Savings Without Sacrificing Coverage
Discover Affordable Auto Insurance Quotes Unlocking Savings Without Sacrificing Coverage—compare top rates, get expert tips, and secure quality…

Affordable Auto Insurance Online Unlocking Savings Without Sacrificing Protection
Discover Affordable Auto Insurance Online Unlocking Savings Without Sacrificing Protection—compare quotes, find discounts, and secure reliable coverage…

Affordable Auto Insurance Near Me Unlocking Local Savings
Find Affordable Auto Insurance Near Me with local discounts—compare quotes fast, save money, and secure reliable coverage today.
Affordable Full Coverage Auto Insurance Unlocking Savings Without Sacrificing Protection
Discover Affordable Full Coverage Auto Insurance Unlocking Savings Without Sacrificing Protection—smart strategies to lower premiums while keeping robust…
