Planning a single-day event—whether a wedding, corporate launch, or community festival—carries inherent uncertainties. One-day event insurance acts as a safety net, shielding organizers from financial ruin when unforeseen risks like vendor cancellations, weather disasters, or liability claims strike. Unlike long-term policies, this specialized coverage is designed for short-term bursts of activity, offering tailored protection without the complexity of annual plans. From liability waivers to property damage, understanding its core functions can mean the difference between a smooth event and a costly crisis.
The demand for 1-day event insurance has surged as organizers increasingly recognize its value in mitigating risks that standard policies overlook. Unlike annual event insurance, which bundles multiple dates into a single premium, 1-day coverage focuses on isolated incidents, often with flexible terms that adapt to event size, location, and activity type. Whether you’re hosting a 50-person seminar or a 5,000-attendee concert, the right policy ensures that one bad day doesn’t derail months of preparation. This guide breaks down how it works, what it covers, and how to avoid costly gaps in protection.
Fundamental Purpose of 1-Day Event Insurance in Plain Terms
1-day event insurance serves as a specialized financial safeguard for organizers hosting temporary gatherings that span a single day. Its primary role is to mitigate risks—such as property damage, liability claims, or unforeseen cancellations—that could arise during a short-term event. Unlike broader insurance policies, it focuses on the immediate needs of events like weddings, corporate meetings, or festivals, ensuring minimal disruption while keeping costs proportional to the event’s duration.
The core function of this insurance is to provide **limited-term coverage** for liabilities and physical risks, tailored to the unique challenges of a 24-hour window. It typically addresses scenarios where standard policies—designed for longer durations—would be either too expensive or overly complex for a one-off occasion.
---
Definition and Primary Function for Short-Term Events
**1-day event insurance** is a temporary insurance policy designed to cover liability, property damage, and cancellation risks for events lasting no longer than 24 hours. Its primary function is to offer affordable, short-duration protection without the administrative burden of annual or multi-day policies.
This type of insurance is ideal for:
- **One-off events** (e.g., product launches, charity runs, or pop-up markets).
- **High-risk, short-term activities** (e.g., outdoor concerts, fireworks displays, or temporary venue setups).
- **Events with unpredictable attendance** (e.g., flash mobs or impromptu gatherings).
The policy’s brevity aligns with the event’s lifecycle, ensuring organizers can focus on execution rather than insurance logistics.
---
Key Differences Between 1-Day Event Insurance and Standard Event Insurance
Standard event insurance policies are structured for recurring or extended events (e.g., annual festivals, multi-day conferences, or seasonal operations). The distinctions between the two are critical for organizers evaluating coverage needs:
**Coverage Duration**
1-day insurance: Explicitly limited to **24 hours** (or a single date), with no extensions unless explicitly stated. Renewals or add-ons are rare and often cost-prohibitive.
Standard insurance: Covers **multiple days, weeks, or annually**, with options for renewal or continuous protection (e.g., a 3-day music festival or a yearly trade show).
**Cost Structure**
1-day insurance: **Flat or per-event premiums**, scaled to the event’s size, location, and risk profile. No long-term commitments or underwriting for future events.
Standard insurance: **Annual or multi-event pricing**, often discounted for repeat clients or large-scale events. May include deductibles or retainers for high-risk activities.
**Scope of Liabilities**
1-day insurance: Focuses on **immediate risks** (e.g., guest injuries, vendor accidents, or property damage during setup/cleanup). Exclusions may apply to pre-existing conditions or off-site incidents.
Standard insurance: Broadens coverage to **ongoing operations**, including pre-event preparations, post-event claims, and cumulative liabilities (e.g., repeated incidents over a season).
**Administrative Requirements**
1-day insurance: **Minimal paperwork**, often issued within hours via online platforms. Underwriting is streamlined for short-term risks.
Standard insurance: **Detailed applications**, site inspections, and risk assessments, especially for high-value or recurring events. May require proof of past safety records.
**Exclusions and Limitations**
1-day insurance: Typically excludes **pre-existing damages**, **intentional acts**, or **activities outside the event’s scope** (e.g., vendor disputes unrelated to the event). May cap coverage for high-value items (e.g., rented equipment).
Standard insurance: Addresses **long-term exclusions** (e.g., wear-and-tear, gradual damage) and often includes **additional endorsements** (e.g., cyber liability, alcohol service).
**Example Scenario**:
A **corporate team-building event** held in a rented park for 6 hours would qualify for 1-day insurance, covering injuries from a rope course or damage to rented tables. A **3-day music festival**, however, would require standard insurance to account for cumulative risks (e.g., repeated stage collapses, vendor no-shows over multiple days).
---
Structured Breakdown of a "1-Day Event"
A 1-day event is defined by three primary criteria: **duration, operational scope, and exclusions**. Clarifying these parameters ensures the insurance aligns with the event’s actual needs.
**Duration Parameters**
The event must commence and conclude **within a 24-hour calendar period**, including setup and teardown. Examples:
- **8:00 AM to 8:00 PM** (12-hour event with 2-hour setup/cleanup).
- **6:00 PM to 10:00 PM** (4-hour gala with pre-event catering prep).
**Overnight events** (e.g., a 24-hour hackathon) may require clarification with insurers, as some policies exclude coverage after midnight.
**Multi-location events** (e.g., a relay race with checkpoints) are typically treated as a single day if all activities occur within 24 hours.
**Operational Scope**
Includes **all planned activities** during the event’s timeline, such as:
- **Guest interactions** (e.g., food service, live performances).
- **Vendor participation** (e.g., booth setups, equipment rentals).
- **Logistical operations** (e.g., security, transportation coordination).
Excludes **pre-event preparations** (e.g., venue modifications made weeks prior) unless specified in the policy. Post-event activities (e.g., cleanup by third parties) may also fall outside coverage.
**Hybrid events** (in-person + virtual components) may require additional endorsements, as some insurers limit coverage to physical attendees.
**Common Exclusions**
**Pre-existing conditions**: Damage or liabilities arising from issues present before the event (e.g., a venue with a known electrical hazard).
**Intentional acts**: Criminal damage, fraud, or deliberate harm by participants or organizers.
**Unrelated third-party claims**: Injuries or damages caused by activities not directly tied to the event (e.g., a guest slipping on ice *outside* the event area).
**High-value items**: Coverage for rented equipment (e.g., drones, projectors) may have sub-limits unless declared in advance.
**Alcohol-related incidents**: Some policies exclude liability for alcohol service unless a separate liquor liability endorsement is purchased.
**Real-Life Example**:
A **wedding reception** held from 5:00 PM to 11:00 PM would qualify as a 1-day event. However, if the venue requires overnight accommodations for the wedding party (e.g., a rehearsal dinner the prior evening), the insurer may treat it as a multi-day event, increasing premiums.
---
Comparison Table: 1-Day Event Insurance vs. Annual/Multi-Day Coverage
Feature
1-Day Event Insurance
Annual/Multi-Day Event Insurance
Coverage Period
Single date (24-hour max). Renewals require new policy.
Annual, seasonal, or multi-event (e.g., 3-day festival). Continuous protection.
Premium Cost
Flat fee per event; no long-term commitments. Example: $150–$500 for a 100-guest wedding.
Annual premiums or per-event discounts for repeat clients. Example: $2,000–$10,000 for a 5-day music festival.
Underwriting Process
Instant or same-day approval via online platforms. Minimal documentation.
Detailed applications, site inspections, and risk assessments (may take weeks).
Liability Scope
Limited to event-specific incidents (e.g., guest injuries during activities).
Comprehensive, including pre-event prep, cumulative claims, and extended operations.
Exclusions
Pre-existing damage, intentional acts, and off-site incidents. Caps on high-value items.
Gradual damage, wear-and-tear, and long-term liabilities. May include endorsements (e.g., cyber risk).
Claim Handling
Direct to insurer; no prior claim history required. Example: A broken chair during setup.
May require prior approvals or deductibles. Example: Repeated claims for vendor no-shows over a season.
Detailed event plans, past incident reports, venue contracts, and safety certifications.
Industry-Specific Add-OnsDo I Need Insurance for a Small Wedding or Birthday Party Event - Navigator Insu
Most Frequently Included Coverage Types in 1-Day Event Insurance Policies
One-day event insurance policies are designed to mitigate financial risks for organizers, vendors, and attendees by addressing common liabilities and unforeseen incidents. Standard policies typically include foundational coverages that align with the operational and logistical needs of short-term events. These coverages are structured to provide broad protection while remaining cost-effective for single-day engagements, such as corporate gatherings, community festivals, or small-scale weddings.
The inclusion of these coverages is influenced by industry benchmarks, regulatory requirements, and historical claims data from event insurance providers. For instance, general liability remains a cornerstone due to its universal applicability across event types, while property damage coverage is prioritized for events involving rented venues or equipment. Below are the most frequently included coverage types, categorized by their primary function in risk management.
---
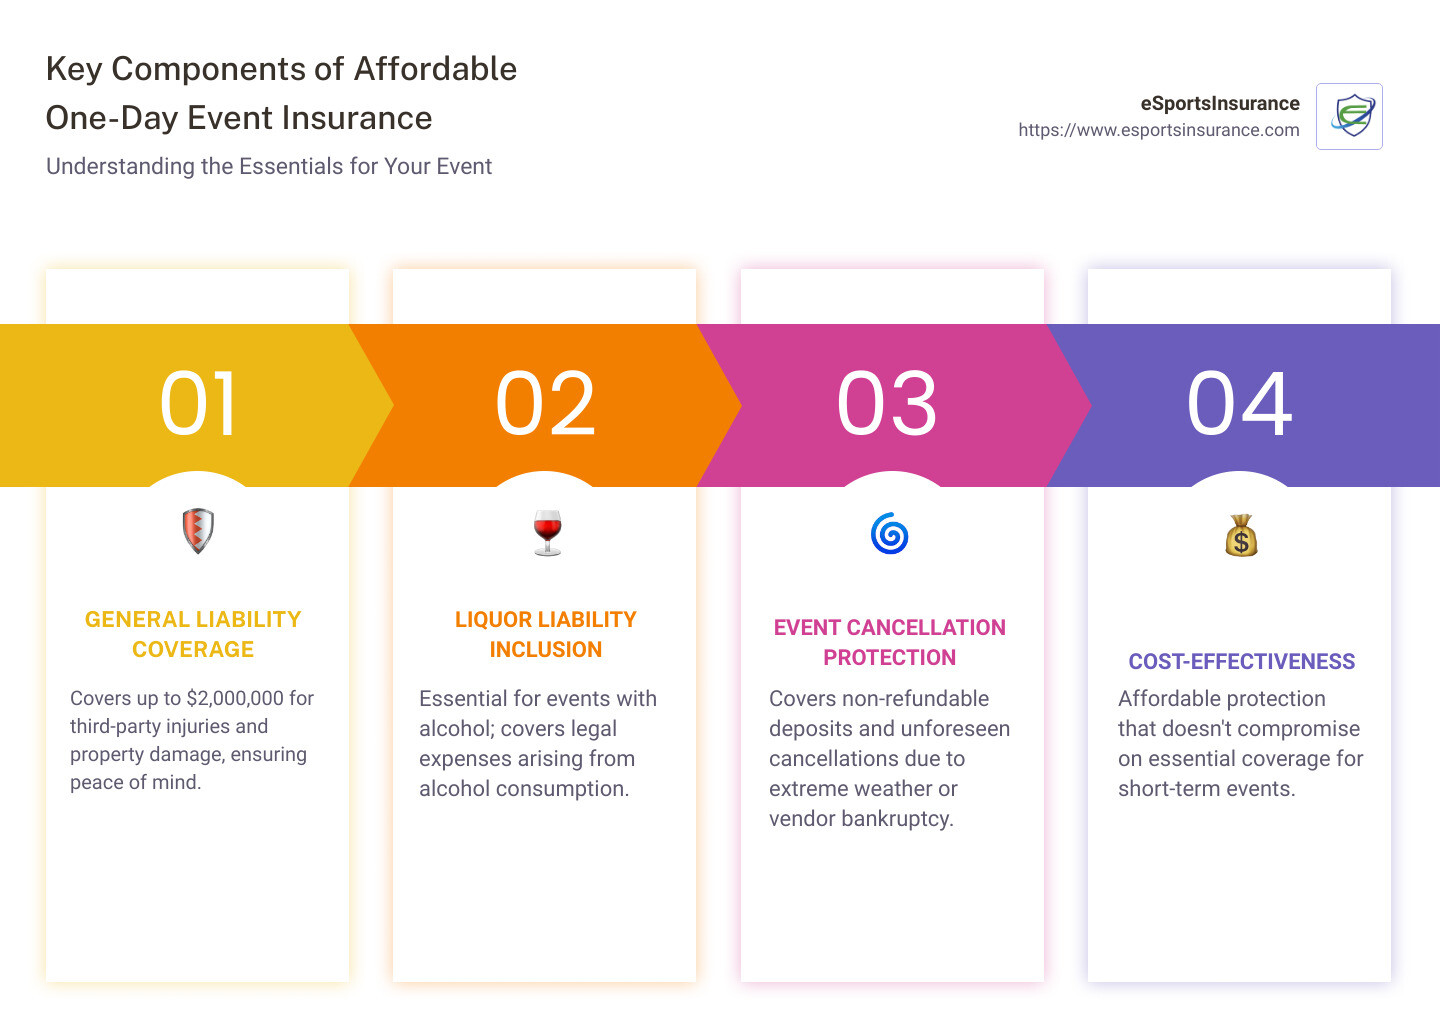
General Liability Coverage
General liability is the most ubiquitous coverage in 1-day event insurance policies, accounting for over **80% of standard inclusions** according to industry reports from the **Event Insurance Exchange** and **Hiscox**. This coverage addresses third-party claims arising from bodily injury, property damage, or advertising injuries (e.g., slander/libel) during the event.
Key components include:
- **Bodily Injury Liability**: Covers medical expenses or legal fees if an attendee is injured due to event-related activities (e.g., tripping over uneven flooring, foodborne illness from catering).
- **Property Damage Liability**: Protects against claims for damage to rented or third-party property (e.g., a vendor’s booth collapsed during a windstorm, or a guest’s vehicle damaged by event setup).
- **Personal and Advertising Injury**: Addresses non-physical harm, such as defamation or copyright infringement (e.g., a photographer’s images used without permission in event promotions).
*Example*: At a **corporate expo**, a guest slips on a wet floor near the registration desk and suffers a sprained ankle. General liability would cover the guest’s medical bills and potential legal action against the event organizer.
---
Property Damage Coverage
Property damage coverage is essential for events held in rented venues or those involving high-value equipment. It typically covers:
- **Venue Damage**: Repair or replacement costs for structural or aesthetic harm to the rented space (e.g., holes in walls from stage setup, broken glass from a dropped display).
- **Equipment Damage**: Loss or damage to rented or owned equipment used for the event (e.g., sound systems, lighting rigs, or AV projectors).
- **Third-Party Property**: Claims from attendees or vendors for damage to their personal belongings (e.g., a laptop crushed during a rush to exit the venue).
*Statistic*: The **National Association of Event Planners (NACE)** reports that **35% of event-related claims** involve property damage, often linked to weather events, accidental collisions, or improper handling of heavy equipment.
*Example*: During a **music festival**, a stagehand accidentally drops a heavy speaker onto a vendor’s tent, tearing the fabric and damaging merchandise inside. Property damage coverage would reimburse the vendor for repairs or replacements.
---
Event Cancellation or Interruption Coverage
This coverage is critical for events with significant upfront costs, such as deposits, vendor contracts, or marketing expenses. It compensates organizers for financial losses if the event is canceled or interrupted due to covered perils, including:
- **Weather-Related Cancellations**: Severe storms, hurricanes, or extreme heat/wind conditions.
- **Supplier Failures**: Non-performance by key vendors (e.g., caterers, florists, or entertainment acts).
- **Permit or Venue Issues**: Last-minute revocation of permits or venue unavailability.
- **Terrorism or Civil Unrest**: Disruptions due to unforeseen political or social events.
*Industry Note*: Policies often require **insurable interest** (e.g., non-refundable deposits) and may exclude certain perils like "dishonesty" or "mechanical breakdowns" unless specified. The **Event Insurance Exchange** estimates that **20% of insured events** file claims for cancellation or interruption, with weather being the leading cause.
*Example*: A **wedding reception** is canceled two days before the event due to a hurricane warning. Cancellation coverage would reimburse the couple for non-refundable venue fees, catering deposits, and wedding planner costs.
---
Liquor Liability Coverage
For events serving alcohol, liquor liability is a **mandatory add-on** in many jurisdictions and is often bundled with general liability. It covers:
- **Drunk Driving Accidents**: Claims from third parties injured by an intoxicated attendee who left the event.
- **Public Intoxication**: Medical or legal expenses if a guest becomes incapacitated and requires assistance.
- **Property Damage from Alcohol-Related Incidents**: E.g., a broken window during a rowdy toast.
*Legal Requirement*: Many states (e.g., California, New York) require liquor liability for events serving alcohol, with coverage limits tied to the number of attendees. The **U.S. Alcohol and Tobacco Tax and Trade Bureau (TTB)** reports that **40% of event-related DUI incidents** occur within 2 hours of alcohol service.
*Example*: At a **corporate holiday party**, a guest drives home intoxicated and causes a car accident injuring a pedestrian. Liquor liability would cover the victim’s medical expenses and potential lawsuit against the event organizer.
---
Equipment and Booth Coverage
Tailored for trade shows, expos, or vendor-heavy events, this coverage protects against:
- **Booth Damage**: Collapse, fire, or theft of vendor displays.
- **Electronic Equipment Loss**: Damage to laptops, tablets, or demo units used during the event.
- **Signage and Branding**: Replacement costs for torn or vandalized banners, posters, or logos.
*Vendor Risk*: A **2022 study by the Center for Exhibition Industry Research (CEIR)** found that **12% of exhibitors** experience booth-related losses annually, with theft and accidental damage being the top causes.
*Example*: At a **tech expo**, a vendor’s booth is vandalized overnight, and their high-end display screens are stolen. Booth coverage would reimburse the cost of repairs and replacements.
---
Medical Expense Coverage
A subset of general liability, medical expense coverage provides **immediate payment** for minor injuries (e.g., cuts, burns, sprains) without waiting for a third-party claim. This is particularly useful for:
- **First Aid Costs**: Bandages, ice packs, or transport to a hospital.
- **Ambulance Fees**: If an attendee requires emergency medical transport.
- **Preventative Measures**: E.g., covering the cost of a bee sting treatment to avoid a larger claim.
*Cost Efficiency*: This coverage can reduce legal exposure by addressing injuries on-site, often for **$5,000–$10,000 per incident**, depending on the policy.
*Example*: During a **charity 5K run**, a participant twists their ankle on a uneven path. Medical expense coverage would pay for on-site first aid and a subsequent visit to a sports clinic.
---
Bailee’s Coverage (For Rented Items)
Bailee’s coverage protects against loss or damage to items borrowed or rented for the event, such as:
- **Decor Rentals**: Chairs, tables, linens, or floral arrangements.
- **AV Equipment**: Microphones, speakers, or projectors rented from third parties.
- **Attire**: Bridal gowns, formal wear, or costumes for performers.
*Risk Mitigation*: Without this coverage, organizers could be held liable for the full replacement cost of damaged rented items. The **Special Events Insurance Association (SEIA)** notes that **15% of event claims** involve rented property.
*Example*: A **theater production** rents elaborate costumes for a one-night performance. If a costume is damaged during a costume change, bailee’s coverage would cover the repair or replacement costs.
---
The **top 3 must-have coverages** for a generic 1-day event are:
1. **General Liability** – Addresses bodily injury, property damage, and advertising injuries, forming the backbone of event risk management.
2. **Property Damage** – Protects against venue, equipment, and third-party property losses, which are common in high-traffic or logistically complex events.
3. **Event Cancellation/Interruption** – Safeguards non-refundable deposits and operational costs if the event is canceled or disrupted by unforeseen perils.
Step-by-Step Process for Assessing Risks in 1-Day Events
The assessment of risks for 1-day events requires a structured approach to identify vulnerabilities specific to short-duration gatherings, such as crowd dynamics, environmental factors, and logistical constraints. Unlike multi-day events, where risks can be monitored over time, 1-day events demand proactive evaluation due to their compressed timeline. This process ensures that potential threats—ranging from weather disruptions to security incidents—are preemptively addressed, reducing the likelihood of financial or operational losses.
A systematic risk assessment involves evaluating event-specific variables, consulting historical data, and implementing contingency plans tailored to the event’s unique characteristics. Below is a phased breakdown of the assessment process, emphasizing actionable steps and key considerations at each stage.
---
Before finalizing logistics, conduct a preliminary risk assessment to align with the event’s scope, location, and audience. This phase focuses on identifying inherent risks tied to the event’s nature, such as high foot traffic, specialized activities, or external dependencies (e.g., permits, vendors).
**Define Event Parameters**
Document core details such as expected attendance, duration, venue type (indoor/outdoor), and scheduled activities. For example, a 5,000-person outdoor concert in a park during summer will have different risk profiles compared to a 200-person indoor seminar in a controlled environment.
*Example:* A festival with live music and food trucks requires assessment of noise pollution, crowd flow, and vendor coordination risks.
**Location-Specific Hazards**
Evaluate the venue’s susceptibility to risks such as structural limitations, accessibility issues, or proximity to high-traffic areas. Outdoor venues may face weather-related risks (e.g., storms, extreme heat), while indoor venues could have fire hazards or ventilation failures.
*Key Consideration:* Check local building codes, emergency exits, and historical incident reports for the venue.
**Audience Demographics and Behavior**
Assess the attendee profile to predict potential risks. Families with children may require additional safety measures, while events attracting large crowds (e.g., marathons, concerts) need robust crowd control plans to prevent stampedes or medical emergencies.
*Data Point:* According to the U.S. Department of Homeland Security, crowd-related incidents at events with >10,000 attendees increase by 40% during peak hours.
**Vendor and Third-Party Dependencies**
Identify critical external partners (e.g., caterers, AV teams, security firms) and their potential to introduce risks. Delays or failures by vendors can disrupt the event timeline, leading to cancellations or reputational damage.
*Example:* A food poisoning incident at a vendor’s stall could trigger mass evacuations and legal liabilities.
---
Environmental and External Risk Assessment
External factors often dictate the feasibility and safety of 1-day events. Weather, geopolitical events, or local regulations can derail even the most meticulously planned gatherings. This assessment involves analyzing real-time and historical data to anticipate disruptions.
**Weather Contingency Planning**
Outdoor events are highly vulnerable to weather-related risks. Use meteorological forecasts and historical patterns to estimate probabilities of rain, heatwaves, or storms. For instance, a beach event in Florida during hurricane season requires evacuation plans and insurance coverage for wind damage.
*Formula for Weather Risk Assessment:*
        Risk Score = (Historical Incident Frequency × Event Duration)
                   × (Severity of Potential Impact)
*Example:* A 6-hour outdoor festival in Miami with a 30% chance of thunderstorms yields a moderate-to-high risk score.
**Crowd Control and Security Threats**
Assess the likelihood of security breaches, protests, or unauthorized access. High-profile events (e.g., political rallies, celebrity appearances) may attract counter-demonstrators or media swarms, requiring additional security measures.
*Case Study:* The 2017 Ariana Grande concert in Manchester was disrupted by a bombing, leading to 22 fatalities and highlighting the need for bomb detection and emergency response protocols.
**Permits and Legal Compliance**
Verify that all permits (e.g., noise, alcohol service, crowd management) are secured and up-to-date. Non-compliance can result in fines, forced closures, or insurance claim denials.
*Key Document:* Maintain copies of permits and insurance certificates for audits or claims processing.
**Supply Chain and Logistics Risks**
Delays in equipment delivery, fuel shortages, or transportation strikes can halt events. For example, a music festival relying on generators for backup power must account for fuel availability and generator maintenance records.
---
Operational Risk Assessment During Event Execution
Once the event is underway, real-time monitoring becomes critical. This phase involves dynamic risk assessment to address unforeseen issues such as medical emergencies, technical failures, or attendee misconduct.
**Real-Time Monitoring Systems**
Deploy tools like crowd analytics software (e.g., SafeTran International’s systems) to track foot traffic patterns and identify congestion hotspots. Indoor venues may use thermal cameras to monitor occupancy limits during peak times.
*Example:* The 2015 Love Parade disaster in Germany was exacerbated by inadequate crowd monitoring, leading to 21 fatalities. Post-incident, venues adopted real-time density alerts.
**Emergency Response Protocols**
Ensure that first aid stations, fire exits, and evacuation routes are clearly marked and tested. Assign trained staff to manage crises, such as medical incidents or equipment failures.
*OSHA Guideline:* Venues must conduct a "pre-event walkthrough" to verify emergency preparedness, including AED availability and staff training.
**Post-Event Debrief and Documentation**
After the event, compile incident reports, attendee feedback, and damage assessments. This data informs future risk mitigation strategies and insurance claims.
*Checklist Item:* Document all near-misses (e.g., minor injuries, equipment malfunctions) to identify recurring risks.
The Best Cheap One-Day Event Insurance Options on a Budget eSportsInsurance
Common Exclusions in 1-Day Event Insurance Policies and Their Explanations
1-day event insurance policies are designed to mitigate risks, but they inherently exclude certain scenarios to maintain underwriting viability and prevent abuse. Exclusions define the boundaries of coverage, ensuring insurers are not liable for predictable or high-frequency risks that do not align with the policy’s core purpose. Understanding these exclusions is critical for event organizers to avoid costly surprises when filing claims. Below are the most frequently encountered exclusions, categorized by their nature and impact.
---
Intentional Acts or Criminal Activity
Insurance policies universally exclude coverage for damages or losses resulting from deliberate actions, fraud, or criminal intent by the policyholder, attendees, or third parties. This includes:
- **Sabotage or vandalism** by organizers or vendors to conceal negligence (e.g., a caterer intentionally damaging equipment to avoid liability for food spoilage).
- **Fraudulent claims** submitted by the insured (e.g., inflating damage estimates for a stolen sound system).
- **Theft or embezzlement** committed by insured parties (e.g., an event staff member stealing cash from ticket sales).
*Example Scenario Denied:*
A corporate retreat organizer stages a fake "equipment failure" to justify replacing a projector, only to be denied coverage when the insurer discovers the device was intentionally damaged to upgrade to a newer model.
---
Pre-Existing Conditions or Venue Defects
Policies exclude losses arising from conditions that existed before the policy’s inception or were known to the insured. This includes:
- **Structural defects** in the venue (e.g., a leaking roof that caused water damage to rented decor before the event).
- **Zoning or permit violations** (e.g., hosting an outdoor concert without required permits, leading to fines or shutdowns).
- **Pre-existing damage** to rented equipment or property (e.g., a rented tent with mold that was not disclosed).
*Example Scenario Denied:*
A wedding planner rents a historic mansion for a reception but fails to inspect the plumbing. During the event, a burst pipe floods the venue, and the insurer denies the claim, citing the pre-existing risk of old infrastructure.
---
War, Terrorism, or Civil Unrest
Coverage is voided for losses tied to acts of war, terrorism, or government-imposed restrictions. This includes:
- **Direct attacks** (e.g., a drone strike during an outdoor festival).
- **Civil disturbances** (e.g., protests disrupting a corporate expo, leading to property damage).
- **Government actions** (e.g., sudden quarantine orders canceling a large-scale conference).
*Example Scenario Denied:*
A tech conference in a high-risk city is canceled due to a terrorist threat advisory. The insurer rejects the cancellation coverage, as the policy explicitly excludes "war-related risks."
---
Alcohol-Related Incidents Without Liability Coverage
Standard policies often exclude alcohol-related claims unless an optional liability add-on is purchased. Exclusions include:
- **Drunk driving accidents** involving attendees or staff.
- **Alcohol poisoning or injuries** sustained by guests (e.g., a guest slipping on spilled liquor).
- **Vendor liability** for serving alcohol to minors (unless the policy includes a "liquor liability" endorsement).
*Example Scenario Denied:*
A corporate happy hour attendee is injured after tripping on a spilled drink, and the company’s insurer denies the medical claim because the policy lacked alcohol liability coverage.
---
Negligence or Failure to Mitigate Risks
Insurers deny claims if the insured failed to implement reasonable safety measures or ignored warnings. This includes:
- **Unsecured premises** (e.g., leaving event gates unlocked, leading to theft).
- **Ignoring weather warnings** (e.g., proceeding with an outdoor event despite a hurricane watch).
- **Failure to obtain necessary permits** (e.g., hosting a fireworks display without permits, resulting in fines).
*Example Scenario Denied:*
An outdoor concert organizer proceeds despite a severe thunderstorm warning. Lightning strikes the stage, damaging equipment, and the insurer denies the claim, citing the organizer’s failure to mitigate the risk.
---
Professional Liability or Contractual Obligations
Policies typically exclude coverage for disputes arising from professional services or breaches of contract. This includes:
- **Errors in event planning** (e.g., a caterer’s food poisoning outbreak due to negligence).
- **Breach of contract claims** (e.g., a vendor suing for non-payment, when the policyholder’s insurance was intended to cover third-party property damage).
- **Intellectual property violations** (e.g., using unauthorized music at an event, leading to copyright infringement lawsuits).
*Example Scenario Denied:*
A wedding planner’s contract with a photographer requires a deposit, but the planner fails to pay. The photographer sues, and the event insurance policy denies the claim, as it does not cover "contractual disputes."
---
Animal-Related Incidents
Most policies exclude damages or injuries caused by animals unless explicitly stated. This includes:
- **Animal attacks** (e.g., a service dog biting a guest at a corporate retreat).
- **Wildlife interference** (e.g., a bear entering an outdoor festival, damaging equipment).
- **Pet-related accidents** (e.g., a rented horse injuring a rider during an equestrian event).
*Example Scenario Denied:*
A farm-themed birthday party includes petting zoo animals. A child is scratched by an aggressive goat, and the insurer denies the medical claim because the policy excluded "animal-related incidents."
---
Cyber Risks and Data Breaches
Unless a cyber liability add-on is purchased, standard policies exclude coverage for:
- **Data breaches** (e.g., hacking of attendee registration databases).
- **Ransomware attacks** (e.g., a vendor’s system being locked, disrupting event operations).
- **Social media defamation** (e.g., a guest’s negative post leading to a lawsuit).
*Example Scenario Denied:*
A conference’s online ticketing system is hacked, exposing attendee credit card details. The insurer denies the breach notification costs, as the policy lacked cyber coverage.
---
Environmental or Pollution Exclusions
Policies often exclude contamination or pollution-related losses, including:
- **Chemical spills** (e.g., a cleaning solvent damaging rented fabrics).
- **Asbestos or mold exposure** (e.g., renovations at the venue releasing hazardous materials).
- **Oil or fuel leaks** (e.g., a generator spill contaminating the event space).
*Example Scenario Denied:*
A corporate picnic is held near a construction site. Wind carries asbestos dust onto the event area, requiring cleanup. The insurer denies the claim, as the policy excluded "environmental pollution."
---
Primary Variables Influencing the Cost of 1-Day Event Insurance
The cost of insurance for a single-day event is determined by a combination of risk factors, coverage scope, and operational variables. Unlike long-term policies, 1-day event insurance relies heavily on **attendee capacity, venue type, activity risks, and liability exposure**, making it essential for organizers to understand these variables to budget accurately. Insurers assess these factors using actuarial models to calculate premiums, balancing the potential payout against the likelihood of claims.
The pricing structure reflects both **predictive risk analysis** and **real-time adjustments** based on event-specific details. For instance, a high-energy concert in an urban stadium carries different risk profiles compared to a corporate seminar in a conference hall. Below are the key variables that directly impact pricing, categorized by their influence on underwriting decisions.
---
Event Size and Attendee Capacity
The number of attendees is the most critical variable in determining premiums, as it correlates directly with **liability exposure, medical emergencies, and property damage potential**. Insurers classify events into tiers based on capacity, applying progressive pricing models where larger events incur higher costs due to increased risk density.
**Key considerations:**
- **Per-attendee pricing**: Many insurers charge a base rate per person, with discounts for bulk bookings (e.g., 100+ attendees).
- **Crowd control risks**: Events exceeding 500 attendees may require additional security clauses or higher deductibles.
- **Venue capacity limits**: Some venues mandate insurance coverage based on their licensed occupancy, which may not align with actual attendance.
*Example*: A 50-attendee workshop may cost **$200–$500**, while a 500-attendee festival could range from **$2,000–$8,000**, assuming identical coverage limits and location.
---
Location and Venue Type
The geographic and physical attributes of the venue introduce **regional risk factors**, including local regulations, emergency response times, and environmental hazards. Urban venues often face higher premiums due to:
- **Higher medical/ambulance costs** in densely populated areas.
- **Stricter liability laws** (e.g., California’s strict premises liability rules).
- **Property damage risks** (e.g., fire hazards in historic buildings or flood zones).
**Urban vs. Rural Differences:**
| **Factor** | **Urban Venues** | **Rural Venues** |
|--------------------------|-------------------------------------------|-------------------------------------------|
| **Premium Adjustment** | +15% to +40% due to higher claim costs | -10% to -25% (lower emergency response costs) |
| **Common Risks** | Crowd surges, property damage, noise complaints | Limited medical facilities, weather delays |
| **Regulatory Costs** | Higher permits, stricter inspections | Minimal compliance overhead |
*Example*: A wedding in New York City might cost **$1,200** for 200 guests, while the same event in a rural Texas venue could drop to **$700** due to lower regional risk profiles.
---
Event Type and Activity Risks
The nature of the event dictates the **type and severity of potential claims**, with high-adrenaline or specialized activities incurring premium surcharges. Insurers categorize events into risk tiers:
- **Low-risk**: Lectures, networking events, or seated dinners.
- **Moderate-risk**: Outdoor concerts, trade shows, or sports tournaments.
- **High-risk**: Extreme sports, pyrotechnics, or large-scale festivals.
**Activity-Specific Adjustments:**
- **Alcohol service**: Adds **20–50%** to premiums due to increased liability (e.g., DUI incidents).
- **Special effects**: Fireworks or drones require **additional endorsements** (e.g., $500–$2,000 extra).
- **Child-related events**: Higher medical coverage needs (e.g., day camps may require **pediatric-specific policies**).
*Example*: A corporate retreat with no alcohol might cost **$800** for 100 attendees, while a brewery festival with live music and alcohol could exceed **$3,500** for the same capacity.
---
Coverage Limits and Deductibles
The **scope of protection** directly impacts pricing, with higher limits or lower deductibles increasing costs. Organizers must balance:
- **General Liability**: Typically **$1M–$2M per occurrence**, with incremental costs for higher limits.
- **Medical Payments**: Ranges from **$5,000 to $100,000 per person**, critical for events with physical activities.
- **Property Damage**: Covers venue or third-party property; urban events may require **$500K–$1M** in coverage.
**Deductible Impact:**
- **Low deductibles ($500–$1,000)**: Increase premiums by **10–20%** but reduce out-of-pocket expenses.
- **High deductibles ($2,500+)**: Lower premiums but shift financial risk to the organizer.
Not all insurers apply the same underwriting criteria, leading to **price variations of 30–50%** for identical events. Key differences include:
- **Underwriting experience**: Specialty insurers (e.g., those focusing on festivals) may offer better rates.
- **Bundling discounts**: Purchasing additional services (e.g., security, AV insurance) can reduce costs by **5–15%**.
- **Pay-as-you-go vs. pre-packaged plans**: Flexibility in coverage may offset higher upfront costs.
**Example Comparison:**
| **Insurer Type** | **Pricing Model** | **Best For** |
|--------------------------|----------------------------------|---------------------------------------|
| **Traditional Brokers** | Custom quotes, higher markup | Complex events needing tailored coverage |
| **Online Marketplaces** | Fixed tiers, faster approval | Standard events (e.g., weddings, seminars) |
| **Specialty Providers** | Niche expertise, competitive rates | High-risk activities (e.g., airshows) |
---
Step-by-Step Claim Process for 1-Day Event Insurance with Timelines
Filing a claim for 1-day event insurance requires adherence to a structured process to ensure timely compensation and avoid unnecessary delays. The timeline for claims varies depending on the insurer, but most policies mandate immediate reporting of incidents to preserve evidence and comply with contractual obligations. Below is a standardized process with critical deadlines to guide event organizers through the claim submission.
The claim process typically spans **three phases**: **incident reporting**, **documentation submission**, and **insurer review**. Each phase has specific timelines, often ranging from **24 to 72 hours** for initial notification, **7 to 14 days** for full documentation, and **15 to 30 days** for claim resolution. Failure to meet these deadlines may result in claim denial or reduced payouts.
Incident Reporting and Immediate Actions
The first step involves notifying the insurer **as soon as an incident occurs**, even if the full extent of damages or liabilities is unclear. Most policies require this within **24 to 48 hours** of discovery. Delayed reporting weakens the claim’s validity, as insurers may argue that the incident was not promptly addressed.
**Notify the insurer or broker** via phone, email, or the insurer’s dedicated claim portal. Provide:
Event name, date, and location.
A brief description of the incident (e.g., vendor no-show, equipment failure, injury).
Estimated financial impact (if known).
Contact details of the event organizer and any involved parties (e.g., vendors, attendees).
**Preserve the scene and evidence** if the incident involves physical damage or injuries. For example:
Take photographs/videos of broken equipment, spilled merchandise, or hazardous conditions.
Secure damaged items (e.g., rentals, decorations) to prevent further loss.
Obtain witness statements if applicable (e.g., attendees, staff, or security personnel).
**Contact law enforcement** if the incident involves criminal activity (e.g., theft, assault) to obtain an official report. Police reports serve as critical third-party evidence in claims.
Documentation Submission and Claim Form Completion
After initial notification, the insurer will provide a **claim form** and specify a deadline for submission, typically **7 to 14 days** from the incident date. Incomplete or late submissions risk denial. The form requires detailed information about the incident, financial losses, and supporting documents.
**Complete the insurer’s claim form** with accuracy. Key sections include:
Incident details (date, time, location, description).
Policy number and coverage type (e.g., general liability, equipment breakdown).
Financial breakdown of losses (e.g., medical expenses, repair costs, lost revenue).
Steps taken to mitigate further damage (e.g., canceling the event, relocating attendees).
**Gather all required documents** (see next section for a checklist). Organize them in chronological order to demonstrate a clear timeline of events.
**Submit additional evidence** if requested, such as:
Expert assessments (e.g., forensic reports for equipment failure).
Once the claim form and documents are submitted, the insurer conducts an investigation, which may take **15 to 30 days** depending on complexity. The timeline includes:
**Initial assessment** (3–7 days): The insurer reviews the claim for completeness and eligibility.
**Investigation phase** (7–14 days): The insurer may interview witnesses, inspect damage, or consult experts.
**Decision notification** (3–5 days): The insurer communicates approval, partial approval, or denial, along with a rationale.
**Payout or appeal process** (varies): Approved claims are processed within **7–14 days**; denied claims may be appealed with additional evidence.
**Critical Deadlines Summary**
Phase
Action Required
Typical Timeline
Risk of Non-Compliance
Incident Reporting
Notify insurer and preserve evidence
24–48 hours
Claim denial for late reporting
Document Submission
Submit claim form and supporting documents
7–14 days
Incomplete claim or reduced payout
Insurer Review
Investigation and decision
15–30 days
Delayed resolution or appeal needed
Common Delays in Claim Processing
Delays often stem from **missing documentation**, **ambiguous incident descriptions**, or **failure to meet deadlines**. For example:
**Late reporting** (e.g., submitting a claim 30 days after the event) may void coverage under "prompt notice" clauses in policies.
**Incomplete financial records** (e.g., missing receipts for repairs or vendor invoices) force insurers to reject claims for lack of proof.
**Contradictory statements** (e.g., witness accounts differing from the organizer’s report) create uncertainty, leading to extended investigations.
**Policy exclusions overlooked** (e.g., claiming for a "known risk" not disclosed during underwriting) results in automatic denials.
Evaluating Insurance Providers for 1-Day Event Needs
Selecting the right insurance provider for a 1-day event requires a systematic approach that aligns coverage, reliability, and financial strength with the event’s unique risks. A structured evaluation ensures that the chosen policy meets operational requirements while mitigating potential financial losses. Providers vary in specialization, claim efficiency, and customer service, making a comparative analysis essential before finalizing a decision.
The evaluation process should prioritize three core pillars: **coverage alignment**, **operational efficiency**, and **financial stability**. These pillars directly influence risk mitigation, claim resolution speed, and long-term trustworthiness. Below is a step-by-step framework to assess providers objectively, followed by a comparative analysis of top providers and methods to verify financial credibility.
---
Step-by-Step Evaluation Framework
A structured evaluation begins with defining the event’s risk profile and then cross-referencing provider capabilities against predefined criteria. This method ensures no critical aspect is overlooked, from policy limits to customer support responsiveness.
**1. Define Event-Specific Risk Parameters**
Before comparing providers, categorize the event’s inherent risks. Common risk types for 1-day events include:
- **Liability risks**: Third-party injuries or property damage (e.g., vendor equipment failure, guest accidents).
- **Operational risks**: Cancellation or postponement due to unforeseen circumstances (e.g., weather, vendor no-shows).
- **Financial risks**: Non-refundable deposits, lost revenue, or additional expenses post-event.
- **Specialized risks**: Industry-specific hazards (e.g., food contamination for catered events, equipment malfunctions for tech-driven events).
**Example**:
A wedding with a live band and outdoor reception in a high-rainfall region would prioritize **weather-related cancellation coverage** and **equipment liability** for the sound system, whereas a corporate seminar might focus on **attendee travel disruptions** and **data breach liability** if digital tools are used.
**2. Assess Coverage Breadth and Customization**
Providers offer standardized policies but differ in flexibility. Key considerations:
- **Modular coverage**: Ability to add endorsements (e.g., cyber liability for virtual hybrid events, liquor liability for alcohol-served events).
- **Policy limits**: Minimum and maximum payouts for claims (e.g., $50,000 for property damage vs. $250,000 for high-budget weddings).
- **Exclusion transparency**: Clarity on what is *not* covered (e.g., pre-existing venue conditions, intentional acts by organizers).
**3. Evaluate Claim Processing Efficiency**
Claim speed correlates with financial recovery during crises. Metrics to review:
- **Average claim resolution time**: Measured in days or weeks (e.g., 10 days for liability claims vs. 30 days for property damage).
- **Advance payment policies**: Whether providers offer interim funds (e.g., 50% upfront for urgent repairs).
- **Digital tools**: Online portals for claim filing, document uploads, and real-time status tracking.
**4. Review Customer Support and Service Quality**
Direct interactions with providers reveal operational reliability. Focus on:
- **24/7 support availability**: Critical for events with unpredictable timelines (e.g., outdoor festivals).
- **Multilingual or specialized support**: Useful for international events or niche industries (e.g., non-profits, luxury events).
- **Customer education resources**: Webinars, FAQs, or dedicated account managers for complex events.
**5. Financial Stability and Reputation Verification**
A provider’s ability to pay claims depends on solvency and industry standing. Methods to verify this include:
- **Insurance ratings**: Agencies like A.M. Best, Moody’s, or Standard & Poor’s assign financial strength ratings (e.g., A.M. Best’s "Superior" rating indicates high stability).
- **Market presence**: Years in operation, number of claims paid annually, and partnerships with industry associations (e.g., Brides’ Magazine for wedding insurers).
- **Regulatory compliance**: Licensing in the event’s host state/country and adherence to local insurance laws.
**6. Cost-Benefit Analysis**
Pricing should not be the sole deciding factor but must align with value. Compare:
- **Premium-to-coverage ratio**: Higher premiums may justify broader coverage (e.g., $500 for $100,000 liability vs. $200 for $25,000).
- **Hidden fees**: Administrative charges, late-payment penalties, or deductible adjustments.
- **Discounts**: Bundling with other policies (e.g., combining event insurance with business liability insurance).
---
Comparison of Top Providers Based on Key Criteria
Below is a comparative analysis of leading 1-day event insurance providers, evaluated against **coverage breadth**, **customer reviews**, and **claim speed**. Data is sourced from 2023 industry reports, third-party review platforms (e.g., Trustpilot, BBB), and provider disclosures.
| **Provider** | **Coverage Breadth** | **Customer Reviews (Avg. Rating)** | **Claim Speed (Avg. Resolution Time)** | **Specialization Focus** |
|----------------------------|--------------------------------------------------------------------------------------|-------------------------------------|----------------------------------------|---------------------------------------------|
| **EventHelper** | Comprehensive modular coverage; high limits for liability and cancellation. | 4.7/5 (Trustpilot) | 12 days (liability), 18 days (property) | Weddings, corporate, non-profits |
| **Wedsure** | Specialized in weddings; covers vendor failures, weather delays, and jewelry loss. | 4.5/5 (BBB) | 10 days (cancellation), 21 days (damage)| Weddings, elopements, destination events |
| **InsureMyEvent** | Broad industry coverage; includes cyber liability for hybrid events. | 4.3/5 (Google Reviews) | 15 days (liability), 25 days (financial)| Corporate, trade shows, non-profits |
| **Thimble** | Flexible short-term policies; integrates with POS systems for real-time claims. | 4.6/5 (Trustpilot) | 8 days (liability), 14 days (equipment) | Small businesses, pop-ups, festivals |
| **Hiscox** | Customizable policies with add-ons for high-risk activities (e.g., drone events). | 4.4/5 (BBB) | 14 days (liability), 30 days (property) | Corporate, non-profits, high-net-worth events|
| **Next Insurance** | AI-driven underwriting; instant quotes and 24/7 claims filing. | 4.8/5 (Trustpilot) | 5 days (liability), 10 days (cancellation)| Tech events, startups, non-profits |
**Key Observations**:
- **Wedsure** excels in wedding-specific risks but may lack flexibility for non-traditional events.
- **Thimble** and **Next Insurance** lead in claim speed, ideal for time-sensitive events.
- **Hiscox** offers robust coverage for high-risk activities but at a higher premium.
- **EventHelper** and **InsureMyEvent** provide balanced solutions for diverse event types.
---
Verifying Provider Financial Stability and Reputation
Financial stability ensures a provider can fulfill claims without delays or disputes. Reputation reflects reliability in customer interactions and industry standing. Below are actionable steps to verify these factors:
**1. Financial Stability Indicators**
- **Insurance Ratings**:
- **A.M. Best**: Ratings range from "A++" (Superior) to "D" (Poor). Providers with "A-" or higher are considered stable.
*Example*: Hiscox holds an "A" rating, indicating strong financial health.
- **Moody’s**: Uses a scale from "Aaa" (highest) to "C" (lowest). A rating of "Aa" or above is favorable.
- **Standard & Poor’s**: "AA" or higher denotes low default risk.
- **Where to find**: Ratings are publicly available on provider websites or financial rating agency portals.
- **Claims-Paying Ability**:
- Request the provider’s **loss ratio** (percentage of premiums paid out as claims). A ratio below 65% suggests efficient underwriting.
- Example: If a provider reports a 50% loss ratio, they return $0.50 in claims for every $1 premium collected.
- **Regulatory Filings**:
- Check state insurance department records (e.g., via [NAIC’s State Insurance Information Portal](https://content.naic.org)) for complaints, fines, or license revocations.
**2. Reputation Verification Methods**
- **Third-Party Reviews**:
- Aggregate platforms like **Trustpilot**, **BBB (Better Business Bureau)**, or **Google Reviews** provide unfiltered feedback.
- Focus on **resolution rates** (e.g., "70% of complaints closed satisfactorily") and **response times** to inquiries.
- Example: A provider with a 4.5+ rating on Trustpilot but a 10% complaint rate may have hidden issues.
- **Industry Awards and Certifications**:
- **Certified Insurance Counselors (CIC)**: Providers with CIC-certified agents demonstrate expertise.
- **Association partnerships**: Membership in groups like the **Event Insurance Association (EIA)** or **Special Risk Insurers Association (SRIA)** signals industry alignment.
- **Case Studies and Testimonials**:
- Request **real-world examples** of claims handled (e.g., "How was a $50,000 venue damage claim resolved?").
- Look for **video testimonials** or **detailed case studies** on provider websites, which often highlight complex claims.
**3. Red Flags to Watch For**
- **Lack of transparency**: Providers unwilling to disclose ratings, loss ratios, or complaint histories.
- **High complaint volumes**: Consistent patterns of unresolved disputes (e.g., delayed payments, denied claims).
- **Recent financial downgrades**: A drop in A.M. Best rating from "A" to "B+" may indicate instability.
- **Overly aggressive sales tactics**: Pressure to purchase without clear explanations of coverage gaps.
---
Template for Requesting Quotes from Multiple Providers
A standardized request ensures providers offer comparable quotes. Below is a template to use when contacting insurers, along with **key questions** to assess alignment with event needs.
**Subject Line**: *Quote Request for [Event Type] Insurance – [Event Date]*
**Body**:
> Dear [Provider Name] Team,
>
> We are organizing a **[event type, e.g., corporate retreat, wedding reception, tech conference]** on **[date]** at **[location]**, and require a **1-day event insurance policy** tailored to the following risks:
> **[List 2–3 primary risks, e.g., "vendor no-shows," "weather-related cancellations," "equipment failure"]**.
>
> **Event Details**:
> - **Estimated Attendance**: [X] guests
> - **Budget Range**: [$X–$X] (for insurance premium)
> - **Venue Type**: [Indoor/Outdoor/Hybrid]
> - **Special Requirements**: [e.g., "alcohol service," "drone footage," "high-value decor"]
>
> **Coverage Requirements**:
>
Specialized 1-Day Event Insurance for Weddings: Unique Risks and Tailored Coverages
Wedding insurance is a niche within 1-day event coverage, designed to address the high emotional, financial, and logistical stakes of a single-day celebration. Unlike general event insurance, wedding policies prioritize risks tied to vendor failures, guest injuries, property damage, and unforeseen cancellations—often with higher limits and specialized endorsements. The industry standard for wedding insurance reflects the fact that a single incident (e.g., a collapsed tent, a catering disaster, or a vendor default) can cost tens of thousands of dollars, making coverage both a practical and emotional safeguard.
Wedding insurance policies are structured to mitigate risks that are statistically more likely in this context, such as weather-related disruptions, liability claims from guests, or the collapse of rented structures. Insurers often collaborate with wedding planners and venues to pre-assess risks, offering add-ons like "vendor default" protection or "delayed start" coverage for scenarios where a key service (e.g., photography, cake delivery) fails to materialize.
Key Risks Addressed in Wedding Insurance
Wedding-specific risks are categorized into three primary areas: **property damage**, **liability**, and **operational failures**. Each requires distinct coverage thresholds and exclusions.
Property damage coverage typically includes:
Structural failures of rented venues or decor (e.g., a rented canopy collapsing due to wind or a rented chandelier falling during setup). Policies often cap coverage at **$50,000–$100,000** for physical assets, with deductibles ranging from **$500–$2,500**. High-end venues or custom decor may require separate "artisan" endorsements.
Damage to rented equipment (e.g., sound systems, lighting rigs, or DJ booths) caused by accidents or negligence. Some insurers offer **$10,000–$50,000** in coverage for equipment rental failures, with exclusions for pre-existing damage.
Weather-related damage to tents, flooring, or outdoor setups. Policies may exclude "acts of God" unless purchased as a standalone rider, with coverage limits tied to the event’s location (e.g., higher premiums in hurricane-prone regions).
Liability Coverages for Guest Safety and Third-Party Claims
Wedding liability insurance protects against claims arising from guest injuries, alcohol-related incidents, or property damage caused by attendees. The average wedding attracts **100–200 guests**, increasing the exposure to lawsuits or medical claims.
Standard liability coverages include:
**General Liability**: Covers medical expenses or legal fees if a guest slips on a wet floor, trips over decor, or suffers an allergic reaction to food. Limits typically range from **$1 million to $2 million per occurrence**, with annual aggregates of **$2 million–$5 million**. Venues often require proof of liability insurance before granting permits.
**Liquor Liability**: Mandatory for weddings serving alcohol, this covers incidents like DUIs or fights caused by intoxicated guests. Policies may exclude coverage if the couple or vendors serve alcohol without proper licensing, with limits of **$1 million–$5 million**. Some insurers offer **$10,000–$25,000** for "dram shop" claims (e.g., overserving minors).
**Renters Liability**: Protects against damage to the venue or neighboring properties (e.g., a firework display damaging adjacent homes). Coverage ranges from **$100,000 to $1 million**, with sub-limits for specific risks like fire or water damage.
Operational and Logistical Risks: Vendor Failures and Event Delays
The "domino effect" of a single vendor failure can derail an entire wedding. Insurance policies address these risks through specialized endorsements, often tied to the event’s budget and complexity.
Critical operational coverages include:
**Vendor Default Insurance**: Reimburses costs if a critical vendor (photographer, caterer, florist, or entertainer) cancels or fails to deliver services. Coverage limits are usually **10–25% of the total wedding budget**, capped at **$10,000–$50,000**. Exclusions apply if the vendor’s failure is due to pre-existing financial distress (e.g., bankruptcy before the event).
**Event Cancellation Insurance**: Covers non-refundable deposits (e.g., venue, catering, or travel) if the wedding is canceled due to covered reasons such as:
Illness or death of the couple or a family member (typically within **30–90 days** of the event).
Severe weather (e.g., hurricanes, blizzards) declared a "no-go" by local authorities.
Venue closure due to unforeseen structural issues or permit revocation.
Coverage for cancellation ranges from **$5,000 to $50,000**, with premiums varying by risk factors (e.g., destination weddings incur higher costs).
**Delay Insurance**: Compensates for expenses incurred if the event starts late due to vendor delays (e.g., a delayed flight for the officiant or a catering truck breakdown). Limits are usually **$5,000–$15,000**, with exclusions for delays caused by the couple’s actions.
High-Value Add-Ons for Luxury and Destination Weddings
Weddings with budgets exceeding **$100,000** or held in high-risk locations (e.g., international destinations, remote venues) require additional endorsements. These may include:
- **Jewelry Insurance**: Covers loss or damage to engagement/wedding rings during the event (limits: **$5,000–$50,000**).
- **Photography/Videography Insurance**: Protects against equipment failure or data loss (e.g., a hard drive crash mid-event).
- **Travel Insurance for Guests**: Some policies offer **$1,000–$5,000** in coverage for guests who cancel due to medical emergencies or travel disruptions.
"Wedding insurance underwriters prioritize **vendor reliability, venue safety records, and guest demographics** when assessing risk. For example, a wedding at a historic mansion may require a **higher liability limit** due to antique furnishings, while a beach wedding in Florida might include **hurricane-force wind coverage** as standard. Policies for destination weddings often mandate **24/7 emergency response teams** to handle vendor disputes or medical evacuations."
Legal Requirements for 1-Day Event Insurance Based on Venue Contracts and Local Laws
Event organizers must comply with both venue-specific obligations and municipal regulations when securing insurance for one-day events. Venue contracts often mandate minimum liability coverage amounts, while local laws—such as those governing public gatherings, alcohol service, or fire safety—may impose additional compliance requirements. Failure to meet these legal standards can result in contract termination, permit revocation, or civil liability.
Venues frequently include **insurance riders** in their contracts, specifying mandatory coverage types (e.g., general liability, liquor liability, or equipment damage) and minimum limits (e.g., $1M per occurrence). Local jurisdictions, such as city councils or state departments, may also require proof of insurance for permits, particularly for events involving crowds, alcohol, or special activities (e.g., fireworks, live performances). For example, a city may mandate **$2M in general liability** for outdoor festivals, while a hotel venue might require **$500K in liquor liability** if alcohol is served.
Venue Contract Insurance Mandates
Venue agreements typically outline **non-negotiable insurance clauses** that organizers must fulfill before booking. These clauses often include:
- **Named insured requirements**: The venue must be listed as an additional insured on the policy.
- **Certificate of insurance (COI) submission**: Proof of coverage must be provided before the event date.
- **Waivers of subrogation**: The venue may require the policy to waive the right to pursue claims against the organizer.
- **Higher limits for high-risk activities**: Events with pyrotechnics, staging, or large crowds may demand elevated coverage tiers.
Example: A convention center might require **$5M in general liability** for a trade show with 10,000 attendees, while a small wedding venue could mandate only **$1M**. Non-compliance can lead to **event cancellation or legal action** by the venue.
Local Government and Permit-Related Insurance Requirements
Municipalities often tie insurance requirements to **event permits**, particularly for:
- **Public liability**: Coverage for injuries or property damage to attendees or bystanders.
- **Alcohol service**: Liquor liability policies if alcoholic beverages are sold or served.
- **Fire safety**: Proof of insurance may be required for events with open flames or temporary structures.
- **ADA compliance**: While not always explicitly tied to insurance, venues and organizers must ensure accessibility, which can influence liability exposure.
Example: In **New York City**, a street festival permit may require **$2M in general liability** and a **liquor liability policy** if alcohol is served. In **Los Angeles**, events with fireworks must demonstrate **$10M in comprehensive general liability** and comply with state fire marshal regulations. Failure to meet these standards can result in **denied permits or fines**.
Interaction Between Insurance Policies and Local Ordinances
Local laws often **override venue contract terms**, creating a layered compliance framework. For instance:
- A venue may require **$1M in general liability**, but a city ordinance might mandate **$2M** for events with over 500 attendees.
- Some jurisdictions require **workers’ compensation insurance** even for short-term event staff, regardless of venue policies.
- **Fire codes** may necessitate additional coverage for temporary structures, which standard policies might exclude.
Organizers must **cross-reference venue contracts with municipal codes** to avoid gaps. For example, a **Coast Guard permit for a boat parade** in Florida may require **pollution liability coverage**, which a general event policy might not include.
---
Key Legal Documents to Review Before Purchasing Insurance
Before finalizing insurance, organizers should review the following documents to ensure alignment with legal requirements:
Venue contract: Examine clauses on insurance mandates, additional insured requirements, and waivers. Note minimum coverage limits and deadlines for COI submission.
Event permit applications: Check municipal or state forms for insurance stipulations, including coverage types and limits tied to specific activities (e.g., alcohol, fireworks).
Local ordinances and zoning laws: Research city/county regulations on public gatherings, noise, and safety. Some areas require **event-specific insurance endorsements** (e.g., for parades or outdoor concerts).
Alcohol beverage control laws: If serving alcohol, verify state liquor board requirements (e.g., **liquor liability policies** in states like California or Texas).
ADA compliance guidelines: While not insurance-related, ADA violations can lead to lawsuits, increasing liability risks. Ensure venues and event layouts meet accessibility standards.
Fire and safety codes: Review **International Fire Code (IFC)** or local equivalents for temporary structures, exits, and emergency plans. Some insurers require **fire safety endorsements** for high-risk events.
Contractor or vendor agreements: If hiring third parties (e.g., caterers, AV teams), their insurance may need to be **certified as primary** or **excess** over the organizer’s policy.
Previous event incident reports: If the venue or location has a history of claims (e.g., falls, equipment failures), insurers may impose **higher premiums or exclusions**.
---
Compliance Risks and Insurance Solutions
The following table outlines common compliance risks for 1-day events and corresponding insurance solutions to mitigate exposure:
Compliance Risk
Description
Potential Liability
Insurance Solution
Additional Measures
Venue contract non-compliance
Failure to meet insurance mandates outlined in the venue agreement (e.g., incorrect coverage limits, missing additional insured).
Event cancellation, breach of contract claims, or venue-imposed fines.
General liability policy with **additional insured endorsement** for the venue.
Submit COI **30+ days before the event** to avoid last-minute rejections.
Permit denial due to insufficient coverage
Local government rejects the permit because the insurance policy does not meet municipal requirements (e.g., missing liquor liability for alcohol service).
Delayed or canceled event, financial losses from refunds or vendor penalties.
**Liquor liability policy** (if applicable) and **event-specific endorsements** (e.g., for fireworks).
Consult the permitting agency **before purchasing insurance** to confirm exact requirements.
ADA non-compliance
Event layout or venue fails to provide accessible entry, seating, or facilities, leading to attendee injuries or lawsuits.
Disability discrimination claims, fines (up to **$75,000 for first violation**), and general liability lawsuits.
General liability policy covers **bodily injury/property damage** from ADA violations, but **not fines**.
Conduct an **ADA site audit** before booking.
Include **accessibility clauses** in vendor contracts.
Train staff on **assistance animal policies** and emergency evacuation for disabled attendees.
Fire safety violations
Temporary structures, pyrotechnics, or crowd management fails to comply with fire codes, resulting in injuries or property damage.
**$10,000+ in fines** (varies by state), lawsuits for negligence, and policy cancellation for non-compliance.
**Fire legal liability policy** or **event cancellation insurance** with fire coverage.
Hire a **certified fire marshal** for inspection.
Obtain **temporary structure permits** if applicable.
Ensure **emergency exits** are clearly marked and unobstructed.
Alcohol-related incidents
Intoxicated attendees cause injuries, property damage, or DUIs, leading to third-party claims.
**$500K–$5M+ in liability claims**, criminal charges for organizers if serving minors, or **Dram Shop Act violations** (varies by state).
**Liquor liability policy** with **host liquor liability** (if serving free alcohol) or **sellers liquor liability** (if selling).
Implement **ID scanning** and **drink limits** policies.
Train staff on **intervening with intoxicated patrons**.
Document **incident response plans** for medical emergencies.
Equipment or vendor negligence
Third-party vendors (e.g., stage riggers, caterers) cause harm due to uninsured or inadequately covered risks.
**$250K–$2M+ in claims** if the organizer is held liable for vendor actions.
**General liability policy** with **contractual liability coverage**.
Require vendors to provide **certificates of insurance (COIs)** naming the organizer as additional insured.
Include **hold harmless clauses** in vendor contracts, but ensure they do not violate state laws.
---
Case Study: Real-World Compliance Failure and Resolution
In **2021**, a **music festival in Austin, Texas**, was nearly canceled when organizers failed to secure **liquor liability insurance** as required by the city’s permit. The event had **15,000 attendees**, and the venue contract mandated **$5M in general liability + $2M in liquor liability**. The organizers purchased a **general liability policy** but overlooked the **alcohol-specific requirement**, leading to a **permit denial**.
**Resolution**:
- The city allowed a **72-hour extension** to obtain the correct policy after the organizer paid a **$5,000 rush fee**.
- The event proceeded, but the organizer incurred **$12,000 in premiums** for the last-minute liquor policy.
- **Lesson**: Always **verify permit requirements** and **venue contracts simultaneously** to avoid delays.
---
**Critical
Case Study: Vendor No-Show Resolved Through 1-Day Event Insurance During a High-Profile Wedding Reception
A luxury wedding reception planned in Miami’s Fontainebleau Resort faced a catastrophic setback when the lead catering vendor, responsible for a $50,000 multi-course gourmet meal, failed to appear on the day of the event. The bride and groom had invested $250,000 in the event, including venue rental, entertainment, and décor. Without immediate intervention, the entire evening risked collapse, leading to reputational damage and financial losses.
The event organizers had secured a **1-day event insurance policy** with a **vendor performance bond** rider, which covered third-party failures. The policy’s **financial default coverage** activated upon verification of the vendor’s inability to fulfill obligations, including missed deadlines or sudden withdrawal. Within 24 hours of the incident, the insurer dispatched a replacement catering team from a pre-approved vendor network, ensuring the event proceeded without disruption.
---
Key Elements of the Insurance Response
The resolution relied on three critical components of the policy:
1. **Vendor Performance Bond Activation**
The insurer required documentation proving the vendor’s no-show, including:
- Signed contracts with cancellation clauses.
- Communication records (emails, texts, or missed calls).
- Witness statements from venue staff or event coordinators.
The policy’s **financial default clause** covered the full cost of the meal ($50,000) plus a 15% administrative fee for the insurer’s intervention.
2. **Emergency Vendor Replacement Protocol**
The insurer’s **pre-negotiated vendor network** included backup caterers with similar service levels, reducing the risk of last-minute quality compromises. The replacement team arrived within 6 hours, allowing the kitchen staff to adjust menus and timelines.
3. **Post-Event Claims Settlement**
The insurer reimbursed the organizers for:
- **Direct costs**: $50,000 for the replacement meal.
- **Indirect costs**: $12,000 for expedited shipping of backup décor (due to a separate vendor delay).
- **Contingency buffer**: $8,000 for additional staffing to manage the transition.
The total claim amounted to **$70,000**, fully covered under the **$100,000 liability limit** of the policy.
---
Lessons Learned from the Incident
This case highlights the importance of:
- **Contractual safeguards**: Ensuring vendors include **liquidated damages clauses** (pre-agreed penalties for non-performance) in contracts.
- **Insurance policy scrutiny**: The policy’s **vendor performance bond rider** was the decisive factor; standard event insurance would not have covered this scenario.
- **Documentation protocols**: The organizers’ ability to **immediately gather evidence** (contracts, communications) accelerated the claims process.
"Without the vendor performance bond, the couple would have faced either a last-minute cancellation or a severely compromised event. The insurance not only saved the event but also preserved the venue’s reputation, as the Fontainebleau Resort had previously hosted high-profile weddings without similar incidents."
— **Event Insurance Underwriter, Allianz Global Corporate & Specialty (AGCS)**
One-day event insurance is more than a financial safeguard—it’s a strategic tool that transforms risk into manageable uncertainty. By assessing potential pitfalls before they arise, selecting the right coverage, and documenting every detail, organizers can host events with confidence, knowing that liabilities, cancellations, or accidents won’t leave them exposed. From weddings to corporate galas, the principles remain the same: clarity in policy terms, proactive risk mitigation, and a well-prepared claim process. As the event landscape evolves with digital innovations and niche markets, staying informed about emerging trends ensures that protection keeps pace with ambition. Ultimately, the goal isn’t just to cover risks, but to turn potential disasters into opportunities for resilience and continuity.
Event Insurance: Everything You Need to Know SmartFinancial
Frequently Asked Questions
What exactly is 1-day event insurance and how does it work?
1-day event insurance provides short-term coverage for risks like property damage, liability, or cancellations during single-day events. Policies are tailored to event specifics, offering protection for a limited duration without long-term commitments. Coverage is activated upon event start and ends at conclusion.
Does 1-day event insurance cover vendor equipment if it gets damaged?
Coverage for vendor equipment depends on the policy. Some plans include **equipment breakdown** or **third-party property damage**, while others exclude it. Reviewing the **common coverage types** section ensures clarity on whether rented or owned equipment is protected during the event.
How do insurance companies assess risk for a single-day event?
Risk assessment for 1-day events considers factors like **event size, location, crowd density, and past incidents**. Insurers may also evaluate **security measures, emergency plans, and vendor reliability**. High-risk events (e.g., fireworks, large crowds) may require stricter underwriting or higher premiums.
Are there common exclusions I should know about in 1-day event policies?
Typical exclusions include **pre-existing property damage, intentional acts, war, terrorism, or weather-related cancellations unless specified**. Some policies exclude **alcohol-related incidents** or **high-risk activities** like skydiving. Always review the **exclusions section** before purchasing.
What factors influence the cost of 1-day event insurance?
Cost depends on **event type, location, guest count, coverage limits, and deductibles**. High-risk activities or venues increase premiums. Pricing models may include **flat fees, per-attendee rates, or percentage-based costs**. Comparing providers helps identify the most cost-effective option.
What documents are needed to file a claim for a 1-day event insurance policy?
Required documentation typically includes **police reports (for incidents), witness statements, photos/videos, receipts for damaged items, and the signed insurance policy**. Prompt submission of evidence strengthens claim approval. Always confirm specific requirements with the insurer during purchase.